

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aircraft Carbon Brake Disc Market Set to Grow at 6.1% CAGR Through 2032

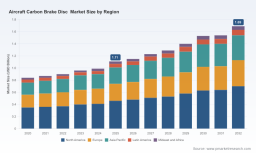
Aircraft Carbon Brake Disc Market: Strategic Briefing for 2026 Corporate Decision-Making
Executive Snapshot
The aircraft carbon brake disc market is entering a phase of measured but sustained expansion. Our analysis at PW Consulting places the global market at approximately USD 1.11 Billion in the 2025 base year, with an expected compound annual growth rate (CAGR) of roughly 6.1% through our 2026–2032 forecast window. By 2032, the market is projected to approach the high single‑digit billions range, driven by fleet renewal, rising aircraft utilization following normalization of air travel, replacement cycles in both commercial and military segments, and ongoing material and production innovations.
Aircraft Carbon Brake Disc Market
Why This Report Matters for 2026 Decisions
Leading aerospace suppliers, OEM procurement teams, private equity investors, and Tier‑2 component manufacturers will confront a clustered market structure, accelerating capital investments, and evolving technical requirements in 2026. Decisions made in 2026 — about capacity, strategic partnerships, product development roadmaps, and procurement contracting — will determine competitive positioning for the rest of the decade. This report provides the analytical foundation to make those choices with confidence, combining historical elasticity (2020–2025) and scenario‑based forecasts (2026–2032) with actionable supplier intelligence and risk matrices.
Aircraft Carbon Brake Disc Market
Market Dynamics: What’s Driving Growth
-
Fleet turnover and replacement: Global airline and military operators are refreshing landing‑gear and braking subsystems as part of broader fleet modernization programs. Replacement cycles for carbon brake discs remain a core demand driver, supported by rising flight hours and heavier mission profiles on certain aircraft types.
Aircraft Carbon Brake Disc Market -
Materials and performance innovation: High‑strength carbon and carbon‑ceramic composite formulations, multi‑layer functional architectures, and proprietary processing routes are improving thermal and mechanical durability. These material advances are lengthening service intervals for some platforms and enabling weight reductions — both financially and operationally significant for lessors and operators.
-
Capacity investments and automation: Major suppliers are committing to large, automated facilities to increase throughput, improve quality consistency, and reduce energy intensity. These investments are also framed as emissions and sustainability initiatives that resonate with OEMs and national regulators.
-
Military procurement tailwinds: Continued defense spend and sustainment contracts provide a stable, often higher‑margin, revenue stream. Multiple suppliers hold certifications and delivery agreements for military platforms, underpinning a dual commercial/military demand profile that smooths cyclical exposure.
Competitive Landscape: Profiles & Strategic Signals
The market is moderately concentrated. The top three suppliers control a significant portion of the global installed base, and the top five account for the majority of revenue and certified platform coverage. This configuration creates both barriers and opportunities: incumbents benefit from scale, certification portfolios, and long OEM relationships, while focused challengers can win share through flexible supply, competitive pricing, and niche technical advantages.
-
Safran — A market pioneer and de facto leader, Safran operates multi‑continental manufacturing footprints and is scaling to meet future demand with a new 30,000 m² automated facility planned at Plaine de l’Ain Industrial Park, slated for operations by 2030. The plant is positioned to support a material production uplift over the coming decade and is explicitly linked to efficiency and emissions reductions. Safran’s installed program list — spanning major Airbus and Boeing platforms — and its broad airline and military customer base make it the strategic fulcrum for many supply chains.
-
Meggitt Aircraft Braking Systems — A well‑established player with NuCarb carbon brakes and recent military delivery awards, Meggitt underscores how supply contracts spanning civil and defense segments can stabilize volumes and provide a platform for growth. Its active long‑term supply engagements with OEM programs are a signal for procurement teams considering supplier risk sharing.
-
Honeywell and Collins Aerospace — Both firms supply integrated braking and landing systems and bring systems‑level integration expertise, aftermarket service networks, and installed base scale. Their proprietary technologies and aftersales footprints (including large installed aircraft counts) are strategic differentiators when customers evaluate lifecycle costs and reliability.
-
China‑based manufacturers and materials specialists — A cohort of Chinese producers has secured airworthiness certifications for prominent commercial platforms and is aggressively expanding supply to domestic and export markets. Their emergence is shaping global competitive dynamics and creating alternate sourcing pathways for OEMs and MRO networks.
-
Materials and component specialists — European and global material suppliers and component houses play a pivotal role as upstream enablers. Proprietary materials (including carbon‑carbon and specialized composite variants) influence product differentiation and aftermarket service life.
Strategic Themes for 2026 Planning
-
Build vs. buy decisions: Organizations must evaluate the total cost of ownership, certification timeline, and volume economics. For high‑volume OEMs or nationalized suppliers, internalizing production with targeted automation may make strategic sense; for others, long‑term supply partnerships reduce certification burden and capital outlay.
-
Capacity and geographic exposure: The next wave of capacity additions by established suppliers will shift lead times and pricing power. Procurement teams should stress‑test supplier roadmaps, prioritize suppliers with redundant geographically distributed capacity, and factor in political and trade considerations when qualifying second sources.
-
Certification and technical moat: Certification portfolios for commercial and military platforms remain a high barrier to entry. Investment in testing, materials R&D, and close collaboration with airworthiness authorities accelerates access to OEM programs and creates long‑term revenue stickiness.
-
Aftermarket and MRO strategies: With an aging installed base in some fleets and intensified fleet activity, aftermarket service and parts availability present revenue upside. Suppliers with robust MRO partnerships can capture both replacement parts and life‑cycle upgrades.
-
Sustainability and operational efficiency: Automation projects are increasingly framed around energy use, waste reduction, and emissions. Suppliers articulating verifiable sustainability metrics can influence OEM procurement decisions tied to ESG commitments.
What the PW Consulting Report Delivers (Practical Elements)
-
A concise executive dashboard with historical market sizing (2020–2025), and a transparent forecast model through 2032 built on scenario analysis and sensitivity testing.
-
A supplier‑level competitive map with capabilities, planned capacity investments, program certifications, and strategic risk profiles — including the closest comparable programs and aftermarket exposure for each named supplier.
-
A materials and technology primer that explains performance trade‑offs (durability, thermal capacity, weight) and identifies which material pathways are most likely to influence procurement specifications.
-
Procurement playbooks and negotiation levers tailored to OEMs, Tier‑1s, and MROs — including contract structures, service level expectations, and suggested KPIs for supplier governance.
-
Risk matrices for supply chain disruption, certification lead times, and geopolitical exposure, with recommended mitigation strategies and contingency sourcing options.
Practical Implications: Actionable Steps for 2026
-
For OEM procurement leaders: Initiate multi‑year framework agreements with tiered pricing tied to verified production capacity expansions, and require transparency on automation and sustainability milestones from existing prime suppliers.
-
For component manufacturers and potential entrants: Prioritize certification paths that map to the largest OEM programs and invest in retrofit solutions that reduce entry barriers into aftermarket channels.
-
For investors and corporate development teams: Use the report’s scenario outputs to assess M&A timing and target profiles — particularly suppliers with niche material IP, in‑place military certifications, or cost‑advantaged regional capacity.
-
For MRO networks: Reassess stocking policies and repair capabilities in light of projected service life improvements from newer materials; a small increase in repair throughput can yield outsized aftermarket returns.
Limitations & Where to Find the Full Intelligence
This briefing highlights the core themes and strategic levers. For readers requiring detailed segmentation tables, regional and application splits, company revenue/market‑share estimates, and the full quantitative model underlying the 6.1% CAGR and 2026–2032 outlook, the full PW Consulting report includes comprehensive datasets, supplier scorecards, and downloadable models. The full report also provides validated citations, contractual timelines for key supplier agreements, and the raw inputs used in scenario simulations.
Concluding Perspective
The aircraft carbon brake disc market in 2026 sits at a tactical inflection: stable structural demand intersecting with supplier capacity shifts, material innovation, and a concentrated competitive set. Organizations that align procurement, engineering, and capital planning around the trajectories described here — while leveraging the deeper, transaction‑level intelligence in the full report — will be best placed to capture value, reduce supply risk, and influence product roadmaps during the next growth cycle.
For detailed analysis of this topic, please visit the official page: Aircraft Carbon Brake Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com