

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Glass Bending Machine Market Set to Reach USD 758.23 Million by 2032, Expanding at a 5.38% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Glass Bending Machine Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s newest market study on the Worldwide Glass Bending Machine Market delivers the kind of actionable foresight senior executives, strategic investors, and plant operations leaders need to make high-stakes decisions in 2026. Our analysis shows the global market continuing its steady expansion from a base-year value of USD 525.4 Million (2025) to an anticipated USD 758.23 Million in 2032, implying a compound annual growth rate of 5.38% over the forecast horizon. While this briefing outlines the critical themes and decision levers, the complete report contains the granular models, supplier scorecards and ROI tools that ground confident capital allocation — available on our report page.
Worldwide Glass Bending Machine Market
What the Report Delivers: Practical, Executable Intelligence
- Investment-grade market sizing and forecast: A robust, audited time series from 2020 through 2032, with scenario variants calibrated to demand shocks, energy price swings and regulatory tightening.
- Decision-ready segmentation: Multi-dimensional segmentation by technology class, application end-market and region, with downloadable demand-driving indices and sensitivity drivers for each segment. (Note: detailed segment figures are reserved for the full report.)
- Supplier benchmarking and procurement kit: Comparative profiles, technology differentiation maps, installation case studies, vendor risk matrices, and a tender checklist that procurement teams can adapt for RFPs.
- CapEx/OpEx playbooks: Life-cycle cost models, energy-consumption baselines, retrofit vs greenfield calculators and payback timelines under multiple pricing and throughput scenarios.
- Technology and production roadmaps: Trajectories for automation, zero-tooling bending, infrared systems, and hybrid tempering-bending lines; guidance on which investments enable margin recovery in high-energy-price regimes.
- Strategic M&A and alliance framework: Valuation comparables, capability-gap heatmaps, and an acquisition target scorecard for corporates and private equity pursuing vertical or horizontal consolidation.
- Operational risk and resilience module: Supply-chain stress-tests, raw material and energy sensitivity analyses, and mitigation playbooks tailored to different geographic footprints.
Market Dynamics Shaping 2026 Choices
- Steady volume growth, rising technical complexity: Demand for curved and complex-shaped glass — driven by contemporary architectural aesthetics and next-generation vehicle designs — is accelerating higher-value equipment purchases. This is reflected in the market’s steady mid-single-digit CAGR, which favors suppliers with advanced bending and tempering integration.
- Energy and raw material volatility: Fluctuations in energy costs and silica inputs materially alter operating economics. Energy-efficient process technologies and demand-side management are no longer optional: they are central to maintaining margin under stress.
- Regulatory tightening and sustainability imperatives: New efficiency and emissions standards are compressing the useful life of older, less-efficient lines. Investors and operators must weigh compliance capex against retrofit options when planning plant upgrades in 2026.
- Automation and digitalization: The competitive frontier is shifting to integrated digital controls and zero-tooling workflows that lower changeover times and increase first-pass yield for complex shapes. These capabilities matter more for customers with mixed-product runs and high customization rates.
Competitive Landscape — Who Matters and Why
The market displays a moderate concentration profile: the top three global vendors capture a meaningful share of industry revenues, and the top five consolidate over half of the market value. This creates a supplier environment where incumbents wield technology depth and aftermarket scale, while a vigorous set of regional and specialist vendors push innovation and price competition.
Worldwide Glass Bending Machine Market
- Changzhou ZT Machine Co., Ltd. (ZTMachine) — China: Recognized for large-format and highly complex architectural bending furnaces and turnkey projects, ZTMachine’s strength is end-to-end project delivery and training services — a key consideration for developers of flagship buildings with bespoke curved glazing.
- CMS Glass Machinery — Turkey: Positioned with integrated tempering and bending solutions that support curved tempered glass production for architectural applications — relevant for fabricators seeking compact, hybrid lines with flexible throughput.
- LandGlass Technology — Luoyang, China: Focused on intelligent automotive bending and tempering; their portfolio suits high-mix automotive suppliers looking to converge bending and tempering in automated flows.
- Glaston Corporation — Finland: Differentiates on process innovation (e.g., HTBS, ProBend, ScreenMax) and has recent field traction with major windshield production installations. Their June 2025 ScreenMax installation at Finn Lamex illustrates how turnkey advanced bending systems enable OEMs to scale specialized glazing production.
- Glasstech, Inc. — USA: Offers high-capacity, energy-efficient deep bend systems for automotive glass, catering to manufacturers prioritizing throughput and thermal efficiency.
- European specialists (Mappi, LiSEC, Bottero, Bavelloni): These vendors emphasize high precision, automation and customization for architectural and specialty glass markets; they are frequently chosen where premium tolerances and integration with downstream CNC/IG lines matter.
- Chinese regional players (Luoyang Lever, Shandong Eworld, Liaoda): Competitive on price and service coverage for regional fabricators; attractive for producers scaling capacity in cost-sensitive markets.
- Casso-Solar Technologies — USA: A notable niche provider of infrared furnaces used across architectural, aerospace and ballistic applications — relevant for specialized, small-batch production or materials with unique thermal profiles.
From a strategic procurement perspective, the choice of supplier is increasingly about fit-to-process rather than lowest CapEx. Considerations include energy intensity, retrofit complexity, digital interoperability with MES/ERP, spare-parts availability, and training/aftercare capabilities.
Worldwide Glass Bending Machine Market
Strategic Imperatives for 2026 — What Leaders Should Do Next
- Reassess CapEx timing through scenario lenses: Use the report’s scenario models to test investment timing under alternative energy and material-price paths. In many cases, modest delays combined with targeted upgrades (e.g., energy recovery modules, digital controls) deliver better risk-adjusted returns than immediate full-line replacement.
- Prioritize energy efficiency in procurement specs: New regulatory thresholds and operating-cost pressures make energy consumption a primary procurement metric. Tender specifications should include standardized energy-consumption test protocols and lifetime energy-cost transparency.
- Design for modularity and flexibility: Favor equipment architectures that support line reconfiguration and mixed-product runs to manage demand volatility across architectural and automotive cycles.
- Build supplier partnerships, not purely vendor relationships: For complex projects, contractualize knowledge transfer, performance guarantees and spare-parts lead times. Consider co-investment models where supplier IP and plant operator incentives are aligned around throughput and yield KPIs.
- Use M&A strategically to buy capabilities: In markets with rising demand for bespoke glazing, acquiring regional specialists or automation providers can accelerate time-to-market while retaining price competitiveness.
- Operationalize resilience: Run supply-chain stress-tests against raw-material and energy shocks, and hedge where practical. Maintain a credible plan for rapid parts replacement and cross-sourced components to avoid multi-week downtime on critical bending lines.
- Leverage digital twins and data-driven maintenance: Deploy predictive maintenance and process-optimization modules early in the deployment lifecycle to capture productivity gains that accrue over the equipment’s lifetime.
Why PW Consulting’s Report Is Different
- Decision-focused analytics: Beyond descriptive market statistics, the study delivers prescriptive models — CapEx/OpEx calculators, scenario-based NPV outcomes, and vendor scorecards tailored to buyer priorities.
- Proprietary primary research: Data inputs combine OEM project-level installations, fabricator operating metrics, and structured interviews with procurement and plant heads across continents to reduce the usual reliance on secondary estimates.
- Action blueprints: Each thematic chapter concludes with a 60–90 day action checklist for C-suite, operations and procurement leaders to translate insight into implementation.
- Practical confidentiality design: The public briefing respects competitive sensitivities — we surface strategic implications and concentration metrics, while detailed segment-level figures, vendor share tables and plant-level case economics are provided only in the full report and interactive dashboards.
In an industry where product complexity, energy intensity and regulatory pressure are converging, the decisions you take in 2026 will determine cost structures and competitive positioning for a decade. PW Consulting’s Worldwide Glass Bending Machine Market report equips you with the models, vendor intelligence and scenario playbooks to choose the right timing, partners and technology pathways. For the full dataset, segment breakdowns, supplier scorecards and downloadable calculators, visit our report page and download the complete study.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Bending Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Headless CMS Software Market to Grow at 21.45% CAGR, Reaching USD 5,009.82 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Headless CMS Software Market — Strategic Preview for 2026 Buyers
As organizations accelerate omnichannel digital experiences, the headless CMS market has moved from niche developer tooling to a strategic platform decision that shapes product velocity, compliance posture, and customer experience across the enterprise. PW Consulting’s new market study (base year 2025; historical 2020–2025; forecast 2026–2032) projects the sector to sustain a high-growth trajectory — driven by composable architectures, API-first integrations, and the industrialization of content as data. This preview summarizes the report’s strategic value for 2026 decision-making while intentionally withholding the full subsegment tables and regional breakouts that are included in the paid report.
Worldwide Headless CMS Software Market
Market snapshot — what the headline numbers say
- Trajectory: The market has expanded rapidly from the early 2020s and reaches a clear inflection point in 2025 as enterprise adoption accelerates across marketing, product, and digital channels.
- Growth rate: Our forecast models show a sustained compound annual growth rate (CAGR) of approximately 21.45% through the 2026–2032 forecast window, underscoring structural demand for headless approaches.
- Scale: The market has moved from startup-scale dollars in the early 2020s to a multi‑hundred‑million-dollar industry by 2025, with projections into the multiple billions by the end of the forecast period — signaling maturation, consolidation pressure, and new opportunity for adjacent services.
- Structure: Market concentration remains moderate — the three largest vendors collectively hold roughly one‑third of market revenue and the top five capture under half — indicating robust competition and room for specialist and open-source players to carve sustainable niches.
Why this matters to enterprise leaders in 2026
- Strategic platform choice equals business velocity. Selecting a headless CMS today is not merely a content decision; it governs feature delivery cadence for new channels (voice, IoT, in-app, digital signage), API economics, and the organization’s ability to recompose digital experiences without monolithic replatforming.
- Risk and compliance have moved to the forefront. European regulatory drivers (GDPR evolution, NIS2) and global data‑residency expectations force architecture choices that balance latency, sovereignty, and operational complexity.
- TCO and talent dynamics are decisive. Managed SaaS reduces operational lift but shifts costs to usage drivers (API calls, CDN bandwidth, seats). Conversely, open-source/self‑hosted variants deliver data sovereignty and control at the cost of significantly higher developer operational time — our operations analysis shows self-hosted deployments commonly demand materially more engineering hours for maintenance, patching, and infrastructure management.
- Security and future‑proofing matter. Organizations must evaluate API security, role‑based access controls, and cryptographic roadmaps (including early planning for post‑quantum cryptography) to mitigate “harvest now, decrypt later” threats.
What PW Consulting’s report delivers (practical, actionable content)
- Decision frameworks: vendor selection matrices tailored to buyer archetypes (enterprise digital experience platform, marketing-centric teams, developer-first shops, and regulated industries).
- TCO and runbook templates: customizable models that isolate primary cost drivers — usage-based API traffic, CDN egress, user seats, and incremental engineering effort for self-hosted options — and Monte Carlo scenarios for scale planning.
- Security & compliance playbooks: prescriptive controls for GDPR/NIS2 alignment, data residency mapping, API hardening checklists, and PQC preparatory steps.
- Migration blueprints: phased migration patterns (strangler, parallel, and hybrid-headless) with rollback triggers, content model remediation checklists, and integration test suites for large CMS-to-headless replatforms.
- Vendor benchmarking and capability maps: qualitative and quantitative scoring across developer experience, localization, governance, composability, AI-enablement, and enterprise support — full vendor scorecards and regional market breakouts are reserved for the full report.
Competitive landscape — how to read vendor positioning
The market’s vendor mix blends enterprise incumbents, cloud-native specialists, and open-source projects. Below are distilled profiles and implications for procurement and architecture teams.
Worldwide Headless CMS Software Market
- Contentful (Berlin, Germany) — An enterprise-grade pioneer with a robust API-first backbone (REST + GraphQL), strong localization features, and a composable content platform. Best suited for large brands that demand high‑scale omnichannel delivery and mature governance models. Contentful’s commercial positioning focuses on scale, SLAs, and enterprise integrations.
- Sanity (San Francisco, USA) — Developer-focused content operating system with real-time collaboration, a customizable studio, GROQ querying, and strong TypeScript support. Attractive for engineering-led teams that prioritize realtime editing, developer ergonomics, and extensibility; capable of cost-efficient scaling via usage-based pricing.
- Strapi (Paris, France) — Leading open-source, Node.js-based option offering full self‑hosting control and an extensible plugin ecosystem. With Strapi 5 (2026) introducing improved TypeScript support and Vite integration, it increasingly addresses enterprise accessibility concerns while preserving data sovereignty benefits — but buyers should account for higher operational engineering effort for self-hosting.
- Storyblok (Linz, Austria) — Emphasizes visual, component-driven editing with strong marketing usability and continuous enhancements in AI-enabled workflows. Recognized in independent industry evaluations for leadership in AI-enabled editing, Storyblok is often selected by teams seeking marketer autonomy with enterprise governance.
- Hygraph (London, UK) — GraphQL-native platform focused on content federation and deep relational modeling; tailored for complex multi-brand and multi-channel environments that need rich relationships and schema-first workflows.
- Prismic (Paris, France) — Slice-based page-building approach favors non-technical teams; recent positioning among top enterprise platforms highlights growth in the page-builder + headless bucket — a solid choice for marketing-driven page composition.
- Contentstack (San Francisco, USA) — Positioned for enterprises requiring advanced governance, workflows, and composable DXP features. Industry recognition in analyst reports cements its score for large-scale digital experience programs that require rigorous enterprise support.
- Kontent.ai (Brno, Czech Republic) — API-first CMS focused on governance, collaboration, and AI-assisted workflows — notably appropriate in regulated environments requiring sophisticated localization and review workflows.
- Payload CMS, Directus, Agility, Butter and other specialists — These platforms occupy developer-centric or niche usability positions: code-first control and Next.js integration (Payload), SQL-backed data-platforms (Directus), high-speed content delivery (Agility), or marketer-friendly APIs for simple editorial needs (Butter). They are commonly chosen for targeted use cases or as components in a composable stack.
Notable vendor developments to watch (early 2026)
- Strapi released a major v5 update in Feb 2026, improving TypeScript support and build performance — an important signal for enterprises considering open-source for core systems.
- Prismic was repositioned in March 2026 among leading enterprise headless platforms for its slice-based page building, reflecting broader adoption in marketing-led page composition.
- Storyblok received recognition tied to IDC/Forrester analyses for AI-enabled headless capabilities and advancements in visual editing and vector data layers.
- Contentstack continues to be cited in analyst literature for enterprise-grade DXP capabilities, reinforcing its appeal to organizations with complex governance needs.
Procurement & architecture checklist — practical tradeoffs
- SaaS vs self-hosted: SaaS minimizes operational headcount and accelerates time-to-value but exposes buyers to usage-based cost structures (API calls, CDN egress, user seats). Self-hosted solutions deliver control and data residency, yet our operations research indicates materially higher developer operations effort for maintenance and security.
- Integration surface: prioritize platforms with robust GraphQL/REST dual support, webhook maturity, and SDK ecosystems aligned to your tech stack (TypeScript, Next.js, Jamstack tooling).
- Security & compliance: require vendor articulation of role-based access controls, encryption-at-rest and in-transit, regional hosting options, and a roadmap for cryptographic migration to PQC where relevant.
- AI readiness: evaluate how a platform integrates AI for content generation, RAG workflows, and vector search — ensure guardrails for data leakage and model governance are in place.
90‑day playbook for 2026
- Month 1 — Align stakeholders: run a two-hour architecture & procurement workshop to map channel priorities, compliance constraints, and integration dependencies. Use our starter TCO model to stress-test spend scenarios.
- Month 2 — Shortlist & pilot: evaluate 3–4 vendors against tailored use cases (editorial workflow, multi‑brand federation, developer DX). Run a seven‑to‑ten day spike that validates performance under expected API traffic and localization volumes.
- Month 3 — Decide & plan migration: finalize vendor, define phased migration (pilot property → strangler pattern → full cutover), and set measurables for time-to-market, content reuse, and cost per channel.
Closing — where to go next
PW Consulting’s full Worldwide Headless CMS Software Market report contains the complete regional and application-level segmentation, vendor scorecards, downloadable TCO models, and step‑by‑step migration templates that enterprises need to operationalize a 2026 headless strategy. This preview is intended to surface the strategic signals and immediate actions: the detailed subsegment intelligence and vendor benchmarking needed to execute procurement and architectural decisions are available in the full report at PW Consulting.
Worldwide Headless CMS Software Market
For detailed analysis of this topic, please visit the official page: Worldwide Headless CMS Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Achondrogenesis Market Poised to Grow at a 5.59% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Achondrogenesis Market: Strategic Preview for 2026 — A PW Consulting Industry Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to present an executive preview of our comprehensive Worldwide Achondrogenesis Market study. This briefing synthesizes the high-level findings that will shape executive decisions in 2026 — from R&D prioritization and commercial planning to partnership strategies and M&A screening. The full report contains the granular datasets, subsegment breakdowns, and company-level scorecards that commercial and investment teams will need to operationalize these insights.
Worldwide Achondrogenesis Market
Market Trajectory at a Glance
-
Base year and scope: The report uses 2025 as the base year and analyzes historical trends from 2020–2025, with a detailed forecast across 2026–2032.
Worldwide Achondrogenesis Market -
Growth profile: The global achondrogenesis market is modeled to grow at a compound annual growth rate (CAGR) of approximately 5.59% over the forecast horizon. After reaching an estimated USD 155.0 Million in 2025, our central case projects the market to expand to roughly USD 226.75 Million by 2032 under current assumptions.
Worldwide Achondrogenesis Market -
Short-term dynamics: In the near term (2026–2028), growth is expected to follow a steady climb as diagnostic adoption and prenatal screening workflows continue to scale. The model incorporates scenario sensitivity for accelerated genetic screening adoption and reimbursement advances that could materially increase near-term revenue capture.
Why This Market Matters for 2026 Decisions
Achondrogenesis — as a rare, severe skeletal disorder — operates at the intersection of prenatal diagnostics, genetic testing, and specialized clinical pathways. For life sciences, diagnostics companies, and healthcare providers considering resource allocation in 2026, the market offers three decision levers with outsized strategic consequences:
-
Capability investments: Investments in advanced genetic testing platforms and scalable prenatal imaging integrations will determine which organizations capture rising diagnostic volumes and downstream clinical partnerships.
-
Evidence and reimbursement: Generating convincing real-world evidence (RWE) to support clinical utility and payer recognition is the single most impactful action to accelerate commercial uptake.
-
Partnerships vs. in-house: Given the specialty nature of diagnostic workflows, alliances between clinical centers, diagnostic labs, and imaging vendors provide the lowest-cost path to market entry for most players — while vertical integration remains attractive for larger incumbents.
Market Structure and Competitive Dynamics
Our concentration analysis indicates a moderately consolidated landscape. The top three players account for a meaningful portion of market revenue, and the top five increase that share further, which suggests a market where a few strategically placed organizations wield significant influence over distribution, platform access, and institutional relationships. For entrants and investors, this structure implies:
-
Defensible niches are attainable: Focused investments in specialized service offerings (e.g., prenatal counseling tied to specific genetic panels, or bespoke assay development) can secure stable margins even in a concentrated market.
-
Partnerships are essential: Collaborating with clinical hubs and reference labs can accelerate credibility and access without the need for large upfront capital deployment.
-
M&A and bolt-on acquisitions remain high-leverage moves for firms seeking rapid scale — but must be guided by rigorous integration playbooks.
What the Full Report Delivers: Practical, Transaction-Ready Intelligence
To inform 2026 strategy and transactional activity, the report delivers actionable modules designed for executive teams and deal professionals:
-
Market model with sensitivities: A dynamic model that reconciles historical uptake (2020–2025) with alternative adoption scenarios across 2026–2032, enabling revenue and EBITDA impact simulations under conservative, base, and accelerated cases.
-
Commercial playbooks: Go-to-market frameworks for three archetypes — diagnostic laboratories, prenatal imaging providers, and integrated care networks — including channel strategies, pricing-guidance, and customer acquisition economics.
-
Regulatory and reimbursement map: Country- and region-specific regulatory checkpoints and payer pathways that affect time-to-market and revenue realization. This includes a prioritized list of jurisdictions where early reimbursement wins are plausible in 2026–2028.
-
RWE and HTA strategy templates: Protocols and study designs for generating the clinical and economic evidence that payers and institutional purchasers demand.
-
Risk and mitigation matrices: Scenario-based risks spanning technology obsolescence, guideline shifts, and macro reimbursement changes, paired with tactical mitigations and trigger points for escalation.
-
M&A and partnership pipeline screening: A scoring methodology and shortlist criteria to identify high-value targets and collaboration partners tailored to different strategic intents (capability acquisition, geographic expansion, or service bundling).
Key Market Dynamics Shaping the Forecast
Several structural forces underpin the 5.59% CAGR and the forecasted growth to USD 226.75 Million by 2032. These forces are not uniformly distributed and will create windows of advantage for agile players:
-
Diagnostic technology maturation: Ongoing improvements in genetic sequencing, expanded prenatal testing panels, and integration of molecular diagnostics with imaging workflows are reducing per-patient diagnostic cost and time-to-diagnosis — driving adoption in high-volume clinical centers.
-
Clinical guideline evolution: Emerging consensus on prenatal diagnosis and counseling for severe skeletal dysplasias will shape referral patterns and influence investment decisions by hospitals and specialist networks.
-
Payer pressure and value demonstration: Increased demand for health-economic validation means that firms that can demonstrate downstream cost avoidance (e.g., through informed pregnancy management or targeted neonatal care) will unlock better reimbursement and accelerated uptake.
-
Geographic divergence: While overall market expansion is positive, incident rates, diagnostic infrastructure, and payer readiness vary considerably across regions — creating differentiated opportunity sets that require tailored commercial playbooks.
Strategic Imperatives for 2026
For executive teams preparing budgets, R&D pipelines, or commercial initiatives in 2026, the following imperatives translate our findings into concrete action items:
-
Prioritize diagnostic interoperability: Invest in systems and partnerships that enable seamless data flow between imaging, genetic testing, and electronic health records to reduce friction and accelerate clinical adoption.
-
Commit to RWE up front: Allocate budget and operational capacity to prospective RWE collection. Early evidence will materially shorten the payer negotiation cycle and improve commercial terms.
-
Selective geographic entry: Use a phased approach — target jurisdictions with faster reimbursement trajectories and strong clinical centers of excellence first, then reinvest gains into broader rollouts.
-
Build modular offerings: Offer configurable diagnostic bundles (e.g., combined genetic panel + prenatal imaging interpretation + counseling) that can be adapted to payer and provider preferences.
-
Prepare M&A playbooks: Maintain a near-term list of bolt-on targets and a playbook for rapid integration to capture market share and clinician relationships efficiently.
Why PW Consulting’s Analysis Is Different
Many publications provide headline numbers. PW Consulting’s report integrates those numbers into executable guidance. Our work is distinguished by three characteristics:
-
Transaction-focused modeling: Our market model is built for deal teams and product leaders, with scenario-driven outputs that feed directly into valuations, capex planning, and go-to-market investment decisions.
-
Operational playbooks: We translate market insights into step-by-step commercial and clinical adoption playbooks — not just high-level recommendations.
-
Transparent assumptions and sensitivity analysis: Every forecast is accompanied by its assumptions and sensitivity bands, enabling clients to stress-test strategies under alternative futures.
Access to the Full Intelligence
This preview intentionally focuses on strategic insights and omits the granular subsegment figures and company-level data that are included in the full report. The complete study provides the detailed regional, type, and end-user splits, plus firmographic profiles, proprietary market models in USD Million, and a repository of primary interviews and data sources.
If your 2026 planning cycle includes decisions about capability investments, strategic partnerships, or M&A in the achondrogenesis space, securing the full report and the underlying model will materially reduce execution risk and shorten time-to-impact. For licensing, bespoke workshops, or to obtain the dataset and model files used to derive the projections above, please visit our report page or contact a PW Consulting engagement lead.
Closing Perspective
The achondrogenesis market, while specialized, presents a clear growth pathway driven by diagnostic innovation, guideline evolution, and the growing premium on early, accurate prenatal information. With a projected rise from an estimated USD 155.0 Million in 2025 to roughly USD 226.75 Million by 2032 at a 5.59% CAGR, the window for value creation is open but conditional: organizations that align diagnostic capabilities, evidence generation, and payer strategies in 2026 will be best positioned to capture disproportionate share and influence clinical pathways over the next decade.
PW Consulting’s full Worldwide Achondrogenesis Market report supplies the practical, transaction-ready intelligence required to act decisively. The preview above highlights the strategic contours — the complete report supplies the maps, models, and operational tools to navigate them.
For detailed analysis of this topic, please visit the official page: Worldwide Achondrogenesis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Telescopic Cylinder Market to Grow from USD 2,185.5M in 2025 to USD 3.10B by 2032 at a 5.12% CAGR
By pmarketresearch, 2026-07-15
Worldwide Telescopic Cylinder Market — Strategic Imperatives for 2026
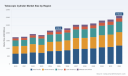
PW Consulting’s latest industry brief on the Worldwide Telescopic Cylinder Market synthesizes a granular, execution-oriented research program into a single strategic asset for executive teams preparing for 2026. The market has expanded from roughly USD 1.7 billion in 2020 to about USD 2.19 billion in 2025, and our forecast modeling indicates a steady compound annual growth rate (CAGR) of 5.12% across the 2026–2032 horizon, pushing the market toward roughly USD 3.10 billion by 2032. Those top‑line figures frame meaningful tactical choices: where to invest, who to partner with, how to defend margin, and which risks to hedge first. This press release delivers the evidence-based line-of-sight PW Consulting clients will use to convert foresight into 2026 action.
Worldwide Telescopic Cylinder Market
Why this report matters for 2026 decision cycles
- Prioritize capital allocation with precision: With measured, scenario-driven forecasts, firms can sequence product R&D, factory upgrades and aftermarket investments to match demand corridors rather than chase short‑term fluctuations.
- Translate raw-material volatility into procurement strategy: Steel accounts for a very large share of component cost in telescopic cylinders. The report models sensitivity to steel and high‑grade alloy price swings and prescribes contracting and hedging mechanisms.
- Mitigate regulatory and tariff risk: We map tariff exposure across key supply chains (steel tubes, precision rods, seals and machined components) and recommend sourcing/nearshoring strategies and pricing clauses to protect margins.
- Target high-value applications and channels: The analysis identifies where telescopic cylinders win because of stroke-to-retracted-length economics (notably space-constrained urban construction equipment) and how OEM and aftermarket routes differ in margin and service requirements.
- Inform M&A and partnership plays: Market concentration is moderate—top-three players account for about 38% of market activity and the top-five about 53%—a structure that favors strategic bolt-ons to accelerate scale, capabilities or geographic reach. Our playbooks show how to size targets and prioritize synergy capture.
What’s inside the report — actionable modules (high level)
- Executive dashboard: base-year (2025) sizing, historical trend (2020–2025) and probabilistic forecasts to 2032 with scenario toggles for commodity shocks and demand shifts.
- Commercial playbooks: go‑to‑market templates for OEM, distributor and aftermarket channels, with pricing levers and service-bundling structures.
- Cost and sourcing module: bill of materials breakdown, supplier segmentation, lead-time analysis and recommended contracting models to manage steel‑price exposure.
- Technology and product roadmap: assessment of sensor-integration (IoT-enabled cylinders), sealing and nitriding treatments, large-bore and piggyback designs, and the product features that command premium pricing.
- Competitive and M&A toolkit: profiles of incumbent and emerging manufacturers, overlap matrices, and an M&A heatmap that ranks strategic fit across capability, geography and customer access.
- Operational playbook: factory-capacity assessments, quality and certification checklists (ISO 9001 baseline), test-rig recommendations and CAPEX sequencing for efficiency and verticalization.
- Decision support assets: TCO calculators, supplier scorecards, and scenario planning templates clients can deploy immediately in procurement and strategy meetings.
Competitive landscape — who matters and why
The market includes a mix of global hydraulics majors, specialized OEMs, and regional manufacturers. Competitive positioning tends to fall into three clear plays: multi‑product hydraulics integrators; high‑value specialty manufacturers; and cost‑competitive regional producers focused on local OEMs and aftermarket channels. Below is a snapshot of representative players and the strategic signals we track.
Worldwide Telescopic Cylinder Market
- Parker Hannifin Corporation (Cleveland, OH, USA) — Extensive single‑ and double‑acting portfolios and growing investment in sensor-integrated “smart” actuators. Parker’s recent launches underscore an industry pivot to IoT-enabled cylinders for predictive maintenance and remote diagnostics.
- Bosch Rexroth AG (Lohr am Main, Germany) — Offers industrial and mobile heavy‑duty telescopic solutions, with emphasis on larger-bore and high‑precision variants; strong OEM relationships in Europe and a reputation for engineering depth.
- Eaton Corporation (Dublin, Ireland) — Leverages hydraulics division scale to serve construction and mobile equipment sectors; focus on integration and aftermarket support.
- HYDAC International GmbH (Sulzbach, Germany) — Niche strength in industrial and mobile hydraulic systems, with close ties to system integrators and testing capabilities valued by quality-conscious OEMs.
- Mailhot Industries (Saint‑Jacques, Quebec, Canada) — North American specialist, known for durable nitrided telescopic cylinders and recent consolidation activity that reinforces aftermarket and custom capabilities.
- HSI Corporation, Texas Hydraulics, Aggressive Hydraulics — Smaller, highly specialized suppliers that compete on custom engineering, large-bore and high-duty-cycle designs, and rapid response for demanding applications.
- Regional OEMs in Asia (e.g., leading Chinese and Indian manufacturers) — Provide cost‑competitive products to domestic OEMs and export markets; their scale and vertical integration can compress margins for global incumbents if quality expectations align.
Recent industry moves—product launches featuring integrated sensors and Bauma 2025 trade-show innovations—signal that incumbents are pairing materials and machining know‑how with digital capabilities to create differentiated service offerings. This is important for 2026 because product differentiation is increasingly realized through data and service rather than metallurgical novelty alone.
Worldwide Telescopic Cylinder Market
Market dynamics, operational risks and how to act
- Commodity sensitivity: Steel represents a substantial portion of production cost for telescopic cylinders. Our model shows margin exposure to steel-price swings and recommends five immediate levers: long‑term supply contracts, alternative alloys where feasible, strategic inventory buffers, price‑pass clauses, and a supplier hedging program.
- Tariffs & trade policy: Tariffs affecting imported steel tubes, rods and seals raise both costs and lead times in North America and Europe. For 2026, firms should build tariff‑aware sourcing maps and evaluate nearshore manufacturing to reduce exposure.
- Urban construction trend: Telescopic cylinders are increasingly preferred for machines that require long stroke but compact retracted length. Product roadmaps should prioritize stroke density and shorter assembly footprints to win OEM specification contests in urban projects.
- Quality & standards: ISO 9001 remains the baseline expectation. Moving beyond baseline—demonstrable process controls, nitriding and test rigs—drives differentiation for premium accounts and heavy‑duty applications.
- Supply chain resilience: Precision rods and machined components are bottlenecks. A supplier diversification play and selective vertical integration for critical tolerances will be decisive for continuity and margin control in 2026.
Priority recommendations for 2026 — concrete, time-bound actions
- Procurement: Secure multi‑year contracts for key steel inputs with indexation clauses; qualify alternative suppliers in low‑tariff jurisdictions within Q1–Q2.
- Product & R&D: Accelerate sensor-enabled cylinder programs and modular product platforms that reduce lead times and enable aftermarket software services—target a prototype and pilot OEM program by Q3.
- Go‑to‑market: Rebalance channel focus to bolster aftermarket and service contracts (higher margin, recurring revenue) and expand distributor stocking strategies in urban construction hotspots.
- M&A & partnerships: Use the report’s M&A heatmap to shortlist targets that close gaps in nitriding, large‑bore machining, or regional aftermarket coverage; prioritize deals that deliver immediate cross-sell and cost synergies.
- Operations: Invest in test‑rig automation and quality tracing to shorten qualification cycles for OEMs and to command premium pricing for heavy‑duty segments.
How senior teams should use this report during 2026 planning
- Ceos and Board members: Validate capital allocation and M&A pipelines against the provided scenario suite.
- Heads of Product and R&D: Use the product roadmap and TCO models to prioritize feature investment and prototype timelines.
- Procurement leaders: Deploy the supplier scorecards and contracting templates to secure raw‑material continuity and cost control.
- Commercial and Sales leads: Implement the channel playbooks to expand aftermarket revenue and accelerate adoption of sensor‑enabled cylinders.
- Investors and private equity: Leverage our competitive landscape and concentration analysis to size platform investments and bolt‑on targets.
PW Consulting’s Worldwide Telescopic Cylinder Market report is intentionally structured as an operational toolkit—more than a forecast, it is a set of playbooks, models and checklists that turn insight into executable initiatives. This summary is a strategic trailer: it signals the depth of our research and the practical nature of the outputs while reserving the full segmentation tables, deterministic models and granular competitor metrics for the complete report.
For executives preparing budgets, negotiating supplier contracts, or evaluating M&A targets for 2026, the full report provides the granular segmentation, regional and application analytics, and downloadable decision-support workbooks you will need to act with confidence. Contact PW Consulting to access the comprehensive dossier and accompanying toolkits that will make your 2026 strategy decisive rather than defensive.
For detailed analysis of this topic, please visit the official page: Worldwide Telescopic Cylinder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insight: Worldwide Oral Solid Dosage Market Poised for 6.3% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Oral Solid Dosage Medicine Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
PW Consulting’s newest market research briefing on the Worldwide Oral Solid Dosage (OSD) medicine market synthesizes a decade-long perspective and a forward-looking operational playbook tailored for 2026 corporate decisions. Built on historical performance (2020–2025) and a proprietary forecasting engine covering 2026–2032, the report frames a market that has grown from the mid‑2020s trajectory to an estimated USD 738.5 Billion in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 6.3% through the forecast window. By 2032, total market value is modeled to exceed USD 1.1 trillion under the base scenario — a scale that demands strategic clarity across manufacturing, sourcing, commercialization and corporate finance.
Worldwide Oral Solid Dosage Medicine Market
Why this report matters for 2026 strategies
-
Timing: 2026 is a pivot year for OSD decision-makers — capital allocation cycles restart, new facilities announced in 2024–2025 begin feeding pipeline choices, and regulatory and supply shocks from prior years remain active. Our analysis identifies when near-term actions will produce outsized returns versus when to defer.
Worldwide Oral Solid Dosage Medicine Market -
Concentration and competition: Market concentration remains relatively low (CR3 ≈ 18.4%, CR5 ≈ 24.5%), indicating fragmentation and room for strategic consolidation, vertical integration, and specialist CDMO expansion.
Worldwide Oral Solid Dosage Medicine Market -
Scale and velocity: With a multi‑hundred‑billion USD market expanding at mid-single digits CAGR, both incumbents and challengers must reconcile volume-driven generics economics alongside high-margin branded OSD launches and specialty small-molecule therapies.
-
Operational urgency: End-to-end supply resilience, raw-material sourcing strategies, and modular capacity expansion are now non‑negotiable components of commercial planning.
What’s inside: practical, decision-grade content
The report is structured to move executives from high‑level market understanding to immediate, actionable steps. Key deliverables include:
-
Proprietary total‑market forecast model (2020–2032) with scenario toggles for pricing, patent expiry timing, and supply disruption intensity — designed to feed board-level capital allocation and annual operating plans.
-
Scenario playbooks (best case / base case / stress case) that quantify revenue and margin sensitivity to generic erosion, excipient shortages, tariffs, and new‑capacity ramp schedules.
-
Manufacturing and CDMO opportunity maps that identify where to invest, partner, or divest based on technology fit (e.g., continuous manufacturing, high‑potency handling, orally disintegrating tablets), time to market, and regulatory complexity.
-
Supply‑chain resilience toolkit: dual‑sourcing matrices, critical‑excipient single‑point‑failure audits, and an implementation timeline for transitioning from single to dual qualified suppliers without disrupting regulatory filings.
-
Regulatory and shortage risk matrix with prioritized mitigations — includes practical procurement hedges, buffer stock policies, and government engagement templates for jurisdictions experiencing product shortages.
-
Pricing & reimbursement playbook for managing post‑patent pricing pressure, tender‑market dynamics and cost‑plus negotiations with payers and large group purchasers.
-
M&A and partnership readiness checklist for both strategics and financial sponsors seeking to consolidate manufacturing assets or scale CDMO platforms.
-
CapEx prioritization framework tying facility investments to expected return windows, product life‑cycle phasing and optionality for modular expansion.
Competitive landscape: what leading players are signaling
The OSD ecosystem in 2026 is best characterized as a two‑tiered competitive environment: large, integrated pharmaceutical companies that retain sizeable in‑house OSD manufacturing capabilities, and a robust, fragmented CDMO and generics community that provides capacity, technical specialization and route‑to‑market agility.
-
Integrated majors (Pfizer, Merck, Johnson & Johnson, AbbVie, AstraZeneca, Sanofi, GSK, Novartis, Eli Lilly): These players continue to secure control of critical parts of the value chain. Recent landmark commitments — including multi‑billion dollar manufacturing investments announced by select firms — demonstrate a strategic preference for end‑to‑end control in key markets and therapeutic categories. Such investments are aimed at shortening supply chains, protecting IP-sensitive processes and ensuring prioritized manufacturing for strategic brands.
-
CDMOs and generics manufacturers (Teva, Catalent, Lonza, Aenova, Recipharm, Piramal, Thermo Fisher/Patheon, Jubilant, Siegfried, CordenPharma, LGM Pharma): These firms are expanding capability sets and capacity with focused capital allocations. Examples include recent facility expansions and partnerships that enable specialized OSD forms (multi‑layer tablets, high‑potency handling, orally disintegrating tablets), and phased investments that de‑risk capacity builds for niche, high‑value products.
-
Strategic implications: Integrated players will selectively insource where control over supply, quality and speed-to-market are mission critical; conversely, mid‑size pharma and many originators will continue to rely on CDMOs for flexible capacity, technical know‑how and cost optimization. For CDMOs, the runway is favorable — but success will hinge on differentiated capabilities, regulatory reliability, and execution speed.
Market dynamics shaping near‑term decisions
-
Supply disruptions and shortages: While reported drug shortages declined from recent peaks, availability remains elevated versus pre‑2020 norms. Shortage episodes continue to enforce premium pricing on prioritized products and force manufacturers into contingency inventory and qualification cycles.
-
Patent expirations and generic erosion: A concentrated set of small‑molecule patent expiries over the 2025–2030 window implies substantial revenue erosion for originators, accelerating the need to roadmap lifecycle strategies — from line extensions to authorized generics and new formulation patents.
-
Raw‑material volatility: Documented excipient supply issues have been material contributors to shortages, underlining the commercial importance of supplier diversification and earlier qualifying timelines for alternative excipients.
-
Trade and tariff risk: Policy shifts affecting APIs and intermediate imports can rapidly reshape cost structures for generics and create short to mid-term reshoring incentives for specialty OSD lines.
Actionable recommendations for 2026 leaders
-
Embed supply resilience in the KPIs that drive capital allocation. Prioritize investments that reduce single‑point failures (dual qualifying critical excipients; geographically diversified packaging lines).
-
Use a scenario‑based capital review for any new facility. Validate investments against stress cases that assume accelerated generic entry and 25–40% price compression in tender markets.
-
For originators facing near‑term patent cliffs, plan multi‑track defense strategies: authorized generics, reformulation/line extensions, selective divestiture of commodity OSD SKUs, and fast follow manufacturing partnerships.
-
CDMO strategy: invest in narrowly differentiated capabilities where regulatory entry barriers and technical complexity justify price premiums (e.g., multi‑layer tablets, high‑potency handling, or rapidly disintegrating formats).
-
Operationalize excipient risk management — not as a procurement checkbox but as a continuous manufacturing readiness program with qualification triggers tied to demand surge scenarios.
-
Leverage modular, digitalized manufacturing technologies (continuous manufacturing, PAT) to compress time-to-scale and reduce working capital intensity on inventory buffers.
-
Align commercial teams and manufacturing planners through integrated S&OP that explicitly models generic erosion, shortage probabilities and contract manufacturing capacity constraints.
-
Consider selective M&A to accelerate capability acquisition and geographic footprint consolidation — the current fragmentation creates favorable acquisition entry points but requires rigorous integration playbooks.
Closing: where to go next
This briefing outlines the strategic levers that matter for 2026 and beyond. PW Consulting’s full Worldwide Oral Solid Dosage Medicine Market report contains the underlying datasets, detailed sub‑segment forecasts, country‑level scenarios, and downloadable tools referenced above. The report’s downloadable appendices include the full time‑series model, contractual sourcing templates, and an executable 18‑month implementation plan for manufacturing and supply‑chain interventions — intentionally withheld here to preserve the value proposition of the full report.
For executives ready to convert insight into action, PW Consulting offers tailored workshops and model integrations that adapt the report’s scenarios to your P&L and balance‑sheet realities. Contact our industry team to schedule a strategic briefing and to access the complete dataset and interactive forecasting tool.
For detailed analysis of this topic, please visit the official page: Worldwide Oral Solid Dosage Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Motorcycle Headlight Bracket Market to Reach USD 369.37 Million by 2032, Growing at a 5.82% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Motorcycle Headlight Bracket Market — Strategic Outlook for 2026
PW Consulting’s new market study on the Worldwide Motorcycle Headlight Bracket Market provides a hard-nosed, decision-ready perspective for executives preparing strategy, sourcing, product and M&A plans in 2026. The sector is small but strategically important to both OEM vehicle architectures and an increasingly vibrant aftermarket, and our analysis translates macro trends into practical actions—while reserving the full granular breakdown for the complete report.
Worldwide Motorcycle Headlight Bracket Market
Executive snapshot: scale, growth and what it means
The global motorcycle headlight bracket market reached an estimated USD 248.6 Million (revenue unit: Million USD) in our 2025 base year and is projected to continue its steady expansion into 2026 and beyond. The study models a multi-year trajectory consistent with a compound annual growth rate of approximately 5.8% across the forecast window, underpinned by both OEM refresh cycles and an expanding aftermarket driven by electrification, customization and LED conversions.
Worldwide Motorcycle Headlight Bracket Market
For 2026 specifically, the model anticipates a meaningful uplift in absolute revenue versus the 2025 base, reflecting healthy underlying demand paired with material- and regulation-driven product requalification cycles. For management teams, that combination represents a blend of organic growth and recurring reengineering opportunities—ideal conditions for targeted investment, supplier consolidation, or premium product introduction.
Worldwide Motorcycle Headlight Bracket Market
Why this report is strategic for 2026 decision-making
- Turn macro signals into procurement actions: we translate global demand growth and material volatility into concrete cost-impact scenarios for buy-side teams.
- Mitigate regulatory risk: our mapping of safety standards and certification touchpoints helps product and compliance teams prioritize redesign or testing programs before enforcement becomes binding.
- Prioritize portfolio moves: the study highlights where to invest in premium materials, where to optimize for cost, and where to pursue aftermarket expansion versus OEM partnerships.
- Frame M&A and partnership theses: we identify where consolidation creates value and where nimble, niche players can extract premium margins.
Key market dynamics shaping strategies in 2026
- Materials and manufacturing:
Aluminum alloy continues to dominate as the preferred material for headlight brackets because of its favorable strength-to-weight ratio, corrosion resistance and compatibility with CNC machining. Steel remains relevant where cost and extreme durability are primary drivers. Emerging use of composites—primarily in premium and custom builds—creates a runway for differentiated products but requires manufacturing and repair-readiness planning.
- Raw material price volatility:
Aluminum price fluctuations materially influence production economics. Our sensitivity analysis quantifies the pass-through window for suppliers and shows how short-term hedging, dual-sourcing strategies and value-engineering initiatives can protect gross margins without eroding product quality.
- Regulation and safety standards:
Standards such as FMVSS 108 (and equivalent international rules) directly affect bracket design and validation cycles by specifying lighting mounting performance and durability requirements. As regulators focus more on durability and crashworthiness, companies must budget for expanded testing and, in some cases, redesign to maintain compliance and avoid costly recalls.
- Aftermarket momentum and electrification:
The aftermarket is growing in lockstep with the rise of electric two-wheelers, custom builds and LED retrofits. CNC-machined aluminum brackets and conversion kits have become de facto solutions for enthusiasts and fleet operators seeking upgraded lighting systems; for suppliers this means a dual-channel go-to-market play—maintain OEM quality and support aftermarket customization.
- Technology convergence:
Integration with LED lighting systems and electronic accessories is becoming a product differentiator. Bracket makers that partner with lighting OEMs or offer modular mounting interfaces can capture share in higher-margin retrofit projects and OEM accessory programs.
Competitive landscape — who matters and why (strategic implications)
The market today presents a mix of specialty artisan shops, tier suppliers, and OEMs with captive parts programs. The competitive field is moderately fragmented, with the top three suppliers accounting for roughly a third of market revenue and the top five approaching the mid‑40% range—conditions that favor both niche premium players and disciplined consolidators.
- Tommaselli (Italy) —
Renowned for high-quality levers and fork-mounted brackets, Tommaselli’s brushed aluminum craftsmanship and vibration-focused designs position it as a preferred supplier for premium restorations and boutique OEM programs. Strategic takeaway: partner with Tommaselli for co-branded premium accessories or benchmark its vibration attenuation approaches when redesigning mid‑segment products.
- Wunderkind-Custom (Germany) —
Specializes in individually adjustable, CNC-aluminum premium brackets with certified quality. Their design-led positioning makes them a logical collaborator for OEMs seeking limited-run or premium accessory programs. Strategic takeaway: consider licensing design elements or using Wunderkind as a proof point for higher-margin accessory bundles.
- Motodemic (USA) —
Known for machined 6061-T6 mounts that ease installation on customs without top clamp removal. Their user-friendly designs are highly attractive in aftermarket conversions. Strategic takeaway: acquisition or distribution partnerships can rapidly increase an OEM’s accessory portfolio with low development lead time.
- Denali Electronics (USA) —
Provides LED lighting and compatible mounting systems for major brands, bridging electronics and mechanical mounting. Their integrated offering is a template for higher-margin, systems-level accessory sales. Strategic takeaway: pursue supplier alliances to offer certified lighting+bracket bundles for fleet electrification and dealership upsell.
- BrightstarTW (Taiwan) —
Taiwanese CNC specialist producing standard and premium 6061 brackets with a focus on durability and ease of fit. Their volume CNC capability makes them an attractive partner for OEM supply scaling. Strategic takeaway: evaluate BrightstarTW for cost-effective, high-spec contract manufacturing or second-source supply for critical SKUs.
- Baak Motocyclettes (France) —
Artisanal workshop producing universal brackets in satin black aluminum for common fork sizes; a strong brand in boutique customization. Strategic takeaway: small acquisitions or white‑label manufacturing agreements can help OEMs tap style-forward aftermarket demand.
- Chinese fabricators (e.g., Xinzhe Metal, Foshan Dragon) —
Large-volume metal fabricators supplying carbon steel and other bracket designs. Their low-cost manufacturing remains central for price-sensitive programs and volume aftermarket SKUs. Strategic takeaway: deploy strict quality control, dual-sourcing and lead-time clauses when engaging to avoid downstream warranty exposure.
- OEM captive suppliers (Polaris / Indian Motorcycle, BMW Motorrad) —
Major OEMs supplying genuine brackets and relocation kits as OEM parts, often tying brackets into wider accessory ecosystems. Strategic takeaway: for third-party suppliers, OEM channels demand stringent certification and warranty alignment, but they also offer scale and brand halo.
What the PW Consulting report delivers (practical contents)
- Methodology and validated market sizing with year-by-year revenue modeling (historical base and forecast horizon), including sensitivity scenarios linked to material pricing and regulatory shifts.
- A supplier matrix and capability map that classifies players by manufacturing process, material expertise, channel strength (OEM vs aftermarket) and margin archetype.
- Regulatory impact table and recommended test/certification roadmap aligned to major markets and safety standards—designed for product and compliance teams to action in 2026.
- Pricing and cost-to-produce benchmarks, together with a delta-analysis showing the P&L impact of switching materials, processes or geographic sourcing.
- Commercial playbooks for OEM accessory programs, aftermarket scaling, and channel strategies—complete with go-to-market timelines and required investment profiles.
- M&A shortlist and diligence checklist tailored for acquirers seeking bolt-on suppliers or niche premium brands; plus integration risk indicators.
Note: the report intentionally keeps granular regional and application-level figures gated in the full deliverable to preserve their role as strategic, monetizable assets. This release highlights the implications and actionable intelligence without disclosing every segmentation datapoint.
Recommended priorities for 2026 (condensed action plan)
- For OEM product and sourcing teams:
Initiate dual-sourcing pilots for aluminum bracket families, finalize a certified supplier list by Q2, and start regulatory requalification programs ahead of planned model refreshes to avoid launch delays.
- For aftermarket manufacturers and distributors:
Invest in modular, LED-compatible mounting interfaces and expand premium CNC lines targeted at custom builders and e-bike fleets; leverage co-marketing relationships with lighting suppliers.
- For investors and M&A teams:
Prioritize targets offering systems-level integration (lighting + bracket), proven CNC capacity, or distinctive design IP—these attributes compress time-to-value and defend margins.
- For risk and compliance leads:
Map product portfolios against FMVSS 108 and regional equivalents; budget 2026 testing cycles and build supplier audit clauses to enforce compliance and traceability.
Next steps — how to use this intelligence
PW Consulting’s Worldwide Motorcycle Headlight Bracket Market study is designed to be plugged directly into 2026 planning cycles. Management teams can use the modeling workbook to stress-test procurement contracts, sales teams to size accessory campaigns, and corporate development groups to validate acquisition price assumptions.
If your 2026 roadmap includes supplier consolidation, product premiumization, or a shift toward systems-oriented accessory bundles, this study provides the scenario-level foresight and tactical playbooks to execute. For readers wanting the full segmentation, supplier scorecards, and downloadable financial models, the complete report and ancillary datasets are available through PW Consulting’s report page—these elements provide the granular substantiation needed to operationalize the recommendations summarized here.
PW Consulting remains available for bespoke workshops, supplier due diligence, and implementation roadmaps that translate this market intelligence into prioritized 90‑180 day action plans for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Motorcycle Headlight Bracket Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polycarbonate Glazing Market to Climb from USD 1,832.03 Million in 2025 to USD 2,612.42 Million by 2032 at a 5.19% CAGR — Asia Pacific Tops with USD 790.78 Million
By pmarketresearch, 2026-07-15
Worldwide Polycarbonate Glazing Market — Strategic Outlook for 2026: A PW Consulting Perspective
PW Consulting’s latest market study on Worldwide Polycarbonate Glazing provides a focused, decision-ready synthesis designed for executive teams planning for 2026 and beyond. This briefing teases the report’s strategic value: it demonstrates where the market is headed, why it matters to producers, converters, and large end-users, and which tactical moves will preserve margin and market share—while preserving reserve on the granular market splits that require the full report to unlock.
Worldwide Polycarbonate Glazing Market
Market trajectory at a glance
Polycarbonate glazing has entered a sustained expansion phase following the volatility of the early 2020s. After a base-year market size of about USD 1.83 billion in 2025, our model projects growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 5.19%. That trajectory raises the market to an addressable size exceeding USD 2.6 billion by 2032 under the baseline scenario. The path to that outcome has not been linear—historical annual movements between 2020 and 2025 show supply, demand and regulatory drivers pushing and pulling volumes and prices—but the mid-term consensus is constructive.
Worldwide Polycarbonate Glazing Market
Why this matters for 2026 decision cycles
- Volume growth supporting strategic capacity decisions: The projected expansion implies continued demand across glazing categories. For manufacturing and investment committees, this justifies medium-term capital allocation for differentiated capacity—particularly lines capable of producing tailored, higher-margin grades rather than undifferentiated commodity sheeting.
- Margin pressure from feedstock and trade policy: Bisphenol A (BPA) price volatility—especially observed in APAC during 2025—combined with trade policy uncertainty (notably reciprocal tariff moves in the U.S. in 2025), means near-term margins will be compressed for exposed converters and resin suppliers. Hedging strategies, diversification of feedstock sourcing, and near-shoring are valid levers.
- Regulatory-driven product repositioning: Recent EU regulatory changes restricting BPA in food-contact applications have a two-fold effect: they curtail certain legacy end-uses while accelerating demand for low-migration, certified and alternative polycarbonate grades in other sectors, especially architecture and transportation glazing where safety and clarity matter. R&D and regulatory-compliance roadmaps should therefore be prioritized for 2026.
Commercial and product strategy implications
- Premiumization and technical differentiation: As commoditization pressures mount, suppliers that can offer UV-stable, high-clarity, and certified sustainable grades will capture outsized value. Investment in value-added coatings, multi-functional multilayer constructions, and recyclable/ISCC-certified options will be a competitive differentiator.
- Channel and application focus: Construction and automotive glazing remain strategic anchors, but the market is also being shaped by security, transport and controlled-environment agriculture demands. Companies must use a product-by-channel profitability lens rather than a volume-only playbook when allocating sales and application engineering resources for 2026.
- Supply-chain resilience and localization: The combined effect of feedstock swings and trade policy headwinds necessitates a 2026 playbook focused on supply diversification, inventory optimization, and selective near-shoring of critical extrusion capacity.
Competitive landscape — what to watch
Market concentration is meaningful but not prohibitive: the top three players account for roughly two-fifths of the market, and the top five just over half—leaving ample room for regional specialists and technology-focused challengers. Strategic moves in the last 18 months illustrate how leaders are positioning for the coming cycle.
Worldwide Polycarbonate Glazing Market
- Covestro AG (Leverkusen, Germany): With a strong reputation in high-performance Makrolon resins and sheets, Covestro’s recent capacity expansion in Hebron, Ohio, underscores a strategy of tailored grades for automotive, electronics and specialty glazing. For 2026, Covestro’s emphasis on custom formulations and regional capacity should translate into faster response times for OEMs seeking premium glazing solutions.
- SABIC / POLYVANTIS (Riyadh-based heritage): Known for LEXAN products, the integration and product-line innovation under the POLYVANTIS banner—most recently a light-weight, mechanically enhanced LEXAN sheet series—signals a dual play: performance uplift for rail and mobility, and cost-in-use narratives for large-volume construction projects.
- Palram Industries Ltd. (Israel): A strong converter and system supplier, Palram’s focus on a broad portfolio across flat, multiwall and corrugated formats positions it well for construction and agricultural channels where system-level offerings matter as much as raw sheet specs.
- Trinseo and Teijin: Trinseo’s sustainability emphasis and Teijin’s optical/impact grades highlight two adjacent strategies—eco-premium and technical premium. Both are attractive to customers aiming to meet evolving regulatory and performance requirements in 2026.
- Mitsubishi Gas Chemical Company (MGC): MGC’s ISCC PLUS certification for resin production marks a strategic forward step: sustainability credentials are increasingly table stakes in procurement decisions for institutional buyers and large construction contractors.
- Regional converters and specialist suppliers: North American players such as Plaskolite, European sheet specialists like EXOLON, and focused regional manufacturers (e.g., LG Chem, LOTTE) will continue to leverage local channel strength and service orientation to defend margins and secure OEM partnerships.
Recent developments and 2026 implications
- Covestro’s Hebron expansion (Jan 2025): More tailored production capacity in North America reduces lead times for bespoke grades—raising the bar for competitors in vehicle glazing and electronics applications.
- New Indian capacity (Deepak Advanced Materials, Mar 2025): Additional capacity in India increases regional supply flexibility for construction and industrial markets across South Asia—a factor to consider when modeling regional price differentials for 2026 sourcing decisions.
- MGC ISCC PLUS certification (Jun 2024): Certified mass-balance supply enables buyers to meet sustainability commitments with less product differentiation risk—an important procurement lever for large contractors and OEMs in 2026 RFPs.
- POLYVANTIS LEXAN launch (Sep 2024): Material innovations that reduce weight while maintaining mechanical performance will be significant in rail and mobility tenders where lifecycle and energy considerations influence supplier selection.
Regulatory and raw-material dynamics to factor into 2026 planning
- BPA regulation and migration limits: New EU rules enacted in 2025 tighten BPA migration limits and restrict certain food-contact uses. While glazing is largely outside the strictest food-contact restrictions, the regulatory tone accelerates demand for low-migration and alternative chemistries in adjacent applications and raises compliance/OEM scrutiny.
- BPA feedstock volatility: 2025 saw mixed global price trajectories with episodic spikes tied to plant maintenance and restocking. Pricing and procurement strategies for 2026 should include multi-sourcing clauses, hedging windows and flexible long-term contracts.
- Trade policy and tariffs: The 2025 U.S. reciprocal tariff environment—introducing baseline duties affecting imports from multiple origin countries—has tangible implications for cost competitiveness and should influence near-term location and logistics choices.
What the full PW Consulting report provides (practical, action-oriented deliverables)
- Robust market-sizing methodology and reconciled demand-supply balances with scenario outputs for 2026–2032.
- Price-curve and margin-driver models integrating feedstock scenarios, energy costs, and duty regimes.
- Competitive benchmarking and capability matrices for the leading manufacturers and converters, aligned to go-to-market archetypes.
- Regulatory impact assessment with tactical compliance checklists and product-transition pathways for customers and suppliers.
- M&A and partnership playbook including valuation sensitivities for bolt-on assets (regional converters, specialty extrusion lines, coating technologies).
- Commercial templates: tender response frameworks, specification-change roadmaps, and channel segmentation guidance to optimize mix and margin in 2026.
How to use these insights in 2026 planning
Executives should treat the 2026 planning window as a pivot point. Use the macro growth trajectory and scenario outputs to set medium-term capital and R&D budgets. Simultaneously, operational leaders must address near-term margin pressure by optimizing feedstock sourcing, adjusting price ladders for premium grades, and tightening inventory discipline. Commercial teams should re-align account plans to emphasize certification, system solutions, and lifecycle cost narratives rather than unit price alone.
Finally, corporate development teams will find asymmetries in the market: scale provides cost advantages in commodity sheeting, while mid-sized, nimble players retain advantages in specialty grades, rapid customization and close OEM relationships. A deliberate portfolio approach—where capital is directed to differentiated capabilities and partnerships buy access to scale—will outperform blunt capacity expansion strategies.
Next steps and access to the full analysis
This briefing highlights the strategic lines of sight we consider critical for informed 2026 decision-making. PW Consulting’s full Worldwide Polycarbonate Glazing Market report contains the underlying tables, segmented forecasts, supplier scorecards and transaction-playbook details referenced here. To obtain the complete dataset, proprietary segmentation, and supplier-specific appendices required for operational execution, please visit our report page or contact your PW Consulting account representative.
PW Consulting remains available to run custom scenario modeling, integrate client P&L assumptions with the market model, and facilitate supplier diligence or transaction advisory services tailored to your 2026 agenda.
For detailed analysis of this topic, please visit the official page: Worldwide Polycarbonate Glazing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Industrial Bypass Switches Market Poised to Grow at a 5.5% CAGR, Led by Asia Pacific
By pmarketresearch, 2026-07-15
PW Consulting Releases Strategic Brief on the Worldwide Industrial Bypass Switches Market: 2026 Imperatives for Corporate Decision‑Makers
PW Consulting today publishes a forward‑looking strategic brief derived from our upcoming Worldwide Industrial Bypass Switches Market study (base year 2025), designed to inform executive decision‑making as companies set priorities for 2026. The market reached approximately USD 175.5 Million in 2025 and—guided by a projected compound annual growth rate (CAGR) of 5.5%—is modeled to approach USD 255.3 Million by 2032. These headline metrics underline a healthy expansion driven by reliability requirements, the integration of renewables, and the continued acceleration of automation at industrial scale. This release presents high‑value insights and tactical guidance while preserving the report’s proprietary segment-level detail for subscribers and clients seeking the full dataset and interactive models.
Worldwide Industrial Bypass Switches Market
Market Snapshot: Trends Shaping 2026 Choices
From 2020 through 2025 the industrial bypass switch market demonstrated steady recovery and incremental expansion as end users prioritized uptime, maintainability, and safety during increasingly complex power transitions. Three structural dynamics are central to our 2026 outlook:
Worldwide Industrial Bypass Switches Market
- Operational continuity and automation: Demand stems from manufacturing, data center and critical infrastructure operators who require seamless maintenance bypass and fast transfer capabilities to avoid costly downtime.
- Energy transition and grid edge complexity: As renewable generation, energy storage and HV‑DC projects proliferate, bypass switches are specified not only for isolation and maintenance but also as enablers of safe, coordinated switching in hybrid power architectures.
- Input cost and supply chain pressure: Base and industrial metal prices rebounded through 2024–25, and many manufacturers report rising semiconductor and conductor costs. Manufacturers commonly favor copper or aluminum conductors for their performance characteristics, which means procurement strategies for these materials materially affect product cost and margins.
Regulation and standards remain a non‑negotiable design boundary: UL‑1008 testing for three‑cycle closing and withstand performance, along with IEC compliance in many jurisdictions, continue to define acceptable designs for mission‑critical installations. For buyers and specifiers, this means technical compliance is table stakes; differentiators arise in speed, maintenance ergonomics, and safety of isolation mechanisms.
Worldwide Industrial Bypass Switches Market
Competitive Landscape: What the Leader Profiles Tell Us
The market exhibits moderate concentration: established supplier groups capture a material portion of revenue, yet there remain meaningful opportunities for specialized players and newcomers that can combine application‑specific performance with supply reliability. Our corporate benchmarking highlights strategic positioning and near‑term moves worth watching for 2026 planning.
- ABB (Zurich): Strong in mechanical and motorized bypasses with space‑efficient designs. ABB’s breadth across low‑voltage switchgear and its modular product families make it a logical partner for integrated distribution projects where footprint and serviceability matter.
- Eaton (Dublin / US ops): Deep capability in overhead three‑phase and loadbreak solutions for utility and industrial distribution. Eaton’s emphasis on rugged construction and service‑friendly features is a selling point for outdoor and grid‑side applications.
- Siemens / Russelectric (Munich): Emphasizes fast automatic transfer and fail‑safe maintenance bypass designs, with UL‑1008 validation for mission‑critical settings. Recent product highlights from Russelectric signal continued focus on healthcare, data centers and pharmaceutical facilities where certification and fast switching are decisive.
- Socomec (France): Focused on low‑voltage on‑load transfer and bypass solutions with close attention to IEC compliance and infrastructure applications—well suited to customers prioritizing standards conformity and global support networks.
- Miba (Austria): A specialist in very high‑power, fast‑acting bypasses. Miba’s sub‑millisecond closures and high continuous current ratings position it for niche, high‑energy uses such as HV‑DC, MW‑scale renewables and capacitor storage protection.
- S&C Electric (USA): Strong in outdoor distribution‑class devices and station equipment for voltage regulation bypass and isolation—an incumbent choice for utilities and large outdoor substations.
- Cummins & Generac (USA): Both integrate bypass and transfer functionality into broader power generation portfolios, pairing switches with controls and powertrain services to offer turnkey resilience solutions for mission‑critical sites.
- PCE Merz (Germany): German‑engineered UPS and maintenance bypass specialists with flexible actuation designs, appealing to manufacturing and infrastructure customers seeking engineered durability.
Taken together, these profiles show a market where the top handful of vendors account for slightly more than half of demand, but specialized technology providers and vertically integrated power houses continue to capture important pockets of value. Competitive advantage will increasingly depend on speed of switching, ease of maintenance, and the ability to co‑engineer solutions with system integrators and end‑users.
What Our Report Provides — Practical, Actionable Components
The full PW Consulting study goes beyond high‑level market sizing to equip commercial, procurement and technology teams with operational tools for 2026 planning. Key deliverables include:
- Annualized market sizing and demand forecasts (historical 2020–2025; forecast 2026–2032) in USD Million and scenario variants.
- Supply chain and input cost analysis, with exposure maps for copper, aluminum, steel and semiconductor components and recommended hedging/pricing strategies.
- Regulatory and standards matrix (UL‑1008, IEC and regional variants) with compliance checklists for product design and procurement specs.
- Competitive scorecards and supplier maturity assessments covering product breadth, service footprint, and route‑to‑market strengths.
- Buyer decision frameworks and ROI models for selecting bypass switch architectures (manual vs. static vs. automatic) across common industrial use cases—presented without disclosing proprietary segmentation in this summary.
- Capex cycle and end‑user adoption scenarios with sensitivity analyses to raw‑material shocks and equipment‑lifecycle decisions.
- Strategic playbooks for OEMs and new entrants: go‑to‑market, channel strategies, and M&A screening criteria.
- Customizable dashboards and downloadable datasheets for internal workshops and supplier negotiations.
These components are designed to be immediately operational in 2026: procurement teams can adopt the raw‑material exposure playbook; product managers can prioritize high‑speed transfer functionality; and corporate development teams can apply the M&A screening criteria to identify bolt‑on capabilities that complement their thermal, electronic or service portfolios.
Five Strategic Actions for 2026
- Secure flexible material contracts: Negotiate indices‑linked or option‑based arrangements for copper, aluminum and key semiconductors to contain cost volatility and preserve margin.
- Prioritize modular, serviceable designs: Specify or develop bypass switches with accessible maintenance bypasses and draw‑out features that reduce Mean Time To Repair (MTTR) and total cost of ownership.
- Target high‑velocity verticals: Focus sales and product investments on data centers, renewable farms and industrial automation clusters where the value of uptime and rapid transfer is highest.
- Pursue technology partnerships: Co‑develop fast‑acting transfer mechanisms or advanced control integration (e.g., predictive switching/monitoring) with specialist providers to create differentiated offerings.
- Embed compliance and test certainty in procurement: Require UL‑1008 and other relevant certifications as minimums in vendor contracts to reduce execution risk on mission‑critical projects.
Signals to Watch in 2026
Executives should monitor accelerating product announcements from leading transfer switch suppliers and trade presence at major industrial and automation shows—early 2026 developments already include UL‑tested automatic transfer series re‑emphasized by Russelectric and increased exhibition visibility for industrial networking and bypass products at global trade events. These signals suggest intensified competition around certified mission‑critical solutions and tighter integration with automation ecosystems.
Conclusion — Why This Matters for Your 2026 Plan
With a mid‑single digit CAGR and a market trajectory that supports both incremental and disruptive plays, bypass‑switch strategies have become a lever for resilience, customer value and margin expansion. Whether your organization is an OEM, systems integrator, utility, or large industrial user, the tactical choices you make in 2026—on procurement, product architecture, partnerships and compliance—will materially influence your position through the next equipment replacement cycle and beyond.
PW Consulting’s full report contains the granular models, supplier benchmarks and custom scenario tools necessary to convert these insights into executable plans. To access the full dataset, interactive dashboards and tailored advisory options, please visit the official report page for subscription and engagement details. Our team is available for executive briefings and bespoke analyses aligned to your 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Bypass Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com