

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insight: Worldwide Oral Solid Dosage Market Poised for 6.3% CAGR Through 2032

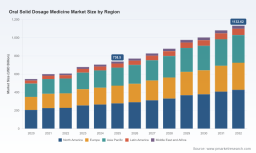
Worldwide Oral Solid Dosage Medicine Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
PW Consulting’s newest market research briefing on the Worldwide Oral Solid Dosage (OSD) medicine market synthesizes a decade-long perspective and a forward-looking operational playbook tailored for 2026 corporate decisions. Built on historical performance (2020–2025) and a proprietary forecasting engine covering 2026–2032, the report frames a market that has grown from the mid‑2020s trajectory to an estimated USD 738.5 Billion in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 6.3% through the forecast window. By 2032, total market value is modeled to exceed USD 1.1 trillion under the base scenario — a scale that demands strategic clarity across manufacturing, sourcing, commercialization and corporate finance.
Worldwide Oral Solid Dosage Medicine Market
Why this report matters for 2026 strategies
-
Timing: 2026 is a pivot year for OSD decision-makers — capital allocation cycles restart, new facilities announced in 2024–2025 begin feeding pipeline choices, and regulatory and supply shocks from prior years remain active. Our analysis identifies when near-term actions will produce outsized returns versus when to defer.
Worldwide Oral Solid Dosage Medicine Market -
Concentration and competition: Market concentration remains relatively low (CR3 ≈ 18.4%, CR5 ≈ 24.5%), indicating fragmentation and room for strategic consolidation, vertical integration, and specialist CDMO expansion.
Worldwide Oral Solid Dosage Medicine Market -
Scale and velocity: With a multi‑hundred‑billion USD market expanding at mid-single digits CAGR, both incumbents and challengers must reconcile volume-driven generics economics alongside high-margin branded OSD launches and specialty small-molecule therapies.
-
Operational urgency: End-to-end supply resilience, raw-material sourcing strategies, and modular capacity expansion are now non‑negotiable components of commercial planning.
What’s inside: practical, decision-grade content
The report is structured to move executives from high‑level market understanding to immediate, actionable steps. Key deliverables include:
-
Proprietary total‑market forecast model (2020–2032) with scenario toggles for pricing, patent expiry timing, and supply disruption intensity — designed to feed board-level capital allocation and annual operating plans.
-
Scenario playbooks (best case / base case / stress case) that quantify revenue and margin sensitivity to generic erosion, excipient shortages, tariffs, and new‑capacity ramp schedules.
-
Manufacturing and CDMO opportunity maps that identify where to invest, partner, or divest based on technology fit (e.g., continuous manufacturing, high‑potency handling, orally disintegrating tablets), time to market, and regulatory complexity.
-
Supply‑chain resilience toolkit: dual‑sourcing matrices, critical‑excipient single‑point‑failure audits, and an implementation timeline for transitioning from single to dual qualified suppliers without disrupting regulatory filings.
-
Regulatory and shortage risk matrix with prioritized mitigations — includes practical procurement hedges, buffer stock policies, and government engagement templates for jurisdictions experiencing product shortages.
-
Pricing & reimbursement playbook for managing post‑patent pricing pressure, tender‑market dynamics and cost‑plus negotiations with payers and large group purchasers.
-
M&A and partnership readiness checklist for both strategics and financial sponsors seeking to consolidate manufacturing assets or scale CDMO platforms.
-
CapEx prioritization framework tying facility investments to expected return windows, product life‑cycle phasing and optionality for modular expansion.
Competitive landscape: what leading players are signaling
The OSD ecosystem in 2026 is best characterized as a two‑tiered competitive environment: large, integrated pharmaceutical companies that retain sizeable in‑house OSD manufacturing capabilities, and a robust, fragmented CDMO and generics community that provides capacity, technical specialization and route‑to‑market agility.
-
Integrated majors (Pfizer, Merck, Johnson & Johnson, AbbVie, AstraZeneca, Sanofi, GSK, Novartis, Eli Lilly): These players continue to secure control of critical parts of the value chain. Recent landmark commitments — including multi‑billion dollar manufacturing investments announced by select firms — demonstrate a strategic preference for end‑to‑end control in key markets and therapeutic categories. Such investments are aimed at shortening supply chains, protecting IP-sensitive processes and ensuring prioritized manufacturing for strategic brands.
-
CDMOs and generics manufacturers (Teva, Catalent, Lonza, Aenova, Recipharm, Piramal, Thermo Fisher/Patheon, Jubilant, Siegfried, CordenPharma, LGM Pharma): These firms are expanding capability sets and capacity with focused capital allocations. Examples include recent facility expansions and partnerships that enable specialized OSD forms (multi‑layer tablets, high‑potency handling, orally disintegrating tablets), and phased investments that de‑risk capacity builds for niche, high‑value products.
-
Strategic implications: Integrated players will selectively insource where control over supply, quality and speed-to-market are mission critical; conversely, mid‑size pharma and many originators will continue to rely on CDMOs for flexible capacity, technical know‑how and cost optimization. For CDMOs, the runway is favorable — but success will hinge on differentiated capabilities, regulatory reliability, and execution speed.
Market dynamics shaping near‑term decisions
-
Supply disruptions and shortages: While reported drug shortages declined from recent peaks, availability remains elevated versus pre‑2020 norms. Shortage episodes continue to enforce premium pricing on prioritized products and force manufacturers into contingency inventory and qualification cycles.
-
Patent expirations and generic erosion: A concentrated set of small‑molecule patent expiries over the 2025–2030 window implies substantial revenue erosion for originators, accelerating the need to roadmap lifecycle strategies — from line extensions to authorized generics and new formulation patents.
-
Raw‑material volatility: Documented excipient supply issues have been material contributors to shortages, underlining the commercial importance of supplier diversification and earlier qualifying timelines for alternative excipients.
-
Trade and tariff risk: Policy shifts affecting APIs and intermediate imports can rapidly reshape cost structures for generics and create short to mid-term reshoring incentives for specialty OSD lines.
Actionable recommendations for 2026 leaders
-
Embed supply resilience in the KPIs that drive capital allocation. Prioritize investments that reduce single‑point failures (dual qualifying critical excipients; geographically diversified packaging lines).
-
Use a scenario‑based capital review for any new facility. Validate investments against stress cases that assume accelerated generic entry and 25–40% price compression in tender markets.
-
For originators facing near‑term patent cliffs, plan multi‑track defense strategies: authorized generics, reformulation/line extensions, selective divestiture of commodity OSD SKUs, and fast follow manufacturing partnerships.
-
CDMO strategy: invest in narrowly differentiated capabilities where regulatory entry barriers and technical complexity justify price premiums (e.g., multi‑layer tablets, high‑potency handling, or rapidly disintegrating formats).
-
Operationalize excipient risk management — not as a procurement checkbox but as a continuous manufacturing readiness program with qualification triggers tied to demand surge scenarios.
-
Leverage modular, digitalized manufacturing technologies (continuous manufacturing, PAT) to compress time-to-scale and reduce working capital intensity on inventory buffers.
-
Align commercial teams and manufacturing planners through integrated S&OP that explicitly models generic erosion, shortage probabilities and contract manufacturing capacity constraints.
-
Consider selective M&A to accelerate capability acquisition and geographic footprint consolidation — the current fragmentation creates favorable acquisition entry points but requires rigorous integration playbooks.
Closing: where to go next
This briefing outlines the strategic levers that matter for 2026 and beyond. PW Consulting’s full Worldwide Oral Solid Dosage Medicine Market report contains the underlying datasets, detailed sub‑segment forecasts, country‑level scenarios, and downloadable tools referenced above. The report’s downloadable appendices include the full time‑series model, contractual sourcing templates, and an executable 18‑month implementation plan for manufacturing and supply‑chain interventions — intentionally withheld here to preserve the value proposition of the full report.
For executives ready to convert insight into action, PW Consulting offers tailored workshops and model integrations that adapt the report’s scenarios to your P&L and balance‑sheet realities. Contact our industry team to schedule a strategic briefing and to access the complete dataset and interactive forecasting tool.
For detailed analysis of this topic, please visit the official page: Worldwide Oral Solid Dosage Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com