

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
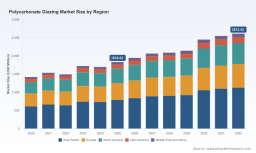
PW Consulting: Polycarbonate Glazing Market to Climb from USD 1,832.03 Million in 2025 to USD 2,612.42 Million by 2032 at a 5.19% CAGR — Asia Pacific Tops with USD 790.78 Million

Worldwide Polycarbonate Glazing Market — Strategic Outlook for 2026: A PW Consulting Perspective
PW Consulting’s latest market study on Worldwide Polycarbonate Glazing provides a focused, decision-ready synthesis designed for executive teams planning for 2026 and beyond. This briefing teases the report’s strategic value: it demonstrates where the market is headed, why it matters to producers, converters, and large end-users, and which tactical moves will preserve margin and market share—while preserving reserve on the granular market splits that require the full report to unlock.
Worldwide Polycarbonate Glazing Market
Market trajectory at a glance
Polycarbonate glazing has entered a sustained expansion phase following the volatility of the early 2020s. After a base-year market size of about USD 1.83 billion in 2025, our model projects growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 5.19%. That trajectory raises the market to an addressable size exceeding USD 2.6 billion by 2032 under the baseline scenario. The path to that outcome has not been linear—historical annual movements between 2020 and 2025 show supply, demand and regulatory drivers pushing and pulling volumes and prices—but the mid-term consensus is constructive.
Worldwide Polycarbonate Glazing Market
Why this matters for 2026 decision cycles
- Volume growth supporting strategic capacity decisions: The projected expansion implies continued demand across glazing categories. For manufacturing and investment committees, this justifies medium-term capital allocation for differentiated capacity—particularly lines capable of producing tailored, higher-margin grades rather than undifferentiated commodity sheeting.
- Margin pressure from feedstock and trade policy: Bisphenol A (BPA) price volatility—especially observed in APAC during 2025—combined with trade policy uncertainty (notably reciprocal tariff moves in the U.S. in 2025), means near-term margins will be compressed for exposed converters and resin suppliers. Hedging strategies, diversification of feedstock sourcing, and near-shoring are valid levers.
- Regulatory-driven product repositioning: Recent EU regulatory changes restricting BPA in food-contact applications have a two-fold effect: they curtail certain legacy end-uses while accelerating demand for low-migration, certified and alternative polycarbonate grades in other sectors, especially architecture and transportation glazing where safety and clarity matter. R&D and regulatory-compliance roadmaps should therefore be prioritized for 2026.
Commercial and product strategy implications
- Premiumization and technical differentiation: As commoditization pressures mount, suppliers that can offer UV-stable, high-clarity, and certified sustainable grades will capture outsized value. Investment in value-added coatings, multi-functional multilayer constructions, and recyclable/ISCC-certified options will be a competitive differentiator.
- Channel and application focus: Construction and automotive glazing remain strategic anchors, but the market is also being shaped by security, transport and controlled-environment agriculture demands. Companies must use a product-by-channel profitability lens rather than a volume-only playbook when allocating sales and application engineering resources for 2026.
- Supply-chain resilience and localization: The combined effect of feedstock swings and trade policy headwinds necessitates a 2026 playbook focused on supply diversification, inventory optimization, and selective near-shoring of critical extrusion capacity.
Competitive landscape — what to watch
Market concentration is meaningful but not prohibitive: the top three players account for roughly two-fifths of the market, and the top five just over half—leaving ample room for regional specialists and technology-focused challengers. Strategic moves in the last 18 months illustrate how leaders are positioning for the coming cycle.
Worldwide Polycarbonate Glazing Market
- Covestro AG (Leverkusen, Germany): With a strong reputation in high-performance Makrolon resins and sheets, Covestro’s recent capacity expansion in Hebron, Ohio, underscores a strategy of tailored grades for automotive, electronics and specialty glazing. For 2026, Covestro’s emphasis on custom formulations and regional capacity should translate into faster response times for OEMs seeking premium glazing solutions.
- SABIC / POLYVANTIS (Riyadh-based heritage): Known for LEXAN products, the integration and product-line innovation under the POLYVANTIS banner—most recently a light-weight, mechanically enhanced LEXAN sheet series—signals a dual play: performance uplift for rail and mobility, and cost-in-use narratives for large-volume construction projects.
- Palram Industries Ltd. (Israel): A strong converter and system supplier, Palram’s focus on a broad portfolio across flat, multiwall and corrugated formats positions it well for construction and agricultural channels where system-level offerings matter as much as raw sheet specs.
- Trinseo and Teijin: Trinseo’s sustainability emphasis and Teijin’s optical/impact grades highlight two adjacent strategies—eco-premium and technical premium. Both are attractive to customers aiming to meet evolving regulatory and performance requirements in 2026.
- Mitsubishi Gas Chemical Company (MGC): MGC’s ISCC PLUS certification for resin production marks a strategic forward step: sustainability credentials are increasingly table stakes in procurement decisions for institutional buyers and large construction contractors.
- Regional converters and specialist suppliers: North American players such as Plaskolite, European sheet specialists like EXOLON, and focused regional manufacturers (e.g., LG Chem, LOTTE) will continue to leverage local channel strength and service orientation to defend margins and secure OEM partnerships.
Recent developments and 2026 implications
- Covestro’s Hebron expansion (Jan 2025): More tailored production capacity in North America reduces lead times for bespoke grades—raising the bar for competitors in vehicle glazing and electronics applications.
- New Indian capacity (Deepak Advanced Materials, Mar 2025): Additional capacity in India increases regional supply flexibility for construction and industrial markets across South Asia—a factor to consider when modeling regional price differentials for 2026 sourcing decisions.
- MGC ISCC PLUS certification (Jun 2024): Certified mass-balance supply enables buyers to meet sustainability commitments with less product differentiation risk—an important procurement lever for large contractors and OEMs in 2026 RFPs.
- POLYVANTIS LEXAN launch (Sep 2024): Material innovations that reduce weight while maintaining mechanical performance will be significant in rail and mobility tenders where lifecycle and energy considerations influence supplier selection.
Regulatory and raw-material dynamics to factor into 2026 planning
- BPA regulation and migration limits: New EU rules enacted in 2025 tighten BPA migration limits and restrict certain food-contact uses. While glazing is largely outside the strictest food-contact restrictions, the regulatory tone accelerates demand for low-migration and alternative chemistries in adjacent applications and raises compliance/OEM scrutiny.
- BPA feedstock volatility: 2025 saw mixed global price trajectories with episodic spikes tied to plant maintenance and restocking. Pricing and procurement strategies for 2026 should include multi-sourcing clauses, hedging windows and flexible long-term contracts.
- Trade policy and tariffs: The 2025 U.S. reciprocal tariff environment—introducing baseline duties affecting imports from multiple origin countries—has tangible implications for cost competitiveness and should influence near-term location and logistics choices.
What the full PW Consulting report provides (practical, action-oriented deliverables)
- Robust market-sizing methodology and reconciled demand-supply balances with scenario outputs for 2026–2032.
- Price-curve and margin-driver models integrating feedstock scenarios, energy costs, and duty regimes.
- Competitive benchmarking and capability matrices for the leading manufacturers and converters, aligned to go-to-market archetypes.
- Regulatory impact assessment with tactical compliance checklists and product-transition pathways for customers and suppliers.
- M&A and partnership playbook including valuation sensitivities for bolt-on assets (regional converters, specialty extrusion lines, coating technologies).
- Commercial templates: tender response frameworks, specification-change roadmaps, and channel segmentation guidance to optimize mix and margin in 2026.
How to use these insights in 2026 planning
Executives should treat the 2026 planning window as a pivot point. Use the macro growth trajectory and scenario outputs to set medium-term capital and R&D budgets. Simultaneously, operational leaders must address near-term margin pressure by optimizing feedstock sourcing, adjusting price ladders for premium grades, and tightening inventory discipline. Commercial teams should re-align account plans to emphasize certification, system solutions, and lifecycle cost narratives rather than unit price alone.
Finally, corporate development teams will find asymmetries in the market: scale provides cost advantages in commodity sheeting, while mid-sized, nimble players retain advantages in specialty grades, rapid customization and close OEM relationships. A deliberate portfolio approach—where capital is directed to differentiated capabilities and partnerships buy access to scale—will outperform blunt capacity expansion strategies.
Next steps and access to the full analysis
This briefing highlights the strategic lines of sight we consider critical for informed 2026 decision-making. PW Consulting’s full Worldwide Polycarbonate Glazing Market report contains the underlying tables, segmented forecasts, supplier scorecards and transaction-playbook details referenced here. To obtain the complete dataset, proprietary segmentation, and supplier-specific appendices required for operational execution, please visit our report page or contact your PW Consulting account representative.
PW Consulting remains available to run custom scenario modeling, integrate client P&L assumptions with the market model, and facilitate supplier diligence or transaction advisory services tailored to your 2026 agenda.
For detailed analysis of this topic, please visit the official page: Worldwide Polycarbonate Glazing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com