

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Industrial Bypass Switches Market Poised to Grow at a 5.5% CAGR, Led by Asia Pacific

PW Consulting Releases Strategic Brief on the Worldwide Industrial Bypass Switches Market: 2026 Imperatives for Corporate Decision‑Makers
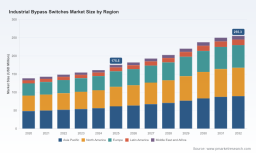
PW Consulting today publishes a forward‑looking strategic brief derived from our upcoming Worldwide Industrial Bypass Switches Market study (base year 2025), designed to inform executive decision‑making as companies set priorities for 2026. The market reached approximately USD 175.5 Million in 2025 and—guided by a projected compound annual growth rate (CAGR) of 5.5%—is modeled to approach USD 255.3 Million by 2032. These headline metrics underline a healthy expansion driven by reliability requirements, the integration of renewables, and the continued acceleration of automation at industrial scale. This release presents high‑value insights and tactical guidance while preserving the report’s proprietary segment-level detail for subscribers and clients seeking the full dataset and interactive models.
Worldwide Industrial Bypass Switches Market
Market Snapshot: Trends Shaping 2026 Choices
From 2020 through 2025 the industrial bypass switch market demonstrated steady recovery and incremental expansion as end users prioritized uptime, maintainability, and safety during increasingly complex power transitions. Three structural dynamics are central to our 2026 outlook:
Worldwide Industrial Bypass Switches Market
- Operational continuity and automation: Demand stems from manufacturing, data center and critical infrastructure operators who require seamless maintenance bypass and fast transfer capabilities to avoid costly downtime.
- Energy transition and grid edge complexity: As renewable generation, energy storage and HV‑DC projects proliferate, bypass switches are specified not only for isolation and maintenance but also as enablers of safe, coordinated switching in hybrid power architectures.
- Input cost and supply chain pressure: Base and industrial metal prices rebounded through 2024–25, and many manufacturers report rising semiconductor and conductor costs. Manufacturers commonly favor copper or aluminum conductors for their performance characteristics, which means procurement strategies for these materials materially affect product cost and margins.
Regulation and standards remain a non‑negotiable design boundary: UL‑1008 testing for three‑cycle closing and withstand performance, along with IEC compliance in many jurisdictions, continue to define acceptable designs for mission‑critical installations. For buyers and specifiers, this means technical compliance is table stakes; differentiators arise in speed, maintenance ergonomics, and safety of isolation mechanisms.
Worldwide Industrial Bypass Switches Market
Competitive Landscape: What the Leader Profiles Tell Us
The market exhibits moderate concentration: established supplier groups capture a material portion of revenue, yet there remain meaningful opportunities for specialized players and newcomers that can combine application‑specific performance with supply reliability. Our corporate benchmarking highlights strategic positioning and near‑term moves worth watching for 2026 planning.
- ABB (Zurich): Strong in mechanical and motorized bypasses with space‑efficient designs. ABB’s breadth across low‑voltage switchgear and its modular product families make it a logical partner for integrated distribution projects where footprint and serviceability matter.
- Eaton (Dublin / US ops): Deep capability in overhead three‑phase and loadbreak solutions for utility and industrial distribution. Eaton’s emphasis on rugged construction and service‑friendly features is a selling point for outdoor and grid‑side applications.
- Siemens / Russelectric (Munich): Emphasizes fast automatic transfer and fail‑safe maintenance bypass designs, with UL‑1008 validation for mission‑critical settings. Recent product highlights from Russelectric signal continued focus on healthcare, data centers and pharmaceutical facilities where certification and fast switching are decisive.
- Socomec (France): Focused on low‑voltage on‑load transfer and bypass solutions with close attention to IEC compliance and infrastructure applications—well suited to customers prioritizing standards conformity and global support networks.
- Miba (Austria): A specialist in very high‑power, fast‑acting bypasses. Miba’s sub‑millisecond closures and high continuous current ratings position it for niche, high‑energy uses such as HV‑DC, MW‑scale renewables and capacitor storage protection.
- S&C Electric (USA): Strong in outdoor distribution‑class devices and station equipment for voltage regulation bypass and isolation—an incumbent choice for utilities and large outdoor substations.
- Cummins & Generac (USA): Both integrate bypass and transfer functionality into broader power generation portfolios, pairing switches with controls and powertrain services to offer turnkey resilience solutions for mission‑critical sites.
- PCE Merz (Germany): German‑engineered UPS and maintenance bypass specialists with flexible actuation designs, appealing to manufacturing and infrastructure customers seeking engineered durability.
Taken together, these profiles show a market where the top handful of vendors account for slightly more than half of demand, but specialized technology providers and vertically integrated power houses continue to capture important pockets of value. Competitive advantage will increasingly depend on speed of switching, ease of maintenance, and the ability to co‑engineer solutions with system integrators and end‑users.
What Our Report Provides — Practical, Actionable Components
The full PW Consulting study goes beyond high‑level market sizing to equip commercial, procurement and technology teams with operational tools for 2026 planning. Key deliverables include:
- Annualized market sizing and demand forecasts (historical 2020–2025; forecast 2026–2032) in USD Million and scenario variants.
- Supply chain and input cost analysis, with exposure maps for copper, aluminum, steel and semiconductor components and recommended hedging/pricing strategies.
- Regulatory and standards matrix (UL‑1008, IEC and regional variants) with compliance checklists for product design and procurement specs.
- Competitive scorecards and supplier maturity assessments covering product breadth, service footprint, and route‑to‑market strengths.
- Buyer decision frameworks and ROI models for selecting bypass switch architectures (manual vs. static vs. automatic) across common industrial use cases—presented without disclosing proprietary segmentation in this summary.
- Capex cycle and end‑user adoption scenarios with sensitivity analyses to raw‑material shocks and equipment‑lifecycle decisions.
- Strategic playbooks for OEMs and new entrants: go‑to‑market, channel strategies, and M&A screening criteria.
- Customizable dashboards and downloadable datasheets for internal workshops and supplier negotiations.
These components are designed to be immediately operational in 2026: procurement teams can adopt the raw‑material exposure playbook; product managers can prioritize high‑speed transfer functionality; and corporate development teams can apply the M&A screening criteria to identify bolt‑on capabilities that complement their thermal, electronic or service portfolios.
Five Strategic Actions for 2026
- Secure flexible material contracts: Negotiate indices‑linked or option‑based arrangements for copper, aluminum and key semiconductors to contain cost volatility and preserve margin.
- Prioritize modular, serviceable designs: Specify or develop bypass switches with accessible maintenance bypasses and draw‑out features that reduce Mean Time To Repair (MTTR) and total cost of ownership.
- Target high‑velocity verticals: Focus sales and product investments on data centers, renewable farms and industrial automation clusters where the value of uptime and rapid transfer is highest.
- Pursue technology partnerships: Co‑develop fast‑acting transfer mechanisms or advanced control integration (e.g., predictive switching/monitoring) with specialist providers to create differentiated offerings.
- Embed compliance and test certainty in procurement: Require UL‑1008 and other relevant certifications as minimums in vendor contracts to reduce execution risk on mission‑critical projects.
Signals to Watch in 2026
Executives should monitor accelerating product announcements from leading transfer switch suppliers and trade presence at major industrial and automation shows—early 2026 developments already include UL‑tested automatic transfer series re‑emphasized by Russelectric and increased exhibition visibility for industrial networking and bypass products at global trade events. These signals suggest intensified competition around certified mission‑critical solutions and tighter integration with automation ecosystems.
Conclusion — Why This Matters for Your 2026 Plan
With a mid‑single digit CAGR and a market trajectory that supports both incremental and disruptive plays, bypass‑switch strategies have become a lever for resilience, customer value and margin expansion. Whether your organization is an OEM, systems integrator, utility, or large industrial user, the tactical choices you make in 2026—on procurement, product architecture, partnerships and compliance—will materially influence your position through the next equipment replacement cycle and beyond.
PW Consulting’s full report contains the granular models, supplier benchmarks and custom scenario tools necessary to convert these insights into executable plans. To access the full dataset, interactive dashboards and tailored advisory options, please visit the official report page for subscription and engagement details. Our team is available for executive briefings and bespoke analyses aligned to your 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Bypass Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com