

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Musk Aroma Chemicals Market Poised for 4.25% CAGR Expansion
By pmarketresearch, 2026-07-15
Worldwide Musk Aroma Chemicals Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s new market study on Worldwide Musk Aroma Chemicals furnishes senior executives, R&D leaders, procurement heads and corporate strategists with the forward-looking intelligence required to make high‑stakes decisions in 2026. Grounded in a robust historical review (2020–2025) and a detailed forecast (2026–2032), the study translates macro trends, regulatory dynamics, and supplier strategies into concrete options for action. The overall market stood at approximately USD 1.15 billion in the 2025 base year and, under our base-case assumptions, is projected to expand at a compound annual growth rate (CAGR) of 4.25% across the forecast window—reaching a materially larger market by 2032.
Worldwide Musk Aroma Chemicals Market
Key market snapshot
-
Market trajectory: After a period of volatility in the early 2020s, the musk aroma chemicals market has stabilized with modest expansion driven by reformulation demand, new biodegradable chemistries, and resilient end‑use applications.
Worldwide Musk Aroma Chemicals Market -
Growth drivers: Regulatory-driven reformulation, the shift to biodegradable macrocyclic chemistries, and investment in biotech-enabled supply are the primary structural forces underpinning the mid-term growth outlook.
Worldwide Musk Aroma Chemicals Market -
Concentration and competitive dynamics: The market remains moderately consolidated—top incumbents retain meaningful share and technical advantage, shaping access to advanced musk chemistries and production capacity.
Why this matters in 2026
-
Regulatory compliance is no longer an operational checkbox. IFRA amendments and REACH tightening are actively redefining permissible ingredient sets, timelines for compliance, and documentation requirements—creating both risks and first-mover advantages.
-
Sustainability claims are now commercial requirements. Brand customers increasingly expect validated biodegradability and low-environmental persistence attributes, raising the bar for raw material selection and supplier transparency.
-
Supply-chain resilience will be a differentiator. Capacity expansions, regional manufacturing footprints, and vertical integration by major suppliers will alter spot availability and negotiation leverage for buyers in 2026.
What the PW Consulting report delivers (practical, execution-focused)
-
Transparent market sizing and vintage-aware demand curves: Our methodology reconciles historical shipments, manufacturer capacity, and downstream consumption to produce a defensible top‑line baseline and alternative scenarios.
-
Regulatory impact matrix and reformulation playbook: We quantify the likely reformulation lift by product category, provide a decision matrix for substituting legacy musks with macrocyclic or biodegradable options, and outline validation testing timelines.
-
Supplier and capability benchmark: Proprietary scoring across technology, regulatory expertise, capacity flexibility, and price competitiveness—designed to inform preferred‑supplier selection and dual‑sourcing strategies.
-
Cost curve and margin stress tests: Line‑item models highlight how feedstock price shocks, compliance costs, and scaling of new processes affect delivered cost and gross margins across typical customer contracts.
-
M&A and capex playbooks: Prioritized acquisition targets, capability gaps suited for bolt‑on M&A, and an investment sequencing guide for new manufacturing lines or licensing of proprietary biodegradable musks.
-
Commercial and innovation roadmaps: Go‑to‑market approaches for launching sustainable musk variants, including claim substantiation, partner roles, and expected trade‑off timelines between performance and cost.
Competitive landscape — what incumbents are doing and what it means
The sector remains dominated by established fragrance houses and specialty chemical producers that combine formulation expertise with production capabilities. Our competitive analysis synthesizes public disclosures, capacity announcements, and product positioning to highlight strategic plays that matter for 2026 planning.
-
Givaudan (Vernier, Switzerland) — As a global leader, Givaudan leverages a broad portfolio of synthetic and macrocyclic musk ingredients and emphasizes biodegradable, regulatory‑compliant variants. For buyers, Givaudan’s depth in fixatives and formulation services means faster route-to-market for reformulated SKUs but typically at a premium and with longer-term contract expectations.
-
dsm‑firmenich (Switzerland) — The company has signaled a decisive move into sustainable musks: in 2024 it commissioned new facilities focused on biodegradable ingredients such as Habanolide. This capacity expansion materially reduces lead‑time risk for biodegradable chemistries and raises competitive pressure on legacy polycyclic suppliers.
-
Symrise AG (Germany) — Symrise continues to invest in performance innovation and regulatory compliance, prioritizing formulations tailored to personal care and fine fragrance customers. Their approach favors iterative product upgrades and strong regulatory dossiers—an attractive profile for players seeking low‑friction substitution.
-
International Flavors & Fragrances (IFF, USA) — IFF’s integrated supply-chain and biotechnology investments target cost-effective, high‑performance musk fixatives. For mid‑sized and large buyers, IFF’s biotech plays could lower total cost of ownership for premium musk variants if scale-up succeeds on timelines.
-
MANE, Takasago, PFW, LANXESS, SODA AROMATIC, Privi, Robertet — These firms span family‑owned niche innovators, regional-scale producers, and specialty chemical houses. Their strategic positions range from proprietary macrocyclic syntheses and niche perfumery capabilities to cost‑competitive supply for commodity applications. Robertet and other nature‑focused players are accelerating bio‑based or nature‑identical alternatives, which will increasingly compete on validated sustainability credentials.
Regulatory and raw‑material realities shaping strategy
-
IFRA’s 51st Amendment and related regulatory actions introduce concrete concentration limits and compliance deadlines that compel reformulation or product withdrawal in some cases. Companies must map exposure by SKU and customer segment and prioritize compliance pathways.
-
REACH and regional legislations continue to restrict legacy nitro musks and certain polycyclic chemistries, accelerating spend toward macrocyclic and biodegradable options. This regulatory tightening changes the economics of ingredient selection and increases upfront R&D and analytical costs.
-
Synthetic musks still supply the large majority of market demand—on the order of around four‑fifths—driven by cost efficiency, consistent quality, and regulatory adaptability compared to natural extracts. However, the marginal growth in the forecast period is captured increasingly by next‑generation, lower‑persistence chemistries.
Strategic playbook — prioritized actions for 2026
-
Perform a SKU‑level regulatory exposure audit within Q1‑2026. Map which compositions require reformulation, the expected compliance cost, and customer notification timelines.
-
Initiate dual‑sourcing contracts for critical musk classes and demand contractual commitments on allocation and price‑stabilization mechanisms to mitigate capacity dislocations.
-
Accelerate pilot programs with biodegradable macrocyclic providers—particularly those with demonstrated scale plans—to secure first‑mover shelf space with key brand customers.
-
Recalibrate procurement and pricing models: include compliance cost pass‑through clauses, and stress‑test margins against raw material and regulatory cost shocks using the report’s scenario templates.
-
Build an M&A watchlist focusing on smaller specialty firms with validated bio‑based musk patents or niche synthesis routes that complement larger manufacturers’ portfolios.
-
Invest in dossier quality and third‑party validation to underpin sustainability claims; this reduces trade friction and supports faster acceptance by global customers and regulators.
Scenario planning & financial modeling included in the study
The report contains three rigorously built scenarios—base, regulatory shock, and technology acceleration—each with projected top‑line, margin, and capex implications through 2032. We present breakpoint analyses showing when to accelerate capital investment in dedicated biodegradable lines versus when to seek tolling or licensing arrangements. Our models enable CFOs to quantify payback periods for capex under various adoption and pricing paths, and provide procurement teams with hedging thresholds to guide long‑term supplier contracts.
How to use this intelligence in boardroom decisions
-
Align R&D roadmaps with regulatory timelines. Use the report’s reformulation playbook to set a prioritized three‑year R&D calendar tied to customer launch windows.
-
Inform M&A and partnership discussions with the scorecards and target filters provided—focus on capability stretch rather than revenue lift alone.
-
Embed the scenario outputs into capital allocation processes to decide whether 2026 is the year to commit to new manufacturing lines, licensing, or strategic offtake agreements.
PW Consulting’s Worldwide Musk Aroma Chemicals Market study is intentionally structured as a decision‑enablement tool. The narrative in this release outlines the strategic contours; the full report contains the proprietary datasets, supplier scorecards, and executable playbooks that operational teams and boards need to act confidently in 2026. To access the complete analysis, proprietary spreadsheets, and a tailored briefing for your executive team, visit PW Consulting’s reports page or contact our industry leads for a confidential walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Musk Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Pro Microphone Market Poised to Grow at a 6.01% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Pro Microphone Market — Strategic Preview for 2026 Decisions
PW Consulting today releases an executive preview of our forthcoming Worldwide Pro Microphone Market report. Built on a 2020–2025 historical audit and a 2026–2032 forecast horizon (base year: 2025), this analysis distils the structural shifts, competitive dynamics, and supply-chain fault lines that will shape vendor and buyer choices in 2026. The full report (USD, revenue expressed in Million) provides the granular segmentation, market-share tables, and scenario models required for transaction-grade decision-making; this preview highlights the strategic implications while intentionally withholding core segment-level details to encourage direct access to the full intelligence pack.
Worldwide Pro Microphone Market
Market Trajectory at a Glance
- Base year: 2025 (latest audited market snapshot).
- Forecast period: 2026–2032, with a compound annual growth rate (CAGR) of 6.01% across the period.
- Recent trend: a robust recovery and expansion from 2020 through 2025, reflecting a combination of live-event resurgence, continued studio and content-creation investment, and product innovation in wireless and networked audio.
For executives preparing 2026 budgets, the headline numbers matter: the pro microphone market has moved from a pandemic-constrained base to a multi‑billion-dollar global opportunity. Our scenario models anticipate continued growth into 2032, driven by product premiumization, workflow integration (DSP, network audio), and increasing spend across new content-creation verticals.
Worldwide Pro Microphone Market
Why this report matters for 2026 decision cycles
- Timing: 2026 is a strategic inflection point. Capital investment cycles initiated in 2023–2025 now reach procurement and go-to-market execution; suppliers and buyers will reprice portfolios, reconfigure supply chains, and set roadmap priorities.
- Actionability: The report translates macro forecasts into operational imperatives — SKU rationalization, component hedging, contract-tiering for OEMs, and channel segmentation for distributors.
- M&A and partnerships: With market concentration metrics showing a mid-to-high level of top-firm dominance, the intelligence identifies whitespace for bolt-on acquisitions, IP licensing, and distribution alliances that are likely to accelerate value creation in 2026.
Key market dynamics shaping supplier and buyer strategy
- Product innovation is accelerating along three axes: wireless systems with improved RF resilience and spectrum efficiency; embedded DSP and hybrid analog/digital signal chains; and miniaturization for livestreaming, podcasting, and immersive audio capture. Recent product launches underscore this trend (e.g., leading manufacturers introducing new wireless vocal systems, next‑generation studio condensers with DSP, and Dante-enabled conferencing boundary microphones).
- Supply-chain and raw-material volatility: neodymium oxide price pressure (average price point observed in 2023) and concentration in refined rare-earth production (majority share originating from a single country) create procurement risk for dynamic-microphone magnets and certain actuator subsystems. Concurrently, electronic component lead times (capacitors, ICs) averaged multiple months in late 2023, impacting time-to-market and NPI cadence.
- Regulatory and trade exposure: RoHS compliance remains a baseline requirement in key markets; tariffs (notably Section 301 duties on certain imports) materially alter landed cost calculations for import-dependent players and influence localization strategies.
- Channel shifts: Direct-to-creator channels, subscription bundled hardware/software models, and hybrid distribution combine to compress traditional distributor margins while expanding addressable markets in conferencing, e‑sports, and creator ecosystems.
- Concentration and competitive dynamics: the market shows a moderate concentration pattern among top vendors (CR3 and CR5 metrics indicate several leading firms control a meaningful share of the market). This balance creates both defensive incumbent strategies (brand, service networks) and opportunistic plays for challengers focused on niche performance, price, or integrated tech stacks.
Competitive landscape — what to watch in 2026
The pro microphone ecosystem blends heritage engineering houses with newer, digitally-native entrants. PW Consulting’s competitive framework evaluates firms across product breadth (condenser, dynamic, wireless, specialty), technological differentiation (DSP, digital interfaces, miniaturization), supply-chain control (magnet sourcing, capsule manufacturing), and go-to-market channels (pro audio, broadcast, content-creator retail, enterprise conferencing).
Worldwide Pro Microphone Market
- Heritage engineering leaders maintain defensive advantages through deep catalogues, channel trust, and studio credentials. These firms are investing selectively in wireless and DSP to protect high-margin segments.
- Specialist high‑end manufacturers continue to command premium pricing in studio and broadcast markets; their roadmap choices emphasize capsule quality and pro-audio fidelity over cost optimization.
- Challengers and digital-first brands are expanding share by delivering targeted solutions for creators and remote work: lower-cost, feature-rich condensers and USB/network-enabled products that undercut incumbents on convenience and platform integration.
- Recent product milestones (new studio condensers with ultra-low self-noise, wireless dual-diaphragm systems, networked boundary mics, and subminiature lavaliers with improved moisture resistance) illustrate the immediate vectors for feature competition and product repositioning in 2026.
What the report delivers — practical, transaction-level content
- Action-oriented forecasting: Top-line and scenario-based outlooks (base, upside, downside) across the 2026–2032 horizon, with sensitivity tests for raw-material shocks, tariff escalations, and RF spectrum changes.
- Full segmentation matrices: product type, application, and regional demand models (note: segment-level figures are reserved for the full report to preserve competitive value).
- Comprehensive vendor dossiers: including product roadmaps, SWOT diagnostics, and relative positioning against tech adoption and channel access metrics.
- Pricing and margin benchmarks: manufacturer and distributor margin curves, landed-cost calculators, and recommendations for contractual hedging and local-assembly thresholds.
- Supply-chain playbook: supplier risk heat maps, alternative sourcing strategies for critical inputs, and recommended inventory buffers tied to lead-time scenarios.
- Go-to-market playbooks: tailored actions for incumbents, challengers, and private-equity investors (SKU rationalization, growth-by-product vs. growth-by-channel decision frameworks, OEM partnerships, and licensing triggers).
- M&A intelligence: target archetypes, valuation multiples observed in recent device/audio component deals, and integration checklists for cross-border acquisitions under current trade regimes.
Practical strategic recommendations for 2026 planning
- Hedge critical raw materials and secure multi-sourced magnet supply to reduce exposure to concentrated rare-earth production. Negotiate cost-pass provisions where feasible and model scenarios with material price shocks.
- Prioritize networked-audio and DSP-enabled platforms for mid- to high-end SKUs: customers are increasingly willing to invest in workflow-integrated products that reduce end-user complexity.
- Optimize product portfolios by aligning SKUs to clear buyer personas — studio, live sound, creator, conferencing — and sunset low-velocity variants to reinvest in R&D and channel development.
- Consider onshore or nearshore assembly for tariff-sensitive SKUs to preserve competitive pricing in northern-hemisphere markets; evaluate contract manufacturing partners against component lead-time performance.
- For investors and M&A teams: seek bolt-on targets that provide either unique capsule IP, wireless-spectrum expertise, or software layering that supports recurring revenue models (firmware/service subscriptions).
- Design contingency playbooks for geopolitical and regulatory shocks: tariff reclassifications, RoHS updates, or RF-spectrum reallocations can rapidly change product compliance costs.
Risks and triggers to monitor
- Raw material outages or price spikes for magnet materials, which would compress margins and shift competitive dynamics to vertically integrated players.
- Prolonged component lead times that make new-product introductions economically unviable in the short term.
- Escalation of trade barriers that favor local manufacturers and reshape cross-border supply chains.
- Rapid format shifts (e.g., new network audio standards or dominant DSP platforms) that can render incumbent products less competitive without significant firmware/hardware upgrades.
How to use this intelligence in 2026
Procurement leaders should use the report’s supply-chain heat maps and landed-cost scenarios to renegotiate supplier terms and recalibrate inventory policies. Product and R&D executives will find the technology adoption curves and competitor product timelines essential for prioritizing features and launch windows. Corporate development teams will benefit from our valuation and target-qualification frameworks to accelerate deal screening and diligence.
PW Consulting’s full Worldwide Pro Microphone Market report contains the segmented market tables, vendor market shares, and downloadable financial models needed to operationalize the recommendations above. This executive preview intentionally omits the granular regional and application split figures to preserve the practical value of the full dataset — stakeholders seeking transaction-ready insights and downloadable models should consult the full report on our website.
Next steps
- Contact PW Consulting for the full report package, which includes Excel models, vendor dossiers, and scenario-simulation tools tailored for 2026 planning cycles.
- Schedule a strategy workshop with our industry team to translate the report’s findings into a 90‑day execution plan for procurement, product, or M&A teams.
PW Consulting remains committed to delivering impartial, actionable market intelligence. As manufacturers, distributors, and investors position themselves for the 2026 inflection, our analysis will help convert macro forecasts into defensible, revenue-driving initiatives.
For detailed analysis of this topic, please visit the official page: Worldwide Pro Microphone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Heavy Truck Battery Swap Stations Market to Expand at a Robust 21% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Heavy Truck Battery Swap Stations Market — Strategic Outlook for 2026 Decisions
PW Consulting today publishes its in-depth market research on the Worldwide Heavy Truck Battery Swap Stations Market, with base year 2025 and a forward-looking forecast to 2032. The market has expanded rapidly from an estimated USD 350 Million in 2020 to USD 1,250 Million in 2025, and our model projects a sustained compound annual growth rate (CAGR) of 21.0% through the 2026–2032 forecast window, with the global market set to approach the USD 4.75 Billion mark by 2032 (all figures in USD Million). This release is designed as a strategic briefing for executives who must make 2026 investment, partnership, and deployment decisions under conditions of technological standardization, capital intensity, and fast-moving competitive consolidation.
Worldwide Heavy Truck Battery Swap Stations Market
Why 2026 Is the Strategic Inflection Point
-
Acceleration into scale: The combination of rapidly improving technical standards, fleet electrification commitments, and early commercial rollouts means 2026 is when pilots either transition to networked rollouts or fade. Our baseline CAGR (21.0%) reflects momentum that rewards early standardization decisions and penalizes fragmented, proprietary approaches.
Worldwide Heavy Truck Battery Swap Stations Market -
Regulatory and standards crystallization: National and industry group standards (for example, T/CAMPEV 115-2023) now codify high-voltage architectures and sub-6-minute swap targets for heavy trucks. These standards materially reduce technical risk — but they raise the bar on interoperability and procurement specifications.
Worldwide Heavy Truck Battery Swap Stations Market -
Capital and grid constraints: Heavy truck swap stations are capital-intensive and impose non-trivial grid loads. Industry data indicate construction outlays in the range typical for complex depots (reported at RMB 15–25 million per station in recent benchmarking) and minimum grid connection capacities (commonly ≥2 MVA for multi-bay operations). Utilities, financiers, and site planners must align timelines to grid upgrade cycles to avoid deployment bottlenecks.
-
Public support and economics: Local subsidy schemes can materially improve project IRRs (some jurisdictions have offered support up to RMB 10 million per station). At the same time, battery pack pricing (bulk LFP 500–700 kWh units reported at approximately RMB 800–1,200 per kWh) remains a key sensitivity in operational cost models.
What the PW Consulting Report Delivers (Practical, Executable Content)
-
Robust market sizing and high-resolution forecasting: historical (2020–2025) and forecast (2026–2032) topline estimates built from vehicle electrification trajectories, fleet replacement curves, and station-level throughput modeling. Topline figures summarized above; granular tables and downloadable model files are included in the full report.
-
Investment-grade unit economics: station-level capex/opex templates, payback curves under multiple utilization and tariff scenarios, sensitivity matrices tied to battery pricing and swap throughput assumptions.
-
Operational playbooks: station design reference architectures (automated vs semi-automated considerations), site power and civil engineering checklists, safety and maintenance KPIs, turn-key vendor task lists, and recommended contractual frameworks for fleet-dedicated vs public-access operation models.
-
Regulatory and standards dossier: consolidated review of recent standards and policy levers that shape interoperability, vehicle-to-station electrical envelopes (including standardized voltage ceilings), and recommended compliance checkpoints for procurement teams.
-
Competitive intelligence and vendor selection: structured profiles of incumbent and emerging players, capability assessments across hardware, software, and station operations, and an M&A/partnership playbook for acquirers and strategic alliances.
-
Site selection and rollout sequencing: commercially actionable routing and priority maps (GIS-ready), traffic and logistics node scoring, and a staged rollout template that aligns station deployment with fleet electrification timelines and utility upgrade windows.
-
Risk register and mitigation plans: grid risk, component supply volatility, standards divergence, and business-model stress tests (including low-utilization and battery-cost spike scenarios).
Competitive Landscape — What Leaders and Challengers Mean for Your Strategy
-
Market concentration: The heavy truck battery swap station ecosystem is already exhibiting concentration, with the top three providers commanding a significant share and the top five controlling an even larger portion. This concentration has practical implications for pricing, interoperability decisions, and negotiation leverage.
-
Profiles of strategic players: Leading companies are converging on standardized, high-throughput designs and platform-as-a-service operating models. Notable market participants examined in the report include technology-first battery suppliers operating networked swap systems, OEM-aligned integrators rolling modular station designs, and engineering-focused vendors offering turnkey installations and operations. Each profile includes capabilities, go-to-market strategy, recent milestones, and strategic implications.
-
Recent industry milestones: Industry developments relevant to 2026 planning include the commissioning of standardized heavy-duty swap stations by major suppliers, formal release of group standards specifying high-voltage and sub-6-minute swap targets, and the first commercial station launches for series production heavy trucks. These events underscore that technical feasibility and early commercial viability have been validated in multiple operating environments.
Strategic Implications by Stakeholder
-
For C-suite and corporate strategy teams: Adopt a portfolio approach to investment in 2026. The macro CAGR and topline trajectory suggest that staged capital deployment — pilots that convert to scalable hubs — yields the best trade-off between commercial learning and exposure. Prioritize interoperability commitments early to avoid stranded assets.
-
For fleet operators: Decisioning should center on the fleet-dedicated versus public-access tradeoff. Fleet-dedicated stations can accelerate operational certainty and unit economics, while public-access nodes offer broader upside if network effects materialize. Our financial templates allow rapid comparison under realistic duty cycles.
-
For utilities and grid planners: Anticipate concentrated, high-capacity draws at proposed swap hubs. Early coordination on 2 MVA+ connections, demand-management strategies, and tariff design will materially affect project feasibility and schedule.
-
For investors and financiers: Station capex profiles and subsidy regimes produce differentiated return profiles. Use the report’s scenario stress tests to evaluate downside outcomes and prepare covenant structures that account for utilization ramp risk.
-
For policymakers: Standard harmonization and targeted subsidies can unlock network effects and accelerate commercial viability. The report’s policy appendix quantifies the trade-offs between direct station grants and ongoing operating subsidies.
Three Recommended Moves for 2026 (High-Impact, Immediate)
-
1) Lock in interoperability and procurement standards before committing large-scale capex. Align vehicle electrical interfaces, communications protocols, and swap mechanical interfaces with the prevailing group standards to preserve resale value and cross-network compatibility.
-
2) Secure grid and site readiness agreements as a showstopper mitigation. Integrate 2 MVA+ capacity planning and staged civil works into early project timelines and cost projections; factor potential utility lead times into go/no-go decisions.
-
3) Form strategic partnerships that balance capability gaps. Combine an OEM or fleet partner for demand certainty, a battery supplier for cost and lifecycle management, and a station integrator for build-and-operate execution. Our partnership decision matrix in the report helps prioritize counterparties and contract structures.
Why This Report Is Operationally Valuable for 2026
Many market briefings highlight the headline growth rate. PW Consulting’s study goes further: it converts that growth into executable decisions that can be implemented within a 12–24 month window. From procurement specifications and cost build-ups tied to realistic supply-price scenarios, to rollout sequencing aligned with utility readiness and regulatory approvals — the report is built to shorten the path from strategy to operating reality. Importantly, while this briefing outlines the macro trajectory and strategic lines of action, the full report contains the granular segment-level tables, station-level P&L models, scenario outputs, and partner scorecards necessary to execute with confidence.
Access and Next Steps
To preserve commercial value and drive informed engagements, core sub-segment tables, downloadable financial models, and GIS templates are available only with the full report. PW Consulting offers rapid advisory packages (30–60 day sprints) to translate the report into board-ready investment cases, procurement RFPs, and pilot-to-scale roadmaps. Contact PW Consulting or visit our report page to obtain the complete dataset, model files, and bespoke consulting options tailored to your organization’s role in the emerging heavy truck battery swap ecosystem.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy Truck Battery Swap Stations Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mine Shaft Elevator Market to Rise from USD 1,049.82 Million (Base Year 2025) to USD 1,502.0 Million by 2032 at a 5.25% CAGR — Asia Pacific Leads with USD 390.54M; Friction Hoists and Metal Mining Dominate
By pmarketresearch, 2026-07-15
Worldwide Mine Shaft Elevator Market: Strategic Intelligence to Guide 2026 Decisions
PW Consulting’s latest market study on the Worldwide Mine Shaft Elevator Market (base year 2025, historical coverage 2020–2025, forecast 2026–2032) is released at a moment when capital planners, operations directors and OEM strategists must simultaneously manage safety compliance, cost pressure and long lead-time asset programs. Our analysis places the 2025 market at approximately USD 1,049.8 Million and models a steady compound annual growth through the forecast window (CAGR 5.25%), reaching roughly USD 1,502.0 Million by 2032. This release is designed to be an executable intelligence product — it identifies the commercial inflection points companies will face in 2026 and provides the operational playbook they will need to respond.
Worldwide Mine Shaft Elevator Market
Why this study matters for 2026 strategy
- Capital allocation clarity. Mine shaft hoisting systems and elevators are high-capital, long-lead procurements that materially affect multi-year mine plans. The report translates market momentum into investment timing guidance so CFOs and asset managers can prioritize replacements, retrofits and new shaft builds within 2026 budgets.
- Regulatory alignment as a competitive constraint. Recent regulatory activity — including updated MSHA safety standards and ongoing U.S. CFR requirements for overspeed, overwind and braking systems — elevates compliance risk into a procurement criterion. Our study maps the regulatory delta across equipment classes so procurement and engineering teams can lock in compliant technical specifications early in the RFP process.
- Risk-aware sourcing and supply continuity. Steel wire ropes and specialized hoist components remain critical single points of failure. The report synthesizes raw material and NDT inspection dynamics with supplier concentration indicators to help supply chain leaders harden resilience without eroding margin.
- Technology and operational ROI. From electrification, energy recovery and high-efficiency drives to digital condition-based maintenance, the study quantifies where operational improvements deliver the fastest payback and where trade-offs extend lifecycle costs.
What the report delivers — practical, deployable modules
- Market sizing and forward scenarios. Multiple forecast scenarios calibrated to commodity cycles and CAPEX plans enable decision-makers to stress-test program timing against both conservative and accelerated mine development paths.
- Product and retrofit playbooks. Detailed guidance on selection criteria for hoist types, shaft elevator architectures and modernization approaches (mechanical, electrical and control upgrades), accompanied by procurement specification templates and capital budgeting heuristics.
- Vendor benchmarking and scorecards. A systematic vendor evaluation framework covering technical capability, aftermarket coverage, safety record, delivery performance and total cost of ownership (TCO) — intended for use in RFP scoring and strategic partnership screening.
- Supply-chain heatmaps and mitigation plans. Identification of single-vendor dependencies, lead-time concentration, and a set of contingency actions (dual-sourcing playbooks, strategic inventory, component requalification programs).
- Operational dashboards and KPIs. Ready-to-adopt KPI sets for hoist availability, rope lifecycle, brake inspection intervals and predictive maintenance triggers, plus sample dashboards for board-level reporting.
- Regulatory compliance checklist. Practical checklists reflecting recent MSHA updates and international standards that teams can embed into procurement contracts, acceptance testing and commissioning regimes.
- Financial tools. Spreadsheet-based TCO and NPV templates that incorporate energy consumption, maintenance cadences and downtime penalties to compare retrofit vs replacement options on a like-for-like basis.
Top-line strategic takeaways for 2026
- Prioritize modernization over like-for-like replacement when downtime risk is high. For many operators, retrofitting modern drive and control systems yields faster ROI than full mechanical replacement while buying time to align capital with mine life extensions.
- Embed regulatory compliance into supplier selection, not as an afterthought. Given tightened inspection regimes and specific control requirements for person-transporting hoists, contractual technical acceptance criteria must include test protocols, inspection schedules and third-party validation clauses.
- Invest in rope and component NDT capabilities. On-site nondestructive testing and competency development materially lower catastrophic failure risk and reduce unscheduled downtime.
- Design procurement cycles around project-phase modularity. Modular shaft components and factory-complete hoist packages reduce on-site work scope and compress startup timelines — a key lever to contain execution risk on greenfield projects.
- Use vendor scorecards to separate system integrators from component suppliers. The market shows a mix of specialist rack-and-pinion suppliers, broad systems integrators and niche vendors focused on narrow shaft applications; selecting the right partner depends on whether the priority is speed-to-commission, custom engineering or lifecycle service.
Competitive landscape — what the leading firms reveal about industry direction
The market concentration metrics indicate a moderate-to-high consolidation at the top (CR3 ~42.5%; CR5 ~61.2%), signaling that a small group of large suppliers and system integrators capture a majority of project value. The competitive set exhibits distinct strategic archetypes:
Worldwide Mine Shaft Elevator Market
- Alimak Group (Stockholm, Sweden). Known for rack-and-pinion industrial elevators and construction hoists, Alimak’s strength lies in adaptable vertical access platforms suitable for both permanent and temporary mine applications. Their portfolio aligns with clients seeking modular, safety-certified access solutions for vertical transport and egress.
- ABB (Zurich, Switzerland). With a pedigree of more than a century and over a thousand installations, ABB operates as a full-scope mine hoist systems provider — offering friction and drum hoists plus electrical drives and shaft equipment. Their recent collaboration activity around demonstrator projects signals a push to reduce capital build time through novel hoisting concepts and integration of digital controls.
- SIEMAG TECBERG (Haiger, Germany). A specialist in shaft hoisting systems, SIEMAG’s project deliveries continue to validate demand for turnkey mechanical and electrical packages. Their recent cold start-up deliveries for multi-shaft projects in India illustrate that experienced engineering houses remain sought-after partners for complex, multi-shaft implementations.
- Century Elevators (United States). Focused on narrow shaftways and high-safety vertical transport, Century is relevant to underground operations where shaft geometry and regulatory constraints demand compact, robust designs with mine-grade controls.
- KONE Corporation (Espoo, Finland). KONE’s laboratory testing in deep shaft conditions and focus on energy-efficient, customizable elevator solutions position them strongly where energy recovery, long travel distances and lifecycle efficiency dominate procurement decisions.
For 2026, clients should treat supplier selection as a portfolio decision: combine a systems integrator for capital projects with specialist OEMs for retrofit modules and local service partnerships to secure aftermarket coverage and spare part continuity.
Worldwide Mine Shaft Elevator Market
Key risks to monitor
- Regulatory evolution. Ongoing MSHA guidance and U.S. CFR requirements around overspeed and overwind protections, braking capacity and motor-driven equipment standards can alter acceptance criteria mid-project. Maintain an issues log and pre-agreed change control terms in contracts.
- Raw material and inspection risk. Steel wire rope condition is both a safety and a lifecycle economics driver. Regular NDT and rope management strategies must be budgeted into operating plans.
- Execution and delivery lead times. Long lead items — winches, drums, large gear assemblies — create schedule sensitivity. Early supplier engagement and milestone-linked procurement reduce schedule exposure.
- Technological lock-in. Adopting proprietary control systems without clear upgrade paths can increase lifecycle cost and limit ability to switch service providers.
How to use this report in your 2026 planning cycle
- As an input to CapEx prioritization. Use the provided TCO templates and scenario outputs to rank shaft projects and allocate 2026 capital across replacement, retrofit and new build programs.
- To de-risk procurement. Apply the vendor scorecards and contract clauses included in the report to standardize RFP language and acceptance testing procedures.
- To build a maintenance-led value plan. Integrate the KPI dashboards and rope life models into 2026 maintenance budgets to optimize spare part stocking and condition-based interventions.
- For M&A and partnership screening. The competitive mappings and concentration metrics are immediately deployable in target screening and JV partner selection.
PW Consulting’s Worldwide Mine Shaft Elevator Market report blends macro sizing (with a clear forecast trajectory), actionable procurement and maintenance playbooks, and vendor-level insight — without diluting commercial sensitivity. To review the full segment-level data, downloadable financial and risk models, and the complete vendor scorecards and contract templates that support 2026 decision-making, please visit the PW Consulting report page for the Worldwide Mine Shaft Elevator Market.
For detailed analysis of this topic, please visit the official page: Worldwide Mine Shaft Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Blown Castor Oil Market to Expand at a 5.6% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Blown Castor Oil Market — Strategic Outlook for 2026
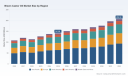
PW Consulting today publishes a forward-looking executive briefing accompanying our comprehensive Worldwide Blown Castor Oil Market report (base year: 2025). This briefing is designed as a strategic “trailer” for senior leaders making 2026 resource allocation, sourcing, product, and M&A decisions. It surfaces actionable implications grounded in the report’s market-sizing, trend analysis, and supplier intelligence, while preserving the full granular datasets and segment-level forecasts for subscribers.
Worldwide Blown Castor Oil Market
Market trajectory: what the macro numbers tell procurement and strategy teams
Blown castor oil has shown resilient expansion through the 2020–2025 period and is materially larger today than it was at the start of the decade. Our modeling indicates continued growth through the coming planning cycle, with an expected compound annual growth rate (CAGR) of 5.6% across the 2026–2032 forecast window. The market’s steady recovery and expansion reflect a combination of recovering downstream demand in coatings and inks, the prevalence of castor-derived specialty chemistries in adhesives and sealants, and incremental adoption in niche lubricant and plasticizer formulations.
Worldwide Blown Castor Oil Market
For executives, the implication is clear: blown castor oil is not a static commodity niche — it is a mid-growth specialty input that will require disciplined strategic planning to capture margin and secure supply through 2026 and beyond.
Worldwide Blown Castor Oil Market
Why this matters for 2026 decision-making
- Sourcing and supply security: Agricultural cycles remain the primary upstream driver. The supply chain’s sensitivity to castor crop yields and origin logistics means procurement teams must move beyond spot buying toward layered strategies (e.g., multi-origin contracts and origin diversification) to avoid price and availability shocks.
- Price risk management: Recent market observations show notable short-term volatility in castor oil pricing across major origin markets. Buyers and sellers who set up transparent price-adjustment mechanisms and hedging protocols will reduce margin leakage in 2026.
- R&D and product differentiation: Formulators increasingly prize tailored blown castor chemistries (varied oxidation levels and viscosity grades) that improve performance in heat-set inks, specialty adhesives, and bio-based coatings. Prioritizing co-development partnerships with targeted suppliers will accelerate time-to-market for higher-margin specialty formulations.
- M&A and capacity plays: With a market exhibiting mid-single-digit CAGR and moderate supplier concentration, strategic acquisitions—particularly in origin production, oxidation-processing capability, or specialty distribution—can create durable advantages in cost and service.
What PW Consulting’s full report delivers (practical, hands-on content)
- Transparent market-sizing framework (base year 2025) and a reproducible forecast methodology covering 2026–2032, enabling scenario-sensitivity testing for internal planning.
- Historical demand reconstruction for 2020–2025, mapping cyclical hits and recoveries by end-use category to clarify which demand pockets are structural vs. transient.
- End-use application narratives and commercial playbooks—covering coatings & inks, adhesives & sealants, lubricants, plasticizers, and niche industrial uses—focused on product positioning and margin capture (note: detailed application-level volumes and values are reserved for the full subscription report).
- Viscosity-grade and grade-differentiation analysis that links technical specs to pricing premiums and formulation advantages, plus supplier capability matrices for grades from low to high viscosity and polymerized/oxidized variants.
- Supply-chain risk heatmaps integrating origin production cycles, logistics bottlenecks, and inventory benchmarking—designed for immediate use in S&OP and procurement risk forums.
- Commercial diligence pack for investors and acquirers: EBITDA sensitivity to feedstock cost swings, customer concentration checklists, and a prioritized checklist for on-site technical verification.
- Executive-ready slide decks and decision templates to accelerate board-level approvals for sourcing, price-setting, or acquisition strategies.
Competitive landscape — how to read supplier positions in 2026
The market’s supplier set combines long-established integrated castor processors, regional producers with specialized oxidation capability, and distributors that add reliability and documentation (COA/TDS/MSDS). PW Consulting’s qualitative and quantitative analysis identifies the following strategic archetypes among active companies:
- Integrated origin processors (scale and backward integration): Producers with seed-processing capacities and downstream oxidation/polymerization capabilities can insulate margins better than pure traders. These players often offer the widest range of standard grades and command logistical advantages near origin hubs.
- Specialty oxidizers/polymerizers: Firms focusing on engineered blown castor oils (tailored oxidation levels, polymerization for heat-set inks, and solvent-resistant plasticizers) capture premium pricing through formulation performance and technical support.
- Global suppliers and document-focused distributors: Companies offering rigorous documentation, consistent COAs and technical datasheets, and multi-regional logistics are preferred by formulators in regulated markets and by customers requiring traceability.
Representative players profiled in our report include integrated manufacturers and exporters, specialized oxidized-oil producers, origin-focused processors, and value-added distributors. Each profile provides strategic takeaways—capabilities, likely commercial playbook, and where they sit on the value chain—without disclosing proprietary market shares in this public summary.
Supply dynamics and raw material context: immediate signals for procurement
Two immediate price signals that should influence 2026 procurement planning:
- Price peaks and subsequent easing in late 2025/early 2026 underscore the market’s responsiveness to downstream buying and origin availability. Recent origin-price moves signaled temporary tightness followed by easing as buyers moderating purchases met ample origin supply.
- Regional divergences in origin pricing persist and can present arbitrage opportunities for buyers with flexible logistics and duty planning. At the same time, source-dependent logistics lead times and quality variance remain discriminating factors for formulators.
Operational recommendations:
- Implement a graded purchasing model: core contracts (covering a material share of expected need), opportunistic spot buys (to capture transient arbitrage), and contingency inventory buffers for key grades used in critical formulations.
- Lock in technical cooperation agreements with 1–2 specialty oxidizers to secure access to tailored grades and co-development routes that justify premium pricing.
- Revise payables and payment terms to reflect seasonality in origin markets and free up working capital during typical crop-cycle squeezes.
Commercial, technical, and regulatory playbooks for product teams
- Prioritize formulation trials that replace petrochemical plasticizers and oxidized oils with blown castor solutions where performance gains (adhesion, flexibility, thermal stability) yield a demonstrable TCO advantage.
- Invest in technical documentation and stewardship (COA/TDS/MSDS) and focus on regulatory preparedness in core markets—this converts quality into commercial access, especially for industrial and regulated end-users.
- Segment customers by value — large formulators seeking continuity, mid-market converters prioritizing cost/performance, and niche formulators seeking specialty chemistries — and tailor service models (JIT, small-batch custom grades, or long-term supply agreements) accordingly.
M&A and investment lens for 2026
With mid-single-digit CAGR and an industry structure that balances regional production strengths against specialty oxidation know-how, potential acquirers should evaluate targets against three criteria:
- Feedstock security and contract coverage—does the target control or have long-term access to origin supply?
- Technical differentiation—does the company offer unique oxidation/polymerization assets or proprietary grade formulations that are hard to replicate?
- Customer and channel fit—does the acquisition create cross-sell potential or strengthen presence in premium end-use segments?
Our report provides a deal-diligence checklist tailored to blown castor oil transactions, including margin sensitivity tables, integration risks, and a prioritized list of synergies to pursue post-close.
How to use the full PW Consulting report
This public briefing is intended to accelerate the early-stage debate inside executive committees. The full report contains the granular intelligence required to operationalize these strategies: a complete set of regional and application-level forecasts, detailed supplier scorecards, price-path scenarios, and model-ready datasets you can import into procurement and finance planning tools. Those subscribing to the full deliverable will get the downloadable datasets, a strategic playbook tailored to your company type (producer, formulator, or distributor), and a one-hour webinar with our lead analyst to walk through scenario implications.
If your 2026 planning cycle includes supply contracts, capability investments, or M&A exploration in blown castor oil, the full report will materially shorten your decision timeline and reduce execution risk by providing validated inputs and practical templates.
Closing — an executive call to action
Blown castor oil occupies a distinctive position: technically specialized, sufficiently concentrated to reward strategic supplier selection, and structurally linked to agricultural and origin dynamics that require forward-looking management. For 2026, companies that combine smart procurement design, targeted product development, and selective investments in capability or distribution are best positioned to convert the market’s steady growth into durable margin and competitive differentiation.
PW Consulting’s full Worldwide Blown Castor Oil Market report provides the detailed, transaction-ready intelligence required to make those calls with confidence. Visit our research portal to access the complete report and subscriber resources.
For detailed analysis of this topic, please visit the official page: Worldwide Blown Castor Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide SPECT Camera Market to Climb from USD 2,195.0 Million in 2025 to USD 3,304.8 Million by 2032 at a 6.02% CAGR — Hybrid SPECT/CT and North America Lead the Charge
By pmarketresearch, 2026-07-15
Worldwide SPECT Camera Market — Strategic Imperatives for 2026
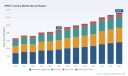
PW Consulting today releases a strategic briefing based on our forthcoming Worldwide SPECT Camera Market report (base year 2025, forecast 2026–2032). As decision makers plan capital allocation, product strategy, and clinical adoption programs for 2026, this briefing summarizes the report’s most consequential insights and the practical, executable implications they create for manufacturers, hospital systems, private equity investors, and policy teams.
Worldwide SPECT Camera Market
Executive snapshot — growth trajectory and what it means
The global SPECT camera market has demonstrated resilient expansion through the early 2020s and enters 2026 from a position of measured momentum. Our model pegs the market at USD 2,195 Million in 2025 (base year) and projects it to grow at a compound annual growth rate (CAGR) of 6.02% across the 2026–2032 forecast window, reaching roughly USD 3,305 Million by 2032. This tempo of growth reflects a confluence of factors: substitution and upgrade cycles in mature imaging centers, accelerating clinical adoption of high-sensitivity detectors and hybrid SPECT/CT platforms, and an expanding evidence base for cardiac, oncology, and neurology applications.
Worldwide SPECT Camera Market
For executives making 2026 investment choices, the headline is clear: the market is neither commodity-stagnant nor hyper-disruptive — it is a medium-growth, technology-driven segment where timing, product differentiation, and go-to-market nuance will determine winners. The market concentration metrics reinforce this: the top three vendors account for the majority share of current revenues, and the top five capture more than four-fifths of the market — a structure that favors scale, channel depth, and regulatory expertise.
Worldwide SPECT Camera Market
What the PW Consulting report gives you — actionable, not academic
- Dynamic demand model — a scenario-based revenue model that converts clinical adoption curves, capital cycles, and reimbursement shifts into 2026–2032 revenue trajectories (editable Excel deliverable).
- Commercial playbooks — vendor-facing go-to-market strategies and hospital procurement checklists that address trade-offs between upfront pricing, consumables/service economics, and bundled-payment negotiations.
- Regulatory & reimbursement navigator — step-by-step decision trees for 510(k) pathways, common pitfalls in PMN submissions, and payer-variant reimbursement mapping for myocardial perfusion and oncology SPECT codes.
- Technology and clinical evidence roadmaps — prioritized R&D and clinical trial designs to de-risk market access for CZT and digital detector technologies, AI-enabled workflow, and dose-reduction claims.
- Competitive benchmark suite — qualitative and quantitative assessments of incumbent and challenger vendors across product capability, installed base health, go-to-market strength, and M&A/partnering propensity.
- Procurement and deployment playbook for health systems — capital cycle timing, site-prep templates, patient throughput optimization, and multi-year service contracting strategies.
Market dynamics shaping 2026 decisions
Several persistent and emergent dynamics will define tactical choices in 2026:
- Technology transition: High-sensitivity detectors (including CZT) and hybrid SPECT/CT configurations are shifting the performance floor and changing the conversation from “if” to “how fast.” Vendors that can quantify patient throughput, dose-sparing, and diagnostic confidence will win tenders in capital-constrained systems.
- Regulatory predictability: SPECT cameras are classified under established medical device pathways requiring 510(k) premarket notification. Major vendors have demonstrated regulatory progress in recent years — including notable clearances for AI-enabled and CZT-enabled systems; such clearances materially shorten time-to-revenue for next-generation products.
- Reimbursement variability: Myocardial perfusion and certain oncology procedures retain dedicated CPT pathways and DRG inclusion in inpatient settings, but reimbursement levels and coding interpretation vary by payor and geography. Evidence dossiers that align clinical benefit with cost offsets — e.g., reduced downstream testing or fewer hospital readmissions — are increasingly decisive in procurement rounds.
- Standards and quality mandates: Professional and IEC standards define acceptance and routine testing expectations. Compliance with these norms is a procurement checkbox and a clinical-safety differentiator for vendors and health systems alike.
Competitive landscape — positioning the key players
The competitive landscape is anchored by several multinational OEMs and a set of focused innovators. Our report provides a granular view of strategic positioning, recent regulatory milestones, and technology roadmaps for each major player.
- GE HealthCare — strong incumbent with a broad SPECT/CT portfolio and investments in AI-enabled quantification for cardiac imaging; recent clearances bolster its leadership in high-throughput and cardiology-focused installations.
- Siemens Healthineers — differentiated by workflow automation and AI-driven tools that accelerate time-to-image and standardize protocols; recent FDA approvals for intelligent imaging features enhance its hospital appeal.
- Philips Healthcare — positions itself on low-dose optimization and integrated clinical workflows, focusing on value propositions for cardiac and oncology users.
- Spectrum Dynamics Medical — a focused innovator in CZT and 360° detector architectures, delivering step-change performance that targets high-end cardiac and oncology use cases; targeted clearances have de-risked North American commercialization.
- United Imaging Healthcare and Mediso — emerging regional and niche players with digital-detector and preclinical-to-clinical product lines respectively; each plays to strengths in cost-competitive positioning or specialized clinical workflows.
Together, these vendors create a market where incumbency and specialization coexist. Our competitive benchmarks show clear opportunities for selective challengers to pick off lifecycle upgrades, service contracts, and add-on software revenue — provided they can show validated clinical and economic outcomes.
Strategic recommendations for 2026 decision makers
Below are priority actions tailored to different stakeholders. Each recommendation is grounded in scenario analysis and the practical trade-offs identified in our modeling.
- For OEMs: Accelerate evidence-generation tied to payer-relevant endpoints. Prioritize multifactor value dossiers (throughput × dose reduction × diagnostic yield) and align clinical trials with reimbursement milestones to compress commercialization timelines.
- For hospital systems and IDNs: Treat SPECT procurement as a systems-level decision, not a platform purchase. Quantify total cost of ownership over 7–10 years, and structure service agreements around uptime and throughput guarantees to insulate against obsolescence.
- For investors and private equity: Seek targets that combine differentiated detector IP with scalable service capabilities. Bolt-on M&A that strengthens installed-base economics (service, parts, software) can materially improve valuation multiples in a market with material concentration among top vendors.
- For payers and policy makers: Engage early with vendors and health systems to define value-based pathways that reward demonstrable reductions in downstream interventions. Standardized quality and imaging performance metrics will reduce variation and improve cost predictability.
Practical playbooks and scenario planning embedded in the report
PW Consulting’s report is structured for operational use in 2026 planning cycles. Deliverables include:
- Decision matrices that convert clinical requirements into procurement specifications and scoring templates for RFPs.
- Regulatory milestones calendar and 510(k) checklist tailored to both incremental and disruptive product launches.
- Reimbursement-impact models that translate clinical trial outcomes into revenue implications across common payor archetypes.
- Service and spare-parts optimization models to manage capital expenditure cycles and reduce mean-time-to-repair for high-utilization sites.
Why this matters now — timing and the path to competitive advantage
2026 will be a decisive year for firms and systems that can convert incremental technology improvements into durable economic advantage. With the market growing at roughly a mid-single-digit CAGR and industry concentration favoring scaled players, the ability to demonstrate differentiated clinical utility, secure regulatory clearance efficiently, and negotiate service-driven commercial terms will separate winners from the rest. Companies that defer evidence generation or treat reimbursement as an afterthought will find it increasingly difficult to win high-value tenders.
Next steps — how to use the full report
This article is a strategic preview. The full Worldwide SPECT Camera Market report contains the detailed financial model, vendor scorecards, procurement templates, and clinical-evidence playbooks that operational teams require to convert strategy into 2026 action plans. PW Consulting is offering tailored briefings and model walkthroughs to executive teams that wish to accelerate decision timelines.
To access the complete dataset, proprietary segmentation, and executable toolkits, please visit the PW Consulting report landing page or contact our advisory team for a customized briefing. The full report contains the granular segmentation, scenario files, and supplier-level financials not disclosed in this preview but essential for execution.
For detailed analysis of this topic, please visit the official page: Worldwide SPECT Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Masonry Coating Market Poised for a 4.82% CAGR Through 2032, Led by Asia-Pacific Surge
By pmarketresearch, 2026-07-15
Worldwide Masonry Coating Market 2026: Strategic Imperatives for Executive Decision‑Making
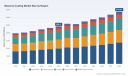
PW Consulting’s newly released Worldwide Masonry Coating Market report (base year 2025, forecast 2026–2032) frames the next phase of industry evolution as firms balance durable growth with intensifying product, regulatory and supply‑chain complexity. The market is projected to grow from an estimated USD 4,850.5 Million in 2025 to approximately USD 6,743.7 Million by 2032, representing a compound annual growth rate (CAGR) of 4.82%. For executives preparing capital plans, commercial strategies and M&A roadmaps in 2026, the report delivers targeted, actionable intelligence to convert that steady macro expansion into competitive advantage.
Worldwide Masonry Coating Market
Why this report matters for 2026 decisions
-
Macro clarity with tactical line of sight — We quantify near‑term demand drivers, model cost‑pass‑through under multiple raw‑material scenarios, and stress‑test margin outcomes across product classes so leaders can set pricing, inventory and sourcing policies that preserve IRR on committed projects.
Worldwide Masonry Coating Market -
Concentration and competition decoded — The market remains fragmented (CR3 ~18.5%; CR5 ~27.1%), creating both margin pressure in commoditized channels and pockets of outsized value for differentiated technologies and distribution models. Our competitive maps identify where to compete, partner, or consolidate.
Worldwide Masonry Coating Market -
Resilience and regulation — The combination of rising construction input prices (Producer Price Index volatility observed through 2025), accelerating low‑VOC regulatory requirements, and climate‑driven demand for waterproofing materially reshapes product roadmaps and capital allocation choices.
-
Investment‑grade recommendations — The report translates scenario outputs into investment actions: R&D prioritization, targeted capex, optimum M&A archetypes, and go‑to‑market playbooks for both OEMs and specialty applicators.
Report scope and practical outputs
This is not a high‑level overview. The deliverable is built for decision makers who need evidence‑backed levers, including:
-
Market sizing and dynamic forecasts by product technology and end‑use (2020–2032), with sensitivity runs under alternative raw‑material inflation and regulatory pathways.
-
Supplier and channel economics: margins by channel (distribution, specification, contractor direct), SKU rationalization models, and pricing elasticity matrices.
-
Supply‑chain vulnerability mapping: exposure to resin, pigment and cement price oscillations; concentration risk across key suppliers; and contingency playbooks to secure critical inputs.
-
Commercial playbooks: specification capture strategies for architects and contractors, retrofit vs new‑build sales motions, lifecycle cost calculators, and training/incentive programs for applicators.
-
M&A and partnership roadmaps: prioritized target archetypes, valuation benchmarks, and integration checklists for acquiring technology (e.g., crystalline waterproofing) or distribution footholds in fast‑growing markets.
-
Regulatory and sustainability tracker: timelines for low‑VOC adoption, labeling and green‑building incentives that affect product acceptance and pricing power.
Market dynamics that will shape 2026 strategy
-
Input cost pressure: Construction input inflation accelerated through 2025, increasing cost volatility for binders, pigments and cementitious inputs. Pricing playbooks in 2026 must balance pass‑through with demand elasticity to avoid share loss in price‑sensitive channels.
-
Shift toward low‑VOC and sustainable chemistries: Regulatory and specification pressure is creating new value pools for waterborne systems, bio‑based additives and lifecycle‑verified coatings; these are high‑margin opportunities for firms that can invest quickly and credibly.
-
Waterproofing and resilience demand: Waterproofing chemistries and damp‑proof systems are among the fastest growing subsegments as clients prioritize climate resilience. This favors technologies that combine durability with low maintenance and proven long‑term performance.
-
Technology differentiation matters: Acrylics remain a dominant binder technology globally, but specialized performance — crystalline waterproofing, elastomerics with high crack‑bridging, polymer‑modified cementitious systems — create defensible niches.
Competitive landscape — who’s doing what
The market is a mix of global coatings giants, regional construction‑chemical leaders and highly specialized niche players. Executives should think in three strategic buckets: global scale players that push specification and distribution, construction‑chemical integrators that bundle coatings with repair and waterproofing systems, and specialists focused on restoration or severe‑exposure solutions.
-
Global coatings leaders (e.g., multi‑brand manufacturers): These firms leverage broad distribution, specification influence and sizable R&D budgets to shape architectural and protective masonry demand. Recent strategic moves in 2024–2025 — including divestitures and completed mergers — have reallocated focus and capital toward performance coatings and cross‑category synergies.
-
Construction‑chemical integrators and system providers: Companies that combine admixtures, waterproofing systems and polymer‑modified mortars create ‘system’ value propositions that simplify procurement for large projects and public infrastructure programs.
-
Highly specialized technology players: Firms that offer crystalline waterproofing, restoration‑grade polymer modifiers, or elastomeric breathable systems capture premium margin in repair and severe‑exposure segments. These players are often the most attractive tuck‑in targets for acquirers seeking immediate capability uplift.
Noteworthy recent corporate developments have already re‑shaped the competitive map: a completed global merger in late 2025 enlarges a major player’s performance coatings footprint; a leading architectural coatings business was divested in late 2024, allowing sharper focus on performance and protective offerings; and capacity expansions in key regions have begun to unlock local production for cement‑based systems. Each of these moves has material implications for competition, pricing and access to specification channels in 2026.
Strategic recommendations for 2026
To convert steady market growth into durable share and margin gains in 2026, executives should prioritize four integrated actions:
-
Portfolio & R&D triage — Rapidly segment SKUs into defend‑cost, upgrade‑to‑premium and exit buckets. Redirect R&D toward low‑VOC, waterproofing and polymer‑modified cementitious chemistries where willingness‑to‑pay and specification barriers justify higher development spend.
-
Supply‑chain hedging — Execute dual‑sourcing for critical resins and cementitious inputs, implement hedging or indexed contracts for high‑volatility components, and localize manufacturing (or secure JV capacity) in regions with high cement‑based demand to reduce freight and input risk.
-
Commercial re‑engineering — Move beyond price competition by monetizing performance: lifecycle cost tools, extended warranties linked to approved applicators, and training‑led channel programs that lock applicators into spec’d systems.
-
M&A and partnerships — Prioritize tuck‑ins that add crystalline waterproofing, polymer modification or restoration credentials and consider strategic JVs to access fast‑growing regional demand without full greenfield exposure.
Risk matrix and near‑term mitigations
-
Raw material shocks — Mitigation: indexed supply contracts, safety‑stock protocols and formula reformulation playbooks that preserve margins under multiple price scenarios.
-
Regulatory acceleration on VOCs — Mitigation: accelerate certification programs, pursue third‑party eco‑labels and pre‑qualify products with major green‑building rating systems.
-
Channel disintermediation — Mitigation: invest in digital commerce for contractors, launch installer subscription services, and bundle training/certification that raises switching costs.
-
Climate/change in demand profile — Mitigation: reweight R&D and commercial focus toward waterproofing and resilient systems for retrofit and public‑works channels.
What the full PW Consulting report provides (and what you’ll only find there)
In keeping with our “trailer” principle, this release outlines the strategic line of sight — but the full report contains the proprietary, transaction‑grade detail required to execute in 2026:
-
Granular, model‑ready forecasts by technology, application and region with downloadable spreadsheets and scenario toggles.
-
Supplier scorecards and an adhoc M&A target list by capability, with integration risk ratings and price multiple benchmarks.
-
Price‑to‑margin sensitivity models that quantify the P&L impact of raw‑material moves and regulatory compliance costs.
-
Ready‑to‑use commercial playbooks, specification templates, and contractor incentive schemes that accelerate specification capture.
PW Consulting’s Worldwide Masonry Coating Market report is designed as a working tool for CEOs, strategy teams, business unit heads and PE investors who must make allocation decisions this calendar year. The market’s projected steady expansion masks tectonic shifts in product mix, supply chains and specification behavior — get the full intelligence pack to turn those shifts into actionable advantage.
Next steps
-
Download the full report for the complete quantitative model, supplier assessments and executable playbooks.
-
Contact PW Consulting for a tailored executive briefing and implementation road‑map workshop to align your 2026 plans with the scenarios that matter most to your business.
For detailed analysis of this topic, please visit the official page: Worldwide Masonry Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wheel Balancer With Touchscreen Market to Grow at 6.55% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Wheel Balancer With Touchscreen Market — Strategic Preview for 2026 Decision-Makers
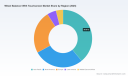
PW Consulting’s new market study on the Worldwide Wheel Balancer With Touchscreen market arrives at a pivotal moment for manufacturers, distributors, and investors. The market demonstrated steady expansion through the early 2020s and reached an estimated USD 391.0 Million in 2025 (base year). Our forecasting framework projects compounded growth across the 2026–2032 horizon, with an average annual growth rate of 6.55% that drives the industry toward an expected market scale of approximately USD 609.6 Million by 2032. These topline dynamics underpin a practical, decision-focused body of work designed to inform capital allocation, product strategy, commercial models, and supply-chain risk mitigation throughout 2026 and beyond.
Worldwide Wheel Balancer With Touchscreen Market
Why this report matters for 2026 strategic planning
-
Timing: 2026 is the inflection point at which touchscreen-enabled balancing platforms and embedded diagnostics move from differential product features to baseline expectations in mid-to-high-volume service channels. The forecasted market trajectory underscores both opportunity and competitive urgency.
Worldwide Wheel Balancer With Touchscreen Market -
Investment clarity: the report translates market momentum into investable themes — capex sizing for production upgrades, R&D prioritization for embedded diagnostics and remote services, and M&A targets for scale in service networks.
Worldwide Wheel Balancer With Touchscreen Market -
Operational risk management: escalating raw-material and electronics exposure, together with evolving environmental regulation, require scenario-based procurement and product-material strategies. Our analysis exposes where organizations are most vulnerable and where hedging and design shifts produce outsized returns.
-
Commercial tactics: distribution, pricing, and aftersales structures must evolve to capture recurring revenue from software, diagnostics, and consumables. The report provides frameworks to reshape go-to-market motion for 2026 rollouts.
What PW Consulting’s report delivers — practical contents and tools
This is not a catalogue of numbers alone. The report is a pragmatic toolkit for executives and functional leaders who must convert market insight into action during 2026. Key inclusions:
-
Market sizing & forecasting methodology — transparent model architecture, assumptions, and scenario outputs (base, upside, downside) covering 2026–2032 so teams can stress-test plans under alternate macro and commodity regimes.
-
Demand-driver diagnostics — quantified drivers (OEM production trends, aftermarket service density, electrified vehicle considerations, and adoption curves for advanced balancing features) and their sensitivity to serviceable addressable market (SAM) parameters.
-
Commercial playbooks — go-to-market templates for OEM partnerships, multi-channel distribution, franchise / dealer enablement, and high-throughput tire chain strategies with suggested incentive structures and KPI scorecards.
-
Product roadmap blueprints — prioritization grids for touchscreen UX, automated measurement arms, laser placement, and integrated diagnostics, aligned to price tiers and target customer segments.
-
Supply-chain heatmaps & procurement playbook — tiered supplier mapping for steel and electronic components, recommended dual-sourcing approaches, lead-time mitigation, and contractual language for component-indexed pricing clauses.
-
Regulatory and sustainability pathways — compliance checklists, zinc-replacement adoption scenarios, and lifecycle analyses to align product and packaging design with emerging environmental mandates.
-
Competitive benchmarking toolkit — profile matrices that map feature sets, production footprints, channel reach, and service capability for the principal vendors, plus a reproducible peer-comparison template.
-
Deal and M&A playbook — valuation sensitizers, integration checklists, and synergy capture templates focused on combining equipment manufacturing with service networks and consumables distribution.
-
Sales enablement & pilot KPIs — field playbooks, workshop scripts, and ROI calculators to accelerate trial deployments and shorten customer payback periods.
Competitive landscape — who matters and how they are positioning
The market structure shows a moderate concentration: the top three vendors control a meaningful plurality of market share, while the top five exceed half of the industry, creating a dual dynamic of scale-based competition and fragmented pockets of regional specialization. Against that backdrop, PW Consulting’s competitive chapter synthesizes product, channel and service differentiation among leading suppliers to reveal practical implications for competitors and customers alike.
-
CEMB S.p.A. (Italy) — breadth of touchscreen models and technical depth. CEMB’s portfolio spans passenger, truck and motorcycle applications and emphasizes automated gauges, laser spotters and 2-HIT productivity features that appeal to multi-service operators. Strategic takeaways: modular product lines support both export-led growth and targeted aftermarket campaigns.
-
Hunter Engineering (USA) — brand leader in integrated service workflows. Hunter’s SmartWeight® Elite and Road Force® series leverage intuitive touch experiences and automated centering/measurement features that reduce operator variability. Strategic takeaways: premium positioning with deep service integration creates recurring aftermarket upside.
-
Hofmann / Snap-on (North America operations) — productivity-first designs. The geodyna® and Armored Series optimize throughput with laser-assisted placement and power-clamping. Strategic takeaways: channel control via dealer networks and strong field-service offerings shores up installed-base monetization.
-
Coats Company (USA) — recent product innovation. The 2025 launch of the ProBalance E900 introduced diagnostic-first positioning: direct-drive mechanics paired with laser data entry and diagnostic analytics aimed at high-volume shops. Strategic takeaways: diagnostic capability is a high-return differentiator for shop customers and a lever for subscription services.
-
Giuliano and Corghi (Italy) — automation and operator ergonomics. These vendors emphasize super-automatic platforms, large TFT touch displays and rapid size detection to reduce cycle time. Strategic takeaways: automation commands price premiums in high-throughput segments if paired with extended warranties and remote support.
-
John Bean / Snap-on (North America ops) — mid-to-high productivity offerings. Semi-automatic touchscreen models and 3D imaging tools aim at cost-conscious buyers seeking productivity gains without full automation. Strategic takeaways: attractive targets for lease finance programs and distribution tie-ups with independent service chains.
-
Ravaglioli, Beissbarth and other European suppliers — focus on imaging, sonar detection and ergonomic interfaces. Strategic takeaways: strong OEM ties and regional service networks create resilient revenue streams even as technology features standardize.
Supply-chain and regulatory dynamics to watch in 2026
-
Input exposure: steel and electronics remain the principal cost drivers for wheel balancer manufacturing. Price volatility and lead-time variability in these inputs materially affect gross margins and production scheduling.
-
Zinc transition: environmental regulation is accelerating adoption of recyclable materials — notably zinc — in wheel weights and related components. Zinc’s recyclability is attractive but carries a material premium; we identify supplier strategies and product-design offsets to mitigate margin erosion.
-
Component sourcing: sensors, motors and control electronics concentrate sourcing risk. The report maps out tier-1 vs. alternative suppliers, qualification pathways, and recommended contractual protections (indexation, supply credits, and capacity reservation clauses).
Strategic playbook for action in 2026
-
Prioritize diagnostic and software features as revenue drivers — design devices for telemetry, predictive maintenance and paid diagnostic bundles rather than treating software as a secondary add-on.
-
Design differentiated tiers — entry, mid and premium configurations aligned to service throughput profiles, with clear migration paths and trade-in programs that accelerate repeat purchases.
-
Strengthen distribution economics — incentivize high-volume channel partners through performance-based rebates and integrated service bundles rather than one-time discounting.
-
Hedge input risk — adopt dual-sourcing and contractual indexation for steel and critical electronics; evaluate strategic inventory buffers during contractual negotiation windows.
-
Build sustainability into the value proposition — capture early-adopter premiums by offering zinc-compatible workflows and verified recyclability statements for buyers subject to regulatory scrutiny.
-
Prepare for consolidation and selective M&A — target acquisitions that add service footprint, consumables distribution, or software analytics capabilities rather than simple capacity plays.
-
Operationalize pilot-to-scale pathways — use the report’s ROI calculators and pilot KPIs to accelerate commercialization cycles and shorten time-to-revenue for new touchscreen-enabled models.
Next steps — where this preview leads you
This briefing is a strategic “trailer”: it reveals the macro trajectory, the competitive topology, and the practical playbooks that matter in 2026, while reserving the core, granular segmentation tables, regional and application splits, and detailed vendor revenue models for the full report. For commercial teams, product leaders, procurement heads and investors, the full dataset contains the operative figures and downloadable models required to build financial cases, perform cross-border scenario planning, and develop targeted sales initiatives.
To access the complete report, including the full set of regional analyses, application breakdowns, vendor scorecards, and downloadable financial models, please visit the PW Consulting publication page. The full dossier supplies the empirical backbone to convert the strategic directions outlined here into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Wheel Balancer With Touchscreen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com