

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Masonry Coating Market Poised for a 4.82% CAGR Through 2032, Led by Asia-Pacific Surge

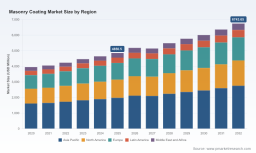
Worldwide Masonry Coating Market 2026: Strategic Imperatives for Executive Decision‑Making
PW Consulting’s newly released Worldwide Masonry Coating Market report (base year 2025, forecast 2026–2032) frames the next phase of industry evolution as firms balance durable growth with intensifying product, regulatory and supply‑chain complexity. The market is projected to grow from an estimated USD 4,850.5 Million in 2025 to approximately USD 6,743.7 Million by 2032, representing a compound annual growth rate (CAGR) of 4.82%. For executives preparing capital plans, commercial strategies and M&A roadmaps in 2026, the report delivers targeted, actionable intelligence to convert that steady macro expansion into competitive advantage.
Worldwide Masonry Coating Market
Why this report matters for 2026 decisions
-
Macro clarity with tactical line of sight — We quantify near‑term demand drivers, model cost‑pass‑through under multiple raw‑material scenarios, and stress‑test margin outcomes across product classes so leaders can set pricing, inventory and sourcing policies that preserve IRR on committed projects.
Worldwide Masonry Coating Market -
Concentration and competition decoded — The market remains fragmented (CR3 ~18.5%; CR5 ~27.1%), creating both margin pressure in commoditized channels and pockets of outsized value for differentiated technologies and distribution models. Our competitive maps identify where to compete, partner, or consolidate.
Worldwide Masonry Coating Market -
Resilience and regulation — The combination of rising construction input prices (Producer Price Index volatility observed through 2025), accelerating low‑VOC regulatory requirements, and climate‑driven demand for waterproofing materially reshapes product roadmaps and capital allocation choices.
-
Investment‑grade recommendations — The report translates scenario outputs into investment actions: R&D prioritization, targeted capex, optimum M&A archetypes, and go‑to‑market playbooks for both OEMs and specialty applicators.
Report scope and practical outputs
This is not a high‑level overview. The deliverable is built for decision makers who need evidence‑backed levers, including:
-
Market sizing and dynamic forecasts by product technology and end‑use (2020–2032), with sensitivity runs under alternative raw‑material inflation and regulatory pathways.
-
Supplier and channel economics: margins by channel (distribution, specification, contractor direct), SKU rationalization models, and pricing elasticity matrices.
-
Supply‑chain vulnerability mapping: exposure to resin, pigment and cement price oscillations; concentration risk across key suppliers; and contingency playbooks to secure critical inputs.
-
Commercial playbooks: specification capture strategies for architects and contractors, retrofit vs new‑build sales motions, lifecycle cost calculators, and training/incentive programs for applicators.
-
M&A and partnership roadmaps: prioritized target archetypes, valuation benchmarks, and integration checklists for acquiring technology (e.g., crystalline waterproofing) or distribution footholds in fast‑growing markets.
-
Regulatory and sustainability tracker: timelines for low‑VOC adoption, labeling and green‑building incentives that affect product acceptance and pricing power.
Market dynamics that will shape 2026 strategy
-
Input cost pressure: Construction input inflation accelerated through 2025, increasing cost volatility for binders, pigments and cementitious inputs. Pricing playbooks in 2026 must balance pass‑through with demand elasticity to avoid share loss in price‑sensitive channels.
-
Shift toward low‑VOC and sustainable chemistries: Regulatory and specification pressure is creating new value pools for waterborne systems, bio‑based additives and lifecycle‑verified coatings; these are high‑margin opportunities for firms that can invest quickly and credibly.
-
Waterproofing and resilience demand: Waterproofing chemistries and damp‑proof systems are among the fastest growing subsegments as clients prioritize climate resilience. This favors technologies that combine durability with low maintenance and proven long‑term performance.
-
Technology differentiation matters: Acrylics remain a dominant binder technology globally, but specialized performance — crystalline waterproofing, elastomerics with high crack‑bridging, polymer‑modified cementitious systems — create defensible niches.
Competitive landscape — who’s doing what
The market is a mix of global coatings giants, regional construction‑chemical leaders and highly specialized niche players. Executives should think in three strategic buckets: global scale players that push specification and distribution, construction‑chemical integrators that bundle coatings with repair and waterproofing systems, and specialists focused on restoration or severe‑exposure solutions.
-
Global coatings leaders (e.g., multi‑brand manufacturers): These firms leverage broad distribution, specification influence and sizable R&D budgets to shape architectural and protective masonry demand. Recent strategic moves in 2024–2025 — including divestitures and completed mergers — have reallocated focus and capital toward performance coatings and cross‑category synergies.
-
Construction‑chemical integrators and system providers: Companies that combine admixtures, waterproofing systems and polymer‑modified mortars create ‘system’ value propositions that simplify procurement for large projects and public infrastructure programs.
-
Highly specialized technology players: Firms that offer crystalline waterproofing, restoration‑grade polymer modifiers, or elastomeric breathable systems capture premium margin in repair and severe‑exposure segments. These players are often the most attractive tuck‑in targets for acquirers seeking immediate capability uplift.
Noteworthy recent corporate developments have already re‑shaped the competitive map: a completed global merger in late 2025 enlarges a major player’s performance coatings footprint; a leading architectural coatings business was divested in late 2024, allowing sharper focus on performance and protective offerings; and capacity expansions in key regions have begun to unlock local production for cement‑based systems. Each of these moves has material implications for competition, pricing and access to specification channels in 2026.
Strategic recommendations for 2026
To convert steady market growth into durable share and margin gains in 2026, executives should prioritize four integrated actions:
-
Portfolio & R&D triage — Rapidly segment SKUs into defend‑cost, upgrade‑to‑premium and exit buckets. Redirect R&D toward low‑VOC, waterproofing and polymer‑modified cementitious chemistries where willingness‑to‑pay and specification barriers justify higher development spend.
-
Supply‑chain hedging — Execute dual‑sourcing for critical resins and cementitious inputs, implement hedging or indexed contracts for high‑volatility components, and localize manufacturing (or secure JV capacity) in regions with high cement‑based demand to reduce freight and input risk.
-
Commercial re‑engineering — Move beyond price competition by monetizing performance: lifecycle cost tools, extended warranties linked to approved applicators, and training‑led channel programs that lock applicators into spec’d systems.
-
M&A and partnerships — Prioritize tuck‑ins that add crystalline waterproofing, polymer modification or restoration credentials and consider strategic JVs to access fast‑growing regional demand without full greenfield exposure.
Risk matrix and near‑term mitigations
-
Raw material shocks — Mitigation: indexed supply contracts, safety‑stock protocols and formula reformulation playbooks that preserve margins under multiple price scenarios.
-
Regulatory acceleration on VOCs — Mitigation: accelerate certification programs, pursue third‑party eco‑labels and pre‑qualify products with major green‑building rating systems.
-
Channel disintermediation — Mitigation: invest in digital commerce for contractors, launch installer subscription services, and bundle training/certification that raises switching costs.
-
Climate/change in demand profile — Mitigation: reweight R&D and commercial focus toward waterproofing and resilient systems for retrofit and public‑works channels.
What the full PW Consulting report provides (and what you’ll only find there)
In keeping with our “trailer” principle, this release outlines the strategic line of sight — but the full report contains the proprietary, transaction‑grade detail required to execute in 2026:
-
Granular, model‑ready forecasts by technology, application and region with downloadable spreadsheets and scenario toggles.
-
Supplier scorecards and an adhoc M&A target list by capability, with integration risk ratings and price multiple benchmarks.
-
Price‑to‑margin sensitivity models that quantify the P&L impact of raw‑material moves and regulatory compliance costs.
-
Ready‑to‑use commercial playbooks, specification templates, and contractor incentive schemes that accelerate specification capture.
PW Consulting’s Worldwide Masonry Coating Market report is designed as a working tool for CEOs, strategy teams, business unit heads and PE investors who must make allocation decisions this calendar year. The market’s projected steady expansion masks tectonic shifts in product mix, supply chains and specification behavior — get the full intelligence pack to turn those shifts into actionable advantage.
Next steps
-
Download the full report for the complete quantitative model, supplier assessments and executable playbooks.
-
Contact PW Consulting for a tailored executive briefing and implementation road‑map workshop to align your 2026 plans with the scenarios that matter most to your business.
For detailed analysis of this topic, please visit the official page: Worldwide Masonry Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com