

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Mine Shaft Elevator Market to Rise from USD 1,049.82 Million (Base Year 2025) to USD 1,502.0 Million by 2032 at a 5.25% CAGR — Asia Pacific Leads with USD 390.54M; Friction Hoists and Metal Mining Dominate

Worldwide Mine Shaft Elevator Market: Strategic Intelligence to Guide 2026 Decisions
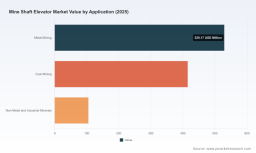
PW Consulting’s latest market study on the Worldwide Mine Shaft Elevator Market (base year 2025, historical coverage 2020–2025, forecast 2026–2032) is released at a moment when capital planners, operations directors and OEM strategists must simultaneously manage safety compliance, cost pressure and long lead-time asset programs. Our analysis places the 2025 market at approximately USD 1,049.8 Million and models a steady compound annual growth through the forecast window (CAGR 5.25%), reaching roughly USD 1,502.0 Million by 2032. This release is designed to be an executable intelligence product — it identifies the commercial inflection points companies will face in 2026 and provides the operational playbook they will need to respond.
Worldwide Mine Shaft Elevator Market
Why this study matters for 2026 strategy
- Capital allocation clarity. Mine shaft hoisting systems and elevators are high-capital, long-lead procurements that materially affect multi-year mine plans. The report translates market momentum into investment timing guidance so CFOs and asset managers can prioritize replacements, retrofits and new shaft builds within 2026 budgets.
- Regulatory alignment as a competitive constraint. Recent regulatory activity — including updated MSHA safety standards and ongoing U.S. CFR requirements for overspeed, overwind and braking systems — elevates compliance risk into a procurement criterion. Our study maps the regulatory delta across equipment classes so procurement and engineering teams can lock in compliant technical specifications early in the RFP process.
- Risk-aware sourcing and supply continuity. Steel wire ropes and specialized hoist components remain critical single points of failure. The report synthesizes raw material and NDT inspection dynamics with supplier concentration indicators to help supply chain leaders harden resilience without eroding margin.
- Technology and operational ROI. From electrification, energy recovery and high-efficiency drives to digital condition-based maintenance, the study quantifies where operational improvements deliver the fastest payback and where trade-offs extend lifecycle costs.
What the report delivers — practical, deployable modules
- Market sizing and forward scenarios. Multiple forecast scenarios calibrated to commodity cycles and CAPEX plans enable decision-makers to stress-test program timing against both conservative and accelerated mine development paths.
- Product and retrofit playbooks. Detailed guidance on selection criteria for hoist types, shaft elevator architectures and modernization approaches (mechanical, electrical and control upgrades), accompanied by procurement specification templates and capital budgeting heuristics.
- Vendor benchmarking and scorecards. A systematic vendor evaluation framework covering technical capability, aftermarket coverage, safety record, delivery performance and total cost of ownership (TCO) — intended for use in RFP scoring and strategic partnership screening.
- Supply-chain heatmaps and mitigation plans. Identification of single-vendor dependencies, lead-time concentration, and a set of contingency actions (dual-sourcing playbooks, strategic inventory, component requalification programs).
- Operational dashboards and KPIs. Ready-to-adopt KPI sets for hoist availability, rope lifecycle, brake inspection intervals and predictive maintenance triggers, plus sample dashboards for board-level reporting.
- Regulatory compliance checklist. Practical checklists reflecting recent MSHA updates and international standards that teams can embed into procurement contracts, acceptance testing and commissioning regimes.
- Financial tools. Spreadsheet-based TCO and NPV templates that incorporate energy consumption, maintenance cadences and downtime penalties to compare retrofit vs replacement options on a like-for-like basis.
Top-line strategic takeaways for 2026
- Prioritize modernization over like-for-like replacement when downtime risk is high. For many operators, retrofitting modern drive and control systems yields faster ROI than full mechanical replacement while buying time to align capital with mine life extensions.
- Embed regulatory compliance into supplier selection, not as an afterthought. Given tightened inspection regimes and specific control requirements for person-transporting hoists, contractual technical acceptance criteria must include test protocols, inspection schedules and third-party validation clauses.
- Invest in rope and component NDT capabilities. On-site nondestructive testing and competency development materially lower catastrophic failure risk and reduce unscheduled downtime.
- Design procurement cycles around project-phase modularity. Modular shaft components and factory-complete hoist packages reduce on-site work scope and compress startup timelines — a key lever to contain execution risk on greenfield projects.
- Use vendor scorecards to separate system integrators from component suppliers. The market shows a mix of specialist rack-and-pinion suppliers, broad systems integrators and niche vendors focused on narrow shaft applications; selecting the right partner depends on whether the priority is speed-to-commission, custom engineering or lifecycle service.
Competitive landscape — what the leading firms reveal about industry direction
The market concentration metrics indicate a moderate-to-high consolidation at the top (CR3 ~42.5%; CR5 ~61.2%), signaling that a small group of large suppliers and system integrators capture a majority of project value. The competitive set exhibits distinct strategic archetypes:
Worldwide Mine Shaft Elevator Market
- Alimak Group (Stockholm, Sweden). Known for rack-and-pinion industrial elevators and construction hoists, Alimak’s strength lies in adaptable vertical access platforms suitable for both permanent and temporary mine applications. Their portfolio aligns with clients seeking modular, safety-certified access solutions for vertical transport and egress.
- ABB (Zurich, Switzerland). With a pedigree of more than a century and over a thousand installations, ABB operates as a full-scope mine hoist systems provider — offering friction and drum hoists plus electrical drives and shaft equipment. Their recent collaboration activity around demonstrator projects signals a push to reduce capital build time through novel hoisting concepts and integration of digital controls.
- SIEMAG TECBERG (Haiger, Germany). A specialist in shaft hoisting systems, SIEMAG’s project deliveries continue to validate demand for turnkey mechanical and electrical packages. Their recent cold start-up deliveries for multi-shaft projects in India illustrate that experienced engineering houses remain sought-after partners for complex, multi-shaft implementations.
- Century Elevators (United States). Focused on narrow shaftways and high-safety vertical transport, Century is relevant to underground operations where shaft geometry and regulatory constraints demand compact, robust designs with mine-grade controls.
- KONE Corporation (Espoo, Finland). KONE’s laboratory testing in deep shaft conditions and focus on energy-efficient, customizable elevator solutions position them strongly where energy recovery, long travel distances and lifecycle efficiency dominate procurement decisions.
For 2026, clients should treat supplier selection as a portfolio decision: combine a systems integrator for capital projects with specialist OEMs for retrofit modules and local service partnerships to secure aftermarket coverage and spare part continuity.
Worldwide Mine Shaft Elevator Market
Key risks to monitor
- Regulatory evolution. Ongoing MSHA guidance and U.S. CFR requirements around overspeed and overwind protections, braking capacity and motor-driven equipment standards can alter acceptance criteria mid-project. Maintain an issues log and pre-agreed change control terms in contracts.
- Raw material and inspection risk. Steel wire rope condition is both a safety and a lifecycle economics driver. Regular NDT and rope management strategies must be budgeted into operating plans.
- Execution and delivery lead times. Long lead items — winches, drums, large gear assemblies — create schedule sensitivity. Early supplier engagement and milestone-linked procurement reduce schedule exposure.
- Technological lock-in. Adopting proprietary control systems without clear upgrade paths can increase lifecycle cost and limit ability to switch service providers.
How to use this report in your 2026 planning cycle
- As an input to CapEx prioritization. Use the provided TCO templates and scenario outputs to rank shaft projects and allocate 2026 capital across replacement, retrofit and new build programs.
- To de-risk procurement. Apply the vendor scorecards and contract clauses included in the report to standardize RFP language and acceptance testing procedures.
- To build a maintenance-led value plan. Integrate the KPI dashboards and rope life models into 2026 maintenance budgets to optimize spare part stocking and condition-based interventions.
- For M&A and partnership screening. The competitive mappings and concentration metrics are immediately deployable in target screening and JV partner selection.
PW Consulting’s Worldwide Mine Shaft Elevator Market report blends macro sizing (with a clear forecast trajectory), actionable procurement and maintenance playbooks, and vendor-level insight — without diluting commercial sensitivity. To review the full segment-level data, downloadable financial and risk models, and the complete vendor scorecards and contract templates that support 2026 decision-making, please visit the PW Consulting report page for the Worldwide Mine Shaft Elevator Market.
For detailed analysis of this topic, please visit the official page: Worldwide Mine Shaft Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com