

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Wheel Balancer With Touchscreen Market to Grow at 6.55% CAGR Through 2032

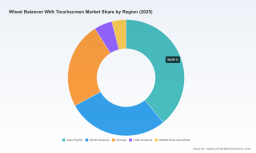
Worldwide Wheel Balancer With Touchscreen Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Wheel Balancer With Touchscreen market arrives at a pivotal moment for manufacturers, distributors, and investors. The market demonstrated steady expansion through the early 2020s and reached an estimated USD 391.0 Million in 2025 (base year). Our forecasting framework projects compounded growth across the 2026–2032 horizon, with an average annual growth rate of 6.55% that drives the industry toward an expected market scale of approximately USD 609.6 Million by 2032. These topline dynamics underpin a practical, decision-focused body of work designed to inform capital allocation, product strategy, commercial models, and supply-chain risk mitigation throughout 2026 and beyond.
Worldwide Wheel Balancer With Touchscreen Market
Why this report matters for 2026 strategic planning
-
Timing: 2026 is the inflection point at which touchscreen-enabled balancing platforms and embedded diagnostics move from differential product features to baseline expectations in mid-to-high-volume service channels. The forecasted market trajectory underscores both opportunity and competitive urgency.
Worldwide Wheel Balancer With Touchscreen Market -
Investment clarity: the report translates market momentum into investable themes — capex sizing for production upgrades, R&D prioritization for embedded diagnostics and remote services, and M&A targets for scale in service networks.
Worldwide Wheel Balancer With Touchscreen Market -
Operational risk management: escalating raw-material and electronics exposure, together with evolving environmental regulation, require scenario-based procurement and product-material strategies. Our analysis exposes where organizations are most vulnerable and where hedging and design shifts produce outsized returns.
-
Commercial tactics: distribution, pricing, and aftersales structures must evolve to capture recurring revenue from software, diagnostics, and consumables. The report provides frameworks to reshape go-to-market motion for 2026 rollouts.
What PW Consulting’s report delivers — practical contents and tools
This is not a catalogue of numbers alone. The report is a pragmatic toolkit for executives and functional leaders who must convert market insight into action during 2026. Key inclusions:
-
Market sizing & forecasting methodology — transparent model architecture, assumptions, and scenario outputs (base, upside, downside) covering 2026–2032 so teams can stress-test plans under alternate macro and commodity regimes.
-
Demand-driver diagnostics — quantified drivers (OEM production trends, aftermarket service density, electrified vehicle considerations, and adoption curves for advanced balancing features) and their sensitivity to serviceable addressable market (SAM) parameters.
-
Commercial playbooks — go-to-market templates for OEM partnerships, multi-channel distribution, franchise / dealer enablement, and high-throughput tire chain strategies with suggested incentive structures and KPI scorecards.
-
Product roadmap blueprints — prioritization grids for touchscreen UX, automated measurement arms, laser placement, and integrated diagnostics, aligned to price tiers and target customer segments.
-
Supply-chain heatmaps & procurement playbook — tiered supplier mapping for steel and electronic components, recommended dual-sourcing approaches, lead-time mitigation, and contractual language for component-indexed pricing clauses.
-
Regulatory and sustainability pathways — compliance checklists, zinc-replacement adoption scenarios, and lifecycle analyses to align product and packaging design with emerging environmental mandates.
-
Competitive benchmarking toolkit — profile matrices that map feature sets, production footprints, channel reach, and service capability for the principal vendors, plus a reproducible peer-comparison template.
-
Deal and M&A playbook — valuation sensitizers, integration checklists, and synergy capture templates focused on combining equipment manufacturing with service networks and consumables distribution.
-
Sales enablement & pilot KPIs — field playbooks, workshop scripts, and ROI calculators to accelerate trial deployments and shorten customer payback periods.
Competitive landscape — who matters and how they are positioning
The market structure shows a moderate concentration: the top three vendors control a meaningful plurality of market share, while the top five exceed half of the industry, creating a dual dynamic of scale-based competition and fragmented pockets of regional specialization. Against that backdrop, PW Consulting’s competitive chapter synthesizes product, channel and service differentiation among leading suppliers to reveal practical implications for competitors and customers alike.
-
CEMB S.p.A. (Italy) — breadth of touchscreen models and technical depth. CEMB’s portfolio spans passenger, truck and motorcycle applications and emphasizes automated gauges, laser spotters and 2-HIT productivity features that appeal to multi-service operators. Strategic takeaways: modular product lines support both export-led growth and targeted aftermarket campaigns.
-
Hunter Engineering (USA) — brand leader in integrated service workflows. Hunter’s SmartWeight® Elite and Road Force® series leverage intuitive touch experiences and automated centering/measurement features that reduce operator variability. Strategic takeaways: premium positioning with deep service integration creates recurring aftermarket upside.
-
Hofmann / Snap-on (North America operations) — productivity-first designs. The geodyna® and Armored Series optimize throughput with laser-assisted placement and power-clamping. Strategic takeaways: channel control via dealer networks and strong field-service offerings shores up installed-base monetization.
-
Coats Company (USA) — recent product innovation. The 2025 launch of the ProBalance E900 introduced diagnostic-first positioning: direct-drive mechanics paired with laser data entry and diagnostic analytics aimed at high-volume shops. Strategic takeaways: diagnostic capability is a high-return differentiator for shop customers and a lever for subscription services.
-
Giuliano and Corghi (Italy) — automation and operator ergonomics. These vendors emphasize super-automatic platforms, large TFT touch displays and rapid size detection to reduce cycle time. Strategic takeaways: automation commands price premiums in high-throughput segments if paired with extended warranties and remote support.
-
John Bean / Snap-on (North America ops) — mid-to-high productivity offerings. Semi-automatic touchscreen models and 3D imaging tools aim at cost-conscious buyers seeking productivity gains without full automation. Strategic takeaways: attractive targets for lease finance programs and distribution tie-ups with independent service chains.
-
Ravaglioli, Beissbarth and other European suppliers — focus on imaging, sonar detection and ergonomic interfaces. Strategic takeaways: strong OEM ties and regional service networks create resilient revenue streams even as technology features standardize.
Supply-chain and regulatory dynamics to watch in 2026
-
Input exposure: steel and electronics remain the principal cost drivers for wheel balancer manufacturing. Price volatility and lead-time variability in these inputs materially affect gross margins and production scheduling.
-
Zinc transition: environmental regulation is accelerating adoption of recyclable materials — notably zinc — in wheel weights and related components. Zinc’s recyclability is attractive but carries a material premium; we identify supplier strategies and product-design offsets to mitigate margin erosion.
-
Component sourcing: sensors, motors and control electronics concentrate sourcing risk. The report maps out tier-1 vs. alternative suppliers, qualification pathways, and recommended contractual protections (indexation, supply credits, and capacity reservation clauses).
Strategic playbook for action in 2026
-
Prioritize diagnostic and software features as revenue drivers — design devices for telemetry, predictive maintenance and paid diagnostic bundles rather than treating software as a secondary add-on.
-
Design differentiated tiers — entry, mid and premium configurations aligned to service throughput profiles, with clear migration paths and trade-in programs that accelerate repeat purchases.
-
Strengthen distribution economics — incentivize high-volume channel partners through performance-based rebates and integrated service bundles rather than one-time discounting.
-
Hedge input risk — adopt dual-sourcing and contractual indexation for steel and critical electronics; evaluate strategic inventory buffers during contractual negotiation windows.
-
Build sustainability into the value proposition — capture early-adopter premiums by offering zinc-compatible workflows and verified recyclability statements for buyers subject to regulatory scrutiny.
-
Prepare for consolidation and selective M&A — target acquisitions that add service footprint, consumables distribution, or software analytics capabilities rather than simple capacity plays.
-
Operationalize pilot-to-scale pathways — use the report’s ROI calculators and pilot KPIs to accelerate commercialization cycles and shorten time-to-revenue for new touchscreen-enabled models.
Next steps — where this preview leads you
This briefing is a strategic “trailer”: it reveals the macro trajectory, the competitive topology, and the practical playbooks that matter in 2026, while reserving the core, granular segmentation tables, regional and application splits, and detailed vendor revenue models for the full report. For commercial teams, product leaders, procurement heads and investors, the full dataset contains the operative figures and downloadable models required to build financial cases, perform cross-border scenario planning, and develop targeted sales initiatives.
To access the complete report, including the full set of regional analyses, application breakdowns, vendor scorecards, and downloadable financial models, please visit the PW Consulting publication page. The full dossier supplies the empirical backbone to convert the strategic directions outlined here into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Wheel Balancer With Touchscreen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com