

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Worldwide Dual-arm Robots Market to Expand at a Robust 12.85% CAGR (2026–2032) Driven by Collaborative Systems
By pmarketresearch, 2026-07-17
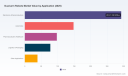
Worldwide Dual-arm Robots Market: Strategic Briefing for 2026 Decision-Makers
As organizations recalibrate automation roadmaps for resilience and precision, PW Consulting’s newest market study on Worldwide Dual-arm Robots empowers executives with the strategic perspective needed to act in 2026. The dual-arm category—spanning collaborative humanoid-style cobots to force-controlled, mobile systems—has moved beyond pilots to commercially meaningful deployments. Our analysis quantifies that shift: the market grew from approximately USD 365 million in 2020 to USD 655 million in 2025 (base year), and the model projects an expansion to roughly USD 1,527 million by 2032. The forecast period (2026–2032) is characterized by a 12.85% compound annual growth rate, underscoring a window of accelerated adoption that demands timely, risk-aware strategy.
Worldwide Dual-arm Robots Market
Why this matters for 2026
- Decision velocity: With a double-digit growth trajectory, 2026 will be a pivotal year for committing capital to pilot-to-scale transitions. Organizations that define selection criteria and procurement cadence now will capture outsized operational and talent benefits over competitors who delay.
- Complexity of choice: The market is neither a fragmented long-tail nor a tightly closed oligopoly—our concentration analysis shows meaningful market share among a handful of suppliers (CR3 ~48.2%; CR5 ~61.5%). This creates both opportunity and negotiation leverage for large volume buyers, while leaving room for differentiated entrants.
- Regulatory and ecosystem inflection: Recent updates to international and U.S. robot safety standards, coupled with supply‑chain dynamics for precision actuators and lightweight materials, mean that technical spec sheets alone will not be sufficient to de‑risk deployments.
Strategic imperatives for corporate leaders in 2026
- Prioritize modular pilots with clear scale triggers: Design proofs-of-concept that validate not only cycle time and quality gains but also integration effort, safety interlocks, and operator upskilling requirements. Use pilot exit criteria linked to TCO and risk thresholds.
- Institutionalize safety and compliance early: Incorporate ISO 10218-1:2025 and the updated ANSI/A3 R15.06-2025 guidance into technical and contractual specifications to avoid costly retrofits and certification delays.
- Adopt a supplier-risk scorecard approach: Evaluate vendors across performance, service footprint, roadmap maturity, parts supply resilience, and intellectual property posture—especially for force-control and vision-enabled systems.
- Move beyond capex-only thinking: Include operating models that capture software updates, digital twins, remote diagnostics, and the human capital investments necessary to sustain multi-cell deployments.
- Plan for complementary investments: AMRs, vision stacks, and end-of-arm tooling strategies often determine ROI more than the robot body itself—coordinate procurement and integration planning across functions.
What PW Consulting’s report gives you—practical tools, not just charts
This study is designed as an operational playbook for 2026, with deliverables tailored to executive and program levels. Highlights include:
Worldwide Dual-arm Robots Market
- Strategic decision frameworks that map organizational objectives (throughput, dexterity, co‑working, mobility) to the dual-arm technology archetypes best suited to achieve them.
- Vendor selection and contracting templates, including a weighted evaluation matrix for performance, lifecycle cost, spare parts lead time, and indemnity clauses tied to evolving safety standards.
- Deployment playbooks—step-by-step guides for pilot design, human-factors assessment, safety validation, and scale-up sequencing—reducing time from pilot to production line by an average of months in our field benchmarks.
- Financial models and TCO calculators built in USD million units that capture capex, integration, service, downtime risk, and anticipated productivity gains—enabling scenario planning under multiple labor-cost and material-sourcing assumptions.
- Supply-chain stress tests and sourcing recommendations for critical components (precision actuators, sensors, composites), including alternate-supplier pathways and inventory strategies to mitigate price volatility and lead-time shocks.
- Regulatory compliance matrix aligning ISO and ANSI revisions to engineering and certifying activities, plus recommended audit checklists for internal and third‑party inspectors.
- Operator reskilling roadmaps and change-management templates to ensure safe human–robot collaboration and to preserve institutional knowledge during automation transitions.
Competitive landscape—who’s shaping technology and go-to-market in 2026
Our market mapping identifies several established and fast-evolving suppliers whose product strategies are influencing buyer choices:
Worldwide Dual-arm Robots Market
- ABB (Zurich, Switzerland) : ABB’s IRB 14000 YuMi platform remains a reference point for collaborative dual-arm design—multi-axis dexterity paired with human-safe elements aimed at small-parts assembly in high-mix environments. ABB’s strong global service network and enterprise-grade integration capabilities make it a frequent option for blue‑chip manufacturers prioritizing uptime and certified safety pathways.
- Kawasaki Robotics (Tokyo, Japan) : The duAro series (SCARA dual-arm collaborative platforms) emphasizes safe human coexistence and compact cell footprints for assembly, handling and inspection. Kawasaki’s channel reach and proven reliability in traditional industrial segments make its offerings attractive where predictable performance and low integration complexity are primary considerations.
- Yaskawa Electric / Motoman (Kitakyushu, Japan) : The SDA family—slim, multi‑axis dual-arm robots—targets high-dexterity assembly and handling tasks that mimic human movement. Yaskawa’s strength lies in its depth of motion-control expertise and ecosystem of tooling, which suits projects that require precise choreography and production-grade reliability.
- Kawada Robotics (Tokyo, Japan) : Kawada’s NEXTAGE humanoid-style dual-arm robot positions itself for inspection, machine tending and packaging where environmental perception and human-like manipulation are needed. Its vision-enabled stack and task-focused design reduce integration time for specific production use cases.
- ROKAE Robotics (Beijing, China) : ROKAE is notable for integrating dual-arm force control with mobility (wheeled platforms), enabling embodied intelligence use cases like battery pack assembly and feedbox handling. Recent demonstrations show a push toward system-level solutions combining autonomy, force control, and dexterous manipulation.
Understanding these vendors’ differentiated value propositions helps buyers match capability to intent—whether the priority is cell-level co-working safety, high-dexterity assembly, or mobile material handling.
Signals from the field: why 2026 is different
- Productronica Shanghai and ITES Shenzhen (April 2026): ROKAE’s showcases of wheeled dual-arm systems and force-controlled demos for battery assembly indicate a commercialization push in advanced battery and electronics manufacturing.
- Hannover Messe 2026 (April 2026): Further global exposure for mobile dual-arm demonstrations illustrates cross-regional interest in embodied automation solutions that combine mobility, perception, and two-handed manipulation.
- South Korea first-field demo (April 2026): A live dual-arm cobot mounted on an AMR platform began on-site field trials in Daegu—evidence that integrated mobile-cobot solutions are moving from labs to live production floors, with implications for AMR‑robot interoperability standards.
Regulatory and supply-side dynamics to factor into 2026 plans
Updated safety standards—ISO 10218-1:2025 and the revised ANSI/A3 R15.06-2025—place new emphasis on system-level risk assessment, particularly for collaborative and multi‑robot configurations. Procurement teams must require compliance demonstrations at contract signature, not as a post-deployment checkbox.
On the supply side, dual-arm platforms are sensitive to actuator, sensor, and lightweight-structure pricing and lead times. Buyers should incorporate component availability scenarios into procurement cycles and consider multi-source strategies for critical subsystems to prevent deployment delays and cost overruns.
How PW Consulting’s insights translate into board-level actions
- Capital allocation: Use our scenario-based TCO models to test capex assumptions under varying labor rates and uptime targets—allowing boards to allocate automation budgets to programs with the strongest risk-adjusted returns for 2026–2028.
- M&A and partnerships: Identify where strategic partnerships or bolt-on acquisitions accelerate capabilities (force-control, mobility, vision) rather than building from scratch. Our vendor maps reveal white spaces where technology and distribution capabilities are misaligned.
- Operational readiness: Adopt our deployment playbooks to reduce integration cycle time, specifying training hours per operator, safety validation steps, and spare-parts provisioning tied to uptime commitments.
- Procurement strategy: Negotiate service-level agreements and spare-part consignment models before first-article production; leverage market concentration dynamics to secure favorable pricing and lead-time protections.
About the report—and what you’ll need to see in the full version
The PW Consulting Worldwide Dual-arm Robots Market report (base year 2025) combines bottom-up vendor analysis, primary interviews, and scenario-driven financial models to produce an actionable body of work for 2026 decision-makers. This press summary highlights directional findings and strategic recommendations while intentionally withholding full segmentation tables and granular vendor share matrices to guide readers to the full report for proprietary datasets, model templates, and executable procurement artifacts.
Next steps
PW Consulting is offering executive briefings and custom deep dives aligned to buyer archetypes—OEMs, contract manufacturers, integrators, and investors—throughout 2026. For organizations ready to move from strategy to scale, the full report contains the vendor scorecards, TCO tools, compliance matrices, and deployment playbooks you will need to operationalize dual-arm robotics programs with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Dual-arm Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide On‑Demand Staffing Market Poised for Rapid Growth — 17.5% CAGR Projected Over 2026–2032, Report Finds
By pmarketresearch, 2026-07-17
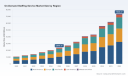
Worldwide On-Demand Staffing Service Market: Strategic Imperatives for 2026 — PW Consulting Insights
As the on-demand staffing economy matures beyond early adopters into mainstream enterprise supply chains and HR strategies, organizations face a rapidly shifting competitive and regulatory landscape. PW Consulting’s latest Worldwide On-Demand Staffing Service Market report synthesizes five years of historical performance and a detailed 2026–2032 forecast to equip leadership teams with the intelligence they need to make decisive investments next year. The market expanded from roughly USD 10.8 billion in 2020 to about USD 23.9 billion in 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of 17.5%, reaching in excess of USD 73.8 billion by 2032. This release summarizes the report’s strategic value for 2026 decision-making, highlights actionable implications, and outlines the executive playbook we recommend.
Worldwide On-Demand Staffing Service Market
Why this matters for 2026 planning
- Rapid scale, sustained margin pressure: The market’s high CAGR signals accelerating enterprise adoption, but also rising buyer sophistication and downward pricing pressure in commoditized segments. Procurement teams must balance cost with platform reliability, compliance support and integration capability.
- Technology and integration become table stakes: Demand-side systems (HRIS, scheduling, ERP, WFM) and supply-side platform architectures (mobile-first matching, payrails, verification) are increasingly decisive selection criteria for large customers.
- Regulation is reshaping economic models: Recent labor and data rules materially affect operating cost, classification risk and vendor selection. Organizations that proactively bake compliance into vendor contracts and TCO models will avoid costly disruptions in 2026.
- Specialization unlocks premium value: Vertical-focused providers and white-glove models continue to command price premiums in high-regulation or high-skill sectors, providing a hedge against generalized marketplace competition.
What PW Consulting’s report delivers (practical, operational intelligence)
Our report is designed as a working toolkit for procurement, HR, operations and corporate development teams preparing 2026 budgets and sourcing strategies. Key deliverables include:
Worldwide On-Demand Staffing Service Market
- Transparent market-sizing and forecast model (2020–2032) with scenario variants for high-growth and constrained regulation outcomes.
- Vendor scorecards and capability matrices covering market leaders, scale specialists, and adjacent freelance marketplaces — scoring across integration, compliance, worker model (W2 vs contractor), vertical expertise and unit economics.
- Operational playbooks for pilot design, vendor onboarding, SLA construction, worker verification, and payrail integration — including a sample procurement RFP template and checklist.
- Total cost of ownership (TCO) and ROI calculators tailored to different buyer archetypes (logistics hubs, hospitality chains, retail networks, healthcare facilities) to model labor mix and flexibility benefits.
- Regulatory impact assessments and mitigation checklists for North America, the European Union and selected APAC jurisdictions, including template contract clauses and compliance KPIs.
- M&A and partnership due diligence framework, with red flags specific to gig and on-demand staffing businesses (worker classification liabilities, legacy tech debt, contingent workforce insurance exposures).
Strategic signals from the data
Several cross-cutting trends emerge from our analysis that will shape winner strategies in 2026:
Worldwide On-Demand Staffing Service Market
- Enterprise adoption is broadening beyond ad hoc staffing: Large operators increasingly use on-demand platforms to manage peak capacity and last-mile labor variability rather than as a purely tactical stopgap.
- Mobile-first user experiences accelerate worker acquisition and retention: Platforms with top-tier mobile UX and quick payout features show materially higher fill rates in time-sensitive verticals.
- Hybrid workforce models proliferate: Employers are combining W2, contractor and internal flex pools to manage risk and maintain service continuity—favoring platform partners that can demonstrate audited compliance workflows.
- Cost inflation and insurance pressure persist: Rising hourly wage baselines and increased insurance burdens (notably workers’ compensation and payroll-related costs) compress margins for intermediaries unless offset by automation or vertically specialized pricing.
Competitive landscape — who matters and why
The market is characterized by a mix of specialist on-demand staffing platforms and global freelance marketplaces. PW Consulting’s vendor analysis highlights three structural archetypes:
- Vertical specialists focused on hourly, location-based work (examples include platforms connecting vetted hourly workers for warehousing, hospitality and events). These firms differentiate through local density, vetted talent pools and operational integrations with frontline systems.
- W2-centric operators that hire workers as employees to offer higher compliance assurances and enterprise-grade SLAs—appealing to customers with acute classification risk concerns.
- Global freelance marketplaces that serve skilled, project-based demand across knowledge work; these players compete more on breadth and flexible contracting rather than onsite hourly fulfillment.
Representative names we profile in depth include firms that lead in mobile-based on-demand matching and enterprise integrations, W2-staffing platforms that prioritize compliance and benefits, and large marketplaces that bring scale and cross-border reach. Recent corporate developments underscore strategic trajectories: partnerships to embed staffing into HRIS ecosystems, geographic expansions into new markets, and fresh capital injections to scale operations. These moves reflect a market simultaneously consolidating at scale players while leaving openings for niche, high-value providers.
Regulation, compliance and risk — what 2026 buyers must plan for
Regulatory initiatives in 2023–2024 have materially changed the compliance baseline for platform operators and their customers. Important developments include finalized rules on worker classification, platform work directives requiring written contracts and payment transparency, and data-protection amendments that increase vendor accountability for worker data. From a buyer’s perspective, these forces translate into:
- Higher verification and contractual compliance costs embedded in vendor pricing.
- Increased liability transfer through indemnities, insurance thresholds and contractual representations—requiring robust compliance audits during vendor selection.
- Operational resilience needs: platforms must deliver audit-ready documentation for payroll, tax and social benefits to minimize downstream risk.
Companies must also quantify labor-cost volatility: wage baseline inflation and insurance percentages materially affect the value proposition of on-demand staffing vs. alternative labor models. Our report provides regulatory scenario models and a compliance checklist to operationalize these inputs into 2026 budgets.
Actionable playbook for 2026 (executive checklist)
- Prioritize pilots that test full-stack integration: run small-scale pilots that connect your HRIS/WFM and the vendor’s payrail to validate end-to-end SLAs before scaling.
- Score vendors on compliance observability: require vendors to supply real-time compliance dashboards and third-party audit reports as part of procurement evaluation.
- Design a hybrid workforce policy: set explicit rules for when to use W2 providers, contractor-based platforms and internal pools to control classification risk.
- Embed regulatory scenarios into your TCO model: stress-test budgets against wage inflation, insurance increases and potential classification remediation costs.
- Use M&A diligence checklists: for in-market acquisitions, prioritize historical claims data, payroll reconciliation practices and data-protection controls as deal breakers.
Market concentration and competitive implications
The market displays moderate concentration among the largest providers, with top-three and top-five aggregates indicating that while scale advantages exist, the opportunity for regional specialists and vertical specialists remains meaningful. For incumbents and new entrants alike, focus areas that create defensibility include proprietary worker verification, deep vertical workflows, enterprise-grade integrations and compliance-as-a-service offerings. Strategic partnerships—particularly embedding staffing into HR and ERP ecosystems—are accelerating as a path to capture larger, sticky enterprise customers.
The PW Consulting differential — why this report is operational
Many studies stop at high-level growth curves. Our report is intentionally operational: we provide procurement documents, playbooks, vendor scoring rubrics and integrated financial models that translate market projections into budget-ready inputs. We also include validated case studies across logistics, hospitality, retail and healthcare that show the real-world levers that drive ROI and risk mitigation.
What’s intentionally withheld here — and where to find it
In this briefing we present the strategic signals and top-line forecast to inform 2026 planning. To preserve the value of the full market intelligence and to support rigorous procurement and diligence processes, detailed segmentation tables (regional splits, application-level shares, granular vendor financials and per-vertical pricing models) are available exclusively in the full PW Consulting report and our downloadable datasets. Buyers and investors who require these granular inputs, model files, and vendor scorecards should consult the full report page on PW Consulting’s website for access.
Conclusion — a 2026 lens
As organizations finalize 2026 budgets, the on-demand staffing market requires a disciplined response that combines tactical pilots with strategic supplier changes. The market’s strong growth trajectory presents both upside for organizations seeking flexible capacity and a mandate to fortify compliance and integration capabilities. PW Consulting’s Worldwide On-Demand Staffing Service Market report converts market momentum into executable steps—helping leaders reduce execution risk, optimize labor costs and capture operational agility in the year ahead.
For detailed analysis of this topic, please visit the official page: Worldwide On-Demand Staffing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Eco‑Friendly Bitumen Market Poised for Rapid Expansion — 12.54% CAGR Projected During 2026–2032
By pmarketresearch, 2026-07-15
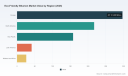
Worldwide Eco-Friendly Bitumen Market: Strategic Intelligence to Shape 2026 Decisions
PW Consulting’s new market study on the Worldwide Eco-Friendly Bitumen Market distils five years of historical performance and a seven‑year forecast into an operational playbook for strategy, procurement, R&D and M&A in 2026. The eco-friendly bitumen market has shown rapid expansion — rising from USD 410.6 Million in 2020 to USD 740.0 Million in 2025 — and our base‑case projects it to reach USD 886.36 Million in 2026, growing at a compound annual growth rate (CAGR) of 12.54% through the 2026–2032 forecast window (ending near USD 1.69 Billion in 2032). This momentum, together with a market concentration where the top three players account for roughly 32.4% and the top five for about 45.2%, creates a distinctive set of strategic imperatives for corporate leaders entering 2026.
Why this report matters for 2026 planning
- Timing the transition: The market is transitioning from pilot deployments to mainstream specification acceptance. The projected step‑up in absolute market value in 2026 signals an inflection point where technology selection, feedstock contracts and scale investments must be synchronized.
- Regulatory-enabled demand: Binding and emerging mandates — most notably regional public procurement requirements — mean that product certification and compliance will be decisive for winning public contracts starting in 2025–2026.
- Margin & feedstock pressure: Raw material volatility (for example, vegetable oil prices rose ~12% YoY to about USD 1,200/MT in Q4 2024) is already affecting input cost structures; procurement strategies and feedstock flexibility will determine winners.
- Consolidation window: Moderate market concentration and fast growth create fertile ground for scale‑seeking acquisitions, selective joint ventures, and capability buys in 2026 to secure regional access and technical competencies.
What PW Consulting’s report delivers — practical, transaction‑ready intelligence
- Proprietary market sizing and a forward model calibrated to 2025 as the base year, with scenario outputs (base, accelerated adoption, supply‑constrained) to stress test 2026 budgets.
- Regulatory roadmap and certification tracker (including timelines and likely acceptance thresholds) that map which product attributes unlock public‑sector tenders in key jurisdictions.
- Feedstock risk matrix and blended cost curves — actionable for procurement teams to negotiate multi‑year contracts and design hedging strategies.
- Technology readiness and performance benchmarking for bio‑based binders, recycled rubber blends and plastic‑modified bitumens, paired with on‑road lifecycle carbon and performance trade‑offs.
- Supplier scorecards, manufacturing footprint optimization and a shortlist of M&A targets ranked by strategic fit, integration complexity and near‑term revenue accretion potential.
- Commercial playbooks: pricing models, public tender positioning, and pilot‑to‑scale templates that accelerate route‑to‑revenue while protecting margin.
- Case studies and pilot data: real‑world outcomes for warm‑mix, high‑recycled content mixes, and rejuvenated asphalt overlays to support technical and commercial due diligence.
Note: To preserve the integrity of market negotiations and to encourage direct engagement, we intentionally limit disclosure of granular subsegment valuations and regional/application splits in this release. Full tables, models and the interactive forecast dashboard are available on the PW Consulting report page.
Competitive landscape: who matters and what they are doing
The eco‑friendly bitumen value chain is populated by a mix of specialist innovators, incumbent energy players expanding into bio‑modified binders, and regional innovators focusing on recycled‑content mixes. The competitive map reveals distinct strategic archetypes — technology innovators, feedstock integrators, and networked incumbents — each requiring different response strategies in 2026.
- Green Asphalt (USA) — A specialist in bio‑based asphalt binders using non‑petroleum oils as partial replacements. Having recently expanded U.S. production capacity to 50,000 tonnes/year (March 2024), Green Asphalt exemplifies a scale‑through‑specialization strategy. Their trajectory is relevant to firms planning North American supply partnerships or looking to secure feedstock verticals.
greenasphalt.com - Iterchimica (Italy) — Focused on rejuvenator chemistry, Iterchimica’s ReRoad product recently received EN 15381 certification (June 2024), removing a major commercial barrier for recycled asphalt use on EU highways. Their approach — chemistry + certification — demonstrates the high leverage of validated product standards in unlocking large public projects.
iterchimica.it - Bituchem (UK) — Offers bio‑enzyme modified bitumen for warm‑mix asphalt applications that lower production temperatures and CO2 emissions. Bituchem represents firms that compete on process energy arbitrage and emissions intensity — a valuable differentiator where carbon pricing or tender scoring favors low‑temperature technologies.
bituchem.com - Eco Asphalt (Canada) — Manufactures mixes with high recycled content and bio‑binders derived from lignin and vegetable oils. Their integrated recycled‑content model is instructive for asset‑heavy players exploring in‑house recycling streams and municipal partnerships.
ecoasphalt.ca - Colas (France) — As a large networked incumbent, Colas markets low‑carbon bituminous ranges combining bio‑sourced binders and recycled aggregates. Their scale and downstream construction capabilities illustrate the advantages incumbents hold in rapid specification rollout for public projects.
colas.com - Shell Bitumen (Netherlands) — Expanding into renewable blend content, Shell launched a bio‑naphtha modified product in October 2024 for European markets, claiming up to 50% lower CO2 emissions for certain mixes. Shell’s participation underscores big‑energy entrants’ ability to leverage feedstock supply and certification to compete on carbon intensity and logistics.
shell.com
For corporates evaluating partnerships or acquisition targets in 2026, PW Consulting’s supplier scorecards and integration risk matrices expose technology readiness, IP defensibility and contract ramp timelines for each of these archetypes.
Regulatory and supply dynamics shaping 2026 priorities
- Procurement mandates: The European Green Deal’s requirement for minimum bio‑based content in public road asphalt contracts (10% starting 2025) materially raises the floor for product specifications and accelerates scale demand for certified bio‑binders.
- Standards convergence: The U.S. adoption of AASHTO MP 45‑24 (effective January 2024) creates a pathway for accelerated federal and state procurement in North America, but only for products that pass the new test regimen — elevating the value of certification programs.
- Tariff & trade frictions: Trade policy is a near‑term constraint — for example, a 25% U.S. tariff on imported bio‑binders from China (Feb 2025) raises landed costs and reorients sourcing decisions, benefiting domestic producers or alternative origin suppliers.
- Feedstock volatility: Vegetable oil price inflation (~+12% YoY to USD 1,200/MT in Q4 2024) already pressures margins for bio‑based formulations and increases the value of feedstock diversification (lignin, waste oils, pyrolysis oils) and contract hedging solutions.
Actionable recommendations for 2026
- Prioritize certifications now: Firms should allocate budget and lab resources in H1 2026 to secure regional certifications (EN, AASHTO, national standards). Certification is the gate to public demand and materially shortens sales cycles when procurement rules mandate bio‑content.
- Hedge feedstock and diversify suppliers: Negotiate multi‑year agreements with blended feedstock clauses, and qualify at least one secondary feedstock source to mitigate vegetable oil price spikes and trade disruptions.
- Design pilots that scale: Structure pilot contracts with municipalities and highway agencies to include stepwise volume commitments and performance‑linked payments so that pilots cascade into large public work packages.
- Targeted M&A and partnerships: Use the market concentration data and PW Consulting’s M&A shortlist to identify targets that fill capability gaps — chemistry, recycling logistics or local plant footprint — enabling rapid market share capture as demand accelerates.
- Embed LCA into commercial offers: Carbon‑lifecycle claims will be decisive in tender scoring; integrate verifiable LCA outputs into bids and customer dashboards to capture price premiuмs tied to decarbonization outcomes.
How PW Consulting supports your 2026 playbook
This study is structured to be immediately operational: plug our forecast outputs into your capital allocation model, extract supplier scorecards for procurement RFPs, and deploy the policy and certification timelines in your bid strategy. For deal teams, our integration risk scores and valuation multipliers provide a short list of targets most accretive under base and accelerated adoption scenarios.
We have intentionally limited the disclosure of detailed regional, type and application split figures in this release to preserve negotiation leverage for our clients and partners. The full report and interactive dataset — including subsegment tables, sensitivity scenarios, and downloadable financial models (USD Million unit basis) — are available on the PW Consulting report portal.
Next steps
- Download the full report to access the interactive forecast dashboard and subsegment tables.
- Book a consulting session for a customized 90‑day implementation plan aligned to your 2026 budget cycle.
- Request the supplier scorecard and M&A shortlist to accelerate procurement and strategic transactions.
In 2026, decision windows will be short and the rewards for being first‑to‑specification will be large. PW Consulting’s Worldwide Eco‑Friendly Bitumen Market study equips leaders with the market, technical and commercial intelligence needed to convert policy momentum into scalable, profitable deployments.
For detailed analysis of this topic, please visit the official page: Worldwide Eco-Friendly Bitumen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Ice‑Cream Premix & Stabilizer Market Tops USD 1,485.6 Million in 2025, Poised for 5.12% CAGR Through 2032
By pmarketresearch, 2026-07-15
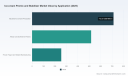
Worldwide Ice-cream Premix and Stabilizer Market: Strategic Insights for 2026 Decision-Making
Executive snapshot
As global frozen dessert consumption matures, the market for ice‑cream premixes and stabilizers is evolving from a largely commodity-driven ingredient trade into a platform for product innovation, regulatory differentiation and supply‑chain resilience. PW Consulting’s latest market study — anchored to a 2025 base year and projecting through 2032 — shows steady expansion at a mid-single‑digit compound annual growth rate (CAGR). This trajectory masks important inflection points that will determine winners and laggards in 2026: raw material volatility, tightening additive and packaging rules in major markets, and an intensifying competitive focus on clean‑label and plant‑based systems.
Worldwide Ice-cream Premix and Stabilizer Market
Why this report matters for decisions in 2026
- Timing of regulatory change: New EU rules published in early 2026 introduce stricter specifications and compliance windows for food additives and packaging. Manufacturers and ingredient suppliers must map reformulation or documentation plans to these timelines now to avoid lost access to key markets.
- Cost and ingredient risk: Dairy input dynamics — including the continuing role of long‑life dairy ingredients and regional milk price trajectories — are directly impacting premix cost structures and margin profiles. Procurement strategies that were sufficient in 2024 will not be robust against the 2026 commodity environment.
- Acceleration of functional innovation: Demand for melt‑resistance, heat‑shock stability and plant‑based texture solutions is shifting R&D investment toward specialized emulsifier‑stabilizer systems and premix formats that can be deployed at industrial and artisanal scales.
- Consolidation and capacity moves: Strategic M&A and footprint expansion by ingredient multinationals are changing supplier options and bargaining dynamics for co‑packers and private‑label manufacturers.
Core findings (teaser)
Our modeling, which synthesizes primary interviews, plant‑level cost build‑ups and trade‑show intelligence, confirms continued market growth through the forecast window, underpinned by product premiumization and the proliferation of non‑traditional frozen desserts. However, the growth path is non‑linear: episodic commodity spikes, regulatory shocks and accelerated product innovation will create differentiated outcome scenarios across geographies and customer segments. PW Consulting’s report provides probabilistic scenario maps that translate these macro drivers into actionable revenue and margin implications for 2026 planning cycles.
Worldwide Ice-cream Premix and Stabilizer Market
What the full report delivers (practical deliverables)
- Detailed, bottom‑up market sizing and forecasting to 2032, with sensitivity runs for commodity and regulatory scenarios.
- Raw material cost model calibrated to 2020–2025 history and updated to capture forward price signals, enabling transparent margin shock analysis for premix and stabilizer formulations.
- Regulatory impact matrix covering Codex, new EU additive rules, packaging obligations and major national frameworks, with compliance timelines and recommended mitigation pathways.
- Supplier scorecards and capability audits across formulation expertise, production footprint, certification coverage and go‑to‑market support.
- Commercial playbooks for value capture — including segmentation strategies for industrial vs artisanal channels, route‑to‑market options, pricing levers and private‑label approaches.
- M&A and partnership screening: target lists, valuation benchmarks and integration risk checklists for both horizontal and vertical plays.
Competitive landscape — strategic read
The supplier ecosystem ranges from ingredient specialists rooted in hydrocolloids and emulsification systems, to premix manufacturers that combine flavor, dairy solids and functional blends into customer‑ready formats. Key strategic archetypes observed in market intelligence are:
Worldwide Ice-cream Premix and Stabilizer Market
- Formulation specialists: Firms that focus on bespoke emulsifier‑stabilizer chemistry and application engineering, offering solutions for creaminess, meltdown control and plant‑based replacements.
- Ready‑to‑use premix manufacturers: Companies that deliver powder and liquid mixes optimized for soft‑serve, gelato and industrial processes, often with private‑label and co‑packing services.
- Raw material integrators: Large ingredient groups that bundle texturants, sweeteners and functional blends as part of broader food ingredient portfolios and global supply chains.
Several established players are executing clear strategic moves that merit attention from buyers, investors and competing suppliers. For example:
- European formulation houses continue to leverage deep application know‑how to serve gelato and specialty segments, while expanding certifications and export networks.
- Multinationals with broad ingredient portfolios are accelerating tailored blends for plant‑based and low‑sugar variants, positioning premixes as solution platforms rather than commodity inputs.
- Regional manufacturers in high‑growth markets are emphasizing customization, cost‑to‑serve and rapid time‑to‑market for foodservice and artisanal chains.
Notable company actions and implications
- Strategic capacity moves by ingredient suppliers in 2025–2026 are reshaping regional sourcing options and shortening lead times — a trend that favors buyers prioritizing reliability and quality certification.
- High‑profile product showcases and trade‑show launches have highlighted the push toward indulgence with health positioning — blends that deliver creaminess with lower sugar or dairy content are becoming table stakes for premium launches.
- Recent asset acquisitions and footprint expansions by global stabilizer producers signal a wave of near‑shoring aimed at lowering logistics risk and meeting localized regulatory and labeling requirements.
Industry dynamics to watch
- Regulatory compliance windows: New EU additive and packaging regulations impose compliance milestones that will affect reformulation timelines, labeling and packaging redesign costs.
- Raw material exposure: Long‑life dairy ingredients remain central to many premix formulations and are a material driver of cost. Buyers should assume continued sensitivity to milk price movements in 2026 contracting.
- Clean‑label and plant‑based substitutions: Demand is pushing suppliers to validate alternatives that replicate textural function without compromising stability in industrial freezing processes.
- Channel bifurcation: Industrial producers require scale‑grade solutions and consistent performance; artisan and soft‑serve operators prize flexibility, flavor breadth and faster innovation cadences. Each requires distinct commercial and technical support models.
Strategic recommendations for 2026
Across the value chain — from premix producers and ingredient suppliers to co‑packers and private‑label brands — the following moves should be prioritized in 2026 decision calendars:
- Lock in multi‑tier supply: Build contract layers that combine indexed spot exposure with longer‑dated fixed agreements for key dairy and hydrocolloid inputs, and stress‑test contracts against regulatory compliance costs.
- Accelerate formulation modularity: Invest in modular premix platforms (base + functional add ons) to speed customer customization while preserving manufacturing efficiency.
- Regulatory first‑mover advantage: Use early compliance investments (e.g., documentation, micro testing, packaging redesign) as a market differentiator in regions where enforcement timelines are converging in 2026–2028.
- Commercial segmentation: Reconfigure sales motions to separate industrial, artisanal and foodservice clients; each segment demands different margin structures, SKU rationales and co‑innovation programs.
- M&A and partnerships: Pursue bolt‑on capabilities for plant‑based functionality or regional finishing capacity, prioritizing targets that add application know‑how and shorten time‑to‑market.
How PW Consulting supports your 2026 agenda
Our Worldwide Ice‑cream Premix and Stabilizer Market report is designed as an operational decision tool: it contains modular dashboards, supplier due‑diligence templates, regulatory compliance playbooks and scenario models that translate macro trends into actionable commercial and technical plans. Clients also receive tailored advisory sessions to convert findings into 100‑day and 12‑month roadmaps aligned to procurement cycles and product launch calendars.
For procurement directors, R&D heads and corporate strategists preparing 2026 budgets and growth initiatives, the report provides the evidence base and execution templates necessary to de‑risk product pipelines and capture share amid regulatory and cost pressures. To explore the full dataset, proprietary segment breakdowns and supplier scorecards that underpin these recommendations, please consult the full PW Consulting release and accompanying online intelligence portal.
For detailed analysis of this topic, please visit the official page: Worldwide Ice-cream Premix and Stabilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Pen Insulin Syringe Market to Reach USD 5.43 Billion by 2032 at a 7% CAGR, Fueled by Homecare Dominance
By pmarketresearch, 2026-07-15
Worldwide Pen Insulin Syringe Market — Strategic Outlook for 2026
Executive summary
As healthcare systems and diabetes care pathways continue their rapid evolution, pen insulin syringes remain a foundational component of ambulatory and home-based diabetes management. PW Consulting’s newly published market study — based on a 2025 base year and a 2026–2032 forecast horizon — projects the global pen insulin syringe market to expand at a compound annual growth rate (CAGR) of 7.0% through the forecast window. The market, measured in USD millions, advances from a 2025 baseline into materially larger scale by 2032 under our central scenario.
Worldwide Pen Insulin Syringe Market
For executives making 2026 decisions — whether portfolio prioritization, manufacturing investments, channel realignment, or M&A — this study is designed as a pragmatic roadmap. It balances quantitative rigor (top-line sizing, scenario modelling, market-concentration analytics) with executable recommendations that anticipate regulatory and reimbursement shifts, new device-clearance dynamics, and the accelerating intersection of disposable consumables with digital insulin-delivery ecosystems.
Worldwide Pen Insulin Syringe Market
Market sizing and trajectory — what the headline data means for strategy
Our top-line estimates confirm a resilient, mid-single-digit-to-high-single-digit growth market. After steady expansion in the historical 2020–2025 window, the market is forecast to grow at a 7.0% CAGR across 2026–2032. This trajectory is driven by three demand vectors: continued prevalence growth of diabetes in aging and urbanizing populations, sustained uptake of pen-based insulin therapies in non-hospital settings, and incremental per-patient consumption gains supported by trends in needle design and user preference.
Worldwide Pen Insulin Syringe Market
From a strategic planning standpoint, two implications are immediate. First, the absolute market scale and growth profile justify targeted investments in production capacity and supply-chain resilience for manufacturers that can secure durable share. Second, growth is neither uniform nor frictionless — regulatory compliance, reimbursement positioning, and device-differentiation (safety features, needle ergonomics, digital connectivity) are decisive levers for share shifts in 2026 and beyond.
Regulatory and reimbursement dynamics shaping 2026 choices
- ISO and quality frameworks: Compliance with ISO 11608-2 (needle-based injection systems), ISO 9626 (stainless steel tubing), ISO 13485 (medical device QMS) and ISO 11607 (sterile packaging validation) is non-negotiable. Companies must treat compliance as a strategic capability, not a checklist — audits and supply validations will increasingly influence procurement awards.
- Reimbursement movements: Recent payer actions (including targeted Medicaid plan designations) demonstrate that payer formularies can shift preference toward specific branded suppliers without prior authorization. This creates both upside (preferred listings = volume stability) and downside risks (rapid volume migration for non-favored suppliers).
- Clearance and product innovation: Regulatory clearances for integrated or smart-delivery systems — and approvals for user-fillable pen formats — expand clinical and commercial options. These clearances accelerate the convergence of consumable pen needles/syringes with digital dose-capture and sensor ecosystems, altering value propositions for OEMs and service partners.
What the PW Consulting report delivers — operational, commercial and M&A use cases
This study is built as a decision tool for 2026. Key deliverables include:
- Robust top-line market sizing and growth scenarios (base, upside, downside) with sensitivity testing for key variables such as reimbursement shifts, regulatory timing, and pricing pressure.
- Commercial due diligence packs: pricingbenchmarks, channel margin matrices, tender-playbooks for national procurement, and provider-preference drivers for homecare versus institutional settings.
- Competitor dossiers and capability maps featuring clinical differentiation, manufacturing footprint, regulatory posture, and digital connectivity roadmaps.
- Supply-chain stress-testing: supplier concentration analytics, lead-time modelling, and contingency playbooks for raw-material or capacity disruption.
- M&A and partnership screening: a prioritized list of targets and partnership archetypes (CMOs, digital add-on firms, regional distributors), with expected deal economics under multiple integration scenarios.
- Actionable GTM (go-to-market) playbooks and a stakeholder-ready executive slide kit to accelerate board and investor discussions.
Competitive landscape — who matters and how to map opportunity
The pen insulin syringe landscape is concentrated: our CR3 and CR5 analysis shows a market where the top three players account for a substantial majority of share, and the top five consolidate an even larger proportion. This concentration raises barriers to entry for commoditized supply, while opening white-space opportunities in specialty niches — e.g., safety-engineered needles, connected add-ons, and cost-competitive regional supply.
Key strategic profiles to watch:
- Embecta Corp. (formerly BD Diabetes Care) — A global leader in insulin injection devices, with broad market reach and strong formulary positioning in some payer systems. Embecta’s scale and channel access make it a default partner for large-volume tenders; monitoring its reimbursement wins is essential for competitor scenario planning.
- Becton, Dickinson and Company (BD) — A major OEM in pen needles and safety-engineered disposable syringes. BD’s emphasis on precision and needle-safety positions it well for institutional tenders and markets where occupational safety is a procurement priority.
- Ypsomed AG — Differentiates on high-precision pen systems and nascent digital connectivity. For firms seeking to play in the smart pen value chain, Ypsomed exemplifies the blend of mechanical expertise and digital-forward product development.
- Terumo Corporation, NIPRO Corporation and B. Braun SE — Each combines manufacturing quality with regional strengths. These firms often compete on a mix of premium and cost-efficient offerings, and their manufacturing footprints can be decisive in supply-constrained scenarios.
- HTL-STREFA (MTD Group) — A strong player in safety pen needles with notable North American presence; its brand-driven approach targets both safety and value-conscious buyers.
- Insulin pen OEMs (Novo Nordisk, Eli Lilly, Sanofi) — While primarily insulin manufacturers, their vertically-integrated or co-marketed pen solutions influence accessory markets (needles and syringes) via compatibility, bundled strategies and brand loyalty.
- Regional and emerging suppliers — Several Asian and Indian manufacturers provide cost-competitive alternatives and play important roles in tender-backed markets. Their presence increases price elasticity and is a key variable in our downside scenarios.
Recent industry events underline how quickly dynamics can shift: regulatory clearances for integrated smart-delivery systems and CE-mark approvals for user-fillable pen formats create new commercial vectors that incumbents and challengers must account for in 2026 planning cycles.
Strategic recommendations for 2026 decision-makers
- Manufacturers — Prioritize regulatory and QMS investments to meet ISO standards end-to-end; accelerate integration pathways with digital dosing ecosystems; pursue selective capacity expansion in geographies tied to major payers and tenders; and evaluate bolt-on M&A for digital or regional-fill capabilities rather than large greenfield bets.
- Payers and procurement leads — Reassess total cost of care: device selection should be evaluated alongside adherence outcomes, safety incident reduction, and downstream utilization. Opportunistic preferred-list negotiations can secure savings and supply predictability but require validated quality and supply assurances.
- Investors and PE firms — Look for consolidation plays that combine manufacturing scale with digital differentiation or distribution footholds in high-growth outpatient channels. Validation of ISO-compliant manufacturing and existing payer relationships materially de-risks target screens.
- Hospitals and integrated delivery networks — Consider multi-year contracting for safety-engineered products to reduce occupational incidents, matched with clinician education programs to protect adoption and realize projected efficiency gains.
Why this report is a strategic must-read for 2026
Our study is intentionally practice-oriented: it translates macro growth rates and concentration metrics into specific choices that will determine share and margin trajectories over the next 18 months and beyond. It is designed as a “trailer” — demonstrating analytical depth and line-of-sight into the levers that matter for 2026, while reserving granular segment and country-level forecasts, supplier scorecards, and downloadable financial models for the full report package.
Next steps
- If you are preparing a 2026 capital plan, priority list, or M&A pipeline, the full report’s scenario models and supplier scorecards will provide the input you need to stress-test assumptions.
- For commercial teams, the included tender-playbooks and pricing decks accelerate go-to-market execution in both public and private channels.
- For investors, our diligence annexes and target screening matrices cut weeks from conventional underwriting workstreams.
About PW Consulting
PW Consulting is a strategic advisory firm specializing in medical devices and life‑science commercial strategy. Our global industry analysts combine primary market engagement, regulatory expertise, and financial modelling to produce decision-ready deliverables. For access to the full Worldwide Pen Insulin Syringe Market report — including detailed segment-level forecasts, country breakdowns, competitor scorecards and an Excel modelling appendix — visit the PW Consulting publications portal or contact our industry desk to request the complete dossier.
For detailed analysis of this topic, please visit the official page: Worldwide Pen Insulin Syringe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Intra‑Articular Injection Market to Surge to USD 12.08 Billion by 2032
By pmarketresearch, 2026-07-15
Worldwide Intra-Articular Injection Market: A Strategic Playbook for 2026 Decision-Makers
Executive summary
The intra-articular injection market has entered a period of accelerated, structurally-driven expansion. Our latest report—Worldwide Intra-Articular Injection Market (base year 2025)—shows the market expanding from approximately USD 4.45 billion in 2020 to roughly USD 6.66 billion in 2025, with a forecast trajectory that reaches in excess of USD 12.0 billion by 2032. The underlying compound annual growth rate across the forecast window is 8.87%—a pace that demands strategic recalibration across R&D, commercial, regulatory and M&A agendas.
Worldwide Intra-Articular Injection Market
PW Consulting’s analysis is designed as a practical decision-support tool for executives who must translate these macro dynamics into high-confidence 2026 plans. This release previews the report’s most consequential takeaways while reserving the granular segmentation tables and proprietary model outputs for subscribers and authorized stakeholders.
Worldwide Intra-Articular Injection Market
Why this matters for boardrooms and business unit leaders in 2026
- Market growth is meaningful and sustained. The combination of demographic tailwinds, rising procedural adoption, and therapeutic innovation is creating a multi-year growth runway. Organizations that align portfolio decisions and commercial investment with this trajectory can capture disproportionate share.
- Strategic timing is critical. 2026 will be a pivot year for several late-stage technologies (extended-release corticosteroids, novel viscosupplements, and regenerative approaches). Decisions taken early in 2026—on licensing, co-development, or launch sequencing—will materially influence market share and long-term margins.
- Operational readiness is a competitive differentiator. Supply continuity, manufacturing scale-up for injectable formats, and commercial training for procedure-based adoption are nontrivial execution risks that will separate winners from laggards.
Macro drivers and the risk landscape
Our analysis synthesizes epidemiology, payer behavior, clinician adoption patterns, and product innovation to identify the primary growth vectors and associated risks:
Worldwide Intra-Articular Injection Market
- Clinical demand and unmet need. Osteoarthritis and other degenerative joint conditions continue to represent the core clinical rationale for intra-articular interventions. An aging population and higher expectations for function-preserving treatments support continued procedural volume growth.
- Therapeutic innovation. The portfolio of intra-articular options is diversifying beyond traditional viscosupplements and short-acting corticosteroids. Extended-release corticosteroids and biologic/regenerative candidates (including gene therapy strategies that have attracted expedited regulatory designations) introduce new value propositions—longer pain relief, fewer injections, and potential disease modification—that can reset pricing and utilization dynamics.
- Payer and reimbursement pressures. Reimbursement coding and billing practices are a material determinant of real-world uptake. Existing procedure codes and site-based billing rules remain relevant for commercialization planning; proactive payer engagement and real-world evidence generation will be essential to secure favorable access.
- Regulatory and manufacturing risk. Recent approvals and manufacturing authorizations for injectable platforms underscore the importance of validated supply chains and compliant production suites. Firms without proven sterile manufacturing footprints face either third-party dependency or longer timelines to market.
- Competitive concentration and consolidation risk. Market concentration metrics indicate a landscape where a handful of established players retain material share, yet the market remains open to entrants with differentiated efficacy, convenience, or cost structures. This profile encourages targeted M&A and licensing as rapid routes to capability-building.
Competitive landscape — who matters and why
Our proprietary competitive mapping synthesizes public filings, product portfolios, pipeline status and recent corporate actions. Several incumbent manufacturers and specialty biopharma firms occupy strategic positions:
- Large multi-nationals with established viscosupplement franchises continue to leverage brand equity, distribution reach, and payer relationships to protect share. Their advantage lies in scale, broad clinician relationships, and integrated commercial capabilities.
- Specialty and orthopedic-focused firms deploy high-touch field teams and procedure-level training to drive adoption of single-injection and high molecular weight formulations. These players are nimble on clinical education and local market penetration.
- Emerging biotechs and platform developers are pursuing differentiated mechanisms—extended-release corticosteroids, gene therapy, and novel biologic constructs—seeking to leapfrog incumbents on duration of effect and clinical outcomes.
Recent corporate moves underscore the evolving dynamics: a high-profile licensing and collaboration deal to advance a long-acting non-opioid analgesic in intra-articular use highlights how pain management strategies are converging with procedural care; a regenerative medicine program received expedited regulatory designation for intra-articular gene therapy, signaling the potential for transformative, although higher-risk, entrants; and continued partnerships among manufacturers reflect the importance of co-development and regional commercialization arrangements.
Report contents — practical deliverables for 2026 action
Our full report is structured to convert data into executable strategies. Key deliverables include:
- Market model and scenario engine. A transparent, auditable model that projects topline demand under multiple adoption and reimbursement scenarios. Subscribers receive a packaged Excel model plus an interactive dashboard to stress-test assumptions.
- Commercial playbooks. Go-to-market sequences for different asset types (short-acting corticosteroids, extended-release injectables, viscosupplements, and regenerative therapies), including field force sizing, key opinion leader (KOL) engagement plans, and specialty pharmacy versus hospital channel strategies.
- Regulatory and payer pathway maps. Tactical guidance for securing market access, from early HTA engagement to RWE design that addresses payer evidence gaps—anchored to current coding and billing realities.
- Competitive intelligence dossiers. Deep profiles of leading players, pipeline watchlists, technology differentiation matrices, and a rolling M&A opportunities tracker. Recent deal flow and product approvals are contextualized to reveal acquisition and partnership windows.
- Manufacturing and supply risk assessment. A checklist for sterile injectable scale-up, partner selection criteria, and contingency scenarios informed by recent manufacturing approvals and supply events.
- Clinical evidence synthesis. Comparative evidence maps that translate trial endpoints into payer-relevant outcomes and clinical adoption signals.
We intentionally treat subsegment-level revenue splits and proprietary elasticities as subscriber-only assets. The executive package previews strategic implications and high-level levers while preserving the granular data that subscribers use to build business cases and negotiate deals.
How leading companies can use these insights in 2026
Executives across R&D, commercial, corporate development and regulatory functions can derive immediate, high-leverage actions from the report:
- Portfolio prioritization. Use the scenario engine to compare marginal NPV of late-stage programs versus licensing opportunities, factoring in time-to-market, clinical differentiation and payer acceptance.
- Deal sequencing and structuring. Identify partnership windows where co-development or asset licensing accelerates access to clinicians and payers while minimizing upfront capital allocation.
- Commercial resource allocation. Optimize field force deployment and targeting by aligning market potential with procedure-centers of excellence and reimbursement variability.
- Manufacturing investments. Prioritize sterile-fills, multi-dose versus single-dose formats, and contingency capacity that match forecasted demand curves and regulatory requirements.
- Regulatory and evidence strategy. Design RWE and post-approval study commitments that anticipate payer demands and support premium pricing for differentiated therapies.
Strategic implications for M&A and partnerships
Given the market’s moderate concentration, opportunities for inorganic growth remain attractive. Strategic buyers should focus on assets that provide either: (1) meaningful clinical differentiation with defensible evidence; (2) distribution or site-of-care advantages; or (3) manufacturable injectable platforms with validated sterile capabilities. The report’s M&A sieve identifies targets that satisfy these criteria and quantifies the value uplift under multiple integration scenarios.
What executives should do next
- Commission a targeted workshop using our interactive model to align 2026 budgets and milestone-based decision gates.
- Prioritize early payer engagement for any asset seeking premium positioning, and prepare companion real-world evidence plans that map to specific reimbursement levers.
- Assess manufacturing readiness now—delays in sterile capacity can push commercial launches out by quarters, which materially impacts valuation and market share.
- Use our competitive dossiers to identify non-obvious partners and white-space opportunities where clinical differentiation meets unmet payer needs.
Closing—what this preview does and does not disclose
This preview demonstrates the depth and applicability of PW Consulting’s market intelligence for strategic decision-making in 2026. It highlights the macro growth path, the critical levers shaping adoption, and the tactical actions firms should prioritize. In keeping with our “trailer” approach, detailed segmentation tables, company share matrices, and the full interactive forecast model are available in the complete report package and via our subscription portal.
For boards, corporate development teams, and business unit leaders preparing 2026 plans, the question is not whether the intra-articular injection market will grow—our modeling is clear that it will—but rather how to position assets, partners and capabilities to capture the most valuable portion of that growth. PW Consulting’s full report provides the granular inputs and execution templates you need to make those calls with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Intra-Articular Injection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cell & Tissue Preservation Market to Expand at 11.8% CAGR, Crossing Approximately USD 28.56 Billion by 2032
By pmarketresearch, 2026-07-15
Worldwide Cell and Tissue Preservation Market: Strategic Imperatives for 2026 — PW Consulting Executive Insight
Executive preview
The cell and tissue preservation market is entering a decisive phase. After accelerating from an estimated USD 7,550 Million in 2020 to USD 13,080 Million in 2025 (base year), the market is forecast to expand at a compound annual growth rate (CAGR) of 11.8% across our 2026–2032 horizon, reaching an estimated USD 28,556 Million by 2032. These headline dynamics underline both the size of the opportunity and the velocity of change — a combination that will force corporate strategy teams, product leaders, and investors to rethink portfolio priorities, manufacturing footprints, and regulatory engagement for decisions made in 2026.
Worldwide Cell and Tissue Preservation Market
Why this report matters to decision‑makers in 2026
- Timing and trajectory: The market’s rapid doubling potential through the forecast window creates short windows for first-mover advantage in high-margin niches and for securing key supply-chain capacity.
- Concentration profile: Market concentration is meaningful but not prohibitive — the top three players account for a significant share, while the top five represent a clear majority. This structure simultaneously lowers barriers for strategic partnerships and elevates the value of scale and channel access.
- Regulatory inflection points: Regulatory clarifications and guideline updates in 2025–2026 are reshaping GMP and material‑sourcing expectations for clinical-grade preservation, with direct implications for product formulation, audit-readiness, and clinical partner selection.
- Commercial and clinical integration: Preservation solutions are increasingly embedded into end-to-end cell therapy, biobanking, and tissue-engineering workflows, expanding total addressable opportunity for vendors who can demonstrate validated, workflow‑level value.
What the PW Consulting report delivers — operationally useful intelligence
This study is designed to be decision‑ready for corporate strategy, business development, and manufacturing leaders planning actions in 2026. The report synthesizes primary research, supplier and end‑user interviews, and quantitative market modeling across a multi‑year historical window (2020–2025) and a seven‑year forecast (2026–2032). Key deliverables include:
Worldwide Cell and Tissue Preservation Market
- Top‑down and bottom‑up market sizing and a tested forecasting framework that reconciles demand drivers coming from clinical trials, commercial cell therapies, biobanking expansion, and research throughput.
- Scenario modeling (base, accelerated adoption, and constrained access) that isolates the impact of regulatory tightening, raw material shortages, and cold‑chain failures on revenue and margin profiles.
- Vendor benchmarking and a competitive positioning matrix that evaluates technological depth, regulatory readiness, commercial reach, and manufacturing scale — enabling rapid shortlists for partnerships or acquisition targets.
- Actionable go‑to‑market playbooks with pricing sensitivity, channel strategies (direct, distributor, clinical systems integrator), and commercial KPIs tied to contract types typical in clinical and biobanking customers.
- Supply‑chain and operations guides covering cold‑chain logistics, single‑use vs. reusable assets, contract manufacturing considerations, and capacity planning templates for 2026–2028 ramp scenarios.
- Regulatory and reimbursement intelligence: a concise mapping of relevant guidance, inspection focus areas, and likely payer stances — including where reimbursement levers do and do not currently exist.
Competitive landscape — what leading vendors are signalising
The market is served by a mix of global life‑science platform players, specialized biopreservation providers, and upstream materials suppliers. Our vendor analysis highlights how strategic orientations differ across the incumbent set:
Worldwide Cell and Tissue Preservation Market
- Thermo Fisher Scientific (Waltham, MA): Broad portfolio reach across culture media, cryopreservation reagents, and storage equipment positions the company to capture workflow‑level value; the strategic imperative is integrating consumables, instruments, and services for recurring revenue streams.
- Merck KGaA / MilliporeSigma (Darmstadt): Deep reagent and media expertise supports upstream quality control and formulation innovation, with a playbook centered on regulatory‑grade chemistry and distribution density.
- BioLife Solutions (Bothell, WA): A focused specialist strategy — clinical‑grade CryoStor® and HypoThermosol® platforms — is being tactically deployed into cell therapy workflows and cold‑chain solutions; recent investor communications signal efforts to expand total addressable markets for clinical biopreservation tools.
- Lonza (Basel): Integration into manufacturing for cell and gene therapies gives access to high‑value preservation contracts as part of broader CDMO relationships.
- BD (Becton, Dickinson and Company): Strength in consumables and processing tools supports adoption at point‑of‑care and hospital laboratories; their scale makes them competitive on logistics and regulatory support.
- Cytiva (Danaher), Corning, STEMCELL Technologies, FUJIFILM Irvine Scientific, Avantor, Sartorius, AMSBIO, CellGenix: Each brings complementary strengths — from cultureware and media to GMP reagents and bioprocess equipment — creating an ecosystem where collaboration and bundling strategies can unlock share gains.
For leaders evaluating M&A, JV, or OEM arrangements in 2026, the research identifies which vendor attributes — regulatory dossiers, GMP capacity, clinical evidence, cold‑chain logistics, or channel partnerships — most strongly predict post‑deal value creation.
Regulatory and reimbursement context shaping near‑term strategy
Two regulatory items merit particular attention for 2026 planning. First, the U.S. regulator’s agenda includes finalized guidance related to safety testing for allogeneic cells and the use of human‑ and animal‑derived materials in cell and gene therapy manufacturing — changes that will influence supplier qualification and documentation requirements for preservation media and consumables. Second, international guidance updates (including targeted ISSCR revisions in 2025) shift research governance and may affect sourcing and clinical trial design for stem‑cell derived products.
Importantly, payer dynamics remain neutral in the absence of new reimbursement codes specifically for preservation media or consumables; consequently, commercial value propositions must focus on clinical outcomes, cost‑of‑failure reduction (e.g., avoided cell loss), and operational savings to support price realization.
Strategic playbook: immediate actions for 2026
- Prioritize regulatory readiness: Accelerate cGMP conversion of clinical formulations, strengthen raw material traceability, and align stability programs to anticipated guidance on human‑ and animal‑derived inputs.
- Lock supply and scale capacity: Secure manufacturing slots and dual‑source critical reagents to mitigate supplier concentration risk; review cold‑chain partners for validated end‑to‑end temperature control and chain‑of‑custody capabilities.
- Shift commercial conversations to outcomes: Build case studies and real‑world evidence demonstrating improved post‑thaw viability, workflow throughput, and reduced downstream clinical failures to justify premium positioning.
- Design partnership frameworks: Seek alliances with CDMOs, clinical trial sponsors, and biobanks where preservation solutions can be embedded as part of service bundles that create recurring revenue and higher switching costs.
- Targeted R&D investments: Invest in serum‑free and low‑protein formulations, alternative cryoprotectant strategies, and automation‑friendly consumables that reduce handling risk and support scale‑up.
- Scenario planning and stress‑testing: Use the report’s scenario models to stress test business plans against raw material shocks, cold‑chain interruptions, and accelerated regulatory timelines to prioritize contingencies and capital allocation.
Case signals from recent industry developments
- Public disclosures from specialty vendors are re‑framing commercial narratives around clinical integration of preservation media and hypothermic storage platforms — a window into how category leaders intend to expand use cases and capture more of therapy economics.
- Regulatory agendas published in late 2025 and early 2026 indicate inspectors and policymakers will place greater emphasis on safety testing and material sourcing in cell‑based products, reinforcing the need for documented supply‑chain control and robust QC.
- The lack of new payer codes for preservation consumables means reimbursement levers are likely to come through bundled therapy payment models or value‑based arrangements rather than product‑specific codes in the immediate term.
How to use this intelligence in boardroom decisions
For CEOs, CFOs, and heads of strategy making 2026 commitments, this report serves three practical functions:
- It quantifies the growth envelope and concentration dynamics so capital allocation debates are grounded in a reconciled market outlook rather than anecdote.
- It provides tactical roadmaps to reduce execution risk — from supplier hedging templates to regulatory gap assessments — that can be converted into 90‑, 180‑ and 360‑day plans.
- It produces defensible shortlists for M&A or partnership targets based on operating KPIs and clinical alignment, reducing time to value in deal sourcing and diligence.
Conclusion and how to access the full analysis
The cell and tissue preservation market is transitioning from commodity positioning to a workflow‑integrated, clinically critical category. The next 12 months present a narrow window for strategy teams to secure capacity, validate clinical value, and align with evolving regulatory expectations before competitive dynamics intensify. PW Consulting’s Worldwide Cell and Tissue Preservation Market report offers the granular datasets, vendor scorecards, and executable playbooks needed to make those decisions with confidence — while core segment-level tables and partner‑level financials are reserved for the full report.
For access to the complete dataset, company scorecards, scenario worksheets, and procurement templates that will directly inform 2026 planning, please visit our report landing page or contact PW Consulting’s industry team to request the full research package.
For detailed analysis of this topic, please visit the official page: Worldwide Cell and Tissue Preservation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Diabetes Lancing Devices Market Set to Grow at 7.15% CAGR (2026–2032), Reaching USD 1,870.43 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Diabetes Lancing Devices Market — Strategic Outlook for 2026: A PW Consulting Brief
As diabetes self-management continues to evolve, lancing devices remain a deceptively strategic product class: low-cost per unit, high frequency of use, and tightly coupled to meter ecosystems, reimbursement rules, and regulatory regimes. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast — synthesizes commercial, clinical and policy drivers to create a practical playbook for executives planning investment, product, and go-to-market decisions in 2026.
Worldwide Diabetes Lancing Devices Market
Market snapshot (macro)
Our assessment quantifies the global lancing devices market in USD Million. The category expanded steadily through the historical window and enters the forecast period with robust momentum: the market is estimated at approximately 1,153.45 USD Million in 2025 and is projected to grow to about 1,870.43 USD Million by 2032. The modeled 2026–2032 compound annual growth rate (CAGR) is 7.15%. These headline figures reflect a combination of rising diabetes prevalence, intensifying self-monitoring behaviors, incremental product innovation, and evolving reimbursement and regulatory frameworks that together reshape commercial opportunity and execution risk.
Worldwide Diabetes Lancing Devices Market
Why this matters for 2026 corporate decisions
- Resource allocation optimization: A mid-single-digit-to-high-single-digit CAGR during 2026–2032 validates continued investment, but capital should be prioritized toward innovations that enhance adherence, safety and integration with glucose-monitoring ecosystems rather than marginal aesthetic changes.
- Regulatory-first product design: Reclassification and labeling guidance mean design choices now have downstream approval and commercial implications; early regulatory engagement will shorten time-to-market.
- Reimbursement-driven commercialization: Coding and payer policies materially shape unit economics—companies that secure favorable coding, evidence packages and payer relationships will unlock volume at preferable margins.
- M&A and partnerships over greenfield: Market concentration (top-3 firms accounting for a majority share and top-5 for near three-quarters) suggests targeted M&A, OEM partnerships, or white-label agreements offer faster scale and distribution advantages than pure organic expansion in many jurisdictions.
What the PW Consulting report delivers
Designed as an executable intelligence product for C-suite, corporate development and commercial leaders, the full report pairs quantitative forecasting with qualitative strategy. Key deliverables include:
Worldwide Diabetes Lancing Devices Market
- Transparent forecasting methodology and scenario analysis (base, upside, downside) with sensitivity to pricing, substitution and regulatory shocks.
- Actionable go-to-market playbooks segmented by business model (OEM, branded, private label) with channel economics, KPI benchmarks and suggested launch timelines.
- Comprehensive regulatory and reimbursement matrix linking device classes to likely approval pathways, labeling imperatives and payer coding strategies.
- Opportunity heat maps that prioritize product-investment themes (safety, pain reduction, integration) and commercialization lanes for 12 strategic markets.
- Competitive benchmarking and capability gap analysis for the leading manufacturers and emergent entrants, together with a pipeline assessment and recommended M&A targets by risk appetite.
- Supply-chain resilience diagnostics and sourcing playbooks tailored to medical-device manufacturers, including inventory, supplier concentration and cost-to-serve models.
- Primary research insights: interviews with payers, procurement leads, diabetes educators, clinicians and end-users that underpin go/no-go recommendations and launch messaging.
Competitive landscape — strategic takeaways
The competitive map is bifurcated between multi-national medtech incumbents with integrated ecosystems and agile innovators leveraging differentiated user experience or cost advantages. Our concentration analysis shows the top three firms together control a dominant portion of the market (CR3 ≈ 58.4%), and the top five command an even larger share (CR5 ≈ 72.15%), indicating substantial advantage for established players while leaving profitable niches for specialists.
- Large system players (e.g., long-established meter OEMs): Firms with existing meter portfolios retain structural advantages through bundle economics, channel depth and brand trust. Expect continued defensive product refreshes, bundling strategies, and exclusive supply agreements with payers and retail chains.
- Medical device leaders: Manufacturers with broad hospital and POC footprints emphasize safety lancets and regulatory-compliant disposables for institutional channels, while selectively expanding into home settings via partnerships.
- Specialty disruptors and user-experience innovators: Niche players focusing on pain mitigation, vacuum-assisted sampling, or novel single-use safety features can secure premium positioning with targeted direct-to-consumer channels and telehealth partners.
- Regional OEMs and contract manufacturers: Cost-competitive suppliers, especially those in Asia, are accelerating approvals and leveraging flexible manufacturing to supply private-label and mass-market retail segments.
Recent regulatory approvals demonstrate this dynamic: select entrants have obtained regulatory clearances in 2023–2024 that materially improve their pathway to scaled commercialization, enabling sharper competition on price and feature differentiation.
Regulatory and reimbursement dynamics shaping 2026 strategy
Regulation and payer policy are active levers in this market. Key developments to factor into 2026 planning include:
- Regulatory reclassification that delineates single-use and multiple-use devices into distinct regulatory pathways—with multiple-patient use potentially facing more onerous requirements. This elevates the importance of clear labeling and design choices to avoid expensive PMA pathways.
- Guidance favoring single-patient labeling to reduce pathogen transmission risk; product labeling and user instructions are now an essential element of market access dossiers.
- Payer coding and quantity limits that affect unit demand and refill cycles; teams must secure favorable HCPCS coding, understand per-beneficiary quantity caps, and build evidence to influence payer policy.
- Emerging bundled and integrated device codes reflecting device-meter integration, which create both opportunity (value-added bundles) and risk (reimbursement tied to integrated products rather than standalone lancets).
For commercial teams, these developments mean reimbursement strategy and regulatory affairs must be embedded in product roadmaps from concept to launch.
Strategic playbook for 2026 — prioritized initiatives
- Embed regulatory strategy into product design: Early engagement with regulators, rigorous human factors testing, and labeling strategies that align with single-patient use guidance will reduce submission risk and time-to-revenue.
- Build reimbursement evidence: Invest in real-world evidence (RWE) and health-economic dossiers that demonstrate adherence benefits, reduced complication costs and clear coding pathways to influence payer policies.
- Partner for ecosystem integration: Negotiate OEM partnerships or interoperability agreements with meter manufacturers and digital health platforms to capture share within bundled purchases.
- Optimize the supply chain: Diversify suppliers for critical components, qualify alternate contract manufacturers, and model inventory buffers to protect launch timelines.
- Pursue focused M&A or licensing: Target assets that add novel user-experience capabilities, regulatory-cleared technology, or rapid access to high-volume distribution channels.
- Differentiate via end-user outcomes: Position products around measurable benefits—pain reduction, reduced fingertip trauma, or simplified workflows for caregivers—to justify premium pricing where clinical or behavioral benefits exist.
How PW Consulting supports your 2026 decisions
Our full report translates market size, concentration metrics and regulatory signal into a prioritized action agenda. For executives evaluating whether to scale R&D, pursue acquisition, or double-down on commercial execution in 2026, PW Consulting provides: tailored market entry simulations, competitor negotiation playbooks, reimbursement evidence templates, and a short-list of high-potential partnership and acquisition targets aligned to strategic risk appetite.
This briefing is a trailer — a strategic orientation meant to inform immediate decisions while directing commercial teams to the full intelligence set. The comprehensive report contains the granular segment-level forecasts, regional heat maps, channel unit economics and company-level scorecards that operational teams require to execute with confidence. For teams preparing budgets, pipeline roadmaps or M&A diligence for 2026, the report converts market insight into an executable plan.
PW Consulting stands ready to co-develop a 90–day launch-or-exit plan that integrates regulatory, reimbursement, and commercial imperatives into a single roadmap tailored to your organization’s capabilities and risk tolerance.
For detailed analysis of this topic, please visit the official page: Worldwide Diabetes Lancing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com