

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Diabetes Lancing Devices Market Set to Grow at 7.15% CAGR (2026–2032), Reaching USD 1,870.43 Million by 2032

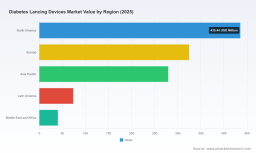
Worldwide Diabetes Lancing Devices Market — Strategic Outlook for 2026: A PW Consulting Brief
As diabetes self-management continues to evolve, lancing devices remain a deceptively strategic product class: low-cost per unit, high frequency of use, and tightly coupled to meter ecosystems, reimbursement rules, and regulatory regimes. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast — synthesizes commercial, clinical and policy drivers to create a practical playbook for executives planning investment, product, and go-to-market decisions in 2026.
Worldwide Diabetes Lancing Devices Market
Market snapshot (macro)
Our assessment quantifies the global lancing devices market in USD Million. The category expanded steadily through the historical window and enters the forecast period with robust momentum: the market is estimated at approximately 1,153.45 USD Million in 2025 and is projected to grow to about 1,870.43 USD Million by 2032. The modeled 2026–2032 compound annual growth rate (CAGR) is 7.15%. These headline figures reflect a combination of rising diabetes prevalence, intensifying self-monitoring behaviors, incremental product innovation, and evolving reimbursement and regulatory frameworks that together reshape commercial opportunity and execution risk.
Worldwide Diabetes Lancing Devices Market
Why this matters for 2026 corporate decisions
- Resource allocation optimization: A mid-single-digit-to-high-single-digit CAGR during 2026–2032 validates continued investment, but capital should be prioritized toward innovations that enhance adherence, safety and integration with glucose-monitoring ecosystems rather than marginal aesthetic changes.
- Regulatory-first product design: Reclassification and labeling guidance mean design choices now have downstream approval and commercial implications; early regulatory engagement will shorten time-to-market.
- Reimbursement-driven commercialization: Coding and payer policies materially shape unit economics—companies that secure favorable coding, evidence packages and payer relationships will unlock volume at preferable margins.
- M&A and partnerships over greenfield: Market concentration (top-3 firms accounting for a majority share and top-5 for near three-quarters) suggests targeted M&A, OEM partnerships, or white-label agreements offer faster scale and distribution advantages than pure organic expansion in many jurisdictions.
What the PW Consulting report delivers
Designed as an executable intelligence product for C-suite, corporate development and commercial leaders, the full report pairs quantitative forecasting with qualitative strategy. Key deliverables include:
Worldwide Diabetes Lancing Devices Market
- Transparent forecasting methodology and scenario analysis (base, upside, downside) with sensitivity to pricing, substitution and regulatory shocks.
- Actionable go-to-market playbooks segmented by business model (OEM, branded, private label) with channel economics, KPI benchmarks and suggested launch timelines.
- Comprehensive regulatory and reimbursement matrix linking device classes to likely approval pathways, labeling imperatives and payer coding strategies.
- Opportunity heat maps that prioritize product-investment themes (safety, pain reduction, integration) and commercialization lanes for 12 strategic markets.
- Competitive benchmarking and capability gap analysis for the leading manufacturers and emergent entrants, together with a pipeline assessment and recommended M&A targets by risk appetite.
- Supply-chain resilience diagnostics and sourcing playbooks tailored to medical-device manufacturers, including inventory, supplier concentration and cost-to-serve models.
- Primary research insights: interviews with payers, procurement leads, diabetes educators, clinicians and end-users that underpin go/no-go recommendations and launch messaging.
Competitive landscape — strategic takeaways
The competitive map is bifurcated between multi-national medtech incumbents with integrated ecosystems and agile innovators leveraging differentiated user experience or cost advantages. Our concentration analysis shows the top three firms together control a dominant portion of the market (CR3 ≈ 58.4%), and the top five command an even larger share (CR5 ≈ 72.15%), indicating substantial advantage for established players while leaving profitable niches for specialists.
- Large system players (e.g., long-established meter OEMs): Firms with existing meter portfolios retain structural advantages through bundle economics, channel depth and brand trust. Expect continued defensive product refreshes, bundling strategies, and exclusive supply agreements with payers and retail chains.
- Medical device leaders: Manufacturers with broad hospital and POC footprints emphasize safety lancets and regulatory-compliant disposables for institutional channels, while selectively expanding into home settings via partnerships.
- Specialty disruptors and user-experience innovators: Niche players focusing on pain mitigation, vacuum-assisted sampling, or novel single-use safety features can secure premium positioning with targeted direct-to-consumer channels and telehealth partners.
- Regional OEMs and contract manufacturers: Cost-competitive suppliers, especially those in Asia, are accelerating approvals and leveraging flexible manufacturing to supply private-label and mass-market retail segments.
Recent regulatory approvals demonstrate this dynamic: select entrants have obtained regulatory clearances in 2023–2024 that materially improve their pathway to scaled commercialization, enabling sharper competition on price and feature differentiation.
Regulatory and reimbursement dynamics shaping 2026 strategy
Regulation and payer policy are active levers in this market. Key developments to factor into 2026 planning include:
- Regulatory reclassification that delineates single-use and multiple-use devices into distinct regulatory pathways—with multiple-patient use potentially facing more onerous requirements. This elevates the importance of clear labeling and design choices to avoid expensive PMA pathways.
- Guidance favoring single-patient labeling to reduce pathogen transmission risk; product labeling and user instructions are now an essential element of market access dossiers.
- Payer coding and quantity limits that affect unit demand and refill cycles; teams must secure favorable HCPCS coding, understand per-beneficiary quantity caps, and build evidence to influence payer policy.
- Emerging bundled and integrated device codes reflecting device-meter integration, which create both opportunity (value-added bundles) and risk (reimbursement tied to integrated products rather than standalone lancets).
For commercial teams, these developments mean reimbursement strategy and regulatory affairs must be embedded in product roadmaps from concept to launch.
Strategic playbook for 2026 — prioritized initiatives
- Embed regulatory strategy into product design: Early engagement with regulators, rigorous human factors testing, and labeling strategies that align with single-patient use guidance will reduce submission risk and time-to-revenue.
- Build reimbursement evidence: Invest in real-world evidence (RWE) and health-economic dossiers that demonstrate adherence benefits, reduced complication costs and clear coding pathways to influence payer policies.
- Partner for ecosystem integration: Negotiate OEM partnerships or interoperability agreements with meter manufacturers and digital health platforms to capture share within bundled purchases.
- Optimize the supply chain: Diversify suppliers for critical components, qualify alternate contract manufacturers, and model inventory buffers to protect launch timelines.
- Pursue focused M&A or licensing: Target assets that add novel user-experience capabilities, regulatory-cleared technology, or rapid access to high-volume distribution channels.
- Differentiate via end-user outcomes: Position products around measurable benefits—pain reduction, reduced fingertip trauma, or simplified workflows for caregivers—to justify premium pricing where clinical or behavioral benefits exist.
How PW Consulting supports your 2026 decisions
Our full report translates market size, concentration metrics and regulatory signal into a prioritized action agenda. For executives evaluating whether to scale R&D, pursue acquisition, or double-down on commercial execution in 2026, PW Consulting provides: tailored market entry simulations, competitor negotiation playbooks, reimbursement evidence templates, and a short-list of high-potential partnership and acquisition targets aligned to strategic risk appetite.
This briefing is a trailer — a strategic orientation meant to inform immediate decisions while directing commercial teams to the full intelligence set. The comprehensive report contains the granular segment-level forecasts, regional heat maps, channel unit economics and company-level scorecards that operational teams require to execute with confidence. For teams preparing budgets, pipeline roadmaps or M&A diligence for 2026, the report converts market insight into an executable plan.
PW Consulting stands ready to co-develop a 90–day launch-or-exit plan that integrates regulatory, reimbursement, and commercial imperatives into a single roadmap tailored to your organization’s capabilities and risk tolerance.
For detailed analysis of this topic, please visit the official page: Worldwide Diabetes Lancing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com