

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Intra‑Articular Injection Market to Surge to USD 12.08 Billion by 2032

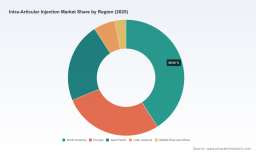
Worldwide Intra-Articular Injection Market: A Strategic Playbook for 2026 Decision-Makers
Executive summary
The intra-articular injection market has entered a period of accelerated, structurally-driven expansion. Our latest report—Worldwide Intra-Articular Injection Market (base year 2025)—shows the market expanding from approximately USD 4.45 billion in 2020 to roughly USD 6.66 billion in 2025, with a forecast trajectory that reaches in excess of USD 12.0 billion by 2032. The underlying compound annual growth rate across the forecast window is 8.87%—a pace that demands strategic recalibration across R&D, commercial, regulatory and M&A agendas.
Worldwide Intra-Articular Injection Market
PW Consulting’s analysis is designed as a practical decision-support tool for executives who must translate these macro dynamics into high-confidence 2026 plans. This release previews the report’s most consequential takeaways while reserving the granular segmentation tables and proprietary model outputs for subscribers and authorized stakeholders.
Worldwide Intra-Articular Injection Market
Why this matters for boardrooms and business unit leaders in 2026
- Market growth is meaningful and sustained. The combination of demographic tailwinds, rising procedural adoption, and therapeutic innovation is creating a multi-year growth runway. Organizations that align portfolio decisions and commercial investment with this trajectory can capture disproportionate share.
- Strategic timing is critical. 2026 will be a pivot year for several late-stage technologies (extended-release corticosteroids, novel viscosupplements, and regenerative approaches). Decisions taken early in 2026—on licensing, co-development, or launch sequencing—will materially influence market share and long-term margins.
- Operational readiness is a competitive differentiator. Supply continuity, manufacturing scale-up for injectable formats, and commercial training for procedure-based adoption are nontrivial execution risks that will separate winners from laggards.
Macro drivers and the risk landscape
Our analysis synthesizes epidemiology, payer behavior, clinician adoption patterns, and product innovation to identify the primary growth vectors and associated risks:
Worldwide Intra-Articular Injection Market
- Clinical demand and unmet need. Osteoarthritis and other degenerative joint conditions continue to represent the core clinical rationale for intra-articular interventions. An aging population and higher expectations for function-preserving treatments support continued procedural volume growth.
- Therapeutic innovation. The portfolio of intra-articular options is diversifying beyond traditional viscosupplements and short-acting corticosteroids. Extended-release corticosteroids and biologic/regenerative candidates (including gene therapy strategies that have attracted expedited regulatory designations) introduce new value propositions—longer pain relief, fewer injections, and potential disease modification—that can reset pricing and utilization dynamics.
- Payer and reimbursement pressures. Reimbursement coding and billing practices are a material determinant of real-world uptake. Existing procedure codes and site-based billing rules remain relevant for commercialization planning; proactive payer engagement and real-world evidence generation will be essential to secure favorable access.
- Regulatory and manufacturing risk. Recent approvals and manufacturing authorizations for injectable platforms underscore the importance of validated supply chains and compliant production suites. Firms without proven sterile manufacturing footprints face either third-party dependency or longer timelines to market.
- Competitive concentration and consolidation risk. Market concentration metrics indicate a landscape where a handful of established players retain material share, yet the market remains open to entrants with differentiated efficacy, convenience, or cost structures. This profile encourages targeted M&A and licensing as rapid routes to capability-building.
Competitive landscape — who matters and why
Our proprietary competitive mapping synthesizes public filings, product portfolios, pipeline status and recent corporate actions. Several incumbent manufacturers and specialty biopharma firms occupy strategic positions:
- Large multi-nationals with established viscosupplement franchises continue to leverage brand equity, distribution reach, and payer relationships to protect share. Their advantage lies in scale, broad clinician relationships, and integrated commercial capabilities.
- Specialty and orthopedic-focused firms deploy high-touch field teams and procedure-level training to drive adoption of single-injection and high molecular weight formulations. These players are nimble on clinical education and local market penetration.
- Emerging biotechs and platform developers are pursuing differentiated mechanisms—extended-release corticosteroids, gene therapy, and novel biologic constructs—seeking to leapfrog incumbents on duration of effect and clinical outcomes.
Recent corporate moves underscore the evolving dynamics: a high-profile licensing and collaboration deal to advance a long-acting non-opioid analgesic in intra-articular use highlights how pain management strategies are converging with procedural care; a regenerative medicine program received expedited regulatory designation for intra-articular gene therapy, signaling the potential for transformative, although higher-risk, entrants; and continued partnerships among manufacturers reflect the importance of co-development and regional commercialization arrangements.
Report contents — practical deliverables for 2026 action
Our full report is structured to convert data into executable strategies. Key deliverables include:
- Market model and scenario engine. A transparent, auditable model that projects topline demand under multiple adoption and reimbursement scenarios. Subscribers receive a packaged Excel model plus an interactive dashboard to stress-test assumptions.
- Commercial playbooks. Go-to-market sequences for different asset types (short-acting corticosteroids, extended-release injectables, viscosupplements, and regenerative therapies), including field force sizing, key opinion leader (KOL) engagement plans, and specialty pharmacy versus hospital channel strategies.
- Regulatory and payer pathway maps. Tactical guidance for securing market access, from early HTA engagement to RWE design that addresses payer evidence gaps—anchored to current coding and billing realities.
- Competitive intelligence dossiers. Deep profiles of leading players, pipeline watchlists, technology differentiation matrices, and a rolling M&A opportunities tracker. Recent deal flow and product approvals are contextualized to reveal acquisition and partnership windows.
- Manufacturing and supply risk assessment. A checklist for sterile injectable scale-up, partner selection criteria, and contingency scenarios informed by recent manufacturing approvals and supply events.
- Clinical evidence synthesis. Comparative evidence maps that translate trial endpoints into payer-relevant outcomes and clinical adoption signals.
We intentionally treat subsegment-level revenue splits and proprietary elasticities as subscriber-only assets. The executive package previews strategic implications and high-level levers while preserving the granular data that subscribers use to build business cases and negotiate deals.
How leading companies can use these insights in 2026
Executives across R&D, commercial, corporate development and regulatory functions can derive immediate, high-leverage actions from the report:
- Portfolio prioritization. Use the scenario engine to compare marginal NPV of late-stage programs versus licensing opportunities, factoring in time-to-market, clinical differentiation and payer acceptance.
- Deal sequencing and structuring. Identify partnership windows where co-development or asset licensing accelerates access to clinicians and payers while minimizing upfront capital allocation.
- Commercial resource allocation. Optimize field force deployment and targeting by aligning market potential with procedure-centers of excellence and reimbursement variability.
- Manufacturing investments. Prioritize sterile-fills, multi-dose versus single-dose formats, and contingency capacity that match forecasted demand curves and regulatory requirements.
- Regulatory and evidence strategy. Design RWE and post-approval study commitments that anticipate payer demands and support premium pricing for differentiated therapies.
Strategic implications for M&A and partnerships
Given the market’s moderate concentration, opportunities for inorganic growth remain attractive. Strategic buyers should focus on assets that provide either: (1) meaningful clinical differentiation with defensible evidence; (2) distribution or site-of-care advantages; or (3) manufacturable injectable platforms with validated sterile capabilities. The report’s M&A sieve identifies targets that satisfy these criteria and quantifies the value uplift under multiple integration scenarios.
What executives should do next
- Commission a targeted workshop using our interactive model to align 2026 budgets and milestone-based decision gates.
- Prioritize early payer engagement for any asset seeking premium positioning, and prepare companion real-world evidence plans that map to specific reimbursement levers.
- Assess manufacturing readiness now—delays in sterile capacity can push commercial launches out by quarters, which materially impacts valuation and market share.
- Use our competitive dossiers to identify non-obvious partners and white-space opportunities where clinical differentiation meets unmet payer needs.
Closing—what this preview does and does not disclose
This preview demonstrates the depth and applicability of PW Consulting’s market intelligence for strategic decision-making in 2026. It highlights the macro growth path, the critical levers shaping adoption, and the tactical actions firms should prioritize. In keeping with our “trailer” approach, detailed segmentation tables, company share matrices, and the full interactive forecast model are available in the complete report package and via our subscription portal.
For boards, corporate development teams, and business unit leaders preparing 2026 plans, the question is not whether the intra-articular injection market will grow—our modeling is clear that it will—but rather how to position assets, partners and capabilities to capture the most valuable portion of that growth. PW Consulting’s full report provides the granular inputs and execution templates you need to make those calls with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Intra-Articular Injection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com