

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cell & Tissue Preservation Market to Expand at 11.8% CAGR, Crossing Approximately USD 28.56 Billion by 2032

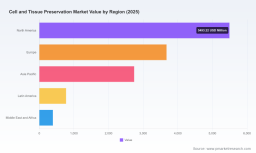
Worldwide Cell and Tissue Preservation Market: Strategic Imperatives for 2026 — PW Consulting Executive Insight
Executive preview
The cell and tissue preservation market is entering a decisive phase. After accelerating from an estimated USD 7,550 Million in 2020 to USD 13,080 Million in 2025 (base year), the market is forecast to expand at a compound annual growth rate (CAGR) of 11.8% across our 2026–2032 horizon, reaching an estimated USD 28,556 Million by 2032. These headline dynamics underline both the size of the opportunity and the velocity of change — a combination that will force corporate strategy teams, product leaders, and investors to rethink portfolio priorities, manufacturing footprints, and regulatory engagement for decisions made in 2026.
Worldwide Cell and Tissue Preservation Market
Why this report matters to decision‑makers in 2026
- Timing and trajectory: The market’s rapid doubling potential through the forecast window creates short windows for first-mover advantage in high-margin niches and for securing key supply-chain capacity.
- Concentration profile: Market concentration is meaningful but not prohibitive — the top three players account for a significant share, while the top five represent a clear majority. This structure simultaneously lowers barriers for strategic partnerships and elevates the value of scale and channel access.
- Regulatory inflection points: Regulatory clarifications and guideline updates in 2025–2026 are reshaping GMP and material‑sourcing expectations for clinical-grade preservation, with direct implications for product formulation, audit-readiness, and clinical partner selection.
- Commercial and clinical integration: Preservation solutions are increasingly embedded into end-to-end cell therapy, biobanking, and tissue-engineering workflows, expanding total addressable opportunity for vendors who can demonstrate validated, workflow‑level value.
What the PW Consulting report delivers — operationally useful intelligence
This study is designed to be decision‑ready for corporate strategy, business development, and manufacturing leaders planning actions in 2026. The report synthesizes primary research, supplier and end‑user interviews, and quantitative market modeling across a multi‑year historical window (2020–2025) and a seven‑year forecast (2026–2032). Key deliverables include:
Worldwide Cell and Tissue Preservation Market
- Top‑down and bottom‑up market sizing and a tested forecasting framework that reconciles demand drivers coming from clinical trials, commercial cell therapies, biobanking expansion, and research throughput.
- Scenario modeling (base, accelerated adoption, and constrained access) that isolates the impact of regulatory tightening, raw material shortages, and cold‑chain failures on revenue and margin profiles.
- Vendor benchmarking and a competitive positioning matrix that evaluates technological depth, regulatory readiness, commercial reach, and manufacturing scale — enabling rapid shortlists for partnerships or acquisition targets.
- Actionable go‑to‑market playbooks with pricing sensitivity, channel strategies (direct, distributor, clinical systems integrator), and commercial KPIs tied to contract types typical in clinical and biobanking customers.
- Supply‑chain and operations guides covering cold‑chain logistics, single‑use vs. reusable assets, contract manufacturing considerations, and capacity planning templates for 2026–2028 ramp scenarios.
- Regulatory and reimbursement intelligence: a concise mapping of relevant guidance, inspection focus areas, and likely payer stances — including where reimbursement levers do and do not currently exist.
Competitive landscape — what leading vendors are signalising
The market is served by a mix of global life‑science platform players, specialized biopreservation providers, and upstream materials suppliers. Our vendor analysis highlights how strategic orientations differ across the incumbent set:
Worldwide Cell and Tissue Preservation Market
- Thermo Fisher Scientific (Waltham, MA): Broad portfolio reach across culture media, cryopreservation reagents, and storage equipment positions the company to capture workflow‑level value; the strategic imperative is integrating consumables, instruments, and services for recurring revenue streams.
- Merck KGaA / MilliporeSigma (Darmstadt): Deep reagent and media expertise supports upstream quality control and formulation innovation, with a playbook centered on regulatory‑grade chemistry and distribution density.
- BioLife Solutions (Bothell, WA): A focused specialist strategy — clinical‑grade CryoStor® and HypoThermosol® platforms — is being tactically deployed into cell therapy workflows and cold‑chain solutions; recent investor communications signal efforts to expand total addressable markets for clinical biopreservation tools.
- Lonza (Basel): Integration into manufacturing for cell and gene therapies gives access to high‑value preservation contracts as part of broader CDMO relationships.
- BD (Becton, Dickinson and Company): Strength in consumables and processing tools supports adoption at point‑of‑care and hospital laboratories; their scale makes them competitive on logistics and regulatory support.
- Cytiva (Danaher), Corning, STEMCELL Technologies, FUJIFILM Irvine Scientific, Avantor, Sartorius, AMSBIO, CellGenix: Each brings complementary strengths — from cultureware and media to GMP reagents and bioprocess equipment — creating an ecosystem where collaboration and bundling strategies can unlock share gains.
For leaders evaluating M&A, JV, or OEM arrangements in 2026, the research identifies which vendor attributes — regulatory dossiers, GMP capacity, clinical evidence, cold‑chain logistics, or channel partnerships — most strongly predict post‑deal value creation.
Regulatory and reimbursement context shaping near‑term strategy
Two regulatory items merit particular attention for 2026 planning. First, the U.S. regulator’s agenda includes finalized guidance related to safety testing for allogeneic cells and the use of human‑ and animal‑derived materials in cell and gene therapy manufacturing — changes that will influence supplier qualification and documentation requirements for preservation media and consumables. Second, international guidance updates (including targeted ISSCR revisions in 2025) shift research governance and may affect sourcing and clinical trial design for stem‑cell derived products.
Importantly, payer dynamics remain neutral in the absence of new reimbursement codes specifically for preservation media or consumables; consequently, commercial value propositions must focus on clinical outcomes, cost‑of‑failure reduction (e.g., avoided cell loss), and operational savings to support price realization.
Strategic playbook: immediate actions for 2026
- Prioritize regulatory readiness: Accelerate cGMP conversion of clinical formulations, strengthen raw material traceability, and align stability programs to anticipated guidance on human‑ and animal‑derived inputs.
- Lock supply and scale capacity: Secure manufacturing slots and dual‑source critical reagents to mitigate supplier concentration risk; review cold‑chain partners for validated end‑to‑end temperature control and chain‑of‑custody capabilities.
- Shift commercial conversations to outcomes: Build case studies and real‑world evidence demonstrating improved post‑thaw viability, workflow throughput, and reduced downstream clinical failures to justify premium positioning.
- Design partnership frameworks: Seek alliances with CDMOs, clinical trial sponsors, and biobanks where preservation solutions can be embedded as part of service bundles that create recurring revenue and higher switching costs.
- Targeted R&D investments: Invest in serum‑free and low‑protein formulations, alternative cryoprotectant strategies, and automation‑friendly consumables that reduce handling risk and support scale‑up.
- Scenario planning and stress‑testing: Use the report’s scenario models to stress test business plans against raw material shocks, cold‑chain interruptions, and accelerated regulatory timelines to prioritize contingencies and capital allocation.
Case signals from recent industry developments
- Public disclosures from specialty vendors are re‑framing commercial narratives around clinical integration of preservation media and hypothermic storage platforms — a window into how category leaders intend to expand use cases and capture more of therapy economics.
- Regulatory agendas published in late 2025 and early 2026 indicate inspectors and policymakers will place greater emphasis on safety testing and material sourcing in cell‑based products, reinforcing the need for documented supply‑chain control and robust QC.
- The lack of new payer codes for preservation consumables means reimbursement levers are likely to come through bundled therapy payment models or value‑based arrangements rather than product‑specific codes in the immediate term.
How to use this intelligence in boardroom decisions
For CEOs, CFOs, and heads of strategy making 2026 commitments, this report serves three practical functions:
- It quantifies the growth envelope and concentration dynamics so capital allocation debates are grounded in a reconciled market outlook rather than anecdote.
- It provides tactical roadmaps to reduce execution risk — from supplier hedging templates to regulatory gap assessments — that can be converted into 90‑, 180‑ and 360‑day plans.
- It produces defensible shortlists for M&A or partnership targets based on operating KPIs and clinical alignment, reducing time to value in deal sourcing and diligence.
Conclusion and how to access the full analysis
The cell and tissue preservation market is transitioning from commodity positioning to a workflow‑integrated, clinically critical category. The next 12 months present a narrow window for strategy teams to secure capacity, validate clinical value, and align with evolving regulatory expectations before competitive dynamics intensify. PW Consulting’s Worldwide Cell and Tissue Preservation Market report offers the granular datasets, vendor scorecards, and executable playbooks needed to make those decisions with confidence — while core segment-level tables and partner‑level financials are reserved for the full report.
For access to the complete dataset, company scorecards, scenario worksheets, and procurement templates that will directly inform 2026 planning, please visit our report landing page or contact PW Consulting’s industry team to request the full research package.
For detailed analysis of this topic, please visit the official page: Worldwide Cell and Tissue Preservation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com