

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Pneumococcal Vaccination Market — 5.3% CAGR Forecast (2026-2032)
By pmarketresearch, 2026-07-22
Pneumococcal Vaccination Market 2026: Strategic Imperatives from PW Consulting
As health systems, vaccine manufacturers, and life sciences investors set strategy for 2026, an evidence-led view of the pneumococcal vaccine market is no longer optional — it is determinative. Our latest PW Consulting industry brief synthesizes seven years of historical performance (2020–2025) with a forward-looking forecast (2026–2032). At the aggregate level the market expands from a base‑year value of approximately USD 9,385 Million (2025) and grows at a compound annual growth rate (CAGR) of 5.3% through the forecast window, with our top‑line scenario reaching just over USD 13,256 Million by 2032. This macro trajectory masks crucial structural shifts that will drive winners and losers in 2026 — and this article outlines the strategic questions that matter for corporate decision‑makers while preserving the detailed segment-level intelligence contained in the full report.
Pneumococcal Vaccination Market
Why this report matters for 2026 decision-making
-
Timing of product and capacity investments: The market’s steady mid-single-digit growth conceals episodic demand surges tied to new valency launches, approvals and government procurement cycles. Firms deciding whether to greenlight manufacturing lines, strategic partnerships, or late‑stage clinical investments need scenario-based forecasts that reconcile these pulses with secular growth.
Pneumococcal Vaccination Market -
Pricing and reimbursement pressure: Payer frameworks and geographically adjusted reimbursement rates are reshaping private and public segments. Understanding the interplay between national reimbursement rules and private-market pricing is central to commercial strategy and tender positioning.
Pneumococcal Vaccination Market -
Supply-security and localization: Recent manufacturing alliances and local production agreements are indicative of a trend toward localized supply to reduce geopolitical and logistical risk. Companies and governments must decide between in‑house capacity expansion, contract manufacturing, or strategic licenses.
-
Competitive concentration: The market remains highly concentrated — our concentration analysis shows the three largest players control the lion’s share of the market, with the top five controlling an even larger portion — creating both barriers and strategic openings for challengers and niche players.
What the PW Consulting report delivers (practical, actionable content)
-
Integrated market model: A demand‑and‑price model with scenario toggles for valency adoption, adult booster uptake, and Gavi/tender dynamics. (Note: segment-level downloads and country-level tables are available in the full report.)
-
Supply‑chain and capacity map: Site-level capacity overlays, critical path timelines for new fill/finish lines, and risk heatmaps for raw‑material chokepoints.
-
Regulatory and payer matrix: Region‑specific regulatory milestones, likely approval timelines for next‑generation PCVs, and reimbursement sensitivity analysis that models updated geographically-adjusted payment rates.
-
Competitive playbooks: Comparative intelligence on pipeline, valency roadmaps, pricing strategies, and tender behavior for the leading manufacturers; includes play-by-play implications for strategic collaborations and M&A.
-
Commercial go-to-market frameworks: Country prioritization tools, tender-entry criteria, and private-market segmentation for nuanced pricing and promotional planning.
-
Scenario workshops and executive dashboards: Ready-to-use deliverables for boardroom decisions, including downside/upside scenarios for capacity investments and licensing deals.
Market dynamics shaping 2026 strategy
-
Valency race and clinical differentiation: The technical trend toward higher-valency conjugate vaccines continues to accelerate. Expect product life‑cycle events — approvals, label expansions and pediatric program initiations — to create waves of competitive displacement that favor firms with broad clinical datasets and scalable manufacturing.
-
Reimbursement and payer complexity: Public payers in several large markets have updated payment frameworks that materially affect margin realization. Providers with deep payer intelligence will be able to prioritize tenders and channel investments more profitably.
-
Price tiering and affordability: There is a persistent two‑tier dynamic between high‑income private markets and heavily subsidized programs in lower‑income settings. This differential drives distinct commercial models — premium private pricing vs. high-volume/low-margin tender strategies — and compels manufacturers to optimize channel segmentation rigorously.
-
Cold chain and logistics: Operational constraints remain real. PCV products generally require 2–8°C cold‑chain logistics, with limited thermal stability allowances for short excursions. These handling requirements influence procurement strategies, last‑mile design, and cost-to-serve calculations.
-
Manufacturing and localization: Recent production partnerships and local manufacturing agreements signal a strategic shift toward regionalization of supply. For manufacturers and governments, the calculus now includes technology transfer timelines, PAHO-style revolving-fund procurement dynamics, and regional capacity gaps.
Competitive landscape — who matters and why
The pneumococcal vaccine market is dominated by a small number of global incumbents and a growing set of regional producers. The competitive map includes global leaders, multinational vaccine divisions, and regional challengers with WHO prequalification and localized supply advantages. Key players covered in-depth in our report include:
-
Pfizer Inc. — With major PCV offerings for both pediatric and adult indications and an active R&D pipeline pursuing higher-valency conjugates, Pfizer remains a pivotal strategic actor. Recent late‑stage program initiations underscore its intention to defend and expand market access.
-
Merck & Co., Inc. — A long-established portfolio owner navigating lifecycle management and pipeline expansion, including advanced-valency candidates progressing through regulatory review in major jurisdictions.
-
Sanofi S.A. — Focused on pediatric conjugate vaccines with regional reach and partnerships that support access programs.
-
Serum Institute of India Pvt. Ltd. and Biological E. Limited — High-volume regional producers with WHO prequalified products that are strategically positioned for developing‑market tenders and Gavi-enabled programs.
-
China‑based manufacturers — Domestic producers with strong pediatric market presence and growing export ambitions as regulatory pathways evolve.
Our concentration analysis quantifies the competitive dynamics: the top three companies command a substantial majority of market share, with the top five controlling an even larger slice. This concentration has implications for pricing, tender negotiation dynamics, and the ability of new entrants to secure scale.
Recent developments to watch (strategic implications)
-
Manufacturing partnerships and localization agreements are becoming a procurement prerequisite in several regions. Such deals compress timelines and can accelerate local uptake when tied to public procurement channels.
-
Regulatory momentum for next‑generation PCVs in 2025–2026 is reshaping adult market opportunities and may reframe booster strategies for older populations.
-
Targeted manufacturing expansions and specialized fill‑finish investments by smaller biotech firms are altering supplier dynamics and creating potential contract manufacturing partners for large incumbents.
-
Clinical program initiations for higher‑valency candidates signal continued product evolution; firms without clear pipeline responses will face erosion of pricing power over time.
Strategic implications and recommended actions for 2026
-
Prioritize capacity and partnership decisions with scenario gating: Use the report’s scenario engine to stress‑test capacity investments against upside product adoption and downside procurement shifts.
-
Align pricing strategy with channel economics: Differentiate pricing by tender, private payers and subsidized programs; ensure that list price strategy is paired with execution plans for access in lower‑income markets.
-
Lock down supply chain resilience: Invest in redundant fill/finish capacity, supplier dual sourcing, and cold‑chain optimization to reduce time‑to‑market risk and cost‑to‑serve.
-
Design M&A and licensing frameworks around rapid local scale: Target assets that de‑risk scale-up timelines or that provide regional regulatory footholds.
-
Invest in evidence generation: Real‑world evidence and head‑to‑head clinical data will be decisive in tender outcomes and adult market adoption; prioritize studies that demonstrate broader serotype coverage and economic value.
How PW Consulting supports executive decisions in 2026
-
Executive workshops that translate model outputs into board-ready decision options and investment timelines.
-
Customizable commercial and regulatory playbooks tailored to specific product portfolios and target countries.
-
Access to our granular market model and country‑level forecasts (available in the full report), enabling transaction diligence, pricing optimization, and tender bid modeling.
Conclusion — The pneumococcal vaccine market in 2026 is characterized by steady aggregate growth, significant competitive concentration, and a fast‑moving product and capacity evolution. For firms making high‑stakes investments this year, the difference between a prudent deployment of capital and a costly misstep will be grounded in scenario-driven planning, supply‑chain foresight, and a calibrated market‑entry playbook. PW Consulting’s full Pneumococcal Vaccination Market report equips executives with the granular, actionable intelligence required to make those decisions with confidence. For access to the complete dataset, country-level splits, and company-specific revenue forecasts, consult the full report on our website or contact our engagement team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Pneumococcal Vaccination Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Slurry Pump Market at USD 1,247.5M in 2025, 2.5% CAGR through 2032
By pmarketresearch, 2026-07-22
Slurry Pump Market — 2026 Strategic Briefing
Introduction
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, decision-oriented briefing built from our comprehensive Slurry Pump Market research (base year 2025). The objective is simple: equip executive teams with the strategic line-of-sight they need to make high-consequence decisions in 2026 — from capital allocation and product roadmaps to M&A prioritization and procurement hedging. This briefing demonstrates the depth of our analysis while intentionally reserving detailed segmentation intelligence for the full report.
Slurry Pump Market
Executive snapshot — market trajectory you cannot ignore
The slurry pump market has evolved through a period of steady baseline growth into a phase of renewed investment and product innovation. Our consolidated sizing shows an overall market that expanded from a 2020 baseline and reached approximately USD 1,247.5 Million in the 2025 base year. Under the central forecast (2026–2032), annualized growth is projected at a compound rate of roughly 2.5%, with the market reaching an estimated USD 1,468.6 Million by 2032. Early signs in 2025–2026 point to a near-term uplift driven by product launches, targeted manufacturing investments, and selective replacement cycles in heavy industrial segments.
Slurry Pump Market
Why this research matters for 2026 decisions
- Capital prioritization: Understand where incremental capex generates the highest risk-adjusted returns across product lines, manufacturing upgrades, and aftermarket service networks.
- Product strategy: Align R&D and product-module investments to market growth pockets, regulatory efficiency drivers, and evolving wear-material economics.
- M&A & partnerships: Use concentration metrics and competitor positioning to identify tuck-in targets, scale plays, and distribution alliances.
- Procurement & supply chain: Translate raw-material volatility into executable hedging and vertical-integration plans to protect margins.
- Commercial planning: Structure channel and aftermarket offers to capture higher-margin service revenues during replacement cycles.
What the full report delivers — operationally usable intelligence
The report is structured as a practical playbook for leaders who must act, not just observe. Key deliverables include:
Slurry Pump Market
- Methodology & baseline: Transparent market-sizing approach (2020–2025 historical, 2026–2032 forecast), data inputs, and sensitivity/forecast scenarios tied to macro and micro drivers.
- Demand drivers & use-case mapping: A synthesis of end-market dynamics (mining, industrial processing, dredging, power, construction and others), lifecycle replacement cycles, and capex cadence which drive near-term demand.
- Product taxonomy & competitive benchmarking: Standardized definitions (horizontal, vertical, submersible, agitator types), performance envelopes, and relative cost-to-serve matrices to inform portfolio rationalization.
- Supply-chain risk & input-cost playbook: Actionable analysis of raw-material supply (high-chrome alloys, elastomers), typical lead times, price volatility scenarios, and commercial hedging templates.
- Regulatory & standards matrix: Mapping of relevant standards (including hydraulic efficiency and quality certifications) and compliance pathways linked to reliability and warranty outcomes.
- Aftermarket & service economics: Margin models for parts, service contracts, remanufacturing, and digital condition-monitoring offerings — with go-to-market templates for faster conversion.
- Scenario planning & stress tests: Upside/downside market scenarios tied to commodity cycles, CAPEX shocks in core end-markets, and supply disruptions — with tailored contingency playbooks.
- M&A and partnership playbooks: Screening criteria, valuation levers, integration checklists, and post-acquisition 100/200-day plans for quick synergies capture.
- Implementation toolkits: Capex prioritization scorecards, procurement term-sheets, pilot KPIs for product launches, and sample commercial contracts for aftermarket agreements.
- Appendices: Detailed company profiles, recent developments, and primary-sourced intelligence supporting competitive assessments and opportunity mapping.
Competitive landscape — what the market structure implies
The market exhibits moderate concentration: our concentration metrics show that the top three firms account for around 28.5% of revenue, while the leading five aggregate to approximately 45.2%. This structure creates distinct strategic pathways — from competing on engineered differentiation to pursuing consolidation for scale.
Key strategic observations on select competitors (high-level):
- Sulzer (Winterthur, Switzerland): Strong in heavy-duty slurry pumps and fast-following product expansions into decarbonization-supporting flows. Recent investment in U.S. submersible production capacity signals a commitment to localized supply and energy-efficiency value propositions.
- KSB / GIW (Frankenthal, Germany): Engineered high-pressure, extreme-duty mill-circuit offerings; recent launches underscore a tactical push to win North American retrofit and tailings projects.
- Metso (Espoo, Finland): Broad series coverage tailored to mineral processing, with channel depth and brand recognition in large-scale projects.
- Goulds Pumps (ITT) (USA): Positioned in extra-heavy-duty lined pumps; competitive strength lies in legacy OEM support and parts availability for large industrial customers.
- Schurco Slurry & EDDY Pump (USA): Niche players focused on heavy-duty and high-solids applications — differentiated by aftermarket responsiveness and dredging solutions.
- Kingda & Hebei Tobee (China): Cost-competitive engineered solutions with aggressive exhibition and regional-business development tactics; they are important to consider for low-cost sourcing and regional partnerships.
- Pioneer Pump & Fristam: Niche strengths — hygienic and certified offerings for regulated process industries; these players illustrate the value of product-certification strategies in non-mining verticals.
Market dynamics — headwinds and levers
- Raw-material volatility: High-chrome white iron alloys and specialized elastomers remain a key margin and availability risk. Typical market pricing dynamics and service-life trade-offs materially influence lifecycle cost models and procurement negotiation strategies.
- Standards & performance expectations: Meeting contemporary hydraulic-efficiency and quality standards is table stakes for long-term reliability and warranty reduction; achieving the specified hydraulic efficiency thresholds materially improves total cost of ownership for end users.
- Energy-efficiency & decarbonization: Manufacturers that align pump designs to plant-level energy reduction goals (and provide validated efficiency gains) gain preferential consideration in large procurement decisions and long-term service contracts.
- Aftermarket & parts scarcity: Shortages or long lead-times for high-wear components translate into higher aftermarket margins and substitution opportunities for producers who can guarantee parts availability.
- Product launches & localized manufacturing: Recent product initiatives and capacity investments reflect a play to shorten lead times and capture retrofit business — a trend that will intensify in 2026.
Strategic imperatives — a prioritized agenda for 2026
- Secure critical inputs: Negotiate tiered supply agreements for high-wear alloys, consider dual-sourcing, and evaluate selective vertical integration for critical parts.
- Invest in efficiency-led product upgrades: Allocate R&D to hydraulic improvements and material science that demonstrably lower lifecycle energy and replacement costs.
- Shift focus to aftermarket-first economics: Design service bundles, predictive-maintenance offerings, and parts-availability guarantees to stabilize revenue and improve margins.
- Pursue targeted M&A: Use concentration metrics to identify complementary targets that increase share in prioritized geographies or fill capability gaps (e.g., hygienic pumps, dredging, or submersible lines).
- Localize for responsiveness: Evaluate investments in regional lines and spare-parts hubs to reduce lead times in mission-critical projects.
- Commercialize certifications: Prioritize product certification where it unlocks regulated buyers (e.g., food, potable-water, or specific mine specifications) — certification can be a premium generator.
- Digitalize service delivery: Pilot condition-monitoring platforms tied to outcome-based contracts to capture annuity-style revenues and reduce customer TCO.
How PW Consulting supports your 2026 roadmap
Our full engagement options include: M&A target screens and due diligence, procurement hedging and supplier negotiation playbooks, product rationalization and R&D prioritization roadmaps, aftermarket transformation programs, and pilot designs for digital predictive maintenance. For boards and CEOs, we provide a tailored 90-day action plan that translates market scenarios into immediate tactical steps to protect margin and capture upside.
Next steps — secure the intelligence that drives value
This briefing demonstrates the strategic contours and high-impact levers in the slurry pump market for 2026. For granular segmentation, geo- and application-level intelligence, tactical pricing benchmarks, and executable templates that drive near-term commercial and operational decisions, access the full PW Consulting Slurry Pump Market report. The complete research contains proprietary breakdowns, supplier scorecards, and model files needed to fast-track implementation.
Contact PW Consulting to request the full report and a complimentary strategic briefing tailored to your role — procurement, product, or corporate development — so you can move from insight to action in 2026.
For detailed analysis of this topic, please visit the official page: Slurry Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PCB Design Software Market to Hit USD 10.11B by 2032 at 13.7% CAGR
By pmarketresearch, 2026-07-22
PCB Design Software Market — A Strategic Primer for 2026 Decision-Makers
As companies plan investments and product roadmaps for 2026, the PCB design software market presents a fast-evolving nexus of technology, regulation, and economics. PW Consulting’s latest market research synthesizes the historical growth trajectory (2020–2025) and a forward-looking forecast (2026–2032) to help executives convert market motion into defensible decisions. At the macro level, the market has expanded rapidly—from a multi‑billion USD base in 2020 to a significantly larger market by 2025—and, under a 13.7% compound annual growth rate, is projected to more than double through the forecast window to 2032. This primer highlights the strategic value of those findings for procurement officers, R&D leaders, corporate strategists, and private investors while intentionally reserving the granular segmentation tables and proprietary scorecards for the full report.
PCB Design Software Market
Why this research matters in 2026
-
Strategic timing: The market’s sustained double‑digit growth means that product development tool choices made in 2026 will shape R&D productivity and system cost structure for years. Rapid adoption of advanced capabilities—AI-assisted routing, cloud-native collaboration, and integrated simulation—changes the effective lifetime of design tool investments.
PCB Design Software Market -
Regulatory inflection points: New regulatory obligations are arriving in force. The U.S. Quality Management System Regulation (QMSR), aligned to ISO 13485:2026, imposes enhanced risk‑based design controls, traceability, and documentation on medical-device PCB design processes effective February 2026. At the same time, the EU Cyber Resilience Act introduces cyber‑reporting obligations for digital products, including design tooling, beginning September 2026. Both raise compliance costs and influence deployment choices (cloud vs on‑premise) across regulated verticals.
PCB Design Software Market -
Cost and skills economics: Advanced PCB toolchains are no longer low‑friction plug‑ins; they carry non‑trivial seat costs and a material total cost of ownership driven by license fees, workstation hardware, and upskilling. For many organizations, those costs prompt evaluation of hybrid approaches—combining commercial suites, lighter professional tiers, and open‑source tools—to balance capability and capital efficiency.
-
Supplier dynamics and fragmentation: While leading vendors supply feature‑rich integrated suites, market concentration remains modest (CR3 and CR5 indicate a fragmented competitive landscape). That fragmentation creates choice but also raises vendor risk—differing data models, library formats, and interoperability practices increase migration friction and lock‑in risk.
What PW Consulting’s full report delivers (practical modules)
-
Macro market model: A transparent historical series (2020–2025) and a scenario‑based forecast (2026–2032) with clear assumptions and sensitivity tests that let users stress‑test investment timing against adoption, pricing, and regulation scenarios.
-
Vendor workbench: Actionable vendor profiles, capability matrices, and capability‑to‑value mapping for mainstream and niche providers. Profiles include product roadmaps, enterprise deployment options, technical differentiators (e.g., SI/PI simulation, 3D substrate support, AI automation), and common migration pathways.
-
Procurement playbook: A practical checklist for RFPs—functional requirements, data model compatibility, cybersecurity clauses, on‑premise/cloud SLAs, and compliance evidentiary needs tailored to regulated sectors.
-
TCO and ROI models: Template calculators that incorporate seat costs, hardware and software maintenance, training, productivity delta assumptions, and compliance enforcement costs to help justify investments or switch decisions to CFOs.
-
Use‑case scoring: Comparative decision matrices—consumer electronics, telecom, medical devices, automotive—mapping which capability sets materially accelerate time‑to‑market versus which add marginal value.
-
M&A and partnership intelligence: Identification of consolidation targets, white‑space opportunities for bolt‑on capabilities (e.g., advanced signal integrity, multi‑domain collaboration), and licensing or OEM partnership strategies for platform extensibility.
Competitive landscape: practical takeaways
The market is characterized by a mix of established commercial suites, enterprise platforms, and vibrant open‑source projects. Key competitive dynamics include product integration, verification toolchains, and the path to cloud‑enabled collaboration.
-
Altium LLC (United States) — Strength lies in an integrated design environment that combines schematic capture, layout, simulation, and collaboration. For organizations prioritizing ecosystem integration and centralized library management, Altium’s suite often presents a compelling one‑stop proposition, though decision makers should evaluate lock‑in risk and upgrade cadence relative to internal roadmaps.
-
Zuken Inc. (Yokohama, Japan) — Zuken competes strongly in complex subsystem and 3D layout environments. Recent releases (e.g., eCADSTAR 2025) show investment in parallel library paths, AI‑assisted workflows, and enhanced signal‑integrity and collaboration features—moves that reduce time spent on repetitive tasks and improve cross‑discipline coordination.
-
Siemens EDA (United States) — With platforms like Xpedition, PADS, and HyperLynx, Siemens offers deep verification and manufacturability tooling well suited for enterprise customers with complex verification needs. Their footprint in regulated industries is amplified by strong systems‑level toolchains and lifecycle traceability.
-
Cadence Design Systems (United States) — Cadence’s OrCAD X and related platforms push toward AI‑enabled design acceleration and analysis integration. Their strategy emphasizes automation that augments experienced engineers and compresses iteration cycles.
-
RS Components (United Kingdom) & KiCad Development Team (International) — RS Components supports professional tiers alongside a free offering, while KiCad’s open‑source suite continues to mature. The growth of accessible and community‑driven tools (e.g., recent KiCad 10.x updates) is lowering the entry barrier for SMEs and accelerating a hybrid adoption model where open‑source prototypes feed into commercial toolchains for final release engineering.
-
WestDev Ltd. (United Kingdom) — Focuses on localized, complementary offerings and integration services; represents the type of niche supplier that becomes attractive for targeted acquisitions or partnerships with larger platform vendors.
Strategically, the modest market concentration (CR3 and CR5 metrics) signals opportunity for selective consolidation, specialized M&A plays, and vendor partnerships to deliver integrated end‑to‑end flows that many buyers still lack.
Regulatory and deployment dynamics to plan for in 2026
-
Compliance as a product requirement: For medical device firms, QMSR’s effective date in February 2026 elevates traceability, documentation, and risk‑based design controls from “nice to have” to procurement gating criteria. Equally, the EU Cyber Resilience Act’s reporting timeline in late 2026 makes cybersecurity features and patch management contractual necessities—especially for cloud or SaaS offerings.
-
Data residency and IP protection: On‑premise deployments continue to dominate in aerospace, defense, and automotive because of IP risk. Cloud offerings will gain in collaborative workflows but must demonstrate hardened security and enterprise‑grade isolation to displace on‑premise incumbents in regulated verticals.
-
Cost of adoption: Expect seat‑level economics to be a primary barrier for SMEs. Advanced suites require both licensing and capable hardware, while training curves create initial productivity drag. Organizations should model multi‑year TCO rather than license list price alone.
Recommended 2026 playbook for executives
-
Classify product lines by regulatory sensitivity and select deployment model accordingly: strictly regulated products → on‑premise/private cloud with attested traceability; lower‑risk consumer lines → cloud‑first tools to accelerate collaboration.
-
Adopt a hybrid procurement strategy: combine open‑source tooling for early prototyping with commercial suites for verification and production release, using standardized data export/import layers to minimize migration cost.
-
Prioritize vendors with explicit regulatory and cybersecurity roadmaps. Ask for documented QMS integrations, patch SLAs, and demonstrable compliance artifacts that align with QMSR and the Cyber Resilience Act.
-
Invest in automation and SI/PI simulation: as designs densify, the marginal value of integrated simulation grows—early investment reduces late‑stage rework and accelerates time to market.
-
Capitalize on consolidation opportunities: for strategic buyers, mid‑market vendors with complementary IP (library management, simulation engines, or cloud collaboration) present attractive bolt‑on targets to build scale and close capability gaps.
-
Operationalize skills uplift: build certification pathways (leveraging industry programs) to reduce onboarding time and ensure consistent design practice across distributed teams.
Recent signals that matter now
-
Product innovation: Zuken’s 2025 release highlights the pace at which vendors add AI assistance and collaboration features—capabilities that materially reduce repetitive manual work and improve cross‑team traceability.
-
Open‑source momentum: Ongoing KiCad 10.x updates demonstrate that community projects are increasingly viable for serious design work, shifting some early‑stage demand away from paid tools and prompting commercial vendors to clarify enterprise upgrade paths.
-
Skills and certification: Industry training initiatives launched in early 2026 reflect a market response to talent shortages; buyers should incorporate certification attainment into procurement scoring models.
How to use this primer — and where to go next
This article is a strategic orienting document: it synthesizes the macro trends, regulatory pivots, supplier dynamics, and actionable tactics that will shape 2026 decisions. PW Consulting’s full PCB Design Software Market report contains the granular segmentation, vendor scorecards, downloadable TCO templates, and primary‑data appendices that decision‑makers rely on when committing budget or pursuing M&A. For procurement teams, R&D heads, and investors who need the underlying datasets, method notes, and downloadable decision tools, the full report and supporting workbench are available on PW Consulting’s website.
To convert insight into an executable program for 2026, organizations should combine the report’s scenario outputs with internal product roadmaps and compliance timelines. If you would like a tailored briefing that maps the report’s findings to your specific product lines, regulatory exposure, or M&A appetite, PW Consulting offers bespoke strategy workshops and vendor selection facilitation.
For detailed analysis of this topic, please visit the official page: PCB Design Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cleaning Robots Market Set to Grow at 20.6% CAGR Through 2032
By pmarketresearch, 2026-07-22
Cleaning Robots Market: Strategic Outlook for 2026 Decision-Makers
As corporate leaders plan capital allocation, product roadmaps, and partnership strategies for 2026, understanding the cleaning-robotics ecosystem is no longer optional — it is strategic. PW Consulting’s latest Cleaning Robots Market study synthesizes seven years of historical performance and a forward-looking forecast to 2032, providing the evidence base executives need to move from opportunistic pilots to scalable deployments. This article previews the study’s most consequential insights, the decision levers they unlock in 2026, and the practical frameworks embedded in the full report that enable rapid, defensible action.
Cleaning Robots Market
Executive snapshot: Market momentum and what it means
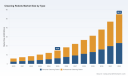
The cleaning robots market has moved from niche automation to mainstream adoption in less than a decade. Our base-year analysis (2025) shows the global market expanded materially from under USD 6 billion in 2020 to approximately USD 14.8 billion in 2025. Under our central forecast, the market continues to accelerate — reaching an anticipated USD 18.4 billion in 2026 and progressing toward more than USD 54.9 billion by 2032, reflecting a strong compounded annual growth rate (CAGR) of roughly 20.6% across the forecast period. These numbers reflect a compound convergence of improving AI navigation, enriched services monetization, and heightened procurement of automation in both commercial and residential channels.
Cleaning Robots Market
Why this matters for 2026 corporate decisions
- Investment timing: The pronounced growth trajectory from 2025 into 2026-2028 alters yield expectations for both hardware-heavy players and SaaS-enabled service providers. Investors must recalibrate assumptions on payback periods for robotic fleets and supporting cloud platforms.
- Procurement strategy: Facilities managers and enterprise buyers must decide whether to expand pilot fleets, standardize on a vendor, or adopt a multi-vendor strategy to de-risk performance variability. These choices affect maintenance budgets, integration efforts, and data governance commitments.
- Product and R&D prioritization: For OEMs and component suppliers, 2026 is a decisive year to prioritize investments in perception (LiDAR, vision), autonomy (SLAM and obstacle negotiation), and robot-human safety to comply with the most recent standards and to cost-effectively differentiate.
- Partnership and M&A playbook: Rapid consolidation in selected subsegments is likely. Companies should prepare playbooks for bolt-on acquisitions, strategic alliances, and minority investments to secure distribution, software capabilities, or regional scale.
Technology and business-model inflection points
Our analysis highlights several cross-cutting inflection points that will drive winners and losers in the coming 24 months:
Cleaning Robots Market
- From single-product to platform economics: Vendors that convert one-off hardware sales into subscription services (fleet management, consumables replenishment, analytics) capture disproportionately higher lifetime value.
- Sensing and autonomy as a commodity layer: Improvements in low-cost, high-resolution sensing and open SLAM frameworks are commoditizing basic navigation; competitive advantage shifts to higher-level software — resilient autonomy, contextual cleaning intelligence, and multi-robot orchestration.
- Aftermarket and field ops as margin engines: Service and spare-parts ecosystems are becoming primary profit centers, especially for commercial fleets where uptime and predictable maintenance matter most.
- Interoperability and integration: Buyers increasingly demand robots that integrate with building management systems, property-management workflows, and enterprise IAM systems. Compliance with privacy and cybersecurity standards is fundamental to procurement.
Competitive landscape — who to watch and why
The market is populated by a mix of consumer-electronics champions, dedicated robotics specialists, and commercial facilities players. Our qualitative company profiles and comparative capability matrices in the full report examine product roadmaps, channel strategies, and technology moats. Key players covered include:
- iRobot Corporation (Bedford, MA, United States) — https://www.irobot.com — A market-defining residential brand known for the Roomba series and innovations such as self-emptying docks and integrated mopping systems.
- Ecovacs Robotics Co., Ltd. (Suzhou, China) — https://www.ecovacs.com — Strong global presence in both household and larger-space solutions; recent strategic partnerships are extending co-development pathways for next-generation platforms.
- Beijing Roborock Technology Co., Ltd. (Beijing, China) — https://www.roborock.com — Focused on premium navigation and pet-hair handling for residential users, with differentiated firmware and hardware synergies.
- SharkNinja Operating LLC (Needham, MA, United States) — https://www.sharkninja.com — A fast-mover in branded AI robot vacuums and mops, leveraging retail channels and consumer marketing reach.
- Alfred Kärcher SE & Co. KG (Winnenden, Germany) — https://www.kaercher.com — Deep expertise in commercial and industrial cleaning systems; emphasis on autonomous scrubbers for facilities and regulated environments.
- LG Electronics Inc. (Seoul, South Korea) — https://www.lg.com — Brings consumer-electronics scale to robotics, integrating advanced suction, air-purification, and lifestyle features.
- Samsung Electronics Co., Ltd. (Suwon, South Korea) — https://www.samsung.com — Integrates robots into broader smart-home and IoT strategies, emphasizing object recognition and platform integration.
- Maytronics Ltd. (Tel Aviv, Israel) — https://www.poolrobots.com — Specialist with strong pool-cleaning solutions for residential and commercial aquatic facilities.
- SoftBank Robotics Corp. (Tokyo, Japan) — https://www.softbankrobotics.com — Targets commercial-grade environments with scrubbers and sweepers designed for scale deployments.
Beyond these incumbents, the report includes a tracker of emerging entrants, solution integrators, and component suppliers, each profiled by growth strategy, funding status, and commercialization readiness.
Regulation, standards, and data privacy — practical implications
The regulatory and standards environment is tightening in ways that materially affect product design and deployment timelines. Notable developments include updates to industrial robot safety standards and active performance standards for commercial robotic cleaning systems. These changes increase certification complexity for vendors and raise the bar for procurement teams assessing compliance risk.
Data privacy and cybersecurity are equally consequential. Major providers now enforce GDPR and CCPA compliance for cloud-connected robots. Certifications related to information security lifecycle management are emerging as procurement prerequisites for enterprise customers. Our report maps how these regulatory vectors affect contractual language, insurance exposures, and needed IT integrations.
Recent market moves and tactical signals
- Strategic partnerships and co-development agreements indicate a shift toward bundled appliance ecosystems and faster product cycles.
- Commercial product expansions and milestone fleet sales highlight accelerating uptake in facilities management where predictable ROI is demonstrable.
- New entrants and niche-product launches (e.g., restroom-cleaning and industrial scrubbers) reveal pockets of white space where specialized automation is economically viable today.
What the PW Consulting report delivers (practical, decision-ready contents)
Designed for executives, corporate development teams, and product leaders, the study delivers actionable intelligence rather than academic summaries. Key deliverables include:
- Top-down market sizing and a bottom-up supply-side model across the 2020–2032 horizon (base year 2025), including sensitivity scenarios and a transparent methodology appendix that explains assumptions and margin models.
- Vendor scorecards and capability maps that assess technology maturity, commercial reach, and execution risk — enabling rapid short-listing for pilots or partnerships.
- Commercial playbooks: procurement decision trees, pilot-to-scale checklists, and procurement contract templates tailored to both residential-platform operators and large facility owners.
- Tech roadmap and component supply analysis that identifies critical bottlenecks (sensors, batteries, edge compute) and supplier risk concentration.
- M&A and partnership heatmaps: target lists, valuation heuristics, and integration checklists for acquirers and corporate venture teams.
- Operational models: fleet TCO templates, uptime/maintenance curves, and example ROI calculations for common commercial use cases.
How to use this intelligence in 2026 — five concrete moves
- Recalculate capital projects with automation-adjusted cash flows. Replace conservative adoption curves with the market’s accelerated central-case and stress-test procurement commitments across three scenarios.
- Design a modular vendor strategy. Standardize APIs and data contracts to maintain vendor flexibility while leveraging best-in-class robotics autonomy.
- Invest in aftermarket capabilities. Plan for in-house or partner-based maintenance networks to protect uptime and margins for fleets deployed in mission-critical environments.
- Embed compliance into procurement. Require third-party attestations for functional safety and cybersecurity as part of RFPs to reduce downstream remediation costs.
- Target adjacent service revenues. Explore subscriptions for consumables, analytics, and scheduling services that turn hardware sales into recurring revenue streams.
Conclusion — the strategic edge for 2026
By 2026, the cleaning-robot market will reward clarity of choice: those who combine rigorous market intelligence with operational readiness will capture disproportionate share and margin. PW Consulting’s Cleaning Robots Market study provides the layered analysis needed to make those choices — large-scale forecasts, vendor-score comparisons, regulatory impact assessments, and practical procurement tools — while protecting the proprietary, segment-level analytics that inform our recommendations. For teams preparing budgets, M&A pipelines, or product strategies in 2026, the right intelligence delivered early makes the difference between leading the automation wave and reacting to it.
Access the full report for detailed segment models, downloadable vendor scorecards, and our executable playbooks that translate market conviction into results.
For detailed analysis of this topic, please visit the official page: Cleaning Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Performance Apparel to Grow from $141M (2025) to $280M by 2032—10.4% CAGR
By pmarketresearch, 2026-07-22
High Performance Apparel Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
By the time companies set budgets and strategic roadmaps for 2026, the high performance apparel market will have shifted from recovery-era reconstruction into a structurally stronger growth phase. Our market model shows a clear trajectory: the global market expanded from roughly USD 90 million in 2020 to about USD 141 million in 2025 and is projected to approach USD 280 million by 2032. That trajectory implies an expected compound annual growth rate of approximately 10.4% across the 2026–2032 forecast window. For executives, those headline numbers are not just comfort: they demand concrete choices about where to invest, which capabilities to scale, and how to de-risk supply chains as competition intensifies.
High Performance Apparel Market
Why this report matters for 2026 planning
Many organizations prepare plans using either high-level trend narratives or disconnected tactical spreadsheets. This study closes that gap by translating macro momentum into decision-ready, operational levers. It isolates the growth vectors that will meaningfully move the P&L in the next 12–24 months — from fabric innovation and digital retailing to regional production strategies and channel economics — and calibrates the investment case for each. The result is a playbook for resource allocation that balances growth capture with margin protection.
High Performance Apparel Market
What the report delivers (practical, actionable outputs)
- Forward-looking market model: a granular forecast built from the 2020–2025 historical base and extended through 2032, enabling scenario testing under different demand, pricing, and raw-material volatility assumptions.
- Commercial go-to-market blueprints: segmented GTM strategies tailored to premium performance, mass-performance, and technical outdoor subsegments — including recommended assortment mixes, pricing sweeps, and retail/wholesale channel tilts.
- Supply chain and sourcing playbooks: supply-mix optimization, nearshoring vs. offshore decision frameworks, and a supplier risk heat map for contract renewal and capacity planning.
- Technology and materials ROI models: capital-allocation calculators that estimate payback horizons for investments in textile R&D, advanced finishing lines, and automated manufacturing cells.
- M&A and partnership scorecards: a tactical list of capability targets (e.g., fabric science startups, circular supply platforms) with acquisition economics and integration risk factors.
- Commercial dashboards and KPIs: pre-built templates for inventory elasticity, sell-through velocity, markdown thresholds, and channel profitability to operationalize the strategy.
Market dynamics shaping 2026 decisions
Three structural forces define the near-term opportunity set:
High Performance Apparel Market
- Material science and product differentiation: Advanced synthetics and engineered blends continue to underpin performance claims — moisture management, thermal regulation, lightweight insulation and compressive support remain the primary product differentiators. However, incorporating these technologies requires elevated R&D and manufacturing complexity, which translates into higher unit costs and longer product development cycles.
- Commercial and digital sophistication: Leaders are investing in demand-sensing and dynamic inventory allocation to reduce overproduction and improve margins. These capabilities are now a competitive necessity, not a nice-to-have, because consumer expectations for rapid assortment refresh and availability have increased.
- Supply-side reconfiguration: Pricing pressure and raw material volatility, especially in synthetic feedstocks, are reshaping sourcing strategies. Companies are balancing cost, speed-to-market and sustainability mandates, with nearshoring and capacity diversification emerging as common responses.
Competitive landscape — what the front-runners are doing
The market remains concentrated: the top three players collectively account for roughly six in ten dollars of market value, and extending the view to the top five shows only a small additional concentration gain. That structure creates high barriers for new entrants but also distinct strategic openings for challengers that focus on agility, sustainability or niche technical differentiation.
Key incumbents and their directional moves you should track:
- Nike (Portland, OR): Accelerating its digital retail ecosystem and deploying advanced demand-forecasting tools to tighten inventory allocation and reduce overproduction. These investments sharpen gross-margin defenses and improve responsiveness to short-cycle trends (Nike press releases, Jan & Jun 2026).
- Adidas (Herzogenaurach): Expanding lines that incorporate bio-based and recycled feedstocks to address both regulatory and consumer sustainability pressures, while seeking to maintain performance parity (Adidas press release, Jun 2026).
- Lululemon (Vancouver): Continuing to push fabric innovation at the premium activewear end with collections built around proprietary textile systems that emphasize fit, breathability and stretch (Lululemon press release, Mar 2026).
- Under Armour, Puma, ASICS, FILA: Each is reinforcing core technical claims (moisture management, compression, durability) while experimenting with digital channels and athlete partnerships to preserve brand salience.
- Outdoor specialists (Patagonia, Arc'teryx, Columbia, VF Corp./The North Face): Differentiation persists through extreme-condition engineering, sustainability credentials and direct-to-consumer control over distribution.
- Newer players (Vuori) and fast-fashion adjacent groups (Inditex): Aggressive capacity moves and nearshoring experiments indicate a desire to compress lead times and enter performance-adjacent categories with lower working-capital exposure (Inditex press release, May 2026).
Risks, trade-offs and sensitivity vectors
When building or revising 2026 strategies, leaders must explicitly weigh three trade-offs:
- Innovation vs. accessibility: Advanced textile technologies command premium pricing and require scale to amortize R&D. Firms that pursue bleeding-edge materials must define clear premium pathways or risk inventory write-downs.
- Speed vs. cost in sourcing: Nearshoring shortens lead time and improves responsiveness but often increases unit costs. The right balance differs by channel: premium DTC collections often justify higher input costs, while mass-market performance lines must optimize for cost elasticity.
- Sustainability vs. margin pressure: Recycled and bio-based inputs improve brand equity but can introduce supply constraints and cost volatility. Scenario planning for raw material price shocks is essential.
How to use this research in 2026 strategic planning
Executives should treat the findings as a tactical supplement to annual planning cycles. Specific use cases include:
- Budgeting R&D and capex: Use the report’s ROI models to select which textile platforms to advance to pilot production in 2026, and which to defer.
- Channel prioritization: Apply the commercial playbooks to determine SKU depth for direct channels versus wholesale partners, and to set promotion calendars tied to inventory velocity thresholds.
- Sourcing optimization: Run the supplier risk heat map against your contracts expiring in 2026–2027 to decide between renegotiation, diversification or capacity co-investment.
- M&A screening: Filter acquisition targets by capability fit, payback timeline and integration complexity using the report’s scorecards.
Why the market model matters — not just the headline growth
Growth alone is insufficient guidance. Our model decomposes the total into drivers you can influence: product-technology adoption rates, channel mix shifts, pricing elasticity, and raw-material cost pass-through. For 2026, the most actionable insight is not whether the market grows, but which combinations of product and channel will expand share sustainably. That is where investment dollars should flow.
Next steps and how to access the full intelligence
This briefing intentionally surfaces the strategic contours of the opportunity while withholding the granular regional, application and type-level splits that executives need to run procurement models, assortment planning and M&A diligence. The full report contains the proprietary segmentation, interactive scenario tools, supplier scorecards and downloadable dashboards necessary to operationalize the recommendations described here.
For market participants preparing 2026 budgets, this research offers a pragmatic, execution-focused lens: it explains where the market is going, why it will get there, who is reshaping the competitive field right now, and which near-term moves are likely to alter competitive positioning. To obtain the complete dataset, segmentation breakdowns, and the interactive models referenced above, please visit the PW Consulting report page where the full High Performance Apparel Market study and accompanying tools are available.
For detailed analysis of this topic, please visit the official page: High Performance Apparel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Phosphate Ester Market to reach USD 3,298.4 Million by 2032 at 5.4% CAGR
By pmarketresearch, 2026-07-22
Phosphate Ester Market 2026: Strategic Imperatives for Decision Makers
As companies prepare budgets, supply arrangements and product roadmaps for 2026, the phosphate ester market presents a distinctly actionable — yet nuanced — opportunity set. Our latest PW Consulting analysis, with base year 2025 and a historical lens covering 2020–2025, shows the market expanding from roughly USD 1.88 billion in 2020 to USD 2.285 billion in 2025 and, under our central scenario, reaching approximately USD 3.298 billion by 2032. That trajectory translates to a steady compound annual growth rate of 5.4% through the 2026–2032 forecast window. These headline figures frame three essential truths for 2026 planning: growth is material but heterogeneous; value creation will be concentrated in differentiated chemistries and applications; and supply-chain and regulatory risks will shape winners and losers.
Phosphate Ester Market
Why this research matters for 2026 decisions
-
Capital allocation: For producers contemplating brownfield versus greenfield capacity, our supply-demand balance and price-sensitivity scenarios quantify near-term revenue tailwinds and margin pressure windows so you can sequence investments with clarity.
Phosphate Ester Market -
Procurement and hedging: Buyers can use our feedstock volatility maps — including n-butanol and tributyl phosphate dynamics — to structure multi-year sourcing agreements that stabilize operating costs for formulations and downstream manufacturing.
Phosphate Ester Market -
Product strategy and R&D prioritization: As end-market requirements shift (fire-resistance, low-toxicity flame retardancy, EV hydraulic fluids), the research distills which phosphate ester chemistries will justify premium pricing and which will be commoditized.
-
M&A and partnership screening: We provide a risk-adjusted playbook to value regional assets, IP-rich product lines and bolt-on acquisitions while accounting for trade policy and export controls that can materially affect deal economics.
-
Regulatory compliance and reputation risk: With new trade actions and export-controls in play, compliance teams can prioritize mitigations that reduce legal and commercial exposure.
Key market dynamics that will determine 2026 outcomes
-
Demand vectors are diversifying. Aviation-grade hydraulic fluids, industrial fire-retardant systems, and specialty lubricants continue to anchor volume, while emerging demand from electric vehicles (new hydraulic and thermal-management formulations) and sustainable-materials initiatives is creating higher-margin adjacencies. These pockets will be the locus of premium demand growth over the next 18–36 months.
-
Feedstock and price volatility remain a central operational risk. For example, n-butanol — a key precursor for some phosphate esters — exhibited pronounced price swings between roughly USD 700–1,200 per tonne during 2022–2025. Separately, tributyl phosphate (TBP) prices in Asia were observed at around USD 2,600/MT in December 2025. Producers and buyers must model these inputs explicitly when stress-testing 2026 margins.
-
Trade policy and export-control friction are reshaping flows. Recent determinations regarding countervailable subsidies on certain alkyl phosphate ester exports and ongoing dual-use export controls for TBP (especially for nuclear applications) mean that geographic sourcing and route-to-market strategies must incorporate tariff, duty and licensing risk as first-order planning variables.
-
Sustainability is no longer optional. Product launches of bio-based phosphate esters and customer procurement mandates are accelerating the shift toward lower-carbon chemistries. While bio-based entrants will initially target premium segments, incumbents that can industrialize low-carbon routes at scale will secure durable competitive advantage.
-
Consolidation and capacity moves are underway. Recent strategic activity — including regional capacity expansions and acquisitions — signals that supply-side rationalization is likely to continue. Our market-concentration assessment shows a moderately consolidated landscape: the top three firms control roughly the mid-30% range of global market share, while the top five control just over half of the market. That structure creates both cooperative and competitive dynamics around pricing, specification harmonization and technical service.
Competitive landscape: what leading players are doing
Across the value chain, incumbent chemical companies and specialty players are pursuing distinct strategies to capture differentiated value:
-
Clariant (Muttenz, Switzerland) is leveraging its Hordaphos™ platform and specialty formulation know-how to serve detergents, coatings and multifunctional additive markets — emphasizing formulation performance and regulatory compliance.
-
Stepan Company (Northfield, Illinois, US) focuses on customized phosphate ester variants geared to agricultural adjuvants, metalworking fluids and hydraulic applications, positioning for technical fit and regional serviceability.
-
Eastman Chemical Company (Kingsport, Tennessee, US) continues to defend niche leadership in fire-resistant hydraulic fluids (Skydrol™ line) and has recently entered a strategic partnership with an automotive OEM to co-develop phosphate ester solutions tailored for electric vehicles — a clear signal that adjacency plays will accelerate.
-
LANXESS , Solvay , Dow , AkzoNobel , Croda , ExxonMobil , Ashland and Evonik are each pursuing combinations of product differentiation, sustainability claims, and downstream collaboration to protect margins. Some prioritize industrial fluids and flame-retardant chemistries; others target personal care, surfactant and specialty additive niches.
-
Recent market moves matter. BASF’s August 2025 launch of a bio-based phosphate ester line underscores the speed of sustainability-driven product introductions, while Huntsman’s July 2025 acquisition of a regional competitor materially expanded capacity in Asia-Pacific. These developments alter competitive posture and capacity balances that will directly influence 2026 sourcing and pricing.
Strategic playbook for 2026 — prioritized actions
-
For producers: adopt a dual-track approach — protect legacy high-volume applications with cost and logistics optimization, while selectively investing in specialty and bio-based chemistries that command better pricing. Use hedging and diversified feedstock contracts to blunt n-butanol and TBP volatility.
-
For OEMs and formulators: move from transactional sourcing to strategic supplier partnerships that include co-development clauses, joint regulatory roadmaps and access to qualified alternatives to mitigate export-control disruption.
-
For investors and M&A teams: prioritize assets with technical depth, regulatory-compliant production sites, and close proximity to end-users in high-growth verticals (avionics, EVs, industrial fire safety). Factor in the potential impact of trade remedies and licensing requirements on cash flow projections.
What our report delivers — practical outputs you can use today
The full PW Consulting Phosphate Ester Market report goes beyond narrative to provide operationally oriented tools for 2026 decision-makers, including:
-
A regional and global supply-demand model with scenario toggles for feedstock price shocks, policy changes and demand acceleration in EV and aviation verticals.
-
Supplier benchmarking and scorecards covering technical capabilities, regulatory risk, sustainability credentials and customer-service metrics.
-
Price-sensitivity and margin-impact dashboards for common and specialty phosphate ester grades — designed for use in commercial and capital-planning reviews.
-
A regulatory matrix and trade-risk tracker tailored to export-control and subsidy investigations, with mitigation playbooks for alternative sourcing and licensing.
-
A prioritized list of near-term partnerships and investment targets informed by recent market activity and capacity moves.
To honor the “trailer” principle that guides our executive briefings, we display the strategic framework, consolidated market trajectory and competitive dynamics here while intentionally withholding granular segment-by-segment figures and region/application-level splits. That detailed intelligence, which underpins the decision-ready tools listed above, is available in the full report and supporting models.
How PW Consulting de-risks your 2026 agenda
-
We combine a bottom-up plant and capacity mapping with contract-level trade-flow analysis to expose where physical bottlenecks and policy constraints intersect. This is essential where dual-use export restrictions or countervailing determinations can abruptly reroute supply chains.
-
Our scenario suite quantifies financial outcomes across alternative futures — from fast-decarbonization to protectionist trade regimes — enabling CFOs and strategy teams to stress-test capex and M&A plans.
-
Complementing quantitative models, our supplier due-diligence templates and regulatory playbooks translate market intelligence into executable procurement terms, joint-development agreements and compliance protocols.
Conclusion — a pragmatic guide to capturing value in 2026
The phosphate ester market presents a classic industrial-chemicals playbook in 2026: steady headline growth (5.4% CAGR into the 2032 horizon), pockets of premium demand, and structural risks centred on feedstock volatility and policy enforcement. Companies that move early to de-risk their feedstock exposure, codify supplier partnerships that include technical co-development, and invest selectively in sustainable, application-differentiated chemistries will capture disproportionate value.
For the decision-critical details — including the full segment and regional models, supplier scorecards and the playbook to operationalize these recommendations — access the full PW Consulting report and interactive model. Our team is available for bespoke briefings to tailor scenarios specifically to your portfolio, procurement profile or investment thesis.
For detailed analysis of this topic, please visit the official page: Phosphate Ester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dicalcium Phosphate Market to Reach USD 1,561 Million by 2032
By pmarketresearch, 2026-07-22
Dicalcium Phosphate Market 2026: Strategic Imperatives for Competitive Advantage
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused primer on the Dicalcium Phosphate (DCP) market that frames the strategic choices corporate leaders must make in 2026. This briefing distils the directional signals from our full 2026–2032 study—anchored to a 2025 base year—and highlights where executives should concentrate capital allocation, risk mitigation and growth initiatives. Our objective here is to demonstrate analytical depth while preserving the full, actionable granularity inside the complete report: regional and application-level breakdowns, company-by-company share tables and executable playbooks are available in the full study.
Dicalcium Phosphate Market
Market snapshot: a stable growth story with clear inflection points
Our macro view: the global Dicalcium Phosphate market is a mature, industrially intensive commodity-excipient sector characterized by steady demand growth. With a 2025 base-year market size measured in USD (Million) and a mid-single digit compound annual growth rate (CAGR) of approximately 5.0% through the 2026–2032 forecast window, the market trajectory supports measured expansion across supply chains. Historical dynamics through 2020–2025 show recovery and rebalancing after episodic volatility, while the forecast horizon to 2032 signals expansion backed by continued demand from animal nutrition, food fortification and pharmaceutical applications.
Dicalcium Phosphate Market
Concentration dynamics are meaningful for strategy: the market sits in a moderate-to-high concentrated state (CR3 ≈ 45%, CR5 ≈ 60%), indicating that a relatively small group of global and regional players exert disproportionate influence over pricing, specification-setting and access to premium channels (e.g., pharmaceutical-grade excipients). This concentration creates both barriers and opportunities for newcomers and adjacent players pursuing vertical integration.
Dicalcium Phosphate Market
Why this analysis matters for 2026 corporate decisions
For executives planning capital allocation, sourcing, M&A or commercial repositioning in 2026, DCP presents a set of distinctive strategic imperatives:
- Operational leverage vs raw-material exposure: phosphate rock is the single largest operational cost driver in DCP production—industry benchmarks place it as roughly 60–70% of operating expenses. This cost concentration means procurement strategy (long-term offtakes, blended sourcing, hedging) materially moves margin curves.
- Regulatory differentiation as a barrier and a premium lever: feed, food and pharmaceutical channels are governed by divergent quality and traceability frameworks (e.g., EU feed additives regulation and pharmacopeial standards). Compliance and certification unlock higher-margin channels but require disciplined investment in quality systems and documentation.
- Consolidation and scale economies: the existing CR3/CR5 footprint implies scale matters for negotiating steam-of-supply and capturing downstream formulation business—particularly where branded excipients and tableting performance (flow, compressibility) create sticky demand.
- Sustainability and social licence to operate: mining and phosphate processing face increasing scrutiny on water, land and legacy waste. Early movers who certify sustainable sourcing, close phosphorus loops or offer recycled-phosphorus products can pre-empt regulatory and buyer-driven restrictions.
Structural drivers and cost dynamics you must model now
When stress-testing scenarios for 2026 investments, three structural elements deserve primary modelling attention:
- Feedstock price sensitivity: the average f.o.b. mine price for marketable phosphate rock is a direct input to cost curves (industry references place it near USD 80 per metric ton in recent reporting). A moderate swing in that price cascades through gross margins—so procurement and backward integration scenarios should be central to any feasibility work.
- Specification-driven demand segmentation: the market consists of several distinct end-use buckets—animal feed, food fortification and pharmaceuticals—each with separate quality specifications and buying logics. The economics of serving pharmaceutical-grade customers (higher compliance cost, premium price, lower volume) differ materially from bulk feed supply.
- Regulatory variability across geographies: the EU, the United States (pharmacopeial frameworks) and Codex standards create overlapping but non-identical requirements. Companies expanding cross-border must budget for dossier management, stability data and audits—costs that frequently surprise first-time exporters.
Competitive landscape: what incumbents are doing and what it means
Our consolidated analysis of leading producers reveals three archetypal strategic postures and highlights the representative firms occupying them:
- Global integrators focused on formulation and branded excipients — exemplified by players that pair DCP production with downstream tableting or supplement portfolios. Such firms leverage product science (e.g., branded excipients) to capture value beyond commodity margins, enabling better resilience to raw-material swings.
- Regionally diversified industrial suppliers — firms with multi-site footprints across Europe, North Africa, Latin America and Asia. These players trade on logistics optimization and regulatory familiarity to serve feed and industrial channels efficiently, while selectively moving up-spec into food-grade offerings.
- API and pharma-focused specialists — companies concentrating on high-compliance pharmaceutical-grade DCP, where certification, consistent particle properties and clean-room-compatible manufacturing are paramount. Margins here depend less on volume and more on validated processes and customer acceptance testing.
Representative firms we profile in the full report include established global ingredient and excipient manufacturers, European and Asian producers with multi-site capacities, and a set of India- and China-based suppliers active in both feed and pharma supply chains. Each company is profiled for manufacturing footprint, product portfolio, recent strategic moves and exposure to feedstock cost. Recent industry activity—such as announced investments in new production facilities for animal feed supplement DCP—illustrate the continued appetite for capacity expansion in select markets.
Practical components of the PW Consulting report (what you’ll get)
The full PW Consulting study is intentionally action-oriented. It provides executives with the tools they need to convert insight into decisions, including:
- Validated market sizing and a 2026–2032 forecast model (base year 2025) with configurable scenario levers for raw-material price, demand elasticity and regulatory tightening.
- Supply-chain and cost-curve analysis that isolates fixed vs variable cost pools and quantifies the sensitivity of EBITDA to phosphate rock pricing.
- A regulatory and standards matrix mapping requirements across feed, food and pharma channels and the incremental CAPEX/OPEX required to meet each.
- Peer benchmarking, including operating footprints, product portfolios and strategic orientation (excipients vs commodity DCP vs API supply).
- M&A screening and a short list of potential targets/partners by strategic objective (scale, technology, regional access), accompanied by indicative valuation ranges and integration risk profiles.
- Commercial playbooks—pricing strategies, contract structures (long-term offtake, indexation clauses), and go-to-market tactics for premiumization of DCP products.
- Sustainability roadmaps and circular phosphorus scenarios that quantify cost and reputational benefits of closed-loop initiatives.
Scenario framing for 2026 planning
We recommend that C-suite teams run three canonical scenarios when framing 2026 decisions:
- Base Case (Aligned with our 5% CAGR): Incremental capacity additions, conservative procurement contracts, selective premiumization. This scenario favours operational efficiency and targeted certification investments.
- Upside Case (Accelerated feed & fortification demand): Aggressive capacity and downstream product expansion; pursue M&A to secure regional access and accelerate branded excipient penetration.
- Downside Case (Raw-material shocks / regulatory tightening): Defensive posture—defer non-essential CAPEX, prioritize long-term offtake and accelerate development of substitution/circular phosphorus pathways.
Immediate strategic actions for 2026
If you are leading a DCP-exposed business and must set a 2026 agenda, prioritize these five actions:
- Lock in diversified phosphate rock supply via medium-term contracts and strategic inventory policy; quantify the margin benefit of backward integration as a sensitivity case.
- Validate compliance readiness for target channels—invest in the documentation, third-party audits and traceability systems needed to access food and pharma premiums.
- Pursue selective partnerships to acquire formulation or tableting expertise if your strategy targets higher-margin excipient markets.
- Re-run capital allocation with sustainability filters—evaluate water, waste and emissions implications of greenfield vs brownfield expansions and price in potential regulatory tightening.
- Map M&A targets against the CR3/CR5 landscape—opportunities exist to increase share or secure logistical chokepoints, but integration economics must be stress-tested against feedstock volatility.
Closing and how to use the full study
This briefing surfaces the structural imperatives and near-term strategic options you need to make confident decisions in 2026. The full PW Consulting Dicalcium Phosphate Market report contains the granular tables, regional and application splits, supplier scorecards and downloadable financial models required to operationalize these recommendations. We intentionally withhold subsegment-level numerical tables in this primer to protect the commercial value of the underlying work—those details are embedded in the full report and accompanying Excel models for licensed subscribers.
For teams preparing capital proposals, procurement strategies, or M&A hypotheses for 2026, the PW Consulting report will shorten the decision cycle by providing validated assumptions, scenario outputs and a prioritized action plan. Reach out to PW Consulting to obtain the full dataset, bespoke modelling support and a workshop to convert these insights into a 90–180 day execution roadmap.
For detailed analysis of this topic, please visit the official page: Dicalcium Phosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fuel Cell Electric Vehicles Market: Strategic Outlook for 2026 Decision-Makers
As organizations prepare budgets, strategic roadmaps, and investment theses for 2026, the Fuel Cell Electric Vehicles (FCEV) market presents both a high-growth opportunity and a complex execution environment. PW Consulting’s latest market research—anchored on a 2025 base year and projecting through 2032—captures the commercial inflection that industry participants must understand before making consequential commitments. At the macro level the market is expanding at a compound annual growth rate (CAGR) of 26.6% between the historical window and our forecast horizon, rising from early commercial volumes in the 2020s to a materially larger opportunity by the early 2030s. This briefing distills the strategic value of the full report for 2026 decisions while deliberately reserving granular segmentation tables to encourage direct consultation of the source research.
Fuel Cell Electric Vehicles Market
Why this report matters for 2026
- Timing: 2026 is a pivotal year for converting pilots into scaled deployments. The market’s growth trajectory signals accelerated demand that favors organizations with ready-to-scale supply chains and station access.
- Capital allocation: With a sustained high-growth projection through 2032, capital should be allocated with a view to multi-year product cycles, infrastructure co-investment, and staged exposure to hydrogen production and distribution economics.
- Partnership and ecosystem design: The opportunity is ecosystem-driven. OEMs, system integrators, station operators, and industrial gas suppliers must align commercial incentives to overcome deployment bottlenecks.
- Policy sensitivity: Regulatory and incentive shifts can materially re-rate project economics in short order. Active policy engagement and scenario-driven contingency plans are essential.
What the full report provides (practical, transaction-ready content)
- Executive synthesis and rapid-read decision guidance tailored for board-level and investment committees.
- Transparent market-sizing methodology with historical reconstructions (2020–2025) and detailed forecasts (2026–2032), including unit and revenue projections at the market level.
- Demand-driver diagnostics—technology desirability, total cost of ownership (TCO) modeling, and route-to-market economics for passenger, commercial, and fleet use cases.
- Segment and channel overviews, with actionable go-to-market playbooks for OEMs, suppliers, and infrastructure developers.
- Supply-chain maps and component-level exposure analysis (membranes, catalysts, balance-of-plant), including supplier risk heatmaps and lead-time scenarios.
- Competitive benchmarking with strategic profiles for incumbent and emerging players, and decision trees for partnering, licensing, and M&A.
- Policy, regulation, and incentives matrix cross-referenced by jurisdictional risk and opportunity.
- Investment case templates, sensitivity tables, and scenario models that support valuation and capex planning.
- Appendices with data tables and source references—note: detailed regional and application-level splits are included in the full dataset accessible via the report landing page.
Data-driven market context
Our market reconstruction shows that FCEV commercialization has moved beyond isolated pilots into nascent scaling. On a revenue basis the market exhibits a steep growth curve into the forecast window—driven by commercial use cases that require long range and rapid refueling, and by policy-driven decarbonization of hard-to-electrify segments. The industry’s projected CAGR of 26.6% reflects both increasing vehicle introductions and accelerated hydrogen infrastructure investments that will reduce logistical barriers to adoption.
Fuel Cell Electric Vehicles Market
Despite this momentum, deployment dynamics are uneven. Public agency reporting from major early-adopter regions highlights both progress and friction. For example, a recent regulatory evaluation noted a measured decline in registered FCEVs in a leading submarket during 2025 and underscored the need for an expanded hydrogen station network to sustain growth trajectories into the latter half of the decade. These mixed signals create windows for opportunistic investments but also mandate conservative staging in capex plans.
Fuel Cell Electric Vehicles Market
Strategic implications for 2026 planning
- Investors: Prioritize staged exposure via hybrid instruments (convertibles, staged equity) and early-offtake agreements. The market concentration metrics suggest top-tier incumbents hold meaningful share but leave room for specialized entrants and vertical integrators.
- OEMs: Consider platform strategies that allow multiple powertrain variants to share the same architecture—this preserves optionality while enabling faster production ramp once hydrogen stations proliferate.
- Suppliers: Secure long-lead raw materials and diversify component sourcing. Suppliers that can demonstrate reliability and scale-up pathways for key stack components will command superior margins.
- Infrastructure developers and hydrogen producers: Adopt hub-and-spoke deployment that prioritizes corridor economics and fleet anchor customers. Leverage public–private funding models to de-risk early station rollouts.
- Fleets and operators: Use leasing and fuel-as-a-service contracts to hedge technology and fuel-price risk. Early deployment case studies show leasing reduces adoption friction and accelerates utilization.
- Policymakers and regulators: Design incentives that address both vehicle cost and infrastructure density; insufficient station coverage remains a primary constraint on rapid scale-up.
Competitive landscape — what the data tells executives
The market is characterized by a mix of established OEM leaders and technology specialists. At the headline level, the top three companies account for a material share of market activity while the top five capture a modestly larger portion—indicating a market that is neither fully consolidated nor atomized, and one where strategic alliances can meaningfully shift positioning.
- Toyota Motor Corporation (Toyota City, Japan) — The Mirai program has delivered early commercial learning on passenger FCEVs and continues to be a strategic reference point for hydrogen passenger mobility. Toyota’s approach emphasizes systems integration and long-cycle product development, making it a benchmark for durability and OEM-level hydrogen commitment. (See the Mirai program)
- Hyundai Motor Company (Seoul, South Korea) — With product families that span passenger cars and heavy-duty trucks, Hyundai’s investments in both vehicle lines and commercial partnerships reflect a bet on heavy and medium-duty deployments as early scale drivers. Recent product debuts underscore Hyundai’s intent to maintain technological leadership in stack integration and vehicle packaging. (See Hyundai Xcient and NEXO)
- Honda Motor Co., Ltd. (Tokyo, Japan) — Honda’s market entry strategies include leasing in select markets and supplying modular fuel cell systems for commercial applications. Leasing pilots in North America demonstrate how flexible ownership models can accelerate initial uptake in regulated, incentive-led markets. (See Honda CR-V e:FCEV)
- BMW Group (Munich, Germany) — BMW’s roadmap targets series production models toward the latter half of the decade, positioning the company as a premium-segment contender that prioritizes integration with existing vehicle lines and brand propositions. (See BMW’s fuel-cell initiatives)
Each of these players brings distinct advantages—scale, product breadth, or niche technical expertise—and the full report analyzes their product roadmaps, supply-chain control, and partnership strategies in actionable detail. Recent events—ranging from product launches and leasing programs to policy seminars—are synthesized to show how competitive intent translates into deployment outcomes.
Risks, scenarios, and contingency planning
Our scenario framework models three high-level paths over the 2026–2032 horizon: a base case aligned with the 26.6% CAGR, an accelerated case driven by stronger-than-expected policy support and station rollouts, and a constrained case where infrastructure lag and higher hydrogen prices slow adoption. Key sensitivities in all scenarios include hydrogen feedstock pricing, station throughput (utilization), and relative TCO versus battery-electric alternatives. The report supplies sensitivity matrices and break-even heatmaps to support negotiation of supply contracts, incentive bids, and fleet procurement.
How to use this research in 2026 decision cycles
- Incorporate our scenario outputs into capital allocation models—use the provided sensitivity tables to stress-test investment returns under different hydrogen price curves and station density assumptions.
- Prioritize pilots that co-locate fleets with planned station infrastructure to minimize refueling risk and accelerate utilization thresholds that unlock station economics.
- Adopt partnership-first strategies where manufacturing, fuel supply, and station operations are shared—this reduces single-party capex burden and improves go-to-market speed.
- Leverage the report’s transaction-ready templates for offtake agreements, JV term sheets, and public funding proposals to accelerate approvals and de-risk execution.
Next steps
For executives preparing 2026 strategies, the full PW Consulting report is designed as a working tool: it includes the complete dataset, regional and application-level segmentations, and downloadable financial models that translate forecasts into project-level cash-flow scenarios. The high-level market trajectory, concentration metrics, and competitive positioning summarized here will be most effective when combined with the report’s granular segmentation and scenario tables, which are accessible from the report landing page.
PW Consulting’s FCEV market study is built to inform boardroom decisions, investment committees, and operational planning teams confronting the near-term challenges and long-term upside of hydrogen mobility. For those preparing to act in 2026, the report offers the empirical foundation and executable frameworks necessary to convert strategic intent into measurable results.
For detailed analysis of this topic, please visit the official page: Fuel Cell Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com