

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PCB Design Software Market to Hit USD 10.11B by 2032 at 13.7% CAGR

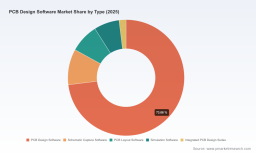
PCB Design Software Market — A Strategic Primer for 2026 Decision-Makers
As companies plan investments and product roadmaps for 2026, the PCB design software market presents a fast-evolving nexus of technology, regulation, and economics. PW Consulting’s latest market research synthesizes the historical growth trajectory (2020–2025) and a forward-looking forecast (2026–2032) to help executives convert market motion into defensible decisions. At the macro level, the market has expanded rapidly—from a multi‑billion USD base in 2020 to a significantly larger market by 2025—and, under a 13.7% compound annual growth rate, is projected to more than double through the forecast window to 2032. This primer highlights the strategic value of those findings for procurement officers, R&D leaders, corporate strategists, and private investors while intentionally reserving the granular segmentation tables and proprietary scorecards for the full report.
PCB Design Software Market
Why this research matters in 2026
-
Strategic timing: The market’s sustained double‑digit growth means that product development tool choices made in 2026 will shape R&D productivity and system cost structure for years. Rapid adoption of advanced capabilities—AI-assisted routing, cloud-native collaboration, and integrated simulation—changes the effective lifetime of design tool investments.
PCB Design Software Market -
Regulatory inflection points: New regulatory obligations are arriving in force. The U.S. Quality Management System Regulation (QMSR), aligned to ISO 13485:2026, imposes enhanced risk‑based design controls, traceability, and documentation on medical-device PCB design processes effective February 2026. At the same time, the EU Cyber Resilience Act introduces cyber‑reporting obligations for digital products, including design tooling, beginning September 2026. Both raise compliance costs and influence deployment choices (cloud vs on‑premise) across regulated verticals.
PCB Design Software Market -
Cost and skills economics: Advanced PCB toolchains are no longer low‑friction plug‑ins; they carry non‑trivial seat costs and a material total cost of ownership driven by license fees, workstation hardware, and upskilling. For many organizations, those costs prompt evaluation of hybrid approaches—combining commercial suites, lighter professional tiers, and open‑source tools—to balance capability and capital efficiency.
-
Supplier dynamics and fragmentation: While leading vendors supply feature‑rich integrated suites, market concentration remains modest (CR3 and CR5 indicate a fragmented competitive landscape). That fragmentation creates choice but also raises vendor risk—differing data models, library formats, and interoperability practices increase migration friction and lock‑in risk.
What PW Consulting’s full report delivers (practical modules)
-
Macro market model: A transparent historical series (2020–2025) and a scenario‑based forecast (2026–2032) with clear assumptions and sensitivity tests that let users stress‑test investment timing against adoption, pricing, and regulation scenarios.
-
Vendor workbench: Actionable vendor profiles, capability matrices, and capability‑to‑value mapping for mainstream and niche providers. Profiles include product roadmaps, enterprise deployment options, technical differentiators (e.g., SI/PI simulation, 3D substrate support, AI automation), and common migration pathways.
-
Procurement playbook: A practical checklist for RFPs—functional requirements, data model compatibility, cybersecurity clauses, on‑premise/cloud SLAs, and compliance evidentiary needs tailored to regulated sectors.
-
TCO and ROI models: Template calculators that incorporate seat costs, hardware and software maintenance, training, productivity delta assumptions, and compliance enforcement costs to help justify investments or switch decisions to CFOs.
-
Use‑case scoring: Comparative decision matrices—consumer electronics, telecom, medical devices, automotive—mapping which capability sets materially accelerate time‑to‑market versus which add marginal value.
-
M&A and partnership intelligence: Identification of consolidation targets, white‑space opportunities for bolt‑on capabilities (e.g., advanced signal integrity, multi‑domain collaboration), and licensing or OEM partnership strategies for platform extensibility.
Competitive landscape: practical takeaways
The market is characterized by a mix of established commercial suites, enterprise platforms, and vibrant open‑source projects. Key competitive dynamics include product integration, verification toolchains, and the path to cloud‑enabled collaboration.
-
Altium LLC (United States) — Strength lies in an integrated design environment that combines schematic capture, layout, simulation, and collaboration. For organizations prioritizing ecosystem integration and centralized library management, Altium’s suite often presents a compelling one‑stop proposition, though decision makers should evaluate lock‑in risk and upgrade cadence relative to internal roadmaps.
-
Zuken Inc. (Yokohama, Japan) — Zuken competes strongly in complex subsystem and 3D layout environments. Recent releases (e.g., eCADSTAR 2025) show investment in parallel library paths, AI‑assisted workflows, and enhanced signal‑integrity and collaboration features—moves that reduce time spent on repetitive tasks and improve cross‑discipline coordination.
-
Siemens EDA (United States) — With platforms like Xpedition, PADS, and HyperLynx, Siemens offers deep verification and manufacturability tooling well suited for enterprise customers with complex verification needs. Their footprint in regulated industries is amplified by strong systems‑level toolchains and lifecycle traceability.
-
Cadence Design Systems (United States) — Cadence’s OrCAD X and related platforms push toward AI‑enabled design acceleration and analysis integration. Their strategy emphasizes automation that augments experienced engineers and compresses iteration cycles.
-
RS Components (United Kingdom) & KiCad Development Team (International) — RS Components supports professional tiers alongside a free offering, while KiCad’s open‑source suite continues to mature. The growth of accessible and community‑driven tools (e.g., recent KiCad 10.x updates) is lowering the entry barrier for SMEs and accelerating a hybrid adoption model where open‑source prototypes feed into commercial toolchains for final release engineering.
-
WestDev Ltd. (United Kingdom) — Focuses on localized, complementary offerings and integration services; represents the type of niche supplier that becomes attractive for targeted acquisitions or partnerships with larger platform vendors.
Strategically, the modest market concentration (CR3 and CR5 metrics) signals opportunity for selective consolidation, specialized M&A plays, and vendor partnerships to deliver integrated end‑to‑end flows that many buyers still lack.
Regulatory and deployment dynamics to plan for in 2026
-
Compliance as a product requirement: For medical device firms, QMSR’s effective date in February 2026 elevates traceability, documentation, and risk‑based design controls from “nice to have” to procurement gating criteria. Equally, the EU Cyber Resilience Act’s reporting timeline in late 2026 makes cybersecurity features and patch management contractual necessities—especially for cloud or SaaS offerings.
-
Data residency and IP protection: On‑premise deployments continue to dominate in aerospace, defense, and automotive because of IP risk. Cloud offerings will gain in collaborative workflows but must demonstrate hardened security and enterprise‑grade isolation to displace on‑premise incumbents in regulated verticals.
-
Cost of adoption: Expect seat‑level economics to be a primary barrier for SMEs. Advanced suites require both licensing and capable hardware, while training curves create initial productivity drag. Organizations should model multi‑year TCO rather than license list price alone.
Recommended 2026 playbook for executives
-
Classify product lines by regulatory sensitivity and select deployment model accordingly: strictly regulated products → on‑premise/private cloud with attested traceability; lower‑risk consumer lines → cloud‑first tools to accelerate collaboration.
-
Adopt a hybrid procurement strategy: combine open‑source tooling for early prototyping with commercial suites for verification and production release, using standardized data export/import layers to minimize migration cost.
-
Prioritize vendors with explicit regulatory and cybersecurity roadmaps. Ask for documented QMS integrations, patch SLAs, and demonstrable compliance artifacts that align with QMSR and the Cyber Resilience Act.
-
Invest in automation and SI/PI simulation: as designs densify, the marginal value of integrated simulation grows—early investment reduces late‑stage rework and accelerates time to market.
-
Capitalize on consolidation opportunities: for strategic buyers, mid‑market vendors with complementary IP (library management, simulation engines, or cloud collaboration) present attractive bolt‑on targets to build scale and close capability gaps.
-
Operationalize skills uplift: build certification pathways (leveraging industry programs) to reduce onboarding time and ensure consistent design practice across distributed teams.
Recent signals that matter now
-
Product innovation: Zuken’s 2025 release highlights the pace at which vendors add AI assistance and collaboration features—capabilities that materially reduce repetitive manual work and improve cross‑team traceability.
-
Open‑source momentum: Ongoing KiCad 10.x updates demonstrate that community projects are increasingly viable for serious design work, shifting some early‑stage demand away from paid tools and prompting commercial vendors to clarify enterprise upgrade paths.
-
Skills and certification: Industry training initiatives launched in early 2026 reflect a market response to talent shortages; buyers should incorporate certification attainment into procurement scoring models.
How to use this primer — and where to go next
This article is a strategic orienting document: it synthesizes the macro trends, regulatory pivots, supplier dynamics, and actionable tactics that will shape 2026 decisions. PW Consulting’s full PCB Design Software Market report contains the granular segmentation, vendor scorecards, downloadable TCO templates, and primary‑data appendices that decision‑makers rely on when committing budget or pursuing M&A. For procurement teams, R&D heads, and investors who need the underlying datasets, method notes, and downloadable decision tools, the full report and supporting workbench are available on PW Consulting’s website.
To convert insight into an executable program for 2026, organizations should combine the report’s scenario outputs with internal product roadmaps and compliance timelines. If you would like a tailored briefing that maps the report’s findings to your specific product lines, regulatory exposure, or M&A appetite, PW Consulting offers bespoke strategy workshops and vendor selection facilitation.
For detailed analysis of this topic, please visit the official page: PCB Design Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com