

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cleaning Robots Market Set to Grow at 20.6% CAGR Through 2032

Cleaning Robots Market: Strategic Outlook for 2026 Decision-Makers
As corporate leaders plan capital allocation, product roadmaps, and partnership strategies for 2026, understanding the cleaning-robotics ecosystem is no longer optional — it is strategic. PW Consulting’s latest Cleaning Robots Market study synthesizes seven years of historical performance and a forward-looking forecast to 2032, providing the evidence base executives need to move from opportunistic pilots to scalable deployments. This article previews the study’s most consequential insights, the decision levers they unlock in 2026, and the practical frameworks embedded in the full report that enable rapid, defensible action.
Cleaning Robots Market
Executive snapshot: Market momentum and what it means
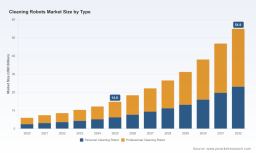
The cleaning robots market has moved from niche automation to mainstream adoption in less than a decade. Our base-year analysis (2025) shows the global market expanded materially from under USD 6 billion in 2020 to approximately USD 14.8 billion in 2025. Under our central forecast, the market continues to accelerate — reaching an anticipated USD 18.4 billion in 2026 and progressing toward more than USD 54.9 billion by 2032, reflecting a strong compounded annual growth rate (CAGR) of roughly 20.6% across the forecast period. These numbers reflect a compound convergence of improving AI navigation, enriched services monetization, and heightened procurement of automation in both commercial and residential channels.
Cleaning Robots Market
Why this matters for 2026 corporate decisions
- Investment timing: The pronounced growth trajectory from 2025 into 2026-2028 alters yield expectations for both hardware-heavy players and SaaS-enabled service providers. Investors must recalibrate assumptions on payback periods for robotic fleets and supporting cloud platforms.
- Procurement strategy: Facilities managers and enterprise buyers must decide whether to expand pilot fleets, standardize on a vendor, or adopt a multi-vendor strategy to de-risk performance variability. These choices affect maintenance budgets, integration efforts, and data governance commitments.
- Product and R&D prioritization: For OEMs and component suppliers, 2026 is a decisive year to prioritize investments in perception (LiDAR, vision), autonomy (SLAM and obstacle negotiation), and robot-human safety to comply with the most recent standards and to cost-effectively differentiate.
- Partnership and M&A playbook: Rapid consolidation in selected subsegments is likely. Companies should prepare playbooks for bolt-on acquisitions, strategic alliances, and minority investments to secure distribution, software capabilities, or regional scale.
Technology and business-model inflection points
Our analysis highlights several cross-cutting inflection points that will drive winners and losers in the coming 24 months:
Cleaning Robots Market
- From single-product to platform economics: Vendors that convert one-off hardware sales into subscription services (fleet management, consumables replenishment, analytics) capture disproportionately higher lifetime value.
- Sensing and autonomy as a commodity layer: Improvements in low-cost, high-resolution sensing and open SLAM frameworks are commoditizing basic navigation; competitive advantage shifts to higher-level software — resilient autonomy, contextual cleaning intelligence, and multi-robot orchestration.
- Aftermarket and field ops as margin engines: Service and spare-parts ecosystems are becoming primary profit centers, especially for commercial fleets where uptime and predictable maintenance matter most.
- Interoperability and integration: Buyers increasingly demand robots that integrate with building management systems, property-management workflows, and enterprise IAM systems. Compliance with privacy and cybersecurity standards is fundamental to procurement.
Competitive landscape — who to watch and why
The market is populated by a mix of consumer-electronics champions, dedicated robotics specialists, and commercial facilities players. Our qualitative company profiles and comparative capability matrices in the full report examine product roadmaps, channel strategies, and technology moats. Key players covered include:
- iRobot Corporation (Bedford, MA, United States) — https://www.irobot.com — A market-defining residential brand known for the Roomba series and innovations such as self-emptying docks and integrated mopping systems.
- Ecovacs Robotics Co., Ltd. (Suzhou, China) — https://www.ecovacs.com — Strong global presence in both household and larger-space solutions; recent strategic partnerships are extending co-development pathways for next-generation platforms.
- Beijing Roborock Technology Co., Ltd. (Beijing, China) — https://www.roborock.com — Focused on premium navigation and pet-hair handling for residential users, with differentiated firmware and hardware synergies.
- SharkNinja Operating LLC (Needham, MA, United States) — https://www.sharkninja.com — A fast-mover in branded AI robot vacuums and mops, leveraging retail channels and consumer marketing reach.
- Alfred Kärcher SE & Co. KG (Winnenden, Germany) — https://www.kaercher.com — Deep expertise in commercial and industrial cleaning systems; emphasis on autonomous scrubbers for facilities and regulated environments.
- LG Electronics Inc. (Seoul, South Korea) — https://www.lg.com — Brings consumer-electronics scale to robotics, integrating advanced suction, air-purification, and lifestyle features.
- Samsung Electronics Co., Ltd. (Suwon, South Korea) — https://www.samsung.com — Integrates robots into broader smart-home and IoT strategies, emphasizing object recognition and platform integration.
- Maytronics Ltd. (Tel Aviv, Israel) — https://www.poolrobots.com — Specialist with strong pool-cleaning solutions for residential and commercial aquatic facilities.
- SoftBank Robotics Corp. (Tokyo, Japan) — https://www.softbankrobotics.com — Targets commercial-grade environments with scrubbers and sweepers designed for scale deployments.
Beyond these incumbents, the report includes a tracker of emerging entrants, solution integrators, and component suppliers, each profiled by growth strategy, funding status, and commercialization readiness.
Regulation, standards, and data privacy — practical implications
The regulatory and standards environment is tightening in ways that materially affect product design and deployment timelines. Notable developments include updates to industrial robot safety standards and active performance standards for commercial robotic cleaning systems. These changes increase certification complexity for vendors and raise the bar for procurement teams assessing compliance risk.
Data privacy and cybersecurity are equally consequential. Major providers now enforce GDPR and CCPA compliance for cloud-connected robots. Certifications related to information security lifecycle management are emerging as procurement prerequisites for enterprise customers. Our report maps how these regulatory vectors affect contractual language, insurance exposures, and needed IT integrations.
Recent market moves and tactical signals
- Strategic partnerships and co-development agreements indicate a shift toward bundled appliance ecosystems and faster product cycles.
- Commercial product expansions and milestone fleet sales highlight accelerating uptake in facilities management where predictable ROI is demonstrable.
- New entrants and niche-product launches (e.g., restroom-cleaning and industrial scrubbers) reveal pockets of white space where specialized automation is economically viable today.
What the PW Consulting report delivers (practical, decision-ready contents)
Designed for executives, corporate development teams, and product leaders, the study delivers actionable intelligence rather than academic summaries. Key deliverables include:
- Top-down market sizing and a bottom-up supply-side model across the 2020–2032 horizon (base year 2025), including sensitivity scenarios and a transparent methodology appendix that explains assumptions and margin models.
- Vendor scorecards and capability maps that assess technology maturity, commercial reach, and execution risk — enabling rapid short-listing for pilots or partnerships.
- Commercial playbooks: procurement decision trees, pilot-to-scale checklists, and procurement contract templates tailored to both residential-platform operators and large facility owners.
- Tech roadmap and component supply analysis that identifies critical bottlenecks (sensors, batteries, edge compute) and supplier risk concentration.
- M&A and partnership heatmaps: target lists, valuation heuristics, and integration checklists for acquirers and corporate venture teams.
- Operational models: fleet TCO templates, uptime/maintenance curves, and example ROI calculations for common commercial use cases.
How to use this intelligence in 2026 — five concrete moves
- Recalculate capital projects with automation-adjusted cash flows. Replace conservative adoption curves with the market’s accelerated central-case and stress-test procurement commitments across three scenarios.
- Design a modular vendor strategy. Standardize APIs and data contracts to maintain vendor flexibility while leveraging best-in-class robotics autonomy.
- Invest in aftermarket capabilities. Plan for in-house or partner-based maintenance networks to protect uptime and margins for fleets deployed in mission-critical environments.
- Embed compliance into procurement. Require third-party attestations for functional safety and cybersecurity as part of RFPs to reduce downstream remediation costs.
- Target adjacent service revenues. Explore subscriptions for consumables, analytics, and scheduling services that turn hardware sales into recurring revenue streams.
Conclusion — the strategic edge for 2026
By 2026, the cleaning-robot market will reward clarity of choice: those who combine rigorous market intelligence with operational readiness will capture disproportionate share and margin. PW Consulting’s Cleaning Robots Market study provides the layered analysis needed to make those choices — large-scale forecasts, vendor-score comparisons, regulatory impact assessments, and practical procurement tools — while protecting the proprietary, segment-level analytics that inform our recommendations. For teams preparing budgets, M&A pipelines, or product strategies in 2026, the right intelligence delivered early makes the difference between leading the automation wave and reacting to it.
Access the full report for detailed segment models, downloadable vendor scorecards, and our executable playbooks that translate market conviction into results.
For detailed analysis of this topic, please visit the official page: Cleaning Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com