

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Phosphate Ester Market to reach USD 3,298.4 Million by 2032 at 5.4% CAGR

Phosphate Ester Market 2026: Strategic Imperatives for Decision Makers
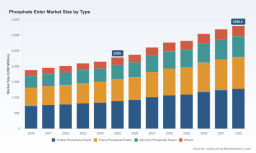
As companies prepare budgets, supply arrangements and product roadmaps for 2026, the phosphate ester market presents a distinctly actionable — yet nuanced — opportunity set. Our latest PW Consulting analysis, with base year 2025 and a historical lens covering 2020–2025, shows the market expanding from roughly USD 1.88 billion in 2020 to USD 2.285 billion in 2025 and, under our central scenario, reaching approximately USD 3.298 billion by 2032. That trajectory translates to a steady compound annual growth rate of 5.4% through the 2026–2032 forecast window. These headline figures frame three essential truths for 2026 planning: growth is material but heterogeneous; value creation will be concentrated in differentiated chemistries and applications; and supply-chain and regulatory risks will shape winners and losers.
Phosphate Ester Market
Why this research matters for 2026 decisions
-
Capital allocation: For producers contemplating brownfield versus greenfield capacity, our supply-demand balance and price-sensitivity scenarios quantify near-term revenue tailwinds and margin pressure windows so you can sequence investments with clarity.
Phosphate Ester Market -
Procurement and hedging: Buyers can use our feedstock volatility maps — including n-butanol and tributyl phosphate dynamics — to structure multi-year sourcing agreements that stabilize operating costs for formulations and downstream manufacturing.
Phosphate Ester Market -
Product strategy and R&D prioritization: As end-market requirements shift (fire-resistance, low-toxicity flame retardancy, EV hydraulic fluids), the research distills which phosphate ester chemistries will justify premium pricing and which will be commoditized.
-
M&A and partnership screening: We provide a risk-adjusted playbook to value regional assets, IP-rich product lines and bolt-on acquisitions while accounting for trade policy and export controls that can materially affect deal economics.
-
Regulatory compliance and reputation risk: With new trade actions and export-controls in play, compliance teams can prioritize mitigations that reduce legal and commercial exposure.
Key market dynamics that will determine 2026 outcomes
-
Demand vectors are diversifying. Aviation-grade hydraulic fluids, industrial fire-retardant systems, and specialty lubricants continue to anchor volume, while emerging demand from electric vehicles (new hydraulic and thermal-management formulations) and sustainable-materials initiatives is creating higher-margin adjacencies. These pockets will be the locus of premium demand growth over the next 18–36 months.
-
Feedstock and price volatility remain a central operational risk. For example, n-butanol — a key precursor for some phosphate esters — exhibited pronounced price swings between roughly USD 700–1,200 per tonne during 2022–2025. Separately, tributyl phosphate (TBP) prices in Asia were observed at around USD 2,600/MT in December 2025. Producers and buyers must model these inputs explicitly when stress-testing 2026 margins.
-
Trade policy and export-control friction are reshaping flows. Recent determinations regarding countervailable subsidies on certain alkyl phosphate ester exports and ongoing dual-use export controls for TBP (especially for nuclear applications) mean that geographic sourcing and route-to-market strategies must incorporate tariff, duty and licensing risk as first-order planning variables.
-
Sustainability is no longer optional. Product launches of bio-based phosphate esters and customer procurement mandates are accelerating the shift toward lower-carbon chemistries. While bio-based entrants will initially target premium segments, incumbents that can industrialize low-carbon routes at scale will secure durable competitive advantage.
-
Consolidation and capacity moves are underway. Recent strategic activity — including regional capacity expansions and acquisitions — signals that supply-side rationalization is likely to continue. Our market-concentration assessment shows a moderately consolidated landscape: the top three firms control roughly the mid-30% range of global market share, while the top five control just over half of the market. That structure creates both cooperative and competitive dynamics around pricing, specification harmonization and technical service.
Competitive landscape: what leading players are doing
Across the value chain, incumbent chemical companies and specialty players are pursuing distinct strategies to capture differentiated value:
-
Clariant (Muttenz, Switzerland) is leveraging its Hordaphos™ platform and specialty formulation know-how to serve detergents, coatings and multifunctional additive markets — emphasizing formulation performance and regulatory compliance.
-
Stepan Company (Northfield, Illinois, US) focuses on customized phosphate ester variants geared to agricultural adjuvants, metalworking fluids and hydraulic applications, positioning for technical fit and regional serviceability.
-
Eastman Chemical Company (Kingsport, Tennessee, US) continues to defend niche leadership in fire-resistant hydraulic fluids (Skydrol™ line) and has recently entered a strategic partnership with an automotive OEM to co-develop phosphate ester solutions tailored for electric vehicles — a clear signal that adjacency plays will accelerate.
-
LANXESS , Solvay , Dow , AkzoNobel , Croda , ExxonMobil , Ashland and Evonik are each pursuing combinations of product differentiation, sustainability claims, and downstream collaboration to protect margins. Some prioritize industrial fluids and flame-retardant chemistries; others target personal care, surfactant and specialty additive niches.
-
Recent market moves matter. BASF’s August 2025 launch of a bio-based phosphate ester line underscores the speed of sustainability-driven product introductions, while Huntsman’s July 2025 acquisition of a regional competitor materially expanded capacity in Asia-Pacific. These developments alter competitive posture and capacity balances that will directly influence 2026 sourcing and pricing.
Strategic playbook for 2026 — prioritized actions
-
For producers: adopt a dual-track approach — protect legacy high-volume applications with cost and logistics optimization, while selectively investing in specialty and bio-based chemistries that command better pricing. Use hedging and diversified feedstock contracts to blunt n-butanol and TBP volatility.
-
For OEMs and formulators: move from transactional sourcing to strategic supplier partnerships that include co-development clauses, joint regulatory roadmaps and access to qualified alternatives to mitigate export-control disruption.
-
For investors and M&A teams: prioritize assets with technical depth, regulatory-compliant production sites, and close proximity to end-users in high-growth verticals (avionics, EVs, industrial fire safety). Factor in the potential impact of trade remedies and licensing requirements on cash flow projections.
What our report delivers — practical outputs you can use today
The full PW Consulting Phosphate Ester Market report goes beyond narrative to provide operationally oriented tools for 2026 decision-makers, including:
-
A regional and global supply-demand model with scenario toggles for feedstock price shocks, policy changes and demand acceleration in EV and aviation verticals.
-
Supplier benchmarking and scorecards covering technical capabilities, regulatory risk, sustainability credentials and customer-service metrics.
-
Price-sensitivity and margin-impact dashboards for common and specialty phosphate ester grades — designed for use in commercial and capital-planning reviews.
-
A regulatory matrix and trade-risk tracker tailored to export-control and subsidy investigations, with mitigation playbooks for alternative sourcing and licensing.
-
A prioritized list of near-term partnerships and investment targets informed by recent market activity and capacity moves.
To honor the “trailer” principle that guides our executive briefings, we display the strategic framework, consolidated market trajectory and competitive dynamics here while intentionally withholding granular segment-by-segment figures and region/application-level splits. That detailed intelligence, which underpins the decision-ready tools listed above, is available in the full report and supporting models.
How PW Consulting de-risks your 2026 agenda
-
We combine a bottom-up plant and capacity mapping with contract-level trade-flow analysis to expose where physical bottlenecks and policy constraints intersect. This is essential where dual-use export restrictions or countervailing determinations can abruptly reroute supply chains.
-
Our scenario suite quantifies financial outcomes across alternative futures — from fast-decarbonization to protectionist trade regimes — enabling CFOs and strategy teams to stress-test capex and M&A plans.
-
Complementing quantitative models, our supplier due-diligence templates and regulatory playbooks translate market intelligence into executable procurement terms, joint-development agreements and compliance protocols.
Conclusion — a pragmatic guide to capturing value in 2026
The phosphate ester market presents a classic industrial-chemicals playbook in 2026: steady headline growth (5.4% CAGR into the 2032 horizon), pockets of premium demand, and structural risks centred on feedstock volatility and policy enforcement. Companies that move early to de-risk their feedstock exposure, codify supplier partnerships that include technical co-development, and invest selectively in sustainable, application-differentiated chemistries will capture disproportionate value.
For the decision-critical details — including the full segment and regional models, supplier scorecards and the playbook to operationalize these recommendations — access the full PW Consulting report and interactive model. Our team is available for bespoke briefings to tailor scenarios specifically to your portfolio, procurement profile or investment thesis.
For detailed analysis of this topic, please visit the official page: Phosphate Ester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com