

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting — A2P SMS Market: From USD 71.5B (2025) to USD 96.0B by 2032 at 4.5% CAGR
By pmarketresearch, 2026-07-30
A2P SMS Market 2026: A Strategic Preview for Enterprise Decision-Makers
As organizations finalize budgets and channel strategies for 2026, A2P (application-to-person) SMS remains a cornerstone of digital customer engagement and authentication. PW Consulting’s latest A2P SMS Market study — with base year 2025 and a forward-looking forecast through 2032 — offers the empirical foundation that executives need to shape resilient, compliant, and cost-effective messaging strategies. This preview highlights the research’s strategic value, synthesizes market dynamics, and surfaces actionable priorities that will matter most in 2026, while preserving the full, proprietary segment-level intelligence for the complete report.
A2P SMS Market
Market Trajectory: What the Macro Numbers Tell Us
The A2P SMS market has demonstrated steady expansion through the early 2020s. Our model shows a notable increase in global revenue from the beginning of the decade into the 2025 base year, and a continuation of growth across the forecast window. PW Consulting’s scenario modelling projects growth consistent with a mid-single-digit compound annual growth rate (CAGR) through 2032, reflecting a balance between legacy SMS demand (authentication, alerts) and evolving channel migration toward richer messaging formats over time.
A2P SMS Market
- Market momentum: The industry’s trajectory reflects sustained enterprise reliance on SMS for high-assurance use cases (e.g., OTPs, transactional notifications) even as omnichannel strategies diversify.
- Forecast durability: A forecast CAGR of approximately 4.5% to 2032 underpins our baseline scenario, with upside and downside sensitivities driven by regulatory shifts, operator commercialization of RCS, and enterprise migration rates to rich channels.
- Concentration metrics: The sector shows measurable concentration — our CR3 and CR5 estimates indicate that a relatively small set of global providers control a meaningful share of A2P volume and revenue, shaping routing dynamics and commercial bargaining power.
Why This Study Matters for 2026 Decisions
Enterprises face three intersecting pressures in 2026: heightened regulatory scrutiny, evolving operator economics, and the need to modernize customer engagement stacks without disrupting mission-critical flows. PW Consulting’s research equips decision-makers to act on each pressure with precision:
A2P SMS Market
- Regulatory compliance is no longer optional: Mandatory registration regimes and operator-enforced blocking have increased the operational risk of legacy approaches to A2P messaging. Our analysis translates regulatory timelines and enforcement practices into a pragmatic compliance roadmap for enterprises and their vendors.
- Cost and performance optimization: With wholesale and termination pricing under review in several markets, buyers must balance unit costs with deliverability and latency. The report provides an evidence-based framework for assessing total cost of ownership across multi-vendor routing strategies.
- Channel strategy orchestration: While SMS remains indispensable for certain transactional flows, the right mix of SMS, RCS, push channels, and voice differs by use case and geography. We show how to prioritize migrations that preserve security and conversion while capturing efficiency gains.
Key Market Dynamics and Implications
The next 12–24 months will be shaped by a handful of observable trends that are already influencing vendor behaviour and enterprise procurement.
- Regulatory tightening and carrier commitments: Several national regulators and large operator groups have introduced voluntary commitments, proposed price caps, and mandatory registration programs. These measures reduce commercial uncertainty in some corridors but raise compliance and administrative demands for enterprises — particularly those using multi-country short codes, toll-free messaging, or 10DLC-type arrangements.
- Operator-led infrastructure moves: Investments in fiberization and operator-grade A2P platforms signal that some national carriers are positioning to capture more enterprise value. Where operators control delivery and routing, enterprises will need to adapt contracts and testing regimes to maintain throughput and service-level guarantees.
- Vendor consolidation and concentration: The market shows notable concentration among a handful of global CPaaS and messaging platform providers. This dynamic creates bargaining leverage for large suppliers but also opportunities for nimble regional specialists to win by optimizing local termination and compliance.
- Product differentiation: Vendors are layering analytics, delivery assurance, omnichannel integration (SMS + RCS + chat), and compliance tooling to escape commoditization. Enterprises should evaluate vendors across these dimensions rather than on headline price alone.
Competitive Landscape: How Leading Providers Are Positioning
Our competitive review profiles the strategic positioning of global and regional A2P players. The following summaries reflect each provider’s primary market strengths and the strategic questions buyers should ask during vendor selection.
- Twilio, Inc.: Known for programmable messaging APIs that support high-volume A2P use cases, Twilio’s global carrier partnerships and developer-centric platform make it a default choice for firms prioritizing speed-to-market and API flexibility. Evaluate real-world SLA performance, regional termination economics, and managed compliance support when assessing fit.
- Sinch AB: Sinch’s emphasis on omnichannel integration and direct operator relationships in several regions positions it well for enterprises seeking consolidated messaging footprints. Ask about direct operator routing versus wholesale fallbacks and the vendor’s roadmap for RCS scale.
- Infobip Ltd: Infobip combines global reach with engagement tooling that supports both transactional and marketing use cases. Focus discussions on analytics fidelity, segmentation control, and campaign governance, especially where regulatory opt-in compliance is material.
- Vonage America LLC: Vonage’s API suite supports authentication and alerts with integrated voice and messaging capabilities — useful for multi-modal authentication strategies. Probe redundancy strategies and delivery telemetry for high-throughput authentication flows.
- Plivo, Inc.: Plivo offers messaging APIs and compliance-focused routing. For enterprises with complex routing needs, validate how the provider manages carrier relationships and handles regulatory registrations on behalf of customers.
- Route Mobile Ltd and regional carriers: Providers with strong footprints in Asia and emerging markets can offer favorable termination economics and localized compliance expertise. Confirm scale commitments and SLAs for cross-border campaigns.
- Tata Communications and global network operators: These players leverage network infrastructure to offer multinational reach with fiber-enhanced delivery. Evaluate contractual terms for multinational SLAs and dispute resolution.
- CM.com, Syniverse, Bandwidth, Kaleyra: Each brings specialized strengths — European omnichannel integration, advanced routing and compliance, North American carrier integrations, and analytics-driven messaging, respectively. Use vendor scorecards to match provider capabilities to priority use cases.
Recent Industry Moves — Practical Takeaways
Recent launches and regulatory milestones are already reshaping vendor and buyer behaviours:
- National operator platforms and fiberization initiatives have created new direct-delivery options that can improve reliability for enterprise traffic, but they also require contractual and technical adjustments.
- Toll-free A2P services and mandatory registration regimes have tightened the operational window for unregistered traffic in large markets — a hard stop that requires immediate remediation for non-compliant senders.
- Regulators’ voluntary commitments on termination pricing introduce temporary stability in some markets through defined time horizons; however, enterprises should plan for pricing resets at commitment expirations.
What the Full Report Contains — Practical, Actionable Assets
The full PW Consulting A2P SMS Market report is designed to be directly usable by strategy, procurement, security, and channel teams. Key deliverables include:
- Proprietary market model and forecast (2026–2032) with scenario sensitivity and upside/downside paths for regulatory and technology adoption variables.
- Use-case decision matrix that maps messaging channels to authentication, transactional, and marketing outcomes — including migration sequencing and migration ROI estimates.
- Vendor scorecards and procurement playbook, including RFP templates, evaluation checklists, contract clauses for delivery SLAs, and compliance obligations.
- Compliance and registration roadmap covering major regulatory regimes, required registrations, and operational controls to prevent blocking or filtering.
- Technical annex: deliverability best practices, monitoring KPIs, test plan templates, and integration guides for hybrid routing architectures.
- Country-by-country regulatory tracker and operator landscape briefing for prioritized markets.
Five Strategic Priorities for 2026
Enterprises should prioritize the following actions in 2026 to preserve SMS’s value while positioning for channel evolution:
- Operationalize compliance: Complete mandatory registrations, adopt doctrinal controls for consent and opt-out, and build monitoring to detect carrier-level blocks quickly.
- Diversify delivery: Implement multi-route architectures with at least one primary and one fallback provider per critical corridor to protect availability and pricing leverage.
- Measure beyond price: Evaluate vendors on deliverability, latency, fraud detection, and support for re-routing during outages — not price per message alone.
- Prioritize high-assurance flows for SMS: Keep SMS for OTPs and critical transactional alerts while testing richer channels (RCS, in-app messaging) for engagement-focused journeys.
- Embed analytics into procurement: Require vendors to provide standardized delivery and engagement metrics to enable continuous optimization and transparency.
Conclusion — The Strategic Edge in 2026
For enterprises, SMS will remain a mission-critical channel in 2026 — but success will be determined by how quickly organizations manage regulatory compliance, restructure routing and vendor relationships, and incorporate richer channel options where appropriate. PW Consulting’s A2P SMS Market study provides the quantitative foundation, competitive intelligence, and actionable toolkits that decision-makers need to execute on these imperatives.
To access the full segmentation insights, provider benchmarks, and the comprehensive implementation playbook that underpin these strategic conclusions, please visit the PW Consulting study landing page for subscribers and decision-makers. The granular data and vendor-level scoring are held in the full report to ensure you have the detailed inputs required to operationalize these recommendations inside your organization.
For detailed analysis of this topic, please visit the official page: A2P SMS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Helium Gas Market to Reach USD 344.8M by 2032 at 6.98% CAGR — PW Consulting Insight
By pmarketresearch, 2026-07-30
Helium Gas Market Outlook 2026: Strategic Imperatives for Navigating a Volatile Supply Era
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused briefing that translates our latest Helium Gas Market study into the concrete decisions executives must face in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the study models a market expanding from roughly USD 215 million in 2025 to about USD 345 million by 2032 at a compound annual growth rate of approximately 6.98%. Those headline metrics frame a market whose growth is real and durable—but whose near-term shape is being remade by geopolitics, new supply entrants, and accelerating technology requirements.
Helium Gas Market
Why this research matters for 2026 decision-makers
-
Immediate supply shock and reconfiguration: The industry experienced a material supply disruption in early 2026. The loss of a major production hub removed a substantial share of global supply, producing acute spot-market volatility and squeezing inventories across industrial and strategic users. This shock exposed structural vulnerabilities in procurement strategies and storage infrastructure.
Helium Gas Market -
Rapid emergence of new domestic capacity and storage options: Counterbalancing the shock, a number of new projects and storage assets came online or advanced through regulatory and commercial milestones in 2025–2026, particularly in North America. These developments shorten paths to recovery but do not immediately erase regional mismatches and logistics constraints.
Helium Gas Market -
Demand-side acceleration in high-value end uses: Cryogenics, advanced electronics manufacturing, and medical applications continue to underpin a structural demand tailwind. At the same time, higher purity specifications and new delivery modalities are changing the economics of supply and creating premium tiers that require differentiated commercial approaches.
What the full report delivers (practical, operational outputs)
-
Forward-looking supply-demand models: A transparent, scenario-driven engine that projects volumes, storage drawdown/rebuild timelines, and price trajectories across a range of disruption and policy outcomes. These models are built to be used as board- and transaction-ready appendices.
-
Commercial playbooks: Negotiation templates for multi-year offtakes, indexation structures, inventory pooling agreements, and force majeure clauses designed to protect both buyers and sellers in volatile cycles.
-
Supplier scorecards and procurement risk maps: Qualitative and quantitative assessments of upstream producers, liquefiers, and distributors—covering technical capability, contractual flexibility, geopolitical exposure, and delivery reliability.
-
Project-level investment toolkits: Standardized NPV templates, capex/opex benchmarks, liquefaction sizing guidelines, and break-even sensitivity analyses for greenfield and brownfield helium projects.
-
Regulatory and storage strategy playbook: An operational guide for engaging with regulators, structuring storage incentives, and deploying cavern or cryogenic inventory solutions to stabilize supply for critical users.
-
Actionable risk-heatmaps and early-warning indicators: A compact set of trigger metrics—geopolitical exposure, spare liquefaction capacity, cavern inventory days, and purity premium trends—designed to translate market signals into commercial actions within quarterly board cycles.
Note: This briefing presents our strategic synthesis. The full report contains granular segment-level tables, regional and application splits, and downloadable financial models that are intentionally withheld from this preview to preserve the report’s proprietary value.
Competitive landscape — positioning and strategic moves
-
Incumbent integrated gas majors retain structural advantages. Companies with integrated upstream access, large-scale liquefaction capability, and established distribution networks hold pricing leverage during tight markets because they can allocate volumes to higher-value applications and optimize logistics across regions.
-
Product innovation is a differentiator. Recent launches of ultra-high-purity product lines and improved liquid helium delivery systems underscore that manufacturers who can combine technical specifications with delivery efficiency capture premium segments and sticky contracts.
-
Independent producers and explorers are high-opportunity targets. Junior and mid-sized operators that can deliver de-risked volumes with offtake security become attractive partners for co-investment or acquisition as incumbents seek to diversify feedstocks and shorten lead times.
-
Market concentration remains relatively low. The industry is still fragmented, with top players collectively holding modest shares relative to other industrial gases—this fragmentation creates fertile ground for strategic consolidation, especially among companies that can add liquefaction, storage, or logistics capabilities.
Our company-by-company analysis in the full report dissects balance-sheet strength, contract footprints, recent product and project announcements, and operational risk. Public developments through mid‑2026—anything from force majeure declarations to high-purity product introductions and long-term offtake deals—are factored into supplier risk rankings and acquisition screens.
Scenario planning: three pathways every executive must stress-test
-
Short-term shock and constrained recovery (most relevant early–mid 2026): Severe regional shortages and elevated spot premiums compel buyers to deploy contingency inventories, renegotiate indexation clauses, and prioritize critical processes. Sellers that can re-route limited volumes to the most lucrative applications outperform peers.
-
Normalization through new capacity (base case over 2027–2030): New production wells, liquefaction trains, and storage caverns progressively restore global availability. The pace of commercialization and logistics ramp determines whether price normalization will be gradual or abrupt.
-
Structural tightness driven by demand step‑up (tail risk to 2032): If long-term demand from advanced electronics and cryogenic applications accelerates beyond current project additions, persistent premiums and incentivized investment will keep returns strong for marginal producers.
Each scenario in our model is accompanied by decision triggers and tactical timelines that tell procurement teams when to shift from spot to committed cover, when to mobilize co-investment offers, and when to accelerate substitution or recycling programs.
Six priority actions for executives in 2026
-
Lock flexible multi-year access: Secure a mix of indexed and fixed-price offtakes that balance cost certainty and supply flexibility. Include rights to volume take-or-pay adjustments tied to force majeure and logistical disruptions.
-
Invest in storage and on-site buffering: Where feasible, expand cavern or cryogenic storage holdings to create operational resilience for mission‑critical processes.
-
Pursue strategic co-investments with explorers and midstream developers: De-risk new supply by offering staged capital in return for prioritized delivery windows or equity-linked pricing.
-
Accelerate purity and delivery innovations: For buyers in electronics and research sectors, demand contracts that guarantee purity tiers and optimized delivery modalities to reduce boil‑off and handling losses.
-
Deploy a supplier diversification playbook: Avoid single-supplier dependency by combining national producers, regional distributors, and international trading partners.
-
Institutionalize scenario-driven procurement: Use the report’s scenario engine and early-warning indicators to convert market signals into procurement actions on a 90–180 day cadence.
Closing: translating insight into competitive action
In the volatile environment of 2026, helium is no longer a fungible commodity that can be purchased on short notice without strategic consequence. The market’s near-term turbulence—driven by significant supply disruptions and matched by a pipeline of new projects and storage assets—creates a decisive window for corporate action. Firms that combine disciplined procurement, targeted capital deployment, and smart partnerships will convert current market stress into long-term competitive advantage.
PW Consulting’s full Helium Gas Market report provides the granular, actionable elements your team needs: detailed segment forecasts, supplier scorecards, contract templates, and downloadable financial models. For executives preparing budgets, negotiating offtakes, or assessing M&A in 2026, the full analysis turns headline trends into executable strategy. Contact our advisory team to access the proprietary datasets and scenario models referenced in this briefing.
For detailed analysis of this topic, please visit the official page: Helium Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lumpectomy Market to Reach $260M by 2032 — 5% CAGR (Base Year 2025)
By pmarketresearch, 2026-07-30
Lumpectomy Market 2026: A Strategic Preview for Decision‑Makers
Executive snapshot
As health systems and medtech investors evaluate where to allocate capital in 2026, the lumpectomy ecosystem presents a uniquely investable intersection of imaging, localization, and intraoperative analytics. Our market model — built on a 2025 base year with a historical window covering 2020–2025 and a forward forecast to 2032 — projects the global lumpectomy market to grow at a steady compound annual growth rate (CAGR) of approximately 5.0%. In absolute terms, the market expands meaningfully from its 2020 baseline through 2025 and is forecast to approach the mid‑hundreds (USD, revenue unit: Million) by the end of the 2026–2032 horizon. This trajectory, combined with recent regulatory milestones and persistent reimbursement dynamics, makes 2026 a pivotal planning year for product strategy, commercialization, and M&A activity.
Lumpectomy Market
Why this research matters for 2026 decisions
- Capital allocation: Whether you are a strategic acquirer, growth‑stage investor, or corporate VC, our analysis translates market momentum into timing signals for late‑stage financing and tuck‑in M&A.
- Regulatory sequencing: Recent approvals and submissions are reshaping the acceptable engineering and clinical evidence bar—this report maps decision gates and pragmatic alternatives for regulatory pathways.
- Payer strategy: As payers demand value evidence in surgical adjuncts, our reimbursement playbook links clinical endpoints to billing pathways and pricing levers.
- Commercial prioritization: The full study identifies where to deploy limited sales resources first, which clinical champions to engage, and how to structure pilot programs to accelerate uptake.
Data‑driven context (what the numbers tell us)
From a modeling perspective, the lumpectomy market demonstrated consistent growth during 2020–2025, reflecting both rising procedure volumes and higher per‑case spend driven by advanced intraoperative tools and adjunctive imaging. Using 2025 as the base year, our forecast period (2026–2032) assumes a 5.0% CAGR reflecting conservative uptake of new technologies, continued pressure on per‑procedure reimbursement, and the gradual diffusion of AI and localization platforms into standard practice. The model incorporates scenario runs that stress test adoption curves, reimbursement shocks, and accelerated regulatory approvals; these scenarios materially change investment timing and expected IRR for product launches.
Lumpectomy Market
What the full report contains (actionable deliverables)
- Executive summary with 3‑ to 5‑year strategic options tailored to manufacturers, investors, and hospital systems.
- Market sizing methodology and model (built on USD, revenue unit: Million) with downloadable forecasting tools and sensitivity levers.
- Go‑to‑market playbooks for device OEMs and software providers—including direct sales vs. distributor models, hospital contracting templates, and KOL engagement timelines.
- Regulatory pathway mapping that compares De Novo, FDA PMA, and 510(k) strategies with timelines, evidence expectations, and filing risks.
- Reimbursement and payer engagement framework: coding ladders, HTA / economic dossier outlines, and payer negotiation templates.
- Competitive intelligence dossiers on leading and fast‑emerging companies, including capability maps and partnership vectors.
- Investment and M&A thesis with target screening criteria, valuation drivers, and integration checklists.
- Primary market research insights from surgeon interviews, hospital procurement officers, and payers alongside real‑world evidence design templates.
Competitive landscape — strategic implications
The competitive field in 2026 is a blend of imaging pioneers, localization platform providers, and niche innovators delivering point solutions for intraoperative margin assessment and tumor localization. Key companies shaping competitive dynamics include:
Lumpectomy Market
- Perimeter Medical Imaging AI, Inc. — Perimeter’s Claire system (formerly B‑Series OCT with ImgAssist AI 2.0) has recently achieved FDA premarket approval (PMA) as the first AI‑enabled intraoperative imaging device specifically cleared for margin assessment. This regulatory milestone raises the bar for developers of intraoperative imaging: PMA‑level evidence is now precedent for devices claiming similar clinical utility. Strategically, competitors must decide whether to pursue expedited PMA pathways with extensive clinical endpoints or to position as adjunctive tools under alternative regulatory strategies.
- Lumicell, Inc. — Lumicell’s fluorescence‑guided LumiSystem secured FDA approval in 2024 and has a permanent HCPCS code after commercial availability. The combination of approval plus a coding pathway materially lowers the commercial friction for fluorescence adjuncts, enabling hospital adoption and third‑party billing. For incumbents, Lumicell’s commercial footprint and coding success illustrate the commercial uplift achievable when clinical differentiation and reimbursement alignment coincide.
- Endomag (a Hologic company) — Endomag’s magnetic localization solutions (Magseed®/Sentimag®) continue to be a robust, non‑radioactive localization alternative. Endomag’s integration within a larger corporate parent introduces distribution scale and cross‑sell potential—important considerations for any competitor evaluating independent commercialization vs. strategic partnership.
- Dilon Technologies — Dilon’s MarginProbe technology, rooted in radiofrequency spectroscopy, remains an important legacy approach for margin assessment. Established incumbents with strong OR penetration and long clinical track records present adoption inertia challenges for new entrants; overcoming this requires clear evidence of improved outcomes or workflow benefits.
- Cairn Surgical, Inc. — Cairn’s patient‑specific 3D‑printed Breast Cancer Locator (BCL™) submitted a De Novo 510(k) application in March 2026. If cleared, patient‑specific guidance systems could alter the localization landscape by offering bespoke intraoperative navigation with potential benefits in margin clearance and cosmetic outcomes. Watch for the FDA’s feedback and the company's plans for clinical roll‑out and reimbursement capture.
Regulatory and reimbursement dynamics to monitor
- Regulatory precedent: The March 2026 PMA for an AI‑enabled intraoperative device signals FDA receptivity to AI when supported by rigorous clinical trials. Companies must plan longer development cycles or invest in registries that can underpin PMA‑grade submissions.
- Coding & billing: The presence of permanent HCPCS for a lumpectomy adjunct materially shortens commercial time‑to‑revenue. Conversely, CPT coverage frameworks remain variable by payer; CPT 19301 (partial mastectomy / lumpectomy) is a common billing pathway, but macro trends show Medicare reimbursement erosion over time—necessitating robust cost‑effectiveness arguments.
- Payer expectations: Payers increasingly request hard endpoints—reduction in re‑excisions, OR time saved, and downstream cost avoidance. Early generation economic models should be conservative and validated through prospective real‑world studies.
Strategic playbook — recommended moves for 2026
- Prioritize evidence that pays: design trials that link device use to reductions in re‑excisions and total episode cost, not just surrogate imaging endpoints.
- Dual‑track regulatory planning: where feasible, prepare for PMA/De Novo while leveraging 510(k) pathways in parallel geographies to accelerate commercialization.
- Negotiate coding early: pursue HCPCS / local coverage determinations alongside pivotal studies to align market access timing with launch.
- Build hospital value propositions: focus pilots in high‑volume centers of excellence and instrument adoption to produce compelling case studies and peer‑reviewed outcomes.
- Form selective partnerships: engage larger device platforms or distributors to accelerate OR penetration; consider co‑development with imaging or pathology firms to create bundled solutions.
- Structure commercial pilots for scalability: define KPIs (re‑excision rate, OR time, length of stay), collect prospective data, and prepare turnkey implementation packages for rollout.
- Prepare for consolidation: identify adjacent technologies or regional players as potential tuck‑ins to round out a surgical oncology portfolio.
Key risks and mitigations
- Reimbursement pressure — mitigation: invest early in health economic studies and payer engagement to support coding and coverage.
- Regulatory uncertainty — mitigation: build robust trial designs, engage the FDA early, and consider international regulatory diversification.
- Clinical adoption inertia — mitigation: prioritize workflow integration, surgeon ergonomics, and OR staff training to minimize friction.
- Concentration of market power among incumbents — mitigation: differentiate on outcomes, total cost of care, and post‑market evidence to create adoption vectors.
Conclusion — what to do now
The lumpectomy market in 2026 represents a measured growth opportunity underpinned by technological innovation, regulatory milestones, and evolving payer expectations. For corporate strategists and investors, the imperative is clear: align regulatory strategy with payer evidence generation, prioritize pilot deployments that generate real‑world outcomes, and consider partnership routes to accelerate clinical scale. Our full PW Consulting Lumpectomy Market report contains the granular, model‑driven inputs that convert these strategic recommendations into executable investment and commercialization plans — including region‑by‑region roll‑out options, scenario financials, and a vendor matrix. For the detailed segment breakdowns, vendor share models, and the interactive forecast tools that power board‑level decisions, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Lumpectomy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acrylic Foam Tape Market Set to Grow at 7.2% CAGR Through 2032
By pmarketresearch, 2026-07-30
Acrylic Foam Tape Market — Strategic Preview for 2026 Decisions
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a condensed, decision-focused preview of our new Acrylic Foam Tape Market study. This briefing is crafted to help executives, product leaders, procurement heads, and corporate strategists position their organizations for the opportunities and risks that will define 2026. It showcases the report’s analytical depth and actionable frameworks while deliberately withholding the granular subsegment datapoints that form the core intelligence of the full study—details that are available via the full report.
Acrylic Foam Tape Market
Market trajectory at a glance
Measured on a USD-billion basis with 2025 as the reference year, the global acrylic foam tape market has moved from an estimated USD 3.6 billion in 2020 to about USD 5.1 billion in 2025. Under our central scenario, the market is projected to expand to roughly USD 5.51 billion in 2026 and continue growing to an estimated USD 8.3 billion by 2032. That expansion reflects a compound annual growth rate (CAGR) of approximately 7.2% over the forecast window (2026–2032), underscoring a durable demand environment driven by structural bonding applications across automotive, construction, and electronics segments.
Acrylic Foam Tape Market
Why this research matters for 2026 strategic moves
- Investment timing: Our modeled demand curves and scenario-based cash-flow impacts identify inflection windows for capacity expansion, tooling spend, and new adhesive formulation rollouts.
- Procurement optimization: The report quantifies cost exposure to raw-material volatility and proposes hedging and supplier-portfolio tactics aligned with likely price pathways through 2026 and beyond.
- Go-to-market prioritization: We translate end-market dynamics into product- and channel-level plays—helping product managers decide where to accelerate R&D and which value propositions will win in short-cycle procurement competitions.
- M&A and partnership screening: Given the high market concentration among a handful of global suppliers, we provide a practical target-scoring framework to identify horizontal and vertical consolidation opportunities that deliver scale and access to proprietary adhesive technologies.
- Regulatory & trade risk navigation: With evolving antidumping reviews and raw-material trade flows shaping margin outcomes, the analysis pinpoints the compliance and sourcing levers that will preserve competitive positioning in 2026.
What the full report delivers (practical components)
- Top-down and bottoms-up market sizing reconciled across historical (2020–2025) and forecast (2026–2032) horizons, including high/low scenario envelopes tied to macro and end-market sensitivities.
- Demand- and price- forecasting models with configurable inputs (raw material cost indices, energy assumptions, logistics stress scenarios) so buyers and planners can run bespoke sensitivity analyses.
- Supplier and product scorecards—coverage of adhesive chemistries, carrier constructions, performance attributes (e.g., shear, peel, creep), and application-fit guidance for automotive, construction, electronics, and specialty use-cases.
- Commercial playbooks—pricing strategy options, channel segmentation tactics, specification-driven value propositions, and win-loss analysis from procurement RFQs.
- Risk heatmaps and mitigation templates—material supply disruption playbooks, regulatory tracking matrices, and contingency sourcing routes.
- M&A playbook and target shortlist methodology—synergy quantification templates and integration risk checklists tailored to acrylic-foam-tape technology and go-to-market realities.
- Appendices detailing methodology, data sources, and assumptions to support replication, audit, or internal governance review.
High-level, data-driven insights (without revealing proprietary splits)
Several takeaways from our analysis are immediately actionable:
Acrylic Foam Tape Market
- Demand resilience is broad-based. The market’s mid-single-digit to high-single-digit compound growth is underpinned by multiple industrial end-markets that are themselves evolving—most notably in structural bonding for lightweight vehicle design, façade and interior construction materials, and increasingly compact, bonded electronics assemblies.
- Concentration confers both opportunity and barrier. The market is dominated by a small number of global players with deep adhesive and application engineering capabilities. This concentration creates attractive corridors for M&A and scale-driven margin expansion, while simultaneously raising the bar for new entrants attempting to break into specification-led industrial procurement.
- Product innovation is buyer-facing. Advances in primerless adhesion to low-surface-energy (LSE) plastics, improved temperature and creep resistance, and engineered carrier constructions are shifting buyer preferences away from mechanical fasteners in many high-value applications.
- Raw-material cost dynamics matter. Recent moves by major chemical suppliers and observed spot prices have meaningful pass-through effects on margin unless manufacturers adopt smarter contracting, indexation clauses, or technical R&D that reduces butyl acrylate intensity per unit of finished tape.
Competitive landscape—profiles and strategic posture
The competitive review in the full report drills into the product portfolios, route-to-market, and technology moats of the sector’s leading firms. Below are the strategic profiles we use to interpret competitive behavior and shortlist actions for 2026:
- 3M Company — The originator of high-performance acrylic foam bonding tapes with a broad global footprint and a reputation for end-to-end application engineering. Their VHB™ family is a benchmark for structural-bond solutions across automotive, aerospace, and electronics. Their strength is combination of brand trust, specification presence, and deep technical support capabilities.
- tesa SE — European-based, known for industrial-grade acrylic foam tapes with an emphasis on reliable long-term adhesion in demanding environments. tesa’s strength lies in manufacturing consistency, standards compliance, and OEM relationships in automotive and building components.
- CCL Design — Niche innovator focused on primerless solutions that bond to LSE plastics—an important capability as OEMs shift towards lightweight polymers. Recent product launches underscore an R&D-led growth posture targeted at automotive paint and plastics bonding challenges.
- AFTC Group — Specialist producer with product lines designed to displace traditional mechanical bonding in industrial scenarios. Their approach combines targeted product performance with agility to serve bespoke industrial use-cases.
- Saint-Gobain — Leveraging material science expertise and broad distribution channels, they offer durable bonding tapes suitable for interior and exterior applications, benefitting from cross-selling into construction and industrial markets.
- Avery Dennison — Focused on closed-cell acrylic foam carriers and industrial bonding, with strength in scalable manufacturing and industrial customer service models.
- Scapa Group PLC — Provides a range of acrylic foam tapes for bonding, sealing and insulation, with reach across construction, automotive and cable sectors and a service-oriented customer approach.
Collectively, the top-tier firms create a market environment where technological differentiation, application engineering, and distribution breadth determine winner-take-most dynamics. Our competitive matrices rank firms across innovation, cost competitiveness, application breadth, and supply resilience to help clients craft response strategies.
Raw-material and regulatory developments shaping 2026
- Raw-material price actions: Major chemical suppliers’ pricing decisions are transmitting into finished-tape cost structures. For example, a recent pricing announcement by a leading monomer supplier raised selling prices in North America, and procurement data shows regional spot-price variances that influence manufacturer margin trajectories and sourcing strategy.
- Trade & regulatory shifts: Trade remedies and antidumping reviews in select markets are creating both short-term dislocations and longer-term sourcing re-routes—creating windows for local manufacturers while adding compliance burdens for global buyers.
Strategic imperatives for 2026
- Embed raw-material indexation and flexible contracting in commercial agreements to protect margins from monomer price swings.
- Pursue product differentiation through adhesion to LSE substrates and temperature-resistant formulations—these features command specification premium in key OEM accounts.
- Prioritize supplier resilience: dual sourcing, near-shoring options, and strategic alliances reduce delivery and compliance risk in trade-sensitive jurisdictions.
- Pursue targeted M&A to acquire formulation IP or application-engineering capabilities rather than scale-for-scale alone; bolt-ons that secure OEM approval pathways deliver outsized value.
- Operationalize go-to-market playbooks for construction and automotive aftermarket channels where specification inertia is lower and adoption cycles are faster.
Next steps — accessing the complete intelligence
This preview outlines the report’s strategic relevance and highlights the levers executives should prioritize in 2026. The full PW Consulting Acrylic Foam Tape Market report contains the granular segmentations, region-by-region and application-by-application forecasts, supplier scorecards, pricing ladders, and downloadable financial models referenced here. Those core subsegment datapoints, which we intentionally withhold in this executive preview, are crucial for tactical planning and are available in the full study.
For decision teams preparing budgets, R&D roadmaps, or M&A scorecards for 2026, the full report delivers the empirical foundation and operational templates to translate opportunity into measurable outcomes.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Acrylic Foam Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
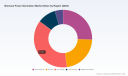
Biomass Power Generation Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As PW Consulting’s lead industry analyst, I present a strategic preview of our comprehensive Biomass Power Generation Market study — the operational intelligence that will inform go/no-go choices, M&A road maps, and policy engagement strategies in 2026. The global biomass power generation market, which grew from roughly USD 73.7 billion in 2020 to an estimated USD 92.3 billion in our 2025 base year, is forecast to expand at a compound annual growth rate (CAGR) of approximately 5.3% over the 2026–2032 forecast window, reaching an estimated USD 132.3 billion by 2032. These headline dynamics hide important inflection points for participants across the value chain: fuel suppliers, plant OEMs, utility operators, project financiers, and downstream offtakers.
Biomass Power Generation Market
Why this research matters in 2026
- Policy-driven capital flows. 2026 is a decisive year in many jurisdictions as subsidy frameworks, tax-credit regimes, and clean power procurement rules reach new maturity. Understanding how technology-neutral incentives and CfD-type arrangements interact with project economics can change project prioritization within months.
- Operational and supply-chain stressors. Raw material prices, logistics bottlenecks, and interconnection queues are not background noise — they shape near-term deliverability of capacity and the bidding behavior of incumbents and new entrants.
- Competitive repositioning. Leading names on the supply and developer side are rapidly consolidating capabilities (fuel supply, conversion technology, and grid-scale dispatch), creating tactical windows for partnerships and carve-outs. The market exhibits measurable concentration among larger players even as specialized technologies broaden the competitive set.
Market trajectory: what the macro numbers reveal
The market’s movement from about USD 73.7 billion in 2020 to an estimated USD 92.3 billion in 2025 underscores sustained demand for bio-based generation as part of broader decarbonization portfolios. At a ~5.3% CAGR through 2032, the sector is not a hyper-growth bubble but rather a resilient, capital-intensive market where scale, offtake security, and fuel strategy determine long-term returns. Year-on-year volatility in our projections—driven by commodity cycles, policy timing, and one-off project commissions—means that timing of investments and staged capital deployment are critical practical levers for 2026 decision-making.
Biomass Power Generation Market
Key dynamics shaping 2026 strategy
- Policy and incentives: Technology-neutral clean electricity credits and investment tax incentives that came into effect in several jurisdictions are reshaping project IRRs. However, eligibility conditions (e.g., prevailing wage, domestic content) require operational and contractual adjustments that, if unaddressed, erode anticipated benefit capture.
- Fuel-cost and feedstock security: Densified biomass pricing and new processing capacity materially affect long-term fuel contracts. Domestic fuel pricing benchmarks and new supply nodes (e.g., pellet processors, palm-kernel-shell plants) change procurement strategy from single-source long-term contracts to diversified portfolio sourcing.
- Grid and interconnection constraints: Interconnection queue backlogs and regional capacity limits create uncertainty around commissioning timelines — making staged or repurposable project designs (co-firing, modular gasification, hybridization with other renewables) more attractive to financiers.
- Technology and asset lifecycle: Mature combustion technologies dominate installed capacity, but emerging pathways (advanced gasification, anaerobic digestion integration, and co-processing with industrial sites) are becoming commercially relevant. Lifecycle cost, feedstock flexibility, and retrofitability determine which technologies win in specific applications.
- ESG and sustainability traceability: Increasing buyer and regulator scrutiny around feedstock origin, carbon accounting, and land-use impacts means that sustainable supply chain verification is no longer a nice-to-have — it is a gate for offtake and financing.
Competitive landscape — who matters and what they’re doing
The competitive map in 2026 is a mix of pure-play biomass operators, diversified utilities adding bioenergy to their portfolios, EPC and turbine OEMs, and vertically integrated industrial players. Market concentration is meaningful: the top three players control a notable share of installed capacity and pellet sourcing channels, while the top five further consolidate scale advantages in logistics and financing. This concentration has several implications:
Biomass Power Generation Market
- Scale enables better access to long-term fuel contracts and favorable financing;
- Incumbents can rapidly pivot portfolio exposure through acquisitions or asset swaps;
- Niche players can still capture value by specializing in feedstock types, regional execution expertise, or advanced conversion technologies.
Representative firms to watch in 2026 include Drax Group plc, ACCIONA Energía, Rayonier Advanced Materials, Mitsubishi Heavy Industries, Babcock & Wilcox, Engie SA, Vattenfall AB, Siemens Energy, GE Vernova, and Ørsted A/S. Collectively, these organizations demonstrate three strategic postures worth emulating or guarding against:
- Vertical integration and fuel control: Examples include large pellet production commitments to secure feedstock for fleet operations, enabling predictable dispatch economics and risk mitigation on fuel price volatility.
- Project-scale and turnkey delivery: OEMs and EPCs are offering bundled supply, operations, and long-term maintenance contracts to de-risk brownfield conversions and greenfield projects for utilities and industrial players.
- Innovation through partnerships: Cross-border and industrial joint ventures are accelerating the deployment of bioenergy at sites with existing steam or process-heat needs, creating synergies between power generation and industrial decarbonization.
Notable 2025–2026 developments and what they mean for 2026 action
- Drax’s record pellet production and transatlantic logistics milestones establish a template for scale-driven feedstock strategies; they also highlight the logistics-capex trade-offs new entrants must evaluate.
- ACCIONA Energía’s recent grid-connected 50 MW project illustrates continued appetite for mid-scale plants that can be integrated into regional renewable stacks and ancillary-services markets.
- Localized fuel-processing investments (e.g., palm-kernel-shell processing enablers) suggest the emergence of new regional supply hubs — an opportunity for offtake contracts and localized logistics plays.
- Policy signals — such as technology-neutral tax credits — increase optionality for investors, but the detail matters: wage and content requirements, inflation adjustments, and carbon accounting rules determine whether a project is bankable under modern project finance diligence.
What the PW Consulting report delivers — practical, transaction-ready intelligence
Our full study is built for decision-makers who need to act in 2026. It includes:
- Actionable investment frameworks that translate policy regimes and fuel-price scenarios into project-level IRR sensitivities and payback timelines;
- Due-diligence checklists tailored for developers, lenders, and technology vendors — covering feedstock procurement, sustainability verification, permitting, and grid interconnection risk allocation;
- Commercial playbooks for developers and feedstock providers that outline viable partnership structures, contract terms, and risk-sharing mechanisms (including sample term-sheet language and capex/O&M benchmarking);
- Technology decision matrices mapping plant scale, feedstock flexibility, lifecycle emissions, and retrofit potential to practical procurement choices;
- A competitor intelligence annex profiling strategy, asset portfolios, and recent moves of leading players — with scenario analysis on how these players could shape regional supply-demand balances;
- Stress-tested market forecasts across multiple macro scenarios so executives can model staged investment and exit options against alternative policy and commodity outcomes.
To preserve the strategic value of our research as a commercial product, we deliberately exclude granular segmentation tables and regional/application-specific dollar breakdowns from this preview. The full report provides those precise splits, enabling granular financial modeling and market-entry plans.
Implications and tactical recommendations for 2026
- Prioritize optionality in capital allocation. Given the moderate but steady growth trajectory, favor staged investments or modular technologies that allow capacity scaling aligned with offtake certainty and policy windows.
- Secure diversified feedstock portfolios. Locking in a mix of local and regional suppliers, and incorporating contingency clauses for price and quality variation, reduces fuel exposure and improves bankability.
- Engage early with regulators and grid operators. Interconnection bottlenecks mean project timelines are frequently governed by systemic constraints rather than plant-level execution. Active advocacy and early technical coordination shorten time-to-market and preserve value.
- Explore strategic partnerships. For mid-sized developers, partnering with vertically integrated partners or large EPC players can bridge capability gaps in logistics, fuel procurement, and financing.
- Embed sustainability traceability into commercial terms. Anticipate lender and offtaker requirements for feedstock origin verification and lifecycle carbon accounting from project inception — a retrospective remedy is expensive and reputationally risky.
- Use policy windows to de-risk returns. Where available, align project timelines with predictable incentive schedules (e.g., tax credit qualification periods), while validating compliance with any prevailing wage or localization conditions.
How to use this preview
This preview is intended to surface the critical strategic questions and near-term levers that will define success in 2026. If you are evaluating capacity additions, M&A targets, financing structures, or supply-chain repositioning, the full PW Consulting Biomass Power Generation Market report contains the granular market sizing, regional and feedstock splits, and financial templates necessary to convert strategy into executable plans.
Next steps
- Request the full report for transaction-ready detail: segmented market tables, technology-specific unit economics, and competitor asset-level data; these are essential for term-sheet drafting, bid pricing, and portfolio stress testing.
- Schedule a tailored briefing with our senior consultants to map findings to your portfolio and craft a 6–12 month playbook that aligns with expected 2026 policy and capital markets timelines.
PW Consulting’s Biomass Power Generation Market study synthesizes market-scale forecasting (with a 2025 base of ~USD 92.3 billion and a forecast path to ~USD 132.3 billion by 2032 at ~5.3% CAGR), operational intelligence, and competitor insight — delivering what decision-makers need to move from strategy to transaction in 2026. For the comprehensive datasets and executable templates that underlie these conclusions, please consult the full report.
For detailed analysis of this topic, please visit the official page: Biomass Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lockout Tagout Equipment Market to Reach USD 481.0M by 2032 at 5.4% CAGR
By pmarketresearch, 2026-07-30
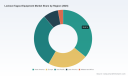
Lockout Tagout Equipment Market: Strategic Intelligence for 2026 — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused preview of our comprehensive Lockout Tagout (LOTO) Equipment Market study. This briefing is designed to clarify why the LOTO market will matter strategically to manufacturing, energy, utilities, and large-scale maintenance organizations in 2026 — and to show the decision-grade capabilities embedded in the full report. Consider this a high-fidelity trailer: we demonstrate methodological rigor, directional findings, and practical implications while intentionally withholding core granular segment tables that reside in the full subscription report.
Lockout Tagout Equipment Market
Market trajectory: macro facts you can act on
Across the historical sample (2020–2025) and into our forecast horizon (2026–2032), the global LOTO equipment market exhibits steady, policy-driven expansion. PW Consulting’s base-year anchoring in 2025 shows the market at approximately USD 336.05 Million (revenue unit: Million). Historically the market grew from roughly USD 261.61 Million in 2020 to that 2025 baseline, reflecting a multiyear response to tightening workplace-safety standards and capital renewal cycles in heavy industry. Looking forward, our model — built on bottom-up supplier models, procurement cycles, and regulatory diffusion scenarios — projects a compound annual growth rate (CAGR) of 5.4% across the 2026–2032 forecast window, with the market approaching the high hundreds of millions of USD by the end of the period.
Lockout Tagout Equipment Market
Why does this matter? Growth in a safety-critical consumables market signals not only replacement demand but also new specification requirements (durability, traceability, and connectivity) that change sourcing, product development, and compliance priorities for enterprises and vendors alike.
Lockout Tagout Equipment Market
Why 2026 is a decision inflection point
-
Regulatory enforcement intensity. OSHA’s Control of Hazardous Energy standards and the persistent incidence of serious injuries during maintenance continue to drive compliance spending. The legal and financial downside — including civil penalties that can reach into the tens or hundreds of thousands of dollars for willful violations — elevates LOTO from an operations item to a board-level risk issue.
-
Technology adoption window. Larger facilities are moving from passive mechanical locks toward connected LOTO (cLOTO) systems with electronic locking, Bluetooth-enabled tracking, and cloud-based compliance logs. Early pilots are now shifting into procurement roadmaps, creating opportunity for incumbents and challengers.
-
Procurement timing. Capital planning and safety program cycles in 2026 present buyers with the option to roll cLOTO into scheduled equipment refreshes or to target immediate upgrades for high-risk zones. The economics differ across asset classes; our report provides the scenario models that show when to accelerate versus when to pilot.
What PW Consulting’s report delivers (practical, executable)
This study is intentionally tactical. We combine market sizing and forecasts with decision-support assets that procurement, safety and engineering leaders can put to work immediately:
-
Dynamic market model (2020–2032) with base-year calibration (2025), enabling executives to run alternate regulatory and adoption scenarios and to quantify upside in connectivity-led upgrades.
-
Vendor landscape and operating profiles — detailed but anonymized benchmarking that compares product breadth, channel reach, and service capability across incumbent manufacturers, distributors, and emerging tech-enabled suppliers.
-
Buyers’ playbooks — step-by-step procurement templates for outright replacement, phased rollouts, and cLOTO pilots including risk scoring, tender language samples, and a supplier evaluation matrix.
-
Implementation checklists and field case studies — real-world lessons on installation sequencing, worker training, and integration to permit-to-work systems.
-
M&A and partnership filters for strategic investors — screens that identify where consolidation yields recurring revenue, service-led differentiation, or access to digital platforms.
-
Financial impact tools — TCO calculators that balance hardware costs, installation and training, compliance risk mitigation, and expected reductions in lost-time incidents.
Competitive landscape: market structure and key players
The LOTO equipment market is moderately concentrated. Our concentration analysis shows that the top three vendors collectively control a meaningful share of traditional mechanical LOTO supply, with the top five extending that concentration further as they incorporate digital capabilities and distribution networks. This concentration creates both barrier and opportunity — established channel relationships favor incumbents, while gaps in digital service and localized support create entry points for agile suppliers.
Profiles of representative firms in the study (summarized):
-
Master Lock — U.S.-based manufacturer known for LOTO padlocks, group lock boxes, hasps, and expanding cLOTO solutions that combine proven hardware with emerging connectivity.
-
Brady — Global supplier of LOTO devices and procedural software, notable for integrated solution sets that pair hardware with documentation and workflow controls.
-
Seton — Distributor and supplier with deep channel presence and compliance-focused assortments, serving large maintenance and safety programs.
-
ABUS — European manufacturer with industrial-grade padlocks and comprehensive program support for multinational operations.
-
IDEAL Industries — Specialist in electrical safety devices and job-site kits supporting trade and maintenance segments.
-
E-Square Alliance — Emerging supplier with innovation-focused product designs and competitive price points in global markets.
-
Creative Safety Supply — Distributor known for breadth of kits, labeling, and site-level safety supplies that enable rapid deployment.
Each profile in the full report includes capabilities scoring, channel coverage, recent go-to-market moves, and supplier risk factors — tools that make vendor shortlists actionable for 2026 tenders.
Strategic implications and recommended executive actions for 2026
Based on our analysis, executives should prioritize decisions across three horizons: near-term compliance, medium-term capability build, and long-term strategic positioning.
-
Near-term (0–12 months): Prioritize legal risk mitigation. Conduct a gap assessment against regulatory requirements and potential fine exposure. Standardize durable, identifiable LOTO devices on critical assets and document procedures to reduce immediate enforcement risk.
-
Medium-term (12–36 months): Pilot cLOTO where ROI is clear. Select 1–3 high-value facilities for cLOTO pilots that integrate with maintenance management systems and provide measurable traceability. Use our TCO and scenario models to quantify the payback window for your portfolio.
-
Strategic (36+ months): Redefine service-led differentiation. Manufacturers and distributors should evolve from selling parts to selling outcomes — warranties, training services, compliance-as-a-service, and software-enabled audit trails that lock in recurring revenue.
-
Supply chain resilience: Map single-source dependencies, qualify second-source suppliers, and insist on traceability and quality standards. Rapid procurement shocks in 2026 can be managed by multi-tier agreements and safety-stock policies informed by our scenario forecasts.
-
M&A and partnerships: For investors and strategic buyers, prioritize targets that provide digital enablement, recurring revenue models, or access to critical distribution channels outlined in our acquisition filters.
Decision-support toolkit included in the full study
Subscribers will receive an integrated toolkit designed to accelerate deployment and reduce decision friction in 2026, including:
-
Interactive Excel market model with sensitivity levers for regulatory shock, cLOTO adoption rate, and regional procurement velocity.
-
Vendor scorecards and procurement RFP templates.
-
Implementation checklists, worker-training curricula, and compliance audit templates.
-
Playbooks for pilot-to-scale roadmaps, including KPIs to validate ROI and compliance outcomes.
How to use this preview — next steps for leaders
This preview is intended to be operationally provocative: it frames the strategic choices that will define winners and laggards in 2026. If your objectives are to reduce regulatory exposure, lower the cost of safety compliance, or capture growth in connected LOTO offerings, the full PW Consulting study contains the granular market splits, supplier-level financial proxies, and implementation templates you need to execute with confidence.
Engage with the full report if you need any of the following in Q1–Q3 2026:
-
A prioritized supplier shortlist and negotiated contract terms tailored to your asset base and maintenance cadence.
-
Region- and application-specific adoption roadmaps with capital timing aligned to your CAPEX cycle.
-
A bespoke pilot design and measurement framework to prove cLOTO benefits within 6–12 months.
PW Consulting’s full study is structured to convert market insight into executable plans. For access to the complete dataset, vendor-level intelligence, and the downloadable decision toolkit, please visit our report page or contact our industry practice lead to arrange a tailored briefing.
— PW Consulting, Strategy & Industry Insights
For detailed analysis of this topic, please visit the official page: Lockout Tagout Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Indene Market to Reach USD 283M by 2032 at 5.2% CAGR (2026-2032)
By pmarketresearch, 2026-07-30
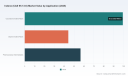
Indene (CAS 95-13-6) Market Outlook — Strategic Brief for 2026 Decisions
PW Consulting’s Indene Market primer frames why 2026 is a pivotal planning year for buyers, producers and investors in this niche aromatic intermediate. Drawing on a detailed base-year snapshot (2025), five-year historical context and a 2026–2032 forecast, this introduction highlights the structural drivers that will shape commercial outcomes and the tactical choices that senior leaders must make to capture upside or mitigate downside risk. The material below demonstrates our analytical depth while deliberately withholding granular segment and regional breakdowns that are available in the full report.
Indene (CAS 95-13-6) Market
Executive snapshot — market scale, pace and structure
The global Indene market (base year 2025) has shown steady recovery and re‑rating since 2020. Key macro markers: PW Consulting’s topline series places the market at USD 135.0 Million in 2020, expanding to USD 200.0 Million by the 2025 base year, and we project it to reach approximately USD 283.0 Million by 2032. Our modeled trajectory for the forecast window implies a compound annual growth rate (CAGR) of roughly 5.2% (2026–2032), reflecting both product maturation in specialty resins and continued feedstock-linked demand from chemical intermediates.
Indene (CAS 95-13-6) Market
Market structure is neither hyper‑consolidated nor atomized. Concentration metrics indicate meaningful scale players alongside a broad set of regional and specialty suppliers — the top three firms account for a quarter of market share while the top five command roughly two‑fifths. That balance creates space for differentiated plays (purity, service, vertical integration) while leaving tactical opportunities for M&A and capacity rationalization.
Indene (CAS 95-13-6) Market
Why 2026 matters — the strategic value of timely intelligence
- Feedstock volatility is a strategic lever. Indene is principally produced from coal tar C9 fractions and its commercial economics are tightly coupled to the availability and refining of coal‑tar‑derived streams. Buyers that lock multi‑year sourcing and producers that secure feedstock integration are positioned to smooth margin volatility.
- Purity premiums and product segmentation. High‑purity grades command meaningful pricing differentials versus technical grades — a dynamic that rewards investments in fractionation and vacuum/extractive distillation. Understanding where to compete on price versus specification is central to 2026 commercial planning.
- Regulatory inflection points affect capex and operations. Indene is classed as a flammable liquid (UN 1993) and is subject to stringent handling and occupational exposure expectations under major regimes. Emerging occupational exposure guidance and evolving regional regulations will drive compliance investments and may alter the cost curve for smaller producers.
- Demand bifurcation creates strategic choices. End‑uses span resins and adhesives to pharmaceutical intermediates and research supply. Each route-to-market implies different buyer relationships, service models and margin profiles — choosing focus areas today determines the next three to five years of revenue mix.
Market dynamics and operational implications
Several dynamics stand out as actionable for 2026 planning:
- Upstream integration and feedstock security. Producers with access to integrated coal tar distillation or refineries are advantaged on cost and continuity. For procurement teams, multi‑tiered supplier strategies and feedstock‑linked contracts will reduce supply disruption risk.
- Quality and certification as commercial differentiators. High‑purity Indene for functional materials and pharmaceutical intermediates is an escalating focus area. Investments in validated production processes, GMP pathways and certified analytics can unlock premium segments.
- Regulatory compliance and occupational safety. Closed‑system handling, updated occupational exposure guidance and transport classification are non‑negotiable. Capital planning should include containment, monitoring and training to meet both local and export market requirements.
- Price architecture and premium capture. Given persistent purity‑driven price differentials, pricing strategies must be tied to measurable specifications and supported by traceable analytics to sustain premiums without eroding volume.
Competitive landscape — what the leading players tell us
The Indene value chain combines global diversified chemicals houses, specialty resin makers, and regional producers focused on volume and local demand. Strategic positioning falls into three archetypes: global integrated suppliers, specialty high‑purity vendors, and resin/derivative producers with downstream capture.
- Global integrated suppliers: Incumbents with upstream access to coal tar fractions and broad downstream channels retain a cost and security edge. These firms can selectively invest in higher‑spec grades while optimizing overall plant throughput.
- Specialty and high‑purity vendors: Companies focused on research, pharma intermediates and certified products have a route to higher margins through service and quality. Their go‑to‑market depends on tight regulatory compliance and responsive custom synthesis capabilities.
- Resin and derivative manufacturers: Producers that convert Indene into coumarone‑indene or styrene‑indene resins integrate downstream value and reduce exposure to commodity swings, but their returns hinge on resin cyclicality.
Representative industry players underscore these archetypes: large integrated chemical firms that have signaled expansion into high‑purity derivatives; specialty suppliers that emphasize custom synthesis and GMP readiness for pharmaceuticals; and resin producers that leverage Indene as a core feedstock for adhesive and coating portfolios. Recent corporate moves — product updates highlighting high‑purity grades and catalog additions emphasizing GMP and custom services — reinforce a competitive tilt toward specification and service rather than purely commodity pricing.
Risks, uncertainties and monitoring framework
Key risks to monitor through 2026 include feedstock supply interruptions, tightening occupational exposure recommendations, transport or labeling shifts that increase handling costs, and resin market cyclicality that can compress downstream demand. PW Consulting recommends a concise monitoring dashboard for executive teams that includes:
- Feedstock availability and pricing indicators (monthly)
- Regulatory changes in principal markets and ACGIH/OSHA/REACH updates (quarterly)
- High‑purity order volumes and lead times (monthly)
- Competitor capacity announcements and product launches (real‑time alerts)
- Downstream resin demand indices and end‑market sentiment (quarterly)
What the full PW Consulting Indene report delivers
Our full market study is structured to convert insight into executable plans. Highlights include:
- Comprehensive market sizing and validated topline series (2020–2025 historical; 2026–2032 forecast) with scenario variants for demand and feedstock shocks.
- Supplier matrix and commercial scoring (capability, capacity, quality certification, geographic reach) to support sourcing and partnership decisions.
- Pricing model calibrated to purity bands, feedstock spreads and distillation economics, enabling margin stress‑testing under multiple scenarios.
- Regulatory compliance playbook and capital checklist for safe handling, transport and occupational exposure management across key jurisdictions.
- Segment level strategies (resins, pharmaceutical intermediates, research/reagent supply) with go‑to‑market guidance, channel strategies and expected margin profiles. Note: the detailed segment shares and regional breakdowns are intentionally withheld in this primer to preserve the full‑report value for subscribers.
- M&A and investment briefs identifying adjacencies, bolt‑on acquisition targets and integration risk matrices.
- Operational playbooks covering quality control, analytics, and certification paths for high‑purity production lines.
Practical recommendations for 2026 execution
- Buyers: Prioritize dual‑sourcing agreements with at least one high‑purity certified supplier and one integrated feedstock provider. Include capacity reservation clauses for cyclical resin demand windows.
- Producers: Decide whether to invest in purity‑upgrading capacity or pursue vertical integration into resins; both paths are viable but require different capital and commercial commitments.
- Investors: Focus due diligence on firms with secure feedstock access, validated high‑purity processes, and exposure to diversified downstream markets to reduce single‑market cyclicality.
- Regulatory/compliance leads: Accelerate occupational exposure monitoring programs and ensure transport labeling and containment systems meet evolving international expectations.
Closing — how to use this intelligence
For executives planning 2026 strategies, PW Consulting’s Indene study is built to convert market visibility into defined actions: procurement hedges, targeted capex, M&A screening, and regulatory roadmaps. This primer outlines the strategic contours and operational levers; our full report supplies the granular segmentation, supplier scores and numeric scenarios needed to finalize negotiations, budgets and investment commitments.
Access the full Indene (CAS 95‑13‑6) Market report on PW Consulting’s report page to obtain the complete segment tables, regional breakdowns, supplier profiles and downloadable modeling tools. The data‑rich package is designed to underpin board presentations, vendor negotiations and capital approval packages in 2026.
For detailed analysis of this topic, please visit the official page: Indene (CAS 95-13-6) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vinyl Ester Resins to reach USD 1,757.1M by 2032 at 5.27% CAGR — PW Consulting
By pmarketresearch, 2026-07-30
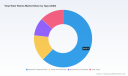
Vinyl Ester Resins Market: Strategic Imperatives for 2026 Decision-Making
As companies prepare budgets, allocate capital, and reset product roadmaps for 2026, the vinyl ester resins market presents a blend of steady growth, episodic commodity pressure, and intensifying strategic differentiation. Our proprietary market model places the industry at approximately USD 1.23 billion in 2025 and projects it to reach about USD 1.76 billion by 2032, implying a compound annual growth rate of roughly 5.27% over the forecast horizon. Those headline figures mask important inflection points that will materially affect procurement, R&D prioritization, and M&A decisions in the year ahead.
Vinyl Ester Resins Market
Market trajectory and short-term dynamics
From 2020 through 2025 the vinyl ester market expanded consistently despite volatile input-cost cycles and uneven downstream demand. That resilience reflects the polymer’s unique position—bridging epoxy-class performance and polyester-style processing—making it the material of choice where corrosion resistance, chemical durability, and composite processing flexibility collide.
Vinyl Ester Resins Market
- Input-cost volatility: The industry experienced sharp feedstock price shocks in 2024 driven by spikes in styrene and epoxide monomers; manufacturers implemented list-price increases in response. By late 2025 acrylic acid cost pressures eased, helping to moderate list prices and produce a Q4 softening in resin prices. Market commentators recorded U.S. spot resin prices at roughly USD 4,500/MT in December 2025 before the year-end easing.
- Demand unevenness: End-use markets—ranging from marine and corrosion-protection systems to wind-energy components—continue to be the primary demand engines, but order patterns are sensitive to capex cycles and regional infrastructure programs.
- Concentration and competition: The market exhibits moderate concentration (CR3 ~35%, CR5 ~45%), leaving room for scale players to defend share while specialty suppliers grow through product differentiation and geographic reach.
Structural drivers that will shape 2026 strategy
For executives planning next-year moves, five structural forces demand attention:
Vinyl Ester Resins Market
- End-market durability demands: Continued investment in corrosion mitigation (industrial piping, tanks, and chemical processing) and marine applications keeps performance resins in demand even when bulk composites slow.
- Energy transition opportunities and risks: Wind energy and offshore installations create specific resin requirements (fatigue, toughness, long-term durability). These are growth pathways but require tailored resin grades and validated supply chains.
- Raw-material and inflation risk: The feedstock cost pass-through dynamic remains active. Companies that refine sourcing strategies, develop strategic hedges, or invest in alternative chemistries will preserve margins.
- Sustainability and regulatory pressure: Rapid emergence of bio-derived and low-carbon content resin lines (e.g., new offerings with high biogenic carbon content) means sustainability credentials are moving from marketing nicety to procurement filter for large OEMs and fabricators.
- Regional manufacturing gravity: Asia-Pacific has become the dominant demand basin and supply hub for many resin producers—decisions on capacity, logistics, and local partnerships will determine commercial success in 2026.
Competitive landscape — what matters to buyers and investors
The competitive set combines multinational resin majors, regional formulators, and specialty players with differentiated go-to-market models. Leading companies include Polynt S.p.A., Resonac Holdings Corporation, RealLand Composite Material Technology, FGCI, Interplastic Corporation, Scott Bader, and several Chinese composite resin manufacturers that serve both domestic and export markets. Each brings distinct strengths:
- Scale and breadth: Large integrated resin producers leverage global manufacturing footprints and broad product portfolios to serve diverse end-markets and to manage feedstock shocks.
- Technical differentiation: Certain players compete on high-performance grades (e.g., epoxy-novolac chemistries, brominated fire-retardant types, or high-reactivity formulations) that command premium positioning in demanding applications.
- Channel and service models: Some suppliers emphasize formulation support and onsite technical services for fabricators and OEMs; others prioritize low-cost distribution to commodity applications.
- Regional champions: Local manufacturers, particularly in Asia, supply regionally optimized grades and can undercut importers on lead time and logistics—an important structural advantage for large downstream fabricators.
Recent industry developments reinforce these trends. In 2025, select players launched higher-reactivity epoxy-novolac vinyl ester grades aimed at elevated chemical resistance and faster cure cycles, and others introduced resin lines with a significant renewable/biogenic carbon content to address sustainability mandates. These product moves highlight two emergent playsheet items for 2026: technical premiumization and green credentials as sources of margin expansion.
What our PW Consulting vinyl ester report delivers
The full PW Consulting report is built to convert insight into action. It is structured around several operational modules that directly support 2026 decision-making:
- Macro-to-micro demand forecasts: Base-year and historical reconciliations, 2026–2032 scenario outputs, and sensitivity analyses under alternate macroeconomic and feedstock-cost assumptions.
- Price and margin modeling: Dynamic feedstock pass-through simulations, negotiated vs. spot pricing frameworks, and break-even cost curves by formula type.
- Competitive benchmarking: Capabilities maps, plant-level cost proxies, product overlap matrices, and playbooks for defending or expanding share in targeted geographies.
- Commercial playbooks: Customer segmentation, contract-design templates, distributor economics, and value-based pricing roadmaps tuned for marine, corrosion, and wind-energy customers.
- Technology and sustainability roadmaps: Assessment of bio-based and low-emission formulations, R&D priorities, and certification pathways that influence adoption cycles.
- M&A and investment screening: Target archetypes, valuation multipliers, integration risk checklists, and prioritized lists of acquisition candidates (with overlays by strategic fit).
- Raw-material and logistics risk matrix: Strategic sourcing options, hedging scenarios, and contingency plans for acute supply disruptions.
To honor the "trailer" principle: this article highlights the analytical scaffolding and strategic implications but intentionally omits granular split tables, country-level volumes, and individual product-line share data. Those proprietary deliverables—central to tactical procurement and M&A decisions—are included in the full report and its downloadable appendices.
Concrete recommendations for 2026
For C-suite and business-unit leaders setting 2026 priorities, we recommend a balanced program of short-term protection and medium-term capability building:
- Protect margins through diversified sourcing and pricing discipline: Implement dynamic contracts that allow for quicker feedstock cost pass-through while protecting key accounts with value-based offerings.
- Prioritize product tiers that match downstream value capture: Identify two or three premium grades where your technical support and testing services deliver measurable ROI to customers and shift sales mix toward those grades.
- Invest selectively in sustainability credentials: Fast-track certification and reporting for bio-content and lower-carbon products to secure long-term OEM relationships, especially in marine and infrastructure segments.
- Localize where logistic economics favor it: For companies targeting Asia-Pacific and other high-growth basins, prioritize satellite production or tolling agreements to shorten lead times and reduce landed cost exposure.
- Pursue bolt-on M&A to fill capability gaps: Look for targets that provide complementary chemistries, specialized formulations, or regional distribution that can be integrated with limited capital expenditure.
- Coordinate closely with composite fabricators and OEMs: Co-development partnerships that reduce qualification cycles can accelerate adoption of new resin grades and reduce customer switching costs.
- Run scenario-based capex plans: Use the report’s scenario outputs (base, upside, downside) to set phased capacity investments with clear go/no-go triggers tied to feedstock and end-market indicators.
Risks and the upside thesis
Key risks heading into 2026 include another round of raw-material price spikes, regulatory tightening on monomers and flame retardants, and potential substitution pressure from novel composite systems. Offsetting these risks is a credible upside path: technical premiumization (higher-spec grades for offshore wind and specialist corrosion protection), sustainability-driven specification changes, and improving OEM consolidation that favors suppliers who can guarantee long-term supply and validated performance.
How PW Consulting helps clients act
Our clients use this study to align procurement thresholds, prioritize product development investments, size acquisition targets, and craft commercial contracts with built-in feedstock-risk mechanics. The report combines market-level forecasts with actionable playbooks, templates, and a prioritized list of near-term actions that procurement, technical, and corporate development teams can implement within 90–180 days.
If you are evaluating capacity expansions, negotiating multi-year supply agreements, or considering acquisitions in the vinyl ester value chain for 2026, the full PW Consulting report provides the tables, regional and application splits, and company-level share data necessary to move from strategy to execution. Contact PW Consulting’s industry desk to access the complete report, underlying datasets, and bespoke advisory support keyed to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Vinyl Ester Resins Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com