

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Biomass Power Market Set for 5.3% CAGR (2026–2032)

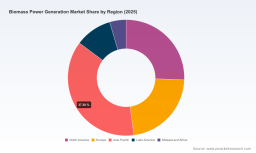
Biomass Power Generation Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As PW Consulting’s lead industry analyst, I present a strategic preview of our comprehensive Biomass Power Generation Market study — the operational intelligence that will inform go/no-go choices, M&A road maps, and policy engagement strategies in 2026. The global biomass power generation market, which grew from roughly USD 73.7 billion in 2020 to an estimated USD 92.3 billion in our 2025 base year, is forecast to expand at a compound annual growth rate (CAGR) of approximately 5.3% over the 2026–2032 forecast window, reaching an estimated USD 132.3 billion by 2032. These headline dynamics hide important inflection points for participants across the value chain: fuel suppliers, plant OEMs, utility operators, project financiers, and downstream offtakers.
Biomass Power Generation Market
Why this research matters in 2026
- Policy-driven capital flows. 2026 is a decisive year in many jurisdictions as subsidy frameworks, tax-credit regimes, and clean power procurement rules reach new maturity. Understanding how technology-neutral incentives and CfD-type arrangements interact with project economics can change project prioritization within months.
- Operational and supply-chain stressors. Raw material prices, logistics bottlenecks, and interconnection queues are not background noise — they shape near-term deliverability of capacity and the bidding behavior of incumbents and new entrants.
- Competitive repositioning. Leading names on the supply and developer side are rapidly consolidating capabilities (fuel supply, conversion technology, and grid-scale dispatch), creating tactical windows for partnerships and carve-outs. The market exhibits measurable concentration among larger players even as specialized technologies broaden the competitive set.
Market trajectory: what the macro numbers reveal
The market’s movement from about USD 73.7 billion in 2020 to an estimated USD 92.3 billion in 2025 underscores sustained demand for bio-based generation as part of broader decarbonization portfolios. At a ~5.3% CAGR through 2032, the sector is not a hyper-growth bubble but rather a resilient, capital-intensive market where scale, offtake security, and fuel strategy determine long-term returns. Year-on-year volatility in our projections—driven by commodity cycles, policy timing, and one-off project commissions—means that timing of investments and staged capital deployment are critical practical levers for 2026 decision-making.
Biomass Power Generation Market
Key dynamics shaping 2026 strategy
- Policy and incentives: Technology-neutral clean electricity credits and investment tax incentives that came into effect in several jurisdictions are reshaping project IRRs. However, eligibility conditions (e.g., prevailing wage, domestic content) require operational and contractual adjustments that, if unaddressed, erode anticipated benefit capture.
- Fuel-cost and feedstock security: Densified biomass pricing and new processing capacity materially affect long-term fuel contracts. Domestic fuel pricing benchmarks and new supply nodes (e.g., pellet processors, palm-kernel-shell plants) change procurement strategy from single-source long-term contracts to diversified portfolio sourcing.
- Grid and interconnection constraints: Interconnection queue backlogs and regional capacity limits create uncertainty around commissioning timelines — making staged or repurposable project designs (co-firing, modular gasification, hybridization with other renewables) more attractive to financiers.
- Technology and asset lifecycle: Mature combustion technologies dominate installed capacity, but emerging pathways (advanced gasification, anaerobic digestion integration, and co-processing with industrial sites) are becoming commercially relevant. Lifecycle cost, feedstock flexibility, and retrofitability determine which technologies win in specific applications.
- ESG and sustainability traceability: Increasing buyer and regulator scrutiny around feedstock origin, carbon accounting, and land-use impacts means that sustainable supply chain verification is no longer a nice-to-have — it is a gate for offtake and financing.
Competitive landscape — who matters and what they’re doing
The competitive map in 2026 is a mix of pure-play biomass operators, diversified utilities adding bioenergy to their portfolios, EPC and turbine OEMs, and vertically integrated industrial players. Market concentration is meaningful: the top three players control a notable share of installed capacity and pellet sourcing channels, while the top five further consolidate scale advantages in logistics and financing. This concentration has several implications:
Biomass Power Generation Market
- Scale enables better access to long-term fuel contracts and favorable financing;
- Incumbents can rapidly pivot portfolio exposure through acquisitions or asset swaps;
- Niche players can still capture value by specializing in feedstock types, regional execution expertise, or advanced conversion technologies.
Representative firms to watch in 2026 include Drax Group plc, ACCIONA Energía, Rayonier Advanced Materials, Mitsubishi Heavy Industries, Babcock & Wilcox, Engie SA, Vattenfall AB, Siemens Energy, GE Vernova, and Ørsted A/S. Collectively, these organizations demonstrate three strategic postures worth emulating or guarding against:
- Vertical integration and fuel control: Examples include large pellet production commitments to secure feedstock for fleet operations, enabling predictable dispatch economics and risk mitigation on fuel price volatility.
- Project-scale and turnkey delivery: OEMs and EPCs are offering bundled supply, operations, and long-term maintenance contracts to de-risk brownfield conversions and greenfield projects for utilities and industrial players.
- Innovation through partnerships: Cross-border and industrial joint ventures are accelerating the deployment of bioenergy at sites with existing steam or process-heat needs, creating synergies between power generation and industrial decarbonization.
Notable 2025–2026 developments and what they mean for 2026 action
- Drax’s record pellet production and transatlantic logistics milestones establish a template for scale-driven feedstock strategies; they also highlight the logistics-capex trade-offs new entrants must evaluate.
- ACCIONA Energía’s recent grid-connected 50 MW project illustrates continued appetite for mid-scale plants that can be integrated into regional renewable stacks and ancillary-services markets.
- Localized fuel-processing investments (e.g., palm-kernel-shell processing enablers) suggest the emergence of new regional supply hubs — an opportunity for offtake contracts and localized logistics plays.
- Policy signals — such as technology-neutral tax credits — increase optionality for investors, but the detail matters: wage and content requirements, inflation adjustments, and carbon accounting rules determine whether a project is bankable under modern project finance diligence.
What the PW Consulting report delivers — practical, transaction-ready intelligence
Our full study is built for decision-makers who need to act in 2026. It includes:
- Actionable investment frameworks that translate policy regimes and fuel-price scenarios into project-level IRR sensitivities and payback timelines;
- Due-diligence checklists tailored for developers, lenders, and technology vendors — covering feedstock procurement, sustainability verification, permitting, and grid interconnection risk allocation;
- Commercial playbooks for developers and feedstock providers that outline viable partnership structures, contract terms, and risk-sharing mechanisms (including sample term-sheet language and capex/O&M benchmarking);
- Technology decision matrices mapping plant scale, feedstock flexibility, lifecycle emissions, and retrofit potential to practical procurement choices;
- A competitor intelligence annex profiling strategy, asset portfolios, and recent moves of leading players — with scenario analysis on how these players could shape regional supply-demand balances;
- Stress-tested market forecasts across multiple macro scenarios so executives can model staged investment and exit options against alternative policy and commodity outcomes.
To preserve the strategic value of our research as a commercial product, we deliberately exclude granular segmentation tables and regional/application-specific dollar breakdowns from this preview. The full report provides those precise splits, enabling granular financial modeling and market-entry plans.
Implications and tactical recommendations for 2026
- Prioritize optionality in capital allocation. Given the moderate but steady growth trajectory, favor staged investments or modular technologies that allow capacity scaling aligned with offtake certainty and policy windows.
- Secure diversified feedstock portfolios. Locking in a mix of local and regional suppliers, and incorporating contingency clauses for price and quality variation, reduces fuel exposure and improves bankability.
- Engage early with regulators and grid operators. Interconnection bottlenecks mean project timelines are frequently governed by systemic constraints rather than plant-level execution. Active advocacy and early technical coordination shorten time-to-market and preserve value.
- Explore strategic partnerships. For mid-sized developers, partnering with vertically integrated partners or large EPC players can bridge capability gaps in logistics, fuel procurement, and financing.
- Embed sustainability traceability into commercial terms. Anticipate lender and offtaker requirements for feedstock origin verification and lifecycle carbon accounting from project inception — a retrospective remedy is expensive and reputationally risky.
- Use policy windows to de-risk returns. Where available, align project timelines with predictable incentive schedules (e.g., tax credit qualification periods), while validating compliance with any prevailing wage or localization conditions.
How to use this preview
This preview is intended to surface the critical strategic questions and near-term levers that will define success in 2026. If you are evaluating capacity additions, M&A targets, financing structures, or supply-chain repositioning, the full PW Consulting Biomass Power Generation Market report contains the granular market sizing, regional and feedstock splits, and financial templates necessary to convert strategy into executable plans.
Next steps
- Request the full report for transaction-ready detail: segmented market tables, technology-specific unit economics, and competitor asset-level data; these are essential for term-sheet drafting, bid pricing, and portfolio stress testing.
- Schedule a tailored briefing with our senior consultants to map findings to your portfolio and craft a 6–12 month playbook that aligns with expected 2026 policy and capital markets timelines.
PW Consulting’s Biomass Power Generation Market study synthesizes market-scale forecasting (with a 2025 base of ~USD 92.3 billion and a forecast path to ~USD 132.3 billion by 2032 at ~5.3% CAGR), operational intelligence, and competitor insight — delivering what decision-makers need to move from strategy to transaction in 2026. For the comprehensive datasets and executable templates that underlie these conclusions, please consult the full report.
For detailed analysis of this topic, please visit the official page: Biomass Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com