

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Helium Gas Market to Reach USD 344.8M by 2032 at 6.98% CAGR — PW Consulting Insight

Helium Gas Market Outlook 2026: Strategic Imperatives for Navigating a Volatile Supply Era
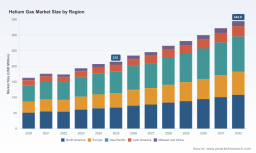
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused briefing that translates our latest Helium Gas Market study into the concrete decisions executives must face in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the study models a market expanding from roughly USD 215 million in 2025 to about USD 345 million by 2032 at a compound annual growth rate of approximately 6.98%. Those headline metrics frame a market whose growth is real and durable—but whose near-term shape is being remade by geopolitics, new supply entrants, and accelerating technology requirements.
Helium Gas Market
Why this research matters for 2026 decision-makers
-
Immediate supply shock and reconfiguration: The industry experienced a material supply disruption in early 2026. The loss of a major production hub removed a substantial share of global supply, producing acute spot-market volatility and squeezing inventories across industrial and strategic users. This shock exposed structural vulnerabilities in procurement strategies and storage infrastructure.
Helium Gas Market -
Rapid emergence of new domestic capacity and storage options: Counterbalancing the shock, a number of new projects and storage assets came online or advanced through regulatory and commercial milestones in 2025–2026, particularly in North America. These developments shorten paths to recovery but do not immediately erase regional mismatches and logistics constraints.
Helium Gas Market -
Demand-side acceleration in high-value end uses: Cryogenics, advanced electronics manufacturing, and medical applications continue to underpin a structural demand tailwind. At the same time, higher purity specifications and new delivery modalities are changing the economics of supply and creating premium tiers that require differentiated commercial approaches.
What the full report delivers (practical, operational outputs)
-
Forward-looking supply-demand models: A transparent, scenario-driven engine that projects volumes, storage drawdown/rebuild timelines, and price trajectories across a range of disruption and policy outcomes. These models are built to be used as board- and transaction-ready appendices.
-
Commercial playbooks: Negotiation templates for multi-year offtakes, indexation structures, inventory pooling agreements, and force majeure clauses designed to protect both buyers and sellers in volatile cycles.
-
Supplier scorecards and procurement risk maps: Qualitative and quantitative assessments of upstream producers, liquefiers, and distributors—covering technical capability, contractual flexibility, geopolitical exposure, and delivery reliability.
-
Project-level investment toolkits: Standardized NPV templates, capex/opex benchmarks, liquefaction sizing guidelines, and break-even sensitivity analyses for greenfield and brownfield helium projects.
-
Regulatory and storage strategy playbook: An operational guide for engaging with regulators, structuring storage incentives, and deploying cavern or cryogenic inventory solutions to stabilize supply for critical users.
-
Actionable risk-heatmaps and early-warning indicators: A compact set of trigger metrics—geopolitical exposure, spare liquefaction capacity, cavern inventory days, and purity premium trends—designed to translate market signals into commercial actions within quarterly board cycles.
Note: This briefing presents our strategic synthesis. The full report contains granular segment-level tables, regional and application splits, and downloadable financial models that are intentionally withheld from this preview to preserve the report’s proprietary value.
Competitive landscape — positioning and strategic moves
-
Incumbent integrated gas majors retain structural advantages. Companies with integrated upstream access, large-scale liquefaction capability, and established distribution networks hold pricing leverage during tight markets because they can allocate volumes to higher-value applications and optimize logistics across regions.
-
Product innovation is a differentiator. Recent launches of ultra-high-purity product lines and improved liquid helium delivery systems underscore that manufacturers who can combine technical specifications with delivery efficiency capture premium segments and sticky contracts.
-
Independent producers and explorers are high-opportunity targets. Junior and mid-sized operators that can deliver de-risked volumes with offtake security become attractive partners for co-investment or acquisition as incumbents seek to diversify feedstocks and shorten lead times.
-
Market concentration remains relatively low. The industry is still fragmented, with top players collectively holding modest shares relative to other industrial gases—this fragmentation creates fertile ground for strategic consolidation, especially among companies that can add liquefaction, storage, or logistics capabilities.
Our company-by-company analysis in the full report dissects balance-sheet strength, contract footprints, recent product and project announcements, and operational risk. Public developments through mid‑2026—anything from force majeure declarations to high-purity product introductions and long-term offtake deals—are factored into supplier risk rankings and acquisition screens.
Scenario planning: three pathways every executive must stress-test
-
Short-term shock and constrained recovery (most relevant early–mid 2026): Severe regional shortages and elevated spot premiums compel buyers to deploy contingency inventories, renegotiate indexation clauses, and prioritize critical processes. Sellers that can re-route limited volumes to the most lucrative applications outperform peers.
-
Normalization through new capacity (base case over 2027–2030): New production wells, liquefaction trains, and storage caverns progressively restore global availability. The pace of commercialization and logistics ramp determines whether price normalization will be gradual or abrupt.
-
Structural tightness driven by demand step‑up (tail risk to 2032): If long-term demand from advanced electronics and cryogenic applications accelerates beyond current project additions, persistent premiums and incentivized investment will keep returns strong for marginal producers.
Each scenario in our model is accompanied by decision triggers and tactical timelines that tell procurement teams when to shift from spot to committed cover, when to mobilize co-investment offers, and when to accelerate substitution or recycling programs.
Six priority actions for executives in 2026
-
Lock flexible multi-year access: Secure a mix of indexed and fixed-price offtakes that balance cost certainty and supply flexibility. Include rights to volume take-or-pay adjustments tied to force majeure and logistical disruptions.
-
Invest in storage and on-site buffering: Where feasible, expand cavern or cryogenic storage holdings to create operational resilience for mission‑critical processes.
-
Pursue strategic co-investments with explorers and midstream developers: De-risk new supply by offering staged capital in return for prioritized delivery windows or equity-linked pricing.
-
Accelerate purity and delivery innovations: For buyers in electronics and research sectors, demand contracts that guarantee purity tiers and optimized delivery modalities to reduce boil‑off and handling losses.
-
Deploy a supplier diversification playbook: Avoid single-supplier dependency by combining national producers, regional distributors, and international trading partners.
-
Institutionalize scenario-driven procurement: Use the report’s scenario engine and early-warning indicators to convert market signals into procurement actions on a 90–180 day cadence.
Closing: translating insight into competitive action
In the volatile environment of 2026, helium is no longer a fungible commodity that can be purchased on short notice without strategic consequence. The market’s near-term turbulence—driven by significant supply disruptions and matched by a pipeline of new projects and storage assets—creates a decisive window for corporate action. Firms that combine disciplined procurement, targeted capital deployment, and smart partnerships will convert current market stress into long-term competitive advantage.
PW Consulting’s full Helium Gas Market report provides the granular, actionable elements your team needs: detailed segment forecasts, supplier scorecards, contract templates, and downloadable financial models. For executives preparing budgets, negotiating offtakes, or assessing M&A in 2026, the full analysis turns headline trends into executable strategy. Contact our advisory team to access the proprietary datasets and scenario models referenced in this briefing.
For detailed analysis of this topic, please visit the official page: Helium Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com