

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Indene Market to Reach USD 283M by 2032 at 5.2% CAGR (2026-2032)

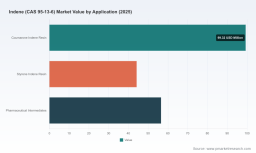
Indene (CAS 95-13-6) Market Outlook — Strategic Brief for 2026 Decisions
PW Consulting’s Indene Market primer frames why 2026 is a pivotal planning year for buyers, producers and investors in this niche aromatic intermediate. Drawing on a detailed base-year snapshot (2025), five-year historical context and a 2026–2032 forecast, this introduction highlights the structural drivers that will shape commercial outcomes and the tactical choices that senior leaders must make to capture upside or mitigate downside risk. The material below demonstrates our analytical depth while deliberately withholding granular segment and regional breakdowns that are available in the full report.
Indene (CAS 95-13-6) Market
Executive snapshot — market scale, pace and structure
The global Indene market (base year 2025) has shown steady recovery and re‑rating since 2020. Key macro markers: PW Consulting’s topline series places the market at USD 135.0 Million in 2020, expanding to USD 200.0 Million by the 2025 base year, and we project it to reach approximately USD 283.0 Million by 2032. Our modeled trajectory for the forecast window implies a compound annual growth rate (CAGR) of roughly 5.2% (2026–2032), reflecting both product maturation in specialty resins and continued feedstock-linked demand from chemical intermediates.
Indene (CAS 95-13-6) Market
Market structure is neither hyper‑consolidated nor atomized. Concentration metrics indicate meaningful scale players alongside a broad set of regional and specialty suppliers — the top three firms account for a quarter of market share while the top five command roughly two‑fifths. That balance creates space for differentiated plays (purity, service, vertical integration) while leaving tactical opportunities for M&A and capacity rationalization.
Indene (CAS 95-13-6) Market
Why 2026 matters — the strategic value of timely intelligence
- Feedstock volatility is a strategic lever. Indene is principally produced from coal tar C9 fractions and its commercial economics are tightly coupled to the availability and refining of coal‑tar‑derived streams. Buyers that lock multi‑year sourcing and producers that secure feedstock integration are positioned to smooth margin volatility.
- Purity premiums and product segmentation. High‑purity grades command meaningful pricing differentials versus technical grades — a dynamic that rewards investments in fractionation and vacuum/extractive distillation. Understanding where to compete on price versus specification is central to 2026 commercial planning.
- Regulatory inflection points affect capex and operations. Indene is classed as a flammable liquid (UN 1993) and is subject to stringent handling and occupational exposure expectations under major regimes. Emerging occupational exposure guidance and evolving regional regulations will drive compliance investments and may alter the cost curve for smaller producers.
- Demand bifurcation creates strategic choices. End‑uses span resins and adhesives to pharmaceutical intermediates and research supply. Each route-to-market implies different buyer relationships, service models and margin profiles — choosing focus areas today determines the next three to five years of revenue mix.
Market dynamics and operational implications
Several dynamics stand out as actionable for 2026 planning:
- Upstream integration and feedstock security. Producers with access to integrated coal tar distillation or refineries are advantaged on cost and continuity. For procurement teams, multi‑tiered supplier strategies and feedstock‑linked contracts will reduce supply disruption risk.
- Quality and certification as commercial differentiators. High‑purity Indene for functional materials and pharmaceutical intermediates is an escalating focus area. Investments in validated production processes, GMP pathways and certified analytics can unlock premium segments.
- Regulatory compliance and occupational safety. Closed‑system handling, updated occupational exposure guidance and transport classification are non‑negotiable. Capital planning should include containment, monitoring and training to meet both local and export market requirements.
- Price architecture and premium capture. Given persistent purity‑driven price differentials, pricing strategies must be tied to measurable specifications and supported by traceable analytics to sustain premiums without eroding volume.
Competitive landscape — what the leading players tell us
The Indene value chain combines global diversified chemicals houses, specialty resin makers, and regional producers focused on volume and local demand. Strategic positioning falls into three archetypes: global integrated suppliers, specialty high‑purity vendors, and resin/derivative producers with downstream capture.
- Global integrated suppliers: Incumbents with upstream access to coal tar fractions and broad downstream channels retain a cost and security edge. These firms can selectively invest in higher‑spec grades while optimizing overall plant throughput.
- Specialty and high‑purity vendors: Companies focused on research, pharma intermediates and certified products have a route to higher margins through service and quality. Their go‑to‑market depends on tight regulatory compliance and responsive custom synthesis capabilities.
- Resin and derivative manufacturers: Producers that convert Indene into coumarone‑indene or styrene‑indene resins integrate downstream value and reduce exposure to commodity swings, but their returns hinge on resin cyclicality.
Representative industry players underscore these archetypes: large integrated chemical firms that have signaled expansion into high‑purity derivatives; specialty suppliers that emphasize custom synthesis and GMP readiness for pharmaceuticals; and resin producers that leverage Indene as a core feedstock for adhesive and coating portfolios. Recent corporate moves — product updates highlighting high‑purity grades and catalog additions emphasizing GMP and custom services — reinforce a competitive tilt toward specification and service rather than purely commodity pricing.
Risks, uncertainties and monitoring framework
Key risks to monitor through 2026 include feedstock supply interruptions, tightening occupational exposure recommendations, transport or labeling shifts that increase handling costs, and resin market cyclicality that can compress downstream demand. PW Consulting recommends a concise monitoring dashboard for executive teams that includes:
- Feedstock availability and pricing indicators (monthly)
- Regulatory changes in principal markets and ACGIH/OSHA/REACH updates (quarterly)
- High‑purity order volumes and lead times (monthly)
- Competitor capacity announcements and product launches (real‑time alerts)
- Downstream resin demand indices and end‑market sentiment (quarterly)
What the full PW Consulting Indene report delivers
Our full market study is structured to convert insight into executable plans. Highlights include:
- Comprehensive market sizing and validated topline series (2020–2025 historical; 2026–2032 forecast) with scenario variants for demand and feedstock shocks.
- Supplier matrix and commercial scoring (capability, capacity, quality certification, geographic reach) to support sourcing and partnership decisions.
- Pricing model calibrated to purity bands, feedstock spreads and distillation economics, enabling margin stress‑testing under multiple scenarios.
- Regulatory compliance playbook and capital checklist for safe handling, transport and occupational exposure management across key jurisdictions.
- Segment level strategies (resins, pharmaceutical intermediates, research/reagent supply) with go‑to‑market guidance, channel strategies and expected margin profiles. Note: the detailed segment shares and regional breakdowns are intentionally withheld in this primer to preserve the full‑report value for subscribers.
- M&A and investment briefs identifying adjacencies, bolt‑on acquisition targets and integration risk matrices.
- Operational playbooks covering quality control, analytics, and certification paths for high‑purity production lines.
Practical recommendations for 2026 execution
- Buyers: Prioritize dual‑sourcing agreements with at least one high‑purity certified supplier and one integrated feedstock provider. Include capacity reservation clauses for cyclical resin demand windows.
- Producers: Decide whether to invest in purity‑upgrading capacity or pursue vertical integration into resins; both paths are viable but require different capital and commercial commitments.
- Investors: Focus due diligence on firms with secure feedstock access, validated high‑purity processes, and exposure to diversified downstream markets to reduce single‑market cyclicality.
- Regulatory/compliance leads: Accelerate occupational exposure monitoring programs and ensure transport labeling and containment systems meet evolving international expectations.
Closing — how to use this intelligence
For executives planning 2026 strategies, PW Consulting’s Indene study is built to convert market visibility into defined actions: procurement hedges, targeted capex, M&A screening, and regulatory roadmaps. This primer outlines the strategic contours and operational levers; our full report supplies the granular segmentation, supplier scores and numeric scenarios needed to finalize negotiations, budgets and investment commitments.
Access the full Indene (CAS 95‑13‑6) Market report on PW Consulting’s report page to obtain the complete segment tables, regional breakdowns, supplier profiles and downloadable modeling tools. The data‑rich package is designed to underpin board presentations, vendor negotiations and capital approval packages in 2026.
For detailed analysis of this topic, please visit the official page: Indene (CAS 95-13-6) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com