

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Metakaolin Market to Reach USD 994M by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-30
Metakaolin Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
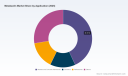
As PW Consulting’s senior industry analyst, I present a forward-looking briefing that distills the strategic implications of our full Metakaolin Market study for decisions to be made in 2026. The global metakaolin market has demonstrated steady expansion, rising from a baseline near USD 500 Million in 2020 to approximately USD 700 Million in our 2025 base-year estimate, and is forecast to grow through our 2026–2032 horizon to just under USD 1.0 Billion by 2032 at a compound annual growth rate (CAGR) of 5.2%. These headline metrics encapsulate both an enlarging addressable market and a durable adoption trend tied to infrastructure build programs and low‑carbon construction mandates.
Metakaolin Market
Why this matters for 2026 strategy
-
Portfolio positioning: Metakaolin is no longer a niche cement additive — it is becoming a specified material for durability and carbon reduction in major infrastructure projects. Firms that lock in the right product types and quality ranges in 2026 will secure premium specification slots through the decade.
Metakaolin Market -
Supply security: Production depends on high‑purity kaolin feedstock and energy‑intensive calcining; long‑lead investments in feedstock offtake, kiln capacity, or vertical integration materially shift cost curves and competitive posture.
Metakaolin Market -
Pricing discipline: Unit prices and plant economics are sensitive to energy and kiln utilization. Market signals in early 2025 showed US pricing near the high‑hundreds per metric ton range; buyers and sellers must bake energy volatility into multi‑year contracts.
-
Regulatory and specification advantage: Meeting ASTM C-618 / AASHTO M295‑11 Class N and demonstrating life‑cycle CO2 reduction creates differentiation in public procurement and sustainability‑led tenders.
-
M&A and partnership timing: The market’s relatively low top‑concentration (CR3 roughly mid‑20s percent) indicates fragmentation — a window where focused consolidation and vertical plays can unlock synergies and market share.
Market dynamics — what is driving the growth
The structural growth thesis rests on three pillars. First, infrastructure pipelines and sustainable construction policies are driving increased specification of supplementary cementitious materials that lower clinker intensity. Second, technical advances in high‑reactivity metakaolin production and consistent quality control make substitution more reliable for designers and contractors. Third, supply‑side moves — new calcining capacity, offtake agreements for kaolin feedstock, and targeted commercial launches — are reducing perceived scarcity, though cost differentials versus competing SCMs (fly ash, slag) remain material due to higher calcining costs.
Operationally, metakaolin production requires calcining kaolin at 650–750°C, which implies higher energy and operating costs compared with unprocessed SCMs; industry analyses indicate calcining‑driven production costs are materially above alternative SCMs. That cost premium, together with regional energy regimes and kiln efficiencies, shapes where producers opt to place new capacity and how they structure pricing and contractual terms with downstream customers.
What our full report delivers (practical, transaction‑ready content)
-
Granular market model (2020–2032) with scenario‑based demand drivers and an interactive forecast engine — note: this preview omits detailed segment tables reserved for subscribers.
-
Supply‑side mapping: mine-to-kiln network maps, capacity utilization curves, and a cost‑of‑production ladder that isolates energy, labor, and feedstock contributions to unit economics.
-
Price and contract playbook: calibrated price decks, benchmarking vs. fly ash/slag, and recommended contract clauses for energy pass‑throughs, force majeure, and quality variance.
-
Commercial go‑to‑market strategies: target client profiles, specification pathways (ASTM/AASHTO compliance), formulation trials playbook, and tendering templates for infrastructure procurement teams.
-
M&A & investment diligence toolkit: valuation comparables, integration checklists (feedstock, calcining assets, logistics), and a 100‑point ESG & permitting scorecard.
-
Case studies and pilot KPI templates: successful low‑carbon concrete projects and the laboratory‑to‑field scale up steps that minimize performance risk.
Competitive landscape and strategic moves to monitor
The competitive map is characterized by a mix of global mineral majors, regional specialists, and innovative challengers. Market concentration remains modest (CR3 approximately 24.6%, CR5 approximately 26.2%), which favors targeted consolidation and niche leadership rather than dominance by a handful of actors.
-
Imerys S.A. (France) — A global minerals player with branded metakaolin lines tailored to concrete and lime mortar systems. Imerys’ strength lies in integrated mineral handling and worldwide commercial channels that accelerate specification adoption in multinational projects.
-
Advanced Cement Technologies, LLC (USA) — Marketed PowerPozz™ emphasizes high reactivity, positioning the company for performance‑led segments such as high‑strength and pre‑cast concrete.
-
R‑E‑D Industrial Products (USA) — Offers Dynapoz under ASTM/AASHTO compliance claims; their emphasis on standards certification reduces adoption friction among engineering houses.
-
Burgess Pigment Company (USA) and Thiele Kaolin Company (USA) — Notably, Burgess’ announced acquisition of Thiele (March 2026) creates a vertically integrated specialty minerals platform with broadened metakaolin and kaolin portfolios, enhancing capture of both industrial and packaging applications.
-
SCR‑Sibelco N.V. (Belgium) — Focuses on high‑purity metakaolin for construction and industrial uses, leveraging large minerals distribution reach.
-
PORAVER GmbH (Germany) — Offers expanded glass alternatives that compete as lightweight, durable fillers — an innovation vector that buyers evaluate alongside metakaolin for specific use cases.
-
KaMin, Green360, Zeotech and others — Regional specialists and innovators: Green360’s commercial calcining run in 2025 and Zeotech’s large raw kaolin offtake agreement underscore a trend toward securing feedstock and scaling low‑carbon, high‑reactivity offerings.
Recent developments to watch: Burgess’ strategic acquisition (March 2026) signals consolidation and verticalization; Green360’s production ramp (mid‑2025) demonstrates rapid commercialization of sustainable supply; Zeotech’s multi‑year offtake (2025) emphasizes the importance of raw material contracts; and industry trade shows continue driving specification awareness.
Risk factors and mitigants for 2026 planners
-
Energy price volatility: Hedging strategies, fuel‑efficient kiln investments, and location choices tied to low‑cost energy can materially improve margins.
-
Feedstock concentration: Pursue diversified sourcing, DSOs (direct shipping ore agreements), and captive reserves where WACC and permitting permit.
-
Substitution and competition: Maintain product differentiation (e.g., high‑reactivity grades, certified performance) and monitor alternative materials such as expanded glass and geopolymers.
-
Regulatory shifts: Align product claims with ASTM/AASHTO and emerging sustainability reporting standards to avoid specification disqualification.
Recommended 2026 action plan (practical next steps)
-
Immediate (0–6 months): Initiate engineering trials with target concrete formulators; secure short‑term offtake pilots; model P&L sensitivity to energy and kiln utilization.
-
Medium (6–18 months): Negotiate medium‑term feedstock contracts or strategic minority investments into kaolin suppliers; evaluate brownfield upgrades to existing calcining assets to lower unit costs.
-
Strategic (18–36 months): Consider M&A targets that provide either proprietary high‑reactivity processing technology or logistics advantages; deploy commercial teams into prioritized infrastructure corridors where low‑carbon mandates drive specification.
How PW Consulting’s full study supports your 2026 decisions
This preview is purposefully calibrated to demonstrate analytical rigor while preserving detailed segment matrices, company financials, regional and application splits, and interactive dashboards for subscribers. The full study provides the executable artifacts you need to operationalize the strategic lines above: downloadable scenario models, procurement contract templates, an M&A valuation pack, and supplier due‑diligence worksheets tailored to metakaolin’s unique production chain.
For firms preparing capital allocation, procurement, or M&A moves in 2026, the combination of a near‑term procurement playbook and a medium‑term capacity and feedstock strategy represents the highest value. Our work highlights where to deploy capital, how to structure offtakes and partnerships, and which technical differentiators (reactivity, fineness control, certification) translate to commercial premiums.
Next steps
-
Download the full PW Consulting Metakaolin Market report to access the confidential segment tables, regional / application breakdowns, and the interactive forecast model.
-
Engage our advisory team for a tailored 6–12 month implementation roadmap that aligns procurement, R&D, and commercial channels with your capital plan.
In 2026, decisions made around feedstock security, calcining capability, and product specification will determine who captures the disproportionate upside from a market that is growing steadily but remains technically and operationally demanding. PW Consulting’s full report arms you with the granular, transaction‑ready intelligence to act decisively — contact us to access the detailed segment intelligence and proprietary playbooks referenced here.
For detailed analysis of this topic, please visit the official page: Metakaolin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Balanced-armature Magnetic Speakers Market to Reach USD 60.77M by 2032 at 1.5% CAGR
By pmarketresearch, 2026-07-30
Balanced-armature Magnetic Speakers Market: Strategic Outlook for 2026 Decision-Making
As organizations plan their 2026 product roadmaps, sourcing strategies, and M&A tests-of-reality, a granular understanding of the balanced-armature magnetic speakers market is no longer optional — it is strategic. PW Consulting’s latest market study (base year 2025, historical window 2020–2025, forecast 2026–2032) distills performance trends, supplier dynamics, and risk vectors that will materially affect supplier selection, product architecture choices, and investment prioritization in the year ahead.
Balanced-armature Magnetic Speakers Market
Why this market matters in 2026
Balanced-armature drivers remain a critical enabler across several high-value audio end-markets — from premium true wireless stereo (TWS) earbuds and in-ear monitors (IEMs) to hearing aids and certain pro-audio devices. The market has demonstrated modest yet persistent resilience through a period of product transitions and geopolitical stress. Our sizing places the market at roughly mid‑50s (USD Million) in 2025 and projects a long-term, stable trajectory underpinned by a conservative compound annual growth rate (CAGR) of around 1.5% through 2032. That profile — slow growth with periodic volatility — creates a distinct decision environment in which optimization of supplier relationships and technology choices delivers outsized returns.
Balanced-armature Magnetic Speakers Market
What the 2026 strategic horizon looks like
-
Product differentiation will increasingly hinge on subsystem-level innovation. Multi-way and hybrid driver configurations, integrated crossovers, and micro-acoustic tuning are transitioning from "nice-to-have" to commercially important differentiators for premium devices. Manufacturers that lock in access to advanced micro-driver platforms can accelerate time-to-market for premium TWS and IEM SKUs.
Balanced-armature Magnetic Speakers Market -
Supply concentration amplifies supplier risk. The market displays a concentrated supplier landscape; the leading few firms together command a material share of global production capacity. This concentration drives bargaining power dynamics, elevates supplier reliability as a procurement criterion, and intensifies the importance of diversified sourcing strategies and long-lead component hedges.
-
Regulatory and IP realities are non-negotiable. Compliance pathways for hearing-health products and over-the-counter devices are shaping product architectures and supplier selection. Concurrently, transnational IP friction has surfaced as a non-trivial operational risk in recent years, forcing multinational buyers to add legal risk assessments to their supplier due diligence.
Market trajectory and interpretation for 2026 plans
Between 2020 and 2025 the market oscillated within a narrow band, reflecting substitution pressures from electrodynamic alternatives, fluctuating consumer demand cycles, and supply-side bottlenecks. With a projected CAGR of approximately 1.5% during the 2026–2032 forecast period, the market’s growth profile signals a shift from volume-driven expansion to value-driven competition. For decision-makers in 2026, that suggests prioritizing product mixes and supply chain investments that maximize margin capture per unit rather than purely chasing unit volumes.
Competitive landscape — what matters to buyers and investors
Our competitive analysis spotlights a small set of specialized component manufacturers that exert disproportionate influence on product innovation and pricing. These firms have deep R&D capabilities, geographically dispersed manufacturing footprints, and established OEM relationships. Notable players include long-standing specialists in miniature drivers and multi-driver systems whose product roadmaps are actively shaping OEM design choices.
-
Knowles Corporation: A leader in multi-way balanced-armature solutions and integrated driver combinations, Knowles continues to push premium TWS and IEM architectures with recent launches of multi-way driver families and pre-configured crossover assemblies. For OEMs targeting the premium segment, Knowles’ platforms shorten development cycles and reduce acoustic tuning risk.
-
Sonion A/S: With a global reputation in miniature receivers for hearing aids and audio applications, Sonion’s designs and production depth make it a default supplier for buyers requiring compact form factors and stringent quality standards.
-
Etymotic Research: Known for high-performance micro-drivers, Etymotic’s product pedigree is particularly relevant for IEMs and certain medical-grade hearing solutions where audio fidelity and reliability are critical.
-
Bellsing Acoustic Tec. Co., Ltd.: A major China-based supplier of multi-driver configurations, Bellsing’s capacity and product breadth contribute materially to global supply. However, its involvement in past IP-contentious cases underscores the geopolitical and legal dimensions that buyers must factor into supplier selection.
Collectively, the market exhibits notable concentration at the top; our analysis shows that the top three and five suppliers capture a significant majority of supply — a dynamic that feeds both opportunities (stable partnerships, co-development) and risks (supply disruptions, pricing pressure, and IP exposure).
Recent developments that change the 2026 playbook
-
Product launches that pre-integrate acoustic crossovers and multi-driver configurations lower system integration risk for OEMs and accelerate premium product introductions. These platforms are especially material for firms aiming to enter or expand in the high-margin TWS and IEM segments.
-
Supplier selection is now routinely informed by compliance assurance for hearing-health and over-the-counter device standards; vendors that can demonstrate regulatory readiness reduce time-to-market for medical-adjacent product lines.
-
Geopolitical and IP events have briefly reshaped sourcing decisions and pushed some multinational buyers to dual-source or nearshore portions of their supply chains to insulate product roadmaps from export controls or legal actions.
Report contents — what PW Consulting provides (practical, action-oriented)
Our study blends quantitative market sizing with executable frameworks designed for 2026 decision cycles. The report includes:
-
Consolidated market sizing and multi-scenario forecasts (2026–2032) with base-year calibration (2025).
-
Segmentation analysis by form-factor, application, and region — presented with trend diagnostics and demand-side elasticities (note: detailed segment tables and regional splits are available in the full report).
-
Supply chain mapping and node-level risk heat maps indicating single-source exposures, capacity constraints, and lead-time variability.
-
Competitive benchmarking profiles that compare technology roadmaps, capacity, regulatory posture, and IP posture for the leading suppliers.
-
Commercial playbooks for OEMs: supplier shortlists, negotiation levers, quality gating checklists, and a procurement timeline aligned with product development calendars.
-
M&A and partnership screening matrices that identify attractive targets and partnership archetypes based on capability gaps and integration complexity.
-
Scenario-based stress tests for pricing and supply disruptions, with recommended hedging and contract structures tailored to 2026 procurement cycles.
How organizations should use this analysis in 2026
-
Product teams: Prioritize platform components that deliver the most defensible acoustic differentiation per engineering hour. Consider co-development arrangements with select suppliers to lock in advanced driver combinations and reduce tuning cycles.
-
Procurement: Rebalance long-term contracts with tactical spot allocations to manage supplier concentration risk. Insist on regulatory compliance evidence and IP-clearance covenants in supplier contracts — especially for hearing-related product lines.
-
Strategy and Corporate Development: Use the report’s M&A and partnership frameworks to identify bolt-on acquisitions that fill capability gaps (e.g., miniaturization, acoustic tuning tools) and to evaluate strategic minority investments in regional suppliers as de-risking plays.
-
Investors: Understand that the market’s modest CAGR favors companies with scalable premium offerings or distinctive IP; commodity players face margin compression unless they secure scale or vertical synergies.
Research rigor and limitations
PW Consulting’s estimates are anchored to a 2025 base year and informed by historical performance (2020–2025), primary interviews across OEMs and component suppliers, and supply-chain audits. Forecast trajectories for 2026–2032 reflect a conservative macro assumption set and incorporate scenario overlays for regulatory change and trade disruptions. As a teaser to our full intelligence suite, this article highlights directional findings and strategic implications — the full report contains the detailed segment breakdowns, regional splits, and company-level market-share tables that are essential for transactional diligence and procurement negotiations.
Final takeaway — a focused checklist for 2026
-
Treat supplier concentration and IP exposure as first-order risks; build contractual and sourcing countermeasures now.
-
Allocate R&D and procurement capital toward driver platforms that enable premium differentiation rather than volume commodity bets.
-
Factor regulatory readiness into supplier scorecards when targeting hearing-health adjacent products.
-
Use the conservative CAGR and multi-year forecast window to stress-test pricing and margin scenarios for the next funding or sourcing cycle.
For practitioners setting strategy in 2026, PW Consulting’s balanced-armature magnetic speakers market study offers the quantification, supplier intelligence, and executable tools you need to convert modest market growth into durable competitive advantage. Access the full dataset and supplier-level tables on our website to unlock the specific segmentation figures and detailed company metrics that underpin these recommendations.
For detailed analysis of this topic, please visit the official page: Balanced-armature Magnetic Speakers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Omega‑3 Products market to expand at 6.98% CAGR through 2032
By pmarketresearch, 2026-07-30
Omega‑3 Products Market: Strategic Briefing for 2026 Decision‑Makers
Executive summary
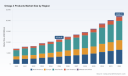
As global health narratives and sustainability imperatives converge, the omega‑3 products market is entering a structurally transformative phase. Our latest PW Consulting market study — with a base year of 2025 and a forecast window spanning 2026–2032 — shows continued expansion at a compound annual growth rate (CAGR) of 6.98%. The market measured USD 11,314.42 Million in 2025 and, under our baseline scenario, is forecast to more than double by the end of the modelling period. For executives preparing investment, portfolio, or go‑to‑market choices in 2026, this study is designed to convert epidemiological, consumer and regulatory trends into executable commercial actions.
Omega 3 Products Market
Why this research matters for 2026 strategy
-
From opportunity timing to risk mitigation: 2026 is a turning point. Growth is no longer linear; it is being re‑cast by ingredient innovation (notably microalgal and other non‑marine sources), regulatory tightening, and accelerating e‑commerce adoption. Firms that align upstream sourcing, formulation and digital distribution now will secure scale advantages as the market matures.
Omega 3 Products Market -
Clarity for allocation decisions: with overall market momentum established, the pressing question for boards and strategic planning teams is not whether to play, but where and how much to invest. Our modelling translates high‑level growth into probabilistic outcome bands that support capital budgeting, plant investment, and M&A prioritization under multiple macro scenarios.
Omega 3 Products Market -
Actionable compliance readying: regulatory attention on dietary supplements has intensified. Anticipated rule‑making and process modernization initiatives in 2026 raise execution risks for product launches and cross‑border supply chains. The study provides regulatory readiness frameworks that map probable timelines and required controls to practical program milestones.
What the report delivers — practical, operational intelligence
-
Market sizing and trajectory: a transparent reconciliation of historical performance (2020–2025) against forward projections (2026–2032), with scenario lenses (conservative, baseline, upside) and sensitivity to raw‑material price shocks.
-
Commercial playbooks: channel‑specific GTM templates (DTC/e‑commerce, brick‑and‑mortar, pet food, infant nutrition and pharma pathways) tailored to ingredient form (triglyceride vs. ethyl ester vs. algal concentrates) and consumer purchase behaviors.
-
Supplier and manufacturing scorecards: independent assessments of ingredient producers, contract manufacturers and third‑party certifiers, including operational capacity, sustainability credentials, traceability practices and unit economics.
-
Regulatory risk heatmaps and GRAS readiness checklists: step‑by‑step compliance actions keyed to the FDA’s 2026 priorities for recall process modernization and planned guidance around new‑substance notices.
-
Financial and M&A analytics: target screening for bolt‑on acquisitions, accretion/dilution modelling, and integration playbooks aligned to consolidation scenarios consistent with observed market concentration metrics.
Competitive landscape — what leading players are doing in 2026
The market remains moderately fragmented: our competitive concentration analysis indicates that the three largest players account for roughly a quarter of market value, and the top five capture only marginally more — a structural signal of opportunity for consolidation and scale plays.
-
Aker BioMarine (Lysaker, Norway) — continues to leverage its brand and R&D orientation in krill and algae solutions. Recent participation at Vitafoods India 2026 to introduce a high‑concentration algae DHA demonstrates a dual strategy: expand into higher‑margin sustainable ingredients while reinforcing global distribution relationships.
-
GC Rieber VivoMega (Kristiansund, Norway) — has focused on high‑potency triglyceride concentrates for nutraceuticals. Its early‑2026 launch of a high‑potency algal TG product signals a deliberate push to capture demand from vegan and label‑conscious consumer segments.
-
dsm‑firmenich (Kaiseraugst, Switzerland) — is pursuing scale in North America, evidenced by a multi‑million dollar upgrade of regional premix capacity and product introductions targeted at adjacent categories (e.g., pet nutrition). Their activity underlines a platform strategy: combine ingredient IP with customer‑facing formulation services.
-
Corbion (Gorinchem, Netherlands) — remains focused on algal DHA for infant and plant‑based markets, maintaining a differentiated stance on sustainability and system integration with infant formula makers.
-
Pharma Marine (Søvik, Norway) and Neptune Wellness Solutions (Toronto) — represent suppliers that blend marine sourcing with certification playbooks, positioning for customers looking for traceability and sustainability assurances.
-
Omega Protein Corporation (Houston) — continues to be a strategic supplier for high‑volume fish oil requirements, relevant for companies that prioritize cost and scale.
Recent industry movements worth tracking
-
Product innovation: several suppliers introduced concentrated algal and marine omega‑3 ingredients in early 2026, sharpening the competitive boundary between traditional marine oils and next‑generation non‑marine sources.
-
Capacity and capability investments: modernization projects in premix and formulation centers reflect supplier bets on faster time‑to‑market in the Americas and pet nutrition expansion.
-
Certification and sustainability signaling: suppliers are increasingly using third‑party sustainability credentials to underpin premium pricing and secure partnerships with consumer brands that require verified chain‑of‑custody.
Market dynamics, headwinds and strategic implications
-
Raw‑material volatility: fluctuations in marine by‑product and shellfish markets materially affect manufacturing margins. Scenario analysis in the report quantifies margin impacts across sourcing choices and shows where hedging, multi‑supplier contracts and backward integration alter outcomes.
-
Regulatory tightening: the FDA’s 2026 agenda — including recall modernization and proposed requirements for broader GRAS submissions — elevates the cost of non‑compliance. Firms should accelerate product documentation, expand lot‑level traceability, and budget for faster response capabilities.
-
Consumer purchase shifts: online grocery and direct e‑commerce channels now represent a significant share of sales in 2026, driving demand for smaller‑format, single‑serve and subscription‑friendly omega‑3 SKUs. Brands that adapt packaging, fulfillment and digital engagement see larger conversion and retention gains.
-
Fragmentation and consolidation dynamics: with the market concentration metrics indicating room for scale economies, well‑capitalized players and PE sponsors will find attractive arbitrage between manufacturing optimization and brand roll‑ups.
Actionable plays for 2026 — 90‑day and 12‑month roadmaps
-
90‑day priorities: complete an audit of supplier traceability; run a GRAS/compliance gap assessment for all SKUs; pilot a high‑potency algal SKU with a small e‑commerce partner; stress‑test contracts for raw‑material price pass‑through clauses.
-
12‑month priorities: establish a multi‑source ingredient strategy; pursue targeted capacity upgrades or tolling arrangements; execute one focused acquisition to capture distribution or ingredient IP; implement lot‑level serialization and a rapid recall playbook aligned to regulatory timelines.
Why PW Consulting’s Omega‑3 Report is the right decision tool
Our study is built to be operational: not an archive of descriptive statistics, but a toolkit for deployment. It combines detailed market modelling (historical 2020–2025, base year 2025, forecast 2026–2032), supplier due diligence templates, regulatory readiness matrices and commercial playbooks that link to P&L and cash‑flow implications. We preserve confidentiality of sensitive sub‑segment datasets in this overview so executives can assess strategic direction quickly; the full dataset, including granular regional and application breakouts, pricing curves, and supplier scorecards, is available via the report portal.
Next steps
-
If you are setting 2026 capex or M&A mandates, use our scenario modules to quantify downside exposure to raw‑material shocks and regulatory cost ramps.
-
If you are a commercial or R&D leader, review the GTM templates and pilot planning checklist to reduce time‑to‑launch for algal and alternative omega‑3 SKUs.
-
For investor teams, our competitive concentration analysis and deal‑scoping tools identify the most accretive target profiles within current consolidation dynamics.
To access the complete intelligence set — including the granular segmentation that underpins the figures summarized here and executable annexes for procurement, regulatory and commercial teams — please consult the full PW Consulting Omega‑3 Products Market report on our website.
For detailed analysis of this topic, please visit the official page: Omega 3 Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Shirting Fabrics Market to Grow at 5.9% CAGR Through 2032
By pmarketresearch, 2026-07-30
Shirting Apparel Fabrics Market — Strategic Outlook for 2026
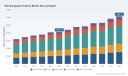
As corporate planning cycles turn toward mid‑decade execution, supply‑chain managers, sourcing leads, product strategists and private equity sponsors face a pivotal question: how will the shirting fabrics market evolve and what concrete actions should be taken in 2026 to protect margin, secure supply and capture growth? PW Consulting’s latest Shirting Apparel Fabrics Market study — rooted in historic performance (2020–2025) and forward forecasts through 2032 — provides a pragmatic compass. The market expanded from roughly USD 32,000 million in 2020 to about USD 41,400 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.9% through the 2026–2032 forecast window, reaching an anticipated total above USD 61,500 million by 2032. This trajectory confirms both resilience and opportunity, but also signals strategic inflection points for 2026 decision‑making.
Shirting Apparel Fabrics Market
What this study delivers — applied intelligence, not just numbers
-
Actionable market sizing and forecasting: granular top‑line modeling calibrated to recent shock events and policy shifts so teams can convert percentage growth into procurement and revenue targets for 2026 planning cycles.
Shirting Apparel Fabrics Market -
Value‑chain diagnostics: detailed mapping from fiber sourcing through finishing and cut‑make‑trim, highlighting where margin pools are widening or compressing and where near‑term operational interventions unlock the most value.
Shirting Apparel Fabrics Market -
Supplier benchmarking and playbooks: comparative profiles and operating levers for leading mills and integrated suppliers, plus negotiation templates and commercial KPIs to accelerate shorter supplier onboarding cycles.
-
Risk and compliance matrices: regulatory, tariff and sustainability risk assessments with mitigation blueprints calibrated for real‑world 2026 scenarios.
-
Go‑to‑market and product innovation pathways: practical roadmaps for launching differentiated shirting lines (premium, performance, sustainable) with pricing, margin and channel implications modeled across plausible demand scenarios.
Key dynamics shaping 2026 decisions
-
Policy and tariff volatility. The apparel import tariff environment has become materially more uncertain. Notably, the average U.S. apparel import tariff rate surged to a record high in late 2025, creating immediate commercial and strategic consequences for importers, brand sourcing desks and ODM partners. Procurement teams must now build tariff‑aware sourcing models and contract clauses that explicitly convert tariff volatility into hedged pricing or contingency cost allocations.
-
Accelerating sustainability standards. Global standards bodies and industry consortia updated chain‑of‑custody and product standards in 2025–2026. New requirements for organic, recycled and responsibly sourced inputs are shifting capital and operating spend into traceability, testing and supplier onboarding — all of which have near‑term cost and long‑term brand value implications.
-
Product specification governance. Technical standards and performance specifications remain central to risk control. ASTM and equivalent standards continue to be touchstones for product teams, and the evolving standard set is influencing supplier acceptance criteria, lab testing cadence and warranty exposure for brands.
-
Demand polarisation and channel shift. Consumer demand is bifurcating between accessible ready‑to‑wear shirting and premium, sustainable offerings. Retailers and brands that can translate technical fabric attributes into clear consumer value narratives will capture disproportionate share; those that cannot will face margin compression from price competition and inventory risk.
-
Supply‑side modernization. Investment in finishing technologies, digital sampling and near‑sourcing is changing lead‑time economics. Suppliers with deeper integration across spinning, weaving and finishing — or with strategic partnerships to guarantee fabric feedstock — will disproportionately benefit in a market where agility becomes a competitive advantage.
Competitive landscape — incumbents, challengers and what they signal for 2026
The market displays mid‑level concentration: the top three suppliers account for a meaningful share of industry shipments, and the top five consolidate a larger majority — a structure that supports both scale advantages and partnership opportunities. This concentration pattern creates predictable supplier power dynamics but still leaves room for agile specialists and vertically integrated entrants to capture niche premiums.
-
Acorn Fabrics (UK) — a heritage mill focused on premium cotton and linen shirtings that sells directly to designers and end customers. Their model underscores the commercial value of brand‑led mill positioning and high‑margin D2C channels for premium shirting.
-
Esquel Group (Hong Kong) — an integrated player supplying global brands with both fabrics and finished apparel. Esquel’s strength is end‑to‑end control and close OEM partnerships, which provide resilience against open‑market raw material swings and tariff shocks.
-
Raymond Group and Arvind Limited (India) — large‑scale, vertically integrated manufacturers that combine cotton input control with extensive finishing capacity. Their scale supports competitive pricing for both formal and casual shirting while enabling rapid capacity reallocation.
-
Hebei Gaibo Textile (China) — a specialist in polyester blends and workwear shirting fabrics, representing the continued importance of synthetics in cost‑sensitive segments and institutional contracts (uniforms, workwear).
-
Ranjini Textiles (India) and TAL Apparel (Vietnam) — examples of differentiated supply strategies: Ranjini leverages heritage yarn‑dyed craftsmanship for niche designers, while TAL combines garment manufacturing scale with dedicated fabric supply, reducing negotiation friction for apparel brands.
For 2026 planning, the strategic lesson is clear: scale and integration confer protection against input and policy shocks, but differentiation and speed to market create pockets of outsized margin. Partnerships and JVs remain highly effective means for brands to secure capacity without ceding margin.
Strategic implications and recommended actions for 2026
-
Re‑segment suppliers by strategic value: move beyond cost‑per‑meter to a triage approach — strategic (capacity, quality, innovation), tactical (cost, fill rate) and transactional (spot buys). Allocate relationship management resources and contractual protections accordingly.
-
Model tariff scenarios into sourcing decisions: develop three tariff scenarios (baseline, moderate shock, and structural shock) and run P&L sensitivity for each major sourcing corridor. Embed tariff pass‑through clauses in new contracts and adopt financial hedges where practical.
-
Prioritise compliance and traceability investments: in markets where sustainability claims drive premium placement, invest in digital traceability pilots, audit roadmaps and supplier capability uplift to secure certification faster than competitors.
-
Shorten the commercialization loop: accelerate digital sampling and micro‑production runs to reduce time‑to‑market for new shirting collections. Faster validation cycles lower inventory risk and support premium pricing for differentiated technical or sustainable fabrics.
-
Pursue strategic partnerships, not just spot buying: where scale is constrained, prefer capacity reservation agreements, JV arrangements for local finishing, or minority investments in mills that have unique capability sets (e.g., specialty weaves, finishing technologies).
-
Embed scenario triggers into 2026 OKRs: define trigger points (e.g., sustained tariff levels, raw material price thresholds, certification lead times) that prompt pre‑authorized actions so teams can move from analysis to execution without bureaucratic delay.
How to use this research in your 2026 planning cycle
-
90‑day triage: use the report’s supplier scorecards and risk matrices to reclassify top suppliers, update contractual terms and establish contingency inventory buffers for high‑risk SKUs.
-
6–12 month execution: pilot near‑sourcing initiatives, implement traceability pilots with priority suppliers, and launch a pricing playbook that internalises tariff scenarios and sustainability premiums.
-
18–36 month structural changes: consider capacity investments, vertical partnerships, or targeted M&A to secure long‑term feedstock, finishing capability and technical fabric IP aligned with forecast demand profiles.
Why PW Consulting’s Shirting Fabrics report matters
This study is built to be operational. It translates a forecasted 5.9% CAGR and multi‑year market expansion into the concrete decisions procurement, product and corporate development teams must make in 2026. We combine macroeconomic scenario work, policy monitoring, supplier benchmarking and pragmatic playbooks so that your 2026 planning process is driven by defensible intelligence, not guesswork.
Importantly, this overview is a strategic trailer: it demonstrates the report’s analytical depth and the immediate value you can extract, while reserving the full, segment‑level forecasts, granular regional breakdowns, company scorecards and contract templates for the full report. If your organisation is preparing budgets, vendor agreements, or M&A screens for 2026, the full dataset and executable templates in the report will materially reduce implementation time and execution risk.
For teams that need to move from insight to action this quarter, the recommended next step is straightforward: run the report’s supplier reclassification exercise, stress‑test your top SKUs against the tariff sensitivity models and pilot one traceability upgrade with a strategic supplier. These three moves alone will re‑orient many organisations from reactive cost control to proactive, profitable growth in the evolving shirting fabrics market.
For detailed analysis of this topic, please visit the official page: Shirting Apparel Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CMTS/QAM Market to Reach USD 7,494M by 2032 at 8.8% CAGR
By pmarketresearch, 2026-07-30
CMTS & QAM Market 2026: Strategic Intelligence for Executive Decision-Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
CMTS/QAM Market
Executive teaser
The global CMTS (Cable Modem Termination System) and QAM (Quadrature Amplitude Modulation) market has moved from a niche operator concern into a decisive infrastructure topic for broadband strategy. Our CMTS/QAM Market research, anchored on 2025 as base year and a multi-year historical series (2020–2025), projects sustained momentum through 2032. The market expands from a multi‑billion dollar base in 2025 to an even larger addressable opportunity by 2032, driven by DOCSIS evolution, virtualization, and video distribution models. Over the 2026–2032 forecast window we model an 8.8% CAGR — a rate that demands active strategic choices in procurement, architecture, and ecosystem partnerships during 2026.
CMTS/QAM Market
Why this matters for 2026 strategy
Service providers and vendors face a convergence of three strategic pressures: accelerating customer demand for multi‑gigabit services, the economics of headend consolidation, and an industry trajectory toward cloud‑native, software‑defined access. These forces create a binary set of choices for network executives in 2026: move decisively to virtualized, distributed architectures with vendor interop and managed transition paths — or manage rising OpEx and capacity constraints by extending legacy architectures with incremental upgrades.
CMTS/QAM Market
- Timing matters: the projected 8.8% CAGR amplifies the cost of delay. Every quarter of deferred modernization compounds capacity and support costs, and reduces negotiating leverage with suppliers.
- Architecture choices are strategic bets: hardware‑centric CCAP/CMTS platforms remain relevant, but virtual CMTS (vCMTS) and cloud‑native implementations materially alter TCO profiles and upgrade cadence.
- Regulatory and security contours are changing: industry‑wide interoperability events and security‑focused interop sessions in 2026 underline that vendor compatibility and secure software lifecycles will be procurement differentiators.
What the research delivers (practical toolkit)
This report is built as an operational playbook for decision‑makers, not an academic exercise. Highlights include:
- Market sizing and trend analytics: a validated historical series (2020–2025) and scenario‑based forecasts to 2032 that quantify the macro opportunity and downside sensitivities.
- Adoption curves and migration roadmaps: tested deployment templates for phased DOCSIS 3.1→4.0 and vCMTS adoption, with milestone‑based gating criteria to align CapEx cycles with customer demand.
- TCO and CapEx/OpEx models: comparative analyses showing the inflection points where virtualization becomes financially attractive, including power, rack‑space, and personnel assumptions.
- Interoperability matrix and vendor readiness scoring: vendor capabilities assessed against criteria such as DOCSIS feature parity, QAM integration, cloud‑native maturity, and security posture.
- Procurement playbook: negotiation levers, SLA templates, and upgrade path clauses designed to protect operators during multi‑year migrations.
- Risk register and mitigation playbooks: scenarios spanning component cost volatility, supplier consolidation, and interoperability lags, with practical mitigation steps.
Competitive landscape — what to watch in 2026
The market structure features a mixture of global incumbents, specialist vendors, and emerging cloud‑native challengers. Aggregate concentration indicates meaningful scale among the top players, yet the vendor field remains sufficiently fragmented to allow strategic sourcing options.
- Cisco Systems — a traditional incumbent with integrated CMTS/Edge QAM platforms that continue to serve large operators requiring tightly integrated hardware solutions. Strengths: global field support, breadth of platform functionality, and legacy operator relationships. Watch: migration path toward greater software modularity and cloud interop.
- Arris Group — positioned with high‑density CCAP and Edge QAM offerings suitable for operators wanting a path from video‑dense headends to combined data/video services. Strengths: density and service provider familiarity. Watch: roadmap alignment to DOCSIS 4.0 and virtualization.
- Casa Systems — a leading voice for virtual CCAP/vCMTS and distributed access. Strengths: DAA‑oriented solutions and strong software stacks for operators planning cloud migration. Watch: commercial scalability and integration with third‑party virtualization platforms.
- Harmonic Inc. — notable for cloud‑native vCMTS and Edge QAM products and recent contract wins supporting DOCSIS 4.0 pilots. Strengths: cloud‑first approach and strong presence in video streaming stacks. Watch: execution on large‑scale Unified DOCSIS projects.
- Vecima Networks — a specialist whose Entra vCMTS and video QAM management solutions are increasingly selected by operators pursuing cloud‑native modernization. Strengths: interoperability focus and tailored modernization offers. Watch: ability to scale to multi‑operator contracts.
- Huawei, WISI, Sumavision, Teleste and regional OEMs — provide alternative technology and price points, especially in markets where regional supply diversity or localization matters. Strengths: cost competitiveness and regional support models. Watch: compliance, interoperability, and long‑term software support commitments.
- Smaller entrants (e.g., C9 Networks, Chongqing Jinghong) — bring niche innovation and targeted platform features; suitable for pilots and regional rollouts but require caution on roadmaps and support SLAs.
Recent industry signals that change tactical choices
Market signals over the past 18 months accelerate the need for decisive choices in 2026:
- Contract awards to cloud‑native vCMTS suppliers demonstrate operator willingness to shift away from pure hardware dependency. Selected deployments validate scale and commercial models for virtualization.
- Interoperability events organized by CableLabs in early 2026 expanded DOCSIS 4.0 testing, explicitly adding security and multi‑vendor interop scenarios — a positive for operators requiring vendor agnosticism but also a warning that multi‑vendor integration carries execution risk if not planned.
- Partnerships in Distributed Access Architecture (DAA) deployments signal a move toward disaggregated headend functionality; procurement teams must therefore evaluate components for fit in both centralized and distributed topologies.
Cost and technology dynamics to factor into 2026 decisions
Two structural cost dynamics will shape vendor selection and architecture choices:
- Hardware complexity: DOCSIS 3.1/4.0 implementations demand advanced LDPC error correction and OFDM/OFDMA modulation support, which drives higher component and unit costs versus legacy 256‑QAM platforms. These costs must be weighed against lifecycle benefits and per‑subscriber capacity gains.
- Virtualization economics: relocating CMTS functions to commercial off‑the‑shelf servers can materially reduce headend footprint and power consumption; however, the financial case depends on virtualization maturity, orchestration overhead, and integration with existing OSS/BSS systems.
Actionable recommendations for 2026 — a concise checklist
- Run a staged migration pilot: prioritize vCMTS pilots with clearly defined KPIs (latency, throughput, operational overhead) before committing to network‑wide rollouts.
- Embed interoperability clauses: require multi‑vendor interop certification milestones and security audit results as part of procurement contracts.
- Quantify TCO with sensitivity testing: model scenarios where virtualization yields breakeven at different energy, personnel, and capacity assumptions to inform CapEx timing.
- Protect upgrade optionality: include modular upgrade and rollback clauses to preserve options as DOCSIS standards and vendor roadmaps evolve.
- Align procurement with architecture: build vendor shortlists around target architecture — centralized CCAP, hybrid DAA, or fully distributed vCMTS — rather than selecting vendors first and forcing design later.
- Monitor supply and regulatory tides: track interoperability events and regulatory guidance that may change timelines for secure DOCSIS 4.0 rollouts.
What we intentionally withhold here — and why
To preserve the strategic "trailer" value of this briefing, detailed segmentation tables — including regional and application breakouts, and granular vendor share by subsegment — are only available in the full CMTS/QAM Market report. The high‑level market trajectory, CAGR, and practical implications for 2026 strategy are disclosed here to inform executive decisions; the granular splits, procurement‑grade vendor scorecards, and downloadable TCO models are provided in the paid report to ensure decision teams have a single canonical source for negotiations and planning.
Next steps
Executives preparing procurement or network transformation roadmaps in 2026 should request the full PW Consulting CMTS/QAM Market report to obtain:
- Operational playbooks and vendor scorecards for procurement teams.
- Downloadable TCO models and scenario planners tailored to operator scale.
- Access to proprietary interoperability matrices and secure‑by‑design checklists that are updated against the latest CableLabs testing outcomes.
PW Consulting will be publishing an executive briefing series and supporting workshops in Q3 2026 to help operators convert these findings into 12–36 month execution plans. For operators and vendors seeking to participate in workshop engagements or to obtain the full dataset and annexes, visit our report page or contact our advisory desk.
For detailed analysis of this topic, please visit the official page: CMTS/QAM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Doorbell Market to Reach USD 538M by 2032 at 13.45% CAGR
By pmarketresearch, 2026-07-30
Doorbell Market 2026 Preview: Strategic Imperatives for Decision-Makers
Executive snapshot
As enterprises prepare strategic plans for 2026, the global doorbell market presents a clear growth runway underpinned by technology-led substitution, expanding smart-home ecosystems, and regulatory re‑calibration. Our latest PW Consulting Doorbell Market study—anchored on a 2025 base year and projecting through 2032—identifies a sustained compound annual growth rate (CAGR) of 13.45% and models a near‑term inflection as vendors commercialize higher‑resolution imaging, advanced on‑device AI, and Matter‑enabled interoperability. In plain terms: the market that was measured in the low hundreds of USD Million scale in 2025 is on a multi‑year trajectory to more than double by the end of the forecast horizon, creating definable windows for product, channel, and M&A plays in 2026 and beyond.
Doorbell Market
Why 2026 matters
-
Technology convergence accelerates product differentiation. Vendors are shipping devices that combine 2K+/4K imaging, radar and multi‑camera optics, and on‑device AI inference—features that materially change value propositions for both residential and commercial buyers.
Doorbell Market -
Interoperability standards are moving from promise to practice. The Connectivity Standards Alliance’s March 2026 refinements to Matter tighten expectations for camera streaming and device profiles—lowering integration costs for platform players but raising compliance pressure on legacy and “closed” systems.
Doorbell Market -
Regulatory scrutiny is intensifying. Recent enforcement trends and policy proposals in North America and elsewhere underscore certification, supply‑chain transparency, and radio‑spectrum allocation as active risk vectors for vendors and integrators.
Market trajectory — what the numbers tell us (high level)
Our modelling—built from a 2020–2025 historical series and projecting 2026–2032—captures the compound forces driving market expansion. The 2025 baseline provides a reliable starting point for scenario planning: when combined with the 13.45% CAGR embedded in our base case, the implication is a robust and sustained growth environment rather than a fleeting spike. For commercial leaders, that matters because it changes the math on product R&D payback, channel investment, and M&A timing: what may have been a multi‑year horizon to profitability now compresses, making 2026 the year to convert R&D and strategic partnerships into tangible go‑to‑market advantage.
Competitive landscape: who matters and why
The market remains fragmented—top incumbents do not yet dominate—and competitive dynamics are best understood as an interplay between platform incumbency, hardware differentiation, and go‑to‑market agility. Leading firms span ecosystems players, dedicated security brands, and a growing set of value‑price entrants.
-
TP‑Link (Tapo series) : Strength in cost‑competitive hardware and straightforward local storage/no‑subscription positioning. Well‑placed to capture mainstream residential upgrades where ecosystem attachment (Wi‑Fi + smart‑home hubs) is a buyer consideration.
-
Arlo Technologies : Focused on premium optics and field of view innovations (head‑to‑toe, 180°), with flexible wired/wireless options. Arlo’s value is in differentiated user experience and integrator familiarity in the channel.
-
Eufy Security : A clear proposition around no‑monthly‑fee models and dual‑camera configurations. Strong appeal for privacy‑sensitive buyers and international channels that prioritize local storage and AI‑based person/package detection.
-
Ring : Continues to push advanced sensing (radar, 3D motion) and deep voice/assistant integration. As Ring evolves its higher‑resolution line and radar features, it presents a case study in how platform attachment and ecosystem lock‑in translate to service revenue opportunity.
-
Google (Nest) : Seamless Google Assistant and Nest ecosystem integration remain a competitive moat for user experience and cross‑sell. Google’s product cadence emphasizes both wired and battery variants with high accuracy detection and fast cloud alerts.
-
Aqara : Targeting Apple HomeKit and early Matter compatibility; they play to the premium smart‑home integrator and pro‑install channel with PoE/wired options and on‑device facial recognition.
-
Signify (Hue Secure) : Leverages lighting integration to create differentiated illumination and privacy features—an example of adjacent category leverage that changes how a doorbell is positioned in a broader connected‑home solution.
-
Reolink, Hikvision, Bosch : These vendors emphasize professional distribution, advanced analytics, and systems interoperability—critical for commercial segments and multi‑site deployments.
Recent product launches—from Qualcomm‑powered long‑life battery doorbells to new Retinal Vision doorbell models—signal that hardware roadmaps will continue to reset competitive expectations in 2026. Vendors that combine hardware leadership with clear pathways to platform integration will capture the highest‑value segments.
Regulatory and standards dynamics — practical implications
Three regulatory currents should orient any 2026 decision:
-
Interoperability pressure: Matter 1.5.1 (March 2026) refines device profiles and streaming efficiency. For vendors, this reduces friction to enter platform ecosystems but creates an implementation bar: certified interoperability demands engineering and test investment. For product managers, prioritize Matter‑aligned firmware roadmaps now to avoid second‑mover penalties.
-
Certification and compliance risk: Recent enforcement actions and federal measures targeting telecommunications certification signal that compliance failures can yield material business disruption. Firms with opaque agent‑of‑record practices or rushed market entry may face recalls, fines, or channel access issues—making auditability and transparent supply‑chain controls a board‑level concern.
-
Spectrum and safety discussions: Industry comments on radio reallocation and public‑safety impacts highlight potential constraints for certain wireless doorbell technologies. Product roadmaps should include fallback architectures (e.g., wired/PoE options) and regional radio strategy to de‑risk market access.
What the PW Consulting report delivers (practical, actionable content)
Our full study is intentionally operational. We help enterprises convert insight into action by providing:
-
Market sizing and demand scenarios across a range of 2026 strategic choices, with sensitivity analyses for price, induced feature adoption, and channel mix.
-
Technology roadmaps and feature matrices that benchmark vendor capabilities—imaging, sensor fusion, AI inference, storage approaches (cloud vs local), and standards support—so product teams can prioritize engineering investments for 2026 launches.
-
Go‑to‑market playbooks for OEMs, retail brands, and professional integrators, including channel economics, bundling strategies, and service attachment models that improve lifetime value.
-
Regulatory compliance checklists and mitigation playbooks for certification risk, supply‑chain transparency, and spectrum sensitivity—designed to reduce time‑to‑market and avoid enforcement exposure.
-
M&A and partnership scouting: target profiles, valuation ranges, and integration risk matrices to help corporate development teams identify accretive acquisitions and alliance structures.
-
Financial models, pricing templates, and KPI dashboards that translate the 13.45% CAGR environment into EBITDA and cash‑flow scenarios under multiple commercialization strategies.
Importantly, while the report demonstrates aggregate market sizing and trajectory, it deliberately withholds granular segment tables in this overview. That guarded approach ensures stakeholders must access the full dataset to unlock the precise revenue splits, regional shares, and application‑level forecasts required to execute tactical plans.
Strategic priorities for 2026 — a concise checklist
-
Certify for Matter and align firmware roadmaps: early certification reduces integration friction and enables premium bundle strategies with platform partners.
-
Invest in on‑device AI and power efficiency: buyers increasingly value accurate detection without recurring fees—on‑device inference and long battery life are differentiators in 2026.
-
Design multi‑modal product lines (wired/PoE + battery): regulatory and spectrum uncertainty favors vendors that can offer alternative power and comms models.
-
Harden compliance and documentation processes: build or acquire certification expertise now to avoid mid‑cycle disruptions from enforcement actions or tightened approvals.
-
Prioritize channel economics for service attach: instruct retail and pro‑install partners with clear value‑capture models and subscription optionality to maximize LTV without alienating privacy‑sensitive buyers.
Conclusion — what boards and execs need to act on in Q1–Q2 2026
For executives, 2026 is both an execution and a timing inflection: the market’s underlying growth rate compels faster product commercialization, while standards and regulatory shifts raise the cost of late compliance. PW Consulting’s Doorbell Market study provides the strategic framework and the operational tools—scenarios, product benchmarks, regulatory playbooks, and financial models—that leadership teams need to convert the market’s growth into durable advantage. The high‑level indicators are clear: sustained CAGR expansion creates substantial upside, but only for firms that pair technical differentiation with disciplined compliance and sharp go‑to‑market economics.
Next steps
To receive the full dataset, vendor scorecards, and our proprietary scenario models (including the granular segment forecasts and regional breakdowns reserved for report subscribers), visit the PW Consulting Doorbell Market research page. The detailed annex contains the tables and downloadable models that product, regulatory, and corporate development teams will use to operationalize their 2026 plans.
For detailed analysis of this topic, please visit the official page: Doorbell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Slitter Market Set to Expand at 6.2% CAGR Through 2032
By pmarketresearch, 2026-07-30
Slitter Market 2026 Strategic Outlook — A PW Consulting Preview
As companies finalize capital allocation and product roadmaps for 2026, understanding the slitter market’s structural dynamics has moved from useful to essential. This preview synthesizes the strategic implications drawn from PW Consulting’s new Slitter Market research (base year 2025, historical 2020–2025, forecast 2026–2032). It signals where opportunities, supply risks, and competitive inflection points will occur — and how executives should reframe decisions to capture durable advantage. Note: this piece is intentionally high-level. Core segment-level detail and granular tables are reserved for the full report to preserve its tactical value.
Slitter Market
Market Trajectory: What the Numbers Tell Us
The slitter market has demonstrated steady expansion through the first half of the decade, growing from an estimated market size in 2020 to a substantially larger base in 2025. Our forecast models, calibrated across demand-side drivers and supply-side constraints, project a compound annual growth rate (CAGR) of 6.2% through the 2026–2032 horizon, with the overall market continuing to expand meaningfully by 2032. These aggregate trends signal a mid-single-digit growth regime that is large enough to justify targeted investment yet selective enough to reward disciplined segmentation and execution.
Slitter Market
Two observations follow immediately from the headline trajectory. First, above-market growth pockets will be tied to semiconductor packaging, advanced films, and precision electronics applications — areas where tolerance and automation premiums justify higher unit ASPs and aftersales revenue. Second, cyclical pressures and episodic raw-material shocks will create idiosyncratic timing opportunities to acquire capacity or enter adjacencies at favorable valuations.
Slitter Market
Demand Drivers and Technology Inflection Points
- Electronics miniaturization and panel-level packaging (PLP): The transition toward larger glass panels and PLP-compatible workflows is reshaping machine specifications. Equipment that supports panel-level processing and high-throughput film handling commands strategic importance.
- Higher-precision requirements: Micron-level tolerances for thin metal and copper strips are raising the bar on machine rigidity, blade technology, and inline metrology integration.
- Aftermarket and service revenue: As capital intensity rises, so does the lifetime value of installed bases. Service contracts, retrofit kits, and consumables will be decisive contributors to margin expansion.
- Automation and integration: Buyers increasingly prefer slitter systems that integrate seamlessly into MES/Industry 4.0 stacks, reducing manual intervention and improving uptime.
Supply Chain, Materials, and Regulatory Stressors
Macro and micro supply constraints materially affect deployment timing and cost curves. Key dynamics to account for in 2026 decisions:
- Component lead times: Precision optics and specialty gas shortages have extended lead times beyond six months in many cases, forcing firms to build inventory buffers or secure prioritized allocations.
- Raw-material price volatility: Critical inputs such as copper have experienced sharp price spikes, crossing materially elevated thresholds in 2026. This raises the cost of slitting solutions for copper foil and thin strip applications and compresses gross margins unless recovered through pricing or design efficiencies.
- Regulatory compliance: Market access requirements remain in flux. In the European context, continued compliance with key machinery safety directives is required for market entry through January 2027, and high-precision slitters used for thin copper strips face specific tariff/HTS classifications with commercial implications.
- Labor and sourcing: Rising labor costs and geopolitical uncertainty make multi-sourcing mandatory for many OEMs; single-source strategies expose manufacturers to interruption risks and potential contractual penalties.
Competitive Landscape — Where the Power Sits
The market remains fragmented by design: incumbent equipment specialists, semiconductor-capable OEMs, and niche slitter manufacturers each play distinct roles. Market concentration metrics indicate that the top three and top five suppliers capture a modest share of industry revenues, leaving ample room for differentiated entrants and consolidation plays. For executives, the recommendation is clear — prioritize positioning rather than attempting to outscale incumbents on their terms.
- Applied Materials, Inc. (Santa Clara, CA): A major player in precision wafer dicing and cutting equipment. Their strengths are deep process knowledge and integration into semiconductor fabs — a lever for upselling slitting-capable tools into established customer lifecycles.
- Tokyo Electron Limited (Tokyo, Japan): Known for dicing and precision materials-handling equipment, TEL’s footprint in semiconductor production equipment makes it an important competitor for panel- and wafer-level slitting solutions.
- KLA Corporation (San Jose, CA): While principally a metrology and inspection vendor, KLA’s ability to embed inspection into slitting workflows changes the value proposition for high-accuracy applications and can shift procurement toward bundled solutions.
- Toray Engineering (Tokyo, Japan): A focused innovator in film slitting and panel-level packaging equipment. Recent product launches targeting PLP and large glass panels underscore the strategic pivot toward advanced semiconductor packaging markets.
- ACRETECH Co., Ltd. (Tokyo, Japan): Specialized in semiconductor dicing — a company whose precision tooling and market access in electronics make it a natural partner or competitor depending on route-to-market.
Notable near-term developments include a cluster of product introductions by firms addressing PLP and larger-panel compatibility — a clear signal that the supply side is racing to meet packaging-led demand. These vendor moves alter incumbent cost structures and create timing windows for strategic partnerships or targeted capex.
What the PW Consulting Report Contains (Practical, Transaction-Ready Intelligence)
Our full Slitter Market study is built to inform commercial execution and investment decisions rather than to be merely descriptive. It includes:
- Transparent market-sizing and a reproducible methodology spanning 2020–2032, with scenario-based forecasts calibrated to material, regulatory, and demand shocks.
- Actionable segmentation frameworks identifying where premium pricing and higher service attach rates are sustainable (note: detailed segment tables are withheld in this preview).
- Supplier and vendor heat maps, including supplier capability matrices, lifecycle cost models, and retrofit opportunities for installed machines.
- Buy-side decision playbooks: procurement timing, TCO calculators, and prioritized sourcing checklists to reduce lead-time exposure and protect margins.
- Regulatory and tariff mapping with tactical guidance on customs classifications and compliance timelines affecting market entry and aftersales.
- M&A and partnership thesis pages that identify consolidation targets, typical valuation multiples observed, and integration risk checklists.
- Technology roadmaps and R&D priority matrices to align product development with near-term application demand.
Strategic Actions for 2026 — Where to Place Bets
For executives preparing budgets and strategic plans for 2026, PW Consulting recommends a set of coordinated actions that balance growth capture with downside protection.
- Prioritize high-precision, integrated offerings: Invest in slitter systems that come with embedded metrology or inspection, or partner with inspection vendors to offer bundled solutions. These systems demand premium pricing and deliver recurring service revenues.
- Lock in critical components and diversify sources: Given extended lead-times for precision optics and specialty gases, secure multi-year supply agreements and create dual-sourcing strategies to avoid bottlenecks.
- Hedge material inflation: Implement index-linked pricing clauses or design-to-cost initiatives for copper-intensive products; consider pass-through mechanisms for volatile commodities.
- Time capital deployment: Use forecasted mid-single-digit market growth to stage capacity additions. Avoid blanket greenfield expansions; instead, target incremental capacity or modular platforms that can be scaled as demand crystallizes.
- Monetize installed bases: Accelerate aftermarket programs — remote diagnostics, retrofit kits for automation, and service subscriptions — to convert equipment sales into annuity-style revenue.
- Regulatory readiness: Update compliance roadmaps for EU machinery directives and HTS classifications, and price new products to account for compliance-related cost increases.
- Prepare M&A playbooks: With low-to-moderate concentration, acquisition targets will often be technology-rich but capital-constrained. Prioritize targets that provide route-to-market synergies or gap-filling IP.
Using This Intelligence — Practical Next Steps
This preview is designed to align leadership around the material trends, constraints, and competitive moves shaping the slitter market as 2026 planning commences. The full PW Consulting Slitter Market report contains the granular, transaction-level analysis (including segment tables, regional maps, and supplier scorecards) needed to underwrite deals, set product-roadmap priorities, and design procurement programs.
For teams deciding on capital allocation, procurement timing, or M&A targets, the right next step is a focused diagnostic: a 4–6 week engagement to stress-test your demand assumptions against our scenarios, calibrate supplier scorecards to your product mix, and produce a bespoke execution plan with prioritized initiatives for 2026.
Final Word
The slitter market sits at the intersection of precision engineering and high-growth electronics applications. Aggregate growth supports investment, but execution will be won by firms that integrate metrology, secure supply chains, and convert equipment into recurring revenue streams. PW Consulting’s full market study operationalizes those insights into the playbooks and models companies need in 2026. For the detailed segment breakdowns, vendor-by-vendor benchmarking, and transaction-ready appendices that underlie these conclusions, access to the complete report is required.
For detailed analysis of this topic, please visit the official page: Slitter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Patient Infotainment Terminal Market Outlook — 8.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-30
Patient Infotainment Terminal Market — Strategic Preview for 2026 Decision-Makers
Executive teaser
As healthcare providers shift from one-size-fits-all bedside experiences to integrated clinical-communication platforms, patient infotainment terminals are transitioning from a service differentiation to a clinical-enablement component. PW Consulting’s forthcoming Patient Infotainment Terminal Market research frames that transition with a data-driven lens: the market has expanded materially through 2020–2025 and, under conservative modeling, is set to continue growing at a compound annual growth rate of 8.5% through the 2026–2032 forecast window. This preview outlines the strategic implications executives must address in 2026 without disclosing the granular segmentation that makes the full report indispensable for tactical planning.
Patient Infotainment Terminal Market
Why this matters for 2026
-
Capital allocation: Buyers and investors must reconcile near-term modernization budgets with multi-year integration costs—hardware replacement cycles, software licensing, and EHR integration all compound total cost of ownership.
Patient Infotainment Terminal Market -
Clinical outcomes and satisfaction: Infotainment terminals are increasingly part of clinical workflows—patient education, medication reconciliation, telemedicine access and recovery pathway adherence—making vendor selection a clinical as well as an IT decision.
Patient Infotainment Terminal Market -
Regulatory and procurement posture: Medical-grade certification, privacy compliance, and procurement-ready technical specifications are gating factors for large systems procurements and public-sector tenders.
Market trajectory — the macro picture
PW Consulting’s base-year alignment is 2025, and the dataset shows the market growing from its early-decade base to a materially larger installed footprint by the mid-2020s. Our forecast horizon (2026–2032) is modeled with conservative to moderate adoption scenarios and returns a compounded growth rate of 8.5% across the period. That trajectory reflects several reinforcing dynamics: accelerating digital patient engagement initiatives at health systems, continued replacement of legacy TV-only systems with integrated clinical interfaces, and pressure to standardize medical-grade endpoints under strict safety and privacy regimes.
Dynamics shaping demand
-
Regulatory inflection: Compliance with medical electrical safety and manufacturing standards (UL/IEC/ANSI families) and increasing scrutiny of data privacy elevate validation timelines and cost for suppliers and system integrators.
-
Reimbursement friction: Because payers are slow to create pathways for non-clinical or partially clinical digital tools, procurement decisions increasingly rely on measurable operational and quality-of-care KPIs rather than direct reimbursement offsets.
-
Input-cost pressure: Hardware component pricing, anti-microbial enclosures, and secure network infrastructure contribute to higher upfront and lifecycle expenses, prompting buyers to emphasize upgradeability and modularity.
-
Clinical interoperability: EHR integration, bedside clinical workflows, and telehealth links are now baseline asks; vendors who can demonstrate certified connectors and predictable integration effort stand a far greater chance in large tenders.
Where the value pools are opening (high-level)
Value is forming at the intersection of clinical utility, IT manageability, and operational cost. Specifically:
-
Integrated platforms that combine entertainment, secure messaging, patient education, and basic clinical data capture are being valued higher than single-function displays.
-
Endpoints designed for easy device management and standardized security patching reduce hospital IT support costs and therefore change procurement evaluation criteria.
-
Modularity—swap-in media modules, upgradeable SoCs, or standardized peripheral interfaces—reduces replacement capex and increases appeal to large multi-site health systems.
Competitive landscape — who to watch
The market shows a mix of deep-specialist medical-electronics firms, IT-focused integrators, and regional OEMs. Competition is neither purely commoditized nor fully consolidated: the top-tier firms account for meaningful share, but compelling capabilities exist across mid-market and regional players. Below is a high-level strategic read on key participants and their positioning.
-
BEWATEC (Germany) — Strengths: integrated bedside series and a platform approach (ConnectedCare) that connects scheduling, treatment plans and medication information. Strategic implication: deep clinical workflows integration makes BEWATEC a natural partner for health systems seeking an out-of-the-box clinical-to-patient experience; challengers must match both software breadth and deployment references.
-
Onyx Healthcare Inc. (Taiwan) — Strengths: emphasis on medical-grade certification and manufacturing compliance. Strategic implication: Onyx is well-positioned where procurement mandates strict safety certifications. For partners and buyers, certification roadmaps are as important as price.
-
PDi Communication Systems (USA) — Strengths: strong integrations with leading EHR patient engagement modules. Strategic implication: for hospital systems where EHR-embedded patient experiences are prioritized, vendors with proven EHR connectors reduce integration risk and shorten time-to-value.
-
ClinicAll (Canada) — Strengths: platforms that blend entertainment with communication and operational workflows. Strategic implication: vendors offering configurable UX and a portfolio of clinical engagement features will win pilots and scale across wards.
-
Teguar (USA) — Strengths: rugged, MIL-STD-oriented hardware and capacitive touch. Strategic implication: in high-acuity or transportable-use cases (e.g., emergency, mobile carts), ruggedization and durability are differentiators.
-
Advantech (Taiwan) — Strengths: recognized medical-grade bedside tablets and recent Android Enterprise Recommended certification that streamlines device management in hospital IT environments (certified late 2025). Strategic implication: standardization of update and management protocols materially reduces TCO and is a procurement-winning attribute.
-
Barco NV (Belgium) — Strengths: advanced visualization and differentiated experiences (e.g., glasses-free 3D). Strategic implication: specialty deployments (surgical suites, high-end patient education) can justify premium UX spend when tied to clinical outcomes.
-
Lincor Solutions (Canada) — Strengths: EHR connectivity and patient engagement services. Strategic implication: providers seeking a single-vendor software/hardware procurement path may favor integrated service providers who can deliver both content and endpoint management.
-
Saintwaytech & Hitekon (China) — Strengths: competitive pricing, rapid product variants, antimicrobial touch surfaces, and Android/Linux options. Strategic implication: regional deployments and price-sensitive procurements will look to these suppliers; however, buyers must balance unit-price advantages against validation and long-term support risk.
Recent vendor and market signals
-
Advantech’s Android Enterprise Recommended certification for a medical-grade tablet (Nov 2025) signals greater IT-friendliness and a lower lifecycle management burden for large hospital networks.
-
BEWATEC’s expanded rollouts of its VITOS bedside terminals following organizational consolidation events are indicative of M&A-driven scale and platform integration strategies gaining traction among incumbents.
-
Regulatory reminders from multiple vendors underscore that UL/IEC/ANSI medical safety certifications and registered manufacturing remain mandatory design constraints—organizations must budget for conformance validation early in the product roadmap.
Practical 2026 playbook — what executives should do now
-
Prioritize integration pilots over feature pilots. Run end-to-end trials that include EHR integration, device management, cybersecurity verification and clinician workflow tests. Short pilots that only test streaming content will not reveal integration costs.
-
Require a lifecycle TCO model from vendors. Ask for 5–7 year scenarios that include security patching, warranty, spare-part logistics and upgrade paths; compare them on normalized net-present-value terms rather than unit price alone.
-
Lock in regulatory proof points. For public tenders and larger systems, demand evidence of relevant safety certifications and manufacturing registrations up front; vendor prequalification should include certification artifacts and a vulnerability response SLA.
-
Design modular procurement. Specify modular hardware and standardized APIs so that entertainment, telehealth and clinical modules can evolve independently of the display hardware.
-
Consider hybrid sourcing. Combine global suppliers for core clinical-grade endpoints with regional OEMs for non-critical deployments to balance cost, speed and risk.
-
Embed outcome measurement. Negotiate pilots and rollouts tied to measurable KPIs—patient satisfaction, readmission rates for specific cohorts, nursing time saved—and use those KPIs to unlock subsequent deployment tranches.
What the full PW Consulting report delivers (practical contents)
-
Robust forecasting model (2026–2032) with scenario sensitivity, and explicit assumptions so procurement teams can rerun models under their own pricing, replacement cycles and site counts.
-
Vendor scorecards and capability matrices covering certifications, integration footprints, device-management support, upgrade paths and commercial models.
-
Procurement-ready RFx language, a compliance checklist (certification and privacy), and a 90-day pilot protocol template with suggested KPIs, data collection plans and go/no-go gates.
-
Investment and M&A lenses that surface likely consolidation targets, strategic fit assessments and upside synergies for acquirers.
-
Deployment economics templates—TCO calculators that incorporate hardware, software, staging, integration and ongoing support.
Final perspective — the strategic insight in one line
Infotainment terminals are no longer a bedside luxury; they are an operational and clinical integration point whose selection determines cost, cybersecurity posture, and patient experience for the next hardware cycle. The market momentum (with an 8.5% CAGR through our forecast window) rewards vendors who can prove both clinical interoperability and IT manageability, while buyers who demand lifecycle transparency and certified endpoints will avoid hidden costs.
Next step
This preview highlights the strategic questions and directional data executives must confront in 2026. For the full segmentation, vendor scoring, and actionable RFx materials that operational teams need to execute, access the complete PW Consulting Patient Infotainment Terminal Market report and the accompanying toolkit available on our website. The detailed breakdowns—including site-level adoption scenarios, vendor share analysis, and procurement templates—are intentionally reserved for the full publication to support your team’s tactical deployment and capital planning.
For detailed analysis of this topic, please visit the official page: Patient Infotainment Terminal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com