

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Shirting Fabrics Market to Grow at 5.9% CAGR Through 2032

Shirting Apparel Fabrics Market — Strategic Outlook for 2026
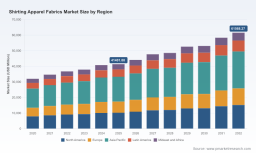
As corporate planning cycles turn toward mid‑decade execution, supply‑chain managers, sourcing leads, product strategists and private equity sponsors face a pivotal question: how will the shirting fabrics market evolve and what concrete actions should be taken in 2026 to protect margin, secure supply and capture growth? PW Consulting’s latest Shirting Apparel Fabrics Market study — rooted in historic performance (2020–2025) and forward forecasts through 2032 — provides a pragmatic compass. The market expanded from roughly USD 32,000 million in 2020 to about USD 41,400 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.9% through the 2026–2032 forecast window, reaching an anticipated total above USD 61,500 million by 2032. This trajectory confirms both resilience and opportunity, but also signals strategic inflection points for 2026 decision‑making.
Shirting Apparel Fabrics Market
What this study delivers — applied intelligence, not just numbers
-
Actionable market sizing and forecasting: granular top‑line modeling calibrated to recent shock events and policy shifts so teams can convert percentage growth into procurement and revenue targets for 2026 planning cycles.
Shirting Apparel Fabrics Market -
Value‑chain diagnostics: detailed mapping from fiber sourcing through finishing and cut‑make‑trim, highlighting where margin pools are widening or compressing and where near‑term operational interventions unlock the most value.
Shirting Apparel Fabrics Market -
Supplier benchmarking and playbooks: comparative profiles and operating levers for leading mills and integrated suppliers, plus negotiation templates and commercial KPIs to accelerate shorter supplier onboarding cycles.
-
Risk and compliance matrices: regulatory, tariff and sustainability risk assessments with mitigation blueprints calibrated for real‑world 2026 scenarios.
-
Go‑to‑market and product innovation pathways: practical roadmaps for launching differentiated shirting lines (premium, performance, sustainable) with pricing, margin and channel implications modeled across plausible demand scenarios.
Key dynamics shaping 2026 decisions
-
Policy and tariff volatility. The apparel import tariff environment has become materially more uncertain. Notably, the average U.S. apparel import tariff rate surged to a record high in late 2025, creating immediate commercial and strategic consequences for importers, brand sourcing desks and ODM partners. Procurement teams must now build tariff‑aware sourcing models and contract clauses that explicitly convert tariff volatility into hedged pricing or contingency cost allocations.
-
Accelerating sustainability standards. Global standards bodies and industry consortia updated chain‑of‑custody and product standards in 2025–2026. New requirements for organic, recycled and responsibly sourced inputs are shifting capital and operating spend into traceability, testing and supplier onboarding — all of which have near‑term cost and long‑term brand value implications.
-
Product specification governance. Technical standards and performance specifications remain central to risk control. ASTM and equivalent standards continue to be touchstones for product teams, and the evolving standard set is influencing supplier acceptance criteria, lab testing cadence and warranty exposure for brands.
-
Demand polarisation and channel shift. Consumer demand is bifurcating between accessible ready‑to‑wear shirting and premium, sustainable offerings. Retailers and brands that can translate technical fabric attributes into clear consumer value narratives will capture disproportionate share; those that cannot will face margin compression from price competition and inventory risk.
-
Supply‑side modernization. Investment in finishing technologies, digital sampling and near‑sourcing is changing lead‑time economics. Suppliers with deeper integration across spinning, weaving and finishing — or with strategic partnerships to guarantee fabric feedstock — will disproportionately benefit in a market where agility becomes a competitive advantage.
Competitive landscape — incumbents, challengers and what they signal for 2026
The market displays mid‑level concentration: the top three suppliers account for a meaningful share of industry shipments, and the top five consolidate a larger majority — a structure that supports both scale advantages and partnership opportunities. This concentration pattern creates predictable supplier power dynamics but still leaves room for agile specialists and vertically integrated entrants to capture niche premiums.
-
Acorn Fabrics (UK) — a heritage mill focused on premium cotton and linen shirtings that sells directly to designers and end customers. Their model underscores the commercial value of brand‑led mill positioning and high‑margin D2C channels for premium shirting.
-
Esquel Group (Hong Kong) — an integrated player supplying global brands with both fabrics and finished apparel. Esquel’s strength is end‑to‑end control and close OEM partnerships, which provide resilience against open‑market raw material swings and tariff shocks.
-
Raymond Group and Arvind Limited (India) — large‑scale, vertically integrated manufacturers that combine cotton input control with extensive finishing capacity. Their scale supports competitive pricing for both formal and casual shirting while enabling rapid capacity reallocation.
-
Hebei Gaibo Textile (China) — a specialist in polyester blends and workwear shirting fabrics, representing the continued importance of synthetics in cost‑sensitive segments and institutional contracts (uniforms, workwear).
-
Ranjini Textiles (India) and TAL Apparel (Vietnam) — examples of differentiated supply strategies: Ranjini leverages heritage yarn‑dyed craftsmanship for niche designers, while TAL combines garment manufacturing scale with dedicated fabric supply, reducing negotiation friction for apparel brands.
For 2026 planning, the strategic lesson is clear: scale and integration confer protection against input and policy shocks, but differentiation and speed to market create pockets of outsized margin. Partnerships and JVs remain highly effective means for brands to secure capacity without ceding margin.
Strategic implications and recommended actions for 2026
-
Re‑segment suppliers by strategic value: move beyond cost‑per‑meter to a triage approach — strategic (capacity, quality, innovation), tactical (cost, fill rate) and transactional (spot buys). Allocate relationship management resources and contractual protections accordingly.
-
Model tariff scenarios into sourcing decisions: develop three tariff scenarios (baseline, moderate shock, and structural shock) and run P&L sensitivity for each major sourcing corridor. Embed tariff pass‑through clauses in new contracts and adopt financial hedges where practical.
-
Prioritise compliance and traceability investments: in markets where sustainability claims drive premium placement, invest in digital traceability pilots, audit roadmaps and supplier capability uplift to secure certification faster than competitors.
-
Shorten the commercialization loop: accelerate digital sampling and micro‑production runs to reduce time‑to‑market for new shirting collections. Faster validation cycles lower inventory risk and support premium pricing for differentiated technical or sustainable fabrics.
-
Pursue strategic partnerships, not just spot buying: where scale is constrained, prefer capacity reservation agreements, JV arrangements for local finishing, or minority investments in mills that have unique capability sets (e.g., specialty weaves, finishing technologies).
-
Embed scenario triggers into 2026 OKRs: define trigger points (e.g., sustained tariff levels, raw material price thresholds, certification lead times) that prompt pre‑authorized actions so teams can move from analysis to execution without bureaucratic delay.
How to use this research in your 2026 planning cycle
-
90‑day triage: use the report’s supplier scorecards and risk matrices to reclassify top suppliers, update contractual terms and establish contingency inventory buffers for high‑risk SKUs.
-
6–12 month execution: pilot near‑sourcing initiatives, implement traceability pilots with priority suppliers, and launch a pricing playbook that internalises tariff scenarios and sustainability premiums.
-
18–36 month structural changes: consider capacity investments, vertical partnerships, or targeted M&A to secure long‑term feedstock, finishing capability and technical fabric IP aligned with forecast demand profiles.
Why PW Consulting’s Shirting Fabrics report matters
This study is built to be operational. It translates a forecasted 5.9% CAGR and multi‑year market expansion into the concrete decisions procurement, product and corporate development teams must make in 2026. We combine macroeconomic scenario work, policy monitoring, supplier benchmarking and pragmatic playbooks so that your 2026 planning process is driven by defensible intelligence, not guesswork.
Importantly, this overview is a strategic trailer: it demonstrates the report’s analytical depth and the immediate value you can extract, while reserving the full, segment‑level forecasts, granular regional breakdowns, company scorecards and contract templates for the full report. If your organisation is preparing budgets, vendor agreements, or M&A screens for 2026, the full dataset and executable templates in the report will materially reduce implementation time and execution risk.
For teams that need to move from insight to action this quarter, the recommended next step is straightforward: run the report’s supplier reclassification exercise, stress‑test your top SKUs against the tariff sensitivity models and pilot one traceability upgrade with a strategic supplier. These three moves alone will re‑orient many organisations from reactive cost control to proactive, profitable growth in the evolving shirting fabrics market.
For detailed analysis of this topic, please visit the official page: Shirting Apparel Fabrics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com