

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Computer Consulting Services Market to Expand from USD 865.0 Billion in 2025 to USD 1.50 Trillion by 2032 at an 8.2% CAGR — North America Leads with USD 327.7B; Top‑5 Firms Hold 24.1%
By pmarketresearch, 2026-08-12
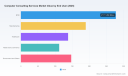
Computer Consulting Services Market 2026: Strategic Imperatives from PW Consulting
PW Consulting’s newest market research release, Computer Consulting Services Market — 2026 Edition, frames a decisive moment for CIOs, procurement chiefs, and private equity investors planning enterprise technology allocations this year. With a robust compound annual growth rate (CAGR) of 8.2% and a global services market that reached an estimated USD 865.0 Billion in our 2025 base year, our analysis projects sustained expansion through 2032 — underlining both scale and the structural shifts reshaping how organizations buy, contract and consume IT consulting services.
Digital Trunking Intercom Market
Why this report matters for 2026 decision cycles
Corporate technology roadmaps for 2026 must confront three simultaneous forces: accelerated adoption of AI and real-time data architectures; intensifying regulatory and operational resilience requirements; and continued pressure on total cost of ownership driven by labor market dynamics. PW Consulting’s study synthesizes these forces into a pragmatic playbook. The report translates macro growth (with a forecasted pathway extending to a projected market north of USD 1.5 Trillion by 2032) into tangible, time-bound actions — enabling leaders to prioritize investments that preserve optionality while capturing near-term value.
Totem Pole PFC Market
What the research reveals (high level)
- Market momentum is structural, not cyclical: the services market has expanded markedly since 2020 and our base-year analysis shows continued year-on-year growth into 2026 and beyond.
- Vendor ecosystems are expanding around data, cloud and AI platforms. Strategic M&A, platform plays and managed offerings are re-shaping competitive advantage — creating new choices but also new integration and governance imperatives for buyers.
- The provider landscape remains fragmented. Top-tier firms capture a meaningful share, yet overall concentration is moderate (our concentration analysis shows a three-firm and five-firm share that underlines available room for specialist players and new entrants).
- Regulation and labor cost trends are now first-order considerations in vendor selection, contract design, and sourcing strategy.
Practical content inside the report
This is a practitioner’s report designed to inform active procurement and strategy decisions in 2026. Core deliverables include:
AI Tool for Aviation Market
- Proprietary market-sizing and forecast model (historical 2020–2025, forecast 2026–2032) with scenario lanes for macro, technology adoption and regulatory shock events.
- A vendor assessment framework with scored dimensions for capability depth, delivery footprint, platform partnerships, IP controls, pricing models and migration velocity.
- Go-to-market playbooks and procurement templates tailored for enterprise buyers — including phased engagement models (proof-of-concept → scale → run), outcome-based contracting clauses, and performance SLAs mapped to business outcomes.
- Technology adoption timelines and capability roadmaps for AI, hybrid cloud, real-time data streaming, and cybersecurity, highlighting typical adoption lags, integration costs and break-even horizons.
- Risk registers and regulatory compliance checklists that align operational controls with the latest rules affecting IT service providers and their clients.
- Financial impact tools: TCO comparators, build-vs-buy calculators and vendor selection decision trees calibrated to industry archetypes.
To preserve strategic value, the report intentionally reserves granular regional and subsegment-level revenue tables for the full release. Readers looking to obtain deep segmentation, vendor-specific revenue splits, and downloadable model files should refer to the report subscription page.
Competitive landscape — how leading firms are positioning in 2026
The report profiles incumbent global firms and highlights how each is adapting to the era of AI, cloud-native architectures, and elevated resilience requirements. High-level takeaways:
- Accenture remains the archetypal integrator: broad industry reach, deep transformation practice, and aggressive investment in cloud, AI and industry cloud platforms. Its emphasis on outcome-oriented delivery makes it a frequent partner for large-scale modernization programs.
- IBM Consulting is doubling down on real-time data and hybrid cloud capabilities. A major strategic step in 2026 was the completion of a transformational acquisition to bolster real-time streaming and enterprise AI workflows — a capability set that materially alters turnkey options for clients building event-driven architectures.
- Deloitte continues to blend traditional consulting excellence with technology modernization services, focusing on enterprise systems modernization, cybersecurity and risk advisory — attractive for highly regulated sectors.
- Capgemini and other engineering-led firms are leveraging strong domain engineering capabilities and industry-specific IP to win complex digital engineering and cloud migration engagements.
- Tata Consultancy Services, Cognizant, Infosys and Wipro maintain scale advantages in global delivery, hybrid sourcing models and broad platform partnerships, enabling cost-competitive, rapid delivery for extensive transformation programs.
Collectively these providers define the strategic “shelf” from which most large enterprises will procure services. Yet our market-concentration analysis shows meaningful headroom for specialized firms and new entrants to capture value in niche verticals and emerging capabilities.
Recent developments shaping 2026 strategy
- Strategic M&A has accelerated platform consolidation and capability stacking across consulting leaders. Notably, a leading global consulting firm completed a high-profile acquisition in early 2026 to secure real-time data streaming and enterprise AI orchestration capabilities — a deal with significant implications for how clients source streaming architectures and agentic AI solutions.
- Smaller scale strategic acquisitions continue to re-bundle managed services, cybersecurity, and regional delivery capabilities — enabling acquirers to rapidly fill capability gaps without multiyear organic build plans.
- Regulatory milestones (described below) and ongoing labor-market pressures are driving buyers to re-evaluate risk allocation in contracts and to build stronger compliance and audit capabilities into sourcing decisions.
Regulation, labor and resilience: non-negotiable variables for 2026
Two regulatory changes and labor-market forces demand special attention in 2026 planning:
- The EU’s Digital Operational Resilience Act (DORA) has come fully into force and now applies to financial institutions and relevant ICT service providers, raising the bar for operational risk management, testing regimes and supplier oversight. Enterprises operating in, or serving, the EU must re-baseline vendor due diligence and contractual compliance clauses.
- U.S. regulatory measures governing bulk sensitive personal data transactions have expanded compliance obligations for relevant systems and providers, increasing the need for technical controls and forensic record-keeping across service deliveries.
- On the labor side, salary inflation pressures continue to bite. Average increases across technology roles are modest but meaningful; specialized skills in AI/ML and data engineering are commanding outsized premium growth compared with general IT roles. These dynamics influence near-term project costing, retention strategies and the attractiveness of managed or outcome-based contracts.
What this means for enterprise buyers — five prioritized actions for 2026
- Re-balance vendor portfolios to manage integration and regulatory risk: favor modular contracts that allow rapid substitution of components (platform, implementation partner, and managed services) without vendor lock-in.
- Price in talent premium and design for skill obsolescence: include reskilling clauses, success-based milestones and supplier retention incentives where AI and data-science expertise are central to outcomes.
- Adopt hybrid contracting models that shift more upside to outcome metrics: clients should pilot outcome-linked pricing in greenfield or low-risk domains and expand as measurement fidelity increases.
- Embed resilience and compliance KPIs into procurement checklists: require evidence of regulatory program maturity, third-party testing and incident response readiness as part of standard RFP evaluations.
- Use scenario-based forecasting to stress-test plans: leverage the report’s scenario lanes to assess implications of accelerated AI adoption, protracted supply constraints or regulatory escalations on program timing and economics.
Methodology and rigor
PW Consulting’s market model is built on a blend of bottom-up vendor analysis, top-down macro drivers, primary interviews with vendor and buyer executives, and triangulation against public filings and proprietary engagement data. Historical series cover 2020–2025, with forward-looking forecasts for 2026–2032 across three market scenarios. The report includes downloadable model worksheets for licensed clients, enabling customized sensitivity analysis aligned with a buyer’s industry, geography and technology focus.
How to use this report in your 2026 planning
Leaders planning budgets and procurement in 2026 should use this study as both a risk matrix and a prioritization instrument. The document converts large-scale market growth forecasts into recommended investment horizons, vendor engagement sequencing, and contract design patterns that reduce integration risk while preserving upside participation in AI and cloud modernization value pools.
Because the most valuable parts of the analysis are the tactical tables, vendor scorecards and downloadable financial models, PW Consulting has structured this release as a “strategic preview.” The preview demonstrates our evidence-based approach and the direction of travel without disclosing all segment-level ratios and provider revenues — encouraging investors and enterprise buyers to access the full report for operationalized intelligence.
Next steps
- Download the full report and model package from PW Consulting’s report page to obtain segment-level forecasts, vendor revenue splits, and industry-specific playbooks.
- Schedule a briefing with our senior advisors to translate findings into a one-page action plan tailored to your organization’s 2026 budget cycle.
- Engage our vendor due diligence service to validate proposed provider selections against compliance, resilience and delivery-readiness criteria.
In an environment where technology-driven advantage increasingly depends on data velocity, resilience and talent orchestration, the choices made in 2026 will compound through the decade. PW Consulting’s Computer Consulting Services Market — 2026 Edition equips leaders with the foresight and practical tools to convert market growth into defensible, measurable outcomes.
For detailed analysis of this topic, please visit the official page: Computer Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide WIPS Market to Surge from USD 1,245.5 Million in 2025 to USD 3,155.06 Million by 2032 at a 14.2% CAGR
By pmarketresearch, 2026-08-12
Worldwide WIPS Market 2026: Strategic Imperatives for Enterprises — Preview of PW Consulting’s In-Depth Analysis
As organizations accelerate digital transformation, wireless networks have evolved from peripheral convenience to mission-critical infrastructure. Our new PW Consulting market brief for the Worldwide Wireless Intrusion Prevention System (WIPS) market synthesizes five years of historical performance and a forward-looking forecast through 2032 to equip C-suite and security leaders with the strategic intelligence required to act decisively in 2026. This preview highlights the market’s macro trajectory, regulatory and technology catalysts, competitive dynamics, and the practical playbook contained in the full report — while intentionally withholding granular segment tables to preserve the incentive to consult the primary research for procurement-level decisions.
Worldwide Heavy Duty Diesel Engine Oils Market
Market Trajectory at a Glance
The WIPS market has transitioned from a niche control measure to a scalable security capability tightly coupled to enterprise networking strategies. Between 2020 and 2025 the market expanded rapidly, and by our base year (2025) the global WIPS market exceeded the billion-dollar threshold. Looking forward, our model forecasts a sustained compound annual growth rate (CAGR) of approximately 14.2% during the 2026–2032 forecast window, culminating in a multi‑billion dollar opportunity by 2032. These high-level metrics frame three core strategic realities for 2026 decision-makers:
5-leg IV Stand Market
- WIPS is now a board-level risk consideration rather than a point security control.
- Technology convergence — between WLAN, cloud management, and security analytics — amplifies the value of integrated vendor platforms.
- Regulatory mandates and spectrum expansion are accelerating demand for continuous wireless monitoring and active prevention.
Why This Matters for 2026 Strategic Decisions
For security executives planning budgets, procurement cycles, or network architectures in 2026, the WIPS market’s trajectory has direct implications for three decision domains:
Worldwide Big Data Marketing Market
- Risk Prioritization and Compliance: Mandatory and advisory regulations introduced across payments, healthcare, and critical infrastructure now explicitly reference wireless monitoring and intrusion controls. Organizations facing PCI DSS, HIPAA-related guidance, NIS2 obligations, or government compliance frameworks must operationalize WIPS capabilities as part of their control baselines — not as optional add‑ons.
- Architecture and Procurement Timing: With cloud-enabled management and AI-enhanced detection maturing rapidly, the optimal procurement window hinges on defining desired outcomes (detection accuracy, latency of mitigations, integration with SOAR/SIEM) rather than simply buying the lowest-cost appliance. Our forecast suggests that delaying modernization may increase integration costs as organizations move from bolt-on approaches to platform consolidation.
- Operational Models and Skillsets: Continuous spectrum monitoring, device fingerprinting, and automated mitigation require updated operational playbooks. Security operations centers should plan for tighter collaboration with networking teams and invest in telemetry, analytics, and incident playbooks that include wireless-specific use cases.
Regulatory and Technology Tailwinds
The WIPS market is being pulled by a combination of regulatory mandates and technological enablers. Recent regulatory shifts — including the full enforcement of PCI DSS 4.0 requirements for wireless controls, updated guidance under HIPAA frameworks, and the implementation of NIS2 in Europe — elevate wireless monitoring from best practice to compliance requirement for organizations that manage sensitive data or operate as essential services. Meanwhile, spectrum policy changes (notably expanded indoor use of the 6 GHz band) and the roll‑out of Wi‑Fi 6/6E increase RF complexity and the need for sophisticated spectrum awareness.
Technologically, the market is maturing along three vectors:
- Integrated Platform Approaches: Vendors are embedding WIPS capabilities into WLAN infrastructure and network security platforms to reduce operational friction and improve mitigation velocity.
- Cloud Management and Analytics: Cloud-native orchestration and AI/ML analytics are improving anomaly detection and reducing false positives, enabling faster, more reliable automated responses from centralized consoles.
- Standards and Certification: Government-led certification efforts for secure wireless monitoring are lowering procurement friction for public sector buyers and setting higher assurance expectations across critical sectors.
Competitive Dynamics — What Leading Vendors Are Doing
The competitive landscape is characterized by platform incumbents extending wireless security into their networking portfolios and specialized vendors innovating with cloud-first architectures and patented detection methods. Market concentration is moderate: a handful of major vendors capture a meaningful share of market value, but there remains space for niche innovators and systems integrators to differentiate on deployment model, detection accuracy, and managed services.
Key vendor trends we observed:
- Network Infrastructure Leaders: Established networking vendors are strengthening WIPS through integration with their wireless access portfolios and management controllers. Expect continued emphasis on end-to-end visibility and orchestration between access layer and security controls.
- Security Platform Consolidation: Traditional security vendors are integrating wireless threat prevention into broader security platforms, aiming to deliver unified policy and incident response across wired and wireless perimeters.
- Cloud-Native and Access-Point Innovation: Cloud-managed WIPS offerings and access points with embedded detection mechanisms are gaining traction, particularly where low operational overhead and rapid scaling are priorities.
Representative vendor activity includes product enhancements focused on AI-driven anomaly detection, ongoing feature updates to embedded WIPS modules in enterprise WLAN portfolios, and government-oriented certification work that raises assurance baselines. These movements underscore the market’s dual shift toward cloud-driven analytics and regulatory-grade assurance.
What the Full Report Provides (Practical, Actionable Content)
PW Consulting’s full research deliverable is designed as a decision-support tool for CISOs, procurement teams, network architects, and vendor strategists. The report contains:
- Comprehensive market sizing and a seven-year forecast with scenario sensitivity analysis to help you stress-test procurement and budget assumptions.
- Vendor profiles and comparative capability matrices mapping detection techniques, mitigation options, integration touchpoints, and enterprise-grade management features.
- Regulatory impact analysis translating compliance requirements into implementation checklists and control baselines for key sectors.
- Deployment playbooks that cover on-premise, hybrid, and cloud-centric operational models — including staffing, telemetry requirements, and incident playbooks tailored to wireless threats.
- Procurement frameworks and RFP templates to accelerate vendor selection while ensuring alignment to desired security outcomes rather than feature checklists.
- Risk-quantified ROI models that help you compare lifecycle costs of retrofit WIPS versus integrated platform approaches under multiple threat and compliance scenarios.
Note: this preview intentionally refrains from reproducing granular segment and regional breakdowns. The full report contains detailed tables and appendices that are essential for vendor short-listing and budget approvals.
Strategic Recommendations for 2026
Based on our analysis, PW Consulting recommends the following pragmatic steps for organizations formulating WIPS strategies in 2026:
- Map WIPS to Business-Critical Assets: Prioritize deployment where cardholder, healthcare, or operational technology traffic terminates. Use a risk lens to sequence rollout and then expand coverage iteratively.
- Favor Integrated Detection and Response: Assess vendors on their ability to integrate wireless telemetry into broader security operations and automation platforms to reduce mean time to detect and respond.
- Plan for Spectrum Complexity: Include spectrum monitoring capabilities and RF analytics in procurement requirements to ensure visibility across legacy and new frequency bands.
- Adopt a Compliance-First Baseline: Align WIPS implementations with applicable regulatory frameworks to avoid remediation costs and penalties; document controls to streamline audits.
- Consider Managed and Co-Managed Models: Where in-house skill gaps exist, evaluate managed WIPS or co-managed options to accelerate time-to-protection while transferring operational overhead.
For Vendors and Investors
Vendors should prioritize interoperability, explainable AI for detection confidence, and simplifying deployment footprints. Investors can look for scale-ups that combine high-fidelity detection with low operational false-positive rates, or service providers that offer turnkey managed WIPS with compliance guarantees. Market concentration indicates meaningful opportunity for both established incumbents to expand share and for specialized innovators to capture vertical pockets where unique capabilities (e.g., government certifications or patented detection methods) create defensible differentiation.
Conclusion — How to Use This Preview
WIPS is now a central component of enterprise security posture and compliance strategy. Our forecast and market analysis demonstrate sustained, above-market growth driven by regulatory mandates, wireless technology shifts, and vendor innovation. This preview provides the strategic context and high-level implications that should inform 2026 planning cycles; the full PW Consulting report delivers the actionable segmentation data, vendor comparisons, and procurement tools you will need to operationalize these insights.
To access the detailed segment tables, vendor matrices, and deployment playbooks that underpin the recommendations in this preview, please consult the full Worldwide WIPS Market report — it is designed to be the operational manual for your 2026 wireless security roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Wireless Intrusion Prevention System (WIPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 18.24% CAGR for Worldwide Battery Manufacturing Software Market — Rapid Expansion Expected Through 2032
By pmarketresearch, 2026-08-12
Worldwide Battery Manufacturing Software Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to introduce our latest market research brief: the Worldwide Battery Manufacturing Software Market. Built on a rigorous historical baseline (2020–2025) with a declared base year of 2025 and a forward-looking forecast window of 2026–2032, this study translates fast-moving technological, regulatory and operational dynamics into actionable guidance for executives planning capital and product strategies in 2026.
Worldwide Cloud Computing Chips Market
Market Trajectory: A Macro View You Can Act On
Battery manufacturing software is in a sustained expansion phase. In monetary terms (USD, revenue unit: Million), the market expanded from roughly 510.45 in 2020 to 1,127.29 in our base year of 2025. Our forecast projects continuation of this momentum into the coming decade — with the market crossing the mid-thousands by 2032. The compound annual growth rate for the forecast window stands at 18.24%, reflecting accelerated adoption across gigafactories, cell pilot lines, EV supply chains and utility-scale storage projects.
Worldwide Organic Tableware Market
This macro-scale growth is not abstract: it directly influences supplier selection, capital planning, digital transformation sequencing and workforce strategy. The numbers embedded in this report equip leaders to size near-term budgets, stress-test multi-year roadmaps and build procurement clauses that align software delivery with production ramp milestones.
Basic Travel Insurance Market
Why 2026 Is an Inflection Year
- Regulatory urgency: New compliance regimes — notably the EU battery passport and associated requirements for carbon-footprint declarations and component traceability — become increasingly binding within the next two years. For large manufacturers, this drives mandatory investments in traceability and data sovereignty capabilities.
- Policy-driven onshoring: Public incentives and industrial policy have already catalyzed a dramatic increase in domestic battery output in key markets. This rapid onshoring amplifies the need for interoperable software stacks that can be integrated across newly built gigafactories.
- Operational leverage: Empirical industry studies show targeted digitalization use cases — from predictive quality to traceability automation — can materially lower staffing needs and reduce energy and material waste. Energy-tracking and optimization alone can deliver sizeable reductions in consumption at discrete process stages, while predictive approaches significantly reduce startup scrap and ramp-time losses.
- Cyber and data risks: Connected manufacturing environments for batteries require explicit compliance with cybersecurity frameworks and cryptographic standards; secure communications and update mechanisms are no longer optional.
What the Report Delivers — Practical, Executable Intelligence
This research is designed as a decision-support tool for CXOs, product leaders, plant managers and procurement teams. Our deliverables emphasize operational utility over academic completeness; in other words, we show you how to act.
- Market sizing and scenario forecasts: Detailed top-line sizing for historical and forecast periods (2020–2032), with stress-tested scenarios that reflect variation in capex cycles, policy shifts and EV demand trajectories.
- Buyer-focused playbooks: Use-case driven procurement templates and RFx language that translate desired KPIs (yield, energy intensity, traceability latency, cybersecurity posture) into contract milestones and acceptance tests.
- Implementation roadmaps: Stepwise deployment blueprints for MES/MOM, digital-twin and analytics rollouts across pilot, scale-up and gigafactory stages — including suggested pilot metrics and governance models.
- ROI and TCO modeling: Financial templates to evaluate build-vs-buy, capex/OPEX tradeoffs, and payback timing under different yield and energy-saving scenarios.
- Vendor scorecards and gap analyses: Qualitative and quantitative assessments of incumbent and specialist software vendors across capability dimensions — from traceability and quality management to AI-driven analytics and edge/cloud architectures.
- Regulatory and cybersecurity checklists: Practical checklists and control mappings against contemporary standards and requirements — for example, guidance that aligns traceability workflows with forthcoming battery passport rules and cybersecurity controls based on recommended standards for connected manufacturing.
- Data architecture patterns: Reference designs for secure, scalable data flows (edge ingestion, canonical data models, lineage, and cloud-analytic pipelines) that prioritize interoperability and vendor portability.
- Case studies and playbooks: De-identified case studies that show how leading adopters compressed ramp times, reduced scrap and improved first-pass yield through specific software configurations and organizational changes.
To preserve competitive sensitivity of our clients and to respect commercial confidentiality within vendor contracts, the report intentionally avoids publishing vendor-specific pricing schedules or granular account-level contract terms. Detailed segmentation tables and proprietary model outputs are available in the full report for registered users.
Competitive Landscape — Who Is Shaping Solutions Today
The vendor ecosystem combines large industrial-software incumbents, controls-and-automation leaders, and nimble analytics specialists. Each group brings different strengths: scale and integration breadth on one hand, focused analytics and fast iteration on the other.
- Industrial incumbents and automation leaders: Companies such as GE Vernova, Siemens, Rockwell Automation, ABB and Panasonic Connect provide broad MES/MOM portfolios and deep integration with plant automation stacks. Their value proposition centers on end-to-end production visibility, quality governance, and standardized process planning, all critical for gigafactory-scale operations.
- Enterprise analytics and battery-specialist vendors: Firms like Voltaiq, PDF Solutions and Energsoft offer targeted analytics platforms that span R&D through manufacturing, enabling data-driven failure-mode identification and predictive quality control that complement MES capabilities.
- Modular and AI-focused players: camLine (Elisa IndustrIQ) and others supply MES/MOM variants with strong traceability and AI-driven process controls — attractive for manufacturers who want faster time-to-value and modular implementations.
Recent product launches underscore strategic positioning across the ecosystem: Honeywell’s Battery Manufacturing Excellence Platform (Battery MXP) — an AI-enabled solution introduced in mid-2024 — targets yield improvement and ramp compression. Panasonic Connect’s Syncora platform, announced in late 2024, is positioned to accelerate MES-driven digital transformation in nascent domestic production hubs. These developments point to intensified competition around AI-driven optimization and full-stack MES offerings.
Strategic Priorities and Technology Imperatives for 2026
- Traceability and data sovereignty: Build architectures that can satisfy compliance regimes (battery passports and similar disclosures) while protecting IP and sensitive process data.
- Modular MES integration: Prioritize vendors who support phased rollouts and open APIs to avoid lock-in and enable best-of-breed analytics overlays.
- AI for yield and energy: Deploy analytics that address both quality (reducing scrap and improving cell yields) and energy optimization — use cases with clear, measurable ROI.
- Cybersecurity by design: Adopt secure communication standards and update mechanisms (strong encryption, mutually authenticated TLS channels, and secure firmware/update flows) aligned to industry recommendations.
- Workforce and process change management: Combine automation with reskilling programs; quantify labor cost exposure and design automation projects that deliver measured headcount and efficiency gains.
- Pilots with KPI discipline: Execute short-cycle pilots with clearly defined acceptance criteria (yield delta, ramp-time reduction, MTTR improvements) to de-risk scale deployments.
How Executives Should Use This Report in 2026
- Use the market forecast and scenario outputs to justify multi-year software budgets and align them to production-capacity milestones.
- Run vendor shortlists through the supplied scorecards and RFx templates to capture contractual protections tied to production KPIs.
- Adopt the report’s ROI models to compare automation investments across cell lines and facility expansions, integrating energy and labor-savings assumptions.
- Leverage the regulatory and cybersecurity checklists to accelerate compliance readiness and reduce audit exposure ahead of mandated regimes.
- Prioritize pilots that combine MES/MOM, process analytics and digital-twin capabilities to deliver measurable ramp and yield outcomes within 6–12 months.
Conclusion — A Teaser for Deeper, Transactional Intelligence
The Worldwide Battery Manufacturing Software Market is transitioning from niche digital projects to central pillars of factory economics and regulatory compliance. With the market expanding rapidly — following an 18.24% CAGR over the forecast period and a multi-fold increase in absolute market size between 2020 and 2032 — the decisions you make in 2026 will determine whether your software choices accelerate or constrain production, compliance and margin outcomes.
PW Consulting’s full report contains the granular segmentation, vendor benchmarking matrices, contract language templates and detailed scenario model outputs that support procurement, investment and M&A decisions. To access the complete data tables and our executable toolkits (including per-solution implementation playbooks and sample RFx documents), please visit the report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Battery Manufacturing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Tilt & Turn Window Handles Market Set to Expand at a 5.23% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Handles of Tilt & Turn Windows Market — Strategic Briefing for 2026 Decision-Makers
Executive preview
As PW Consulting’s lead industry analyst, I present a targeted strategic briefing drawn from our comprehensive Worldwide Handles of Tilt & Turn Windows Market report (base year 2025). The product category—specialised handles and related hardware for tilt & turn windows—sits at the intersection of building energy-performance regulation, materials cost volatility, and accelerating smart-home integration. Our analysis finds the market has recovered from mid‑cycle volatility and is tracking a steady expansion trajectory, underpinned by regulatory retrofit demand and rising preference for durable metal-based hardware. The market size in 2025 was measured at USD 648.5 million and, given current dynamics, we project steady growth at a compound annual growth rate (CAGR) of 5.23% across our 2026–2032 forecast horizon, with long‑term upside if smart‑home and energy retrofits accelerate.
Worldwide Infiltration Marketing Market
Why this briefing matters for 2026 strategic planning
- Pinpointing inflection points: The next 18–36 months will determine winners in both specification‑driven commercial projects and high-volume residential retrofit channels. Companies that move early on energy‑compliant and connected hardware will capture disproportionate share.
- Cost‑to‑value pressure: Manufacturers face higher input costs (notably aluminum) while buyers demand enhanced functionality. Strategic choices on material mix, finish technologies, and supply contracts will materially affect margin outcomes in 2026.
- Consolidation and partnership windows: Industry concentration is moderate—top manufacturers command meaningful but not dominant shares—creating attractive M&A and joint‑venture opportunities for platform expansion or geographic scale.
Market outlook — a data‑led snapshot (high level)
From a macro perspective the handles market shows resilience and structural expansion. After a modest mid‑cycle dip, total market revenue reached USD 648.5 million in 2025. Under our base scenario—reflecting current regulation, construction and retrofit pipelines, and normalised raw‑material inputs—the market grows at a 5.23% CAGR during 2026–2032, reaching an elevated market size by the end of the forecast period. This trajectory reflects steady demand for high‑performing hardware in both new construction and retrofit markets, with periodic acceleration tied to major regulatory milestone years and smart‑home adoption cycles.
Worldwide Productivity Bots Software Market
Dynamics shaping supplier and buyer strategy
- Regulation as demand lever: Updated energy performance standards in major jurisdictions (notably the EU’s EPBD revisions and the UK’s Future Homes/Part L updates) are driving window replacement and specification upgrades. Tilt & turn systems—due to their airtightness, ease of retrofit, and compatibility with advanced locking hardware—are frequently specified in compliance projects.
- Raw‑material volatility: Producer prices for aluminium mill shapes rose materially in 2025 (notable year‑over‑year increases). This has immediate cost implications for metal‑dominant handle portfolios and places a premium on procurement sophistication—longer contracts, metal hedging or strategic alloy substitution where performance allows.
- Material and finish priorities: Aluminum‑based handles continue to gain share where corrosion resistance and weight are priorities; zinc and stainless offerings retain roles where cost or design premium drive selection. Metal finishes and coatings that extend lifespan in coastal or corrosive environments are becoming specification differentiators.
- Smart integration and standards: Smart window hardware is transitioning from niche to mainstream. Recent product launches supporting Matter and robust radio ecosystems create a new vector of value—security, occupant comfort and system‑level energy optimisation. Suppliers who integrate open, cross‑platform connectivity will find easier entry into premium retrofit projects and OEM spec lists.
- Form and fabrication: Trends toward concealed hinges, multi‑point locking and special‑shape window solutions (round tops, trapezoids) are influencing handle design and mounting systems—requiring closer collaboration between handle makers and hardware system suppliers.
Competitive landscape — positioning and implications
The competitive field blends established European system houses with value‑oriented regional suppliers and design‑led premium brands. Market concentration is moderate—top three players collectively hold a meaningful but not overwhelming portion of market sales, leaving room for nimble specialists and regional consolidators.
Worldwide Inorganic Waveplates Market
- HOPPE (Germany) — https://www.hoppe.com
Strengths: Broad design portfolio across multiple series and finishes; strong brand recognition in Europe; integrated security features for tilt & turn. Strategic implication: HOPPE’s design depth makes it a preferred partner for high‑quality residential and bespoke commercial specifications.
- Gretsch‑Unitas (G‑U) (Germany) — https://www.g-u.com
Strengths: Certified hardware meeting EN standards; lockable handle options; engineering focus for modern systems. Strategic implication: G‑U is well positioned for spec‑led projects requiring tested, certified performance—an important differentiator in regulatory procurement.
- MACO (Austria) — https://www.maco.eu
Strengths: Integrated turn & tilt systems for different profile materials; strong OEM and fabricator relationships. Strategic implication: MACO’s multi‑profile capability supports scale through fabrication channels—key for volume growth in retrofit markets.
- Roto Frank (Germany) — https://www.roto-frank.com
Strengths: Focus on aluminium solutions, concealed hinges, and long‑life corrosion performance; recent product updates emphasize design and endurance. Strategic implication: Roto is the go‑to for premium aluminium systems and international manufacturers seeking robust aesthetic and functional solutions.
- Siegenia (Germany) — https://www.siegenia.com
Strengths: Smart handle development and Matter‑ready 2nd generation products; recent FENSTERBAU showcase. Strategic implication: Siegenia’s connectivity roadmap is a blueprint for entrants pursuing smart‑home and retrofit value pools—expect accelerated adoption where installers can upsell connectivity.
- Winkhaus (Germany) — https://www.winkhaus.com
Strengths: High‑performance hardware solutions including concealed hinge options; strong engineering pedigree. Strategic implication: Winkhaus competes strongly on performance features for premium windows and special shapes.
- ASSA ABLOY Fenestration — https://www.assaabloyfenestration.com
Strengths: Global scale, corrosion‑resistant aluminium solutions, and offerings for special shapes. Strategic implication: Benefitting from group scale, ASSA ABLOY targets international OEM channels and specification projects that demand global supply consistency.
- Trojan (UK) — https://www.trojan.co.uk
Strengths: Value and performance for uPVC and common profiles. Strategic implication: Trojan is a go‑to in price‑sensitive segments where installers prioritise reliability and cost control.
- FPL Hardware (US) — https://fplhardware.com
Strengths: Range tailored for tilt‑turn and casement applications; US‑market orientation. Strategic implication: Regionalisation matters—FPL’s portfolio illustrates the advantage of tailoring SKUs to local profile systems and distributor expectations.
- Formani (Netherlands) — https://www.formani.com
Strengths: Design‑led, award‑winning premium handles for architectural projects. Strategic implication: Formani captures premium margins where aesthetics and brand cachet matter, especially in high‑end European retrofits and new build projects.
Recent signals worth watching in 2026
- Siegenia’s launch of a Matter‑version smart handle (Jan 2026) signals a migration to industry standard smart protocols—buyers will increasingly request Matter compatibility in tender documents.
- Roto’s continued promotion of aluminium‑focused tilt & turn systems (2025 updates) highlights ongoing demand for corrosion‑resistant, premium aluminium solutions in international markets.
- Trade show activity (e.g., new products showcased at IBS 2026) indicates suppliers are pushing integrated system narratives—handle + hardware + connectivity—rather than standalone SKUs.
Actionable strategic playbook for 2026
- Procurement and cost management: Lock targeted aluminium volumes under multi‑year contracts where feasible; assess alloy substitution or partial material mix shifts for non‑structural components to protect margin against metal price spikes.
- Product strategy: Prioritise development of energy‑compliant handle assemblies and Matter‑capable smart handles. Invest in robust radio links and cyber‑security certification to reduce installation friction and reassure specifiers.
- Channel and go‑to‑market: Accelerate partnerships with fabricators and window system OEMs. Offer bundled hardware + connectivity packages to installers to increase attachment rates in retrofits.
- Aftermarket and services: Develop retrofit kits and certification packages for energy‑upgrade projects (labelling, testing, and installer training) to capture high‑margin downstream revenues.
- M&A and partnerships: With moderate top‑end concentration, there is strategic logic to bolt‑on acquisitions that fill material, connectivity, or geographic gaps—targeted tuck‑ins can rapidly expand specification reach.
- Regulatory and standards engagement: Proactively engage with certification bodies and standards consortia to ensure product compliance and to influence emerging test protocols for smart window hardware.
What our full report delivers (operational value)
The PW Consulting report goes beyond headline growth to provide decision-ready deliverables for 2026 planning cycles, including:
- Proprietary market sizing and scenario forecasts through 2032 with sensitivity to raw‑material price paths and regulatory accelerants.
- Supply‑chain mapping and a cost‑to‑serve model that isolates procurement levers and margin pressure points.
- Detailed competitor profiles, product matrices, and go‑to‑market playbooks for market entry, expansion, and consolidation strategies.
- Regulatory impact assessment across major jurisdictions and a compliance roadmap for manufacturers and specifiers.
- Commercial tools: pricing frameworks, bundling strategies, and aftermarket monetisation options tailored to manufacturers, distributors and installers.
To respect the role of this briefing as a prelude, we intentionally reserve the granular segment and regional splits, SKU‑level unit economics and modelled price‑elasticity matrices for the full report and interactive dashboard available on our site.
How to use this insight immediately
- Run a 90‑day procurement stress test: model current supplier contracts against a +20% aluminium price scenario and quantify margin exposure.
- Pilot Matter‑capable handle deployments with two installer partners in retrofit projects to validate installation workflows and capture first‑mover premium data.
- Identify one regional M&A target that closes a capability gap (connectivity, coating tech, or fabrication scale) and initiate commercial diligence.
Next steps
PW Consulting’s full Worldwide Handles of Tilt & Turn Windows Market report is the practical resource for teams preparing 2026 budgets, R&D roadmaps, or M&A pipelines. For bespoke briefings, scenario runs, or to access the full dataset and interactive dashboard (including regional and subsegment detail), contact our research team and download the report from the PW Consulting portal. Use the intelligence to convert regulatory and material volatility into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Handles of Tilt & Turn Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Electrical Orchard Sprayer Market to Reach USD 1,000.44 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Electrical Orchard Sprayer Market — Strategic Outlook for 2026 Decision-Making
PW Consulting is pleased to announce the release of our in-depth market research brief on the Worldwide Electrical Orchard Sprayer Market. Built to be immediately usable by executive teams, product leaders, procurement officers and investors, this briefing synthesizes five years of historical performance, a detailed forward-looking model, and practical decision frameworks to guide capital allocation and go-to-market choices in 2026. The analysis demonstrates where value will be created in the next wave of orchard electrification while intentionally reserving core segmentation tables in order to drive clients to the full report for the granular inputs that underpin commercial decisions.
VCSEL Laser Chips Market
Executive snapshot
Electrification of orchard spraying is no longer a pilot-stage curiosity. Our market model values the global market at approximately USD 631.24 Million in the base year 2025 and forecasts growth to about USD 1,000.44 Million by 2032, representing a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. The market has accelerated from the historical period of 2020–2025, driven by advances in battery energy density, autonomy and precision application technologies, and by a faster-than-expected willingness by growers to trade capital expense for operating cost reduction and regulatory compliance.
Worldwide Infrared Transmitting Glass Market
Why this matters for 2026 decision-makers
- Capital allocation: Manufacturers and component suppliers must decide whether to prioritize electrified orchard platforms, hybrid architectures, or modular retrofits. The mid-single-digit CAGR through 2032 signals a growth runway long enough to justify factory retooling, but decision timing will affect margin and market share.
- Technology integration: Battery systems and autonomy stacks are now sufficiently mature to deliver full-shift operation in many orchard use-cases. Third‑party battery packs (notably 60–70 kWh-class systems) have been demonstrated to support 10–12 hours of continuous operation in representative deployments, removing a key operational barrier for adoption.
- Operational economics and sustainability: Precision spot-spraying using AI-powered weed detection has been shown in field demonstrations to cut chemical usage substantially. Where installed, these systems materially reduce input spend and regulatory compliance risk, changing the payback calculus for end users.
- Channel and service model implications: With electrified and autonomous platforms, the aftermarket and software subscription layers become as important as hardware sales. Dealer networks that move from pure equipment sales to outcome-based services will capture disproportionate lifetime value.
What our report delivers — practical tools and proven frameworks
PW Consulting’s report is structured as a commercial playbook for 2026 implementation. We pair a transparent market model with actionable tools designed to accelerate good decisions and de-risk execution:
CTA Head and Neck Analysis System Market
- Proprietary market model (Excel): fully auditable top‑down and bottom‑up demand estimates, scenario toggles (adoption curves, battery-cost declines, regulatory tightening) and sensitivity analysis to test strategic options.
- Five strategic scenarios for 2026–2032: baseline, accelerated electrification, delayed battery rollout, rapid autonomy adoption, and fragmented standards — each with P&L impact for OEMs and expected payback periods for growers.
- Vendor scorecards and supplier due-diligence templates: a standardized assessment across technology readiness, manufacturing scale, channel strength, service capability and regulatory posture.
- Field validation case studies: operational KPIs from commercial pilots that explain the gap between lab claims and on-farm economics — including real-world duty cycles, maintenance profiles and operator acceptance metrics.
- TCO / TCA calculators and financing frameworks: factory-to-farm total cost of ownership worksheets incorporating battery life, chemical-use reductions, labour displacement, and service revenue streams to support procurement decisions and leasing structures.
- Regulatory and safety matrix: regional compliance checklists, data privacy considerations for telematics, and operator-safety design priorities for autonomous spraying in mixed-use orchard environments.
Competitive landscape — what recent moves mean
The vendor environment is transitioning from fragmented hardware specialists toward integrated systems players that combine electrification, autonomy and software. Notable industry developments tracked in the report illustrate these dynamics and the strategic responses required of incumbents and newcomers alike:
- John Deere’s integration of an autonomous electric orchard sprayer platform has been a watershed event. The acquisition completed in 2025 brings a fully electric autonomous herbicide sprayer — built around high-capacity battery packs and advanced AI weed-detection — into a global dealer network. This move signals OEM commitment to bundling autonomy, battery and telematics as a single commercial offering targeted at high-value orchard segments.
- Specialist manufacturers are doubling down on complementary strategies. Select European and Oceania-based suppliers have prioritized compact, fully electric sprayers designed for compatibility with electric tractors and small-farm ergonomics. These firms emphasize modularity, field serviceability and crop-specific application techniques (for example, recapture/recycling technologies for disease control in high-density plantings).
- Product updates from established agricultural equipment brands show a parallel playbook: incremental performance improvements in tank design and control systems paired with simplified operation for specialty crop contexts, making electric options more accessible to traditional buyers.
The net effect: a moderately concentrated market where a small group of well-capitalized OEMs and specialist innovators shape platform standards, while a broad base of niche suppliers address diverse orchard types and regional channel structures. For strategy teams, this means monitoring both headline consolidation moves and the ecosystem of accessory suppliers (battery manufacturers, AI detection software providers, retrofit specialists) that will determine who can deliver end-to-end solutions at scale.
Key operational implications and strategic imperatives for 2026
- Design for serviceability and modular upgrades: Battery and autonomy components evolve quickly. OEMs should design platforms that allow battery swaps, electronic control upgrades and sensor refreshes without full-system replacements.
- Build dealer capacity for electric and software services: Training, tooling and new parts inventories are prerequisites for scaling commercial deployments; dealers that invest here will capture aftersales revenue and reduce downtime for growers.
- Pursue strategic battery and software partnerships: Vertical integration can fast-track capability, but partnering with battery specialists and AI providers preserves capex and accelerates time-to-market.
- Create clear financing and subscription offers: Leasing batteries, offering software-as-a-service for precision application, and bundling maintenance into subscription packages materially reduce buyer friction.
- Operationalize safety and compliance: Autonomous sprayers must embed robust person-detection and automatic pause mechanisms to align with liability expectations in orchard work environments.
How growers and procurement leaders should think about 2026 purchases
- Run TCO scenarios that include chemical-use savings from precision spot-spraying and expected battery replacement cycles; the combination often materially shortens payback for high-input, labor-constrained operations.
- Require field trial data from vendors in similar crop architectures and climates. Benchmarks for spray accuracy, drift reduction and maintenance intervals should be contractually specified.
- Prioritize interoperability: if you are electrifying a fleet, choose solutions that integrate with your preferred tractor OEMs and telematics systems to avoid lock-in and stranded assets.
- Factor in dealer footprint and service SLAs: uptime in spray seasons is a business-critical KPI; ensure vendor contractual commitments reflect real-season response times.
Investor and M&A perspective
John Deere’s strategic move to internalize an autonomous electric sprayer underscores the market’s growing strategic value. Investors evaluating targets should focus on four valuation levers: IP in autonomy and detection models, proven battery integration for full-shift operations, established channel or distribution agreements, and recurring revenue potential from software and service offerings. Our report includes precedent transaction analysis and a valuation sensitivity tool built around those levers to support diligence and offer strategy.
Next steps — how to use PW Consulting’s full report
This briefing is designed to be a decision-ready trailer: it communicates the direction and the levers that matter without disclosing every cell in the model. The full PW Consulting report contains the complete, auditable market model (with regional, type and application splits), supplier scorecards with graded assessments, downloadable TCO calculators and step-by-step implementation roadmaps tailored to grower size segments and regional regulatory regimes.
For teams preparing 2026 budgets and product roadmaps, the full dataset and playbooks will materially shorten evaluation cycles and reduce execution risk. Access to vendor-level segmentation and the full scenario matrices enables precise capital planning, procurement evaluation and go-to-market sequencing that can convert the projected growth runway into defensible revenue streams.
To request the full report, the interactive Excel model, or a tailored briefing for your executive team, please contact PW Consulting through our website and reference the Worldwide Electrical Orchard Sprayer Market 2026 Briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Electrical Orchard Sprayer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Non‑Filtering Cloth Vacuum Filters Market Forecast to Hit USD 378.74 Million by 2032, Growing at a 5.85% CAGR
By pmarketresearch, 2026-08-12
Worldwide Non-Filtering Cloth Vacuum Filters Market — Strategic Outlook for 2026: A PW Consulting Preview
PW Consulting’s latest market study on the Worldwide Non-Filtering Cloth Vacuum Filters market provides an operationally focused intelligence package for executives who must make consequential 2026 decisions across procurement, product strategy, operations and M&A. This is a preview designed to demonstrate the report’s depth and immediate relevance while reserving detailed segment-level figures for the full report.
Worldwide Dioctyl Fumarate Market
Market snapshot: Growth trajectory and concentration
The non-filtering cloth vacuum filters market has shown steady expansion through the current decade. Our compiled historical database records market size growth from approximately USD 192 million in 2020 to about USD 254 million in 2025. Looking forward, the market is projected to continue expanding through the 2026–2032 forecast window, reaching roughly USD 379 million by 2032 under a compounding annual growth rate of about 5.85%.
4K Endoscopy Camera System Market
Concentration dynamics matter for strategy: the market remains moderately fragmented, with the top-three vendors accounting for under half of revenues and the top-five approaching just over half. Such a structure creates room for both niche specialists and consolidation plays, depending on technology, service depth and supply chain integration.
Worldwide Inhaler Devices Market
Why this matters for 2026 decision-making
-
Capital allocation and product development: sustained mid-single-digit CAGR signals predictable demand across core industrial end users—enough to justify targeted capex for product line upgrades and automation of manufacturing lines for synthetic yarns and woven cloths.
-
Supplier selection and risk mitigation: fragmentation combined with concentrated material inputs (polypropylene, polyester and specialized multifilament yarns) increases vendor dependency risks. Procurement strategies in 2026 must balance cost, lead-time and technical collaboration ability—particularly for high-stability, wide-format belts and high-temperature synthetics.
-
M&A and partnership discipline: the market structure supports bolt-on acquisitions for firms seeking immediate access to filtration fabrics expertise, regional footprints or specific polymer technologies. A focused due diligence framework will separate scale-driven targets from technology-led niche players.
-
Regulatory and quality-driven segmentation: increasing regulatory scrutiny in food, pharmaceutical and certain clean-water applications favors suppliers that can demonstrate food-grade certifications, hygienic manufacturing and traceable supply chains—criteria that should be embedded in 2026 supplier scorecards.
Market dynamics shaping 2026 priorities
-
Raw material tightness and cost pass-through. Polypropylene and polyester remain the dominant feedstocks for woven and non-woven vacuum filter cloths. Price volatility in these polymers, together with periodic logistic constraints, will influence manufacturers’ margin structures and contract terms in 2026. Buyers will look for vendors with upstream relationships or hedging strategies to stabilize supply and pricing.
-
Performance-driven adoption. Across mining, mineral processing and wastewater treatment, demand is being driven by requirements for improved cake dryness, faster throughput and reduced downtime. Customers are increasingly procuring tailored cloth architectures (monofilament vs multifilament, specialized coatings, edge reinforcements) and demanding validated life-cycle metrics rather than simple unit price comparisons.
-
Certification and hygiene. Where vacuum filter cloths interface with food processing or pharmaceutical streams, compliance with food-grade standards (FDA, CE-equivalent hygiene standards) is a gating factor—affecting which vendors can participate in shortlists and how product life-cycle documentation is managed.
-
Technology and manufacturing scale. The ability to produce wide-format belts with dimensional stability and abrasion resistance (some vendors report belt widths of several meters) differentiates suppliers in industries requiring large-area filtration. Proprietary closures, edge reinforcement techniques and polymer blends are practical competitive levers.
Competitive landscape — profiles and positioning
The market combines global engineering groups, vertically integrated manufacturers and specialized European fabric innovators. The following is an analytical primer on five emblematic competitors identified in our study and the strategic implications for buyers and investors.
-
Micronics Engineered Filtration Group (part of Cleanova) — A US-based custom-engineering leader with deep capabilities across rotary disc, drum and horizontal belt filters. Micronics’ strength lies in application engineering and systems-level integration, making them a preferred partner for operations-constrained industrial users seeking turnkey upgrades and performance validation across mining, alumina refining and wastewater. For 2026 procurement strategies, Micronics is a candidate where technical co-development and long-term service agreements are priority selection criteria.
-
Bolian Filtration Solutions (Liaoning Bolian) — A China-headquartered manufacturer focused on woven filter cloths for a wide range of vacuum filtration variants and expanding into energy-related niches such as lithium battery processing. Recent activity shows an emphasis on industry engagement—exhibitions and supplier awards—indicating an aggressive commercial push and growing recognition among large OEMs and process operators. For buyers, Bolian represents a cost-competitive, rapidly scaling alternative with improving credentials for global project supply.
-
GKD Group (GKD Gebr. Kufferath AG) — A German supplier offering belt systems and cloths with integrated know-how in vacuum box design and wash-water management. GKD’s proposition is systems-oriented: cloth + hardware + spares. Companies prioritizing uptime and system harmonization often favor this model, as it reduces specification risk and simplifies warranty and maintenance pathways.
-
Testori S.p.A. — An Italian supplier focused on polymer-variant filter media and cake-discharge engineering. Testori’s strength is customization in polymer selection and yarn architecture, making them viable for applications where precise cake-release behavior and polymer compatibility are critical—food and specialty chemicals among them.
-
K2TEC — A French firm noted for material breadth (PP, PES, PA, PVDF, PTFE) and mechanical innovations such as patented closures and reinforced edges. K2TEC’s technical IP is valuable for operations requiring very fine control over pore size and mechanical durability—pharmaceuticals, fine chemicals and abrasive mineral processing.
Recent vendor movements and what they signal
-
Trade-show activity and supplier awards are more than marketing; they are barometers of market momentum and procurement recognition. Bolian’s sustained presence at major filtration exhibitions and recent supplier commendations in 2026 signal rising commercial acceptance and should prompt global buyers to include them in competitive bid lists where cost and scale matter.
-
European and US suppliers continue to compete on engineering depth and service models, while Asian manufacturers increasingly offer competitive lead-times and modular customization. Expect supplier strategies in 2026 to converge around hybrid offers: engineering + localized manufacturing footprints.
What the full PW Consulting report delivers (practical, executable content)
The full report is structured for action. Key deliverables include:
-
Transparent market sizing and conservative-to-optimistic scenario modelling for 2026–2032, including sensitivity testing on polymer price swings and capex cycles in mining and wastewater sectors.
-
A competitive scorecard with supplier capability maps, including manufacturing footprint, material range, certifications, lead-time profiles and aftermarket service models—designed to fast-track vendor shortlisting.
-
Procurement playbook for 2026: recommended contractual clauses, SLAs tied to cake dryness and belt lifetime, inventory buffers and raw-material pass-through templates.
-
Operational improvement guide: process KPIs to validate cloth upgrade ROI (cake moisture reduction, cycle-time uplift, cloth service life) and a template workshop agenda for supplier co-engineering pilots.
-
M&A and partnership framework: valuation multipliers for niche fabricors, integration risk checklist, and price/volume threshold models to justify bolt-on acquisitions.
-
Regulatory and compliance appendix: food-grade and hygiene checklists mapped to procurement gate criteria for 2026 tenders.
How to use the preview in 2026 planning
-
Prioritize proof-of-value projects: use short pilot programs to validate supplier claims on cloth life and cake moisture benefits before committing to large rollouts.
-
Lock flexible supply agreements: structure contracts with optionality on volumes to protect against raw-material cost swings while preserving preferred pricing for scale.
-
Embed certification milestones: require evidence of hygiene and material certifications for food and pharma applications early in the RFP phase to avoid late disqualifications.
-
Consider targeted acquisitions: small fabricators with IP in edge-reinforcement or closure systems may be high-impact, lower-cost ways to accelerate technical capability.
Next steps — where to get the complete intelligence
This preview highlights the broad contours and strategic imperatives the PW Consulting report provides to executives planning for 2026. The full report contains the granular supplier matrices, validated methodology, scenario models and downloadable procurement templates instrumental for executable decisions. For procurement directors, operations heads and strategy teams preparing budgets and R&D roadmaps in 2026, the complete report is the practical tool to convert market opportunity into measurable outcomes.
Access the full Worldwide Non-Filtering Cloth Vacuum Filters Market report on our website to download the comprehensive dataset, supplier scorecards and actionable playbooks required for confident decision-making in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Filtering Cloth Vacuum Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 2D Game Market to Surge from USD 55,200 Million in 2025 to USD 91,579.5 Million by 2032 at 7.5% CAGR — Mobile (USD 35,955.7M), Asia‑Pacific (USD 27,593.4M) and RPGs (USD 19,291.6M) Lead the Charge
By pmarketresearch, 2026-08-12
Worldwide 2D Game Market — 2026 Strategic Outlook: What Leaders Need to Know
PW Consulting’s latest market intelligence brief, the Worldwide 2D Game Market, delivers a focused, decision‑grade synthesis for executives, investors, and studio leaders preparing strategies in 2026 and beyond. Built on a detailed historical baseline (2020–2025) and a forward forecast (2026–2032), the study combines quantitative forecasting with tactical playbooks and competitor diagnostics to convert trends into actionable choices. This release is intended as a strategic “trailer”: we surface the critical implications and frameworks that matter for boardrooms and product teams, while directing decision‑makers to the full report for granular segment tables, interactive models, and proprietary vendor scoring.
Worldwide Liquorice Extract Market
Market snapshot: the macro trajectory that underpins 2026 decisions
Over the last half‑decade the global 2D game market has shown steady expansion. From a solid baseline in 2020, the market reached an institutional milestone in our base year, 2025, and is projected to continue growing through the 2026–2032 forecast window at a compound annual growth rate of 7.5%. Underlying this trajectory are persistent consumer demand for accessible experiences, renewed commercial interest in retro and “HD‑2D” aesthetics, and tooling advances that lower time‑to‑market for studios of all sizes.
Worldwide Land-Based Salmon Market
For strategy teams evaluating product roadmaps, regional entry or M&A, the headline facts matter because they change capital allocation, talent hiring and platform prioritization. The magnitude of the market and the multi‑year growth profile create room for differentiated bets — but only when organizations align offering design, monetization and distribution to contemporary market dynamics rather than legacy assumptions.
Engine Cabin Market
Why 2D is a strategic priority in 2026
- Creative leverage: 2D enables distinctive art direction and compact production cycles, giving indie and mid‑sized studios pathways to global attention without AAA budgets.
- Technical leverage: Advances in 2D engines and pipelines (sprite atlases, lighting, particle systems) are reducing friction for high fidelity visual styles, including HD‑2D remakes and hybrid titles.
- Commercial leverage: Niche communities and retro IP revivals demonstrate outsized engagement and durable monetization — if product, pricing and community management are well aligned.
- Distribution leverage: Emerging regulatory scrutiny and evolving store economics are reshaping discoverability; a nuanced distribution strategy is now a material competitive factor.
What the PW Consulting report delivers — practical, implementable content
Our research is built for action. The report is organized to support three immediate use cases: product strategy and roadmaps, corporate development and M&A screening, and operational optimization for studios and publishers. Key deliverables include:
- Quantitative forecast model (2026–2032) with scenario variants and sensitivity analysis calibrated to alternative consumer, pricing and regulatory outcomes.
- Engine and tool selection matrix that evaluates total cost of ownership, platform reach, talent availability and upgrade paths for Unity, Godot, GameMaker and other toolchains.
- Go‑to‑market playbooks for indie titles, mid‑tier launches and legacy IP remasters — including launch cadence, pricing levers, live ops frameworks and UA sequencing.
- Monetization decision framework comparing premium, tiered, ad‑supported and subscription cross‑sells against player segment behavior profiles.
- Outsourcing and delivery scorecards for art, animation and QA providers with recommended governance, SLAs and cost‑control templates.
- M&A screening filters and valuation heuristics tailored to 2D assets, IP portfolios and specialist studios, plus a short‑list methodology for bolt‑on acquisitions.
- Regulatory and distribution risk register with mitigation steps for discoverability disruption and platform policy changes.
- Executive dashboards and KPIs (LTV, CAC, retention cohorts, creative iteration velocity) ready for integration into investor decks and product war rooms.
Competitive landscape and strategic positions
The 2D ecosystem in 2026 is a mosaic of legacy platform holders, indie specialists, engine providers and outsourcing partners. Our competitive chapter synthesizes the strategic posture of the most consequential players and the implications for partners and competitors.
- Nintendo (Kyoto): Continues to set a premium standard for platform‑level 2D delivery and IP stewardship. Its first‑party titles remain a commercial lighthouse and a benchmark for quality expectations in platformers and adventure games.
- Capcom (Osaka): Leverages legacy franchises and specialist teams to sustain catalog value in 2D fighting and side‑scroll genres; their episodic and remaster strategies are instructive for monetizing classic IP.
- Konami (Tokyo): Recent announcements signal continued investment in retro‑inspired 2D titles; publishers with strong IP catalogs are demonstrating viable paths for mid‑cycle revivals and co‑development partnerships.
- Devolver Digital (Austin): The indie publisher’s global distribution and marketing finesse shows how curated, auteur‑driven 2D titles can achieve outsized returns with disciplined UA and PR.
- Engine providers — Unity (San Francisco), Godot (open source), YoYo Games (GameMaker): Each engine plays a distinct role. Unity’s broad reach and recent 2D improvements accelerate scale projects and cross‑platform parity; Godot offers cost advantages and community velocity for lightweight titles; GameMaker remains a rapid‑prototyping staple for 2D-first teams.
- Platform and storefront players (Epic, Ubisoft): Epic’s store and partnerships can amplify discoverability for curated 2D releases; Ubisoft’s indie programs illustrate publisher support models and hybrid publishing opportunities.
- Outsourcers and co‑development specialists (Keywords Studios, Virtuos, Room 8, Kevuru, Stepico): These firms are critical leverage points for studios scaling art, animation and QA with consistent quality. Their geographic footprint and specialization allow buyers to optimize cost, speed and creative fidelity.
Recent catalysts and what they mean for strategy
- Tooling updates (Unity 6.3 LTS, March 2026): Reductions in art pipeline friction and improved sprite atlas practices lower development risk for higher‑quality 2D titles and enable teams to push into HD‑2D aesthetics without disproportionate engineering lift.
- IP-driven releases (Konami’s 2026 announcement): High‑profile legacy IP revivals validate the commercial runway for curated remakes and create marketing halos that benefit adjacent indie sales windows.
- Authoring platform movement (RPG Maker HD‑2D support teased, March 2026): Democratization of HD‑2D toolchains expands the addressable community of creators and increases supply of stylistically similar titles — intensifying discoverability competition.
- Industry reports (e.g., BCG, Dec 2025) highlighting tiered pricing and subscription pressure: Monetization strategies must be nimble. Our consumer segmentation insight — with a material cohort willing to pay premium and another that is price sensitive — should guide mixed pricing experiments.
- Macro context: Global video game software and content revenues hit record levels in 2025, signaling capital availability and buyer interest; concurrently, evolving platform regulation affects distribution economics and discoverability strategies.
Five strategic imperatives for executives in 2026
- Prioritize engine and toolchain fit by product archetype. For episodic, cross‑platform releases choose engines with mature 2D pipelines; for lean indie projects evaluate open‑source and lightweight engines to preserve margin and control.
- Design monetization as a portfolio, not a point decision. Use a mix of premium, episodic DLC, season passes and low‑friction subscriptions tailored to the distinct player segments identified in market research.
- Build a discoverability playbook that anticipates platform regulation. Invest in owned channels (community, direct commerce), strategic storefront partnerships and data-driven UA to reduce dependence on single‑source discoverability.
- Operationalize outsourcing with governance. Use scorecarded outsourcing for art and QA while preserving core creative competencies in‑house; establish rapid feedback loops and IP protections in contracts.
- Adopt a dynamic M&A and IP strategy. Target acquisitions that provide creative teams, proprietary tech or stable live revenue streams; valuation should reflect the relatively fragmented competitive structure and the ability to scale niche hits.
How PW Consulting’s report accelerates 2026 decision cycles
Executives facing constrained time horizons need evidence‑based, executable guidance. Our report reduces uncertainty by combining an audited macro model, scenario testing and hands‑on playbooks that product, commercial and corporate development teams can deploy immediately. Whether you’re sizing a new studio investment, prioritizing an engine migration, or calibrating pricing tests, the report supplies the quantitative inputs, qualitative diagnostics and templates to fast‑track decisions without sacrificing rigor.
We intentionally withhold detailed regional, platform and genre splits in this press summary to preserve the investigative value of the full research package. The full report includes the complete segmentation matrices, interactive forecast workbooks, granular vendor ratings and case studies required to operationalize the recommendations above.
Next steps
For boards, PE sponsors, publishers and studio leaders preparing 2026 budgets and strategic plans, this report is designed to be a working document: import the model into planning cycles, run scenarios against your own KPIs and use the vendor scorecards to inform procurement and M&A screening. Visit PW Consulting’s Worldwide 2D Game Market page to access the full dataset, dashboards and downloadable templates that power these recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Game Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: International Business Travel Insurance Market Set to Reach USD 31,402.92 Million by 2032 from USD 18,500 Million in 2025, Growing at a 7.85% CAGR
By pmarketresearch, 2026-08-12
International Business Travel Insurance Plans Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on International Business Travel Insurance Plans (base year 2025) frames an actionable roadmap for corporate buyers, insurers, brokers, and investors preparing strategic moves in 2026. The market reached approximately USD 18,500 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.85% over the forecast horizon, reaching north of USD 31,000 Million by the end of the 2026–2032 forecast window. This trajectory reflects a sustained rebound in cross‑border corporate mobility, intensifying duty‑of‑care obligations, and steady product innovation from incumbent and challenger insurers.
Bots Market
Why this matters for 2026 corporate strategy
For multinational employers and mobility program leads, the marketplace is shifting from commodity indemnity to integrated duty‑of‑care platforms. Procurement decisions in 2026 should treat travel insurance not as a risk transfer line item but as a component of employee safety, compliance, and continuity planning. The market growth and concentration dynamics we document have three implications:
Worldwide Food Grade Ethanol Market
- Buyers can expect more modular offerings (policy + assistance + tech), enabling tighter integration with corporate EHS and HR systems. Procurement frameworks must therefore evaluate API interoperability, response SLAs, and provider network depth alongside price.
- The mix of competition and scale — reflected in a moderately concentrated market structure — means selective partnerships and affinity models will yield outsized returns for insurers that can combine underwriting strength with distribution reach.
- Regulatory and reputational pressures (duty of care) are increasing the total cost of non‑compliance; insurance solutions that demonstrably support risk mitigation and repatriation logistics will command premium positioning.
Market trajectory and what the numbers hide (and reveal)
The headline growth (CAGR ~7.85%) masks important structural shifts that senior leaders must calibrate for 2026:
Battery Intercell Connectors Market
- Volume recovery and premium normalization — business travel volumes are recovering past pandemic troughs and are trending toward new steady states driven by hybrid work and resumed international assignments. Insurers should prepare for a steady uptick in frequency of short‑term international trips and a parallel increase in multi‑trip demand models.
- Value migration to services — emergency medical evacuation, 24/7 global assistance, visa and logistics support, and telemedicine are increasingly where differentiation and margin reside. Pricing for pure indemnity is under pressure; value is captured through services and ecosystem play.
- Concentration offers consolidation opportunities — the market’s top players capture a meaningful share of premium, but there remains room for regional specialists and technology‑led entrants to carve defensible niches. M&A and partnership activity in 2026 will likely target capability gaps rather than scale alone.
Competitive landscape — what incumbents are doing now
The report profiles leading global players and examines how their strategic moves alter competitive dynamics. Highlights from our competitive assessment:
- Allianz Partners — remains a strategic bellwether: recent partnerships and board‑level hires signal an intent to deepen affinity under‑writing and policy distribution, particularly in mature travel markets. Their membership in industry councils demonstrates a play for policy influence and traveler confidence leadership.
- Specialists such as International Medical Group (IMG) and Seven Corners — are capitalizing on international medical expertise and customizable plans for employer groups, emphasizing evacuation, cross‑border medical continuity, and group administration.
- Distribution‑focused players like Travelex Insurance Services and Travel Guard (AIG) — leverage expansive broker and retail channels to bundle travel protection with corporate travel programs, while competing on claims turnaround and customer experience.
- Newer or differentiated entrants (e.g., Berkshire Hathaway Travel Protection, Blue Cross Blue Shield Global Solutions) — stress claims efficiency, global network access, and integrated group health linkages to win corporate accounts that demand consolidated healthcare administration across jurisdictions.
Our company profiles include underwriting posture, distribution strategy, claims benchmarks, and partnership maps. Recent publicly disclosed moves — including strategic alliances and senior appointments announced in April 2026 — are analyzed for their knock‑on effects on capacity, distribution and product development cycles.
Practical intelligence contained in the full report
PW Consulting’s report is built as a decision tool, not just a reference volume. The operational modules most relevant to 2026 decisions include:
- Scenario‑based market sizing and sensitivity analysis that link travel volume scenarios to premium pools and loss ratios.
- Go‑to‑market playbooks for carriers and brokers: product blueprints, recommended pricing levers, channel segmentation, and partner selection criteria.
- Procurement templates for corporate buyers: RFP language, SLA templates for assistance services, and evaluation scorecards that prioritize duty‑of‑care outcomes.
- Claims and service benchmarking: response time standards, repatriation cost comparisons, and digital claims conversion metrics.
- Regulatory and compliance checklist across major employer jurisdictions, with operational implications for travel policy design and insurer selection.
- M&A and partnership opportunity maps informed by market concentration metrics and capability gaps; a practical guide for buyers and investors targeting tuck‑ins or capability acquisitions in 2026.
Dynamics shaping product and procurement decisions
Three dynamics deserve special attention in 2026:
- Duty of care as procurement lever — employers are increasingly using insurance selection to discharge legal and reputational responsibilities to travelers. Contract clauses and verification procedures tied to evacuation capabilities and medical network access will be standard.
- Data‑driven underwriting & pricing — carriers that invest in travel pattern analytics and telemedicine integrations will be able to segment risk more precisely, offering bespoke premiums for high‑frequency traveler cohorts and corporate programs.
- Digital customer experience — rapid triage, multilingual assistance, and frictionless claims are becoming non‑negotiable for corporations focused on traveler retention and satisfaction. Investment in digital frontdoors and API connectivity will shorten sales cycles and improve renewal economics.
Strategic recommendations for 2026
For corporate buyers
- Reframe travel insurance RFPs to emphasize outcome metrics (evacuation time, medical network breadth, employee satisfaction) rather than premium alone.
- Bundle insurance procurement with duty‑of‑care technology and medical assistance providers to create an integrated supplier ecosystem with shared KPIs.
- Run a two‑track supplier strategy: retain a core global partner for scale and compliance, and pilot niche specialists for high‑risk or high‑value itineraries.
For insurers and brokers
- Prioritize partnerships that fill capability gaps (medical networks, telemedicine, local assistance) instead of chasing commoditized distribution.
- Invest in data platforms that support traveler‑level risk scoring and dynamic pricing for frequent travelers and corporate book-of‑business accounts.
- Use SLAs and service design as a competitive weapon — demonstrable evacuation and claims performance will attract corporate renewals.
For investors and M&A teams
- Target bolt‑on acquisitions that add assistance capabilities, telemedicine, or regional medical networks rather than broad top‑line purchases; these deliver quicker integration value.
- Monitor regulatory changes in employer duty‑of‑care obligations — such shifts create windows for rapid re‑pricing and re‑contracting across corporate portfolios.
How PW Consulting’s report saves you time and risk in 2026
Decision‑makers told us they need fast, actionable inputs that translate to contracts, product roadmaps, and M&A theses. Our report combines primary interviews, underwriting benchmarks, claims analytics, and legal/regulatory mapping to produce playbooks rather than abstract forecasts. Where necessary for commercial discretion, we summarize high‑level trends and frameworks in this briefing while retaining the granular segmentation, detailed pricing models, and deal‑level data exclusively in the full report.
Next steps — where to find the full intelligence
This briefing is designed to clarify the strategic choices facing buyers, carriers and investors in 2026. To access the complete market segmentation, granular regional and application volumes, pricing matrices, and downloadable procurement templates, please visit the report landing page. The full dataset and actionable appendices are available to subscribers and licensed purchasers; they include company scorecards, modeled scenarios, and an exportable RFP pack ready for immediate use.
Closing
International business travel insurance is moving from policy issuance to integrated traveler protection. For leaders making 2026 decisions, the question is no longer whether to buy or sell coverage, but how to architect partnerships, platforms and processes that turn insurance into a corporate capability for safe, compliant, and resilient international operations. PW Consulting’s International Business Travel Insurance Plans Market report provides the field guide to do exactly that — with the granular evidence and operational templates reserved in the full publication to support immediate execution.
For detailed analysis of this topic, please visit the official page: International Business Travel Insurance Plans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com