

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Mammography X-ray Unit Market: Why 8.75% CAGR & Shifting Digital Demand Redefine Growth
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Mammography X-ray Unit Market
The global mammography equipment sector has entered a decisive phase of structural expansion. Valued at approximately $1.15 billion in 2020, the market has grown steadily through 2025, crossing the $1.65 billion threshold. Over the coming years, the trajectory projects sustained momentum, with revenue expected to approach the $3 billion mark by 2032, translating to a compound annual growth rate of 8.75 percent. This growth is not merely a function of broader healthcare spending; it reflects a fundamental shift in how imaging systems are engineered, deployed, and reimbursed. For manufacturers, investors, and healthcare procurement teams, the market is evolving from a volume-driven replacement cycle into a technology-and-outcomes-led upgrade environment.
The macro picture, however, masks underlying asymmetries. Regional deployment patterns, modality preferences, and clinical use cases are converging around digital capabilities and screening-first workflows. At the same time, the market remains highly concentrated, with a small group of players accounting for the majority of share. That concentration creates both resilience and friction: established incumbents benefit from installed-base loyalty and service ecosystems, while emerging entrants test the boundaries of clinical differentiation and capital efficiency. Understanding where value is being created—and where it is being eroded—requires looking beyond top-line numbers to the operational and regulatory forces reshaping purchasing decisions.
Market Snapshot and Core Challenges
The overall market size reflects a steady climb from 2020 through 2025, with a pronounced acceleration expected over the forecast horizon. This cadence aligns with capital equipment replacement cycles, expanded screening participation in mature markets, and the gradual modernization of imaging fleets in emerging regions. The growth rate is supported by a mix of fresh unit sales and the recurring economics tied to system upkeep, calibration, and software-enabled upgrades. Yet the headline figures do not tell the full story. Three structural challenges are reshaping how the market behaves and where commercial opportunities are forming.
Challenge 1: Concentrated Supply and the Cost of Differentiation
With a small number of companies commanding the majority of market share, competition has shifted from pure hardware parity to integrated clinical value. Leading vendors compete on workflow integration, dose management, image quality reproducibility, and service reliability. For newer or smaller players, this environment raises the bar for entry: differentiation must be clinically credible and economically defensible, not just technically novel. The challenge is not simply to launch a system, but to demonstrate that a new configuration can reduce total cost of ownership, improve throughput, or enhance diagnostic confidence in ways that matter to facilities and payers.
PW Consulting
Challenge 2: Regulatory Rigor and the Burden of Compliance
Mammography is one of the most tightly regulated imaging modalities. Equipment must meet specific performance and dose standards, and operating sites are expected to maintain rigorous quality control routines. Compliance is not a one-time approval event; it is a continuous operational commitment. Facilities must conduct regular testing, address deviations promptly, and document corrective actions. For manufacturers, this means that product design, training, documentation, and service support must be engineered for sustained compliance—not just initial installation. For buyers, the regulatory layer influences procurement choices, as the cost of non-compliance and downtime can outweigh the upfront price difference between systems.
Challenge 3: Capital Sensitivity Amid Evolving Reimbursement Dynamics
Mammography systems represent significant capital investments, with pricing spread across entry-level, intermediate, and premium configurations depending on features such as three-dimensional imaging capability. At the same time, service contracts add a recurring cost dimension that facilities must plan for over the life of the equipment. On the revenue side, imaging services are tied to specific coding frameworks, and reimbursement outcomes depend on Medicare and private payer policies. This combination creates a tension familiar to capital equipment markets: clinical ambition must be reconciled with budget realism. Buyers increasingly weigh not only acquisition cost, but also the likelihood of sustained reimbursement coverage, utilization patterns, and the operational efficiency gains that can justify premium configurations.
Key Drivers Shaping the Market
The growth trajectory is underpinned by forces that extend beyond simple demand expansion. These drivers interact with one another, creating a market in which technology, regulation, and purchasing behavior reinforce new standards of care.
Technological Innovation and Clinical Value Creation
Digital mammography has become the dominant modality, with digital systems representing the majority of revenue and analog systems playing a diminishing role. The shift reflects more than legacy replacement; it reflects the operational and diagnostic advantages of digital workflows, including improved image handling, integration with downstream reporting, and the ability to support advanced acquisition modes. Three-dimensional capabilities and newer imaging architectures have further raised expectations around lesion visibility, dose optimization, and reading efficiency. These innovations are not merely feature upgrades; they change the economics of screening and diagnostic workflows by influencing recall rates, throughput, and radiologist confidence.
Recent milestones illustrate the pace of clinical exploration in this space. In early 2026, a first-in-human clinical study of a 4D mammography system reached enrollment completion at a regional health facility, signaling continued interest in higher-dimensional acquisition approaches and their potential to improve lesion characterization or workflow efficiency. Whether such approaches ultimately scale depends on clinical evidence, reproducibility, and the ability to integrate into routine practice without disrupting throughput. What is clear is that the market is actively testing the boundaries of acquisition geometry, image reconstruction, and workflow design.
Medical X-Ray Generator Market
Policy and Regulatory Environment as a Market Architect
Regulatory frameworks do more than set minimum standards; they shape procurement behavior, service expectations, and product roadmaps. In the United States, mammography systems are subject to equipment standards that include average glandular dose limits under federal rulemaking, and facilities must maintain quarterly quality control testing per manufacturer specifications, with corrective actions required if tests fail. This regulatory environment elevates the importance of reliable hardware design, consistent calibration, and responsive service infrastructure.
Regulatory guidance also evolves in ways that affect testing practices and equipment validation. Recent updates have revised phantom testing references, aligning quality assurance practices with current standards and commercial phantom solutions. While such changes may appear procedural, they matter commercially because they influence validation protocols, service training, and the documentation that facilities rely on to maintain compliance. For manufacturers, the operational implication is clear: regulatory alignment must be embedded into product lifecycle management, not treated as a separate compliance exercise.
Demand-Side Shifts in Screening and Diagnostic Workflows
Clinical demand is increasingly organized around screening as the dominant application, with diagnostic imaging representing a smaller share of usage. This pattern reflects both public health priorities and the operational logic of early detection programs. Screening-driven demand tends to favor systems that can handle higher volumes, maintain consistent image quality across broad patient populations, and support efficient reading workflows. At the same time, diagnostic demand remains important for problem-solving, recall evaluation, and symptomatic assessment, which keeps advanced imaging capabilities relevant across the product spectrum.
Behaviorally, healthcare organizations are paying closer attention to total cost of ownership and clinical outcomes, not just unit price. The decision to adopt premium configurations is increasingly tied to expected improvements in workflow efficiency, dose management, and diagnostic confidence, balanced against reimbursement realities. This demand-side evolution is pushing vendors to present not just equipment, but integrated solutions that bundle acquisition, training, service, and workflow optimization.
Supply-Side and Cost Structure Dynamics
The market’s cost structure is defined by a wide price spectrum across system tiers, with premium configurations commanding materially higher investment. This gradient creates an environment in which service contracts, parts availability, and upgrade paths have outsized importance. Annual service agreements typically vary with system age and feature set, making lifecycle cost a central element of procurement planning. In addition, the concentration of market share among leading vendors reinforces the importance of service networks and installed-base support, since many facilities prioritize reliability and long-term support over speculative new entrants.
For manufacturers, supply-side strategy increasingly involves balancing premium innovation with accessible configurations that meet the needs of smaller facilities or cost-sensitive markets. For buyers, the key question is how to select systems that fit clinical requirements without creating avoidable operational or financial strain over the equipment’s life. The result is a market where commercial success depends as much on service economics and compliance readiness as on hardware specifications.
Competitive Landscape and Leading Strategies
The competitive field is broad, spanning established global medtech and imaging companies as well as regional manufacturers and specialized innovators. This mix creates a layered competitive environment in which incumbents compete on ecosystem depth, while challengers attempt to carve out niches through clinical novelty, cost efficiency, or regional focus.
Strategic Positioning of Core Players
Hologic, GE HealthCare, and Siemens Healthineers represent the scale end of the market, where breadth of portfolio, installed-base leverage, and service infrastructure matter. These companies typically compete by integrating mammography into wider imaging and women’s health ecosystems, emphasizing workflow connectivity, dose management, and reproducibility across sites. Their strategic advantage lies in the ability to support large deployments, offer consistent service coverage, and align equipment with broader enterprise imaging and IT strategies.
FUJIFILM, Philips, and Canon Medical Systems bring strong imaging heritage and differentiated technology narratives. Their positioning often emphasizes image quality, system design, and workflow integration, with an eye toward supporting both screening throughput and diagnostic precision. Meanwhile, companies such as Konica Minolta, Carestream Health, Planmed, and IMS Giotto illustrate the value of specialized positioning. These players often target specific clinical use cases, regional markets, or configuration preferences, using focused product strategies to compete against broader portfolios.
On the emerging and regional side, companies such as Metaltronica, Beijing Wandong Medical Technology, Perlong Medical Equipment, and Shenzhen Angell Technology reflect the continued presence of cost-conscious manufacturing ecosystems and regional demand. Their commercial challenge is to demonstrate reliability, regulatory alignment, and service viability in markets where procurement decisions are highly sensitive to upfront price and local support.
Newer entrants such as Calidar highlight a different strategic pathway: clinical differentiation through novel acquisition concepts. In this case, early clinical study activity points to an innovation-focused approach that seeks to establish a distinct value proposition. Whether such a strategy scales will depend on the strength of clinical evidence, regulatory navigation, and the ability to position the system within existing workflows without imposing excessive operational complexity.
Market Evolution: Consolidation, Differentiation, and New Entry
The market is unlikely to become uniformly fragmented. Concentration in the upper tier is supported by the economics of service, compliance, and enterprise integration, which favor companies with broad reach and mature support structures. At the same time, differentiation remains possible through technology advances, workflow innovation, and regional specialization. New entrants are most likely to succeed when they can demonstrate a credible clinical benefit, fit into existing compliance and service expectations, and offer a clear economic rationale for switching or augmenting existing fleets.
For incumbents, the strategic imperative is to protect installed-base value while continuing to upgrade systems and service offerings in ways that align with regulatory expectations and clinical demand. For challengers, the opportunity lies in identifying segments where premium incumbents may be over-indexed on capability, or where regional demand is better served by focused product and support models. The broader trend is not a single winner-takes-all dynamic, but a layered market in which different players compete on different axes of value.
Future Trends and Commercial Opportunities
Looking ahead over the next three to five years, several trends are likely to define where growth and margin potential concentrate.
Trend 1: Digital-First Deployment and Advanced Acquisition Maturity
Digital systems will continue to dominate new deployments, while analog installations decline further as replacement cycles and modernization programs progress. Beyond the broad digital shift, more advanced acquisition approaches will mature from early research and limited adoption toward more mainstream consideration, particularly where evidence supports workflow or diagnostic gains. Commercial opportunity lies not only in selling higher-end systems, but in designing upgrade paths, software enhancements, and service models that allow facilities to move along the capability curve without full fleet replacement.
Medical X-Ray Tube Market
Trend 2: Compliance and Quality Assurance as Commercial Leverage
Regulatory expectations and quality control requirements will remain central to purchasing behavior. Facilities will increasingly favor vendors that make compliance easier to maintain through intuitive testing workflows, clear documentation, and responsive service. Manufacturers that embed compliance support into the product experience—rather than treating it as a separate service line—can turn a regulatory burden into a competitive advantage. This creates opportunities for service contracts, training programs, and digital quality management tools that reduce administrative friction for sites.
Trend 3: Total Cost of Ownership and Outcome-Linked Procurement
Buyers will continue to weigh acquisition price against lifecycle cost, reimbursement risk, and operational outcomes. As a result, vendors that can articulate how a system affects throughput, recall dynamics, dose management, and service reliability will have an advantage in competitive evaluations. The commercial opportunity here is to shift conversations from unit price to value over time, including service predictability, consumables efficiency, and integration with existing imaging IT and reporting workflows.
Risks and Uncertainties
These trends are not without risk. Reimbursement changes can alter the economic logic of premium configurations, especially if coding or payer policies shift in ways that affect facility revenue. Regulatory updates can increase testing and documentation burdens or change validation requirements, influencing procurement timing and service expectations. In addition, clinical novelty does not automatically translate into adoption; new acquisition modes must prove themselves in routine practice, with acceptable workflow impact and reproducible results. Finally, competitive intensity may compress margins in certain segments, particularly where regional manufacturers compete aggressively on price or where incumbents face pressure to modernize fleets without triggering full replacement cycles.
Actionable Guidance for Decision Makers
Different stakeholders face different strategic questions, but all benefit from a clear view of where value is forming and how the market is likely to evolve.
For Manufacturers and Technology Providers
- Design for lifecycle value, not just launch features. Emphasize serviceability, compliance support, and upgrade pathways that extend relevance across multiple procurement cycles.
- Align product narratives with operational outcomes. Frame capabilities in terms of throughput, dose management, reading efficiency, and quality assurance, not only image quality claims.
- Prepare for layered competition. Defend installed-base value while identifying segments where a focused configuration, regional support model, or clinical innovation can open new opportunities.
For Investors
- Focus on ecosystems, not only units. Recurring service economics, installed-base durability, and regulatory alignment often matter as much as new hardware sales.
- Watch for differentiation that is clinically and economically credible. Novel acquisition concepts or software-enabled workflows should be evaluated against adoption friction, evidence trajectory, and integration demands.
- Monitor concentration dynamics and regional expansion. High share among leading players creates stability, but also raises the importance of service reach, local support, and the ability to participate in modernization cycles across diverse markets.
For Healthcare Procurement and Facility Leaders
- Evaluate total cost of ownership with service and compliance in mind. Acquisition price is only one part of the equation; service contracts, downtime risk, and quality control support can shape financial outcomes over the life of the system.
- Match configuration to clinical mission and utilization patterns. Premium capabilities may be justified in high-volume or complex diagnostic environments, while simpler configurations may better serve sites with narrower use cases and tighter capital constraints.
- Request evidence of workflow integration and support reliability. Confirm that vendors can demonstrate not only system performance, but also the operational support needed to maintain compliance and minimize disruption.
For decision makers navigating this market, the most valuable intelligence is granular and current: segmentation details, regional deployment patterns, pricing and service economics, regulatory timelines, and competitive moves that affect procurement timing. Access to a complete research report can provide the depth needed to translate these dynamics into procurement strategy, investment thesis, or commercial planning. The broader market trajectory points to continued growth, but the distribution of value will depend on how well organizations align product strategy, compliance readiness, and service economics with evolving clinical demand.
For detailed analysis of this topic, please visit the official page: Mammography X-ray Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
5-Aminolevulinic Acid Market: Why 9.8% CAGR and Pharma’s Dominance Reshape 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the 5-Aminolevulinic Acid Market: A 2032 Outlook
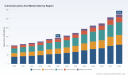
The global 5-Aminolevulinic Acid (5-ALA) market has transitioned from a specialized biochemical niche to a multi-sectoral growth engine, driven by converging advances in photodynamic therapies, agricultural biotechnology, and cosmetic formulations. With a compound annual growth rate of 9.8% through 2032, the sector reflects a disciplined expansion pattern rather than speculative hype. The trajectory from 2020 to 2032 demonstrates consistent value creation, with revenue rising steadily as clinical validation, manufacturing scale-up, and cross-industry adoption reinforce each other. Yet beneath the headline growth metrics lies a more nuanced reality: regulatory fragmentation, formulation bottlenecks, and an evolving competitive map are reshaping how value is captured. For executives, investors, and procurement leaders, the question is no longer whether the market is expanding, but where capital, R&D, and commercial execution will yield the highest risk-adjusted returns.
This analysis examines the structural drivers, competitive dynamics, and forward-looking inflection points that will define the 5-ALA landscape over the next three to five years. The goal is to translate macroeconomic momentum into actionable strategic positioning, highlighting where operational excellence, regulatory navigation, and application diversification intersect.
Market Snapshot and Core Challenges
The market has demonstrated resilient upward momentum, expanding from a baseline in 2020 to an estimated valuation in 2025, with projections pointing toward a multi-hundred-million-dollar scale by 2032. The growth profile is characterized by sustained, double-digit compounding that reflects both volume expansion and value migration toward higher-margin applications. Rather than a single breakthrough driving this trajectory, the expansion is the product of incremental clinical adoption, agricultural pilot scaling, and formulation optimization across multiple end-use sectors.
Despite this momentum, three structural challenges are redefining the commercial playbook.
Regulatory Uncertainty and Classification Gaps
The regulatory landscape for 5-ALA remains uneven across major markets. In pharmaceutical and medical device contexts, approvals have progressed through established clinical pathways, enabling commercialization in specific diagnostic and therapeutic applications. Outside these narrow indications, however, classification remains unresolved. In the United States, the absence of definitive guidance on whether 5-ALA qualifies as a New Dietary Ingredient has created ambiguity for supplement and functional nutrition ventures. Similarly, in the European Union, the compound continues to navigate Novel Food review processes, with no final determination enabling broad dietary supplement deployment. This regulatory lag is not merely a compliance issue; it dictates which business models can scale, which distribution channels remain accessible, and how quickly new formulations can reach consumers or enterprise buyers.
PW Consulting Chemical & Energy Research Center
Formulation and Delivery Optimization Constraints
While 5-ALA’s biochemical properties are well understood, translating laboratory efficacy into consistent clinical or agricultural outcomes remains a non-trivial engineering challenge. Photodynamic applications require precise timing, concentration control, and tissue-specific uptake, while agricultural and cosmetic use cases demand stability, dermal or foliar compatibility, and shelf-life reliability. Recent clinical data has demonstrated that extending the administration window for oral 5-ALA can improve procedural flexibility in diagnostic settings, underscoring that delivery protocols—not just molecule availability—are critical value drivers. Companies that treat formulation and dosing protocols as afterthoughts risk ceding margin and differentiation to competitors who integrate pharmacokinetics, user experience, and application-specific optimization into their core product architecture.
Supply Chain Concentration and Quality Standardization
The market exhibits moderate concentration among established suppliers, with a meaningful share of high-purity material flowing through a limited set of manufacturers and regional production hubs. This structure offers efficiency advantages but introduces vulnerability: batch consistency, regulatory documentation, and specialty-grade purification remain bottlenecks for downstream formulators. Moreover, as demand expands beyond research-grade supply into commercial-scale pharmaceutical, agricultural, and cosmetic volumes, the industry faces pressure to standardize quality frameworks while managing cost structures. Firms that rely on fragmented sourcing or lack robust analytical validation risk delays, compliance friction, and margin erosion as end-market specifications tighten.
Key Growth Drivers Reshaping the Landscape
The 5-ALA market’s expansion is not uniform; it is being pulled forward by a set of interlocking drivers that reward companies capable of aligning technical, regulatory, and commercial execution.
Clinical Validation and Fotodynamic Therapy Evolution
The most consequential driver is the maturation of photodynamic diagnosis and therapy applications. Clinical evidence continues to reinforce the utility of 5-ALA as a photosensitizing precursor in tumor visualization and targeted treatment protocols. Recent regulatory acknowledgments that extend oral administration windows for specific diagnostic procedures illustrate how clinical data can directly translate into procedural flexibility and broader adoption. As hospitals and specialty clinics integrate these protocols into routine workflows, demand shifts from experimental or pilot-scale use toward standardized, repeatable procurement. This transition elevates the importance of product reliability, regulatory documentation, and clinician training support, turning commercial success into a function of ecosystem enablement rather than molecule supply alone.
Policy and Regulatory Pathway Clarification
While regulatory uncertainty remains a challenge, incremental policy progress is also a growth catalyst. Where health authorities provide clearer indications for medical use, downstream investment becomes more predictable. In parallel, agricultural and cosmetic applications are shaping their own compliance trajectories, often leveraging existing biostimulant, cosmetic ingredient, or research-grade frameworks to accelerate go-to-market timelines while broader dietary classifications remain unresolved. The companies that navigate this environment effectively do not wait for a single global ruling; they design application-specific regulatory strategies that align with the fastest available pathways, using clinical or agronomic data packages to support targeted approvals and market access.
Demand-Side Shifts in Agriculture and Personal Care
Beyond the clinic, demand-side behavior is evolving rapidly. In agriculture, the push for yield optimization, stress tolerance, and reduced dependency on conventional inputs has elevated interest in biochemical biostimulants. 5-ALA’s role in chlorophyll synthesis and plant metabolic pathways positions it as a candidate for precision agricultural programs, particularly in markets where sustainability mandates and input cost pressures coincide. In cosmetics and personal care, consumer interest in biologically derived actives and skin-health benefits has spurred formulation exploration, with brands seeking ingredients that can anchor marketing narratives in mechanistic plausibility rather than purely cosmetic claims. These demand shifts expand the addressable base for 5-ALA beyond traditional medical channels, but they also require differentiated value propositions, safety data packages, and supply reliability tailored to each sector’s procurement standards.
Manufacturing and Cost Structure Improvements
Scaling production of high-purity 5-ALA and its salt forms has become a strategic priority as multi-sector demand intensifies. Advances in synthesis routes, purification processes, and quality control analytics are gradually improving cost structures and batch-to-batch consistency. The effect is twofold: it lowers barriers for formulators seeking dependable supply, and it enables incumbents to expand margins while investing in application-specific development. However, cost leadership alone is unlikely to secure durable advantage. The more durable moats are emerging around integrated quality systems, regulatory-ready documentation, and partnerships that link manufacturing capability with formulation science and end-market technical support.
Competitive Landscape and Strategic Positioning
The competitive field spans specialty pharmaceutical developers, chemical suppliers, research-grade distributors, and regional manufacturers pursuing agricultural and cosmetic applications. Rather than competing solely on price, leading players are carving out positions based on application focus, regulatory readiness, and technical service capabilities.
Differentiated Playbooks Across the Value Chain
Several companies have built recognizable identities around specific use cases. In the medical and diagnostic segment, firms with approved 5-ALA-based products for photodynamic visualization have leveraged clinical evidence, procedural training, and regulatory approvals to anchor their positions. Their advantage lies not simply in supplying the molecule, but in enabling clinical adoption through protocol clarity, product consistency, and medical affairs support.
In the research and reagent space, established chemical suppliers compete on purity certification, documentation reliability, and breadth of catalog support. Their customers prioritize batch traceability and analytical validation, which makes quality systems and supplier credibility central to retention. In the industrial and specialty chemical segment, manufacturers that can provide high-purity intermediates and customized synthesis options gain relevance among formulators who need flexibility in specifications and scale. Meanwhile, regional players in Asia have expanded their footprint by addressing both pharmaceutical and agricultural biostimulant demand, often combining API production with formulation exploration tailored to local crop and market conditions.
Strategic Advantages and Ecosystem Positioning
The most defensible positions emerge where molecule supply intersects with application expertise. Companies that combine reliable purification and manufacturing with regulatory documentation, stability data, and end-use technical support create friction for customers considering multi-sourcing or switching to lower-cost alternatives. In diagnostic and therapeutic niches, approval status and clinical protocol alignment function as strong barriers to entry. In agricultural and cosmetic channels, success increasingly depends on demonstrating consistent performance, safety profiles, and supply continuity rather than competing on commodity pricing alone.
This landscape is also being shaped by selective external collaboration. Major pharmaceutical and biotechnology players have shown interest in exploring enhanced 5-ALA formulations for photodynamic applications, signaling that formulation innovation and partnership-driven development can accelerate value creation even when internal R&D capacity is constrained. Such collaborations often focus on improving efficacy, expanding treatment or diagnostic windows, or tailoring delivery characteristics, which reinforces the broader industry shift toward formulation-led differentiation.
Market Structure Evolution: Consolidation, Specialization, and New Entrants
The market is neither fully consolidated nor highly fragmented; it is evolving through a combination of specialization and selective consolidation. In research-grade and reagent segments, brand trust and analytical reliability support stable positioning, while in commercial-scale pharmaceutical and agricultural segments, scale, regulatory readiness, and application support increasingly matter. New entrants are likely to appear where application gaps remain: niche cosmetic actives, regional agricultural biostimulant programs, and next-generation formulation concepts that improve stability, targeting, or ease of use. The strategic implication is clear: competitive advantage will belong to firms that define a precise application focus, build the corresponding regulatory and technical evidence base, and align supply chain capabilities with that focus rather than pursuing undifferentiated volume expansion.
5-Aminolevulinic Acid Hydrochloride Market
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026–2032 window, three trends are likely to shape how value is created and captured in the 5-ALA market.
Application-Specific Formulation as a Core Differentiator
The next phase of growth will increasingly reward companies that tailor 5-ALA products to specific end-use requirements rather than selling a uniform molecule across all channels. In medical and diagnostic settings, this means optimizing administration timing, concentration ranges, and procedural compatibility. In agriculture, it means developing formulations aligned with foliar application, stress resilience, and compatibility with existing crop management programs. In cosmetics, it means prioritizing stability, sensory attributes, and claim-supportive safety data. The commercial opportunity lies in building a portfolio architecture where each product variant is backed by the right evidence package, regulatory positioning, and technical support for its intended market.
Levulinic Acid Market
Regulatory Clarity as a Market Access Accelerator
As regulatory frameworks continue to mature, segments that secure clearer pathways will experience faster scaling, while ambiguous segments will remain dependent on workaround strategies or narrower use cases. Companies that proactively invest in data generation, dossier preparation, and early engagement with health authorities will be better positioned to convert scientific potential into commercial reach. Conversely, businesses that rely on regulatory ambiguity as a temporary advantage may face increasing scrutiny as standards tighten and downstream customers demand demonstrated compliance. The strategic lesson is to treat regulatory preparation as a growth investment rather than a compliance cost.
Supply Chain Integration and Regional Capacity Expansion
Demand diversification across regions and applications will pressure the industry to build more resilient, regionally balanced supply capability. Where production remains overly concentrated, downstream buyers will seek redundancy, quality guarantees, and localized technical support. The likely response is a mix of expanded regional manufacturing, strengthened analytical and quality frameworks, and closer integration between suppliers and formulators. This shift creates opportunities for players that can offer dependable supply, transparent documentation, and the flexibility to support application-specific requirements. It also raises the stakes for firms that cannot meet increasing quality and consistency expectations as commercial volumes grow.
These trends carry inherent uncertainty. Regulatory timelines can shift, clinical adoption can plateau if procedural barriers persist, and agricultural or cosmetic adoption can be sensitive to economic cycles and input-cost dynamics. Competitive entry may compress margins in certain segments, and formulation claims will face higher scrutiny as markets mature. The businesses that navigate these risks most effectively will be those that combine disciplined application focus with credible data, robust quality systems, and flexible commercial models.
Strategic Recommendations for Decision-Makers
For executives and investors evaluating exposure to 5-ALA, the opportunity is real but increasingly segmented. Value creation will depend less on broad commodity positioning and more on targeted application strategies, regulatory alignment, and supply chain reliability.
For Manufacturers and Product Developers
- Define a clear primary application focus and build the supporting evidence package, quality documentation, and technical support around it. A molecule-centric strategy without application-specific differentiation is increasingly vulnerable to competition and margin pressure.
- Treat formulation science and delivery protocols as core IP. Improvements in stability, timing flexibility, compatibility, and ease of use can create defensible positioning, especially in medical and diagnostic channels where procedural fit matters.
- Invest in regulatory readiness early. Proactive data generation, dossier preparation, and engagement with relevant authorities reduce time-to-access and improve customer confidence, particularly when downstream buyers are risk-averse.
For Investors and Strategic Capital Allocators
- Evaluate exposure by application pathway rather than by aggregate market growth alone. Segments with clearer regulatory status, established clinical or agronomic use, and repeatable procurement cycles tend to offer more predictable value capture than ambiguous or early-stage segments.
- Look for combination value: manufacturing reliability plus formulation capability plus application-specific support. Companies that only compete on volume or price may face structural margin risk as quality and compliance expectations rise.
- Monitor partnership activity and selective collaborations that signal formulation innovation or expanded indications. Such moves often preview where the next wave of differentiation will emerge.
For Procurement and Commercial Buyers
- Prioritize supplier consistency, analytical validation, and documentation completeness over lowest-unit-cost options, especially when formulations are integrated into regulated or performance-sensitive workflows.
- Align sourcing strategies with end-use requirements. A supplier strong in research-grade reliability may not be the best fit for commercial-scale agricultural or cosmetic programs, and vice versa.
- Build contingency planning into supply agreements. As demand grows across multiple sectors, multi-source strategies, clear quality specifications, and contractual clarity on documentation and batch traceability can reduce operational risk.
Moving from Insight to Execution
The 5-Aminolevulinic Acid market is entering a phase where breadth of opportunity is giving way to the need for precision in execution. Growth will continue, but the distribution of value will increasingly favor companies that combine scientific credibility, application-specific product design, regulatory preparedness, and dependable supply. For decision-makers, the strategic task is to identify which segment aligns with organizational capabilities, which evidence and compliance gaps must be closed, and how supply partnerships should be structured to support growth without exposing the business to unnecessary quality or continuity risk.
Detailed segmentation data, company-level profiling, and scenario-based forecasts can materially improve the quality of strategic planning in this environment. For organizations seeking a deeper, data-rich view of regional dynamics, application breakdown, competitive positioning, and tailored commercial options, the full PW Consulting market research report provides the structured detail and customized analytical support needed to translate these trends into concrete execution plans.
For detailed analysis of this topic, please visit the official page: 5-Aminolevulinic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Master Data Management Market: Strategic Trends and Commercial Opportunities in a Consolidating Data Economy
The global enterprise data landscape is undergoing a structural transformation, with Master Data Management (MDM) emerging as a critical control layer between fragmented operational systems and AI-driven decision processes. Market valuations have moved steadily upward through the 2020–2025 cycle, climbing from approximately $7.5 billion to $13.3 billion, and forward projections indicate sustained momentum through 2032. A compound annual growth rate of 12.5 percent places MDM among the faster-growing infrastructure categories in enterprise software, reflecting its shift from a specialized governance function to a strategic prerequisite for analytics, automation, and customer-facing applications.
This trajectory is not merely a reflection of incremental IT spending. It signals a deeper realignment in how organizations treat foundational data as a reusable, governed asset rather than a byproduct of operational databases. As organizations pursue data unification across customer, product, supplier, and organizational domains, MDM has become the connective tissue for compliance adherence, operational efficiency, and AI model reliability. For executives and capital allocators, the market's expansion carries both operational urgency and investment relevance. Grasping where value is concentrating, where vendor strategies are diverging, and how regulatory and technological pressures are reshaping procurement decisions is essential for positioning in the next phase of data management adoption.
Market Snapshot: Expansion With Maturing Structure
The MDM market's progression from 2020 through 2025 illustrates a category that has moved beyond early experimentation into mainstream enterprise deployment. Revenue growth accelerated notably as cloud architectures matured, data governance requirements hardened, and organizations recognized that AI initiatives frequently fail without reliable foundational data. Looking toward the 2026–2032 horizon, continued expansion is anticipated, with the market potentially reaching levels above $30 billion by the end of the forecast period. Growth velocity is expected to remain strong, though the character of that growth is changing as consolidation pressures and platform integration agendas reshape vendor positioning and buyer expectations.
Alongside top-line expansion, market structure is becoming more concentrated. A small group of large platform providers and specialized leaders now commands a significant share of enterprise engagements, while mid-tier and niche vendors compete on interoperability, domain specificity, and deployment simplicity. This concentration matters for decision-makers because it changes the purchasing environment: risk is shifting toward integration complexity, vendor lock-in, and the ability to govern data that spans both legacy and next-generation systems. At the same time, concentration is creating clearer reference architectures and more defined evaluation criteria for enterprises that need MDM to support cross-functional data products.
Core Challenges and Inflection Points
Despite strong demand, MDM adoption continues to face friction that limits the pace at which organizations can convert data unification ambitions into durable production outcomes. One persistent challenge is an operational paradox: many enterprises want MDM to be comprehensive, but comprehensive deployments often stall under the weight of governance overhead, cross-departmental alignment, and change management. MDM is no longer a one-time master data cleanup exercise; it increasingly requires continuous stewardship, workflow discipline, and integration with data quality and observability practices. Organizations that underestimate these operating requirements frequently encounter delayed time-to-value and reduced adoption across business units.
A second inflection point involves the collision between AI ambitions and data readiness. Enterprise interest in generative AI, agentic workflows, and advanced analytics has accelerated the realization that model performance and trustworthiness depend heavily on the consistency, lineage, and contextual completeness of master data. This has reframed MDM from a back-office governance concern to a front-line enabler of AI use cases. The challenge is that many existing MDM deployments were not designed for high-velocity, AI-ready data products. Bridging that gap requires new integration patterns, metadata enrichment, and governance that can accommodate both strict regulatory controls and the flexibility demanded by modern data architectures.
A third challenge is regulatory and compliance fragmentation across geographies and sectors. As privacy obligations, reporting mandates, and industry-specific standards continue to evolve, MDM implementations must support auditable stewardship, hierarchy management, and recordkeeping without becoming brittle. Compliance is no longer a side benefit; it is becoming a design constraint that shapes vendor selection, data model architecture, and operational workflows. Enterprises operating in multiple jurisdictions or regulated industries face a more complex balancing act between speed of deployment and durability of governance.
Primary Growth Drivers Reshaping the Market
Several interrelated forces are intensifying demand for MDM and changing the way solutions are evaluated. The first is technological innovation centered on AI-augmented data unification and cloud-native data foundations. MDM platforms are increasingly expected to support intelligent matching, automated stewardship, and continuous data quality feedback loops, reducing the manual burden that historically slowed adoption. This is particularly relevant as organizations attempt to scale data products across functions without proportionally increasing specialized labor. Embedded training, certification, and guided workflows are becoming part of the value proposition because they lower the practical cost of adoption and help standardize data governance practices across teams.
The second driver is the regulatory environment, which is turning data governance from an optional discipline into a compliance necessity. Privacy regulations and sector-level requirements are expanding the scope of data that must be traceable, correctable, and consistently governed. MDM architectures that provide documented stewardship workflows, hierarchy controls, and audit-ready trails are becoming more attractive in environments where data errors or inconsistent records create legal, operational, or reputational exposure. In parallel, emerging sustainability and environmental reporting expectations are adding new categories of master data that require governance and consistency, extending the relevance of MDM beyond traditional customer and product domains.
The third driver is demand-side behavior, particularly the growing expectation that enterprise data should support real-time, customer-centric, and cross-functional use cases. Organizations are moving away from treating master data as static reference content toward viewing it as an active input to segmentation, personalization, supply continuity, product lifecycle management, and trusted analytics. That shift creates demand for MDM solutions capable of producing reliable golden records, supporting multi-domain unification, and integrating with broader data platforms and cloud ecosystems. As consumers and business users alike expect more coherent experiences and more accurate information, the cost of fragmented master data becomes more visible and more consequential.
The fourth driver relates to the evolving cost and integration structure of enterprise data environments. Organizations are increasingly managing hybrid landscapes that blend legacy systems, cloud data platforms, and specialized applications. MDM that can operate across these environments without forcing a full platform replacement is gaining relevance because it reduces migration risk and preserves existing investments. This dynamic favors solutions that offer flexible deployment models, strong integration hooks, and the ability to function as a governed data layer rather than a closed ecosystem. The market is therefore rewarding vendors that can reduce complexity rather than add another rigid layer of infrastructure.
Competitive Dynamics and Strategic Positioning
The competitive landscape reflects a mix of platform-scale providers, specialized MDM vendors, and emerging entrants with strong cloud or AI orientations. Large enterprise platform companies continue to anchor the market by embedding MDM capabilities within broader data management and business application ecosystems. Their advantage lies in cross-functional reach, existing customer relationships, and the ability to connect master data governance with ERP, analytics, and cloud infrastructure strategies. In this context, MDM becomes part of a wider harmonization and AI-readiness agenda, which can simplify procurement for organizations already committed to a primary platform but can also raise integration dependency concerns for those seeking vendor flexibility.
Specialized vendors, meanwhile, compete on depth, agility, and targeted domain strengths. Some emphasize AI-powered SaaS platforms for multi-domain unification and governance, with particular attention to integration with widely used CRM and data ecosystems. Others differentiate through cloud-native architectures that support rapid scaling across business functions and simplify data cleaning and unification. Several leaders have positioned around multi-domain data platforms with strong governance, AI-ready data products, and native integration into modern cloud data warehouses. A further segment focuses on augmented platforms that combine MDM with embedded data quality and automation, appealing to organizations that want governance and quality in a single operational flow. In regulated verticals, product information management-oriented vendors extend MDM capabilities into lifecycle and compliance use cases where traceability and controlled authoring are critical.
Recent strategic movements make the consolidation theme especially visible. Major platform transactions completed in recent years demonstrate how MDM is being absorbed into broader data management and business data clouds. These moves are designed to strengthen AI-ready data unification across both native and external systems, while also expanding the reach of governance, quality, and master data capabilities within larger ecosystems. For buyers, this signals a market in which MDM is increasingly evaluated not as a standalone utility but as part of a larger data architecture strategy. The practical implication is that vendor selection is becoming more about ecosystem fit, integration roadmap, and long-term governance model than about point-feature comparison alone.
At the same time, analyst recognition and product releases indicate that differentiation remains highly active. Leadership placements in independent evaluations, continued platform releases, and public commitments to AI-powered MDM and broader ecosystem integration show that competition is not simply about scale. Vendors are competing on stewardship usability, compliance readiness, interoperability, and the ability to lower labor and training barriers to adoption. These factors matter because they influence not just initial purchase decisions but the likelihood that MDM will be operationalized effectively across the enterprise.
PW Consulting Information & Electronics Research Center
Strategic Implications of Market Evolution
One clear trend is the convergence of MDM with broader data governance, data quality, and data product thinking. The market is moving toward solutions that can serve as governed data foundations for multiple downstream consumers, including analytics, AI, customer operations, and supply chain processes. This convergence is reducing the isolation of MDM as a niche repository and increasing its role as an active contributor to enterprise data value chains. Organizations that treat MDM as a product platform rather than a static catalog are more likely to extract sustained value from their investments.
Another trend is the growing importance of interoperability across heterogeneous environments. As companies continue to accumulate cloud data platforms, legacy systems, and specialized applications, MDM must bridge gaps without demanding full architectural standardization. Solutions that support flexible integration, strong metadata handling, and consistent governance across environments are positioned to capture demand from enterprises that need progress without wholesale replacement. This favors a more practical, integration-aware buying posture, where evaluation criteria emphasize time-to-value, data product readiness, and operational maintainability.
A third trend is the increasing alignment between MDM and compliance-driven data operations. The demand for auditable workflows, stewardship accountability, and reliable hierarchy management is expanding the functional scope of MDM implementations. This is particularly relevant for organizations operating across regions or industries with distinct data obligations. MDM is increasingly expected to help demonstrate control, support reporting, and reduce exposure from inconsistent or poorly governed foundational data. In this environment, solution evaluation increasingly includes evidence of governance maturity, not just unification capability.
Digital Rights Management (DRM) Market
Future Outlook: Three Strategic Trajectories
Over the next three to five years, the MDM market is likely to be shaped by the continued blending of governance, AI readiness, and platform integration. One trajectory is the acceleration of AI-native MDM capabilities that support automated matching, stewardship assistance, and continuous data quality improvement. This will not eliminate the need for human oversight, but it should reduce the operational friction that has historically constrained scale. Commercial opportunities will arise for vendors and implementers that can demonstrate measurable improvements in data consistency, time-to-golden-record, and stewardship efficiency without sacrificing control.
A second trajectory is deeper embedding of MDM into broader data and application ecosystems. As enterprises pursue unified data foundations for analytics and AI, MDM is likely to be evaluated more often as part of a combined platform strategy rather than a discrete project. This creates opportunities for organizations that can connect master data governance with cloud data platforms, CRM workflows, and operational systems in a coherent way. It also raises the stakes for enterprises that must manage dependency risk and ensure that MDM remains adaptable if platform strategies shift.
Patient Data Management Systems (PDMS) Market
A third trajectory involves the widening applicability of MDM into sustainability, supply chain, and regulated product data contexts. As reporting obligations and operational transparency requirements grow, governed master data will become more relevant to environmental compliance, product traceability, and cross-border trade documentation. Commercial value will accrue to organizations that can extend MDM beyond traditional customer and product domains into new governance-sensitive areas. The uncertainty here lies in how quickly standards, data definitions, and audit expectations will crystallize across industries and regions, which will influence the pace of adoption in these newer use cases.
Actions for Decision-Makers Across Different Roles
For enterprise executives and strategy teams, the central task is to treat MDM as an operational capability with measurable business outcomes rather than a data cleanup initiative. That means defining the data domains that matter most to revenue, compliance, and customer experience, then investing in governance workflows, stewardship accountability, and integration to AI or analytics pipelines. Prioritizing use cases that produce visible improvements in customer data consistency, product information accuracy, or regulatory readiness can accelerate organizational support and reduce the risk of stalled deployments.
For technology and procurement leaders, the evaluation criteria should extend beyond feature lists to the reality of operating the platform in a hybrid enterprise. Important considerations include how well the solution supports multi-domain unification, how easily it integrates with existing cloud data environments, how it handles stewardship and compliance workflows, and how it lowers training and operational costs through usability and guided processes. Procurement decisions should also account for long-term adaptability, especially as platform consolidation, ecosystem integrations, and AI readiness requirements continue to evolve.
For investors and market participants, the key is to distinguish between vendors with durable differentiation and those that are primarily riding platform momentum. Value creation will increasingly depend on the ability to maintain AI-ready data products, support multi-domain governance, and demonstrate measurable improvements in data quality and operational efficiency. Monitoring strategic consolidation, ecosystem integrations, and analyst recognition can provide useful signals, but the underlying question remains whether a vendor's MDM capability is becoming a genuine enabler of enterprise data products or mainly a feature within a broader platform narrative.
Conclusion: Data Foundations as Strategic Leverage
The MDM market is expanding in a context where data is no longer a side concern but a core organizational capability. Growth is being driven by AI readiness demands, regulatory complexity, cloud-based data architectures, and the growing cost of inconsistent master data across customer, product, and operational domains. At the same time, the market is consolidating and maturing, which means the strategic question for most organizations is not whether to strengthen master data governance, but how to do so in a way that delivers durable, scalable value.
Organizations that succeed will be those that align MDM with real business outcomes, choose integration paths that reduce friction, and build governance models that can support both compliance and AI-driven innovation. Given the pace of change, timely access to detailed segment-level data, vendor benchmarking, and use-case-specific guidance can materially improve planning accuracy and investment confidence. For those seeking a deeper view of segmentation dynamics, competitive positioning, and tailored strategic options, the full PW Consulting research report provides a more granular basis for decision-making and next-step execution planning.
For detailed analysis of this topic, please visit the official page: Master Data Management (MDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Posture Correctors Market: Why 6.5% CAGR and Fragmented Demand Rewrite Strategy
By pmarketresearch, 2026-09-21
Navigating the Posture Correctors Market: Strategic Shifts and Commercial Trajectories (2026–2032)
The posture correction landscape is undergoing a structural transformation. Once confined to clinical rehabilitation and basic ergonomic aids, the category has absorbed consumer wellness demand, smart-device integration, and cost pressures from global manufacturing. The sector has expanded from a $134.2 million baseline in 2020 to an estimated $186.0 million in 2025, with the trajectory continuing toward the high $280 million range by 2032. A compound annual growth rate of 6.5 percent across the 2026–2032 forecast window signals steady, rather than explosive, expansion. This pace rewards disciplined execution: companies that align product architecture, compliance readiness, and channel strategy will capture disproportionate value, while those relying on generic positioning will face margin compression and channel consolidation.
Three structural realities define the current market state. First, the category sits at the intersection of consumer self-care and clinical expectation, creating tension around efficacy claims, user retention, and reimbursement pathways. Second, pricing dispersion—from roughly $15 for passive supports to the high $90s for smart wearables—reflects divergent value propositions that are not yet fully resolved by consumer education or procurement standards. Third, the competitive field is moderately concentrated, with the top three players accounting for around 25 percent of revenue and the top five near 35 percent, leaving meaningful space for differentiation but also inviting consolidation moves that reshape distribution leverage.
Market Landscape and Core Challenges
The revenue curve shows a notable inflection between 2022 and 2023, followed by more measured gains through 2025. This pattern aligns with a market that has absorbed pandemic-era ergonomic attention and is now normalizing around sustained workplace habits, active aging, and a broader acceptance of posture as a wellness indicator rather than a purely medical issue. Growth is no longer driven by a single catalyst; it is being distributed across adult consumers seeking daily comfort, geriatric users requiring stability, and younger segments influenced by screen-time awareness and athletic recovery practices.
The first core challenge is claim validation and user adherence. Passive braces and support devices can deliver immediate perceptual relief, but long-term posture change depends on neuromuscular retraining, habit formation, and behavioral design. Products that rely solely on mechanical correction often face churn once the initial discomfort subsides, while offerings that integrate feedback loops or training protocols must prove that their cues produce durable outcomes. The gap between short-term comfort and sustained alignment remains the category’s most persistent commercial friction.
The second challenge involves reimbursement ambiguity and channel dependency. While many posture correctors are positioned as consumer or wellness products, their functional overlap with spinal support and post-trauma stabilization places them near clinical categories. In the current policy environment, posture correctors are generally treated as Class I devices in the United States, which means premarket notification is not required provided basic labeling standards are met. At the same time, there are no dedicated CPT or HCPCS reimbursement codes in the 2026 Medicare Physician Fee Schedule final rule for these devices, and FDA registration remains required for manufacturers even without hospital billing codes. This combination limits institutional procurement as a reliable growth engine and elevates the importance of direct-to-consumer, retail, and professional-channel strategies.
The third challenge is cost architecture and product tiering. Medical-grade fabrics and polymer components influence unit economics, and the spread between passive and smart models creates a bifurcated market. Manufacturers must decide whether to compete on accessibility and volume, or on sensing, feedback, and app-linked engagement. This decision is not cosmetic: it shapes supply chain complexity, after-sales support, and the credibility of efficacy narratives. Companies that attempt to straddle both tiers without clear segmentation risk diluting brand signal and inflating operational cost.
Key Demand Drivers
Technology innovation and behavioral design
Smart wearables have introduced a new value layer to the category. Devices that combine haptic feedback with app-based tracking are shifting the conversation from static correction to active training. The most relevant innovation is not the sensor itself, but the behavioral loop around it: short, repeated cues that encourage habit formation and make posture correction feel achievable rather than prescriptive. Products that have reached meaningful user bases through this model illustrate the commercial potential of engagement-led design. The emergence of two-week habit-formation narratives, for example, reflects an understanding that adoption depends on measurable progress and low-friction daily use. This design philosophy is increasingly expected by consumers who compare posture tools to fitness and sleep technologies.
Beyond wearables, the broader innovation frontier includes material comfort, ergonomic geometry, and hybrid product architectures. Cushion-based seating support, posture bands, and neuromuscular activation approaches each address different user pain points. The strategic question is how to combine immediate relief with longer-term correction without overcomplicating the product or the purchase decision. Companies that clarify this balance are better positioned to defend price and reduce returns.
Policy and regulatory environment
Regulatory clarity is simultaneously enabling and constraining. On the enabling side, Class I classification and 510(k) exemption reduce time-to-market barriers for many posture correctors, provided labeling and registration requirements are satisfied. Harmonized quality management expectations, such as ISO 13485 references across global supply chains, also support cross-border compliance and can smooth distributor onboarding in multiple markets. On the constraining side, the absence of dedicated reimbursement codes keeps posture correctors largely outside institutional payment flows, reinforcing a consumer and professional-channel orientation. This does not block growth, but it does reshape the economics: customer acquisition, retention, and repeat purchase cycles matter more than bulk clinical procurement.
Worldwide Spinal Orthosis Market
For manufacturers, this environment rewards upfront compliance discipline. Registration readiness, labeling consistency, and documentation that supports professional recommendations can become differentiators in channels where clinicians, physiotherapists, and ergonomic advisors influence purchase decisions. In contrast, brands that treat compliance as an afterthought face higher friction when scaling internationally or entering retail and professional networks.
Demand-side behavior and lifestyle shifts
Demand is being reshaped by the normalization of remote and hybrid work, increased screen time, and a growing awareness of musculoskeletal discomfort as a daily quality-of-life issue. Adults represent the largest application segment by volume, reflecting both workplace ergonomics and self-directed wellness spending. At the same time, geriatric and pediatric segments are gaining relevance for different reasons: aging populations seek stability and fall-prevention support, while younger users are influenced by posture education, sports recovery, and parent-guided ergonomic interventions.
Behaviorally, consumers are comparing posture products against broader wellness categories. They expect comfort, discretion, and evidence-informed claims. They also respond to tools that integrate into existing routines rather than requiring a separate regimen. This places a premium on minimalist design, intuitive wear patterns, and clear instructions that connect product use to tangible outcomes such as reduced discomfort or improved sitting posture during long work sessions.
Supply chain and cost structure dynamics
Cost structures remain sensitive to material selection and assembly complexity. Medical-grade fabric and polymer components establish a pricing floor for products that want to signal durability and skin-safe wear, while smart components add electronics, software support, and return-rate management. These choices affect not only unit price but also margin resilience when input costs fluctuate. Manufacturers relying on single-region sourcing face greater exposure, while those with diversified supplier bases and clear bill-of-materials segmentation can adjust faster to cost pressure.
The distribution side is also evolving. Recent activity shows companies expanding through acquisition and channel integration, signaling that scale and reach are becoming increasingly valuable. Product launches targeting immediate posture and alignment needs suggest that firms are prioritizing fast-turn use cases alongside longer-term support solutions. These moves indicate a market in which manufacturers are trying to balance breadth, speed, and specialization rather than relying on a single product narrative.
Competitive Landscape and Leading Strategies
The competitive field is defined by divergent approaches to the same core problem: how to improve posture in a way that users will actually sustain. One cluster emphasizes immediate mechanical support and comfort. Brands in this group focus on cushions, bands, and orthotic-style supports that address pelvic alignment, spinal support, and post-trauma stabilization. Their value proposition is tangible and often easy to demonstrate, which makes them attractive in professional referrals and retail environments where quick perceived benefit matters.
A second cluster emphasizes neuromuscular activation and natural posture training. These offerings aim to reduce dependence on constant wear by encouraging the body to maintain better alignment through balance and muscle engagement. This approach appeals to users who want longer-term change without feeling permanently braced. It also aligns with a broader shift toward active correction rather than passive restriction.
Worldwide Hip Orthosis Market
A third cluster centers on smart feedback and habit formation. Wearable devices that use vibration cues and app-based tracking are designed to make posture correction a short, repeatable behavior. By framing the product as a training tool rather than a permanent support, these brands try to solve the adherence problem that limits many passive devices. Their commercial success depends on software experience, user onboarding, and credible progress metrics as much as on hardware quality.
Other players contribute through specialization. Some focus on spinal orthoses and stabilization lines for post-trauma and longer-term support, reinforcing credibility in clinical-adjacent channels. Others extend into sports performance and joint support, where posture and alignment intersect with athletic movement. Still others pursue brand-led distribution through professional and direct channels, using specialized positioning to avoid competing solely on price.
Recent company-level moves illustrate how the landscape is evolving. One major sports medicine supplier expanded its bracing and posture support lineup through acquisition, integrating new devices into existing distribution channels. This kind of move increases assortment depth and can strengthen retailer relationships, but it also raises the bar for portfolio clarity: buyers increasingly expect coherent product families rather than loosely connected SKUs. Elsewhere, a medical products company appointed new leadership with a mandate to drive growth in posture correction and spinal bracing, a signal that posture is being treated as a strategic segment rather than a byproduct of broader orthopedic offerings. At the same time, another firm launched new products aimed at immediate posture correction and alignment needs, reflecting continued investment in fast-cycle use cases. Together, these developments point to a market where both scale plays and targeted launches are being used to capture share.
Market structure appears poised for selective consolidation rather than uniform concentration. Moderate concentration at the top leaves room for specialized entrants, but channel economics increasingly reward breadth, compliance readiness, and brand trust. New entrants are most likely to succeed by solving a specific user problem well—smart training for desk workers, discreet support for active aging, or comfortable seating aids for hybrid workplaces—rather than by launching general-purpose posture products into saturated retail channels. The differentiation frontier is moving toward integration: hardware that is comfortable and durable, behavior design that supports adherence, and channel strategy that matches the product’s intended use.
Forward Outlook: Trends and Commercial Opportunities
From passive support to behavior-led correction
Over the next three to five years, the most commercially relevant shift is likely to be the continued migration from static correction toward feedback-informed training. This does not mean passive devices will disappear; many users will still want immediate comfort and support. However, products that combine ergonomic design with lightweight cues and simple progress tracking will gain relevance because they address the adherence gap that limits long-term outcomes. The commercial opportunity lies in packaging this experience clearly: users should understand what the product does in the first minutes, what changes over weeks, and how success is measured. Brands that articulate this journey effectively can reduce returns, improve word-of-mouth, and support premium pricing within the smart and hybrid tiers.
Channel rebalancing and professional influence
As reimbursement remains limited and direct consumer competition intensifies, professional and ergonomic channels will become more important as trust intermediaries. Physiotherapists, workplace wellness programs, chiropractors, and ergonomic consultants can reduce purchase uncertainty by aligning products with specific use cases. The strategic implication is that manufacturers should design for recommendability: clear labeling, consistent quality, and product narratives that distinguish post-trauma support from daily posture training. Companies that make it easy for professionals to recommend the right product for the right user will gain a defensible channel advantage, especially where retail shelves are crowded and online comparisons are fragmented.
PW Consulting
Segmented product architecture and pricing clarity
The pricing spread across passive and smart models will likely persist, but successful portfolios will become more deliberate about segmentation. The opportunity is to avoid internal cannibalization by defining separate use cases, user journeys, and price anchors for each tier. For example, seating support and posture bands can anchor accessibility and immediate comfort, while smart wearables and neuromuscular solutions can target habit formation and longer-term training. When segmentation is clear, marketing becomes more efficient, customer expectations are better aligned, and after-sales support can be tailored to product complexity. Companies that treat pricing as a strategic map rather than a reactive lever will be better equipped to defend margins as competition increases.
Risks and uncertainties
The outlook carries real uncertainty. Regulatory classifications may be revisited as posture devices continue to blur consumer and clinical boundaries, potentially reshaping labeling expectations or market access requirements. Reimbursement dynamics could shift if professional usage patterns change or if institutions seek standardized ergonomic interventions, but reliance on such changes would be speculative. On the demand side, adoption can stall if users perceive limited long-term benefit, if app-based features create friction, or if competing wellness categories draw attention and spending elsewhere. Supply-side risks include material cost volatility, component availability for smart models, and the operational burden of managing returns and support for connected products. Finally, consolidation could tighten distribution leverage for smaller brands, making channel partnerships and professional credibility more valuable than ever.
Strategic Implications for Decision-Makers
For manufacturers and product leaders
- Define a clear posture problem and avoid over-broad positioning. Products that solve a specific use case—desk-related discomfort, post-trauma stabilization, active sitting, or habit-based training—can communicate value more precisely and reduce return rates.
- Invest in adherence mechanics as much as hardware. Comfort, discretion, and intuitive wear matter, but so do cues, onboarding, and simple progress feedback. If the product depends on repeated use, the experience must make repetition easy.
- Align compliance and documentation with your target channel. Registration readiness, labeling consistency, and quality system references become commercially relevant when professionals, retailers, or international distributors are part of the growth plan.
- Segment the portfolio deliberately. Separate accessibility-driven products from engagement-driven products so that pricing, marketing, and support do not blur together and undermine margin.
For investors and strategic planners
- Look for durable differentiation rather than feature novelty. Sensor-led products can attract attention, but long-term value depends on retention, user outcomes, and channel trust. Evaluate whether a company has a credible path to repeat use and recommendability.
- Assess channel resilience. Companies with diversified routes to market—consumer, professional, retail, and direct—may be better positioned if reimbursement remains limited or if retail competition intensifies.
- Monitor consolidation signals. Acquisitions and leadership changes focused on posture and spinal support suggest that scale and portfolio coherence are becoming strategic assets. Consider how target companies would fit within a consolidating distribution environment.
For procurement and channel decision-makers
- Match the device to the user outcome. Immediate relief, postural training, and stabilization are not interchangeable needs. Procurement criteria should reflect whether the priority is comfort, alignment support, or behavior change.
- Prioritize consistency and recommendability. In professional and workplace settings, documentation, labeling clarity, and predictable quality often matter more than marginal feature differences. Products that are easy to explain and safe to recommend reduce adoption friction.
- Evaluate total cost of ownership for smart solutions. Connected devices may require app support, user onboarding, and return management. Procurement should weigh these operational factors alongside unit price.
The posture correctors market is maturing into a more disciplined competition between comfort, correction, and compliance. Growth at a steady mid-single-digit pace will reward companies that can articulate a specific posture problem, build an experience people will actually use, and position themselves where trust can be earned—whether through professional recommendation, retail clarity, or direct consumer engagement. For decision-makers seeking deeper segment mapping, regional dynamics, pricing architecture, and customized scenario planning, the full PW Consulting research report provides the detailed breakdowns and forward modeling needed to translate these trends into precise commercial choices.
For detailed analysis of this topic, please visit the official page: Posture Correctors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
FRP Market Vision: Inside the 5.26% CAGR Growth and What's Driving It
By pmarketresearch, 2026-09-21
Fire Retardant Polypropylene Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The fire retardant polypropylene market has matured into a critical materials segment where regulatory pressure, downstream safety expectations, and engineering performance requirements intersect. 2025 marks an inflection point in this trajectory. Over the past five years, annual market revenue climbed from roughly 1.34 billion USD in 2020 to an estimated 1.8 billion USD in 2025. The forward path remains constructive, with the market projected to surpass 2.3 billion USD by 2030 and approach 2.57 billion USD by 2032, translating to a compound annual growth rate of about 5.26 percent through the forecast horizon. These figures describe a market that is no longer expanding purely on volume replenishment, but on specification upgrades, legislative compliance, and substitution into higher-value polymer applications.
Beneath the headline growth, the industry is navigating several structural tension points. First, the regulatory tightening on halogenated chemistry continues to reshape formulation economics and downstream acceptance. Even where halogenated systems still command the largest revenue share, their future application envelope is narrowing as OEMs and end customers prioritize reduced smoke, lower toxicity, and improved residue profiles. This creates a compliance-versus-performance trade-off that compounders must resolve without sacrificing flame retardancy, processability, or cost competitiveness.
Second, the automotive and electrical sectors are redefining what "adequate fire protection" means. In electric vehicle battery enclosures, connector systems, and charging infrastructure, thermal runaway and ignition propagation have moved from engineering edge cases to core design constraints. Suppliers are no longer asked to meet a baseline rating; they are being asked to contain propagation, delay ignition, and maintain mechanical integrity under sustained heat exposure. Polypropylene compounds that historically served as cost-effective structural or interior materials are now expected to function as active safety layers, which changes the threshold for qualification and commercialization.
Third, raw material availability and ingredient sourcing introduce volatility into the cost structure. Grade development that depends on specialized phosphorus-based intermediates, metal salts, or proprietary synergists is sensitive to feedstock pricing, qualification cycles, and regional supply continuity. The result is a widening gap between compounders with integrated formulation capabilities and those that assemble off-the-shelf additives without closed-loop performance validation. This differentiation matters increasingly because customers are evaluating total cost of ownership rather than resin price alone.
Drivers of Market Change
Technology innovation in flame retardant formulation is the most immediate driver of competitive differentiation. Advances in aluminum hypophosphite and DOPO-based chemistries have expanded the design space for halogen-free polypropylene compounds, enabling lower smoke density and reduced toxicity without fully abandoning performance targets in demanding applications. These ingredient pathways are not simple drop-in replacements; they require systematic optimization of dispersion, thermal stability, and mechanical retention. However, when executed well, they open access to segments where halogenated systems face reputational, regulatory, or specification barriers. This shift is particularly relevant for injection molding and extrusion grades, where compounders can engineer purpose-built formulations rather than offering a generic flame-retardant compromise.
Policy and regulatory momentum reinforces the technology shift. In Europe, long-standing restrictions on certain brominated and polybrominated substances have steadily constrained the use of halogenated systems in electronics and industrial components, while REACH continues to tighten controls and scrutiny on chemical safety profiles. In Asia, China’s GB 38031-2025 for electric vehicle batteries introduces a more demanding performance mandate, effective from July 2026, requiring that packs do not catch fire or explode during thermal runaway. The regulation is not limited to battery cells; it cascades into surrounding materials, including battery housings, internal components, and charging-system polymers. In practice, this elevates the bar for flame retardant polypropylene used in EV-related assemblies and encourages adoption of grades that can demonstrably contribute to containment and delayed ignition.
Demand-side behavior is evolving in parallel. OEMs and Tier suppliers are increasingly specifying materials based on end-use safety outcomes rather than nominal fire class. In electrical and electronics applications, miniaturization, higher power density, and enclosed designs increase the stakes of material flammability. In construction and building products, fire safety expectations in public and multi-occupancy environments favor materials that can support compliant assemblies with less compromise on weight or processing convenience. Consumer-facing brands are also more sensitive to smoke, toxicity, and sustainability messaging, which amplifies preference for halogen-free solutions where feasible. These demand-side shifts mean that polypropylene compounders are being evaluated on a broader set of attributes: flame performance, emissions profile, durability, appearance, and processing consistency.
Supply chain and cost dynamics further shape the market. Polymer base prices, additive sourcing, logistics, and qualification lead times all influence the speed at which new grades reach commercial scale. Where raw material options for lower-smoke, lower-toxicity halogen-free systems are broadening, the competitive question becomes whether suppliers can secure reliable access, integrate the chemistry into repeatable compounding processes, and defend margin as volumes scale. Companies with closer upstream integration, robust testing infrastructure, and established customer validation pathways are better positioned to convert ingredient innovation into commercial wins, while others risk longer time-to-market and greater exposure to substitution risk.
Competitive Landscape and Leading Strategies
The competitive set in this market is concentrated and increasingly performance-led. A small number of major polymer and specialty materials players account for a significant share of revenue, and their strategies differ in the way they connect resin platforms, additive chemistry, and application engineering. Leadership in flame retardant polypropylene is less about resin supply alone and more about offering a validated solution that meets regulatory and application requirements with predictable processing behavior.
SABIC has focused its positioning on high-performance thermoplastic offerings that address specific safety and thermal challenges, particularly where flame retardancy intersects with structural and thermal management demands. Its product development narrative highlights use cases in electric vehicle battery systems, where thermoplastic-based thermal runaway barrier solutions are being introduced to support containment objectives. This approach signals a move toward application-specific solutions rather than generic flame-retardant grades, with emphasis on qualification support and system-level compatibility.
LyondellBasell has emphasized expansion of compounding capacity in North America, reinforcing its ability to serve regional demand with locally relevant supply and formulation options. Capacity expansion in flame retardant polypropylene compounds is not merely a volume play; it reflects a strategic decision to shorten supply chains, improve responsiveness, and capture growth in markets where regional content, lead time, and technical service matter. Combined with broad polymer expertise, this positioning supports a value proposition centered on availability, scale, and downstream formulation support.
Borealis continues to build its identity around advanced materials solutions, leveraging European engineering heritage and sustainability-oriented product development. Its relevance in this segment lies in the ability to align flame retardant grades with broader performance and regulatory trends, especially in applications where material composition, emissions profile, and recyclability considerations influence specification decisions. For customers navigating increasingly complex compliance environments, this type of positioning adds value through formulation consistency and documentation support.
Recent market activity shows how quickly the landscape is moving. In mid-2025, LyondellBasell expanded production capacity for flame retardant polypropylene compounds in North America, strengthening regional availability for high-demand applications. In late 2024, SABIC introduced thermoplastic-based thermal runaway barrier solutions for electric vehicle batteries using STAMAX flame retardant polypropylene, a clear example of aligning product development with the most stringent application requirements in mobility. Earlier in 2025, Tosaf launched a halogen-free flame retardant grade for sustainable polypropylene solutions in injection molding and extrusion, underscoring the push toward lower-toxicity and lower-smoke chemistries in mainstream processing routes.
The competitive trajectory suggests a market that is both consolidating and fragmenting at the same time. At the top, scale players and specialty compounders are strengthening their positions through capacity investments, application-specific launches, and closer engagement with high-value end markets. At the same time, the demand for differentiated formulations, particularly halogen-free grades tuned for lower smoke and improved toxicity profiles, opens room for new entrants and niche developers who can solve specific engineering pain points. The most durable advantage is likely to come from companies that can combine chemistry know-how, application validation, and reliable supply in a way that reduces specification risk for the buyer.
Future Trends and Commercial Implications
Over the next three to five years, the market will likely be shaped by the convergence of stricter safety mandates, broader adoption of halogen-free chemistries where performance allows, and a growing preference for application-engineered compounds rather than generic grades. One clear trend is the continued redirection of demand toward electric vehicle and electrical infrastructure applications, where fire safety requirements are becoming more prescriptive and more tied to system-level outcomes. Polypropylene compounds used in battery-associated components, enclosure structures, and power-related assemblies will face more rigorous qualification, and suppliers that can demonstrate repeatable performance under thermal stress will capture higher-value demand.
A second trend is the widening commercial relevance of lower-smoke, lower-toxicity solutions, especially as regulatory frameworks and customer expectations continue to penalize emissions-intensive formulations. Halogen-free grades using advanced phosphorus-based chemistries are positioned to gain traction in segments where smoke and toxicity are as important as flammability classification. The commercial opportunity lies not just in the chemistry itself, but in the ability to deliver consistent processing behavior, acceptable mechanical properties, and clear documentation that helps customers justify specification changes.
PW Consulting
A third trend is the shift toward solution selling and integrated technical support. As flame retardant polypropylene becomes more embedded in safety-critical applications, customers will increasingly want partners who can assist with material selection, testing interpretation, process optimization, and supply assurance. This favors suppliers that can offer more than a data sheet. It also suggests that margin pressure will not be uniform: products positioned purely on price will face erosion, while differentiated, validated solutions will command stronger positioning.
Potential risks should not be overlooked. Regulatory evolution can accelerate demand but also create uncertainty when standards change faster than product cycles. Ingredient availability for advanced chemistries may create bottlenecks if demand scales before supply ecosystems are fully matured. In addition, substitution risk remains real, particularly if alternative engineering polymers or hybrid material strategies prove more effective in certain high-performance applications. The market will reward agility and validation capability, while punishing reliance on static product portfolios.
Actionable Guidance for Decision Makers
For polymer manufacturers and compounders, the priority is to align product development with application-specific safety requirements rather than treating flame retardancy as a generic additive feature. Investment should focus on grades that can address stricter flammability outcomes, reduced smoke and toxicity expectations, and demonstrable qualification support for automotive and electrical applications. Equally important is securing reliable access to advanced ingredient chemistries so that formulation advantages can be scaled without disruption. Companies that move early toward application-validated halogen-free options, while maintaining cost discipline, will be better positioned to defend share as halogenated systems face tighter application limits.
For investors, the strategic signal is that value creation in this segment is increasingly tied to differentiation, regional supply capability, and application adjacency rather than broad commodity volume. Capacity expansions in regional markets, launches targeting electric vehicle battery safety, and new halogen-free grades for mainstream processing all point to a market where targeted exposure matters. Investment theses should therefore weigh a company’s ability to commercialize specialized formulations, serve regulated end markets, and convert material innovation into recurring, specification-locked demand. Volatility in raw material access and regulatory timing should be considered as part of the risk profile, especially for businesses that lack formulation depth or customer validation infrastructure.
Flame Retardant Fabric Market
For procurement and specification teams, the practical implication is that material selection should be evaluated against total safety performance, regulatory trajectory, and supply reliability instead of resin cost alone. Where applications are moving toward stricter fire outcomes, early engagement with suppliers that can provide validated grades, test data, and consistent availability will reduce downstream risk. Halogen-free options should be assessed not just on baseline flammability metrics but also on smoke behavior, toxicity considerations, processability, and compatibility with existing manufacturing lines. Building a qualified supplier base across both halogenated and halogen-free options can provide flexibility as regulation and customer expectations continue to evolve.
Fire Retardant Additives Market
Market participants who want to act on these dynamics with precision need detailed segmentation, regional nuance, and granular product-level intelligence that goes beyond macro growth trends. Deeper analysis of grade-level demand, application migration, regulatory timing, and competitive positioning can sharpen planning for capacity, portfolio decisions, and supplier selection. Readers seeking that level of detail can access the full research report for comprehensive data, scenario context, and tailored strategic implications.
For detailed analysis of this topic, please visit the official page: Fire Retardant Polypropylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
What Drives the UX Research Software Market's 11.6% CAGR to $769.85M by 2032
By pmarketresearch, 2026-09-21
The UX Research Software Market: Strategic Trends and Commercial Opportunities (2025–2032)
The user experience research software market has transitioned from a niche utility to a core component of enterprise product development. Over the past five years, the sector has demonstrated consistent expansion, moving from approximately $213 million in 2020 to roughly $362 million by 2025. This trajectory reflects a compound annual growth rate of 11.6% across the historical period, with forward projections indicating the market will approach $770 million by 2032. The growth is not merely incremental; it signals a structural shift in how organizations design, validate, and iterate digital products. For executives and investors, this landscape presents both operational imperatives and allocation decisions that require precise positioning. Understanding where the market is heading, who is shaping it, and what friction points are emerging will determine whether firms capture value or fall behind.
Market Overview and Core Challenges
The expansion of the UX research software market reflects broader digital transformation priorities. Organizations are no longer treating user research as an optional step in the design process; it has become embedded in product roadmaps, compliance frameworks, and customer retention strategies. The revenue trajectory shows steady acceleration, with the market crossing the $300 million threshold in 2024 and continuing to climb through the forecast window. This growth is distributed across cloud-based and on-premises deployment models, large enterprise buyers, and small to medium-sized enterprises, indicating that the demand is not confined to a single organizational profile or technology preference. The market remains concentrated, with the top three players accounting for roughly 60% of total revenue, which suggests that scale advantages, brand recognition, and integrated research workflows still matter significantly.
Despite the positive momentum, the sector faces several structural challenges that will shape competitive outcomes over the next few years. First, the proliferation of tools has created fragmentation. Research teams often juggle separate platforms for participant recruitment, usability testing, qualitative analysis, and insight repository management. This fragmentation increases operational overhead, complicates data continuity, and raises the risk of insights being siloed rather than operationalized. Second, data privacy and compliance requirements are tightening globally. Research software must now accommodate regional data protection standards, consent management, and secure handling of participant information, especially in regulated sectors such as healthcare and financial services. Tools that cannot demonstrate robust compliance posture face growing adoption friction. Third, the market is navigating an identity shift around artificial intelligence. While AI-driven synthesis and automated analysis promise efficiency gains, organizations are still evaluating where automation adds genuine rigor versus where it introduces noise or bias. The balance between speed and validity remains a live tension for buyers and vendors alike.
Key Drivers Shaping the Market
Technical innovation continues to be the most visible catalyst for market expansion. Platforms are moving beyond static testing workflows toward integrated environments that combine prototype evaluation, survey instrumentation, card sorting, tree testing, and automated insight generation within a single interface. The emergence of AI-assisted interview analysis, automated reporting, and rapid synthesis has reduced the turnaround time between data collection and actionable recommendations. This shift matters because it compresses the feedback loop for product teams, allowing faster iteration without sacrificing the depth of qualitative insight. For vendors, the strategic question is no longer whether to incorporate intelligent features, but how to embed them in ways that preserve methodological integrity and user trust.
Policy and regulatory dynamics are equally influential. Organizations are increasingly seeking solutions that not only comply with existing regulations but also provide clear safeguards for user data throughout the research lifecycle. This has led to product-level adjustments, including compliance-ready configurations, regional data handling options, and integration with enterprise governance workflows. In practice, compliance is no longer a backend concern; it is becoming a purchasing criterion. Buyers in healthcare, public sector, and financial services are evaluating research platforms through the lens of data protection, auditability, and consent management. Vendors that can articulate and demonstrate these capabilities are gaining a clearer path to enterprise accounts.
Demand-side behavior is also evolving. Consumer expectations for seamless, personalized digital experiences have raised the stakes for product teams. A single poorly designed flow can erode trust, increase support costs, and accelerate churn. As a result, organizations are investing more heavily in continuous research rather than episodic testing. This shift favors platforms that support recurring studies, participant panels, longitudinal tracking, and shared insight repositories. At the same time, small and mid-sized enterprises are gaining access to capabilities that were once concentrated in large organizations, because cloud-based delivery and panel access have lowered the barrier to entry. The net effect is a broader buyer base with more varied use cases and more diverse integration requirements.
Supply-side and cost dynamics contribute to the picture as well. The transition toward cloud-based deployment has expanded scalability and reduced the friction of setup and maintenance for many buyers. At the same time, the operational economics of running global participant panels, maintaining research infrastructure, and integrating with existing product toolchains require sustained investment. This creates a natural tilt toward vendors that can combine panel depth, workflow integration, and analytical automation without forcing buyers to stitch together multiple subscriptions. Cost efficiency is increasingly measured not only by license price, but by the reduction in time, coordination, and rework that a platform can deliver.
Competitive Landscape and Leading Strategies
The market features a mix of established platforms and specialized entrants, each pursuing a distinct value proposition. UserTesting operates as an enterprise-focused remote usability testing platform, offering both moderated and unmoderated studies with AI analytics integration and broad participant access. Its positioning emphasizes scale, enterprise readiness, and the ability to run structured studies across global audiences. The inclusion of UserZoom within the same platform ecosystem reflects a strategy of consolidating compliance-oriented and analytics-heavy research capabilities under a unified offering.
Maze has built its profile around an AI-first approach to prototype testing, surveys, card sorting, tree testing, and automated analysis. Its differentiation lies in speed and workflow simplicity, targeting teams that want rapid insights without navigating complex research setups. Optimal Workshop positions itself as a full research operations platform, combining card sorting, tree testing, unmoderated testing, AI-assisted interviews, and an integrated repository. Its strength is in supporting end-to-end research operations rather than isolated testing events. Lyssna, formerly known as UsabilityHub, offers an integrated user research platform spanning usability testing, surveys, interviews, and recruitment, with access to a large global panel. Its emphasis on breadth of research methods and participant availability appeals to teams seeking flexibility across study types.
Dovetail has carved out a distinct position as a customer intelligence platform focused on assembling, analyzing, and acting on qualitative research data. Its repository and AI synthesis capabilities address a recurring pain point: the loss of insight continuity when research findings remain scattered across files, notes, and individual team members. Baymard Institute takes a different approach, offering a subscription-based UX research database and tools derived from extensive original studies, paired with AI-powered assistants. Its model centers on curated insight access rather than primary data collection, which serves organizations that want to benchmark and inform decisions without running every study in-house. Great Question combines participant recruitment, study management, interviews, surveys, and AI-driven insights within a single platform, appealing to teams that want to reduce tool fragmentation. Userlytics rounds out the landscape with a full-featured remote user experience research platform backed by a large global participant panel and automated reporting, emphasizing reach and reporting efficiency.
PW Consulting Information & Electronics Research Center
Recent developments illustrate how these players are refining their positions in real time. In early 2025, Validately released a mobile-first UX research platform designed to enable usability studies and feedback collection directly from mobile devices, reflecting the growing importance of mobile-centric research workflows. Later in the year, Dovetail announced an integration partnership with Atlassian to streamline research documentation and collaboration within Jira and Confluence, signaling a push toward embedding research outputs directly into product and engineering workflows. UserZoom launched a compliance-ready UX research suite for the healthcare sector, supporting HIPAA and GDPR requirements for sensitive data, which highlights how regulatory specialization is becoming a viable differentiation path. These moves point to a market where vendors are competing not only on core testing capabilities, but on workflow integration, compliance readiness, and platform extensibility.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interrelated trends. The first is deeper workflow integration. Research platforms will increasingly connect with product management, design, engineering, and customer support tools, reducing the distance between insight generation and implementation. This will favor vendors that can embed research artifacts into existing collaboration environments and support traceability from finding to decision. For buyers, the commercial implication is clear: platforms that integrate smoothly will lower adoption barriers and increase the likelihood that research actually influences product outcomes.
Exit Interview Management Software Market
The second trend is the maturation of AI-assisted analysis, paired with growing demand for transparency and methodological rigor. Automated synthesis, summarization, and pattern detection will become more common, but buyers will also expect clearer controls around data sourcing, confidence levels, and human review. The opportunity lies in tools that augment rather than replace researcher judgment, especially in complex qualitative contexts where nuance matters. Vendors that can demonstrate consistent, auditable AI workflows will be better positioned to win enterprise trust, while those that overpromise on automation risk credibility setbacks.
User Generated Content (UGC) Software Market
The third trend is the continued expansion of compliance and data sovereignty requirements as a purchasing criterion. As regulations evolve and organizational risk tolerance shifts, research software will need to accommodate region-specific data handling, consent workflows, and sector-specific safeguards. This creates opportunities for platforms that can offer configurable compliance features without sacrificing usability or panel access. At the same time, it introduces uncertainty: regulatory trajectories are not uniform across geographies, and platforms that over-index on one compliance model may face friction when scaling into new markets. Buyers will need to evaluate not only current compliance posture, but also the flexibility to adapt as requirements change.
Strategic Recommendations for Decision Makers
For product and research leaders evaluating or expanding their use of UX research software, the priority should be to reduce fragmentation while preserving analytical depth. Consolidating recruitment, testing, qualitative analysis, and insight storage into a coherent workflow can improve speed and consistency, but only if the platform supports the methods and integrations that the organization actually uses. Before committing, teams should map their research lifecycle, identify where handoffs create delays or data loss, and assess whether a platform’s integration model aligns with existing product and engineering tools. The goal is not to chase feature lists, but to build a research operation that turns evidence into actionable decisions with minimal friction.
For investors and strategic planners, the market signals a shift from pure testing capability toward integrated research operations, compliance readiness, and workflow embedding. These are the areas where differentiation is becoming most visible. Investment attention should focus on vendors with clear expansion pathways: platforms that can deepen enterprise adoption through compliance and governance features, strengthen cross-tool integration, or scale participant access without compromising data security. At the same time, concentration in the market suggests that scale and ecosystem advantages still matter, so evaluating vendor durability, roadmap coherence, and customer retention will be important when weighing exposure.
For procurement teams and business unit leaders, the purchasing decision should be framed around operational fit and risk management rather than headline capabilities alone. Evaluate how each platform handles participant data, consent management, and regional compliance requirements, especially if the organization operates across multiple jurisdictions or serves regulated customer segments. Assess the total coordination cost, including integration with existing systems, training requirements, and the ease of moving insights into downstream workflows. Where possible, prioritize platforms that can demonstrate measurable improvements in research turnaround, insight reuse, and decision traceability, because these outcomes translate more directly into business value than feature volume.
The UX research software market is moving from expansion to refinement. Growth is still robust, but the next phase will reward platforms and buyers that prioritize integration, compliance, and actionable insight continuity. For decision makers who need detailed segmentation data, company-level benchmarking, and tailored recommendations aligned to specific operating models, the full PW Consulting market report provides a closer look at the segments, competitive dynamics, and implementation scenarios shaping the market through 2032.
For detailed analysis of this topic, please visit the official page: User Experience (UX) Research Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PCM Market Analysis: Why 17.4% CAGR and $662M Size Redefine the Industry
By pmarketresearch, 2026-09-21
The Phase Change Material Market: Strategic Trends and Commercial Opportunities Through 2032
The phase change material market has entered a decisive growth cycle. Valued at approximately $215 million in 2025 and projected to exceed $660 million by 2032, the sector is expanding at a compound annual growth rate of 17.42 percent. This trajectory reflects a structural shift rather than a cyclical upturn. Phase change materials are moving from niche thermal management applications into mainstream commercial deployment across buildings, healthcare logistics, energy storage, and industrial cooling. The acceleration is being driven by converging pressures: stricter energy efficiency mandates, rising cold chain complexity, and a corporate push toward passive thermal solutions that reduce operational energy consumption.
Yet growth alone does not guarantee commercial success. Companies operating in this space face a market that is simultaneously expanding and fragmenting. Demand is broadening across multiple application verticals, but each vertical carries distinct performance requirements, regulatory expectations, and procurement cycles. The result is a landscape where material science, application engineering, and compliance capability often matter more than raw production capacity. Understanding where the market is heading—and where the bottlenecks lie—requires looking beyond headline growth figures and examining the forces reshaping competitive positioning.
Market Reality and the Core Challenges Ahead
The current market structure reflects both momentum and friction. Growth is anchored by a broad base of end-use sectors, but the pace of adoption varies significantly depending on how readily phase change materials can be integrated into existing systems. In mature applications, performance validation and lifecycle economics are well understood. In emerging use cases, the burden of proof remains high, and procurement teams are often cautious about switching from established thermal management approaches.
Three challenges define the current inflection point:
Performance Standardization and Validation Gaps
Despite rapid commercial interest, the industry still lacks universally accepted testing protocols and performance benchmarks across different material chemistries and operating conditions. Buyers in construction, healthcare, and energy storage frequently encounter inconsistent data on thermal conductivity, cycling durability, and long-term stability. This creates hesitation among engineering-led procurement teams and lengthens qualification cycles. Companies that can provide independent validation, repeatable performance data, and transparent degradation profiles gain a meaningful advantage in markets where trust is still being built.
Cost Structure and Scalability Tension
Phase change materials are increasingly expected to deliver both thermal performance and economic efficiency. However, high-performance formulations often require precise synthesis, specialized encapsulation, or advanced stabilization techniques that raise production costs. At the same time, price-sensitive segments such as large-scale building integration and consumer-adjacent applications exert downward pressure on unit economics. The tension between performance differentiation and cost competitiveness is forcing manufacturers to make deliberate choices about where to position their products. Broad commoditization risks eroding margins, while overly specialized solutions can limit addressable volume.
Regulatory and Application-Specific Compliance Burdens
Regulatory expectations are becoming a more decisive factor in market access, particularly in pharmaceuticals, medical devices, and building materials. In healthcare logistics, temperature-controlled shipping must meet stringent handling and safety requirements. In construction and energy applications, material classification, fire performance, and environmental compliance can influence specification decisions. These requirements are not uniform across regions or verticals, which means companies must navigate a patchwork of standards rather than a single global framework. Compliance capability is therefore evolving from a backend obligation into a front-line differentiator.
Core Drivers Reshaping the Market
The expansion of the phase change material market is not being pulled by a single force. It is being reshaped by four interconnected drivers that reinforce one another and create distinct strategic implications for participants.
Worldwide Paraffin Phase Change Material (PCM) Market
Technological Innovation and Material-Level Breakthroughs
Material innovation remains the most direct lever for market expansion. Advances in organic, inorganic, and bio-based formulations are widening the range of usable temperature windows and improving stability under repeated thermal cycling. Equally important is the development of shape-stable and composite systems that reduce leakage risk and simplify integration into walls, panels, packaging, and storage units. These improvements lower the engineering barrier for adoption and make phase change materials more compatible with existing manufacturing and construction processes.
Recent product activity illustrates this trajectory. In April 2024, Pluss Advanced Technologies introduced a form-stable organic PCM designed for pharmaceutical cold chain logistics in the 2°C to 8°C range. That launch signaled a focus on application-specific thermal precision rather than generic cooling capacity. More recently, in June 2025, Cryopak expanded its cold chain portfolio with a flexible high-performance universal packaging solution featuring integrated PCM. These moves reflect a broader industry shift: the value proposition is moving from raw material supply toward engineered, application-ready thermal systems.
PCM Metal Sheet Market
Policy and Regulatory Environment as a Deployment Accelerant
Policy momentum is strengthening the economic case for passive thermal management. Energy efficiency targets in buildings, decarbonization goals in industrial operations, and reliability requirements in healthcare logistics all create indirect pressure to adopt materials that reduce active cooling loads or improve temperature stability. Where regulations or procurement standards begin to reward lower energy consumption, longer service life, or reduced dependency on continuous refrigeration, phase change materials become more attractive in feasibility studies and specification lists.
PW Consulting
Regulatory dynamics are also shaping product design. In medical and pharmaceutical applications, compatibility and safety expectations increasingly influence material selection. Patents and technical approvals are becoming relevant commercial signals. For example, Microtek Laboratories secured a U.S. patent in April 2025 for radiation-curable shape-stable thermoset PCM gels designed for medical cold packs, a development that underscores how intellectual property and regulatory-aligned formulation work are converging. In parallel, companies such as Modus Advanced must ensure that PCM systems intended for patient-contact medical devices meet FDA biocompatibility standards, reinforcing the need for early-stage compliance planning rather than retrospective adaptation.
Demand-Side Shifts in Cold Chain, Healthcare, and Building Operations
Demand is being reshaped by operational risk tolerance and total-cost thinking. In pharmaceutical and biologics transport, the consequences of temperature excursions have made thermal reliability a strategic priority rather than a logistics detail. This is driving interest in PCM-based containers, packs, and shippers that can maintain narrow temperature bands with less reliance on active refrigeration. In building and construction, operators and developers are increasingly evaluating thermal mass and temperature-regulation materials as part of broader energy-reduction strategies. The shift is not simply about acquiring a new material; it is about reducing vulnerability in fragile supply chains and lowering long-term energy exposure in built environments.
Supply Chain and Cost Dynamics
Supply chain factors are becoming more central to competitive positioning. Material availability, encapsulation capacity, packaging integration, and regional manufacturing footprints all influence responsiveness and margin structure. While some components remain subject to broader chemical and raw material cost fluctuations, companies are also finding advantage in localized production, application-tailored packaging, and closer collaboration with end-users. Pricing transparency is rising in certain segments, and customers are increasingly comparing solutions on installed performance rather than unit price alone. For example, in pharmaceutical applications, pricing for PCM cooling solutions has been positioned in a range that reflects both performance specificity and volume considerations, reminding manufacturers that price leadership without differentiated performance is difficult to sustain.
Competitive Landscape and Leading Strategies
The competitive environment is defined by moderate concentration and high application specialization. The market does not yet belong to a small group of dominant incumbents controlling the entire value chain. Instead, it features a mix of specialized material developers, packaging-focused solution providers, and application engineers that operate across healthcare, construction, energy, and industrial segments. This structure favors companies that can combine material knowledge with vertical-specific go-to-market capability.
Strategic Positioning Among Leading Participants
Several companies illustrate the different ways value is being captured in the current market:
-
Pluss Advanced Technologies has built a presence around PCM solutions for pharmaceutical cold chain and medical temperature-controlled packaging, with product development that emphasizes form-stable organic systems for narrow temperature ranges. Its recent launches highlight a strategy centered on application-specific precision and cold chain reliability.
-
Cryopak continues to focus on temperature-sensitive medical and pharmaceutical shipping, expanding into flexible high-performance packaging with integrated PCM. Its approach demonstrates how packaging design and material integration can be combined to simplify deployment for end users.
-
Cold Chain Technologies and Pelican BioThermal both address biologics and medical device transport through temperature-controlled packaging with PCM-based solutions. Their positioning reflects the importance of trusted supply chains, validation support, and compliance-aware product design in healthcare logistics.
-
PureTemp LLC has focused on bio-based PCMs for medical temperature-sensitive applications and cold chain use, showing how sustainability-oriented materials can align with performance requirements in regulated environments.
-
Rubitherm Technologies and Climator Sweden AB represent European expertise in high-performance PCMs for healthcare and pharmaceutical cold chain, indicating that regional technical reputations can support international commercialization when paired with consistent quality and application support.
-
va-Q-tec AG combines vacuum insulation panel and PCM solutions for temperature-controlled medical transport, an example of hybrid system design that aims to improve overall thermal efficiency rather than relying on PCM alone.
-
Companies such as Microtek Laboratories, Modus Advanced, RGEES, and Sonoco ThermoSafe illustrate the breadth of specialized work occurring across shape-stable gels, medical device integration, custom pharmaceutical packs, and pharmaceutical-grade shipping solutions. Together, they show that differentiation frequently comes from solving a narrow, high-value problem exceptionally well.
Market Evolution Trends
The competitive landscape is likely to evolve along three lines. First, application-led consolidation may accelerate as customers prefer suppliers that can provide integrated solutions rather than standalone materials. Second, vertical specialization will remain powerful because performance, compliance, and service requirements differ so sharply between healthcare logistics, building construction, thermal energy storage, and electronics. Third, new entrants may find opportunity not by competing head-on in established segments, but by targeting underserved temperature windows, novel encapsulation methods, or regional manufacturing advantages. The market is broad enough to reward focused strategies, but unforgiving to undifferentiated ones.
Forward Outlook: Three Trends to Watch
Looking across current data and commercial signals, three trends are likely to shape the market over the next three to five years.
Trend 1: Application-Engineered PCM Systems Will Outperform Standalone Material Sales
The commercial center of gravity is shifting toward engineered systems that combine PCM with packaging, panels, containers, or building components. This matters because end users increasingly evaluate thermal solutions based on installed performance, integration complexity, and operational risk reduction. Companies that design for specific temperature bands, durability requirements, and deployment conditions will be better positioned to capture premium value than those offering generalized materials. The opportunity lies in building repeatable application architectures that can scale across customers without sacrificing performance integrity.
Trend 2: Healthcare and Pharmaceutical Cold Chain Will Remain a High-Value Battleground
Temperature-sensitive medical transport continues to be one of the most demanding and lucrative segments. Biologics, vaccines, diagnostics, and medical devices require reliable temperature control with limited tolerance for deviation. As logistics networks become more complex and product portfolios expand, demand for PCM-based containers, packs, and shipping systems is likely to remain strong. The commercial prize is significant, but so is the scrutiny. Success in this segment will depend on validation documentation, biocompatibility awareness, packaging reliability, and the ability to support customers through qualification and auditing processes.
Trend 3: Energy-Connected Applications Will Grow as Passive Thermal Strategies Gain Traction
In buildings, thermal energy storage, and industrial cooling, phase change materials are increasingly viewed as part of broader energy-management strategies. Where operators seek to reduce peak cooling loads, improve temperature stability, or lower dependency on active systems, PCM can offer a complementary lever. Growth in this direction will depend on proving lifecycle value, streamlining integration, and aligning with evolving energy codes and sustainability expectations. The opportunity is scalable, but it requires credible performance narratives and practical installation pathways.
Risks and Sources of Uncertainty
These trends do not imply smooth expansion. Several sources of uncertainty remain. If performance data remains inconsistent across suppliers, qualification bottlenecks could slow adoption in conservative sectors. If raw material or manufacturing costs rise faster than customers are willing to absorb, price pressure may compress margins in commoditizing segments. If regulatory expectations diverge further across regions or application categories, compliance complexity could raise the barrier to scale. Finally, technology substitution remains a constant risk, particularly if alternative thermal management approaches improve rapidly in cost or convenience. Companies that monitor these risks early and design strategies around them will be better positioned than those that assume growth alone will resolve structural challenges.
Strategic Actions for Decision Makers
The market’s direction is becoming clearer, but the right move depends on where a company sits in the value chain. The following actions are most relevant for the three groups most directly affected.
For Manufacturers and Solution Providers
-
Focus product development on application-ready systems rather than broad material portfolios. Narrow temperature targets, shape stability, encapsulation durability, and integration simplicity often create stronger commercial traction than incremental chemistry improvements alone.
-
Invest in validation, documentation, and compliance readiness early. In regulated segments, the ability to supply repeatable performance data and meet safety or biocompatibility expectations can shorten sales cycles and improve win rates.
-
Build pricing strategy around total installed value, not unit cost. Where PCM reduces energy use, lowers excursion risk, or simplifies logistics, customers are more likely to justify premium pricing when the value case is made explicit.
For Investors and Strategic Backers
-
Evaluate companies on application depth, not just material technology. The most durable advantages often come from combining formulation capability with vertical-specific engineering, regulatory understanding, and customer support.
-
Watch for consolidation patterns in high-stakes segments such as pharmaceutical cold chain and medical transport, where trust, validation, and service networks create natural barriers and acquisition appeal.
-
Assess exposure to regulatory and compliance shifts. Companies that treat compliance as a strategic capability rather than an administrative cost are better positioned to scale across regions and application categories.
For Procurement and End-User Decision Makers
-
Evaluate PCM solutions against operational risk and total cost, not only purchase price. In applications where temperature excursions, energy costs, or system downtime carry significant consequences, performance reliability may outweigh modest upfront savings.
-
Require transparent testing data, degradation expectations, and application-specific qualification support before committing to scale. Incomplete performance evidence is one of the most common sources of project delay.
-
Prioritize suppliers that can support integration, training, and ongoing technical service. Phase change materials often succeed or fail based on how well they are deployed in real systems, not just how they perform in isolation.
Closing Perspective
The phase change material market is no longer defined solely by laboratory promise or narrow specialty use. It is entering a phase where commercial outcomes will be decided by application engineering, compliance capability, validation credibility, and cost-performance balance. Growth to 2032 is likely to be substantial, but the companies and buyers that benefit most will be those who treat PCM as a system-level decision rather than a commodity purchase.
For organizations that need a sharper view of segment-specific sizing, regional dynamics, pricing structures, competitive positioning, and technical requirements, deeper market intelligence can materially improve planning quality. A more detailed research report can help translate these strategic trends into segment-level assumptions, scenario planning, and actionable go-to-market choices. If the objective is to move from broad opportunity to executable strategy, the next step is to ground decisions in granular data tailored to the relevant application, region, and business model.
For detailed analysis of this topic, please visit the official page: Phase Change Material (PCM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Nerve Repair Biomaterial Market: Why 8.2% CAGR Signals 1.4B Shift
By pmarketresearch, 2026-09-21
The Nerve Repair Biomaterial Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Resilience Meets Complexity
The global nerve repair biomaterial market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately $557.7 million in 2020 to an estimated $827.0 million in 2025. This trajectory reflects a compound annual growth rate of 8.2 percent, positioning the sector for continued expansion through 2032 when revenue is projected to reach $1.44 billion. Growth has been underpinned by steady adoption of bioengineered conduits, structured wraps, and advanced connector systems that support peripheral nerve reconstruction following trauma, oncologic resection, and degenerative conditions.
Behind the headline figures lies a more nuanced picture. The market is characterized by moderate concentration, with the top three players accounting for roughly 55 percent of total revenue and the top five capturing close to 72 percent. This structure suggests that scale advantages and proprietary product portfolios remain meaningful barriers to entry, while simultaneously leaving room for specialized innovators who can address specific clinical gaps. The mid-2020s have also brought a period of recalibration, as manufacturers navigate evolving regulatory expectations, reimbursement scrutiny, and surgical workflow integration across diverse procedural settings.
Several structural challenges define the current inflection point. First, clinical heterogeneity across indication types—ranging from sensory nerve gaps to motor nerve discontinuities—creates variability in device performance expectations and complicates head-to-head evidence generation. Second, the regulatory and reimbursement landscape is tightening even as innovation accelerates, placing a premium on robust biocompatibility documentation, ISO 13485 quality systems, and clearly mapped coverage pathways. Third, supply chain maturity for specialized biomaterials remains uneven, with certain polymer and processing components requiring tightly controlled manufacturing environments that can constrain volume scalability.
PW Consulting
Key Growth Drivers: Technology, Policy, Demand, and Cost Structures
Technological progress continues to be the most visible catalyst. Recent clearances highlight a shift from passive scaffolding toward active, workflow-optimized repair systems. In December 2025, regulators approved an expanded biologics license application for an acellular nerve allograft, broadening indications to include sensory, mixed, and motor peripheral nerve discontinuities. That same year, an atraumatic sutureless polymer-based repair system received De Novo authorization for gaps up to 1 cm, signaling growing acceptance of devices that reduce operative time and technical variability. These developments point to a market that increasingly values not only regeneration potential but also ease of use, predictable handling characteristics, and compatibility with minimally invasive surgical practices.
Policy and regulatory dynamics are creating both opportunity and friction. In situ polymerizing peripheral nerve repair devices operate under Class II classification pathways, while biocompatibility evaluation follows established biological evaluation standards. Commercialization typically requires ISO 13485 certification alongside 510(k) clearance or De Novo authorization, which raises the bar for new entrants but also reinforces confidence among operating room teams and procurement committees. Reimbursement structures are aligning with specific procedural codes that cover nerve repair using synthetic conduits or vein allografts for both commercial and Medicare populations. Together, these frameworks create a clearer route to market for well-documented devices, while also demanding disciplined evidence generation and health economic positioning.
Demand-side changes are reshaping utilization patterns across surgical disciplines. Neurosurgery remains a dominant application area, supported by increasing procedural volume in peripheral nerve reconstruction and a growing willingness to intervene earlier in cases of compressive or traumatic neuropathy. Orthopedic surgery continues to drive meaningful volume through nerve injury management associated with joint and soft tissue procedures. Dental surgery and other specialized procedural areas contribute additional growth, often benefiting from smaller-diameter constructs and application-specific handling profiles. Across these settings, surgeons are prioritizing devices that offer consistent luminal dimensions, predictable deployment, and reduced reliance on complex microsurgical steps, which is steering purchasing decisions toward clinically differentiated product lines.
Cost and supply chain considerations are becoming more prominent as manufacturers scale and as hospitals scrutinize implant economics. The production of acellular matrices, scaffolds, and polymer-based guides involves controlled processing, sterilization, and storage requirements that can influence total landed cost. At the same time, value analysis committees are weighing not only unit price but also operating room efficiency, revision rates, and training burden. Companies that can demonstrate integrated workflows, stable inventory availability, and clear procedural benefits are better positioned to defend pricing and expand adoption.
Competitive Landscape and Leading Strategies
The market’s leading participants are pursuing distinct strategic positions that reflect their technological heritage and procedural focus. Several established players are emphasizing acellular allografts and complementary connector and protector portfolios, leveraging expanded indications to deepen presence across sensory and motor applications. Others are anchored in nerve guides and protector lines that address gap management and surrounding tissue protection, often paired with surgeon education and procedural support programs. A subset of innovators is differentiating through sutureless or minimally traumatic repair concepts, aiming to simplify handling and shorten case time while maintaining structural integrity during the critical healing window.
Strategic differentiation is increasingly multidimensional. Product architecture matters, but so does the alignment with surgical workflow. For example, devices designed to integrate smoothly into existing microsurgical or minimally invasive routines can reduce adoption friction, especially when accompanied by targeted training and in-service support. Regulatory readiness also functions as a competitive moat; organizations with mature quality systems and a track record of successful clearances are better equipped to iterate product families, pursue indication expansions, and respond to emerging clinical needs. Reimbursement alignment further enhances commercial resilience, as coverage clarity reduces purchasing uncertainty for both large health systems and ambulatory settings.
The competitive landscape is evolving along several axes. Incumbents with broad portfolios are seeking to consolidate clinical positioning by linking core repair products with complementary protective and connective devices, thereby increasing per-case relevance and strengthening relationships with surgical teams. Smaller, technology-focused entrants are introducing differentiated mechanics or material designs that address specific gap lengths, handling sensitivities, or procedure types. At the same time, consolidation dynamics are plausible where larger organizations seek to acquire specialized capabilities, expand into adjacent procedural segments, or accelerate access to novel polymer and processing platforms. The net effect is a market that rewards both clinical differentiation and commercial execution, with winners likely to be those that can combine credible evidence, workflow fit, and reliable supply.
Recent regulatory milestones illustrate how strategy and timing intersect. The expanded clearance for an acellular allograft broadened its addressable use cases and reinforced a biologic-centric positioning, while the De Novo authorization for a sutureless system introduced a differentiated repair modality for short gaps. These milestones do not merely reflect product-level achievements; they signal to the broader field where regulatory tolerance, clinical interest, and surgeon receptivity are converging. Competitors and new entrants alike are likely to calibrate their development roadmaps in response, prioritizing indication coverage, handling simplicity, and documentation rigor.
Forward-Looking Trends: Where Value Is Likely to Emerge
Over the next three to five years, one of the most consequential trends will be the continued broadening of indication pathways paired with differentiated device architectures. As regulatory frameworks accommodate expanded use across sensory, mixed, and motor discontinuity scenarios, and as sutureless or atraumatic options gain traction for short gaps, the market is likely to segment more precisely by gap length, tissue type, and procedural setting. This segmentation opens the door to targeted product strategies, with opportunity for manufacturers to build family-based portfolios that address multiple clinical scenarios without diluting focus.
A second trend is the growing emphasis on operating room efficiency and procedural standardization. Surgeons and health systems are increasingly weighing handling characteristics, deployment reproducibility, and training requirements alongside regenerative performance. Devices that reduce technical variability, shorten setup and repair time, and integrate with established surgical sequences can gain adoption advantage even when technical specifications appear similar on paper. This dynamic favors companies that invest in user-centric design, procedural education, and consistent quality across production lots.
A third trend concerns the tightening interplay between evidence, coverage, and procurement. Reimbursement codes are available for specific conduit and allograft-based repair approaches, but coverage decisions and value analysis expectations are becoming more granular. Manufacturers that can articulate not only clinical performance but also procedural value—lower revision potential, smoother learning curves, predictable inventory needs—will be better positioned to sustain adoption and pricing. Health economic framing is likely to become a standard element of commercialization rather than a post-market afterthought.
These trends carry commercial opportunity, but they also introduce uncertainty. Regulatory pathways and coverage policies can evolve unevenly across jurisdictions and payers, which may affect timing and breadth of adoption. Material supply and processing complexity can limit scalability if not managed proactively, especially for advanced constructs that rely on tightly controlled manufacturing. In addition, competition may intensify as new entrants attempt to target niche gap lengths or procedural conditions, potentially compressing margins in specific sub-segments. Organizations planning multi-year investments should therefore balance optimism about demand growth with disciplined scenario planning around regulation, reimbursement, and manufacturing readiness.
Strategic Actions for Decision-Makers
For manufacturers and product developers, the priority is to align innovation with procedural reality and regulatory clarity. Building product families that span complementary repair, connection, and protection functions can strengthen per-case relevance and reduce the risk of isolated-item commoditization. At the same time, early attention to biocompatibility documentation, quality system maturity, and coverage mapping can shorten the path from concept to sustained commercialization. Companies should also evaluate whether their manufacturing footprint and supply resilience support consistent availability, since procurement committees increasingly view reliability as part of value rather than a separate operational concern.
For investors, the market’s growth profile argues for selective exposure to platforms with clear differentiation and defensible execution. Due diligence should focus on indication coverage, evidence strategy, regulatory readiness, and the ability to convert procedural efficiency into adoption. Particular attention is warranted for technologies that either expand usable clinical scenarios for existing product classes or introduce meaningful surgical workflow advantages, provided the company also demonstrates credible reimbursement alignment and scalable operations. Given the moderate concentration in the market, there may also be value in tracking partnerships, acquisition signals, and capability-accretion moves that could reshape competitive positions over time.
Worldwide Peripheral Nerve Stimulators Market
For procurement leaders and clinical decision-makers, the emphasis should be on total procedural value rather than device price alone. Evaluation criteria should include handling consistency, deployment reliability, training burden, inventory stability, and the strength of supporting documentation. Where feasible, institutions can benefit from structured surgeon education, case-based feedback loops, and value analysis frameworks that account for operating room time, revision risk, and downstream resource use. Aligning purchasing decisions with the products that best match local procedural mix can improve outcomes while managing cost risk.
Worldwide Soft Tissue Repair Mesh Market
As the market expands toward a projected $1.44 billion revenue level by 2032, the volume of strategic decisions will only increase. Detailed segmentation data, company-specific capability mapping, and customized scenario analysis can materially improve planning quality for organizations operating across product development, investment, and procurement functions. Readers seeking a deeper dive into regional dynamics, application-by-application trajectories, supplier-level benchmarking, and tailored strategic recommendations are encouraged to review the full PW Consulting report, where the underlying data set and segmentation detail support more precise decision-making.
For detailed analysis of this topic, please visit the official page: Nerve Repair Biomaterial Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com