

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Ultrafiltration Membrane Market to Hit $321.45M by 2032 on 7.45% CAGR
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Imperatives in the Ultrafiltration Membrane Filtration Market (2026–2032)
The global ultrafiltration (UF) membrane filtration market is entering a decisive phase of expansion, driven by tightening water regulations, industrial process intensification, and the accelerating adoption of membrane-based separation technologies across diverse end-use sectors. As organizations prepare their capital allocation and operational strategies for the 2026–2032 horizon, understanding the structural dynamics of this market has transitioned from a technical consideration to a core strategic imperative. This report delivers a granular, forward-looking assessment of market trajectories, competitive positioning, and technology adoption curves, providing decision-makers with the analytical rigour needed to align investment portfolios with emerging demand signals.
Market Trajectory and Structural Growth Indicators
Over the historical review period (2020–2025), the ultrafiltration membrane filtration market demonstrated resilient, compounding growth, advancing from approximately 152.3 USD Million in 2020 to an estimated 195.4 USD Million by the 2025 base year. This upward trajectory reflects sustained capital expenditure in municipal water infrastructure, industrial wastewater compliance, and process-oriented filtration in food, beverage, and pharmaceutical manufacturing. Looking ahead, the forecast period (2026–2032) projects a steady expansion trajectory, with the market anticipated to reach 213.86 USD Million in 2026 and continue scaling toward 321.45 USD Million by 2032. The implied compound annual growth rate (CAGR) of approximately 7.45 percent underscores a market that is not merely recovering from cyclical fluctuations but is structurally re-rating higher as membrane solutions become embedded in long-term operational planning.
For strategic planners, this growth profile signals more than top-line expansion. It indicates a market where demand is being pulled by regulatory pressure, supply chain resilience priorities, and the ongoing shift toward water reuse and closed-loop industrial processes. The inflection observed between 2023 and 2025, followed by the projected acceleration into the late 2020s, suggests that early-mover organizations that align their R&D, manufacturing capacity, and service networks with these demand curves will be positioned to capture disproportionate value as the market matures.
The 2026–2032 Decision Window: Why Timing Matters
The 2026–2032 forecast window is particularly consequential for enterprise strategy. During this period, several converging forces will reshape procurement cycles, technology selection criteria, and regional deployment priorities. First, the integration of pre-filtration and ultrafiltration into unified module architectures is reducing footprint requirements and capital intensity, making membrane systems viable for a broader set of brownfield and space-constrained installations. Second, biofouling mitigation, pore-size engineering, and material durability are becoming decisive differentiators as operators seek to extend membrane lifecycles and reduce chemical cleaning frequency. Third, stringent discharge limits and water-stressed regional conditions are pushing municipal and industrial buyers toward solutions that combine high removal efficiency with operational reliability under variable feedwater quality.
In this environment, firms that rely on retrospective snapshots or generic market narratives risk misallocating resources. A disciplined, forward-looking analysis enables leadership teams to stress-test investment theses against realistic adoption curves, identify where consolidation or partnership opportunities are likely to emerge, and calibrate product roadmaps to the specifications that end-users will increasingly demand. The strategic value of this report lies precisely in its ability to convert macroeconomic and sector-level signals into actionable planning parameters for procurement, R&D, regional expansion, and competitive positioning.
What This Research Unpacks: From Macro Signals to Operational Intelligence
This study is constructed to serve as a decision-support framework rather than a static market summary. It begins with a rigorous historical reconstruction of market size and growth trends, establishing a credible baseline against which forward projections can be evaluated. From there, the analysis progresses into structured segmentation that examines how demand characteristics diverge across membrane material types, end-use applications, and geographic deployment patterns. Rather than presenting isolated percentages, the report contextualizes each segment within the operational realities that drive purchasing behavior: pore-size requirements, chemical compatibility, cleaning protocols, throughput expectations, and total cost of ownership considerations.
The research also maps the competitive landscape with attention to product architecture, technology roadmaps, and recent commercial moves that signal where incumbents and challengers are placing their bets. By examining product launches, certifications, and flagship contract awards, the analysis reveals how leading players are adapting their portfolios to address footprint constraints, fouling resistance, and application-specific performance thresholds. This competitive intelligence is paired with demand-side insights that clarify how municipal utilities, industrial processors, and life sciences operators are evaluating UF solutions against alternative separation technologies.
Ultrafiltration Membrane Market
Throughout, the report emphasizes practical applicability. Readers will find structured analysis that supports capacity planning, identifies high-growth application pathways, highlights regions where infrastructure investment cycles are accelerating, and flags technology transitions that could reshape procurement specifications over the next several years. The objective is to equip strategy, product, and commercial teams with a shared analytical foundation that can be translated into regional rollout plans, partnership strategies, and portfolio prioritization decisions.
Competitive Landscape: Incumbents, Innovators, and the Shape of the Market
The competitive architecture of the ultrafiltration membrane filtration market reflects a mix of established multinational players, specialized material innovators, and regional manufacturers that are expanding their commercial footprint. With a top-three concentration ratio of 18.75 percent and a top-five concentration of 25.6 percent, the market remains relatively fragmented at the upper tier, leaving meaningful room for differentiation through technology, service integration, and application-specific solutions. This fragmentation is not a sign of immaturity; rather, it indicates a market where performance credentials, regional support networks, and total-cost positioning can decisively influence procurement outcomes.
Several leading companies illustrate the strategic directions currently shaping the market. Toray Industries, Inc., based in Tokyo, has been advancing hollow-fiber UF membrane modules tailored for high-removal wastewater treatment and water reuse, including a next-generation lower-biofouling module with a nominal pore size of 0.005 micrometers. This product direction reflects an industry-wide emphasis on tightening separation performance while reducing fouling-related operational burdens, particularly for reuse and sensitive industrial streams.
Ultrafiltration Membrane Filtration Market
DuPont de Nemours, Inc., headquartered in Wilmington, Delaware, continues to expand its UF portfolio through both established offerings and targeted product launches. Its Inge™ UF modules, including PVDF and PES multi-bore variants with integrated pre-filters, are designed to streamline system architecture and reduce capital footprint. The company also maintains the ZeeWeed™ hollow-fiber UF platform for municipal, industrial, and offshore applications, signaling a strategy that balances standardized high-volume solutions with application-specific configurations.
Veolia Water Technologies & Solutions, headquartered in Paris, reinforces the importance of system-level integration and long-term operational partnerships. Through its UF and UF/RO membrane systems, the company addresses drinking water, wastewater, semiconductor, and offshore injection water production. Recent contract activity, including a multi-year operation award for a large-scale semiconductor water treatment facility, underscores how membrane providers are increasingly rewarded for reliability, recovery performance, and lifecycle service capabilities rather than component pricing alone.
BASF SE, based in Ludwigshafen, Germany, contributes multi-bore PES UF membranes and modules that support drinking water treatment, seawater pretreatment, and desalination optimization. Meanwhile, Cembrane A/S in Aarhus, Denmark, has established itself as a major producer of silicon carbide-based UF membranes for drinking water purification and high-throughput industrial wastewater applications, highlighting the growing relevance of robust inorganic membrane materials in demanding service environments.
The market also includes specialized and regionally focused players that expand the breadth of available solutions. Synder Filtration, Inc., in Vacaville, California, provides custom UF membrane flat sheets and spiral-wound elements for process water, food and beverage, and chemical industry applications. Meissner Filtration Products, Inc., in Carlsbad, California, supplies hollow-fiber PES UF membranes and modules for laboratory, bioprocess, and industrial filtration, reflecting the continued importance of precision filtration in controlled-process environments. Theway Membranes Pvt. Ltd., based in Chennai, India, represents the expansion of domestic manufacturing capability, producing hollow-fiber UF membranes for beer and wine filtration, membrane distillation, and industrial use. Taken together, these players illustrate a competitive field where material science, module design, and application know-how are the primary levers for differentiation.
Deployment Drivers Across Applications and Regions
Demand for ultrafiltration membranes is being shaped by distinct application-level priorities that influence performance requirements, procurement cycles, and service expectations. Water and wastewater treatment remains a central demand driver, as municipalities and industrial operators seek to meet stricter effluent standards, support water reuse initiatives, and improve the reliability of pretreatment trains ahead of downstream processes. In food and beverage processing, UF is increasingly valued for separation steps that must preserve product quality while maintaining consistent yield and operational uptime. Pharmaceutical and biotechnology applications continue to rely on UF for process fluid clarification, buffer preparation, and controlled filtration steps where material compatibility and regulatory documentation are critical. Chemical industry usage favors membranes that can handle variable feed compositions and resist fouling or chemical degradation under repeated cleaning cycles.
Geographically, deployment patterns reflect differences in infrastructure investment cycles, water stress intensity, industrial mix, and regional manufacturing capacity. Some markets are driven by large-scale municipal modernization programs and compliance-led retrofits, while others are expanding through industrial decentralization, beverage and food processing growth, and semiconductor-related water treatment requirements. The interplay between these regional dynamics and application-specific demand creates a complex but navigable landscape for organizations that can align their distribution, technical support, and product specifications with local procurement realities.
Recent commercial activity reinforces the strategic importance of these deployment drivers. Product introductions that unify pre-filtration and UF in a single module are reducing installation footprints and simplifying capital planning for space-constrained sites. Advances in lower-biofouling designs and fine pore-size engineering are attracting attention from operators seeking to extend run lengths and reduce maintenance intensity. In parallel, high-profile certifications and long-duration operation contracts are signaling that end-users increasingly evaluate UF suppliers on proven reliability, recovery performance, and the ability to support complex, multi-year service requirements. Exhibit presence at major industry events further illustrates how vendors are using technical demonstrations and utility-focused presentations to shape specification conversations well before procurement decisions are finalized.
Strategic Takeaways for Leadership Teams
As organizations move from market awareness to concrete planning, several strategic implications emerge from the current landscape. First, technology selection is increasingly governed by total cost of ownership rather than initial module pricing. Decisions around material compatibility, fouling resistance, cleaning frequency, and footprint compression can materially affect operating economics over the life of an installation. Second, the fragmented upper-tier concentration suggests that differentiation through application expertise, regional service coverage, and integrated system design can outweigh scale alone for many buyer segments. Third, the forecast growth trajectory indicates that demand will continue to broaden across both traditional and emerging use cases, making portfolio flexibility and specification agility important capabilities for producers and solution providers alike.
For procurement and operations leaders, the practical priority is to align membrane specifications with realistic operating conditions and lifecycle cost models rather than relying on generalized performance claims. For commercial and strategy teams, the priority is to identify where regional infrastructure cycles, industrial expansion, and regulatory momentum are likely to generate near-term demand clusters, and to position partnerships, distribution, or manufacturing capacity accordingly. For R&D and product organizations, the priority is to track the convergence of material improvements, module architecture changes, and application-specific performance requirements that are redefining what buyers consider a competitive offering.
Access the Full Strategic Assessment
The ultrafiltration membrane filtration market is moving from incremental adoption to structural integration across water, industrial, and process applications. Organizations that base their 2026–2032 planning on a detailed, forward-looking assessment will be better equipped to prioritize investments, refine product and service strategies, and anticipate specification shifts before they become mainstream procurement requirements. This report provides the analytical depth required to support those decisions, combining historical reconstruction, segmented growth analysis, competitive intelligence, and deployment-context insights into a single decision-ready framework.
To explore the complete segmentation analysis, regional deployment patterns, application-level demand drivers, and the full competitive profiling included in the study, access the complete market research on the source page. The full report delivers the granular intelligence needed to translate market momentum into executable strategy for the years ahead.
For detailed analysis of this topic, please visit the official page: Ultrafiltration Membrane Filtration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Algae Market Reaching $15.15B in 2025, Projects 8.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Blue Horizon: Strategic Imperatives in the Global Algae Products Market (2026–2032)
Executive Overview
The global transition toward sustainable, bio-based ingredients has moved beyond niche experimentation into mainstream industrial adoption. As we enter 2026, the algae products market stands at a critical inflection point, driven by converging forces in health-conscious consumer behavior, regulatory evolution, and advanced cultivation technologies. This strategic overview contextualizes the latest market intelligence, highlighting the trajectory from 2025 baseline data into a projected forecast period spanning 2026 to 2032. For executives, investors, and supply chain strategists, understanding these dynamics is not merely an academic exercise but a necessity for capital allocation, R&D prioritization, and competitive positioning.
The market has demonstrated remarkable resilience and growth velocity over the past half-decade. Historical data from 2020 through 2025 reveals a consistent upward trajectory, culminating in a robust valuation at the close of the base year. Building on this foundation, the forecast period anticipates sustained expansion, with a compound annual growth rate reflecting strong underlying demand and technological maturation. This growth is not uniform but is instead shaped by regional industrial clusters, application-specific value drivers, and a concentrated group of key players who are actively shaping the competitive landscape through strategic partnerships, regulatory navigation, and product innovation.
This article serves as a foundational primer for our comprehensive industry research. It outlines the structural forces defining the market, the operational realities faced by leading organizations, and the strategic questions that decision-makers must address. While high-level metrics provide directional clarity, the nuanced segmentation data, competitive benchmarking, and granular risk assessments required for precise execution are detailed in the full report. Leaders who engage with this intelligence will be better positioned to navigate regulatory complexity, capitalize on emerging application vectors, and align their portfolios with long-term market realities.
Macro Trajectory: Historical Momentum and Forecast Dynamics
The algae products sector has evolved from a fragmented landscape of regional producers into a globally integrated value chain with clear center-of-gravity markets. Historical tracking indicates steady volume and value appreciation, with the market crossing significant thresholds in the early 2020s and accelerating noticeably by the mid-decade. The base year valuation reflects this maturation, supported by advances in photobioreactor efficiency, strain optimization, and downstream processing capabilities. These operational improvements have reduced cost structures while enhancing product consistency, enabling broader commercial deployment across multiple end-use categories.
Microalgae Market
Looking forward, the forecast horizon extends through 2032, projecting a continued expansion curve underpinned by a mid-to-high single-digit compound annual growth rate. This trajectory assumes stable macroeconomic conditions, sustained investment in sustainable agriculture and nutrition infrastructure, and ongoing regulatory clarity in major consumer markets. The projected revenue envelope expands substantially over the period, signaling that the market is approaching a scale where economies of scale and vertical integration will increasingly differentiate winners from laggards. Strategic planners should view this growth not as a passive tailwind but as an active opportunity to secure supply agreements, invest in capacity, and capture premium positioning in high-value segments.
It is important to recognize that macroeconomic and regulatory variables will influence the pace and distribution of this growth. Currency fluctuations, trade policy shifts, and localized environmental constraints can impact sourcing strategies and margin structures. Furthermore, the market's concentration dynamics suggest that competitive advantage will increasingly derive from proprietary strain libraries, advanced bioprocessing expertise, and strong downstream distribution networks rather than volume production alone. Organizations that map these variables into their scenario planning will be better equipped to manage volatility and capture disproportionate value.
Competitive Architecture and Recent Strategic Maneuvers
The landscape is characterized by a tightly concentrated group of multinational and specialized players who command significant market share through diversified portfolios and strategic agility. Leading participants span the spectrum from ingredient suppliers and nutraceutical formulators to bioprocessing innovators and industrial biotechnology firms. Organizations such as Cargill, Incorporated and BASF SE leverage extensive global supply chains and broad formulation expertise to serve food, feed, and personal care markets. Meanwhile, DSM-Firmenich focuses heavily on high-potency algal DHA and EPA oils, targeting infant nutrition and premium supplement formulations. Corbion N.V. has emerged as a specialist in algae-based omega-3 and astaxanthin solutions, increasingly aligning its commercial strategy with regulatory approvals and strategic partnerships in high-growth regions.
Beyond the large-cap incumbents, specialized and regionally anchored firms are driving niche innovation and application expansion. Euglena Co., Ltd. has built a distinct profile around superfood powders and incorporated food ingredients, capitalizing on consumer interest in functional nutrition. Cyanotech Corporation continues to strengthen its position in Hawaiian Spirulina and astaxanthin for dietary supplements, benefiting from brand recognition and consistent quality standards. CP Kelco U.S., Inc. applies algae-derived carrageenan and alginate across food and industrial applications, while Algenol Biotech pursues renewable oils and biofuels through photobioreactor technology. Arizona Algae Products LLC rounds out the competitive mix with a focus on Nannochloropsis-derived EPA omega-3 oils and protein powders for nutraceutical applications.
Recent developments underscore the strategic velocity of these players. Regulatory approvals have opened new commercial pathways, notably with Corbion securing market access in China for its algae-based omega-3 solutions, followed by a strategic partnership to develop and commercialize natural astaxanthin derived from heterotrophic microalgae. Technological and product innovation is equally active: dsm-firmenich introduced a high-potency algal DHA oil formulation designed to meet demanding potency specifications for supplements and infant nutrition, while earthrise nutritionals, a subsidiary of DIC, inaugurated a next-generation Spirulina cultivation facility in California integrating AI, SCADA, robotics, and zero-discharge systems. In the food ingredients space, collaborations have brought microalgae-derived cooking oils to market using fermentation pathways that convert sugarcane sugars into functional culinary fats. Together, these moves illustrate a competitive environment where regulatory navigation, technological integration, and product potency are becoming decisive differentiators.
Segmentation Architecture and Application Economics
The market's value is distributed across multiple product types, geographic clusters, and application categories, each with distinct cost structures, demand drivers, and margin profiles. Spirulina and Chlorella remain central to the product mix, supported by long-standing consumer familiarity, established cultivation practices, and broad applicability in dietary supplements and functional foods. Dunaliella Salina and Aphanizomenon Flos-Aquae occupy complementary positions, often leveraged for specialized pigment, antioxidant, and nutraceutical applications. While high-level valuation splits indicate strong representation across these categories, the relative commercial weighting varies materially by region, regulatory context, and downstream formulation requirements. A detailed segmentation analysis is essential for identifying where pricing power, volume growth, and supply constraints intersect.
Application demand is equally multifaceted. Dietary supplements represent the largest application corridor, reflecting sustained consumer interest in plant-based omega-3 alternatives, immune-support ingredients, and antioxidant-rich formulations. Food and beverages form a rapidly expanding use case, driven by clean-label trends, novel ingredient acceptance, and the growing incorporation of algae-derived proteins, oils, and colorants into mainstream product pipelines. Animal feed constitutes a structurally important demand base, particularly where aquaculture and livestock nutrition seek sustainable, nutrient-dense alternatives to traditional marine and terrestrial inputs. Each application vector carries different regulatory burdens, customer procurement cycles, and technical formulation requirements, making application-level granularity a critical input for market entry and portfolio strategy.
Regional concentration patterns further shape commercial strategy. Broad valuation distributions indicate that Asia Pacific, Europe, and North America collectively anchor the market, while Latin America and the Middle East and Africa present distinct growth and sourcing dynamics. These regional profiles differ in terms of cultivation infrastructure, regulatory maturity, import dependency, and local demand composition. Executives evaluating market entry, capacity siting, or supplier diversification must account for these regional nuances rather than relying on aggregated global totals. The full report provides detailed regional breakdowns and application-specific revenue estimates to support location-specific decision-making and scenario modeling.
Regulatory Regimes, Demand Catalysts, and Structural Dynamics
Regulatory developments have become a central force shaping product design, sourcing strategy, and market access. In 2025, the United States Food and Drug Administration granted Generally Recognized as Safe status to additional chlorella and spirulina strains, broadening the pool of qualifying ingredients for food and supplement applications. Concurrently, the European Food Safety Authority and the United States Pharmacopeia tightened contaminant thresholds for algae-based ingredients, raising the bar for quality assurance and process control. These stricter specifications reward producers with robust purification capabilities and traceable cultivation practices, while raising the cost of compliance for less mature operators.
At the same time, novel-food pathways are expanding the commercial envelope. The European Food Safety Authority granted novel-food approvals for algae-derived omega-3 oils and phycocyanin colorants, enabling product developers to incorporate these ingredients into regulated food categories that previously restricted their use. These approvals do not simply open new SKUs; they alter the value proposition of algae-based inputs by enabling substitution for marine-derived and synthetic alternatives in premium formulations. For marketers and R&D teams, this translates into longer development cycles, more rigorous documentation, and higher technical validation requirements, but also into stronger differentiation and margin potential in approved applications.
Demand-side catalysts continue to reinforce growth momentum. Health-conscious consumers are actively seeking natural, plant-based alternatives to fish oil for omega-3 supplementation, driven by concerns over ocean sustainability, taste preference, and allergen considerations. This shift is not limited to niche wellness circles; it is increasingly visible in mainstream retail, e-commerce, and food service environments. At the same time, industrial and food manufacturing customers are evaluating algae-based ingredients for functional performance, sustainability credentials, and supply chain resilience. The combination of consumer preference and B2B formulation needs creates a reinforcing demand loop that supports volume expansion across supplements, food and beverages, and animal feed.
Strategic Decision Framework for 2026 and Beyond
As organizations plan through 2026 and toward the end of the decade, several strategic priorities emerge from the market structure and competitive behavior observed to date. First, portfolio alignment should reflect the interplay between product potency, application specificity, and regulatory readiness. High-potency omega-3 oils, certified spirulina and chlorella strains, and approved colorants each command different commercial logics, and companies must decide whether to pursue broad ingredient platforms or concentrated specialty positions. Second, supply chain design should account for regional concentration, contamination control requirements, and the growing premium on traceable, sustainable cultivation methods. Third, R&D and partnerships should target the convergence of bioprocessing technology, strain optimization, and downstream formulation, as these are increasingly the sources of durable advantage rather than scale alone.
Algae Products Market
Competitive positioning will also depend on the ability to interpret and act on high-level market signals with precision. Aggregated growth figures provide direction, but the actionable intelligence lies in understanding where specific product types, application categories, and regional markets create asymmetric opportunities or risk exposures. Pricing dynamics, capacity utilization, regulatory approvals, and customer procurement cycles all vary by segment and require dedicated analysis. Leaders who invest in this level of detail will be better prepared to negotiate supply terms, prioritize innovation investments, and respond to competitor moves with greater speed and confidence.
The report accompanying this overview delivers the depth required to turn macro signals into operational decisions. It combines historical and forecast market sizing with detailed segmentation, competitive profiling, recent developments tracking, and regulatory context across the forecast window. By linking market structure to strategic action, it provides a practical foundation for market entry planning, investment prioritization, and portfolio optimization. For teams responsible for 2026 planning cycles, the full research offers the granularity necessary to move from directional confidence to precise execution.
For detailed analysis of this topic, please visit the official page: Algae Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Swab Market Hits $3.76B in 2025, Projects 6.98% CAGR Through 2032
By pmarketresearch, 2026-09-15
The Diagnostic Edge: Why the Medical Swab Market Demands Strategic Clarity in 2026
In the global healthcare ecosystem, few consumables are as unassuming yet operationally critical as the medical swab. From nasopharyngeal specimen collection to wound care and disinfection protocols, these devices form the frontline interface between patient biology and diagnostic accuracy. As the industry moves through a period of post-pandemic normalization, regulatory tightening, and supply chain maturation, the medical swab market is entering a phase of structured growth driven by diagnostics demand, material innovation, and compliance enforcement. Our latest market research delivers the analytical rigor required to navigate this landscape, translating historical trajectories and forward-looking forecasts into actionable intelligence for executive decision-making.
The strategic value of this study lies in its capacity to replace assumption with evidence. By mapping the market from 2020 through a forecast horizon extending to 2032, we provide a continuous view of demand evolution, capacity expansion, and competitive repositioning. The report is designed not as a static data repository, but as a decision-support instrument for procurement leaders, product strategy teams, investors, and regulatory affairs professionals who must anticipate volume shifts, evaluate supplier options, and align portfolio roadmaps with emerging compliance requirements.
Market Architecture: Trajectory, Scale, and Structural Signals
The medical swab market has demonstrated consistent expansion over the past half-decade, evolving from a crisis-amplified procurement category into a stabilized, clinically embedded supply stream. Historical data from 2020 to 2025 captures this transition, showing a clear upward arc in total revenue as diagnostic testing volumes, routine clinical usage, and wound-care consumption converged. The base-year snapshot for 2025 anchored the market at a substantial multi-billion-dollar level, reflecting the consolidation of swab-based workflows into everyday laboratory, hospital, and point-of-care environments.
Building on that foundation, the forecast period from 2026 to 2032 projects sustained momentum, with the market expected to reach an annual revenue level exceeding six billion USD by 2032. This growth trajectory is underpinned by a compound annual growth rate of 6.98 percent, signaling steady, above-inflation expansion rather than speculative surges. For corporate planners, that rate is meaningful because it implies a market where incremental volume gains, product mix optimization, and service-level improvements can compound into defensible market positions.
Crucially, the report avoids siloing these figures in isolation. Instead, it situates the macro trajectory within the operational realities that shape it: the ongoing shift toward flocked and non-woven formats for specimen collection, the persistent demand for sterile cotton and gauze swabs in clinical wound care, and the expanding utility of swabs in disinfection and ancillary procedures. The narrative structure ensures that revenue trends are interpreted through the lens of end-use behavior, material preference, and regional procurement patterns, giving readers a coherent map of where growth is originating and how it is likely to propagate.
Competitive Arena: Incumbents, Innovators, and the Push for Differentiation
The competitive landscape in the medical swab market is characterized by a blend of established medical-device manufacturers, diagnostic-focused specialists, and regional producers with expanding compliance credentials. Market concentration data indicates a moderately consolidated environment, with the top three players holding a combined share of roughly 35 percent and the top five approaching 47 percent. This structure suggests that while scale and regulatory clearance confer advantages, there remains meaningful room for differentiated offerings, particularly in specimen-collection performance, single-use sterility assurance, and regionally tailored distribution.
Puritan Medical Products, headquartered in Guilford, Maine, exemplifies the U.S.-centric, compliance-forward posture that has become a competitive differentiator. Its product portfolio spans medical-grade sterile and non-sterile swabs, flocked formats such as HydraFlock and PurFlock, and the PurSafe Plus collection and transport system, which has been cleared by the FDA for rapid diagnostics including SARS-CoV-2. In October 2025, the company introduced an FDA-cleared PurSafe Plus system designed for rapid SARS-CoV-2 inactivation and preservation with turnaround under one hour, manufactured entirely in the United States. This launch underscores how domestic production, regulatory clearance, and time-to-result performance are being leveraged as strategic assets.
Copan Diagnostics, with its Italian heritage and U.S. operational footprint, has built its reputation around FLOQSwabs flocked swabs engineered for optimal specimen collection in microbiology and diagnostics. In August 2024, the company published an evaluation of its FecalSwab effectiveness for enteric pathogen detection on the BD MAX system, illustrating a broader industry tendency to validate swab performance against specific diagnostic platforms and workflow requirements. Such validation activity is increasingly relevant as laboratories and procurement teams seek documented performance evidence rather than relying solely on material specifications.
Other significant participants reinforce the breadth of the competitive field. Dynarex Corporation in Orangeburg, New York, supplies sterile cotton swabs and medical swabs for clinical, laboratory, and diagnostic applications. GPC Medical Ltd in India manufactures medical gauze swabs, cotton swabs, and related wound-care consumables, reflecting the role of cost-competitive, high-volume producers in the broader supply architecture. Medline Industries, LP, based in Northfield, Illinois, provides cotton swabs, gauze swabs, and medical disposables to hospitals and healthcare facilities, embedding swab procurement within broader infection-prevention and clinical supply portfolios.
In Europe, Sarstedt AG & Co. KG in Germany offers laboratory swabs and medical sampling swabs, including forensic and diagnostic variants, supporting specialized applications that demand precise sample integrity. BD, the Becton, Dickinson and Company, supplies flocked and cotton swabs for microbiology, diagnostics, and specimen collection, extending its influence through a diversified diagnostics and care portfolio. Meanwhile, a cluster of Chinese manufacturers—including Hubei Baikang Medical Instrument Co., Ltd. (BKAMED), Winner Medical Co., Ltd., Shenzhen Huachenyang Technology Co., Ltd., and Jiangsu Huida Medical Instruments—contributes gauze swabs, cotton-based swabs, and flocked formats with varying levels of compliance documentation. Notably, Shenzhen Huachenyang emphasizes ISO 13485, CE, and FDA compliance for sampling and diagnostics, indicating that regulatory credentialing is becoming a key gate for expanding access to higher-value diagnostic channels.
For decision-makers, the competitive picture is not merely a roster of names. It is a map of capability clusters: U.S. and European firms with strong regulatory and diagnostic-validation positioning, large healthcare distributors integrating swabs into broader consumables ecosystems, and Asian manufacturers scaling capacity while selectively pursuing compliance milestones. The report examines how these clusters interact across procurement channels, hospital group purchasing organizations, and diagnostic-lab supply chains, helping readers identify where substitution risk is highest and where partnership or sourcing strategies can be optimized.
Regulatory Pressures and Supply Chain Realities
The medical swab market does not operate in a regulatory vacuum. FDA oversight has become an increasingly prominent force shaping product design, manufacturing controls, and distribution practices. In mid-2025, the FDA highlighted voluntary recalls for medical swabs, including nasal swabs, citing microbial contamination risks that are especially concerning for vulnerable populations such as children and immunocompromised individuals. This reminder of contamination risk reinforces why sterility assurance, packaging integrity, and lot-level traceability have moved from operational concerns to strategic imperatives.
A further regulatory inflection point involves laboratory-developed tests. A proposed FDA final rule on LDTs would classify them as in vitro diagnostic products, phasing out enforcement discretion for premarket review and quality system requirements, with the transition taking effect in February 2026. As LDT frameworks tighten, the downstream implications for specimen-collection devices are significant: laboratories seeking compliance may increasingly prioritize swabs with documented performance, consistent lot quality, and compatibility with validated workflows. This shift favors suppliers able to provide not just products, but the evidentiary support that laboratories need for their own regulatory positioning.
In parallel, FDA-authorized at-home OTC COVID-19 diagnostic tests continue to require self-collection with approved swabs or equivalent devices, with updated authorization lists effective into 2026. This requirement sustains demand for swabs that meet self-collection usability standards while maintaining analytical performance. The intersection of consumer-facing testing and professional diagnostics creates a bifurcated demand environment, where product design, packaging, and instructions-for-use clarity can be as influential as raw material selection.
Supply chain exposure remains a structural consideration. Sterile cotton swabs and gauze swabs are standard medical consumables used in FDA-regulated diagnostic testing and wound care, and historical supply chain reports have documented exposure during prior demand surges. The lesson for procurement leaders is that resilience depends on diversified sourcing, visibility into raw-material inputs, and contingency planning for sterile-processing capacity. Our research addresses these issues by mapping supplier readiness, compliance posture, and regional sourcing patterns, allowing organizations to stress-test their supply strategies against plausible disruption scenarios.
Quality incidents also serve as practical reminders of risk. In March 2026, a voluntary nationwide recall was issued for Webcol Large Alcohol Prep Pads due to potential microbial contamination, impacting more than 170 million units. While this event centered on alcohol prep pads rather than swabs per se, it illustrates the broader sterilization and packaging vigilance required across adjacent medical consumables categories. The market’s response to such events typically accelerates scrutiny of supplier quality systems and encourages buyers to formalize acceptance criteria beyond price and lead time.
What the Report Delivers: From Insight to Execution
This market research is built to support practical decision-making across multiple functions. Rather than stopping at aggregate market sizing, the study moves into the operational details that executives and category managers need to act with confidence. The report integrates demand drivers, product-format dynamics, regional procurement behavior, competitive positioning, and regulatory context into a unified analytical framework.
Medical Swab Market
Inside the report, readers will find:
- A structured analysis of market evolution from 2020 through 2032, with clear separation between historical performance and forecasted trajectory.
- An examination of product-type dynamics across sterile cotton, flocked, foam-tipped, non-woven, and other formats, linked to their respective clinical and diagnostic use cases.
- A regional assessment of demand distribution and procurement characteristics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, framed in terms of market access, supplier presence, and growth potential.
- A deep competitive review of leading manufacturers, their core offerings, compliance positioning, and recent developments that signal strategic direction.
- An evaluation of application-side demand across specimen collection, disinfection, and other clinical uses, showing how volume concentration and workflow requirements shape sourcing priorities.
- A regulatory and supply chain section that connects FDA actions, LDT policy changes, at-home test requirements, and contamination-recall precedents to procurement and product-design decisions.
- Forward-looking scenarios that help teams anticipate how demand, compliance, and competitive intensity may evolve under different operational conditions.
Each section is designed to be usable on its own while contributing to an integrated view. Procurement teams can use the supplier and region analysis to refine sourcing briefs and evaluate risk exposure. Product and R&D leaders can reference the format and application analysis to inform material selection, sterility strategy, and packaging decisions. Strategy and investment teams can draw on the macro trajectory and competitive concentration data to assess market attractiveness, entry timing, and partnership opportunities. Regulatory and quality functions can use the compliance narrative to anticipate documentation expectations and align internal controls with emerging enforcement patterns.
Strategic Implications for 2026 and Beyond
As the market moves deeper into the 2026–2032 forecast window, several strategic themes become increasingly important. First, the growth rate suggests that broad, undifferentiated participation will be less rewarding than targeted positioning. Companies that can demonstrate measurable advantages in specimen release, sample integrity, sterility assurance, or platform compatibility are better placed to capture value in diagnostic-intensive segments, while those competing primarily on volume must manage cost, consistency, and supply reliability with exceptional discipline.
Laboratory Swabs Market
Second, regulatory momentum is tilting the market toward documentation and validation. With LDT oversight tightening and at-home test requirements evolving, the ability to provide clear evidence of performance and quality control is becoming part of the commercial proposition. Suppliers that treat regulatory readiness as a strategic capability, rather than a periodic compliance exercise, will have an advantage in securing long-term contracts with laboratories, hospital systems, and distributor networks.
Third, supply chain diversification remains essential. The combination of sterility requirements, contamination-risk precedents, and historical surge exposure means that single-source dependency can create outsized vulnerability. Organizations should assess not only unit pricing and lead times, but also manufacturing geography, sterilization capacity, quality-system maturity, and contingency readiness. In this context, the report’s supplier and regional analysis offers a basis for constructing more resilient sourcing architectures.
Fourth, product mix strategy matters more than ever. As specimen-collection workflows become more specialized and disinfection and wound-care applications continue to consume standard sterile formats, the most effective portfolios are those aligned to real workflow economics rather than generic category assumptions. Understanding which formats are gaining traction, where substitution is plausible, and how procurement specifications are changing enables more precise portfolio planning and pricing strategy.
How to Use This Research
This study is intended to be a working document for strategic planning, not a one-time read. Teams can use it to benchmark current assumptions, pressure-test procurement options, and identify the data points needed for internal business cases. For organizations evaluating market entry, expansion, or supplier consolidation, the competitive and regional analysis provides the kind of structured context that reduces uncertainty before capital or sourcing commitments are made.
Because the report deliberately moves from macro trajectory to operational detail, it supports both top-line strategy discussions and granular category reviews. Executives can rely on the revenue and growth framework to frame market opportunity, while operational teams can drill into supplier profiles, format trends, application dynamics, and regulatory developments to build executable plans. The goal is to make the intelligence directly usable, so that the time between insight and action is minimized.
Next Steps: Access the Full Intelligence
The overview presented here captures the analytical direction and strategic framing of the full study, but the complete report contains the detailed segmentation, supplier-by-supplier assessment, regional demand dynamics, application-level market structure, and forward scenario analysis that executives need for confident decision-making. The depth of the segmentation data, the competitive profiles, and the regulatory mapping are designed to support precise planning discussions across sourcing, product strategy, compliance, and investment functions.
To explore the full market sizing trajectory, the segmentation architecture, the competitive landscape, and the operational implications in detail, access the complete medical swab market research on our website. The full report provides the comprehensive intelligence necessary to translate market momentum into structured, defensible strategy for 2026 and the forecast years ahead.
For detailed analysis of this topic, please visit the official page: Medical Swab Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Headless Compression Screws Market Hits $312.8M in 2025, Growing at 4.1% CAGR to 2032
By pmarketresearch, 2026-09-15
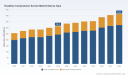
The Strategic Imperative of Headless Compression Screws in 2026 Orthopedic Markets
Executive Vision
The global market for headless compression screws has entered a phase of steady, methodical growth that rewards precision planning over reactive expansion. As orthopedic surgery continues to prioritize minimally invasive fixation, reduced soft-tissue compromise, and faster postoperative mobilization, headless compression screws have secured an irreplaceable position in the small-bone and extremity trauma playbook. Our latest market research places the industry trajectory in sharp relief: a global revenue base of 312.8 million USD in 2025, expanding to 334.77 million USD in 2026, and continuing its upward march toward 414.4 million USD by 2032. With a forecast-period CAGR of 4.1 percent, the sector reflects a mature but persistently expanding landscape where operational efficiency, clinical differentiation, and supply-chain discipline determine who captures disproportionate share.
For executive teams navigating 2026 planning cycles, this research is not a static snapshot. It is a working decision tool. The report translates granular market mechanics into actionable intelligence on product mix, application priorities, regional corridors of opportunity, competitive positioning, regulatory exposure, and raw-material economics. The narrative below previews the strategic architecture of the study and illustrates how its findings can be operationalized for portfolio strategy, commercialization roadmaps, and risk management.
Headless Compression Screws Market
Market Architecture and Trajectory
The historical record from 2020 through 2025 reveals a market that has weathered macroeconomic pressure while maintaining constructive momentum. Revenue moved from 255.87 million USD in 2020 to 273.88 million USD in 2021, reached 285.71 million USD in 2022, and experienced a brief plateau near 285.46 million USD in 2023 before resuming expansion to 299.86 million USD in 2024. This cadence signals resilient demand rooted in surgical practice patterns, rather than a cyclical surge dependent on transient tailwinds. The market closed 2025 at 312.8 million USD and opens 2026 at 334.77 million USD, with subsequent years advancing through 341.28 million USD in 2027, 352.24 million USD in 2028, 354.84 million USD in 2029, 387.98 million USD in 2030, 405.48 million USD in 2031, and 414.4 million USD in 2032.
This growth arc is not uniform, and that unevenness is where value is created. The report decomposes the market by type, by application, and by region, and then integrates those splits with pricing logic, procedural volume assumptions, and competitive overlap to reveal where growth concentrates and where margins compress. Rather than presenting segment figures in isolation, the study arranges them into a decision framework that helps leaders identify which product categories justify expanded capacity, which applications offer the best clinical-commercial alignment, and which geographies provide the most efficient route to scale. We intentionally reserve the exact regional and application percentage breakdowns for the full report, since those layers interact with reimbursement, surgeon adoption curves, and distribution reach in ways that can be misinterpreted when read out of context.
Concentration dynamics reinforce the need for disciplined strategy. The market is not a commodity arena; a relatively small group of manufacturers controls a substantial portion of revenue, with the top three firms accounting for approximately 57 percent and the top five capturing roughly 65 percent. This structure rewards differentiation, technical credibility, and trusted surgeon relationships. It also means that late movers must find a clearly defined value proposition, whether through design innovation, service reliability, pricing architecture, or specialized clinical support, to avoid competing solely on access and availability.
Segmentation Depth as a Decision Engine
A core strength of this report is the way it translates segmentation into operational guidance. By type, the market divides between fully threaded screws and both-ends threaded screws, each with distinct mechanical behaviors, insertion characteristics, and clinical use patterns. Fully threaded designs typically dominate volume in applications where uniform compression and fragment stability are paramount, while both-ends threaded configurations serve select procedural needs where targeted fixation and construct flexibility are prioritized. The research evaluates how these categories map to procedural mix, surgeon preference, inventory requirements, and manufacturing complexity.
Cannulated Compression Headless Screws Market
By application, the study examines the clinical territories where headless compression screws are most consequential. Small-bone and extremity procedures in the hand, wrist, foot, and ankle form the operational core of demand, with additional volume coming from adjacent indications. The report connects each application area to the implant dimensions, material grades, instrumentation needs, and surgical techniques that influence adoption. It also explores the practical implications for product development teams: where miniaturization and variable-pitch geometry drive surgeon preference, where cannulation and biocompatibility elevate repeat usage, and where broader footprint systems open room for integrated fixation platforms.
Regional analysis is developed as a deployment roadmap rather than a simple map of current sales. The report assesses how mature markets differ from emerging ones in terms of purchasing dynamics, hospital procurement cycles, ambulatory migration, surgeon training pathways, and the competitive intensity facing new entrants. It identifies which regions are best suited for volume expansion, which require clinical evidence and service investment, and which present tactical opportunities through partnership, distribution, or focused indication targeting. Detailed regional figures and application-level shares are preserved within the full study so that leadership can evaluate them alongside internal pipeline assumptions and market-access realities.
Competitive Landscape and Strategic Positioning
The competitive set in headless compression screws reflects a mix of globally scaled orthopedic platforms and highly specialized small-bone fixation experts. DePuy Synthes anchors a broad trauma and extremities portfolio with its Synthes Headless Compression Screws series, offered in multiple diameters and available in titanium and stainless variants for small-to-large bone fracture fixation. Its scale and clinical reputation make it a reference point for the market, even as individual product events periodically reset risk expectations and quality commitments. Acumed LLC competes with a focused small-bone philosophy, exemplified by the Acutrak systems, whose variable-pitch cannulated titanium architecture has become closely associated with scaphoid, metacarpal, and other small-fragment indications. Zimmer Biomet contributes with headless compression and twist-off systems designed for intra-articular and extra-articular stabilization in foot and ankle procedures, while Arthrex extends its presence through compression designs that span foot, ankle, hand, wrist, and small-bone applications.
The landscape also includes companies with distinctive positioning. Rita Leibinger GmbH & Co. KG emphasizes cannulated compression screws for corrective osteotomies and selected fracture scenarios, reflecting a strong European engineering heritage. Stryker supports headless compression screw workflows through enabling systems that reinforce surgical precision in orthopedic trauma and small-bone fixation. Trax Surgical pursues a differential-pitch compression philosophy with FDA-registered and ISO 13485 aligned manufacturing, an approach that appeals to customers seeking procedural reliability and documented quality controls. TriMed Inc. offers titanium and stainless options across a practical dimension range for hand, foot, and ankle fixation, while TST Orthopedics structures its offering around a compact set of size options for precise fixation and osteotomy placement. Bonetech Precision adds a China-based precision manufacturing presence with titanium alloy solutions for fracture and non-union repair, illustrating the broader geographic spread of capability building.
Recent developments show that competitive advantage is increasingly shaped by execution events as well as product design. In early 2026, DePuy Synthes initiated a Class 2 device recall for certain 3.0 mm headless compression screws, a reminder that quality systems and field vigilance remain central to brand trust, even for well-established lines. In January 2026, Acumed reinforced its small-bone platform with the release of an updated surgical technique guide for its Acutrak 3 system, accompanied by expanded 2.0 mm Nano screw options and length extensions, underscoring how technique documentation and dimensional breadth can strengthen adoption. In July 2025, Zimmer Biomet announced a strategic partnership with Getinge to distribute operating room products, including orthopedic implants such as headless compression screws, to ambulatory surgery centers, highlighting the commercial importance of channel expansion as surgical care continues moving toward lower-acuity settings. The report situates these events within broader competitive dynamics rather than treating them as isolated headlines, helping leadership assess implications for purchasing confidence, surgeon behavior, and channel strategy.
Industry Dynamics Shaping 2026 Decisions
Several structural forces continue to define how the market behaves and where strategic leverage lies. Surgical migration toward ambulatory and outpatient environments is changing how suppliers approach inventory, sterilization compatibility, tray design, and procedure efficiency. As clinicians seek to reduce operative time and soft-tissue disruption, headless compression screws remain attractive because they allow compression across fracture or osteotomy sites without prominent hardware that can irritate surrounding tissue. At the same time, the specification of titanium grades and alloy choices influences both clinical performance and cost structure. Commercial-grade titanium has moved within a range of roughly 8 to 15 USD per pound in mid-2026, while aerospace-grade Ti-6Al-4V has traded at higher levels, and titanium scrap has remained a meaningful offset within procurement planning. These input costs form the backdrop for pricing strategy, margin management, and make-versus-buy decisions across the value chain.
Standards and clinical protocols also continue to stabilize demand by reinforcing confidence in specific screw dimensions for defined repair scenarios. For example, the AO Foundation maintains approval and licensing for the use of 4.5 mm and 6.5 mm headless compression screw solutions in fracture and deformity correction, a reference point that shapes surgeon familiarity and implant selection logic. Regulatory events, material availability, and procedural standardization together create a market environment where consistency matters as much as innovation. The report examines these dynamics as interacting forces, not as separate lists, so that readers can evaluate how product engineering, quality assurance, procurement timing, and clinical education reinforce one another.
Inside the Report: What Decision-Makers Will Gain
This research is designed to convert market complexity into executable strategy. It provides a comprehensive view of market size and growth, with historical calibration and a forward forecast that supports planning through 2032. Beyond the headline numbers, the study maps the segmentation architecture in a way that supports product planning and commercialization choices. It analyzes the competitive landscape by company profile, product philosophy, and recent strategic moves, allowing readers to benchmark their own positioning and identify gaps in capability, coverage, or clinical messaging.
The report also integrates industry context into the analysis. It addresses regulatory considerations and quality events as factors that influence purchasing and brand trust. It incorporates raw-material cost conditions to inform margin planning and sourcing strategy. It considers clinical protocol standards as part of the adoption environment. In addition, the study is structured to support practical questions that executive teams face in 2026: where to concentrate R&D and portfolio investment, which application areas offer the strongest alignment between clinical need and commercial return, how regional opportunities should be prioritized, and what competitive responses are most likely from incumbents and niche specialists alike.
To preserve analytical integrity, the report avoids overstating precision where assumptions remain sensitive to local reimbursement, surgeon behavior, and channel access. Instead, it presents a layered view in which top-line trajectory, concentration structure, segment relationships, and competitive events can be read together. This approach helps organizations avoid the common trap of interpreting a single figure in isolation, and instead focus on the interactions that actually drive outcomes.
Translating Intelligence into 2026 Action
For companies operating in or entering this market, the strategic conclusions are consistent. First, growth is real but disciplined, so portfolio strategy should be built around durable demand signals rather than speculative spikes. Second, concentration in the competitive field means that differentiation must be credible, clinically meaningful, and supported by dependable execution. Third, segmentation is not a taxonomy exercise; it is the basis for prioritizing dimensions, materials, instrumentation, and service levels that match surgical reality. Fourth, recent regulatory and commercial events demonstrate that quality, technique support, and channel strategy are as important as implant design in winning and retaining share.
The full study extends these themes with the detailed figures, regional breakdowns, application-level shares, and competitive analysis required to build investment cases, sales plans, and risk controls. It is intended for leaders who need a rigorous foundation before committing resources, whether the objective is to expand an existing line, enter a specific application zone, strengthen distribution in a chosen region, or anticipate competitor moves with greater confidence. The preview above establishes the strategic logic behind the research; the complete report delivers the numbers, comparisons, and scenario-ready detail that turn logic into action.
In a market moving from 334.77 million USD in 2026 toward 414.4 million USD in 2032, with a forecast CAGR of 4.1 percent and a concentrated competitive structure, the winners will be those who combine evidence with discipline. Our research is built to give them exactly that: a clear view of where value is forming, how the competitive field is evolving, and what decisions are most likely to create durable advantage in the years ahead.
For detailed analysis of this topic, please visit the official page: Headless Compression Screws Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: INP Market Hits 215 Million in 2025, 5.5% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Isophthalonitrile Market: A 2026 Decision-Making Framework
The global chemical landscape is undergoing a structural shift where specialty intermediates are no longer mere commodities but strategic assets. As we enter 2026, the Isophthalonitrile (INP) market stands at a critical juncture, defined by evolving supply chains, stringent purity requirements, and geopolitical realignments. For executives navigating this complexity, the ability to distinguish between transient volatility and long-term structural growth is paramount. This insight serves as an introduction to our comprehensive market research, designed to equip stakeholders with the intelligence needed to capitalize on emerging opportunities while mitigating systemic risks.
Market Trajectory and Historical Context
Understanding the trajectory of the INP market requires a look at the consistent growth pattern observed over the past half-decade. From a valuation of approximately 163.15 million USD in 2020, the market has demonstrated resilience and expansion, reaching an estimated 215.0 million USD by 2025. This growth is not merely linear but reflects accumulating demand across high-tech and industrial sectors. The momentum continues into the forecast period, with projections indicating the market will approach 233.0 million USD in 2026 alone. Looking further ahead, the upward trend is expected to sustain, driven by deepening integration of INP into specialized manufacturing processes that prioritize performance and durability.
However, the narrative is not just about top-line revenue. The compound annual growth rate (CAGR) of 5.5 percent through 2032 suggests a steady, mature expansion rather than a speculative boom. This stability is crucial for capital allocation decisions. Companies must recognize that while the growth is robust, it is embedded within a larger ecosystem subject to external shocks. The historical data from 2020 to 2025 shows a market that has absorbed disruptions and continued to climb, yet the forecast period from 2026 to 2032 introduces new variables. The peak values projected around 2032 imply a significant maturing of the market size, requiring strategic planners to anticipate capacity needs and investment horizons well in advance.
Segmentation Dynamics and Strategic Focus
The value distribution within the INP market reveals where strategic attention must be directed. Our analysis breaks down the market across regions, types, and applications, each presenting distinct opportunities. Geographically, the demand is dispersed across major global zones, with North America, Europe, and Asia Pacific representing significant pillars of consumption. Each region carries its own regulatory environment and supply chain characteristics. For instance, while certain regions show higher revenue contributions in the baseline data, the strategic value lies in understanding the growth velocity and risk profile associated with each territory. Latin America and the Mideast and Africa also contribute to the global tally, offering niche opportunities for market penetration, though often with different risk-return profiles compared to established industrial hubs.
On the product side, purity levels define the value proposition. The market is segmented around different purity grades, with higher purity variants commanding significant attention due to their application in sensitive industries. The data indicates a heavy reliance on specific purity standards that align with downstream manufacturing needs. As electronic and pharmaceutical applications demand tighter tolerances, the ability to supply premium grade materials becomes a competitive moat. Similarly, the application landscape is dominated by specific derivatives and intermediates. The largest share of consumption is tied to key chemical derivatives used in advanced materials, while other segments like agrochemicals and miscellaneous industrial uses contribute to the diversified demand base. Understanding the weighting of these segments is essential for pricing strategies and production planning, though specific percentage breakdowns are reserved for the full report to maintain strategic granularity.
Competitive Landscape and Industry Concentration
Oligopolistic Structure and Key Players
The INP market is characterized by a high degree of concentration, which fundamentally shapes competitive dynamics. With a CR3 of 85.0 percent and a CR5 of 90.0 percent, the market is tightly held by a few dominant entities. This oligopolistic structure implies that pricing power and supply stability are heavily influenced by the strategic moves of these key players. For new entrants or existing companies seeking to expand market share, this concentration presents both a barrier and an opportunity to identify gaps left by incumbents.
Among the prominent entities shaping this landscape are Mitsubishi Gas Chemical Company, Inc., headquartered in Tokyo, Japan. As an active producer within its Green Energy & Chemicals Business Sector, the company leverages its scale to serve synthetic resins and electronics applications. Their positioning highlights the integrated nature of chemical manufacturing where energy and chemical portfolios converge to optimize costs and environmental impact. In China, Jiangsu Weunite Fine Chemical Co., Ltd., based in Xinyi, operates as a significant producer focusing on fine chemical intermediates for agrochemicals and electronics. Their activity underscores the role of Chinese manufacturing hubs in the global value chain, particularly where cost efficiency meets technical capability. Another key player, Suli Co., Ltd., located in Shanghai, China, focuses on pharmaceutical and fine chemical intermediates. Their profile suggests a specialization in high-value downstream applications, reflecting a trend where suppliers align closely with specific end-user industries to secure demand stability.
Polyacrylonitrile (PAN) Market
These companies do not operate in a vacuum. Their strategies are influenced by raw material availability and regulatory environments. The high concentration means that competitors must closely monitor the production adjustments of these leaders. A supply cut or a capacity expansion by any of the top players can ripple through the market, affecting availability and pricing for downstream users. Therefore, strategic procurement and partnership negotiations require insights into the operational statuses and investment plans of these specific entities.
Industry Dynamics and Risk Factors
Raw Material Volatility
One of the persistent challenges facing the Isophthalonitrile market is the fluctuation in raw material prices. This volatility poses a direct challenge to market stability and margin preservation. Manufacturers relying on specific precursors must navigate price swings that can erode profitability or force pass-through costs that risk demand elasticity. Our analysis delves into the correlation between upstream feedstock costs and INP pricing structures. Understanding these linkages allows companies to implement hedging strategies or long-term contracting models that safeguard against unexpected cost surges. The sensitivity of the market to input costs means that procurement teams must remain agile, balancing inventory levels with cost forecasts to maintain competitive pricing without sacrificing margins.
Regulatory and Geopolitical Pressures
The regulatory environment adds another layer of complexity to market operations. Notably, recent years have seen significant shifts in export controls regarding critical materials. China enacted export controls on gallium and germanium, elements critical for related compound semiconductors, during 2023-2024. These restrictions have ongoing implications into 2026 and beyond. While these materials are distinct from INP, the broader context of supply chain security and regulatory friction affects the entire electronics and high-tech materials ecosystem. Companies producing INP for electronics applications must factor in the potential for tightened export regulations, logistics bottlenecks, or retaliatory measures that could disrupt cross-border trade. This geopolitical backdrop necessitates a diversification of supply chains and a careful assessment of regulatory risk in key manufacturing and consumption zones.
Strategic Value of the Full Report
While this overview highlights the macro trends and competitive structure, it only scratches the surface of the intelligence required for decisive action in 2026. The full Isophthalonitrile Market Report provides a granular dissection of the data needed to formulate robust strategies. Decision-makers need access to detailed segmentation splits that quantify the exact revenue contribution of each region, type, and application without relying on estimates. For example, knowing the precise market size contribution of specific purity grades versus standard grades can determine R&D prioritization. Similarly, understanding the exact consumption volumes in key application sectors like m-Xylylenediamine production versus pesticide intermediates allows for targeted sales efforts and capacity allocation.
Isophthalonitrile (INP) Market
Furthermore, the report offers a deep dive into the competitive profiles of the key companies. Beyond the basic headquarters and activity summaries, the full analysis includes potential strategic moves, technological capabilities, and market positioning nuances that are not publicly advertised. This intelligence is vital for merger and acquisition assessments, partnership evaluations, and competitive benchmarking. The report also contextualizes the recent developments and industry noise within a structured forecast model. It translates the raw data on market concentration and historical growth into actionable scenarios. By accessing the complete intelligence package, stakeholders can move from general awareness to specific, data-backed planning. The detailed regional analysis helps in identifying not just where the market is, but where the growth pockets are emerging. The application breakdown reveals which downstream industries are driving demand acceleration, enabling suppliers to align their production mixes accordingly.
Conclusion: Navigating the Future
As the Isophthalonitrile market moves through the forecast period, the interplay of high concentration, raw material sensitivity, and evolving regulatory landscapes will define success. The steady CAGR and projected revenue growth to over 311 million USD by 2032 indicate a healthy long-term outlook, but realizing value within this trajectory requires precise navigation. Companies that rely on surface-level data risk misallocating resources or missing nuanced shifts in demand drivers. The strategic imperative for 2026 is to secure the deepest possible understanding of market mechanics. This involves not only tracking the top-line numbers but also comprehending the underlying segmentation dynamics and the strategic intentions of the dominant players. Our comprehensive research is designed to provide that clarity, bridging the gap between abstract market trends and concrete business decisions. For executives ready to secure a competitive advantage in this specialized chemical sector, the detailed insights contained within the full report are an indispensable tool for charting the path forward.
For detailed analysis of this topic, please visit the official page: Isophthalonitrile (INP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: District Heating & Cooling Market to Reach $354B by 2032, 4.5% CAGR from 2026
By pmarketresearch, 2026-09-15
Unlocking Strategic Value in the District Heating and Cooling Market: A 2026 Decision-Maker's Guide
The global energy landscape is undergoing a seismic shift, driven by the dual imperatives of urbanization and decarbonization. At the heart of this transition lies the District Heating and Cooling (DHC) sector, a critical infrastructure network that is redefining how cities manage thermal energy. For enterprise leaders, investors, and policy strategists, understanding the trajectory of this market is no longer optional—it is a prerequisite for resilient planning in the coming decade.
PW Consulting's latest comprehensive study on the District Heating and Cooling Market offers a definitive roadmap for navigating this complex environment. This article serves as a strategic primer, highlighting the macro-economic forces, competitive dynamics, and regulatory tailwinds that define the sector through 2032. While we outline the broad contours of opportunity here, the full depth of our quantitative modeling and granular segmentation remains available within our proprietary report, designed specifically to empower high-stakes decision-making in 2026.
District Heating and Cooling Market
The Macro Trajectory: Growth Amidst Transformation
The DHC market has demonstrated remarkable resilience and expansion over the past half-decade. Drawing on historical data from 2020 through 2025, the sector has evolved from a niche utility model into a mainstream energy delivery mechanism. The market valuation has seen consistent upward momentum, reflecting increased investment in infrastructure and a growing preference for centralized energy systems that offer efficiency at scale.
Looking forward, the forecast period extending to 2032 projects a sustained growth trajectory. Our analysis indicates a Compound Annual Growth Rate (CAGR) that underscores the sector's maturity and its integral role in future energy mixes. This growth is not merely linear; it is compounded by technological innovations and policy shifts that are accelerating adoption rates in key urban centers globally. The revenue outlook suggests that by the end of the forecast window, the market will have substantially increased its contribution to the global energy economy, moving decisively toward higher valuation benchmarks.
However, raw market size figures only tell part of the story. The true value for 2026 strategists lies in understanding the velocity of this growth and the specific catalysts driving it. Our full report dissects these trends further, providing the nuanced intelligence required to time market entry, infrastructure investment, or partnership opportunities effectively.
Segmentation Dynamics: Diverse Opportunities Across the Value Chain
The District Heating and Cooling ecosystem is not monolithic. It is a layered market comprising distinct operational types, application verticals, and regional peculiarities. Understanding where value is generated within these layers is essential for targeted strategy.
At the core, the market is split between heating and cooling solutions. District Heating remains a substantial component of the revenue pool, driven by industrial needs and residential heating demands in colder climates. District Cooling, while smaller in total revenue share currently, represents a high-growth vector, particularly in regions facing intensifying heat waves and rapid urban development. The interplay between these two segments often converges in fifth-generation systems that offer bidirectional thermal energy exchange.
Application-wise, the market serves a triad of critical sectors. Industrial users leverage DHC for process heat and efficiency, representing a significant portion of demand. Residential applications are expanding as cities replace individual boilers with centralized systems to meet carbon targets. Commercial entities, including data centers and large-scale business districts, are increasingly turning to DHC for cooling solutions to manage high-density thermal loads. Each of these application verticals carries its own investment requirements, regulatory considerations, and return profiles.
Geographically, the market exhibits varied maturity levels. While established economies in North America and Europe continue to upgrade legacy infrastructure, the Asia Pacific region shows significant potential for new network deployments driven by rapid urbanization. Emerging markets in Latin America and the Mideast and Africa are also beginning to explore DHC as a solution for sustainable urban development, though at different stages of market evolution. Detailed regional analysis, including specific market contributions and growth rates by territory, is a cornerstone of our full study, enabling clients to prioritize geographies based on their risk appetite and operational capabilities.
Competitive Landscape: Innovators, Operators, and Strategic Moves
The competitive environment in the DHC sector is characterized by a mix of technology manufacturers, utility operators, and integrated energy service providers. Market concentration indicators suggest a moderately fragmented landscape, where strategic partnerships and M&A activity are reshaping the hierarchy.
Leading technology providers like Danfoss, headquartered in Nordborg, Denmark, play a pivotal role in enabling network efficiency. Their portfolio, ranging from advanced control valves to complete substation solutions, forms the hardware backbone of modern DHC systems. Manufacturers focusing on precision control and heat exchange technology are critical partners for operators seeking to optimize network performance and reduce thermal losses.
On the operational side, global giants are aggressively expanding their footprint. Veolia, based in Paris, operates and develops networks with a strong focus on fifth-generation systems utilizing geothermal and waste heat, aligning closely with decarbonization goals. Similarly, ENGIE maintains a massive presence as a global operator of heating and cooling networks across multiple countries, boasting significant production capacity in both heat and cooling. Their recent activities highlight the strategic nature of this sector. For instance, in April 2025, ENGIE secured a 13-year concession agreement with Rennes Métropole for a green district heating network powered by biomass and recovered energy. This project involves expanding the network by 78 kilometers to serve approximately 47,000 households, demonstrating the scale of infrastructure commitments being made.
Regional and specialized operators are also making significant strides. Fortum, headquartered in Helsinki, is leveraging innovative heat recovery strategies. In a notable development reported in May 2026, Fortum commenced operations at large-scale heat pump plants in Espoo, utilizing excess heat from Microsoft data centers. This initiative produces 180 MWh of district heating and covers 40% of the area's demand, showcasing the growing synergy between digital infrastructure and thermal energy networks. Fortum also plans for carbon-neutral supply by 2030, signaling a clear long-term strategic direction.
In the Middle East, Emicool, based in Dubai, continues to operate district cooling systems with a focus on energy-efficient cooling supply, catering to the region's specific climatic demands. Meanwhile, collaborations are deepening; in November 2025, ENGIE and Sunway advanced a strategic partnership to expand the Sunway Square district cooling system, targeting sustainable cooling for eight education group buildings with completion set for September 2026. Additionally, major plant inaugurations, such as Empower's Deira Waterfront district cooling plant in November 2025 with a production capacity of 39,000 RT, highlight the ongoing capital expenditure in high-capacity infrastructure.
Public funding is also catalyzing new entrants. Mijnwater received a EUR 13.5 million European Commission grant to develop a sustainable network in the Netherlands, illustrating how policy support enables project viability. The full report provides a detailed competitive benchmarking analysis, mapping the strategic positioning, financial health, and technology portfolios of key players to help you identify potential partners or competitive threats.
Regulatory and Environmental Dynamics: The Push for Decarbonization
No strategic analysis of the DHC market is complete without acknowledging the regulatory framework that underpins it. The sector is heavily influenced by government mandates and incentive structures aimed at accelerating the energy transition.
In Europe, the regulatory landscape is particularly robust. The EU Renewable Energy Directive includes binding national targets for increasing the share of renewables in district heating and cooling. Measures such as revised methodologies for counting renewable cooling performance are reshaping how projects are evaluated and funded. Furthermore, the EU Heating and Cooling Strategy is planned for publication in the second quarter of 2026 to support the implementation of current legislation, aiming to accelerate the decarbonization of the sector. This upcoming strategy is a critical signal for market participants, promising potential new guidelines, support mechanisms, or compliance requirements.
Financial incentives are also playing a crucial role. The LIFE-2025-CET-DHC call provides funding at up to 95% for proposals supporting efficient district heating and cooling networks that integrate renewable energy and waste heat. Such high levels of subsidy significantly de-risk projects and lower the barrier to entry for innovative solutions, making this a vital consideration for project finance and development teams.
Beyond regulation, the environmental imperative is a primary driver. District heating and cooling networks help decarbonize urban areas by leveraging local energy sources. Industry reports indicate that these networks helped avoid 1.9 Mt of CO₂ in 2025 alone. This tangible impact on carbon reduction strengthens the case for DHC as a cornerstone of climate action plans, attracting support from stakeholders focused on ESG objectives. However, the physical requirements remain substantial. District heating networks require extensive piping infrastructure and material components such as substations and valves, meaning capital intensity and supply chain considerations are integral to project planning.
Strategic Imperatives for 2026 Decision-Makers
As we move through 2026, the convergence of market growth, technological innovation, and regulatory pressure creates a unique window for strategic action. Organizations operating in or adjacent to the DHC space must consider several key imperatives.
First, alignment with decarbonization pathways is non-negotiable. Projects that integrate waste heat recovery, renewable sources, and high-efficiency technologies will likely secure preferential treatment in terms of funding, permitting, and public acceptance. The shift toward fifth-generation systems and the utilization of data center heat, as seen in recent developments, point to the types of hybrid solutions that will define the next generation of networks.
Second, understanding the competitive dynamics is essential for positioning. Whether you are a manufacturer seeking to expand your footprint, an operator looking for acquisition targets, or an investor evaluating portfolio exposure, the concentration levels and strategic moves of key players provide critical context. The market is seeing active consolidation and partnership formation, suggesting that agility and the ability to collaborate across the value chain will be key differentiators.
Third, geographic and application-specific intelligence is required to allocate resources wisely. The growth drivers in Asia Pacific may differ significantly from those in mature European markets. Similarly, the investment case for industrial heating may vary from that of residential cooling. A one-size-fits-all strategy is insufficient in a market this diverse.
Finally, the regulatory horizon must be monitored closely. With new strategies and directives on the cusp of implementation, the rules of engagement are evolving. Early adopters who anticipate and align with these changes will be better positioned to capture value as the market matures. The LIFE-2025-CET-DHC funding, for example, represents an immediate opportunity for eligible projects to secure significant financial support.
The Case for Deep Intelligence
The overview provided here sketches the broad landscape of the District Heating and Cooling Market, highlighting the growth trajectory, the key players, the segmentation nuances, and the regulatory forces at play. The market is on a clear upward path, driven by the necessity of efficient, low-carbon urban energy systems. However, for executives and analysts tasked with making concrete decisions in 2026, macro-level insights are only the starting point.
PW Consulting's full market research report goes far beyond this summary. It delivers the granular data, precise forecasts, and actionable intelligence needed to build robust business cases, identify high-potential segments, and navigate the competitive field with confidence. The report contains detailed segmentation splits by region, type, and application, offering the specific breakdowns required for targeted strategic planning. It includes comprehensive profiles of key companies, analysis of recent developments, and a deep dive into the regulatory and macro trends shaping the industry.
In a market defined by complex infrastructure requirements, evolving technologies, and shifting policy landscapes, information asymmetry is a competitive advantage. The complete report is designed to eliminate that asymmetry, providing the clarity needed to invest, expand, and innovate with precision.
We invite you to access the full study to unlock the complete dataset and strategic recommendations. The future of district energy is being written now, and the decisions made in 2026 will set the course for the next decade. Equip your organization with the intelligence it needs to lead.
Heat Cost Allocator Market
For detailed analysis of this topic, please visit the official page: District Heating and Cooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Conference Microphone Market Hits $215M in 2025, Projected 7.62% CAGR to $358.54M by 2032
By pmarketresearch, 2026-09-15
Navigating the Evolution of the Conference System (Microphone) Market: Strategic Intelligence for 2026 Leadership
Executive Summary
The modern conference environment is no longer defined by simple audio capture. It is a complex integration of digital signal processing, hybrid connectivity, and user-centric interface design. As organizations worldwide prioritize seamless collaboration across distributed teams, the Conference System (Microphone) Market has emerged as a critical infrastructure sector. Our latest market research provides a comprehensive examination of this landscape, offering enterprise leaders, procurement strategists, and technology officers the data required to navigate capital allocation and vendor selection in 2026 and beyond.
This report serves as a strategic compass. It moves beyond surface-level observations to deliver actionable intelligence on revenue trajectories, competitive positioning, and the technological forces reshaping audio communication in professional spaces. By understanding the magnitude of growth and the nuances of segmentation, stakeholders can anticipate shifts in supply chain dynamics, regulatory compliance, and end-user expectations.
Market Trajectory and Growth Fundamentals
The financial architecture of the conference microphone sector demonstrates robust expansion. Following a consistent upward trajectory from 2020 through 2025, the market has established a solid foundation for sustained acceleration. The overall market size has progressed from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. This historical performance underscores the resilience of the sector despite broader economic fluctuations in hardware and installation markets.
Looking forward, the forecast period from 2026 to 2032 projects a compelling growth narrative. The market is anticipated to reach 230.61 million USD in 2026, reflecting continued investment in meeting space technology. The compound annual growth rate over the forecast horizon is registered at 7.62 percent. This CAGR indicates that the sector is outpacing many traditional AV hardware categories, driven by the permanent shift toward hybrid work models and the modernization of legacy conference facilities. By 2032, the revenue scale is expected to exceed 358.54 million USD, signaling a mature but still expanding ecosystem.
For decision-makers, these figures represent more than headline numbers. They imply a market where volume growth is coupled with technological upgrading. Capital expenditures are shifting from basic wired setups to sophisticated networked audio solutions. Understanding where the volume concentrates and how revenue streams evolve across different phases of the forecast is essential for timing investments and mitigating obsolescence risk.
Competitive Landscape and Strategic Positioning
The industry structure is characterized by a balanced yet competitive dispersion of market share. The top three players hold a combined share of approximately 24.6 percent, while the top five firms account for roughly 26.2 percent of total market value. This concentration level suggests that while established giants maintain significant influence, there is ample room for specialized innovators and regional leaders to capture niche segments and expand through tailored solutions.
Several key enterprises define the current competitive arena, each bringing distinct technological philosophies and product architectures to the table.
- Shure Incorporated, headquartered in Niles, Illinois, emphasizes precision audio capture through its Microflex MXA series ceiling and table array microphones. Their strategic focus includes the Microflex Complete Wireless discussion systems and IntelliMix audio processing, which are engineered specifically for hybrid conference rooms requiring high-fidelity voice tracking and noise reduction.
- Bosch Security Systems, based in Gerlingen, Germany, delivers robust infrastructure for formal gatherings. Their DICENTIS wired and wireless conference systems, including DCNM main units and MMD2 multimedia devices, cater to professional meetings where reliability and integration with security and control systems are paramount.
- Sennheiser Electronic GmbH & Co. KG, located in Wedemark, Germany, focuses on streamlined deployment and audio clarity. Their TeamConnect ceiling microphones and TeamConnect Bar all-in-one solutions address the need for rapid setup and high-quality sound in meeting and conference environments without complex installation overhead.
- Televic NV, operating from Kortrijk, Belgium, specializes in digital wired and wireless conference systems with an emphasis on paperless solutions and hybrid meeting technologies. Their offerings are designed for formal gatherings that require structured discussion flow, voting capabilities, and seamless remote participant integration.
- TOA Corporation, headquartered in Kobe, Japan, provides the TS series wired conference systems and AM-CF1 audio collaboration units. Their wireless microphones for conferences complement a portfolio that prioritizes clear voice transmission and integration with broader AV control ecosystems.
- TAIDEN Industrial Co., Ltd., based in Guangzhou, China, contributes the HCS series digital conference systems alongside paperless multimedia solutions. Their infrared wireless options offer flexibility for environments where cable management is a constraint, while maintaining the structured functionality expected in government and corporate briefing rooms.
- Audio-Technica Corporation, from Tokyo, Japan, brings expertise in discussion systems with the ATUC-50 digital discussion platform. Their boundary and ceiling microphone arrays are positioned for meeting spaces that require discreet aesthetics without compromising pickup quality.
- Gonsin Conference Equipment Co., Ltd., located in Foshan, China, offers digital wired and wireless conference systems with paperless multimedia capabilities. Their product line supports formal conference settings that demand integrated display, voting, and audio management.
- Vissonic Electronics Co., Ltd., also headquartered in Guangzhou, China, provides the CLEACON wireless and DSP digital conference systems. Their AI-optimized ceiling microphones represent a growing trend toward intelligent audio processing that adapts to room acoustics and speaker positioning in real time.
- Auditel Systems, based in the United Kingdom, maintains a legacy of pioneer infrared and wired conference microphone systems. Their focus on discussion, voting, and decision-making in formal settings aligns with institutions that prioritize structured deliberation and reliable signal integrity.
Recent developments highlight the pace of innovation. In February 2026, VISSONIC exhibited a full line of digital conference systems, ceiling microphones, and paperless multimedia units at ISE 2026 in Barcelona. TAIDEN showcased the new HCS-8600MA/30 fully digital conference main unit, the HCS-MFUN Conference FlexDock, and paperless multimedia terminals at the same event. By April 2026, TAIDEN further participated in InfoComm China 2026, presenting the HCS-8586ST and HCS-4895 conference solutions. These launch cycles indicate that product refreshes are accelerating, and buyers must evaluate roadmaps carefully to avoid premature deployment of platforms nearing end-of-evolution.
Conference System (Microphone) Market
Technology Shifts and Application Dynamics
The market is segmented by type, application, and region, each presenting distinct growth drivers and procurement considerations. While specific breakdowns remain part of the detailed intelligence contained in the full report, the overarching patterns are clear. Wired and wireless configurations coexist, with wireless solutions gaining traction in environments where flexibility, rapid reconfiguration, and hybrid participant inclusion are strategic priorities. The demand for wireless conference microphone coverage in enterprise settings has risen sharply as organizations expand hybrid meeting adoption since 2024, reinforcing the importance of mobility and seamless roaming audio.
Application diversity further shapes purchasing behavior. Conference and meeting rooms remain the primary deployment zone, reflecting the everyday need for reliable discussion audio. Convention halls, press centers, classrooms, and other specialized venues contribute additional demand streams, each with unique acoustic, seating, and integration requirements. The variation across these use cases means that a single product category rarely satisfies all requirements. Procurement teams must weigh coverage, scalability, and ease of integration when aligning solutions with facility types.
Worldwide Pro Microphone Market
Supply chain and cost structure factors are also coming into sharper focus. In 2026, polymer housings and rare-earth magnets used in wireless conference microphones contribute a measurable portion of total unit cost within supply chains. This cost dynamic interacts with material availability and manufacturing lead times, making vendor selection a function not only of performance but also of supply resilience. Infrastructure readiness plays an equally important role. Networked conference systems that support simultaneous interpretation in large halls often rely on Ethernet upgrades with Cat 6A cabling to maintain signal integrity and low latency. Institutions planning major installations must account for these backend requirements to avoid performance bottlenecks.
Regulatory, Funding, and Market Dynamics
The operating environment for conference microphone systems is influenced by compliance frameworks and public sector funding mechanisms. Digital infrared conference systems must comply with IEC 60914 for electromagnetic compatibility and safety in public meeting spaces. Compliance is not optional; it affects procurement eligibility, installation approval, and long-term operational risk. Buyers should verify that vendor offerings meet these standards, especially for deployments in government buildings, educational institutions, and publicly accessible venues.
At the same time, conference microphone systems installed in government facilities are eligible for public procurement funding under digital government modernization programs. This funding pathway creates an avenue for organizations to accelerate upgrades by aligning project scopes with modernization criteria. The intersection of regulatory compliance and funding eligibility makes government and institutional segments particularly strategic for vendors and integrators seeking sustained project pipelines.
Macro trends continue to reshape demand. Hybrid meeting adoption has increased the emphasis on wireless conference microphone coverage in enterprise environments, reflecting the need to capture remote and in-room participants with equal clarity. This shift is not merely about hardware; it is about creating equitable participation experiences that support decision-making, collaboration, and institutional credibility. As a result, audio systems are increasingly evaluated as part of broader collaboration ecosystems rather than standalone devices.
Why This Research Matters for 2026 Decisions
Market data alone does not create competitive advantage. Interpretation does. This report is designed to translate macroeconomic figures and product-level developments into decision-ready insights. It maps the relationship between historical performance and forward-looking growth, helping leaders distinguish between temporary fluctuations and structural shifts. It examines how type, application, and regional factors influence demand intensity and procurement timing, while deliberately reserving the most granular segmentation values and precise percentage splits for the complete dataset.
The competitive profiles contained in the study are built around real product offerings, recent trade show activity, and the functional capabilities that matter in operational deployments. By linking company strategies to tangible solutions such as array microphones, wireless discussion systems, paperless multimedia terminals, and AI-assisted ceiling arrays, the report enables side-by-side evaluation of fit, scalability, and future-proofing. Recent launch activity further illustrates how quickly product generations are evolving, reinforcing the need for a structured evaluation framework rather than ad hoc selection.
Supply-side considerations are integrated into the analysis as well. Understanding the role of material costs, cabling infrastructure, and compliance standards helps procurement teams anticipate total cost of ownership and project risk. Funding opportunities in public sectors add another layer of strategic leverage, allowing organizations to plan deployments that align with eligibility windows and modernization objectives.
Conclusion
The Conference System (Microphone) Market is entering a phase where growth is sustained by technological sophistication, hybrid work permanence, and institutional modernization. With a forecast CAGR of 7.62 percent and a revenue trajectory extending well beyond 358 million USD by 2032, the sector offers meaningful opportunities for organizations that approach deployment with discipline and foresight. Success depends on selecting solutions that balance audio performance, integration readiness, compliance adherence, and total cost of ownership.
This market research provides the strategic foundation to make those choices with confidence. It consolidates historical context, forward projections, competitive intelligence, and operational dynamics into a single reference point for 2026 planning. The full report delivers the detailed segmentation values, precise regional and application breakdowns, and deeper comparative analysis needed to refine procurement strategy, vendor negotiation, and capital allocation. For leaders ready to move from high-level awareness to actionable intelligence, the complete study offers the depth required to turn market momentum into informed execution.
For detailed analysis of this topic, please visit the official page: Conference System (Microphone) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LTCC Ceramic Substrates Hit $1.46B in 2025, $2.23B by 2032 at 6.3% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the LTCC Ceramic Substrates Market: A 2026 Decision-Maker's Preview
The landscape of advanced electronics packaging is undergoing a structural shift, driven by the insatiable demand for higher frequency performance, miniaturization, and thermal management in critical applications. At the heart of this evolution lies Low-Temperature Co-fired Ceramic (LTCC) technology, a foundational enabler for RF modules, automotive radar, and high-density interconnects. As enterprises navigate the complexities of the 2026 fiscal year, understanding the trajectory of the LTCC ceramic substrates market is no longer optional; it is a strategic necessity.
LTCC Ceramic Substrates Market
PW Consulting's latest comprehensive market study offers a definitive lens into this sector. This article serves as a strategic preview, outlining the macro-economic trajectory, the intensifying competitive theatre, and the operational dynamics that will define investment and procurement decisions in the coming years. While we illuminate the strategic contours here, the precise segmentation data and granular forecasts contained in the full report remain a vital asset for detailed planning, available exclusively through our detailed intelligence portal.
HTCC Ceramic Substrates Market
Macro-Economic Trajectory and Growth Signals
The market for LTCC ceramic substrates has demonstrated resilience and steady expansion over the past half-decade. Historical data from the base period indicates a consistent upward trend in revenue valuation, reflecting the technology's entrenched position in high-value electronics. The narrative of growth is not merely historical; the forecast period extending from 2026 to 2032 suggests a continued accumulation of market value.
Our analysis projects a Compound Annual Growth Rate (CAGR) of 6.3% throughout the forecast window. This rate underscores a mature yet expanding market, fueled by specific high-growth verticals without relying on speculative bubbles. To understand the scale of this opportunity, one must look at the progression of overall market revenue. Starting from a baseline in the early 2020s, the valuation has climbed steadily, reaching significant milestones by 2025. The transition into the forecast period sees the market valuation continuing its ascent, with projections indicating substantial growth by the end of the decade.
For strategic planners, this macro-trajectory signals that LTCC is not a niche commodity but a critical component of the broader electronics supply chain. The growth is broad-based, yet its concentration varies significantly across types, applications, and geographies. While the aggregate numbers provide a health check for the industry, the real strategic value lies in understanding where this growth is concentrated and which players are capturing the value. The full report dissects these revenue streams across multiple dimensions, providing the granularity needed to allocate capital efficiently.
Competitive Landscape: The Battle for Dominance
The LTCC ceramic substrates market is characterized by a moderately concentrated structure, where a select group of established manufacturers holds significant sway over pricing, technology standards, and supply chain relationships. Our analysis highlights a market environment where the top players command a substantial share of total industry revenue, creating a high barrier to entry for smaller challengers, though innovation continues to emerge from specialized firms.
The leadership cohort is heavily weighted toward Japanese manufacturers, who have historically dominated the multilayer ceramic component space. Companies such as Murata Manufacturing Co., Ltd., Kyocera Corporation, and TDK Corporation remain pivotal actors. Murata, for instance, continues to leverage its massive production capabilities to support automotive and telecommunications demand, recently expanding capacity to ensure continuity for multilayer ceramic capacitors integral to LTCC performance. Kyocera has pushed the boundary of material science with announcements regarding breakthrough multilayer ceramic core substrates designed for advanced AI semiconductors, emphasizing high rigidity and circuit miniaturization. TDK remains active in optimizing dielectric formulations for high-reliability RF front-end modules.
Beyond the Japanese giants, the landscape includes specialized firms that carve out niches through specific application focus or regional strength. Yokowo Co., Ltd. and KOA Corporation focus heavily on automotive sensors and integrated resistor/sensor solutions, respectively. Hitachi Metals, Ltd. and NIKKO provide critical supply for industrial and power applications, emphasizing thermal management.
In Europe, the scene is defined by high-reliability specialists. Bosch provides LTCC solutions for automotive and industrial control modules, while firms like IMST GmbH and MST Group focus on high-frequency and sensor technologies. API Technologies (CMAC) serves the defense and industrial high-reliability sector, maintaining standards crucial for government contracts.
The Americas host a mix of specialized manufacturers and custom fabricators. Selmic targets commercial and medical applications, while NEO Tech offers in-house multilayer fabrication capabilities up to 50+ layers, catering to complex custom requirements. NTK Technologies and TTM Technologies provide crucial support for automotive, medical, and aerospace electronics, with TTM offering custom LTCC turnkey solutions compatible with major material systems.
In Asia, outside of Japan, players like Samsung Electro-Mechanics and Yageo Corporation contribute to the mobile and consumer electronics supply chain, while Walsin Technology Corporation and Shenzhen Sunlord Electronics Co., Ltd. serve the growing demand for RF and 5G components in the region.
This diverse array of competitors suggests a market where partnership ecosystems are vital. A manufacturer might excel in material formulation while another dominates in high-volume modular production. The full report provides a detailed competitive benchmarking analysis, evaluating these key companies on capacity, recent developments, and strategic positioning.
Industry Dynamics and Operational Context
Strategic decision-making cannot occur in a vacuum; it must account for the raw material and regulatory environment. Currently, the operational backdrop for LTCC production appears stable, which is a significant factor for long-term capacity planning.
On the raw material front, alumina feedstock prices have remained stable throughout the 2025-2026 period, with no reported increases or disruptions affecting LTCC production. This stability is crucial for margin preservation in a market where cost control is competitive. Furthermore, the global alumina supply chain showed no force majeure events or capacity constraints impacting LTCC substrate manufacturing as of early 2026. This supply chain resilience allows manufacturers to focus on technical innovation rather than fighting for scarce raw materials.
Regulatory dynamics also present a neutral-to-positive environment for the sector. No new export controls or targeted tariffs specifically impacting alumina or LTCC ceramic substrates were announced by major economies in the recent period. This lack of trade friction facilitates smoother cross-border commerce, which is essential given the global nature of the key companies and their customer bases. Additionally, ongoing compliance with ISO 9001 and automotive AEC-Q200 standards continues as a standard requirement without recent changes, meaning established players maintain their compliance moats without new regulatory burdens shifting the landscape. There are also no new environmental restrictions or transport surcharges on key LTCC precursors reported by producers, further stabilizing operational costs.
Technological Horizons and Recent Developments
Innovation remains the primary driver of differentiation in this market. Recent activities by key players highlight the direction of technological advancement. In April 2026, Kyocera Corporation announced the commercialization of a breakthrough multilayer ceramic core substrate for advanced AI semiconductors. This development, scheduled for unveiling at ECTC 2026, features high rigidity and circuit miniaturization, addressing the thermal and dimensional challenges of next-generation AI xPUs. This signals a widening of LTCC applicability beyond traditional RF and passive components into the frontier of computing hardware.
Murata Manufacturing Co., Ltd. has also been aggressive in aligning its capacity and product portfolio with market demand. In mid-2025, Murata expanded production capacity for multilayer ceramic capacitors integral to LTCC substrate performance to meet automotive and telecommunications demand. Shortly thereafter, they launched a next-generation ceramic substrate optimized for high-frequency 5G modules and automotive radar applications. These moves illustrate a strategy of vertical integration and product specialization to capture high-margin segments in connectivity and autonomy.
These developments are indicative of broader industry trends where material performance, layer density, and thermal conductivity are the new battlegrounds. The full report details these technological shifts and their implications for substrate selection in various design contexts.
Strategic Takeaways for 2026 Decision-Makers
As you finalize strategies for the 2026 fiscal year and beyond, several imperatives emerge from our analysis of the LTCC ceramic substrates market:
- Validate Supply Chain Resilience: While raw material stability is currently high, the concentration of manufacturing capacity among a few key regions and players necessitates a robust risk assessment. Understanding the capacity utilization and expansion plans of top-tier suppliers is critical to avoiding bottlenecks.
- Align Technology Roadmaps with Material Innovation: The emergence of LTCC solutions for AI semiconductors and high-frequency 5G/radar applications suggests that early engagement with suppliers offering advanced dielectric formulations and high-rigidity cores can provide a competitive edge in product performance.
- Monitor Competitive Intensity: With a significant portion of market revenue concentrated among top players, pricing pressure and technology licensing dynamics will be influenced by the strategic moves of these leaders. Keeping abreast of their product launches and capacity expansions is essential for negotiation and sourcing strategies.
- Segment-Specific Growth Opportunities: While the overall market grows at a steady CAGR, growth rates vary significantly by application and type. Automotive electronics and consumer electronics continue to drive volume, while aerospace and military sectors demand high-reliability niches. Identifying which segment aligns with your organization's capabilities requires detailed segmentation data.
The LTCC ceramic substrates market is at a point where steady historical growth meets emerging technological demands. The convergence of stable raw material costs, a lack of disruptive regulatory headwinds, and significant innovation in material science creates a favorable environment for strategic investment. However, the complexity of the supply chain and the competitive intensity require deep intelligence to navigate successfully.
This preview has outlined the macro-environment and the key actors shaping the industry. To access the full suite of quantitative forecasts, detailed segmentation by region and type, specific revenue valuations for each sub-sector, and the comprehensive competitive benchmarking matrix, we invite you to explore the complete PW Consulting Market Research report. The detailed data contained therein is designed to support precise forecasting, sourcing decisions, and investment analysis for the 2026-2032 period.
For detailed analysis of this topic, please visit the official page: LTCC Ceramic Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com