

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medical Swab Market Hits $3.76B in 2025, Projects 6.98% CAGR Through 2032

The Diagnostic Edge: Why the Medical Swab Market Demands Strategic Clarity in 2026
In the global healthcare ecosystem, few consumables are as unassuming yet operationally critical as the medical swab. From nasopharyngeal specimen collection to wound care and disinfection protocols, these devices form the frontline interface between patient biology and diagnostic accuracy. As the industry moves through a period of post-pandemic normalization, regulatory tightening, and supply chain maturation, the medical swab market is entering a phase of structured growth driven by diagnostics demand, material innovation, and compliance enforcement. Our latest market research delivers the analytical rigor required to navigate this landscape, translating historical trajectories and forward-looking forecasts into actionable intelligence for executive decision-making.
The strategic value of this study lies in its capacity to replace assumption with evidence. By mapping the market from 2020 through a forecast horizon extending to 2032, we provide a continuous view of demand evolution, capacity expansion, and competitive repositioning. The report is designed not as a static data repository, but as a decision-support instrument for procurement leaders, product strategy teams, investors, and regulatory affairs professionals who must anticipate volume shifts, evaluate supplier options, and align portfolio roadmaps with emerging compliance requirements.
Market Architecture: Trajectory, Scale, and Structural Signals
The medical swab market has demonstrated consistent expansion over the past half-decade, evolving from a crisis-amplified procurement category into a stabilized, clinically embedded supply stream. Historical data from 2020 to 2025 captures this transition, showing a clear upward arc in total revenue as diagnostic testing volumes, routine clinical usage, and wound-care consumption converged. The base-year snapshot for 2025 anchored the market at a substantial multi-billion-dollar level, reflecting the consolidation of swab-based workflows into everyday laboratory, hospital, and point-of-care environments.
Building on that foundation, the forecast period from 2026 to 2032 projects sustained momentum, with the market expected to reach an annual revenue level exceeding six billion USD by 2032. This growth trajectory is underpinned by a compound annual growth rate of 6.98 percent, signaling steady, above-inflation expansion rather than speculative surges. For corporate planners, that rate is meaningful because it implies a market where incremental volume gains, product mix optimization, and service-level improvements can compound into defensible market positions.
Crucially, the report avoids siloing these figures in isolation. Instead, it situates the macro trajectory within the operational realities that shape it: the ongoing shift toward flocked and non-woven formats for specimen collection, the persistent demand for sterile cotton and gauze swabs in clinical wound care, and the expanding utility of swabs in disinfection and ancillary procedures. The narrative structure ensures that revenue trends are interpreted through the lens of end-use behavior, material preference, and regional procurement patterns, giving readers a coherent map of where growth is originating and how it is likely to propagate.
Competitive Arena: Incumbents, Innovators, and the Push for Differentiation
The competitive landscape in the medical swab market is characterized by a blend of established medical-device manufacturers, diagnostic-focused specialists, and regional producers with expanding compliance credentials. Market concentration data indicates a moderately consolidated environment, with the top three players holding a combined share of roughly 35 percent and the top five approaching 47 percent. This structure suggests that while scale and regulatory clearance confer advantages, there remains meaningful room for differentiated offerings, particularly in specimen-collection performance, single-use sterility assurance, and regionally tailored distribution.
Puritan Medical Products, headquartered in Guilford, Maine, exemplifies the U.S.-centric, compliance-forward posture that has become a competitive differentiator. Its product portfolio spans medical-grade sterile and non-sterile swabs, flocked formats such as HydraFlock and PurFlock, and the PurSafe Plus collection and transport system, which has been cleared by the FDA for rapid diagnostics including SARS-CoV-2. In October 2025, the company introduced an FDA-cleared PurSafe Plus system designed for rapid SARS-CoV-2 inactivation and preservation with turnaround under one hour, manufactured entirely in the United States. This launch underscores how domestic production, regulatory clearance, and time-to-result performance are being leveraged as strategic assets.
Copan Diagnostics, with its Italian heritage and U.S. operational footprint, has built its reputation around FLOQSwabs flocked swabs engineered for optimal specimen collection in microbiology and diagnostics. In August 2024, the company published an evaluation of its FecalSwab effectiveness for enteric pathogen detection on the BD MAX system, illustrating a broader industry tendency to validate swab performance against specific diagnostic platforms and workflow requirements. Such validation activity is increasingly relevant as laboratories and procurement teams seek documented performance evidence rather than relying solely on material specifications.
Other significant participants reinforce the breadth of the competitive field. Dynarex Corporation in Orangeburg, New York, supplies sterile cotton swabs and medical swabs for clinical, laboratory, and diagnostic applications. GPC Medical Ltd in India manufactures medical gauze swabs, cotton swabs, and related wound-care consumables, reflecting the role of cost-competitive, high-volume producers in the broader supply architecture. Medline Industries, LP, based in Northfield, Illinois, provides cotton swabs, gauze swabs, and medical disposables to hospitals and healthcare facilities, embedding swab procurement within broader infection-prevention and clinical supply portfolios.
In Europe, Sarstedt AG & Co. KG in Germany offers laboratory swabs and medical sampling swabs, including forensic and diagnostic variants, supporting specialized applications that demand precise sample integrity. BD, the Becton, Dickinson and Company, supplies flocked and cotton swabs for microbiology, diagnostics, and specimen collection, extending its influence through a diversified diagnostics and care portfolio. Meanwhile, a cluster of Chinese manufacturers—including Hubei Baikang Medical Instrument Co., Ltd. (BKAMED), Winner Medical Co., Ltd., Shenzhen Huachenyang Technology Co., Ltd., and Jiangsu Huida Medical Instruments—contributes gauze swabs, cotton-based swabs, and flocked formats with varying levels of compliance documentation. Notably, Shenzhen Huachenyang emphasizes ISO 13485, CE, and FDA compliance for sampling and diagnostics, indicating that regulatory credentialing is becoming a key gate for expanding access to higher-value diagnostic channels.
For decision-makers, the competitive picture is not merely a roster of names. It is a map of capability clusters: U.S. and European firms with strong regulatory and diagnostic-validation positioning, large healthcare distributors integrating swabs into broader consumables ecosystems, and Asian manufacturers scaling capacity while selectively pursuing compliance milestones. The report examines how these clusters interact across procurement channels, hospital group purchasing organizations, and diagnostic-lab supply chains, helping readers identify where substitution risk is highest and where partnership or sourcing strategies can be optimized.
Regulatory Pressures and Supply Chain Realities
The medical swab market does not operate in a regulatory vacuum. FDA oversight has become an increasingly prominent force shaping product design, manufacturing controls, and distribution practices. In mid-2025, the FDA highlighted voluntary recalls for medical swabs, including nasal swabs, citing microbial contamination risks that are especially concerning for vulnerable populations such as children and immunocompromised individuals. This reminder of contamination risk reinforces why sterility assurance, packaging integrity, and lot-level traceability have moved from operational concerns to strategic imperatives.
A further regulatory inflection point involves laboratory-developed tests. A proposed FDA final rule on LDTs would classify them as in vitro diagnostic products, phasing out enforcement discretion for premarket review and quality system requirements, with the transition taking effect in February 2026. As LDT frameworks tighten, the downstream implications for specimen-collection devices are significant: laboratories seeking compliance may increasingly prioritize swabs with documented performance, consistent lot quality, and compatibility with validated workflows. This shift favors suppliers able to provide not just products, but the evidentiary support that laboratories need for their own regulatory positioning.
In parallel, FDA-authorized at-home OTC COVID-19 diagnostic tests continue to require self-collection with approved swabs or equivalent devices, with updated authorization lists effective into 2026. This requirement sustains demand for swabs that meet self-collection usability standards while maintaining analytical performance. The intersection of consumer-facing testing and professional diagnostics creates a bifurcated demand environment, where product design, packaging, and instructions-for-use clarity can be as influential as raw material selection.
Supply chain exposure remains a structural consideration. Sterile cotton swabs and gauze swabs are standard medical consumables used in FDA-regulated diagnostic testing and wound care, and historical supply chain reports have documented exposure during prior demand surges. The lesson for procurement leaders is that resilience depends on diversified sourcing, visibility into raw-material inputs, and contingency planning for sterile-processing capacity. Our research addresses these issues by mapping supplier readiness, compliance posture, and regional sourcing patterns, allowing organizations to stress-test their supply strategies against plausible disruption scenarios.
Quality incidents also serve as practical reminders of risk. In March 2026, a voluntary nationwide recall was issued for Webcol Large Alcohol Prep Pads due to potential microbial contamination, impacting more than 170 million units. While this event centered on alcohol prep pads rather than swabs per se, it illustrates the broader sterilization and packaging vigilance required across adjacent medical consumables categories. The market’s response to such events typically accelerates scrutiny of supplier quality systems and encourages buyers to formalize acceptance criteria beyond price and lead time.
What the Report Delivers: From Insight to Execution
This market research is built to support practical decision-making across multiple functions. Rather than stopping at aggregate market sizing, the study moves into the operational details that executives and category managers need to act with confidence. The report integrates demand drivers, product-format dynamics, regional procurement behavior, competitive positioning, and regulatory context into a unified analytical framework.
Medical Swab Market
Inside the report, readers will find:
- A structured analysis of market evolution from 2020 through 2032, with clear separation between historical performance and forecasted trajectory.
- An examination of product-type dynamics across sterile cotton, flocked, foam-tipped, non-woven, and other formats, linked to their respective clinical and diagnostic use cases.
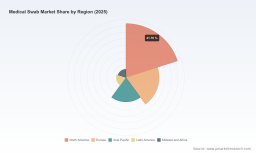
- A regional assessment of demand distribution and procurement characteristics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, framed in terms of market access, supplier presence, and growth potential.
- A deep competitive review of leading manufacturers, their core offerings, compliance positioning, and recent developments that signal strategic direction.
- An evaluation of application-side demand across specimen collection, disinfection, and other clinical uses, showing how volume concentration and workflow requirements shape sourcing priorities.
- A regulatory and supply chain section that connects FDA actions, LDT policy changes, at-home test requirements, and contamination-recall precedents to procurement and product-design decisions.
- Forward-looking scenarios that help teams anticipate how demand, compliance, and competitive intensity may evolve under different operational conditions.
Each section is designed to be usable on its own while contributing to an integrated view. Procurement teams can use the supplier and region analysis to refine sourcing briefs and evaluate risk exposure. Product and R&D leaders can reference the format and application analysis to inform material selection, sterility strategy, and packaging decisions. Strategy and investment teams can draw on the macro trajectory and competitive concentration data to assess market attractiveness, entry timing, and partnership opportunities. Regulatory and quality functions can use the compliance narrative to anticipate documentation expectations and align internal controls with emerging enforcement patterns.
Strategic Implications for 2026 and Beyond
As the market moves deeper into the 2026–2032 forecast window, several strategic themes become increasingly important. First, the growth rate suggests that broad, undifferentiated participation will be less rewarding than targeted positioning. Companies that can demonstrate measurable advantages in specimen release, sample integrity, sterility assurance, or platform compatibility are better placed to capture value in diagnostic-intensive segments, while those competing primarily on volume must manage cost, consistency, and supply reliability with exceptional discipline.
Laboratory Swabs Market
Second, regulatory momentum is tilting the market toward documentation and validation. With LDT oversight tightening and at-home test requirements evolving, the ability to provide clear evidence of performance and quality control is becoming part of the commercial proposition. Suppliers that treat regulatory readiness as a strategic capability, rather than a periodic compliance exercise, will have an advantage in securing long-term contracts with laboratories, hospital systems, and distributor networks.
Third, supply chain diversification remains essential. The combination of sterility requirements, contamination-risk precedents, and historical surge exposure means that single-source dependency can create outsized vulnerability. Organizations should assess not only unit pricing and lead times, but also manufacturing geography, sterilization capacity, quality-system maturity, and contingency readiness. In this context, the report’s supplier and regional analysis offers a basis for constructing more resilient sourcing architectures.
Fourth, product mix strategy matters more than ever. As specimen-collection workflows become more specialized and disinfection and wound-care applications continue to consume standard sterile formats, the most effective portfolios are those aligned to real workflow economics rather than generic category assumptions. Understanding which formats are gaining traction, where substitution is plausible, and how procurement specifications are changing enables more precise portfolio planning and pricing strategy.
How to Use This Research
This study is intended to be a working document for strategic planning, not a one-time read. Teams can use it to benchmark current assumptions, pressure-test procurement options, and identify the data points needed for internal business cases. For organizations evaluating market entry, expansion, or supplier consolidation, the competitive and regional analysis provides the kind of structured context that reduces uncertainty before capital or sourcing commitments are made.
Because the report deliberately moves from macro trajectory to operational detail, it supports both top-line strategy discussions and granular category reviews. Executives can rely on the revenue and growth framework to frame market opportunity, while operational teams can drill into supplier profiles, format trends, application dynamics, and regulatory developments to build executable plans. The goal is to make the intelligence directly usable, so that the time between insight and action is minimized.
Next Steps: Access the Full Intelligence
The overview presented here captures the analytical direction and strategic framing of the full study, but the complete report contains the detailed segmentation, supplier-by-supplier assessment, regional demand dynamics, application-level market structure, and forward scenario analysis that executives need for confident decision-making. The depth of the segmentation data, the competitive profiles, and the regulatory mapping are designed to support precise planning discussions across sourcing, product strategy, compliance, and investment functions.
To explore the full market sizing trajectory, the segmentation architecture, the competitive landscape, and the operational implications in detail, access the complete medical swab market research on our website. The full report provides the comprehensive intelligence necessary to translate market momentum into structured, defensible strategy for 2026 and the forecast years ahead.
For detailed analysis of this topic, please visit the official page: Medical Swab Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com