

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LTCC Ceramic Substrates Hit $1.46B in 2025, $2.23B by 2032 at 6.3% CAGR

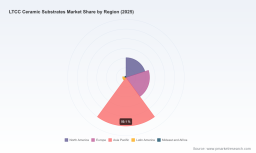
Strategic Imperatives in the LTCC Ceramic Substrates Market: A 2026 Decision-Maker's Preview
The landscape of advanced electronics packaging is undergoing a structural shift, driven by the insatiable demand for higher frequency performance, miniaturization, and thermal management in critical applications. At the heart of this evolution lies Low-Temperature Co-fired Ceramic (LTCC) technology, a foundational enabler for RF modules, automotive radar, and high-density interconnects. As enterprises navigate the complexities of the 2026 fiscal year, understanding the trajectory of the LTCC ceramic substrates market is no longer optional; it is a strategic necessity.
LTCC Ceramic Substrates Market
PW Consulting's latest comprehensive market study offers a definitive lens into this sector. This article serves as a strategic preview, outlining the macro-economic trajectory, the intensifying competitive theatre, and the operational dynamics that will define investment and procurement decisions in the coming years. While we illuminate the strategic contours here, the precise segmentation data and granular forecasts contained in the full report remain a vital asset for detailed planning, available exclusively through our detailed intelligence portal.
HTCC Ceramic Substrates Market
Macro-Economic Trajectory and Growth Signals
The market for LTCC ceramic substrates has demonstrated resilience and steady expansion over the past half-decade. Historical data from the base period indicates a consistent upward trend in revenue valuation, reflecting the technology's entrenched position in high-value electronics. The narrative of growth is not merely historical; the forecast period extending from 2026 to 2032 suggests a continued accumulation of market value.
Our analysis projects a Compound Annual Growth Rate (CAGR) of 6.3% throughout the forecast window. This rate underscores a mature yet expanding market, fueled by specific high-growth verticals without relying on speculative bubbles. To understand the scale of this opportunity, one must look at the progression of overall market revenue. Starting from a baseline in the early 2020s, the valuation has climbed steadily, reaching significant milestones by 2025. The transition into the forecast period sees the market valuation continuing its ascent, with projections indicating substantial growth by the end of the decade.
For strategic planners, this macro-trajectory signals that LTCC is not a niche commodity but a critical component of the broader electronics supply chain. The growth is broad-based, yet its concentration varies significantly across types, applications, and geographies. While the aggregate numbers provide a health check for the industry, the real strategic value lies in understanding where this growth is concentrated and which players are capturing the value. The full report dissects these revenue streams across multiple dimensions, providing the granularity needed to allocate capital efficiently.
Competitive Landscape: The Battle for Dominance
The LTCC ceramic substrates market is characterized by a moderately concentrated structure, where a select group of established manufacturers holds significant sway over pricing, technology standards, and supply chain relationships. Our analysis highlights a market environment where the top players command a substantial share of total industry revenue, creating a high barrier to entry for smaller challengers, though innovation continues to emerge from specialized firms.
The leadership cohort is heavily weighted toward Japanese manufacturers, who have historically dominated the multilayer ceramic component space. Companies such as Murata Manufacturing Co., Ltd., Kyocera Corporation, and TDK Corporation remain pivotal actors. Murata, for instance, continues to leverage its massive production capabilities to support automotive and telecommunications demand, recently expanding capacity to ensure continuity for multilayer ceramic capacitors integral to LTCC performance. Kyocera has pushed the boundary of material science with announcements regarding breakthrough multilayer ceramic core substrates designed for advanced AI semiconductors, emphasizing high rigidity and circuit miniaturization. TDK remains active in optimizing dielectric formulations for high-reliability RF front-end modules.
Beyond the Japanese giants, the landscape includes specialized firms that carve out niches through specific application focus or regional strength. Yokowo Co., Ltd. and KOA Corporation focus heavily on automotive sensors and integrated resistor/sensor solutions, respectively. Hitachi Metals, Ltd. and NIKKO provide critical supply for industrial and power applications, emphasizing thermal management.
In Europe, the scene is defined by high-reliability specialists. Bosch provides LTCC solutions for automotive and industrial control modules, while firms like IMST GmbH and MST Group focus on high-frequency and sensor technologies. API Technologies (CMAC) serves the defense and industrial high-reliability sector, maintaining standards crucial for government contracts.
The Americas host a mix of specialized manufacturers and custom fabricators. Selmic targets commercial and medical applications, while NEO Tech offers in-house multilayer fabrication capabilities up to 50+ layers, catering to complex custom requirements. NTK Technologies and TTM Technologies provide crucial support for automotive, medical, and aerospace electronics, with TTM offering custom LTCC turnkey solutions compatible with major material systems.
In Asia, outside of Japan, players like Samsung Electro-Mechanics and Yageo Corporation contribute to the mobile and consumer electronics supply chain, while Walsin Technology Corporation and Shenzhen Sunlord Electronics Co., Ltd. serve the growing demand for RF and 5G components in the region.
This diverse array of competitors suggests a market where partnership ecosystems are vital. A manufacturer might excel in material formulation while another dominates in high-volume modular production. The full report provides a detailed competitive benchmarking analysis, evaluating these key companies on capacity, recent developments, and strategic positioning.
Industry Dynamics and Operational Context
Strategic decision-making cannot occur in a vacuum; it must account for the raw material and regulatory environment. Currently, the operational backdrop for LTCC production appears stable, which is a significant factor for long-term capacity planning.
On the raw material front, alumina feedstock prices have remained stable throughout the 2025-2026 period, with no reported increases or disruptions affecting LTCC production. This stability is crucial for margin preservation in a market where cost control is competitive. Furthermore, the global alumina supply chain showed no force majeure events or capacity constraints impacting LTCC substrate manufacturing as of early 2026. This supply chain resilience allows manufacturers to focus on technical innovation rather than fighting for scarce raw materials.
Regulatory dynamics also present a neutral-to-positive environment for the sector. No new export controls or targeted tariffs specifically impacting alumina or LTCC ceramic substrates were announced by major economies in the recent period. This lack of trade friction facilitates smoother cross-border commerce, which is essential given the global nature of the key companies and their customer bases. Additionally, ongoing compliance with ISO 9001 and automotive AEC-Q200 standards continues as a standard requirement without recent changes, meaning established players maintain their compliance moats without new regulatory burdens shifting the landscape. There are also no new environmental restrictions or transport surcharges on key LTCC precursors reported by producers, further stabilizing operational costs.
Technological Horizons and Recent Developments
Innovation remains the primary driver of differentiation in this market. Recent activities by key players highlight the direction of technological advancement. In April 2026, Kyocera Corporation announced the commercialization of a breakthrough multilayer ceramic core substrate for advanced AI semiconductors. This development, scheduled for unveiling at ECTC 2026, features high rigidity and circuit miniaturization, addressing the thermal and dimensional challenges of next-generation AI xPUs. This signals a widening of LTCC applicability beyond traditional RF and passive components into the frontier of computing hardware.
Murata Manufacturing Co., Ltd. has also been aggressive in aligning its capacity and product portfolio with market demand. In mid-2025, Murata expanded production capacity for multilayer ceramic capacitors integral to LTCC substrate performance to meet automotive and telecommunications demand. Shortly thereafter, they launched a next-generation ceramic substrate optimized for high-frequency 5G modules and automotive radar applications. These moves illustrate a strategy of vertical integration and product specialization to capture high-margin segments in connectivity and autonomy.
These developments are indicative of broader industry trends where material performance, layer density, and thermal conductivity are the new battlegrounds. The full report details these technological shifts and their implications for substrate selection in various design contexts.
Strategic Takeaways for 2026 Decision-Makers
As you finalize strategies for the 2026 fiscal year and beyond, several imperatives emerge from our analysis of the LTCC ceramic substrates market:
- Validate Supply Chain Resilience: While raw material stability is currently high, the concentration of manufacturing capacity among a few key regions and players necessitates a robust risk assessment. Understanding the capacity utilization and expansion plans of top-tier suppliers is critical to avoiding bottlenecks.
- Align Technology Roadmaps with Material Innovation: The emergence of LTCC solutions for AI semiconductors and high-frequency 5G/radar applications suggests that early engagement with suppliers offering advanced dielectric formulations and high-rigidity cores can provide a competitive edge in product performance.
- Monitor Competitive Intensity: With a significant portion of market revenue concentrated among top players, pricing pressure and technology licensing dynamics will be influenced by the strategic moves of these leaders. Keeping abreast of their product launches and capacity expansions is essential for negotiation and sourcing strategies.
- Segment-Specific Growth Opportunities: While the overall market grows at a steady CAGR, growth rates vary significantly by application and type. Automotive electronics and consumer electronics continue to drive volume, while aerospace and military sectors demand high-reliability niches. Identifying which segment aligns with your organization's capabilities requires detailed segmentation data.
The LTCC ceramic substrates market is at a point where steady historical growth meets emerging technological demands. The convergence of stable raw material costs, a lack of disruptive regulatory headwinds, and significant innovation in material science creates a favorable environment for strategic investment. However, the complexity of the supply chain and the competitive intensity require deep intelligence to navigate successfully.
This preview has outlined the macro-environment and the key actors shaping the industry. To access the full suite of quantitative forecasts, detailed segmentation by region and type, specific revenue valuations for each sub-sector, and the comprehensive competitive benchmarking matrix, we invite you to explore the complete PW Consulting Market Research report. The detailed data contained therein is designed to support precise forecasting, sourcing decisions, and investment analysis for the 2026-2032 period.
For detailed analysis of this topic, please visit the official page: LTCC Ceramic Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com