

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Headless Compression Screws Market Hits $312.8M in 2025, Growing at 4.1% CAGR to 2032

The Strategic Imperative of Headless Compression Screws in 2026 Orthopedic Markets
Executive Vision
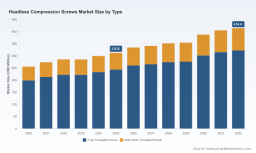
The global market for headless compression screws has entered a phase of steady, methodical growth that rewards precision planning over reactive expansion. As orthopedic surgery continues to prioritize minimally invasive fixation, reduced soft-tissue compromise, and faster postoperative mobilization, headless compression screws have secured an irreplaceable position in the small-bone and extremity trauma playbook. Our latest market research places the industry trajectory in sharp relief: a global revenue base of 312.8 million USD in 2025, expanding to 334.77 million USD in 2026, and continuing its upward march toward 414.4 million USD by 2032. With a forecast-period CAGR of 4.1 percent, the sector reflects a mature but persistently expanding landscape where operational efficiency, clinical differentiation, and supply-chain discipline determine who captures disproportionate share.
For executive teams navigating 2026 planning cycles, this research is not a static snapshot. It is a working decision tool. The report translates granular market mechanics into actionable intelligence on product mix, application priorities, regional corridors of opportunity, competitive positioning, regulatory exposure, and raw-material economics. The narrative below previews the strategic architecture of the study and illustrates how its findings can be operationalized for portfolio strategy, commercialization roadmaps, and risk management.
Headless Compression Screws Market
Market Architecture and Trajectory
The historical record from 2020 through 2025 reveals a market that has weathered macroeconomic pressure while maintaining constructive momentum. Revenue moved from 255.87 million USD in 2020 to 273.88 million USD in 2021, reached 285.71 million USD in 2022, and experienced a brief plateau near 285.46 million USD in 2023 before resuming expansion to 299.86 million USD in 2024. This cadence signals resilient demand rooted in surgical practice patterns, rather than a cyclical surge dependent on transient tailwinds. The market closed 2025 at 312.8 million USD and opens 2026 at 334.77 million USD, with subsequent years advancing through 341.28 million USD in 2027, 352.24 million USD in 2028, 354.84 million USD in 2029, 387.98 million USD in 2030, 405.48 million USD in 2031, and 414.4 million USD in 2032.
This growth arc is not uniform, and that unevenness is where value is created. The report decomposes the market by type, by application, and by region, and then integrates those splits with pricing logic, procedural volume assumptions, and competitive overlap to reveal where growth concentrates and where margins compress. Rather than presenting segment figures in isolation, the study arranges them into a decision framework that helps leaders identify which product categories justify expanded capacity, which applications offer the best clinical-commercial alignment, and which geographies provide the most efficient route to scale. We intentionally reserve the exact regional and application percentage breakdowns for the full report, since those layers interact with reimbursement, surgeon adoption curves, and distribution reach in ways that can be misinterpreted when read out of context.
Concentration dynamics reinforce the need for disciplined strategy. The market is not a commodity arena; a relatively small group of manufacturers controls a substantial portion of revenue, with the top three firms accounting for approximately 57 percent and the top five capturing roughly 65 percent. This structure rewards differentiation, technical credibility, and trusted surgeon relationships. It also means that late movers must find a clearly defined value proposition, whether through design innovation, service reliability, pricing architecture, or specialized clinical support, to avoid competing solely on access and availability.
Segmentation Depth as a Decision Engine
A core strength of this report is the way it translates segmentation into operational guidance. By type, the market divides between fully threaded screws and both-ends threaded screws, each with distinct mechanical behaviors, insertion characteristics, and clinical use patterns. Fully threaded designs typically dominate volume in applications where uniform compression and fragment stability are paramount, while both-ends threaded configurations serve select procedural needs where targeted fixation and construct flexibility are prioritized. The research evaluates how these categories map to procedural mix, surgeon preference, inventory requirements, and manufacturing complexity.
Cannulated Compression Headless Screws Market
By application, the study examines the clinical territories where headless compression screws are most consequential. Small-bone and extremity procedures in the hand, wrist, foot, and ankle form the operational core of demand, with additional volume coming from adjacent indications. The report connects each application area to the implant dimensions, material grades, instrumentation needs, and surgical techniques that influence adoption. It also explores the practical implications for product development teams: where miniaturization and variable-pitch geometry drive surgeon preference, where cannulation and biocompatibility elevate repeat usage, and where broader footprint systems open room for integrated fixation platforms.
Regional analysis is developed as a deployment roadmap rather than a simple map of current sales. The report assesses how mature markets differ from emerging ones in terms of purchasing dynamics, hospital procurement cycles, ambulatory migration, surgeon training pathways, and the competitive intensity facing new entrants. It identifies which regions are best suited for volume expansion, which require clinical evidence and service investment, and which present tactical opportunities through partnership, distribution, or focused indication targeting. Detailed regional figures and application-level shares are preserved within the full study so that leadership can evaluate them alongside internal pipeline assumptions and market-access realities.
Competitive Landscape and Strategic Positioning
The competitive set in headless compression screws reflects a mix of globally scaled orthopedic platforms and highly specialized small-bone fixation experts. DePuy Synthes anchors a broad trauma and extremities portfolio with its Synthes Headless Compression Screws series, offered in multiple diameters and available in titanium and stainless variants for small-to-large bone fracture fixation. Its scale and clinical reputation make it a reference point for the market, even as individual product events periodically reset risk expectations and quality commitments. Acumed LLC competes with a focused small-bone philosophy, exemplified by the Acutrak systems, whose variable-pitch cannulated titanium architecture has become closely associated with scaphoid, metacarpal, and other small-fragment indications. Zimmer Biomet contributes with headless compression and twist-off systems designed for intra-articular and extra-articular stabilization in foot and ankle procedures, while Arthrex extends its presence through compression designs that span foot, ankle, hand, wrist, and small-bone applications.
The landscape also includes companies with distinctive positioning. Rita Leibinger GmbH & Co. KG emphasizes cannulated compression screws for corrective osteotomies and selected fracture scenarios, reflecting a strong European engineering heritage. Stryker supports headless compression screw workflows through enabling systems that reinforce surgical precision in orthopedic trauma and small-bone fixation. Trax Surgical pursues a differential-pitch compression philosophy with FDA-registered and ISO 13485 aligned manufacturing, an approach that appeals to customers seeking procedural reliability and documented quality controls. TriMed Inc. offers titanium and stainless options across a practical dimension range for hand, foot, and ankle fixation, while TST Orthopedics structures its offering around a compact set of size options for precise fixation and osteotomy placement. Bonetech Precision adds a China-based precision manufacturing presence with titanium alloy solutions for fracture and non-union repair, illustrating the broader geographic spread of capability building.
Recent developments show that competitive advantage is increasingly shaped by execution events as well as product design. In early 2026, DePuy Synthes initiated a Class 2 device recall for certain 3.0 mm headless compression screws, a reminder that quality systems and field vigilance remain central to brand trust, even for well-established lines. In January 2026, Acumed reinforced its small-bone platform with the release of an updated surgical technique guide for its Acutrak 3 system, accompanied by expanded 2.0 mm Nano screw options and length extensions, underscoring how technique documentation and dimensional breadth can strengthen adoption. In July 2025, Zimmer Biomet announced a strategic partnership with Getinge to distribute operating room products, including orthopedic implants such as headless compression screws, to ambulatory surgery centers, highlighting the commercial importance of channel expansion as surgical care continues moving toward lower-acuity settings. The report situates these events within broader competitive dynamics rather than treating them as isolated headlines, helping leadership assess implications for purchasing confidence, surgeon behavior, and channel strategy.
Industry Dynamics Shaping 2026 Decisions
Several structural forces continue to define how the market behaves and where strategic leverage lies. Surgical migration toward ambulatory and outpatient environments is changing how suppliers approach inventory, sterilization compatibility, tray design, and procedure efficiency. As clinicians seek to reduce operative time and soft-tissue disruption, headless compression screws remain attractive because they allow compression across fracture or osteotomy sites without prominent hardware that can irritate surrounding tissue. At the same time, the specification of titanium grades and alloy choices influences both clinical performance and cost structure. Commercial-grade titanium has moved within a range of roughly 8 to 15 USD per pound in mid-2026, while aerospace-grade Ti-6Al-4V has traded at higher levels, and titanium scrap has remained a meaningful offset within procurement planning. These input costs form the backdrop for pricing strategy, margin management, and make-versus-buy decisions across the value chain.
Standards and clinical protocols also continue to stabilize demand by reinforcing confidence in specific screw dimensions for defined repair scenarios. For example, the AO Foundation maintains approval and licensing for the use of 4.5 mm and 6.5 mm headless compression screw solutions in fracture and deformity correction, a reference point that shapes surgeon familiarity and implant selection logic. Regulatory events, material availability, and procedural standardization together create a market environment where consistency matters as much as innovation. The report examines these dynamics as interacting forces, not as separate lists, so that readers can evaluate how product engineering, quality assurance, procurement timing, and clinical education reinforce one another.
Inside the Report: What Decision-Makers Will Gain
This research is designed to convert market complexity into executable strategy. It provides a comprehensive view of market size and growth, with historical calibration and a forward forecast that supports planning through 2032. Beyond the headline numbers, the study maps the segmentation architecture in a way that supports product planning and commercialization choices. It analyzes the competitive landscape by company profile, product philosophy, and recent strategic moves, allowing readers to benchmark their own positioning and identify gaps in capability, coverage, or clinical messaging.
The report also integrates industry context into the analysis. It addresses regulatory considerations and quality events as factors that influence purchasing and brand trust. It incorporates raw-material cost conditions to inform margin planning and sourcing strategy. It considers clinical protocol standards as part of the adoption environment. In addition, the study is structured to support practical questions that executive teams face in 2026: where to concentrate R&D and portfolio investment, which application areas offer the strongest alignment between clinical need and commercial return, how regional opportunities should be prioritized, and what competitive responses are most likely from incumbents and niche specialists alike.
To preserve analytical integrity, the report avoids overstating precision where assumptions remain sensitive to local reimbursement, surgeon behavior, and channel access. Instead, it presents a layered view in which top-line trajectory, concentration structure, segment relationships, and competitive events can be read together. This approach helps organizations avoid the common trap of interpreting a single figure in isolation, and instead focus on the interactions that actually drive outcomes.
Translating Intelligence into 2026 Action
For companies operating in or entering this market, the strategic conclusions are consistent. First, growth is real but disciplined, so portfolio strategy should be built around durable demand signals rather than speculative spikes. Second, concentration in the competitive field means that differentiation must be credible, clinically meaningful, and supported by dependable execution. Third, segmentation is not a taxonomy exercise; it is the basis for prioritizing dimensions, materials, instrumentation, and service levels that match surgical reality. Fourth, recent regulatory and commercial events demonstrate that quality, technique support, and channel strategy are as important as implant design in winning and retaining share.
The full study extends these themes with the detailed figures, regional breakdowns, application-level shares, and competitive analysis required to build investment cases, sales plans, and risk controls. It is intended for leaders who need a rigorous foundation before committing resources, whether the objective is to expand an existing line, enter a specific application zone, strengthen distribution in a chosen region, or anticipate competitor moves with greater confidence. The preview above establishes the strategic logic behind the research; the complete report delivers the numbers, comparisons, and scenario-ready detail that turn logic into action.
In a market moving from 334.77 million USD in 2026 toward 414.4 million USD in 2032, with a forecast CAGR of 4.1 percent and a concentrated competitive structure, the winners will be those who combine evidence with discipline. Our research is built to give them exactly that: a clear view of where value is forming, how the competitive field is evolving, and what decisions are most likely to create durable advantage in the years ahead.
For detailed analysis of this topic, please visit the official page: Headless Compression Screws Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com