

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global Pharmaceutical L-Carnitine Market Hits $245.5M in 2025, 5.45% CAGR Forecast to 2032
By pmarketresearch, 2026-09-16
Navigating the Global Pharmaceutical Grade L-Carnitine Market: A 2026 Strategic Overview
The global pharmaceutical landscape is witnessing a subtle yet significant shift in the nutritional pharmacotherapy sector, with Pharmaceutical Grade L-Carnitine emerging as a critical compound for clinical nutrition, metabolic support, and therapeutic interventions. As we move into 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for stakeholders ranging from API manufacturers to pharmaceutical distributors and healthcare investors. PW Consulting latest comprehensive market research provides a definitive lens through which to view these dynamics, offering a granular analysis of the value chain, competitive forces, and regulatory hurdles that define this sector.
This market, driven by an aging global population and increasing awareness of metabolic health, has demonstrated resilience and structured growth over the past half-decade. Our analysis indicates that the market reached a valuation of approximately 245.5 million USD in 2025, reflecting a steady upward trend from 187.65 million USD in 2020. Looking ahead, the forecast period spanning 2026 to 2032 suggests a continued expansion, with the market projected to reach 355.95 million USD by the end of the forecast window. This trajectory corresponds to a Compound Annual Growth Rate (CAGR) of 5.45 percent, signaling a stable, mature growth environment rather than a volatile speculative bubble. For decision-makers, this consistency implies predictable revenue streams but also necessitates precise positioning to capture share in a consolidating landscape.
Structural Dynamics and Value Chain Complexity
The pharmaceutical grade L-Carnitine ecosystem is defined by rigorous quality standards that separate it distinctly from bulk industrial or feed-grade variants. Industry data suggests that pharmaceutical-grade material commands a significant price premium, often ranging from three to five times higher per kilogram than feed-grade counterparts. This pricing power is underpinned by the stringent purity requirements mandated for human consumption, particularly in injectable forms where safety profiles are paramount. Manufacturers must adhere to USP 43 and EP 10.0 standards, which include strict GMP manufacturing protocols and endotoxin limits below 0.05 EU/mg for injectable grades. These regulatory barriers create a high entry threshold, naturally favoring established players with robust quality assurance infrastructures.
Production capabilities remain a central bottleneck. Both fermentation and chemical synthesis processes for high-purity L-Carnitine face capacity constraints, which has driven a trend toward vertical integration among producers. Companies are increasingly seeking control over raw material sourcing and bioprocess capabilities to ensure consistent quality and supply security. This vertical integration is not merely operational but strategic, as it mitigates the risk of supply chain disruptions that could compromise clinical supply agreements. The market concentration reflects this maturity, with the top three competitors holding a significant portion of the revenue share, indicating that scale and compliance are key determinants of market leadership.
Segmentation and Therapeutic Applications
While the aggregate numbers tell a story of growth, the true strategic value lies in understanding where that value is generated. The market is segmented by type, region, and application, each presenting unique opportunities and challenges. In terms of chemical forms, the landscape includes L-Carnitine Base, L-Carnitine Tartrate, Acetyl-L-Carnitine, and other variants. Each form serves distinct therapeutic niches; for instance, Acetyl-L-Carnitine is often associated with neurological support, while tartrate forms are prevalent in metabolic and nutritional formulations. The distribution of revenue across these types highlights the dominance of specific chemical structures in current clinical practice, though the demand for specialized forms continues to evolve with emerging research.
Worldwide Pharmaceutical Grade Taurine Market
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The Asia Pacific region represents a substantial volume contributor, driven by domestic manufacturing capabilities and growing healthcare infrastructure. North America and Europe maintain strong positions, largely influenced by established reimbursement pathways and high adherence to clinical nutrition guidelines. However, the dynamics vary significantly by jurisdiction. In China, for example, specific pharmaceutical products have historically held considerable market share in hospital settings, reflecting established reimbursement pathways in clinical nutrition. This regional nuance is critical for companies looking to expand their footprint, as regulatory environments and procurement mechanisms differ vastly between tenders in Europe and hospital procurement in Asia.
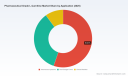
Application-wise, the market is driven primarily by Intravenous Injections and Oral Dosage Forms, with Clinical Nutrition also representing a significant pillar. The dominance of intravenous formulations underscores the critical role of L-Carnitine in acute care and hospital-based metabolic support. Oral dosage forms, meanwhile, cater to chronic management and outpatient supplementation. The balance between these application routes influences manufacturing requirements, as injectable grades require stricter sterility and purity controls compared to oral intermediates. Understanding the revenue split between these applications helps manufacturers align their production capacities with the highest value segments.
Competitive Landscape: Giants and Specialists
The competitive environment is a mix of global life sciences giants, specialized European manufacturers, and large-scale Chinese producers. Leading the pack is the Lonza Group, based in Basel, Switzerland. With over 30 years of expertise, Lonza offers high-purity Carnipure L-Carnitine in crystalline and tartrate forms, manufactured via bioprocess and chemical synthesis. Their strength lies in quality-compliant production for clinical nutrition and supplements, positioning them as a preferred partner for high-value pharmaceutical applications. Similarly, Merck KGaA, including Sigma-Aldrich, supplies high-purity L-Carnitine for pharmaceutical-grade and laboratory applications, supporting clinical and research needs with analytical standards and GMP-compliant materials.
In Europe, Alfasigma (Sigma-tau) maintains a strong hospital market presence with their CARNITENE product. Their strategy involves distribution and promotional activities in key regions, including China, where they have navigated complex market redeployment strategies to maintain brand visibility. Biosint S.p.A. in Italy also contributes to the European supply chain, focusing on USP/EP compliance for API and clinical nutrition formulations. These European players leverage regulatory expertise and brand heritage to command premium positioning.
On the other side of the spectrum, Chinese manufacturers play a pivotal role in global supply. Northeast Pharmaceutical Group Co., Ltd. (NEPG) is a major producer of L-carnitine series including pharmaceutical-grade API, with integrated chemical raw materials and GMP-compliant manufacturing for domestic and export markets. Liaoning Koncepnutra Co., Ltd. operates as one of the largest professional production bases in China, focusing on nutrition ingredients and pharmaceutical chemical intermediates with GMP standards. Hubei Truevita Pharmaceutical Co., Ltd. has scaled significantly, with annual capacity reaching 1500 tons in the first phase, supplying chemical APIs, food additives, and feed additives under high-standard operations. Ningxia Kunzheng Biotechnology Co., Ltd. further expands capacity with a 3000-ton annual production project for L-carnitine and its salts, operational since late 2021.
Other significant players include Chengda Pharmaceuticals Co., Ltd., offering L-carnitine with USDMF and WC documentation for pharmaceutical-grade API supply, and Apino Pharma Co., Ltd., a GMP-certified supplier with CoA, MSDS, and USDMF for API markets. Changzhou Comwin Fine Chemicals Co., Ltd. and Sandoo Pharmaceuticals and Chemicals Co., Ltd. also provide GMP, ISO9001, and FDA-approved sources for export. AgEx Pharma, based in India/USA, operates as a cGMP bulk manufacturer with substantial monthly capacity for pharma and food-grade applications. Rochem International, Inc. serves as a distributor and supplier in the United States with extensive GMP and regulatory documentation. Kaiyuan Hengtai Nutrition Co., Ltd. rounds out the specialized manufacturer group focusing on nutrition and pharmaceutical applications. This diverse competitive set means that buyers have options ranging from high-cost, high-touch European suppliers to high-volume, cost-competitive Asian manufacturers, depending on their specific quality and price requirements.
Recent Market Developments and Strategic Shifts
The period leading into 2026 has been marked by specific corporate actions and product innovations that reshape the competitive terrain. In January 2025, Otsuka Pharmaceutical Factory launched the ENSOLID semi-solid enteric nutrition formula incorporating pharmaceutical-grade L-Carnitine. This launch targets fatty acid metabolism support in clinical and geriatric health settings, signaling a move toward integrated nutritional solutions rather than standalone ingredients. Such product launches expand the addressable market by embedding L-Carnitine into broader care regimens.
Conversely, portfolio rationalization is also occurring. In December 2024, BASF SE signed a binding agreement to divest its Food and Health Performance Ingredients business, which includes production facilities tied to the L-Carnitine production chain. This divestiture suggests a strategic shift among large conglomerates to focus on core competencies, potentially opening opportunities for specialized buyers or competitors to acquire assets and capacity. Meanwhile, Balchem Corporation reported strong growth in its Human Nutrition & Health segment in April 2025, including L-Carnitine and related functional ingredients, indicating sustained demand in the nutrition sector.
Regulatory and market access dynamics continue to evolve. Levocarnitine remains the generic ingredient in multiple approved injectable and oral formulations. Recent ANDA approvals and expirations, such as the Deva Holding As product expiring in June 2025, influence generic competition levels. In China, historical data showed established products holding significant market share in the hospital carnitine market, valued at billions of RMB, reflecting the importance of reimbursement pathways. These dynamics require constant monitoring, as changes in patent status or reimbursement policies can rapidly alter market shares.
Strategic Imperatives for 2026 and Beyond
For stakeholders navigating this market in 2026, several strategic imperatives emerge from the data. First, supply chain resilience is paramount. Given the capacity bottlenecks in fermentation and synthesis, securing reliable sources of API is critical. Vertical integration or long-term contracts with key producers like Lonza or major Chinese GMP-certified facilities can mitigate supply risk. Second, regulatory compliance must be viewed as a competitive advantage. With endotoxin limits and USP/EP standards acting as gatekeepers, manufacturers who can demonstrably exceed these requirements will secure premium contracts in sensitive applications like intravenous injections.
Third, geographic diversification is essential. While Asia Pacific offers volume and growth, North America and Europe offer stability and higher margins due to established reimbursement structures. Companies must tailor their go-to-market strategies to these regions, understanding that distribution channels and procurement rules differ. Fourth, innovation in formulation offers growth potential. The launch of semi-solid enteric formulas by players like Otsuka suggests that combining L-Carnitine with other nutritional elements can unlock new value pools in clinical nutrition.
Finally, the market concentration indicates that M&A activity or strategic partnerships could reshape the landscape. With a significant portion of revenue held by the top competitors, smaller players may need to specialize or form alliances to remain relevant. The divestiture by BASF and the strong growth reported by Balchem highlight that capital is flowing toward specific segments of the nutrition value chain, and investors should align their portfolios accordingly.
PW Consulting comprehensive research report delves deeper into these trends, offering detailed segmentation analysis, granular country-level data, and proprietary forecasts that go beyond the macro overview presented here. While the high-level growth rates and total market values provide a necessary context, the true decision-making intelligence lies in the specific regional splits, application breakdowns, and competitive benchmarking contained within the full study. Understanding the exact allocation of revenue across types, the specific growth drivers in each region, and the detailed operational profiles of every key competitor requires access to the complete dataset.
In an environment where premium pricing relies on compliance, where capacity constraints dictate supply security, and where regional reimbursement pathways determine market access, having granular intelligence is not optional—it is essential. The projected growth to 355.95 million USD by 2032 represents a significant opportunity, but capturing it requires navigating a complex web of regulatory, operational, and competitive factors. This introduction serves as a primer to the landscape, but the full strategic roadmap requires the depth of analysis that only our complete market research can provide. Stakeholders are encouraged to leverage this intelligence to refine their sourcing strategies, identify partnership opportunities, and forecast their revenue potential with precision in the evolving global pharmaceutical grade L-Carnitine market.
Worldwide Pharmaceutical Grade L-Carnitine Market
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade L-Carnitine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SocialFi NFT Market Hits $480M in 2025, Projected to Reach $1.09B by 2032
By pmarketresearch, 2026-09-16
Beyond Likes: The Strategic Imperative of SocialFi NFTs in 2026
The convergence of decentralized social networks and non-fungible token (NFT) technology has moved beyond speculative experimentation into a structured economic layer for digital interaction. As we navigate the midpoint of 2026, the SocialFi NFTs market stands at a critical inflection point. What was once a niche intersection of Web3 experimentation is now a validated infrastructure for creator ownership, community governance, and social monetization. For enterprise leaders, venture capitalists, and product strategists, understanding this landscape is no longer optional—it is essential for positioning within the next generation of digital economies.
This article serves as a strategic introduction to our latest comprehensive market research report on SocialFi NFTs. It outlines the macro-economic trajectory, the evolving competitive architecture, and the operational depth contained within the full study. However, like any high-value intelligence briefing, this overview acts as a trailer: it demonstrates the rigor and scope of our analysis while reserving the precise segmentation figures and proprietary forecasts for the complete report. Decision-makers who require granular data to validate investment theses or product roadmaps are encouraged to access the full document.
A Macro Growth Trajectory Defined by Digital Ownership
The financial architecture of the SocialFi NFTs market demonstrates a consistent upward trajectory, signaling a shift from early-adopter volatility to sustained institutional and consumer adoption. Analyzing historical performance from 2020 through the base year of 2025 reveals a market that has expanded its revenue foundation significantly. In 2020, the market operated at a modest scale, but by 2025, the revenue base had grown to approximately 480 million USD. This escalation is not merely a function of speculative trading but reflects the integration of NFT primitives into social applications that users engage with daily.
Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is expected to reach roughly 539 million USD in 2026, accelerating toward an estimated 1.09 billion USD by the end of the forecast window in 2032. This growth is underpinned by a compound annual growth rate that underscores the durability of the asset class within the broader social technology sector. Such figures suggest that SocialFi NFTs are transitioning into a core component of the digital creator economy rather than a peripheral innovation. For stakeholders, this implies a need to evaluate long-term infrastructure plays rather than short-term hype cycles. The revenue unit consistency across the forecast period allows for clear planning, though the specific allocation of these revenues across different verticals requires deeper segmentation analysis available in our full dataset.
It is important to note the concentration dynamics within this expanding market. Current metrics indicate a competitive environment where no single entity dominates completely, yet top players hold significant sway. The combined market share of the top three firms hovers around 35.5 percent, while the top five entities control approximately 42.8 percent. This distribution suggests a fragmented but maturing landscape where innovation speed and user retention are the primary drivers of market share acquisition. For enterprises entering this space, this concentration data highlights the opportunity for disruption in underserved niches while acknowledging the barriers to entry posed by established protocol layers.
Segmentation: Types and Applications Driving Utility
The utility of SocialFi NFTs is not monolithic. Our research dissects the market across three primary types that define how digital assets are utilized within social contexts. The first category involves Identity and Decentralized Identifier (DID) NFTs, which serve as the foundational layer for user sovereignty and portable reputations across chains. The second, and currently substantial, portion of the market comprises Creator Monetization NFTs, which enable direct economic relationships between content producers and their audiences. The third category includes Membership and Access Passes, which function as gating mechanisms for communities, exclusive content, or governance rights.
Worldwide Fashion Influencer Market
These types manifest through distinct application vectors. Decentralized Social Platforms represent the largest application segment, utilizing NFT infrastructure to power on-chain social graphs and content ownership. Creator Economy Marketplaces form the second major application layer, facilitating the trading of digital collectibles and tipping mechanisms. The third application domain lies within DAO Governance Ecosystems, where NFTs act as voting tokens and participation credentials. Each of these application areas interacts differently with user behavior and revenue models. For instance, while decentralized platforms focus on network effects, marketplaces prioritize liquidity and trading volume. A nuanced understanding of these operational differences is critical for solution providers aiming to target specific user needs without applying a one-size-fits-all strategy.
Furthermore, geographic distribution plays a pivotal role in how these segments perform. The market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, each with varying levels of regulatory clarity and digital infrastructure maturity. While aggregate numbers show a balanced global interest, regional adoption rates differ based on local creator ecosystems and blockchain infrastructure availability. Detailed regional breakdowns, including specific market values and growth percentages by territory, are provided in the full report to assist multinational strategies in prioritizing market entry or expansion efforts.
Competitive Landscape: Protocols Shaping the Social Web
The competitive landscape of the SocialFi NFTs market is characterized by a mix of established protocols, innovative platforms, and specialized marketplace providers. Leading this space is Friend.tech, based in San Francisco, which has pioneered the concept of trading shares in creators to monetize social interactions. Their integration of NFT profiles has set a precedent for linking social capital directly to tradable assets. Similarly, Lens Protocol, operating out of the United Kingdom, offers a decentralized social graph that allows creators to own their profiles and followers as NFTs, emphasizing portability and interoperability across applications.
Farcaster, headquartered in West Hollywood, provides another critical layer with its decentralized social protocol featuring NFT-based identities and collectibles. The platform has recently seen significant corporate activity, including an acquisition by Neynar in early 2026, which signaled a strategic shift toward developer-focused tools for on-chain social features. Zora, based in New York, continues to expand its on-chain social network and NFT protocol, recently launching Attention Markets on Solana in February 2026. This move allows users to trade social trends and cultural moments, further blurring the lines between content consumption and financial speculation.
Beyond the major protocols, specialized entities are carving out niches. BLAQclouds, Inc., located in Robesonia, Pennsylvania, provides the ApolloNFT Marketplace and theAlley SocialFi platform, recently expanding their offerings in March 2026 to enhance NFT minting and direct fan monetization capabilities. CyberConnect, with primary operations in Singapore, focuses on the social identity layer, using NFTs for user profiles and connections. Cheelee, also based in Singapore, targets the short-video segment with NFT glasses that enable reward earning and content monetization. These companies illustrate the diversity of approaches within the market, ranging from infrastructure layers to consumer-facing applications.
Recent developments highlight the velocity of change. The acquisition of Farcaster by Neynar suggests a consolidation trend where infrastructure providers seek to control the social stack. Zora's expansion into attention markets indicates a pivot toward monetizing cultural relevance directly on-chain. Meanwhile, BLAQclouds' platform updates emphasize the ongoing demand for tools that simplify creator monetization. These events collectively point to a market that is rapidly maturing, with companies increasingly focusing on sustainability, developer tooling, and tangible revenue generation rather than pure user acquisition.
SocialFi NFTs Market
Industry Dynamics and Adoption Signals
Several key dynamics are currently shaping the operational environment for SocialFi NFTs. Market growth remains robust, with independent analyst insights estimating the sector's scale in the hundreds of millions, driven largely by the dominance of Social Content Monetization NFTs. The United States, in particular, is projected to experience significant growth rates, fueled by platforms like Friend.tech and a mature creator economy. However, global adoption is evident, with protocols recording millions of daily active wallets in early 2026. This level of engagement indicates that users are moving beyond testing phases into habitual usage of decentralized social tools.
Monetization capabilities are proving to be a key retention driver. Reports indicate that top creators on platforms like Lens have generated substantial income through collect NFT sales and tipping mechanisms in the first quarter of 2026. These figures demonstrate that the economic value proposition of SocialFi is becoming real for participants, not just theoretical. For businesses, this signals a shift in value capture strategies. Platforms that can facilitate seamless monetization while maintaining user experience standards are likely to capture more value than those relying solely on advertising or speculative tokenomics.
Nevertheless, the noise of industry data requires careful filtering. While overall growth is positive, specific segments may vary in performance based on macroeconomic conditions and regulatory developments. The presence of multiple competing standards and the evolving nature of blockchain scalability solutions add layers of complexity to strategic planning. Organizations must remain agile, monitoring not just price action but also user retention metrics, governance participation rates, and the integration of social NFTs with broader Web2 platforms.
What This Report Delivers for Enterprise Decision-Makers
Our comprehensive report, "SocialFi NFTs Market," is designed to provide the depth required for high-stakes decision-making. It goes beyond surface-level summaries to offer an executive summary that distills key findings for C-suite consumption. The methodology section details the research approach, ensuring transparency and reliability for stakeholders who need to validate the data for internal governance or investment committees.
The core of the report includes a rigorous market estimate analysis covering the historical period from 2020 to 2025 and a detailed forecast extending to 2032. This analysis breaks down the market by region, allowing strategists to identify high-potential geographies without relying on generalizations. It also segments the market by type and application, providing the specific revenue values and growth rates necessary to size opportunities accurately. For example, knowing the exact market size of Creator Monetization NFTs versus Membership Passes enables targeted product development and resource allocation.
Additionally, the report features a vendor analysis section profiling key companies in detail, including their product offerings, recent developments, and strategic positioning. This section is invaluable for competitive intelligence, partnership identification, and M&A targeting. It contextualizes recent moves, such as platform expansions and acquisitions, within the broader market trajectory. The report also addresses market dynamics, exploring drivers, restraints, and trends that will influence the sector's evolution. For organizations looking to enter the market, the segmentation analysis provides a roadmap of where value is being created and where gaps remain.
Ultimately, this research serves as a strategic compass. Whether you are a technology provider building the next social layer, an investor evaluating exposure to the creator economy, or a brand exploring NFT-based loyalty programs, the data within this report is structured to support evidence-based strategy. The full document contains the precise figures and detailed breakdowns necessary to build financial models and market entry plans.
Accessing the Full Intelligence
The landscape of SocialFi NFTs is complex, dynamic, and rapidly evolving. While this overview highlights the strategic importance of the market, the actionable intelligence required to navigate it lies in the details. The interplay of specific regional growth rates, exact revenue splits across types and applications, and deep-dive company profiles necessitates a comprehensive view that only the full report can provide.
We invite industry leaders, analysts, and strategic planners to access the complete SocialFi NFTs Market report. By doing so, you will gain access to the granular data, forecasts, and competitive analyses needed to make informed decisions in 2026 and beyond. In a market defined by speed and innovation, having access to verified, detailed intelligence is the ultimate competitive advantage.
For detailed analysis of this topic, please visit the official page: SocialFi NFTs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global All Solid State RF Power Supply Market to Hit $2.76B by 2032 at 9.48% CAGR
By pmarketresearch, 2026-09-16
Powering the Next Decade: Strategic Insights into the Worldwide All Solid State RF Power Supply Market
The global industrial landscape is undergoing a fundamental transformation in how energy is delivered, controlled, and optimized across critical manufacturing and scientific processes. At the forefront of this shift is the worldwide all solid state RF power supply market, a sector that has evolved from a niche technology provider into a cornerstone of modern plasma processing, industrial heating, and advanced semiconductor fabrication. As organizations navigate increasing demands for precision, energy efficiency, and operational reliability, understanding the strategic trajectory of this market has become indispensable for executive decision-making. This comprehensive analysis outlines the market structure, competitive dynamics, technological drivers, and forward-looking opportunities that will define the industry through the mid-2030s.
Recent historical performance demonstrates a steady, compounding expansion. Between 2020 and 2025, the market grew from approximately 912.45 million USD to 1465.0 million USD, reflecting a consistent upward trajectory fueled by the gradual replacement of legacy vacuum tube and magnetron-based systems. Looking ahead, the forecast period spanning 2026 to 2032 projects a robust compound annual growth rate of 9.48 percent. By the close of the forecast horizon, the market is anticipated to reach 2765.26 million USD in revenue. These figures are not merely statistical milestones; they represent a structural realignment in how industries source, regulate, and deploy radio frequency energy. For corporate strategists, capital allocators, and technology procurement leaders, this growth trajectory signals both immediate deployment opportunities and long-term value creation pathways.
Foundational Market Architecture and Strategic Segmentation
The revenue distribution across the global all solid state RF power supply market reveals distinct concentration patterns that directly inform sourcing strategies, partnership models, and regional investment prioritization. Historically, the Asia Pacific region has commanded the largest share of total market revenue, followed by North America and Europe. The Rest of World segment, while comparatively smaller in absolute terms, is experiencing accelerated adoption as emerging industrial hubs and specialized research facilities integrate solid state RF solutions into localized production ecosystems. Understanding these geographic weight distributions is critical for companies evaluating supply chain resilience, localized service infrastructure, and market entry sequencing.
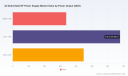
Power output segmentation further illuminates the operational priorities driving procurement decisions. The 2 kW to 5 kW bracket consistently represents the highest revenue concentration, underscoring the widespread demand for mid-range precision power delivery across semiconductor processing, thin film manufacturing, and controlled plasma applications. The below 2 kW segment holds significant volume in specialized laboratory, medical, and low-power industrial use cases, while the above 5 kW category captures high-intensity industrial heating, large-scale plasma excitation, and next-generation fusion research environments. Revenue distribution across these power tiers highlights how manufacturers balance throughput requirements against thermal management, cooling architecture, and control system complexity.
Application-driven segmentation reveals where the technology is creating the most measurable operational impact. Semiconductor etching continues to represent a dominant demand driver, reflecting the industry's relentless push toward finer feature dimensions, higher process repeatability, and tighter plasma uniformity tolerances. Thin film deposition follows as a closely aligned growth pillar, where precise RF energy modulation directly influences film quality, adhesion, and material stoichiometry. Medical treatment and imaging applications contribute a substantial and steadily expanding revenue stream, leveraging solid state RF for controlled therapeutic heating, diagnostic equipment, and non-invasive procedural technologies. Industrial plasma applications round out the core demand base, supporting surface treatment, cleaning, activation, and specialized material processing across aerospace, automotive, and advanced manufacturing verticals.
Technological Catalysts and Regulatory Alignment
The accelerated transition toward all solid state RF power architecture is fundamentally rooted in performance economics rather than incremental upgrades. Solid state designs rely on advanced semiconductor devices such as LDMOS, GaN, and SiC transistors as core amplification components, enabling high-efficiency power conversion with dramatically improved thermal stability and modulation responsiveness. The operational advantages are quantifiable: modern solid state RF power supplies routinely achieve energy efficiencies ranging from 60 to 95 percent, and in continuous industrial processes, this performance differential can reduce energy expenditures by as much as 50 percent when compared to traditional tube-based architectures.
Beyond efficiency, the industry is propelled by the demand for longer operational lifetimes, precise digital control, and substantially reduced maintenance overhead. Vacuum tube and magnetron systems inherently carry wear-related degradation, frequency drift, and periodic replacement burdens that disrupt high-uptime production environments. Solid state RF platforms address these vulnerabilities through modular design, real-time impedance management, and software-defined power profiling. These capabilities are increasingly non-negotiable in advanced manufacturing lines where process consistency directly correlates with yield, scrap reduction, and capital equipment utilization.
Regulatory alignment further reinforces market momentum. Operation within designated ISM frequency bands such as 13.56 MHz, 27.12 MHz, and 2.45 GHz enables manufacturers to maintain compliance for industrial, scientific, and medical RF power applications while maintaining controlled electromagnetic emissions. This regulatory compatibility streamlines global sourcing, simplifies certification pathways, and reduces integration friction across multinational production facilities. For enterprises scaling operations across jurisdictions, ISM band alignment is not a technical footnote; it is a strategic enabler of deployment velocity.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated competitive structure, with the top three players collectively accounting for approximately 54.2 percent of total industry revenue, while the top five firms command an estimated 68.85 percent. This concentration indicates a mature yet still dynamic competitive environment, where scale advantages, application-specific engineering capabilities, and integrated delivery ecosystems play decisive roles in customer acquisition and retention. The presence of strong regional specialists alongside global technology incumbents creates a multi-layered procurement landscape that rewards buyers who align vendor capabilities with process requirements rather than defaulting to generalized brand recognition.
Solid State Power Amplifiers Market
Advanced Energy continues to anchor its market presence through solid state RF plasma generators such as the eVerest, Paramount Plus, and Paramount series, which deliver precise RF and pulse control tailored for plasma processing and semiconductor applications. Their product philosophy emphasizes control fidelity and process repeatability, positioning the company as a preferred partner for high-stakes fabrication environments.
MKS Instruments maintains a differentiated value proposition by delivering solid state RF power generators integrated with impedance matching networks, effectively offering a complete RF delivery system rather than isolated power components. This systems-level approach resonates strongly with thin film processing equipment manufacturers seeking to reduce integration complexity, streamline troubleshooting, and improve overall plasma stability.
Worldwide All Solid State RF Power Supply Market
TRUMPF Hüttinger strengthens the European industrial supply base through its TruPlasma RF and MW series, which support plasma excitation and industrial heating applications. Their engineering heritage and cross-sector industrial footprint provide credible continuity for customers operating in demanding thermal and plasma environments.
Coaxial Power Systems Ltd addresses cost-sensitive and highly customized industrial use cases by specializing in solid state RF power supplies and automatic matching networks for sputter coating, inductively coupled plasma, diamond deposition, plastic welding, and bespoke scientific projects. Their flexible engineering model is particularly relevant for laboratories and specialized manufacturers requiring tailored RF configurations without excessive lead times.
Elite RF LLC pushes into the high-power segment with solid state RF amplifiers and microwave generators reaching up to 100 kW, marketed explicitly as replacements for magnetrons in plasma generation, CVD diamond growth, and precision industrial heating. Their capability to substitute legacy microwave sources while retaining or improving process outcomes positions them as a strategic alternative for facilities seeking to retire aging tube infrastructure.
Empower RF Systems supplies technologically advanced high-power solid state RF and microwave amplifiers and systems, available in both air-cooled and liquid-cooled configurations, serving industrial, test and measurement, and defense-related RF power applications. Their emphasis on cooling architecture flexibility and high-power system integration broadens their addressable market across both commercial and specialized government-adjacent use cases.
Aethera Technologies develops high-efficiency APG series solid state RF generators spanning 10 to 400 kW, targeting industrial heating, plasma, and fusion research applications with a reliability-first mindset that explicitly contrasts against vacuum tube technology. Their stated efficiency ceiling approaching 95 percent reinforces the broader industry narrative that energy performance and uptime reliability can be optimized simultaneously.
pinkRF B.V. has emerged as a notable innovator in programmable solid state RF energy generation, recently introducing the MPG10kS 10 kW model for 2.45 GHz ISM band applications. The product highlights improved reliability, precision control, and longevity over magnetron systems for plasma and industrial heating. The company amplified visibility through a trade show exhibition at SEMICON Europa 2025, positioning the platform as a magnetron alternative with measurable efficiency and control advantages.
Crescend Technologies continues to pioneer solid state RF microwave generators and systems as magnetron alternatives for material processing, mining, and laboratory applications, with an emphasis on zero emissions outcomes. This environmental and operational positioning appeals to organizations seeking cleaner process footprints alongside dependable microwave energy delivery.
Ampegon contributes a specialized but strategically important capability through fully solid state RF amplifiers built on modular LDMOS technology, supporting CW or pulsed outputs for accelerator and scientific applications across frequencies from 120 to 500 MHz and powers up to 320 kW CW. Their high-frequency, high-power design scope addresses demanding research and scientific infrastructure requirements that are less sensitive to volume pricing but highly sensitive to performance and reliability.
Recent activity from Wattsine Electronic Technology Co., Ltd. further illustrates the pace of product iteration across the competitive field. At SEMICON China, the company exhibited ESL and ESM series full digital solid state RF power supplies alongside solid state microwave remote plasma sources, emphasizing high stability for semiconductor applications. Such exhibition activity signals that digital control integration and remote plasma architecture are becoming standard competitive benchmarks rather than differentiating luxuries.
Operational Intelligence Embedded in the Research Framework
A strategically valuable market study must extend beyond top-line sizing and generic segmentation to provide actionable intelligence that procurement leaders, R&D directors, and corporate strategists can operationalize. The research framework associated with this market assessment is structured to support precisely that objective. It delivers a comprehensive mapping of historical demand patterns and forward-looking growth inflection points, enabling organizations to stress-test capacity planning, supplier diversification, and capital expenditure timing.
The analytical scope includes detailed segmentation evaluations that illuminate where revenue intensity is concentrated and where adoption curves are accelerating. By isolating power output requirements, application-specific consumption behaviors, and regional deployment momentum, the research equips decision-makers to align product roadmaps, distribution strategies, and service infrastructure investments with the highest-probability demand nodes. The inclusion of concentration metrics further supports competitive benchmarking by clarifying the share dynamics that shape pricing leverage, partnership feasibility, and barrier-to-entry assessments.
In addition to structural segmentation, the research integrates technology transition indicators that explain why certain procurement cycles are shifting. The documented move toward high-efficiency solid state architectures, digital control interfaces, and modular amplifier designs is presented in a manner that connects engineering characteristics with commercial outcomes. This is critical for organizations evaluating total cost of ownership, maintenance scheduling, and facility upgrade sequencing. Rather than treating technology migration as an abstract trend, the research framework ties it to tangible operational advantages, including reduced downtime exposure, improved process repeatability, and lower long-term energy intensity.
Regulatory and standards alignment is also interwoven into the analysis, ensuring that market evaluation reflects real-world deployment constraints. Frequency band compatibility, electromagnetic emission control, and industrial compliance pathways are treated as strategic variables that influence product selection, cross-border procurement, and integration timelines. For enterprises managing multi-site operations or expanding into new regulatory environments, this dimension of the research provides a pragmatic lens for de-risking adoption decisions.
The competitive profiling embedded within the study goes beyond descriptive company summaries. It evaluates how major players structure their value propositions, where they concentrate engineering resources, and how recent product introductions or exhibition activity signal near-term market intent. By connecting product launches, trade show positioning, and application-specific messaging to broader commercial strategies, the research helps readers interpret competitor behavior as forward-looking signals rather than isolated announcements. This is particularly relevant for organizations tracking magnetron replacement pathways, high-power amplifier expansion, and digital control standardization, all of which are actively reshaping procurement expectations.
Strategic Implications for 2026 Decision-Making
For organizations preparing for 2026 and beyond, the worldwide all solid state RF power supply market presents a convergence of operational necessity and strategic opportunity. The combination of sustained growth momentum, measurable efficiency advantages, and accelerating technology migration creates a window in which procurement strategy, vendor evaluation, and internal capability development can be synchronized with long-term production goals. Companies that delay assessment risk paying a premium in energy cost, maintenance exposure, and process variability, particularly as competitors adopt solid state RF platforms that improve repeatability and reduce lifecycle friction.
Procurement and engineering leaders should treat the current market phase as an opportunity to recalibrate supplier partnerships. Concentration metrics suggest that scale players hold meaningful share, but specialized firms continue to capture high-value segments through application-specific design, flexible cooling architectures, and programmable control features. Evaluating vendors against actual process requirements, not just catalog specifications, will increasingly separate efficient adopters from organizations that overpay for misaligned capabilities.
Similarly, the push toward digital control, modular amplification, and ISM band compatibility indicates that future operational resilience will depend on integration readiness as much as raw power output. Facilities that plan for impedance management, thermal architecture, and software-defined tuning now will be better positioned to scale throughput without incurring disruptive retrofits later. For R&D-intensive organizations, the availability of high-power solid state alternatives to magnetrons and vacuum tubes opens new experimental and production pathways in plasma generation, material deposition, and precision heating.
Capital allocation decisions should also account for the energy economics embedded in solid state RF adoption. With efficiency improvements capable of substantially reducing operating costs in continuous industrial processes, the total cost of ownership calculus is shifting in favor of upfront integration investment where uptime, control precision, and energy savings compound over time. Decision-makers who model these trade-offs explicitly will gain a clearer line of sight into payback horizons, capacity utilization targets, and competitive cost positioning.
Path Forward: Accessing the Complete Intelligence Framework
The trajectory of the worldwide all solid state RF power supply market reflects more than incremental technological replacement; it signals a structural recalibration of how industry delivers, controls, and harvests RF energy across high-value applications. The market's growth arc, competitive concentration, and technology transition patterns all point toward an environment where informed strategic planning will separate scalable operators from reactive followers. For executives and technical leaders looking to translate this environment into concrete action, the full research study provides the detailed segmentation evidence, competitive profiling, and forward-looking scenario analysis required to support confident planning.
Readers seeking the complete dataset, in-depth regional and application breakdowns, competitive benchmarking detail, and comprehensive technology transition analysis are encouraged to access the full Worldwide All Solid State RF Power Supply Market research report directly. The complete study offers the granular intelligence necessary to convert high-level market awareness into targeted procurement strategy, investment prioritization, and operational roadmap development. In a market defined by efficiency imperatives, control precision, and accelerating solid state adoption, the depth of intelligence accessed today will shape the resilience and competitiveness of industrial decisions throughout the coming forecast cycle.
For detailed analysis of this topic, please visit the official page: Worldwide All Solid State RF Power Supply Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Laser Type Oil Film Detector Market to Hit $191.2M by 2032, Expanding at 6.32% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence Report: Worldwide Laser Type Oil Film Detector Market 2026-2032
In an era where environmental compliance and industrial safety intersect with technological precision, the global market for laser type oil film detectors is undergoing a significant transformation. PW Consulting is proud to release our comprehensive Worldwide Laser Type Oil Film Detector Market research, a definitive guide designed to empower corporate strategists, procurement leaders, and investment analysts with actionable intelligence for the 2026 fiscal year and beyond. As industries face mounting pressure to monitor hydrocarbon contamination in real-time, understanding the trajectory of this specialized instrumentation market is no longer optional—it is a strategic imperative.
Worldwide Vibration Detector Market
This market research serves as a critical roadmap for navigating the complexities of industrial environmental monitoring. By integrating historical performance data from 2020 through 2025 with a forward-looking forecast extending to 2032, our analysis provides a robust framework for decision-making. The report is structured to reveal not just where the market stands today, but how it will evolve under the influence of regulatory shifts, technological advancements, and regional industrial growth. For executives aiming to secure market share or optimize supply chain investments, this document offers the granularity required to move from assumption to certainty.
Global Market Trajectory and Financial Outlook
The financial architecture of the laser type oil film detector market demonstrates resilient growth, driven by the dual forces of stricter environmental legislation and the modernization of industrial sensing infrastructure. Based on our comprehensive analysis, the global market generated revenue of 124.5 million USD in the base year of 2025. This figure represents the culmination of a steady growth period observed from 2020 to 2025, reflecting the increasing adoption of non-contact optical sensing technologies over traditional manual inspection methods.
Worldwide Laser Type Oil Film Detector Market
Looking ahead, the forecast period from 2026 to 2032 projects a compelling expansion trajectory. The market is anticipated to reach a valuation of 132.37 million USD in 2026, growing consistently to exceed 191.2 million USD by 2032. This growth path underscores a Compound Annual Growth Rate (CAGR) of 6.32 percent over the forecast horizon. Such a rate indicates a healthy, sustained demand rather than a temporary spike, suggesting that investment in this sector offers long-term stability. The consistent year-over-year increase highlights the deepening integration of laser-based detection systems into standard operational protocols across heavy industry and energy sectors.
This financial outlook is not merely a projection of unit sales but a reflection of value addition. As detectors become more sophisticated, incorporating features like false alarm prevention and extended operational ranges, the average value per unit is expected to support the revenue growth even as volume scales. For stakeholders, this means that the market opportunity is not solely dependent on mass adoption but also on the premiumization of technology capable of meeting rigorous industrial standards.
Segmentation Dynamics and Application Drivers
Our research delves deep into the structural components of the market, dissecting the demand across product types and end-use applications. This segmentation is vital for companies looking to specialize their product portfolios or identify underserved niches. The market is currently defined by a diverse range of hardware solutions, with a notable concentration in scanning technologies that offer comprehensive coverage of water surfaces and industrial drainage systems. Fixed-point sensors and portable units also constitute significant portions of the product landscape, catering to specific monitoring needs where mobility or continuous stationary surveillance is required.
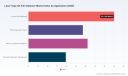
The application landscape reveals where the critical demand originates. Oil and gas refineries remain a primary driver, necessitating robust monitoring to prevent hydrocarbon discharge into drainage and storage facilities. Marine and offshore platforms represent another substantial vertical, where the detection of oil films on water is crucial for both environmental compliance and operational safety. Power generation plants and industrial wastewater management facilities also contribute significantly to the demand profile, leveraging laser technology to ensure that effluent discharge meets stringent regulatory limits.
Geographically, the market exhibits a distinct distribution of demand. Asia Pacific stands as the largest regional contributor, reflecting the intense industrial activity and manufacturing output in the region. Europe follows as a significant market, driven by rigorous EU environmental directives and a mature industrial base. North America maintains a strong presence, supported by its extensive energy infrastructure and stringent safety regulations. Meanwhile, emerging opportunities are being tracked in the Middle East and Africa, as well as Latin America, where industrial expansion is beginning to necessitate advanced monitoring solutions. Our report provides detailed analysis of these regional variances without exposing the specific allocation percentages, directing stakeholders to the full dataset for precise regional planning.
Competitive Landscape and Strategic Player Analysis
The market environment is characterized by a mix of established Japanese manufacturers dominating the technology space and innovative players entering from other regions. The competitive landscape is moderately concentrated, with the top three companies holding a combined market share that reflects the high barrier to entry regarding specialized laser technology and certification standards. The top five players collectively command a significant portion of the market, indicating that partnerships or acquisitions with these key entities could be a viable strategy for broader market access.
Asahi Kasei Technosystem, headquartered in Japan, continues to be a pivotal player with its Apolarm series, including the LMD-3000N and LMD-600 models. These products are renowned for their ability to detect micron-level films at specific distances, making them essential for environmental monitoring in drainage and purification plants. Competitor HORIBA Ltd. also maintains a strong position with its LO-300 laser scanning oil film detector, which utilizes semiconductor laser technology for non-contact detection. HORIBA's focus on extended laser module life and improved resistance to false alarms from debris demonstrates a commitment to reliability in harsh industrial environments. DKK-TOA Corporation and TOKYO KEIKI INC. further strengthen the Japanese presence in the market, offering both explosion-proof and non-explosion-proof variants suitable for diverse safety requirements in industrial settings.
On the international front, Laser Diagnostic Instruments AS (LDI) from Estonia provides a unique value proposition with its ROW remote optical watcher technology. Capable of detecting oil films from significant heights, LDI addresses applications where access to the water surface is limited, expanding the utility of laser detection in offshore and large-scale environmental monitoring. The presence of these key companies creates a dynamic competitive environment where differentiation through specification, certification, and regional support becomes the primary battleground.
Regulatory Tailwinds and Technological Innovations
Market dynamics are heavily influenced by the regulatory environment. In key jurisdictions, revisions to safety acts and environmental compliance standards are mandating earlier detection of oil leaks in industrial drainage and storage facilities. For instance, in Japan, laser type oil film detectors are increasingly recognized as supports for compliance with the Fire Service Act revisions. This regulatory pressure transforms the detector from a optional safety tool into a required compliance asset, directly stimulating market demand.
Technological specifications are evolving to meet these regulatory needs. Recent industry developments highlight a focus on durability and accuracy. For example, recent product demonstrations by HSA Asia and Asahi Kasei in early 2026 showcased comprehensive performance testing of the Apolarm M LMD-3000, emphasizing its capability in thin-layer detection within drainage systems. Such events validate the technology for procurement teams and signal a market readiness to adopt higher-specification units. Furthermore, advancements such as extended laser module life and certifications like CE marking compliant with EMC and Low-voltage Directives are becoming table stakes for suppliers aiming to operate in global markets. These certifications ensure that equipment can be deployed safely in industrial environments without electromagnetic interference issues, a critical factor for plant managers.
The industry is also seeing a shift towards enhanced wave resistance and false alarm prevention. As detectors are deployed on flowing water surfaces or in areas with biological matter, the ability to distinguish between an oil film and debris is paramount. Manufacturers are responding by refining their optical algorithms and hardware resilience, ensuring that the data provided to operators is reliable enough to trigger immediate action without unnecessary downtime caused by false positives.
Strategic Value for 2026 Decision Making
For corporations operating in or servicing the industrial sector, the insights contained in this report are designed to mitigate risk and identify opportunity. The 2026 decision-making landscape requires a clear understanding of where capital should be allocated. Whether a company is looking to manufacture components, distribute finished units, or implement monitoring systems within their own facilities, the granular data on market size, growth rates, and competitive positioning is indispensable.
The report offers actionable content that goes beyond high-level summaries. It includes detailed profiles that assess the capabilities and strategic directions of key manufacturers, allowing readers to benchmark their own offerings or potential partners against industry leaders. By understanding the specific strengths of competitors—such as HORIBA's certification standards or Asahi Kasei's drainage system focus—businesses can carve out differentiated positions in the market. Additionally, the analysis of recent developments provides a pulse on the current pace of commercialization and technology validation, helping planners align their product launch timelines with market readiness.
Investment in this market is not just about selling hardware; it is about enabling compliance and safety. The report elucidates how the intersection of regulatory demand and technological capability creates a locked-in growth path. For investors, this reduces the uncertainty associated with technology adoption cycles. For vendors, it highlights the importance of aligning marketing and sales efforts with regulatory milestones and specific application pain points, such as oil-water separation in refineries or environmental monitoring in wastewater plants.
Conclusion and Access to Comprehensive Intelligence
The Worldwide Laser Type Oil Film Detector Market is at a pivotal stage where technology, regulation, and industrial necessity converge. The projected growth from 124.5 million USD in 2025 to over 191.2 million USD by 2032 signals a robust environment for strategic engagement. However, mastering this market requires more than just top-line numbers. It demands an understanding of the nuanced segmentation splits, the specific competitive advantages of key players, and the regional regulatory frameworks that dictate deployment.
PW Consulting's full market research report provides the depth required to navigate this landscape confidently. We have outlined the macro trajectory and the key players in this overview, but the strategic edge lies in the details. The complete report offers exhaustive data tables, deep-dive regional analyses, and specific revenue splits across segments that are essential for precise forecasting and resource allocation. We invite stakeholders to access the full intelligence package to equip their organizations with the knowledge needed to lead in this evolving sector. In a market driven by precision and compliance, having the most accurate intelligence is the ultimate competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Laser Type Oil Film Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cloud Machine Translation Market Hits $1.85B in 2025, Projected to Reach $6.07B by 2032
By pmarketresearch, 2026-09-16
Global Cloud Machine Translation Market: Strategic Intelligence for Enterprise Decision-Making in 2026 and Beyond
The worldwide landscape of digital communication is undergoing a fundamental shift, driven by the rapid maturation of neural machine translation technologies deployed within cloud environments. As organizations expand their global footprint, the ability to localize content, facilitate cross-border collaboration, and engage customers in native languages has transitioned from a competitive advantage to a operational necessity. PW Consulting presents a comprehensive analysis of the Worldwide Cloud Machine Translation Market, offering a detailed roadmap of the industry's trajectory from 2026 through 2032. This report is designed not merely as a statistical overview, but as a strategic asset for executives, investors, and technology leaders who must navigate the complexities of this high-growth sector.
The expansion of this market reflects broader trends in artificial intelligence adoption, cloud infrastructure scalability, and the increasing demand for real-time language services across diverse industries. Our research provides a rigorous examination of market size, growth trajectories, competitive dynamics, and the regulatory environment that will define the next era of cloud-based translation services. By synthesizing historical performance data with forward-looking projections, we enable stakeholders to make informed decisions regarding investment, technology selection, and market entry strategies.
Market Scale and Growth Trajectory
The cloud machine translation market has demonstrated robust expansion over the past five years, establishing a strong foundation for continued acceleration. In 2025, the global market generated revenue of 1,850.0 million USD, representing a significant increase from 820.0 million USD in 2020. This historical progression underscores the growing reliance on cloud-based translation solutions as organizations move away from legacy on-premise systems and embrace the flexibility, scalability, and cost-efficiency of cloud deployment models.
Looking forward, the market is projected to maintain a compelling compound annual growth rate of 18.5 percent throughout the forecast period spanning 2026 to 2032. Under this growth trajectory, market revenue is expected to reach 2,326.58 million USD in 2026, followed by steady escalations to 2,583.93 million USD in 2027, 3,119.43 million USD in 2028, and 3,664.40 million USD in 2029. By the conclusion of the forecast horizon in 2032, the worldwide cloud machine translation market is anticipated to achieve a total revenue of 6,070.15 million USD. These figures highlight the substantial economic opportunity present in this sector and the critical importance of strategic positioning for organizations seeking to capture value within this expanding ecosystem.
Deployment Models and Industrial Adoption Patterns
The architecture of cloud machine translation adoption is shaped by diverse deployment preferences and industry-specific requirements. Organizations evaluate public cloud, private cloud, and hybrid cloud environments based on factors such as scalability needs, data security considerations, compliance obligations, and integration complexity. Each deployment model serves distinct use cases, and understanding the relative advantages of these approaches is essential for technology procurement and infrastructure planning. Our report provides a detailed breakdown of how revenue is distributed across these deployment categories, offering insight into prevailing enterprise preferences and emerging shifts in deployment strategy.
Worldwide AI Learning Machine Market
Industry verticalization represents another critical dimension of market analysis. Different sectors exhibit varying levels of adoption intensity, driven by unique operational demands and translation volume requirements. The information technology and telecommunications sector leads adoption, reflecting the industry's inherent global connectivity and reliance on multilingual interfaces for software, support, and user engagement. E-commerce and retail platforms leverage cloud machine translation to localize product catalogs, customer reviews, and marketing content, enabling seamless cross-border commerce experiences. Healthcare and life sciences organizations increasingly depend on accurate translation for medical documentation, research collaboration, and patient communication, where precision and regulatory compliance are paramount. Media and entertainment companies utilize these technologies for content localization, subtitle generation, and global distribution, while government and defense agencies apply translation solutions for intelligence analysis, diplomatic communication, and multinational operations. Our research maps these industry dynamics in detail, revealing the specific drivers, barriers, and growth opportunities within each vertical.
Regional Market Dynamics
Geographical distribution of cloud machine translation revenue reflects the varying maturity levels, digital infrastructure capabilities, and localization demands across global regions. North America constitutes a substantial share of the market, supported by advanced cloud infrastructure, a dense concentration of technology enterprises, and high adoption rates among both established corporations and emerging startups. Europe represents a significant market segment, characterized by diverse linguistic requirements, stringent data protection regulations, and a strong emphasis on translation quality and privacy-preserving deployment options. The Asia Pacific region demonstrates considerable growth potential, fueled by expanding digital economies, increasing cross-border trade, and the proliferation of multilingual user bases across countries such as China, Japan, South Korea, and India. Latin America and the Middle East and Africa regions, while currently representing smaller revenue contributions, are emerging as important growth corridors as digital transformation initiatives accelerate and localization requirements intensify.
Our report examines these regional dynamics with granularity, providing insights into local market characteristics, infrastructure developments, and the interplay between regional regulations and market growth. Understanding these geographical nuances is critical for organizations developing global market entry strategies or optimizing their cloud translation deployments across multiple jurisdictions.
Competitive Landscape: Key Market Participants
The cloud machine translation market is shaped by a diverse array of technology providers, ranging from hyperscale cloud platforms to specialized translation firms, each bringing distinct capabilities, ecosystem advantages, and strategic positioning. The competitive environment is characterized by ongoing innovation in neural network architectures, expansion of language coverage, integration with broader artificial intelligence and cloud service portfolios, and increasing focus on enterprise-grade security and customization.
Worldwide Cloud Machine Translation Market
Google LLC, headquartered in Mountain View, California, provides the Google Cloud Translation API, a scalable cloud-based neural machine translation service supporting over two hundred languages with real-time text and speech translation capabilities designed for enterprise integration. This offering leverages Google's extensive research in artificial intelligence and its global cloud infrastructure to deliver high-volume, low-latency translation services.
Microsoft Corporation, based in Redmond, Washington, offers Microsoft Azure Translator, a cloud machine translation service with neural models supporting more than one hundred languages. This service benefits from deep integration with the Microsoft ecosystem, including Office and Teams, enabling seamless translation functionality within productivity workflows and enterprise applications widely used across global organizations.
Amazon Web Services Inc., headquartered in Seattle, Washington, delivers Amazon Translate, a neural machine translation service within the AWS cloud supporting more than seventy-five languages. This offering is optimized for customization, batch processing, and tight integration with other AWS services, appealing to organizations already invested in the Amazon cloud ecosystem and seeking flexible, scalable translation solutions.
DeepL GmbH, headquartered in Cologne, Germany, provides the DeepL API and Enterprise cloud machine translation focused on high-accuracy neural translations, with particular strength in European language pairs. DeepL emphasizes quality and nuance in translation output, complemented by privacy-focused cloud deployment options that address the requirements of security-conscious enterprise clients.
IBM Corporation, based in Armonk, New York, offers IBM Watson Language Translator, a cloud-based machine translation service using neural networks with domain customization capabilities within the IBM Cloud. This solution targets organizations seeking tailored translation models aligned with specific industry terminology and operational contexts.
Alibaba Cloud, headquartered in Hangzhou, China, provides the Alibaba Cloud Machine Translation API, a neural machine translation service integrated with the Alibaba Cloud ecosystem. This offering supports multiple languages with a focus on Asian language pairs, catering to the growing digital commerce and communication needs of the Asia Pacific region.
Tencent Cloud, based in Shenzhen, China, delivers Tencent Machine Translation, a cloud-based neural machine translation service with strong performance in Chinese-English and other language pairs, integrated with Tencent Cloud infrastructure. This service supports the translation demands of enterprises operating within Tencent's extensive digital ecosystem.
SYSTRAN SA, headquartered in Paris, France, offers SYSTRAN Translate cloud and hybrid machine translation solutions with neural and hybrid models. SYSTRAN emphasizes secure enterprise deployments and customization capabilities, appealing to organizations with stringent security requirements and specialized translation needs.
The market concentration among existing participants reflects a moderately consolidated competitive environment, with the top three firms accounting for a combined revenue share that underscores the influence of major cloud platform providers while still leaving meaningful space for specialized vendors to differentiate through quality, domain expertise, and regional focus. The top five firms collectively represent a substantial portion of market revenue, illustrating the importance of ecosystem integration, brand recognition, and technological scale in this sector.
Regulatory and Infrastructure Dynamics Shaping Market Evolution
The trajectory of the cloud machine translation market is increasingly influenced by regulatory frameworks and infrastructure considerations that affect how translation services are deployed, governed, and consumed. Organizations operating in this space must navigate an evolving landscape of data protection laws, artificial intelligence regulations, and energy infrastructure constraints that collectively shape the operational and strategic environment.
In the regulatory domain, the European Union AI Act, which became effective in 2024 with phased implementation, classifies certain high-risk artificial intelligence systems, including advanced machine translation solutions, and imposes requirements for risk assessment, transparency, and compliance. This regulatory framework introduces new obligations for providers and users of cloud machine translation services operating within or targeting the European market, necessitating robust governance structures and documentation practices.
Data sovereignty regulations further complicate the deployment of cloud machine translation services. The General Data Protection Regulation, the EU Data Act applicable from September 2025, the Digital Operational Resilience Act, and the NIS2 Directive collectively require localized data processing and control for cloud services handling sensitive information within machine translation workflows. These requirements influence deployment model selection, provider choice, and architectural design, particularly for organizations managing personally identifiable information, confidential business data, or regulated content.
From an infrastructure perspective, the energy demands of artificial intelligence data centers represent a growing consideration for the cloud machine translation sector. AI data centers, which are critical for powering cloud machine translation inference workloads, are projected to drive significant increases in global electricity demand. Estimates suggest that United States data center consumption could reach between 325 and 580 terawatt-hours by 2028, according to research from the Lawrence Berkeley National Laboratory. This surge in energy consumption has implications for operational costs, sustainability initiatives, and the broader economic environment in which cloud services operate. Concurrently, United States residential electricity prices rose by 7.1 percent in 2025, with data center-driven demand cited as a major contributing factor alongside grid investments, as reported by the United States Energy Information Administration. These energy cost dynamics may influence cloud service pricing structures and the economic calculus of large-scale translation deployments.
In the United States, the CLOUD Act allows federal authorities to compel United States-based cloud providers to disclose data regardless of storage location, impacting data sovereignty considerations for international cloud machine translation users. This legal framework introduces additional complexity for multinational organizations evaluating provider options and data residency requirements.
Strategic Value of Comprehensive Market Intelligence
For enterprise leaders, technology investors, and strategic planners, the decisions made in 2026 will have lasting implications for competitive positioning and operational efficiency in the global marketplace. Selecting the appropriate cloud machine translation partner, determining the optimal deployment architecture, anticipating regulatory shifts, and understanding the competitive landscape require a depth of analysis that goes beyond surface-level market observations.
PW Consulting's Worldwide Cloud Machine Translation Market report delivers actionable intelligence across multiple dimensions critical to decision-making. The report provides detailed segmentation analysis across deployment models, industry verticals, and geographic regions, revealing the specific growth vectors and revenue concentrations that define the market. It includes comprehensive profiles of key market participants, examining their service offerings, technological capabilities, ecosystem integrations, and strategic positioning. The analysis incorporates an evaluation of market concentration metrics, competitive intensity, and the potential for new entrants or consolidation activities that could reshape the industry structure.
Furthermore, the report addresses the practical implications of regulatory developments and infrastructure trends, providing guidance on compliance considerations, data sovereignty management, and the economic factors influencing cloud service economics. By integrating these diverse elements into a cohesive analytical framework, the research enables organizations to develop robust strategies that account for both current market conditions and future evolution.
The insights contained within this report are essential for organizations seeking to optimize their translation technology investments, identify partnership opportunities, assess competitive threats, and capitalize on emerging growth areas. Whether you are evaluating vendor selection criteria, planning market expansion, or developing long-term technology roadmaps, the detailed analysis presented in this study provides the foundation for confident, data-informed strategic decisions.
To access the complete market intelligence, including all segmentation data, competitive profiles, regional breakdowns, and forward-looking projections, we invite you to obtain the full report through our official channels. The comprehensive analysis delivered in this publication represents the depth of expertise and rigorous research methodology that PW Consulting brings to complex technology markets, empowering our clients to navigate the future of cloud machine translation with clarity and strategic foresight.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud Machine Translation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Difurfuryldisulfide Market Hits $24.8M in 2025, Driven by F&B Flavoring and Asia Pacific
By pmarketresearch, 2026-09-16
Navigating the Difurfuryldisulfide Market: Strategic Intelligence for 2026 and Beyond
The specialty chemicals sector continues to reward organizations that pair operational precision with forward-looking market intelligence. As industrial formulators, flavor houses, and supply chain leaders finalize their 2026 procurement and capacity strategies, the difurfuryldisulfide market presents a compelling case for disciplined evaluation. In this landscape, our latest research deliverable arrives not as a static snapshot, but as a decision-enabling framework designed to align procurement, R&D, and competitive positioning with the realistic trajectory of a maturing, value-driven niche.
Built on a rigorous five-year historical baseline spanning 2020 through 2025 and extending through a seven-year forecast window to 2032, this analysis translates longitudinal demand signals, pricing behaviors, and structural shifts into actionable intelligence. The narrative that follows is deliberately curated: it demonstrates the depth of our methodology and the relevance of our findings while preserving the granular segmentation required for precise planning. For executives who require exact regional breakdowns, purity-tier valuations, and application-level market shares, the full report remains the definitive source.
A Measured Expansion Trajectory Anchored in Value-Tier Demand
The difurfuryldisulfide market has followed a disciplined growth curve, expanding from a baseline of USD 20.12 million in 2020 to a projected USD 26.26 million in 2026. This progression is not the result of volatile speculation but rather reflects steady consolidation across flavor, fragrance, and industrial applications where sulfur-linked furan derivatives serve distinct functional roles. Over the forecast horizon through 2032, the market is expected to reach USD 33.52 million, translating to a compound annual growth rate of 4.4 percent.
For strategic planners, that trajectory carries two immediate implications. First, growth is structural rather than cyclical, suggesting that demand is anchored in recurring formulation requirements rather than one-off sourcing events. Second, the pace of expansion is moderate enough to reward careful supplier evaluation and contract structuring, yet fast enough to penalize organizations that treat this category as a commoditized afterthought. Companies that treat difurfuryldisulfide as a strategic input, rather than a back-pocket ingredient, will be better positioned to manage continuity, specification compliance, and total cost of ownership.
The research also situates this trajectory within a broader feedstock and regulatory context. Furfural, the primary upstream material for furfuryl derivatives, is derived substantially from agricultural residues such as corn cobs, and its downstream pathways influence both availability and cost stability for difurfuryl disulfide producers. In parallel, evolving environmental frameworks, including European emission restrictions on formaldehyde that favor furfuryl alcohol-based resins over phenolic alternatives, are reshaping demand patterns in adjacent furan-chemistry applications. These dynamics do not merely color the headline numbers; they define the operating environment in which suppliers and buyers must make long-term commitments.
Competitive Architecture and the New Relevance of Compliance
The competitive landscape for difurfuryldisulfide is concentrated but diversified by function, geography, and certification posture. With the top three players holding approximately 42.5 percent of the market and the top five extending that share to 58.8 percent, the industry exhibits enough fragmentation to preserve sourcing flexibility while maintaining enough concentration to reward supplier relationship management. Organizations that understand who controls which grade, which certifications, and which distribution channels will move faster when specifications tighten or lead times compress.
Several established participants illustrate how the market is bifurcating between natural-identity positioning, synthetic-grade utility, and research-grade precision. In North America, Advanced Biotech Inc. continues to supply difurfuryl disulfide natural and synthetic grades for food, beverage, and aroma applications, with kosher and other certifications maintained through 2026. Its recent renewal of kosher certification for DIFURFURYL DISULFIDE 10% ETOH NATURAL, valid through November 2026, underscores how compliance continuity has become a differentiator in food and beverage supply chains. Axxence Aromatic GmbH, operating from Germany, provides a natural-grade offering recognized under EU natural and FEMA 3146 standards, and its December 2025 halal certification renewal reflects a broader trend: identity-preserved and certification-backed materials are increasingly tying up market share in sensitive applications.
Beyond these Western and European players, the competitive field extends across East Asia and specialized distribution networks. TCI America, through Tokyo Chemical Industry Co., Ltd., manufactures and distributes difurfuryl disulfide at 95.0+ percent purity for research, synthesis, and industrial use, often routed through established laboratory distributors. Spectrum Chemical Mfg. Corp. and Scimplify serve parallel but distinct roles in the U.S. market by offering laboratory-scale and bulk industrial supply, respectively, with regulatory documentation and COA/SDS support. Alfa Chemistry positions itself as an ISO 9001:2015 certified supplier of furan derivatives with 98+ percent purity options, while Aurochemicals addresses the natural flavor enhancement segment with diluted formats such as 1 percent in ethanol or propylene glycol. On the manufacturing side, Nanjing MSN Chemical Co., Ltd. and Beijing Lys Chemicals Co., Ltd. emphasize global distribution of fine chemicals and gram-to-ton scale production, respectively, while Tengzhou Runlong Fragrance Co., Ltd., operating since 2004, focuses on meat flavor agent applications with FEMA 3146 and CAS 4437-20-1 specifications.
This roster is not merely a directory; it is a map of capability, risk, and negotiation leverage. Some participants compete primarily on purity thresholds and documentation readiness, others on natural identity and certification portability, and still others on scale, logistics, and price architecture. The report’s competitive assessment section explains how these postures interact with buyer requirements across food and beverage, fragrance and cosmetics, and animal feed applications, helping procurement teams match specification needs with supplier strengths rather than defaulting to price alone.
Natural Sulforaphane Market
From Headline Numbers to Operating Decisions
A realistic market study must do more than describe demand; it must help teams convert context into commercial decisions. Our research is structured to support that translation through practical, cross-functional modules that move beyond the aggregate market size and CAGR. The report examines how upstream cost differentials and feedstock geography influence derivative pricing, how regulatory shifts alter preferred resin and polymer pathways and, by extension, downstream furan demand, and how certification renewals and safety data sheet updates affect sourcing continuity.
Readers will find detailed attention to the interplay between purity requirements and application suitability, a critical dimension in a category where 98+ percent purity often commands a premium but where certain formulations may be optimized at lower thresholds. The analysis also explores how regional manufacturing costs and logistics friction shape supply options, noting for example that furfural production economics can differ materially between China and North America due to labor and logistics variables, and that furfuryl alcohol pricing has moved within defined bands over recent years depending on purity and grade. These factors do not operate in isolation; they help explain why some buyers prioritize certified natural identity while others emphasize bulk pricing and documentation speed.
Equally important, the report assesses supply continuity risk through the lens of certification lifecycles, regulatory documentation, and distributor networks. With recent events ranging from Advanced Biotech’s SDS update in mid-2025 to Axxence’s halal certification in late 2025 and Advanced Biotech’s kosher renewal in early 2026, the evidence points to a market where compliance is not a static checkbox but an ongoing operational commitment. Organizations that track these milestones and incorporate them into supplier scorecards will face fewer surprises during qualification cycles and audits.
Difurfuryldisulfide Market
Where the Report Goes Further: Executive Intelligence Designed for Action
To support execution across procurement, R&D, and strategy, the full report delivers operational content that extends well beyond the macro summary. Decision-makers can expect:
- A structured view of market size evolution from the 2020 base through the 2026 forecast and the full projection period to 2032, framed in U.S. dollars and millions of dollars, with analysis of inflection points rather than isolated figures.
- A competitive mapping that aligns each key company’s product grades, purity ranges, certification posture, and distribution channels with the applications and geographies where they matter most.
- An examination of how upstream feedstock dynamics, including furfural availability and furfuryl alcohol pricing trends, influence derivative supply chains and downstream cost structures.
- A regulatory and compliance narrative that connects emission directives, certification renewals, and documentation practices to sourcing decisions and audit readiness.
- Practical guidance on evaluating natural versus synthetic identity, purity thresholds, and dilution formats across food, beverage, fragrance, cosmetics, and animal feed applications.
This structure is intentional. Rather than overwhelming readers with static tables, the report connects each insight to a decision point: which supplier to qualify, which purity tier to target, how to structure multi-period contracts, and where to place R&D emphasis as feedstock economics and regulatory frameworks evolve.
Why 2026 Decisions Depend on Precision, Not Just Direction
The difurfuryldisulfide market in 2026 is best understood as a category where the cost of ambiguity is rising. Moderate but steady growth, a moderately concentrated supplier base, and certification-sensitive end uses all point to the same conclusion: organizations that operate on generic assumptions will pay for it in qualification delays, specification mismatches, or avoidable premium pricing. By contrast, teams that integrate feedstock context, competitive capability, and compliance continuity into a single planning framework can protect continuity while improving unit economics.
That is precisely where the full research earns its place in the decision cycle. The executive overview presented here has outlined the strategic contours and demonstrated the analytical rigor behind the study. What it cannot do, by design, is replace the detailed regional, purity, and application segmentation that purchasing directors and formulation leads need before committing capital. Those specifics, including precise market values and split-level intelligence, are preserved in the complete report so that each organization can align the data with its own specification thresholds, volume profiles, and compliance requirements.
Accessing the Full Intelligence
A market of this shape rewards early clarity. The full Difurfuryldisulfide Market research report provides the granular segmentation, company-by-company capability mapping, regulatory timeline, and forecast detail required to convert strategy into procurement and product decisions with confidence. For leaders planning 2026 sourcing, R&D prioritization, and supplier qualification, the complete study is the optimal reference point. Detailed segmentation data, company profiles, and forecast tables are available through our research portal, where the full dataset can be aligned to your internal volume assumptions and compliance standards.
For detailed analysis of this topic, please visit the official page: Difurfuryldisulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Aesthetic Phototherapy Lamp Market Hits $645.5M in 2025, Poised for 8.75% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence: Navigating the Worldwide Aesthetic Phototherapy Lamps Market in 2026
The global aesthetic phototherapy lamps market stands at a pivotal inflection point as industry stakeholders transition from the 2020-2025 historical growth cycle into the 2026-2032 forecast period. Driven by a compound annual growth rate of 8.75 percent, the sector is projected to expand from a 2025 baseline of USD 645.5 million to an estimated USD 1.16 billion by 2032. This trajectory reflects a structural shift in how aesthetic dermatology, clinical skincare, and at-home wellness converge around evidence-based light-based interventions. For executives, investors, and product strategists, 2026 represents the year when regulatory clarity, reimbursement pathway maturation, and competitive consolidation will decisively shape market entry, portfolio positioning, and revenue forecasting. Our latest Worldwide Aesthetic Phototherapy Lamps Market research is designed to convert this momentum into executable intelligence.
Macro Trajectory and the 2026 Decision Window
The five-year historical record from 2020 through 2025 demonstrates consistent expansion, moving from USD 425.1 million to USD 594.85 million before reaching the 2025 anchor of USD 645.5 million. The forward projection series maps a steady climb: USD 701.98 million in 2026, USD 763.4 million in 2027, USD 830.2 million in 2028, USD 902.84 million in 2029, USD 981.84 million in 2030, USD 1.07 billion in 2031, and USD 1.16 billion in 2032. While aggregate figures establish the scale of opportunity, the strategic value of this research lies in unpacking the forces that will redistribute share, pricing power, and margin profiles across light source categories, application verticals, end-user channels, and regional ecosystems. Companies that treat 2026 as a planning horizon rather than a passive transition will be better positioned to align capital allocation, regulatory filings, and channel strategy with the market’s actual architecture.
What the Report Delivers: Actionable Scoping for Product, Pricing, and Channel Strategy
This study is structured to support operational decision-making rather than high-level observation. It maps the market across multiple dimensions, providing a granular view of how demand concentrates by technology platform, clinical and consumer application, procurement environment, and geography. The segmentation analysis examines light source dynamics across LED, IPL, and other lamp technologies, clarifying where performance characteristics, total cost of ownership, and regulatory status create durable advantages or exposure. The application lens dissects demand patterns across skin rejuvenation, acne treatment, pigmentation treatment, and wound healing, highlighting how clinical indications, consumer adoption curves, and service models diverge by use case. The end-user framework evaluates medical clinics, beauty salons, and home care settings, exposing the distinct purchasing behaviors, service expectations, and price sensitivity that define each channel.
Beyond segmentation, the report addresses competitive concentration and ecosystem structure. With the top three players accounting for approximately 42.15 percent of market value and the top five reaching roughly 58.8 percent, the landscape reflects meaningful incumbency advantages alongside persistent entry points in niche indications, regional channels, and consumer-grade devices. The study integrates company profiles, capability assessments, and recent development tracking to help strategists benchmark positioning, identify partnership targets, and anticipate where capacity expansion, product refreshes, or regulatory filings may alter local supply dynamics.
Regulatory and Reimbursement Context: Why 2026 Is a Policy-Sensitive Year
Aesthetic phototherapy is increasingly governed by a layered regulatory and reimbursement environment, and 2026 is a year in which several structural developments will influence commercial planning. Aesthetic LED phototherapy devices intended for wrinkle reduction and acne treatment are classified as Class II under 21 CFR 878.4810 with product codes including OHS, requiring 510(k) clearance for U.S. marketing. This clearance pathway has become a strategic gatekeeper, particularly as manufacturers pursue over-the-counter and at-home indications. Recent FDA 510(k) clearances illustrate the pace of this activity: in December 2025, Shenzhen Saidi Light Therapy Technology received clearance for its LED Light Therapy Face Mask series, including FM60X, FM80, and FM100X variants for facial wrinkles and mild to moderate inflammatory acne. In June 2025, Shenzhen Kaiyan Medical Equipment, the manufacturer behind CurrentBody Skin, secured clearance for the CurrentBody Skin LED Light Therapy Mask Series 2, MK-90H, for over-the-counter full-face wrinkle treatment. In February 2025, Xuzhou Kernel Medical Equipment obtained clearance for 308nm excimer phototherapy device models for psoriasis and vitiligo, which are relevant in aesthetic dermatology contexts. In November 2024, Shenzhen Walton Technology received clearance for LED Light Therapy Machine models G1, G3, G4, and G6 for over-the-counter aesthetic use in wrinkle treatment and acne.
These clearances are not isolated product events; they signal broader pathway trends. The American Medical Association activated CPT Category III Code 0936T effective January 1, 2025, for photobiomodulation therapy to support data collection toward potential future Medicare reimbursement. Simultaneously, revised CPT code descriptors for excimer laser procedures, CPT 96920, 96921, and 96922, are scheduled to become effective January 1, 2027, expanding reimbursable indications to include additional inflammatory and autoimmune skin conditions such as vitiligo, atopic dermatitis, and alopecia areata. In parallel, national CPT code reimbursement rates for excimer laser treatments in 2025 ranged from USD 137 to USD 183 per treatment depending on treated area, spanning under 250 square centimeters to over 500 square centimeters. Together, these developments shape the economics of clinical adoption, the attractiveness of medical-channel procurement, and the incentive structure for device manufacturers pursuing reimbursable indications.
Procurement realities further complicate the commercial picture. Hospital and institutional purchasing for phototherapy equipment is frequently executed as structured value-based purchases bundled with accessories, installation, and service, reflecting capital expenditure constraints in public tenders. This bundling behavior influences not only upfront pricing but also service-level expectations, lifecycle support requirements, and the competitive leverage of manufacturers that can deliver integrated deployment models rather than standalone hardware.
Competitive Landscape and Where Share Is Being Won or Lost
The competitive set in aesthetic phototherapy spans dermatologic device leaders, specialty lamp manufacturers, consumer-grade wearable and mask developers, and integrated energy-based aesthetic platform companies. Beijing Sincoheren offers dermatologic phototherapy lamps including LUMERA for aesthetic skin treatments. Kernel Medical Equipment, based in Xuzhou, Jiangsu, manufactures aesthetic and dermatologic phototherapy lamps and excimer devices for skin rejuvenation and treatment. LightSources and LightTech, headquartered in Orange, Connecticut, specialize in fluorescent and UV specialty light therapy lamps for medical and aesthetic phototherapy applications. Lumitex, based in Strongsville, Ohio, provides therapeutic lighting solutions and light therapy components for medical device manufacturers in aesthetic applications. ProReset, operating across Germany and Europe, offers aesthetic phototherapy lamps such as ProRed, Lumina, and Eva Led for skin rejuvenation, blood circulation, and muscle recovery. BioPhotas, Inc., in the United States, develops the Celluma series of biophotonic LED devices for aesthetic anti-aging, acne, and skin rejuvenation treatments. Shenzhen Idea Light Limited, also known as IDEATHERAPY, manufactures red light therapy panels and wearable LED phototherapy devices for aesthetic skin treatments. CurrentBody, manufactured by Shenzhen Kaiyan Medical Equipment, provides LED light therapy masks such as Series 2 for at-home aesthetic treatment of facial wrinkles. LightStim offers LED light therapy devices integrated in aesthetic systems for skin rejuvenation and acne treatment. Alma Lasers develops energy-based aesthetic devices including phototherapy and light-based systems for skin treatments. Lumenis provides laser and light-based aesthetic solutions with phototherapy capabilities for skin rejuvenation. Candela Medical, formerly Syneron Candela, offers aesthetic light and laser systems for phototherapy applications in dermatology and skin rejuvenation. Cutera manufactures aesthetic laser and light devices including phototherapy options for skin treatments. Fotona combines laser and light-based aesthetic solutions for precision skin rejuvenation and phototherapy. The Daavlin Company specializes in phototherapy lamps and units for dermatologic and aesthetic skin treatments. National Biological Corporation provides phototherapy lamps for aesthetic medicine and dermatologic applications. Herbert Waldmann GmbH & Co. KG manufactures phototherapy lamps and lighting systems used in aesthetic and medical treatments.
This diversity of players reflects a market in which technology leadership, regulatory access, distribution reach, and brand positioning all matter. Some firms compete primarily through clinical-grade performance and reimbursement-adjacent indications; others compete through consumer usability, aesthetics, and at-home convenience. The report evaluates where these strategies intersect, where overlap creates pricing pressure, and where differentiation remains defensible. It also tracks how recent FDA clearances and product introductions may alter regional supply, channel availability, and benchmark specifications for downstream procurement teams.
Segmentation Signals That Matter for 2026 Planning
While aggregate market size and growth rates set the overall context, the operational value of this research lies in its ability to help teams interpret where demand is forming and how it will translate into procurement, sales, and investment decisions. Light source selection, for example, is not merely a technical preference; it affects regulatory classification, treatment protocols, consumables and service economics, and the credibility of clinical claims. Application focus shapes channel strategy, because skin rejuvenation, acne treatment, pigmentation treatment, and wound healing each carry distinct practitioner adoption patterns, consumer expectations, and reimbursement or self-pay dynamics. End-user channel mix is equally critical, since medical clinics, beauty salons, and home care settings differ in purchasing cycles, training requirements, service contracts, and price elasticity.
The regional dimension further complicates planning. Demand is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, but distribution is not uniform in either volume or strategic significance. Local regulatory environments, clinical practice norms, aesthetic service infrastructure, and procurement models influence how quickly new products are adopted and how aggressively pricing is contested. Rather than presenting isolated percentage splits, the study frames regional analysis as a set of operational considerations: where channel access is mature, where regulatory clearance creates an entry barrier or an opportunity, and where procurement bundling and service expectations alter the economics of market participation.
How to Use This Research for 2026 Decision-Making
The report is intended to support a range of strategic actions. For product and R&D leaders, it provides context on where light source and application segmentation create the strongest case for investment, iteration, or portfolio pruning. For commercial and market-access teams, it clarifies how regulatory classification, 510(k) activity, CPT coding developments, and reimbursement ranges influence the viability of clinical versus consumer positioning. For corporate development and investor relations, it frames competitive concentration, company-level capabilities, and recent clearance activity in a way that supports benchmarking, partnership identification, and risk assessment. For regional and channel strategists, it connects segmentation and dynamics to practical questions about where to prioritize go-to-market resources, how to structure service and installation offerings, and which procurement environments demand bundled value propositions.
Crucially, the study is designed to be read as a decision framework, not a static snapshot. The 2026-2032 forecast horizon is long enough to matter for capital planning and product roadmaps, yet near enough that the assumptions behind it can be tested against live regulatory filings, procurement behavior, and competitor moves. By linking historical performance, forward projections, segmentation logic, and regulatory context, the report helps organizations avoid plans that are either too optimistic about adoption speed or too conservative about structural growth.
Worldwide Aesthetic Phototherapy Lamps Market
Why This Study Matters Now
The aesthetic phototherapy lamps market is expanding, but expansion alone does not create advantage. Advantage comes from understanding where growth is concentrated, which regulatory and reimbursement shifts alter commercial logic, and how competitive intensity differs across light sources, applications, channels, and regions. With an 8.75 percent CAGR driving the market from USD 645.5 million in 2025 toward USD 1.16 billion in 2032, the cost of misreading segmentation or timing is rising. The Worldwide Aesthetic Phototherapy Lamps Market research gives decision-makers the structured intelligence needed to calibrate strategy for 2026 and beyond.
To access the complete segmentation detail, competitive benchmarks, regional analysis, and forward forecast tables that support these conclusions, we invite you to explore the full report. The underlying data, scenario logic, and company-level profiles are available in the complete publication, where they can be used directly for internal planning, investment review, and market-entry assessment.
Aesthetic Devices Market
For detailed analysis of this topic, please visit the official page: Worldwide Aesthetic Phototherapy Lamps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LCD Scrubber Market to Hit $509.4M by 2032, Growing 5.85% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Heat Wet Scrubber for LCD Market
As the display manufacturing industry enters a critical phase of technological iteration and environmental compliance, the heat wet scrubber segment has emerged as a foundational infrastructure component. PW Consulting provides this strategic overview to introduce our latest comprehensive study on the Worldwide Heat Wet Scrubber for LCD Market, designed to equip executives, procurement leaders, and investment strategists with the analytical framework required for high-stakes decisions in 2026 and beyond. The intersection of next-generation production lines, stringent emission mandates, and evolving gas abatement architectures demands a clear, data-grounded understanding of market trajectories. This report delivers that clarity.
Macro Trajectory and the 2026 Decision Horizon
The heat wet scrubber market for LCD manufacturing has demonstrated consistent expansion over the past five years, reflecting the sector's structural reliance on reliable hazardous gas treatment. Historical performance from 2020 through 2025 establishes a clear growth baseline, with revenue scaling from 258.4 million USD to 342.15 million USD. This upward momentum carries into the forecast window, where the market is projected to advance at a compound annual growth rate of 5.85 percent, ultimately reaching 509.4 million USD by 2032. The trajectory underscores a shift from incremental capacity additions to strategically integrated abatement ecosystems.
For decision-makers in 2026, these figures are not merely historical artifacts or forward estimates; they represent a structural inflection point. The sustained growth pattern signals that heat wet scrubber deployment is transitioning from a peripheral compliance purchase to a core facility planning parameter. Manufacturers are increasingly evaluating scrubber architectures alongside line configurations, chemical process adjustments, and regional regulatory calendars. The forecast period extending to 2032 reveals continued expansion, with notable acceleration phases that will reshape supply chain negotiations, capacity planning, and technology roadmaps. Understanding where these inflection points occur, which product families capture incremental share, and how regional deployment patterns evolve will separate reactive procurement from proactive strategic positioning.
Technological Architecture and Segment Dynamics
Heat wet scrubbers within the LCD manufacturing environment are engineered to neutralize hazardous process gases, including perfluorocarbons and other reactive exhaust streams, through high-temperature interaction with liquid-phase treatment media. The operational demands of modern LCD fabs require systems that balance destruction efficiency, chemical resistance, and seamless integration into both point-of-use and central abatement layouts. Materials science plays a decisive role; corrosion-resistant alloys and specialized polymers are routinely specified to withstand acidic and reactive exhaust conditions, ensuring long-term reliability under continuous operational cycles.
The product landscape in this market is structured around distinct architectural approaches. Single-stage configurations offer streamlined installation and targeted treatment for specific exhaust profiles, while multi-stage architectures provide extended residence times and enhanced capture efficiency for complex gas mixtures. Integrated systems combine thermal treatment, wet scrubbing, and auxiliary control modules into unified platforms, increasingly favored by facilities seeking to minimize footprint, standardize maintenance protocols, and reduce inter-system coordination complexity. Parallel to these product categories, application segmentation reflects the generational evolution of LCD production lines. Legacy and mid-generation fabs continue to drive steady demand for abatement capacity aligned with established process chemistries, while advanced-generation lines, including Gen 8.5 and Gen 10.5 architectures, are reshaping throughput requirements and exhaust composition, prompting equipment manufacturers to refine thermal-wet treatment parameters and housing configurations.
Raw material selection, unit sizing, and integration topology are no longer purely engineering decisions; they directly influence total cost of ownership, downtime exposure, and future expansion flexibility. Decision-makers must evaluate how these architectural choices interact with their specific process roadmap and compliance timeline.
Competitive Landscape and Strategic Positioning
The market exhibits a moderately concentrated competitive structure, with the top three players collectively representing 62.45 percent of revenue and the top five accounts capturing 78.3 percent. This concentration reflects the capital intensity of abatement engineering, the need for application-specific process validation, and the importance of long-term service and compliance support in LCD manufacturing environments. Established Korean and Japanese equipment providers dominate much of the installed base, leveraging deep experience in semiconductor and display fab environments, while specialized innovators continue to challenge incumbents through modular designs, plasma-hybrid configurations, and differentiated thermal-wet treatment platforms.
Several core enterprises define the current competitive terrain. Triple Cores Technology delivers plasma, thermal-wet, and heat wet scrubber systems tailored for hazardous gas treatment in semiconductor and LCD manufacturing, including PFC decomposition capabilities. YOUNGJIN IND specializes in gas abatement systems, offering heat wet scrubber models such as the YHS-06W and YHS-04W, complemented by high-temperature plasma and eco-friendly hazardous gas treatment options. Global Standard Technology manufactures a range of scrubbers, including thermal wet types, focused on harmful gas purification for semiconductor and LCD production. KC Innovation provides scrubber solutions for gas processing within semiconductor and display manufacturing workflows. Unisem supplies heat wet scrubbers and gas abatement equipment directed at LCD and semiconductor applications, while SemiAn Technology offers heat wet scrubber solutions integrated into broader gas treatment systems for LCD manufacturing. Japan Pionics contributes heat wet scrubber equipment aligned with LCD and semiconductor gas abatement requirements. Integrated Plasma Inc combines plasma and heat wet scrubber technologies for LCD process exhaust gas treatment, and Ebara Technologies provides wet scrubber abatement systems, including models engineered for display and LCD sub-fab environments, addressing water-soluble process gases across semiconductor and adjacent industries.
The competitive environment is further shaped by ongoing portfolio evolution. In March 2026, DAS Environmental Experts introduced a flexible SALIX wet scrubber portfolio optimized for semiconductor manufacturing applications, with relevance to high-purity exhaust treatment in display processes. Developments of this nature illustrate the continuous refinement of abatement platforms and the increasing emphasis on adaptability across process chemistries and fab layouts. For market participants, the strategic question is not simply which vendor offers the lowest upfront price, but which provider can sustain performance across generation transitions, minimize service disruption, and adapt to evolving emission standards without requiring costly architectural retrofits. The concentration metrics suggest that scale advantages, installed-base service networks, and application-specific validation remain decisive competitive moats.
Regulatory, Operational, and Supply Chain Forces
Regulatory pressure continues to be a primary catalyst for abatement investment. Semiconductor and LCD manufacturing facilities must deploy high-efficiency abatement systems to comply with strict emission standards for PFCs and other hazardous process gases. Compliance is no longer a static target; it is a moving threshold shaped by regional environmental policy, community exposure expectations, and evolving best-practice frameworks for process exhaust management. Facilities that treat abatement as a compliance checkbox risk encountering costly retrofits or operational interruptions when standards tighten. Conversely, organizations that integrate abatement strategy into long-range fab planning can align equipment selection with anticipated regulatory calendars and process chemistry shifts.
Operational durability and material resilience are equally critical. Heat wet scrubbers for LCD typically incorporate corrosion-resistant materials such as specialized alloys or polymers to handle acidic and reactive exhaust streams. The durability of these components directly affects maintenance frequency, replacement cycles, and overall system availability. In high-uptime environments, the choice of construction materials and the robustness of thermal management design can determine whether a scrubber functions as a stable backbone of the emission control infrastructure or becomes a recurring source of downtime and unplanned service spend.
On the demand side, increasing LCD and display panel production drives demand for reliable point-of-use and central abatement systems, including heat wet scrubbers, to manage process emissions. This production-driven demand is not uniform across regions or line generations, and procurement strategies must account for varying deployment intensities, local sourcing considerations, and integration requirements with existing sub-fab and exhaust infrastructure. Supply chain resilience also matters as manufacturers evaluate lead times, component availability, and the ability of suppliers to support rapid installation schedules aligned with line build-outs or upgrade cycles.
What the Analysis Delivers: Operational Intelligence for 2026
This research report is built to convert market complexity into executable intelligence. It provides a detailed mapping of historical performance and forecast trajectories, enabling executives to benchmark current procurement assumptions against macro growth patterns and identify periods of likely demand acceleration. The analysis examines segmentation architecture across product types and application generations, allowing strategy teams to evaluate which configurations are gaining traction, where capacity is expanding, and how line generational shifts influence equipment preferences. Regional deployment patterns are assessed to clarify where concentration is highest, where growth is emerging, and how geographic factors shape sourcing, installation, and service logistics.
Beyond market sizing, the report delivers a competitive benchmarking framework that evaluates the positioning of leading equipment providers, including their technology portfolios, application focus, and strategic movement patterns. It integrates the impact of recent product portfolio expansions and regulatory developments into an actionable context, helping procurement and engineering teams anticipate vendor evolution and align vendor selection with long-range compliance and capacity plans. The study also incorporates material and design considerations relevant to heat wet scrubber performance in LCD environments, linking corrosion-resistant construction, thermal treatment efficiency, and system integration choices to total cost of ownership and operational risk.
For 2026 decision-making, the report functions as a strategic filter. It helps leadership teams prioritize capital allocation, evaluate make-versus-buy considerations for abatement infrastructure, prepare for generation transitions in LCD production, and develop vendor engagement strategies that account for market concentration and ongoing product innovation. The objective is not to provide a static snapshot, but to equip decision-makers with the structural understanding required to anticipate change rather than merely react to it.
Worldwide Spray Scrubbers Market
Conclusion: Positioning for the Next Phase of Market Development
The worldwide heat wet scrubber market for LCD manufacturing is entering a phase defined by technological maturity, regulatory reinforcement, and evolving production architectures. Historical growth trajectories, forward forecast patterns, and the concentrated nature of the competitive field all point to a market where strategic clarity yields durable advantage. Organizations that approach abatement planning with a full understanding of product architecture, application generation shifts, regional deployment dynamics, and vendor positioning will be better prepared to manage cost, compliance, and operational continuity through 2032 and beyond.
This research study provides the depth, structure, and forward-looking analysis required to support those decisions. We invite industry leaders, engineering directors, and strategy teams to engage with the full report, where detailed segmentation insights, competition mapping, and forecast methodology are presented in complete form. The 2026 planning window demands more than surface-level market awareness; it requires the kind of structured intelligence that turns evolving market signals into confident strategic action.
Worldwide Heat Wet Scrubber for LCD Market
For detailed analysis of this topic, please visit the official page: Worldwide Heat Wet Scrubber for LCD Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com