

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Pharmaceutical L-Carnitine Market Hits $245.5M in 2025, 5.45% CAGR Forecast to 2032

Navigating the Global Pharmaceutical Grade L-Carnitine Market: A 2026 Strategic Overview
The global pharmaceutical landscape is witnessing a subtle yet significant shift in the nutritional pharmacotherapy sector, with Pharmaceutical Grade L-Carnitine emerging as a critical compound for clinical nutrition, metabolic support, and therapeutic interventions. As we move into 2026, understanding the trajectory of this market is not merely an academic exercise but a strategic imperative for stakeholders ranging from API manufacturers to pharmaceutical distributors and healthcare investors. PW Consulting latest comprehensive market research provides a definitive lens through which to view these dynamics, offering a granular analysis of the value chain, competitive forces, and regulatory hurdles that define this sector.
This market, driven by an aging global population and increasing awareness of metabolic health, has demonstrated resilience and structured growth over the past half-decade. Our analysis indicates that the market reached a valuation of approximately 245.5 million USD in 2025, reflecting a steady upward trend from 187.65 million USD in 2020. Looking ahead, the forecast period spanning 2026 to 2032 suggests a continued expansion, with the market projected to reach 355.95 million USD by the end of the forecast window. This trajectory corresponds to a Compound Annual Growth Rate (CAGR) of 5.45 percent, signaling a stable, mature growth environment rather than a volatile speculative bubble. For decision-makers, this consistency implies predictable revenue streams but also necessitates precise positioning to capture share in a consolidating landscape.
Structural Dynamics and Value Chain Complexity
The pharmaceutical grade L-Carnitine ecosystem is defined by rigorous quality standards that separate it distinctly from bulk industrial or feed-grade variants. Industry data suggests that pharmaceutical-grade material commands a significant price premium, often ranging from three to five times higher per kilogram than feed-grade counterparts. This pricing power is underpinned by the stringent purity requirements mandated for human consumption, particularly in injectable forms where safety profiles are paramount. Manufacturers must adhere to USP 43 and EP 10.0 standards, which include strict GMP manufacturing protocols and endotoxin limits below 0.05 EU/mg for injectable grades. These regulatory barriers create a high entry threshold, naturally favoring established players with robust quality assurance infrastructures.
Production capabilities remain a central bottleneck. Both fermentation and chemical synthesis processes for high-purity L-Carnitine face capacity constraints, which has driven a trend toward vertical integration among producers. Companies are increasingly seeking control over raw material sourcing and bioprocess capabilities to ensure consistent quality and supply security. This vertical integration is not merely operational but strategic, as it mitigates the risk of supply chain disruptions that could compromise clinical supply agreements. The market concentration reflects this maturity, with the top three competitors holding a significant portion of the revenue share, indicating that scale and compliance are key determinants of market leadership.
Segmentation and Therapeutic Applications
While the aggregate numbers tell a story of growth, the true strategic value lies in understanding where that value is generated. The market is segmented by type, region, and application, each presenting unique opportunities and challenges. In terms of chemical forms, the landscape includes L-Carnitine Base, L-Carnitine Tartrate, Acetyl-L-Carnitine, and other variants. Each form serves distinct therapeutic niches; for instance, Acetyl-L-Carnitine is often associated with neurological support, while tartrate forms are prevalent in metabolic and nutritional formulations. The distribution of revenue across these types highlights the dominance of specific chemical structures in current clinical practice, though the demand for specialized forms continues to evolve with emerging research.
Worldwide Pharmaceutical Grade Taurine Market
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The Asia Pacific region represents a substantial volume contributor, driven by domestic manufacturing capabilities and growing healthcare infrastructure. North America and Europe maintain strong positions, largely influenced by established reimbursement pathways and high adherence to clinical nutrition guidelines. However, the dynamics vary significantly by jurisdiction. In China, for example, specific pharmaceutical products have historically held considerable market share in hospital settings, reflecting established reimbursement pathways in clinical nutrition. This regional nuance is critical for companies looking to expand their footprint, as regulatory environments and procurement mechanisms differ vastly between tenders in Europe and hospital procurement in Asia.
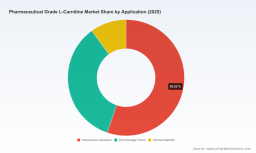
Application-wise, the market is driven primarily by Intravenous Injections and Oral Dosage Forms, with Clinical Nutrition also representing a significant pillar. The dominance of intravenous formulations underscores the critical role of L-Carnitine in acute care and hospital-based metabolic support. Oral dosage forms, meanwhile, cater to chronic management and outpatient supplementation. The balance between these application routes influences manufacturing requirements, as injectable grades require stricter sterility and purity controls compared to oral intermediates. Understanding the revenue split between these applications helps manufacturers align their production capacities with the highest value segments.
Competitive Landscape: Giants and Specialists
The competitive environment is a mix of global life sciences giants, specialized European manufacturers, and large-scale Chinese producers. Leading the pack is the Lonza Group, based in Basel, Switzerland. With over 30 years of expertise, Lonza offers high-purity Carnipure L-Carnitine in crystalline and tartrate forms, manufactured via bioprocess and chemical synthesis. Their strength lies in quality-compliant production for clinical nutrition and supplements, positioning them as a preferred partner for high-value pharmaceutical applications. Similarly, Merck KGaA, including Sigma-Aldrich, supplies high-purity L-Carnitine for pharmaceutical-grade and laboratory applications, supporting clinical and research needs with analytical standards and GMP-compliant materials.
In Europe, Alfasigma (Sigma-tau) maintains a strong hospital market presence with their CARNITENE product. Their strategy involves distribution and promotional activities in key regions, including China, where they have navigated complex market redeployment strategies to maintain brand visibility. Biosint S.p.A. in Italy also contributes to the European supply chain, focusing on USP/EP compliance for API and clinical nutrition formulations. These European players leverage regulatory expertise and brand heritage to command premium positioning.
On the other side of the spectrum, Chinese manufacturers play a pivotal role in global supply. Northeast Pharmaceutical Group Co., Ltd. (NEPG) is a major producer of L-carnitine series including pharmaceutical-grade API, with integrated chemical raw materials and GMP-compliant manufacturing for domestic and export markets. Liaoning Koncepnutra Co., Ltd. operates as one of the largest professional production bases in China, focusing on nutrition ingredients and pharmaceutical chemical intermediates with GMP standards. Hubei Truevita Pharmaceutical Co., Ltd. has scaled significantly, with annual capacity reaching 1500 tons in the first phase, supplying chemical APIs, food additives, and feed additives under high-standard operations. Ningxia Kunzheng Biotechnology Co., Ltd. further expands capacity with a 3000-ton annual production project for L-carnitine and its salts, operational since late 2021.
Other significant players include Chengda Pharmaceuticals Co., Ltd., offering L-carnitine with USDMF and WC documentation for pharmaceutical-grade API supply, and Apino Pharma Co., Ltd., a GMP-certified supplier with CoA, MSDS, and USDMF for API markets. Changzhou Comwin Fine Chemicals Co., Ltd. and Sandoo Pharmaceuticals and Chemicals Co., Ltd. also provide GMP, ISO9001, and FDA-approved sources for export. AgEx Pharma, based in India/USA, operates as a cGMP bulk manufacturer with substantial monthly capacity for pharma and food-grade applications. Rochem International, Inc. serves as a distributor and supplier in the United States with extensive GMP and regulatory documentation. Kaiyuan Hengtai Nutrition Co., Ltd. rounds out the specialized manufacturer group focusing on nutrition and pharmaceutical applications. This diverse competitive set means that buyers have options ranging from high-cost, high-touch European suppliers to high-volume, cost-competitive Asian manufacturers, depending on their specific quality and price requirements.
Recent Market Developments and Strategic Shifts
The period leading into 2026 has been marked by specific corporate actions and product innovations that reshape the competitive terrain. In January 2025, Otsuka Pharmaceutical Factory launched the ENSOLID semi-solid enteric nutrition formula incorporating pharmaceutical-grade L-Carnitine. This launch targets fatty acid metabolism support in clinical and geriatric health settings, signaling a move toward integrated nutritional solutions rather than standalone ingredients. Such product launches expand the addressable market by embedding L-Carnitine into broader care regimens.
Conversely, portfolio rationalization is also occurring. In December 2024, BASF SE signed a binding agreement to divest its Food and Health Performance Ingredients business, which includes production facilities tied to the L-Carnitine production chain. This divestiture suggests a strategic shift among large conglomerates to focus on core competencies, potentially opening opportunities for specialized buyers or competitors to acquire assets and capacity. Meanwhile, Balchem Corporation reported strong growth in its Human Nutrition & Health segment in April 2025, including L-Carnitine and related functional ingredients, indicating sustained demand in the nutrition sector.
Regulatory and market access dynamics continue to evolve. Levocarnitine remains the generic ingredient in multiple approved injectable and oral formulations. Recent ANDA approvals and expirations, such as the Deva Holding As product expiring in June 2025, influence generic competition levels. In China, historical data showed established products holding significant market share in the hospital carnitine market, valued at billions of RMB, reflecting the importance of reimbursement pathways. These dynamics require constant monitoring, as changes in patent status or reimbursement policies can rapidly alter market shares.
Strategic Imperatives for 2026 and Beyond
For stakeholders navigating this market in 2026, several strategic imperatives emerge from the data. First, supply chain resilience is paramount. Given the capacity bottlenecks in fermentation and synthesis, securing reliable sources of API is critical. Vertical integration or long-term contracts with key producers like Lonza or major Chinese GMP-certified facilities can mitigate supply risk. Second, regulatory compliance must be viewed as a competitive advantage. With endotoxin limits and USP/EP standards acting as gatekeepers, manufacturers who can demonstrably exceed these requirements will secure premium contracts in sensitive applications like intravenous injections.
Third, geographic diversification is essential. While Asia Pacific offers volume and growth, North America and Europe offer stability and higher margins due to established reimbursement structures. Companies must tailor their go-to-market strategies to these regions, understanding that distribution channels and procurement rules differ. Fourth, innovation in formulation offers growth potential. The launch of semi-solid enteric formulas by players like Otsuka suggests that combining L-Carnitine with other nutritional elements can unlock new value pools in clinical nutrition.
Finally, the market concentration indicates that M&A activity or strategic partnerships could reshape the landscape. With a significant portion of revenue held by the top competitors, smaller players may need to specialize or form alliances to remain relevant. The divestiture by BASF and the strong growth reported by Balchem highlight that capital is flowing toward specific segments of the nutrition value chain, and investors should align their portfolios accordingly.
PW Consulting comprehensive research report delves deeper into these trends, offering detailed segmentation analysis, granular country-level data, and proprietary forecasts that go beyond the macro overview presented here. While the high-level growth rates and total market values provide a necessary context, the true decision-making intelligence lies in the specific regional splits, application breakdowns, and competitive benchmarking contained within the full study. Understanding the exact allocation of revenue across types, the specific growth drivers in each region, and the detailed operational profiles of every key competitor requires access to the complete dataset.
In an environment where premium pricing relies on compliance, where capacity constraints dictate supply security, and where regional reimbursement pathways determine market access, having granular intelligence is not optional—it is essential. The projected growth to 355.95 million USD by 2032 represents a significant opportunity, but capturing it requires navigating a complex web of regulatory, operational, and competitive factors. This introduction serves as a primer to the landscape, but the full strategic roadmap requires the depth of analysis that only our complete market research can provide. Stakeholders are encouraged to leverage this intelligence to refine their sourcing strategies, identify partnership opportunities, and forecast their revenue potential with precision in the evolving global pharmaceutical grade L-Carnitine market.
Worldwide Pharmaceutical Grade L-Carnitine Market
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade L-Carnitine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com