

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Biogas Upgrading Market Outlook — 6.57% CAGR to USD 6.09B by 2032
By pmarketresearch, 2026-07-13
Biogas Upgrading Market: Strategic Outlook for 2026 Decision-Makers
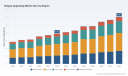
As governments, utilities, and industrial energy buyers accelerate decarbonization plans in 2026, biogas upgrading has moved from niche sustainability projects into strategic energy infrastructure. PW Consulting’s new Biogas Upgrading Market study—anchored to a 2025 base year and projecting through 2032—translates market momentum into decision-grade intelligence. The global market is on a clear growth trajectory with a compound annual growth rate (CAGR) of 6.57% over the forecast window; our topline modeling shows growth from a 2025 market size of USD 3.91 Billion to USD 6.09 Billion by 2032. This report is designed to help executives convert regulatory signals, technology differentials, and project economics into robust investment choices in 2026.
Biogas Upgrading Market
Why this study matters for 2026 strategic decisions
-
Timing: 2026 is a hinge year for policy-driven demand. Recent regulatory moves—most notably the REPowerEU measures coming into force and the revised Renewable Energy Directive—are creating binding and non-binding targets that materially affect offtake and subsidy frameworks across major markets.
Biogas Upgrading Market -
Capital allocation: With financiers demanding bankable cash flows, our assessment links technology pathways (e.g., membrane systems, PSA, amine scrubbing, water scrubbing, cryogenic options) to capex/opex profiles and revenue risk under multiple policy scenarios.
Biogas Upgrading Market -
Supply chain & vendor selection: The market remains moderately concentrated (CR3 ~32.1%, CR5 ~45.7%), meaning supplier selection and negotiating strategy are decisive for cost and warranty exposure.
-
Market sizing & prioritization: Our model translates macro drivers—feedstock availability, gas grid access, transport fuel mandates, and LNG opportunities—into opportunity maps you can use to prioritize projects and geographies without depending on single-case optimism.
Report composition: what you will find (and what we deliberately withhold)
-
Comprehensive market model: Historical data (2020–2025) and a bottom-up forecast (2026–2032) that reconciles policy pathways, feedstock flows, and technology adoption curves. Topline figures are presented to guide portfolio sizing; granular regional and sub-segment revenue matrices are reserved for the full report to preserve client value and to enable tailored licensing.
-
Project economics playbook: Standardized pro forma models for typical plant configurations, sensitivity runs for gas prices, tariff regimes, and incentive structures, plus integrated LCOE-style comparators for biomethane vs. alternative decarbonization options.
-
Technology decision framework: Comparative matrices that map operating envelopes, impurity tolerance, water footprint, CH4 slip, scalability, and retrofit friendliness across the full spectrum of upgrading technologies.
-
Commercial & contracting guidance: Templates for EPC risk allocation, O&M KPIs, performance guarantees, and offtake contract clauses designed for financiers and corporate offtakers.
-
Vendor shortlists and diagnostic toolkits: Qualitative vendor profiles and a diagnostic toolkit for vendor due diligence, procurement scorecards, and post-installation performance monitoring. Note: while we summarize vendor strengths in this introduction, detailed benchmarking scores and price curves are available in the complete report.
-
Scenario-based policy analysis: Three pragmatic scenarios—Policy-Accelerated, Market-Driven, and Stalled Transition—each with implied demand curves and risk appetites for 2026 decision-makers.
Competitive landscape — who to watch and why
The biogas upgrading vendor pool mixes specialized engineering houses with industrial gas majors and modular-systems providers. In our coverage, the following players are notable for capability or market momentum:
-
EnviTec Biogas AG (Germany) — Known for a hollow-fibre membrane system designed for high-purity biomethane and grid injection, with recent commissioning activity in Central Europe that underscores their operational scale-up path.
-
Wärtsilä Corporation (Finland) — Offers amine-based PuregasCA technology with projects targeting both grid injection and bio-LNG applications; recent large-capacity contracts illustrate demand for high-throughput upgrading solutions.
-
Greenlane Renewables (Canada) — Focuses on membrane-based upgrading and H2S removal solutions, positioning for RNG markets and transport-fuel use cases.
-
Air Products & Chemicals (USA) and Air Liquide (France) — Industrial gas majors with membrane and integrated CO2 capture/upgrading systems; they bring balance-sheet strength and global project delivery capability, which is material when lenders assess offtake and construction risk.
-
Xebec Adsorption and DMT International — Providers of PSA and water-scrubbing solutions, respectively, often competing on lifecycle cost and modular delivery timelines.
-
Regional integrators and anaerobic digestion specialists — PlanET Biogas, Scandinavian Biogas, Hitachi Zosen Inova, IES Biogas, WELTEC Biopower, among others, are active in integrated project delivery, where anaerobic digestion, upgrading, and CO2 utilization are packaged for municipal and industrial clients.
Recent commercial milestones validate our market modeling: Wärtsilä’s late‑2025 contract for a large amine-scrubber plant in Denmark and EnviTec’s project rollouts in Central Europe signal continued utility and grid integration activity. Separately, project reporting from large-scale facilities in California demonstrates operational readiness for bankable biomethane assets in North American markets.
Policy & market dynamics shaping 2026 choices
-
Binding and non-binding targets: The REPowerEU roadmap (and the operational regulation from early 2026) plus the revised Renewable Energy Directive are changing demand composition by widening recognized biomethane uses and setting tougher renewable-share targets to 2030. For investors, this shifts revenue certainty curves and expands potential offtake customers beyond power to heating, transport, and industrial feedstocks.
-
National mandates and blending rules: Several countries implemented biomethane blending and offtake mandates in 2026. These create near-term demand pull, but also require asset owners to adapt to varying quality standards and certification regimes.
-
Incentives and targets: Supra-national plans set production targets that shape pipeline expectations. While targets themselves are not guarantees, they materially de-risk long-horizon forecasts used by corporate strategy teams.
Risk map and scenario implications for 2026 investments
-
Policy risk: Fast-moving regulatory environments increase upside in the Policy-Accelerated scenario but also raise compliance complexity. Our scenario models translate these dynamics into project-level cash flows for use in investment committees.
-
Technology & performance risk: Differences in methane recovery, CO2 co‑product streams, and O&M intensity create meaningful variation in life-cycle returns. The report includes a decision tree to match plant scale, feedstock variability, and local utility requirements to appropriate upgrading technology choices.
-
Offtake & market access: Grid injection vs. localized bio-LNG or transport fuelling has distinct pricing and logistics implications. We provide a contractual playbook to negotiate merchant exposure, indexed tariffs, and capacity reservation agreements.
-
Financing & counterpart risk: With CR3 and CR5 concentration metrics indicating a moderate supplier market, counterparty strength and indemnities are salient for project lenders; our lender-ready risk matrices outline the clauses that move funding decisions.
Practical recommendations for executives in 2026
-
Start with zone-level feedstock and grid-access audits. Before committing to technology, validate sustained feedstock volumes and quality across seasonal cycles; our rapid-audit checklist reduces stranded-capacity risk.
-
Use modular procurement strategies. For many developers, splitting plant delivery into standardized modular packages—upgrading skid, gas polishing, and CO2 handling—lowers time-to-operation and improves negotiation leverage.
-
Optimize offtake portfolios. Blend long-term offtakes with indexed merchant sales or bio-LNG contracts to balance bankability and upside. The report provides model contract structures aligned to lender expectations.
-
Embed performance guarantees and methane-slip metrics into SPAs and O&M contracts. Lenders and corporate buyers increasingly treat methane leakage as a primary covenant driver.
-
Factor in CO2 valorization. Where feasible, integrate CO2 capture and liquefaction options to create secondary revenue streams; our economic sensitivity tools show break-even thresholds under conservatively priced CO2 markets.
Methodology and sources
Our analysis synthesizes public filings, company press releases, project reports, regulatory texts, primary interviews with technology providers, and a bottom-up project database covering 2020–2025. Key recent inputs include public announcements and regulatory events that have shaped 2025–2026 market expectations; examples cited in the report include large-capacity contracts and project commissioning activity across Europe and North America.
Next steps — how to use this work
PW Consulting’s Biogas Upgrading Market study is structured as a strategic tool: use the executive digest for board-level prioritization; deploy the financial models in diligence and the vendor scorecards in procurement. To preserve the commercial value of our deep segmentation and project-level datasets, we provide paywalled access to the full database and downloadable modeling files. For 2026 capital plans, we recommend combining our scenario outputs with in-country legal opinions and utility interconnection studies before final investment decisions.
To obtain the full report, datasets, and customizable modeling spreadsheets that unlock the segment-level and regional insights referenced here, visit our report page or contact PW Consulting’s industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Biogas Upgrading Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Laser Marking Market Poised for 8.45% CAGR Through 2032
By pmarketresearch, 2026-07-13
Industrial Laser Marking Machine Market 2026: Strategic Preview for Executive Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise yet strategic preview of our full Industrial Laser Marking Machine Market study — the working guide senior executives will use to shape procurement, product, and M&A decisions in 2026. This briefing synthesizes the market’s trajectory, competitive dynamics, regulatory inflections, and the operational levers that separate opportunistic buyers from long‑term winners. It intentionally showcases the analytical architecture and executive implications of the report while preserving the granular segmentation tables and raw datasets for subscribers.
Industrial Laser Marking Machine Market
Why this report matters for 2026 planning
-
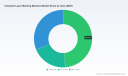
Scale and momentum: After steady expansion from an estimated 1,900 Million USD in 2020 to a base‑year market size of 2,650 Million USD in 2025, the market enters the 2026–2032 forecast window with clear growth momentum. Our forecast models embed an 8.45% CAGR across the period, reflecting accelerated adoption in serialisation, traceability and automated inline production marking.
Industrial Laser Marking Machine Market -
Decision timing: For capital planners and product‑line owners, 2026 is a pivotal year to convert strategic intent into procurement and integration. The market’s growth profile means that first movers in automated, high‑throughput marking and those who secure integrator partnerships will claim outsized operational and margin advantages.
Industrial Laser Marking Machine Market -
Actionable risk management: The report translates market growth into actionable risk matrices — highlighting vendor concentration, technology substitution risk (e.g., fiber vs. ultrashort pulse and UV solutions), and regulatory compliance timelines that will affect TCO and time‑to‑market.
What the full study delivers (practical, executable content)
-
Proprietary market model: A transparent, audited forecast engine built on historical shipments (2020–2025), validated OEM sell‑through, and bottom‑up channel checks — enabling users to re‑run scenarios with different adoption curves, price movements, and macro assumptions.
-
Vendor scorecards and integration playbooks: Comparative assessments of more than 25 OEMs and integrators across technology breadth, service footprint, automation readiness, and enterprise IT compatibility — plus concrete templates for RFPs, SLA clauses, and acceptance tests for 2026 deployments.
-
Procurement and TCO toolkit: CapEx and OpEx modeling templates, expected replacement cycles, spare parts consumption profiles, and sensitivity analyses showing how markup, throughput, and uptime assumptions drive payback periods.
-
Use‑case roadmaps: Application‑level decision trees (from high‑volume automotive line marking to low‑volume, high‑precision electronics and semiconductor tasks) with recommended laser class, head configurations, and integration architectures to minimize rework and maximize traceability.
-
M&A and partnership playbook: A structured framework for evaluating targets (technology IP, customer roster, aftersales capability), plus deal‑sizing heuristics and integration checklists tailored to strategic or financial buyers.
-
Compliance and certification tracker: A living matrix of standards and regulatory triggers that affect procurement, including industrial safety, defence traceability, and region‑specific process specifications — mapped to upgrade timelines and supplier capabilities.
Market trajectory and what it means for capital allocation
The market’s historical rise from 2020 to 2025 reflects a combination of backlog recovery, incremental automation in manufacturing, and rising demand for permanent, machine‑readable marking across regulated sectors. With a compounded forecast growth rate of 8.45% over 2026–2032, buyers should expect both expanding opportunity and increasing competitive pressure on pricing and service differentiation.
From a capital allocation standpoint, the implication is twofold: (1) buyers with production lines scheduled for modernization in 2026–2027 should prioritize vendor relationships and early integration pilots to lock in lead times and service agreements; and (2) strategic investors should evaluate both OEMs with deep R&D in photonics and integrators that can convert marking hardware into recurring service revenue.
Competitive landscape: strategic archetypes and who’s playing where
The market is populated by several strategic archetypes: vertically integrated photonics houses, global OEMs with diversified machine portfolios, regionally dominant manufacturers, and cost‑focused suppliers targeting small and mid‑sized users. Notable names in each category — drawn from our coverage universe — include long‑standing photonics and industrial leaders, specialist marking OEMs, and a wide field of regional manufacturers and system integrators.
-
Vertically integrated photonics and high‑tech OEMs — firms with in‑house laser source development and optics integration — are positioned to capture margin and lead innovation cycles for advanced marking (including ultrashort pulse and high‑power fiber lines).
-
Specialist marking OEMs and integrators focus on turnkey production line solutions and regulatory compliance; these companies often win through faster installation and domain expertise in targeted end markets (e.g., automotive, aerospace, defence, and medical devices).
-
Value players and regional manufacturers provide accessible entry points for cost‑sensitive applications, expanding addressable market breadth while intensifying price competition at the lower end.
The full report contains an expanded competitor matrix profiling each major supplier by headquarters, product specialization, recent strategic moves and integration maturity — and includes pragmatic, supplier‑specific negotiation playbooks for procurement teams.
Recent industry moves and regulatory dynamics shaping 2026 decisions
-
Product refresh cycles and catalog releases continued through 2025–2026, with multiple suppliers updating fiber and high‑power offerings and several introducing new turnkey and heavy‑duty systems. These product events compress vendor switching costs but also raise the bar on technical due diligence for buyers.
-
Regulatory standards — ranging from industrial safety certifications to defence traceability mandates and regional process specifications — are actively shaping buyer requirements. For regulated industries, compliance timelines translate directly into procurement deadlines and preferred supplier lists.
-
Operational trend: manufacturers are increasingly using laser marking to reduce manual labelling, shorten changeover times, and improve digital traceability — aligning directly with wider supply‑chain resilience and Industry 4.0 initiatives.
Practical implications by stakeholder group
-
COOs: Prioritize pilot programs that validate uptime and service KPIs under production conditions. The payback period is sensitive to throughput and spare parts availability; operational readiness must be verified before enterprise roll‑outs.
-
CPOs and procurement: Use our RFP templates and vendor scorecards to benchmark TCO rather than upfront price. Negotiate multi‑year service contracts tied to uptime SLAs and parts pricing protections.
-
Product leaders: Factor marking capability into DFM discussions early. Design choices that simplify laser marking (material selection, surface finish, accessibility) materially reduce integration cost and cycle time.
-
Investors and M&A teams: Target companies that combine hardware with software and services, or those that can be scaled via channel partnerships. The highest strategic value is in firms that convert once‑off equipment sales into recurring aftermarket revenue.
Where the report shows depth — and where it intentionally does not
We provide transparent macro‑numbers: historical backcasts, a 2025 base, and our forward curve predicated on an 8.45% CAGR through 2032. We also deliver supplier benchmarking, pricing envelopes, and a full set of operational toolkits. However, in line with PW Consulting’s distribution strategy and the “preview” approach, this briefing does not publish the detailed segmentation tables, regional/application share breakdowns, or full raw datasets used to construct the market model. These detailed splits and downloadable models are available to licensed subscribers and clients who request the complete study.
Immediate next steps for 2026 execution
-
Initiate one or two controlled pilot integrations in priority lines during Q1–Q2 2026 to validate throughput and mark quality under representative runtime conditions.
-
Complete vendor shortlists using our scorecards and run parallel negotiations for equipment and service contracts to compare TCO and SLAs on a like‑for‑like basis.
-
Map regulatory requirements for your applications against supplier capabilities now — allow for certification lead times and potential retrofit costs.
-
For investors, commission a targeted diligence on aftermarket revenue streams and service delivery economics prior to execution — these often determine enterprise value in this sector.
How to obtain the full study
The full Industrial Laser Marking Machine Market report contains the complete dataset, granular segmentation, vendor scorecards, and client‑ready procurement tools referenced above. Organizations planning capital investment, strategic partnerships, or M&A activity in 2026 should engage with PW Consulting for the complete report and a tailored briefing that maps the findings to your specific production footprint and regulatory exposure.
PW Consulting’s analysis equips leaders to make faster, lower‑risk decisions in a market growing from a strong 2025 base and expanding at a double‑digit cadence in many application pockets. For executives needing both strategic perspective and executable tactics, the full study is the decision support asset for 2026.
For detailed analysis of this topic, please visit the official page: Industrial Laser Marking Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Feed Processing Equipment Market to expand at 3.8% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Feed Processing Equipment Market — Strategic Preview for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a strategic preview of our Feed Processing Equipment Market study designed specifically to inform executive decisions in 2026. This briefing demonstrates the analytical depth and practical orientation of the full research while intentionally withholding the granular subsegment figures that power our models — an invitation to consult the full report for the data-driving worktables, downloadable scenario models, and vendor scorecards that boards and investment committees will rely on this year.
Feed Processing Equipment Market
Executive snapshot
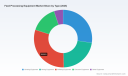
Our market model — built on a 2025 base year with a 2020–2025 historical window and a 2026–2032 forecast horizon — shows a market that has regained growth momentum after pandemic-era volatility. Total industry revenues rose materially from the start of the decade and reached a stable base in 2025; with a projected compound annual growth rate (CAGR) of 3.8% across the forecast period, the market is expected to expand into the low-to-mid thirties (USD Billion scale) by the end of the 2032 horizon. That macro trajectory frames the investment calculus for manufacturers, systems integrators, and feed processors as they prioritize product roadmaps, M&A targets, and plant modernization programs in 2026.
Feed Processing Equipment Market
Why this study matters for 2026 strategy
- Capital allocation: A clear top-line growth path and region-agnostic scenarios help CFOs size near-term CapEx and multi-year replacement cycles for grinding, pelleting, extrusion and complementary systems.
- M&A and partnership prioritization: Deal teams gain a shortlist framework to screen targets against modularity, aftermarket revenue potential, and technology ownership (automation, extrusion, drying).
- Product and R&D roadmaps: Engineering leaders can benchmark design priorities — sanitary and sustainable fabrication, energy efficiency, and digital controls — against peer performance and regulatory risk.
- Regulatory compliance planning: Procurement and quality teams can build compliance timetables and supplier KPIs tied to evolving sanitary design and traceability requirements.
- Service and recurring revenue models: Operations and commercial heads can quantify the upside of retrofits, remote monitoring subscriptions, and spare-parts strategies versus one‑time equipment sales.
What the report contains — practical, board-ready deliverables
Beyond the market narrative, the report is engineered for execution. Highlights include:
Feed Processing Equipment Market
- Proprietary market model (2020–2032) with base-year calibration, demand-side scenarios, and sensitivity toggles for commodity-price shocks and regulatory shifts.
- Capital and operating cost profiles for major equipment classes, enabling CapEx/Opex return simulations for new builds versus retrofit paths.
- Technology and adoption roadmaps — from basic grinding and pelleting to twin-screw extrusion and digital process control — with staging guidance for 1–3–5 year implementation horizons.
- Competitive benchmarking toolkit: vendor capability matrices, aftermarket-service scoring, and a supplier selection RFP template tuned to sanitary design and energy-efficiency criteria.
- Commercial playbooks for sales and aftermarket teams, including contract templates, spare-parts pricing frameworks, and service-level benchmark KPIs.
- Scenario playbooks for regulatory shocks and trade disruptions, with prescriptive mitigation actions and supplier continuity checklists.
Key market dynamics shaping 2026 decisions
Several converging forces will dominate boardroom attention in 2026:
- Regulatory acceleration and complexity. USDA updates to sanitary design and fabrication standards in 2026 raise the bar for equipment certification and may reshape purchase specifications and warranty obligations. Procurement teams must embed these standards into vendor qualification and technical acceptance tests immediately.
- Traceability timelines. The FDA’s extension of the FSMA Food Traceability compliance deadline provides breathing room for software and process upgrades, but it also compresses the schedule for larger integrators who must deliver piloted solutions ahead of the revised cutoff date.
- Shifting risk-safety frameworks. Recent regulatory reversals and withdrawn proposals have created uncertainty around pathogen-specific frameworks; feed-equipment manufacturers should prioritize flexible sanitary design that anticipates tighter future standards without over-engineering to a single regulatory outcome.
- Technology and labor economics. Automation, AI-driven process optimization, and precision nutrition integrations (showcased at industry gatherings in 2026) are becoming decisive differentiators. Early adopters can extract throughput, yield, and energy savings that materially improve plant economics in under three years.
- Market concentration and consolidation pressure. The sector presents a moderate concentration profile: leading manufacturers capture a material share of supply but there remains room for niche specialists and regional champions to win through aftermarket services and turnkey offerings.
Competitive landscape — who matters and why
The competitive map blends long-established equipment conglomerates, specialized European technology houses, and scale-oriented Chinese OEMs. Our report includes deep profiles and strategic diagnostics; a high-level orientation follows.
- Bühler Group (Uzwil, Switzerland): Strong in end-to-end milling and modular line design; its focus on sustainability and lifecycle services positions it for customers prioritizing turnkey, low-carbon solutions.
- CPM Holdings Inc. (Waterloo, Iowa, USA): Known for reliable pellet and thermal processing platforms; competitive on service network density and solutions tailored to livestock and aquaculture feed producers.
- ANDRITZ AG (Graz, Austria): Offers robust pelleting plant solutions and process engineering capabilities that make it a go‑to for large-scale plant projects and retrofit engineering.
- FAMSUN Group (Yangzhou, China): A rapidly internationalizing supplier with turnkey offerings across grinding, pelleting, extrusion and drying — a compelling player for cost-sensitive greenfield projects and regional rollouts.
- Van Aarsen (Wageningen, Netherlands): Strong in feed mill design, upgrades, and automation — frequently selected for premium compound-feed projects in markets emphasizing efficiency and traceability.
- Clextral SAS (France) & Wenger Manufacturing (USA): Niche leaders in extrusion technologies and thermal process control, particularly relevant for premium pet food, aquatic feeds and plant‑based protein processing.
- Triott Group (Netherlands): Integration and automation specialist; brings systems-level project delivery and process control IP, attractive to customers seeking single-source accountability.
- Zhengchang Group (China): High-capacity pellet and granulation solutions, competitive on price and scale; a natural partner for large-volume processors in fast-growing feed markets.
Our competitive scoring combines technical capability, geographic footprint, aftermarket strength, and compliance-readiness — a matrix that helps clients decide when to buy, partner, or build.
Strategic implications and recommended moves for 2026 leaders
- Make compliance the vector for differentiation. Convert new sanitary and traceability requirements into product features and service offerings that justify price premiums and lengthen customer lifetime value.
- Prioritize modular, upgradeable platforms. Given regulatory and technology uncertainty, modular architectures reduce stranded asset risk and accelerate time-to-value for automation add-ons.
- Invest in aftermarket economics. Service contracts, remote-monitoring subscriptions, and consumables can shift margin profiles meaningfully; design commercial models that capture retrofit demand and spare-parts flows.
- Double down on process automation and digital twins. Piloted AI-driven control loops that improve pelleting consistency or energy intensity can deliver quick wins; prioritize scalable pilots that are replicable across plants.
- Be selective in M&A: target capabilities that fill gaps in extrusion, drying, or systems integration — assets that expand recurring revenue and shorten delivery cycles for turnkey projects.
- Design supply continuity plans now. Regulatory-driven requalification and extended compliance timelines will stress lead times; secure dual-sourcing for critical components and pre-qualify retrofit contractors.
How to use this report in your 2026 decision cycle
The report is structured to be operational from day one:
- Board pack-ready excerpts and C-suite one-pagers for governance and investment approval meetings.
- 90-day action plans for procurement, engineering, and product management teams — prioritized by ROI and regulatory urgency.
- Scenario stress-test models to assess outcomes under slower demand, accelerated regulation, or rapid technology adoption.
- Supplier RFP templates and a vendor-scoring rubric tied to sanitary design, lifecycle cost, and aftermarket propensity.
For teams preparing capital budgets for 2026 or evaluating strategic acquisitions, the combination of our modeled market trajectory, regulatory readouts, and vendor-level diagnostics will shorten decision cycles and reduce execution risk.
Next steps
This preview intentionally demonstrates the study’s analytical granularity while withholding the detailed subsegment tables and vendor scorecards that clients use to finalize procurement and M&A plays. Access to the full report provides the calibrated datasets, downloadable models, and tactical templates referenced here — the exact inputs your investment committee, engineering team, and supply chain leadership need to act within 2026 windows.
Contact PW Consulting to arrange a briefing of the full study and a tailored workshop to convert insights into a prioritized 90‑day plan aligned to your balance sheet and operational capacity.
For detailed analysis of this topic, please visit the official page: Feed Processing Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Through Wall Radar Market to hit USD 291.04M by 2032 at 5.1% CAGR
By pmarketresearch, 2026-07-13
Through-Wall Radar Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our Through Wall Radar Market study — a practical intelligence product designed to influence procurement, R&D, M&A and go-to-market choices in 2026. This preview synthesizes the macro trajectory, competitive dynamics, regulatory inflections and the practical deliverables contained in the full report. It demonstrates the type of rigor and decision-ready insight you can expect while intentionally withholding the granular segmentation tables and proprietary breakdowns that are reserved for the full report.
Through Wall Radar Market
Market snapshot: where the opportunity stands
The through-wall radar market has matured from a narrow, mission-focused technology to a multi-use instrument deployed across public safety, search-and-rescue, infrastructure inspection and select commercial security applications. On a macro level, the market reached USD 206.63 Million (base year 2025) after consistent expansion from USD 130.00 Million in 2020. Our forecasting model projects growth to approximately USD 291.04 Million by 2032; the forecast period (2026–2032) implies a compound annual growth rate (CAGR) of 5.1%.
Through Wall Radar Market
Two implications flow directly from this trajectory for 2026 decision-makers: first, the market is large enough and sufficiently liquid to support specialized product lines, services and aftermarket models; second, growth is steady rather than explosive — favoring measured investments that emphasize differentiation, channel development and integration with adjacent sensor systems.
Through Wall Radar Market
Key structural features that matter for strategy
- Moderate concentration: The market exhibits a concentration dynamic in which a small group of established suppliers capture a meaningful share of spend. This creates both barriers and focal points: suppliers can shape standards and procurement expectations, while new entrants must identify narrow value propositions or partner with incumbents to scale.
- Technology-driven differentiation: Advances in ultra-wideband (UWB), signal processing, 3D imaging and motion-tolerant algorithms are the primary levers of competitive advantage. Systems that improve detection in cluttered environments or extend detection standoff will command strategic interest from law enforcement and search-and-rescue organizations.
- Procurement & regulatory sensitivity: Adoption is heavily influenced by public-sector procurement cycles, export-control regimes and evolving privacy and use-of-force policy frameworks. Vendors that can demonstrate compliance, auditable logs and benign-failure modes accelerate acceptance within agencies.
Recent events shaping 2026 strategies
- Product innovation: In February 2025, a leading vendor introduced a long-range Sense-Through-Wall system capable of detecting stationary persons through thicker barriers. Products that extend standoff and detection capability materially change tactical doctrine and procurement requirements.
- Commercialization of life-detection research: Mid-2025 saw government R&D organizations complete upgraded life-detection technologies and partner with industry to bring them to market. The transition from lab to fielded product reduces technical risk for buyers and pressures vendors to accelerate validation against operational scenarios.
- Standards & testing: Independent testing cycles and RFIs continue to shape acceptable performance baselines. Agencies now expect vendors to present lifecycle testing, reproducible detection metrics and integration blueprints for real-world deployments.
Competitive landscape — what to look for
The supplier ecosystem is diverse: it includes niche specialists focused on tactical handhelds, companies that build tripod or vehicle-mounted long-range systems, integrators who bundle radar with situational-awareness suites, and GPR vendors that address overlapping subsurface use-cases. The top-tier vendors have carved leadership by combining product reliability, field-proven performance and government relationships. Market concentration metrics point to a scenario where the three largest players capture a meaningful share of global revenue, while the top five widen the competitive moat — an environment that favors strategic partnerships, channel exclusivity and targeted R&D investments.
- Incumbent innovators: Companies that originated see-through-wall imaging solutions continue to lead on system performance, field validation and global references. Their advantage is rooted in product maturity, ecosystem relationships and mission credibility.
- Agile new entrants: Smaller engineering-driven firms challenge incumbents by focusing on narrow problems: lower-cost handhelds for tactical teams, optimized systems for USAR (urban search and rescue), or modular sensor packages for integrators. Their agility makes them attractive targets for partnership or acquisition.
- Integrators and security conglomerates: Established defense and security suppliers bring system integration, compliance frameworks and procurement experience. Their role is critical for large agency deals where integration, sustainment and lifecycle costs dominate selection criteria.
Representative company positioning (select examples)
- Established imaging pioneers: Firms that commercialized early sense-through-wall products remain benchmark providers; recent long-range launches from established vendors underscore continuing investment in extended standoff capability.
- Regional engineering specialists: Several European and U.S.-based companies drive portable and mission-tailored products that emphasize rapid deployment, robustness and user ergonomics for tactical units.
- Integrators & GPR suppliers: Organizations with ground-penetrating radar pedigree or broad security portfolios are expanding into through-wall technologies by leveraging channel relationships and complementary sensor stacks.
Each vendor category implies a different go-to-market approach for purchasers. For example, agencies focused on rapid fielding may prefer mature vendors with proven logistics; private-sector security integrators may prioritize modular, API-friendly sensors.
What the full PW Consulting report delivers
We designed this report to be directly operational for 2026 planning cycles. Key deliverables include:
- Validated market sizing and trend analysis (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario-based projections and sensitivity tests that reflect technology adoption and procurement timing.
- Actionable segmentation frameworks (by geography, system type, and application) and a clear explanation of how buyer behavior varies across these segments. Note: granular segment tables and region/application splits are available only in the full report.
- Competitor dossiers and benchmarking: vendor profiles, product roadmaps, patent landscaping, and a feature-performance matrix to accelerate vendor shortlisting.
- Procurement playbooks and evaluation templates: scorecards, RFP language, test protocols and acceptance criteria tailored for law enforcement, search-and-rescue and civil-defence buyers.
- Go-to-market playbook for vendors: channel strategies, pricing posture options, partnership models and an acquisition playbook for strategic expansion.
- Technical risk map and compliance checklist: guidance on electromagnetic spectrum constraints, export controls, privacy compliance, and field validation requirements.
- Case studies and deployment lessons: tested field operational procedures, integration pitfalls and sustainment cost drivers.
Strategic recommendations for 2026
- Prioritize validated performance over feature lists. Buyers should require reproducible test evidence under representative conditions; vendors that can demonstrate detection in cluttered, motion-prone environments reduce program risk.
- Adopt staged procurement. Combine pilot buys for operational validation with conditional follow-on orders. This limits capital exposure while enabling rapid capability scaling if pilots meet operational thresholds.
- Invest in integration and training. The highest adoption friction is at the human-sensor interface. Procurement bundles should include operator training, scenario-based validation and maintenance contracts.
- Use partnerships to accelerate capability. Vendors and agencies should pursue partnerships that link radar with other sensors and command systems; integrators often provide the fastest route to enterprise deployment.
- Watch regulatory and testing inflection points. Continued government-led testing and standardization will alter procurement baselines; organizations that track these developments will set specification expectations rather than react to them.
- Consider targeted M&A or minority investments. For incumbents and well-funded integrators, acquiring or partnering with agile engineering firms can accelerate entry into adjacent application niches without large greenfield investments.
- Plan for lifecycle costs. Emphasize sustainment, software updates and spectrum management in TCO calculations rather than acquisition price alone.
Why PW Consulting’s report matters for your 2026 planning
We built this study to answer the practical questions decision-makers face in 2026: which suppliers to short-list for pilots, how to structure contracts to mitigate tech and policy risk, and where to invest for differentiated capability. The report combines primary interviews, procurement data, field-testing protocols and a reproducible financial model so organizations can run alternative scenarios against their operational calendars.
Note on confidentiality and scope: this preview intentionally omits the granular regional and application splits, detailed unit economics, and per-vendor share tables that are included in the full deliverable. Those data assets are critical for bid preparation, target identification in M&A, and capital budgeting — and are therefore controlled as part of the paid report.
Next steps
- For procurement leads: request the RFP-ready annex and field-test templates to accelerate pilot mobilization.
- For product leaders and investors: obtain the vendor benchmarking package and patent landscape to inform product roadmaps and target screens.
- For policy and standards teams: access the regulatory risk matrix and recommended compliance language for inclusion in acquisition specifications.
PW Consulting’s Through Wall Radar Market study is calibrated to convert market intelligence into executable plans for 2026. For access to the full dataset, segmentation tables, and the complete vendor benchmark suite, please visit our report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Through Wall Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Banknote-Printing Machine Market to reach USD 333.3 Million by 2032 at 10.4% CAGR
By pmarketresearch, 2026-07-13
Banknote-Printing Machine Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused introduction to our latest Banknote-Printing Machine Market study. This briefing synthesizes the structural trajectory, competitive dynamics, and tactical implications that should inform procurement, capital planning, and partnership strategies in 2026. It intentionally showcases the analytical depth and decision-grade frameworks contained in the full report while withholding detailed sub-segment tables and proprietary breakouts—designed to invite direct engagement with the full study for operational execution.
Banknote-Printing Machine Market
Why this market matters in 2026
The banknote-printing machine market has moved from a niche, capacity-focused sector into a strategic industrial sub-market at the intersection of sovereign finance, security technology, and advanced manufacturing. On the macro scale, the market expanded from roughly USD 101.8 Million in 2020 to about USD 167.0 Million in our base year (2025), and our projections indicate continued momentum through the forecast window (2026–2032), culminating near USD 333.3 Million by 2032 at a compound annual growth rate of 10.4%. That rate embeds both recurring replacement cycles for central banks and accelerations tied to technology refresh, polymer adoption, and higher-security feature demand.
Banknote-Printing Machine Market
Core demand drivers and structural dynamics
- Sovereign lifecycle and capacity planning: Central banks and large security printers operate on long lead times and multi-year modernization plans. Public modernization programs and multi-year print orders materially shape near-term OEM order books and service revenues.
- Security innovation vs. cost pressure: The paradox of this market is that rising security requirements (new features, hybrid substrates, enhanced inspection systems) increase per-unit complexity and cost, yet budget pressures on currency issuers push for more efficient lines and lower total cost of ownership.
- Technology convergence: Integrations across intaglio, offset, screen, and web-fed hybrid lines—combined with inline inspection, digital controls, and automated convertors—are shifting value from single-process machines to platform-based production lines that support shorter changeover times and higher uptime.
- Regulatory and strategic tailwinds: Recent procurement decisions and strategic modernization initiatives by major sovereign printers have created a pull for new equipment and aftermarket services. Industry conferences and awards continue to codify innovations that accelerate adoption, while procurement cycles at major issuers create discrete opportunities for suppliers.
- Concentration and supplier economics: The market exhibits meaningful concentration—our study measures a top-three concentration near the mid-50 percent range and a top-five near the low-70 percent range—implying an oligopolistic supplier structure with differentiated scale and aftermarket advantages.
Technology and product evolution
From equipment design to plant engineering and inline quality assurance, the evolution in this sector is practical rather than speculative: tighter tolerances, enhanced process automation, and modular architectures that let operators combine security printing processes in flexible lines. These shifts favor manufacturers that can offer integrated solutions—machines plus plant-level engineering and digital services—over isolated press sellers. Expect procurement criteria to increasingly reward lifecycle services (predictive maintenance, retrofitability, spare-part pools) as well as cybersecurity and compliance features embedded in control systems.
Banknote-Printing Machine Market
Competitive landscape: players to watch
The competitive map is shaped by a handful of legacy players and specialized OEMs that combine press engineering with high-security expertise. Our full report contains comparative vendor scorecards; below is a synthesized qualitative view of principal competitors and recent market signals that are critical for 2026 planning.
- Koenig & Bauer Banknote Solutions (Lausanne, Switzerland)
Koenig & Bauer is positioned as a high-security specialist, offering integrated screen and offset systems and end-to-end production lines. Its strengths are engineering depth for banknote-specific requirements and a track record of trade-fair innovation signaling. For buyers, Koenig & Bauer is often a go-to when complete line integration and legacy compatibility matter. - Komori Corporation (Tokyo, Japan)
Komori’s CURRENCY Series and combination multiprocess machines have global reach and an installed base across many markets. Komori’s credentials include supplying mission-critical systems for national currency projects and recent high-profile orders for major sovereign printers. Its scale and technology leadership make it a preferred partner where long-term support and large-system delivery reliability are prioritized. - Giesecke+Devrient (Munich, Germany)
G+D combines machine supply with high-tech plant engineering and consulting services, which is valuable where process design and quality inspection are decisive. G+D’s offerings lean into end-to-end delivery—equipment, software, and operational know-how—making it adept at complex modernization projects. - De La Rue (Basingstoke, United Kingdom)
De La Rue, with its long-established security-printing capabilities and equipment lineage, remains a full-solution provider including substrate expertise. Their capabilities are often tapped where integrated supply—from design to execution—is required, including polymer transitions and production technique dissemination in regional markets. - Goebel Capital GmbH, SPS TechnoScreen, Pasaban
These specialized OEMs (hybrid web-fed systems, cylinder screen presses, paper converting and sheeting equipment) play crucial roles in niche elements of the production chain. Their value is in modularity, specialized process performance, and the ability to supply retrofits and ancillary plant equipment that increase line throughput or support substrate transitions.
Recent market signals — reading the tea leaves
- Mid-2020s procurement and modernization plans among major sovereign printers have continued to drive equipment demand and aftermarket services. Prime examples include large-system orders awarded in 2025 and strategic equipment roadmaps published by national printers that prioritize efficiency improvements.
- Trade shows and industry awards during 2025–2026 have highlighted both incremental and step-change innovations in substrates, security features, and production ergonomics—indicating that buyers are actively benchmarking new technologies.
- Plant-level modernization programs emphasize that opportunity lies as much in engineering services, retrofit capability, and quality inspection systems as in the sale of new presses. This widens the addressable services market for suppliers with systems-integration capabilities.
Implications for 2026 corporate decisions
For corporate leaders—OEMs, security printers, central banks, and investors—the next 12–18 months are pivotal. Below are high-level strategic takeaways to guide 2026 decisions; the full report converts each into actionable roadmaps and templates.
- Procurement strategy must be lifecycle-aware: Evaluate suppliers on total cost of ownership, retrofitability, and aftermarket coverage, not only on capex price. Insist on demonstrable field data for uptime, mean time to repair, and spare-part logistics.
- Partnerships trump point-solutions: Seek vendors capable of delivering combined equipment-and-engineering solutions. Where capacity constraints or specialized substrates are in play, a converged supplier can reduce project risk and shorten time-to-production.
- Mitigate concentration risk: The market’s top-firm concentration creates supplier dependency risks. Structuring procurement to include second-source options, licensable technology, or performance-based contracts can lower supply-chain vulnerability.
- Capitalize on retrofit and services growth: For OEMs and service providers, investing in predictive maintenance, digital spare-part catalogs, and modular retrofit kits is the most direct path to recurring, higher-margin revenue.
- Policy and program timing matters: Align sales and investment pipelines with sovereign procurement cycles and modernization programs—these create discrete peaks in demand and influence capacity planning.
What our report delivers (practical content)
The full PW Consulting study is highly operational and built for decision-making. Key deliverables include:
- Market sizing and 2026–2032 forecast models with scenario sensitivity and unit economics calibrated to different modernization pathways;
- Vendor due-diligence templates and comparative scorecards covering technology, service footprint, financial strength, and incumbent risk;
- CapEx budgeting tools and procurement negotiation playbooks, including RFP checklists and contractual clauses to safeguard uptime and IP;
- M&A and partnership blueprints—target screen criteria, valuation levers for bolt-on services, and integration planning checklists;
- Operational readiness matrices for central banks and large printers—plant-engineering best practices, retrofit sequencing, and quality-inspection baseline expectations;
- Risk registers for supply-chain, regulatory, and cybersecurity exposures with mitigations and contingency cost models.
Closing: how to use this briefing in 2026
Use this briefing to orient your 2026 strategic priorities: align procurement calendars to sovereign modernization timelines, re-weight supplier assessments toward lifecycle services, and prepare for selective investments in retrofit and digital service capabilities. The landscape favors integrated suppliers and service-led business models, yet concentration in supplier share creates both opportunity and risk for buyers and investors.
PW Consulting’s full Banknote-Printing Machine Market report converts these insights into the analytic assets decision-makers need—forecast models, vendor scorecards, procurement playbooks, and executable roadmaps. For teams preparing CapEx proposals, vendor negotiations, or M&A screens in 2026, the study is structured as an operational toolkit rather than a purely descriptive market review.
To access the complete analysis, detailed supplier benchmarking, and the ready-to-use templates that underpin these recommendations, visit the PW Consulting research portal and request the Banknote-Printing Machine Market report package.
For detailed analysis of this topic, please visit the official page: Banknote-Printing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Thermal Infrared Imagers Market Poised for 11.11% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Thermal Infrared Imagers Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our new Thermal Infrared Imagers Market study. This briefing synthesizes the structural trends and executive-grade implications executives must factor into their 2026 planning cycles. The global market has expanded materially over the past half-decade — rising from a modest multi-billion-dollar base in 2020 to a 2025 baseline that anchors our forward view — and is projected to continue growing through the 2026–2032 forecast window at a compound annual growth rate of roughly 11.11%. That growth trajectory fundamentally changes how suppliers, system integrators, OEMs, and end users should allocate capital, secure supply, and design go-to-market strategies in 2026.
Thermal Infrared Imagers Market
Why this market matters for 2026 decisions
- Acceleration of application diversity. Thermal imagers are no longer niche instruments for defense and specialist industrial inspection — they are moving into mainstream safety (firefighting, industrial safety), security and perimeter surveillance, automotive ADAS/AV platforms, and medical/diagnostic applications. Each of these end-markets imposes distinct performance, certification, and service expectations.
- Technology bifurcation: cooled vs. uncooled. Advances in sensor fabrication and system integration are expanding the practical envelope for both cooled, high-sensitivity systems and compact, cost-effective uncooled modules. Product strategies that ignore either axis risk ceding either premium or volume segments.
- Vertical integration and scale matter. Manufacturers that combine optics, detectors, module production and software stacks are achieving meaningful cost and time-to-market advantages — a dynamic that will intensify as module-level demand from automotive and uncrewed platforms ramps in 2026.
- Regulation and safety standards influence product roadmaps. Automotive functional-safety standards and public-safety procurement frameworks are shaping which modules qualify for critical programs — compliance is a table-stakes capability for any supplier targeting ADAS/AV or first-responder contracts.
- Supply resilience and capacity expansion. Recent announcements of capacity increases and new product rollouts show that both supply constraints and strategic capacity plays will be central to competitive positioning this year.
What our research delivers — practical, executable content
The full PW Consulting report translates market momentum into tools executives can use immediately. Key deliverables include:
Thermal Infrared Imagers Market
- Market sizing and trend maps with a 2025 base year and granular forecasts across the 2026–2032 horizon, enabling capital planning and revenue-target setting.
- Segment frameworks by region, product type (cooled/uncooled and module vs. complete systems), and application — presented as strategic opportunity matrices rather than raw numbers, to support prioritization without overloading tactical teams.
- Technology readiness and roadmaps: sensor architectures, detector types, optics, and software stacks — and how each maps to end-use requirements.
- Supply-chain heatmaps and risk assessments, highlighting single-source dependencies, critical materials, and actionable mitigation levers.
- Competitor benchmarking and vendor scorecards that go beyond product lists to evaluate manufacturability, vertical integration, route-to-market, and services capability.
- Commercial playbooks: pricing archetypes, channel strategies, procurement recommendations for large buyers, and aftermarket/service models to drive recurring revenue.
- M&A and partnership scouting: prioritized targets and alliance structures to fast-track capability gaps.
- Scenario-driven investment cases and a 24-month activation plan with KPI dashboards tailored for board-level oversight.
Competitive landscape — strategic takeaways
The market remains contested: a handful of established players retain leadership through technology breadth and scale, while specialized vendors exploit niches with narrow, high-value propositions. Our analysis highlights several archetypes worth noting for 2026 strategy:
Thermal Infrared Imagers Market
- Integrated leader: Global incumbents who combine detector manufacturing, module production and systems integration are leveraging vertical scale to address both professional and emerging automotive demand. Their investments in module-level quality and software stacks create high barriers for late entrants.
- Volume disruptor: Firms focused on compact, cost-engineered sensors are forcing price-performance trade-offs, opening consumer and cost-sensitive industrial segments while nudging incumbents to rethink cost structures.
- High-end specialist: Companies that focus on cooled, high-resolution imagers retain advantages in demanding industrial inspection, scientific, and long-range defense applications where sensitivity and image fidelity command premium pricing and long product lifecycles.
- System integrators and safety OEMs: Producers of explosion-proof and firefighter-grade devices, and suppliers of networked security cameras, are turning thermal modules into complete propositions, emphasizing certification, ruggedization and serviceability.
Market concentration is moderate: the top three vendors do not dominate the entire space, and the top-five aggregate indicates meaningful headroom for differentiation and new entrants who combine technology and channels effectively.
Recent competitive moves that matter in 2026
- Automotive-grade module launches are reshaping supplier evaluations — OEMs and Tier-1s now demand module suppliers with functional-safety credentials and automotive-grade validation programs.
- Defense and ISR-focused product rollouts demonstrate renewed program spending and integration opportunities for long-range and missionized systems.
- Capacity expansions for cooled cameras signal supplier confidence in long-term demand for premium systems and highlight potential bottlenecks for buyers without secured supply arrangements.
- Industry events and knowledge campaigns continue to educate buyers on thermography use-cases in automation and predictive maintenance, broadening the TAM for thermal imaging beyond traditional buyers.
Six priority moves for executives in 2026
- Define a clear product-positioning bifurcation: Decide whether to pursue premium cooled systems, high-volume uncooled modules, or a hybrid portfolio. Positioning determines required capital intensity and channel choices.
- Pursue functional-safety and procurement compliance early if targeting automotive or public-safety segments. Certification timelines and validation programs should be built into 2026 roadmaps to avoid market exclusion.
- Secure strategic supply and manufacturing capacity. Where possible, negotiate multi-year offtake or co-investment agreements to de-risk ramp periods and lock-in attractive lead-times.
- Invest in software and edge analytics. Hardware commoditization is real — differentiation through image processing, AI-enabled analytics, cloud services and lifecycle management will sustain higher margins.
- Rework commercial models to capture aftermarket and services revenue. Field upgrades, calibration services, and subscription analytics convert single sales into annuity streams.
- Use M&A selectively to close capability gaps — target high-value IP, sensor fabrication access, or channel reach rather than broad consolidation which can dilute focus.
Decision framework & KPIs for 2026 planning
We recommend a concise evaluation framework executives can adopt immediately:
- Market alignment: Does the target segment map to a core strength (technology, channel, or service)?
- Time to compliance: How many quarters to achieve necessary functional-safety or procurement certifications?
- Supply robustness: What percentage of supply is single-source and what mitigation levers exist?
- Unit economics: Projected margin after software and service uplift at target volumes.
- Revenue mix targets: Share of product vs services and projected ARR build in a three-year horizon.
Establishing these KPIs in Q1–Q2 of 2026 will enable leadership teams to make go/no-go decisions before budget lock-in cycles later in the year.
How to use the full PW Consulting report
This preview is deliberately strategic and selective. The complete report supplies the granular intelligence procurement, R&D, commercial and corporate-development teams need to act with precision: detailed regional and application splits, product-level pricing benchmarks, vendor scorecards with comparative technical matrices, supply-chain maps with single-source risk flags, and financial models to populate board-level investment cases.
For teams running parallel pilots, our scenario models quantify outcomes across conservative, aggressive-growth, and disruption scenarios — enabling you to size investment, forecast breakeven horizons, and stress-test partner strategies under realistic supply and regulatory contingencies.
In closing, the thermal infrared imaging market in 2026 represents both opportunity and complexity: the market is expanding at a double-digit CAGR from a solid 2025 base, incumbents are consolidating advantages through integration, and new entrants are accelerating adoption through affordable sensing and smarter software. For executives, the immediate task is not merely to recognize growth, but to design repeatable commercial models that convert technological capability into sustainable margin and platform value. PW Consulting’s full study provides the playbook and the tactical instruments to do exactly that.
To access the full dataset, vendor benchmarks, and executable 24-month activation plan, please visit the PW Consulting report page or contact our advisory team for a bespoke briefing.
For detailed analysis of this topic, please visit the official page: Thermal Infrared Imagers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fish Finders Market to Expand at 6.9% CAGR Through 2032
By pmarketresearch, 2026-07-13
Fish Finders Market — 2026 Strategic Preview
As PW Consulting’s lead industry analyst, I present a focused preview of our comprehensive Fish Finders Market study — designed to inform executive decisions in 2026 and beyond. This briefing demonstrates the analytical depth we bring to product planning, channel strategy, and M&A, while intentionally withholding select granular tables and segment-level datapoints to preserve the investigative value of the full report.
Fish Finders Market
Macro snapshot: where the market stands in 2026
The fish finders market has shown resilient expansion through the early 2020s, moving from a clear mid‑hundreds million USD footprint in 2020 to a base‑year total of USD 566 million in 2025. Our forecast modeling indicates a continuation of that trajectory: the global market is projected to approach roughly USD 857 million by the end of the forecast horizon, driven by a compound annual growth rate of 6.9% across the 2026–2032 period. Market concentration is meaningful — the top three vendors account for approximately 60% of industry revenues and the top five roughly 75% — underscoring a competitive landscape dominated by a small set of well‑resourced incumbents.
Fish Finders Market
Why this matters for 2026 decision-makers
Three immediate implications should shape boardroom priorities and tactical plans this year:
Fish Finders Market
- Product portfolio timing: Technological steps such as 360° scanning, forward‑facing CHIRP imaging, and castable wireless sonars are moving from novelty into buyer expectations. For firms planning 2026/2027 launch cycles, alignment with these capabilities — or clear differentiation strategies — will determine access to the fast‑growing segment of premium buyers.
- Channel and partner plays: OEM integrations with boatbuilders, and software partnerships (e.g., weather/fishing‑forecast overlays), are accelerating value capture. Channel expansion without integration roadmaps will underutilize investments in connectivity and data services.
- Regulatory and event risk management: Tournament rules that restrict forward‑facing sonar in a subset of events create both compliance obligations and marketing narratives. Firms must balance product enablement with configurable modes and firmware‑level controls to reduce exposure to event‑specific bans.
Key trends shaping demand and competitive dynamics
- Imaging evolution: Multi‑modal sonar (CHIRP, TruEcho enhancements, and high‑definition MEGA/Live imaging) is increasing the perceived utility of devices for sports and tournament anglers. This raises willingness to pay in premium segments while compressing margins for low‑end legacy devices.
- Portable & connected formats: Castable and smartphone‑integrated sonars are broadening the addressable market to shore, kayak, and ice anglers, creating an adjacent aftermarket and app‑monetization opportunities.
- Integrated navigation ecosystems: Chartplotter/sonar convergence, radar overlay integrations, and fishing‑forecast layers are shifting value toward ecosystems rather than standalone hardware, favoring vendors with software roadmaps and recurring service models.
- Consolidation and concentration: The CR3/CR5 figures indicate a market where scale matters for R&D and distribution. Expect vigorous competition for exclusive OEM deals and a steady cadence of bolt‑on acquisitions to fill capability gaps.
- Event and rules noise: Practical rules from major tournament organizers — for example, new limits on the use of forward‑facing sonar in specific events in 2026 — have introduced short‑term demand uncertainty and changed product feature priorities for tournament anglers and sponsors.
Competitive landscape — what to watch from the leaders and specialists
The market is populated by a mix of diversified electronics giants, niche innovators, and value players. Our report profiles each principal competitor and evaluates strategic posture across product platforms, channel strength, and software capabilities.
- Garmin (Olathe, KS): A clear innovation driver in integrated marine electronics — expanding its portfolio with 360° scanning solutions and motorized Spy Pole systems that combine TruEcho CHIRP performance with panoramic coverage. Garmin’s depth across consumer and pro channels makes it a baseline competitor for any premium offering.
- Lowrance (Olathe, KS): Focused on tournament‑grade imaging and side/down imaging systems. Lowrance’s product cadence is oriented toward competitive anglers and high‑performance recreational use, making it a benchmark for feature completeness in the sport segment.
- Humminbird (Eden Prairie, MN): Positioned as an innovator in forward‑facing MEGA imaging and livebait tracking; recent model introductions emphasize clarity and live‑tracking refinements that appeal to bass anglers and tournament circuits.
- Furuno (Kobe; North America ops in Vancouver, WA): Strong in both commercial and recreational applications, competing on robustness and multifunction displays with deep analog/digital sonar competence.
- Simrad Yachting (Kent, WA): Leveraging integrations with radar and fishing‑forecast overlays — recent rollouts of FishCast demonstrate how software can enhance offshore planning and create stickier user experiences.
- Raymarine (Southampton, UK): Competing on premium chartplotter/sonar combos with a focus on marine navigation and a differentiated operating system approach for user experience.
- HawkEye / NorCross (St. Louis, MO): Serving accessible portable and kayak/ice markets with value‑oriented handhelds and simple boat mounts; attractive for volume channels and mass‑market adoption strategies.
- SI‑TEX (Riverhead, NY): Focused on professional GPS/chart fishfinders, serving commercial and specialized users who prioritize durability and integration over consumer bells and whistles.
- Deeper (Vilnius, Lithuania): The castable, smartphone‑connected sonar specialist that has redefined the shore and kayak segments; represents a case study in how software UX and mobility can create new categories.
Recent market activity underscores these trajectories: Garmin’s introduction of a GT360 UHD transducer and motorized Spy Pole (March 2026) and Simrad’s deployment of FishCast forecast overlays (late 2025–early 2026) are tangible examples of hardware–software bundling and OEM partner expansion. Additionally, boatbuilders are increasingly pre‑fitting electronics suites under partnership agreements — a distribution dynamic that favors vendors with integrated system offers.
What the full PW Consulting report includes (operational value)
For executives planning product roadmaps, channel expansions, or M&A in 2026, our report provides an operational toolkit rather than a mere market narrative. Key deliverables include:
- Comprehensive market sizing and validated historical series (2020–2025) with model transparency and sensitivity testing.
- Forecast scenarios through 2032 (base, upside, downside) that incorporate technology adoption curves, regulation scenarios (including tournament rule impacts), and macroeconomic stress tests.
- Detailed competitive intelligence dossiers on leading vendors (product portfolios, go‑to‑market maps, partnership matrices, and product roadmaps) and a five‑year capability gap assessment.
- Segmentation frameworks (by product type, channel, and end‑use) with demand drivers and elasticities — note: high‑resolution segment tables are available in the full report portal.
- Component and supply‑chain analysis (key sensors, transducers, semiconductor dependencies, and cost migration forecasts) with supplier risk rankings.
- Commercial playbooks: pricing benchmarks, bundling strategies (hardware + software + services), subscription models for data overlays, and recommended channel mixes by target cohort.
- Regulatory & tournament compliance playbook to minimize product feature conflicts and to design configurable firmware that satisfies both rules and user expectations.
- M&A and partnership screening tool: candidate profiles, valuation heuristics, and integration risk checklists tailored to both strategic and financial sponsors.
Strategic recommendations for 2026
- Prioritize software ecosystems: Even modest hardware vendors should roadmap companion apps, forecast overlays, and firmware-updatable imaging algorithms to extend lifetime revenue and lock in customers.
- Design for configurability: Build feature‑level switches and competition‑mode presets to address tournament restrictions while preserving premium functionality for open events and casual anglers.
- Accelerate OEM partnerships: Target selective boatbuilders and kayak brands with bundled offers and data integrations that make the electronics suite the default purchase decision.
- Segment go‑to‑market rigorously: Separate propositions for tournament anglers, recreational buyers, and commercial/research customers — each cohort values different performance metrics and service expectations.
- Assess consolidation opportunities: Given current concentration levels, acquiring complementary imaging, app, or distribution assets can be an efficient path to scale and margin improvement.
Final note — the value of the full intelligence set
This preview highlights the structural moves and strategic choices that will define winners in 2026. The full PW Consulting Fish Finders Market report delivers the empirical foundation — including complete segment tables, price decks, and supplier mappings — required to move from strategy to execution. If your 2026 roadmap depends on accurate forecasts, scenario planning, or competitive playbooks, the full dossier provides the data and tools to act with conviction.
To access the complete study, including proprietary segment breakdowns and executable annexes, please consult the PW Consulting report portal or contact our industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Fish Finders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Active Air Sampler Market to Hit USD 594.5M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-13
Active Air Sampler Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
PW Consulting’s new Active Air Sampler Market study delivers a pragmatic intelligence package aimed squarely at the decisions you will make in 2026. The market for active air samplers has shown steady expansion through the recent historical window (2020–2025), rising from approximately USD 285 Million in 2020 to USD 384.3 Million in the base year 2025. Our baseline forecast (2026–2032) projects continued growth to roughly USD 594.5 Million by 2032, implying a compound annual growth rate (CAGR) of 6.5% across the forecast period.
Active Air Sampler Market
Those topline figures capture both structural tailwinds (regulatory tightening, biopharma manufacturing scale‑up, and renewed focus on food/health safety) and the tactical responses of vendors (product, service and digital integration). This preview highlights why these dynamics matter for procurement, R&D, M&A, and service strategy in 2026 — while deliberately preserving detailed subsegment data and granular regional splits to encourage access to the full study.
Active Air Sampler Market
Why this study matters for decisions made in 2026
- Regulatory inflection is real and immediate. Updates to cleanroom and aseptic processing guidance have elevated the commercial importance of validated, continuous viable monitoring and documented data integrity. Compliance timelines and validation build windows mean procurement cycles initiated in 2026 will determine equipment and service footprints for several years.
- Technology convergence reshapes value chains. The integration of active samplers with remote sampling, real‑time particle counters and digital logging platforms is changing purchase criteria from pure instrument cost to integrated solution economics.
- Service & calibration becomes a competitive moat. As buyers prioritize chain‑of‑custody, calibration integrity and 21 CFR/ISO aligned documentation, vendors with robust service networks and accredited calibration offerings capture higher lifetime value.
- Fragmentation creates both risk and opportunity. Market concentration metrics show the industry remains fragmented (CR3 ~19.8% and CR5 ~24.5%), signaling acquisition opportunities for strategic consolidators and whitespace for focused specialists.
- M&A and partnerships will accelerate. Strategic investments and technology partnerships are already visible; the next 12–24 months will separate nimble integrators from single‑product incumbents.
What the full report delivers — practical contents for immediate action
- Market sizing and validated forecasting (base year 2025, historical 2020–2025, forecast 2026–2032) with scenario and sensitivity testing to stress‑test capex plans.
- Segmentation frameworks by region, product type and application, with decision‑grade worksheets for prioritizing addressable revenue pools (note: granular split tables and proprietary subsegment figures are available only in the full report).
- Competitive landscaping and vendor scorecards assessing product portfolio breadth, regulatory fit, digital maturity, service footprint, and channel strategy.
- Regulatory mapping — line‑by‑line implications of EU GMP Annex 1 and ISO 14698‑1 for procurement specifications, validation requirements, sampling protocols, and audit readiness.
- Technology deep dives covering impactor technologies, cyclonic samplers, membrane and gelatin filtration approaches, remote sampling platforms, and real‑time microbial detection integrations.
- Go‑to‑market playbooks and procurement templates: validated RFP language, acceptance test scripts, ROI and TCO calculators, and sample service level agreements.
- Strategic recommendation engine for M&A targeting, partnership screening, and product roadmap prioritization — including a short list of capability gaps buyers and vendors should address immediately.
Competitive landscape — tactical takeaways for vendors and buyers
The vendor universe is populated by specialist instrument makers and larger life‑science players. Several archetypes are visible: engineering‑first innovators focusing on sampling technology (impactors, cyclonic samplers, membrane solutions), platform integrators pursuing digital/data integrity advantages, and service‑centric players anchoring sales through accredited calibration and support networks.
Active Air Sampler Market
- Product innovators: Companies producing cyclonic samplers and multi‑head impactors are advancing sampling efficiency and usability. These firms compete on throughput, capture efficiency and ergonomic design.
- Platform integrators: Vendors offering remote/automated sampling capable of integration with particle counters and LIMS are capturing incremental value as buyers prioritize continuous monitoring and audit trails.
- Compliance & service specialists: Firms that combine instrument sales with ISO/17025‑grade calibration, 21 CFR Part 11–aligned data management and field validation become preferred partners for large regulated customers.
Representative vendors in the market exemplify these archetypes. For example, certain U.S. and European manufacturers offer remote Annex 1‑compliant samplers designed for aseptic Grade A/B environments, while other European and Asian manufacturers focus on portable impactor devices and membrane filter solutions for traditional viable monitoring. Notable moves in the recent timeline reinforce strategic direction: a Swiss vendor launched a next‑generation active microbial air sampler in May 2026 emphasizing improved usability for cleanroom monitoring, a major French life‑science company invested in a real‑time air microbial particle counter integrator in March 2026, and a U.S. supplier received ISO 17025 accreditation for calibration services in late 2025. These events demonstrate the market’s twin emphasis on product refinement and service/accreditation as competitive levers.
Regulatory and technical dynamics shaping procurement
- EU GMP Annex 1 & ISO 14698‑1: Both documents are driving purchases toward systems that facilitate validated continuous viable monitoring, traceable sample handling and documented method performance. Buyers must embed Annex 1 and ISO requirements into technical specifications and acceptance testing.
- Data integrity and remote monitoring: Requirements such as 21 CFR Part 11 compliance and secure electronic records are elevating expectations for onboard software, audit logs, and integration capabilities.
- Validation first, features second: For regulated customers, validated performance (recovery efficiency, repeatability under cleanroom conditions) often trumps minor feature differentials; vendors must prioritize validation packages and ready‑to‑deploy protocols.
Four‑point strategic playbook for 2026
- For vendors — product & validation roadmap: Prioritize modular designs that support both portable and remote deployment, publish independent validation data aligned to ISO 14698‑1, and bundle documented Annex 1 compliance aids to reduce buyer friction.
- For service leaders — accreditation & network expansion: Invest in ISO 17025 capabilities, scale field calibration teams in key manufacturing clusters, and offer subscription‑based calibration and validation services to convert transactional sales into recurring revenue.
- For strategic buyers — procurement discipline: Convert regulatory requirements into mandatory RFP pass/fail criteria (validation artifacts, software audit trails, service SLAs). Evaluate total cost of ownership including calibration cadence, consumables, and validation labor — not just capital price.
- For consolidators — targeted M&A & partnerships: Seek targets that add either accredited calibration infrastructure or digital sampling/real‑time detection capabilities. Partnerships with specialist integrators can accelerate time‑to‑market for combined hardware/software propositions.
Why PW Consulting’s report is uniquely actionable
We combine rigorous top‑down market sizing (base year 2025; historical 2020–2025; forecast 2026–2032) with bottom‑up device, consumables and services economics to produce decision‑grade outputs. Our vendor scorecards synthesize product validation, regulatory fit, service footprint and digital maturity into a single advisory framework that procurement, product and corporate development teams can operationalize. The report also contains editable procurement templates, validation checklists, and M&A screening matrices that accelerate execution timelines for 2026 initiatives.
How to use this preview — next steps
This briefing is intended as a strategic “trailer”: it exposes the trends, vendor archetypes and regulatory drivers that will shape budgets, roadmaps and M&A moves in 2026, while intentionally withholding proprietary subsegment tables and granular regional/application splits. If you are preparing procurement cycles, launching product development initiatives, or evaluating acquisition targets this year, the full PW Consulting report provides the detailed split‑level intelligence, vendor benchmarking matrices and customizable templates that translate insight into action.
Contact PW Consulting to access the complete study and receive a tailored briefing that maps the findings directly to your organization’s product, procurement and M&A priorities for 2026.
For detailed analysis of this topic, please visit the official page: Active Air Sampler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Remote Control Radio Equipment to reach USD 344.8M by 2032 at 6.98% CAGR – PW Consulting
By pmarketresearch, 2026-07-13
Remote Control Radio Equipment Market: Strategic Imperatives for 2026 — PW Consulting Preview
As organisations recalibrate capital allocation and product roadmaps for 2026, remote control radio equipment has moved from a niche industrial input into a strategic vector for operational productivity, safety compliance, and service-led revenue. PW Consulting’s new market research, anchored to a 2025 base year, projects a continuation of steady growth through our 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.98%. By taking a systems-level view of technology, regulation, and buying behaviour, this research provides the decision support that executives and product leaders need to convert momentum into durable competitive advantage.
Remote Control Radio Equipment Market
Why this study matters for 2026 decisions
-
Timing and scale: The market has expanded consistently in the early 2020s and, on our base-year measurement, global revenue reached a material level by 2025. That scale makes strategic moves (R&D investment, channel shifts, or M&A) meaningful to firm-level P&L and industry structure.
Remote Control Radio Equipment Market -
Regulatory inflection points: Policy changes in major markets — from the FCC’s equipment authorization adjustments to strengthened EU cybersecurity mandates under the Radio Equipment Directive — materially alter product compliance burdens and time-to-market for radio-enabled systems.
Remote Control Radio Equipment Market -
Safety and efficiency as value drivers: Stricter occupational safety regulation and evolving standards (for example, updates related to machinery and material handling) convert compliance into a buying criterion, enabling premium positioning for certified solutions.
-
Fragmented competitive landscape: Market concentration metrics show a relatively open field. While established OEMs and specialised suppliers dominate certain product segments, the overall industry remains amenable to focused consolidation, platform plays, and white-label OEM partnerships.
What the macro numbers tell us (high level)
Using a transparent, repeatable modelling approach, our analysis quantifies the current market and its trajectory through 2032. From a 2025 base year, the sector is forecast to grow at a mid-single-digit CAGR across the 2026–2032 horizon. This trajectory is consistent with durable demand driven by industrial automation, replacement cycles for legacy systems, and a gradual uptake of software-enabled “smart” controls that add lifecycle revenue through telematics and services.
Two structural observations underpin the headline figures: first, product upgrades are increasingly driven by non-functional requirements — safety, cybersecurity and integration — rather than raw cost-per-unit; second, aftermarket and service models represent a fast-growing margin pool for vendors who can capture telemetry and provide lifecycle services.
Competitive landscape: Reading the players for strategy
The market comprises a mix of long-established specialist manufacturers, OEM platforms, and systems houses that deliver safety-certified, ruggedised radio controls. Key incumbents — each with distinct strengths — offer a roadmap to where value concentrates and where disruption is most likely:
-
HBC-radiomatic — German-based manufacturer known for end-to-end production and safety-forward designs. Their vertical control of manufacturing and certification sets a high bar for reliability in crane and hydraulic applications.
-
Hetronic Group — US-headquartered, with strong focus on customization and operator safety. Their capability to tailor systems for specific clients signals an attractive route for premium, project-based revenues.
-
Tele Radio and Scanreco — Scandinavian producers that combine long heritage with OEM platform offerings. Their emphasis on durability and user ergonomics highlights the premium segment’s emphasis on total cost of ownership.
-
Autec , Cattron Group , OMNEX (Eaton) — These vendors reflect complementary strategies: modular product lines, systems integration and access to broader industrial portfolios, each offering different routes to scale and cross-selling.
-
Regional and niche specialists such as NBB, Akerstroms and Ikusi show that local regulatory knowledge and domain-specific certifications remain important barriers to entry in certain verticals.
Collectively, the top three and top five suppliers capture a limited share of the market by revenue, indicating a landscape that rewards targeted consolidation and platform aggregation. For strategists, this means M&A is a viable lever — but success requires careful integration planning around standards, certification credentials, and channel overlap.
Recent commercial signals (May 2026)
-
Trade show activity has been high-profile: leading suppliers demonstrated next‑generation wireless remotes and modular platforms at global events. These vendor showcases provide early insight into capability roadmaps and the speed of productisation for industry-specific use cases.
-
Exhibitions and product launches have emphasised modularity, safety certification, and integration with process-control ecosystems — a signal that future winners will be those who can translate hardware into systems-level value.
Regulatory and standards dynamics that will shape 2026 planning
-
FCC equipment authorisation rules : Recent changes limit certain modular transmitter authorisations for affected entities — a geopolitical and supply-chain risk that buyers and suppliers must actively manage. Sourcing and component validation strategies are now part of product due diligence.
-
EU Radio Equipment Directive (RED) : The Directive’s cybersecurity requirements impose design-level obligations (risk assessment, fraud protection) that can extend development cycles and increase the cost of compliance for entrants and incumbents alike.
-
Safety and industry standards : ISO and regional machine safety standards continue to evolve. Organisations that map product roadmaps to these standards early will turn compliance into a marketable advantage rather than a reactive cost.
What the PW Consulting report delivers — practical, transaction-ready intelligence
The full PW Consulting study is deliberately operational. It is designed not only to inform, but to be put to work by executives, product leaders, sales heads and corporate development teams. Highlights include:
-
Proprietary market-sizing and scenario forecasts (2026–2032), with transparent assumptions and sensitivity tables so you can re-run scenarios against your own adoption hypotheses.
-
Competitive scorecards and supplier capability matrices that evaluate certification, hardware platforms, software ecosystems, service capabilities and channel reach — enabling rapid shortlist creation for procurement and M&A screening.
-
Regulatory impact matrix mapping FCC, EU RED, ISO and national safety standards to product requirements and time-to-market implications; includes a compliance checklist for product and supply chain owners.
-
Go-to-market playbooks for three strategic archetypes: premium OEMs, systems integrators, and aftermarket-service specialists — each with pricing levers, channel models and sales KPI templates.
-
Technology and product roadmaps summarising tradeoffs between analog, digital and “smart” control architectures, along with practical recommendations on wireless protocols, encryption approaches, and telematics integration.
-
M&A diligence templates and synergy calculators that incorporate integration costs for certification, software harmonisation and channel realignment.
-
Commercial negotiation playbooks, RFP templates and a benchmarked supplier scorecard that support rapid procurement cycles without sacrificing compliance assurance.
Actionable recommendations for 2026 (prioritised)
-
Immediate (0–9 months) : Audit existing product lines for compliance gaps (RED, FCC authorisation and relevant ISO standards). Institute secure provisioning and firmware-update processes to meet cybersecurity obligations and to reduce recall risk.
-
Near-term (9–18 months) : Accelerate product modularisation and partner with certified wireless-component suppliers to mitigate authorisation and supply-chain risk. Pilot a service bundle that leverages telematics for predictive maintenance and recurring revenue.
-
Medium-term (18–36 months) : Evaluate acquisition targets that bring either certification expertise or software/telematics IP. Use the PW Consulting supplier scorecards and synergy tools to prioritise targets that reduce time-to-compliance and increase service monetisation.
-
Strategic (36+ months) : Build a platform play — standardise a core hardware/software stack and offer it via OEM/white-label channels. Use compliance as a market-entry barrier and differentiate on lifecycle services rather than unit price alone.
How to use this preview
This preview is intended as a strategic briefing: it highlights the directional forces, competitive players and regulatory shocks that should influence board-level and product-level decision-making in 2026. For practitioners ready to act, the full PW Consulting report supplies the confidential segmentation, detailed unit economics, and vendor-level financial benchmarks that drive executable plans. We intentionally withhold granular segmentation tables and proprietary supplier revenue splits in this public summary to protect the value of the underlying primary research and to encourage a direct engagement that will deliver tailored scenario modeling for your organisation.
If your team is preparing capital decisions, product roadmaps, or M&A strategies for the remote control radio equipment space this year, PW Consulting’s full report and advisory services convert market insight into executable roadmaps — from compliance remediation to product-platform plays and disciplined roll-up strategies. Contact our strategy desk to request the complete study or to book a briefing tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Remote Control Radio Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Motor Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Motor Market 2026: Strategic Outlook and Action Playbook
Executive summary
As global electrification and automation accelerate, the motor market sits at an inflection point that will define industrial competitiveness and mobility strategies for the rest of the decade. Our Motor Market study, with base year 2025 and a historical window covering 2020–2025, projects the market to expand from an estimated USD 215.0 Million in 2025 to approximately USD 344.8 Million by 2032. This trajectory implies a compound annual growth rate (CAGR) of 6.98% across the forecast period (2026–2032). For corporate leaders making 2026 investment and portfolio choices, this study translates those headline numbers into measurable strategic options — but in this introduction we intentionally surface strategic insights while withholding the granular segment tables to encourage direct engagement with the full report.
Motor Market
Why the 2026 decision window matters
2026 is not merely another year on the growth curve. It is the first year of the forecast period and a practical decision point for capital allocation, supply-chain reorientation, and R&D prioritization. Between 2020 and 2025 the market expanded materially — our baseline grew from roughly USD 163.15 Million in 2020 to USD 215.0 Million in 2025 — demonstrating both resilience and structural momentum. The step-change projected for 2026 (to about USD 231.54 Million) signals that investments initiated in 2026 will capture the earliest portion of compounding returns that drive value through 2032.
Motor Market
Key macro implications for strategy
-
Growth with concentration: Despite healthy market growth, the competitive landscape remains fragmented. The top-three and top-five firms together account for approximately mid‑20 percent market shares (CR3 ≈ 24.6%, CR5 ≈ 26.2%). That fragmentation means scale matters but so does agility — there is room both for large incumbents to consolidate value and for focused challengers to win via niche specialization.
Motor Market -
Demand mix is shifting: Electrification of mobility and rising automation in manufacturing are dominant demand drivers. While we will not disclose the full split here, electric vehicles are the single largest end-market in the base-year construct; industrial automation and other sectors represent material, differentiated growth pockets. That split should influence product roadmaps and go-to-market models.
-
Materials and policy risk are now a strategic headwind: Rare earths, copper, aluminium and other critical inputs are central to product cost, technology choice and supply security. Recent regulatory moves — notably the EU Critical Raw Materials Act and escalated export-controls on rare earths — change how companies must model sourcing and localization risk.
Market dynamics that will shape winners and losers
Understanding the interplay of raw materials, technology cycles and policy is the axis on which near-term choices will compound into long-term advantage.
-
Raw material supply geometry: Demand for rare earth elements is set to surge in Europe and globally as permanent-magnet motor content rises with electrification. Policymakers in Europe are pursuing diversification and local aggregation of critical materials, while other jurisdictions have tightened export controls — a dynamic that can inflate procurement costs, delay product launches or force redesigns.
-
Regulatory architecture: The EU requirement to limit single-country dependency and the launch of centralized material-data infrastructures (e.g., the EU Critical Raw Materials Centre scheduled for launch in 2026) create both compliance obligations and opportunities to secure preferential project pipelines for firms that can demonstrate resilient sourcing.
-
Technology substitution and product mix: Innovations in motor topologies (e.g., synchronous reluctance, hairpin and S-winding technologies, magnetless designs) change the value equation between performance and material dependency. Companies that map expected material constraints into alternate architectures will preserve margins while meeting customer performance thresholds.
-
Price and efficiency sensitivity: A 10MW synchronous motor illustrates the scale of raw-material exposure (tons of copper, hundreds of kilograms of aluminium), underscoring why procurement strategies and engineering choices must be integrated. Small percentage gains in efficiency or reductions in rare-earth intensity can produce outsized commercial returns at scale.
Competitive landscape — what the leading players are doing
The market is being actively contested along three vectors: technology leadership (motor topology and manufacturing), program wins with OEMs (especially in EV platforms), and localized production footprints. Highlights from leading companies and recent developments illuminate tactical moves to watch in 2026:
-
ABB Ltd (Zurich) — continues to place bets on high-efficiency AC and synchronous reluctance motors, amplifying capabilities through demonstration facilities (for example, a new Berlin center opened in late 2025). Their strategy emphasizes combined efficiency and sustainability narratives for industrial automation and mobility customers.
-
Siemens AG (Munich) — retains emphasis on premium AC and DC motors for industrial drives and renewable-generation applications. Expect Siemens to press into integrated drive systems and services, targeting higher gross margins per installed base.
-
Nidec (Kyoto) — focuses on precision DC, e-axles and servo solutions for automotive and robotics; they remain an innovation nucleus for compact, high-density motor designs aligned with EV architectures.
-
WEG S.A. (Brazil) — leverages robust 3-phase AC platforms for heavy industries and energy markets, where durability and low total cost of ownership are competitive differentiators.
-
Regal Rexnord and Bosch Rexroth — pursue breadth in AC/DC and motion-control suites, respectively, prioritizing integrated solutions for HVAC, industrial automation and factory modernization.
-
BorgWarner — has accelerated its automotive focus through recent product awards and program wins across Asia and Korea, including hairpin and S-winding technologies for hybrid and high-voltage EV platforms; these contracts and rolling production phases (through 2027) are exemplar of program-driven scaling strategies in the e-mobility segment.
-
Toshiba and Hyundai Electric — continue to hold positions in large industrial and medium/high-voltage motor markets where utility and heavy-industry specifications dominate procurement decisions.
What the full report delivers (practical, transaction-ready content)
Our Motor Market study is designed for executive teams, corporate development groups, and product leaders who need actionable outputs for 2026 strategy cycles. Deliverables include:
- Transparent market-sizing and growth scenarios with sensitivity testing against commodity price and policy shocks;
- Supply-chain maps and tiered supplier scorecards that quantify single-source exposure and re-shoring opportunity;
- Technology roadmaps comparing magnet-intensive vs. magnet-lean architectures, with R&D timelines and cost-per-performance curves;
- Commercial playbooks: partner archetypes, OEM engagement templates, and service-led monetization models;
- M&A and JV scouting lists with fit/gap diagnostics and prioritized integration checklists;
- Regulatory impact models tailored to regional policy regimes and export-control scenarios;
- Customizable dashboards for scenario-driven capital allocation and product launch sequencing.
Recommended 2026 actions — a concise playbook
For leadership teams preparing 2026 budgets and roadmaps, we advise a balanced set of moves that protect margins, accelerate time-to-market, and hedge material risk:
-
Prioritize program-backed product investments: Allocate incremental capex to programs with signed OEM commitments or high-probability commercial pipelines to shorten payback cycles.
-
Localize critical inputs selectively: Use a risk-weighted framework to decide where to localize rare-earth processing or copper-intensive sub-assembly, focusing on regions with favorable regulatory incentives or customer proximity.
-
Adopt flexible engineering platforms: Invest in motor architectures that allow magnet substitution or different winding technologies without full redesigns, thereby protecting product roadmaps from material supply shocks.
-
Lock strategic partnerships: Pursue joint-ventures with material refiners, coil and stator assemblers, or software integrators to capture margin and secure supply continuity.
-
Instrument scenario planning: Use Monte Carlo–style modelling for commodity and regulatory shocks to set trigger points for hedging, capex deferments or accelerated rollouts.
-
Scan for opportunistic consolidation: Given the fragmented nature of the market, target tuck‑ins that add proprietary technologies, fill geographic gaps, or accelerate time to major OEM programs.
Conclusion and next step
The market's growth trajectory through 2032 is clear and strategically meaningful: structural demand from electrification and automation, combined with material and policy pressures, creates a landscape of both risk and disproportionate opportunity. The CR3 and CR5 figures illustrate a fragmented competitive terrain where disciplined scale and focused differentiation both pay. Our full Motor Market report converts the headline growth (CAGR 6.98% for 2026–2032) into executable recommendations, prioritized deal lists, and quantified risk mitigations — including the segment-level data, regional playbooks and sensitivity matrices that we have intentionally withheld here to maintain this piece as a strategic prelude.
To access the complete dataset, granular segment breakdowns, customizable dashboards and the full set of playbooks for 2026 execution, please refer to the Motor Market report on our publication page.
For detailed analysis of this topic, please visit the official page: Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com