
Blogs
KLH Market 2026 Preview: Strategic Intelligence for Decision-Makers
Keyhole Limpet Hemocyanin (KLH) has quietly become a strategic raw material in immunology and early-stage biopharmaceutical development. As PW Consulting’s senior industry analysis team, we present a forward-looking intelligence brief designed to help executives, procurement leads, and clinical development strategists navigate the KLH landscape as they plan actions in 2026. This preview highlights the report’s analytical rigor and practical utility while preserving the detailed segment-level intelligence for the full publication.
Keyhole Limpet Hemocyanin (KLH) Market
Market snapshot: where the industry stands
The KLH market has expanded steadily through the early 2020s, rising from a mid‑two‑digit million-dollar base in 2020 to an evaluated market of USD 123.6 Million in 2025 (base year). Our modeling indicates continued expansion across the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 5.85%, delivering a market approaching USD 184.1 Million by 2032. This growth trajectory reflects the convergence of several secular trends in immunology research, therapeutic vaccine development, and biologics R&D demand.
Keyhole Limpet Hemocyanin (KLH) Market
Two immediate implications arise for 2026 decision-makers: supply predictability and procurement cost exposure. While the market is growing at a steady mid-single-digit pace, the underlying supply chain and regulatory constraints create asymmetric risks that can outsize the headline growth figure. The full report quantifies these dynamics and provides scenario-based supply forecasts and price-path sensitivities for planning horizon decisions.
Keyhole Limpet Hemocyanin (KLH) Market
Key demand drivers and market dynamics
-
Translational immunology and clinical trial demand: KLH’s role as a carrier protein and as a T‑dependent antibody response challenge agent ties its demand closely to early‑phase vaccine and immunotherapy pipelines. Rising activity in these programs underpins baseline demand, while pockets of accelerated procurement tie to specific trial starts and immunomonitoring initiatives.
-
Regulatory and clinical-grade constraints: Clinical‑grade KLH remains sourced from a limited set of GMP‑certified suppliers. Regulatory guidance from major agencies effectively excludes synthetic substitutes for certain clinical uses, making validated GMP supply a gating factor for timely trial execution.
-
Price and reimbursement realities: GMP‑grade material commands material premiums relative to research grades. Moreover, KLH’s use as a challenge agent is typically reimbursed under research protocols rather than distinct clinical billing codes, influencing sponsor cost models for proof‑of‑concept and early clinical development.
-
Operational intensity of production: Sustainable, GMP‑compliant production is aquaculture‑intensive, involving colony maintenance and specialized low‑endotoxin purification steps. These characteristics raise operating costs and limit rapid scale‑up potential, particularly for new entrants without vertical integration of raw material supply.
Supply chain and raw‑material constraints
KLH is an extractive biologic: GMP‑grade material is derived from hemolymph of Megathura crenulata (keyhole limpets) and requires bespoke purification to meet low‑endotoxin clinical standards. There is no widely accepted synthetic replacement for clinical applications, so supplier capacity, aquaculture health, and process robustness directly determine availability and delivered timelines.
For procurement and supply strategy in 2026, organizations should consider three tactical levers:
-
Supplier portfolio diversification: Prequalified alternates reduce timeline risk; the full report maps supplier capabilities and lead times to support supplier tiering decisions.
-
Contracting and inventory strategies: Given premium pricing for clinical grades and the episodic nature of trial starts, hybrid inventory models (safety stock + call‑off contracts) can be more cost‑effective than spot purchases.
-
Early engagement with regulators: For programs that depend on KLH as an immunological comparator or carrier, early alignment on acceptable suppliers and certificates of analysis reduces approval friction.
Competitive landscape: who matters
The KLH supplier landscape blends global reagents houses, specialist biotech producers, and catalog distributors. Market concentration is moderate — the largest cohort of suppliers accounts for less than a third of total market volume, while the top five players together hold a materially higher share yet still leave space for agile niche players. This competitive structure creates both opportunities for strategic partnerships and bargaining leverage for well‑informed buyers.
-
Sigma‑Aldrich (Merck KGaA): A major life‑science catalog player offering native and high‑purity endotoxin‑free KLH across catalog SKUs and GMP/clinical grades. Their breadth of product formats and global distribution is attractive for institutions that prioritize catalog reliability and integrated reagents procurement.
-
biosyn Corporation / biosyn Arzneimittel GmbH: A vertically oriented producer of GMP‑certified clinical‑grade KLH and reassociated variants, positioning itself as a supplier of active pharmaceutical ingredients for immunotherapy and antibody production applications. Their regulatory posture and API focus make them a natural partner for clinical sponsors.
-
Stellar Biotechnologies, Inc.: Specializes in aquaculture‑sourced GMP KLH with proprietary extraction processes. Their supply model emphasizes sustainability and clinical supply reliability, appealing to sponsors with higher bar for traceability and supply continuity.
-
G‑Biosciences: Catalog supplier of immunological‑grade KLH in research formats, widely used for basic immunology and conjugation workflows. Their role is more pronounced in preclinical and early research settings.
The full report contains detailed supplier scorecards (capability maps, GMP certifications, lead time benchmarks, and failure‑mode analyses) that enable granular supplier selection and risk quantification.
Report content — practical outputs for 2026 planning
PW Consulting’s KLH Market report is constructed to support operational decisions as well as strategic planning. Key deliverables included:
-
Market sizing and validated growth scenarios: Historical series and forecast models calibrated to 2025 base year, including sensitivity analyses around aquaculture constraints and clinical trial activity waves.
-
Procurement playbook: Template contracts, inventory optimization models, and recommended SLA clauses for GMP deliveries tailored to early‑phase clinical programs.
-
Supplier intelligence and scorecards: Comparative assessments of GMP capability, geographic footprint, regulatory track record, and volume scalability for incumbent and emerging suppliers.
-
Price benchmarking and cost‑build analysis: Real‑world price differentials between research and clinical grades, and a factory‑level cost decomposition that highlights levers to negotiate premiums.
-
Regulatory and reimbursement brief: Practical guidance on acceptability of KLH sources in regulatory submissions, and implications of limited reimbursement pathways for trial budgeting and sponsor cost allocation.
-
Risk matrices and contingency plans: Event‑driven scenarios (e.g., supplier outage, aquaculture health event, sudden trial consolidations) with action triggers and pre‑negotiated mitigation steps.
-
M&A and partnership playbook: Investment thesis for capacity buildouts or vertical integration, and partnership archetypes for contract manufacturers, aquaculture providers, and assay developers.
How this intelligence informs 2026 decisions
For 2026, our clients consistently ask: how do I underwrite clinical program timelines, costs, and regulatory risks that depend on KLH? The report converts market data into decisioning tools:
-
Program gating analysis: For each clinical program type, we provide the supply exposure index (lead time × procurement concentration × grade premium) so pipeline managers can prioritize early procurement or contingency stock.
-
Supplier contracting strategy: A decision tree helps legal and procurement teams decide between spot buys, fixed‑price contracts, and capacity reservation agreements based on program size and tolerable supply risk.
-
Portfolio and R&D planning: R&D heads can use scenario outputs to decide whether to standardize on a single GMP supplier for harmonized assays or to retain multiple qualified suppliers to protect timelines.
-
Commercial implications for CDMOs and reagent houses: The report identifies niches where scale economics or certified GMP aquaculture confers defensible margins and thus potential targets for investment or strategic partnership in 2026.
Final thoughts and next steps
The KLH market’s steady headline growth masks a complex interplay of extractive biology, clinical‑grade certification, and episodic demand driven by trial starts. For organizations planning budgets, supplier strategies, or M&A moves in 2026, a nuanced understanding of both market sizing and supplier capabilities is essential. PW Consulting’s report translates the market’s macro trajectory (USD 123.6 Million in 2025, forecast growth at a 5.85% CAGR to 2032) into actionable procurement, clinical, and corporate strategies.
To preserve the tactical value of our modeling and supplier benchmarking, detailed segment tables, regional and application splits, and full financial matrices are reserved for the full report. Access the complete KLH Market report for the proprietary datasets, supplier scorecards, contract templates, and scenario tools that support robust 2026 decision‑making.
For detailed analysis of this topic, please visit the official page: Keyhole Limpet Hemocyanin (KLH) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Screen Protector Market to Reach USD 54.9 Billion in 2025
By pmarketresearch, 2026-07-30
Screen Protector Market — Strategic Outlook for 2026: A PW Consulting Brief
As the global accessories market matures into its second decade of rapid evolution, PW Consulting’s Screen Protector Market study delivers a focused intelligence suite designed to inform high-stakes decisions in 2026. Built on a 2025 base year with a historical lens covering 2020–2025 and forward-looking projections to 2032, the market shows a clear, sustained expansion: the global market grew from roughly USD 38.4 billion in 2020 to about USD 54.9 billion in 2025 and is projected to approach USD 90.5 billion by 2032, tracking a compound annual growth rate of ~7.4% across the forecast period. This brief synthesizes the strategic implications of those dynamics and explains how our full research equips leadership teams to translate market growth into competitive advantage without disclosing the granular tables reserved for report subscribers.
Screen Protector Market
Why this matters for 2026 corporate strategy
-
Demand momentum is durable and multi‑faceted. Growth is driven by a mixture of device proliferation, premiumization of screen protection technologies, and recurring replacement demand in mature markets. These forces create both volume opportunities and margin capture possibilities for differentiated suppliers and brand owners.
Screen Protector Market -
Supply-side innovation is reshaping competitive boundaries. Advances in accessory glass engineering and licensing agreements between glass manufacturers and local contract producers are enabling new entrants to compete on quality rather than price alone.
Screen Protector Market -
Regulatory and standardization developments are increasing the importance of certification and compliant supply chains. Recent moves in standards and trade policy mean that a previously peripheral procurement variable is now core to market access and go-to-market timing.
Key inflection points to watch
-
Premium material adoption: Proprietary engineered glass and specialty coatings (privacy, anti-blue-light, anti-glare) are shifting value away from basic polymer films into higher ASP categories. Companies that can secure supply or licensing of premium glass stand to expand margin pools.
-
Manufacturing localization: New national standards and incentives are accelerating domestic manufacturing initiatives in select markets, reducing historical import dependence. This trend has implications for sourcing, tariff exposure, and speed-to-market for customized SKUs.
-
Regulatory and trade litigation: Industry participants must plan for episodic regulatory events that can rapidly change access to important markets or product classes. Such events can compress planning horizons and create windows for entrants that are strategically prepared.
Competitive landscape — who you must account for
The competitive field is a mix of brand-led incumbents, specialized OEM suppliers, and nimble regional manufacturers. On the brand side, firms with strong consumer recognition and retail distribution bring differentiated product design and marketing scale. Specialized OEM and contract manufacturers supply private label and OEM channels with variable cost and customization advantages. Several company moves and product launches in the past 18 months illustrate how value is being contested along different dimensions:
-
Leading direct-to-consumer brands emphasize ease-of-use and feature-rich positioning (anti-scratch, bubble-free installation, blue-light mitigation, privacy filtering). These firms leverage distribution partnerships and brand loyalty to sustain ASPs in developed markets.
-
Custom glass manufacturers and contract producers are forging closer ties with global glass-engineering firms; these relationships enable higher-spec tempered glass products tailored for retailers, OEMs and private-label partners.
-
Regional entrants are pursuing a localization strategy that combines certification, domestic manufacturing, and co-branded material licensing to displace imports in their home markets and pursue selective exports.
Profiles to watch (strategic takeaways)
-
Brands focused on consumer retail and e-commerce: Their strengths are brand equity, channel control and product innovation centered on end-user features. They will continue to extract value through design and distribution, but must defend against commoditization in lower tiers.
-
Custom and contract manufacturers working with premium glass suppliers: These players are positioned to win OEM and private-label mandates by combining technical glass capability with scale production and rapid SKU customization.
-
Regional champions leveraging certification and local standards: Where governments introduce formal quality standards and incentives, certified local producers can quickly improve their competitive standing vs. established import supply chains.
Recent developments that change strategic calculus
-
Strategic licensing partnerships between glass-engineering firms and local contract manufacturers have lowered the technical barrier to producing premium tempered glass protectors, creating pathways for new supply onshore.
-
National standards and first-of-kind certifications in certain markets are creating preferential conditions for domestic producers and altering sourcing decisions for regional retailers and distributors.
-
Trade and intellectual property disputes surfaced in late 2025 and early 2026 underscore the need for legal/market intelligence as part of any market-entry or scale-up strategy.
Practical, report-backed actions for 2026
For leaders preparing near-term strategies, the research supports a set of pragmatic initiatives that balance offensive growth and defensive resilience:
-
Prioritize materials partnerships: Secure access to engineered glass and differentiated coating technologies either through licensing, long-term supply contracts, or equity stakes in strategic suppliers.
-
Execute a two‑track manufacturing playbook: localize production in high-growth, politically sensitive markets while preserving global-scale, low-cost capacity for high-volume SKUs.
-
Differentiate through certification and warranty: Use third-party standards and extended warranty offerings to reduce price sensitivity and raise switching costs among B2B and retail customers.
-
Optimize channel mix: Rebalance SKU portfolios between direct-to-consumer, retail partnerships and OEM supply, using data-driven SKU profitability models to guide investments.
-
Implement regulatory early-warning: Build a monitoring function to track trade filings, standards updates and certification regimes that can affect access to specific product features or markets.
-
Prepare portfolio M&A playbooks: Identify targets across the value chain—materials specialists, contract manufacturers, and regionally certified manufacturers—that accelerate capability capture with minimal integration risk.
What the PW Consulting report delivers (operationally useful outputs)
Our full study translates market sizing and trend analysis into tools that teams can act on immediately. Deliverables include:
-
Granular historical and forecast market sizing (global and by segmentation), with downloadable models that support scenario testing.
-
Price and margin benchmarking for material types, distribution channels and regional cost stacks.
-
Supply‑chain maps that identify critical suppliers, single‑source dependencies, and alternative sourcing options for engineered glass and specialty films.
-
Commercial diligence templates and acquisition screening criteria focused on synergy capture and integration risk mitigation.
-
Channel and SKU optimization playbooks, including retailer negotiation frameworks and D2C acceleration tactics.
-
Regulatory timeline and risk matrix aligned to litigation and standards events—enabling legal teams to prioritize scenarios and contingency plans.
Decision frameworks and KPIs to operationalize the insight
Turning insight into execution in 2026 requires a compact set of KPIs and decision triggers. We recommend teams align against three horizons:
-
90‑day play: validate supplier/partner options, secure conditional letters of intent for premium glass, and test one certified SKU in a controlled market.
-
12‑month play: establish localization or co-manufacturing arrangements where certification regimes favor domestic producers, and recalibrate SKUs across channels to prioritize margin density.
-
24+ month play: consolidate market positions through strategic acquisitions or exclusive licensing, while hedging regulatory exposure through diversified routing and legal preparedness.
Core KPIs should include SKU-level gross margin, channel contribution margin, lead time variability for critical materials, and certification-compliance time to market.
Risks you cannot afford to ignore
-
Regulatory shocks and trade disputes can ripple through the value chain and create abrupt winners and losers. Scenario planning must be quantitative and updated quarterly.
-
Material concentration risk—particularly in premium engineered glass—creates supplier power that can compress margins if not mitigated through long-term contracts or alternative materials research.
-
Commoditization in entry-level tiers will pressure volumes and unit economics, necessitating a clear differentiation and up-sell strategy for higher-value offerings.
Conclusion — how to use this brief
For executives who must allocate capital and attention in 2026, our research converts the broad market growth story into operationally relevant choices: where to invest in materials and manufacturing, how to defend brand and channel economics, and how to build optionality against regulatory headwinds. The macro picture—robust growth and premiumization—creates meaningful upside for players who act decisively on supply partnerships, certification-led differentiation and targeted localization. At the same time, episodic regulatory and trade events demand that strategy teams keep contingency pathways open and measurable.
PW Consulting’s full Screen Protector Market report contains the detailed segmentation tables, country-level analysis, supplier scorecards, and downloadable models that senior teams use to make final investment decisions. To review the complete dataset and our proprietary scenario models, please access the full report on our website or contact your PW Consulting analyst for a private briefing.
For detailed analysis of this topic, please visit the official page: Screen Protector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sodium Sulfide Market — 2026 Strategic Preview for Corporate Decision-Makers
As PW Consulting’s senior strategy advisor and lead industry analyst, I present this executive preview of our Sodium Sulfide Market research. The document below is a deliberately concentrated briefing designed to demonstrate analytical depth while reserving the full, transaction-grade datasets and segment-level tables for subscribers. Consider this a professional “trailer”: clear on direction, rigorous in logic, and intentionally opaque on granular segmentation so that your team will consult the full report to operationalize strategy.
Sodium Sulfide Market
Headline market context
The sodium sulfide market has shown steady recovery and disciplined expansion since 2020, rising from roughly USD 825 million in 2020 to about USD 1,020 million by the base year of 2025. Under our central forecast (base year 2025; forecast period 2026–2032), the market is projected to grow at a compound annual growth rate (CAGR) of approximately 5.75%, reaching an estimated USD 1,545 million by 2032. The near-term transition from 2025 to 2026 continues that trajectory with market value crossing roughly USD 1,090 million in 2026 under current assumptions.
Sodium Sulfide Market
Why this research matters for 2026 decisions
- Capital allocation: The market’s mid-single-digit CAGR supports selective capacity investments, but only where feedstock security and regulatory alignment are demonstrable.
- Procurement and sourcing: Volatility in sulfur and caustic feedstocks necessitates sourcing resilience—this report maps realistic hedging and contract structures.
- M&A and partnership screening: The industry displays concentrated incumbency dynamics that create acquisition arbitrage and bolt-on opportunities; we provide a pragmatic target scoring framework.
- Regulatory compliance and risk management: New classifications and export controls materially affect shelf-life, transportation and storage economics—our regulatory tracker turns those changes into action steps.
- Commercial strategy: Product-differentiation pathways (low-dust, battery-grade, high-purity) are now value pools; the report quantifies margin implications and go-to-market tradeoffs.
Market trajectory and strategic implications
The market’s increase from 2020 to 2025 and the forecast to 2032 reflects a combination of legacy industrial demand and selective new use-cases. Growth is not uniform: mature applications continue to underpin baseline demand while industrial modernization, specialty grades, and environmental remediation create incremental premium volume. The projected CAGR of 5.75% is neither a runaway expansion nor a flatline—this is a planning horizon that rewards choices which balance scale with optionality.
Sodium Sulfide Market
Two structural implications follow for 2026 planning:
- Scale matters, but specialization pays: Firms with the ability to produce differentiated grades (e.g., low-dust prill, battery-grade, high-purity) can capture premium margins without requiring proportionate increases in working capital.
- Concentration creates leverage: The market exhibits a moderately high concentration among the top suppliers (CR3 approximately 68%; CR5 approximately 79.5%). For buyers, this concentration raises the premium on competitive tender design and multi-sourcing. For sellers, it creates islands of pricing power but also attracts regulatory and reputational scrutiny.
Supply-side dynamics and feedstock exposures
Operational risk in sodium sulfide production is rooted in two feedstocks: elemental sulfur and caustic soda. Global sulfur availability is sensitive to refinery throughput and commodity trade policy—recent geopolitical moves, including extended sulfur export restrictions from key exporters, have demonstrated how supply-side shocks transmit to production costs. In parallel, hydrogen sulfide prices have been comparatively stable through late 2025, but regionally differentiated refinery outputs mean localized price pockets can appear quickly.
Regulation is an equally tangible input cost. Sodium sulfide and related alkali sulfides are increasingly subject to hazardous material classification and concentration-based limits in multiple jurisdictions (for example, recent draft assessments in Canada and tightened hazardous-handling frameworks globally). These regulatory shifts increase compliance capex, constrain storage/transport configurations, and expand end-to-end liability profiles—factors that should be embedded in any 2026 capex or market-entry business case.
Competitive landscape — positioning and recent moves
The competitive set features a mix of global chemical majors, regional industrial producers, and specialty high-purity suppliers. Their strategic postures fall broadly into three buckets: scale incumbents, specialty-grade suppliers, and regional cost players. Recent industry developments illustrate these strategic choices in practice:
- Capacity expansions and automation: Several established players completed or commissioned capacity upgrades and automated product lines to reduce dust and improve handling; these moves compress the commercial window for new entrants targeting conventional grades.
- Product-grade migration: Market leaders are investing in battery-grade and clean-room production for high-purity sodium sulfide, aiming to link into adjacent value chains that command higher margins but require stricter quality control.
- Regional capacity shifts: Select manufacturers in Asia have scaled volumes to serve local manufacturing needs, while European and North American players leverage product differentiation and compliance capabilities.
For executive teams evaluating competitive exposure, the implication is clear: scale without differentiation will face margin pressure; differentiation without supply robustness will face reliability issues. The full report contains supplier profiles, capacity maps, and an actionable competitor matrix that aligns capabilities to the commercial opportunities we identify.
What the full report contains — practical, transaction-grade tools
This preview cannot and should not replace the full report, which is designed for immediate operational use. Key actionable deliverables included in the full research package are:
- Demand model (2020–2032) with scenario toggles for upside/downside industrial recovery paths.
- Price deck and cost curve mapping that integrates sulfur and caustic price sensitivity, freight, and regulatory compliance costs.
- Supplier scorecards and a five-tier risk assessment (commercial, operational, geopolitical, environmental, regulatory).
- Detailed M&A screening matrix and valuation sensitivity outputs for bolt-on and greenfield options.
- Procurement playbook including term structures, indexation clauses, and logistics-contingency templates.
- Regulatory tracker with jurisdictional actions and required remediation timelines for hazardous-handling compliance.
- Commercial negotiation checklists and an integration roadmap for buyers of production assets or offtake contracts.
Because of the preview nature of this document, granular segmentation tables (regional, product-grade, and end-use application percentages and values) are not presented here. Those tables are included in the subscriber package and are essential for transaction execution and contract negotiation.
Priority recommendations for 2026 decision-making
- Lock feedstock optionality: Pursue a mix of long-term sulfur purchase agreements, strategic inventory buffers, and collaboration with roasters/refineries to mitigate export-control shocks.
- Invest selectively in product-differentiation: Prioritize low-dust prill or high-purity lines if downstream customers can support premium pricing and long-term offtake commitments.
- Design flexible capacity: Modular or semi-modular expansions reduce downside exposure in a market with measured CAGR and episodic supply shocks.
- Embed regulatory cost into pricing models: Build predictable pass-through mechanisms or contractual risk-sharing to avoid margin erosion from compliance-driven cost increases.
- Screen M&A targets with a two-track lens: immediate cash-flow uplift plus strategic optionality (e.g., access to specialist products, niche geographic coverage, or feedstock security).
- Operational excellence and ESG: Implement storage, transportation, and waste-handling upgrades early—these reduce both compliance risk and insurance costs while improving buyer confidence.
How PW Consulting can accelerate your 2026 agenda
Our sodium sulfide practice offers bespoke combinations of market intelligence and deal execution support: transaction-grade valuation models, supplier negotiation teams, regulatory compliance roadmaps, and integration management offices for acquired assets. We also deliver rapid scenario-modelling workshops that embed your corporate KPIs (inventory turns, working capital limits, capex thresholds) against the report’s demand and price scenarios.
This briefing is a concentrated orientation. For the complete intelligence set—full regional and application-level segmentation, supplier capacity tables, transaction-ready valuation models, and the regulatory tracker—please consult the primary report page. PW Consulting’s full dataset is designed to convert the 5.75% CAGR narrative and the projected market scale into executable 2026 strategies.
Contact PW Consulting to schedule a focused briefing with our sodium sulfide team. We will walk your executives through the dataset, tailor scenario analyses to your balance sheet, and outline an implementation timeline for the next 12 months.
For detailed analysis of this topic, please visit the official page: Sodium Sulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tetrabromobisphenol-A (TBBPA/TBBA) Market 2026 Strategic Brief — What Chief Executives and Supply-Chain Heads Need to Know
PW Consulting’s market study on Tetrabromobisphenol-A (TBBPA/TBBA, CAS 79-94-7) is designed to be a practical decision-support tool for boards, investment committees, and executive teams planning through 2026 and beyond. Built on a 2020–2025 historical base and anchored at a 2025 base year, the analysis projects the market across a 2026–2032 forecast window and quantifies a steady mid-single-digit expansion with a compound annual growth rate of 5.1%. Our modelling captures both cyclical drivers and structural trends that will determine supplier economics, demand mix, and competitive positioning over the next planning cycle.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
Market Trajectory — A concise snapshot
- Historical momentum: The TBBPA market expanded from an estimated USD 850 million in 2020 to approximately USD 1,075 million in 2025, reflecting recovery dynamics and reorientation of electronics and industrial supply chains.
- Near-term inflection: PW’s central forecast anticipates the market crossing roughly USD 1.13 billion in 2026 and continuing to expand to about USD 1.52 billion by 2032 under our base-case assumptions.
- Structural growth rate: A 5.1% CAGR over the forecast horizon implies sustainable demand growth but one that is highly sensitive to raw-material cycles, regulatory signals, and product substitution risk.
Why this study matters for 2026 corporate decision-making
- Prioritise capital allocation with confidence — Our integrated forecast and scenario tool links demand pathways to margin outcomes so CFOs can sequence capacity investments, retrofit CAPEX for low-emission grades, or delay brownfield expansions with quantified trade-offs.
- De-risk procurement and margin volatility — The report quantifies the exposure to bromine feedstock cost swings and TBBPA spot-price volatility observed in 2024–2025, enabling procurement teams to model collar and forward buying strategies versus the economics of backward integration.
- Navigate regulatory complexity — Recent regulatory actions (notably the US EPA’s August 2025 TSCA test rule requiring fate-and-transport testing and EFSA’s July 2024 dietary assessment update) materially change compliance timelines and testing budgets for manufacturers and processors. Our regulatory matrix maps obligations, lead times, and enforcement risk across jurisdictions, so legal and compliance teams have a clear roadmap into 2026.
- Shape go-to-market strategies — Product managers and commercial teams can use our demand archetypes and customer-propensity models to prioritize product development (e.g., low-emission grades for electronics, formulations for polycarbonates or epoxy systems) and shape commercial incentives that protect price realization.
What the report delivers (practical scope)
- Comprehensive market sizing and triangulated forecasts (2020–2032) with transparent assumptions and sensitivity bands.
- Segmentation frameworks by product chemistry, application and geography together with qualitative demand drivers — note: detailed segment tables and client-only worksheets are available on the source page to preserve competitive confidentiality in this preview.
- Supply-side analysis: capacity maps, utilization dynamics, and a cost curve that explicitly incorporates bromine feedstock movements and processing differentials.
- Price and margin analytics: historical spot ranges, producer lift-and-pressure scenarios, and break-even pricing for different production footprints.
- Regulatory matrix and impact simulations: scenario-led implications of major policy moves, including testing obligations and potential restrictions, with estimated compliance costs and time-to-market impacts.
- Competitor benchmarking and strategic heatmaps focused on vertical integration, regional footprint, product portfolio breadth, and sustainability positioning.
- Transaction support: valuation overlays, target screening, and integration risk checklists for M&A or JV activity in the TBBPA value chain.
Competitive landscape — strategic takeaways
The market exhibits moderate concentration (CR3 ~34.2%, CR5 ~36.8%), signalling a landscape where a small group of vertically integrated players exert meaningful influence but where secondary suppliers and regional manufacturers continue to shape pricing dynamics and service capabilities.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
- Albemarle Corporation — Strengths lie in bromine vertical integration, diversified production footprint spanning the United States and Asia, and product differentiation through low-emission grades targeted at electronics and polycarbonate markets. For incumbents, Albemarle’s position highlights the strategic value of integrated feedstock control and compliance-ready product lines.
- ICL Industrial Products — As one of the larger bromine-based producers, ICL’s recent capacity investments in Israel and Europe position it to serve printed-circuit and other flame-retardant markets at scale. Their moves underscore the importance of capacity timing aligned to customer lead times.
- Jordan Bromine Company — Focused on bromine recovery and incremental expansions, Jordan Bromine illustrates how lower-cost feedstock sources plus efficient recovery can be a defensible basis for a cost-competitive export strategy.
- Shandong Moris Tech & Shandong Tianyi Chemicals — Chinese manufacturers remain significant supply-side actors, especially for epoxy-resin and printed-circuit applications. Their integrated production and export orientation exert pricing pressure and offer fast-to-market responsiveness; however, buyers must balance cost advantages against regulatory-compliance and logistics risk in cross-border supply chains.
Recent developments that change the playbook
- Regulatory: The US EPA finalized a TSCA test rule (Aug 2025) requiring testing for fate and transport — a new compliance cost and data obligation for manufacturers and processors that shortens lead times for product registrations in the US market.
- Regulatory: EFSA’s July 2024 scientific opinion updated dietary risk assessment and concluded no concern for dietary exposure under current occurrence data — a stabilizing signal for markets with food-contact adjacency concerns.
- Regulatory: The European Commission’s December 2024 withdrawal of its RoHS restriction proposal reduced immediate regulatory tail-risk in the EU but does not eliminate future scrutiny — companies should factor in episodic policy shifts when modelling long-term demand.
- Raw-material volatility: Bromine feedstock in 2024 averaged in the mid-thousand USD per MT range and rose ~18% year-over-year amid extraction and logistics constraints; spot TBBPA prices showed wide monthly ranges. These dynamics materially steer margin sensitivity and point to the financial value of de-risking strategies.
Actionable recommendations for 2026 planning
- Immediate compliance investment: Allocate testing and data-collection budgets to meet TSCA obligations and preempt market access delays. Prioritise key SKUs and high-volume processing sites for initial testing to preserve commercial continuity.
- Secure feedstock: Negotiate multi-year bromine contracts with flex provisions or evaluate backward integration where feasible; build feeder-stock buffers into working-capital models to blunt short-term price spikes.
- Differentiate via low-emission and compliance-ready grades: Invest in product certification and customer trials for electronics and automotive OEMs that are increasingly procurement-savvy on chemical footprints.
- Commercial contract redesign: Update pass-through clauses, indexation mechanisms, and force-majeure language to reflect raw-material and regulatory risks exposed since 2022–2024.
- M&A & partnerships: Target bolt-on assets that add regional logistics resilience, bromine recovery capabilities, or formulation IP, rather than solely capacity—these provide quicker returns in a moderately concentrated market.
Scenario outlook and sensitivity focus
Under PW Consulting’s base case (5.1% CAGR), the market steadily expands to ~USD 1.52 billion by 2032. Our alternate scenarios—stressed (regulatory tightening + raw-material shock) and upside (accelerated electronics demand and substitution economics favouring TBBPA formulations)—are provided in the report’s modelling workbook so executives can stress-test balance-sheet and pricing decisions. Key sensitivity levers in all scenarios are bromine feedstock costs, spot-price amplitude for TBBPA, and the speed of regulatory data generation and enforcement.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
Next steps — how to use this brief
- Download the full study for client-only access to the granular segmentation tables, regional and application breakdowns, and the Excel-based forecast and scenario models that underpin the figures cited here.
- For leadership teams seeking an executive workshop, PW Consulting offers a 90–120 minute briefing that applies the report’s scenarios to your specific cost base, contract terms, and growth targets — producing a tailored action plan for 2026 capital and commercial priorities.
PW Consulting’s TBBA market research is calibrated to inform decisive action in 2026: from where to invest, whom to partner with, and how to hardwire regulatory resilience into commercial models. If your mandate includes procurement, plant rationalization, or M&A activity in flame-retardant chemistries this year, this study is engineered to convert market intelligence into executable strategy.
For detailed analysis of this topic, please visit the official page: Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MP3 Player Market to reach USD 339.05 Million by 2032 at 1.12% CAGR — PW Consulting
By pmarketresearch, 2026-07-30
MP3 Player Market — 2026 Strategic Preview for Corporate Decision-Makers
Executive preview
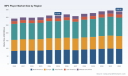
As companies prepare strategic plans for 2026, understanding the MP3 player market’s realistic trajectory is essential for capital allocation, product roadmaps, and go‑to‑market tactics. PW Consulting’s latest study uses a 2025 base year and a 2026–2032 forecast window to deliver a pragmatic, decision‑grade picture. Historically the market has been stable but mature: the total market value moved from roughly USD 293 million in 2020 to approximately USD 312 million by 2024–2025. Under our central projection the market edges higher to about USD 320 million in 2026 and grows at a measured compound annual growth rate (CAGR) of 1.12% through 2032, reaching roughly USD 339 million at the end of our forecast horizon.
MP3 Player Market
Those headline numbers tell a simple story: this is a small, steady market where incremental moves—product differentiation, cost efficiency, and targeted channel strategies—drive success more than mass market disruption. The market concentration metrics underline that reality: the top three players account for roughly 24.6% of the market and the top five for around 26.2%, indicating a fragmented competitive landscape with numerous niche players and localized specialists.
MP3 Player Market
Why this research matters for decisions made in 2026
-
Capital deployment and portfolio pruning: With modest overall growth, CFOs and product leaders must be precise about where to invest. Our study identifies where incremental investments return disproportionate strategic value and where divestment or licensing is the superior option.
MP3 Player Market -
Product roadmap prioritization: Component shortages, battery regulation and codec licensing create windows where differentiated hardware can command premiums. We show which technical trade‑offs (storage, DACs, battery capacity, UI) matter most to the remaining buyer cohorts.
-
Channel & pricing optimization: The market’s fragmentation rewards nimble channel strategies. The report supplies actionable playbooks for balancing direct digital channels, retail partnerships and specialist audio outlets, and for calibrating price tiers to elasticity profiles.
-
M&A and partnership scouting: Low concentration implies opportunities to consolidate cost bases or acquire IP and niche brand equity. We highlight the types of targets and the value levers—cost synergies, distribution, firmware/IP—that make acquisitions accretive.
What the PW Consulting report delivers — practical content
This is not a theoretical exercise. The report is an operational toolkit for leaders taking real decisions in 2026:
-
Proprietary market model (2020–2032): a flexible, drill‑down financial model calibrated to observed historical volatility and multiple demand scenarios. The model is parameterized to run sensitivity tests—price, replacement cycles, streaming penetration—without exposing the confidential segmentation outputs in this preview.
-
Scenario playbooks: three near‑term and two structural scenarios that test combinations of supply constraints, component price shocks, and changes in consumer preferences; each scenario is accompanied by prioritized mitigations and opportunity capture actions.
-
Commercial playbooks: go‑to‑market templates for premium niche devices, volume value models and bundled offerings with streaming or accessories; includes suggested margin targets, channel mixes, and promotional cadences.
-
Cost and supply chain heatmaps: bill‑of‑materials sensitivity analyses, alternate sourcing options, and an assessment of strategic component obsolescence risks (connectors, codecs, battery chemistries).
-
Competitive dossiers and capability maps: in‑depth profiles of leading OEMs and challenger brands, with capability matrices across engineering, software/firmware, distribution and brand equity. (Note: the report contains detailed segmentation matrices that are intentionally summarized in this preview to protect the value of the full analysis.)
-
Consumer cohort archetypes and journey maps: data‑backed profiles of remaining buyer segments and their purchase triggers, retention levers and accessory lifetime spend patterns—designed to inform creative briefs and channel plans.
-
Decision frameworks for M&A and partnerships: checklists and valuation adjustments tied to synergies typical in this market (manufacturing scale, distribution consolidation, and IP cross‑licensing).
Competitive landscape — what to watch from core players
-
Sony Corporation (Tokyo, Japan) — Sony continues to leverage its brand and audio heritage through dedicated digital audio products such as the NW‑A306 Walkman series. Sony’s strengths are product design, audio tuning expertise and an ecosystem approach that links hardware to content and peripherals. For 2026, Sony’s strategic choices will likely center on maintaining premium margins through product differentiation (audio components, form factor, brand cachet) while defending against low‑cost competitors. For partners and rivals, Sony represents both a benchmark and a white‑space target for differentiated co‑branding or tech licensing.
-
Samsung Electronics Co., Ltd. (Suwon, South Korea) — Historically present with legacy and portable media offerings, Samsung’s role in this specific market is more strategic than scale‑dominant. Samsung brings supply‑chain muscle, component integration capabilities and distribution reach. Its presence raises the bar on manufacturing efficiency and feature sets; smaller competitors should anticipate competitive pressure on component sourcing and can respond by specializing or pursuing partnerships that lock in supply chain advantages.
-
Creative Technology Ltd. (Singapore) — As a specialist in portable media players and consumer audio, Creative’s strengths include focused product portfolios, niche audio innovation and community awareness. For companies evaluating competition, Creative exemplifies a viable specialist strategy: defend a set of audio‑focused use cases, cultivate loyal customers and monetize through accessories and content partnerships rather than pure hardware scale.
Market structure and strategic implications
The market’s low top‑player concentration (CR3 ~24.6%, CR5 ~26.2%) signals an environment where differentiation, channel relationships and cost control matter more than broad share grabs. Key implications for 2026 decisions:
-
High opportunity for niche value capture: focused devices that serve specific use cases (audiophile, sport, children’s content) can generate healthy margins even in a small market.
-
Consolidation is selective: broad roll‑up strategies risk integration complexity without clear cost synergies. Targeted acquisitions that secure distribution or unique IP are higher‑value.
-
Pricing discipline is essential: with modest overall growth, price erosion can quickly undermine profitability. Dynamic pricing and bundled value propositions are superior to headline discounting.
-
Supply chain agility wins: whoever can flex BOM costs and secure long‑lead components at scale will sustain margin advantages when component cycles turn negative.
Strategic recommendations for 2026 decision‑makers
Below are prioritized actions to convert insight into outcomes in the coming 12–36 months:
-
Short term (0–12 months) : Tighten SKU portfolios to highest ROI variants; implement an immediate cost‑to‑serve audit across channels; negotiate conditional component commitments that preserve margin in low‑growth scenarios.
-
Medium term (12–24 months) : Launch one or two differentiated products aimed at defensible niches (e.g., audiophile portable device or child‑oriented durable device) with clear attach rates for accessories and services; formalize selective distribution partnerships in high‑value channels.
-
Longer term (24–36 months) : Consider targeted acquisitions for distribution or firmware/IP that accelerate time‑to‑market; evaluate subscription or content bundling models that lock in customer lifetime value beyond hardware sales.
-
Cross‑cutting : Embed scenario planning into annual budgeting—use an updated market model to test +/- 20% swings in component cost and a range of demand elasticity assumptions. Prepare a rapid response playbook for regulatory or codec‑licensing shifts that could materially affect BOM economics.
How to use the full PW Consulting study
This preview demonstrates the analytical depth and practical focus of our MP3 player market study while intentionally withholding core segmentation matrices and confidential granular allocations. The full report gives purchasers access to:
-
The interactive 2020–2032 model with scenario toggles.
-
Granular segmentation outputs and regional dashboards suitable for channel planning and P&L impact analysis.
-
Detailed competitor benchmarking, including product feature comparisons, margin proxies and distribution maps.
-
Templates for term sheets, integration checklists for M&A targets, and vendor negotiation scripts for securing components under multi‑year contracts.
In a mature, niche market where incremental strategic moves create outsized returns, PW Consulting’s MP3 Player Market study is designed to be a practical companion for 2026 decision cycles. If your team is preparing budgets, product plans, or M&A pipelines for the coming year, this research will sharpen choices, quantify risks and highlight the most economical paths to sustainable advantage.
For detailed analysis of this topic, please visit the official page: MP3 Player Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hot Stamping Foil Market to Reach USD 2,859.7M by 2032 at 5.7% CAGR
By pmarketresearch, 2026-07-30
Hot Stamping Foil Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
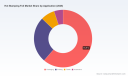
By the close of our 2025 base year the global hot stamping foil market sits at just under USD 2.0 billion and is set on a steady growth trajectory. PW Consulting’s modeling shows a mid-single-digit compound annual growth rate (CAGR) through the 2026–2032 forecast window, producing a market north of the USD 2.8 billion mark by the end of the period. That steady expansion masks important inflection points — regulatory deadlines, material innovation cycles and selective consolidation — that will determine winners and losers in the next two to three years. This short briefing explains why the 2026 planning cycle is a pivotal moment for manufacturers, brand owners and strategic investors, and what the full PW Consulting study provides to de-risk choices made this year.
Hot Stamping Foil Market
Why 2026 is a decisive year
-
Regulatory cliffs and recyclability deadlines are compressing time-to-market for sustainable foils. European and Japanese packaging mandates are accelerating demand for thinner, recyclable carriers and solvent-free formulations. These rules convert what was once a product-differentiation conversation into a commercial imperative for many converters and brand owners.
Hot Stamping Foil Market -
Technology substitution and materials R&D — from aluminum-layer optimization to bio-based carriers — are moving from pilot to commercial scale. Leading suppliers have recently committed substantial R&D resources to sustainable carriers and digital foiling capabilities, and those investments will start to reshape cost curves and qualification timelines between 2026 and 2028.
Hot Stamping Foil Market -
Market structure is neither atomized nor monopolistic. The market concentration metrics show a mid-range consolidation: the top-three suppliers control a significant share, and the top-five approach a commanding majority of market activity. This arrangement produces both opportunity (large-scale partnerships, platform plays) and risk (supply bottlenecks for specialized grades).
Strategic implications for corporate planning
Executives making capital, procurement, or M&A decisions in 2026 should treat hot stamping foil not as a low-margin commodity but as a portfolio of differentiated technologies with separate risk/reward profiles. Our research highlights four practical lenses to evaluate near-term choices:
-
Supply resilience and qualification timelines — assess your tier-1 foil suppliers not only by price, but by their validated recyclable grades, lead times for qualification on specific substrates (paper, PET, PU leather, industrial plastics), and the location of critical coating capacity.
-
Regulatory-aligned product roadmaps — prioritize partner and in-house development efforts that reduce solvent use, enable thinner carrier films, or replace aluminum in applications where recycling streams are constrained.
-
Customer-facing differentiation — for brand owners, foiling remains a high-impact, low-volume visual differentiator. The economic calculus for premium packaging must now explicitly include recyclability claims and the carbon cost of foil options.
-
M&A and partnership playbooks — the market’s concentration profile favors targeted bolt-on acquisitions (to secure specialty grades or regional capacity) and strategic alliances (for co-development of recyclable carriers and digital foiling platforms).
Competitive landscape — what to watch
The competitive set includes long-established European and Japanese technology houses, North American specialty producers, and sizeable Asian coating and converting players. Each group brings a distinct strategic emphasis that informs how they will shape supply and innovation through 2026 and beyond:
-
Legacy European and Japanese innovators continue to lead on decorative performance and premium grades, pairing decades of process know-how with accelerated sustainability roadmaps. Their strength is in premium brand relationships and specification-level acceptance.
-
North American firms emphasize application breadth — industrial laminates, medical packaging, and label systems — and often combine foil offerings with adhesive and laminating technologies, creating integrated solutions for OEMs and converters.
-
Asian suppliers are expanding capacity and product breadth rapidly. Their competitive advantage lies in scale manufacturing and cost-competitive formulations, and an increasing focus on quality and certified recyclable grades.
Recent strategic moves illustrate the market dynamics: there has been acquisition activity aimed at combining color breadth and automatic stamping machinery with plastic decoration expertise — a playbook that accelerates market access for recyclable and digital-capable foils. For companies evaluating supply relationships, our full report maps each major player’s technology strengths, geographic footprint, and recent corporate development activity to identify viable partners or takeover targets without exposing confidential contract-level detail in this preview.
Technology, materials and regulatory dynamics
Three converging forces will define the product roadmap for hot stamping foils over the next investment cycle:
-
Material engineering: aluminum-based metallization remains the dominant visual technology, but alternatives (aluminum-free pigments, modified barrier layers, and bio-based carriers) are commercializing rapidly. Qualification of new carriers against industry recycling streams is the gating item for widespread adoption.
-
Regulatory pressure: emerging packaging regulations in major markets mandate higher recycled content and defined recyclability thresholds within a fixed timeframe. These mandates change supplier selection criteria and accelerate the retirement of legacy foil grades that interfere with polymer-recycling streams.
-
Digitalization: hot stamping is intersecting with digital finishing techniques (digital foiling, variable-data holography) enabling new use cases for security, personalization and brand engagement. The commercial winners will integrate foils, digital print partners, and finishing equipment to shorten customer adoption cycles.
What PW Consulting’s full report delivers (practical outputs)
PW Consulting’s comprehensive Hot Stamping Foil Market study is structured to be actionable for commercial, sourcing and corporate development teams. Highlights include:
-
Granular market sizing and scenario forecasts across a multi-year horizon, with sensitivity analyses that isolate the impact of raw material volatility, regulatory adoption timelines, and substitution rates for alternative carriers.
-
Supply-chain maps that identify choke points for critical raw materials and coating capacity, and a supplier heat map combining technical capability, geographic advantage and sustainability readiness.
-
Commercial playbooks for brand owners and converters: specification checklists, testing protocols and a vendor selection framework that prioritizes recyclability and total cost of ownership over unit price alone.
-
M&A and investment appraisals: scored acquisition targets, integration risk checklists and illustrative valuation ranges based on growth pathways and technology synergies.
-
Operational benchmarks: capital expenditure guidance for foil coating and converting lines, throughput productivity metrics, and estimated payback windows for sustainability retrofits and automation investments.
-
Scenario-based regulatory impact assessments that translate policy milestones into revenue and margin implications for common product classes.
How senior leaders should use this intelligence in 2026
For CEOs and heads of strategy: use the report to align your portfolio bets — decide whether to prioritize premium decorative grades, recyclable mass-market foils, or integrated finishing solutions. For procurement and operations leaders: the supplier heat map and qualification timelines are tools to reconfigure sourcing strategies to reduce single-source exposure and accelerate trials of compliant grades. For corporate development teams: the M&A playbook unpacks what value looks like for bolt-on purchases versus capability acquisitions.
Why this preview — and what it omits
This briefing is designed as a “trailer”: it surfaces the strategic trends, competitive posture and the financial trajectory you need to prioritize 2026 decisions, while intentionally withholding the detailed segment-by-segment figures and proprietary modeling that PW Consulting provides to licensed clients. The full study contains the segmented demand curves, regional and application-level forecasts, supplier-level revenue estimates and price-mix modeling that underpin the summary conclusions presented here.
Final recommendation — actions for the next 90–180 days
-
Initiate supplier audits focused on recyclable-grade availability and qualification timelines; require sample-to-qualification schedules as part of any RFQ issued in 2026.
-
Prioritize pilot programs for aluminum-free or thin-carrier foils on strategically important SKUs where sustainability claims materially influence purchasing decisions.
-
Engage corporate development to build a shortlist of acquisition targets and alliance partners identified in the full report; act on time-limited opportunities created by recent consolidation.
PW Consulting’s Hot Stamping Foil Market study provides the complete empirical foundation and operational playbooks needed to convert the strategic imperatives described above into executed outcomes. For access to the complete dataset, supplier scorecards, and model-ready forecasts that support direct implementation, please consult the full report.
For detailed analysis of this topic, please visit the official page: Hot Stamping Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Public Transport & Rail EAM Market to Reach USD 412.77M by 2032 at 8.85% CAGR
By pmarketresearch, 2026-07-30
Enterprise Asset Management in Public Transport and Railways: Strategic Imperatives for 2026
As mobility networks continue to face rising demand, constrained budgets, and an accelerating technology frontier, Enterprise Asset Management (EAM) for public transport and railways has shifted from an operational enhancement to a core strategic capability. PW Consulting’s new market study — based on a 2025 base year and a 2026–2032 forecast horizon — quantifies this transition and provides a decision-ready roadmap for executives planning investments, procurements, and organizational change through 2026 and beyond.
Enterprise Asset Management Space in Public Transport and Railways Market
Market trajectory: why 2026 is an inflection point
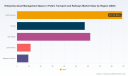
The EAM market serving public transport and railways has been expanding steadily through the first half of the decade and enters a phase of accelerated deployment. Our modelling, grounded in operator deployments, vendor product cycles, and regulatory drivers, shows a continuation of strong growth from the 2025 baseline into the 2030s. The study projects this segment to grow at an annualized pace consistent with a mid-single-digit to high-single-digit CAGR across the forecast window, reflecting broad adoption of cloud platforms, predictive maintenance capabilities, and integrated infrastructure management modules.
Enterprise Asset Management Space in Public Transport and Railways Market
What makes 2026 pivotal is the convergence of three forces: (1) an increasing regulatory and safety mandate for certified digital asset management and audit trails; (2) pragmatic ROI cases emerging from pilot-to-scale transitions; and (3) modernization programs that prioritize digital-first maintenance strategies over legacy, reactive models. Together, they create a near-term window in which investments yield disproportionate operational and financial returns.
Enterprise Asset Management Space in Public Transport and Railways Market
What this means for enterprise decision-makers
- Prioritize compliance-driven upgrades: Regulatory frameworks and safety directives in major markets now require continuous evidence of asset lifecycle management. EAM systems that deliver certified audit trails and regulatory reporting should be treated as minimum viable capabilities, not premium add-ons.
- Treat EAM as a business transformation program: Successful deployments blend technology adoption with process redesign, workforce reskilling, and supplier ecosystem changes. Procurement decisions should weight change management frameworks and integration services as highly as software feature lists.
- Favor outcomes over features: Procurement evaluations should emphasize measurable operational KPIs — availability, mean time to repair, lifecycle cost per asset, and safety incident reduction — rather than headline module counts.
- Plan for hybrid architectures: Cloud-native delivery is reducing on-site staffing needs and accelerating analytics maturity, but many operators will need hybrid configurations to satisfy latency, sovereignty, or legacy interface constraints.
- Embed data governance and security: EAM platforms are now custodians of operational, safety, and passenger data. GDPR, ISO 55000 expectations, and sector-specific privacy rules require a defensible security posture and clear data ownership models.
- Invest in predictive capabilities intelligently: Not every subsystem benefits equally from AI-driven prediction. Prioritize predictive maintenance where failure modes are well characterised and data quality is sufficient to support reliable models.
How PW Consulting’s report supports 2026 decisions
Our study is designed as a pragmatic decision tool for 2026 planning cycles. The report does not simply map vendor logos and technology taxonomy; it provides operationally oriented, actionable outputs that procurement, operations, and executive teams can apply immediately:
- Strategic roadmap templates for transitioning from reactive to reliability-centered maintenance (RCM), including sequencing of quick wins and medium-term modernization milestones.
- Vendor selection frameworks that weight technical fit, integration risk, implementation speed, and total cost of ownership (TCO) over a seven-year lifecycle.
- Implementation playbooks for phased rollouts across depots, corridors, and rolling stock fleets to minimize operational disruption.
- Standardized KPI and benchmarking sets tailored to rail and transit operations to track value capture and guide incentive structures.
- Procurement-ready requirement matrices and contract clauses that address data sovereignty, regulatory compliance, service-level agreements, and auditability.
- Case studies and evidence-based vignettes that demonstrate where investments generated measurable improvements in availability, safety, and unit operating cost.
Competitive landscape — who to watch and why
The vendor ecosystem serving public transport and rail EAM is a blend of specialized suppliers, large enterprise suites, and vertically-integrated engineering firms. While a limited set of established vendors commands significant mindshare, the market remains sufficiently open for challengers that combine domain expertise with strong implementation practices. In practice, top vendors are differentiated by three attributes: transportation-tailored content (workflows, inspection lists, regulatory templates), integration capability with signalling and traffic systems, and services depth for deployments at scale.
- Trapeze Group — Known for solutions explicitly designed for public transportation operators, Trapeze offers lifecycle visibility and regulatory-oriented workflows tailored to bus and rail fleets. Its strength is practical, operations-focused functionality that aligns with transit agency processes.
- Hexagon Asset Lifecycle Intelligence (HxGN) — Hexagon’s platform emphasizes transportation modules, predictive strategies, and data-rich monitoring. Recent platform updates and operator case studies demonstrate momentum in scaling EAM across mixed fleets and infrastructure assets.
- IBM (Maximo) — Maximo remains a go-to for large-scale infrastructure organizations that require proven enterprise capabilities, broad integration footprints, and mature safety and reliability toolsets. Oracle-style breadth combined with deep partner ecosystems is a core value proposition.
- Tyler Technologies — With a focus on the public sector and transit operators, Tyler’s EAM positioning stresses tight ERP integration and pragmatic deployment models suitable for government-funded agencies and regional authorities.
- IFS — IFS Cloud addresses asset-intensive operations with a particular emphasis on uptime and cost-per-unit metrics, increasingly integrating AI-driven maintenance support to reduce lifecycle costs.
- Arcadis Gen — Operating at the intersection of engineering and digital services, Arcadis Gen combines railway-specific digital twins and sustainability optimization with delivery capability, an attractive option for infrastructure programs that combine physical and digital upgrades.
Noteworthy recent developments underline how vendor differentiation is evolving. In late 2025 and early 2026 several high-profile milestones signalled market movement: Hexagon’s platform updates improved actionable operator insights; operator case studies documented successful network-wide transitions; and an engineering-led provider secured a significant ERTMS-related contract in Europe. These signals point to a market where technological refinement, verified deployments, and regulatory-aligned capabilities are accelerating vendor momentum.
Regulation, safety, and the compliance imperative
Regulatory pressure continues to be a dominant adoption driver. International and regional mandates — ranging from harmonized train control specifications to national safety agency guidelines — require asset management solutions to provide auditable, certifiable records across asset lifecycles. Expectations from bodies such as rail safety authorities and road transport regulators increasingly translate into procurement prerequisites rather than optional features. For 2026 planning, organizations must embed compliance checkpoints into their EAM selection and roll-out governance.
Operational dynamics: people, processes, platforms
- Workforce and labor cost considerations: Implementation and training for modern EAM systems require specialized labor inputs. Cloud-based delivery is lowering the need for extensive on-site technical staffing, but the transition still demands investment in capability uplift for maintainers and operations planners.
- Data privacy and governance: Systems must satisfy sector-specific privacy regimes and standards like ISO 55000. Data ownership, anonymization, and cross-border transfer rules should be clarified before procurement finalization.
- Integration with traffic management: Interfacing EAM with traffic, signalling (including ERTMS compliance pathways), and fleet telematics can unlock new reliability gains but increases integration risk. Architectural planning should sequence integration to reduce dependency-related rollout delays.
- Sustainability and lifecycle thinking: Asset management decisions increasingly intersect with decarbonization goals. Optimizing lifecycle emissions and energy consumption is now a differentiator when justifying capital and programmatic spend.
Five practical next steps for 2026 executives
- Validate regulatory gaps now: run a compliance gap assessment focused on audit trails and certified reporting requirements before drafting RFPs.
- Run a three-wave deployment plan: pilot, scale, embed — allocate budgets and KPIs for each wave to limit scope creep and to accelerate value capture.
- Include systems integrator capability in selection criteria: prioritize vendors with proven partner ecosystems that can manage complex cross-domain integrations.
- Design for data first: establish governance, retention, and security rules up front; ensure contractual language enforces those safeguards.
- Measure as you go: set baseline KPIs for maintenance cost, uptime, and safety events before deployment so that contract incentives and internal governance can reward realized improvements.
Conclusion — why this report matters for 2026
For transport and rail operators, 2026 represents a strategic inflection: the combination of regulatory tightening, proven operator use-cases, and maturing vendor capabilities enables a transition from tactical maintenance projects to enterprise-grade asset management programs. PW Consulting’s study synthesizes market sizing, growth trajectories, vendor positioning, regulatory impact, and practical implementation frameworks into a single, actionable guide tailored for executive decision timelines in 2026.
We present a depth of analysis sufficient to shape strategic direction while deliberately reserving granular segmentation figures and proprietary market-breakdown datasets for subscribers and report purchasers. If your organization is evaluating EAM investments, allocating capital for modernization, or preparing procurement cycles this year, the report will serve as a concise, operationally oriented blueprint to de-risk decisions and accelerate benefits realization.
For detailed analysis of this topic, please visit the official page: Enterprise Asset Management Space in Public Transport and Railways Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metakaolin Market to Reach USD 994M by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-30
Metakaolin Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
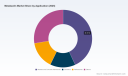
As PW Consulting’s senior industry analyst, I present a forward-looking briefing that distills the strategic implications of our full Metakaolin Market study for decisions to be made in 2026. The global metakaolin market has demonstrated steady expansion, rising from a baseline near USD 500 Million in 2020 to approximately USD 700 Million in our 2025 base-year estimate, and is forecast to grow through our 2026–2032 horizon to just under USD 1.0 Billion by 2032 at a compound annual growth rate (CAGR) of 5.2%. These headline metrics encapsulate both an enlarging addressable market and a durable adoption trend tied to infrastructure build programs and low‑carbon construction mandates.
Metakaolin Market
Why this matters for 2026 strategy
-
Portfolio positioning: Metakaolin is no longer a niche cement additive — it is becoming a specified material for durability and carbon reduction in major infrastructure projects. Firms that lock in the right product types and quality ranges in 2026 will secure premium specification slots through the decade.
Metakaolin Market -
Supply security: Production depends on high‑purity kaolin feedstock and energy‑intensive calcining; long‑lead investments in feedstock offtake, kiln capacity, or vertical integration materially shift cost curves and competitive posture.
Metakaolin Market -
Pricing discipline: Unit prices and plant economics are sensitive to energy and kiln utilization. Market signals in early 2025 showed US pricing near the high‑hundreds per metric ton range; buyers and sellers must bake energy volatility into multi‑year contracts.
-
Regulatory and specification advantage: Meeting ASTM C-618 / AASHTO M295‑11 Class N and demonstrating life‑cycle CO2 reduction creates differentiation in public procurement and sustainability‑led tenders.
-
M&A and partnership timing: The market’s relatively low top‑concentration (CR3 roughly mid‑20s percent) indicates fragmentation — a window where focused consolidation and vertical plays can unlock synergies and market share.
Market dynamics — what is driving the growth
The structural growth thesis rests on three pillars. First, infrastructure pipelines and sustainable construction policies are driving increased specification of supplementary cementitious materials that lower clinker intensity. Second, technical advances in high‑reactivity metakaolin production and consistent quality control make substitution more reliable for designers and contractors. Third, supply‑side moves — new calcining capacity, offtake agreements for kaolin feedstock, and targeted commercial launches — are reducing perceived scarcity, though cost differentials versus competing SCMs (fly ash, slag) remain material due to higher calcining costs.
Operationally, metakaolin production requires calcining kaolin at 650–750°C, which implies higher energy and operating costs compared with unprocessed SCMs; industry analyses indicate calcining‑driven production costs are materially above alternative SCMs. That cost premium, together with regional energy regimes and kiln efficiencies, shapes where producers opt to place new capacity and how they structure pricing and contractual terms with downstream customers.
What our full report delivers (practical, transaction‑ready content)
-
Granular market model (2020–2032) with scenario‑based demand drivers and an interactive forecast engine — note: this preview omits detailed segment tables reserved for subscribers.
-
Supply‑side mapping: mine-to-kiln network maps, capacity utilization curves, and a cost‑of‑production ladder that isolates energy, labor, and feedstock contributions to unit economics.
-
Price and contract playbook: calibrated price decks, benchmarking vs. fly ash/slag, and recommended contract clauses for energy pass‑throughs, force majeure, and quality variance.
-
Commercial go‑to‑market strategies: target client profiles, specification pathways (ASTM/AASHTO compliance), formulation trials playbook, and tendering templates for infrastructure procurement teams.
-
M&A & investment diligence toolkit: valuation comparables, integration checklists (feedstock, calcining assets, logistics), and a 100‑point ESG & permitting scorecard.
-
Case studies and pilot KPI templates: successful low‑carbon concrete projects and the laboratory‑to‑field scale up steps that minimize performance risk.
Competitive landscape and strategic moves to monitor
The competitive map is characterized by a mix of global mineral majors, regional specialists, and innovative challengers. Market concentration remains modest (CR3 approximately 24.6%, CR5 approximately 26.2%), which favors targeted consolidation and niche leadership rather than dominance by a handful of actors.
-
Imerys S.A. (France) — A global minerals player with branded metakaolin lines tailored to concrete and lime mortar systems. Imerys’ strength lies in integrated mineral handling and worldwide commercial channels that accelerate specification adoption in multinational projects.
-
Advanced Cement Technologies, LLC (USA) — Marketed PowerPozz™ emphasizes high reactivity, positioning the company for performance‑led segments such as high‑strength and pre‑cast concrete.
-
R‑E‑D Industrial Products (USA) — Offers Dynapoz under ASTM/AASHTO compliance claims; their emphasis on standards certification reduces adoption friction among engineering houses.
-
Burgess Pigment Company (USA) and Thiele Kaolin Company (USA) — Notably, Burgess’ announced acquisition of Thiele (March 2026) creates a vertically integrated specialty minerals platform with broadened metakaolin and kaolin portfolios, enhancing capture of both industrial and packaging applications.
-
SCR‑Sibelco N.V. (Belgium) — Focuses on high‑purity metakaolin for construction and industrial uses, leveraging large minerals distribution reach.
-
PORAVER GmbH (Germany) — Offers expanded glass alternatives that compete as lightweight, durable fillers — an innovation vector that buyers evaluate alongside metakaolin for specific use cases.
-
KaMin, Green360, Zeotech and others — Regional specialists and innovators: Green360’s commercial calcining run in 2025 and Zeotech’s large raw kaolin offtake agreement underscore a trend toward securing feedstock and scaling low‑carbon, high‑reactivity offerings.
Recent developments to watch: Burgess’ strategic acquisition (March 2026) signals consolidation and verticalization; Green360’s production ramp (mid‑2025) demonstrates rapid commercialization of sustainable supply; Zeotech’s multi‑year offtake (2025) emphasizes the importance of raw material contracts; and industry trade shows continue driving specification awareness.
Risk factors and mitigants for 2026 planners
-
Energy price volatility: Hedging strategies, fuel‑efficient kiln investments, and location choices tied to low‑cost energy can materially improve margins.
-
Feedstock concentration: Pursue diversified sourcing, DSOs (direct shipping ore agreements), and captive reserves where WACC and permitting permit.
-
Substitution and competition: Maintain product differentiation (e.g., high‑reactivity grades, certified performance) and monitor alternative materials such as expanded glass and geopolymers.
-
Regulatory shifts: Align product claims with ASTM/AASHTO and emerging sustainability reporting standards to avoid specification disqualification.
Recommended 2026 action plan (practical next steps)
-
Immediate (0–6 months): Initiate engineering trials with target concrete formulators; secure short‑term offtake pilots; model P&L sensitivity to energy and kiln utilization.
-
Medium (6–18 months): Negotiate medium‑term feedstock contracts or strategic minority investments into kaolin suppliers; evaluate brownfield upgrades to existing calcining assets to lower unit costs.
-
Strategic (18–36 months): Consider M&A targets that provide either proprietary high‑reactivity processing technology or logistics advantages; deploy commercial teams into prioritized infrastructure corridors where low‑carbon mandates drive specification.
How PW Consulting’s full study supports your 2026 decisions
This preview is purposefully calibrated to demonstrate analytical rigor while preserving detailed segment matrices, company financials, regional and application splits, and interactive dashboards for subscribers. The full study provides the executable artifacts you need to operationalize the strategic lines above: downloadable scenario models, procurement contract templates, an M&A valuation pack, and supplier due‑diligence worksheets tailored to metakaolin’s unique production chain.
For firms preparing capital allocation, procurement, or M&A moves in 2026, the combination of a near‑term procurement playbook and a medium‑term capacity and feedstock strategy represents the highest value. Our work highlights where to deploy capital, how to structure offtakes and partnerships, and which technical differentiators (reactivity, fineness control, certification) translate to commercial premiums.
Next steps
-
Download the full PW Consulting Metakaolin Market report to access the confidential segment tables, regional / application breakdowns, and the interactive forecast model.
-
Engage our advisory team for a tailored 6–12 month implementation roadmap that aligns procurement, R&D, and commercial channels with your capital plan.
In 2026, decisions made around feedstock security, calcining capability, and product specification will determine who captures the disproportionate upside from a market that is growing steadily but remains technically and operationally demanding. PW Consulting’s full report arms you with the granular, transaction‑ready intelligence to act decisively — contact us to access the detailed segment intelligence and proprietary playbooks referenced here.
For detailed analysis of this topic, please visit the official page: Metakaolin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Balanced-armature Magnetic Speakers Market to Reach USD 60.77M by 2032 at 1.5% CAGR
By pmarketresearch, 2026-07-30
Balanced-armature Magnetic Speakers Market: Strategic Outlook for 2026 Decision-Making
As organizations plan their 2026 product roadmaps, sourcing strategies, and M&A tests-of-reality, a granular understanding of the balanced-armature magnetic speakers market is no longer optional — it is strategic. PW Consulting’s latest market study (base year 2025, historical window 2020–2025, forecast 2026–2032) distills performance trends, supplier dynamics, and risk vectors that will materially affect supplier selection, product architecture choices, and investment prioritization in the year ahead.
Balanced-armature Magnetic Speakers Market
Why this market matters in 2026
Balanced-armature drivers remain a critical enabler across several high-value audio end-markets — from premium true wireless stereo (TWS) earbuds and in-ear monitors (IEMs) to hearing aids and certain pro-audio devices. The market has demonstrated modest yet persistent resilience through a period of product transitions and geopolitical stress. Our sizing places the market at roughly mid‑50s (USD Million) in 2025 and projects a long-term, stable trajectory underpinned by a conservative compound annual growth rate (CAGR) of around 1.5% through 2032. That profile — slow growth with periodic volatility — creates a distinct decision environment in which optimization of supplier relationships and technology choices delivers outsized returns.
Balanced-armature Magnetic Speakers Market
What the 2026 strategic horizon looks like
-
Product differentiation will increasingly hinge on subsystem-level innovation. Multi-way and hybrid driver configurations, integrated crossovers, and micro-acoustic tuning are transitioning from "nice-to-have" to commercially important differentiators for premium devices. Manufacturers that lock in access to advanced micro-driver platforms can accelerate time-to-market for premium TWS and IEM SKUs.
Balanced-armature Magnetic Speakers Market -
Supply concentration amplifies supplier risk. The market displays a concentrated supplier landscape; the leading few firms together command a material share of global production capacity. This concentration drives bargaining power dynamics, elevates supplier reliability as a procurement criterion, and intensifies the importance of diversified sourcing strategies and long-lead component hedges.
-
Regulatory and IP realities are non-negotiable. Compliance pathways for hearing-health products and over-the-counter devices are shaping product architectures and supplier selection. Concurrently, transnational IP friction has surfaced as a non-trivial operational risk in recent years, forcing multinational buyers to add legal risk assessments to their supplier due diligence.
Market trajectory and interpretation for 2026 plans
Between 2020 and 2025 the market oscillated within a narrow band, reflecting substitution pressures from electrodynamic alternatives, fluctuating consumer demand cycles, and supply-side bottlenecks. With a projected CAGR of approximately 1.5% during the 2026–2032 forecast period, the market’s growth profile signals a shift from volume-driven expansion to value-driven competition. For decision-makers in 2026, that suggests prioritizing product mixes and supply chain investments that maximize margin capture per unit rather than purely chasing unit volumes.
Competitive landscape — what matters to buyers and investors
Our competitive analysis spotlights a small set of specialized component manufacturers that exert disproportionate influence on product innovation and pricing. These firms have deep R&D capabilities, geographically dispersed manufacturing footprints, and established OEM relationships. Notable players include long-standing specialists in miniature drivers and multi-driver systems whose product roadmaps are actively shaping OEM design choices.
-
Knowles Corporation: A leader in multi-way balanced-armature solutions and integrated driver combinations, Knowles continues to push premium TWS and IEM architectures with recent launches of multi-way driver families and pre-configured crossover assemblies. For OEMs targeting the premium segment, Knowles’ platforms shorten development cycles and reduce acoustic tuning risk.
-
Sonion A/S: With a global reputation in miniature receivers for hearing aids and audio applications, Sonion’s designs and production depth make it a default supplier for buyers requiring compact form factors and stringent quality standards.
-
Etymotic Research: Known for high-performance micro-drivers, Etymotic’s product pedigree is particularly relevant for IEMs and certain medical-grade hearing solutions where audio fidelity and reliability are critical.
-
Bellsing Acoustic Tec. Co., Ltd.: A major China-based supplier of multi-driver configurations, Bellsing’s capacity and product breadth contribute materially to global supply. However, its involvement in past IP-contentious cases underscores the geopolitical and legal dimensions that buyers must factor into supplier selection.
Collectively, the market exhibits notable concentration at the top; our analysis shows that the top three and five suppliers capture a significant majority of supply — a dynamic that feeds both opportunities (stable partnerships, co-development) and risks (supply disruptions, pricing pressure, and IP exposure).
Recent developments that change the 2026 playbook
-
Product launches that pre-integrate acoustic crossovers and multi-driver configurations lower system integration risk for OEMs and accelerate premium product introductions. These platforms are especially material for firms aiming to enter or expand in the high-margin TWS and IEM segments.
-
Supplier selection is now routinely informed by compliance assurance for hearing-health and over-the-counter device standards; vendors that can demonstrate regulatory readiness reduce time-to-market for medical-adjacent product lines.
-
Geopolitical and IP events have briefly reshaped sourcing decisions and pushed some multinational buyers to dual-source or nearshore portions of their supply chains to insulate product roadmaps from export controls or legal actions.
Report contents — what PW Consulting provides (practical, action-oriented)
Our study blends quantitative market sizing with executable frameworks designed for 2026 decision cycles. The report includes:
-
Consolidated market sizing and multi-scenario forecasts (2026–2032) with base-year calibration (2025).
-
Segmentation analysis by form-factor, application, and region — presented with trend diagnostics and demand-side elasticities (note: detailed segment tables and regional splits are available in the full report).
-
Supply chain mapping and node-level risk heat maps indicating single-source exposures, capacity constraints, and lead-time variability.
-
Competitive benchmarking profiles that compare technology roadmaps, capacity, regulatory posture, and IP posture for the leading suppliers.
-
Commercial playbooks for OEMs: supplier shortlists, negotiation levers, quality gating checklists, and a procurement timeline aligned with product development calendars.
-
M&A and partnership screening matrices that identify attractive targets and partnership archetypes based on capability gaps and integration complexity.
-
Scenario-based stress tests for pricing and supply disruptions, with recommended hedging and contract structures tailored to 2026 procurement cycles.
How organizations should use this analysis in 2026
-
Product teams: Prioritize platform components that deliver the most defensible acoustic differentiation per engineering hour. Consider co-development arrangements with select suppliers to lock in advanced driver combinations and reduce tuning cycles.
-
Procurement: Rebalance long-term contracts with tactical spot allocations to manage supplier concentration risk. Insist on regulatory compliance evidence and IP-clearance covenants in supplier contracts — especially for hearing-related product lines.
-
Strategy and Corporate Development: Use the report’s M&A and partnership frameworks to identify bolt-on acquisitions that fill capability gaps (e.g., miniaturization, acoustic tuning tools) and to evaluate strategic minority investments in regional suppliers as de-risking plays.
-
Investors: Understand that the market’s modest CAGR favors companies with scalable premium offerings or distinctive IP; commodity players face margin compression unless they secure scale or vertical synergies.
Research rigor and limitations
PW Consulting’s estimates are anchored to a 2025 base year and informed by historical performance (2020–2025), primary interviews across OEMs and component suppliers, and supply-chain audits. Forecast trajectories for 2026–2032 reflect a conservative macro assumption set and incorporate scenario overlays for regulatory change and trade disruptions. As a teaser to our full intelligence suite, this article highlights directional findings and strategic implications — the full report contains the detailed segment breakdowns, regional splits, and company-level market-share tables that are essential for transactional diligence and procurement negotiations.
Final takeaway — a focused checklist for 2026
-
Treat supplier concentration and IP exposure as first-order risks; build contractual and sourcing countermeasures now.
-
Allocate R&D and procurement capital toward driver platforms that enable premium differentiation rather than volume commodity bets.
-
Factor regulatory readiness into supplier scorecards when targeting hearing-health adjacent products.
-
Use the conservative CAGR and multi-year forecast window to stress-test pricing and margin scenarios for the next funding or sourcing cycle.
For practitioners setting strategy in 2026, PW Consulting’s balanced-armature magnetic speakers market study offers the quantification, supplier intelligence, and executable tools you need to convert modest market growth into durable competitive advantage. Access the full dataset and supplier-level tables on our website to unlock the specific segmentation figures and detailed company metrics that underpin these recommendations.
For detailed analysis of this topic, please visit the official page: Balanced-armature Magnetic Speakers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Omega‑3 Products market to expand at 6.98% CAGR through 2032
By pmarketresearch, 2026-07-30
Omega‑3 Products Market: Strategic Briefing for 2026 Decision‑Makers
Executive summary
As global health narratives and sustainability imperatives converge, the omega‑3 products market is entering a structurally transformative phase. Our latest PW Consulting market study — with a base year of 2025 and a forecast window spanning 2026–2032 — shows continued expansion at a compound annual growth rate (CAGR) of 6.98%. The market measured USD 11,314.42 Million in 2025 and, under our baseline scenario, is forecast to more than double by the end of the modelling period. For executives preparing investment, portfolio, or go‑to‑market choices in 2026, this study is designed to convert epidemiological, consumer and regulatory trends into executable commercial actions.
Omega 3 Products Market
Why this research matters for 2026 strategy
-
From opportunity timing to risk mitigation: 2026 is a turning point. Growth is no longer linear; it is being re‑cast by ingredient innovation (notably microalgal and other non‑marine sources), regulatory tightening, and accelerating e‑commerce adoption. Firms that align upstream sourcing, formulation and digital distribution now will secure scale advantages as the market matures.
Omega 3 Products Market -
Clarity for allocation decisions: with overall market momentum established, the pressing question for boards and strategic planning teams is not whether to play, but where and how much to invest. Our modelling translates high‑level growth into probabilistic outcome bands that support capital budgeting, plant investment, and M&A prioritization under multiple macro scenarios.
Omega 3 Products Market -
Actionable compliance readying: regulatory attention on dietary supplements has intensified. Anticipated rule‑making and process modernization initiatives in 2026 raise execution risks for product launches and cross‑border supply chains. The study provides regulatory readiness frameworks that map probable timelines and required controls to practical program milestones.
What the report delivers — practical, operational intelligence
-
Market sizing and trajectory: a transparent reconciliation of historical performance (2020–2025) against forward projections (2026–2032), with scenario lenses (conservative, baseline, upside) and sensitivity to raw‑material price shocks.
-
Commercial playbooks: channel‑specific GTM templates (DTC/e‑commerce, brick‑and‑mortar, pet food, infant nutrition and pharma pathways) tailored to ingredient form (triglyceride vs. ethyl ester vs. algal concentrates) and consumer purchase behaviors.
-
Supplier and manufacturing scorecards: independent assessments of ingredient producers, contract manufacturers and third‑party certifiers, including operational capacity, sustainability credentials, traceability practices and unit economics.
-
Regulatory risk heatmaps and GRAS readiness checklists: step‑by‑step compliance actions keyed to the FDA’s 2026 priorities for recall process modernization and planned guidance around new‑substance notices.
-
Financial and M&A analytics: target screening for bolt‑on acquisitions, accretion/dilution modelling, and integration playbooks aligned to consolidation scenarios consistent with observed market concentration metrics.
Competitive landscape — what leading players are doing in 2026
The market remains moderately fragmented: our competitive concentration analysis indicates that the three largest players account for roughly a quarter of market value, and the top five capture only marginally more — a structural signal of opportunity for consolidation and scale plays.
-
Aker BioMarine (Lysaker, Norway) — continues to leverage its brand and R&D orientation in krill and algae solutions. Recent participation at Vitafoods India 2026 to introduce a high‑concentration algae DHA demonstrates a dual strategy: expand into higher‑margin sustainable ingredients while reinforcing global distribution relationships.
-
GC Rieber VivoMega (Kristiansund, Norway) — has focused on high‑potency triglyceride concentrates for nutraceuticals. Its early‑2026 launch of a high‑potency algal TG product signals a deliberate push to capture demand from vegan and label‑conscious consumer segments.
-
dsm‑firmenich (Kaiseraugst, Switzerland) — is pursuing scale in North America, evidenced by a multi‑million dollar upgrade of regional premix capacity and product introductions targeted at adjacent categories (e.g., pet nutrition). Their activity underlines a platform strategy: combine ingredient IP with customer‑facing formulation services.
-
Corbion (Gorinchem, Netherlands) — remains focused on algal DHA for infant and plant‑based markets, maintaining a differentiated stance on sustainability and system integration with infant formula makers.
-
Pharma Marine (Søvik, Norway) and Neptune Wellness Solutions (Toronto) — represent suppliers that blend marine sourcing with certification playbooks, positioning for customers looking for traceability and sustainability assurances.
-
Omega Protein Corporation (Houston) — continues to be a strategic supplier for high‑volume fish oil requirements, relevant for companies that prioritize cost and scale.
Recent industry movements worth tracking
-
Product innovation: several suppliers introduced concentrated algal and marine omega‑3 ingredients in early 2026, sharpening the competitive boundary between traditional marine oils and next‑generation non‑marine sources.
-
Capacity and capability investments: modernization projects in premix and formulation centers reflect supplier bets on faster time‑to‑market in the Americas and pet nutrition expansion.
-
Certification and sustainability signaling: suppliers are increasingly using third‑party sustainability credentials to underpin premium pricing and secure partnerships with consumer brands that require verified chain‑of‑custody.
Market dynamics, headwinds and strategic implications
-
Raw‑material volatility: fluctuations in marine by‑product and shellfish markets materially affect manufacturing margins. Scenario analysis in the report quantifies margin impacts across sourcing choices and shows where hedging, multi‑supplier contracts and backward integration alter outcomes.
-
Regulatory tightening: the FDA’s 2026 agenda — including recall modernization and proposed requirements for broader GRAS submissions — elevates the cost of non‑compliance. Firms should accelerate product documentation, expand lot‑level traceability, and budget for faster response capabilities.
-
Consumer purchase shifts: online grocery and direct e‑commerce channels now represent a significant share of sales in 2026, driving demand for smaller‑format, single‑serve and subscription‑friendly omega‑3 SKUs. Brands that adapt packaging, fulfillment and digital engagement see larger conversion and retention gains.
-
Fragmentation and consolidation dynamics: with the market concentration metrics indicating room for scale economies, well‑capitalized players and PE sponsors will find attractive arbitrage between manufacturing optimization and brand roll‑ups.
Actionable plays for 2026 — 90‑day and 12‑month roadmaps
-
90‑day priorities: complete an audit of supplier traceability; run a GRAS/compliance gap assessment for all SKUs; pilot a high‑potency algal SKU with a small e‑commerce partner; stress‑test contracts for raw‑material price pass‑through clauses.
-
12‑month priorities: establish a multi‑source ingredient strategy; pursue targeted capacity upgrades or tolling arrangements; execute one focused acquisition to capture distribution or ingredient IP; implement lot‑level serialization and a rapid recall playbook aligned to regulatory timelines.
Why PW Consulting’s Omega‑3 Report is the right decision tool
Our study is built to be operational: not an archive of descriptive statistics, but a toolkit for deployment. It combines detailed market modelling (historical 2020–2025, base year 2025, forecast 2026–2032), supplier due diligence templates, regulatory readiness matrices and commercial playbooks that link to P&L and cash‑flow implications. We preserve confidentiality of sensitive sub‑segment datasets in this overview so executives can assess strategic direction quickly; the full dataset, including granular regional and application breakouts, pricing curves, and supplier scorecards, is available via the report portal.
Next steps
-
If you are setting 2026 capex or M&A mandates, use our scenario modules to quantify downside exposure to raw‑material shocks and regulatory cost ramps.
-
If you are a commercial or R&D leader, review the GTM templates and pilot planning checklist to reduce time‑to‑launch for algal and alternative omega‑3 SKUs.
-
For investor teams, our competitive concentration analysis and deal‑scoping tools identify the most accretive target profiles within current consolidation dynamics.
To access the complete intelligence set — including the granular segmentation that underpins the figures summarized here and executable annexes for procurement, regulatory and commercial teams — please consult the full PW Consulting Omega‑3 Products Market report on our website.
For detailed analysis of this topic, please visit the official page: Omega 3 Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com