

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Screen Protector Market to Reach USD 54.9 Billion in 2025

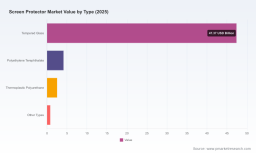
Screen Protector Market — Strategic Outlook for 2026: A PW Consulting Brief
As the global accessories market matures into its second decade of rapid evolution, PW Consulting’s Screen Protector Market study delivers a focused intelligence suite designed to inform high-stakes decisions in 2026. Built on a 2025 base year with a historical lens covering 2020–2025 and forward-looking projections to 2032, the market shows a clear, sustained expansion: the global market grew from roughly USD 38.4 billion in 2020 to about USD 54.9 billion in 2025 and is projected to approach USD 90.5 billion by 2032, tracking a compound annual growth rate of ~7.4% across the forecast period. This brief synthesizes the strategic implications of those dynamics and explains how our full research equips leadership teams to translate market growth into competitive advantage without disclosing the granular tables reserved for report subscribers.
Screen Protector Market
Why this matters for 2026 corporate strategy
-
Demand momentum is durable and multi‑faceted. Growth is driven by a mixture of device proliferation, premiumization of screen protection technologies, and recurring replacement demand in mature markets. These forces create both volume opportunities and margin capture possibilities for differentiated suppliers and brand owners.
Screen Protector Market -
Supply-side innovation is reshaping competitive boundaries. Advances in accessory glass engineering and licensing agreements between glass manufacturers and local contract producers are enabling new entrants to compete on quality rather than price alone.
Screen Protector Market -
Regulatory and standardization developments are increasing the importance of certification and compliant supply chains. Recent moves in standards and trade policy mean that a previously peripheral procurement variable is now core to market access and go-to-market timing.
Key inflection points to watch
-
Premium material adoption: Proprietary engineered glass and specialty coatings (privacy, anti-blue-light, anti-glare) are shifting value away from basic polymer films into higher ASP categories. Companies that can secure supply or licensing of premium glass stand to expand margin pools.
-
Manufacturing localization: New national standards and incentives are accelerating domestic manufacturing initiatives in select markets, reducing historical import dependence. This trend has implications for sourcing, tariff exposure, and speed-to-market for customized SKUs.
-
Regulatory and trade litigation: Industry participants must plan for episodic regulatory events that can rapidly change access to important markets or product classes. Such events can compress planning horizons and create windows for entrants that are strategically prepared.
Competitive landscape — who you must account for
The competitive field is a mix of brand-led incumbents, specialized OEM suppliers, and nimble regional manufacturers. On the brand side, firms with strong consumer recognition and retail distribution bring differentiated product design and marketing scale. Specialized OEM and contract manufacturers supply private label and OEM channels with variable cost and customization advantages. Several company moves and product launches in the past 18 months illustrate how value is being contested along different dimensions:
-
Leading direct-to-consumer brands emphasize ease-of-use and feature-rich positioning (anti-scratch, bubble-free installation, blue-light mitigation, privacy filtering). These firms leverage distribution partnerships and brand loyalty to sustain ASPs in developed markets.
-
Custom glass manufacturers and contract producers are forging closer ties with global glass-engineering firms; these relationships enable higher-spec tempered glass products tailored for retailers, OEMs and private-label partners.
-
Regional entrants are pursuing a localization strategy that combines certification, domestic manufacturing, and co-branded material licensing to displace imports in their home markets and pursue selective exports.
Profiles to watch (strategic takeaways)
-
Brands focused on consumer retail and e-commerce: Their strengths are brand equity, channel control and product innovation centered on end-user features. They will continue to extract value through design and distribution, but must defend against commoditization in lower tiers.
-
Custom and contract manufacturers working with premium glass suppliers: These players are positioned to win OEM and private-label mandates by combining technical glass capability with scale production and rapid SKU customization.
-
Regional champions leveraging certification and local standards: Where governments introduce formal quality standards and incentives, certified local producers can quickly improve their competitive standing vs. established import supply chains.
Recent developments that change strategic calculus
-
Strategic licensing partnerships between glass-engineering firms and local contract manufacturers have lowered the technical barrier to producing premium tempered glass protectors, creating pathways for new supply onshore.
-
National standards and first-of-kind certifications in certain markets are creating preferential conditions for domestic producers and altering sourcing decisions for regional retailers and distributors.
-
Trade and intellectual property disputes surfaced in late 2025 and early 2026 underscore the need for legal/market intelligence as part of any market-entry or scale-up strategy.
Practical, report-backed actions for 2026
For leaders preparing near-term strategies, the research supports a set of pragmatic initiatives that balance offensive growth and defensive resilience:
-
Prioritize materials partnerships: Secure access to engineered glass and differentiated coating technologies either through licensing, long-term supply contracts, or equity stakes in strategic suppliers.
-
Execute a two‑track manufacturing playbook: localize production in high-growth, politically sensitive markets while preserving global-scale, low-cost capacity for high-volume SKUs.
-
Differentiate through certification and warranty: Use third-party standards and extended warranty offerings to reduce price sensitivity and raise switching costs among B2B and retail customers.
-
Optimize channel mix: Rebalance SKU portfolios between direct-to-consumer, retail partnerships and OEM supply, using data-driven SKU profitability models to guide investments.
-
Implement regulatory early-warning: Build a monitoring function to track trade filings, standards updates and certification regimes that can affect access to specific product features or markets.
-
Prepare portfolio M&A playbooks: Identify targets across the value chain—materials specialists, contract manufacturers, and regionally certified manufacturers—that accelerate capability capture with minimal integration risk.
What the PW Consulting report delivers (operationally useful outputs)
Our full study translates market sizing and trend analysis into tools that teams can act on immediately. Deliverables include:
-
Granular historical and forecast market sizing (global and by segmentation), with downloadable models that support scenario testing.
-
Price and margin benchmarking for material types, distribution channels and regional cost stacks.
-
Supply‑chain maps that identify critical suppliers, single‑source dependencies, and alternative sourcing options for engineered glass and specialty films.
-
Commercial diligence templates and acquisition screening criteria focused on synergy capture and integration risk mitigation.
-
Channel and SKU optimization playbooks, including retailer negotiation frameworks and D2C acceleration tactics.
-
Regulatory timeline and risk matrix aligned to litigation and standards events—enabling legal teams to prioritize scenarios and contingency plans.
Decision frameworks and KPIs to operationalize the insight
Turning insight into execution in 2026 requires a compact set of KPIs and decision triggers. We recommend teams align against three horizons:
-
90‑day play: validate supplier/partner options, secure conditional letters of intent for premium glass, and test one certified SKU in a controlled market.
-
12‑month play: establish localization or co-manufacturing arrangements where certification regimes favor domestic producers, and recalibrate SKUs across channels to prioritize margin density.
-
24+ month play: consolidate market positions through strategic acquisitions or exclusive licensing, while hedging regulatory exposure through diversified routing and legal preparedness.
Core KPIs should include SKU-level gross margin, channel contribution margin, lead time variability for critical materials, and certification-compliance time to market.
Risks you cannot afford to ignore
-
Regulatory shocks and trade disputes can ripple through the value chain and create abrupt winners and losers. Scenario planning must be quantitative and updated quarterly.
-
Material concentration risk—particularly in premium engineered glass—creates supplier power that can compress margins if not mitigated through long-term contracts or alternative materials research.
-
Commoditization in entry-level tiers will pressure volumes and unit economics, necessitating a clear differentiation and up-sell strategy for higher-value offerings.
Conclusion — how to use this brief
For executives who must allocate capital and attention in 2026, our research converts the broad market growth story into operationally relevant choices: where to invest in materials and manufacturing, how to defend brand and channel economics, and how to build optionality against regulatory headwinds. The macro picture—robust growth and premiumization—creates meaningful upside for players who act decisively on supply partnerships, certification-led differentiation and targeted localization. At the same time, episodic regulatory and trade events demand that strategy teams keep contingency pathways open and measurable.
PW Consulting’s full Screen Protector Market report contains the detailed segmentation tables, country-level analysis, supplier scorecards, and downloadable models that senior teams use to make final investment decisions. To review the complete dataset and our proprietary scenario models, please access the full report on our website or contact your PW Consulting analyst for a private briefing.
For detailed analysis of this topic, please visit the official page: Screen Protector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com