

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: TBBA Market to Hit USD 1,523M by 2032 at 5.1% CAGR

Tetrabromobisphenol-A (TBBPA/TBBA) Market 2026 Strategic Brief — What Chief Executives and Supply-Chain Heads Need to Know
PW Consulting’s market study on Tetrabromobisphenol-A (TBBPA/TBBA, CAS 79-94-7) is designed to be a practical decision-support tool for boards, investment committees, and executive teams planning through 2026 and beyond. Built on a 2020–2025 historical base and anchored at a 2025 base year, the analysis projects the market across a 2026–2032 forecast window and quantifies a steady mid-single-digit expansion with a compound annual growth rate of 5.1%. Our modelling captures both cyclical drivers and structural trends that will determine supplier economics, demand mix, and competitive positioning over the next planning cycle.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
Market Trajectory — A concise snapshot
- Historical momentum: The TBBPA market expanded from an estimated USD 850 million in 2020 to approximately USD 1,075 million in 2025, reflecting recovery dynamics and reorientation of electronics and industrial supply chains.
- Near-term inflection: PW’s central forecast anticipates the market crossing roughly USD 1.13 billion in 2026 and continuing to expand to about USD 1.52 billion by 2032 under our base-case assumptions.
- Structural growth rate: A 5.1% CAGR over the forecast horizon implies sustainable demand growth but one that is highly sensitive to raw-material cycles, regulatory signals, and product substitution risk.
Why this study matters for 2026 corporate decision-making
- Prioritise capital allocation with confidence — Our integrated forecast and scenario tool links demand pathways to margin outcomes so CFOs can sequence capacity investments, retrofit CAPEX for low-emission grades, or delay brownfield expansions with quantified trade-offs.
- De-risk procurement and margin volatility — The report quantifies the exposure to bromine feedstock cost swings and TBBPA spot-price volatility observed in 2024–2025, enabling procurement teams to model collar and forward buying strategies versus the economics of backward integration.
- Navigate regulatory complexity — Recent regulatory actions (notably the US EPA’s August 2025 TSCA test rule requiring fate-and-transport testing and EFSA’s July 2024 dietary assessment update) materially change compliance timelines and testing budgets for manufacturers and processors. Our regulatory matrix maps obligations, lead times, and enforcement risk across jurisdictions, so legal and compliance teams have a clear roadmap into 2026.
- Shape go-to-market strategies — Product managers and commercial teams can use our demand archetypes and customer-propensity models to prioritize product development (e.g., low-emission grades for electronics, formulations for polycarbonates or epoxy systems) and shape commercial incentives that protect price realization.
What the report delivers (practical scope)
- Comprehensive market sizing and triangulated forecasts (2020–2032) with transparent assumptions and sensitivity bands.
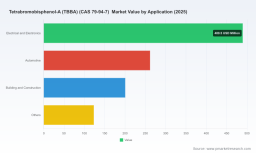
- Segmentation frameworks by product chemistry, application and geography together with qualitative demand drivers — note: detailed segment tables and client-only worksheets are available on the source page to preserve competitive confidentiality in this preview.
- Supply-side analysis: capacity maps, utilization dynamics, and a cost curve that explicitly incorporates bromine feedstock movements and processing differentials.
- Price and margin analytics: historical spot ranges, producer lift-and-pressure scenarios, and break-even pricing for different production footprints.
- Regulatory matrix and impact simulations: scenario-led implications of major policy moves, including testing obligations and potential restrictions, with estimated compliance costs and time-to-market impacts.
- Competitor benchmarking and strategic heatmaps focused on vertical integration, regional footprint, product portfolio breadth, and sustainability positioning.
- Transaction support: valuation overlays, target screening, and integration risk checklists for M&A or JV activity in the TBBPA value chain.
Competitive landscape — strategic takeaways
The market exhibits moderate concentration (CR3 ~34.2%, CR5 ~36.8%), signalling a landscape where a small group of vertically integrated players exert meaningful influence but where secondary suppliers and regional manufacturers continue to shape pricing dynamics and service capabilities.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
- Albemarle Corporation — Strengths lie in bromine vertical integration, diversified production footprint spanning the United States and Asia, and product differentiation through low-emission grades targeted at electronics and polycarbonate markets. For incumbents, Albemarle’s position highlights the strategic value of integrated feedstock control and compliance-ready product lines.
- ICL Industrial Products — As one of the larger bromine-based producers, ICL’s recent capacity investments in Israel and Europe position it to serve printed-circuit and other flame-retardant markets at scale. Their moves underscore the importance of capacity timing aligned to customer lead times.
- Jordan Bromine Company — Focused on bromine recovery and incremental expansions, Jordan Bromine illustrates how lower-cost feedstock sources plus efficient recovery can be a defensible basis for a cost-competitive export strategy.
- Shandong Moris Tech & Shandong Tianyi Chemicals — Chinese manufacturers remain significant supply-side actors, especially for epoxy-resin and printed-circuit applications. Their integrated production and export orientation exert pricing pressure and offer fast-to-market responsiveness; however, buyers must balance cost advantages against regulatory-compliance and logistics risk in cross-border supply chains.
Recent developments that change the playbook
- Regulatory: The US EPA finalized a TSCA test rule (Aug 2025) requiring testing for fate and transport — a new compliance cost and data obligation for manufacturers and processors that shortens lead times for product registrations in the US market.
- Regulatory: EFSA’s July 2024 scientific opinion updated dietary risk assessment and concluded no concern for dietary exposure under current occurrence data — a stabilizing signal for markets with food-contact adjacency concerns.
- Regulatory: The European Commission’s December 2024 withdrawal of its RoHS restriction proposal reduced immediate regulatory tail-risk in the EU but does not eliminate future scrutiny — companies should factor in episodic policy shifts when modelling long-term demand.
- Raw-material volatility: Bromine feedstock in 2024 averaged in the mid-thousand USD per MT range and rose ~18% year-over-year amid extraction and logistics constraints; spot TBBPA prices showed wide monthly ranges. These dynamics materially steer margin sensitivity and point to the financial value of de-risking strategies.
Actionable recommendations for 2026 planning
- Immediate compliance investment: Allocate testing and data-collection budgets to meet TSCA obligations and preempt market access delays. Prioritise key SKUs and high-volume processing sites for initial testing to preserve commercial continuity.
- Secure feedstock: Negotiate multi-year bromine contracts with flex provisions or evaluate backward integration where feasible; build feeder-stock buffers into working-capital models to blunt short-term price spikes.
- Differentiate via low-emission and compliance-ready grades: Invest in product certification and customer trials for electronics and automotive OEMs that are increasingly procurement-savvy on chemical footprints.
- Commercial contract redesign: Update pass-through clauses, indexation mechanisms, and force-majeure language to reflect raw-material and regulatory risks exposed since 2022–2024.
- M&A & partnerships: Target bolt-on assets that add regional logistics resilience, bromine recovery capabilities, or formulation IP, rather than solely capacity—these provide quicker returns in a moderately concentrated market.
Scenario outlook and sensitivity focus
Under PW Consulting’s base case (5.1% CAGR), the market steadily expands to ~USD 1.52 billion by 2032. Our alternate scenarios—stressed (regulatory tightening + raw-material shock) and upside (accelerated electronics demand and substitution economics favouring TBBPA formulations)—are provided in the report’s modelling workbook so executives can stress-test balance-sheet and pricing decisions. Key sensitivity levers in all scenarios are bromine feedstock costs, spot-price amplitude for TBBPA, and the speed of regulatory data generation and enforcement.
Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
Next steps — how to use this brief
- Download the full study for client-only access to the granular segmentation tables, regional and application breakdowns, and the Excel-based forecast and scenario models that underpin the figures cited here.
- For leadership teams seeking an executive workshop, PW Consulting offers a 90–120 minute briefing that applies the report’s scenarios to your specific cost base, contract terms, and growth targets — producing a tailored action plan for 2026 capital and commercial priorities.
PW Consulting’s TBBA market research is calibrated to inform decisive action in 2026: from where to invest, whom to partner with, and how to hardwire regulatory resilience into commercial models. If your mandate includes procurement, plant rationalization, or M&A activity in flame-retardant chemistries this year, this study is engineered to convert market intelligence into executable strategy.
For detailed analysis of this topic, please visit the official page: Tetrabromobisphenol-A (TBBA) (CAS 79-94-7) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com