

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
MP3 Player Market to reach USD 339.05 Million by 2032 at 1.12% CAGR — PW Consulting

MP3 Player Market — 2026 Strategic Preview for Corporate Decision-Makers
Executive preview
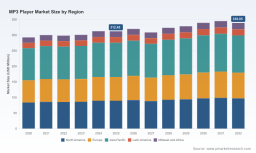
As companies prepare strategic plans for 2026, understanding the MP3 player market’s realistic trajectory is essential for capital allocation, product roadmaps, and go‑to‑market tactics. PW Consulting’s latest study uses a 2025 base year and a 2026–2032 forecast window to deliver a pragmatic, decision‑grade picture. Historically the market has been stable but mature: the total market value moved from roughly USD 293 million in 2020 to approximately USD 312 million by 2024–2025. Under our central projection the market edges higher to about USD 320 million in 2026 and grows at a measured compound annual growth rate (CAGR) of 1.12% through 2032, reaching roughly USD 339 million at the end of our forecast horizon.
MP3 Player Market
Those headline numbers tell a simple story: this is a small, steady market where incremental moves—product differentiation, cost efficiency, and targeted channel strategies—drive success more than mass market disruption. The market concentration metrics underline that reality: the top three players account for roughly 24.6% of the market and the top five for around 26.2%, indicating a fragmented competitive landscape with numerous niche players and localized specialists.
MP3 Player Market
Why this research matters for decisions made in 2026
-
Capital deployment and portfolio pruning: With modest overall growth, CFOs and product leaders must be precise about where to invest. Our study identifies where incremental investments return disproportionate strategic value and where divestment or licensing is the superior option.
MP3 Player Market -
Product roadmap prioritization: Component shortages, battery regulation and codec licensing create windows where differentiated hardware can command premiums. We show which technical trade‑offs (storage, DACs, battery capacity, UI) matter most to the remaining buyer cohorts.
-
Channel & pricing optimization: The market’s fragmentation rewards nimble channel strategies. The report supplies actionable playbooks for balancing direct digital channels, retail partnerships and specialist audio outlets, and for calibrating price tiers to elasticity profiles.
-
M&A and partnership scouting: Low concentration implies opportunities to consolidate cost bases or acquire IP and niche brand equity. We highlight the types of targets and the value levers—cost synergies, distribution, firmware/IP—that make acquisitions accretive.
What the PW Consulting report delivers — practical content
This is not a theoretical exercise. The report is an operational toolkit for leaders taking real decisions in 2026:
-
Proprietary market model (2020–2032): a flexible, drill‑down financial model calibrated to observed historical volatility and multiple demand scenarios. The model is parameterized to run sensitivity tests—price, replacement cycles, streaming penetration—without exposing the confidential segmentation outputs in this preview.
-
Scenario playbooks: three near‑term and two structural scenarios that test combinations of supply constraints, component price shocks, and changes in consumer preferences; each scenario is accompanied by prioritized mitigations and opportunity capture actions.
-
Commercial playbooks: go‑to‑market templates for premium niche devices, volume value models and bundled offerings with streaming or accessories; includes suggested margin targets, channel mixes, and promotional cadences.
-
Cost and supply chain heatmaps: bill‑of‑materials sensitivity analyses, alternate sourcing options, and an assessment of strategic component obsolescence risks (connectors, codecs, battery chemistries).
-
Competitive dossiers and capability maps: in‑depth profiles of leading OEMs and challenger brands, with capability matrices across engineering, software/firmware, distribution and brand equity. (Note: the report contains detailed segmentation matrices that are intentionally summarized in this preview to protect the value of the full analysis.)
-
Consumer cohort archetypes and journey maps: data‑backed profiles of remaining buyer segments and their purchase triggers, retention levers and accessory lifetime spend patterns—designed to inform creative briefs and channel plans.
-
Decision frameworks for M&A and partnerships: checklists and valuation adjustments tied to synergies typical in this market (manufacturing scale, distribution consolidation, and IP cross‑licensing).
Competitive landscape — what to watch from core players
-
Sony Corporation (Tokyo, Japan) — Sony continues to leverage its brand and audio heritage through dedicated digital audio products such as the NW‑A306 Walkman series. Sony’s strengths are product design, audio tuning expertise and an ecosystem approach that links hardware to content and peripherals. For 2026, Sony’s strategic choices will likely center on maintaining premium margins through product differentiation (audio components, form factor, brand cachet) while defending against low‑cost competitors. For partners and rivals, Sony represents both a benchmark and a white‑space target for differentiated co‑branding or tech licensing.
-
Samsung Electronics Co., Ltd. (Suwon, South Korea) — Historically present with legacy and portable media offerings, Samsung’s role in this specific market is more strategic than scale‑dominant. Samsung brings supply‑chain muscle, component integration capabilities and distribution reach. Its presence raises the bar on manufacturing efficiency and feature sets; smaller competitors should anticipate competitive pressure on component sourcing and can respond by specializing or pursuing partnerships that lock in supply chain advantages.
-
Creative Technology Ltd. (Singapore) — As a specialist in portable media players and consumer audio, Creative’s strengths include focused product portfolios, niche audio innovation and community awareness. For companies evaluating competition, Creative exemplifies a viable specialist strategy: defend a set of audio‑focused use cases, cultivate loyal customers and monetize through accessories and content partnerships rather than pure hardware scale.
Market structure and strategic implications
The market’s low top‑player concentration (CR3 ~24.6%, CR5 ~26.2%) signals an environment where differentiation, channel relationships and cost control matter more than broad share grabs. Key implications for 2026 decisions:
-
High opportunity for niche value capture: focused devices that serve specific use cases (audiophile, sport, children’s content) can generate healthy margins even in a small market.
-
Consolidation is selective: broad roll‑up strategies risk integration complexity without clear cost synergies. Targeted acquisitions that secure distribution or unique IP are higher‑value.
-
Pricing discipline is essential: with modest overall growth, price erosion can quickly undermine profitability. Dynamic pricing and bundled value propositions are superior to headline discounting.
-
Supply chain agility wins: whoever can flex BOM costs and secure long‑lead components at scale will sustain margin advantages when component cycles turn negative.
Strategic recommendations for 2026 decision‑makers
Below are prioritized actions to convert insight into outcomes in the coming 12–36 months:
-
Short term (0–12 months) : Tighten SKU portfolios to highest ROI variants; implement an immediate cost‑to‑serve audit across channels; negotiate conditional component commitments that preserve margin in low‑growth scenarios.
-
Medium term (12–24 months) : Launch one or two differentiated products aimed at defensible niches (e.g., audiophile portable device or child‑oriented durable device) with clear attach rates for accessories and services; formalize selective distribution partnerships in high‑value channels.
-
Longer term (24–36 months) : Consider targeted acquisitions for distribution or firmware/IP that accelerate time‑to‑market; evaluate subscription or content bundling models that lock in customer lifetime value beyond hardware sales.
-
Cross‑cutting : Embed scenario planning into annual budgeting—use an updated market model to test +/- 20% swings in component cost and a range of demand elasticity assumptions. Prepare a rapid response playbook for regulatory or codec‑licensing shifts that could materially affect BOM economics.
How to use the full PW Consulting study
This preview demonstrates the analytical depth and practical focus of our MP3 player market study while intentionally withholding core segmentation matrices and confidential granular allocations. The full report gives purchasers access to:
-
The interactive 2020–2032 model with scenario toggles.
-
Granular segmentation outputs and regional dashboards suitable for channel planning and P&L impact analysis.
-
Detailed competitor benchmarking, including product feature comparisons, margin proxies and distribution maps.
-
Templates for term sheets, integration checklists for M&A targets, and vendor negotiation scripts for securing components under multi‑year contracts.
In a mature, niche market where incremental strategic moves create outsized returns, PW Consulting’s MP3 Player Market study is designed to be a practical companion for 2026 decision cycles. If your team is preparing budgets, product plans, or M&A pipelines for the coming year, this research will sharpen choices, quantify risks and highlight the most economical paths to sustainable advantage.
For detailed analysis of this topic, please visit the official page: MP3 Player Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com