
Blogs
PW Consulting: Worldwide Rare Hemophilia Factors Market Valued at USD 1,706.89 Million in 2025, Poised for Continued Growth Through 2032
By pmarketresearch, 2026-08-18
Worldwide Rare Hemophilia Factors Market: Strategic Imperatives for 2026 — PW Consulting Preview
As life‑cycle management, reimbursement pressure and supply‑chain fragilities converge, executives in biotech, specialty pharma and plasma‑derived therapeutics must refine their 2026 strategies with unprecedented granularity. PW Consulting’s new Worldwide Rare Hemophilia Factors Market report (base year 2025, forecast period 2026–2032) synthesizes primary research, quantitative modelling and scenario analysis to deliver the actionable intelligence that senior leaders need. The global rare hemophilia factors market reached USD 1,706.9 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 4.8% through 2032, reaching roughly USD 2.37 Billion by the end of the forecast period. This preview outlines the report’s strategic value for 2026 decision‑making while reserving detailed segment and regional breakdowns for the full study.
Worldwide Manufacturing Execution Software Market
Why this report matters for 2026 planning
-
Timing: The market is at a pivot point. A blend of regulatory approvals for novel rebalancing therapies and maturing recombinant/plasma‑derived portfolios means 2026 is when strategic commitments (manufacturing capacity, licensing deals, clinical investments) begin to lock in future revenue profiles.
Biofouling Management Service Market -
Concentration risk: The market remains concentrated — our analysis shows the top three players account for a substantial majority of revenues, with the top five capturing over four‑fifths of the market. This structural characteristic elevates the importance of M&A, distribution alliances and tender strategies.
Worldwide Cross Linked Sodium Carboxymethyl Cellulose Market -
Operational fragility: Downstream demand is sensitive to plasma availability, manufacturing throughput and regulatory compliance cadence. Companies that address raw material sourcing and scalable viral‑safety platforms will have a disproportionate competitive advantage.
What the PW Consulting report contains (practical, deal‑ready modules)
-
Market sizing and forecast models — transparent methodology, reproducible assumptions and scenario variants (baseline, conservative, disruption) that incorporate both therapeutic substitution and novel prophylactic approaches.
-
Competitor scorecards — comparative assessments of portfolio breadth, manufacturing footprint, regulatory pathway readiness, and commercial reach. Each scorecard includes tactical considerations for partnerships, licensing and geographic prioritization.
-
Clinical and pipeline mapping — end‑to‑end view of therapies in late‑stage development, expected launch windows, and potential cross‑elasticities between factor replacement and non‑factor rebalancing agents.
-
Supply‑chain due diligence toolkit — risk heatmaps for plasma sourcing, virus‑inactivation capacity, contract manufacturing organization (CMO) dependencies, and practical mitigation playbooks for short‑term shocks.
-
Reimbursement and pricing playbook — country‑specific reimbursement levers, tender dynamics, payer negotiation templates and real‑world evidence (RWE) strategies to accelerate access for rare indications.
-
Commercial roll‑out templates — launch sequencing, HCP engagement plans, patient registry integration, and distribution channel optimisation for both hospital and outpatient settings.
-
M&A and partnership screening matrices — prioritized targets by strategic fit, valuation heuristics for niche factor assets, and integration checklists to protect margin and continuity of supply post‑transaction.
Competitive landscape — tactical insights on incumbent positions
The market is guarded by established manufacturers with differentiated capabilities across plasma‑derived and recombinant technologies. PW Consulting’s competitive analysis profiles each major player and highlights where contestability is increasing:
-
CSL Behring — strong in plasma‑derived Factor XIII solutions and with established capabilities in viral safety and large‑scale plasma processing. Their strength is operational resilience and proven prophylaxis product offerings; competitors should evaluate licensing or co‑sourcing rather than head‑on capacity competition.
-
Novo Nordisk — notable for its recombinant Factor VIIa product and recombinant Factor XIII A‑subunit offering. The company’s development of non‑factor reagents and subcutaneous delivery platforms positions it to influence standard‑of‑care evolution; strategic partners should consider combination therapy trials and complementary distribution arrangements.
-
Bio Products Laboratory (BPL) — niche leadership in hereditary Factor X therapeutics and selective regional presence for other concentrates. BPL’s strength is agility in regional approvals and tailored supply to localized protocols.
-
Takeda (Baxalta portfolio), Grifols and Octapharma — collectively important for their plasma‑derived portfolios, diversified product lines and global plasma networks. Their bargaining power with payers and hospitals is significant, making them role players in tender landscapes.
-
Pfizer and Bayer — major global commercial platforms and development capabilities in recombinant factors and adjunctive therapies; they are potential acquirers or collaborators for companies seeking scale and go‑to‑market breadth.
Recent regulatory developments are shaping therapeutic substitution and payer behaviour. Notably, FDA approvals of novel rebalancing agents and ongoing expansions for established recombinant and plasma‑derived concentrates are changing the care paradigm. These approvals broaden prophylaxis options and create headwinds for some factor replacement volumes, while expanding total addressable treatment episodes in certain patient cohorts.
Key dynamics executives must weigh in 2026
-
Therapeutic substitution risk vs. market expansion: Non‑factor modalities that rebalance coagulation (recent approvals in 2024–2025) can displace some factor replacement use but also expand prophylaxis uptake. Strategic product positioning and evidence generation around severity‑specific outcomes will determine which companies gain share.
-
Plasma supply and processing constraints: Plasma remains the principal raw material for many concentrates. Executives must quantify exposure (sourcing concentration, donor base stability) and implement contingency plans that include inventory buffers, diversified sourcing and investments in recombinant alternatives.
-
Regulatory and reimbursement alignment: Although many concentrates have established regulatory precedents, payer policies (including government‑supported programs and grants in major markets) materially affect access. Robust health economic models and early payer engagement are essential.
-
Consolidation opportunities: High market concentration leaves room for bolt‑on acquisitions in niche factors, but bidders must factor in integration risks and the cost of safeguarding supply continuity.
Actionable recommendations for 2026 strategy
-
Secure raw material resilience: Negotiate multi‑year plasma supply agreements, qualify additional CMOs and accelerate recombinant/alternative platform investments to reduce single‑source exposure.
-
Prioritise differentiated value propositions: Invest in delivery improvements (e.g., subcutaneous options), label expansions supported by real‑world effectiveness data and co‑develop patient support programs to bolster adherence and justify premium positioning.
-
Accelerate payer evidence generation: Deploy targeted RWE pilots and health economic dossiers in parallel with regulatory submissions to shorten time to favourable reimbursement decisions post‑launch.
-
Be opportunistic on M&A and licensing: Use concentrated market structure to acquire niche factor assets or secure regional distribution deals where incumbents lack reach.
-
Model disruption scenarios: Build integrated forecasts that include the uptake of non‑factor prophylactics, changing treatment patterns and tender volatility. Treat these as planning inputs for capacity and commercial investment decisions.
The strategic value of PW Consulting’s full report
This preview highlights the directional insights executives need to prioritize in 2026. The full report equips decision‑makers with the granular tools to act: downloadable financial models, country‑level access roadmaps, competitor dossier appendices, transaction valuation templates and detailed operational checklists. We intentionally reserve the granular segment and regional tables for the complete publication to ensure stakeholders access the full, source‑level datasets and interactive models through our platform.
For teams preparing board presentations, M&A diligence packets or launch playbooks, the report reduces execution risk by converting diffuse market noise into prioritized, executable initiatives. With a projected market trajectory showing sustained growth at a 4.8% CAGR through 2032 and clear concentration among incumbent players, 2026 decisions will disproportionately influence market positions for the rest of the decade.
Next steps
-
Contact PW Consulting to obtain the full Worldwide Rare Hemophilia Factors Market report, access the interactive modelling workbook and schedule a briefing with our senior analysts for tailored scenario workshops.
-
Use the report as the foundation for a six‑month strategic plan: immediate supply‑chain audits, a 12‑month payer evidence timeline, and a 24‑month M&A screening and integration plan.
PW Consulting’s team of industry specialists has compiled this study to help executive teams convert complexity into clarity. For confidential conversations about how the findings apply to your portfolio or to request a customised research addendum, please reach out to our advisory desk to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Rare Hemophilia Factors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Agricultural Automated Steering System Market Poised for 12.85% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-08-18
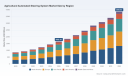
Worldwide Agricultural Automated Steering System Market: Strategic Insights for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Agricultural Automated Steering System market provides a compact but rigorous briefing designed to inform executive decisions in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the report synthesizes market sizing, technology trajectories, vendor positioning, and practical go-to-market playbooks. At the macro level the market demonstrates sustained expansion — growing from approximately USD 855 million in 2020 to roughly USD 1,652 million in 2025, and our modeled outlook projects an increase to about USD 3,851 million by 2032, representing a compound annual growth rate of 12.85% over the forecast period. This trajectory is accompanied by a moderately concentrated supplier base: the top three vendors account for roughly 54.3% of share and the top five for roughly 71.9% — a profile that creates both competitive barriers and consolidation opportunities.
Worldwide Asphalt Anti Strip Agent Market
Why this report matters for 2026 strategists
- Actionable, revenue-linked insight: The study does more than chart growth — it quantifies where value pools are forming and translates those pools into executable pathways for OEMs, Tier‑1 suppliers, distributors, and capital allocators.
- Operational levers prioritized: Cost-of-ownership dynamics, retrofit vs. factory-installed economics, and service-network imperatives are modeled to highlight near-term margin and adoption levers.
- Risk-aware scenario planning: Multiple adoption scenarios reflect sensitivity to regulatory shifts, RTK availability, and commodity-price-driven CAPEX cycles so organizations can stress‑test investment timelines.
What the report contains — practical, useable modules
- Market sizing and methodology: A transparent approach linking historical adoption (2020–2025) to 2026–2032 forecasts, with assumptions on technology substitution, price deflation curves, and service revenue potential.
- Demand-driver diagnostic: Farm economics, operator shortages, precision-agriculture adoption rates, and mechanization trends are modeled to show which farm segments will drive incremental purchases.
- Technology deep dives: Comparative analysis of GNSS/RTK, vision-based, and laser guidance approaches — covering technical performance, cost bands, integration complexity, and terrain/operation suitability.
- Go-to-market playbooks: Practical pathways for OEMs and retrofit suppliers covering channel selection, bundling strategies, financing and subscription models, and dealer enablement templates.
- Commercial models and ROI tools: Build-your-own calculators and sensitivity matrices demonstrating payback timelines under different crop values, operation intensities, and accuracy levels.
- Regulatory and standards radar: Assessment of current and emerging regulatory dynamics that affect operations, spectrum/GNSS policy exposure, and safety/ liability considerations for autonomation features.
- Competitive positioning: Scorecards, partner-fit matrices, and capability maps for leading vendors — enabling immediate benchmarking and M&A screening.
- Implementation playbooks: Field-trial design, fleet‑scale roll-out sequencing, training curricula for dealers and operators, and service logistics optimization.
Competitive landscape: Who matters and why
The market is anchored by a combination of large global OEMs and specialist technology providers. Our assessment identifies a mix of vertically integrated manufacturers and adaptable tech suppliers — each with distinct routes to market and competitive strengths.
Worldwide Activated Alumina Sorbent Market
- John Deere (Moline, Illinois) — A vertically integrated leader offering an OEM-level automated steering platform that emphasizes systems integration, display ecosystems, and proprietary GNSS augmentation. Its value lies in deep OEM integration and dealer network reach.
- Trimble Agriculture (PTx Trimble) (Westminster, Colorado) — A technology-first supplier whose Autopilot platform supports hydraulic and motor-drive configurations and broad OEM and retrofit compatibility, making it a frequent partner for both OEMs and aftermarket players.
- CNH Industrial (Case IH / New Holland) (UK) — Combines factory-installed guidance with retrofit options, balancing brand-led customer trust with cross‑brand technology adoption through their AFS and IntelliSteer lines.
- AGCO (including Fendt) (Duluth, Georgia) — Focused on integrating guidance into its brand portfolio while leveraging partnerships and compatibility with major technology platforms to deliver precision guidance at scale.
- Topcon Agriculture (Livermore, California) — A specialist in guidance systems known for making autosteering more accessible to mid-market tractors; recent product activity demonstrates a deliberate push to expand the addressable retrofit and mid-range segments.
- CHCNAV (Shanghai) — A fast-moving entrant that emphasizes RTK-level accuracy and multi‑GNSS support, offering competitive pricing and rapid global expansion from a China base.
- Ag Leader Technology (Ames, Iowa) — A focused player delivering integrated steering systems with an emphasis on compatibility with precision displays and year‑round machine control.
- FJDynamics (Shenzhen) — A provider concentrating on RTK-level performance and terrain compensation, targeting broad compatibility for tractors and specialized agricultural machinery.
- Raven Industries (CNH affiliate), CLAAS, Kubota — Each brings unique strengths: Raven with precision-control systems, CLAAS with OEM integration in harvesting platforms, and Kubota with scale in certain geographic and mechanization segments.
Collectively, these profiles make clear that competitive advantage will increasingly derive from combination offers — hardware + connectivity + services — and from channel depth rather than hardware differentiation alone.
Online Transformerless UPS Market
Recent industry dynamics shaping 2026 choices
- Product activity in 2025 shows vendors moving to broaden access: for example, new “value line” autosteering solutions target mid-range tractors and smaller farms, lowering the entry threshold for precision guidance.
- High-accuracy systems with RTK-level performance are now widely available from multiple vendors, increasing competitive pressure on price and pushing differentiation toward service, UX, and integration.
- Adoption snapshots indicate meaningful penetration in midsize and large farms — a structural tailwind that translates into a steady replacement and retrofit market, especially where operator shortages and efficiency pressures are acute.
- Field-level benefits — reduced overlap, lower operator fatigue, and extended operating windows — continue to be validated in productivity studies, strengthening the operational case for investment.
Strategic implications and recommended moves for 2026
- For OEMs: Prioritize platform openness with clear upgrade paths. Maintain capture of factory-installed revenue while enabling retrofit-friendly interfaces to address farmers who delay full fleet replacement.
- For aftermarket and tech vendors: Focus on modular solutions that reduce integration friction and on dealer training programs that shorten time-to-value in the field. Consider subscription pricing for positioning recurring revenue streams.
- For distributors and dealers: Invest in service capability and financing options. The purchasing decision is often more about risk mitigation and uptime than sticker price.
- For investors: Look for assets that combine hardware with data and service moats — companies that can monetize recurring GNSS corrections, software updates, and fleet analytics will command premium multiples.
- For policymakers and extension services: Encourage trials and co-funded pilots that de‑risk adoption for smallholders and midsize farms, and support spectrum and GNSS policy that stabilizes RTK availability.
Where this report acts as a strategic tool
Leaders who need to set 18–36 month investment priorities will find this report particularly practical. It turns market momentum into prioritized actions: where to allocate R&D spend, how to sequence product roll-outs, what dealer competencies to build, and which partnership archetypes deliver rapid scale. Our scenario models allow executives to map capital deployment to expected payback under conservative, base, and accelerated adoption cases.
Confidentiality of granular splits — and how to access them
In line with our “trailer” approach, this briefing surfaces the high‑value implications and the strategic narrative you need to act in 2026, while reserving detailed segment breakdowns, regional and application-level revenue tables, and granular vendor share matrices for the full report. That granular data underpins the actionable playbooks and ROI calculators referenced above; organizations that require immediate operationalization of those insights should review the full dataset and appendix.
Next steps
- Download the full report to obtain the segmented datasets, vendor scorecards, and financial models that support the recommendations summarized here.
- Schedule a capability workshop with PW Consulting to translate these insights into a 12–24 month commercial plan, including pilot design and dealer enablement roadmaps.
PW Consulting’s Worldwide Agricultural Automated Steering System market study is designed to convert market momentum into measurable advantage. For strategy teams preparing capital allocations, partnership roadmaps, or go-to-market plans in 2026, the report provides a concise, evidence-based foundation that bridges market sizing, competitive realities, and field-level execution.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Automated Steering System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 20.15% CAGR for Worldwide Autologous Cell Therapy Market, Signaling Rapid Expansion Through 2032
By pmarketresearch, 2026-08-18
PW Consulting Release: Strategic Brief — Worldwide Autologous Cell Therapy Market (Base Year 2025)
PW Consulting today publishes an executive industry brief accompanying our full report, Worldwide Autologous Cell Therapy Market. Designed as a strategic “trailer” for C-suite and deal teams preparing for 2026 decision cycles, this briefing explains why autologous cell therapies will remain a high-growth, high-complexity sector — and how senior executives should prioritize investments, partnerships, and operational choices in the year ahead. For organizations that require the underlying, transaction-grade data and granular regional, application and source splits, the full report contains the complete dataset, modelling files, and playbooks.
Worldwide Social Login Tool Market
Why this market matters to 2026 strategy
The autologous cell therapy market has transitioned from niche clinical promise to commercial reality over the past half-decade. At the macro level, PW Consulting’s model shows a market that expanded markedly from the early 2020s and reached USD 8,426.12 Million (revenue unit: Million USD) in 2025 (base year). Our forecast indicates continued robust expansion into the next decade, with the market projected to exceed USD 10,035.55 Million in 2026 and reach USD 30,457.48 Million by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of 20.15% across the 2026–2032 forecast window — a profile that places autologous approaches among the fastest-growing segments in advanced therapeutics.
Mobile and Portable MRI Scanner Market
High growth plus concentrated supplier dynamics (our concentration analysis indicates a CR3 of 38.5% and a CR5 of 52.1%) creates both opportunity and risk. Market leaders capture meaningful commercial rents, yet there remains substantial room for new entrants with differentiated manufacturing, logistics, or clinical differentiation to disrupt the incumbency.
Worldwide Regulating Human Health Beverage Market
What PW Consulting’s report delivers — practical, decision-focused content
- Actionable market sizing and scenarios : Transparent methodology and stress-tested scenarios for 2026–2032 to support capital allocation, portfolio prioritization, and M&A valuation assumptions. The report includes base, upside and downside demand pathways tied to regulatory and reimbursement inflection points.
- Commercial-readiness playbooks : Step-by-step recommendations for field launches, phased market entry, and payer engagement — including model term-sheets for value-based and outcomes-linked reimbursement pilots.
- Supply chain and manufacturing assessment : Deep-dive on cost drivers, batch economics and scalable processing strategies — from decentralized point-of-care models to regional centralized facilities — plus a vendor matrix for automation, single-use systems and cold-chain partners.
- Regulatory and quality roadmap : Comparative analysis of FDA, EMA and key APAC regulators’ expectations for CMC, cGMP/cGTP compliance, and donor screening where applicable. Includes timelines and checklist templates for audit readiness.
- Pipeline and clinical risk tracker : Live table of late-stage autologous programs, anticipated regulatory milestones and probability-weighted timelines to commercialization — facilitating portfolio reprioritization and partnering decisions.
- Competitive & partnership playbook : Profiles of incumbent and emerging players, commercial strategies, vertical-integration options, and best-practice alliances between developers, CDMOs, and health systems.
- M&A and licensing intelligence : Deal comps, enterprise valuation sensitivities, and an M&A heat map identifying the most attractive capability gaps to fill through acquisition.
Operational dynamics and the business implications for 2026
- Manufacturing economics are decisive : Autologous processes remain inherently high-cost on a per-patient basis. Our sector synthesis finds production cost drivers (facility footprint, specialized labor, reagents, and one-batch-per-patient processing) often driving per-dose manufacturing expenses into a high five-figure range. For 2026 planning, executives must stress-test capital allocation between automation investments that reduce variable labor intensity versus outsourcing to CDMOs with mature patient-flow throughput.
- Logistics and cold-chain management are strategic : Time-sensitive patient-to-facility-to-patient flows magnify operational risk. Companies expanding geographically should prioritize redundant transport corridors, validated cryo-logistics vendors, and localized contingency capacity to protect time-to-treat windows.
- Reimbursement frameworks are evolving but remain a gating factor : Payers continue to demand outcome-linked models. Firms launching in 2026 should secure early payer dialogue, invest in real-world evidence infrastructure, and be prepared to pilot bundled or annuity payment models where clinical durability supports it.
- Regulatory diligence reduces launch risk : CMC and facility compliance issues are frequent causes of launch delays. Organizations targeting 2026 approvals must front-load regulatory interactions and ensure CMC packages and process validation studies are aligned with anticipated agency expectations.
Competitive landscape — strategic takeaways on core players
The marketplace is populated by global pharmaceutical leaders, dedicated cell therapy developers, and specialized biotechs. Our competitive analysis synthesizes capabilities, commercialization models, and near-term catalysts for the most consequential players:
- Novartis AG — A proven first-mover with commercial experience in autologous CAR-T. Novartis’s strengths lie in integrated commercialization, payer contracting experience and scalable manufacturing know-how. For competitors, Novartis sets the benchmark for post-launch support and provider engagement models.
- Gilead Sciences (Kite) — A dominant commercial engine for CAR-Ts with strategic appetite for portfolio diversification; recent M&A moves and late-stage filings indicate continued expansion in blood-cancer indications. Their deal-making posture makes them a natural partner or acquirer for high-quality BCMA or next-generation CAR portfolios.
- Bristol-Myers Squibb — Combines large oncology sales infrastructure with targeted cell therapy assets. BMS’s integration focus favors therapies that can be lodged within existing oncology pathways and benefit from cross-selling synergies.
- Johnson & Johnson (Janssen/Legend) — Positions itself on the multiple-myeloma and specialty-care axis; leverages deep hospital relationships and commercial scale to optimize uptake in complex inpatient and outpatient settings.
- Vertex — Demonstrates the value of gene-editing platform leverage in autologous cell therapy, with potential to expand into other monogenic conditions. Vertex’s regulatory and manufacturing rigor is an exemplar for companies seeking premium valuation multiples.
- bluebird bio, Vericel, Iovance, Autolus — Represent specialist developers with domain expertise in ex vivo gene-modified cells, tissue-engineered autologous products, and TIL or CAR constructs. These companies are potential consolidation targets or partners for commercial roll-out support.
- Notable regionals (e.g., Pharmicell, Holostem, ProKidney) — While smaller in scale, these organizations illustrate the clinical breadth of autologous approaches and the geographic diffusion of capability, particularly for localized indications and rare-disease niches.
For deal teams, the strategic lens should be: does the target add a clinical differentiation, a manufacturing or logistics advantage, or a payer-proven evidence package? Those three levers most directly compress commercialization timelines and derisk pricing negotiations.
Recent industry developments shaping 2026 strategy
- Late-breaking clinical and commercial preparations : 2025–2026 data readouts and leadership appointments highlight an industry moving from development to scale. Examples include late-breaking echocardiography data indicating potential cardiac remodeling benefits in ischemic heart failure, and companies appointing commercialization leadership ahead of expected launches — signals that an expanding set of indications is approaching commercial inflection.
- M&A and regulatory milestones : Ongoing acquisition activity and high-stakes Biologics License Application acceptances are compressing windows for strategic responses. Expect heightened valuation volatility around positive BLA outcomes and successful PDUFA decisions.
- Comparative clinical performance : New data demonstrating parity between innovative gene-edited or next-generation CAR constructs and established autologous CAR-T programs are likely to shift competitive dynamics, enabling nimble entrants to capture premium access if they can align manufacturing capacity with launch timing.
Three strategic recommendations for executives planning 2026
- Prioritize manufacturing modularity : Move capital decisions toward flexible, semi-automated systems that shorten changeover times and reduce per-patient labor. Consider dual-sourcing critical reagents and contracting with accredited CDMOs as a near-term hedge.
- Invest in evidence generation and payer partnerships : Allocate budget to registry infrastructure and early outcomes agreements. Demonstrating durable benefit will unlock broader reimbursement and justify higher list prices in value propositions tied to avoided downstream costs.
- Adopt a ‘selective scale’ commercialization cadence : Launch in high-yield centers of excellence with controlled capacity scaling tied to demonstrated referral flows and logistic performance. This reduces the risk of launch overspend and protects unit economics while adoption pathways mature.
Conclusion — why PW Consulting’s intelligence is decision-critical for 2026
Autologous cell therapies present a rare combination: rapid market expansion (projected to cross the ten-billion-dollar threshold in 2026) and operational complexity that penalizes poor execution. The market’s 20.15% CAGR through 2032 reinforces why boardrooms must move decisively — yet with a risk-managed playbook that addresses manufacturing, logistics, reimbursement, and regulatory realities. PW Consulting’s full report provides the granular segmentation, regional and application breakdowns, and financial models necessary to make those decisions with confidence.
To review the comprehensive datasets, validation tables, company scorecards, and downloadable modelling workbooks that underpin these findings, please consult the full Worldwide Autologous Cell Therapy Market report available through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Worldwide Autologous Cell Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Handheld Arthroscopic Instrument Market to Rise from USD 2,550 Million in 2025 to USD 3,885.19 Million by 2032 at a 6.2% CAGR
By pmarketresearch, 2026-08-18
Handheld Arthroscopic Instrument Market: Strategic Imperatives for 2026 — PW Consulting Report Highlights
PW Consulting’s new market intelligence brief on the Handheld Arthroscopic Instrument market provides senior leaders with the forward-looking evidence they need to set winning strategies in 2026. Drawing on a rigorous historical analysis (2020–2025) and a detailed forecast horizon (2026–2032), the report quantifies the market’s trajectory, isolates commercial inflection points, and converts clinical and regulatory dynamics into executable options for device OEMs, investors, and health system procurement teams.
Zinc-O,O-Dibutyl Phosphorodithioate Market
Why this report matters for 2026 decision-makers
- Clear growth vector: the global market, measured at USD 2,550 Million in our base year (2025), is projected to expand at a compound annual growth rate (CAGR) of 6.2% through the forecast period — reaching roughly USD 3,885 Million by 2032. This steady momentum frames near-term product, channel, and M&A choices.
- Actionable, scenario-based guidance: instead of high-level commentary, PW Consulting provides playbooks that translate market trends into prioritized initiatives for product development, commercial deployment, and partnering in 2026.
- Competitive clarity without overexposure: the market is meaningfully consolidated, with a clear top-tier of incumbent device manufacturers and a smaller, dynamic cohort of specialist innovators. Our assessment shows where scale protects margins and where agility unlocks white-space opportunities.
Executive takeaways — what senior leaders will use
- Portfolio prioritization: identify which handheld capabilities to accelerate (e.g., articulating tools, powered resection adjuncts, and minimally invasive access systems) and where to defer investment until clinical adoption curves steepen.
- Go-to-market calibration: an evidence-backed framework for allocating commercial investment between direct sales, distributor partnerships, and bundled procedure-supply models that optimize hospital procurement economics.
- Supply chain resilience: a supplier-risk matrix focused on critical inputs (medical-grade stainless steels, precision machining, and sterilization consumables) and mitigations for single-source dependencies.
- Regulatory & reimbursement alignment: mapping device design and labeling priorities to real-world sterilization expectations and common arthroscopy billing pathways, enabling smoother adoption and reimbursement capture.
Market trajectory and the strategic horizon (2026–2032)
PW Consulting’s modeling accounts for demographic tailwinds, procedural volume growth in minimally invasive orthopedics, and incremental technology-driven adoption. With a 6.2% CAGR embedded in our base-case scenario, the market presents a reliable expansion environment rather than a volatile boom-or-bust cycle. This implies that near-term strategic moves—optimization of product portfolios, selective capital deployment, and targeted M&A—will compound value over a multi-year window rather than delivering instant, high-risk returns.
Smart Motion Sensor Light Market
Competitive landscape: incumbents, challengers, and specialist innovators
The handheld arthroscopic instrument arena combines global device powerhouses with nimble specialists. Our competitive mapping categorizes participants by technical breadth, commercial reach, and innovation velocity:
Fully Automatic Thermal Analyzer Market
- Global OEMs with broad portfolios: Companies such as Arthrex, Smith+Nephew, Stryker, CONMED, KARL STORZ, Zimmer Biomet, Medtronic, and Johnson & Johnson (DePuy Synthes) maintain extensive product families and deep institutional relationships—advantages for scale-driven pricing, bundled product offerings, and penetration into major health systems.
- Specialists and disruptors: Firms like Joint Preservation Innovations (JPI) and Richard Wolf demonstrate how focused product innovation can create first-mover clinical differentiation. Notably, JPI secured FDA 510(k) clearance in December 2025 for an articulating rotary cutting instrument designed to address bone access in tight joint spaces — an example of how targeted engineering can open new clinical pathways.
- Strategic implications: incumbents will continue to defend core channels and high-volume indications while partnership or tuck-in M&A remains the most efficient route to acquire articulation, single-use solutions, or novel ergonomic designs from smaller innovators.
Technology, clinical practice, and regulatory dynamics
- Technology convergence: incremental advances — miniaturized articulation, refined powered resection tools, and improved ergonomics — are creating tangible usability improvements that shorten learning curves and reduce procedure times. These improvements translate directly to procurement conversations centered on total procedure cost and surgeon productivity.
- Sterilization and reprocessing pressures: CDC guidance and hospital infection-prevention protocols continue to shape device design choices. Reusable handheld instruments that enter sterile sites must meet sterilization or high-level disinfection expectations in many markets; this reality drives demand for corrosion-resistant materials and serviceable designs that ease reprocessing burden.
- Reimbursement context: common CPT coding practices for arthroscopic procedures influence hospital economics and provider willingness to adopt incremental-cost technologies. Aligning product value propositions to established billing pathways accelerates uptake and shortens procurement cycles.
Commercial playbooks for 2026
PW Consulting provides multiple modular playbooks designed for use in corporate planning cycles and board discussions:
- Fast-follower playbook — For mid-sized players: prioritize acquiring or licensing high-impact ergonomic improvements and focus commercial efforts on specialty centers to establish proof points and case-series outcomes.
- Scale-defend playbook — For incumbents: double down on bundled procedure offers, service contracts, and integrated training programs that lock in institutional adoption while evaluating tuck-in acquisitions to fill surgical gaps.
- Disruptor playbook — For startups and medtech VCs: target niche surgical indications where articulation or miniaturization unlocks clear clinical advantage; leverage regulatory milestones and targeted clinical publications to create acquisition visibility within 18–36 months.
Report contents — what’s inside the full PW Consulting study
The published report goes beyond market numbers to deliver practical tools and evidence that can be used immediately in strategic planning:
- Robust historical demand analysis (2020–2025) and transparent forecasting methodology for 2026–2032, including sensitivity and scenario models.
- Clinical adoption pathways and surgeon preference mapping that explain uptake differentials across device features and procedural types.
- Regulatory and reimbursement playbook — a concise guide for labeling, clinical evidence generation, and CPT-code alignment to support payer conversations.
- Vendor benchmarking and go-to-market frameworks that combine commercial KPIs with tender and contract negotiation tactics.
- M&A target-screening criteria and valuation yardsticks tailored to the market’s current consolidation dynamics.
- Supply chain risk assessment and recommended mitigations for sourcing medical-grade materials and precision manufacturing capacity.
- Confidential annexes — including operational scorecards, unit economics templates, and interview-sourced insights from hospital procurement leaders and orthopedic surgeons (available to licensed report holders).
How PW Consulting converts data into decisions
The hallmark of this study is prescriptive clarity. Each chapter concludes with a short list of recommended decisions that senior leaders can action within 90, 180, and 360 days. Examples include tactical pricing adjustments to protect margin while defending hospital tender wins, near-term product development bets that de-risk clinical adoption, and a prioritized list of capabilities suitable for bolt-on acquisition.
Methodology and credibility
Our conclusions are sourced from a triangulation of primary interviews, surgical procedure databases, hospital procurement surveys, and manufacturer disclosures, cross-validated with market-level financial modeling. The report’s base year is 2025, and our forecast covers 2026–2032 — allowing readers to align strategic initiatives with corporate planning cycles and capital budgets set in 2026.
Next steps — using the insight to act in 2026
- Leadership teams: use the report’s scenario toolkit to test how different commercial investments affect market share and margin across a 3–5 year horizon.
- Product & R&D heads: draw on the clinical insights to prioritize features that reduce OR time, improve reprocessing workflows, or enable new procedural approaches.
- Corporate development teams: leverage the M&A screening criteria to shortlist acquisition targets that deliver immediate capability expansion without disrupting core operations.
- Procurement and hospital administrators: utilize the total-cost-of-ownership frameworks to renegotiate contracts and evaluate supplier consolidation strategies.
Read the full analysis
PW Consulting’s Handheld Arthroscopic Instrument Market report is structured to support decision-making across functions and to serve as the 2026 playbook for growth, defense, and selective disruption. For executives seeking the full datasets, confidential annexes, and the step-by-step implementation roadmaps, please visit PW Consulting’s market reports page to access the complete document and licensing options.
For detailed analysis of this topic, please visit the official page: Handheld Arthroscopic Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
A competitive vehicle in Forza Horizon 6 is built through careful decisions rather than simply adding the most powerful parts available. Every upgrade changes how a car accelerates, brakes, corners, or handles different surfaces. Learning to balance these characteristics allows your Forza Horizon 6 Cars to perform more consistently while reducing the amount of Credits spent on ineffective modifications.
Seasonal competitions make this approach even more valuable. Event restrictions can limit vehicle classes, manufacturers, or performance ratings, meaning a carefully upgraded car may be more useful than an expensive vehicle with unsuitable characteristics. Preparing several Forza Horizon 6 Cars for different purposes gives you greater flexibility whenever new Playlist challenges appear.
Identify The Weakest Area
Before installing anything, test the vehicle and determine where it loses performance. A car that feels slow may not actually need more engine power if its poor cornering causes it to lose momentum.
Watch how the vehicle behaves under braking, through corners, and when accelerating out of turns. Identifying the biggest weakness first allows you to spend Credits where they can produce the most noticeable improvement.
This method is more efficient than applying upgrades randomly.
Give Grip A Strong Foundation
Tires are fundamental to almost every racing build because they influence acceleration, cornering, and braking. Additional grip can help a vehicle maintain speed through turns and transfer power more effectively.
Brakes are another important consideration, particularly on technical circuits. Strong braking performance gives you greater control when approaching tight corners and can help reduce mistakes.
A vehicle with excellent grip and braking can often feel significantly faster even before major engine upgrades are installed.
Improve Stability Through Suspension
Suspension upgrades influence how the vehicle reacts to corners, bumps, jumps, and changes in elevation. The ideal setup depends on the type of race and surface.
Road racing builds generally benefit from predictable cornering and strong stability, while rally and cross-country vehicles need suspension characteristics that can handle uneven terrain without becoming difficult to control.
Test suspension changes on familiar sections of track so you can clearly recognize improvements or unwanted side effects.
Add Engine Power Carefully
Once the car has sufficient grip and stability, additional power can become more useful. However, excessive horsepower may create traction problems and make the vehicle less consistent.
Consider acceleration and top speed together with the track layout. A high-speed circuit with long straights may justify additional engine output, while a technical track may benefit more from improved handling.
Transmission tuning can also help optimize power delivery. Adjust gearing according to whether acceleration or maximum speed is the greater priority.
Build Around Seasonal Requirements
Festival Playlist events frequently introduce restrictions that can make certain vehicles more difficult to use. Preparing multiple builds across different classes gives you more freedom when choosing an eligible car.
Before buying another vehicle, examine whether an existing model can be upgraded to meet the requirement. Players who want to expand their available resources may also explore Forza Horizon 6 Credits for sale for vehicle purchases and upgrade projects.
The most efficient garage is not necessarily the largest one. It is the collection where each vehicle has a useful role.
Keep Testing And Refining
A good setup is rarely finished after one upgrade session. Every race provides information about how the vehicle behaves and where further adjustments might help.
If the car understeers, loses traction, brakes poorly, or feels unstable at high speed, address that specific problem instead of changing everything at once. Small, targeted adjustments make it easier to understand the effect of each modification.
With patient testing, purposeful upgrades, and a versatile collection of buy Forza Horizon 6 Boosting , you can create stronger race builds and approach seasonal competitions with greater confidence throughout Forza Horizon 6.
MMOEXP FC 27 Career Mode: New Negotiations, Transfers, and Features Revealed
By Specific, 2026-08-18
EA Sports FC 27 is bringing one of the biggest Career Mode upgrades in recent years, with the Transfer Market Overhaul becoming one of the most exciting additions for manager-focused players. The new system aims to make transfers feel more realistic, strategic, and unpredictable by introducing smarter negotiations, improved player values, and more authentic club interactions. Ultimate Team players can use FC 27 Coins to sign players, complete upgrades, and build stronger squads.
A More Realistic Transfer Market System
In previous FIFA and EA FC titles, Career Mode transfers often felt repetitive, with unrealistic player prices and predictable AI behavior. FC 27 changes this with a rebuilt transfer market designed to better reflect real-world football. Clubs will now evaluate players differently based on ability, form, potential, and squad needs, making every negotiation feel more meaningful.
The new system also introduces more realistic player valuations, helping prevent situations where elite talents can be signed for unrealistic fees. Managers will need to carefully plan their budgets and identify the right targets instead of simply buying every high-potential player.
AI Clubs Can Compete for Your Transfer Targets
One of the biggest improvements is more active AI involvement in the transfer market. When you attempt to sign a player, rival clubs can now enter negotiations and compete for the same target. This creates more pressure and makes scouting and timing much more important.
For example, discovering a young wonderkid will no longer guarantee an easy signing. Bigger clubs may step in with stronger offers, forcing you to negotiate quickly or consider alternative options.
New Negotiation Options and Deal Structures
FC 27 expands transfer negotiations with new contract and deal options. Managers can use different clauses to create more realistic agreements, including performance-based clauses and buy-back options.
These features add more depth to selling and buying players. Clubs can protect themselves when selling young talents, while buyers can structure deals that reduce financial risks.
Dynamic Player Values and Performance Impact
Another major addition is Dynamic OVR, which allows player ratings and values to change depending on performances, morale, fitness, and development. A player’s market value will no longer remain static throughout a career save.
This means managers must pay attention to player form and development. A young star having a breakout season could become far more expensive, while an experienced player struggling with form may lose value.
How Transfer Overhaul Changes Career Mode
The new transfer system could completely change how players approach Career Mode. Building a squad will require smarter scouting, better financial planning, and more strategic decision-making. Instead of simply searching for the highest-rated players, managers will need to create long-term recruitment plans.
For players who enjoy creating dynasty clubs, rebuilding smaller teams, or developing future stars, the FC 27 Transfer Market Overhaul adds a new level of realism and challenge.
Final Thoughts
The FC 27 Career Mode Transfer Market Overhaul is set to make transfers more competitive, realistic, and rewarding. With smarter AI clubs, improved negotiations, Dynamic OVRs, and deeper deal structures, managing a football club should feel closer to the real world than ever before.
For faster Ultimate Team upgrades, cheap EA FC 27 Coins can provide resources for signing players and building stronger squads. Use code "Specific" for 8% off at MMOEXP.com.
The Super Sprinkler is one of the most useful high-tier Grow a Garden 2 Items for players who want to speed up a prepared crop area. It is designed for concentrated farming sessions, giving nearby plants faster growth and improved size luck while the tool remains active.
Super Sprinkler Quick Facts
The current community-listed version places the Super Sprinkler in the Super rarity tier. It is associated with the Gear Shop and is reported to cost 3,000,000 Sheckles when it appears. A direct Robux option is commonly listed at 399 Robux, while the shop appearance chance is reported at 1.2 percent per restock.
◆ Growth speed: 5x for nearby plants.
◆ Size luck: +100.
◆ Effect radius: 55 studs.
◆ Duration: 2 minutes.
◆ Shop refresh: Commonly tracked at about five minutes.
Prepare the Purchase Fund
Save the full Sheckle amount before actively waiting for the item. Leaving the Gear Shop to earn missing currency can make you miss the rotation, especially when the item appears in limited stock. Keep the reserve separate from money intended for seeds, pets, or plot upgrades.
Use the Gear Shop Route
1. Travel to the central marketplace and open the Gear Shop.
2. Read the countdown shown in the live vendor interface.
3. Farm, harvest, and sell while waiting for the next refresh.
4. Return shortly before the timer reaches zero.
5. Reopen the shop menu after the inventory changes.
6. Look for the purple Super Sprinkler and check its current price.
7. Purchase it immediately if the Sheckle reserve is ready.
At a reported 1.2 percent appearance rate, several failed rotations are normal. The chance is applied to each restock and does not create a guaranteed drop after a fixed number of attempts. Server switching is also not a reliable way to force a different stock pattern, so the in-game timer should remain the main reference.
Prepare the First Activation
Place the Super Sprinkler only after the target garden is ready. Group high-value crops within its 55-stud range, harvest mature fruit, replant premium seeds, and equip any pet that supports growth, collection, mutation, or storage. The two-minute duration is short, so preparation should happen before activation.
When comparing Grow a Garden 2 Items for sale , match the sprinkler with valuable seeds and a useful pet role. The tool creates the strongest result when the surrounding garden is already organized for a complete growth cycle.
Start by saving the full displayed price, then follow the Gear Shop countdown and use every waiting interval to improve the crop zone. Once the sprinkler appears, buy it immediately and activate it only after every important plant is inside the coverage area.
Gold has become a major part of progression in Diablo 4 Season 14. With the gold cap now reaching 999,999,999,999, players have much more room to build a reserve. Still, that does not mean gold should be spent whenever possible. If you are looking to Diablo 4 Gold , the real goal is to turn your earnings into upgrades that make a noticeable difference.
1. Save Gold While Leveling
Early gear is temporary, so spending heavily on it usually gives poor returns.
• Keep enchanting costs low on leveling equipment.
• Sell unwanted Legendary and Rare items when you have enough materials.
• Build a reserve before entering serious Torment content.
• Avoid repeated rerolls on items you expect to replace soon.
Once your core build is established, it becomes much easier to decide when to buy Diablo 4 Gold and where those resources will have the biggest impact.
2. Prioritize Enchanting
Enchanting is one of the first major gold sinks worth planning around. The Occultist can replace an unwanted affix, potentially turning a good drop into a piece that fits your build perfectly.
Look for items that already have:
• Useful Greater Affixes
• Strong item power
• Two or more desirable stats
• A role in your long-term setup
Do not chase a perfect roll forever. Enchanting costs can rise quickly, and a nearly perfect item may not justify endless attempts. Keeping some cheap Diablo 4 Gold available for future upgrades is often the smarter move.
3. Invest in Masterworking
Once you have equipment worth keeping, Masterworking becomes a much better place for your money. Instead of constantly replacing gear, you can improve the pieces already supporting your build.
Focus on:
• Main weapons and damage-focused gear
• Armor with important defensive stats
• Amulets and rings with valuable affixes
• Items that directly support your core skill
A well-developed item can remain useful for a long time, making the investment easier to justify.
4. Use Gold for Targeted Trading
The player economy can save enormous amounts of farming time. Rather than waiting for the perfect drop, you can search for specific gear that matches your build.
This is especially useful when you need a particular Greater Affix, defensive combination, or high-value weapon. Before spending on Diablo 4 Gold for sale, know exactly what upgrade you are targeting. A focused purchase is usually better than spending blindly on several mediocre items.
5. Keep a Reserve for Endgame Crafting
Mythic-related crafting and other high-end upgrades can consume resources quickly. These expenses are better handled after your skills, Paragon setup, and main Legendary items are already working together.
For farming, focus on content such as:
• Escalating Nightmare Dungeons
• Helltides
• Infernal Hordes
• Lair Bosses
Sell excess loot when appropriate, collect useful materials, and keep your spending under control.
Final Thoughts
Season 14 rewards players who treat gold as a resource rather than a score. Save during the early stages, spend on strong gear once your build is established, and avoid gambling your entire reserve on tiny improvements. Whether you earn everything through farming or choose to cheap Diablo 4 Gold , smart spending will help your character reach the highest endgame tiers with far less wasted effort.
SeductiveUtopia Net Fashion Editorial: Redefining Contemporary Men’s Style
By ginevak735, 2026-08-17
Fashion is increasingly shaped by individuality, comfort, and a willingness to move beyond traditional style expectations. The SeductiveUtopia net fashion editorial explores this changing landscape through the lens of contemporary menswear, where clothing, bodywear, proportions, fabrics, and personal expression come together to create a more flexible approach to dressing. Modern fashion is no longer defined by a narrow set of rules, giving individuals greater freedom to develop wardrobes that reflect their lifestyles and personalities.
The Evolution of Modern Menswear
Contemporary menswear is becoming more adaptable than ever. Traditional tailoring remains influential, but it is now appearing alongside relaxed trousers, oversized shirts, lightweight layers, soft knitwear, and casual separates.
This mixture creates opportunities for different styling approaches. A structured jacket can be combined with relaxed trousers, while a simple knit can work with tailored clothing. The contrast between formal and casual pieces often creates a more natural and modern appearance.
Comfort Becomes Part of Style
Comfort is no longer separate from fashion. Consumers increasingly expect clothing to look refined while allowing freedom of movement throughout the day.
Fabric selection plays a major role in this development. Cotton, linen, wool blends, modal, jersey, and flexible performance fabrics can each provide different levels of softness, breathability, and structure. Designers are using these materials to create garments that feel practical without losing visual appeal.
Relaxed Proportions Gain Influence
The popularity of relaxed silhouettes has changed how proportions are understood. Wider trousers, longer shirts, roomy jackets, and softer outer layers can create a contemporary outline without appearing careless.
Balance is important when working with relaxed clothing. Combining a generous silhouette with a more structured or fitted element can help maintain definition. This allows oversized pieces to feel intentional rather than overwhelming.
Personal Expression Shapes Wardrobes
Modern fashion increasingly encourages people to choose clothing according to personal identity rather than strict expectations. Color, texture, accessories, prints, and unusual combinations can all become tools for self-expression.
This approach also makes room for subtle experimentation. A wardrobe does not need to be dramatic to feel distinctive. Small changes in proportion, fabric, or color can transform familiar garments into something more personal.
Bodywear Gains Greater Attention
Underwear and other bodywear are also becoming important parts of contemporary wardrobe planning. Fit, fabric, support, and silhouette can influence how outer clothing feels and performs.
Boxer briefs, trunks, briefs, undershirts, and base layers can serve different purposes. Choosing the right style for a particular outfit or activity can improve comfort while creating a more effective foundation for the rest of the wardrobe.
Color Trends Become More Flexible
Neutral colors remain important because they provide reliable foundations for everyday dressing. Black, white, gray, navy, beige, and brown can be combined easily across different outfits.
However, modern menswear is also becoming more comfortable with expressive shades. Deep green, muted blue, burgundy, warm orange, and soft pastel tones can introduce personality without dominating an entire outfit.
Layering Creates Versatility
Layering is another powerful tool in contemporary fashion. Overshirts, lightweight jackets, cardigans, vests, and relaxed blazers can add depth while allowing an outfit to adapt to changing temperatures.
Successful layering often depends on proportion. Different lengths and textures can create visual interest, while keeping the overall color palette coordinated helps the outfit remain cohesive.
Quality Over Excess
A modern wardrobe does not need to contain an enormous number of garments. A smaller collection of versatile, well-made pieces can provide more styling possibilities than a large selection of items that rarely work together.
Durability is also becoming increasingly important. Clothing that maintains its shape, color, and comfort through regular use can provide greater long-term value and encourage more thoughtful consumption.
Digital Fashion Culture Influences Trends
Online fashion communities have changed how trends develop and spread. Editorial platforms, independent creators, visual content, and social discussions can introduce new styling ideas to audiences around the world.
This has made fashion more interactive. Consumers can discover different approaches, share their own combinations, and participate in style conversations rather than simply following traditional fashion authorities.
Creating a Distinctive Personal Wardrobe
The strongest contemporary wardrobe is built around individual needs. Work, travel, social occasions, exercise, relaxation, and seasonal conditions can all influence clothing choices.
Instead of following every trend, individuals can select the elements that complement their lifestyle. A combination of dependable basics, expressive pieces, comfortable bodywear, and adaptable layers can create a wardrobe that feels both modern and authentic.
Conclusion
The SeductiveUtopia net fashion editorial perspective reflects a broader transformation in contemporary menswear. Comfort, relaxed proportions, personal expression, versatile bodywear, thoughtful layering, expressive color, and quality are increasingly shaping how modern wardrobes are created. Fashion is becoming less about rigid expectations and more about making deliberate choices that support individuality, confidence, and everyday life.
Making Stairs Safe and Stylish: Enhancing Your Space with Metal Hand Rails for Steps
By towiy59840, 2026-08-17
When it comes to the safety and aesthetics of your staircase, metal hand rails for steps play a crucial role. These handrails not only provide support and stability but also add a touch of elegance to any space. Whether you are looking to upgrade your home or commercial property, investing in high-quality handrails can make a significant difference.
The Importance of Metal Hand Rails for Steps
Enhancing the safety of staircases is paramount in any building. Metal handrails are known for their durability and strength, offering reliable support for individuals navigating steps. The sleek design of metal handrails can complement various architectural styles, making them a versatile choice for both modern and traditional spaces.
Benefits of Choosing Metal Hand Rails
One of the key advantages of metal handrails is their longevity. Unlike other materials that may wear out over time, metal handrails are built to last, making them a cost-effective investment in the long run. Additionally, metal handrails are easy to maintain and clean, ensuring that your staircase always looks its best.
Customization Options
At TLB, we offer a wide range of customization options for metal hand rails. From different finishes to unique designs, you can personalize your handrails to suit your specific preferences and needs. Our team of experts can work with you to create handrails that not only enhance safety but also elevate the overall look of your staircase.
Enhancing Your Space with TLB Metal Hand Rails
TLB is a trusted name in the industry, known for delivering top-quality metal handrails that exceed expectations. Our commitment to craftsmanship and customer satisfaction sets us apart, making us the preferred choice for those seeking premium handrail solutions.
Installation Process
When you choose TLB for your metal handrail needs, you can expect a seamless installation process. Our experienced team will ensure that your handrails are installed securely and efficiently, giving you peace of mind knowing that your staircase is safe and stylish.
Customer Satisfaction Guarantee
At TLB, customer satisfaction is our top priority. We take pride in our work and strive to exceed customer expectations with every project. When you choose TLB for your metal handrail needs, you can trust that you are getting a product that is not only functional but also visually appealing.
Conclusion
Investing in metal hand rails for steps is a smart choice for anyone looking to enhance the safety and aesthetics of their staircase. With TLB's premium handrail solutions, you can transform your space into a stylish and secure environment. Consider reaching out to TLB for more information on how our metal handrails can elevate your staircase.