

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Rare Hemophilia Factors Market Valued at USD 1,706.89 Million in 2025, Poised for Continued Growth Through 2032

Worldwide Rare Hemophilia Factors Market: Strategic Imperatives for 2026 — PW Consulting Preview
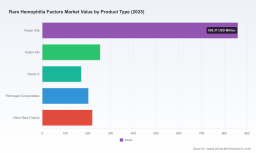
As life‑cycle management, reimbursement pressure and supply‑chain fragilities converge, executives in biotech, specialty pharma and plasma‑derived therapeutics must refine their 2026 strategies with unprecedented granularity. PW Consulting’s new Worldwide Rare Hemophilia Factors Market report (base year 2025, forecast period 2026–2032) synthesizes primary research, quantitative modelling and scenario analysis to deliver the actionable intelligence that senior leaders need. The global rare hemophilia factors market reached USD 1,706.9 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 4.8% through 2032, reaching roughly USD 2.37 Billion by the end of the forecast period. This preview outlines the report’s strategic value for 2026 decision‑making while reserving detailed segment and regional breakdowns for the full study.
Worldwide Manufacturing Execution Software Market
Why this report matters for 2026 planning
-
Timing: The market is at a pivot point. A blend of regulatory approvals for novel rebalancing therapies and maturing recombinant/plasma‑derived portfolios means 2026 is when strategic commitments (manufacturing capacity, licensing deals, clinical investments) begin to lock in future revenue profiles.
Biofouling Management Service Market -
Concentration risk: The market remains concentrated — our analysis shows the top three players account for a substantial majority of revenues, with the top five capturing over four‑fifths of the market. This structural characteristic elevates the importance of M&A, distribution alliances and tender strategies.
Worldwide Cross Linked Sodium Carboxymethyl Cellulose Market -
Operational fragility: Downstream demand is sensitive to plasma availability, manufacturing throughput and regulatory compliance cadence. Companies that address raw material sourcing and scalable viral‑safety platforms will have a disproportionate competitive advantage.
What the PW Consulting report contains (practical, deal‑ready modules)
-
Market sizing and forecast models — transparent methodology, reproducible assumptions and scenario variants (baseline, conservative, disruption) that incorporate both therapeutic substitution and novel prophylactic approaches.
-
Competitor scorecards — comparative assessments of portfolio breadth, manufacturing footprint, regulatory pathway readiness, and commercial reach. Each scorecard includes tactical considerations for partnerships, licensing and geographic prioritization.
-
Clinical and pipeline mapping — end‑to‑end view of therapies in late‑stage development, expected launch windows, and potential cross‑elasticities between factor replacement and non‑factor rebalancing agents.
-
Supply‑chain due diligence toolkit — risk heatmaps for plasma sourcing, virus‑inactivation capacity, contract manufacturing organization (CMO) dependencies, and practical mitigation playbooks for short‑term shocks.
-
Reimbursement and pricing playbook — country‑specific reimbursement levers, tender dynamics, payer negotiation templates and real‑world evidence (RWE) strategies to accelerate access for rare indications.
-
Commercial roll‑out templates — launch sequencing, HCP engagement plans, patient registry integration, and distribution channel optimisation for both hospital and outpatient settings.
-
M&A and partnership screening matrices — prioritized targets by strategic fit, valuation heuristics for niche factor assets, and integration checklists to protect margin and continuity of supply post‑transaction.
Competitive landscape — tactical insights on incumbent positions
The market is guarded by established manufacturers with differentiated capabilities across plasma‑derived and recombinant technologies. PW Consulting’s competitive analysis profiles each major player and highlights where contestability is increasing:
-
CSL Behring — strong in plasma‑derived Factor XIII solutions and with established capabilities in viral safety and large‑scale plasma processing. Their strength is operational resilience and proven prophylaxis product offerings; competitors should evaluate licensing or co‑sourcing rather than head‑on capacity competition.
-
Novo Nordisk — notable for its recombinant Factor VIIa product and recombinant Factor XIII A‑subunit offering. The company’s development of non‑factor reagents and subcutaneous delivery platforms positions it to influence standard‑of‑care evolution; strategic partners should consider combination therapy trials and complementary distribution arrangements.
-
Bio Products Laboratory (BPL) — niche leadership in hereditary Factor X therapeutics and selective regional presence for other concentrates. BPL’s strength is agility in regional approvals and tailored supply to localized protocols.
-
Takeda (Baxalta portfolio), Grifols and Octapharma — collectively important for their plasma‑derived portfolios, diversified product lines and global plasma networks. Their bargaining power with payers and hospitals is significant, making them role players in tender landscapes.
-
Pfizer and Bayer — major global commercial platforms and development capabilities in recombinant factors and adjunctive therapies; they are potential acquirers or collaborators for companies seeking scale and go‑to‑market breadth.
Recent regulatory developments are shaping therapeutic substitution and payer behaviour. Notably, FDA approvals of novel rebalancing agents and ongoing expansions for established recombinant and plasma‑derived concentrates are changing the care paradigm. These approvals broaden prophylaxis options and create headwinds for some factor replacement volumes, while expanding total addressable treatment episodes in certain patient cohorts.
Key dynamics executives must weigh in 2026
-
Therapeutic substitution risk vs. market expansion: Non‑factor modalities that rebalance coagulation (recent approvals in 2024–2025) can displace some factor replacement use but also expand prophylaxis uptake. Strategic product positioning and evidence generation around severity‑specific outcomes will determine which companies gain share.
-
Plasma supply and processing constraints: Plasma remains the principal raw material for many concentrates. Executives must quantify exposure (sourcing concentration, donor base stability) and implement contingency plans that include inventory buffers, diversified sourcing and investments in recombinant alternatives.
-
Regulatory and reimbursement alignment: Although many concentrates have established regulatory precedents, payer policies (including government‑supported programs and grants in major markets) materially affect access. Robust health economic models and early payer engagement are essential.
-
Consolidation opportunities: High market concentration leaves room for bolt‑on acquisitions in niche factors, but bidders must factor in integration risks and the cost of safeguarding supply continuity.
Actionable recommendations for 2026 strategy
-
Secure raw material resilience: Negotiate multi‑year plasma supply agreements, qualify additional CMOs and accelerate recombinant/alternative platform investments to reduce single‑source exposure.
-
Prioritise differentiated value propositions: Invest in delivery improvements (e.g., subcutaneous options), label expansions supported by real‑world effectiveness data and co‑develop patient support programs to bolster adherence and justify premium positioning.
-
Accelerate payer evidence generation: Deploy targeted RWE pilots and health economic dossiers in parallel with regulatory submissions to shorten time to favourable reimbursement decisions post‑launch.
-
Be opportunistic on M&A and licensing: Use concentrated market structure to acquire niche factor assets or secure regional distribution deals where incumbents lack reach.
-
Model disruption scenarios: Build integrated forecasts that include the uptake of non‑factor prophylactics, changing treatment patterns and tender volatility. Treat these as planning inputs for capacity and commercial investment decisions.
The strategic value of PW Consulting’s full report
This preview highlights the directional insights executives need to prioritize in 2026. The full report equips decision‑makers with the granular tools to act: downloadable financial models, country‑level access roadmaps, competitor dossier appendices, transaction valuation templates and detailed operational checklists. We intentionally reserve the granular segment and regional tables for the complete publication to ensure stakeholders access the full, source‑level datasets and interactive models through our platform.
For teams preparing board presentations, M&A diligence packets or launch playbooks, the report reduces execution risk by converting diffuse market noise into prioritized, executable initiatives. With a projected market trajectory showing sustained growth at a 4.8% CAGR through 2032 and clear concentration among incumbent players, 2026 decisions will disproportionately influence market positions for the rest of the decade.
Next steps
-
Contact PW Consulting to obtain the full Worldwide Rare Hemophilia Factors Market report, access the interactive modelling workbook and schedule a briefing with our senior analysts for tailored scenario workshops.
-
Use the report as the foundation for a six‑month strategic plan: immediate supply‑chain audits, a 12‑month payer evidence timeline, and a 24‑month M&A screening and integration plan.
PW Consulting’s team of industry specialists has compiled this study to help executive teams convert complexity into clarity. For confidential conversations about how the findings apply to your portfolio or to request a customised research addendum, please reach out to our advisory desk to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Rare Hemophilia Factors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com