

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Diphenylmethanol Market to Rise from USD 398.15 Million in 2025 to USD 552.07 Million by 2032 at a 4.78% CAGR — Asia Pacific Leads with USD 184.94M
By pmarketresearch, 2026-07-06
Diphenylmethanol Market Outlook 2026: Strategic Imperatives for Decision-Makers
Executive Snapshot
As PW Consulting’s lead industry analysis for the Diphenylmethanol market, this briefing translates our new market study into targeted strategic guidance for 2026 decision-makers. The global market for diphenylmethanol has shown steady expansion through the historical window and is projected to continue growing across the 2026–2032 forecast horizon at a mid-single-digit compound annual growth rate (CAGR) of approximately 4.78%. Our 2025 base-year modelling signals a clear, investable trajectory: predictable growth with pockets of margin upside for firms that proactively manage feedstock exposure, product-grade differentiation, and regulatory compliance.
Diphenylmethanol Market
Why this matters for 2026 planning
-
Predictability with nuance: A CAGR near 4.8% indicates demand stability rather than hypergrowth — an environment where operational excellence, cost control, and targeted differentiation drive returns more reliably than broad capacity bets.
Diphenylmethanol Market -
Concentration and competition: Market concentration metrics show a moderate level of consolidation: the top three and top five suppliers account for a meaningful share of the market, leaving an accessible runway for specialized or regional players to win niche positions through quality, service, or integrated solutions.
Diphenylmethanol Market -
Feedstock and process exposure: Benzophenone is the dominant upstream feedstock and conventional reduction chemistries remain the production mainstay; raw material dynamics and process selection are therefore principal levers for cost structure and sustainability narratives.
Market trajectory — what the numbers imply
Our analysis integrates historic demand patterns and an exhaustive set of primary and secondary inputs to produce a forward view that balances macro drivers (pharmaceutical production and specialty chemical applications) with micro dynamics (supplier capabilities and feedstock supply). The market in 2025 represents the platform from which near-term strategic choices will compound: modest, predictable growth means companies can capture disproportionate value via margin improvement and selective vertical integration rather than relying solely on volume expansion.
Operational and commercial dynamics to watch in 2026
-
Feedstock security and cost management: Because benzophenone is the primary upstream feedstock and established reduction routes (catalytic hydrogenation, metal-reduction processes such as aluminum/caustic or zinc/alkaline systems) remain standard, procurement strategies that lock favorable benzophenone terms or diversify feedstock pathways will materially reduce volatility.
-
Process choice and CAPEX prioritization: Firms deciding between conventional metal-based reductions and hydrogenation options should weigh capital intensity against unit-cost trajectory and environmental compliance. Investments in hydrogenation catalysts and selective processes can unlock long-term cost and environmental advantages, but require disciplined CAPEX phasing to match demand growth.
-
Grade differentiation: The market rewards clear quality segmentation — pharmaceutical-grade and technical-grade product streams each follow distinct purchasing behaviours. Companies that codify QC workflows, certifications, and supply-chain traceability will extract premium pricing in regulated end-markets.
-
Regulatory posture: Current classification under CLP identifies diphenylmethanol as a skin and eye irritant with specific target organ considerations. It is not presently listed under the most restrictive REACH annexes for authorisation or restriction, a fact that informs near-term go-to-market and export planning but does not eliminate the need for stringent SDS and handling protocols.
Competitive landscape — what differentiates winners
The supplier universe comprises custom synthesis specialists, regional-volume manufacturers, and global laboratory reagent houses. Our qualitative assessment of incumbent players reveals three dominant pathways to competitive advantage:
-
Specialty and custom-synthesis excellence: Companies that offer scale-up capabilities from grams to kilograms with tight purity profiles and bespoke service models hold strong appeal to pharmaceutical developers and specialty end-users.
-
Cost leadership through localized scale: Regional producers that optimize feedstock sourcing and cost structures can serve industrial and agrochemical channels effectively where price sensitivity is higher.
-
Brand trust and distribution reach: Established laboratory and reagent suppliers maintain value in R&D and analytical markets via global distribution networks and trusted standards/grades.
Representative company profiles in our coverage illustrate these archetypes — from Asia-based custom synthesis and specialty-chemical manufacturers to global reagent suppliers with multi-format packaging and quality stewardship. Each profile within the full report includes capability maps, strategic intent indicators, and a supplier-fit framework to align vendor selection with buyer priorities.
Supply chain and manufacturing insights
Operational case work in the study details common process routes and practical implications. Documented production methods include catalytic hydrogenation and metal/alkali reduction chemistries; one mature industrial route uses aluminum powder with caustic soda in methanol as a reductive pathway with subsequent work-up and drying steps. These process choices impact waste streams, operator safety requirements, and capex/opex mixes — and therefore should influence plant design, environmental permitting, and margin modelling in 2026 decisions.
Regulatory and safety context
From a compliance perspective, diphenylmethanol is classified under CLP as Skin Irrit. 2 (H315), Eye Irrit. 2 (H319), and STOT SE 3 (H335). Importantly for exporters and formulators, it is not currently subject to REACH Annex XIV authorisation or Annex XVII restriction listings. While that reduces immediate regulatory friction in relevant jurisdictions, the compound’s hazard profile necessitates robust SDS management, worker-protection programs, and customer-facing documentation — all of which are evaluated in our supplier scorecards.
What the full report contains — pragmatic assets for 2026 execution
-
Actionable scenario analyses: upside/downside demand cases tied to pharmaceutical product pipelines, agrochemical cycles, and specialty formulation trends.
-
Price and margin modelling: input-cost sensitivity analyses that let commercial teams stress-test price floors and corridor strategies under feedstock and energy shocks.
-
Supplier scorecards and diligence templates: standardized assessment tools for procurement and M&A teams to evaluate manufacturing quality, regulatory hygiene, and strategic fit.
-
Investment case frameworks: decision matrices for greenfield versus brownfield expansion, retrofitting hydrogenation capability, and acquisition screening criteria.
-
Go-to-market playbooks: differentiated value propositions and channel strategies for high-purity pharmaceutical intermediates versus industrial-grade supply.
Note: This press summary highlights the practical outputs available in the full study. Detailed segment-level data, regional and application splits, and company market shares are reserved for the report itself to preserve the context and comparability that buyers require when making commercial decisions.
Strategic recommendations for 2026
-
For producers: Prioritize feedstock security and evaluate incremental investments in cleaner hydrogenation technology where feasible. Adopt formalized grade-segmentation commercial strategies to capture higher-margin pharmaceutical demand.
-
For buyers (pharma and specialty formulators): Lock multi-year supply terms with quality clauses and audit rights. Favor suppliers that demonstrate process transparency and upstream-benzophenone traceability.
-
For investors and corporate development teams: Target bolt-on acquisitions that add high-purity production capability or regional distribution footprints. Use the market’s steady CAGR to model disciplined, cash-flow-focused returns rather than aggressive volume expansion.
-
For sustainability and operations leads: Quantify emissions and waste differentials between reduction chemistries and prioritize projects that reduce hazardous byproducts and improve energy efficiency.
How PW Consulting’s study supports 2026 decisions
Our Diphenylmethanol market study is intentionally structured as an operational playbook: it translates market sizing and growth modelling into procurement tools, capex prioritization roadmaps, and supplier-fit diagnostics. It equips C-suite leaders, strategy teams, and commercial heads with the context and instruments needed to translate the market’s predictable growth into sustainable margin and share gains during 2026.
Next steps
For access to the complete dataset, granular segmentation, supplier market shares, and downloadable commercial templates referenced above, please visit PW Consulting’s report portal. The full report contains the detailed regional and application breakdowns, primary interview excerpts, and proprietary pricing models omitted from this summary to preserve comparative integrity for clients and subscribers.
For detailed analysis of this topic, please visit the official page: Diphenylmethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Handheld Devices Command 58.41% of Portable Keratometer Market as Industry Eyes 6.75% CAGR Through 2032
By pmarketresearch, 2026-07-06
Portable Keratometer Market: Strategic Imperatives for 2026 — PW Consulting Release
PW Consulting today publishes a strategic preview of our latest Portable Keratometer Market study, designed for C-suite decision makers, corporate strategy teams, product leaders and investors who need an evidence-led playbook for 2026. Grounded in a rigorous historical review (2020–2025) and a seven-year forecast (2026–2032), the report synthesizes commercial, clinical and regulatory dynamics that will determine winners in an evolving portable ophthalmic diagnostics ecosystem.
Portable Keratometer Market
Why this report matters for 2026 planning
Portable keratometers have moved from niche field tools to core assets within hybrid eye-care delivery models — from outreach missions and mobile clinics to integrated point-of-care workflows in ambulatory surgery centers. Our analysis shows a resilient market that expanded through 2025, reaching an estimated market size of USD 73.15 Million in the base year, and is projected to continue expanding at a steady compound annual growth rate of approximately 6.75% over the forecast period. Underlying that headline growth is a mix of accelerating adoption in non-traditional care settings, incremental product innovation (miniaturization, sensor fusion, and app-based analytics), and tighter integration with biometry and refractive platforms.
Portable Keratometer Market
For executives preparing 2026 budgets and three- to five-year roadmaps, the practical implications are clear: invest selectively in portable keratometry if your strategy depends on mobility, cost-optimized refractive screening, or bundle offerings around mobile surgical services. However, the financial upside is best realized by pairing device capability with service models — training, tele-interpretation, and deployment logistics — rather than relying solely on unit sales.
Portable Keratometer Market
What the report delivers — actionable, decision-focused content
- Market sizing and trend narrative: A reconciled historical dataset (2020–2025) and scenario-based forecasts to 2032 that reflect demand elasticity under differing adoption and reimbursement assumptions.
- Go-to-market playbooks: Practical routes to scale in low-resource and premium settings, including channel mix, pricing approaches, and partnership architectures that reduce time-to-adoption.
- Product and technology roadmap guidance: Comparative evaluation of key design trade-offs (handheld ergonomics vs. tabletop-dock versatility; sensor accuracy vs. throughput; local processing vs. cloud analytics) to inform R&D prioritization and M&A screening.
- Regulatory and standards checklist: Mileposts for 510(k) strategies, EU MDR conformity, and ISO standards compliance to avoid time-consuming rework during product commercialization.
- Procurement model templates: Cost-of-ownership frameworks tailored for hospital buyers, NGO procurement teams, and mobile clinic operators — including sample KPIs for uptime, calibration cadence, and operator training requirements.
- Risk heatmaps and mitigation strategies: Operational, regulatory and competitive risks prioritized by likelihood and impact, with recommended mitigations that can be executed within six to 18 months.
The report is deliberately structured to be operational from day one — with executive checklists, an investment decision matrix, and templated vendor evaluation criteria. To preserve strategic value for paying subscribers, detailed segment-by-segment revenue tables and unit-level pricing schedules are available in the full report.
Competitive landscape — concentration and strategic profiles
The portable keratometer market exhibits moderate concentration: the top three vendors account for a meaningful share of the market, and the top five consolidate an even larger portion of available revenues. This concentration presents both risks and opportunities. Established suppliers benefit from brand trust and distribution scale, while agile entrants can capture share by addressing unserved niches — particularly in mobile outreach and low-cost screening.
- Micro Medical Devices (United States) — Micro Medical Devices has positioned its PalmScan PRO and K2000 portable keratometer probe as a field-deployable solution tightly integrated with biometry systems. Their recent mission deployments demonstrate the commercial and reputational benefits of proving devices in real-world outreach programs. Website: https://micromedinc.com/
- PlenOptika (United States) — PlenOptika’s QuickSee Free Pro leverages wavefront aberrometry to deliver clinical-grade refraction and keratometry in a handheld form factor. The company’s platform emphasis is on software and mobile integration; a mid-2025 app update underscores the competitive importance of a robust companion software ecosystem. Website: https://plenoptika.com/
- NIDEK (Japan) — NIDEK’s HandyRef-K demonstrates how incumbent ophthalmic OEMs are adapting core technologies for portable use, addressing both clinic overflow and supine/mobile patient workflows. Website: https://www.nidek-intl.com/
- Marco (United States) — Marco competes with portable ARK devices intended for anytime/anywhere refraction and keratometry, leveraging service networks to support clinicians. Website: https://marco.com/
- Devine Meditech (India) — Focused on cost-effective handheld auto-keratometers, Devine Meditech is an example of regional players filling affordability gaps, especially in emerging markets. Website: https://devinemeditech.com/
- Reichert (AMETEK) (United States) — Reichert offers portable-capable keratometry within a broader ophthalmic diagnostics portfolio, an approach that supports cross-selling into existing installed bases. Website: https://www.reichert.com/
- Huvitz (South Korea) — Huvitz brings portable-compatible ref/keratometers to market, emphasizing ergonomic design and compatibility across refraction workflows. Website: https://www.huvitz.com/
Recent vendor activity highlights how competition is shifting from hardware-only differentiation to software-enabled clinical workflows and field validation. Notable examples include PlenOptika’s February 2025 companion app upgrade and Micro Medical Devices’ documented mission deployment in late 2025. These moves signal that clinical integration and proof-of-field efficacy are decisive purchase triggers.
Regulatory, standards and reimbursement dynamics
Understanding the regulatory and standards environment is critical to getting to market quickly and sustaining commercial traction. Key considerations covered in the report include:
- Regulatory classification: In the United States, auto-keratometers are regulated as Class II devices under FDA 21 CFR Part 886.1500 and typically require 510(k) premarket notification. This drives specific evidence requirements around performance and equivalence.
- European market access: Devices fall under EU MDR 2017/745 classifications that necessitate conformity assessment and ongoing post-market surveillance — a material cost and timeline factor for international launches.
- Standards compliance: ISO 15004-1:2020 establishes test methods and fundamental requirements for non-invasive ophthalmic instruments; alignment with recognized consensus standards can streamline regulatory submissions and reduce review risk.
The report includes a practical timeline for regulatory filings, a prioritized list of performance tests to commission (bench and clinical), and templates for post-market surveillance plans that meet MDR expectations while minimizing surveillance overhead.
Strategic takeaways for 2026 decision cycles
- Prioritize integration over replacement: Buyers increasingly favor keratometers that integrate with biometry and refraction ecosystems. Providers should demonstrate interoperability and data portability as primary value drivers.
- Segment go-to-market by use-case economics: High-throughput ambulatory centers have different payback horizons than mission-driven NGOs or primary-care screening programs. Tailor commercial models — service bundles, device-as-a-service, and volume discounts — to the economics of each buyer segment.
- Invest in software and clinical evidence: App ecosystems, cloud analytics and validated clinical workflows yield disproportionate returns versus marginal hardware improvements. Clinical validation in target use environments (e.g., supine, low-light, pediatric) is a competitive moat.
- Plan regulatory pathways early: For entrants eyeing international scale, prepare parallel regulatory strategies and designate engineering resources to meet MDR and ISO requirements to avoid staggered launches.
- Use procurement KPIs to win long-term contracts: Vendors that commit to measurable uptime, calibration turn-around, and operator training can shorten procurement cycles and secure bundled service contracts.
How to use this preview — and where to find the full intelligence
This release is a strategic preview intended to help leadership teams prioritize initiatives for 2026. PW Consulting’s full Portable Keratometer Market report contains the granular segmentation tables, scenario-model outputs, vendor benchmarking matrices and downloadable procurement templates that buyers and investors rely on when committing capital or entering partnerships.
If your 2026 strategy depends on portable keratometry — whether to scale mobile eye-care programs, defend share in ambulatory settings, or evaluate acquisition candidates — the full report equips you with the data and executable frameworks needed to act confidently. Detailed segment revenue breakdowns, unit economics, and modeled sensitivity analyses are available in the complete study.
To request an executive briefing or access the full report, please contact your PW Consulting account representative or visit our website for subscription options and licensing details.
For detailed analysis of this topic, please visit the official page: Portable Keratometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Livestock Genetic Engineering Vaccines Market to Surge at a 7.69% CAGR Through 2032
By pmarketresearch, 2026-07-06
Livestock Genetic Engineering Vaccines: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive snapshot
PW Consulting’s latest Livestock Genetic Engineering Vaccines Market study delivers a pragmatic, strategy-first view for executive teams, investors, and R&D leaders preparing decisions in 2026. The worldwide market for genetic-engineering-enabled livestock vaccines has demonstrated sustained expansion — growing from approximately USD 1,980 million in 2020 to USD 2,850 million in 2025 — and our model projects a continuation of that trajectory through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 7.69%. By 2032, the market is expected to approach the USD 4,788 million mark under our base scenario.
Livestock Genetic Engineering Vaccines Market
This press briefing outlines why these macro dynamics matter to corporate strategy, what to prioritize in the near term, and how leading players are positioning themselves — while preserving the detailed, segment-level analytics and client-ready playbooks that are reserved for subscribers of the full report.
Livestock Genetic Engineering Vaccines Market
Why 2026 is a decision inflection point
-
Regulatory inflection: Conditional pathways for nucleic-acid and novel-platform veterinary vaccines are maturing. Conditional licenses and expanded guidance for mRNA/DNA products are enabling earlier market entry but require targeted evidence-generation plans. Executives must translate conditional approvals into commercial and post-market strategies rather than treating them as “light” regulatory outcomes.
Livestock Genetic Engineering Vaccines Market -
Platform economics: Advances in mRNA, reverse genetics, and recombinant vector approaches shorten time-to-antigen and widen the range of targetable pathogens. Yet the manufacturing and cold-chain realities materially affect unit economics. Investment timing in scale-up vs. flexible, modular capacity is now a core strategic choice.
-
Consolidation vs. specialization: The market shows moderate concentration — our competitive analysis indicates a Top‑3/Top‑5 market concentration profile that favors scale players with expansive species portfolios, while specialized and regional innovators retain strong tactical and innovation advantages. The next 24 months will determine whether scale converges further through M&A or whether technology specialization spawns high-value niches.
-
Data-driven productization: AI-assisted antigen design and multi-epitope constructs are moving from lab proofs to pilot programs. Organizations that pair computational design with pragmatic field validation will significantly shorten commercialization cycles for rapidly mutating pathogens.
What the report delivers (practical, board-level assets)
The PW Consulting report is constructed to move from insight to action. Key deliverables include:
-
Proprietary market model and scenario runs — top-line market trajectory, upside/downside cases, and sensitivity to adoption rates, regulatory timing, and manufacturing constraints.
-
Regulatory pathway mapping — decision trees for conditional vs. full approvals across major veterinary jurisdictions, evidence packages required for scale-up, and recommended post-authorization surveillance designs.
-
Commercial readiness playbook — species-specific go-to-market templates, cold-chain and distribution viability checklists, pricing and reimbursement levers, and commercialization KPIs keyed to herd-level economics.
-
Manufacturing and supply-chain assessment — capital vs. outsourcing trade-offs, raw-material risk scoring (with cold-chain implications), and vendor due diligence templates for critical biological inputs.
-
Competitive benchmarks and deal-screen frameworks — comparative scorecards for platform maturity, pipeline breadth, regulatory posture, and cultural fit to support M&A and partnerships.
-
Operational playbooks for rapid response launches — clinical-to-commercial timelines, field efficacy validation protocols, and stakeholder engagement frameworks (veterinarians, producers, regulators).
Competitive landscape: strategic positioning of leading players
The industry combines incumbents with broad animal-health portfolios and agile specialists focused on platform or regional strength. Key players featured in our competitive analysis and the strategic takeaways include:
-
Zoetis Inc. — As a leader with deep recombinant and next‑generation investments, Zoetis is advancing mRNA and genetic platforms while leveraging global commercial reach. Strategic consideration: Zoetis’ scale reduces per-unit go‑to‑market friction; competitors should evaluate opportunistic alliance models or co-development to access its distribution footprint.
-
Merck Animal Health — Merck’s SEQUIVITY and related RNA-particle technologies position it to respond to influenza and other high-variability pathogens. Strategic consideration: Product differentiation will hinge on robust field efficacy packages; Merck’s modular platform could become a catalytic partner for smaller innovators.
-
Boehringer Ingelheim Animal Health — Strong in recombinant vectors and biologics, Boehringer’s investment cadence suggests continued focus on multi-species vaccines and biologics. Strategic consideration: Competitors should monitor its pipeline and consider niche-technology counters or specialization in underaddressed indications.
-
Elanco Animal Health — Active in recombinant and mRNA development and recent collaborative pushes into HPAI solutions suggest an aggressive commercialization timetable. Strategic consideration: Elanco’s partnership-led approach is a viable route for academic innovators or CDMOs seeking scale-up partners.
-
Regional and specialist players (Ceva, HIPRA, Vaxxinova, Cambridge Technologies) — These firms combine focused technical strengths and regional market knowledge. Strategic consideration: Their agility makes them valuable targets for licensing deals or bolt-on acquisitions by global players seeking local market penetration or technology access.
Recent catalyst events to watch (2025–2026)
-
Regulatory approvals and conditional authorizations for avian influenza and other targeted vaccines are increasing regulatory precedent.
-
Partnerships between industry and public research institutions — including collaborations aimed at regionally appropriate vaccines for low- and middle-income countries — are accelerating technology transfer and field validation paradigms.
-
Academic advancements in AI-driven antigen design are translating into faster candidate nomination and multi-epitope constructs for challenging pathogens.
Operational and commercial risks that must be managed in 2026
-
Cold-chain and raw-material scarcity: Recombinant and nucleic-acid platforms place premium demands on cold logistics and specialized inputs — cost and availability must be included in go/no-go plant sizing.
-
Regulatory complexity: Conditional licenses require tightly coordinated post-market surveillance and data-collection investments to convert conditional status into durable commercial adoption.
-
Market education: Field uptake depends on veterinary confidence and producer economics. Evidence packages must demonstrate not only safety and serology but tangible herd-level benefits.
-
IP and freedom-to-operate: The landscape contains platform and process IP that can shape partnership structures and royalty regimes; clear FTO analysis is essential prior to scale commitments.
Actionable 90–180 day roadmap for C-suite and investors
-
Conduct a heat‑map review of your pipeline vs. regulatory readiness: classify programs by required evidence, time-to-conditional approval, and commercial levers for adoption.
-
Lock in strategic partnerships for manufacturing flexibility: secure options with CDMOs that offer modular capacity and validated cold-chain solutions to avoid long lead-time exposure.
-
Initiate targeted regulatory engagement: pre-submission meetings and conditional license strategy sessions should be scheduled now to align study designs with jurisdictional expectations.
-
Design a field-evidence playbook: invest in pragmatic, on-farm efficacy pilots tied to producer KPIs (mortality, feed conversion, reproductive performance) to accelerate adoption.
-
Perform a capital allocation stress test: model scenarios for accelerated commercialization vs. delayed roll-out to set thresholds for M&A, partnership, or capex decisions.
KPIs and metrics we recommend tracking in 2026
-
Time-to-conditional license and time-to-full approval by jurisdiction.
-
Field-efficacy delta versus incumbent vaccines on producer economics (e.g., reduction in disease incidence, herd-level ROI timeframe).
-
Manufacturing utilization and per-dose cost at varying volumes, with sensitivity to cold-chain tiers.
-
Distribution reach and veterinary acceptance scores by region/species (qualitative and quantitative).
-
Partnership pipeline velocity — number and strategic fit of licensing, co-development, and distribution agreements executed.
Why PW Consulting’s report is decision-useful
Our study combines a transparent macro model (with scenarios that capture regulatory acceleration, slower adoption, and supply-shock outcomes) with executable playbooks and diagnostic tools. We synthesize primary interviews with industry leaders, regulatory specialists, and field veterinarians to deliver commercially actionable recommendations that translate market projections (CAGR and topline trajectory) into board-ready investment choices.
We intentionally do not publish the granular regional or application-level splits in this briefing; those segment-level findings, pricing matrices, and company scorecards are available in the full report and the interactive dashboard where clients can run customized scenarios tailored to their asset portfolios and geographic priorities.
Closing guidance for 2026
The livestock genetic-engineering vaccine market is maturing from a proof-of-concept era into a commercially operational landscape. That maturation generates concentrated opportunity for organizations that combine platform capability, regulatory savvy, and distribution execution. For executives planning 2026 capital allocation or M&A activity, the prudent approach is to triangulate three inputs — platform maturity, near‑term regulatory path, and field adoption evidence — and to prioritize options that preserve strategic optionality (modular manufacturing, licensing rights, and targeted partnerships).
PW Consulting’s full report provides the proprietary market model, regulatory templates, and commercial playbooks necessary to convert these insights into a defensible, actionable strategy. Contact PW Consulting or visit our website to access the complete report, interactive scenario tools, and bespoke advisory engagements tailored to your role in the livestock vaccines ecosystem.
For detailed analysis of this topic, please visit the official page: Livestock Genetic Engineering Vaccines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Superconducting Magnetometer Market Forecast (2026–2032) — Set to Reach USD 40.68 Million by 2032, Growing at a 7.7% CAGR
By pmarketresearch, 2026-07-06
Superconducting Magnetometer Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest industry briefing previews our full Superconducting Magnetometer Market research report, offering senior executives a forward-looking playbook to inform decisions across product strategy, customer segmentation, and capital allocation in 2026. This preview explains why the market’s trajectory — and the structural forces behind it — make next-year planning a watershed moment for vendors, integrators, and strategic investors. For reasons of competitive sensitivity we deliberately withhold detailed regional and application-level splits in this release; the full dataset and growth scenarios are available in the complete report.
Superconducting Magnetometer Market
Market trajectory at a glance
The superconducting magnetometer market has experienced steady expansion through the early 2020s and is projected to continue on a healthy growth path over the 2026–2032 forecast window. Using 2025 as our base year, PW Consulting’s model projects the market will grow from USD 24.2 Million (revenue unit: Million USD) to approximately USD 40.68 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.7% over the forecast period. This growth is supported by converging demand drivers in research, industrial sensing, and exploration, alongside selective policy tailwinds for quantum-technology adoption.
Superconducting Magnetometer Market
Why 2026 matters: three strategic inflection points
-
Technology convergence: Cryogenics, HTS material advances, and compact readout electronics are lowering system-level barriers for differentiated, application-specific magnetometer products. Vendors that translate subsystem innovations into reliable, serviceable systems will be positioned to capture disproportionate value in 2026–2028.
Superconducting Magnetometer Market -
Market structure and competitive dynamics: The market displays moderate concentration — PW Consulting’s competitive analysis shows a top-three concentration that approaches mid‑range levels and a top‑five concentration that indicates a clear leader cohort. This structure creates room for agile challengers with specialized product offerings (portable systems, integrated sensors) while preserving premium margins for incumbents that can offer integrated service and lifecycle guarantees.
-
Policy and funding inflection: Public funding programs and industrial modernization incentives (notably multi‑billion euro commitments in European quantum programs and targeted national incentives in North America) are accelerating institutional purchases for advanced sensing and quantum-enabled measurement platforms. Vendors that map these public funding cycles into targeted sales pipelines will gain a measurable first-mover advantage.
Report practicalities — what PW Consulting delivers
Our full report is built for executives who must convert market insight into operational plans in 2026. Deliverables include:
-
Market sizing and scenario models (historical 2020–2025; forecast 2026–2032) with baseline, upside, and downside scenarios reflecting supply shocks, policy acceleration, and adoption curves.
-
Vendor benchmarking and value‑chain maps: product portfolios, core component suppliers, margin pools, and service opportunities.
-
Technology heatmaps assessing Low‑Temperature (LTS) and High‑Temperature (HTS) SQUID developments, readout electronics, and system integration tradeoffs for differing applications.
-
Commercial playbooks: go‑to‑market segmentation, channel strategies, pricing sensitivity analyses, and tender play templates for institutional and industrial buyers.
-
Supply‑chain risk register, including materials, labor skills, and manufacturing scalability assessments with mitigation actions and cost impact estimates.
-
M&A and partnership diagnostics: transaction targets, valuation heuristics, and integration checklists tailored to strategic buyers and private equity.
Competitive landscape — who matters and why
The vendor field combines established precision-instrument firms, niche specialist sensor builders, and systems integrators. PW Consulting’s qualitative and quantitative work highlights several strategic archetypes:
-
Full-system incumbents — firms that pair magnetically shielded measurement platforms with superconducting magnets and multi‑mode measurement capability. These players retain strong institutional relationships with research labs and advanced industrial customers due to proven reliability and integrated service offerings.
-
Sensor and electronics specialists — companies focusing on low‑noise SQUID sensors and readout electronics, enabling third‑party system builders to compress product development timelines and differentiate on portability and cost.
-
Application-focused innovators — small, nimble companies delivering fit‑for‑purpose solutions for field exploration, portable diagnostics, and modular research instruments. These firms accelerate market penetration where compactness and ease of deployment are decisive.
Representative companies we profile in the full report include established names and specialized innovators. For example:
-
Quantum Design Inc. (San Diego, USA) — known for high‑sensitivity magnetometer systems that support multiple measurement modes and high‑field capabilities, positioning the firm strongly in laboratory and materials R&D use cases.
-
STAR Cryoelectronics LLC (Santa Fe, USA) — a supplier of both LTS and HTS SQUID sensors and integrated readout electronics, serving research and applied geophysics markets.
-
Tristan Technologies Inc. (San Diego, USA) — a specialist in custom systems for rock magnetometry and geophysical exploration with practical liquid‑nitrogen cooled HTS offerings.
-
Supracon AG (Jena, Germany) — active in geophysical surveys and quantum sensing; recent deployments with exploration partners demonstrate commercialization pathways for ultrasensitive sensors.
-
Cryogenic Limited (London, UK) and Magnicon GmbH (Hamburg, Germany) — companies focused on integrating superconducting magnets with cryogen‑free systems and low‑noise electronics respectively, enabling broader application adoption.
-
ez SQUID (Netherlands) — an emerging entrant delivering compact SQUID sensors for portable applications, a trend that accelerates field deployment and lowers entry friction for new buyers.
Recent vendor activity we analyze includes product launches and partnership deployments that validate both technological readiness and market demand (for instance, compact sensor lines introduced by agile entrants and deployment partnerships for mineral exploration). PW Consulting’s vendor heatmap identifies which firms are investing in modular platforms, which are prioritizing high‑field laboratory systems, and which are pursuing channel partnerships to access industrial users.
Opportunities, risks and operational levers
-
Opportunities: Rising demand for precision magnetic sensing across medical imaging research, geophysical exploration, and quantum R&D creates differentiated niches for premium and portable offerings. Vendors with aftermarket service, remote diagnostics, and modular upgrade paths can expand lifetime value per system.
-
Risks: Input cost pressure from specialized superconducting materials and a constrained pool of cryogenics expertise create supply-side bottlenecks. Regulatory and standards uncertainty in new application domains can slow procurement cycles for system-level buyers.
-
Operational levers: Near-term moves that materially change 2026 outcomes include: securing long‑lead material contracts, investing in remote calibration and service infrastructure, and aligning product roadmaps to public funding cycles that finance institutional procurement.
Policy and ecosystem nudges
Policy accelerators are nontrivial. Public funding initiatives targeting quantum technologies, notably significant allocations in European programs, are indirectly subsidizing adoption of SQUID‑based systems in research and strategic industrial projects. Complementary incentives under North American modernization and energy‑storage policies are also creating procurement pockets for superconducting technologies. PW Consulting models multiple policy uptake scenarios to help clients prioritize market entry and partnership timing.
2026 decision checklist — five recommended actions
-
Prioritize product roadmaps that reduce total cost of ownership (serviceability, cryogen‑free operation, modular upgrades).
-
Lock early supply agreements for specialty superconducting materials and critical readout components to avoid margin erosion from spot shortages.
-
Build go‑to‑market plays aligned with institutional funding cycles and proof‑of‑value deployments in prioritized verticals (research labs, exploration, industrial sensing).
-
Evaluate bolt‑on M&A targets that complement core strengths — e.g., sensor electronics firms for incumbents, or systems integrators for smaller technology players seeking scale.
-
Invest in service capabilities and remote diagnostics to de‑risk field deployments and capture aftermarket revenue.
Conclusion — where PW Consulting adds strategic value
Our analysis shows a market that is both growing and maturing: structurally attractive for firms that can combine deep technical capability with pragmatic commercial execution. PW Consulting’s full report translates the headline CAGR and market trajectory into executable initiatives — from procurement and supply‑chain playbooks to M&A heatmaps and pricing battlegrounds — enabling clients to convert 2026 choices into multi‑year competitive advantage.
To access the full dataset, granular segmentation, and the vendor scorecards that we intentionally omitted from this preview, please consult the complete Superconducting Magnetometer Market report on the PW Consulting website. The full report contains the granular regional and application breakdowns, detailed financial modeling (Million USD unit), and step‑by‑step implementation playbooks tailored for 2026 action.
For detailed analysis of this topic, please visit the official page: Superconducting Magnetometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Multi-Parameter Monitoring Equipment Market Poised for 5.82% CAGR, Signaling Robust Growth Outlook
By pmarketresearch, 2026-07-06
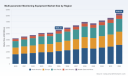
Multi-Parameter Monitoring Equipment Market: Strategic Preview for 2026 Decision Makers
Executive snapshot
PW Consulting’s latest market research—anchored on a 2025 base year and projecting through 2032—delivers an actionable, decision-grade perspective on the Multi-Parameter Monitoring Equipment market. Our modeling shows the market expanding from a 2025 base of approximately USD 5,646 million to roughly USD 8,390 million by 2032, implying a compound annual growth rate (CAGR) of about 5.82% over the forecast interval. That headline trajectory masks important operational inflection points and competitive dynamics that will determine winners and losers as healthcare systems invest in monitoring infrastructure, mobility and integration across the care continuum.
Multi Parameter Monitoring Equipment Market
Why this report matters for 2026 strategy
- Tactical timing: 2026 will be the first full year in which hospitals and health systems operationalize many investments delayed during the post-pandemic capital cycle. Our analysis identifies the equipment categories and purchase triggers most likely to drive replacement and expansion activity in that year.
- Risk-weighted planning: We combine macro forecasting with scenario analysis to quantify downside exposures (supply-chain-driven material cost inflation, regulatory cycles) and upside catalysts (portable/wearable adoption, AI-enabled alarm management). This helps finance and procurement teams set defensible capex envelopes for 2026.
- Competitive positioning: With market concentration metrics indicating material incumbency advantages, the report outlines realistic routes to scale for new entrants, and adjacency strategies for incumbent medical device OEMs and systems integrators.
What you will find (select practical contents)
This study was developed to be a practical playbook—more than a descriptive overview. Key deliverables for commercial leaders and strategists include:
Multi Parameter Monitoring Equipment Market
- Top-down market sizing and stochastic forecasts—our base-case, downside and upside scenarios quantify the financial envelope organizations should expect to compete for between 2026–2032.
- Commercial due diligence templates—vendor scorecards, channel economics models and procurement negotiation levers that purchasers and private equity teams can operationalize immediately.
- Go‑to‑market roadmaps for different go-to-buyer segments—hospital systems, ambulatory/ASC networks and home-care integrators—each with prioritized value propositions and commercial KPIs for 12–36 month windows.
- Technology and integration playbooks—deployment patterns for bed‑side, transport and wearable monitoring; recommended interoperability standards and integration sequencing to reduce clinical alarm fatigue and TCO over a five-year horizon.
- Regulatory and reimbursement mapping—practical checklists for 510(k) pathways, ISO compliance and coding/reimbursement implications for critical care monitoring services.
- Supply‑chain sensitivity analysis—probabilistic models that quantify the impact of material-cost inflation and single‑source component risk on gross margins and lead time variability.
- Executive case studies—real-world procurement and implementation narratives that illustrate pitfalls and accelerate time-to-value for device rollouts.
Market structure and concentration
The market exhibits a meaningful degree of consolidation: the top three competitors account for a majority share of global revenue and the top five together approach a substantial majority. Those concentration levels create both barriers for new entrants and opportunities for mid-tier players to differentiate through services, affordability, and localized manufacturing or channel strategies.
Multi Parameter Monitoring Equipment Market
Competitive landscape—what incumbents are doing
We profile more than a dozen strategic and regional players; below are the recurring strategic themes observed among global leaders and fast followers:
- Philips (Amsterdam): Continues to push algorithmic differentiation via its IntelliVue series and AI-driven early warning scoring. Software-first updates and lifecycle software maintenance are central to its lock-in strategy.
- GE Healthcare (Chicago): Is expanding mobility through wearable continuous monitors and modular designs that target patient flow optimization—recent launches emphasize in-hospital mobility and telemetry integration.
- Dräger (Lübeck): Focuses on acute‑care modularity and ventilation integration; recent regulatory clearances expand its market access in priority geographies and strengthen its acute‑care proposition.
- Mindray (Shenzhen): Leverages cost-to-value economics to scale rapidly in public procurement environments and across emerging markets; strategic contracting wins with major health systems underpin its volume play.
- Nihon Kohden (Tokyo): Maintains differentiation in high‑acuity waveform analysis and advanced physiological signal processing, appealing to tertiary and specialty centers.
- Masimo (Irvine): Continues to emphasize proprietary sensor technologies and non‑invasive monitoring modalities to extend margins and build ecosystem dependence.
- Baxter/Hillrom, Spacelabs, Schiller, Zoll, Contec, Edan: Each occupies defined niches—bed systems integration, ambulatory modules, MRI‑compatible monitors, EMS/transport integration, low‑cost clinic and homecare monitors—and are executing targeted product and channel plays to consolidate those positions.
Recent industry moves—regulatory clearances, wearable product launches and large system contracts—confirm the direction of travel: modularity, mobility and data‑centricness are primary competitive battlegrounds.
Regulation, standards and market enablers
- Regulatory frameworks remain a gating factor—multi-parameter monitors are generally categorized under established medical device classes that require premarket notifications or equivalence demonstrations in major markets. This lengthens product cycle timelines and raises the importance of regulatory strategy in 2026 planning.
- Standards compliance (for example, pulse-oximetry and basic safety standards) is non-negotiable for market access; we provide an execution checklist in the report to accelerate premarket readiness.
- Reimbursement and coding updates can materially alter adoption economics for acute‑care monitoring and telemonitoring services; purchasers should align device selection with prevailing clinical billing rules to avoid downstream underutilization.
Operational risks and cost pressures
Supply‑chain realities remain salient. Medical‑grade polymers and specialty components have seen sustained cost pressure, and our sensitivity analyses show that persistent material inflation in the high‑single digits can compress manufacturer margins and extend lead times—creating tactical opportunities for firms with diversified supply chains or local manufacturing capabilities. Additionally, high-profile product remediation episodes from recent years reinforce the need for robust post-market surveillance and spare‑parts strategies in procurement contracts.
Strategic recommendations for 2026
- Prioritize integration over feature lists: Buyers should value interoperability, vendor openness and lifecycle software support as heavily as initial device capabilities; these factors drive TCO over a typical 7–10 year replacement cycle.
- Use scenario-based capex planning: Build budgets based on our downside and upside scenarios to avoid over-commitment in volatile procurement cycles while preserving optionality to scale in upside cases.
- Segment go-to-market by acuity and mobility: Different commercial motions win in ICU versus ambulatory and home settings—align sales KPIs, reimbursement plays and service bundles accordingly.
- Invest in data services: Vendors that can offer analytics, alarm management and clinician workflow integration will command premium renewal economics; buyers should negotiate explicit SLAs for software performance and data portability.
- Mitigate supply risk proactively: Incorporate multi-sourcing, inventory buffers and local qualification pathways to prevent program delays—especially important for large system rollouts planned in 2026.
How to use the full report
Consider this release a strategic trailer: it demonstrates the depth of our modeling and the practical orientation of our recommendations, while preserving detailed split-level forecasts and proprietary benchmarking metrics for the full report. The comprehensive dataset includes scenario-tagged demand curves, vendor price‑elasticity models, and a library of negotiation templates that procurement and strategy teams can adopt directly. Organizations preparing 2026 budgets, commercial roadmaps or M&A diligence will find the full deliverable especially valuable.
Access and next steps
- For procurement and strategy teams: request a demo of the forecast portal to run bespoke scenarios aligned to your procurement cycles.
- For investors and PE diligence teams: schedule a sponsored deep-dive that bundles our vendor scorecards and supply‑chain stress tests.
- For OEMs and systems integrators: we offer an accelerated executive workshop to translate the report’s findings into a 12–18 month go‑to‑market playbook.
PW Consulting’s Multi‑Parameter Monitoring Equipment Market report combines rigorous top‑down forecasting (CAGR ~5.82% to 2032), practical procurement and commercialization tools, and a competitive analysis grounded in recent regulatory and contract developments. For leaders making capital and strategic commitments in 2026, the report converts uncertainty into a prioritized action plan—helping you protect margin, accelerate adoption, and capture share in a market that is expanding but competitively and operationally complex.
For detailed analysis of this topic, please visit the official page: Multi Parameter Monitoring Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
New PW Consulting Report Forecasts 8.55% CAGR for Airspace Management System Market
By pmarketresearch, 2026-07-06
Airspace Management System Market — 2026 Strategic Preview
PW Consulting's latest market study on Airspace Management Systems provides a forward-looking strategic roadmap for organizations making critical decisions in 2026. Built on a base year of 2025 and a historical analysis covering 2020–2025, the study synthesizes operational realities, regulatory inflection points, and vendor dynamics to project the market through 2032. The market has grown materially in recent years — moving from just over USD 1.0 billion (2020) to approximately USD 1.45 billion in our 2025 base — and our forecast path, underpinned by an 8.55% compound annual growth rate for the forecast horizon, points toward a market that more than doubles by the early 2030s. This preview explains why that trajectory matters to procurement officers, program managers, technology investors, and regulators as they set priorities for 2026.
Airspace Management System Market
Why this report matters for 2026 decision-making
-
Procurement timing and risk mitigation: Major national modernization initiatives and vendor contract cycles create windows where capital allocation and specification choices determine multi-year outcomes. Our study interprets those windows and translates them into actionable procurement sequencing guidance for both civil and defense buyers.
Airspace Management System Market -
Policy and regulatory alignment: With regulators worldwide accelerating transitions — from legacy telecom infrastructure to IP-based networks, to dedicated spectrum decisions for UAS command-and-control — the right technical and contractual posture in 2026 will reduce downstream compliance cost and deployment friction.
Airspace Management System Market -
Commercial opportunity framing: For vendors and investors, the market’s projected mid-to-high single-digit CAGR signals sustained demand across hardware, software, and services. The report distills where growth will be most resilient versus where commoditization and consolidation pressures are likely to compress margins.
Macro dynamics shaping the next investment cycle
-
Large-scale modernization programs: National modernization plans — including multi-billion dollar national air traffic control upgrades and related telecommunications refreshes — are driving short-term procurement spikes and longer-term opportunities for phased deployments and lifecycle services.
-
Regulatory catalysts: Recent regulatory moves (spectrum allocations for UAS CNPC, global interoperability priorities driven by ICAO and regional initiatives) are changing technical requirements and certification pathways, shortening the time-to-market for compliant solutions but raising entry barriers for some suppliers.
-
Technology convergence: Cloud-native platforms, space-based surveillance data, digital and remote towers, and advanced automation are converging into integrated operational concepts. Vendors that combine systems integration expertise with modular, open architectures will capture disproportionate value.
-
New entrants and software platforms: SaaS messaging platforms and cloud-based ATC modules are emerging as viable alternatives to monolithic legacy suites, prompting incumbent vendors to adapt commercial models away from heavy upfront hardware billing toward subscription and managed-service offerings.
What is inside the PW Consulting report — operational, practitioner-focused deliverables
-
Demand-side forecasts and scenario maps: Granular forecasts across relevant horizons, plus scenario-driven sensitivity analyses that quantify the impact of major program deferrals, regulatory shifts, or accelerated UAS integration on procurement curves.
-
Vendor benchmark and capabilities matrix: A comparative framework that evaluates integrators, avionics suppliers, comms specialists, and niche innovators across technology maturity, delivery risk, systems openness, and sustainment models.
-
Procurement playbook and RFP templates: Actionable templates and contracting strategies to protect buyer interests — including interoperability clauses, data ownership and sharing terms, cybersecurity baselines, and staged acceptance/upgrade triggers.
-
Total cost of ownership (TCO) models and migration roadmaps: End-to-end TCOs for multiple deployment archetypes (on-premise, hybrid, cloud-native) and stepwise migration plans that minimize operational disruption while accelerating capability delivery.
-
Risk registers and mitigation strategies: Structured risk matrices for technology obsolescence, vendor lock-in, regulatory non-compliance, and supplier concentration, paired with practical mitigation playbooks for program managers.
-
Use-case driven integration blueprints: Technical pathways for integrating space-based ADS-B, digital towers, UTM interfaces, and automated flow-management tools into existing ATM ecosystems without wholesale ground-up replacement.
Competitive landscape — who matters and why
-
Integrated ATM system leaders: A small set of global integrators continue to dominate large-scale national programs by offering bundled automation, surveillance, and operational suites. Their strengths are scale, legacy relationships with civil aviation authorities, and deep system-integration capability.
-
Defense and aerospace primes: Defense-focused companies bring advanced surveillance, hardened communications, and C2 experience to dual-use and military airspace modernization, enabling rapid delivery of secure, resilient systems for contested environments.
-
Specialists and disruptors: Vendors focused on cloud messaging, space-based surveillance services, digital towers, and safety-critical voice/data communications are carving out profitable niches. Their modular offerings are increasingly integrated into national programs as bolt-on capabilities or managed services.
-
Market dynamics in practice: Recent contract awards and partnerships illustrate the evolving competitive map — from major radar modernization contract wins to national ATM modernization selections, cloud-based ATC messaging platform launches, and strategic partnerships integrating space-based surveillance with flow-management tools. These moves underscore a market where legacy capability remains important, but interoperability, cloud readiness, and data-centric partnerships are becoming decisive.
Actionable strategic recommendations for 2026
-
Buyers: Prioritize modular, standards-compliant architectures in new procurements. Insist on open interfaces and staged acceptance to avoid “rip-and-replace” risk and to enable incremental capability upgrades tied to measurable operational KPIs.
-
Vendors: Fast-track productizing of cloud-native modules, managed services, and data products. Build commercial flexibility (subscription, outcome-based pricing) and invest in certification pathways aligned with evolving regulatory standards for UAS and cross-border operations.
-
Investors and M&A teams: Target niche specialists that accelerate incumbents’ digital roadmaps — especially in space-based surveillance analytics, digital tower tech, secure messaging platforms, and AI-enabled flow-management. Value will accrue to firms that reduce integration risk for national programs.
-
Program leaders: Create early-stage interoperability testbeds and multi-vendor integration pilots to de-risk large-scale roll-outs. Embed contractual clauses that deliver continuous modernization and cybersecurity upgrades over the system lifecycle.
How PW Consulting’s analysis translates into operational advantage
-
Decision-ready deliverables: The report bundles interactive forecasting models, vendor scorecards, RFP templates, and TCO calculators that program teams and procurement officers can apply immediately to 2026 budgets and award strategies.
-
Tailored advisory options: For organizations that require deeper alignment, PW Consulting offers scenario workshops, vendor negotiation support, and bespoke due diligence focused on integration risk and sustainment economics.
-
Evidence-based counsel: Our conclusions are grounded in observed contract awards, product launches, regulatory updates, and infrastructure funding commitments, and are shaped to help clients capture upside while managing transition risk.
Next steps — where to find the complete intelligence
This preview surfaces the strategic contours and practical implications of the Airspace Management System market for 2026. For procurement teams, program directors, technology strategists, and investors seeking the granular inputs — including detailed segmentation, regional and end-user breakdowns, vendor market shares, and the full suite of scenario-modeled forecasts — the complete PW Consulting report supplies those numbers, the underlying data models, and an expanded set of playbooks designed for immediate operational use. Access instructions and licensing options are available through PW Consulting’s insights portal.
PW Consulting remains available to brief leadership teams and to run tailored workshops that convert these insights into executable programs. In a market where technological interoperability, regulatory alignment, and program timing determine outcomes, the right analysis in 2026 will be the difference between strategic advantage and costly catch-up.
For detailed analysis of this topic, please visit the official page: Airspace Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Patient Record Management Market Set to Grow at 6.41% CAGR Through 2032
By pmarketresearch, 2026-07-06
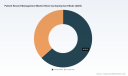
PW Consulting — 2026 Strategic Preview: Patient Record Management Market Outlook
Executive snapshot
As health systems accelerate digital transformation, the global patient record management market is entering a sustained growth phase that will define vendor strategies and provider investments through the rest of the decade. PW Consulting’s latest market study shows the total market expanding from approximately USD 41.7 billion in 2025 to an expected USD 44.7 billion in 2026, driven by an underlying compound annual growth rate (CAGR) of 6.41% over the 2026–2032 forecast horizon and reaching an estimated USD 64.4 billion by 2032. This level of growth, combined with moderate market concentration among the largest vendors, creates distinct windows for consolidation, specialization, and platform differentiation in 2026.
Patient Record Management Market
Why this matters for 2026 decision-makers
-
Timing for scale investments: With mid-single-digit CAGR and clear tailwinds from regulation, standards, and reimbursement incentives, 2026 is a moment for providers and vendors to decide whether to scale enterprise platforms or pursue nimble, targeted deployments.
Patient Record Management Market -
Competitive positioning: Market concentration metrics indicate a handful of major incumbents hold a meaningful share of demand, creating both barriers and strategic openings for challengers focused on interoperability, specialty workflows, or AI-enabled automation.
Patient Record Management Market -
Risk-reward calibration: Regulatory mandates and standardization reduce technical uncertainty but raise compliance and privacy costs. Organizations that align product roadmaps to standards and enforcement timelines will see faster adoption and fewer procurement setbacks.
Key drivers shaping the market in 2026
-
Regulatory and policy triggers: Longstanding mandates (e.g., HITECH and HIPAA frameworks) remain a baseline for secure electronic records. Recent enforcement of anti-information-blocking provisions under the ONC’s 21st Century Cures framework has accelerated demand for interoperable, auditable record systems. For global players, privacy regimes such as GDPR continue to impose stringent controls on processing health data.
-
Standards and technical interoperability: The publication and adoption of modern API standards—highlighted by the latest FHIR release—are reshaping integration architectures. Organizations that adopt a standards-first approach can materially reduce integration costs, improve data portability, and unlock cross-system analytics.
-
Cloud, edge, and hybrid architectures: Cloud-based delivery has become the default choice for many enterprises seeking operational agility and faster time-to-value, while on-premise and hybrid models persist where data sovereignty and latency constraints matter. Strategic architecture choices in 2026 will determine upgrade cadence and total cost of ownership for the next 7–10 years.
-
AI and workflow automation: The uptake of AI for record summarization, clinical decision support, and coding automation has shifted from experimental to mission-critical in large health systems. Vendors integrating validated, auditable AI capabilities into patient records will have a distinct selling proposition.
-
Reimbursement and incentives: Programs designed to promote interoperable EHR usage and quality reporting continue to influence procurement priorities. Financial incentives and penalties tied to certified technology usage remain material inputs to buyer ROI calculations.
Competitive landscape — what incumbents and challengers are doing
The market exhibits a moderate level of concentration: the top three vendors command a sizable portion of the market, and the top five capture a clear majority. This structure favors both entrenched platform providers and specialized entrants that can out-serve niche clinical workflows.
-
Epic Systems Corporation — Leading with deep clinical functionality and broad enterprise footprint. Recent product enhancements emphasize AI-assisted patient record summarization and expanded interoperability capabilities. Epic’s strengths remain tightly integrated clinical workflows and end-to-end platform consolidation, making it the partner of choice for large health systems focused on uniformity and scale.
-
Oracle Cerner — Competing at enterprise scale with investments in cloud infrastructure and analytics. Strategic partnerships with hyperscalers are expanding its analytics and machine learning capabilities, targeting real-time population health and device-generated data integration. Oracle Cerner is positioning itself as an analytics-first platform to complement clinical operations.
-
Allscripts Healthcare Solutions — Emphasizes ambulatory workflows, telehealth integration, and revenue cycle linkages. Its portfolio appeals to practices seeking modular deployment and flexible revenue-cycle interfaces—an option for organizations unwilling or unable to adopt single-platform strategies.
-
NextGen Healthcare — Focused on specialty practices and population health tools, NextGen competes on configurable workflows and mobile access for clinicians in ambulatory and specialty settings.
-
Athenahealth — A cloud-first contender with certified EHR capabilities and a focus on practice management, patient engagement, and rapid deployment. Recent certification milestones strengthen its credentials for buyers prioritizing compliance and speed-to-value.
-
eClinicalWorks — Serves a broad base of ambulatory providers with integrated telehealth and patient portal offerings; its value proposition centers on cost-effective, tightly integrated practice management.
-
GE HealthCare — Differentiates through imaging and diagnostic integration, delivering patient record capabilities that closely connect clinical documentation with diagnostic workflows and imaging informatics.
Recent market movements to watch
-
Product innovation accelerating around AI-assisted documentation and automated summarization—vendors are fast-following leaders who operationalized large language models into record workflows.
-
Cloud partnerships and M&A activity are reconfiguring go-to-market models; alliances with hyperscalers extend analytics and scalability capabilities beyond traditional EHR boundaries.
-
Certification and compliance milestones continue to act as deal catalysts; certified platforms are unlocking incentive streams and reducing procurement friction.
What’s inside the PW Consulting report (practical deliverables)
Our 2026 release is designed as a decision-support toolkit for executives, product leaders, and investors. It blends quantitative market models with executable strategy artifacts:
-
Market-sizing model (historical and forecast) with scenario variants that reflect alternative regulatory and technology adoption pathways.
-
Vendor scorecards and capability matrices that assess clinical fit, interoperability maturity, AI-readiness, and total cost of ownership.
-
Buyer decision frameworks and procurement playbooks tailored to large health systems, ambulatory networks, and specialty practices—covering vendor selection, implementation sequencing, and risk mitigation.
-
Investment and M&A playbooks identifying consolidation corridors, carve-out opportunities, and integration pitfalls for acquirers and strategic investors.
-
Operational playbooks for adoption—change management checklists, KPIs for phased rollouts, and templates for clinical validation of AI-assisted features.
-
Risk and compliance heatmaps aligning GDPR, HIPAA/HITECH, ONC information-blocking rules, and local data-residency requirements to deployment roadmaps.
-
Interactive ROI calculators and case studies that model finance and clinical outcomes across representative provider archetypes.
Actionable recommendations for 2026 stakeholders
-
For vendors: Prioritize API-first architectures and certified interoperability flows. Differentiate through validated AI features that demonstrably reduce clinician burden and improve coding accuracy—avoid hype and focus on explainability and auditability.
-
For health systems and large providers: Reassess platform rationalization strategies—identify where a unified platform yields clinical and operational leverage versus where best-of-breed integrations deliver faster impact. Lock in contractual interoperability clauses and service-level agreements tied to data exchange performance.
-
For payers and investors: Look for providers that have operationalized interoperability and are reporting measurable reductions in administrative overhead. Invest in vendors that combine domain-specific workflows with scalable cloud economics, rather than generic horizontal tools.
-
For technology partners and integrators: Focus on turnkey connectors to standards-compliant APIs, and build assurance services around compliance, privacy, and model validation to capture recurring revenue streams.
Methodology and transparency
The PW Consulting forecast blends bottom-up vendor revenue models, primary interviews with health system CIOs and CMOs, and a top-down review of procurement flows and policy impacts. Our scenarios stress-test outcomes under alternative enforcement intensities, technology adoption curves, and macroeconomic conditions. Note: while this preview surfaces total market trajectory and competitive dynamics, granular segment-level tables and proprietary vendor revenue breakdowns are intentionally reserved for the full report to preserve commercial sensitivity and to enable interactive access for subscribers.
How to use this preview
Consider this document a strategic briefing for 2026 planning cycles. Use it to align executive budgets, prioritize product development sprints, shape M&A thesis checkpoints, and refine procurement evaluation criteria. Organizations that translate these directional insights into six- to twelve-month tactical plans—especially around interoperability pilots and AI governance—will be best positioned to capture upside as the market grows toward the forecasted USD 64+ billion opportunity by 2032.
Next steps and access
PW Consulting’s full Patient Record Management Market report contains the comprehensive datasets, interactive models, and executable playbooks referenced above. For companies preparing 2026 budgets or seeking acquisition targets, the report is the definitive strategic input. To obtain the complete report, vendor scorecards, and access to the interactive ROI tools, please visit PW Consulting’s market research portal.
For detailed analysis of this topic, please visit the official page: Patient Record Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saline Nasal Mist Market Set to Reach USD 1,325.6 Million by 2032 on a 7.7% CAGR
By pmarketresearch, 2026-07-06
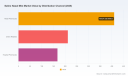
Saline Nasal Mist Market Outlook 2026: Strategic Imperatives for Commercial and R&D Leaders
PW Consulting’s latest industry brief on the Saline Nasal Mist market synthesizes five years of historical performance (2020–2025) and a seven‑year forecast (2026–2032) to deliver an action‑oriented roadmap for executive decision‑making in 2026. The market’s macro trajectory — driven by steady consumer adoption of non‑pharmacologic nasal care, expanded retail and e‑commerce availability, and evolving regulatory expectations — underpins a compound annual growth rate (CAGR) of 7.7% across the 2026–2032 forecast window. From a $788.68 million baseline in 2025, PW Consulting projects continued expansion, underscoring both near‑term commercial opportunity and longer‑term strategic choices for manufacturers, CMOs, retailers and private equity investors.
Saline Nasal Mist Market
Why this report matters for 2026 decisions
-
Actionable, time‑sensitive intelligence: The industry is at an inflection point where product safety, device performance, and channel strategy materially affect market positioning. Our analysis translates macro growth into practical priorities that can be executed in 12–24 month plans.
Saline Nasal Mist Market -
Risk‑aware go‑to‑market: Recent product recalls and fresh launches have amplified quality and differentiation as competitive levers. Regulatory guidance updates in the U.S. and Europe and sterility testing expectations have raised the bar for new product introductions — aspects that this report integrates into compliance checklists and launch decision matrices.
Saline Nasal Mist Market -
Resource allocation clarity: With a clearly rising market and mid‑level industry concentration, the report helps leaders decide whether to prioritize in‑house manufacturing investments, strategic outsourcing, or M&A to capture scale and technical capability.
Market dynamics that should shape 2026 strategy
-
Growth and momentum: Historical performance shows robust expansion from 2020 through 2025, followed by projections that reflect strong consumer adoption and channel evolution. The 7.7% CAGR expected through 2032 implies predictable topline expansion but also intensifying competition for premium positioning and shelf space.
-
Regulatory and quality pressures: Saline nasal mists occupy a regulatory intersection. In the U.S., many non‑sterile saline sprays are classified under a medical device pathway with general 510(k) exemptions when non‑sterile; in the EU, substance‑based devices applied to the nasal cavity commonly align with higher device classes under MDR Rule 21. Additionally, sterility claims trigger USP <71> sterility testing and associated process controls. For 2026 product pipelines, these are not abstract constraints — they are project drivers that affect timeline, cost, and supplier selection.
-
Quality events and market signaling: High‑visibility product recalls and contemporaneous product launches demonstrate two simultaneous trends: (1) consumer appetite for drug‑free, soothing nasal care remains strong; and (2) manufacturing quality is a decisive competitive differentiator. These events increase buyer sensitivity to provenance, sterility assurances, and quality certifications — all of which we quantify and prioritize in the report.
-
Consolidation window: Market concentration metrics show a mid‑tier consolidated landscape — a setting ripe for bolt‑on acquisitions and strategic partnerships among brand owners, private label manufacturers and CDMOs. Our scenario analyses outline thresholds where M&A accelerates value creation versus where focus on organic growth yields better ROI.
Competitive landscape — what distinguishes winners
The competitive mapping in the report profiles incumbent brands, differentiated innovators and CDMOs whose strategic choices will determine share shifts over 2026–2032. Key participants covered include leading global and regional names across brand, retail and contract manufacturing segments. For convenience and rapid validation, each profile includes headquarters, web presence and a concise strategic summary:
- NeilMed Pharmaceuticals Inc. (Santa Rosa, California, USA) — a leader in irrigation systems and nasal care devices, with a broad product set across isotonic and hypertonic formulations.
- Church & Dwight Co., Inc. (Arm & Hammer) (Ewing, New Jersey, USA) — leverages heritage consumer brands and natural‑ingredient positioning for everyday nasal care.
- Ayr (Medtech Products Inc., Prestige Consumer Healthcare) (Tarrytown, New York, USA) — focused on moisturizing and allergy‑friendly formulations with consumer convenience in mind.
- Haleon (Brentford, United Kingdom) — successor consumer healthcare strategy blending legacy OTC portfolio management and saline lines.
- Reckitt (Slough, United Kingdom) — large consumer health player executing targeted product launches into drug‑free sinus relief categories.
- AdvaCare Pharma (New York, NY / global manufacturing footprint) — GMP‑certified supplier with broad international reach and contract supply expertise.
- Bayer AG, Laboratoire de la Mer (Sterimar), Laboratoires URGO (Humer), Little Remedies, Zarbee’s — brand players with differentiated formulations, pediatric focus, or natural seawater propositions.
- Renaissance Pharma and Catalent — CDMO and contract development specialists supporting scale, sterile manufacturing and regulatory readiness.
Each profile in the full report includes innovation pipelines, device IP positions, shelf‑space strategies, and a playbook for competitive response — without disclosing third‑party proprietary sales detail but providing decision‑grade insight for partners and acquirers.
Operational playbook for market entry, expansion or defense in 2026
-
Prioritize compliance‑first product development: Build sterility testing and device robustness requirements into design controls early. Decisions to label sterile vs non‑sterile have immediate supply chain and QC ramifications; our checklist and estimated lead‑time impacts help teams choose faster‑to‑market vs higher‑value routes.
-
Segment by value drivers, not just formulation: While isotonic vs hypertonic formulations and adult vs pediatric narratives matter, the most durable advantages will come from device ergonomics, preservative‑free positioning, and demonstrable clinical comfort. We provide a framework to allocate R&D and marketing spend across these axes.
-
Design a hybrid distribution strategy: Retail pharmacies remain central for mass reach, but online retailers and DTC channels are accelerating discovery, subscription and bundled sales. The report includes channel profitability models and promotional efficiency benchmarks to inform channel mix decisions for 2026 campaigns.
-
Lock in resilient manufacturing partners: Given risks illustrated by recent contamination recalls, multi‑sourcing, audited CMOs and in‑market secondary suppliers are essential. The report maps CDMO capabilities by technology (sterile fill, aseptic processing, device assembly) and provides an RFP checklist to expedite vendor selection.
-
Prepare for consolidation plays: With moderate top‑tier concentration, smart acquirers can scale regional brands quickly. We include valuation heuristics, synergies templates and integration playbooks for rapid post‑close commercial alignment.
What the PW Consulting report delivers (practical contents)
- Executive summary and 2026 strategic implications tailored for commercial, R&D and M&A leadership.
- Historical performance (2020–2025) and a detailed forecasting model through 2032 with sensitivity scenarios and a 7.7% base CAGR across 2026–2032.
- Competitive profiles, capability maps and playbooks for leading brands and CDMOs.
- Regulatory matrix covering U.S. and EU device classification, sterility testing requirements, and manufacturing performance expectations.
- Go‑to‑market templates: channel mix optimization, pricing and promotional efficiency frameworks, pediatric vs adult commercialization strategies.
- Supplier and risk register: audited CDMO directory, supplier contingency planning and recall mitigation strategies.
- M&A and partnership scenarios with valuation heuristics and integration checklists.
- Data annex and methodology: full model inputs, assumptions and downloadable time‑series for executive analysis.
Note: This press brief intentionally highlights strategic and operational findings while withholding detailed sub‑segment tables and proprietary breakdowns. Full segment‑level datasets, regional splits, and granular channel economics are available exclusively in the full PW Consulting report and accompanying downloadable workbook.
Immediate moves for 2026
-
Run a two‑track launch readiness plan: one track optimized for rapid market entry with non‑sterile claims and essential QC controls; a parallel track designed for high‑margin sterile products with extended timelines and certification pathways.
-
Initiate vendor due diligence for at least two CDMOs that can support sterile fills and device assembly; include site audits focused on microbial control programs and supply continuity.
-
Test premium positioning via limited‑run SKUs emphasizing preservative‑free, pediatric suitability, or natural seawater sourcing paired with targeted digital campaigns to measure willingness‑to‑pay before national roll out.
-
Implement a regulatory watch and rapid‑response protocol, incorporating the latest FDA CMC guidance on nasal products and EU MDR implications, so that labeling and claims decisions do not trigger downstream compliance delays.
Conclusion — strategic value for 2026
For leaders allocating capital, standing up manufacturing, or launching products in 2026, the Saline Nasal Mist market presents a blend of predictable growth and executional complexity. PW Consulting’s analysis converts that macro trajectory into a prioritized, risk‑adjusted set of actions: tighten manufacturing quality and sterility programs, pick focused routes‑to‑market that balance retail scale with online agility, and use selective M&A or CDMO partnerships to rapidly close capability gaps. The result is a defensible plan that captures upside from the market’s projected expansion while minimizing exposure to regulatory and supply risks.
To access the full dataset, segmented analytics, and the downloadable forecasting model — including detailed channel economics, regional splits and product‑level scenario outputs — please visit the PW Consulting Saline Nasal Mist market page or contact our advisory team for a briefing.
For detailed analysis of this topic, please visit the official page: Saline Nasal Mist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com