

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Patient Record Management Market Set to Grow at 6.41% CAGR Through 2032

PW Consulting — 2026 Strategic Preview: Patient Record Management Market Outlook
Executive snapshot
As health systems accelerate digital transformation, the global patient record management market is entering a sustained growth phase that will define vendor strategies and provider investments through the rest of the decade. PW Consulting’s latest market study shows the total market expanding from approximately USD 41.7 billion in 2025 to an expected USD 44.7 billion in 2026, driven by an underlying compound annual growth rate (CAGR) of 6.41% over the 2026–2032 forecast horizon and reaching an estimated USD 64.4 billion by 2032. This level of growth, combined with moderate market concentration among the largest vendors, creates distinct windows for consolidation, specialization, and platform differentiation in 2026.
Patient Record Management Market
Why this matters for 2026 decision-makers
-
Timing for scale investments: With mid-single-digit CAGR and clear tailwinds from regulation, standards, and reimbursement incentives, 2026 is a moment for providers and vendors to decide whether to scale enterprise platforms or pursue nimble, targeted deployments.
Patient Record Management Market -
Competitive positioning: Market concentration metrics indicate a handful of major incumbents hold a meaningful share of demand, creating both barriers and strategic openings for challengers focused on interoperability, specialty workflows, or AI-enabled automation.
Patient Record Management Market -
Risk-reward calibration: Regulatory mandates and standardization reduce technical uncertainty but raise compliance and privacy costs. Organizations that align product roadmaps to standards and enforcement timelines will see faster adoption and fewer procurement setbacks.
Key drivers shaping the market in 2026
-
Regulatory and policy triggers: Longstanding mandates (e.g., HITECH and HIPAA frameworks) remain a baseline for secure electronic records. Recent enforcement of anti-information-blocking provisions under the ONC’s 21st Century Cures framework has accelerated demand for interoperable, auditable record systems. For global players, privacy regimes such as GDPR continue to impose stringent controls on processing health data.
-
Standards and technical interoperability: The publication and adoption of modern API standards—highlighted by the latest FHIR release—are reshaping integration architectures. Organizations that adopt a standards-first approach can materially reduce integration costs, improve data portability, and unlock cross-system analytics.
-
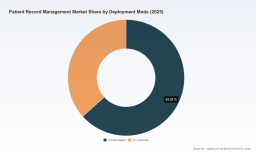
Cloud, edge, and hybrid architectures: Cloud-based delivery has become the default choice for many enterprises seeking operational agility and faster time-to-value, while on-premise and hybrid models persist where data sovereignty and latency constraints matter. Strategic architecture choices in 2026 will determine upgrade cadence and total cost of ownership for the next 7–10 years.
-
AI and workflow automation: The uptake of AI for record summarization, clinical decision support, and coding automation has shifted from experimental to mission-critical in large health systems. Vendors integrating validated, auditable AI capabilities into patient records will have a distinct selling proposition.
-
Reimbursement and incentives: Programs designed to promote interoperable EHR usage and quality reporting continue to influence procurement priorities. Financial incentives and penalties tied to certified technology usage remain material inputs to buyer ROI calculations.
Competitive landscape — what incumbents and challengers are doing
The market exhibits a moderate level of concentration: the top three vendors command a sizable portion of the market, and the top five capture a clear majority. This structure favors both entrenched platform providers and specialized entrants that can out-serve niche clinical workflows.
-
Epic Systems Corporation — Leading with deep clinical functionality and broad enterprise footprint. Recent product enhancements emphasize AI-assisted patient record summarization and expanded interoperability capabilities. Epic’s strengths remain tightly integrated clinical workflows and end-to-end platform consolidation, making it the partner of choice for large health systems focused on uniformity and scale.
-
Oracle Cerner — Competing at enterprise scale with investments in cloud infrastructure and analytics. Strategic partnerships with hyperscalers are expanding its analytics and machine learning capabilities, targeting real-time population health and device-generated data integration. Oracle Cerner is positioning itself as an analytics-first platform to complement clinical operations.
-
Allscripts Healthcare Solutions — Emphasizes ambulatory workflows, telehealth integration, and revenue cycle linkages. Its portfolio appeals to practices seeking modular deployment and flexible revenue-cycle interfaces—an option for organizations unwilling or unable to adopt single-platform strategies.
-
NextGen Healthcare — Focused on specialty practices and population health tools, NextGen competes on configurable workflows and mobile access for clinicians in ambulatory and specialty settings.
-
Athenahealth — A cloud-first contender with certified EHR capabilities and a focus on practice management, patient engagement, and rapid deployment. Recent certification milestones strengthen its credentials for buyers prioritizing compliance and speed-to-value.
-
eClinicalWorks — Serves a broad base of ambulatory providers with integrated telehealth and patient portal offerings; its value proposition centers on cost-effective, tightly integrated practice management.
-
GE HealthCare — Differentiates through imaging and diagnostic integration, delivering patient record capabilities that closely connect clinical documentation with diagnostic workflows and imaging informatics.
Recent market movements to watch
-
Product innovation accelerating around AI-assisted documentation and automated summarization—vendors are fast-following leaders who operationalized large language models into record workflows.
-
Cloud partnerships and M&A activity are reconfiguring go-to-market models; alliances with hyperscalers extend analytics and scalability capabilities beyond traditional EHR boundaries.
-
Certification and compliance milestones continue to act as deal catalysts; certified platforms are unlocking incentive streams and reducing procurement friction.
What’s inside the PW Consulting report (practical deliverables)
Our 2026 release is designed as a decision-support toolkit for executives, product leaders, and investors. It blends quantitative market models with executable strategy artifacts:
-
Market-sizing model (historical and forecast) with scenario variants that reflect alternative regulatory and technology adoption pathways.
-
Vendor scorecards and capability matrices that assess clinical fit, interoperability maturity, AI-readiness, and total cost of ownership.
-
Buyer decision frameworks and procurement playbooks tailored to large health systems, ambulatory networks, and specialty practices—covering vendor selection, implementation sequencing, and risk mitigation.
-
Investment and M&A playbooks identifying consolidation corridors, carve-out opportunities, and integration pitfalls for acquirers and strategic investors.
-
Operational playbooks for adoption—change management checklists, KPIs for phased rollouts, and templates for clinical validation of AI-assisted features.
-
Risk and compliance heatmaps aligning GDPR, HIPAA/HITECH, ONC information-blocking rules, and local data-residency requirements to deployment roadmaps.
-
Interactive ROI calculators and case studies that model finance and clinical outcomes across representative provider archetypes.
Actionable recommendations for 2026 stakeholders
-
For vendors: Prioritize API-first architectures and certified interoperability flows. Differentiate through validated AI features that demonstrably reduce clinician burden and improve coding accuracy—avoid hype and focus on explainability and auditability.
-
For health systems and large providers: Reassess platform rationalization strategies—identify where a unified platform yields clinical and operational leverage versus where best-of-breed integrations deliver faster impact. Lock in contractual interoperability clauses and service-level agreements tied to data exchange performance.
-
For payers and investors: Look for providers that have operationalized interoperability and are reporting measurable reductions in administrative overhead. Invest in vendors that combine domain-specific workflows with scalable cloud economics, rather than generic horizontal tools.
-
For technology partners and integrators: Focus on turnkey connectors to standards-compliant APIs, and build assurance services around compliance, privacy, and model validation to capture recurring revenue streams.
Methodology and transparency
The PW Consulting forecast blends bottom-up vendor revenue models, primary interviews with health system CIOs and CMOs, and a top-down review of procurement flows and policy impacts. Our scenarios stress-test outcomes under alternative enforcement intensities, technology adoption curves, and macroeconomic conditions. Note: while this preview surfaces total market trajectory and competitive dynamics, granular segment-level tables and proprietary vendor revenue breakdowns are intentionally reserved for the full report to preserve commercial sensitivity and to enable interactive access for subscribers.
How to use this preview
Consider this document a strategic briefing for 2026 planning cycles. Use it to align executive budgets, prioritize product development sprints, shape M&A thesis checkpoints, and refine procurement evaluation criteria. Organizations that translate these directional insights into six- to twelve-month tactical plans—especially around interoperability pilots and AI governance—will be best positioned to capture upside as the market grows toward the forecasted USD 64+ billion opportunity by 2032.
Next steps and access
PW Consulting’s full Patient Record Management Market report contains the comprehensive datasets, interactive models, and executable playbooks referenced above. For companies preparing 2026 budgets or seeking acquisition targets, the report is the definitive strategic input. To obtain the complete report, vendor scorecards, and access to the interactive ROI tools, please visit PW Consulting’s market research portal.
For detailed analysis of this topic, please visit the official page: Patient Record Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com