

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Barrel Compressor Market at USD 5.42B in 2025, Poised to Reach USD 7.47B by 2032 at 4.69% CAGR — Asia‑Pacific and Multi‑stage Units Lead
By pmarketresearch, 2026-08-12
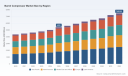
Worldwide Barrel Compressor Market — Strategic Briefing for 2026
Executive summary
PW Consulting’s new Worldwide Barrel Compressor Market study provides an operationally focused intelligence package designed to inform boardroom and engineering decisions through 2026 and beyond. The market for barrel-type centrifugal compressors is recovering and expanding: our base-year analysis shows a global market of approximately USD 5.42 billion in 2025, with a projected step-up to roughly USD 5.63 billion in 2026 and a compound annual growth rate of about 4.7% across the 2026–2032 forecast horizon. This steady, mid-single-digit growth masks significant structural shifts — from energy transition-driven use-cases (CCS, hydrogen) to offshore electrification and intensified aftermarket service demand — that will determine winners and losers in the coming three to five years.
Green Methanol Fuel for Marine Market
Why this report matters for 2026 decision-making
-
Actionable foresight for capital allocation: Our report translates macro growth into optimized CAPEX profiles for OEMs, EPCs and midstream operators, helping executives prioritize investment in product platforms and service networks aligned with accelerating CCS and hydrogen projects.
Robot Cleaner Market -
Procurement and partner selection playbook: We provide a practical framework for drafting tenders, evaluating technology-fit (materials, sealing, bundle/rotor interchangeability), and structuring long-term service agreements to mitigate lead-time and raw-material volatility.
Digital Pathology Image Analysis Software for Clinical Market -
Risk-adjusted scenario planning: Using stochastic demand scenarios and supply-chain stress tests, the study equips management teams to plan contingencies for steel/alloy price shocks, regulatory changes, and project slippages common in heavy rotating equipment projects.
-
Competitive positioning intelligence: Our differentiated company profiles and recent-contract mapping reveal strategic moves by major incumbents and potential white-space opportunities within the value chain.
Market dynamics — what’s driving growth and where strategic attention is needed
Barrel compressors remain the preferred engineering solution for high-pressure and corrosive service due to their vertically split, bundle-removable architecture — a design advantage that reduces operational downtime on complex oil & gas and process installations. Overlaid on this technical preference are three concurrent dynamics shaping near-term demand:
-
Energy-transition projects (CCS and hydrogen infrastructure) are shifting the demand mix from traditional midstream/refining services toward new process requirements. This creates demand for materials, sealing systems and package integration capabilities not always present in legacy designs.
-
Offshore electrification and FPSO electrification projects increase appetite for all-electric compressor drives and compact integrated skids, elevating the importance of modularization and systems engineering capabilities.
-
Supply-side constraints — notably specialized steels and alloy availability, and lead-time extension for critical rotors and casings — are materially affecting project schedules and total installed cost. Procurement strategies and vendor consolidation will therefore materially influence project economics.
Competitive landscape — incumbents, capability moves, and tactical implications
The barrel-compressor vendor ecosystem is concentrated, with the top tier of suppliers commanding a material share of global supply. Our analysis highlights how leading players are translating engineering strengths into commercial advantage:
-
Manufacturers with proven barrel platforms and modular packaging, and those able to offer robust aftermarket networks, hold the upper hand in tenders that prioritize life-cycle cost and availability.
-
Strategic examples: an incumbent won a CCS feedstock compression contract in early 2026 that illustrates the opportunity for vendors who can marry high-pressure barrel designs with offshore installation experience; another leading OEM continues to win FPSO electrification projects by combining vertically split compressors with integrated electrical architectures; and a service-focused acquisition completed by a major compressor OEM in 2026 signals an industry pivot toward bolstering in-region maintenance and MRO capability.
-
Implication for buyers and investors: evaluate vendors not only on nameplate performance but also on their service footprint, integration competence, and supply-chain resilience — the last of which will materially affect schedule and warranty exposure.
What the report contains — practical deliverables for teams executing in 2026
This study is structured as a hands-on decision pack rather than a purely academic exercise. Key components designed for immediate use include:
-
Executive dashboards that translate forecast trajectories into budgetary templates for CAPEX, OPEX and spare-parts stocking over a 7-year horizon.
-
Vendor scorecards comparing engineering capabilities, service reach, delivery performance, and risk exposure across rotating-equipment OEMs and aftermarket providers.
-
Procurement templates and clauses — including recommended warranty structures, escalation mechanisms for raw-material cost shifts, and inspection/test regimes — to reduce tender ambiguity and align supplier incentives.
-
Technical modularization blueprints that outline when to favor integrally geared vs. conventional barrel architectures, and how to prioritize materials and sealing choices for CO2, hydrogen, and sour-gas services.
-
A risk matrix and scenario playbooks covering supply-chain disruption, regulatory changes (including the forthcoming API standard revisions), and market shocks to guide contingency budgeting and contract design.
Strategic imperatives for 2026
Executives planning activity in 2026 should prioritize a set of focused initiatives to capture the upside while controlling downside risks:
-
Build integrated service platforms: Companies that invest in regional MRO capacity, remote monitoring and spares distribution will convert higher uptime into pricing power and recurring revenue.
-
Accelerate materials qualification and dual-sourcing: Given volatility in specialty steels, dual-sourcing critical forgings and qualifying alternative alloys reduces schedule risk and creates bargaining leverage.
-
Modularize designs for electrified platforms: For offshore and FPSO projects, delivering compact, all-electric compressor packages speeds installation and appeals to operators targeting lower-emissions footprints.
-
Pursue targeted M&A and partnerships: Acquisitions that expand rotating-equipment maintenance capabilities or in-region manufacturing shorten delivery cycles and increase capture of aftermarket margin.
-
Embed regulatory foresight into product roadmaps: With API revisions under way and growing environmental constraints, product teams must certify new designs for evolving standards to avoid rework on multi-year projects.
Case signals and near-term indicators to watch
Our monitoring of recent contract awards and strategic transactions yields practical leading indicators for market direction:
-
Large CCS and offshore project awards are immediate demand catalysts for heavy-duty barrel compressors. Track final investment decisions and vendor pre-qualification lists for early signals of procurement windows.
-
Service-capability expansions and MRO acquisitions are leading indicators that operators and EPCs expect tighter service markets; supplier consolidation often precedes margin expansion on aftermarket services.
-
Electrification and integration wins in FPSO and offshore contracts suggest that system-level engineering competence will be a tie-breaker in future RFPs.
How companies should use this report in practice
PW Consulting’s study is deliberately tactical: it tells you not just what is changing, but how to act. Recommended uses by function:
-
Strategy teams: run our scenarios through capital prioritization models to quantify trade-offs between new-product development and aftermarket investment.
-
Procurement: adopt the procurement templates and supplier scorecards to shorten bid evaluation time and lower contract risk exposure.
-
Engineering and product management: use the modularization blueprints and materials guidance to accelerate qualification of next-gen barrels for CCS and hydrogen service.
-
Investor relations and M&A teams: leverage vendor comparative intelligence to identify acquisition targets that fill service-network or material-qualification gaps.
Where to find the granular intelligence (and why it’s essential)
In line with our “teaser” approach, this briefing intentionally surfaces strategic conclusions and operational guidance while holding back certain granular subsegment specifics — such as fine-grained regional and application splits and proprietary vendor bid-models — that are contained in the full report. Those detailed breakdowns, including chapter-level supply/demand matrices, contract pipeline calendars, and downloadable vendor RFP templates, are available through our report portal and are critical for teams preparing to bid or design equipment for 2026 tenders.
Final recommendation
2026 will be a year where execution discipline wins. The barrel-compressor market’s steady growth — evidenced by a global market expanding from roughly USD 5.42 billion in 2025 to an anticipated USD 5.63 billion in 2026, and continuing at about a 4.7% CAGR into the early 2030s — masks both concentrated supplier power and asymmetric opportunities in service and new-energy segments. Organizations that combine supply-chain resilience, localized service capability and system-integration expertise will capture outsized value. PW Consulting’s full study equips executive teams with the granular, executable intelligence needed to convert these structural trends into competitive advantage; consult the full report for the datasets and operational tools required to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Barrel Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Cyclopentylamine Market to Expand at a 4.95% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Cyclopentylamine Market: Strategic Insights for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Cyclopentylamine Market (base year 2025) offers a focused briefing designed to inform executive strategy and capital allocation decisions heading into 2026. The study consolidates historical performance, granular supply-chain analysis, regulatory mapping, and forward-looking scenario modelling across a 2026–2032 forecast window. At the macro level, the market is expected to expand from USD 112.45 Million in 2025 to USD 157.7 Million by 2032, implying a compound annual growth rate (CAGR) of 4.95% over the forecast period. This press summary highlights the report’s strategic takeaways and the pragmatic actions we recommend for market participants, while preserving the detailed segment-level matrices reserved for subscribers of the full report.
Worldwide Small Business eCommerce Software Market
Why this report matters for 2026
-
Timing: 2026 will be a turning point for many players as upstream feedstock dynamics stabilize, regulatory scrutiny intensifies, and demand from higher-value end uses accelerates. The report synthesizes these drivers into actionable scenarios that help prioritize investments in capacity, quality, and compliance.
Spinal Surgery Navigation System Market -
Decision focus: Our analysis is built for three audiences — commercial executives planning pricing and sales strategies, supply-chain teams negotiating contracts and hedges, and corporate development teams assessing M&A or JV opportunities.
Automatic Stone Calibrating Machine Market -
Clarity without paralysis: We combine quantitative forecasts with qualitative intelligence (supplier capability maps, regulatory trackers, and playbooks) so leaders can move from insight to execution with confidence.
What the report contains — practical, transaction-ready analytics
-
Top-down and bottom-up market modelling: A reconciled market size from 2020–2025 and detailed projection through 2032, including sensitivity runs around feedstock price and regulatory stress scenarios.
-
Supply-chain heatmaps: Supplier capability matrices, manufacturing footprints, logistics bottlenecks, and dependency scores for key upstream inputs.
-
Price-sensitivity and margin modelling: Elasticity curves and pricing levers that show how upstream cyclopentanone moves transmit to producer margins under different contracting strategies.
-
Regulatory and environmental compliance tracker: A living map of jurisdictional obligations (including REACH-related obligations and standard US EPA/FDA handling requirements), compliance cost estimates, and implementation timelines.
-
Competitive playbooks and M&A due-diligence checklist: Company benchmarking templates, integration risk matrices, and 100+ datapoints for rapid valuation and target screening.
-
Commercial go-to-market modules: Channel strategies for reagent-grade versus bulk intermediates, sample commercial contracts, and a prioritized outreach plan for key verticals.
-
Operational risk and resilience tools: Supplier scorecards, inventory optimisation models, and contingency playbooks for feedstock shocks or disruptions.
-
Appendices and data room: Source-data tables, methodology documentation, and audit trails that underpin the headline forecasts.
Market dynamics shaping 2026 strategy
Three forces will dominate near-term strategy: feedstock economics, regulatory pressure, and end-market composition. On feedstocks, cyclopentanone — the primary upstream input used in reductive amination routes — experienced a notable price adjustment in late 2024 in specific Asian markets (approximately a 4% decline in China in Q4 2024), driven by temporary oversupply and softer demand. Across 2025, cyclopentanone prices in major producer regions generally trended flat-to-down as benzene and other upstream feedstock costs eased and inventories normalized (Analysts Insights, 2025; Sector Analysis, March 2026). For midstream producers, these dynamics create a window to rebuild margins, renegotiate contracts, and selectively reprice products, but they also increase the importance of agility in procurement and inventory strategies.
On regulation, cyclopentylamine is subject to increased environmental controls under EU REACH due to aquatic toxicity concerns, with parallel handling and manufacturing expectations enforced by US EPA and FDA frameworks in North America (TCI Chemicals SDS, April 2025; Sector Analysis, 2025). Compliance is no longer a back-office checkbox: lead times, capital expenditure for emission controls, and product stewardship commitments will increasingly factor into customer selection and commercial terms.
Demand patterns are evolving. The historical record across 2020–2025 shows volatility linked to broader chemical cycles and end-market investment. Our forecast to 2032 anticipates steady expansion driven by higher-value uses and incremental penetration into specialty applications. Importantly, the growth pathway is not uniform: quality differentiation (e.g., high-purity grades) and service capabilities (just-in-time shipments, hazardous-goods handling) will command premium positioning.
Competitive landscape: concentrated but open to disruption
The market exhibits a moderate concentration profile (CR3 and CR5 metrics indicate a market where a handful of firms hold sizeable positions while a broader competitive field remains active). This structure creates strategic opportunities for both incumbents and challengers.
-
Sigma-Aldrich (Merck KGaA) — a global reagent and specialty supplier — competes on high-purity grades and global distribution. Its strength lies in brand, regulatory compliance, and captive channels into research and pharmaceutical customers.
-
Biosynth Ltd — a UK-based player — offers a blend of R&D and scale capabilities, with hazardous-material handling and international distribution that make it a natural partner for customers bridging lab and production use-cases.
-
TNJ Chemical and other China-based manufacturers — positioned as cost-effective bulk producers and pharmaceutical intermediates suppliers — bring scale, attractive unit economics, and capacity to serve large-volume consumers, especially in manufacturing-intensive segments.
-
Smaller specialist manufacturers and distributors (for example, firms with ISO certifications and bespoke derivative portfolios) focus on niche chemistries, formulation expertise, and rapid sample-to-scale pathways for early-stage developers.
Strategically, we see three plausible competitive moves through 2026: (1) incumbent premium players double down on assurance, traceability, and service to defend price bands; (2) low-cost producers pursue long-term supply agreements and backward integration to lock feedstock access; (3) mid-market players pursue alliances or bolt-on acquisitions to bridge product quality and distribution gaps. The report’s company playbooks and M&A checklists provide the step-by-step templates to execute these moves while quantifying integration risks and synergies.
Strategic imperatives and recommended actions for 2026
Based on our integrated analysis, PW Consulting recommends the following priority actions for executives planning resource allocation in 2026:
-
Implement a layered procurement strategy: Combine short-term spot exposure capture with medium-term fixed-price agreements and optionality via index-linked contracts for cyclopentanone to protect margins while retaining upside.
-
Invest selectively in purity and compliance: Prioritise capital spend on QA/QC and environmental controls where regulatory trajectories increase customer switching costs. Higher assurance will unlock premium channels in pharmaceuticals and specialty chemicals.
-
Strengthen supplier resilience: Build dual-sourcing for critical intermediates, qualify alternative chemistries where feasible, and deploy supplier scorecards from the report to quantify counterparty risk.
-
Rethink commercial segmentation: Differentiate go-to-market by customer willingness-to-pay (e.g., research reagent vs. bulk intermediate), and align service packaging (minimum order, lead-times, hazardous handling) accordingly.
-
Prepare for regulatory tightening: Use the report’s compliance roadmap to forecast capex and OPEX impacts, and incorporate these into product pricing models and contract negotiations.
-
Prioritise bolt-on M&A where it accelerates capabilities: Target assets that close quality, geographic, or distribution gaps. Use our due-diligence templates to speed evaluation and quantify synergies.
-
Deploy analytics for demand sensing: Shorten the feedback loop between customers and planning teams using near-real-time order analytics to reduce inventory drag and improve fill rates.
How to use the full report
The summary above is a strategic trailer: it demonstrates the depth and utility of the study while reserving detailed segment-level shares, regional splits, and contract-level price curves for the full report and data room. Subscribers receive the complete set of Excel models, supplier scorecards, regulatory impact calculators, and a live Q&A session with our industry analysts to tailor the findings to your portfolio.
If your 2026 plans include pricing changes, procurement commitments, CAPEX on compliance, or acquisition screening in the cyclopentylamine value chain, the full report provides the empirical foundation and execution playbooks to move from decision to implementation.
Closing
PW Consulting’s Worldwide Cyclopentylamine Market report translates market complexity into pragmatic, executable guidance. With a forecast CAGR of 4.95% through 2032 and clear upstream and regulatory inflection points identified, 2026 represents a decisive year to lock strategy, secure supply, and capture value. For full access to the data tables, segment-level analyses, and executable templates referenced here, visit the official report page or contact our industry desk to arrange a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Cyclopentylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fragrant Forecast: PW Consulting Says Worldwide Musk Aroma Chemicals Market to Reach USD 1.54 Billion by 2032, Growing at a 4.25% CAGR
By pmarketresearch, 2026-08-12
PW Consulting Releases Strategic Brief: Worldwide Musk Aroma Chemicals Market — Essential Intelligence for 2026 Decision-Makers
PW Consulting today publishes the executive brief accompanying its comprehensive Worldwide Musk Aroma Chemicals Market report. Built on a five-year historical foundation (2020–2025) and a seven-year forecast horizon (2026–2032), the analysis equips executives with the market context, competitive readouts, regulatory risk maps, and executable playbooks needed to navigate a complex transition era for musk aroma chemistries.
Laboratory Remote Monitoring Solution Market
Market snapshot — what the headline numbers tell you
The musk aroma chemicals market has shown steady, if uneven, recovery and renewal since 2020. Total industry revenue in our base year (2025) stands at USD 1,150.0 Million (revenues expressed in USD Million). PW Consulting projects a compound annual growth rate (CAGR) of 4.25% across the 2026–2032 forecast window, driving total industry revenue toward the mid-2030s figure of approximately USD 1,539.0 Million under our central scenario.
Worldwide Appraisal Service Market
Understanding these headline dynamics—near-term stability with mid-term expansion—matters because they encapsulate the combined effects of regulatory reformulation, emerging sustainable chemistries, and renewed demand from fine fragrance and consumer categories. The transition is not a uniform uplift: the historical series through 2020–2025 reflects episodic volatility tied to raw-material cycles, regulatory deadlines, and supplier capacity investments. 2026 is therefore a pivotal planning year: companies that align product development, supply strategy, and regulatory compliance in 2026 will capture disproportionate share gains during the forecast period.
Worldwide CNC Lathes Market
Why this report is strategically material for 2026 planning
- Actionable regulatory intelligence: Our analysis synthesizes the implications of recent IFRA and REACH actions—most notably constraints introduced through recent IFRA amendments—and maps practical reformulation pathways that preserve olfactive quality while reducing compliance risk.
- Supply-side roadmaps: We trace near-term capacity moves and raw-material dynamics that will affect availability and pricing—critical for procurement and trade-off modeling when negotiating contracts in 2026.
- Competitive positioning and concentration analysis: The market exhibits moderate concentration (CR3 ~48.5%, CR5 ~62.1%). We show where scale still matters and where nimble specialists can outmaneuver incumbents.
- Investment-grade scenario planning: The forecast includes downside, base, and upside scenarios with triggers and leading indicators—enabling capital allocators to align capex, M&A, and R&D budgets to market inflection points.
What the report contains — practical tools and deliverables
- Granular market sizing and vintage data across 2020–2025, with transparent methodology and sensitivity testing to reconcile alternative supplier or regulatory outcomes.
- Seven-year forecasts (2026–2032) with scenario matrices, model inputs, and a set of early-warning KPIs to track which scenario is unfolding in real time.
- Regulatory impact maps that translate IFRA and REACH changes into quantifiable reformulation cost vectors and product-category risk profiles.
- Supply-chain and raw-material analysis, including supplier capability heatmaps, capacity expansion timelines, and sourcing risk scores.
- Competitive profiles and playbooks for 12+ manufacturers and fragrance houses—covering R&D capabilities, manufacturing footprints, biotechnology initiatives, and go-to-market approaches.
- Go-to-market and innovation playbooks that deliver step-by-step options for product reformulation, co-development partnerships, and premiumization strategies aligned with sustainability claims.
- M&A and JV target shortlist with acquisition rationale and integration checklists tailored to buyers seeking downstream distribution, technology access, or capacity lift.
Competitive landscape — strategic implications for suppliers and buyers
The musk aroma chemicals arena is shaped by a blend of global fragrance houses, specialty aroma producers, and larger chemical players. Leading firms have differentiated along three vectors: performance formulation (fixative strength and olfactive longevity), regulatory-compliant chemistries (macrocyclic and biodegradable alternatives), and supply-chain integration (to control cost and traceability).
- Major global fragrance houses leverage scale and formulation expertise to defend high-margin fine fragrance segments. Their integrated supply chains and investment in sustainable variants enable them to offer end-to-end solutions to brand customers.
- Specialty players and family-owned firms emphasize nimble innovation and bespoke synthesis routes—making them attractive partners for niche, premium, and artisan fragrance developers.
- New-capacity investments and biotechnology approaches are increasingly decisive. Recent capacity expansion events underscore this shift: for example, in March 2024, a major ingredient producer commissioned new facilities dedicated to biodegradable musk chemistries, a strategic move designed to meet accelerating demand for sustainable alternatives.
For procurement teams, concentration metrics indicate both opportunity and exposure: the market is neither a pure oligopoly nor atomized. Buyers that consolidate volumes intelligently and engage in co-development or offtake agreements can secure preferential pricing and innovation priority. Sellers, meanwhile, should weigh investments in biodegradable macrocyclics and scalable synthesis platforms to protect margins as legacy chemistries face tightening limits.
Regulation and reformulation — risk to revenue and route to resilience
Regulatory change is the single most important near-term driver. Recent IFRA amendments impose concentration limits and usage constraints for certain musk ingredients in specific product categories, with compliance timetables that extend into late 2025 and beyond. At the same time, REACH and other regional frameworks continue to narrow the window for legacy nitro and certain polycyclic musks due to environmental persistence and bioaccumulation concerns.
These forces create a two-fold pressure:
- Downside: Mandatory reformulation costs, potential shelf-life or olfactive performance trade-offs, and impaired availability for traditional chemistries.
- Upside: A structural premium for innovative, biodegradable macrocyclic chemistries and nature-identical alternatives that can be validated against emerging sustainability standards.
Our market intelligence shows synthetic musks currently dominate supply (roughly 85% share by volume), driven by cost efficiency and consistency. But the competitive edge is shifting toward those who can deliver compliant, high-performance replacements without compromising scent signature—this is the primary battleground in 2026.
Strategic playbook for 2026 — prioritized moves
- For ingredient suppliers: Accelerate commercialization of biodegradable macrocyclics and invest in scale-up partnerships. Prioritize flexible manufacturing that can switch between legacy and next-gen routes to manage demand shocks.
- For fragrance houses: Lock in collaborative R&D agreements with suppliers to co-develop compliant substitutes that preserve creative freedom. Use procurement levers to secure capacity through multi-year offtake agreements tied to performance milestones.
- For consumer brands: Treat fragrance reformulation as a cross-functional program (R&D, legal, marketing). Develop claim substantiation plans early to avoid launch delays and to capture sustainability-driven price premiums.
- For investors and M&A teams: Target firms with validated biodegradable portfolios, strong regulatory dossiers, or proprietary synthesis routes that reduce dependence on constrained precursors.
How to use the report in boardroom and planning cycles
Senior leaders should integrate three deliverables into their 2026 planning cycle: (1) the scenario dashboard to align budget allocation against plausible market paths; (2) the regulatory playbook that lists reformulation triggers and mitigation timelines; and (3) the supplier scorecard to prioritize engagement and contractual design. Together, these tools convert macro forecasts into executable decisions—capex timing, product roadmap prioritization, and M&A appetite.
Closing — the strategic value of timing and the next step
2026 is a decisional hinge year for the musk aroma chemicals ecosystem. The combination of steady mid-term growth (CAGR 4.25%), ongoing regulatory tightening, and targeted capacity investments creates windows for both consolidation and rapid premiumization. Firms that align science, supply, and commercial strategy now will enjoy asymmetric returns over the forecast horizon.
PW Consulting’s full report contains the complete datasets, model files, supplier dossiers, and a confidential annex with M&A target rationales and three practitioner-ready implementation roadmaps. To access the full intelligence suite and obtain a tailored briefing for your executive team, visit the PW Consulting report page or contact our industry practice for a customised walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Musk Aroma Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.6% CAGR for Worldwide Blown Castor Oil Market Through 2032
By pmarketresearch, 2026-08-12
Worldwide Blown Castor Oil Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting presents a strategic preview of our upcoming market study, "Worldwide Blown Castor Oil Market," a practical intelligence product built to guide commercial, procurement, and M&A decision-making in 2026. The study uses 2025 as its base year, draws on a historical window from 2020–2025, and provides a forward-looking forecast through 2032. At a macro level, the market exhibits a steady compound annual growth rate (CAGR) of 5.6% over our forecast horizon, reflecting resilient end‑market demand and evolving formulation requirements across coatings, inks, lubricants, and specialty plastics.
Worldwide Retail Pricing Software Market
Why this report matters for 2026 decisions
-
Actionable foresight: With a full forecast to 2032, the report turns market momentum into investment-ready scenarios — helping executives prioritize capital allocation, capacity expansions, or divestitures.
Sterile Goods Transport Cart Market -
Procurement and pricing clarity: Our pricing models and sensitivity analyses translate recent raw-material volatilities into concrete procurement strategies for buyers and hedging pathways for producers.
Multispecific Antibody Development Platform Market -
Commercial roadmaps: Formulators and coating companies receive go‑to‑market playbooks to capture higher-margin formulations and to navigate technical compliance across jurisdictions.
-
M&A and partnership scouting: The study offers a vendor matrix and capability heatmaps to accelerate partner selection and due diligence in a moderately concentrated supply base.
High-level takeaways (a "trailer", not the full cut)
-
Market trajectory: Blown castor oil demand has rebounded from pandemic-era disruption and, on aggregate, expanded from five-year lows in the early 2020s to a more robust base in 2025. Projected growth through 2032 reflects both formulation shifts (towards more functionalized plasticizers and reactive modifiers) and steady volumes in traditional applications.
-
Concentration and competition: The competitive landscape is characterized as moderately concentrated — the top three and top five suppliers account for a substantial share of supply, underscoring the importance of strategic supplier relationships and dual‑sourcing approaches for buyers.
-
Raw‑material sensitivity: Castor oil pricing remains a primary margin determinant. Prices peaked in late 2025 before easing; early‑2026 indicators show regional variation and month‑on‑month softness in some origins, driven by ample supply and variable downstream demand.
-
Value migration: Premiumization is occurring at the formulation layer. Customers are willing to pay for functional benefits such as oxidative stability and improved film properties, creating differentiation opportunities beyond basic commodity selling.
-
Regulatory and sustainability pressure: Environmental and supply‑chain transparency requirements are reshaping supplier selection and certification expectations, particularly among global formulators and brand owners.
What the report contains — practical, operational content
-
Bottom‑up market sizing and comparative scenario forecasts (2026–2032) built from primary consumption ladders and manufacturer shipment reconciliations.
-
Price‑to‑margin sensitivity models that translate castor oil spot and contract movements into finished‑goods margin impacts across target applications.
-
Supplier matrix and capability heatmaps with technical competency, capacity footprint, quality compliance (COA/TDS/MSDS), and export focus — enabling quick filtering for sourcing or JV targets.
-
Application archetypes that map formulation needs (e.g., coatings, inks, greases) to product specifications, helping R&D prioritize product development and sample programs.
-
Scenario playbooks for producers and buyers — covering price shocks, crop‑related supply disruptions, rapid demand shifts, and regulatory constraints — with recommended tactical and strategic responses.
-
M&A and partnership due‑diligence checklists, including commercial synergies, integration risks, and pro forma margin uplift levers.
Competitive landscape: who matters and practical implications
-
Jayant Agro‑Organics Ltd. (Mumbai, India) — As an integrated manufacturer and exporter, Jayant represents the archetypal vertically integrated supplier. For buyers, working with integrated players provides reliability on traceability and larger volume capability; for investors, these players present attractive platforms for vertical integration.
-
Girnar Industries (India) — Known for polymerized grades, Girnar’s positioning underscores the technical segment of blown castor oil where customers pay a premium for tailored functionality (e.g., heat‑set inks, special resins).
-
Vandeputte Group (Belgium) — A European oxidized‑oil specialist, Vandeputte exemplifies regional technical leadership. Their strengths lie in customized oxidized oils for performance‑critical applications — a model to emulate for mid‑sized challengers targeting specialty niches.
-
CanCastor (Swift Current, Canada) and Castor International (Netherlands) — These players illustrate the strategic value of specialized sourcing, documentation rigor, and origin diversification. Buyers prioritizing compliance and consistent specs will find such suppliers attractive.
-
Tongliao TongHua (China), Thai Castor Oil Industries (Thailand), Nikunj Chemicals, Adya Oils, Gokul Agro Group — Regional producers that combine scale, cost competitiveness, and export focus. Their presence highlights the need for sophisticated logistics and quality assurance processes for global buyers.
-
Strategic implication: Given the moderate market concentration and the mixture of integrated and specialty players, firms should calibrate their partner strategies: global formulators need a blend of large integrated suppliers for volume and regional specialists for technical grades.
Supply chain and pricing dynamics — what 2026 decision-makers must watch
-
Price volatility: Castor oil prices exhibited significant swings in late 2025 before easing in early 2026. Regional differentials persist, and short‑term spot movements have translated into margin pressure for producers and cost spikes for formulators.
-
Regional price snapshots (indicative): market intelligence captured peaks and the subsequent softening across major origins in late‑2025 and early‑2026 — reinforcing the need for dynamic pricing clauses and short‑term hedging tools.
-
Supply sensitivity: The castor value chain remains exposed to agricultural cycles and crop yields. Even moderate shifts in origin production can ripple through derivative pricing and availability.
-
Operational levers: Our report models inventory optimization, contract structures (indexation, banded pricing), and localized buffer strategies to mitigate these effects while preserving working capital efficiency.
Strategic playbook for 2026 — recommended actions by stakeholder
-
Producers: prioritize capacity flexibility, invest in value‑added grades, and formalize long‑term offtake structures with key customers. Consider backward integration or tolling arrangements to stabilize margins.
-
Formulators and end users: implement multi‑source procurement, adopt indexed contracting with optionality, and accelerate qualification of technical suppliers to capture premium functionality.
-
Distributors: build inventory hubs in low‑cost logistics gateways, offer technical support services to customers, and create blended stock programs to smooth supply shocks.
-
Investors and strategic buyers: target assets with technical differentiation or strong origin control; prioritize companies with documented supply contracts and quality certifications.
Why PW Consulting’s dataset and approach are distinctive
-
Methodology: the study combines primary interviews across the value chain, shipment and trade reconciliations, and bottom‑up plant capacity modeling. We stress‑test scenarios with price decks and crop yield sensitivities to produce robust forward curves.
-
Practicality: every chapter includes executable templates — from procurement clauses to sample due‑diligence questionnaires — designed to be deployed immediately by commercial teams and boardrooms.
-
Balanced disclosure: in this preview we intentionally present strategic signals and executive recommendations while withholding granular segment splits and confidential unit economics. The full report contains the complete segmentation, granular application demand matrices, and a proprietary supplier scorecard available to subscribers.
Decision‑makers preparing budgets, negotiating contracts, or evaluating strategic transactions in 2026 will benefit from integrating the study’s market forecast (CAGR 5.6% through our 2026‑2032 horizon), supplier heatmaps, and pricing scenarios into their planning cycles. For organizations seeking the full dataset, detailed supplier profiles, and downloadable scenario models, please contact PW Consulting or visit our research portal for subscription access to the complete "Worldwide Blown Castor Oil Market" report.
Authored by: PW Consulting — Senior Strategic Advisory and Industry Analysis Team. Our global practice combines chemicals, materials, and supply‑chain expertise to turn market intelligence into executable strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Blown Castor Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Wiping Cloth Market to Expand from USD 4.52B in 2025 to USD 6.42B by 2032 at a 5.15% CAGR — Asia Pacific Leads with ~USD 1.54B
By pmarketresearch, 2026-08-12
Worldwide Industrial Wiping Cloth Market — Strategic Preview for 2026: What Senior Decision-Makers Need to Know
As PW Consulting’s Chief Industry Analyst, I’m pleased to present an executive preview of our new Worldwide Industrial Wiping Cloth Market report — a targeted, strategy-first study built for executives who need to make high-consequence decisions in 2026. This briefing highlights the structural forces, competitive dynamics, and actionable options that will shape supplier selection, product roadmaps, and M&A activity across the industrial wiping cloth value chain — while intentionally withholding the granular segment tables and region-by-application numbers reserved for authorized report access.
Worldwide Enterprise Storage System Market
Market trajectory at a glance
The industrial wiping cloth market has demonstrated steady expansion through the early 2020s and is set to continue on an upward trajectory across our 2026–2032 forecast window. After recovering and expanding from the 2020 base, the market reached an estimated USD 4.52 billion in 2025. PW Consulting’s top-line forecast uses a 5.15% CAGR for 2026–2032 to model scenarios across varying demand and supply assumptions. By 2032 the market is projected to materially exceed mid‑decade levels, driven by a combination of manufacturing intensity, maintenance spending, and increasing adoption of engineered wiping solutions in controlled environments.
Driver Training Management Software Market
Why 2026 is a strategic inflection point
- Macro-to-micro alignment: Manufacturing and maintenance activity is normalizing post-2024, creating predictable recurring demand for mid- and high-performance wiping solutions rather than purely commodity rags.
- Sustainability and regulations are converging with commercial incentives: Recycling and circular procurement policies are elevating interest in recycled-textile wiping products and rental models, placing new requirements on suppliers and buyers.
- Fragmentation creates opportunity: Market concentration metrics show a fragmented supplier landscape — a small proportion of sales are controlled by the largest global players, leaving room for regional specialists, service-enabled models, and consolidation plays.
What the report contains — practical, executable intelligence
This study is structured to move procurement, product, and corporate development teams from insight to decision-ready actions. Key operational deliverables include:
Animal-Specific Constant Temperature Amplification Nucleic Acid Analyzer Market
- Top-down market model and three-tier scenario forecasts (base, upside, downside) for 2026–2032 that isolate demand drivers and stress-test pricing assumptions under commodity and engineered-product mixes.
- Raw-material and input-cost intelligence: analysis of cotton, polyester, nonwoven (spunlace, airlay, meltblown) and recycled feedstock availability and price sensitivity with supplier risk heatmaps.
- Supplier benchmarking and a decision matrix for vendor selection, comparing service models (rental vs. disposable), vertical integration, geographic sourcing risks, and quality certifications relevant to controlled environments.
- Commercial playbooks tailored to buyer segments — automotive & aerospace, electronics & semiconductors, heavy industry, and healthcare — identifying margin expansion levers (e.g., value-added formulations, pre-saturated wipes, logistics bundling).
- Sustainability impact framework: quantified levers for waste reduction, recycled-content sourcing, and service-based models (rental/collection) to support procurement targets or regulatory compliance through 2028–2032 horizons.
- M&A and partnership screening: target archetypes, valuation multiples observed across related technical textile deals, and integration considerations for bolt-on acquisitions that deliver immediate scale or access to engineered-product capabilities.
- Operational risk playbook covering supply shocks, raw-material volatility, and contamination-control requirements critical to semiconductor and life-science customers.
Competitive landscape — what to watch among established players
The competitive field is diverse: pure-play manufacturers, family-owned wholesalers, contract-service providers, and rental specialists all compete for adjacent demand pools. A cross-section of incumbent and capable challengers illustrates the strategic options for buyers and investors:
- Carolina Textiles — a U.S. Southeast leader with strong wholesale and distribution capabilities focused on bulky, value-oriented rags and wipes across industrial and janitorial channels. Their strengths lie in scale to service regional MRO and automotive aftermarket volumes.
- Berkshire Corporation — focused on engineered wipes for controlled environments and precision manufacturing; well positioned where product specification and certification drive purchasing decisions.
- U.S. Wiping Company and Wipeco — durable, absorbent wipe suppliers that serve manufacturing and janitorial customers; they compete on product breadth and supply reliability.
- A&A Wiping Cloth and Anchor Wiping Cloth — legacy producers with deep manufacturing know-how and established B2B channels; niche strength in sanitized and specialty microfiber products.
- Kleenrags, JEENOR, SYSBEL (China-based) — export-capable manufacturers focused on cost-competitive, high-performance cloths and nonwoven wipes for metalworking and heavy industrial use.
- Lindström Group — a service-oriented Northern European player offering rental and pickup logistics for wipers; their model highlights how service propositions can vertically differentiate in mature markets.
Each of these company archetypes represents a different strategic asset: scale distribution, engineered-product IP, contract service logistics, cost-competitive manufacturing, or circular-service models. The choice of partner depends on buyer priorities — cost, consistency, environmental footprint, or contamination control.
Strategic implications for procurement, product, and corporate development in 2026
We recommend organizations adopt a multi-track approach that preserves optionality while capturing near-term savings and long-term differentiation:
- Segment supplier relationships by total cost of ownership (TCO): Reserve long-term, performance-focused partnerships for controlled-environment lines while pursuing competitive spot sourcing for commodity-grade rags.
- Lock in sustainability commitments early: Buyers with explicit recycled-content or take-back requirements should prioritize suppliers with documented circular-economy capabilities or rental logistics — these become harder to retrofit later.
- Consider hybrid service-product models: Where on-site contamination control and uptime matter (e.g., semiconductors, aerospace), rental and managed-service models reduce buyer logistics burden and create sticky revenue for suppliers.
- Pursue selective consolidation: Given the market’s fragmentation, strategic bolt-ons that add engineered-wipe technology, specialty nonwoven capacity, or last-mile rental logistics can be accretive and defensible.
- Stress-test procurement against raw-material scenarios: Our report provides pre-built scenario sensitivities for common feedstocks (cotton, polyester, nonwoven polymers) to quantify margin exposure and trigger hedge or supplier diversification actions.
Regulatory, sustainability and raw-material dynamics
Three external dynamics should be at the top of any 2026 agenda:
- Raw material mixes are diversifying: supply chains now balance virgin textile inputs and recycled post-consumer fabrics, with process choices (spunlace, airlay, meltblown) influencing both product performance and footprint.
- Sustainability requirements are moving from voluntary to procurement-driven: public and private buyers are increasingly specifying recycled content or lifecycle-impact criteria, which shifts sourcing and supplier capabilities into procurement scorecards.
- Standards and innovation converge at industry events: conferences such as World of Wipes and trade expos provide early signals on advanced formulations, manufacturing efficiencies, and regulatory expectations that can materially change product specifications within 12–24 months.
Signals-of-change and near-term disruptors
Our research actively tracked the most salient recent developments that will influence decision-making in 2026:
- Trade shows and conferences (e.g., World of Wipes, The Clean Show) accelerated adoption curves for advanced nonwoven technologies and sustainability-enabled products in 2025–2026.
- Demand-side shifts in electronics and healthcare are increasing the share of engineered wiping solutions over commodity rags in high-value applications.
- Regional manufacturing restarts and maintenance cycles are driving predictable replenishment flows, but localized material shortages and logistics bottlenecks still create premium opportunities for vertically integrated suppliers.
How to use this report in 2026 — recommended actions by role
- Procurement leaders: Deploy the report’s TCO matrix to re-classify spend and conduct targeted RFPs for engineered wipes and managed-service offerings within the next 90 days.
- Product and R&D heads: Use the raw-material trends and conference intelligence to update product roadmaps, prioritize formulations that meet recycled-content targets, and partner with nonwoven innovators for pilot programs.
- Corporate development teams: Use the target archetypes and valuation heuristics to screen bolt-on acquisitions that close capability gaps — particularly in rental logistics, pre-saturated wipes, and nonwoven production capacity.
- Operations and risk teams: Incorporate the report’s supply-shock scenarios into continuity plans; prioritize dual-sourcing for polymer feedstocks and recycled-textile supplies.
Why PW Consulting’s approach matters
Our methodology blends top-down macro modeling with field-level supplier intelligence and buyer interviews to produce decision-ready guidance rather than a passive data dump. We prioritize actionable outputs — such as negotiation playbooks, supplier scorecards, and M&A target archetypes — so that commercial teams can convert insight into improved margins, reduced risk, and faster time-to-market.
Next steps and how to access the full study
This preview highlights the strategic contours and practical use cases for the full Worldwide Industrial Wiping Cloth Market report. For procurement teams, product leaders, and corporate development professionals preparing 2026 budgets and strategic plans, the full report contains the granular segmentation, supplier scorecards, and downloadable models necessary to operationalize these insights.
To obtain the complete dataset, detailed segmentation tables, and custom consulting options, please visit the PW Consulting market reports page. The full report provides the empirical tables and actionable appendices that we intentionally omitted here to preserve the tractability of executive decision-making while encouraging direct engagement for proprietary detail.
— PW Consulting, Global Industrial Materials Practice
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Wiping Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mine Shaft Elevator Market Poised for a 5.25% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Mine Shaft Elevator Market — Strategic Preview for 2026 Decisions
Executive snapshot
The worldwide mine shaft elevator market has moved from a niche safety and access technology to a strategic lever for operations, capital allocation, and downstream processing efficiency. After recovering from pandemic-era disruptions, the market reached roughly USD 1,050 million in 2025 and is forecast to exceed USD 1,140 million in 2026, with a compound annual growth rate (CAGR) of approximately 5.25% through 2032, when the market is projected to be close to USD 1,500 million. For executive teams planning capital programs, procurement windows, or M&A activity in 2026, these headline dynamics change the calculus: hoisting systems are no longer just engineering line items, they are portfolio-level decisions affecting safety, throughput, and long-dated operating cost profiles.
Heavy Duty Cable Protector Market
Why this report matters for 2026 strategic planning
-
Timing of capital deployment: The market’s steady growth and replacement cycles for mature shaft infrastructure create discrete windows where procurement costs, delivery lead times, and contractor availability materially affect project IRR. Our forecast identifies these windows and models sensitivity to lead times and component scarcity.
Worldwide Environment, Health and Safety (EHS) Management Software Market -
Risk-adjusted total cost of ownership (TCO): Hoist systems are capital-intensive and long-lived. Small design or supplier differences translate to meaningful lifecycle cost variance once safety upgrades, regulatory-driven retrofits, and rope replacement schedules are integrated. The report provides TCO frameworks that prioritize decisions which reduce lifecycle cash drag rather than simply minimizing upfront CAPEX.
Worldwide WeatherProof Outside Television Market -
Regulatory and compliance-driven replacement: New and updated safety requirements—most notably recent MSHA updates and existing federal rules that mandate overspeed, overwind, and automatic stop controls—accelerate upgrade cycles in some jurisdictions. Compliance timelines and the cost of non-compliance are modelled so executives can plan CAPEX and operational budgets with confidence.
What’s inside the PW Consulting report (practical, implementable contents)
-
Market sizing and scenario modelling — A transparent, bottom-up market-sizing methodology with alternate scenarios for commodity cycles, deepening of ore bodies, and regional capex shifts. The report provides scenario outputs for 2026 planning that can be embedded in capital approval packs.
-
Supplier benchmarking and procurement playbooks — Scorecards covering technical capability, service networks, delivery lead times, and aftermarket economics. We translate supplier attributes into procurement strategies (single-supplier vs multi-sourcing; buy-build vs partner; OPEX-based service contracts).
-
Regulatory compliance matrix — A practical matrix that maps common regulatory obligations (e.g., inspection regimes, motor-driven equipment standards, and hoist-specific safety requirements) to design and operational mitigations, with timelines to align compliance capex with broader mine plans.
-
Retrofit and replacement decision trees — Actionable decision frameworks to decide whether to retrofit, rebuild, or replace hoisting systems, incorporating lifecycle rope management, controller/software upgrades, and energy-efficiency retrofits.
-
Digital diagnostics and predictive maintenance playbook — Guidance on deploying nondestructive testing, rope-monitoring sensors, and predictive analytics to extend safe service life and rationalize spare-part inventories.
Competitive landscape — what to watch in 2026
The market exhibits moderate concentration: the top three suppliers account for a meaningful portion of market supply, while the top five capture a clear majority. That structure creates both supply-side leverage and opportunities for differentiated entrants who can address retrofit economics or specialized narrow-shaft applications.
-
Alimak Group (Stockholm, Sweden) — Known for rack-and-pinion industrial elevators and temporary/permanent vertical access solutions, Alimak’s strength is in modular, safety-certified platforms designed for personnel and materials in confined shaft environments. For buyers, Alimak represents a low-friction option for retrofit or vertical access projects where standardization and safety certification are priorities.
-
ABB (Zurich, Switzerland) — With a long history in complete hoist systems, ABB brings integrated electromechanical packages and control systems that enable higher automation and regenerative-energy capabilities. ABB’s recent collaboration to demonstrate novel vertical-bucket elevator concepts highlights the company’s push into capital-productive innovations that can reduce installation complexity and time.
-
SIEMAG TECBERG (Haiger, Germany) — A specialist in shaft hoisting systems with full mechanical and electrical solutions for production and service hoists. Recent project deliveries for multi-shaft systems indicate robust orderflow in certain markets and underline the importance of delivery orchestration in large, multi-system contracts.
-
Century Elevators (United States) — Focused on narrow-shaft permanent mining elevators with an emphasis on control systems and drives that meet mine safety codes. For operators with constrained shaft geometry, Century offers tailored solutions that minimize shaft modifications.
-
KONE Corporation (Espoo, Finland) — Applies elevator R&D and deep-shaft testing capability to mining applications, emphasizing energy-efficient hoists and extensive testing for deep vertical profiles. KONE’s approach benefits mines where energy consumption and deep-shaft performance are significant cost drivers.
Recent vendor moves and implications
-
SIEMAG TECBERG’s multi-system deliveries (May 2025) underline contractor capability as a differentiator: suppliers who can coordinate multiple shaft installs for a single client capture higher margin and reduce integration risk for operators.
-
ABB’s collaboration (Nov 2024) on vertical-bucket demonstrators signals vendor-led innovation aimed at reducing CAPEX and construction time. Buyers should evaluate demonstrator risk and partner early to capture first-mover retrofit economics where appropriate.
Regulatory and operational dynamics that will drive 2026 decisions
-
Regulation is a near-term driver: training programs and updated safety standards for electric motor-driven mine equipment, as well as prescriptive hoist inspection requirements, will push some operators to accelerate upgrades.
-
Component maintenance regimes matter more than ever: steel wire ropes and other critical components are subject to regular nondestructive testing and visual inspection regimes that change life-expectancy profiles and spare-part strategies. Investing in digital inspection and rope-monitoring technologies produces outsized returns on safety and uptime.
-
Service and aftermarket economics will shape supplier selection: with higher concentration among the largest suppliers, operators must balance immediate supplier reliability with the value of open-architecture controls and local service partnerships.
Recommendations for 2026 corporate decision-makers
-
Adopt a scenario-first CAPEX plan — incorporate sensitivity to delivery lead times, rope supply constraints, and regulatory acceleration when approving hoist-related capital budgets; small shifts in timing can change NPV materially given long asset lives.
-
Prioritize TCO over lowest-bid procurement — require lifecycle costing in all RFPs, including rope-change schedules, energy recovery options, and remote diagnostics; reward suppliers that demonstrate measurable lifecycle savings.
-
Invest in digital monitoring pilots — deploy rope- and gearbox-monitoring sensors on one critical shaft as a prelude to a systematic retrofit program; data from pilots will reduce uncertainty and support risk-based maintenance.
-
Defensive supplier strategy — given a market where top players command a significant share, lock in service agreements and consider staged supplier diversification for critical components to reduce single-point failure risk.
-
Explore strategic partnerships — engaging with vendors on demonstrator projects (as seen with ABB and vertical-bucket concepts) can reduce capital intensity and shorten project schedules if proven at scale.
How PW Consulting can help
PW Consulting’s Worldwide Mine Shaft Elevator Market report is designed as a practical decision-support tool for 2026 planning cycles. Our offering includes the full dataset and underlying models, supplier scorecards, executable procurement playbooks, and bespoke workshops that align hoist-investment decisions with broader mine planning and ESG objectives.
We intentionally provide this preview to highlight the strategic implications and practical outputs you can expect. To access full segmentation tables, regional breakout models, and supplier-level datasets that are essential to transactional diligence and procurement, please visit the report landing page or contact our client services team to commission a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Mine Shaft Elevator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hydrochar Market Set to Climb from USD 285.5 Million in 2025 to USD 505.37 Million by 2032, Forecasting 8.5% CAGR
By pmarketresearch, 2026-08-12
Worldwide Hydrochar Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting’s latest market study—anchored on 2025 as the base year and projecting through 2032—distills the strategic intelligence energy, waste and agriculture executives need to make decisive moves in 2026. The hydrochar market has shifted from niche technology to a commercial-scale value pool: global revenue rose from approximately USD 195 million in 2020 to USD 285 million in 2025, and our model now forecasts a trajectory to just over USD 505 million by 2032 at a compound annual growth rate (CAGR) of 8.5% (USD, revenue unit: Million). This report is designed as an operational playbook for boardrooms and deal teams—providing the analytical scaffolding required to convert emerging policy and feedstock advantages into sustainable competitive advantage.
Industrial Tilting Devices Market
Why 2026 is a Pivotal Year
-
Policy inflection points translate into commercial windows. Recent regulatory updates across major markets are tightening organic waste streams and creating clearer pathways for hydrothermal carbonization (HTC) outputs to access incentives designed for low‑carbon fuels and soil amendments. These policy drivers collapse uncertainty that had previously slowed capital deployment.
Worldwide Car Sensors Market -
Feedstock dynamics are converging with technology maturation. Availability of wet biomass residues and municipal biowaste at industrial scales is enabling project bankability in ways not present five years ago—meaning that feasibility studies completed today can be shovel‑ready within typical project development timelines.
Worldwide Chlortetracycline Market -
Investor appetite for carbon‑removal adjacent solutions has increased materially. Hydrochar’s dual role as a fuel substitute and durable carbon product accelerates its appeal to corporates seeking both scope‑reduction and carbon‑storage pathways.
Market Dynamics and Strategic Implications
-
Feedstock supply and logistics determine project economics. While the available tonnages of wet biomass are large, localized collection efficiency, seasonality, pre‑processing costs, and competing valorization routes (anaerobic digestion, composting) create winner‑takes‑most corridors for early movers who integrate supply chains.
-
Technology choice matters for market positioning. HTC variants and competing thermochemical routes diverge on capital intensity, yield, and product specs (energy density, ash content). Strategic buyers must stress‑test vendor claims against independent yield assumptions and downstream handling costs.
-
Market concentration remains low. The sector is populated with specialist technology providers and vertically integrated operators; the top players collectively occupy less than one‑third of the market today—indicating both fragmentation and opportunity for consolidation over the forecast period.
-
Policy‑linked revenue mechanisms are a double‑edged sword. Carbon credit streams and co‑firing incentives materially improve returns but introduce policy risk. Scenario planning across policy outcomes should be embedded in all capital allocation decisions.
Competitive Landscape: Who’s Deploying at Scale and What It Signals
Our fieldwork and primary interviews confirm a cohort of technology and project developers that are setting commercial benchmarks. PW Consulting’s competitive assessment evaluates these firms on technology maturity, feedstock flexibility, route‑to‑market, and financing models.
-
Ingelia (Barcelona, Spain) — Focused on HTC plants that convert sewage sludge and other biowaste into hydrochar for fertilizer and fuel applications. Their recent commercial plant start in Italy demonstrates a move from pilot to repeatable commercial installations, signaling a template for municipal partnerships.
-
TerraNova Energy GmbH (Münster, Germany) — Developer of the HTCycle platform with pipeline commitments for industrial‑scale plants. Partnerships announced for sizeable plants indicate a business model leaning on strategic alliances with waste aggregators and municipal authorities.
-
BlackCarbon GmbH (St. Pölten, Austria) — Produces premium hydrochar from lignocellulosic feedstocks aimed at industrial boiler replacement. Their recent capacity expansion speaks to demand from heavy industry seeking rapid coal substitution pathways.
-
Arbaflame A/S (Aarhus, Denmark) — Builds pelletized hydrochar for co‑firing in power plants. Their positioning illustrates the near‑term commercial opportunity in the power generation sector where co‑firing standards are clear.
-
Haffner Energy (Vitry‑le‑François, France) — Operator of the ERC process producing SynChar; certification of pilot plants shows intent to capture both energy and carbon sequestration use cases.
-
Antaco (Santiago, Chile) — Regional player converting forestry residues and sludge into marketable hydrochar, underscoring geographic diversification and the ability to tap forestry value chains in South America.
Taken together, these players illustrate two convergent strategies: (1) vertically integrated operators that control feedstock and offtake, and (2) technology licensors and OEMs seeking high‑margin equipment and licensing revenue. Investors should evaluate which model aligns to their time horizon—asset‑heavy, lower‑risk cash flows versus asset‑light IP plays with scalability upside.
Regulation, Science and the Value Equation
-
Regulatory tailwinds: Recent updates—such as stricter separate collection rules and clearer ETS treatment for co‑fired hydrochar—are reducing policy ambiguity in key markets and accelerating offtake negotiations for projects that can demonstrate lifecycle emissions reductions.
-
Performance metrics: Independent literature shows hydrochar can deliver high carbon yields from wet biomass and substantial energy densification, making it competitive as both a fuel substitute and a soil amendment—though specifications vary by feedstock and process conditions.
-
Feedstock scale: Large volumes of wet biomass residues are technically available in several regions, but economic capture of these volumes requires logistics integration, contract standardization, and often co‑investment with municipal or agricultural stakeholders.
What PW Consulting’s Report Delivers (Practical Tools for 2026 Actions)
This research is constructed to be operational. Highlights of the deliverables include:
-
A calibrated market model from 2020–2032 with base‑year (2025) reconciliation and scenario variants that stress policy, feedstock cost, and yield assumptions—built for sensitivity testing by CFOs and strategists.
-
Technology comparison matrix and vendor scorecards—benchmarks for CAPEX/OPEX, yields, and product specs to inform procurement and partner selection.
-
Supply‑chain maps and contract templates—practical tools for securing feedstock volumes and structuring offtake agreements, including recommended KPIs and pricing collars.
-
Regulatory impact matrix—translated into quantifiable P&L levers for project financial models and permitting timelines by jurisdiction.
-
M&A and JV playbook—target screens, valuation heuristics, and due diligence checklists tailored to hydrochar assets and technology providers.
-
Commercial go‑to‑market playbooks for utilities, waste companies and industrial end‑users—detailing pilot design, scale‑up milestones, and stakeholder engagement templates.
Actionable Recommendations by Stakeholder
-
Corporate investors and strategics: Lock in feedstock supply through long‑dated contracts or upstream equity, and prioritize technologies with independent yield validation. Layer policy scenarios into valuation—don’t rely on a single incentive mechanism to validate returns.
-
Waste managers and municipalities: Evaluate HTC partnerships as part of an integrated waste‑valorization portfolio. Use demonstrations to validate seasonal collection models and offtake aggregations before committing to full‑scale plants.
-
Utility and power producers: Fast‑track co‑firing pilots where permitting and fuel handling are clearly defined, and use hydrochar as a transitional lever to reduce coal exposure while assessing feedstock price volatility.
-
Equipment manufacturers and EPCs: Standardize modular designs to reduce project timelines and bill‑of‑materials costs; aftermarket service contracts will be an important recurring revenue stream.
-
Policy makers: Harmonize quality standards for hydrochar products and create transparent carbon accounting rules to lower market entry barriers and foster investment.
Methodology and the “Trailer” Principle
PW Consulting’s analysis synthesizes proprietary interviews, plant‑level performance data, vendor disclosures and third‑party literature. The report provides granular spreadsheets and project‑level cashflow models for subscribers. In line with our “trailer” approach, this press release communicates high‑confidence directional findings and strategic recommendations, while detailed segmental splits, regional breakdowns, and proprietary unit‑cost tables are reserved for the full report accessible via our website.
Next Steps for Decision Makers
If 2026 is when your organization moves from study to execution, the right inputs today can determine who captures value tomorrow. PW Consulting’s Worldwide Hydrochar Market report is engineered to shorten the learning curve, de‑risk capital allocation, and identify the most promising corridors for roll‑out and consolidation. For teams preparing investment memos, RFPs, or regulatory filings this year, the models, vendor scorecards and contract templates in the full report will be indispensable.
To explore the full dataset, segmental forecasts and our proprietary project models, visit the PW Consulting report page or contact our hydrochar practice for a briefing and tailored scenario analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Hydrochar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Canine Mammary Tumor Treatment Market Poised for 7.58% CAGR, Eyes USD 1.41 Billion by 2032
By pmarketresearch, 2026-08-12
Worldwide Canine Mammary Tumor Treatment Market: Strategic Imperatives for 2026
By PW Consulting — Chief Industry Analyst
Worldwide Blackcurrant Seed Oil Market
Executive snapshot
The global market for canine mammary tumor treatment is transitioning from a fragmented, surgery-dominant landscape into a multi-modal, innovation-driven healthcare market. Our new PW Consulting report—anchored to a 2025 base year and projecting through 2032—finds the market valued in the high hundreds of millions of USD in 2025 and growing at a compound annual growth rate of roughly 7.6% through the forecast horizon. Under that trajectory, the market moves into the low‑billion dollar range by the end of the forecast period, reflecting sustained clinical demand, technology diffusion in specialty care, and an expanding therapeutic pipeline that spans surgery, chemotherapy, radiation, and next‑generation targeted and immune therapies.
Worldwide Industrial Arc Furnaces Market
Why 2026 is a pivotal year for corporate strategy
- Regulatory inflection points and designation pathways are lowering barriers for veterinary oncology assets, enabling companies to accelerate commercialization strategies that were previously constrained by regulatory ambiguity.
- Precision diagnostics and genomics are shifting oncologic decision‑making from empiric to targeted approaches—creating new pricing, reimbursement, and revenue model opportunities for diagnostics–therapy bundles.
- Capital allocation choices (organic R&D vs. acquisition/partnership) made in 2026 will determine which players secure durable access to high‑margin specialty channels in the veterinary ecosystem over the next five to seven years.
Core market dynamics and clinical context
Surgical resection remains the recognized gold standard for most canine mammary tumors, with adjuvant systemic therapies applied selectively for high‑risk or metastatic disease. That clinical orthodoxy coexists with growing use of off‑label targeted agents and precision radiotherapy in specialized centers, producing a two‑tier market: broad surgical care delivered across general practice and veterinary hospitals, and concentrated, higher‑value care delivered through specialty oncology clinics, referral centers, and dedicated radiation providers.
Worldwide Agile and DevOps Services Market
Two important structural features drive the market’s outlook:
- Comparative oncology: Canine mammary tumors function as a spontaneous model for human breast cancer, creating bidirectional research value. This accelerates translational opportunities (and investor interest) in PI3K inhibitors, tyrosine kinase inhibitors, and vaccine/immunotherapy platforms.
- Service convergence: Diagnostic genomics, targeted systemic agents, and precision radiotherapy are coalescing into bundled care pathways—heightening the strategic importance of cross‑sector partnerships (pharma, device, diagnostics, and service providers).
Competitive landscape — who matters and why
The market is characterized by an ecosystem of large animal-health incumbents, specialized veterinary oncology innovators, and human‑oncology players translating assets into veterinary use. The competitive map is best understood as overlapping clusters: broad animal-health firms with deep commercialization channels; niche biologics and small‑molecule developers innovating in targeted veterinary oncology; precision-radiotherapy system vendors enabling advanced non‑surgical care; and diagnostic/precision‑medicine providers connecting molecular insights to treatment decisions.
Key strategic profiles covered in our analysis:
- Established animal-health leaders that leverage scale, distribution, and portfolio breadth to commercialize oncology-supportive products and in some cases targeted agents (examples profiled in the report include major multinational animal‑health companies).
- Small to mid‑cap biotech firms that advance veterinary‑first molecules (e.g., tyrosine kinase inhibitors and novel immunotherapies) and pursue accelerated or conditional regulatory pathways to establish early clinical footholds.
- Precision‑medicine platforms and genomic diagnostics businesses that create differentiated clinical value by matching existing and emerging therapies to tumor biology—enabling premium pricing and improved outcomes.
- Radiation‑technology and service providers delivering stereotactic radiosurgery and advanced radiotherapy—these providers are central to non‑surgical therapeutic expansion in tertiary veterinary centers.
Our competitive chapter synthesizes public filings, device adoption trends, clinical registries, and direct interviews to produce practical competitor playbooks—mapping each major player’s strengths, capability gaps, go‑to‑market channels, and near‑term catalysts.
Recent industry developments with immediate strategic consequences
- Regulatory momentum: Recent regulatory designations for veterinary oncology molecules underscore the viability of accelerated development paths. Companies should re‑assess their regulatory strategy to determine whether designations such as conditional approvals or minor‑use pathways can be pursued to shorten time‑to‑market.
- Surgical precision and intraoperative innovation: Emerging intraoperative imaging modalities are improving margin assessment and reducing local recurrence risk—altering surgical standards of care and influencing referral patterns to centers of excellence.
- Clinical translation: Advances in oral targeted agents and immunotherapies originally developed for other canine cancers are being evaluated for mammary tumors; this creates both competitive risk and partnership opportunity for animal‑health firms and biotech sponsors.
What the PW Consulting report delivers — practical, decision‑ready content
This study is built to inform capital allocation, portfolio prioritization, M&A diligence, and commercial planning for 2026. The deliverables include:
- A transparent market‑sizing model (base year 2025) with scenario analysis and a modeled CAGR to 2032—designed for integration into corporate financial planning.
- Therapeutic and service pathway maps that translate clinical guidelines into commercializable care bundles and pricing templates.
- Pipeline and clinical evidence compendia that align candidate molecules and devices to unmet clinical needs, recommended trial endpoints, and pragmatic trial designs optimized for veterinary regulatory pathways.
- Channel and capability assessments that show where to invest (clinical training, specialty center buildouts, vendor partnerships) to capture higher‑value care segments.
- Negotiation playbooks and term‑sheet templates for licensing, co‑development, and distribution agreements—customized for veterinary oncology’s stakeholder map.
- Financial benchmarking and ROI calculators for investment in advanced radiotherapy equipment, genomic testing platforms, and new molecular entities.
Strategic options for executives in 2026
Based on our analysis, executive teams should evaluate a mix of the following moves—each accompanied in the report by tactical checklists and implementation timelines:
- Prioritize translational assets that have a realistic regulatory pathway for conditional/accelerated approval in veterinary indications; pursue early engagement with regulators to de‑risk development timelines.
- Form strategic alliances between diagnostics providers and systemic‑therapy sponsors to create bundled offerings—coupling genomic tests with therapy access programs and outcome tracking to justify premium pricing.
- Invest selectively in specialty radiotherapy capacity or partner with existing service providers to capture referrals for non‑surgical cases; financial models contained in the report demonstrate payback timelines under conservative utilization assumptions.
- Use targeted M&A to acquire capability gaps—diagnostics, translational oncology expertise, or regional specialty networks—rather than broad, horizontal deals that dilute focus.
- Build center‑of‑excellence pilots to gather real‑world evidence and case series that support product differentiation, pricing, and payor conversations.
Risk and mitigation framework
While the growth profile is attractive, decision‑makers must manage several risks: regulatory uncertainty for label expansions, variability in owner willingness to pay for advanced interventions, and channel fragmentation between general practice and specialty centers. The report provides a mitigation matrix that links specific near‑term investments (e.g., outcomes registries, tiered pricing, and education programs) to measurable KPIs to reduce these risks.
Why our dataset matters
PW Consulting’s market model synthesizes multi‑source demand indicators, procedure volumes, pricing benchmarks, and adoption curves. It quantifies total addressable demand at the market level and generates bottom‑up revenue scenarios tied to adoption levers—without exposing proprietary, directionally sensitive segment-level tables in this preview. For commercial teams and corporate strategists, the model serves as a deterministic starting point for scenario planning and for stress‑testing business cases under multiple reimbursement and utilization assumptions.
Call to action
For executives preparing 2026 budgets, our report converts clinical trends into executable commercial initiatives. If you are evaluating product investments, potential partnerships, or regional expansion in veterinary oncology, the full PW Consulting study contains the granular data, competitive intelligence, and playbooks you need to move from strategy to execution. Visit our report page to access the complete dataset, company profiles, and customizable financial models that underpin the findings summarized here.
Contact PW Consulting to schedule a proprietary briefing and a hands‑on workshop that translates these insights into a 90‑day action plan tailored to your organization’s capabilities and strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Canine Mammary Tumor Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com