

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
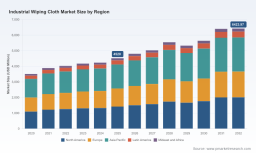
PW Consulting: Industrial Wiping Cloth Market to Expand from USD 4.52B in 2025 to USD 6.42B by 2032 at a 5.15% CAGR — Asia Pacific Leads with ~USD 1.54B

Worldwide Industrial Wiping Cloth Market — Strategic Preview for 2026: What Senior Decision-Makers Need to Know
As PW Consulting’s Chief Industry Analyst, I’m pleased to present an executive preview of our new Worldwide Industrial Wiping Cloth Market report — a targeted, strategy-first study built for executives who need to make high-consequence decisions in 2026. This briefing highlights the structural forces, competitive dynamics, and actionable options that will shape supplier selection, product roadmaps, and M&A activity across the industrial wiping cloth value chain — while intentionally withholding the granular segment tables and region-by-application numbers reserved for authorized report access.
Worldwide Enterprise Storage System Market
Market trajectory at a glance
The industrial wiping cloth market has demonstrated steady expansion through the early 2020s and is set to continue on an upward trajectory across our 2026–2032 forecast window. After recovering and expanding from the 2020 base, the market reached an estimated USD 4.52 billion in 2025. PW Consulting’s top-line forecast uses a 5.15% CAGR for 2026–2032 to model scenarios across varying demand and supply assumptions. By 2032 the market is projected to materially exceed mid‑decade levels, driven by a combination of manufacturing intensity, maintenance spending, and increasing adoption of engineered wiping solutions in controlled environments.
Driver Training Management Software Market
Why 2026 is a strategic inflection point
- Macro-to-micro alignment: Manufacturing and maintenance activity is normalizing post-2024, creating predictable recurring demand for mid- and high-performance wiping solutions rather than purely commodity rags.
- Sustainability and regulations are converging with commercial incentives: Recycling and circular procurement policies are elevating interest in recycled-textile wiping products and rental models, placing new requirements on suppliers and buyers.
- Fragmentation creates opportunity: Market concentration metrics show a fragmented supplier landscape — a small proportion of sales are controlled by the largest global players, leaving room for regional specialists, service-enabled models, and consolidation plays.
What the report contains — practical, executable intelligence
This study is structured to move procurement, product, and corporate development teams from insight to decision-ready actions. Key operational deliverables include:
Animal-Specific Constant Temperature Amplification Nucleic Acid Analyzer Market
- Top-down market model and three-tier scenario forecasts (base, upside, downside) for 2026–2032 that isolate demand drivers and stress-test pricing assumptions under commodity and engineered-product mixes.
- Raw-material and input-cost intelligence: analysis of cotton, polyester, nonwoven (spunlace, airlay, meltblown) and recycled feedstock availability and price sensitivity with supplier risk heatmaps.
- Supplier benchmarking and a decision matrix for vendor selection, comparing service models (rental vs. disposable), vertical integration, geographic sourcing risks, and quality certifications relevant to controlled environments.
- Commercial playbooks tailored to buyer segments — automotive & aerospace, electronics & semiconductors, heavy industry, and healthcare — identifying margin expansion levers (e.g., value-added formulations, pre-saturated wipes, logistics bundling).
- Sustainability impact framework: quantified levers for waste reduction, recycled-content sourcing, and service-based models (rental/collection) to support procurement targets or regulatory compliance through 2028–2032 horizons.
- M&A and partnership screening: target archetypes, valuation multiples observed across related technical textile deals, and integration considerations for bolt-on acquisitions that deliver immediate scale or access to engineered-product capabilities.
- Operational risk playbook covering supply shocks, raw-material volatility, and contamination-control requirements critical to semiconductor and life-science customers.
Competitive landscape — what to watch among established players
The competitive field is diverse: pure-play manufacturers, family-owned wholesalers, contract-service providers, and rental specialists all compete for adjacent demand pools. A cross-section of incumbent and capable challengers illustrates the strategic options for buyers and investors:
- Carolina Textiles — a U.S. Southeast leader with strong wholesale and distribution capabilities focused on bulky, value-oriented rags and wipes across industrial and janitorial channels. Their strengths lie in scale to service regional MRO and automotive aftermarket volumes.
- Berkshire Corporation — focused on engineered wipes for controlled environments and precision manufacturing; well positioned where product specification and certification drive purchasing decisions.
- U.S. Wiping Company and Wipeco — durable, absorbent wipe suppliers that serve manufacturing and janitorial customers; they compete on product breadth and supply reliability.
- A&A Wiping Cloth and Anchor Wiping Cloth — legacy producers with deep manufacturing know-how and established B2B channels; niche strength in sanitized and specialty microfiber products.
- Kleenrags, JEENOR, SYSBEL (China-based) — export-capable manufacturers focused on cost-competitive, high-performance cloths and nonwoven wipes for metalworking and heavy industrial use.
- Lindström Group — a service-oriented Northern European player offering rental and pickup logistics for wipers; their model highlights how service propositions can vertically differentiate in mature markets.
Each of these company archetypes represents a different strategic asset: scale distribution, engineered-product IP, contract service logistics, cost-competitive manufacturing, or circular-service models. The choice of partner depends on buyer priorities — cost, consistency, environmental footprint, or contamination control.
Strategic implications for procurement, product, and corporate development in 2026
We recommend organizations adopt a multi-track approach that preserves optionality while capturing near-term savings and long-term differentiation:
- Segment supplier relationships by total cost of ownership (TCO): Reserve long-term, performance-focused partnerships for controlled-environment lines while pursuing competitive spot sourcing for commodity-grade rags.
- Lock in sustainability commitments early: Buyers with explicit recycled-content or take-back requirements should prioritize suppliers with documented circular-economy capabilities or rental logistics — these become harder to retrofit later.
- Consider hybrid service-product models: Where on-site contamination control and uptime matter (e.g., semiconductors, aerospace), rental and managed-service models reduce buyer logistics burden and create sticky revenue for suppliers.
- Pursue selective consolidation: Given the market’s fragmentation, strategic bolt-ons that add engineered-wipe technology, specialty nonwoven capacity, or last-mile rental logistics can be accretive and defensible.
- Stress-test procurement against raw-material scenarios: Our report provides pre-built scenario sensitivities for common feedstocks (cotton, polyester, nonwoven polymers) to quantify margin exposure and trigger hedge or supplier diversification actions.
Regulatory, sustainability and raw-material dynamics
Three external dynamics should be at the top of any 2026 agenda:
- Raw material mixes are diversifying: supply chains now balance virgin textile inputs and recycled post-consumer fabrics, with process choices (spunlace, airlay, meltblown) influencing both product performance and footprint.
- Sustainability requirements are moving from voluntary to procurement-driven: public and private buyers are increasingly specifying recycled content or lifecycle-impact criteria, which shifts sourcing and supplier capabilities into procurement scorecards.
- Standards and innovation converge at industry events: conferences such as World of Wipes and trade expos provide early signals on advanced formulations, manufacturing efficiencies, and regulatory expectations that can materially change product specifications within 12–24 months.
Signals-of-change and near-term disruptors
Our research actively tracked the most salient recent developments that will influence decision-making in 2026:
- Trade shows and conferences (e.g., World of Wipes, The Clean Show) accelerated adoption curves for advanced nonwoven technologies and sustainability-enabled products in 2025–2026.
- Demand-side shifts in electronics and healthcare are increasing the share of engineered wiping solutions over commodity rags in high-value applications.
- Regional manufacturing restarts and maintenance cycles are driving predictable replenishment flows, but localized material shortages and logistics bottlenecks still create premium opportunities for vertically integrated suppliers.
How to use this report in 2026 — recommended actions by role
- Procurement leaders: Deploy the report’s TCO matrix to re-classify spend and conduct targeted RFPs for engineered wipes and managed-service offerings within the next 90 days.
- Product and R&D heads: Use the raw-material trends and conference intelligence to update product roadmaps, prioritize formulations that meet recycled-content targets, and partner with nonwoven innovators for pilot programs.
- Corporate development teams: Use the target archetypes and valuation heuristics to screen bolt-on acquisitions that close capability gaps — particularly in rental logistics, pre-saturated wipes, and nonwoven production capacity.
- Operations and risk teams: Incorporate the report’s supply-shock scenarios into continuity plans; prioritize dual-sourcing for polymer feedstocks and recycled-textile supplies.
Why PW Consulting’s approach matters
Our methodology blends top-down macro modeling with field-level supplier intelligence and buyer interviews to produce decision-ready guidance rather than a passive data dump. We prioritize actionable outputs — such as negotiation playbooks, supplier scorecards, and M&A target archetypes — so that commercial teams can convert insight into improved margins, reduced risk, and faster time-to-market.
Next steps and how to access the full study
This preview highlights the strategic contours and practical use cases for the full Worldwide Industrial Wiping Cloth Market report. For procurement teams, product leaders, and corporate development professionals preparing 2026 budgets and strategic plans, the full report contains the granular segmentation, supplier scorecards, and downloadable models necessary to operationalize these insights.
To obtain the complete dataset, detailed segmentation tables, and custom consulting options, please visit the PW Consulting market reports page. The full report provides the empirical tables and actionable appendices that we intentionally omitted here to preserve the tractability of executive decision-making while encouraging direct engagement for proprietary detail.
— PW Consulting, Global Industrial Materials Practice
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Wiping Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com