

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Pulp & Paper Enzyme Market Hits $216M in 2025, 8.6% CAGR to $384.62M by 2032
By pmarketresearch, 2026-09-15
Strategic Imperative: Navigating the Enzyme for Pulp & Paper Market in 2026 and Beyond
The global pulp and paper industry stands at a critical juncture where operational efficiency, regulatory compliance, and sustainability mandates converge. As mills across the world strive to optimize production costs while meeting increasingly stringent environmental standards, enzymatic solutions have transitioned from a niche innovation to a core component of modern mill processing. Our latest market research, Enzyme for Pulp & Paper Market, provides a comprehensive strategic roadmap for stakeholders aiming to capitalize on this transformation. With a projected market valuation reaching significant milestones by the end of the forecast period, understanding the underlying drivers, competitive dynamics, and regional nuances is no longer optional—it is essential for informed decision-making in 2026.
This report is designed to equip senior management, procurement leaders, and R&D strategists with the actionable intelligence needed to navigate a landscape defined by rapid technological adoption and shifting supply chain economics. By synthesizing historical data from 2020 through 2025 with a robust forecast extending to 2032, we offer a clear view of the growth trajectory, highlighted by a steady compound annual growth rate that underscores the sector's resilience and long-term potential. The following analysis previews the strategic depth of our findings, illustrating why this intelligence is vital for securing a competitive edge in the coming years.
Macro Growth Trajectory and Market Valuation
The enzyme market for pulp and paper has demonstrated consistent expansion over the past half-decade, recovering from minor fluctuations to establish a strong upward trend. Historical analysis from 2020 to 2025 reveals a market that has grown substantially in revenue terms, surpassing initial expectations as mills accelerate the shift away from harsh chemical processes. This growth momentum is set to accelerate further during the forecast period spanning 2026 to 2032. The market is projected to expand from a robust baseline in 2025 to a substantially larger valuation by 2032, driven by widespread adoption across key application areas and supportive regulatory frameworks globally.
Central to this outlook is a forecasted CAGR that reflects sustained demand for bio-based processing aids. This growth rate is not merely a numerical projection; it signals a structural shift in how pulp and paper manufacturers approach fiber processing, bleaching, and recycling. As raw material costs fluctuate and energy prices remain volatile, enzymes offer a viable pathway to reduce input costs, improve yield, and minimize environmental footprints. Our report details the revenue progression year by year, allowing clients to benchmark their internal projections against market realities and adjust their investment strategies accordingly. The data underscores that the market is moving beyond early adoption phases into a period of mature, scaled integration where enzymatic solutions deliver measurable ROI across diverse mill operations.
Industrial Enzymes Market
Segmentation Insights: Type, Application, and Regional Dynamics
Understanding where value is concentrated requires a granular look at the market's segmentation. Our analysis dissects the market by enzyme type, application, and geography, revealing distinct growth patterns and adoption hotspots. In terms of enzyme types, cellulase and xylanase continue to dominate the landscape, reflecting their critical role in fiber modification, strength enhancement, and bleaching optimization. Amylase, lipase, pectinase, and other specialized enzymes also contribute to the ecosystem, addressing specific process challenges such as deposit control, starch management, and pitch removal. The report provides a detailed breakdown of revenue contributions across these categories, highlighting which enzyme classes are gaining traction and why.
Application-wise, bleaching and deinking represent the largest utilization segments, as manufacturers seek to reduce chlorine usage, lower chemical oxygen demand, and improve pulp brightness without compromising fiber integrity. Fiber modification and other emerging applications are also expanding, driven by the need for customized paper properties and enhanced runnability on the paper machine. The regional analysis further illuminates where demand is strongest. North America, Europe, and Asia Pacific account for the substantial majority of market revenue, each influenced by unique regulatory environments, mill modernization cycles, and raw material availability. Latin America and the Middle East and Africa present emerging opportunities, often linked to capacity expansions and the gradual adoption of cleaner production technologies. Our report maps these regional dynamics in depth, identifying high-growth corridors and potential market entry points without exposing the precise percentage splits or absolute figures that define our premium intelligence offering.
Competitive Landscape: Key Players and Strategic Moves
The market is characterized by a consolidated competitive structure, with a handful of leading biosolution providers commanding a significant share of global revenue. Our report profiles the core companies shaping the industry, analyzing their product portfolios, technological expertise, and recent strategic initiatives. Novonesis, headquartered in Copenhagen, Denmark, remains a dominant force with its FiberCare® enzyme portfolio, which addresses refining, strength improvement, and sustainability in fiber processing. The company has consistently emphasized energy reduction and increased refining capacity in its latest insights, reinforcing its commitment to helping mills achieve both economic and environmental goals.
BASF SE, based in Ludwigshafen, Germany, continues to expand its footprint through comprehensive enzyme solutions for deinking, bleaching optimization, and process efficiency, leveraging its Verenium expertise to deliver tailored mill applications. AB Enzymes, also located in Darmstadt, Germany, has focused on its ECOPULP® portfolio, which targets improved drainage, reduced energy consumption, and sustainable processing. Recent product innovations from AB Enzymes have emphasized enhanced runnability and fewer deposits, responding directly to operational pain points in pulp and paper manufacturing. Buckman, headquartered in Memphis, Tennessee, USA, provides enzymatic technologies that include stickies control, enzymatic deinking, and cost reduction solutions, with products like Maximyze® gaining recognition for their practical impact on mill operations. Meanwhile, Enzymatic Deinking Technologies (EDT) in the US specializes in enzyme-based deinking and recycling solutions, helping mills improve fiber quality while cutting energy and chemical consumption.
Recent developments underscore the intensity of competition and the pace of innovation. Novonesis highlighted its FiberCare® solutions in a mid-2025 catalog release, emphasizing refining capacity gains and energy savings in fine paper production. AB Enzymes launched ECOPULP® innovations in late 2024 to boost drainage and runnability. Buckman announced price adjustments across its pulp and paper product lines in Europe, the Middle East, and North Africa, reflecting broader cost pressures that influence enzymatic offerings. Our report evaluates these moves within the context of a market where the top three and top five players collectively hold a substantial share, indicating barriers to entry and the importance of differentiated technology, service networks, and application support.
Industry Dynamics: Regulation, Raw Materials, and Labor Economics
Market growth does not occur in a vacuum; it is shaped by a complex array of external forces that our report examines in detail. Regulatory frameworks are increasingly favoring enzyme-assisted processes. The European Union's BREF document for pulp, paper, and board production explicitly recommends enzyme-assisted bleaching and pulping to minimize dioxin formation and reduce water consumption. In China, stringent environmental enforcement under the Environmental Protection Law and subsequent industrial standards has compelled mills to adopt cleaner technologies, including enzyme pre-treatment, to meet discharge limits and improve overall sustainability metrics. These regulatory tailwinds create a durable demand base for enzymatic solutions, particularly in regions where compliance costs for traditional chemical processes are rising.
Raw material economics also play a pivotal role. Fluctuations in wood pulp prices directly impact mill operating costs and influence the willingness to invest in process optimization. Recent data shows that the net price of bleached hardwood kraft pulp in China experienced a notable decline, altering cost structures and potentially freeing up capital for technology upgrades. At the same time, labor cost trends in major producing regions, such as the elevated unit labor costs recorded in US pulp, paper, and paperboard mills, reinforce the need for automation and efficiency-enhancing solutions. Enzymes can mitigate labor intensity by improving runnability, reducing downtime, and decreasing the need for manual chemical handling. Our analysis integrates these macroeconomic and sector-specific variables to show how they interact with enzyme adoption rates and pricing strategies.
Report Contents and Strategic Utility for 2026 Decision-Making
The Enzyme for Pulp & Paper Market report is structured to deliver immediate operational and strategic value. It includes comprehensive market sizing and forecasting across multiple dimensions, enabling clients to model revenue scenarios and align capacity planning with market realities. The segmentation analysis provides a clear view of which enzyme types and applications are driving growth, helping R&D teams prioritize development efforts and marketing teams target high-potential segments. Competitive profiling goes beyond basic company descriptions, offering insights into product positioning, recent launches, pricing actions, and strategic focus areas.
Additionally, the report explores supply chain dynamics, regulatory impacts, and regional adoption patterns, giving stakeholders a holistic understanding of the market environment. Detailed tables, charts, and qualitative assessments are included to support presentations, investment memos, and internal strategic reviews. By accessing the full report, clients gain the ability to benchmark their position against market leaders, identify partnership opportunities, and anticipate shifts in customer demand. The intelligence is curated to answer the critical questions that keep industry leaders awake at night: where will growth concentrate, which technologies will define the next cycle, and how should we position our offerings to capture value in a consolidating market?
Enzyme for Pulp & Paper Market
Conclusion: Positioning for Sustained Growth
The enzyme for pulp and paper market is poised for continued expansion, underpinned by regulatory support, cost pressures, and a growing recognition of bio-based solutions as enablers of sustainable manufacturing. As we move through 2026 and look toward 2032, the organizations that succeed will be those that base their strategies on accurate, granular market intelligence rather than generalized industry narratives. Our report provides the depth, clarity, and actionable insight required to make those strategic calls with confidence.
To fully leverage the opportunity, stakeholders need access to the complete dataset, including detailed segmentation values, regional revenue breakdowns, competitive market share analysis, and forward-looking scenario modeling. We invite you to visit the source webpage to explore the full Enzyme for Pulp & Paper Market research and secure the comprehensive intelligence needed to navigate the next phase of industry evolution. The future of pulp and paper processing is being rewritten through enzymatic innovation—ensure your strategy is aligned with the trajectory.
For detailed analysis of this topic, please visit the official page: Enzyme for Pulp & Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optical Fiber Fusion Splicer Market to Hit $344.8M by 2032, Growing at 6.0% CAGR
By pmarketresearch, 2026-09-15
Navigating the Fiber Frontier: Strategic Intelligence for the 2026 Optical Fiber Fusion Splicer Market
The global optical fiber fusion splicer market stands at a pivotal inflection point. As network operators accelerate broadband rollouts, hyperscale data centers push beyond conventional density limits, and public infrastructure programs demand resilient connectivity backbones, equipment procurement decisions carry multi-year operational and financial implications. Our latest market research delivers a decision-ready intelligence package designed specifically for executives navigating 2026 capital allocation, product roadmap planning, and competitive positioning.
This briefing outlines why this analysis matters now, what strategic layers it unravels, and how procurement, R&D, and channel leaders can translate its findings into measurable advantage. Rather than cataloguing incremental shipment figures, the study maps structural forces, capability gaps, and procurement inflection points that will define winner-take dynamics through 2032.
The Trajectory: Why 2026 Is a Strategic Anchor Year
Historical demand patterns reveal a market that has consistently expanded rather than fluctuated with short-cycle technology hype. From 2020 through 2025, global revenue progressed steadily, reflecting sustained deployment cycles in telecommunications, institutional networks, and enterprise infrastructure. The base year of 2025 establishes a clear baseline, and the forward projection through 2032 indicates a compound annual growth rate of approximately 6.0 percent, with market size scaling into the mid-300 million USD range by the end of the forecast window.
This trajectory is not merely a function of incremental device replacements. It reflects compounding pressures: fiber-to-the-x expansions in underserved regions, densification of metro and long-haul routes, and the proliferation of high-capacity fiber arrangements within data center campuses. Organizations that treat the splicer market as a static procurement category risk misaligning budget cycles, inventory strategies, and service-level commitments. By anchoring decisions in a 2026-2032 lens, leaders can evaluate total cost of ownership, technology migration timelines, and supplier reliability under realistic deployment velocity rather than point-in-time pricing snapshots.
Optical Fiber Fusion Splicer Market
The research deliberately frames this growth as a structural shift in how connectivity is engineered, maintained, and scaled. Understanding which demand vectors are accelerating, which are plateauing, and where margin compression is likely allows strategy teams to prioritize investments that compound over the forecast horizon rather than chase short-term volume spikes.
What the Report Delivers: A Decision-Ready Intelligence Architecture
This study is built for operational use, not passive reading. It translates market signal into executable insight across four interconnected layers:
- Demand decomposition across technology categories, application environments, and geographic demand clusters, with emphasis on where capacity utilization, deployment complexity, and service intensity differentiate buyer behavior.
- Product architecture and performance signal analysis, covering core alignment versus ribbon and mass fusion workflows, automation maturity, field-ruggedization requirements, and how feature sets map to installation throughput and OPEX reduction.
- Procurement and policy context, including regulatory classification developments, standardization milestones, and public-sector sourcing activity that influence import costs, compliance risk, and government-adjacent demand pipelines.
- Competitive positioning and capability mapping, tracing how leading manufacturers differentiate through device performance, software connectivity, service ecosystems, and channel control.
Each layer is designed to reduce uncertainty in capital planning and product strategy. Procurement teams can benchmark supplier claims against functional reality, engineering leaders can prioritize feature roadmaps that align with high-growth deployment profiles, and partnership teams can identify where channel strength or after-sales support becomes a decisive differentiator in an increasingly fragmented supply base. The analysis intentionally avoids superficial segmentation summaries and instead focuses on the strategic weightings that determine which demand pockets will command pricing resilience, inventory discipline, and long-term supplier loyalty.
Competitive Landscape: Capability, Momentum, and Positioning Signals
The fusion splicer market is characterized by a relatively concentrated top tier alongside a broad field of regional and application-focused players. The five-firm concentration metric underscores that scale, brand recognition, and ecosystem maturity still command meaningful share, yet the remaining competition remains highly active in niche performance categories, ruggedized field tools, and ribbon or high-density fiber workflows.
Fujikura Ltd. continues to anchor its portfolio around core alignment optical fiber fusion splicers, including models built for telecom and enterprise environments, with increasing emphasis on cloud connectivity and low-loss splicing outcomes. Sumitomo Electric Industries, Ltd. reinforces its field and long-haul credibility through high-speed core alignment platforms that integrate GPS support, automatic cleave checking, and maintenance tooling designed to reduce installation variability. INNO Instrument Inc. has strengthened its positioning around rugged ribbon fiber support platforms, leveraging dual-camera architectures to serve data center and high-density deployment contexts where alignment precision and operational durability matter under demanding site conditions.
OFS Fitel, LLC maintains relevance through single-mode fiber splicing solutions embedded in telecom and enterprise networks, while Furukawa Electric Co., Ltd. extends its footprint across telecom carrier workflows and emergency repair scenarios, pairing core alignment capabilities with advanced ribbon and mass splicing functions. AFL Telecommunications LLC operates a complementary strategy by distributing Fujikura-branded platforms, including mass fusion models with intelligent alignment controls and automatic placement correction, enabling high-volume installation programs to benefit from established device performance with localized service reach.
Recent market momentum illustrates how product launches and institutional procurement activity can alter short-term demand visibility. In May 2026, AFL Telecommunications LLC introduced a Fujikura 100R mass fusion platform featuring automatic placement correction, a development that reduces operator intervention and aligns with high-throughput installation environments. Around the same period, the National Institute of Standards and Technology issued a Sources Sought solicitation to identify potential suppliers and vendors for fiber fusion splicer capabilities, signaling that government-adjacent acquisition planning is actively validating supply options for this equipment class.
Beyond product launches, regulatory and standardization developments are reshaping the market's operational backdrop. A U.S. Customs and Border Protection ruling classified a portable optical fiber fusion splicer under a telecommunications equipment tariff classification, a detail that procurement and import-planning teams must factor into landed-cost modeling and sourcing strategy. Separately, Sumitomo Electric Industries, Ltd. received recognition from Japan's Ministry of Economy, Trade and Industry for contributions to IEC and ISO international standards in optical fiber fusion splicing technology, reinforcing how standards leadership can function as a competitive moat in credibility, interoperability, and export-facing trust. These are not isolated news items; they are signals that connectivity equipment buyers must interpret when evaluating risk, compliance, and long-term supplier durability.
Strategic Implications: Where Decision-Makers Should Focus in 2026
The research translates the market's evolution into actionable priorities for three core functions:
- Procurement and supply chain leaders should stress-test supplier commitments against deployment complexity rather than unit price alone. As installation teams encounter higher fiber densities, tighter site constraints, and greater throughput expectations, device reliability, consumables availability, field-service responsiveness, and diagnostic software maturity become decisive cost drivers.
- Product and R&D teams should evaluate where automation, reduced operator intervention, and cloud-connected diagnostics can create defensible differentiation. In markets where installation labor and rework costs dominate total project expense, splicer platforms that minimize human variability can shift the value conversation from hardware price to operational efficiency.
- Commercial and partnership teams should map channel strength, regional service coverage, and standards-aligned credibility into their go-to-market strategy. In categories where purchase decisions are influenced by long-term support expectations and installer familiarity, ecosystem positioning often outweighs incremental feature announcements.
A critical insight is that the market's growth is not evenly distributed across buyer types or deployment contexts. Telecommunications-dominant demand, data center densification, and varied institutional or specialist applications each impose different performance thresholds, purchasing cycles, and service dependencies. Organizations that generalize their strategy across all segments risk diluting resources where competitive pressure is highest and overlooking pockets where technical specificity or service reliability commands premium positioning. The study isolates where differentiation is durable and where price competition is most likely to compress returns.
Why This Research Matters Now
2026 is not simply another forecast year; it is a calibration point where market momentum, product maturity, and procurement policy intersect. Buyers and suppliers alike are being asked to commit to equipment choices, service agreements, and capacity plans under conditions where installation scale, automation expectations, and public-sector sourcing activity are simultaneously evolving. A decision framework built on retrospective headlines or static segmentation will miss the strategic inflection points that determine margin endurance and market share stability.
Our full report extends well beyond this overview. It provides detailed assessments of demand composition, competitive capability mapping, regulatory and procurement watchpoints, and forward-looking deployment signals that help executives separate structural opportunity from transient noise. The objective is not to overwhelm with volume tables, but to equip teams with a clear lens on where to allocate attention, which supplier traits merit weight in sourcing decisions, and how to anticipate the next wave of installation-driven demand.
For leaders responsible for connectivity infrastructure, network expansion, or equipment portfolio strategy, the message is straightforward: the fusion splicer market is advancing along a definable growth path, but the strategic value lies in understanding which drivers will persist, which capabilities will command premium relevance, and where competitive intensity will reshape buyer expectations. This research is designed to convert that understanding into confident 2026 decisions and a stronger footing for the years that follow.
Worldwide Video Splicer Market
For detailed analysis of this topic, please visit the official page: Optical Fiber Fusion Splicer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oscilloscope Market to Reach $344.8M by 2032, Driven by 6.95% CAGR
By pmarketresearch, 2026-09-15
Navigating the Oscilloscope Market: Strategic Intelligence for the 2026 Decision-Maker
Executive Summary: The Pulse of Modern Electronics
As we move deeper into 2026, the landscape of electronic test and measurement is undergoing a transformative shift. The oscilloscope market, once a domain of purely analog signal visualization, has evolved into a complex ecosystem driven by high-speed digitalization, automotive electrification, and advanced telecommunications infrastructure. For industry leaders, investors, and strategic planners, understanding the trajectory of this market is not merely an academic exercise—it is a critical component of supply chain optimization, R&D allocation, and competitive positioning.
Our latest market research, the Oscilloscope Market Report 2026-2032, is designed to provide the granular intelligence necessary to navigate this complexity. This article serves as an introduction to the strategic value embedded within the report, highlighting key macroeconomic trends, competitive dynamics, and the technological forces shaping revenue projections through the end of the decade.
Dermatoscope Market
Market Trajectory: Growth Vectors and Macro Dynamics
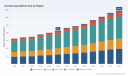
The overarching narrative of the oscilloscope market during the forecast period is one of steady, resilient expansion. Based on historical data ranging from 2020 to 2025, the market has demonstrated consistent upward momentum, recovering from earlier disruptions and capitalizing on robust industrial demand. Our analysis projects this trajectory to continue through 2032, underpinned by a Compound Annual Growth Rate (CAGR) of 6.95%.
To contextualize this growth, consider the revenue progression over the recent past. In 2020, the market valuation stood at 163.15 Million USD. By 2025, this figure had climbed to 215.0 Million USD. This historical baseline establishes a solid foundation for the forecast period, where revenues are expected to breach the 300 Million USD mark by 2030, reaching 344.8 Million USD in 2032.
- Historical Context (2020-2025): The market grew from 163.15 Million USD to 215.0 Million USD.
- Forecast Horizon (2026-2032): Growth is projected to accelerate, moving from 232.32 Million USD in 2026 to 344.8 Million USD in 2032.
- Strategic Implication: The 6.95% CAGR indicates that while the market is mature, it is not stagnant. Growth is being driven by higher-value segments and technological upgrades rather than simple volume expansion.
These numbers represent more than just aggregate revenue; they reflect a shift in how engineering organizations allocate capital toward test equipment. The data suggests that as systems become more complex, the reliance on precision measurement tools becomes non-negotiable, securing long-term demand even amidst fluctuating macroeconomic conditions.
Oscilloscope Market
Competitive Landscape: Concentration and Innovation
One of the most defining characteristics of the oscilloscope market is the significant degree of consolidation among top-tier vendors. Our analysis indicates that the top five companies command a market concentration of 88.7%, while the top three hold a share of 72.3%. This high level of concentration suggests that barriers to entry remain substantial, particularly in the high-performance segments where reliability and bandwidth are critical procurement criteria.
However, within this concentrated landscape, there is vigorous competition driven by distinct technological niches. The role of key players such as Keysight Technologies, Tektronix, and Rohde & Schwarz remains pivotal. These firms are not merely competing on price; they are engaged in a race to deploy advanced analysis capabilities. For instance, the integration of AI-assisted analysis and high-speed digital capabilities is becoming a standard expectation for enterprise-grade instruments.
- High-Performance Dominance: Leaders like Keysight and Tektronix continue to push the envelope in high-speed digital and compliance testing, recently introducing platforms like the Infiniium XR8 and the 2 Series MSO to streamline bench-to-field workflows.
- Specialized Applications: Companies such as Teledyne LeCroy and Yokogawa focus on signal integrity and industrial precision, respectively, catering to niche but high-value engineering requirements.
- Accessibility and Expansion: Vendors from China, such as Siglent and Rigol, are carving out significant presence in entry-level and mid-range segments, offering high-resolution options that democratize access to advanced testing features.
- Portability Trends: The rise of USB-based and PC-integrated solutions, exemplified by companies like Pico Technology, reflects the market's demand for flexible, portable signal capture in field environments.
Understanding the nuances of these competitive moves is essential for procurement strategists. Knowing which vendor is excelling in specific bandwidths or form factors can dictate partnership opportunities and supply chain resilience. The full report details the specific strategic moves, product launches, and regional shifts of these key companies, providing a map of where market power is consolidating and where opportunities for disruption may lie.
Segmentation Nuances: Form Factors, Bandwidth, and Industry Verticals
While the aggregate market size provides a high-level view, the true strategic intelligence lies in understanding how demand is distributed across different segments. The market is fragmented by technology type, usage environment, and end-user industry. Our research dives deep into these splits to reveal where the highest growth potentials reside.
Form Factor Evolution
The choice between benchtop, portable, and PC-based oscilloscopes is increasingly dictated by the workflow of the engineering team. Benchtop units remain a staple for fixed lab environments, but the demand for portable and PC-based solutions is rising as testing moves closer to the production line and into the field. The interplay between these form factors influences inventory strategies and capital expenditure planning for manufacturing firms.
Bandwidth Requirements as a Proxy for Complexity
Bandwidth segmentation serves as a key indicator of the complexity of devices being tested. From low-bandwidth entry-level tools under 500 MHz to high-frequency instruments exceeding 4 GHz, the demand curve shifts based on the industry served. High-bandwidth instruments are critical for 5G infrastructure and high-speed digital computing, while lower bandwidths suffice for basic industrial maintenance and educational purposes.
- Low to Mid-Bandwidth: Segments below 500 MHz and between 500 MHz to 1 GHz represent substantial volumes, driven by general electronics and IT hardware.
- High-Bandwidth: The 1 GHz to 4 GHz and above 4 GHz segments represent specialized, high-value opportunities tied to aerospace, defense, and cutting-edge telecommunications.
Our report quantifies these preferences, helping stakeholders identify which bandwidth categories offer the best return on investment for specific product development cycles.
Industry Vertical Drivers
Demand is not uniform across industries. Automotive and Transportation, IT and Telecommunications, and Consumer Electronics are primary growth engines. However, the specific needs of Aerospace and Defense versus Medical and Life Sciences create distinct purchasing behaviors and technical specifications. For example, the electrification of vehicles requires robust testing protocols that differ significantly from those used in consumer gadget development. By isolating these vertical-specific drivers, companies can tailor their go-to-market strategies more effectively.
Regional Dynamics and Global Supply Chains
Geographically, the market exhibits varied growth patterns influenced by local manufacturing hubs, R&D centers, and regulatory environments. While North America and Europe maintain strong positions due to established industrial bases and high R&D spending, the Asia Pacific region represents a massive volume driver fueled by manufacturing activity and emerging tech adoption.
- North America: A hub for high-performance innovation and key vendor headquarters.
- Europe: Strong presence in automotive testing and industrial engineering sectors.
- Asia Pacific: Rapid expansion driven by electronics manufacturing and infrastructure development.
- Emerging Markets: Latin America and the Middle East/Africa present niche opportunities as industrial sectors in these regions modernize.
Supply chain resilience is a critical concern in 2026. Understanding regional dependencies helps organizations mitigate risks associated with logistics disruptions or localized regulatory changes. The report provides a detailed breakdown of regional revenue contributions, allowing firms to assess exposure and opportunity in each geography without relying on generalized assumptions.
Strategic Value for 2026 Decision-Makers
In an era where data is abundant but insight is scarce, the Oscilloscope Market Report 2026-2032 offers more than just statistics. It provides a framework for decision-making.
Investment and R&D Allocation
For product managers and R&D leaders, understanding which bandwidth categories and form factors are gaining traction allows for optimized resource allocation. Investing in test equipment that aligns with future market demand ensures that development cycles are not bottlenecked by inadequate measurement capabilities.
Competitive Positioning
Sales directors and business development teams can leverage the competitive landscape analysis to identify gaps in the market. Whether it is an underserved segment in a specific region or a technological feature that competitors have not yet standardized, the report highlights where strategic positioning can yield maximum impact.
Procurement and Supply Chain
Procurement officers benefit from the visibility into vendor concentration and regional supply dynamics. Knowing the market share distribution among top vendors aids in negotiation strategies and risk management, ensuring that critical testing hardware is sourced from stable and reliable partners.
Conclusion: Accessing the Full Intelligence
The oscilloscope market in 2026 is at a crossroads of technological innovation and steady economic growth. With a projected CAGR of 6.95% and revenues heading toward 344.8 Million USD by 2032, the sector offers substantial opportunities for those equipped with the right intelligence. However, surface-level data is insufficient for navigating the nuances of segment-specific growth, vendor capabilities, and regional shifts.
This article has outlined the macro trends and competitive framework defining the industry. Yet, the specific percentages, detailed segmentation splits, and comprehensive vendor profiles contained within the full Oscilloscope Market Report provide the actionable granularity required to turn strategy into execution. To make informed decisions that secure your organization's position in the test and measurement landscape, access to the complete dataset is essential.
We invite you to explore the full report to unlock the detailed insights needed to drive your strategic initiatives forward through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Oscilloscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Toilet Tank Fittings Market to Hit $9.7B by 2032 at 7.5% CAGR
By pmarketresearch, 2026-09-15
Navigating the Toilet Tank Fittings Market: Strategic Intelligence for 2026 Decision-Making
The global plumbing fixtures sector stands at a critical inflection point. As infrastructure modernization accelerates and regulatory frameworks tighten around water efficiency, the toilet tank fittings market has emerged as a vital, yet often overlooked, component of the broader sanitation ecosystem. Our latest comprehensive market research provides a detailed examination of this space, offering actionable intelligence designed to support strategic planning throughout the 2026-to-2032 forecast horizon. This report is not merely a retrospective data compilation; it is a forward-looking strategic tool built to help manufacturers, distributors, investors, and procurement leaders navigate market complexity with precision.
The Macro Trajectory: Sustained Growth Anchored in Infrastructure and Efficiency Mandates
Over the historical analysis window spanning 2020 through 2025, the global toilet tank fittings market demonstrated consistent expansion, climbing from approximately 4,200 million USD in 2020 to a valuation of roughly 5,900 million USD by 2025. This upward trajectory reflects robust demand across residential renovations, commercial construction cycles, and the ongoing replacement of aging plumbing infrastructure. Looking ahead, our forecast period covering 2026 through 2032 projects continued momentum, with the market expected to reach approximately 6,181.95 million USD in 2026 and advance steadily toward a 9,700 million USD valuation by 2032. The implied compound annual growth rate of 7.5 percent underscores a resilient market structure supported by replacement-driven demand, sustainable building practices, and evolving municipal water standards.
For executive teams planning capital allocation, product roadmaps, or channel expansion, understanding the pacing of this growth is essential. The market does not experience sudden volatility; rather, it follows a measured, regulation-influenced expansion curve. Stakeholders who align their strategic timelines with this cadence will be better positioned to capture incremental share, optimize inventory positioning, and anticipate shifts in procurement behavior across downstream segments.
What the Report Delivers: Operational Depth Beyond Headline Metrics
A market study earns its executive shelf space only when it translates macro trends into operational guidance. Our research is structured to serve as a practical reference for cross-functional decision-making. The report is organized around several core analytical pillars, each designed to answer the questions that management teams face when allocating resources or evaluating competitive positioning.
Comprehensive Market Sizing and Forecast Modeling
The foundation of the analysis rests on a rigorously constructed revenue model that tracks historical performance and projects forward-looking demand scenarios. Rather than presenting a single-point estimate, the forecast framework accounts for multiple driving variables, including construction activity, renovation cycles, regulatory adoption timelines, and material cost fluctuations. Readers will find a transparent breakdown of the assumptions underpinning each projection phase, allowing leadership teams to stress-test scenarios against their own internal forecasts.
Segment-Level Structural Analysis
The market is inherently diversified, shaped by product architectures, end-use environments, and regional procurement patterns. Our segmentation framework maps these dimensions in detail, offering clarity on where volume concentrates, how value flows across product categories, and which application environments generate the strongest replacement and upgrade signals. This layered approach helps stakeholders identify high-priority segments for product development, sales targeting, and distribution optimization without relying on generalized industry assumptions.
Competitive Landscape and Firm-Level Intelligence
Market share dynamics in this space are shaped by a mix of specialized component manufacturers and broader plumbing solution providers. The report profiles leading participants, examining their product portfolios, geographic footprints, repair-and-maintenance positioning, and strategic responses to evolving building standards. Company-level insights are paired with a qualitative assessment of market concentration, giving readers a structured view of how incumbents defend share, where white space exists, and which competitive moves are most likely to reshape procurement preferences in the coming years.
Regulatory, Pricing, and Input-Cost Dynamics
Few plumbing-adjacent markets are as sensitive to policy shifts and input-cost pressure as toilet tank fittings. Regulatory programs that mandate high-performance, low-flow fittings directly influence product design requirements and replacement demand. At the same time, material and energy cost movements affect pricing strategies, margin management, and supplier negotiations. The report integrates these forces into a coherent dynamics section, helping readers anticipate how compliance mandates and cost pressures will interact with demand patterns and competitive pricing behavior.
Competitive Dynamics: Positioning Among Leading Manufacturers
The competitive environment in the toilet tank fittings market is defined by firms that balance broad compatibility, component reliability, and increasing emphasis on concealed and integrated flushing solutions. Several key companies anchor the landscape, each with distinct strategic identities and market approaches.
Fluidmaster, headquartered in Vista, California, has built recognition around universal toilet tank fill valves, flappers, and complete repair kits designed for both residential and commercial applications. Its product philosophy emphasizes compatibility and ease of replacement, which positions the company strongly in the aftermarket and maintenance segment. Korky, based in Wisconsin, pursues a similar universal-repair strategy but has also cultivated a strong identity around domestically manufactured components, including fill valves, flush valves, and flappers. Danco extends this universal-application theme with repair kits and hardware intended to span multiple brands, broadening its addressable maintenance audience. Geberit, rooted in Jona, Switzerland, represents a more system-oriented approach. Its portfolio covers concealed tank systems, flushing mechanisms, and replacement parts, aligning with projects that prioritize integrated design, concealed installations, and commercial-grade reliability.
Competitive strategy in this market is not solely about unit volume; it also revolves around catalog breadth, parts availability, service responsiveness, and the ability to align products with evolving code requirements. The report examines how these companies navigate the tension between standardization and specification-driven demand, particularly in commercial and hospitality environments where replacement cycles and procurement standards differ meaningfully from residential channels.
Toilet Tank Fittings Market
Recent Strategic Movements Shaping the Landscape
Market leadership is also revealed through operational decisions. In January 2026, Geberit North America released an updated product and parts catalog featuring revised concealed tank systems and replacement flushing components. Catalog refreshes of this nature signal continued investment in component availability and compatibility coverage, which directly affect specification choices and maintenance procurement. Later in the year, in June 2026, the company implemented a 2 percent price adjustment on plastic piping and select products, a move intended to offset rising energy and plastics costs. Pricing actions like this illustrate how manufacturers are managing input-cost pressure while balancing channel relationships and end-user expectations.
These developments are not isolated events. They reflect broader industry themes that the report explores in greater depth: the growing importance of updated parts portfolios, the sensitivity of pricing to material and energy markets, and the strategic need to maintain specification relevance as building standards become more stringent.
Regulatory and Environmental Forces Reshaping Demand
A defining feature of the toilet tank fittings market is the extent to which demand is shaped by water-efficiency policy. Regulation does not merely constrain product design; it actively redirects replacement cycles, influences specification decisions, and alters the mix of fittings required across different environments.
The EPA WaterSense program continues to reinforce expectations for high-performance, low-flow fittings in tank-type toilets, with maximum full flush volumes set at 1.6 gallons per flush. Compliance with such standards encourages the adoption of fittings that support effective bowl clearance while maintaining lower water usage, which in turn influences valve design, flapper performance, and fill control mechanisms. At a state level, standards such as California Title 20 impose additional parameters, requiring tank-type dual-flush toilets manufactured on or after January 1, 2025 to limit full flush volumes to 1.28 gallons per flush. These regional requirements illustrate how local policy can accelerate demand for upgraded components and push manufacturers to calibrate product lines for stricter performance thresholds.
For market participants, the strategic implication is clear: regulatory momentum creates both compliance necessity and commercial opportunity. Replacement programs in older installations, specification updates in commercial projects, and the continued rollout of water-efficient building standards all contribute to a sustained need for reliable, code-compatible fittings. The report connects these regulatory threads to segment-level demand outcomes, helping readers understand where mandate-driven replacement activity is most likely to concentrate.
Pipe Fittings Market
Strategic Implications for 2026 and the Forecast Horizon
As organizations move through 2026, several strategic priorities will separate reactive operators from proactive market participants. The report translates its findings into practical implication areas that management teams can use to guide planning across product, sales, procurement, and market-entry decisions.
Portfolio Alignment and Specification Relevance
With water-efficiency expectations continuing to rise, product portfolios must be evaluated not only for current compatibility but also for forward compliance. Companies that maintain strong coverage across fill valves, flush valves, flappers, and integrated replacement kits are better equipped to serve both maintenance-driven demand and specification-driven projects. The analysis highlights the importance of aligning product assortments with the regulatory thresholds most likely to influence purchasing decisions in key end-use environments.
Pricing, Margin, and Input-Cost Strategy
Recent pricing adjustments in the broader plumbing supply chain underscore the need for disciplined cost management. While market growth remains steady, margin performance can be influenced by plastics pricing, energy costs, and logistics pressure. The report contextualizes these forces within the broader market trajectory, helping leaders assess where pricing flexibility exists, how cost changes may be passed through, and what safeguards are necessary to protect profitability during periods of input-cost volatility.
Channel Focus and End-Use Targeting
Demand does not distribute evenly across residential, hospitality, and commercial building environments. Each channel presents distinct replacement cycles, specification processes, and purchasing behaviors. By mapping these differences, the research supports more targeted channel strategies, helping teams prioritize the environments where product availability, brand recognition, and service responsiveness deliver the greatest return. Rather than treating the market as a single monolithic segment, the report encourages a channel-aware approach to resource allocation.
Anticipating Competitive Shifts
The competitive structure of the market suggests that share gains are often won through service reliability, parts availability, and specification alignment rather than through price alone. Market concentration dynamics indicate a landscape where leading players hold meaningful influence, yet there remains room for differentiated positioning in repair kits, universal components, and concealed system offerings. Understanding where competitive pressure is intensifying, and where customer preferences are shifting, enables firms to make more informed decisions about product investment, geographic focus, and partnership strategy.
Why This Research Supports Better Decisions in 2026
Good market intelligence does more than describe the present; it helps organizations prepare for the next phase of competitive and regulatory change. This report is designed with that objective in mind. It combines macro market sizing, segment-level structural analysis, company profiles, regulatory context, and recent industry developments into a cohesive reference that executives, product planners, and commercial leaders can use throughout the year.
The audience for this research is deliberately broad but equally precise in its utility. Manufacturers can use the findings to evaluate portfolio priorities and specification readiness. Distributors and retailers can assess demand concentration and channel alignment. Investors and strategy teams can interpret growth pacing, competitive structure, and regulatory tailwinds when evaluating market exposure. Procurement leaders can better anticipate pricing dynamics and replacement demand patterns.
The complete research document provides the full depth required to support detailed planning: expanded forecast detail, segment comparisons, competitive profiles, regulatory impact assessment, and scenario-friendly modeling assumptions. It is structured so that decision-makers can move quickly from high-level insight to operational action without relying on fragmented sources or incomplete market summaries.
Next Steps: Access the Full Intelligence
The macro direction of the toilet tank fittings market is clear, but the strategic value lies in the details: where demand is building, how regulatory standards are reshaping component requirements, which competitive moves are redefining availability and pricing, and how organizations can position themselves for the 2026-to-2032 period with confidence. To make those decisions with precision, leaders need the complete dataset, segment mapping, and competitive analysis that this report provides.
We invite executives, product leaders, and commercial strategists to access the full version of the market research for a comprehensive view of the market landscape. The complete report extends far beyond the summary trends presented here, offering the structured intelligence necessary to support product planning, channel strategy, competitive positioning, and investment decisions in a market defined by steady growth, regulatory influence, and evolving component standards. In a sector where timing, compliance readiness, and portfolio relevance determine outcomes, the right intelligence is not optional; it is a strategic asset.
For detailed analysis of this topic, please visit the official page: Toilet Tank Fittings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Etch Equipment Market Reaches $25.13 Billion in 2025, Projects 7.61% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Semiconductor Etch Equipment Market: A 2026 Outlook
The semiconductor manufacturing landscape is entering a decisive phase where equipment capability defines technological leadership. As node sizes shrink and 3D architectures become the standard, the etch process stands as a critical bottleneck and enabler. For executives and investors navigating the 2026 fiscal year, understanding the trajectory of the Semiconductor Etch Equipment Market is not merely an operational concern but a strategic imperative. PW Consulting presents a comprehensive analysis designed to illuminate the path forward, offering clarity amidst volatile demand cycles and tightening regulatory frameworks.
The market has demonstrated remarkable resilience and growth over the past half-decade, evolving from a recovery phase into a sustained expansion period. According to our latest research, the overall market size is projected to reach new heights as we move through the decade. Starting from a base of approximately 25.13 billion USD in 2025, the trajectory indicates a steady climb toward nearly 42 billion USD by 2032. This growth is underpinned by a compound annual growth rate that reflects robust demand across high-performance computing and memory sectors. Such figures represent more than just revenue; they signal a fundamental shift in capital expenditure priorities as manufacturers race to secure supply chain sovereignty and technological edge.
Our report serves as a navigational tool for these complex waters. It dissects the market mechanics without fluff, providing actionable intelligence for strategic planning. Below, we offer a preview of the analytical depth contained within the full study, highlighting why this intelligence is essential for organizational decision-making in 2026.
Market Dynamics and Growth Trajectories
The current valuation of the sector reflects a compound effect of technological adoption and geographic shifts in manufacturing capacity. The progression from 2020 to 2025 shows a clear upward trend, with revenue expanding from 16.0 billion USD to over 25 billion USD. This historical context validates the investment thesis for etch technology but also raises questions about sustainability and concentration risks. The forecast period extending to 2032 suggests that this momentum is not accidental. It is driven by the intensifying requirements for atomic-scale precision in conductor and dielectric processes.
While the aggregate numbers are impressive, the true value for decision-makers lies in understanding the drivers behind the growth. The full report details the segmentation across equipment types, distinguishing between the dominance of dry etch solutions versus wet etch applications. It explores the process-specific demands, analyzing how conductor etch and dielectric etch segments are diverging in terms of growth velocity and technological complexity. Furthermore, the application landscape is scrutinized, revealing how logic chips and memory chips are contributing differently to the revenue pool. Each segment presents unique risk profiles and opportunity sets that require tailored strategic approaches.
Access to the granular data behind these segments is crucial. Organizations need to know not just that the market is growing, but where the growth is concentrated and which technologies are capturing the premium value. The complete analysis provides the necessary breakdown to inform capacity planning, R&D allocation, and partnership strategies without relying on generalized industry assumptions.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a high degree of concentration, where a select few players command the majority of revenue share. Our analysis indicates that the top three companies hold a significant portion of the market, while the top five consolidate even greater dominance. This oligopolistic structure creates a high barrier to entry for newcomers and forces established players to constantly innovate to maintain margins. For stakeholders, this concentration implies that competitor moves must be monitored with extreme precision.
Several key enterprises define the current competitive arena. Applied Materials and Lam Research Corporation remain pivotal forces, each leveraging distinct technological advantages. Tokyo Electron Limited continues to expand its manufacturing footprint to meet demand, while Hitachi High-Tech Corporation and Oxford Instruments plc offer specialized solutions for niche but critical applications. ASML Holding N.V., though often associated with lithography, plays an intertwined role in the broader equipment ecosystem. Other significant contributors include ULVAC, Inc., NAURA Technology Group Co., Ltd., SPTS Technologies Ltd, Plasma-Therm LLC, and SAMCO Inc., each carving out positions based on specific regional strengths or technological niches.
Semiconductor Etch Equipment Market
Recent developments among these key players offer a window into future strategies. Lam Research Corporation, for instance, has been aggressive in both product innovation and ecosystem building. In early 2025, they launched the Akara conductor etch tool, emphasizing atomic-scale precision via DirectDrive plasma control technology. This was followed by a donation of leading-edge multi-chamber etch systems to UC Berkeley for advanced R&D, signaling a commitment to securing the talent pipeline and validating technology in academic settings. Later in the year, collaborations focused on dry resist technology further underscore the industry's shift toward atomic layer etching and deposition.
Tokyo Electron Limited responded to capacity pressures with a facility expansion announcement in Miyagi, aimed at boosting plasma etch systems manufacturing. Meanwhile, Oxford Instruments plc made strides into adjacent emerging sectors, supplying atomic layer etch systems for quantum device fabrication. These moves are not isolated; they are strategic bets on where the next wave of demand will originate beyond traditional logic and memory nodes. Our report analyzes these movements to help clients anticipate competitor capacity expansions and technology pivots.
Regulatory Environment and Geopolitical Risks
No analysis of the semiconductor equipment market in 2026 is complete without a rigorous assessment of the regulatory landscape. The industry is operating under a cloud of evolving export controls and bipartisan legislative actions that directly impact equipment deployment and supply chain logistics. The dynamic nature of these regulations means that compliance is not a one-time checklist but a continuous strategic variable.
Recent actions by the U.S. Department of Commerce Bureau of Industry and Security have tightened constraints significantly. In December 2024, new rules were implemented affecting advanced packaging semiconductor manufacturing equipment, including specific etch tools. This was accompanied by expansions to the foreign direct product rule, extending jurisdiction over foreign-produced equipment destined for certain regions. Additionally, numerous entities were added to the Entity List, and specific types of equipment were added to the Commerce Control List. These measures fundamentally alter the accessible market for major players and require careful navigation for any international supply chain.
Furthermore, legislative moves such as the Bipartisan MATCH Act introduced in April 2026 propose prohibitions on the sale of cryogenic etch tools and deep ultraviolet immersion lithography systems to countries of concern. These regulations create a bifurcated market scenario where technology access is determined by geopolitical alignment rather than purely economic factors. Our report integrates these regulatory variables into the market forecast, helping clients understand the potential impact on revenue streams and market entry strategies in restricted regions. Understanding the nuance of these controls is vital for avoiding compliance pitfalls while optimizing global footprint allocation.
The Strategic Value of Comprehensive Intelligence
In a market defined by high concentration, rapid technological shifts, and stringent regulations, surface-level data is insufficient for robust decision-making. The full PW Consulting report on the Semiconductor Etch Equipment Market goes beyond high-level summaries to provide the depth required for executive strategy. It connects the dots between revenue trends, competitive maneuvers, and regulatory constraints to paint a holistic picture of the operating environment.
The report details the segmentation splits that drive revenue, offering clarity on where capital is flowing. It examines the regional distribution of market value, highlighting the disparities between mature markets and high-growth regions without oversimplifying the complexities of local demand drivers. It provides a thorough examination of the production and consumption dynamics that define the supply-demand equilibrium.
Access to this level of detail allows organizations to:
- Validate internal projections against independent market data.
- Identify potential gaps in product portfolios relative to market demand.
- Assess the risk exposure associated with regulatory changes in key regions.
- Benchmark competitor activities to refine go-to-market strategies.
- Pinpoint emerging opportunities in specialized etch applications beyond standard CMOS manufacturing.
The semiconductor industry rewards those who can anticipate change before it becomes obvious. By leveraging our detailed segmentation data—covering types, processes, applications, and regions—clients can move from reactive planning to proactive strategy. The report includes profiles and strategies for the key companies mentioned, analyzing how their recent developments align with broader market trends. This competitor intelligence is crucial for understanding who is gaining share, who is investing in which technologies, and where the next competitive threats may emerge.
Plasma Etch System Market
Moreover, the analysis considers the macroeconomic context, including the currency valuation and revenue units that frame the financial expectations. The forecast period through 2032 provides a long-term horizon for ROI calculations, allowing stakeholders to justify capital expenditures in equipment development or acquisition. The distinction between dry and wet etch equipment, for example, is not just a technical classification but a financial indicator of where the industry is placing its bets for the next decade. Similarly, the split between conductor and dielectric processes reveals the relative intensity of backend versus frontend manufacturing investments.
Conclusion: Navigating the Next Phase
The Semiconductor Etch Equipment Market is at a crossroads where technological capability and geopolitical reality intersect. The growth trajectory is clear, but the path to capturing value is fraught with complexity. Companies must balance the drive for innovation with the constraints of international regulation. They must watch the few dominant players while keeping an eye on specialists who may disrupt specific segments. They must allocate resources across logic and memory applications without knowing exactly which node will define the next cycle.
PW Consulting's full market research report is designed to equip leadership teams with the intelligence needed to make these judgments with confidence. We invite you to access the complete study to unlock the specific data points, regional breakdowns, and strategic recommendations that will inform your 2026 planning. Do not rely on assumptions when the stakes involve billions in capital and the future of technological sovereignty.
For detailed segmentation data, comprehensive competitor profiles, and in-depth regulatory impact analysis, please visit our dedicated market research portal. The complete intelligence package offers the granularity required to turn market insights into competitive advantage.
For detailed analysis of this topic, please visit the official page: Semiconductor Etch Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Mascara Market Hits $7.5B in 2025, Poised for 6.09% CAGR Growth Through 2032
By pmarketresearch, 2026-09-15
Global Mascara Market 2026: Strategic Intelligence for Competitive Advantage
Setting the Stage: Why This Research Matters Now
The global cosmetics industry is entering a decisive growth cycle, and mascara remains at the center of category innovation. As consumer expectations around wear performance, ingredient transparency, and sustainability continue to reshape purchasing behavior, brands and manufacturers must act on evidence rather than intuition. The latest PW Consulting Mascara Market study delivers exactly that foundation. Covering historical data from 2020 through 2025 with a forward-looking forecast extending to 2032, our analysis is built to help leadership teams evaluate where to invest, how to position portfolios, and which competitive pressures will define the next several years of category development.
The market has already demonstrated steady expansion across the past half-decade, reaching an estimated valuation of 7.5 billion US dollars in 2025. Growth momentum is projected to continue into the forecast window, with the category advancing toward a compound annual growth rate of 6.09 percent between 2026 and 2032. By the terminal year of our modeling horizon, total market value is expected to exceed 11 billion dollars. These are not abstract numbers; they reflect the combined impact of innovation cycles, formulation differentiation, retail infrastructure shifts, and evolving demand patterns in both mainstream and prestige channels. For decision-makers, the central question is no longer whether the category is growing, but which structural forces will determine who captures disproportionate share within it.
This article previews the strategic architecture of our full report. It outlines the business questions the research is designed to answer, describes the operational content included inside the study, and situates the most recent industry developments into a defensible competitive context. Core segment splits, detailed regional breakdowns, and company-specific revenue figures are intentionally held back. That architecture is deliberate: the complete intelligence is structured for use in board-level planning, portfolio reviews, and market-entry assessments, and it belongs in your hands where it can be applied with precision.
The Strategic Value of Data-Backed Forecasting for 2026 Decisions
A market study becomes strategically useful when it converts numerical trends into decision-ready intelligence. For 2026, executives face a particularly crowded field of competing priorities: formulation innovation must be balanced against cost discipline, distribution strategies must align with channel consolidation and digital-led purchase journeys, and sustainability commitments must be translated into credible product narratives that withstand scrutiny. In that environment, high-level growth statements offer little direction. What matters is how the growth breaks down across use cases, format categories, regional demand intensity, and competitive positioning.
The PW Consulting research is built around that requirement. Rather than presenting a single aggregate projection, the analysis is organized to help teams evaluate the category from multiple business angles at once. Readers can examine how different usage occasions contribute to total category pull, assess which product characteristics are most closely associated with repeat purchase behavior, and compare regional market size with structural demand signals. That multi-layered approach is essential because mascara is not a monolithic category. Daily wear routines, event-driven application, and professional makeup contexts each generate distinct purchasing logic, and the relative weight of those contexts shapes everything from SKU architecture to marketing investment.
Equally important, the forecast period is structured to support operational planning. A six-year outlook enables supply chain teams to test capacity assumptions, finance departments to build scenarios around revenue ramps, and product organizations to sequence innovation pipelines with realistic timing. Instead of relying on short-term snapshots, leadership gets a view of how the category is likely to scale and where acceleration or deceleration may occur as competitive intensity and consumer preference evolve.
What the Study Delivers: Operational Content for Real-World Planning
The report is designed for immediate application. It moves beyond high-level commentary to provide content that marketing leaders, product developers, procurement professionals, and strategic planners can use directly in day-to-day decision-making. Among the practical components included are:
Mascara Market
Lipstick Market
- A historical reconstruction of market movement from 2020 to 2025, allowing teams to test how past disruptions, channel shifts, and product launches influenced category performance.
- A forward forecast through 2032 that supports scenario planning for capacity, investment timing, and portfolio prioritization.
- Detailed segmentation across product types, usage occasions, and geographic demand patterns so that strategy teams can identify where specialized formulations and targeted messaging create the strongest commercial logic.
- Competitive analysis covering the major global players and specialized manufacturers shaping supply, innovation, and private-label capability.
- Recent industry developments, including trade show launches and materials innovation, placed in context to show how product and packaging advances are influencing the competitive field.
The segmentation framework is especially valuable for organizations deciding how to allocate limited resources. When companies can see how distinct product attributes relate to overall market structure, they are better positioned to prioritize claims development, packaging choices, and brand differentiation. In practice, that means fewer assumptions about where category growth is concentrated and more confidence in which product narratives deserve shelf space, promotional support, and R&D investment.
Competitive Dynamics in a Concentrated Market
Planning in the mascara category requires an honest assessment of competitive concentration. The market remains led by a small group of large multinational companies, with the top three firms together accounting for a substantial share of category revenue and the top five firms holding an even larger collective position. That structure shapes pricing power, innovation cadence, and channel influence. Large players benefit from broad brand portfolios, established distribution relationships, and the ability to scale successful formulas across multiple consumer tiers. At the same time, the presence of specialized manufacturers, private-label suppliers, and regional leaders creates meaningful opportunities for partners and challengers who can execute with focus.
Several global names define the competitive core. L'Oréal operates across mass and prestige with a wide portfolio that spans accessible and premium performance claims. The Estée Lauder Companies competes in the higher-end space through brands known for advanced wear, curl retention, and premium application experience. Procter & Gamble maintains a strong mass-market footprint with products built around affordable volume and lengthening performance. Coty Inc. continues to play a significant role in color cosmetics with long-wear and waterproof positioning. Shiseido extends the competitive field in Asia with high-precision formulas and conditioning-focused benefits, while Chanel anchors prestige demand with luxury brush design and long-lasting pigmentation. Amorepacific remains closely aligned with K-beauty preferences, particularly around curling and lengthening effects.
Beneath the brand owners, the supplier and contract manufacturing layer is equally important. Schwan Cosmetics specializes in high-volume private-label production with broad texture options and full-service manufacturing capability. Geka GmbH supplies sustainable brush and packaging solutions, including materials using post-consumer recycled content with low-emission decoration processes. HCP Packaging has introduced renewable applicator technologies aimed at reducing dependence on conventional synthetic materials. In the contract and export segment, Homax Cosmetics, Columbia Cosmetics, Xiran Cosmetics, and Aurora Global Brands each support different combinations of budget and premium positioning, private-label customization, and international distribution. Together, this ecosystem determines how quickly new formulas can reach market, how much differentiation can be achieved through applicator and packaging design, and where cost efficiencies are possible without sacrificing product quality.
Latest Developments Shaping Competitive Positioning
Recent activity in materials, packaging, and sustainability commitments is already influencing the category's next competitive cycle. At the trade-show level, Geka GmbH introduced a music-inspired mascara brush collection with updated brush designs and shadow printing on fully post-consumer recycled packaging. Alongside that launch, HCP Packaging presented a cellulose-derived renewable fiber applicator technology developed as an alternative to traditional synthetic materials. These developments are not isolated design exercises; they reflect broader pressure on manufacturers and brands to reduce environmental footprint while preserving application performance and shelf appeal. In that context, packaging and applicator innovation are becoming part of the product proposition itself, not just a logistics consideration.
Sustainability is also entering the formulation conversation more directly. One of the largest multinational players has expanded its long-term sustainability program with a commitment to make its mascara formulations biodegradable or naturally derived by 2030. That kind of public target changes expectations across the supply chain. It raises the bar for ingredient sourcing, encourages supplier partnerships around material innovation, and increases the importance of credible claims language. For competitors and partners alike, it signals that environmental performance is moving from a marketing overlay to a core development requirement.
For industry participants, these shifts create both risk and opportunity. Companies that can integrate performance, sustainability, and application experience into a coherent package will be better positioned to justify premium positioning and consumer loyalty. Those that rely solely on legacy formulas or conventional materials may find it harder to defend differentiation as buyer expectations and regulatory attention continue to increase.
How to Use This Research for Strategic Planning
The report is most valuable when treated as a working document for cross-functional planning. Product teams can use it to evaluate where formulation innovation is likely to generate the strongest return and how to sequence development relative to category demand. Commercial leaders can use it to refine channel and geographic priorities without relying on guesswork about where demand depth is greatest. Procurement and operations teams can use the forecast structure to align capacity and sourcing decisions with a realistic growth path. And corporate strategy groups can use the competitive overview to assess partnership opportunities, private-label dynamics, and the positioning of challenger brands against established leaders.
This preview is intended to demonstrate the scope and rigor of the full study, not to replace it. The market framework, segmentation architecture, company profiles, and competitive developments are built to support precise decisions in a category where small differences in product performance, packaging credibility, and usage positioning can translate into meaningful share movement over time. The full report provides the underlying figures, segmentation detail, and scenario context needed to move from directional insight to actionable planning.
For organizations preparing for 2026 and beyond, the strategic imperative is clear: understand the market structure early, anticipate where innovation and sustainability expectations are heading, and use validated data to prioritize investment. The PW Consulting Mascara Market research is designed to support that process from the first strategic review through ongoing portfolio management.
For detailed analysis of this topic, please visit the official page: Mascara Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Strength Steel Market Hits $130M in 2025, Forecast 7.8% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the High Strength Steel Market: A 2026 Executive Briefing
The global high strength steel market stands at a critical inflection point as industrial demand converges with stringent regulatory frameworks and accelerated technological innovation. For corporate strategists, procurement leaders, and capital allocators, navigating this landscape requires more than top-line projections. It demands granular, actionable intelligence that maps macroeconomic momentum to on-the-ground competitive shifts. PW Consulting’s latest High Strength Steel Market research delivers precisely that intelligence, offering a decision-ready architecture designed to de-risk strategic planning and unlock structural advantages across the 2026 to 2032 horizon.
A Market Defined by Resilient Growth and Structural Rebalancing
Tracing the market’s trajectory from 2020 through 2025 establishes a clear baseline of steady expansion, with revenue compounding at a pace that outpaces broader industrial metal benchmarks. The transition from historical performance into the forecast window reveals an acceleration pattern that demands immediate strategic attention. By 2026, the market has crossed a significant revenue threshold, and the forward projection indicates sustained upward momentum through the end of the decade. The implied compound annual growth rate across the full forecast period underscores a structurally healthy demand environment rather than a cyclical spike. This trajectory is not uniform across all vectors, which is exactly why executives must look beyond aggregate figures. The reallocation of investment, shifting end-user priorities, and evolving material specifications are reshaping where value accrues and which product architectures capture premium positioning.
Leadership teams operating in capital-intensive sectors cannot afford to treat high strength steel as a commoditized input. The market’s expansion is increasingly tied to performance-critical applications, weight-reduction mandates, and infrastructure modernization cycles. Understanding how these drivers fragment across product architectures and end-use ecosystems is the difference between capturing margin expansion and being squeezed by price volatility. Our research isolates these dynamics without diluting them into vague trend summaries, providing a clear line of sight from macro momentum to segment-level execution pathways.
Decoding the Competitive Architecture
The industry’s leadership cohort reflects a deliberate concentration of technological capability, geographic footprint, and application-specific expertise. A handful of entrenched players command the majority of realized market value, yet the competitive field remains highly active as incumbents recalibrate portfolios and challengers target niche performance tiers. The market structure exhibits moderate oligopolistic characteristics, meaning that while scale players set pricing anchors and technology benchmarks, there remains meaningful room for differentiated positioning through grade specialization, regional supply chain optimization, and application engineering.
High Strength Steel Market
Several globally recognized producers anchor the landscape, each pursuing distinct strategic vectors. A Swedish leader has cemented its reputation through premium structural and automotive grades engineered for extreme load conditions and lightweighting targets. A Luxembourg-headquartered multinational continues to scale its high-yield and advanced-grade offerings, particularly where construction durability and automotive crash performance intersect. A South Korean manufacturer has extended its global sales architecture around premium structural steels and automotive high-strength lines, leveraging integrated production advantages to compete in export-driven markets. A Japanese enterprise maintains a strong presence in ultra-high-tensile and offshore-grade plates, serving infrastructure and heavy industrial buyers who prioritize certification depth and metallurgical consistency. In North America, the largest domestic supplier of advanced high-strength steels is pushing third-generation grades that directly address vehicle lightweighting requirements, while a major U.S. integrated producer has introduced proprietary advanced grades designed for electric vehicle platforms and transformer applications. European and Indian counterparts round out the competitive matrix, with one German firm supplying high-strength flat-rolled products for automotive and industrial use, an Austrian manufacturer emphasizing premium grades for machinery and automotive segments, and an Indian producer focusing on corrosion-resistant high-tensile offerings for offshore and maritime environments.
This is not a static hierarchy. Recent corporate movements demonstrate how quickly product launches, capacity decisions, and industry consortium studies can reshape sourcing preferences. A major European producer recently introduced a new line of ultra-high-strength steels engineered specifically for electric vehicle chassis, positioning the release around lightweighting efficiency and updated safety compliance thresholds. A leading U.S. integrated manufacturer simultaneously expanded its portfolio to include proprietary advanced high-strength formulations and ultra-thin lightweight grades tailored for EV and transformer applications. Meanwhile, a North American capacity expansion initiative committed substantial capital toward increasing quenched-and-tempered steel output, extending the availability of flagship high-strength brands for demanding industrial and transportation users. Complementing these corporate moves, an industry-wide research body published a new parts consolidation study that quantifies how advanced high-strength steels can simplify vehicle architecture while maintaining structural integrity. These developments are not isolated headlines; they signal where R&D capital is flowing, where downstream buyers are being encouraged to re-evaluate material selections, and which performance benchmarks are becoming table stakes rather than differentiators.
Forces Reshaping Market Dynamics
Executive decision-making in this sector is being compressed by a convergence of policy shifts, input cost volatility, and standardization updates that directly alter procurement economics and specification strategies. Trade policy remains one of the most immediate variables. The reinstatement and subsequent escalation of import tariffs in the United States through mid-2025 fundamentally altered the cost baseline for imported high strength steel, forcing regional buyers to reconsider sourcing geography, inventory positioning, and contract structuring. Across the Atlantic, parallel moves by the European Union to reduce duty-free quotas and impose steep duties beyond those thresholds have recalibrated the cost landscape for European manufacturers and their supply chain partners. These policy adjustments do not merely affect landed cost; they influence capacity utilization patterns, redirect trade flows, and elevate the strategic importance of regional supply security.
Input cost dynamics add another layer of complexity. Recent price adjustments by major domestic producers in response to rising prime scrap costs illustrate how raw material inflation transmits rapidly into finished high-strength-grade economics. When base material costs move sharply, the margin sensitivity of advanced grades becomes a board-level concern, particularly for automotive and construction programs that operate on tightly negotiated multi-year agreements. Simultaneously, updated welding electrode classification standards have introduced new specification considerations for fabrication and construction workflows, requiring engineering teams to align procurement choices with revised compatibility and certification requirements. These are not peripheral compliance items; they are operational variables that influence total cost of ownership, lead-time reliability, and vendor qualification timelines.
What ties these forces together is their compounding effect. Tariff exposure changes sourcing logic, raw material inflation compresses margin tolerance, and specification updates alter fabrication readiness. Companies that treat these as independent risks often overcorrect in one area while under-hedging another. Our research integrates these variables into a unified operational framework, enabling leaders to model how policy, input costs, and technical standards interact across procurement cycles and capital planning horizons.
Inside the Research: Actionable Architecture for 2026 Decision-Making
This study is constructed for executives who need precision over generality. Rather than presenting a static market snapshot, the report maps the decision environment across product architecture, application demand, regional positioning, and competitive behavior, with explicit guidance on where and how to act. The analytical core is built around a multi-layered segmentation framework that dissects the market by type, application, and geography, while deliberately avoiding the trap of superficial share arithmetic. Each segmentation layer is evaluated for growth durability, price sensitivity, specification trajectory, and substitution risk so that sourcing and product-strategy teams can identify where to protect exposure and where to pursue premium positioning.
The competitive section goes beyond corporate profiling to assess strategic posture, capacity intent, and portfolio direction. Readers gain a structured view of how leading producers are aligning R&D investments with end-user requirements, which product families are being prioritized, and how recent launches and capacity decisions signal the next phase of market competition. This enables procurement and product-development teams to anticipate supplier positioning, evaluate alternative grade pathways, and construct negotiation strategies grounded in forward-looking supplier behavior rather than historical pricing alone.
Regulatory and cost-environment analysis is embedded throughout the report, not isolated in a compliance appendix. Trade-policy escalations, duty-quota adjustments, raw material price movements, and updated technical standards are mapped to their operational consequences, giving strategy and supply-chain leaders a practical reference for scenario planning. The forecast architecture extends across the full outlook window, providing a coherent growth narrative that supports capacity decisions, long-term contract structuring, and product-mix optimization. Crucially, the report maintains a tight focus on decision utility: it highlights where growth is structurally supported, where volatility is likely to intensify, and which strategic levers deliver the highest return on analytical investment.
To preserve the depth required for real-world application, certain granular breakdowns are reserved for the full intelligence package. The complete report provides the detailed regional and application-level decompositions, type-specific revenue architecture, concentration measurements, and company-by-company strategic assessments that turn high-level direction into executable planning inputs. This deliberate structure ensures that the executive summary establishes credibility and directional clarity while the full dataset delivers the specificity needed for budgeting, sourcing, and product-roadmap decisions.
Why This Intelligence Matters Now
Market leadership in high strength steel is increasingly defined by the speed and accuracy with which organizations integrate demand signals, policy reality, and supplier strategy into their capital and procurement plans. The growth trajectory through the end of the decade is robust, but the path to capturing it is uneven. Winners will be those who align material specifications with downstream performance mandates, manage exposure to trade and input-cost volatility, and position their product or sourcing strategies ahead of competitor portfolio shifts. Delaying that alignment until quarterly reviews or spot-market disruptions force action is a structural disadvantage.
PW Consulting’s High Strength Steel Market research provides the analytical foundation to move from reactive monitoring to proactive positioning. It equips leadership teams with a consolidated view of where value is concentrating, how competitive intentions are evolving, and which operational variables deserve immediate attention in 2026. The full report is designed to be read by strategists, commercial directors, procurement executives, and engineering leaders who need to translate market momentum into measurable advantage. Accessing the complete dataset will reveal the detailed segmentation architectures, competitive granularities, and scenario-ready breakdowns necessary to convert insight into execution.
High-strength Polyester Thread Market
For organizations preparing for the next phase of industrial demand, the question is no longer whether high strength steel will remain central to lightweighting, durability, and infrastructure performance, but how precisely to navigate the opportunities and risks embedded in its growth path. This research is built to answer that question with the clarity, rigor, and operational relevance that 2026 decision-making demands.
For detailed analysis of this topic, please visit the official page: High Strength Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Aseptic Packaging Market Hits $78.29B in 2025, Projects 10.5% CAGR Through 2032
By pmarketresearch, 2026-09-15
Unlocking Growth in the Aseptic Packaging Market: Strategic Insights for 2026 and Beyond
The global packaging landscape is undergoing a profound transformation, driven by shifting consumer expectations, stringent regulatory frameworks, and an enduring demand for shelf-stable solutions that ensure product integrity. For senior executives and strategic planners, understanding the nuances of this evolution is no longer optional; it is a critical component of long-term viability. PW Consulting's latest comprehensive market research on the Aseptic Packaging Market offers a detailed roadmap for navigating this complex terrain, providing the intelligence necessary to make informed decisions throughout the forecast period.
This analysis serves as an introduction to our extensive study, highlighting the macro-economic trajectories, competitive shifts, and regulatory pressures that will define the industry from 2026 through 2032. By synthesizing historical performance with future projections, we aim to equip stakeholders with the foresight needed to capitalize on emerging opportunities while mitigating inherent risks.
Macro-Economic Trajectory and Market Valuation
The financial magnitude of the aseptic packaging sector underscores its importance within the broader manufacturing ecosystem. Our historical analysis tracks a consistent upward trend, reflecting the sector's resilience and capacity for expansion. In 2020, the market generated approximately USD 45.67 Billion in revenue. This figure climbed steadily over the following years, reaching USD 50.26 Billion in 2021 and USD 55.08 Billion in 2022. The momentum continued through 2023 and 2024, with valuations rising to USD 61.45 Billion and USD 70.76 Billion respectively, before closing the base year of 2025 at USD 78.29 Billion.
Looking forward, the forecast period from 2026 to 2032 indicates sustained growth. The market is projected to reach USD 88.76 Billion in 2026. This growth trajectory is expected to accelerate slightly, culminating in a valuation of USD 156.25 Billion by 2032. This expansion represents a Compound Annual Growth Rate (CAGR) of 10.5% over the forecast period. Such robust performance suggests that aseptic packaging is not merely a passive container solution but a dynamic sector integrated deeply into supply chain efficiencies and product lifecycle management.
Bulk Aseptic Packaging Market
However, understanding the top-line numbers is only the first step. The strategic value lies in dissecting the drivers behind this growth and anticipating where value pools will shift. Our report delves into these specific drivers, analyzing how different variables interact to influence overall market health. While the aggregate figures provide a horizon, the detailed segmentation analysis within the full study reveals the specific lanes of opportunity that will drive this CAGR.
Structural Dynamics and Regional Shifts
The composition of market demand is shifting as regional economic conditions evolve and manufacturing capabilities expand. Historically, mature markets have held significant share, but the growth velocity in emerging regions is reshaping the competitive map. Our research indicates that regional dynamics are becoming increasingly complex, influenced by local regulatory environments, infrastructure development, and changing consumption patterns.
For instance, the demand landscape is not uniform. Different regions exhibit varying preferences for packaging types and applications based on local industrial strengths. While some areas maintain strong dominance in specific sectors due to established infrastructure, others are witnessing rapid adoption rates driven by urbanization and retail expansion. The full report provides a granular breakdown of these regional performances, allowing strategists to identify where to allocate capital for maximum return.
Furthermore, the type of packaging utilized varies significantly across industries. The market encompasses a diverse range of formats, from cartons and bags to bottles and vials. Each format serves distinct functional requirements regarding barrier properties, portability, and stacking efficiency. The interplay between these formats and the industries they serve creates a complex web of dependencies. Understanding which formats are gaining traction in specific application sectors is crucial for manufacturing planning and inventory management. Our detailed segmentation analysis isolates these trends, offering clarity on which product categories are poised for the steepest growth curves.
Regulatory Pressures and Sustainability Imperatives
One of the most significant forces reshaping the industry is the regulatory environment, particularly within major economic zones. The European Union's Packaging and Packaging Waste Regulation (PPWR), which entered into force on February 11, 2025, stands as a pivotal development. This regulation mandates that all packaging on the EU market must be recyclable, with detailed design for recycling criteria set via delegated acts by 2028. It becomes fully applicable from August 12, 2026, following an 18-month transition period.
For aseptic packaging, this presents a specific compliance challenge. The PPWR requires that aseptic packaging placed on the European market must be recyclable, necessitating aluminum layer minimization and the use of mono-material components to meet compliance standards. This regulatory shift is forcing manufacturers to innovate rapidly. The traditional reliance on multi-layer structures containing aluminum for barrier protection is being scrutinized under the new framework. Companies must now balance the functional requirement of sterility and shelf-life extension with the imperative of recyclability.
This regulatory context is not just a compliance hurdle; it is a catalyst for innovation. It drives the development of new materials and processing technologies that can maintain product safety while reducing environmental impact. Our report analyzes the implications of these regulations across different geographies, helping companies anticipate compliance costs and adjust their product development pipelines accordingly. The transition period offers a window of opportunity for early movers to establish compliant solutions before the enforcement date, potentially securing a competitive advantage in key markets.
Competitive Landscape and Strategic Maneuvers
The market structure is characterized by a moderate level of concentration, with key players exerting significant influence over pricing, technology standards, and supply chain dynamics. The concentration ratio indicates that a handful of major entities control a substantial portion of the market share. This oligopolistic tendency suggests that strategic partnerships, mergers, and acquisitions will continue to be relevant tools for companies seeking to scale or diversify their portfolios.
Several core enterprises define the current competitive arena. Tetra Laval S.A., headquartered in Lund, Sweden, remains a pioneer of aseptic packaging systems and carton/filling technology for dairy, beverages, and liquid foods. Their recent strategic moves highlight the industry's direction. In January 2026, Tetra Pak announced a EUR 60 Million investment in a new pilot plant at Lund, Sweden, focused on paper-based barrier technology to replace aluminum foil in aseptic cartons. This move directly addresses the sustainability challenges posed by regulations like the PPWR, signaling a commitment to mono-material solutions.
Similarly, SIG Combibloc Group AG, based in Zug, Switzerland, is a major provider of flexible aseptic bag-in-box systems, including the SteriSeal Spout for bulk liquids. Their activity level remains high, with a USD 35 Million investment announced in July 2025 to expand their aseptic carton plant in Querétaro, Mexico, targeting dairy and shelf-stable beverages. Furthermore, in January 2026, SIG entered the camel milk category with new aseptic carton solutions, demonstrating agility in capturing niche market segments. They also rolled out a new aluminum-free aseptic carton solution in select European markets in 2025, enhancing recycling yield for dairy and juice applications.
Other significant players contribute to the diverse ecosystem. Amcor plc, located in Zurich, Switzerland, supplies aseptic plastic bottles and extended shelf-life ESL packaging with UV protection and shelf lives ranging from 90 days to 1 year. Elopak AS, from As, Norway, manufactures aseptic cartons for dairy, juice, and shelf-stable beverages. In Asia, Greatview Aseptic Packaging Co., Ltd., based in Beijing, China, is a key producer of rolled-fed and blank-fed aseptic cartons for dairy and non-carbonated soft drinks. DS Smith plc, headquartered in London, United Kingdom, offers aseptic sterilised transit packaging solutions for pharma and food applications. Sealed Air Corporation, in Charlotte, United States, provides advanced flexible aseptic pouches and componentry for liquid food packaging. Sidel Group, based in Paris, France, operates as an aseptic filler and packaging equipment provider, including PET bottle lines.
Recent trade show activity also underscores the collaborative and innovation-driven nature of the sector. In June 2026, ASEPTO exhibited aseptic liquid packaging innovations at ProPak MENA 2026 in Cairo, Egypt. Similarly, Steriline showcased advanced aseptic packaging filling lines at Interphex 2025 in New York. These exhibitions highlight the continuous flow of technological advancements in filling and packaging equipment, which is essential for maintaining the sterility assurance levels required by end-users.
The competitive dynamics are further influenced by raw material suppliers and specialized manufacturers. For example, NewJF Packaging, formed in 2003 and listed on the Hong Kong Stock Exchange, is recognized as the world's third-largest manufacturer of aseptic cartons. Such entities play a critical role in the supply chain, affecting availability and cost structures for downstream converters.
Application Drivers and Sector Growth
The demand for aseptic packaging is fundamentally tied to the needs of the industries it serves. The Food and Beverage sector remains a dominant force, driven by the need to preserve nutritional value, flavor, and safety without the use of preservatives. This sector benefits immensely from the extended shelf-life capabilities that aseptic technology provides, allowing for broader distribution networks and reduced food waste.
The Pharmaceutical sector also represents a critical application area. Sterility and contamination control are non-negotiable in this field. Aseptic packaging ensures that sensitive biological products, vaccines, and liquid medications remain safe for consumption or administration. The stringent regulatory requirements in pharma drive demand for high-quality vials, ampoules, and specialized containers that can withstand rigorous sterilization processes. Our report analyzes how growth in these application sectors correlates with broader healthcare trends and food security initiatives.
While these two sectors are prominent, there are other applications gaining traction. Understanding the specific growth rates and volume contributions of each application segment is vital for companies aiming to specialize or diversify. The full study provides precise data on how each application area contributes to the overall market revenue, enabling clients to benchmark their performance against industry averages.
Aseptic Packaging Market
Strategic Implications for 2026 Decision-Making
As we move through 2026, the decisions made by industry leaders will set the course for the next decade. The convergence of regulatory pressure, material innovation, and regional demand shifts creates a complex operating environment. Companies must decide whether to invest heavily in R&D for sustainable materials, pursue geographic expansion into high-growth regions, or consolidate market share through strategic acquisitions.
The investment signals from key players suggest a clear trend toward sustainability and regional localization. The EUR 60 Mn investment by Tetra Pak and the USD 35 Mn expansion by SIG indicate confidence in long-term demand but also a necessity to adapt product structures to meet future compliance standards. For smaller players or new entrants, the barrier to entry may rise as compliance costs increase, potentially favoring well-capitalized incumbents who can absorb the transition costs.
Moreover, the supply chain resilience demonstrated during previous global disruptions continues to be a priority. Localization of production facilities, such as the expansion in Mexico, reduces logistics risks and aligns with "nearshoring" trends. Understanding the cost implications of these logistics shifts and their impact on final product pricing is another critical insight provided in our detailed analysis.
Conclusion and Access to Comprehensive Intelligence
The Aseptic Packaging Market is poised for significant expansion, driven by a 10.5% CAGR and a valuation trajectory moving from USD 88.76 Billion in 2026 to over USD 156 Billion by 2032. However, realizing value in this environment requires more than just acknowledging growth figures. It demands a deep understanding of the regulatory mechanisms shaping material choices, the competitive strategies employed by industry leaders, and the specific regional dynamics that influence market access.
PW Consulting's full market research report offers an unparalleled depth of analysis. It moves beyond the high-level overview to provide actionable intelligence on market entry strategies, supply chain optimization, and competitive benchmarking. The report details the specific segmentation splits, regional revenue contributions, and application-specific growth rates that are essential for granular strategic planning.
To fully leverage these insights and secure a competitive edge in the evolving landscape of 2026 and beyond, stakeholders are encouraged to access the complete study. The detailed data, combined with our expert analysis of industry trends and regulatory impacts, provides the foundation necessary for robust strategic decision-making. Visit the PW Consulting source page to download the comprehensive report and gain access to the full suite of intelligence designed to guide your organization through the next phase of market evolution.
For detailed analysis of this topic, please visit the official page: Aseptic Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com