
Blogs
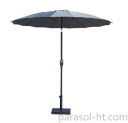
A well-designed patio can become an extension of the living or dining environment, but open-air spaces are strongly influenced by sunlight, temperature, rain, and changing weather conditions. Shade structures help define these spaces while supporting more comfortable outdoor activities. For homeowners, hospitality operators, landscape designers, and distributors, Patio Shade Umbrellas can be evaluated through material selection, structural design, operating convenience, installation conditions, and maintenance requirements.
The canopy is one of the most visible components. Its fabric determines much of the visual character of the umbrella while also contributing to shade coverage and weather management. Different textile constructions provide different combinations of flexibility, appearance, moisture behavior, and resistance to outdoor exposure. Fabric selection should therefore reflect the intended environment rather than being based only on color or appearance.
The frame provides the structural foundation of the umbrella. A typical structure may include a central pole, ribs, stretchers, joints, and opening mechanisms. Each component contributes to the movement and stability of the canopy. When an umbrella is opened or closed repeatedly, these parts experience mechanical movement and contact. Proper component coordination is therefore important for reliable operation.
Patio applications vary significantly. A private residential patio may have limited available space and may require an umbrella that can be opened when needed and stored when not in use. A restaurant terrace may operate shade structures throughout the day and require convenient access for staff. Hotels and resorts may use multiple umbrellas to establish consistent visual arrangements across outdoor dining or relaxation zones.
Size and placement also influence the overall experience. A shade structure should correspond with the furniture underneath it and the available circulation space around it. If an umbrella is positioned too close to walls, doors, trees, or other structures, opening and operation may become inconvenient. Landscape planning can therefore benefit from considering umbrella placement before furniture and shelter systems are installed.
The support base deserves equal attention. An umbrella's stability depends not only on its vertical pole but also on how forces are transferred to the ground. Different applications may require different base solutions depending on surface conditions, installation methods, and the size of the umbrella. A properly selected base should work as part of the complete system rather than being treated as an unrelated accessory.
Manufacturing accuracy affects these relationships. Pole alignment, rib positioning, joint dimensions, fabric cutting, stitching, and final assembly all influence the finished product. Even small inconsistencies can affect opening movement or canopy appearance. Production teams therefore need appropriate process controls throughout manufacturing instead of depending exclusively on final inspection.
For manufacturers, fabric cutting is particularly important. Canopy sections need to be shaped accurately so that they fit together as intended. Stitching lines should remain consistent, and stress areas can receive suitable reinforcement according to the design. These details are relevant not only to appearance but also to the way the canopy responds when opened and exposed to normal outdoor conditions.
Frame finishing also has an important role. Metal components used outdoors need suitable surface treatment based on the material and intended environment. Coating processes can influence appearance and resistance to environmental exposure. Production control should cover surface preparation, coating consistency, curing, and inspection so that finished components meet the required manufacturing specifications.
Linhai Hongtai Leisure Products Co., Ltd. develops and manufactures outdoor leisure products in Linhai, Zhejiang. Its product portfolio includes outdoor push umbrellas, outdoor hand shaking umbrellas, cantilever banana umbrellas, outdoor Roman umbrellas, outdoor shade tents, and outdoor umbrella bases. The company's official information also describes its involvement in design, development, production, sales, and service for outdoor umbrella products.
International distribution creates additional manufacturing considerations. Products may travel long distances before reaching their final application site, making packaging and component protection important. Packaging should protect fabrics from contamination and structural parts from damage while allowing distributors to handle and store products efficiently.
Product documentation can also support smoother installation. Clear identification of components, opening instructions, maintenance information, and assembly guidance can reduce confusion during distribution and installation. For commercial projects involving multiple units, consistent documentation can be particularly useful when products need to be installed across different areas.
Maintenance should be considered from the beginning of product development. Patio environments can expose umbrellas to dust, pollen, rain, sunlight, and other outdoor conditions. Users may need to clean fabric surfaces periodically and inspect moving or connecting components. Practical designs can make routine care easier, helping users understand how the product should be operated and maintained.
Sustainability considerations are also becoming more relevant to outdoor product manufacturing. Material efficiency, longer service cycles, repairability, packaging reduction, and responsible production processes can all contribute to a more considered product-development approach. These factors should be assessed realistically according to manufacturing capabilities and application requirements rather than treated as purely promotional claims.
The development of Patio Shade Umbrellas involves much more than creating visual shade over a table or seating area. It combines textile engineering, structural design, manufacturing precision, base selection, packaging, installation, and maintenance. For residential and commercial patios alike, understanding these factors helps buyers and designers select outdoor shade solutions according to real application requirements. Linhai Hongtai Leisure Products Co., Ltd. presents its outdoor leisure product range and company information at https://www.parasol-ht.com/ .
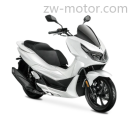
The development of a modern scooter requires cooperation between design, engineering, sourcing, production, inspection, and after-sales planning. A professional Scooter Manufacturer must coordinate these areas so that the finished vehicle is not only visually consistent but also practical for daily use. For international customers, this coordination can influence product stability, market suitability, service efficiency, and the long-term relationship between supplier and distributor.
Scooter design begins with an understanding of the intended application. A vehicle used for urban commuting may require a different balance of seating position, storage, maneuverability, and powertrain behavior than one designed for longer-distance travel. Road quality, climate, traffic density, rider habits, and local regulations can all affect engineering decisions. Establishing the application before production planning helps ensure that the selected components support the expected operating environment.
The frame is the foundation of the vehicle. Its geometry influences stability, handling, seating position, and the placement of major systems. Manufacturing processes such as tube forming, cutting, welding, and fixture alignment must be controlled carefully. Welding quality is particularly important because inconsistent joints or dimensional variation can affect later assembly. Production fixtures help maintain repeatable positioning, while inspection procedures can identify deviations before the frame moves to the next stage.
Bodywork combines functional protection with visual design. Panels must fit together accurately and provide access to components that may require inspection or maintenance. Plastic materials should be selected according to their expected exposure to heat, sunlight, moisture, impact, and vibration. Injection molding can create detailed shapes efficiently, but mold maintenance, material preparation, and cooling conditions all influence the final result. Surface consistency and panel alignment are useful indicators of controlled production.
The powertrain must be integrated with the frame and body structure. Engine mounting, transmission alignment, intake routing, exhaust placement, cooling, and service access should be considered together. Poor coordination may lead to excessive vibration, difficult maintenance, or unwanted heat transfer to surrounding parts. A systematic development process evaluates the relationship between the power unit and other vehicle systems rather than treating the engine as an isolated component.
Electrical integration is equally important. Modern scooters may include electronic instruments, lighting systems, charging functions, sensors, and control modules. These parts require secure mounting and organized wiring. Harnesses should be routed away from sharp edges, excessive heat, and moving components. Connector placement should support service access while reducing exposure to moisture and contamination. Electrical testing during assembly can help identify installation problems before shipment.
Braking and suspension systems require attention to both component quality and assembly accuracy. Brake parts must be installed with suitable alignment and secure fastening. Suspension components should move correctly without unwanted interference or abnormal noise. Tires, wheels, steering parts, and lighting equipment also contribute to the overall riding experience. A production inspection process should examine functional performance as well as cosmetic details.
Manufacturing quality is built through repeatable procedures. Work instructions help operators follow the same sequence, while controlled tools can support consistent fastening. In-process checks may cover frame dimensions, panel fit, wiring, fluid systems, lighting, braking, and starting functions. Final inspection provides another opportunity to identify issues before vehicles are packed. When inspection results are recorded systematically, production teams can analyze recurring problems and improve process control.
Supply chain coordination also affects the performance of a vehicle program. Components from different suppliers must match the engineering requirements and arrive according to the production schedule. Changes in materials or component sources should be reviewed carefully because even a small difference in dimensions or properties can affect assembly. Clear specifications, sample approval, and communication between purchasing and engineering teams help reduce unnecessary variation.
For overseas customers, product development may include additional considerations such as packaging, labeling, documentation, market regulations, and service parts. A supplier should be able to discuss these requirements clearly and explain how they influence production planning. This is particularly important when a vehicle is intended for different climates or road environments. The ability to communicate across technical and commercial teams can make the development process more efficient.
A capable Scooter Manufacturer contributes more than production capacity. Its value is connected to engineering coordination, material understanding, process discipline, quality inspection, and the ability to adapt products to practical market requirements. ZHIWEKI works with international customers on two-wheel vehicle development and manufacturing, with attention to usability, system integration, and production consistency. Its scooter and motorcycle product information can be found at https://www.zw-motor.com/product/scooter-motorcycle/ .
KDB Medical offers home rehabilitation products that are ISO 13485 certified. This means that these products are made with high standards for safety and quality. When someone is recovering from an injury or surgery, having the right tools can make a big difference. At KDB Medical, we understand how important it is to have reliable rehab equipment at home. Our ISO 13485 certification shows our commitment to providing the best products for our customers. With this certification, you can trust that our equipment is designed not just for performance, but also for your safety and comfort during recovery.
What Are the Key Benefits of Choosing ISO 13485 Certified Rehab Equipment?
Choosing ISO 13485 certified rehab equipment, like the ones from KDB Medical, means you are getting products that meet strict quality guidelines. These guidelines ensure that every piece of equipment is safe for use. Imagine using a walker or a wheelchair that has gone through careful testing. It gives you peace of mind knowing that the equipment is reliable. Another benefit is that ISO 13485 certified products are often more durable. They are built to last longer than non-certified items. This means you will not have to replace your equipment as often, saving you money in the long run. Moreover, our certified products often come with better customer support. If you have questions or need help, you can reach out to us, and we will be there to assist. We care about our customers and want to ensure you have a smooth experience while using our products. Lastly, using ISO 13485 certified equipment can also speed up your recovery. Good quality rehab tools can help you regain strength and mobility, making your journey to recovery easier and more effective.
How to Choose the Right ISO 13485 Certified Products for Your Needs
When selecting ISO 13485 certified rehab products, think about what you specifically need for your recovery. Start by considering your personal situation. Are you recovering from surgery, or do you have a condition that makes movement difficult? Knowing your needs will guide you in making the right choice. KDB Medical offers a variety of products, from walkers to braces, so you can find what suits you best. Next, check the features of each product. Some walkers might have extra grips or wheels that make them easier to use. Look for features that will help you feel comfortable and secure. It's also helpful to read reviews from other users. Their experiences can provide insight into how well a product works. Sometimes, talking to a physical therapist can help, too. They can recommend what type of equipment would be best for your recovery. Don’t forget to take your budget into account. While certified products may cost a bit more, remember that you are investing in your health and safety. In the end, choosing the right ISO 13485 certified product means you are setting yourself up for a better recovery experience. At KDB Medical, we are always here to help you find the perfect solution for your needs.
What Do Wholesale Buyers Look for in Home Rehab Equipment?
When wholesale buyers look for home rehab equipment, they want to make sure they are getting the best products for their money. First, they check if the equipment is safe and made well. Safety is very important because these products are often used by people who are recovering from injuries or surgeries. If the equipment is not safe, it could cause more harm instead of helping. Buyers also want to see if the products are easy to use. If someone is recovering, they might have trouble using complicated machines. So, easy-to-use equipment is a big plus.
Another thing buyers look for is whether the products are comfortable. For example, when someone uses a rehab chair or walker, it should feel good to use. If the equipment is uncomfortable, the user may not want to use it at all. Buyers also consider how durable the products are. They want equipment that will last a long time and not break easily. This is especially important for rehab equipment, as it needs to handle a lot of use.
Buyers also like to see products that have good reviews. If other customers bath chair for tub say nice things about the equipment, it makes buyers feel more confident in their choice. Finally, wholesale buyers often look for ISO 13485 certification. This means the products meet high-quality standards for medical devices. KDB Medical offers ISO 13485 certified products, which ensures that every piece of equipment is safe and reliable. This certification helps buyers feel assured that they are getting quality items that can truly help people in their recovery journey.
Where to Source High-Quality ISO 13485 Certified Rehab Products at Wholesale Prices
Finding high-quality rehab products at wholesale prices can be tricky, but it is not impossible. One great way to start is by looking for suppliers who specialize in medical equipment. KDB Medical is a well-known supplier that offers ISO 13485 certified products. This means that their equipment meets strict safety and quality standards. Buyers can trust that when they choose KDB Medical, they are getting reliable and effective rehab equipment.
Buyers can also attend trade shows and medical supply expos. These shower chair for elderly events are a great opportunity to meet suppliers and see products in person. At trade shows, buyers can ask questions, learn about new products, and sometimes even negotiate better prices. Another option is to search online marketplaces that offer wholesale medical supplies. However, it’s important to do research and read reviews before making any purchases.
Networking with other healthcare providers can also help buyers find the best places to buy rehab products. They can share experiences and recommend suppliers that they have used before. Finally, it is smart to compare prices from different suppliers. Just because a product is cheaper does not always mean it is of lower quality, but buyers should always check for that ISO 13485 certification. KDB Medical not only offers competitive prices but also ensures that their products are top-notch, making them a great choice for anyone looking to source quality rehab equipment.
How KDB Health Solves Common Problems in Home Rehab Product Use
Using home rehab products can sometimes come with challenges, but KDB Medical aims to solve these problems effectively. One common issue is that many rehab items can be difficult for users to understand. Users may struggle with how to set up or use the equipment properly, which can lead to frustration. KDB Medical addresses this by providing clear instructions and even video tutorials with their products. This helps users learn how to use the equipment correctly, making their recovery process smoother.
Another problem is that some rehab products do not fit well in different home environments. Not every home is the same, and what works in one place may not work in another. KDB Medical designs their products to be versatile and adjustable. This means that users can modify the equipment to fit their specific needs and spaces, making it easier for them to use it at home.
Additionally, comfort is a big concern. Many rehab items can be hard or uncomfortable to use bath shower chairs elderly over time. KDB Medical prioritizes comfort in their product designs. They use soft materials and ergonomic shapes to ensure that users can use the equipment for longer periods without discomfort.
Finally, KDB Medical understands that some users may need extra support. That is why they have a dedicated customer service team ready to assist with any questions or concerns. This way, if users face any issues, help is just a call away. KDB Medical is committed to helping individuals in their recovery journey by providing quality rehab products that solve everyday problems.
KDB Medical is a company that makes special products to help people at home with their health and recovery. When someone is sick or has an injury, it can be hard for them to get the care they need. KDB Medical believes that everyone deserves to feel better in the comfort of their own home. Our products are designed to be easy to use and very helpful for both patients and caregivers. From comfortable beds to useful rehabilitation equipment, KDB Medical has a wide range of items that support health and healing. Our focus is on making sure that people have what they need to recover and stay healthy, making life easier for everyone involved.
What Makes KDB Health Home Healthcare Products Stand Out in Quality?
KDB Medical takes great pride in the quality of our home healthcare products. One reason our items stand out is that we put a lot of thought into the design. For example, our beds have adjustable features, which can help people find the most comfortable position for resting or getting in and out. This is especially important for people who may struggle with movement. We also use strong materials that last a long time. This means that our products won’t easily break or wear out, saving families money in the long run. Another aspect of our quality focus is safety. Many of our items have special features to prevent accidents. For instance, some of our mobility aids have non-slip surfaces to keep users steady while walking. Our products are also tested to ensure they meet high standards, so users can trust they are safe. Additionally, we listen to feedback from users and caregivers. This helps us improve our products, making sure they meet the needs of those who use them every day. We believe that by focusing on quality, we can make a real difference in people’s lives, helping them feel secure and cared for at home.
What Are the Benefits of Using KDB Health Rehabilitation Equipment?
Using KDB Medical rehabilitation equipment has many benefits for those recovering from surgery or injury. First, our products are made to support movement and strength-building. For example, we have exercise machines that are easy to use, even for those who may be weak or tired. These machines help users gradually get stronger without putting too much strain on their bodies. Another big benefit is that our equipment is designed to be adjustable. This means that as a person gets stronger, they can easily change the settings to match their new abilities. This makes it easier for them to keep improving. Additionally, our rehabilitation products often come with helpful guides and videos. These resources show users the best way to use the equipment safely and effectively. This guidance can help prevent injuries and make sure users are getting the most out of their workouts. Using KDB Medical rehabilitation equipment can also give people a sense of independence. They can do exercises at home, which means they won't have to rely on others for every little thing. This can boost their confidence and motivation. Overall, our rehabilitation equipment helps people recover faster and feel better, giving them the tools they need to regain their strength and live healthier lives.
Where to Buy Wholesale Home Healthcare Supplies for Your Business?
If you are looking to buy home healthcare supplies for your business, KDB Medical toilet seat aids for disabled is a great place to start. KDB Medical offers a wide range of products that are helpful for people needing care at home. You can find everything from wheelchairs to hospital beds, and much more. Buying wholesale means you can get these products in larger amounts, which often makes them cheaper. This is especially good for businesses that need to provide care for many people. To buy from KDB Medical, you can visit their website or contact them directly. They have friendly staff who can help you understand what products are available and how to order them. It’s important to know that KDB Medical not only sells products but also offers guidance on which supplies are best for your needs. They can help you choose the right equipment based on the kind of care you provide. This is very useful because different patients may need different types of equipment. By buying wholesale, you can save money and keep your business stocked with the supplies you need. This way, you can focus on giving the best care to your patients without worrying about running out of important items. KDB Medical makes it easy to find what you need, and they ensure that all their products meet high-quality standards. So, if you run a home healthcare business, think about reaching out to KDB Medical for all your wholesale supply needs.
What Common Issues Do Buyers Face with Home Healthcare Products?
When buyers look for home healthcare products, they often face several common issues. One big problem is the quality of the products. Sometimes, people buy items that look good but do not work well or break easily. This can be very frustrating, especially when caring for someone who needs reliable equipment. KDB Medical understands this issue and ensures that all their products are tested for quality. Another issue is the lack of information. Many buyers do not know enough about what they are buying. They might not understand how to use a certain product or whether it is right for their needs. KDB Medical medical supplies toilet seats helps by providing clear instructions and support for their products. This way, buyers can feel confident in their choices. Price is also a concern for many buyers. Some may find that the costs of home healthcare supplies are too high. KDB Medical aims to offer affordable options without sacrificing quality. This helps businesses get what they need without spending too much money. Lastly, buyers may struggle with finding the right equipment for specific health issues. Different patients have different needs, and it can be hard to know what to choose. KDB Medical offers expert advice to help buyers select the best products for their patients. By addressing these common problems, KDB Medical makes the buying process smoother and easier for everyone involved in home healthcare.
What Are the Latest Trends in Home Healthcare and Rehabilitation Equipment?
The world of home healthcare and rehabilitation equipment is always changing. One of the latest trends is the use of technology in everyday products. For example, many new devices can connect to smartphones or tablets. These smart devices help caregivers keep track of their patients' health. KDB Medical is at the forefront of this trend, offering products that make it easy to monitor things like heart rate or activity levels from home. Another trend is the focus on comfort and design. Companies now understand that people want equipment that not only works well but also looks good in their homes. KDB Medical bariatric bedside toilet offers stylish and comfortable options that blend in nicely with home decor. This helps patients feel more relaxed and less like they are in a hospital. Another exciting trend is the rise of portable and lightweight equipment. Many products are now designed to be easy to move and store. This is especially important for people who may need to travel or go to different places for rehab. KDB Medical provides a variety of portable options that make life easier for patients and caregivers. Finally, there is an increased emphasis on personalized care. More products are being designed to fit individual needs. This means that caregivers can find equipment that suits the specific requirements of each patient. KDB Medical is committed to providing customizable solutions that help improve the quality of care. By staying updated on these trends, KDB Medical ensures that their customers have access to the best and most modern equipment available.
A fuller or less defined neck can result from excess fat, loose skin, weakened tissues, or a combination of these factors. Two procedures commonly considered for improving the neck profile are liposuction and a neck lift. Double Chin Liposuction in Riyadh primarily focuses on removing localized fat beneath the chin, while a neck lift is designed to address loose skin and underlying tissues as well as contour concerns. Understanding these differences can help you discuss your options with a qualified specialist.
What Is Double Chin Liposuction?
Double chin liposuction is a minimally invasive procedure that targets excess fat beneath the chin and around the upper neck. A small cannula is used through tiny access points to remove selected fat deposits and improve the transition between the chin and neck. Double Chin Liposuction in Riyadh may be suitable for people whose main concern is localized under-chin fat and who have relatively good skin elasticity.
How Liposuction Improves Contour
The procedure focuses primarily on fat reduction rather than removing loose skin. By carefully reducing excess fat, a provider can create a more defined appearance around the jawline and neck. The amount of contour improvement depends on factors such as fat distribution, skin quality, facial anatomy, and the individual's healing response.
What Is a Neck Lift?
A neck lift is a surgical procedure designed to improve signs such as loose neck skin, excess tissue, and reduced definition around the jaw and neck. Depending on the individual's anatomy, the procedure may involve removing excess skin, repositioning tissues, and addressing underlying neck structures.
How a Neck Lift Works
A neck lift typically involves carefully placed incisions that allow the surgeon to access and reshape tissues beneath the skin. Excess skin may be removed, and underlying tissues can be repositioned or tightened when appropriate. The specific technique depends on the patient's anatomy and the degree of skin laxity or tissue changes.
Main Difference Between the Two Procedures
The biggest difference is what each treatment is designed to address. Liposuction primarily removes localized fat, whereas a neck lift can address loose skin and underlying tissue in addition to improving overall neck contour. Choosing between them depends largely on what is causing the appearance of a double chin or poorly defined neck.
Fat Versus Loose Skin
If excess fat is the primary concern and the skin can contract adequately after fat removal, liposuction may be considered. If significant loose or sagging skin is present, removing fat alone may not provide the desired result. A neck lift may be considered when skin laxity and tissue changes are more prominent.
Results and Recovery
Both procedures involve recovery, but the experience can differ because a neck lift is generally more extensive than isolated liposuction. After liposuction, temporary swelling, bruising, tenderness, and tightness may occur. A neck lift can involve swelling, bruising, incision healing, and a longer recovery period depending on the surgical technique used.
When Results Become Visible
Liposuction can produce an early change in the contour because fat is removed during the procedure, although swelling may temporarily hide some of the improvement. Neck-lift results also develop progressively as swelling decreases and the tissues settle into their new position. Final results may take time to become fully apparent.
Can Liposuction and a Neck Lift Be Combined?
In some cases, a surgeon may consider combining fat removal with a neck-lifting procedure. This can be relevant when both excess fat and significant skin or tissue laxity contribute to the appearance of the neck. However, whether combination treatment is appropriate depends on the individual's anatomy, health, goals, and surgical assessment.
Why Individual Assessment Matters
A professional evaluation is important because the visible appearance of a double chin does not always come from fat alone. Skin laxity, muscle structure, genetics, aging, and the natural shape of the jaw and neck can all influence facial contour. Identifying the main contributing factors helps determine which approach may be appropriate.
Which Option May Be Considered?
The choice between liposuction and a neck lift should be based on the underlying cause of the concern rather than the procedure name alone. People with localized fat and good skin elasticity may be evaluated for liposuction, while those with considerable loose skin or tissue laxity may be assessed for a neck lift.
Maintaining Results
Both procedures can create long-lasting changes, but natural aging and significant weight changes can affect the appearance of the neck over time. Maintaining a stable weight and following appropriate aftercare can support the longevity of the result.
Book an Appointment at Royal Clinic Saudia
If you are unsure whether fat, loose skin, or both are contributing to your neck profile, Royal Clinic Saudia can provide a personalized assessment. During your consultation, you can discuss Double Chin Liposuction in Riyadh , neck-lift techniques, recovery expectations, and the approach that may be appropriate for your individual anatomy and goals.
A well-defined jawline can influence the overall balance and structure of the face, but factors such as genetics, aging, changes in facial volume, and skin laxity can make the jawline appear softer over time. For people interested in non-surgical facial contouring, Radiesse Filler Injection in Riyadh may be an option for improving jawline definition in appropriately selected patients. Radiesse can provide structural support while also stimulating collagen production, potentially creating a more defined and supported lower-face appearance.
Jawline definition is not simply about adding volume. The shape of the chin, cheeks, lower face, and surrounding tissues all contribute to how the jawline looks. Radiesse Filler Injections in Riyadh may help enhance selected structural points while maintaining facial proportions. A personalized assessment is important because the ideal treatment approach depends on individual anatomy, skin quality, and the amount of definition desired.
How Does Radiesse Help Define the Jawline?
Radiesse is a calcium hydroxylapatite-based injectable filler that can provide immediate structural support after injection. It also has biostimulatory properties that may encourage collagen production over time. These characteristics can make it useful for selected facial contouring goals.
Adding Structural Support
A softer jawline can sometimes be influenced by reduced volume or support along the lower face. Carefully placed Radiesse may provide support in strategic areas, helping create a sharper-looking transition between the lower face and jaw.
Supporting Collagen
The collagen-stimulating properties of Radiesse may contribute to gradual improvements in skin firmness around treated areas. This can complement the initial contouring effect and potentially provide a more supported appearance as the treatment develops.
What Can Affect Jawline Definition?
Several factors determine how prominent or defined a person's jawline naturally appears. Genetics play an important role, while age-related changes can cause shifts in facial fat and reduced skin elasticity. Weight fluctuations can also influence the amount of soft tissue around the jaw.
The underlying bone structure is another important factor. Injectable treatment can enhance the appearance of existing contours, but it cannot change the basic skeletal structure of the face. Understanding these limitations helps patients develop realistic expectations.
Who May Benefit From Jawline Contouring?
Radiesse may be suitable for adults who have mild loss of jawline definition, age-related volume changes, or a desire for greater lower-face structure. Candidates should generally have realistic expectations and understand that injectable contouring is designed to enhance rather than completely transform facial anatomy.
Patients with significant skin laxity or substantial excess tissue may require a different approach. A professional evaluation can determine whether Radiesse is appropriate or whether another treatment would better address the underlying concern.
What Happens During Jawline Treatment?
Treatment typically begins with a consultation and detailed facial assessment. The practitioner examines the jawline, chin, cheeks, skin quality, facial proportions, and areas of volume loss. This helps determine where structural enhancement may create the most balanced result.
During the procedure, Radiesse is injected into carefully selected areas using an appropriate technique. The exact placement and amount depend on the patient's anatomy and treatment goals. The aim is usually to create definition without making the lower face look excessively heavy or unnatural.
Can Radiesse Improve a Weak Jawline?
In selected patients, Radiesse may enhance the appearance of a less prominent jawline by providing additional structural support. The improvement depends on the existing bone structure, soft-tissue characteristics, and treatment plan.
For patients whose concern is primarily related to the underlying shape of the jawbone, filler may provide only a limited degree of enhancement. During consultation, the practitioner can explain what level of improvement is realistically achievable through injectable treatment.
Can Radiesse Help With Jawline Laxity?
Mild laxity may contribute to a less defined jawline. By supporting selected areas and potentially stimulating collagen production, Radiesse may improve the appearance of firmness and contour in appropriate patients.
However, significant loose or excess skin cannot be removed with an injectable filler. Patients with advanced laxity may require other procedures designed specifically to address excess tissue and more substantial lifting needs.
When Will Results Become Visible?
Some jawline definition may be noticeable soon after treatment because Radiesse can provide immediate structural support. However, temporary swelling or redness may make the early appearance different from the eventual result.
As the treatment area settles, the contour can become easier to evaluate. The collagen response develops more gradually, so additional changes in firmness and skin support may become apparent over the following weeks and months.
How Long Can Jawline Results Last?
Radiesse is not a permanent treatment, but its effects can be long-lasting. The initial filler effect gradually changes as the body processes the product, while the collagen response may continue to provide some support.
Longevity varies from person to person and can be influenced by factors such as metabolism, age, lifestyle, skin condition, treatment area, and injection technique. Follow-up assessments can help determine whether additional treatment is appropriate.
What Is Recovery Like?
Patients may experience temporary swelling, redness, tenderness, or bruising after jawline injections. These effects generally improve as the treatment area settles. Following the practitioner's specific aftercare instructions can help support a comfortable recovery.
Patients should avoid unnecessary pressure or manipulation of the treated areas unless instructed otherwise. Any unusual, severe, or worsening symptoms should be promptly evaluated by a qualified medical professional.
How Can Patients Maintain Natural-Looking Results?
Natural-looking jawline enhancement depends heavily on appropriate treatment planning. The goal should be to complement the patient's facial proportions rather than create an exaggerated or overly angular appearance.
A qualified provider may consider the relationship between the jawline, chin, cheeks, and lower face before recommending treatment. Maintaining realistic expectations and following recommended follow-up care can also contribute to a satisfactory outcome.
Why Choose an Experienced Provider?
The jawline contains important anatomical structures, so injectable treatment requires knowledge of facial anatomy and appropriate injection techniques. Provider experience can also influence how naturally the treatment integrates with the patient's existing facial features.
During consultation, patients should discuss their aesthetic goals, medical history, previous filler treatments, medications, allergies, and expectations. They should also ask about possible side effects, recovery, and the anticipated degree of correction.
Is Radiesse Right for Jawline Definition?
Radiesse may be an effective option for selected patients who want to enhance jawline definition without undergoing surgery. Its ability to provide structural support and stimulate collagen may help improve contour, firmness, and lower-face balance.
For people considering Radiesse Filler Injections in Riyadh , suitability depends on facial anatomy, skin laxity, existing jawline structure, and the desired level of definition. A professional consultation can help determine whether Radiesse is the right approach and establish a personalized treatment plan.
Book Your Consultation at Royal Clinic Saudia
If you want a more defined and balanced jawline, Royal Clinic Saudia can help you explore personalized facial contouring options. Schedule a consultation to discuss your goals and learn whether Radiesse may be suitable for enhancing your jawline while maintaining a natural-looking appearance.
PW Consulting: Traffic Signs Market Hits $64.76M in 2025, Projected to Reach $110M by 2032 with 7.75% CAGR
By pmarketresearch, 2026-09-15
Navigating Velocity and Compliance: Strategic Intelligence for the Traffic Signs Market (2026–2032)
Executive Summary: The Imperative for Data-Driven Roadway Infrastructure Planning
As global transportation networks undergo rapid modernization, the traffic signs market stands at a critical intersection of regulatory evolution, material economics, and technological integration. For municipal planners, infrastructure contractors, safety manufacturers, and investment analysts, understanding the directional momentum of this sector is no longer optional—it is a prerequisite for resilient strategic positioning. The latest PW Consulting market intelligence report on the Traffic Signs Market delivers a comprehensive, forward-looking assessment designed to equip decision-makers with the analytical clarity required to navigate the 2026–2032 forecast period with precision. This overview highlights the strategic architecture of the study, demonstrates how macro-level market trajectories inform near-term commercial execution, and outlines the actionable intelligence embedded within our proprietary research framework. Readers seeking complete segmentation matrices, competitive benchmarking metrics, and granular regional demand modeling are directed to the full report, where the complete analytical dataset is systematically deployed.
Macro Trajectory: Decoding the Market's Growth Architecture
The foundational narrative of this analysis is anchored in a rigorous historical reconstruction spanning 2020 through 2025, paired with a structured ten-year projection window extending to 2032. Over the observational baseline, the market demonstrated consistent expansion, moving from an initial revenue benchmark of approximately 44.59 million USD in 2020 to a measured 64.76 million USD by 2025. This historical arc reflects a sector buoyed by sustained public infrastructure investment, iterative safety mandate updates, and incremental modernization of legacy roadway signage networks. Looking ahead, the forecast trajectory projects a continuation of this upward momentum, with annual valuation progressing through 68.75 million USD in 2026 and accelerating toward 109.99 million USD by 2032. Encompassing the full decade, the compound annual growth rate registers at 7.75%, a figure that signals durable underlying demand rather than cyclical speculation.
Traffic Signs Market
For corporate strategists, this trajectory is not merely a numerical projection—it is a diagnostic tool. A sustained mid-to-high single-digit growth environment indicates that procurement cycles, supply chain allocations, and product development pipelines must be calibrated against a market where baseline volume expands organically while competitive differentiation increasingly hinges on compliance readiness, material efficiency, and installation scalability. The report isolates the structural drivers responsible for this velocity, mapping how regulatory standardization, regional infrastructure modernization programs, and shifting public safety priorities converge to shape demand curves. By contextualizing the 7.75% CAGR within operational realities—production lead times, substrate procurement volatility, and contracting agency procurement frameworks—the analysis transforms a high-level statistic into a practical planning instrument. Decision-makers can leverage this framework to align capital deployment, capacity scaling, and market-entry timing without relying on speculative assumptions. The full report unpacks the underlying demand multipliers and scenario-sensitive variables that could accelerate or moderate this trajectory, offering a complete analytical toolkit for long-range portfolio management.
Worldwide Traffic Signal Recognition Market
Regulatory Pressure and Material Economics: The Real-World Dynamics Shaping Procurement
Traffic signage is inherently a compliance-driven ecosystem, and the operational landscape entering 2026 reflects an environment where regulatory precision directly influences manufacturing specifications, procurement eligibility, and end-user adoption patterns. Recent guidance from state-level transportation authorities, including updated retroreflective sheeting requirements for permanent traffic control devices on maintained highways, underscores a sector-wide emphasis on higher-visibility standards, durability benchmarks, and standardized performance thresholds. These mandates do not merely affect sign blank specifications; they ripple through procurement documentation, contractor bidding qualifications, and inventory standardization strategies. Simultaneously, the physical inputs that constitute the market have experienced notable price volatility. Industry tracking data indicates that aluminum, the dominant substrate for the majority of traffic sign blanks, recorded substantial year-over-year price escalation through late 2025, fundamentally altering cost structures for blank manufacturers, fabricators, and system integrators. For procurement officers and pricing strategists, this dual pressure—stricter performance specifications alongside fluctuating raw material economics—creates a complex optimization challenge that demands proactive sourcing diversification, specification alignment, and lifecycle cost modeling.
Within this environment, MUTCD compliance remains the operational backbone for virtually all U.S.-facing manufacturers and system suppliers. Upcoming revisions, including the visibility, placement, and performance expectations embedded in the 11th Edition standards, require that traffic calming systems, dynamic messaging equipment, and static control devices meet stringent functional criteria before qualifying for municipal and departmental procurement pipelines. Companies that integrate compliance validation into their product development cycles—rather than treating it as a post-production checkpoint—secure faster pathway access to government contracts, cooperative purchasing programs, and institutional distributors. The market research report dissects these regulatory dynamics with granular attention to specification transitions, enforcement timelines, and compliance gaps that influence buyer behavior. By mapping how updated sheeting classifications, substrate durability expectations, and standardized placement protocols intersect with actual procurement workflows, the study provides a clear operational roadmap for aligning product portfolios with emerging public-sector requirements. Detailed compliance mapping matrices, procurement eligibility checklists, and material sensitivity analyses are reserved for the complete dataset, ensuring stakeholders can model real-world cost and fulfillment scenarios with precision.
Competitive Positioning and Strategic Differentiation: Mapping the Key Players
The current competitive architecture reflects a mix of established regional manufacturers, specialized safety technology providers, and globally integrated export-focused producers. Leading U.S.-based entities such as RoadTrafficSigns, Eastern Metal Signs and Safety, National Highway Products, and Brimar Industries maintain strong operational footprints by delivering MUTCD/DOT-compliant static signage, custom reflective aluminum blanks, work zone control products, and a broad range of street, speed limit, yield, and parking safety signage. Their market relevance stems from specification alignment, contractor-facing distribution networks, and consistent fulfillment of municipal and departmental standards. Parallel to this traditional manufacturing base, technology-integrated players like Radarsign and SWARCO Traffic are expanding the functional boundaries of roadway signage through dynamic warning solutions, radar-enabled speed awareness platforms, flashing warning sign arrays, RRFB pedestrian crossings, and illuminated or variable-message systems designed for highway corridors and dense urban environments.
Recent operational milestones from 2026 highlight how these players are actively reshaping procurement access and product availability. A notable Sourcewell cooperative purchasing contract awarded to Radarsign in March expanded institutional access to MUTCD-compliant traffic calming and warning solutions for public agencies, effectively shortening procurement cycles and broadening distribution reach for standardized safety systems. That same quarter, the company introduced three new solar-powered flashing warning signs, reinforcing a strategic emphasis on visibility enhancement, energy independence, and reduced installation infrastructure dependency for critical roadway segments. Meanwhile, SWARCO Traffic previewed next-generation sign solutions at the ITS America Conference & Expo in Detroit, signaling continued momentum toward intelligent integration, dynamic message capability, and highway-to-urban deployment versatility. On the international supply side, manufacturers such as JACKWIN demonstrate the scale of cross-border safety signage distribution, maintaining ISO and CE-aligned certifications while exporting road safety products to more than seventy countries. The report's competitive analysis evaluates these operators through product portfolio breadth, compliance positioning, regional reach, procurement channel leverage, and recent commercial developments. Concentration metrics within the broader market indicate a moderately consolidated environment, with the top three and top five operators commanding substantial combined share—an arrangement that encourages both competitive benchmarking and strategic partnership evaluation. Readers requiring complete market share distributions, vendor capability scorecards, and competitive vulnerability mapping will find the full report structured to support precise go-to-market and M&A targeting decisions.
Segmentation Logic and Application Realities: Where Demand Actually Materializes
Understanding how the market distributes across material types, functional applications, and geographic demand centers is essential for manufacturers calibrating production mixes, contractors planning bid strategies, and distributors optimizing inventory positioning. The analysis recognizes that product composition is anchored by a diversified substrate landscape, with metal-based blanks, plastic variants, and composite constructions each serving distinct durability, cost, and deployment requirements. Application-side demand naturally fragments across guidance and directional signage, warning indicators, regulatory control devices, and supplementary sign categories, reflecting the operational hierarchy of road networks and the differing visibility, installation frequency, and replacement cadence associated with each function. Regionally, the demand footprint spans established infrastructure markets and high-growth modernization corridors, where differing procurement models, roadway density, municipal budgeting cycles, and transportation safety mandates shape localized consumption patterns.
Rather than treating segmentation as a static classification exercise, the report maps each segment to its underlying demand triggers. Metal-based signage continues to anchor high-visibility, long-duration deployments where regulatory durability and retroreflective performance are paramount. Plastic and composite alternatives serve specialized use cases where weight reduction, rapid deployment, or specific environmental resistance profiles are prioritized. On the application axis, directional and guidance infrastructure maintains broad utility across highway systems and municipal networks, while warning and regulatory categories respond directly to safety initiative funding, accident-reduction programs, and intersection optimization projects. The geographic distribution reflects a balance between mature procurement ecosystems and developing infrastructure investment tracks, with demand intensity influenced by corridor redevelopment priorities, cooperative purchasing adoption, and cross-border safety standardization efforts. This segmentation framework is designed to help stakeholders identify which product mixes align with specific procurement environments, how application-level replacement cycles affect recurring revenue opportunities, and which regional pipelines present the strongest near-term penetration potential. Comprehensive segment sizing, cross-segment interaction modeling, and region-specific procurement behavior analysis are fully developed in the complete report.
Outlook for 2026 Decision-Making: Translating Forecast Intelligence into Execution
The 2026–2032 horizon is best approached as a planning continuum rather than a static forecast window. Manufacturers and suppliers entering this period must synchronize production planning with evolving sheeting specifications, substrate cost trajectories, cooperative procurement timelines, and intelligent infrastructure pilot programs. Contractors and installation firms require visibility into which sign categories will see accelerated specification upgrades, which public agencies will prioritize solar or energy-independent warning solutions, and where compliance transitions will trigger replacement demand. Investors and strategic acquirers benefit from understanding which operational profiles—compliance agility, regional distribution density, dynamic-message capability, or export certification breadth—are most likely to capture margin expansion in a market growing at a sustainable mid-to-high single-digit rate.
The PW Consulting report translates these strategic questions into actionable intelligence. It provides a structured evaluation of procurement pathways, regulatory timelines, product development alignment, and competitive positioning, enabling organizations to convert market momentum into executable plans. Scenario-sensitive analysis, material cost sensitivity frameworks, compliance transition mapping, and vendor capability assessments are embedded throughout the study to support both near-term procurement decisions and multi-year capital planning. For stakeholders responsible for market entry, capacity expansion, partnership formation, or product portfolio optimization, the full report delivers the complete analytical architecture necessary to reduce uncertainty and sharpen execution.
Access the Full Intelligence: Complete Data, Segmentation, and Competitive Mapping
This overview has outlined the strategic contours of the Traffic Signs Market, highlighted the macro trajectory, contextualized the regulatory and material dynamics, introduced the competitive players shaping the sector, and mapped the segmentation logic that underpins real-world demand. Yet the complete decision-making toolkit—detailed historical reconstruction, full forecast breakdowns, comprehensive segmentation matrices, region-specific procurement behavior, competitive capability scorecards, concentration analysis, and scenario modeling—resides in the full market research publication. For executives, procurement leaders, product strategists, and investment professionals who require precise, auditable intelligence to guide 2026 planning and beyond, the complete report provides the depth, structure, and operational relevance necessary to act with confidence. To access the full dataset and deploy the complete strategic framework, explore the complete PW Consulting Traffic Signs Market research release.
For detailed analysis of this topic, please visit the official page: Traffic Signs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Class 1E Nuclear Instrumentation Cables Market to Hit $49.8M by 2032 at 3.6% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for 2026: Navigating the Class 1E Nuclear Power Plant Instrumentation Cables Market
The nuclear energy sector stands at a pivotal juncture in 2026. As nations accelerate decarbonization agendas and extend the operational licenses of existing fleets, the demand for safety-critical infrastructure has never been more acute. Within this ecosystem, Class 1E instrumentation cables represent the nervous system of nuclear power plants, ensuring the integrity of data transmission, monitoring, and control in radiation-intensive and high-temperature environments. For stakeholders, investors, and procurement leaders, understanding the trajectory of this specialized market is not merely an academic exercise; it is a prerequisite for resilient strategic planning.
Our latest market research report, Class 1E Nuclear Power Plant Instrumentation Cables Market Outlook 2026-2032 , offers a comprehensive dissection of this high-stakes industry. This article serves as a strategic preview, highlighting the macro-economic currents and competitive dynamics that define the landscape, while demonstrating the depth of analysis available to clients who secure the full report.
Market Trajectory and Growth Catalysts
The global market for Class 1E instrumentation cables has demonstrated steady, resilient growth over the past half-decade, reflecting the inertia and long-term commitments inherent in nuclear infrastructure projects. Based on historical data from 2020 through 2025, the market has evolved from a baseline of approximately 31.51 million USD to an estimated 38.25 million USD in the base year of 2025. This progression underscores a consistent upward trend driven by plant life extensions, regulatory upgrades, and the commissioning of new units globally.
Class 1E Nuclear Power Plant Instrumentation Cables Market
Looking forward, the forecast period from 2026 to 2032 projects a compound annual growth rate (CAGR) of 3.6 percent. By 2032, the market revenue is anticipated to reach nearly 49.8 million USD. While these top-line figures indicate stability, the underlying drivers are complex. The growth is not uniform; it is segmented by the type of cable, the specific application within the plant, and the geographic region, each influenced by distinct regulatory and operational pressures.
Key Growth Drivers
Several macro-factors are converging to support this positive outlook:
- Plant Life Extensions: Many existing nuclear facilities are pursuing license renewals extending operations to 60 years or more. This necessitates the replacement or upgrading of instrumentation cables that have reached the end of their original design life, creating a sustained aftermarket demand.
- Safety Regulation Tightening: Global regulatory bodies, including the U.S. Nuclear Regulatory Commission (NRC), continue to enforce stringent standards such as IEEE 383-2003 for qualifying safety-related cables. Compliance drives replacements and ensures that new builds utilize qualified products, reinforcing the market for certified manufacturers.
- Small Modular Reactor (SMR) Development: The emerging SMR sector presents a new avenue for cable demand. While volumes are currently smaller than large-scale Light Water Reactors (LWRs), the specialized requirements for compact, safety-grade instrumentation create niche opportunities for qualified suppliers.
- Decarbonization Policies: Government incentives for clean energy in North America, Europe, and parts of Asia are revitalizing nuclear investment, indirectly bolstering the supply chain for critical components like Class 1E cables.
Competitive Landscape: A Consolidated Arena
The Class 1E nuclear cable market is characterized by high barriers to entry. Qualification processes are rigorous, involving extensive environmental testing, radiation resistance verification, and compliance with codes such as 10 CFR 50.49 and IEEE 323. Consequently, the market exhibits notable concentration. Our analysis indicates that the top three companies command a significant share of the market revenue, while the top five firms collectively hold a majority of the market presence. This consolidation suggests that supply chain security and vendor qualification are critical considerations for plant operators.
Profiles of Industry Leaders
The competitive field is dominated by established players with decades of experience in nuclear-grade manufacturing. Our report provides detailed profiling of key entities shaping the market dynamics:
Mineral Insulated Cables Market
- Prysmian (Italy): A global leader in cable systems, Prysmian offers the ULTROL 60+ Class 1E instrumentation cables. These 600V multiconductor cables are designed for monitoring and data transmission within safety-critical circuits. They are fully qualified to IEEE 323, IEEE 383, and 10 CFR 50.49 for Loss of Coolant Accident (LOCA) and High Energy Line Break (HELB) environments, supporting a 60+ year service life. Notably, their nuclear cables are DecaBDE-free, complying with US EPA prohibitions, reflecting a commitment to environmental standards alongside safety.
- Marmon IEI (United States): With installations in over 130 nuclear plants worldwide, Marmon IEI specializes in radiation-resistant LDVC, control, and instrumentation cables, including their proprietary RSCC® brand. Their designs meet 60-year life expectancy requirements and adhere to IEEE and LOCA standards. Manufacturing is conducted under a 10 CFR Appendix B, NQA-1 quality program, ensuring rigorous quality assurance throughout the production lifecycle.
- Shawflex (Canada): Shawflex manufactures EQ/Class 1E nuclear-grade power, control, and instrumentation cables and assemblies tailored for CANDU, LWR, and SMR plants. Their products are qualified to IEEE 323, IEEE 383, and CSA N290.13, capable of withstanding up to 250 Mrad/200°C with a 60-year life expectancy. Their compliance with Canadian and international standards positions them strongly in both domestic and export markets.
- Habia Cable (Sweden): Habia supplies Habiatron™ LOCA and non-LOCA Class 1E instrumentation cables, including thermocouple types, critical for reactor coolant pumps, safety valves, and control rod positioning. Designed for a 60-year operational life in nuclear safety systems, Habia emphasizes durability and precision in hazardous environments.
- Okonite Company (United States): Okonite provides Okoguard and FMR-N Class 1E nuclear power, control, and instrumentation cables. These products are qualified per IEEE 383 and 10 CFR 50.49 for safety-related applications in nuclear generating stations, reinforcing Okonite's role in the North American supply chain for safety-critical infrastructure.
The strategic implications of this landscape are profound. For procurement managers, relying on qualified suppliers is non-negotiable. For investors, the high concentration suggests that market share gains are difficult but valuable. Our full report delves deeper into the strategic moves, capacity expansions, and partnership networks of these key players.
Market Segmentation and Regional Nuances
Understanding where demand originates is as vital as knowing how much demand exists. The market is segmented by cable type, application location, and geography, each presenting unique opportunities and challenges.
Segmentation by Type and Application
The market is broadly divided into Nuclear Island Cables and Conventional Island Cables. The Conventional Island segment currently represents a larger portion of the market value, reflecting the extensive instrumentation required for turbine control, secondary systems, and general plant monitoring. However, Nuclear Island Cables, which operate within the containment building, command premium pricing due to the extreme conditions they must withstand, including high radiation fields and potential LOCA scenarios.
From an application perspective, instrumentation is deployed both Inside the Reactor and Outside the Reactor. Inside the Reactor applications involve the most stringent safety requirements, critical for core monitoring and control rod positioning. Outside the Reactor applications cover a broader range of safety and non-safety systems, including coolant pumps and safety valves. The balance between these segments shifts based on plant age, upgrade cycles, and specific design characteristics of the reactor types in operation.
Regional Dynamics
Geography plays a defining role in market distribution. North America remains a dominant force in this sector, driven by a large existing fleet of nuclear plants, ongoing life extension programs, and a robust regulatory framework that mandates high-quality instrumentation. The region's emphasis on energy security and clean baseload power supports continued investment in nuclear infrastructure.
Europe follows as a significant market, with countries such as France and Sweden maintaining strong nuclear capabilities. European initiatives to classify nuclear as sustainable under taxonomy rules have stimulated interest in long-term infrastructure stability. Meanwhile, the Asia Pacific region, while currently representing a smaller share of the total market value compared to North America and Europe, holds substantial potential. Growth in China, India, and South Korea, along with emerging interest in SMR technologies, suggests that the regional dynamic may evolve over the forecast period. Latin America and the Mideast and Africa regions contribute to the global total, though their shares are comparatively modest, often tied to specific national nuclear programs or lifecycle extensions of legacy plants.
Detailed regional revenue splits and growth rates are essential for tailoring market entry strategies or investment decisions. These granular insights are fully elaborated in our comprehensive report.
Regulatory and Compliance Landscape
In the Class 1E market, regulation is not just a constraint; it is a market shaper. Compliance with standards such as IEEE 383-2003 for qualifying safety-related cables and field splices is mandatory for operation in nuclear power generating stations. Manufacturers must demonstrate that their products can survive design-basis accidents and maintain functionality throughout the plant's life.
Recent industry context highlights the importance of these standards. For instance, Prysmian's ULTROL 60+ cables are environmentally qualified per 10 CFR 50.49, IEEE 323, and IEEE 383, setting a benchmark for qualification rigor. Similarly, Shawflex's compliance with IEEE 323 and CSA N290.13 ensures suitability for Canadian and international deployments. Marmon IEI's adherence to NQA-1 quality programs underscores the systemic approach required to maintain certification.
Furthermore, environmental regulations are increasingly intersecting with nuclear procurement. The US EPA prohibition on DecaBDE, for example, affects cable formulations. Prysmian's DecaBDE-free nuclear cables illustrate how manufacturers are adapting to regulatory shifts without compromising performance. This convergence of safety and environmental compliance adds layers of complexity that favor experienced, well-resourced suppliers.
Strategic Implications for Stakeholders in 2026
For corporate strategy teams, the Class 1E instrumentation cables market offers several actionable insights:
- Supply Chain Resilience: Given the market concentration and high qualification barriers, diversifying suppliers without compromising certification status is a key challenge. Strategic partnerships with multiple qualified vendors can mitigate risk but require careful management of technical compatibility.
- Lifecycle Planning: Plant operators must integrate cable replacement schedules into broader asset management plans. With many cables designed for 60-year lives, understanding the degradation profiles and replacement lead times is critical for avoiding unplanned outages.
- Investment in Qualification: For cable manufacturers, obtaining and maintaining qualifications such as IEEE 323 and 10 CFR 50.49 is a long-term investment that creates a moat. Companies that can streamline qualification processes or demonstrate superior performance in LOCA/HELB environments gain a competitive edge.
- SMR and New Build Opportunities: As SMRs move toward commercialization, early engagement with qualification bodies and standard-setting organizations can position suppliers to capture first-mover advantages in this nascent segment.
- Regional Strategy: Companies looking to expand should prioritize regions with active nuclear programs and supportive regulatory environments. North America and Europe offer mature markets with steady demand, while Asia Pacific presents growth potential contingent on policy execution and project timelines.
Why This Report is Essential for 2026 Decision-Making
The Class 1E Nuclear Power Plant Instrumentation Cables Market Outlook 2026-2032 is more than a data collection; it is a strategic tool designed to inform critical decisions. In an industry where margins are tight, regulations are strict, and failure is not an option, having access to precise, verified intelligence is paramount.
Our report provides:
- Granular Segmentation Data: Detailed revenue breakdowns by region, type, and application, enabling targeted market sizing and opportunity assessment.
- Competitive Intelligence: In-depth profiles of key companies, including product portfolios, qualification statuses, and strategic positioning.
- Regulatory Analysis: Up-to-date coverage of standards and compliance requirements, helping stakeholders navigate the evolving regulatory landscape.
- Forward-Looking Scenarios: Forecast models that account for variables such as plant closures, new builds, and policy shifts, offering a range of potential outcomes.
- Qualitative Insights: Expert commentary on industry trends, challenges, and emerging technologies that data alone cannot capture.
For executives, procurement managers, investors, and policymakers, the ability to anticipate market shifts and identify credible partners can define success. The data presented in this preview hints at the robust analysis available in the full report. However, to make informed decisions, one must access the complete intelligence package.
Conclusion
The Class 1E nuclear instrumentation cables market is a testament to the enduring importance of safety and reliability in the nuclear energy sector. As we move through 2026, the convergence of plant life extensions, regulatory rigor, and new build momentum creates a stable yet dynamic environment for growth. The market's structure, dominated by qualified specialists and shaped by stringent standards, rewards those who prioritize quality and compliance.
Our comprehensive market research equips stakeholders with the knowledge needed to navigate this complex landscape. From detailed regional analysis to competitive profiling and regulatory tracking, the report provides the depth required for strategic excellence. We invite you to explore the full report to unlock the complete set of insights and make confident, data-driven decisions for the years ahead.
For detailed analysis of this topic, please visit the official page: Class 1E Nuclear Power Plant Instrumentation Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reprocessed Medical Device Market Hits $1.55B in 2025, Projects 16.98% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence Briefing: The Reprocessed Medical Device Market Outlook 2026-2032
Executive Summary: Navigating a High-Growth Sustainability Shift
The global healthcare sector is undergoing a fundamental transformation driven by the dual imperatives of cost containment and environmental sustainability. Within this landscape, the reprocessed medical device market stands out as a critical frontier for strategic investment and operational optimization. Our latest market research provides a comprehensive analysis of this sector, projecting a robust compound annual growth rate of 16.98 percent from 2026 through 2032. This growth trajectory signals more than just incremental change; it indicates a structural shift in how healthcare providers acquire and manage single-use devices.
For corporate strategists, procurement leaders, and investors, understanding the nuance of this market is no longer optional. The data indicates that the market size, valued at approximately 1.55 billion USD in the base year 2025, is expected to surge significantly over the forecast period. By 2032, the revenue landscape is projected to expand into the multi-billion range, reflecting increasing adoption rates across diverse medical specialties. This briefing outlines the strategic value of our new report, designed to equip decision-makers with the actionable intelligence needed to navigate this evolving ecosystem without exposing the organization to unnecessary regulatory or financial risk.
Market Trajectory and Macro-Economic Drivers
The historical performance of the reprocessed medical device sector demonstrates consistent resilience and expansion. Analysis of historical data from 2020 to 2025 reveals a steady upward trend, with revenue climbing from under 1 billion USD to 1.55 billion USD. This growth was not merely a reaction to economic pressure but a result of validated clinical outcomes and regulatory frameworks that have matured over the last half-decade.
Looking forward, the forecast period from 2026 to 2032 suggests an acceleration in market velocity. The projected jump in market size from the base year to the early forecast years indicates that penetration rates are moving from early adopters to mainstream healthcare providers. This expansion is underpinned by several key dynamics. First, the regulatory environment is becoming more defined, with specific pathways for clearance becoming better understood by manufacturers and reprocessors alike. Second, the economic pressure on hospital systems continues to drive demand for cost-effective alternatives that do not compromise patient safety. Third, environmental, social, and governance (ESG) goals are pushing healthcare organizations to reduce medical waste, making reprocessing an attractive component of sustainability portfolios.
Our report dissects these macro trends to provide a clear picture of market momentum. We analyze how revenue units in millions USD are distributed across the forecast horizon, offering a granular view of expected growth phases. This allows stakeholders to time their market entry or expansion strategies corresponding with peak growth periods. Understanding the shift from historical stability to forecasted acceleration is crucial for capital allocation and long-term planning.
Competitive Landscape and Key Player Strategies
The market is characterized by a mix of specialized reprocessors, major original equipment manufacturers (OEMs) with sustainability divisions, and large-scale distributors. Our research identifies critical competitors who are shaping the industry standards. Companies such as Innovative Health, SureTek Medical, Stryker, Medtronic, Cardinal Health, STERIS, NEScientific, ReNu Medical, and Vanguard AG are actively competing for market share. Each employs distinct strategies ranging from specialized FDA-cleared reprocessing of specific device categories to broad sustainability portfolios offered by major conglomerates.
Strategic differentiation is key in this crowded field. For instance, some players focus heavily on electrophysiology and cardiology devices, achieving significant regulatory milestones. Others target ambulatory surgery centers with closed-loop reprocessing programs aimed at supply chain efficiency. Major OEMs leverage their existing distribution networks and sustainability divisions to offer remanufactured solutions alongside new devices. Understanding the positioning of these key companies is vital for identifying partnership opportunities or assessing competitive threats.
Reprocessed Medical Device Market
Recent developments highlight the dynamic nature of this competition. In early 2026, a leading reprocessor achieved a significant regulatory milestone, securing its 50th FDA clearance for a specific steerable introducer, marking it as the only reprocessor cleared for that device. This kind of regulatory exclusivity creates high barriers to entry and defines market leaders. Furthermore, strategic partnerships, such as collaborations between sterilization providers and sales entities, are enhancing surgical service workflows in sterile processing departments. These moves indicate a trend toward integration and service optimization rather than mere product transaction. Our report details these competitive maneuvers to help you benchmark your strategy against industry standards.
Regulatory Frameworks and Reimbursement Dynamics
The regulatory landscape is the backbone of market viability. All FDA-regulated reprocessing of single-use devices is performed by commercial reprocessors or hospitals acting as manufacturers. This status requires strict compliance with Quality System Regulations and specific 510(k) clearances for each device type. The necessity for specific validation for cleaning, inspection, and function testing means that regulatory clearance is not generic but device-specific. This complexity creates a protective moat for established players and dictates the pace at which new devices can enter the reprocessed market.
Reimbursement policies further influence adoption rates. Reprocessed single-use medical devices cleared by the FDA are eligible for Medicare reimbursement under Part B on the same terms as non-reprocessed devices. This parity is a critical driver for hospital adoption, as it removes the financial disincentive for choosing reprocessed options. However, navigating the billing and compliance requirements remains a complex task for healthcare providers. Our analysis delves into the intricacies of these reimbursement structures, ensuring that financial modeling accounts for regulatory realities.
Additionally, regional regulatory shifts are opening new avenues for growth. For example, recent updates in certain European jurisdictions have legalized reprocessing to advance sustainable healthcare practices. Such regulatory changes expand the addressable market and require stakeholders to adjust their compliance strategies accordingly. The report provides a detailed overview of these regulatory nuances, helping organizations anticipate changes that could impact market access or operational compliance.
Operational Cost Structure and Efficiency
One of the most compelling value propositions for reprocessed devices is cost reduction. However, the economics of reprocessing are nuanced. The process includes cleaning, disinfection, and testing, which incurs specific operational costs. Industry data suggests that medical device reprocessing costs facilities approximately 0.34 to 0.47 USD per instrument in a tray, or 0.81 to 0.84 USD in a peel pack. While these figures represent a fraction of the cost of new single-use devices, the total cost of ownership includes logistics, validation, and quality assurance.
Facilities must weigh these operational costs against the savings gained from purchasing reprocessed units. The efficiency of the reprocessing loop depends heavily on workflow integration within sterile processing departments. Strategic partnerships are increasingly focused on enhancing these workflows to minimize turnaround times and maximize throughput. Our research evaluates these cost structures in depth, providing benchmarks that allow healthcare administrators to perform accurate cost-benefit analyses. By understanding the granular cost drivers, organizations can negotiate better terms and optimize their procurement mix between new and reprocessed devices.
Worldwide Medical Device Reprocessing Market
Segmentation Opportunities and Growth Vectors
The market is multifaceted, with growth distributed across various device types, applications, and regions. While the overall market size tells a story of expansion, the underlying segmentation reveals where the most significant opportunities lie. Different device categories, such as cardiovascular, laparoscopic, orthopedic, and gastroenterology devices, exhibit varying levels of reprocessing viability and adoption. Similarly, application areas ranging from cardiology and general surgery to orthopedic surgery and gynecology show distinct demand patterns based on procedure volumes and device complexity.
Geographic dynamics also play a crucial role. Established markets in North America and Europe currently hold significant share, but emerging regions are showing increasing potential as regulatory frameworks mature and cost pressures intensify. The concentration of market revenue among top players indicates a competitive environment where market share gains require strategic precision. Our report segments the market comprehensively, revealing high-growth vectors that are otherwise obscured in aggregate data. By analyzing the splits across region, type, and application, stakeholders can identify niche opportunities that align with their specific capabilities or product portfolios. We provide the framework to understand which segments are mature and which are poised for disruption.
Value of the Full Report for 2026 Decision-Making
In an environment defined by rapid regulatory change and economic pressure, relying on high-level estimates is insufficient for strategic planning. The full version of this market research report offers the depth required for confident decision-making. It goes beyond the macro trends discussed here to provide detailed quantitative analysis, precise segmentation data, and extensive competitor profiling. The report serves as a foundational document for strategic planning, investment thesis development, and operational benchmarking.
Specifically, the report enables you to quantify the revenue potential in millions USD across the forecast period with greater precision. It offers insights into the specific competitive moves of key companies, allowing you to anticipate market shifts before they become obvious. The analysis of regulatory and reimbursement factors provides a compliance roadmap that mitigates risk. Furthermore, the breakdown of cost structures and segmentation splits allows for targeted strategy formulation, whether you are looking to enter the market, expand existing operations, or invest in relevant technologies.
To access the complete dataset, including specific regional valuations, detailed segmentation percentages, and proprietary competitor analysis, we invite you to explore the full report. The information contained within is designed to transform uncertainty into actionable strategy. Secure your organization's position in the growing reprocessed medical device market by leveraging the comprehensive intelligence provided in our latest study. Detailed tables, regional breakdowns, and specific growth drivers are available in the full documentation, ensuring you have the complete picture required for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Reprocessed Medical Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pneumococcal Vaccine Market Hits $9.38B in 2025, Projected 5.3% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Intelligence for the Global Pneumococcal Vaccination Market Through 2032
The global pneumococcal vaccination landscape is entering a decisive inflection point. As healthcare systems worldwide recalibrate immunization priorities, pricing architectures, and supply chain resilience, market participants require more than headline figures to navigate the coming years. PW Consulting has compiled a comprehensive strategic assessment of the Pneumococcal Vaccination Market, designed specifically to equip leadership teams, portfolio strategists, and commercial planners with actionable intelligence for 2026 and beyond. This report translates multi-year epidemiological shifts, regulatory momentum, and competitive realignments into a decision-ready framework that aligns directly with enterprise planning cycles.
Why 2026 Demands a Refined Strategic Lens
Over the past half-decade, the pneumococcal vaccine sector has demonstrated steady commercial expansion, with global revenue climbing from approximately 7,351.69 million USD in 2020 to an estimated 9,384.98 million USD in 2025. The trajectory through the forecast horizon reflects a compound annual growth rate of 5.3 percent, positioning the industry to surpass 10,203.2 million USD in 2026 and continue its upward arc toward 13,256.13 million USD by 2032. These figures are not merely retrospective markers; they represent a structural recalibration of how governments, payers, and manufacturers approach pneumococcal disease prevention across age cohorts and income tiers.
For executives mapping 2026 investments, the critical question is no longer whether demand will expand, but where value will concentrate and which operational capabilities will separate long-term winners from marginal participants. Our analysis isolates the underlying drivers behind this growth curve: updated national immunization schedules, broader adult indications, tiered pricing mechanisms, and the gradual maturation of regional manufacturing capacity. The report details how these forces intersect with reimbursement frameworks, cold-chain constraints, and formulation differentiation, enabling teams to stress-test their commercial assumptions against realistic market conditions rather than speculative narratives.
Decoding Market Architecture: Segmentation, Pricing Tiers, and Demand Channels
A robust strategy begins with a clear understanding of how demand fragments across formulations, patient populations, and geographic corridors. The research evaluates the commercial weight of pneumococcal conjugate vaccines relative to polysaccharide-based alternatives, while mapping application pathways across pediatric and adult immunization programs. Rather than presenting static percentage breakdowns, the report constructs comparative demand profiles that reveal how clinical guidelines, procurement cycles, and public-private funding models shape purchasing behavior in each channel.
Pricing architecture remains one of the most consequential variables for market positioning. The analysis examines the stark divergence between high-income private-market valuations and subsidized procurement channels in lower- and middle-income economies, illustrating how tiered pricing, volume commitments, and external financing mechanisms influence margin expectations and rollout pacing. By modeling these dynamics alongside procurement timelines and tender calendars, the report equips commercial teams to anticipate contract negotiations, forecast uptake velocity, and calibrate manufacturing output without overcommitting to rigid volume assumptions.
Competitive Dynamics: Portfolio Positioning, Development Pipelines, and Capacity Plays
The incumbent landscape remains highly concentrated, with a small group of multinational developers and specialized regional manufacturers commanding the majority of commercial value. The report examines how established players are leveraging broadened valency portfolios to defend market share while simultaneously integrating new indications across age groups. At the same time, emerging manufacturers are pursuing differentiated strategies ranging from WHO prequalification pathways to localized production agreements that reduce dependency on imported supply.
Recent corporate developments underscore how quickly competitive positioning can shift. In early 2025, a strategic manufacturing partnership was formalized to enable local production of a conjugate formulation in Argentina, anchored by regional procurement mechanisms and distribution support. Shortly thereafter, a major developer received a positive regulatory opinion in Europe for an expanded adult-focused conjugate vaccine, signaling intensifying competition in the mature demographics segment. By the start of 2026, another participant announced a dedicated North American facility expansion with a custom fill-finish line optimized for conjugate vaccine production, reflecting a broader industry emphasis on supply chain sovereignty and regional capacity redundancy. Most recently, a leading multinational initiated a Phase 3 pediatric program for a higher-valent candidate, reinforcing the long-cycle innovation race that will shape formulation standards well into the next decade.
These events are analyzed not as isolated announcements but as structural signals. The report maps each development against implications for pricing pressure, tender competitiveness, geographic coverage, and pipeline whitespace. Readers gain a practical view of where incumbents are fortifying defensive positions, where new entrants are attempting to dislodge legacy products, and which strategic levers—such as valency upgrades, manufacturing localization, or public-sector collaboration—offer the highest probability of durable advantage.
Operational Realities: Cold Chain, Reimbursement, and Procurement Mechanics
Commercial success in the pneumococcal vaccine market depends heavily on operational execution. All conjugate formulations require disciplined cold-chain management, maintaining temperatures between 2 and 8 degrees Celsius while tolerating limited thermal exposure under defined stability conditions. The report integrates these logistical constraints into broader supply planning scenarios, highlighting how temperature-sensitive distribution influences inventory turnover, last-mile delivery costs, and regional rollout feasibility. For manufacturers and distributors alike, understanding these parameters is essential to avoid stock disruptions, manage expiry risk, and align production schedules with procurement windows.
Reimbursement architecture presents an equally critical strategic variable. In key mature markets, public coverage programs reimburse pneumococcal vaccines based on standardized pricing benchmarks with geographically adjusted payment rates, creating predictable but administratively complex revenue flows. The analysis examines how these reimbursement pathways interact with private-sector procurement, adult immunization uptake, and provider adoption incentives. By connecting payment mechanics to real-world utilization patterns, the report helps commercial teams model net revenue outcomes more accurately and identify which market segments offer the most favorable balance of volume, margin, and implementation friction.
What the Report Delivers: Decision-Ready Intelligence for 2026 Planning
This assessment is structured to support multiple internal functions simultaneously. Strategic planning teams will find scenario-based growth pathways that connect epidemiological priorities with procurement timelines and pricing evolution. Commercial leaders receive formulation-level demand signals, competitive response matrices, and regional rollout considerations that inform sales targeting, tender preparation, and partnership evaluation. Supply chain and operations stakeholders gain insight into capacity trends, cold-chain requirements, and manufacturing localization patterns that influence sourcing decisions and risk mitigation.
Pneumococcal Vaccination Market
The report is organized around practical deployment rather than abstract observation. Core components include:
- A multi-year market trajectory analysis linking historical performance to forecast conditions across the 2026 to 2032 horizon
- Formulation and application demand profiles that clarify where commercial emphasis is shifting and why
- A competitive landscape evaluation covering portfolio scope, regional footprint, developmental activity, and capacity investments
- An operational dynamics section addressing cold-chain constraints, reimbursement structures, pricing dispersion, and procurement mechanisms
- Scenario planning guidance that helps leadership teams test assumptions around uptake velocity, tender outcomes, and geographic expansion
Every section is designed to feed directly into internal decision processes, from annual operating plans and R&D prioritization to market-entry evaluations and partnership strategy. Rather than offering isolated statistics, the analysis connects data points to strategic consequences, enabling teams to translate market intelligence into concrete next steps.
Worldwide Multivalent Pneumococcal Conjugate Vaccine Market
Turning Intelligence into Actionable Advantage
The pneumococcal vaccination market will continue to reward participants who combine scientific understanding with execution discipline. Growth will not be distributed evenly across formulations, age groups, or geographies. Value will accumulate where organizations can align product strategy with procurement realities, maintain supply reliability under logistical constraints, and anticipate reimbursement shifts before they affect negotiation leverage. In this environment, timely and structured intelligence is not optional; it is a competitive prerequisite.
PW Consulting’s Pneumococcal Vaccination Market research provides the depth, structure, and forward-looking context required to make informed choices in 2026 and throughout the forecast period. The full report contains the complete segmentation architecture, competitive profiling, regional demand mapping, and operational scenario frameworks necessary to build durable market strategies. To access the comprehensive intelligence package and integrate these findings into your planning cycle, visit the source page for the complete study.
For detailed analysis of this topic, please visit the official page: Pneumococcal Vaccination Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com