

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Traffic Signs Market Hits $64.76M in 2025, Projected to Reach $110M by 2032 with 7.75% CAGR

Navigating Velocity and Compliance: Strategic Intelligence for the Traffic Signs Market (2026–2032)
Executive Summary: The Imperative for Data-Driven Roadway Infrastructure Planning
As global transportation networks undergo rapid modernization, the traffic signs market stands at a critical intersection of regulatory evolution, material economics, and technological integration. For municipal planners, infrastructure contractors, safety manufacturers, and investment analysts, understanding the directional momentum of this sector is no longer optional—it is a prerequisite for resilient strategic positioning. The latest PW Consulting market intelligence report on the Traffic Signs Market delivers a comprehensive, forward-looking assessment designed to equip decision-makers with the analytical clarity required to navigate the 2026–2032 forecast period with precision. This overview highlights the strategic architecture of the study, demonstrates how macro-level market trajectories inform near-term commercial execution, and outlines the actionable intelligence embedded within our proprietary research framework. Readers seeking complete segmentation matrices, competitive benchmarking metrics, and granular regional demand modeling are directed to the full report, where the complete analytical dataset is systematically deployed.
Macro Trajectory: Decoding the Market's Growth Architecture
The foundational narrative of this analysis is anchored in a rigorous historical reconstruction spanning 2020 through 2025, paired with a structured ten-year projection window extending to 2032. Over the observational baseline, the market demonstrated consistent expansion, moving from an initial revenue benchmark of approximately 44.59 million USD in 2020 to a measured 64.76 million USD by 2025. This historical arc reflects a sector buoyed by sustained public infrastructure investment, iterative safety mandate updates, and incremental modernization of legacy roadway signage networks. Looking ahead, the forecast trajectory projects a continuation of this upward momentum, with annual valuation progressing through 68.75 million USD in 2026 and accelerating toward 109.99 million USD by 2032. Encompassing the full decade, the compound annual growth rate registers at 7.75%, a figure that signals durable underlying demand rather than cyclical speculation.
Traffic Signs Market
For corporate strategists, this trajectory is not merely a numerical projection—it is a diagnostic tool. A sustained mid-to-high single-digit growth environment indicates that procurement cycles, supply chain allocations, and product development pipelines must be calibrated against a market where baseline volume expands organically while competitive differentiation increasingly hinges on compliance readiness, material efficiency, and installation scalability. The report isolates the structural drivers responsible for this velocity, mapping how regulatory standardization, regional infrastructure modernization programs, and shifting public safety priorities converge to shape demand curves. By contextualizing the 7.75% CAGR within operational realities—production lead times, substrate procurement volatility, and contracting agency procurement frameworks—the analysis transforms a high-level statistic into a practical planning instrument. Decision-makers can leverage this framework to align capital deployment, capacity scaling, and market-entry timing without relying on speculative assumptions. The full report unpacks the underlying demand multipliers and scenario-sensitive variables that could accelerate or moderate this trajectory, offering a complete analytical toolkit for long-range portfolio management.
Worldwide Traffic Signal Recognition Market
Regulatory Pressure and Material Economics: The Real-World Dynamics Shaping Procurement
Traffic signage is inherently a compliance-driven ecosystem, and the operational landscape entering 2026 reflects an environment where regulatory precision directly influences manufacturing specifications, procurement eligibility, and end-user adoption patterns. Recent guidance from state-level transportation authorities, including updated retroreflective sheeting requirements for permanent traffic control devices on maintained highways, underscores a sector-wide emphasis on higher-visibility standards, durability benchmarks, and standardized performance thresholds. These mandates do not merely affect sign blank specifications; they ripple through procurement documentation, contractor bidding qualifications, and inventory standardization strategies. Simultaneously, the physical inputs that constitute the market have experienced notable price volatility. Industry tracking data indicates that aluminum, the dominant substrate for the majority of traffic sign blanks, recorded substantial year-over-year price escalation through late 2025, fundamentally altering cost structures for blank manufacturers, fabricators, and system integrators. For procurement officers and pricing strategists, this dual pressure—stricter performance specifications alongside fluctuating raw material economics—creates a complex optimization challenge that demands proactive sourcing diversification, specification alignment, and lifecycle cost modeling.
Within this environment, MUTCD compliance remains the operational backbone for virtually all U.S.-facing manufacturers and system suppliers. Upcoming revisions, including the visibility, placement, and performance expectations embedded in the 11th Edition standards, require that traffic calming systems, dynamic messaging equipment, and static control devices meet stringent functional criteria before qualifying for municipal and departmental procurement pipelines. Companies that integrate compliance validation into their product development cycles—rather than treating it as a post-production checkpoint—secure faster pathway access to government contracts, cooperative purchasing programs, and institutional distributors. The market research report dissects these regulatory dynamics with granular attention to specification transitions, enforcement timelines, and compliance gaps that influence buyer behavior. By mapping how updated sheeting classifications, substrate durability expectations, and standardized placement protocols intersect with actual procurement workflows, the study provides a clear operational roadmap for aligning product portfolios with emerging public-sector requirements. Detailed compliance mapping matrices, procurement eligibility checklists, and material sensitivity analyses are reserved for the complete dataset, ensuring stakeholders can model real-world cost and fulfillment scenarios with precision.
Competitive Positioning and Strategic Differentiation: Mapping the Key Players
The current competitive architecture reflects a mix of established regional manufacturers, specialized safety technology providers, and globally integrated export-focused producers. Leading U.S.-based entities such as RoadTrafficSigns, Eastern Metal Signs and Safety, National Highway Products, and Brimar Industries maintain strong operational footprints by delivering MUTCD/DOT-compliant static signage, custom reflective aluminum blanks, work zone control products, and a broad range of street, speed limit, yield, and parking safety signage. Their market relevance stems from specification alignment, contractor-facing distribution networks, and consistent fulfillment of municipal and departmental standards. Parallel to this traditional manufacturing base, technology-integrated players like Radarsign and SWARCO Traffic are expanding the functional boundaries of roadway signage through dynamic warning solutions, radar-enabled speed awareness platforms, flashing warning sign arrays, RRFB pedestrian crossings, and illuminated or variable-message systems designed for highway corridors and dense urban environments.
Recent operational milestones from 2026 highlight how these players are actively reshaping procurement access and product availability. A notable Sourcewell cooperative purchasing contract awarded to Radarsign in March expanded institutional access to MUTCD-compliant traffic calming and warning solutions for public agencies, effectively shortening procurement cycles and broadening distribution reach for standardized safety systems. That same quarter, the company introduced three new solar-powered flashing warning signs, reinforcing a strategic emphasis on visibility enhancement, energy independence, and reduced installation infrastructure dependency for critical roadway segments. Meanwhile, SWARCO Traffic previewed next-generation sign solutions at the ITS America Conference & Expo in Detroit, signaling continued momentum toward intelligent integration, dynamic message capability, and highway-to-urban deployment versatility. On the international supply side, manufacturers such as JACKWIN demonstrate the scale of cross-border safety signage distribution, maintaining ISO and CE-aligned certifications while exporting road safety products to more than seventy countries. The report's competitive analysis evaluates these operators through product portfolio breadth, compliance positioning, regional reach, procurement channel leverage, and recent commercial developments. Concentration metrics within the broader market indicate a moderately consolidated environment, with the top three and top five operators commanding substantial combined share—an arrangement that encourages both competitive benchmarking and strategic partnership evaluation. Readers requiring complete market share distributions, vendor capability scorecards, and competitive vulnerability mapping will find the full report structured to support precise go-to-market and M&A targeting decisions.
Segmentation Logic and Application Realities: Where Demand Actually Materializes
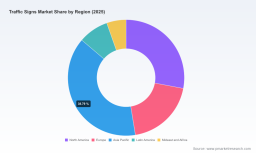
Understanding how the market distributes across material types, functional applications, and geographic demand centers is essential for manufacturers calibrating production mixes, contractors planning bid strategies, and distributors optimizing inventory positioning. The analysis recognizes that product composition is anchored by a diversified substrate landscape, with metal-based blanks, plastic variants, and composite constructions each serving distinct durability, cost, and deployment requirements. Application-side demand naturally fragments across guidance and directional signage, warning indicators, regulatory control devices, and supplementary sign categories, reflecting the operational hierarchy of road networks and the differing visibility, installation frequency, and replacement cadence associated with each function. Regionally, the demand footprint spans established infrastructure markets and high-growth modernization corridors, where differing procurement models, roadway density, municipal budgeting cycles, and transportation safety mandates shape localized consumption patterns.
Rather than treating segmentation as a static classification exercise, the report maps each segment to its underlying demand triggers. Metal-based signage continues to anchor high-visibility, long-duration deployments where regulatory durability and retroreflective performance are paramount. Plastic and composite alternatives serve specialized use cases where weight reduction, rapid deployment, or specific environmental resistance profiles are prioritized. On the application axis, directional and guidance infrastructure maintains broad utility across highway systems and municipal networks, while warning and regulatory categories respond directly to safety initiative funding, accident-reduction programs, and intersection optimization projects. The geographic distribution reflects a balance between mature procurement ecosystems and developing infrastructure investment tracks, with demand intensity influenced by corridor redevelopment priorities, cooperative purchasing adoption, and cross-border safety standardization efforts. This segmentation framework is designed to help stakeholders identify which product mixes align with specific procurement environments, how application-level replacement cycles affect recurring revenue opportunities, and which regional pipelines present the strongest near-term penetration potential. Comprehensive segment sizing, cross-segment interaction modeling, and region-specific procurement behavior analysis are fully developed in the complete report.
Outlook for 2026 Decision-Making: Translating Forecast Intelligence into Execution
The 2026–2032 horizon is best approached as a planning continuum rather than a static forecast window. Manufacturers and suppliers entering this period must synchronize production planning with evolving sheeting specifications, substrate cost trajectories, cooperative procurement timelines, and intelligent infrastructure pilot programs. Contractors and installation firms require visibility into which sign categories will see accelerated specification upgrades, which public agencies will prioritize solar or energy-independent warning solutions, and where compliance transitions will trigger replacement demand. Investors and strategic acquirers benefit from understanding which operational profiles—compliance agility, regional distribution density, dynamic-message capability, or export certification breadth—are most likely to capture margin expansion in a market growing at a sustainable mid-to-high single-digit rate.
The PW Consulting report translates these strategic questions into actionable intelligence. It provides a structured evaluation of procurement pathways, regulatory timelines, product development alignment, and competitive positioning, enabling organizations to convert market momentum into executable plans. Scenario-sensitive analysis, material cost sensitivity frameworks, compliance transition mapping, and vendor capability assessments are embedded throughout the study to support both near-term procurement decisions and multi-year capital planning. For stakeholders responsible for market entry, capacity expansion, partnership formation, or product portfolio optimization, the full report delivers the complete analytical architecture necessary to reduce uncertainty and sharpen execution.
Access the Full Intelligence: Complete Data, Segmentation, and Competitive Mapping
This overview has outlined the strategic contours of the Traffic Signs Market, highlighted the macro trajectory, contextualized the regulatory and material dynamics, introduced the competitive players shaping the sector, and mapped the segmentation logic that underpins real-world demand. Yet the complete decision-making toolkit—detailed historical reconstruction, full forecast breakdowns, comprehensive segmentation matrices, region-specific procurement behavior, competitive capability scorecards, concentration analysis, and scenario modeling—resides in the full market research publication. For executives, procurement leaders, product strategists, and investment professionals who require precise, auditable intelligence to guide 2026 planning and beyond, the complete report provides the depth, structure, and operational relevance necessary to act with confidence. To access the full dataset and deploy the complete strategic framework, explore the complete PW Consulting Traffic Signs Market research release.
For detailed analysis of this topic, please visit the official page: Traffic Signs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com