

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Class 1E Nuclear Instrumentation Cables Market to Hit $49.8M by 2032 at 3.6% CAGR

Strategic Intelligence for 2026: Navigating the Class 1E Nuclear Power Plant Instrumentation Cables Market
The nuclear energy sector stands at a pivotal juncture in 2026. As nations accelerate decarbonization agendas and extend the operational licenses of existing fleets, the demand for safety-critical infrastructure has never been more acute. Within this ecosystem, Class 1E instrumentation cables represent the nervous system of nuclear power plants, ensuring the integrity of data transmission, monitoring, and control in radiation-intensive and high-temperature environments. For stakeholders, investors, and procurement leaders, understanding the trajectory of this specialized market is not merely an academic exercise; it is a prerequisite for resilient strategic planning.
Our latest market research report, Class 1E Nuclear Power Plant Instrumentation Cables Market Outlook 2026-2032 , offers a comprehensive dissection of this high-stakes industry. This article serves as a strategic preview, highlighting the macro-economic currents and competitive dynamics that define the landscape, while demonstrating the depth of analysis available to clients who secure the full report.
Market Trajectory and Growth Catalysts
The global market for Class 1E instrumentation cables has demonstrated steady, resilient growth over the past half-decade, reflecting the inertia and long-term commitments inherent in nuclear infrastructure projects. Based on historical data from 2020 through 2025, the market has evolved from a baseline of approximately 31.51 million USD to an estimated 38.25 million USD in the base year of 2025. This progression underscores a consistent upward trend driven by plant life extensions, regulatory upgrades, and the commissioning of new units globally.
Class 1E Nuclear Power Plant Instrumentation Cables Market
Looking forward, the forecast period from 2026 to 2032 projects a compound annual growth rate (CAGR) of 3.6 percent. By 2032, the market revenue is anticipated to reach nearly 49.8 million USD. While these top-line figures indicate stability, the underlying drivers are complex. The growth is not uniform; it is segmented by the type of cable, the specific application within the plant, and the geographic region, each influenced by distinct regulatory and operational pressures.
Key Growth Drivers
Several macro-factors are converging to support this positive outlook:
- Plant Life Extensions: Many existing nuclear facilities are pursuing license renewals extending operations to 60 years or more. This necessitates the replacement or upgrading of instrumentation cables that have reached the end of their original design life, creating a sustained aftermarket demand.
- Safety Regulation Tightening: Global regulatory bodies, including the U.S. Nuclear Regulatory Commission (NRC), continue to enforce stringent standards such as IEEE 383-2003 for qualifying safety-related cables. Compliance drives replacements and ensures that new builds utilize qualified products, reinforcing the market for certified manufacturers.
- Small Modular Reactor (SMR) Development: The emerging SMR sector presents a new avenue for cable demand. While volumes are currently smaller than large-scale Light Water Reactors (LWRs), the specialized requirements for compact, safety-grade instrumentation create niche opportunities for qualified suppliers.
- Decarbonization Policies: Government incentives for clean energy in North America, Europe, and parts of Asia are revitalizing nuclear investment, indirectly bolstering the supply chain for critical components like Class 1E cables.
Competitive Landscape: A Consolidated Arena
The Class 1E nuclear cable market is characterized by high barriers to entry. Qualification processes are rigorous, involving extensive environmental testing, radiation resistance verification, and compliance with codes such as 10 CFR 50.49 and IEEE 323. Consequently, the market exhibits notable concentration. Our analysis indicates that the top three companies command a significant share of the market revenue, while the top five firms collectively hold a majority of the market presence. This consolidation suggests that supply chain security and vendor qualification are critical considerations for plant operators.
Profiles of Industry Leaders
The competitive field is dominated by established players with decades of experience in nuclear-grade manufacturing. Our report provides detailed profiling of key entities shaping the market dynamics:
Mineral Insulated Cables Market
- Prysmian (Italy): A global leader in cable systems, Prysmian offers the ULTROL 60+ Class 1E instrumentation cables. These 600V multiconductor cables are designed for monitoring and data transmission within safety-critical circuits. They are fully qualified to IEEE 323, IEEE 383, and 10 CFR 50.49 for Loss of Coolant Accident (LOCA) and High Energy Line Break (HELB) environments, supporting a 60+ year service life. Notably, their nuclear cables are DecaBDE-free, complying with US EPA prohibitions, reflecting a commitment to environmental standards alongside safety.
- Marmon IEI (United States): With installations in over 130 nuclear plants worldwide, Marmon IEI specializes in radiation-resistant LDVC, control, and instrumentation cables, including their proprietary RSCC® brand. Their designs meet 60-year life expectancy requirements and adhere to IEEE and LOCA standards. Manufacturing is conducted under a 10 CFR Appendix B, NQA-1 quality program, ensuring rigorous quality assurance throughout the production lifecycle.
- Shawflex (Canada): Shawflex manufactures EQ/Class 1E nuclear-grade power, control, and instrumentation cables and assemblies tailored for CANDU, LWR, and SMR plants. Their products are qualified to IEEE 323, IEEE 383, and CSA N290.13, capable of withstanding up to 250 Mrad/200°C with a 60-year life expectancy. Their compliance with Canadian and international standards positions them strongly in both domestic and export markets.
- Habia Cable (Sweden): Habia supplies Habiatron™ LOCA and non-LOCA Class 1E instrumentation cables, including thermocouple types, critical for reactor coolant pumps, safety valves, and control rod positioning. Designed for a 60-year operational life in nuclear safety systems, Habia emphasizes durability and precision in hazardous environments.
- Okonite Company (United States): Okonite provides Okoguard and FMR-N Class 1E nuclear power, control, and instrumentation cables. These products are qualified per IEEE 383 and 10 CFR 50.49 for safety-related applications in nuclear generating stations, reinforcing Okonite's role in the North American supply chain for safety-critical infrastructure.
The strategic implications of this landscape are profound. For procurement managers, relying on qualified suppliers is non-negotiable. For investors, the high concentration suggests that market share gains are difficult but valuable. Our full report delves deeper into the strategic moves, capacity expansions, and partnership networks of these key players.
Market Segmentation and Regional Nuances
Understanding where demand originates is as vital as knowing how much demand exists. The market is segmented by cable type, application location, and geography, each presenting unique opportunities and challenges.
Segmentation by Type and Application
The market is broadly divided into Nuclear Island Cables and Conventional Island Cables. The Conventional Island segment currently represents a larger portion of the market value, reflecting the extensive instrumentation required for turbine control, secondary systems, and general plant monitoring. However, Nuclear Island Cables, which operate within the containment building, command premium pricing due to the extreme conditions they must withstand, including high radiation fields and potential LOCA scenarios.
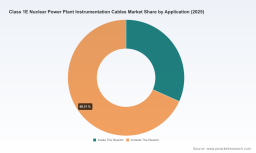
From an application perspective, instrumentation is deployed both Inside the Reactor and Outside the Reactor. Inside the Reactor applications involve the most stringent safety requirements, critical for core monitoring and control rod positioning. Outside the Reactor applications cover a broader range of safety and non-safety systems, including coolant pumps and safety valves. The balance between these segments shifts based on plant age, upgrade cycles, and specific design characteristics of the reactor types in operation.
Regional Dynamics
Geography plays a defining role in market distribution. North America remains a dominant force in this sector, driven by a large existing fleet of nuclear plants, ongoing life extension programs, and a robust regulatory framework that mandates high-quality instrumentation. The region's emphasis on energy security and clean baseload power supports continued investment in nuclear infrastructure.
Europe follows as a significant market, with countries such as France and Sweden maintaining strong nuclear capabilities. European initiatives to classify nuclear as sustainable under taxonomy rules have stimulated interest in long-term infrastructure stability. Meanwhile, the Asia Pacific region, while currently representing a smaller share of the total market value compared to North America and Europe, holds substantial potential. Growth in China, India, and South Korea, along with emerging interest in SMR technologies, suggests that the regional dynamic may evolve over the forecast period. Latin America and the Mideast and Africa regions contribute to the global total, though their shares are comparatively modest, often tied to specific national nuclear programs or lifecycle extensions of legacy plants.
Detailed regional revenue splits and growth rates are essential for tailoring market entry strategies or investment decisions. These granular insights are fully elaborated in our comprehensive report.
Regulatory and Compliance Landscape
In the Class 1E market, regulation is not just a constraint; it is a market shaper. Compliance with standards such as IEEE 383-2003 for qualifying safety-related cables and field splices is mandatory for operation in nuclear power generating stations. Manufacturers must demonstrate that their products can survive design-basis accidents and maintain functionality throughout the plant's life.
Recent industry context highlights the importance of these standards. For instance, Prysmian's ULTROL 60+ cables are environmentally qualified per 10 CFR 50.49, IEEE 323, and IEEE 383, setting a benchmark for qualification rigor. Similarly, Shawflex's compliance with IEEE 323 and CSA N290.13 ensures suitability for Canadian and international deployments. Marmon IEI's adherence to NQA-1 quality programs underscores the systemic approach required to maintain certification.
Furthermore, environmental regulations are increasingly intersecting with nuclear procurement. The US EPA prohibition on DecaBDE, for example, affects cable formulations. Prysmian's DecaBDE-free nuclear cables illustrate how manufacturers are adapting to regulatory shifts without compromising performance. This convergence of safety and environmental compliance adds layers of complexity that favor experienced, well-resourced suppliers.
Strategic Implications for Stakeholders in 2026
For corporate strategy teams, the Class 1E instrumentation cables market offers several actionable insights:
- Supply Chain Resilience: Given the market concentration and high qualification barriers, diversifying suppliers without compromising certification status is a key challenge. Strategic partnerships with multiple qualified vendors can mitigate risk but require careful management of technical compatibility.
- Lifecycle Planning: Plant operators must integrate cable replacement schedules into broader asset management plans. With many cables designed for 60-year lives, understanding the degradation profiles and replacement lead times is critical for avoiding unplanned outages.
- Investment in Qualification: For cable manufacturers, obtaining and maintaining qualifications such as IEEE 323 and 10 CFR 50.49 is a long-term investment that creates a moat. Companies that can streamline qualification processes or demonstrate superior performance in LOCA/HELB environments gain a competitive edge.
- SMR and New Build Opportunities: As SMRs move toward commercialization, early engagement with qualification bodies and standard-setting organizations can position suppliers to capture first-mover advantages in this nascent segment.
- Regional Strategy: Companies looking to expand should prioritize regions with active nuclear programs and supportive regulatory environments. North America and Europe offer mature markets with steady demand, while Asia Pacific presents growth potential contingent on policy execution and project timelines.
Why This Report is Essential for 2026 Decision-Making
The Class 1E Nuclear Power Plant Instrumentation Cables Market Outlook 2026-2032 is more than a data collection; it is a strategic tool designed to inform critical decisions. In an industry where margins are tight, regulations are strict, and failure is not an option, having access to precise, verified intelligence is paramount.
Our report provides:
- Granular Segmentation Data: Detailed revenue breakdowns by region, type, and application, enabling targeted market sizing and opportunity assessment.
- Competitive Intelligence: In-depth profiles of key companies, including product portfolios, qualification statuses, and strategic positioning.
- Regulatory Analysis: Up-to-date coverage of standards and compliance requirements, helping stakeholders navigate the evolving regulatory landscape.
- Forward-Looking Scenarios: Forecast models that account for variables such as plant closures, new builds, and policy shifts, offering a range of potential outcomes.
- Qualitative Insights: Expert commentary on industry trends, challenges, and emerging technologies that data alone cannot capture.
For executives, procurement managers, investors, and policymakers, the ability to anticipate market shifts and identify credible partners can define success. The data presented in this preview hints at the robust analysis available in the full report. However, to make informed decisions, one must access the complete intelligence package.
Conclusion
The Class 1E nuclear instrumentation cables market is a testament to the enduring importance of safety and reliability in the nuclear energy sector. As we move through 2026, the convergence of plant life extensions, regulatory rigor, and new build momentum creates a stable yet dynamic environment for growth. The market's structure, dominated by qualified specialists and shaped by stringent standards, rewards those who prioritize quality and compliance.
Our comprehensive market research equips stakeholders with the knowledge needed to navigate this complex landscape. From detailed regional analysis to competitive profiling and regulatory tracking, the report provides the depth required for strategic excellence. We invite you to explore the full report to unlock the complete set of insights and make confident, data-driven decisions for the years ahead.
For detailed analysis of this topic, please visit the official page: Class 1E Nuclear Power Plant Instrumentation Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com