
Blogs
PW Consulting Thionyl Chloride Market Hits $679.8M in 2025, Growth at 4.8% CAGR to 2032
By pmarketresearch, 2026-09-15
Thionyl Chloride Market Outlook 2026: Strategic Intelligence for Chemical and Battery Sector Decision-Makers
Executive Overview: Why This Market Intelligence Matters Now
The Thionyl Chloride Market is entering a decisive inflection point. As industrial demand matures alongside regulatory realignments in key manufacturing economies, companies that navigate this landscape with precise, forward-looking intelligence will secure measurable competitive advantage. PW Consulting's latest Thionyl Chloride Market report delivers exactly that: a rigorously structured, data-grounded assessment designed to convert macroeconomic signals into actionable corporate strategy.
This research is built for executives, procurement leaders, R&D directors, and investment analysts who require more than headline figures. The analysis spans a comprehensive historical baseline from 2020 through 2025, establishes a clear 2026 starting position, and projects market trajectories through 2032. By anchoring forecasts in verifiable historical growth patterns and structural industry shifts, the report equips stakeholders with the analytical confidence required to allocate capital, adjust supply chains, and position product portfolios ahead of market-wide transitions.
The strategic value of this publication lies in its dual focus: it captures the scale and tempo of market expansion while dissecting the operational, regulatory, and competitive forces that will shape enterprise outcomes year by year. Rather than presenting static snapshots, the research maps the causal relationships between feedstock dynamics, grade-level demand shifts, regional manufacturing realities, and the evolving battery and specialty chemical ecosystems that drive Thionyl Chloride consumption. For decision-makers operating in 2026, that contextual depth is not optional, it is foundational.
Market Trajectory and Structural Growth Signals
Historical Performance and Forecast Architecture
The Thionyl Chloride Market has demonstrated consistent, structurally supported expansion over the past half-decade. Historical revenue progression from 2020 to 2025 reflects a market that has moved beyond cyclical volatility into a phase of steady, demand-led growth. Building on that foundation, the forecast architecture projects a sustained upward trajectory through 2032, underpinned by a compound annual growth rate of 4.8 percent. This growth rate is not an abstract metric; it emerges from the convergence of enduring industrial applications, specialty chemical synthesis requirements, and the expanding role of Thionyl Chloride as a critical component in long-life battery chemistries.
Revenue progression across the forecast window reveals a market that compounds methodically rather than abruptly. The 2026 baseline establishes a clear reference point for near-term planning, while subsequent annual projections illustrate how cumulative demand, capacity adjustments, and application diversification will reshape total market value over the forecast horizon. For enterprise strategists, this phased visibility enables scenario modeling that aligns procurement cycles, production scheduling, and inventory planning with realistic market pacing rather than speculative spikes.
Demand Drivers and Application Resilience
The durability of Thionyl Chloride demand is rooted in its functional indispensability across multiple high-value sectors. As a chlorinating agent and synthetic intermediate, it remains embedded in pharmaceutical manufacturing, agrochemical formulation, organic synthesis, dyes and pigments production, and broader specialty chemical value chains. Equally significant is its role in battery applications, where Thionyl Chloride serves as a core electrolyte component for lithium thionyl chloride systems engineered for long service life, stable discharge performance, and demanding operational environments.
These application pillars do not grow in isolation. Pharmaceutical and agrochemical demand is shaped by regulatory compliance requirements, active ingredient complexity, and regional manufacturing footprints. Organic synthesis and specialty chemical pathways reflect the ongoing shift toward higher-purity intermediates and customized reaction conditions. Battery-related consumption, meanwhile, is influenced by industrial IoT deployments, remote monitoring equipment, defense and infrastructure applications, and broader electrification strategies that favor chemistries with extended shelf life and low maintenance requirements. The report examines how these vectors interact, where demand concentration is likely to intensify, and which application segments are positioned for accelerated uptake over the forecast period.
Competitive Landscape: Positioning, Profiles, and Strategic Implications
Key Enterprise Profiles and Capability Differentiation
The Thionyl Chloride competitive environment is defined by a mix of established specialty chemical manufacturers, regional producers with integrated synthesis capabilities, and reagent-grade suppliers serving laboratory and high-purity research markets. The report provides structured profiles of the core companies shaping this landscape, mapping their geographic base, product focus, and strategic positioning rather than reducing them to undifferentiated competitors.
LANXESS AG, headquartered in Cologne, Germany, occupies a prominent position through its high-purity Thionyl Chloride chlorinating solutions and its relevance to long-life Li-SOCl2 battery electrolytes. Its portfolio spans pharmaceutical, agrochemical, and specialty synthesis applications, giving it cross-sector leverage that aligns with both industrial and advanced battery demand. Merck KGaA, based in Darmstadt, Germany, complements this landscape with reagent-grade Thionyl Chloride at 97 percent purity, targeting laboratory environments and specialty chemical synthesis where consistency and analytical-grade reliability are paramount. Its U.S. affiliate, Sigma-Aldrich Co. LLC, extends this reach across research and organic synthesis applications from St. Louis, Missouri, reinforcing the importance of reagent-grade channels in the broader market architecture.
In the Asia-Pacific and emerging manufacturing corridors, companies such as Jiangxi Selon Industrial Co. Ltd. and Shandong Kaisheng New Materials Co. Ltd. reflect the growing sophistication of regional fine chemical and specialty materials producers. Jiangxi Selon's Thionyl Chloride offerings span pharmaceutical, agrochemical, and industrial synthesis use cases, while Shandong Kaisheng concentrates on organic synthesis and intermediate production within the specialty materials domain. These profiles illustrate how regional capacity is increasingly aligned with downstream formulation needs rather than commodity-style volume alone.
Indian manufacturers add further structural diversity. Transpek Industries Ltd. manufactures Thionyl Chloride for agrochemicals, pharmaceuticals, and specialty chemical intermediates, while Bodal Chemicals Ltd. produces the chemical for pesticide, pharmaceutical, and fine chemical intermediates. Both profiles underscore India's expanding role as a synthesis and intermediate supply hub. CABB Group, based in Germany, rounds out the competitive set as a supplier of Thionyl Chloride and related chlorinating agents for industrial and agrochemical applications, reinforcing Europe's continued relevance in high-specification chlorination chemistry.
Concentration Dynamics and Strategic Interpretation
Market concentration is a critical lens for understanding pricing power, supply reliability, and the pace at which new entrants can scale. The report frames concentration through a measured concentration ratio environment, where the leading cohort holds meaningful but not prohibitive share. This structure suggests a market in which scale, technical differentiation, and application-specific compliance capabilities matter more than sheer volume dominance. For buyers, it signals the importance of multi-source qualification and supplier diversification. For producers, it highlights the strategic value of grade specialization, battery-grade consistency, and regional distribution strength.
Rather than treating concentration as a static statistic, the analysis connects it to operational realities: how grade-level positioning influences customer stickiness, how regional manufacturing proximity affects logistics and lead-time reliability, and how reagent-grade versus technical-grade portfolios create distinct margin and demand profiles. This framing allows executives to interpret competition not as a ranking table but as a map of capability overlaps and whitespace opportunities.
Regulatory and Supply Chain Dynamics Shaping 2026
Regulatory Realignment in Key Manufacturing Markets
Regulatory shifts can reorganize trade flows, alter qualification timelines, and change the economics of battery-related chemical distribution. A notable development affecting the 2026 outlook is the optimization of import and export measures for lithium thionyl chloride batteries containing no more than one kilogram of Thionyl Chloride. Effective January 1, 2026, licensing requirements for these battery configurations are removed under the coordinated policy framework announced in December 2025 by MIIT, MOFCOM, and GAC China.
For market participants, this change is strategically significant because it lowers procedural friction for a defined battery segment that relies on Thionyl Chloride electrolytes. It can accelerate cross-border movement of compliant battery products, influence sourcing decisions for OEMs and integrators, and reshape the competitive balance between exporters and domestic manufacturers in segments previously constrained by licensing overhead. The report contextualizes this development within broader regulatory trends, helping stakeholders distinguish between temporary administrative relief and structural market opening.
Thionyl Chloride Market
Feedstock Realities and Production Architecture
Thionyl Chloride production is fundamentally linked to sulfur dioxide trioxide and sulfur dichloride chemistry, with sulfur dichloride serving as the primary feedstock. The availability and cost dynamics of this feedstock are shaped by refining byproducts and broader chlorination supply chains, making production economics sensitive to upstream industrial activity as well as regional processing capacity. Understanding this dependency is essential for anticipating margin pressure, supply continuity, and the timing of capacity adjustments.
The research integrates these feedstock realities into the market narrative rather than treating them as peripheral technical notes. By connecting synthesis pathways to production constraints and downstream demand, the analysis gives procurement and operations teams a clearer basis for evaluating supplier resilience, lead-time variability, and the likelihood of regional price divergence. This is particularly relevant for enterprises that depend on stable Thionyl Chloride supply for pharmaceutical intermediates, agrochemical production, and battery electrolyte formulations.
Report Architecture: What Decision-Makers Will Gain
Scope, Segmentation, and Analytical Depth
This market research is structured to support both strategic planning and tactical execution. It provides a full historical reconstruction from 2020 to 2025, a clearly defined 2026 baseline, and a forward forecast extending to 2032. All monetary values are presented in USD, with revenue expressed in millions, enabling consistent financial modeling and cross-market comparison. The report integrates segmentation by region, by grade, and by application, allowing stakeholders to isolate the demand structures most relevant to their operational footprint without losing sight of total market context.
Crucially, the report does not stop at segmentation tables. It interprets how regional demand patterns reflect manufacturing localization, how grade-level splits differentiate technical-grade volume from pharmaceutical- and reagent-grade value, and how application-level consumption ties back to product lifecycle, regulatory environment, and end-use durability. This interpretive layer is what separates a data catalog from a strategic asset. For readers who need to understand not only where the market is going, but why certain pathways are more defensible than others, that depth is essential.
Competitive Intelligence and Operational Context
Beyond macro forecasts, the publication delivers company-level intelligence that can inform sourcing strategy, partnership evaluation, and competitive benchmarking. Enterprise profiles are paired with capability summaries that clarify which players serve which demand environments, where high-purity and reagent-grade offerings command differentiated positioning, and how regional producers are building relevance in pharmaceutical, agrochemical, and specialty synthesis markets.
Worldwide Lithium Thionyl Chloride Cell Market
The report also incorporates industry context that affects day-to-day decision-making, including regulatory updates, feedstock dependencies, and the operational implications of battery-related policy changes. By weaving these elements into a unified analytical narrative, the research helps executives anticipate disruptions, validate assumptions, and adjust commercial plans with greater precision. The goal is not simply to inform, but to reduce uncertainty in capital allocation, supplier selection, and market-entry timing.
Strategic Takeaways for 2026 Planning
As organizations finalize 2026 objectives, Thionyl Chloride market intelligence must serve as more than background context. It should directly Shape procurement diversification, grade-level portfolio decisions, and application-specific investment prioritization. The report's central value proposition is that it converts a growing but complex market into a structured decision framework.
Several strategic imperatives emerge from the analysis. First, demand resilience across pharmaceutical, agrochemical, organic synthesis, and battery applications means that supply continuity and grade consistency should be treated as core risk-management priorities rather than operational afterthoughts. Second, the regulatory relaxation affecting specific lithium thionyl chloride battery configurations introduces new trade-flow possibilities that reward early mapping of supply routes and compliance pathways. Third, the concentration structure of the market suggests that differentiation through purity, reliability, and application expertise will remain more lucrative than competing on undifferentiated volume alone.
For investors and corporate strategists, the forecast horizon through 2032 offers a practical basis for long-cycle planning. The steady compound growth trajectory, combined with shifting regulatory and feedstock conditions, creates a market environment in which disciplined forecasting and scenario readiness outperform reactive adjustments. Enterprises that use this research to align product development, sourcing, and geographic exposure with verified market signals will be better positioned to capture value as the Thionyl Chloride Market continues its measured expansion.
PW Consulting's Thionyl Chloride Market report is designed for leaders who require precision, context, and forward visibility in a single analytical package. It provides the structural understanding necessary to navigate 2026 with confidence and the segment-level intelligence required to make informed, defensible decisions across the forecast period.
For detailed analysis of this topic, please visit the official page: Thionyl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Induction Cooktop Market to Hit $34.67 Billion by 2032, 5.6% CAGR: PW Consulting Insight
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Induction Cooktop Market: Navigating the 2026 Decision Landscape
Executive Overview
The global kitchen appliance sector is undergoing a structural shift, and the induction cooktop segment stands at the forefront of this transformation. For executives, product strategists, and capital allocators operating in 2026, the ability to parse market momentum, competitive positioning, and regulatory tailwinds is no longer a supplementary advantage—it is a baseline requirement for sustainable growth. Our latest Induction Cooktop Market research report has been engineered to deliver precisely that clarity. Built on a rigorous historical foundation and extended through a multi-year forecast horizon, this study translates complex market signals into actionable strategic intelligence.
The market has demonstrated remarkable expansion over the past half-decade. Revenue climbed from 10.2 billion USD in 2020 to 23.6 billion USD in 2025, reflecting a compound annual growth trajectory that underscores deepening consumer preference for energy-efficient, precision-controlled cooking surfaces. Looking forward, the market is projected to reach approximately 25 billion USD in 2026, with sustained upward momentum carrying valuations past 34 billion USD by 2032. This expansion is not merely a function of unit volume; it reflects a broader realignment in household appliance portfolios, commercial kitchen retrofitting cycles, and regulatory frameworks that actively incentivize electrification.
Our report treats these headline figures as starting points, not endpoints. The real strategic value lies in understanding the structural forces that will determine which companies capture margin expansion, which product architectures dominate specific use cases, and how supply-chain realities will shape competitive execution in the years ahead.
The Strategic Imperative for 2026 Decision-Makers
Reading the Growth Architecture
Market growth in the induction cooktop space is being driven by intersecting demand vectors. Residential adoption continues to accelerate as homeowners and renters prioritize faster heat response, improved indoor air quality, and compatibility with modern kitchen designs. Commercial environments are simultaneously re-evaluating induction solutions for their precise temperature control, reduced kitchen heat load, and alignment with sustainability mandates. The report dissects how these application dynamics interact with product architectures, revealing where demand concentration creates pricing leverage and where fragmentation rewards agility.
Importantly, the growth trajectory is not uniform across all segments or geographies. The research maps the relative weighting of regional demand, highlighting where mature markets are pivoting toward premium upgrades and where emerging regions are experiencing first-time electrification waves. By separating baseline volume growth from structural adoption shifts, the analysis enables leadership teams to distinguish between cyclical noise and durable market expansion.
For corporate planners, this distinction is critical. Investing in capacity, distribution, or marketing initiatives based on aggregate growth figures alone can lead to misaligned resource allocation. Our forecast framework provides the granularity required to calibrate entry timing, prioritize channel investments, and evaluate whether a particular submarket offers sufficient depth to justify dedicated go-to-market execution.
Induction Cooktop Market
Competitive Positioning and the High-Stakes Arena
Mapping the Enterprise Landscape
The competitive environment in this market is defined by a blend of incumbent appliance manufacturers, premium European engineering houses, and specialized commercial equipment providers. Market concentration metrics indicate that the top three players command a meaningful share of total revenue, while the top five collectively approach nearly half of the market. This concentration signals both the attractiveness of the category and the intensity of competitive rivalry. Companies that fail to differentiate on performance, durability, or connected features risk being compressed into commodity positioning.
Several enterprise players are actively shaping the category through product innovation and brand segmentation. GE Appliances has reinforced its position with a full-line induction portfolio, including the GE Profile series that emphasizes precision control and connected kitchen capabilities. Samsung Electronics continues to push functional differentiation through Flex Zone configurations and power boost technologies designed to streamline home cooking workflows. In the premium residential segment, Miele & Cie has built enduring reputation on durability and long-term reliability, appealing to consumers who view cooking appliances as long-horizon investments.
North American manufacturers are also leveraging multi-brand architectures to cover distinct price and performance tiers. Whirlpool Corporation extends its induction offerings through JennAir, KitchenAid, and Whirlpool, each targeting specific consumer expectations around temperature control and surface maintenance. Electrolux Group has focused on surface engineering, notably through Frigidaire models that incorporate advanced coatings aimed at improving scratch resistance. BSH Hausgeräte operates across Bosch, Thermador, and Gaggenau, offering high-output and full-surface induction solutions that span mainstream and luxury kitchen segments. On the commercial side, The Vollrath Company specializes in professional-grade induction equipment designed for restaurant and foodservice environments where throughput, controllability, and durability are non-negotiable.
Understanding how these players compete requires more than a brand-by-brand summary. The report assesses how product line breadth, regional distribution strength, and technology roadmaps interact to create competitive moats. It also examines where overlaps in target audiences create direct head-to-head pressure and where portfolio gaps invite new entrants or private-label expansion.
Recent Product and Market Movements
Recent product introductions illustrate the pace at which feature competition is escalating. In March 2026, Frigidaire introduced a MatteGuard induction cooktop surface engineered to reduce visible scratches by a significant margin, directly addressing a common consumer concern around long-term aesthetic degradation. Earlier, in August 2025, JennAir launched a temperature-controlled induction cooktop following a Best in Show recognition at KBIS 2025, reinforcing the importance of culinary precision as a purchase driver. In February 2025, Fire Magic unveiled what was described as the first built-in outdoor induction cooktop at KBIS 2025, expanding the addressable use-case envelope with precise temperature control spanning a broad operating range.
These launches are not isolated events; they signal broader strategic themes. Surface durability, temperature precision, and environment expansion are becoming central battlegrounds. The report places these developments within a competitive timeline, helping readers evaluate which innovations are likely to become baseline expectations versus which will sustain premium pricing power.
Regulatory and Structural Dynamics Shaping the Market
Policy Tailwinds and Efficiency Standards
Regulatory and incentive frameworks are playing an increasingly decisive role in shaping demand patterns. Efficiency advocacy has moved from niche sustainability conversations into mainstream procurement criteria. Publicized efficiency comparisons have emphasized that induction appliances can operate substantially more efficiently than conventional electric smooth-top ranges and significantly more efficiently than gas alternatives. This narrative is reinforcing both consumer preference and institutional purchasing guidelines, particularly in regions where energy policy aligns with appliance modernization targets.
Incentive programs are also altering the economics of adoption. Rebate structures for certified efficient models have entered the market with meaningful financial impact, lowering effective purchase barriers and accelerating replacement cycles. At the same time, buyer guides and recognition programs are helping governments and manufacturers identify high-quality, energy-efficient models at scale. These initiatives do more than stimulate short-term demand; they create reference points that influence brand credibility, specification standards, and retailer merchandising strategies.
For companies operating in this space, regulatory momentum represents both opportunity and execution risk. Alignment with recognized efficiency benchmarks can unlock promotional leverage and public-sector eligibility. Conversely, failure to keep pace with evolving specification language or incentive requirements can marginalize otherwise competitive products. The report examines how these dynamics interact with regional market structure and what they imply for product roadmap planning.
Supply-Chain Realities and Input Dependencies
Beyond demand-side forces, the market's expansion is moderated by structural supply considerations. Key input materials, including ceramic glass and induction coils, remain heavily dependent on import flows from China. This concentration exposes manufacturers to currency volatility, logistics disruption, and geopolitical friction. In a category where surface finish, thermal performance, and component reliability are closely tied to customer satisfaction, input availability and quality consistency are not merely cost issues—they are product integrity issues.
The research addresses these dependencies by mapping where supply-chain vulnerability is most likely to influence pricing, lead times, and margin stability. It also frames the strategic options available to firms seeking to reduce exposure, whether through supplier diversification, inventory buffering, or design adjustments that maintain performance while easing procurement constraints. Understanding the intersection of input risk and competitive timing is essential for any organization planning capacity investments or long-term product commitments.
Inside the Report: A Practical Intelligence Toolkit
Scope, Structure, and Decision-Use Design
This study is designed to support multiple internal use cases simultaneously. It integrates historical valuation data, forward-looking forecasts, segmentation analysis, competitive profiling, and market-dynamic contextualization into a single coherent framework. Rather than functioning as a static data sheet, the report is structured to help teams move from market awareness to decision readiness.
The analysis covers the evolution of market size across the 2020 to 2025 historical window and extends through the 2026 to 2032 forecast period, enabling both retrospective validation and forward planning. Segmentation views examine how the market divides by product type, application context, and regional demand concentration, giving readers a multi-axis perspective on where value is being created. The competitive section profiles core enterprise players, their headquarters 위치와 product positioning, and the strategic implications of their portfolio strategies. Recent developments are organized to show how product launches and industry initiatives are reshaping expectations in real time.
In addition, the report integrates regulatory and structural forces that influence market behavior, including efficiency recognition programs, rebate frameworks, and material supply dynamics. These contextual layers are not appended as background notes; they are woven into the analytical narrative so that readers can see how policy, sourcing, and product innovation interact to shape commercial outcomes.
What Leadership Teams Can Do With This Intelligence
For strategy leaders, the report provides a foundation for evaluating market entry, expansion, or repositioning decisions. For product teams, it offers a structured view of feature prioritization and segment alignment. For commercial and sales leadership, it clarifies where demand intensity, competitive pressure, and incentive environments are likely to shape conversion dynamics. For supply-chain and operations stakeholders, it highlights input dependency risks and the strategic importance of robustness in sourcing and inventory planning.
Stainless Steel Cookware Market
By connecting macro growth signals to segment behavior and competitive action, the research reduces the gap between high-level market awareness and operational execution. It is built to support scenario discussion, investment prioritization, and cross-functional alignment around a shared view of market direction.
Conclusion: Making 2026 Decisions With Confidence
The induction cooktop market is moving with enough velocity, complexity, and competitive intensity that legacy assumptions can quickly become liabilities. Growth is real, but its distribution across regions, applications, types, and brand positions is uneven. Policy incentives, efficiency narratives, product innovation, and supply-chain dependencies are all influencing who wins share and who merely participates.
Our Induction Cooktop Market research report is designed to help organizations navigate that complexity with discipline. It provides the market-size architecture, segmentation perspective, competitive mapping, and dynamic context needed to frame 2026 decisions with greater precision. The headline trajectory points to continued expansion, but the strategic opportunities—and risks—reside in the details that determine execution advantage.
For leaders who need a full, structured intelligence package rather than a high-level overview, the complete report offers the deeper segmentation view, forecast breakdown, and competitive analysis required to convert market awareness into confident, evidence-based action.
For detailed analysis of this topic, please visit the official page: Induction Cooktop Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Artificial Blood Vessel Market to Hit $3.45B by 2032, Driven by 5.38% CAGR
By pmarketresearch, 2026-09-15
Strategic Horizons: Navigating the Artificial Blood Vessel Market in 2026 and Beyond
The vascular surgery landscape is undergoing a profound transformation, driven by an aging global population, the rising prevalence of chronic cardiovascular conditions, and rapid advancements in bioengineered materials. For stakeholders operating within the medical device sector, understanding the trajectory of the artificial blood vessel market is no longer optional—it is a strategic imperative. As we move into the 2026 fiscal year, the ability to anticipate demand shifts, regulatory approvals, and competitive maneuvers will define which organizations capture market share and which are left reacting to industry changes.
PW Consulting’s latest comprehensive study on the Artificial Blood Vessel Market offers a detailed roadmap for navigating this complex terrain. Based on rigorous data collection and analysis spanning historical performance from 2020 through 2025 and projections extending to 2032, this report provides the intelligence necessary to make informed decisions. The following analysis highlights the strategic value of this research, outlining the market's current standing, the competitive forces at play, and the critical dynamics shaping the industry environment.
Market Trajectory and Growth Dynamics
The artificial blood vessel market has demonstrated steady resilience and expansion over the past half-decade. Historical data indicates a consistent upward trend in revenue, reflecting increased adoption of vascular grafts and prostheses across various clinical settings. From a base valuation in 2020, the market has grown year-over-year, reaching new milestones by 2025. This growth is not merely a continuation of past trends but is fueled by specific drivers including the shift toward minimally invasive procedures and the limitations associated with autologous vein harvesting.
Looking forward, the forecast period from 2026 to 2032 suggests sustained momentum. The compound annual growth rate (CAGR) is projected at 5.38 percent, signaling a healthy expansion rate that outpaces many general medical device sectors. This growth trajectory implies that the total market revenue will escalate significantly over the next several years, moving from the 2026 estimated levels toward higher valuations by 2032. For executives and investors, this macro-level growth confirms that capital allocation toward vascular technologies remains a viable long-term strategy. However, realizing returns on this potential requires nuanced understanding of where growth is concentrated and which segments are driving the value.
The revenue scale of the market, measured in billions of USD, underscores its significance within the broader cardiovascular device ecosystem. As hospitals and surgical centers update their inventory and procedural capabilities, the demand for reliable, high-performance vascular conduits continues to rise. This demand is particularly acute in regions with advanced healthcare infrastructure, though emerging markets are also beginning to contribute to the overall volume. The report delves into these regional nuances without oversimplifying the complex logistical and regulatory barriers that vary by geography.
Artificial Blood Vessel Market
Competitive Landscape and Key Players
The market is characterized by a mix of established medical technology giants and innovative niche players who are redefining what is possible with vascular grafts. Market concentration metrics indicate that while competition is robust, a core group of companies holds a significant portion of the market share. The CR3 and CR5 concentration ratios suggest a moderately concentrated environment where strategic partnerships and product differentiation are key to maintaining leadership.
Several key companies define the current competitive landscape, each offering distinct technological approaches to vascular reconstruction. Humacyte Global, Inc., based in Durham, North Carolina, represents the frontier of tissue engineering. Their flagship offering, Symvess, is an acellular tissue engineered vessel (ATEV) designed for extremity arterial injury when autologous vein is not feasible. This innovation addresses a critical clinical gap, providing a solution where traditional harvesting is compromised. Humacyte's recent regulatory successes, including FDA approval for Symvess as a vascular conduit for extremity arterial injury, position them as a leader in the bioengineered segment. Furthermore, their planned marketing authorization application in Israel highlights their global expansion strategy.
Artivion, Inc., headquartered in Atlanta, Georgia, offers a different approach through cryopreserved allografts. Their CryoArtery products, specifically the Aortoiliac Artery and Femoral Artery versions, are utilized for below-knee revascularization and peripheral vascular repair. These products leverage the biological compatibility of preserved human tissue, catering to complex reconstructive needs where synthetic options may not be optimal.
LeMaitre Vascular, Inc., located in Burlington, Massachusetts, contributes to the market with collagen-based vascular grafts. Their Artegraft Collagen Vascular Graft, derived from bovine carotid artery, is widely used for hemodialysis access, AV graft salvage, and lower extremity bypass procedures. LeMaitre's continued engagement with the investment community, including participation in upcoming investor conferences, signals confidence in their product pipeline and market position.
On the synthetic side, B. Braun Melsungen AG from Germany provides warp-knitted polyester vascular prostheses. Their Silver Graft and Silver Graft Helix lines are employed in aortic and peripheral reconstructive procedures. These products represent the established standard of care for many synthetic vascular interventions, benefiting from decades of clinical data and manufacturing expertise.
Terumo Medical Corporation, based in Somerset, New Jersey, rounds out the competitive field with a focus on bioengineered vascular grafts. Their innovative product offerings align with the broader industry shift toward advanced materials that improve patency rates and reduce complications. Together, these companies illustrate the diversity of technological solutions available to surgeons and hospitals, ranging from fully synthetic polymers to biologically derived tissues.
Industry Context and Strategic Dynamics
Beyond product portfolios, several external dynamics are reshaping how value is created and captured in this market. Reimbursement policies, regulatory frameworks, and material cost structures are critical variables that influence adoption rates and profitability. One significant development involves the reimbursement pathway for advanced tissue-engineered products. For instance, specific ATEV products like Symvess have been submitted for New Technology Add-On Payment (NTAP) consideration, with potential start dates for discharges kicking off in 2025. The pricing strategy for such innovative units, often priced significantly higher than traditional options, reflects the value proposition of reducing surgical time and improving outcomes in trauma scenarios.
Regulatory milestones continue to act as catalysts for market entry and expansion. Priority designations from government bodies, such as the U.S. Secretary of Defense for specific vascular trauma treatments, can accelerate adoption within specific payer channels and institutional settings. These designations validate the clinical utility of new technologies and often pave the way for broader reimbursement coverage. The interplay between regulatory approval types, such as Biologics License Application (BLA) versus standard device clearance, also impacts commercialization speed and market access strategies.
Cost comparisons between new technologies and standard of care procedures are also driving decision-making. While synthetic grafts and traditional harvesting have established cost baselines, the economic evaluation of new technologies often incorporates broader hospital resource utilization factors. For healthcare providers, the decision to adopt a higher-cost graft often depends on the total procedural cost, including operating room time, recovery metrics, and long-term patency. Understanding these economic trade-offs is essential for manufacturers seeking to justify premium pricing and for providers managing budget constraints.
Report Scope and Operational Intelligence
PW Consulting's Artificial Blood Vessel Market report is designed to translate these macro trends into actionable intelligence. The study provides a granular breakdown of the market by type, application, and region, allowing clients to identify high-growth opportunities and potential risks. The segmentation analysis covers various material types, including polyethylene terephthalate, elastomers, and polydioxanone, as well as applications such as peripheral artery disease, hemodialysis, aortic disease, and other indications. By understanding the specific revenue contributions and growth rates of each segment, companies can tailor their R&D and marketing efforts to the areas with the highest potential.
Regional analysis within the report offers insights into geographic performance, detailing how markets in North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa are evolving. This geographic granularity is vital for companies planning market entry or expansion strategies. Each region presents unique regulatory hurdles, reimbursement environments, and competitive intensities. The report synthesizes this information to help stakeholders prioritize regions where their specific product offerings align best with local clinical needs and economic conditions.
Furthermore, the report includes competitive profiling that goes beyond basic company descriptions. It analyzes strategic moves, recent developments, and positioning within the value chain. Whether monitoring FDA approvals, tracking investor relations activities, or assessing new product launches, the competitive intelligence section provides the context needed to anticipate rival actions. This level of detail enables clients to benchmark their own performance and identify gaps in the market that remain underserved.
Strategic Implications for 2026 Decision-Making
As organizations plan their strategies for 2026 and beyond, the insights contained in this market study serve as a foundational tool for decision-making. For product developers, the data highlights which material technologies and clinical applications are gaining traction, guiding investment in next-generation grafts. For commercial teams, the regional and segmentation data informs go-to-market strategies, ensuring that sales efforts are directed toward the most receptive customer segments and geographic territories.
For investors and financial analysts, the growth projections and market concentration metrics provide a basis for valuation models and risk assessment. Understanding the stability of revenue streams and the intensity of competition helps in evaluating the potential ROI of ventures within this sector. The report's comprehensive coverage of recent developments, from regulatory approvals to investor conferences, ensures that stakeholders have access to the most current information available.
The artificial blood vessel market is at a pivotal point where technological innovation meets significant clinical demand. Success in this environment requires more than just a superior product; it demands a deep understanding of the market ecosystem. PW Consulting's research delivers that understanding, offering a clear view of the past performance, current dynamics, and future potential of the industry. By leveraging this intelligence, organizations can position themselves to capitalize on the projected growth and navigate the complexities of the vascular surgery landscape with confidence.
To access the full depth of this analysis, including detailed segmentation data, precise regional valuations, and comprehensive competitor profiles, stakeholders are encouraged to review the complete market research report. The full document provides the specific data points and strategic recommendations necessary to execute informed decisions in the coming year.
Man-made Vascular Graft Market
For detailed analysis of this topic, please visit the official page: Artificial Blood Vessel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pulp & Paper Enzyme Market Hits $216M in 2025, 8.6% CAGR to $384.62M by 2032
By pmarketresearch, 2026-09-15
Strategic Imperative: Navigating the Enzyme for Pulp & Paper Market in 2026 and Beyond
The global pulp and paper industry stands at a critical juncture where operational efficiency, regulatory compliance, and sustainability mandates converge. As mills across the world strive to optimize production costs while meeting increasingly stringent environmental standards, enzymatic solutions have transitioned from a niche innovation to a core component of modern mill processing. Our latest market research, Enzyme for Pulp & Paper Market, provides a comprehensive strategic roadmap for stakeholders aiming to capitalize on this transformation. With a projected market valuation reaching significant milestones by the end of the forecast period, understanding the underlying drivers, competitive dynamics, and regional nuances is no longer optional—it is essential for informed decision-making in 2026.
This report is designed to equip senior management, procurement leaders, and R&D strategists with the actionable intelligence needed to navigate a landscape defined by rapid technological adoption and shifting supply chain economics. By synthesizing historical data from 2020 through 2025 with a robust forecast extending to 2032, we offer a clear view of the growth trajectory, highlighted by a steady compound annual growth rate that underscores the sector's resilience and long-term potential. The following analysis previews the strategic depth of our findings, illustrating why this intelligence is vital for securing a competitive edge in the coming years.
Macro Growth Trajectory and Market Valuation
The enzyme market for pulp and paper has demonstrated consistent expansion over the past half-decade, recovering from minor fluctuations to establish a strong upward trend. Historical analysis from 2020 to 2025 reveals a market that has grown substantially in revenue terms, surpassing initial expectations as mills accelerate the shift away from harsh chemical processes. This growth momentum is set to accelerate further during the forecast period spanning 2026 to 2032. The market is projected to expand from a robust baseline in 2025 to a substantially larger valuation by 2032, driven by widespread adoption across key application areas and supportive regulatory frameworks globally.
Central to this outlook is a forecasted CAGR that reflects sustained demand for bio-based processing aids. This growth rate is not merely a numerical projection; it signals a structural shift in how pulp and paper manufacturers approach fiber processing, bleaching, and recycling. As raw material costs fluctuate and energy prices remain volatile, enzymes offer a viable pathway to reduce input costs, improve yield, and minimize environmental footprints. Our report details the revenue progression year by year, allowing clients to benchmark their internal projections against market realities and adjust their investment strategies accordingly. The data underscores that the market is moving beyond early adoption phases into a period of mature, scaled integration where enzymatic solutions deliver measurable ROI across diverse mill operations.
Industrial Enzymes Market
Segmentation Insights: Type, Application, and Regional Dynamics
Understanding where value is concentrated requires a granular look at the market's segmentation. Our analysis dissects the market by enzyme type, application, and geography, revealing distinct growth patterns and adoption hotspots. In terms of enzyme types, cellulase and xylanase continue to dominate the landscape, reflecting their critical role in fiber modification, strength enhancement, and bleaching optimization. Amylase, lipase, pectinase, and other specialized enzymes also contribute to the ecosystem, addressing specific process challenges such as deposit control, starch management, and pitch removal. The report provides a detailed breakdown of revenue contributions across these categories, highlighting which enzyme classes are gaining traction and why.
Application-wise, bleaching and deinking represent the largest utilization segments, as manufacturers seek to reduce chlorine usage, lower chemical oxygen demand, and improve pulp brightness without compromising fiber integrity. Fiber modification and other emerging applications are also expanding, driven by the need for customized paper properties and enhanced runnability on the paper machine. The regional analysis further illuminates where demand is strongest. North America, Europe, and Asia Pacific account for the substantial majority of market revenue, each influenced by unique regulatory environments, mill modernization cycles, and raw material availability. Latin America and the Middle East and Africa present emerging opportunities, often linked to capacity expansions and the gradual adoption of cleaner production technologies. Our report maps these regional dynamics in depth, identifying high-growth corridors and potential market entry points without exposing the precise percentage splits or absolute figures that define our premium intelligence offering.
Competitive Landscape: Key Players and Strategic Moves
The market is characterized by a consolidated competitive structure, with a handful of leading biosolution providers commanding a significant share of global revenue. Our report profiles the core companies shaping the industry, analyzing their product portfolios, technological expertise, and recent strategic initiatives. Novonesis, headquartered in Copenhagen, Denmark, remains a dominant force with its FiberCare® enzyme portfolio, which addresses refining, strength improvement, and sustainability in fiber processing. The company has consistently emphasized energy reduction and increased refining capacity in its latest insights, reinforcing its commitment to helping mills achieve both economic and environmental goals.
BASF SE, based in Ludwigshafen, Germany, continues to expand its footprint through comprehensive enzyme solutions for deinking, bleaching optimization, and process efficiency, leveraging its Verenium expertise to deliver tailored mill applications. AB Enzymes, also located in Darmstadt, Germany, has focused on its ECOPULP® portfolio, which targets improved drainage, reduced energy consumption, and sustainable processing. Recent product innovations from AB Enzymes have emphasized enhanced runnability and fewer deposits, responding directly to operational pain points in pulp and paper manufacturing. Buckman, headquartered in Memphis, Tennessee, USA, provides enzymatic technologies that include stickies control, enzymatic deinking, and cost reduction solutions, with products like Maximyze® gaining recognition for their practical impact on mill operations. Meanwhile, Enzymatic Deinking Technologies (EDT) in the US specializes in enzyme-based deinking and recycling solutions, helping mills improve fiber quality while cutting energy and chemical consumption.
Recent developments underscore the intensity of competition and the pace of innovation. Novonesis highlighted its FiberCare® solutions in a mid-2025 catalog release, emphasizing refining capacity gains and energy savings in fine paper production. AB Enzymes launched ECOPULP® innovations in late 2024 to boost drainage and runnability. Buckman announced price adjustments across its pulp and paper product lines in Europe, the Middle East, and North Africa, reflecting broader cost pressures that influence enzymatic offerings. Our report evaluates these moves within the context of a market where the top three and top five players collectively hold a substantial share, indicating barriers to entry and the importance of differentiated technology, service networks, and application support.
Industry Dynamics: Regulation, Raw Materials, and Labor Economics
Market growth does not occur in a vacuum; it is shaped by a complex array of external forces that our report examines in detail. Regulatory frameworks are increasingly favoring enzyme-assisted processes. The European Union's BREF document for pulp, paper, and board production explicitly recommends enzyme-assisted bleaching and pulping to minimize dioxin formation and reduce water consumption. In China, stringent environmental enforcement under the Environmental Protection Law and subsequent industrial standards has compelled mills to adopt cleaner technologies, including enzyme pre-treatment, to meet discharge limits and improve overall sustainability metrics. These regulatory tailwinds create a durable demand base for enzymatic solutions, particularly in regions where compliance costs for traditional chemical processes are rising.
Raw material economics also play a pivotal role. Fluctuations in wood pulp prices directly impact mill operating costs and influence the willingness to invest in process optimization. Recent data shows that the net price of bleached hardwood kraft pulp in China experienced a notable decline, altering cost structures and potentially freeing up capital for technology upgrades. At the same time, labor cost trends in major producing regions, such as the elevated unit labor costs recorded in US pulp, paper, and paperboard mills, reinforce the need for automation and efficiency-enhancing solutions. Enzymes can mitigate labor intensity by improving runnability, reducing downtime, and decreasing the need for manual chemical handling. Our analysis integrates these macroeconomic and sector-specific variables to show how they interact with enzyme adoption rates and pricing strategies.
Report Contents and Strategic Utility for 2026 Decision-Making
The Enzyme for Pulp & Paper Market report is structured to deliver immediate operational and strategic value. It includes comprehensive market sizing and forecasting across multiple dimensions, enabling clients to model revenue scenarios and align capacity planning with market realities. The segmentation analysis provides a clear view of which enzyme types and applications are driving growth, helping R&D teams prioritize development efforts and marketing teams target high-potential segments. Competitive profiling goes beyond basic company descriptions, offering insights into product positioning, recent launches, pricing actions, and strategic focus areas.
Additionally, the report explores supply chain dynamics, regulatory impacts, and regional adoption patterns, giving stakeholders a holistic understanding of the market environment. Detailed tables, charts, and qualitative assessments are included to support presentations, investment memos, and internal strategic reviews. By accessing the full report, clients gain the ability to benchmark their position against market leaders, identify partnership opportunities, and anticipate shifts in customer demand. The intelligence is curated to answer the critical questions that keep industry leaders awake at night: where will growth concentrate, which technologies will define the next cycle, and how should we position our offerings to capture value in a consolidating market?
Enzyme for Pulp & Paper Market
Conclusion: Positioning for Sustained Growth
The enzyme for pulp and paper market is poised for continued expansion, underpinned by regulatory support, cost pressures, and a growing recognition of bio-based solutions as enablers of sustainable manufacturing. As we move through 2026 and look toward 2032, the organizations that succeed will be those that base their strategies on accurate, granular market intelligence rather than generalized industry narratives. Our report provides the depth, clarity, and actionable insight required to make those strategic calls with confidence.
To fully leverage the opportunity, stakeholders need access to the complete dataset, including detailed segmentation values, regional revenue breakdowns, competitive market share analysis, and forward-looking scenario modeling. We invite you to visit the source webpage to explore the full Enzyme for Pulp & Paper Market research and secure the comprehensive intelligence needed to navigate the next phase of industry evolution. The future of pulp and paper processing is being rewritten through enzymatic innovation—ensure your strategy is aligned with the trajectory.
For detailed analysis of this topic, please visit the official page: Enzyme for Pulp & Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optical Fiber Fusion Splicer Market to Hit $344.8M by 2032, Growing at 6.0% CAGR
By pmarketresearch, 2026-09-15
Navigating the Fiber Frontier: Strategic Intelligence for the 2026 Optical Fiber Fusion Splicer Market
The global optical fiber fusion splicer market stands at a pivotal inflection point. As network operators accelerate broadband rollouts, hyperscale data centers push beyond conventional density limits, and public infrastructure programs demand resilient connectivity backbones, equipment procurement decisions carry multi-year operational and financial implications. Our latest market research delivers a decision-ready intelligence package designed specifically for executives navigating 2026 capital allocation, product roadmap planning, and competitive positioning.
This briefing outlines why this analysis matters now, what strategic layers it unravels, and how procurement, R&D, and channel leaders can translate its findings into measurable advantage. Rather than cataloguing incremental shipment figures, the study maps structural forces, capability gaps, and procurement inflection points that will define winner-take dynamics through 2032.
The Trajectory: Why 2026 Is a Strategic Anchor Year
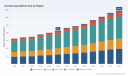
Historical demand patterns reveal a market that has consistently expanded rather than fluctuated with short-cycle technology hype. From 2020 through 2025, global revenue progressed steadily, reflecting sustained deployment cycles in telecommunications, institutional networks, and enterprise infrastructure. The base year of 2025 establishes a clear baseline, and the forward projection through 2032 indicates a compound annual growth rate of approximately 6.0 percent, with market size scaling into the mid-300 million USD range by the end of the forecast window.
This trajectory is not merely a function of incremental device replacements. It reflects compounding pressures: fiber-to-the-x expansions in underserved regions, densification of metro and long-haul routes, and the proliferation of high-capacity fiber arrangements within data center campuses. Organizations that treat the splicer market as a static procurement category risk misaligning budget cycles, inventory strategies, and service-level commitments. By anchoring decisions in a 2026-2032 lens, leaders can evaluate total cost of ownership, technology migration timelines, and supplier reliability under realistic deployment velocity rather than point-in-time pricing snapshots.
Optical Fiber Fusion Splicer Market
The research deliberately frames this growth as a structural shift in how connectivity is engineered, maintained, and scaled. Understanding which demand vectors are accelerating, which are plateauing, and where margin compression is likely allows strategy teams to prioritize investments that compound over the forecast horizon rather than chase short-term volume spikes.
What the Report Delivers: A Decision-Ready Intelligence Architecture
This study is built for operational use, not passive reading. It translates market signal into executable insight across four interconnected layers:
- Demand decomposition across technology categories, application environments, and geographic demand clusters, with emphasis on where capacity utilization, deployment complexity, and service intensity differentiate buyer behavior.
- Product architecture and performance signal analysis, covering core alignment versus ribbon and mass fusion workflows, automation maturity, field-ruggedization requirements, and how feature sets map to installation throughput and OPEX reduction.
- Procurement and policy context, including regulatory classification developments, standardization milestones, and public-sector sourcing activity that influence import costs, compliance risk, and government-adjacent demand pipelines.
- Competitive positioning and capability mapping, tracing how leading manufacturers differentiate through device performance, software connectivity, service ecosystems, and channel control.
Each layer is designed to reduce uncertainty in capital planning and product strategy. Procurement teams can benchmark supplier claims against functional reality, engineering leaders can prioritize feature roadmaps that align with high-growth deployment profiles, and partnership teams can identify where channel strength or after-sales support becomes a decisive differentiator in an increasingly fragmented supply base. The analysis intentionally avoids superficial segmentation summaries and instead focuses on the strategic weightings that determine which demand pockets will command pricing resilience, inventory discipline, and long-term supplier loyalty.
Competitive Landscape: Capability, Momentum, and Positioning Signals
The fusion splicer market is characterized by a relatively concentrated top tier alongside a broad field of regional and application-focused players. The five-firm concentration metric underscores that scale, brand recognition, and ecosystem maturity still command meaningful share, yet the remaining competition remains highly active in niche performance categories, ruggedized field tools, and ribbon or high-density fiber workflows.
Fujikura Ltd. continues to anchor its portfolio around core alignment optical fiber fusion splicers, including models built for telecom and enterprise environments, with increasing emphasis on cloud connectivity and low-loss splicing outcomes. Sumitomo Electric Industries, Ltd. reinforces its field and long-haul credibility through high-speed core alignment platforms that integrate GPS support, automatic cleave checking, and maintenance tooling designed to reduce installation variability. INNO Instrument Inc. has strengthened its positioning around rugged ribbon fiber support platforms, leveraging dual-camera architectures to serve data center and high-density deployment contexts where alignment precision and operational durability matter under demanding site conditions.
OFS Fitel, LLC maintains relevance through single-mode fiber splicing solutions embedded in telecom and enterprise networks, while Furukawa Electric Co., Ltd. extends its footprint across telecom carrier workflows and emergency repair scenarios, pairing core alignment capabilities with advanced ribbon and mass splicing functions. AFL Telecommunications LLC operates a complementary strategy by distributing Fujikura-branded platforms, including mass fusion models with intelligent alignment controls and automatic placement correction, enabling high-volume installation programs to benefit from established device performance with localized service reach.
Recent market momentum illustrates how product launches and institutional procurement activity can alter short-term demand visibility. In May 2026, AFL Telecommunications LLC introduced a Fujikura 100R mass fusion platform featuring automatic placement correction, a development that reduces operator intervention and aligns with high-throughput installation environments. Around the same period, the National Institute of Standards and Technology issued a Sources Sought solicitation to identify potential suppliers and vendors for fiber fusion splicer capabilities, signaling that government-adjacent acquisition planning is actively validating supply options for this equipment class.
Beyond product launches, regulatory and standardization developments are reshaping the market's operational backdrop. A U.S. Customs and Border Protection ruling classified a portable optical fiber fusion splicer under a telecommunications equipment tariff classification, a detail that procurement and import-planning teams must factor into landed-cost modeling and sourcing strategy. Separately, Sumitomo Electric Industries, Ltd. received recognition from Japan's Ministry of Economy, Trade and Industry for contributions to IEC and ISO international standards in optical fiber fusion splicing technology, reinforcing how standards leadership can function as a competitive moat in credibility, interoperability, and export-facing trust. These are not isolated news items; they are signals that connectivity equipment buyers must interpret when evaluating risk, compliance, and long-term supplier durability.
Strategic Implications: Where Decision-Makers Should Focus in 2026
The research translates the market's evolution into actionable priorities for three core functions:
- Procurement and supply chain leaders should stress-test supplier commitments against deployment complexity rather than unit price alone. As installation teams encounter higher fiber densities, tighter site constraints, and greater throughput expectations, device reliability, consumables availability, field-service responsiveness, and diagnostic software maturity become decisive cost drivers.
- Product and R&D teams should evaluate where automation, reduced operator intervention, and cloud-connected diagnostics can create defensible differentiation. In markets where installation labor and rework costs dominate total project expense, splicer platforms that minimize human variability can shift the value conversation from hardware price to operational efficiency.
- Commercial and partnership teams should map channel strength, regional service coverage, and standards-aligned credibility into their go-to-market strategy. In categories where purchase decisions are influenced by long-term support expectations and installer familiarity, ecosystem positioning often outweighs incremental feature announcements.
A critical insight is that the market's growth is not evenly distributed across buyer types or deployment contexts. Telecommunications-dominant demand, data center densification, and varied institutional or specialist applications each impose different performance thresholds, purchasing cycles, and service dependencies. Organizations that generalize their strategy across all segments risk diluting resources where competitive pressure is highest and overlooking pockets where technical specificity or service reliability commands premium positioning. The study isolates where differentiation is durable and where price competition is most likely to compress returns.
Why This Research Matters Now
2026 is not simply another forecast year; it is a calibration point where market momentum, product maturity, and procurement policy intersect. Buyers and suppliers alike are being asked to commit to equipment choices, service agreements, and capacity plans under conditions where installation scale, automation expectations, and public-sector sourcing activity are simultaneously evolving. A decision framework built on retrospective headlines or static segmentation will miss the strategic inflection points that determine margin endurance and market share stability.
Our full report extends well beyond this overview. It provides detailed assessments of demand composition, competitive capability mapping, regulatory and procurement watchpoints, and forward-looking deployment signals that help executives separate structural opportunity from transient noise. The objective is not to overwhelm with volume tables, but to equip teams with a clear lens on where to allocate attention, which supplier traits merit weight in sourcing decisions, and how to anticipate the next wave of installation-driven demand.
For leaders responsible for connectivity infrastructure, network expansion, or equipment portfolio strategy, the message is straightforward: the fusion splicer market is advancing along a definable growth path, but the strategic value lies in understanding which drivers will persist, which capabilities will command premium relevance, and where competitive intensity will reshape buyer expectations. This research is designed to convert that understanding into confident 2026 decisions and a stronger footing for the years that follow.
Worldwide Video Splicer Market
For detailed analysis of this topic, please visit the official page: Optical Fiber Fusion Splicer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oscilloscope Market to Reach $344.8M by 2032, Driven by 6.95% CAGR
By pmarketresearch, 2026-09-15
Navigating the Oscilloscope Market: Strategic Intelligence for the 2026 Decision-Maker
Executive Summary: The Pulse of Modern Electronics
As we move deeper into 2026, the landscape of electronic test and measurement is undergoing a transformative shift. The oscilloscope market, once a domain of purely analog signal visualization, has evolved into a complex ecosystem driven by high-speed digitalization, automotive electrification, and advanced telecommunications infrastructure. For industry leaders, investors, and strategic planners, understanding the trajectory of this market is not merely an academic exercise—it is a critical component of supply chain optimization, R&D allocation, and competitive positioning.
Our latest market research, the Oscilloscope Market Report 2026-2032, is designed to provide the granular intelligence necessary to navigate this complexity. This article serves as an introduction to the strategic value embedded within the report, highlighting key macroeconomic trends, competitive dynamics, and the technological forces shaping revenue projections through the end of the decade.
Dermatoscope Market
Market Trajectory: Growth Vectors and Macro Dynamics
The overarching narrative of the oscilloscope market during the forecast period is one of steady, resilient expansion. Based on historical data ranging from 2020 to 2025, the market has demonstrated consistent upward momentum, recovering from earlier disruptions and capitalizing on robust industrial demand. Our analysis projects this trajectory to continue through 2032, underpinned by a Compound Annual Growth Rate (CAGR) of 6.95%.
To contextualize this growth, consider the revenue progression over the recent past. In 2020, the market valuation stood at 163.15 Million USD. By 2025, this figure had climbed to 215.0 Million USD. This historical baseline establishes a solid foundation for the forecast period, where revenues are expected to breach the 300 Million USD mark by 2030, reaching 344.8 Million USD in 2032.
- Historical Context (2020-2025): The market grew from 163.15 Million USD to 215.0 Million USD.
- Forecast Horizon (2026-2032): Growth is projected to accelerate, moving from 232.32 Million USD in 2026 to 344.8 Million USD in 2032.
- Strategic Implication: The 6.95% CAGR indicates that while the market is mature, it is not stagnant. Growth is being driven by higher-value segments and technological upgrades rather than simple volume expansion.
These numbers represent more than just aggregate revenue; they reflect a shift in how engineering organizations allocate capital toward test equipment. The data suggests that as systems become more complex, the reliance on precision measurement tools becomes non-negotiable, securing long-term demand even amidst fluctuating macroeconomic conditions.
Oscilloscope Market
Competitive Landscape: Concentration and Innovation
One of the most defining characteristics of the oscilloscope market is the significant degree of consolidation among top-tier vendors. Our analysis indicates that the top five companies command a market concentration of 88.7%, while the top three hold a share of 72.3%. This high level of concentration suggests that barriers to entry remain substantial, particularly in the high-performance segments where reliability and bandwidth are critical procurement criteria.
However, within this concentrated landscape, there is vigorous competition driven by distinct technological niches. The role of key players such as Keysight Technologies, Tektronix, and Rohde & Schwarz remains pivotal. These firms are not merely competing on price; they are engaged in a race to deploy advanced analysis capabilities. For instance, the integration of AI-assisted analysis and high-speed digital capabilities is becoming a standard expectation for enterprise-grade instruments.
- High-Performance Dominance: Leaders like Keysight and Tektronix continue to push the envelope in high-speed digital and compliance testing, recently introducing platforms like the Infiniium XR8 and the 2 Series MSO to streamline bench-to-field workflows.
- Specialized Applications: Companies such as Teledyne LeCroy and Yokogawa focus on signal integrity and industrial precision, respectively, catering to niche but high-value engineering requirements.
- Accessibility and Expansion: Vendors from China, such as Siglent and Rigol, are carving out significant presence in entry-level and mid-range segments, offering high-resolution options that democratize access to advanced testing features.
- Portability Trends: The rise of USB-based and PC-integrated solutions, exemplified by companies like Pico Technology, reflects the market's demand for flexible, portable signal capture in field environments.
Understanding the nuances of these competitive moves is essential for procurement strategists. Knowing which vendor is excelling in specific bandwidths or form factors can dictate partnership opportunities and supply chain resilience. The full report details the specific strategic moves, product launches, and regional shifts of these key companies, providing a map of where market power is consolidating and where opportunities for disruption may lie.
Segmentation Nuances: Form Factors, Bandwidth, and Industry Verticals
While the aggregate market size provides a high-level view, the true strategic intelligence lies in understanding how demand is distributed across different segments. The market is fragmented by technology type, usage environment, and end-user industry. Our research dives deep into these splits to reveal where the highest growth potentials reside.
Form Factor Evolution
The choice between benchtop, portable, and PC-based oscilloscopes is increasingly dictated by the workflow of the engineering team. Benchtop units remain a staple for fixed lab environments, but the demand for portable and PC-based solutions is rising as testing moves closer to the production line and into the field. The interplay between these form factors influences inventory strategies and capital expenditure planning for manufacturing firms.
Bandwidth Requirements as a Proxy for Complexity
Bandwidth segmentation serves as a key indicator of the complexity of devices being tested. From low-bandwidth entry-level tools under 500 MHz to high-frequency instruments exceeding 4 GHz, the demand curve shifts based on the industry served. High-bandwidth instruments are critical for 5G infrastructure and high-speed digital computing, while lower bandwidths suffice for basic industrial maintenance and educational purposes.
- Low to Mid-Bandwidth: Segments below 500 MHz and between 500 MHz to 1 GHz represent substantial volumes, driven by general electronics and IT hardware.
- High-Bandwidth: The 1 GHz to 4 GHz and above 4 GHz segments represent specialized, high-value opportunities tied to aerospace, defense, and cutting-edge telecommunications.
Our report quantifies these preferences, helping stakeholders identify which bandwidth categories offer the best return on investment for specific product development cycles.
Industry Vertical Drivers
Demand is not uniform across industries. Automotive and Transportation, IT and Telecommunications, and Consumer Electronics are primary growth engines. However, the specific needs of Aerospace and Defense versus Medical and Life Sciences create distinct purchasing behaviors and technical specifications. For example, the electrification of vehicles requires robust testing protocols that differ significantly from those used in consumer gadget development. By isolating these vertical-specific drivers, companies can tailor their go-to-market strategies more effectively.
Regional Dynamics and Global Supply Chains
Geographically, the market exhibits varied growth patterns influenced by local manufacturing hubs, R&D centers, and regulatory environments. While North America and Europe maintain strong positions due to established industrial bases and high R&D spending, the Asia Pacific region represents a massive volume driver fueled by manufacturing activity and emerging tech adoption.
- North America: A hub for high-performance innovation and key vendor headquarters.
- Europe: Strong presence in automotive testing and industrial engineering sectors.
- Asia Pacific: Rapid expansion driven by electronics manufacturing and infrastructure development.
- Emerging Markets: Latin America and the Middle East/Africa present niche opportunities as industrial sectors in these regions modernize.
Supply chain resilience is a critical concern in 2026. Understanding regional dependencies helps organizations mitigate risks associated with logistics disruptions or localized regulatory changes. The report provides a detailed breakdown of regional revenue contributions, allowing firms to assess exposure and opportunity in each geography without relying on generalized assumptions.
Strategic Value for 2026 Decision-Makers
In an era where data is abundant but insight is scarce, the Oscilloscope Market Report 2026-2032 offers more than just statistics. It provides a framework for decision-making.
Investment and R&D Allocation
For product managers and R&D leaders, understanding which bandwidth categories and form factors are gaining traction allows for optimized resource allocation. Investing in test equipment that aligns with future market demand ensures that development cycles are not bottlenecked by inadequate measurement capabilities.
Competitive Positioning
Sales directors and business development teams can leverage the competitive landscape analysis to identify gaps in the market. Whether it is an underserved segment in a specific region or a technological feature that competitors have not yet standardized, the report highlights where strategic positioning can yield maximum impact.
Procurement and Supply Chain
Procurement officers benefit from the visibility into vendor concentration and regional supply dynamics. Knowing the market share distribution among top vendors aids in negotiation strategies and risk management, ensuring that critical testing hardware is sourced from stable and reliable partners.
Conclusion: Accessing the Full Intelligence
The oscilloscope market in 2026 is at a crossroads of technological innovation and steady economic growth. With a projected CAGR of 6.95% and revenues heading toward 344.8 Million USD by 2032, the sector offers substantial opportunities for those equipped with the right intelligence. However, surface-level data is insufficient for navigating the nuances of segment-specific growth, vendor capabilities, and regional shifts.
This article has outlined the macro trends and competitive framework defining the industry. Yet, the specific percentages, detailed segmentation splits, and comprehensive vendor profiles contained within the full Oscilloscope Market Report provide the actionable granularity required to turn strategy into execution. To make informed decisions that secure your organization's position in the test and measurement landscape, access to the complete dataset is essential.
We invite you to explore the full report to unlock the detailed insights needed to drive your strategic initiatives forward through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Oscilloscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Choosing a facial rejuvenation treatment is easier when you understand how it works, what results to expect, and whether it matches your aesthetic goals. Sculptra Fillers in Riyadh have become an option for patients interested in gradual collagen stimulation and natural-looking facial enhancement. Unlike conventional fillers that mainly focus on immediate volume, Sculptra encourages the body to produce collagen over time. Before getting started, patients should understand the treatment process, expected timeline, potential side effects, recovery, and importance of professional treatment planning.
What Is Sculptra?
Sculptra is an injectable treatment containing poly-L-lactic acid, a biocompatible material designed to stimulate collagen production. As the body's collagen response develops, treated areas may gradually appear fuller, firmer, and more youthful. The treatment is particularly appealing to people who prefer progressive changes rather than a sudden alteration in their appearance.
How It Works
After Sculptra is administered, the product acts as a collagen stimulator. The body gradually produces new collagen around the treated areas, helping improve structural support over time. Because this process takes time, patients should not expect the final result immediately after their appointment.
What Concerns Can Sculptra Address?
Sculptra may be considered for age-related facial changes associated with collagen loss and reduced volume. Depending on the individual's needs, it may help improve the appearance of areas such as the cheeks, temples, or lower face. It can also contribute to a firmer and more refreshed overall appearance.
Individual Treatment Goals
Every patient has different concerns and facial characteristics. Some may want to restore subtle volume, while others may be more interested in improving firmness and facial balance. A professional assessment helps determine whether Sculptra is appropriate and which areas may benefit from treatment.
What Happens During a Sculptra Consultation?
A consultation is an important part of the treatment process. The practitioner can examine your facial structure, evaluate your skin quality, discuss your aesthetic concerns, and review your medical and cosmetic treatment history. This information helps establish an individualized plan.
Questions to Discuss
Patients should ask how Sculptra works, how many sessions may be recommended, when results are expected, what side effects can occur, and what aftercare will be required. Discussing expectations openly can also help ensure that the planned result is realistic.
What Happens During the Treatment?
Once the treatment plan has been established, Sculptra is injected into selected areas using an appropriate technique. The exact approach depends on facial anatomy, treatment goals, and the areas being addressed. A qualified practitioner should explain the procedure before beginning.
Treatment Experience
Some patients may experience mild discomfort, pressure, tenderness, or sensitivity during injections. Temporary redness or swelling can also occur afterward. Your practitioner can explain what you may experience and provide guidance for making the procedure as comfortable as possible.
When Will Results Appear?
One of the most important things patients should know is that Sculptra produces gradual results. Temporary fullness or swelling may be noticeable shortly after treatment, but this should not be confused with the final collagen-related outcome. Improvements generally become more apparent over the following weeks and months.
Why Patience Matters
Collagen production is a natural biological process that takes time. Patients who understand this gradual timeline are more likely to have realistic expectations. Your practitioner can evaluate your progress and determine whether additional sessions may be appropriate.
How Many Sculptra Sessions Are Needed?
The number of sessions varies according to the individual's facial structure, collagen loss, treatment areas, and desired outcome. Some patients may benefit from multiple sessions planned at appropriate intervals rather than receiving all treatment at once.
A Personalized Approach
There is no universal treatment schedule that produces identical results for everyone. A customized plan allows the practitioner to consider your response to treatment and make adjustments when necessary.
What Is Sculptra Recovery Like?
Temporary swelling, redness, bruising, tenderness, or discomfort may occur following treatment. These effects generally improve as the treated areas settle. Patients should follow their practitioner's specific aftercare instructions and avoid unnecessary irritation during recovery.
Supporting Recovery
Your practitioner may provide recommendations concerning exercise, skincare, sun exposure, and other activities after treatment. Following professional guidance can help promote a comfortable recovery and support the treatment process.
Who May Be a Suitable Candidate?
Sculptra may be suitable for adults who want gradual facial rejuvenation and are experiencing changes associated with collagen loss. However, not everyone is an appropriate candidate. Medical history, allergies, active skin conditions, previous treatments, pregnancy or breastfeeding, and other factors should be discussed during consultation.
Realistic Expectations
Sculptra is intended to provide gradual improvement rather than an instant transformation. Patients should understand both its benefits and limitations before treatment. A qualified practitioner can explain whether the expected results align with your goals.
How Can Results Be Maintained?
Results can change naturally as the skin continues to age. Following a consistent skincare routine, protecting the skin from excessive sun exposure, maintaining healthy lifestyle habits, and attending recommended follow-ups can support overall skin quality.
Professional Maintenance
Some patients may consider future maintenance treatments as their results gradually change. The timing should be based on individual needs and professional assessment rather than a fixed schedule.
Book a Sculptra Consultation in Riyadh
If you are considering collagen-based facial rejuvenation, learning about the treatment through a professional consultation can help you make an informed decision. Sculptra Fillers in Riyadh can be discussed with the specialists at Royal Clinic Saudia , where your facial structure, skin condition, treatment history, and aesthetic goals can be assessed to create a personalized treatment plan.
PW Consulting: Toilet Tank Fittings Market to Hit $9.7B by 2032 at 7.5% CAGR
By pmarketresearch, 2026-09-15
Navigating the Toilet Tank Fittings Market: Strategic Intelligence for 2026 Decision-Making
The global plumbing fixtures sector stands at a critical inflection point. As infrastructure modernization accelerates and regulatory frameworks tighten around water efficiency, the toilet tank fittings market has emerged as a vital, yet often overlooked, component of the broader sanitation ecosystem. Our latest comprehensive market research provides a detailed examination of this space, offering actionable intelligence designed to support strategic planning throughout the 2026-to-2032 forecast horizon. This report is not merely a retrospective data compilation; it is a forward-looking strategic tool built to help manufacturers, distributors, investors, and procurement leaders navigate market complexity with precision.
The Macro Trajectory: Sustained Growth Anchored in Infrastructure and Efficiency Mandates
Over the historical analysis window spanning 2020 through 2025, the global toilet tank fittings market demonstrated consistent expansion, climbing from approximately 4,200 million USD in 2020 to a valuation of roughly 5,900 million USD by 2025. This upward trajectory reflects robust demand across residential renovations, commercial construction cycles, and the ongoing replacement of aging plumbing infrastructure. Looking ahead, our forecast period covering 2026 through 2032 projects continued momentum, with the market expected to reach approximately 6,181.95 million USD in 2026 and advance steadily toward a 9,700 million USD valuation by 2032. The implied compound annual growth rate of 7.5 percent underscores a resilient market structure supported by replacement-driven demand, sustainable building practices, and evolving municipal water standards.
For executive teams planning capital allocation, product roadmaps, or channel expansion, understanding the pacing of this growth is essential. The market does not experience sudden volatility; rather, it follows a measured, regulation-influenced expansion curve. Stakeholders who align their strategic timelines with this cadence will be better positioned to capture incremental share, optimize inventory positioning, and anticipate shifts in procurement behavior across downstream segments.
What the Report Delivers: Operational Depth Beyond Headline Metrics
A market study earns its executive shelf space only when it translates macro trends into operational guidance. Our research is structured to serve as a practical reference for cross-functional decision-making. The report is organized around several core analytical pillars, each designed to answer the questions that management teams face when allocating resources or evaluating competitive positioning.
Comprehensive Market Sizing and Forecast Modeling
The foundation of the analysis rests on a rigorously constructed revenue model that tracks historical performance and projects forward-looking demand scenarios. Rather than presenting a single-point estimate, the forecast framework accounts for multiple driving variables, including construction activity, renovation cycles, regulatory adoption timelines, and material cost fluctuations. Readers will find a transparent breakdown of the assumptions underpinning each projection phase, allowing leadership teams to stress-test scenarios against their own internal forecasts.
Segment-Level Structural Analysis
The market is inherently diversified, shaped by product architectures, end-use environments, and regional procurement patterns. Our segmentation framework maps these dimensions in detail, offering clarity on where volume concentrates, how value flows across product categories, and which application environments generate the strongest replacement and upgrade signals. This layered approach helps stakeholders identify high-priority segments for product development, sales targeting, and distribution optimization without relying on generalized industry assumptions.
Competitive Landscape and Firm-Level Intelligence
Market share dynamics in this space are shaped by a mix of specialized component manufacturers and broader plumbing solution providers. The report profiles leading participants, examining their product portfolios, geographic footprints, repair-and-maintenance positioning, and strategic responses to evolving building standards. Company-level insights are paired with a qualitative assessment of market concentration, giving readers a structured view of how incumbents defend share, where white space exists, and which competitive moves are most likely to reshape procurement preferences in the coming years.
Regulatory, Pricing, and Input-Cost Dynamics
Few plumbing-adjacent markets are as sensitive to policy shifts and input-cost pressure as toilet tank fittings. Regulatory programs that mandate high-performance, low-flow fittings directly influence product design requirements and replacement demand. At the same time, material and energy cost movements affect pricing strategies, margin management, and supplier negotiations. The report integrates these forces into a coherent dynamics section, helping readers anticipate how compliance mandates and cost pressures will interact with demand patterns and competitive pricing behavior.
Competitive Dynamics: Positioning Among Leading Manufacturers
The competitive environment in the toilet tank fittings market is defined by firms that balance broad compatibility, component reliability, and increasing emphasis on concealed and integrated flushing solutions. Several key companies anchor the landscape, each with distinct strategic identities and market approaches.
Fluidmaster, headquartered in Vista, California, has built recognition around universal toilet tank fill valves, flappers, and complete repair kits designed for both residential and commercial applications. Its product philosophy emphasizes compatibility and ease of replacement, which positions the company strongly in the aftermarket and maintenance segment. Korky, based in Wisconsin, pursues a similar universal-repair strategy but has also cultivated a strong identity around domestically manufactured components, including fill valves, flush valves, and flappers. Danco extends this universal-application theme with repair kits and hardware intended to span multiple brands, broadening its addressable maintenance audience. Geberit, rooted in Jona, Switzerland, represents a more system-oriented approach. Its portfolio covers concealed tank systems, flushing mechanisms, and replacement parts, aligning with projects that prioritize integrated design, concealed installations, and commercial-grade reliability.
Competitive strategy in this market is not solely about unit volume; it also revolves around catalog breadth, parts availability, service responsiveness, and the ability to align products with evolving code requirements. The report examines how these companies navigate the tension between standardization and specification-driven demand, particularly in commercial and hospitality environments where replacement cycles and procurement standards differ meaningfully from residential channels.
Toilet Tank Fittings Market
Recent Strategic Movements Shaping the Landscape
Market leadership is also revealed through operational decisions. In January 2026, Geberit North America released an updated product and parts catalog featuring revised concealed tank systems and replacement flushing components. Catalog refreshes of this nature signal continued investment in component availability and compatibility coverage, which directly affect specification choices and maintenance procurement. Later in the year, in June 2026, the company implemented a 2 percent price adjustment on plastic piping and select products, a move intended to offset rising energy and plastics costs. Pricing actions like this illustrate how manufacturers are managing input-cost pressure while balancing channel relationships and end-user expectations.
These developments are not isolated events. They reflect broader industry themes that the report explores in greater depth: the growing importance of updated parts portfolios, the sensitivity of pricing to material and energy markets, and the strategic need to maintain specification relevance as building standards become more stringent.
Regulatory and Environmental Forces Reshaping Demand
A defining feature of the toilet tank fittings market is the extent to which demand is shaped by water-efficiency policy. Regulation does not merely constrain product design; it actively redirects replacement cycles, influences specification decisions, and alters the mix of fittings required across different environments.
The EPA WaterSense program continues to reinforce expectations for high-performance, low-flow fittings in tank-type toilets, with maximum full flush volumes set at 1.6 gallons per flush. Compliance with such standards encourages the adoption of fittings that support effective bowl clearance while maintaining lower water usage, which in turn influences valve design, flapper performance, and fill control mechanisms. At a state level, standards such as California Title 20 impose additional parameters, requiring tank-type dual-flush toilets manufactured on or after January 1, 2025 to limit full flush volumes to 1.28 gallons per flush. These regional requirements illustrate how local policy can accelerate demand for upgraded components and push manufacturers to calibrate product lines for stricter performance thresholds.
For market participants, the strategic implication is clear: regulatory momentum creates both compliance necessity and commercial opportunity. Replacement programs in older installations, specification updates in commercial projects, and the continued rollout of water-efficient building standards all contribute to a sustained need for reliable, code-compatible fittings. The report connects these regulatory threads to segment-level demand outcomes, helping readers understand where mandate-driven replacement activity is most likely to concentrate.
Pipe Fittings Market
Strategic Implications for 2026 and the Forecast Horizon
As organizations move through 2026, several strategic priorities will separate reactive operators from proactive market participants. The report translates its findings into practical implication areas that management teams can use to guide planning across product, sales, procurement, and market-entry decisions.
Portfolio Alignment and Specification Relevance
With water-efficiency expectations continuing to rise, product portfolios must be evaluated not only for current compatibility but also for forward compliance. Companies that maintain strong coverage across fill valves, flush valves, flappers, and integrated replacement kits are better equipped to serve both maintenance-driven demand and specification-driven projects. The analysis highlights the importance of aligning product assortments with the regulatory thresholds most likely to influence purchasing decisions in key end-use environments.
Pricing, Margin, and Input-Cost Strategy
Recent pricing adjustments in the broader plumbing supply chain underscore the need for disciplined cost management. While market growth remains steady, margin performance can be influenced by plastics pricing, energy costs, and logistics pressure. The report contextualizes these forces within the broader market trajectory, helping leaders assess where pricing flexibility exists, how cost changes may be passed through, and what safeguards are necessary to protect profitability during periods of input-cost volatility.
Channel Focus and End-Use Targeting
Demand does not distribute evenly across residential, hospitality, and commercial building environments. Each channel presents distinct replacement cycles, specification processes, and purchasing behaviors. By mapping these differences, the research supports more targeted channel strategies, helping teams prioritize the environments where product availability, brand recognition, and service responsiveness deliver the greatest return. Rather than treating the market as a single monolithic segment, the report encourages a channel-aware approach to resource allocation.
Anticipating Competitive Shifts
The competitive structure of the market suggests that share gains are often won through service reliability, parts availability, and specification alignment rather than through price alone. Market concentration dynamics indicate a landscape where leading players hold meaningful influence, yet there remains room for differentiated positioning in repair kits, universal components, and concealed system offerings. Understanding where competitive pressure is intensifying, and where customer preferences are shifting, enables firms to make more informed decisions about product investment, geographic focus, and partnership strategy.
Why This Research Supports Better Decisions in 2026
Good market intelligence does more than describe the present; it helps organizations prepare for the next phase of competitive and regulatory change. This report is designed with that objective in mind. It combines macro market sizing, segment-level structural analysis, company profiles, regulatory context, and recent industry developments into a cohesive reference that executives, product planners, and commercial leaders can use throughout the year.
The audience for this research is deliberately broad but equally precise in its utility. Manufacturers can use the findings to evaluate portfolio priorities and specification readiness. Distributors and retailers can assess demand concentration and channel alignment. Investors and strategy teams can interpret growth pacing, competitive structure, and regulatory tailwinds when evaluating market exposure. Procurement leaders can better anticipate pricing dynamics and replacement demand patterns.
The complete research document provides the full depth required to support detailed planning: expanded forecast detail, segment comparisons, competitive profiles, regulatory impact assessment, and scenario-friendly modeling assumptions. It is structured so that decision-makers can move quickly from high-level insight to operational action without relying on fragmented sources or incomplete market summaries.
Next Steps: Access the Full Intelligence
The macro direction of the toilet tank fittings market is clear, but the strategic value lies in the details: where demand is building, how regulatory standards are reshaping component requirements, which competitive moves are redefining availability and pricing, and how organizations can position themselves for the 2026-to-2032 period with confidence. To make those decisions with precision, leaders need the complete dataset, segment mapping, and competitive analysis that this report provides.
We invite executives, product leaders, and commercial strategists to access the full version of the market research for a comprehensive view of the market landscape. The complete report extends far beyond the summary trends presented here, offering the structured intelligence necessary to support product planning, channel strategy, competitive positioning, and investment decisions in a market defined by steady growth, regulatory influence, and evolving component standards. In a sector where timing, compliance readiness, and portfolio relevance determine outcomes, the right intelligence is not optional; it is a strategic asset.
For detailed analysis of this topic, please visit the official page: Toilet Tank Fittings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Etch Equipment Market Reaches $25.13 Billion in 2025, Projects 7.61% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Semiconductor Etch Equipment Market: A 2026 Outlook
The semiconductor manufacturing landscape is entering a decisive phase where equipment capability defines technological leadership. As node sizes shrink and 3D architectures become the standard, the etch process stands as a critical bottleneck and enabler. For executives and investors navigating the 2026 fiscal year, understanding the trajectory of the Semiconductor Etch Equipment Market is not merely an operational concern but a strategic imperative. PW Consulting presents a comprehensive analysis designed to illuminate the path forward, offering clarity amidst volatile demand cycles and tightening regulatory frameworks.
The market has demonstrated remarkable resilience and growth over the past half-decade, evolving from a recovery phase into a sustained expansion period. According to our latest research, the overall market size is projected to reach new heights as we move through the decade. Starting from a base of approximately 25.13 billion USD in 2025, the trajectory indicates a steady climb toward nearly 42 billion USD by 2032. This growth is underpinned by a compound annual growth rate that reflects robust demand across high-performance computing and memory sectors. Such figures represent more than just revenue; they signal a fundamental shift in capital expenditure priorities as manufacturers race to secure supply chain sovereignty and technological edge.
Our report serves as a navigational tool for these complex waters. It dissects the market mechanics without fluff, providing actionable intelligence for strategic planning. Below, we offer a preview of the analytical depth contained within the full study, highlighting why this intelligence is essential for organizational decision-making in 2026.
Market Dynamics and Growth Trajectories
The current valuation of the sector reflects a compound effect of technological adoption and geographic shifts in manufacturing capacity. The progression from 2020 to 2025 shows a clear upward trend, with revenue expanding from 16.0 billion USD to over 25 billion USD. This historical context validates the investment thesis for etch technology but also raises questions about sustainability and concentration risks. The forecast period extending to 2032 suggests that this momentum is not accidental. It is driven by the intensifying requirements for atomic-scale precision in conductor and dielectric processes.
While the aggregate numbers are impressive, the true value for decision-makers lies in understanding the drivers behind the growth. The full report details the segmentation across equipment types, distinguishing between the dominance of dry etch solutions versus wet etch applications. It explores the process-specific demands, analyzing how conductor etch and dielectric etch segments are diverging in terms of growth velocity and technological complexity. Furthermore, the application landscape is scrutinized, revealing how logic chips and memory chips are contributing differently to the revenue pool. Each segment presents unique risk profiles and opportunity sets that require tailored strategic approaches.
Access to the granular data behind these segments is crucial. Organizations need to know not just that the market is growing, but where the growth is concentrated and which technologies are capturing the premium value. The complete analysis provides the necessary breakdown to inform capacity planning, R&D allocation, and partnership strategies without relying on generalized industry assumptions.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a high degree of concentration, where a select few players command the majority of revenue share. Our analysis indicates that the top three companies hold a significant portion of the market, while the top five consolidate even greater dominance. This oligopolistic structure creates a high barrier to entry for newcomers and forces established players to constantly innovate to maintain margins. For stakeholders, this concentration implies that competitor moves must be monitored with extreme precision.
Several key enterprises define the current competitive arena. Applied Materials and Lam Research Corporation remain pivotal forces, each leveraging distinct technological advantages. Tokyo Electron Limited continues to expand its manufacturing footprint to meet demand, while Hitachi High-Tech Corporation and Oxford Instruments plc offer specialized solutions for niche but critical applications. ASML Holding N.V., though often associated with lithography, plays an intertwined role in the broader equipment ecosystem. Other significant contributors include ULVAC, Inc., NAURA Technology Group Co., Ltd., SPTS Technologies Ltd, Plasma-Therm LLC, and SAMCO Inc., each carving out positions based on specific regional strengths or technological niches.
Semiconductor Etch Equipment Market
Recent developments among these key players offer a window into future strategies. Lam Research Corporation, for instance, has been aggressive in both product innovation and ecosystem building. In early 2025, they launched the Akara conductor etch tool, emphasizing atomic-scale precision via DirectDrive plasma control technology. This was followed by a donation of leading-edge multi-chamber etch systems to UC Berkeley for advanced R&D, signaling a commitment to securing the talent pipeline and validating technology in academic settings. Later in the year, collaborations focused on dry resist technology further underscore the industry's shift toward atomic layer etching and deposition.
Tokyo Electron Limited responded to capacity pressures with a facility expansion announcement in Miyagi, aimed at boosting plasma etch systems manufacturing. Meanwhile, Oxford Instruments plc made strides into adjacent emerging sectors, supplying atomic layer etch systems for quantum device fabrication. These moves are not isolated; they are strategic bets on where the next wave of demand will originate beyond traditional logic and memory nodes. Our report analyzes these movements to help clients anticipate competitor capacity expansions and technology pivots.
Regulatory Environment and Geopolitical Risks
No analysis of the semiconductor equipment market in 2026 is complete without a rigorous assessment of the regulatory landscape. The industry is operating under a cloud of evolving export controls and bipartisan legislative actions that directly impact equipment deployment and supply chain logistics. The dynamic nature of these regulations means that compliance is not a one-time checklist but a continuous strategic variable.
Recent actions by the U.S. Department of Commerce Bureau of Industry and Security have tightened constraints significantly. In December 2024, new rules were implemented affecting advanced packaging semiconductor manufacturing equipment, including specific etch tools. This was accompanied by expansions to the foreign direct product rule, extending jurisdiction over foreign-produced equipment destined for certain regions. Additionally, numerous entities were added to the Entity List, and specific types of equipment were added to the Commerce Control List. These measures fundamentally alter the accessible market for major players and require careful navigation for any international supply chain.
Furthermore, legislative moves such as the Bipartisan MATCH Act introduced in April 2026 propose prohibitions on the sale of cryogenic etch tools and deep ultraviolet immersion lithography systems to countries of concern. These regulations create a bifurcated market scenario where technology access is determined by geopolitical alignment rather than purely economic factors. Our report integrates these regulatory variables into the market forecast, helping clients understand the potential impact on revenue streams and market entry strategies in restricted regions. Understanding the nuance of these controls is vital for avoiding compliance pitfalls while optimizing global footprint allocation.
The Strategic Value of Comprehensive Intelligence
In a market defined by high concentration, rapid technological shifts, and stringent regulations, surface-level data is insufficient for robust decision-making. The full PW Consulting report on the Semiconductor Etch Equipment Market goes beyond high-level summaries to provide the depth required for executive strategy. It connects the dots between revenue trends, competitive maneuvers, and regulatory constraints to paint a holistic picture of the operating environment.
The report details the segmentation splits that drive revenue, offering clarity on where capital is flowing. It examines the regional distribution of market value, highlighting the disparities between mature markets and high-growth regions without oversimplifying the complexities of local demand drivers. It provides a thorough examination of the production and consumption dynamics that define the supply-demand equilibrium.
Access to this level of detail allows organizations to:
- Validate internal projections against independent market data.
- Identify potential gaps in product portfolios relative to market demand.
- Assess the risk exposure associated with regulatory changes in key regions.
- Benchmark competitor activities to refine go-to-market strategies.
- Pinpoint emerging opportunities in specialized etch applications beyond standard CMOS manufacturing.
The semiconductor industry rewards those who can anticipate change before it becomes obvious. By leveraging our detailed segmentation data—covering types, processes, applications, and regions—clients can move from reactive planning to proactive strategy. The report includes profiles and strategies for the key companies mentioned, analyzing how their recent developments align with broader market trends. This competitor intelligence is crucial for understanding who is gaining share, who is investing in which technologies, and where the next competitive threats may emerge.
Plasma Etch System Market
Moreover, the analysis considers the macroeconomic context, including the currency valuation and revenue units that frame the financial expectations. The forecast period through 2032 provides a long-term horizon for ROI calculations, allowing stakeholders to justify capital expenditures in equipment development or acquisition. The distinction between dry and wet etch equipment, for example, is not just a technical classification but a financial indicator of where the industry is placing its bets for the next decade. Similarly, the split between conductor and dielectric processes reveals the relative intensity of backend versus frontend manufacturing investments.
Conclusion: Navigating the Next Phase
The Semiconductor Etch Equipment Market is at a crossroads where technological capability and geopolitical reality intersect. The growth trajectory is clear, but the path to capturing value is fraught with complexity. Companies must balance the drive for innovation with the constraints of international regulation. They must watch the few dominant players while keeping an eye on specialists who may disrupt specific segments. They must allocate resources across logic and memory applications without knowing exactly which node will define the next cycle.
PW Consulting's full market research report is designed to equip leadership teams with the intelligence needed to make these judgments with confidence. We invite you to access the complete study to unlock the specific data points, regional breakdowns, and strategic recommendations that will inform your 2026 planning. Do not rely on assumptions when the stakes involve billions in capital and the future of technological sovereignty.
For detailed segmentation data, comprehensive competitor profiles, and in-depth regulatory impact analysis, please visit our dedicated market research portal. The complete intelligence package offers the granularity required to turn market insights into competitive advantage.
For detailed analysis of this topic, please visit the official page: Semiconductor Etch Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Mascara Market Hits $7.5B in 2025, Poised for 6.09% CAGR Growth Through 2032
By pmarketresearch, 2026-09-15
Global Mascara Market 2026: Strategic Intelligence for Competitive Advantage
Setting the Stage: Why This Research Matters Now
The global cosmetics industry is entering a decisive growth cycle, and mascara remains at the center of category innovation. As consumer expectations around wear performance, ingredient transparency, and sustainability continue to reshape purchasing behavior, brands and manufacturers must act on evidence rather than intuition. The latest PW Consulting Mascara Market study delivers exactly that foundation. Covering historical data from 2020 through 2025 with a forward-looking forecast extending to 2032, our analysis is built to help leadership teams evaluate where to invest, how to position portfolios, and which competitive pressures will define the next several years of category development.
The market has already demonstrated steady expansion across the past half-decade, reaching an estimated valuation of 7.5 billion US dollars in 2025. Growth momentum is projected to continue into the forecast window, with the category advancing toward a compound annual growth rate of 6.09 percent between 2026 and 2032. By the terminal year of our modeling horizon, total market value is expected to exceed 11 billion dollars. These are not abstract numbers; they reflect the combined impact of innovation cycles, formulation differentiation, retail infrastructure shifts, and evolving demand patterns in both mainstream and prestige channels. For decision-makers, the central question is no longer whether the category is growing, but which structural forces will determine who captures disproportionate share within it.
This article previews the strategic architecture of our full report. It outlines the business questions the research is designed to answer, describes the operational content included inside the study, and situates the most recent industry developments into a defensible competitive context. Core segment splits, detailed regional breakdowns, and company-specific revenue figures are intentionally held back. That architecture is deliberate: the complete intelligence is structured for use in board-level planning, portfolio reviews, and market-entry assessments, and it belongs in your hands where it can be applied with precision.
The Strategic Value of Data-Backed Forecasting for 2026 Decisions
A market study becomes strategically useful when it converts numerical trends into decision-ready intelligence. For 2026, executives face a particularly crowded field of competing priorities: formulation innovation must be balanced against cost discipline, distribution strategies must align with channel consolidation and digital-led purchase journeys, and sustainability commitments must be translated into credible product narratives that withstand scrutiny. In that environment, high-level growth statements offer little direction. What matters is how the growth breaks down across use cases, format categories, regional demand intensity, and competitive positioning.
The PW Consulting research is built around that requirement. Rather than presenting a single aggregate projection, the analysis is organized to help teams evaluate the category from multiple business angles at once. Readers can examine how different usage occasions contribute to total category pull, assess which product characteristics are most closely associated with repeat purchase behavior, and compare regional market size with structural demand signals. That multi-layered approach is essential because mascara is not a monolithic category. Daily wear routines, event-driven application, and professional makeup contexts each generate distinct purchasing logic, and the relative weight of those contexts shapes everything from SKU architecture to marketing investment.
Equally important, the forecast period is structured to support operational planning. A six-year outlook enables supply chain teams to test capacity assumptions, finance departments to build scenarios around revenue ramps, and product organizations to sequence innovation pipelines with realistic timing. Instead of relying on short-term snapshots, leadership gets a view of how the category is likely to scale and where acceleration or deceleration may occur as competitive intensity and consumer preference evolve.
What the Study Delivers: Operational Content for Real-World Planning
The report is designed for immediate application. It moves beyond high-level commentary to provide content that marketing leaders, product developers, procurement professionals, and strategic planners can use directly in day-to-day decision-making. Among the practical components included are:
Mascara Market
Lipstick Market
- A historical reconstruction of market movement from 2020 to 2025, allowing teams to test how past disruptions, channel shifts, and product launches influenced category performance.
- A forward forecast through 2032 that supports scenario planning for capacity, investment timing, and portfolio prioritization.
- Detailed segmentation across product types, usage occasions, and geographic demand patterns so that strategy teams can identify where specialized formulations and targeted messaging create the strongest commercial logic.
- Competitive analysis covering the major global players and specialized manufacturers shaping supply, innovation, and private-label capability.
- Recent industry developments, including trade show launches and materials innovation, placed in context to show how product and packaging advances are influencing the competitive field.
The segmentation framework is especially valuable for organizations deciding how to allocate limited resources. When companies can see how distinct product attributes relate to overall market structure, they are better positioned to prioritize claims development, packaging choices, and brand differentiation. In practice, that means fewer assumptions about where category growth is concentrated and more confidence in which product narratives deserve shelf space, promotional support, and R&D investment.
Competitive Dynamics in a Concentrated Market
Planning in the mascara category requires an honest assessment of competitive concentration. The market remains led by a small group of large multinational companies, with the top three firms together accounting for a substantial share of category revenue and the top five firms holding an even larger collective position. That structure shapes pricing power, innovation cadence, and channel influence. Large players benefit from broad brand portfolios, established distribution relationships, and the ability to scale successful formulas across multiple consumer tiers. At the same time, the presence of specialized manufacturers, private-label suppliers, and regional leaders creates meaningful opportunities for partners and challengers who can execute with focus.
Several global names define the competitive core. L'Oréal operates across mass and prestige with a wide portfolio that spans accessible and premium performance claims. The Estée Lauder Companies competes in the higher-end space through brands known for advanced wear, curl retention, and premium application experience. Procter & Gamble maintains a strong mass-market footprint with products built around affordable volume and lengthening performance. Coty Inc. continues to play a significant role in color cosmetics with long-wear and waterproof positioning. Shiseido extends the competitive field in Asia with high-precision formulas and conditioning-focused benefits, while Chanel anchors prestige demand with luxury brush design and long-lasting pigmentation. Amorepacific remains closely aligned with K-beauty preferences, particularly around curling and lengthening effects.
Beneath the brand owners, the supplier and contract manufacturing layer is equally important. Schwan Cosmetics specializes in high-volume private-label production with broad texture options and full-service manufacturing capability. Geka GmbH supplies sustainable brush and packaging solutions, including materials using post-consumer recycled content with low-emission decoration processes. HCP Packaging has introduced renewable applicator technologies aimed at reducing dependence on conventional synthetic materials. In the contract and export segment, Homax Cosmetics, Columbia Cosmetics, Xiran Cosmetics, and Aurora Global Brands each support different combinations of budget and premium positioning, private-label customization, and international distribution. Together, this ecosystem determines how quickly new formulas can reach market, how much differentiation can be achieved through applicator and packaging design, and where cost efficiencies are possible without sacrificing product quality.
Latest Developments Shaping Competitive Positioning
Recent activity in materials, packaging, and sustainability commitments is already influencing the category's next competitive cycle. At the trade-show level, Geka GmbH introduced a music-inspired mascara brush collection with updated brush designs and shadow printing on fully post-consumer recycled packaging. Alongside that launch, HCP Packaging presented a cellulose-derived renewable fiber applicator technology developed as an alternative to traditional synthetic materials. These developments are not isolated design exercises; they reflect broader pressure on manufacturers and brands to reduce environmental footprint while preserving application performance and shelf appeal. In that context, packaging and applicator innovation are becoming part of the product proposition itself, not just a logistics consideration.
Sustainability is also entering the formulation conversation more directly. One of the largest multinational players has expanded its long-term sustainability program with a commitment to make its mascara formulations biodegradable or naturally derived by 2030. That kind of public target changes expectations across the supply chain. It raises the bar for ingredient sourcing, encourages supplier partnerships around material innovation, and increases the importance of credible claims language. For competitors and partners alike, it signals that environmental performance is moving from a marketing overlay to a core development requirement.
For industry participants, these shifts create both risk and opportunity. Companies that can integrate performance, sustainability, and application experience into a coherent package will be better positioned to justify premium positioning and consumer loyalty. Those that rely solely on legacy formulas or conventional materials may find it harder to defend differentiation as buyer expectations and regulatory attention continue to increase.
How to Use This Research for Strategic Planning
The report is most valuable when treated as a working document for cross-functional planning. Product teams can use it to evaluate where formulation innovation is likely to generate the strongest return and how to sequence development relative to category demand. Commercial leaders can use it to refine channel and geographic priorities without relying on guesswork about where demand depth is greatest. Procurement and operations teams can use the forecast structure to align capacity and sourcing decisions with a realistic growth path. And corporate strategy groups can use the competitive overview to assess partnership opportunities, private-label dynamics, and the positioning of challenger brands against established leaders.
This preview is intended to demonstrate the scope and rigor of the full study, not to replace it. The market framework, segmentation architecture, company profiles, and competitive developments are built to support precise decisions in a category where small differences in product performance, packaging credibility, and usage positioning can translate into meaningful share movement over time. The full report provides the underlying figures, segmentation detail, and scenario context needed to move from directional insight to actionable planning.
For organizations preparing for 2026 and beyond, the strategic imperative is clear: understand the market structure early, anticipate where innovation and sustainability expectations are heading, and use validated data to prioritize investment. The PW Consulting Mascara Market research is designed to support that process from the first strategic review through ongoing portfolio management.
For detailed analysis of this topic, please visit the official page: Mascara Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com