

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Induction Cooktop Market to Hit $34.67 Billion by 2032, 5.6% CAGR: PW Consulting Insight

Strategic Intelligence for the Induction Cooktop Market: Navigating the 2026 Decision Landscape
Executive Overview
The global kitchen appliance sector is undergoing a structural shift, and the induction cooktop segment stands at the forefront of this transformation. For executives, product strategists, and capital allocators operating in 2026, the ability to parse market momentum, competitive positioning, and regulatory tailwinds is no longer a supplementary advantage—it is a baseline requirement for sustainable growth. Our latest Induction Cooktop Market research report has been engineered to deliver precisely that clarity. Built on a rigorous historical foundation and extended through a multi-year forecast horizon, this study translates complex market signals into actionable strategic intelligence.
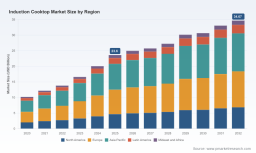
The market has demonstrated remarkable expansion over the past half-decade. Revenue climbed from 10.2 billion USD in 2020 to 23.6 billion USD in 2025, reflecting a compound annual growth trajectory that underscores deepening consumer preference for energy-efficient, precision-controlled cooking surfaces. Looking forward, the market is projected to reach approximately 25 billion USD in 2026, with sustained upward momentum carrying valuations past 34 billion USD by 2032. This expansion is not merely a function of unit volume; it reflects a broader realignment in household appliance portfolios, commercial kitchen retrofitting cycles, and regulatory frameworks that actively incentivize electrification.
Our report treats these headline figures as starting points, not endpoints. The real strategic value lies in understanding the structural forces that will determine which companies capture margin expansion, which product architectures dominate specific use cases, and how supply-chain realities will shape competitive execution in the years ahead.
The Strategic Imperative for 2026 Decision-Makers
Reading the Growth Architecture
Market growth in the induction cooktop space is being driven by intersecting demand vectors. Residential adoption continues to accelerate as homeowners and renters prioritize faster heat response, improved indoor air quality, and compatibility with modern kitchen designs. Commercial environments are simultaneously re-evaluating induction solutions for their precise temperature control, reduced kitchen heat load, and alignment with sustainability mandates. The report dissects how these application dynamics interact with product architectures, revealing where demand concentration creates pricing leverage and where fragmentation rewards agility.
Importantly, the growth trajectory is not uniform across all segments or geographies. The research maps the relative weighting of regional demand, highlighting where mature markets are pivoting toward premium upgrades and where emerging regions are experiencing first-time electrification waves. By separating baseline volume growth from structural adoption shifts, the analysis enables leadership teams to distinguish between cyclical noise and durable market expansion.
For corporate planners, this distinction is critical. Investing in capacity, distribution, or marketing initiatives based on aggregate growth figures alone can lead to misaligned resource allocation. Our forecast framework provides the granularity required to calibrate entry timing, prioritize channel investments, and evaluate whether a particular submarket offers sufficient depth to justify dedicated go-to-market execution.
Induction Cooktop Market
Competitive Positioning and the High-Stakes Arena
Mapping the Enterprise Landscape
The competitive environment in this market is defined by a blend of incumbent appliance manufacturers, premium European engineering houses, and specialized commercial equipment providers. Market concentration metrics indicate that the top three players command a meaningful share of total revenue, while the top five collectively approach nearly half of the market. This concentration signals both the attractiveness of the category and the intensity of competitive rivalry. Companies that fail to differentiate on performance, durability, or connected features risk being compressed into commodity positioning.
Several enterprise players are actively shaping the category through product innovation and brand segmentation. GE Appliances has reinforced its position with a full-line induction portfolio, including the GE Profile series that emphasizes precision control and connected kitchen capabilities. Samsung Electronics continues to push functional differentiation through Flex Zone configurations and power boost technologies designed to streamline home cooking workflows. In the premium residential segment, Miele & Cie has built enduring reputation on durability and long-term reliability, appealing to consumers who view cooking appliances as long-horizon investments.
North American manufacturers are also leveraging multi-brand architectures to cover distinct price and performance tiers. Whirlpool Corporation extends its induction offerings through JennAir, KitchenAid, and Whirlpool, each targeting specific consumer expectations around temperature control and surface maintenance. Electrolux Group has focused on surface engineering, notably through Frigidaire models that incorporate advanced coatings aimed at improving scratch resistance. BSH Hausgeräte operates across Bosch, Thermador, and Gaggenau, offering high-output and full-surface induction solutions that span mainstream and luxury kitchen segments. On the commercial side, The Vollrath Company specializes in professional-grade induction equipment designed for restaurant and foodservice environments where throughput, controllability, and durability are non-negotiable.
Understanding how these players compete requires more than a brand-by-brand summary. The report assesses how product line breadth, regional distribution strength, and technology roadmaps interact to create competitive moats. It also examines where overlaps in target audiences create direct head-to-head pressure and where portfolio gaps invite new entrants or private-label expansion.
Recent Product and Market Movements
Recent product introductions illustrate the pace at which feature competition is escalating. In March 2026, Frigidaire introduced a MatteGuard induction cooktop surface engineered to reduce visible scratches by a significant margin, directly addressing a common consumer concern around long-term aesthetic degradation. Earlier, in August 2025, JennAir launched a temperature-controlled induction cooktop following a Best in Show recognition at KBIS 2025, reinforcing the importance of culinary precision as a purchase driver. In February 2025, Fire Magic unveiled what was described as the first built-in outdoor induction cooktop at KBIS 2025, expanding the addressable use-case envelope with precise temperature control spanning a broad operating range.
These launches are not isolated events; they signal broader strategic themes. Surface durability, temperature precision, and environment expansion are becoming central battlegrounds. The report places these developments within a competitive timeline, helping readers evaluate which innovations are likely to become baseline expectations versus which will sustain premium pricing power.
Regulatory and Structural Dynamics Shaping the Market
Policy Tailwinds and Efficiency Standards
Regulatory and incentive frameworks are playing an increasingly decisive role in shaping demand patterns. Efficiency advocacy has moved from niche sustainability conversations into mainstream procurement criteria. Publicized efficiency comparisons have emphasized that induction appliances can operate substantially more efficiently than conventional electric smooth-top ranges and significantly more efficiently than gas alternatives. This narrative is reinforcing both consumer preference and institutional purchasing guidelines, particularly in regions where energy policy aligns with appliance modernization targets.
Incentive programs are also altering the economics of adoption. Rebate structures for certified efficient models have entered the market with meaningful financial impact, lowering effective purchase barriers and accelerating replacement cycles. At the same time, buyer guides and recognition programs are helping governments and manufacturers identify high-quality, energy-efficient models at scale. These initiatives do more than stimulate short-term demand; they create reference points that influence brand credibility, specification standards, and retailer merchandising strategies.
For companies operating in this space, regulatory momentum represents both opportunity and execution risk. Alignment with recognized efficiency benchmarks can unlock promotional leverage and public-sector eligibility. Conversely, failure to keep pace with evolving specification language or incentive requirements can marginalize otherwise competitive products. The report examines how these dynamics interact with regional market structure and what they imply for product roadmap planning.
Supply-Chain Realities and Input Dependencies
Beyond demand-side forces, the market's expansion is moderated by structural supply considerations. Key input materials, including ceramic glass and induction coils, remain heavily dependent on import flows from China. This concentration exposes manufacturers to currency volatility, logistics disruption, and geopolitical friction. In a category where surface finish, thermal performance, and component reliability are closely tied to customer satisfaction, input availability and quality consistency are not merely cost issues—they are product integrity issues.
The research addresses these dependencies by mapping where supply-chain vulnerability is most likely to influence pricing, lead times, and margin stability. It also frames the strategic options available to firms seeking to reduce exposure, whether through supplier diversification, inventory buffering, or design adjustments that maintain performance while easing procurement constraints. Understanding the intersection of input risk and competitive timing is essential for any organization planning capacity investments or long-term product commitments.
Inside the Report: A Practical Intelligence Toolkit
Scope, Structure, and Decision-Use Design
This study is designed to support multiple internal use cases simultaneously. It integrates historical valuation data, forward-looking forecasts, segmentation analysis, competitive profiling, and market-dynamic contextualization into a single coherent framework. Rather than functioning as a static data sheet, the report is structured to help teams move from market awareness to decision readiness.
The analysis covers the evolution of market size across the 2020 to 2025 historical window and extends through the 2026 to 2032 forecast period, enabling both retrospective validation and forward planning. Segmentation views examine how the market divides by product type, application context, and regional demand concentration, giving readers a multi-axis perspective on where value is being created. The competitive section profiles core enterprise players, their headquarters 위치와 product positioning, and the strategic implications of their portfolio strategies. Recent developments are organized to show how product launches and industry initiatives are reshaping expectations in real time.
In addition, the report integrates regulatory and structural forces that influence market behavior, including efficiency recognition programs, rebate frameworks, and material supply dynamics. These contextual layers are not appended as background notes; they are woven into the analytical narrative so that readers can see how policy, sourcing, and product innovation interact to shape commercial outcomes.
What Leadership Teams Can Do With This Intelligence
For strategy leaders, the report provides a foundation for evaluating market entry, expansion, or repositioning decisions. For product teams, it offers a structured view of feature prioritization and segment alignment. For commercial and sales leadership, it clarifies where demand intensity, competitive pressure, and incentive environments are likely to shape conversion dynamics. For supply-chain and operations stakeholders, it highlights input dependency risks and the strategic importance of robustness in sourcing and inventory planning.
Stainless Steel Cookware Market
By connecting macro growth signals to segment behavior and competitive action, the research reduces the gap between high-level market awareness and operational execution. It is built to support scenario discussion, investment prioritization, and cross-functional alignment around a shared view of market direction.
Conclusion: Making 2026 Decisions With Confidence
The induction cooktop market is moving with enough velocity, complexity, and competitive intensity that legacy assumptions can quickly become liabilities. Growth is real, but its distribution across regions, applications, types, and brand positions is uneven. Policy incentives, efficiency narratives, product innovation, and supply-chain dependencies are all influencing who wins share and who merely participates.
Our Induction Cooktop Market research report is designed to help organizations navigate that complexity with discipline. It provides the market-size architecture, segmentation perspective, competitive mapping, and dynamic context needed to frame 2026 decisions with greater precision. The headline trajectory points to continued expansion, but the strategic opportunities—and risks—reside in the details that determine execution advantage.
For leaders who need a full, structured intelligence package rather than a high-level overview, the complete report offers the deeper segmentation view, forecast breakdown, and competitive analysis required to convert market awareness into confident, evidence-based action.
For detailed analysis of this topic, please visit the official page: Induction Cooktop Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com