
Blogs
In Aion 2 , Templar performance in small-scale PvP is defined less by raw toughness than by disciplined timing. Equipment choices, including upgrades available through Aion 2 Items , can support durability, but the decisive factor is knowing when defense should become pressure.
A defensive skill is not merely a way to reduce incoming damage. Used at the correct moment, it can preserve health while an opponent spends valuable abilities, leaving the Templar ready to control the next exchange.
Read the Offensive Sequence Before Responding
Many opponents begin with a light control effect or a low-value attack to provoke an early defensive response. Activating protection immediately may keep the Templar safe for a few seconds, yet it also gives the opponent freedom to retreat and prepare a stronger sequence.
Instead, watch for commitment. Rapid movement toward the Templar, major visual effects, repeated control attempts, and sudden resource spending often indicate that the real assault has started. Defense becomes more valuable once the enemy has invested enough that withdrawing would waste important abilities.
Hold Protection for the Critical Moment
Saving a defensive ability does not mean accepting unnecessary damage. The goal is to identify which attacks can be endured through armor, positioning, healing, or a smaller response. The strongest protection should answer the part of the sequence that would otherwise force the Templar out of the fight.
Good timing also creates uncertainty. When an opponent cannot predict the defensive response, they may hesitate, interrupt their own rhythm, or spend additional resources trying to secure a result. That hesitation gives the Templar more room to reposition and choose a target.
Track Enemy Recovery Time
After surviving the enemy's main assault, the Templar should quickly evaluate what remains available. If the opposing player has used mobility, control, and high-impact damage together, the following seconds often provide the safest opportunity for aggression.
| Enemy Action | Templar Response |
|---|---|
| Mobility used to engage | Block the assault, then restrict retreat |
| Control effects spent | Advance with less fear of interruption |
| Major damage abilities exhausted | Apply steady pressure and force movement |
This assessment should include nearby enemies as well. A Templar who rushes forward after stopping one attacker may enter another player's prepared abilities. Counterpressure works best when the immediate target is vulnerable and outside help is limited.
Turn Survival Into Controlled Aggression
The transition from defense to offense should be immediate but deliberate. Close distance, apply control, and use reliable attacks before committing every offensive resource. The objective is to prevent recovery while retaining enough protection to handle a final escape attempt or unexpected reinforcement.
Positioning remains essential during this phase. Pressure the target toward walls, narrow paths, or separation from allies. In small encounters, controlling where the fight continues can be more valuable than pursuing maximum damage.
Templar players succeed by treating every defensive choice as preparation for the next exchange. Thoughtful gearing through Aion 2 Items buy options may strengthen the foundation, while patience, cooldown awareness, and decisive counterpressure determine who controls the fight.
Grow a Garden 2 is increasingly being approached as a planning game rather than a simple crop loop. Players looking through Grow a Garden 2 Items often discover that a well-chosen addition can influence not only harvest output, but also the way an entire garden is organized.
The most satisfying plots now tend to reflect a clear personal goal. Some players pursue efficient routines, while others build colorful spaces that make every visit feel like a small creative project. That variety gives the experience a lasting appeal.
Starting With a Clear Garden Identity
Before filling every open space, it helps to decide what the garden should accomplish. A player focused on steady materials may arrange crops differently from someone collecting unusual varieties or designing a decorative display.
This early decision reduces wasted movement later. Instead of placing everything as soon as it appears, players can reserve areas for repeated tasks, seasonal experiments, and special plants that deserve extra attention.
Tools Can Shape the Daily Routine
Useful equipment does more than speed up a single action. The right tool can make watering, planting, gathering, or maintenance feel smoother across several short sessions. That matters for players who prefer checking in briefly rather than spending hours in one sitting.
A practical routine usually has three priorities.
Keep frequently used supplies easy to reach.
Save limited resources for crops with meaningful returns.
Leave room to test new additions without rebuilding everything.
Small improvements become more noticeable when they support a regular pattern. A garden that is easy to read at a glance lets players spend less time searching and more time deciding what to grow next.
Discovery Gives Collections Their Value
Collection progress feels stronger when every new item has a possible purpose. Even a piece that is not immediately useful may inspire a future layout, complete a themed area, or support a later objective.
This creates a pleasant tension between using something now and saving it for a better opportunity. Rather than treating every reward as disposable, players can build a flexible reserve that supports changing plans.
Social Inspiration Changes How Plots Evolve
Community screenshots and shared ideas have made garden design more expressive. One player may use clean rows for clarity, while another creates winding paths, color-focused corners, or dedicated harvest zones.
These examples are valuable because they show that efficiency and personality do not have to compete. A tidy garden can still feel distinctive when its sections have recognizable roles and visual rhythm.
A Long-Term Garden Benefits From Patience
The strongest progress usually comes from consistent attention instead of rushing every choice. Checking needs, adjusting a layout, and setting aside useful supplies can turn modest daily actions into a much larger result over time.
For players who want to refine that approach, browsing GAG 2 Items can provide ideas for the next stage while keeping each garden goal focused and enjoyable.
Buying an Arcade in GTA Online is a useful step if you want faster access to casino missions, extra income, and a private base for future plans. The first thing to handle is the meeting with Lester Crest. Open the map and find the green H marker, then follow the new L symbol to Mirror Park. After the short scene, the Arcade properties become available. If you are building your collection of GTA 5 Accounts , this property is worth considering because its value goes well beyond the games on the floor.
Start With the Lester Meeting
Many players open the property website too early and wonder why no Arcades appear. The listing stays hidden until the Mirror Park introduction has been completed. Lester explains the casino plan, and that conversation unlocks the next stage. It does not take long, but it is easy to miss if you are focused on other activities. Once the scene ends, use your phone, open the browser, and visit the foreclosure property site.
Compare Locations Before Spending
The map shows six Arcade sites, stretching from Paleto Bay to Davis. Location matters more than the decorations because preparation work often sends you across Los Santos. A central property can save a lot of driving, especially when you are working through several setup tasks in one session. Eight-Bit in Vinewood costs more, with a base price of $2,530,000, but its position is convenient for regular casino work.
| Arcade choice | Main advantage | Best suited to |
|---|---|---|
| Vinewood | Shorter city travel | Frequent casino missions |
| Davis | Southern access | Players based near Los Santos |
| Paleto Bay | Lower entry cost | Smaller early budgets |
Spend Carefully on Upgrades
After choosing a site, the renovation screen lets you shape the interior. You can change the style, mural, floor design, and neon displays. Some additions are more practical than others, so think about how you actually play. Living Quarters give you a convenient spawn point. A garage helps with vehicle storage. High Score Screens look good, but they are mainly a visual extra.
Choose the location before spending on decoration.
Add Living Quarters if you want a nearby spawn point.
Consider a garage if you often change vehicles.
Leave cosmetic upgrades for later when cash is tight.
Make the Arcade Work for You
Confirm the purchase once the setup feels right. Your money is taken immediately, and the building becomes yours. Visit the property, place arcade machines across the floor, and keep the machines filled to improve daily takings. The basement is the real reason most players buy the site, since it provides the planning area for the casino job. With sensible spending and a central location, the Arcade can support your wider business plans while you work toward goals such as buy Grand Theft Auto V Money through your normal in-game progress.
What Makes Changhengsaws Plywood Cutting Blades Suitable for Production Needs
By Changhengsaws, 2026-09-17
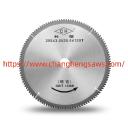
Plywood Cutting Blades can influence how efficiently a workshop handles different panel materials, especially when production involves varied thicknesses, surface structures, and machining requirements. Selecting suitable tooling starts with understanding the material being processed and matching its characteristics with the equipment used. Factors such as tooth geometry, diameter, kerf width, rotation speed, and feed rate can all affect the final result. A suitable combination can help reduce unnecessary adjustments while supporting a smoother production routine.
Panel composition is one of the first factors worth reviewing. Different boards may contain several veneer layers, adhesive structures, surface coatings, or decorative finishes. These characteristics can change how the material responds during machining. A configuration intended for one type of board may not provide the same result when used on another. Buyers should therefore consider the structure and thickness of their regular materials before selecting a suitable specification.
Thickness also plays an important role in equipment selection. Thin sheets may require a different setup from thicker boards because the processing conditions can influence edge condition and material stability. When production includes several thickness ranges, manufacturers may consider specifications that provide suitable performance across their regular workload. This approach can reduce the need for frequent equipment changes and make daily production planning easier.
Tooth geometry deserves careful attention as well. The number, arrangement, and shape of teeth influence how material is removed during operation. A suitable configuration can help achieve cleaner edges while supporting an appropriate feed rate. For workshops producing furniture components, cabinet panels, interior fittings, or construction related boards, these details can affect both appearance and processing time. Buyers should compare the tooling specification with the intended application instead of selecting equipment based only on size.
Machine compatibility is another practical consideration. Arbor dimensions, equipment capacity, rotational speed, and operating direction should all be checked before purchase. Even when two tools have similar external dimensions, their recommended operating conditions may differ. Confirming these details with the equipment manufacturer or supplier can help avoid installation problems and unnecessary production interruptions.
Production volume can also influence the selection process. A small workshop with occasional panel processing may have different requirements from a factory operating multiple shifts. Higher workloads can make durability, maintenance routines, and replacement planning more important. Manufacturers should consider expected operating frequency, material consumption, and production schedules when evaluating different specifications.
Feed rate and rotational speed should also be considered together. Operating outside the recommended range can influence edge condition, noise, heat generation, and service life. Proper machine setup allows the tooling to work within an appropriate operating range. Regular inspection is useful as well. Checking tooth condition, mounting stability, and visible wear can help operators identify issues before they affect a larger production batch.
For manufacturers, consistency is often closely connected with repeatable processes. Using compatible equipment, maintaining suitable machine settings, and following a regular inspection schedule can make daily operations easier to manage. It can also help operators identify differences between material batches and adjust production parameters when necessary.
Changhengsaws provides tooling options for manufacturers working with different panel processing requirements. Product selection can be discussed according to material type, equipment specifications, dimensions, and expected operating conditions. This makes it easier for buyers to communicate their application needs before confirming an order.
A practical selection process does not need to be complicated. Start with the material, identify the required thickness range, check machine compatibility, review the working conditions, and then compare suitable specifications. This method gives buyers a clearer basis for equipment selection while helping workshops organize production with fewer unnecessary changes. For product specifications and application options, manufacturers can review https://www.changhengsaws.com/product/
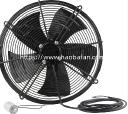
Compact ventilation equipment can provide practical advantages when installation space is limited or when the motor and impeller need to be integrated into a unified structure. An External Rotor Fan places the rotor outside the stator assembly, allowing the motor structure to be incorporated closely with the rotating impeller. This arrangement can support compact equipment design while maintaining a direct relationship between the motor and airflow-producing components.
The external rotor concept differs from conventional motor arrangements in the way the rotating motor element is positioned around the stationary part of the motor. Because the rotor is integrated with the fan assembly, the overall construction can be arranged within a relatively compact housing. This design approach is commonly considered for ventilation equipment where available installation space and equipment layout are important factors.
One significant consideration is the relationship between the motor and impeller. Since the motor is closely integrated with the rotating assembly, manufacturers need to control component alignment and mechanical stability during production. The impeller must rotate smoothly, while the motor needs to provide consistent driving force under the intended operating conditions. Proper assembly can reduce unnecessary mechanical stress and support stable airflow.
Impeller design remains central to the overall performance of the equipment. Blade geometry affects how air enters the rotating assembly and how effectively it is directed toward the outlet. Engineers may evaluate blade shape, angle, material selection, and structural rigidity according to the intended ventilation application. Consistent manufacturing is important because differences in blade geometry can influence airflow and rotational balance.
Material selection is another important factor. Fan components may be exposed to dust, humidity, temperature changes, or other environmental conditions depending on where the equipment is installed. The housing, impeller, mounting structure, and motor-related components therefore need materials that are appropriate for the operating environment. Corrosion considerations can become particularly relevant in industrial or agricultural ventilation applications.
Thermal management is also important in an integrated motor design. Electrical motors naturally generate heat during operation, and ventilation equipment may operate for extended periods. The surrounding airflow and structural arrangement can influence how heat is dissipated. Manufacturers should consider motor operating conditions, ventilation pathways, and material characteristics when developing an integrated fan assembly.
Balance control is essential because the impeller and rotor rotate together. Even relatively small imbalance can result in vibration during operation. Excessive vibration may affect mounting structures, bearings, motor components, and surrounding equipment. Production inspection and balancing procedures can therefore play an important role in maintaining mechanical stability and reducing unnecessary operating disturbance.
Noise control involves several factors beyond the motor itself. Blade movement, airflow turbulence, vibration, housing resonance, and installation conditions can all contribute to sound. Appropriate blade design, accurate balancing, secure mounting, and suitable airflow pathways can help address these factors. The surrounding ductwork or ventilation opening should also be considered because system configuration can influence the final acoustic environment.
Maintenance is generally easier when the equipment is installed with adequate access and when the ventilation pathway remains clean. Dust and debris can accumulate around the impeller and housing, potentially influencing airflow and mechanical balance. Periodic inspection should also check mounting points, protective guards, electrical connections, and visible signs of wear. Maintenance should follow the manufacturer's intended procedures and applicable safety requirements.
Applications for compact integrated fan designs can include equipment cooling, cabinet ventilation, workshop air circulation, air-conditioning systems, refrigeration equipment, and various industrial ventilation installations. The appropriate design depends on the airflow path, available installation space, environmental conditions, and system requirements. Buyers should evaluate the complete application rather than selecting equipment only by physical appearance.
From a procurement perspective, an External Rotor Fan should be evaluated through both motor construction and complete fan-system design. Manufacturing consistency, component quality, balancing processes, inspection procedures, and technical support can all affect the suitability of the equipment for a particular installation. Taizhou Haoba Electromechanical Co Ltd. offers ventilation solutions for different industrial applications, with further product information available at https://www.haobafan.com/product/mixed-flow-fan/ for customers reviewing compact and integrated airflow equipment.
Emergency Plumbers in Boca Raton: Are You Prepared for a Plumbing Emergency?
By allclearofsouthflorida, 2026-09-17
A plumbing emergency can happen when you least expect it. One minute, everything is fine. The next, water may be rushing across your floor. Emergency plumbers in Boca Raton FL can help when a serious leak, burst pipe, or sewer backup puts your home at risk.
But knowing who to call is only one part of being ready. You should also know how to stop the water, protect your belongings, and spot signs of trouble early. These simple steps can help prevent bigger damage and costly repairs.
What Qualifies as a Plumbing Emergency?
Not every plumbing problem needs help right away. A small dripping faucet can usually wait for a normal repair visit. However, some problems can quickly cause serious damage. A plumbing emergency may include a burst pipe, a large leak, a blocked sewer line, or a toilet that keeps overflowing.
A badly leaking water heater can also become a major concern. These problems can damage floors, walls, furniture, and other parts of your home. Knowing what counts as an emergency helps you act quickly when it matters most.
What Should You Do During a Plumbing Emergency?
Your first few actions can help limit the damage. If water is spreading quickly, find your home's main water shutoff valve and turn it off if you can do so safely. For a problem with one fixture, such as a sink or toilet, you may only need to close its small shutoff valve.
Then move valuable items away from the water. Keep electronics, papers, furniture, and other belongings in a dry place. If water is near electrical outlets, wires, or appliances, do not step into it. Move away from the area and wait for professional help.
Take clear photos of the damage, too. These pictures may be helpful when you speak with your insurance company or the plumber.
How Can Boca Raton Homeowners Prepare in Advance?
You do not want to search for answers while water is flooding your home. A little preparation can make an emergency much easier to handle.
Keep These Essentials Accessible
- Know where the main water shutoff valve is.
- Keep a plumber's phone number in your phone.
- Keep simple tools where adults can easily find them.
- Look at exposed pipes for rust, cracks, or damage.
- Know where your water heater and shutoff controls are.
- Watch for slow drains, strange sounds, and small leaks.
Boca Raton homes can face plumbing problems caused by several factors. Heavy rain, moisture, older pipes, and high water use can all affect plumbing systems. Checking your plumbing from time to time can help you find small problems before they become bigger ones.
Why Professional Diagnosis Matters?
A quick fix may hide the real problem. For example, a drain that keeps getting blocked may have a deeper clog. A sudden change in water pressure could also point to a damaged pipe or another plumbing issue.
Emergency plumbers in Boca Raton FL can inspect the system and find the source of the problem. They can then explain what needs to be fixed and how the repair should be done. Before hiring a plumber, ask about their experience, license, insurance, pricing, warranty, and expected arrival time. Clear answers can help you make a safer and smarter choice.
Final Thoughts
The best time to prepare for a plumbing emergency is before it happens. Learn where your water shutoff valve is, keep important phone numbers nearby, and pay attention to warning signs such as leaks, slow drains, strange smells, or unusual water pressure.
If a problem starts spreading quickly, act fast and keep everyone safe. Having a plan can reduce stress and limit damage. When serious trouble occurs, emergency plumbers in Boca Raton FL can help restore your plumbing and get your home back to normal.
PW Consulting: EV Pantograph Market Hits $485.5M in 2025, Surging to $805.47M by 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Worldwide Pantographs for Electric Vehicles Market: Navigating the 2026–2032 Outlook
The worldwide pantographs for electric vehicles market is undergoing a structural transformation that demands immediate strategic attention from infrastructure developers, automotive OEMs, public transit authorities, and energy service providers. As urban electrification accelerates and zero-emission mobility mandates tighten, pantograph-based charging and power collection systems have evolved from niche electrification components into critical enablers of commercial fleet readiness and public transport modernization. Our latest market research publication delivers a comprehensive, data-backed assessment of this sector, framed to equip executive teams with the analytical clarity required to align capital allocation, partnership strategies, and product roadmaps throughout the 2026–2032 forecast horizon.
Market Trajectory and Core Forecast Signals
The sector has demonstrated consistent expansion across the historical window, with total revenue advancing from approximately 339.22 million USD in 2020 to an estimated 485.5 million USD in 2025. This progression reflects sustained commercial-vehicle electrification momentum, infrastructure modernization programs in leading metropolitan corridors, and accelerating adoption of high-power opportunity charging architectures for heavy-duty electric buses and tram networks. Looking forward, the market is projected to reach 523.68 million USD in 2026, with continued growth steering the sector toward 805.47 million USD by 2032.
At the core of this trajectory lies a forecast compound annual growth rate of 7.5 percent across the full assessment window. This growth profile signals more than incremental volume expansion; it indicates an ecosystem-wide shift in how cities and fleet operators approach electric commercial mobility. The rate underscores the compounding impact of regulatory pressure, operational efficiency imperatives, and the maturation of charging hardware compatible with high-load transit cycles. However, despite the clarity of the aggregate direction, the strategic value of this research lies in its ability to translate these headline numbers into actionable intelligence. Understanding where demand concentrates, which product configurations gain traction, and how value migrates across supply chains requires a level of segmentation detail that only the full report provides.
Why This Research Matters for 2026 Decision-Making
For strategy leaders operating in the electric mobility infrastructure space, 2026 represents a pivotal inflection point. Capital programs initiated today must account for hardware durability, compatibility with high-power transfer architectures, compliance with evolving regional standards, and cost structures influenced by both raw material volatility and specialized installation requirements. Pantograph systems sit at the intersection of mechanical engineering, high-voltage energy transfer, and urban transport planning, meaning that decisions made now will shape competitive positioning for the remainder of the decade.
This research is designed to reduce uncertainty in that planning process. Rather than stopping at top-line forecasts, the study dissects the operational and commercial variables that determine real-world deployment economics. It examines how product design choices influence installation complexity, how power-transfer capabilities align with fleet duty cycles, and how regional regulatory frameworks are shaping procurement criteria. The goal is to give decision-makers a structured framework for assessing risk, identifying white space, and evaluating whether to build, buy, partner, or localize components within their value chains.
What the Report Delivers
The full publication is organized to support both strategic planning and tactical execution. It integrates historical performance data with forward-looking analysis, enabling readers to benchmark current portfolios against market trajectories and anticipate demand shifts before they are fully priced into supply contracts. The report also includes a detailed examination of the factors reshaping cost dynamics across the pantograph ecosystem, including material pricing volatility, specialized labor constraints, and the impact of design innovations on deployment speed and system performance.
Readers will also find an in-depth exploration of the operational requirements that distinguish pantograph deployments from conventional charging infrastructure. Because these systems serve heavy-duty commercial fleets and rail-based transit applications, the analysis addresses compatibility considerations, safety standards, environmental protection expectations, and the practical realities of integrating roof-mounted or inverted configurations into existing vehicle platforms. The report evaluates how these constraints are driving product differentiation, influencing procurement specifications, and altering the cost-benefit equation for fleet operators comparing pantograph-based opportunity charging with alternative energy transfer models.
Additionally, the research maps the evolving technology landscape, including engineering advances that are reducing system weight, improving deployment speeds, and expanding the range of viable operating conditions. These innovations matter because they directly affect uptime, service frequency, and total cost of ownership for commercial electric fleets. By capturing how design evolution intersects with performance requirements and procurement priorities, the report provides a narrative that goes far beyond volume projections.
Competitive Landscape and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment, with the top three firms accounting for approximately 55 percent of market value and the top five collectively representing about 72 percent. This concentration reflects the specialized engineering requirements of pantograph systems, the importance of certification and reliability records, and the role of long-term infrastructure partnerships in securing recurring deployment opportunities. It also means that late entrants or smaller players must navigate meaningful barriers if they aim to compete on integration capability, technical performance, or procurement trust.
Several established players define the current competitive frontier. Schunk Group remains a leading provider of pantographs for electric bus charging and rail electrification, offering dynamic and static pantograph systems designed for overhead contact lines in EV infrastructure. ABB supplies pantograph-based charging solutions for electric buses and trucks, including its Pantograph Charging System integrated with high-power DC chargers. Siemens Mobility develops pantographs for electric road vehicles such as buses, with a focus on high-speed opportunity charging and systems compatible up to 1 MW power transfer. Alstom provides pantographs for electric buses and trolleybuses, extending its APS system capabilities into overhead pantograph charging applications. Heliox offers pantograph charging technology for electric buses, including automated roof-mounted pantographs suited to megawatt-level fast charging. Setec Power manufactures dynamic pantographs for electric buses and commercial vehicles, with deployments tied to large-scale electric bus fleets in China. WEG supplies pantograph systems for electric bus charging, supporting overhead catenary charging within Latin American e-bus networks.
Worldwide Mobile Charging Robot for Electric Vehicle Market
Recent activity among these firms reinforces the pace of competitive escalation. In October 2025, ABB launched an upgraded Pantograph Charging System v2.0 for electric buses, introducing 1.5 MW capability and improved alignment sensors. In June 2025, Siemens Mobility deployed pantograph charging infrastructure for 50 electric buses across Hamburg’s public transport network. In March 2025, Schunk Group received IEC 61851 certification for its new generation of dynamic pantographs used in EV bus charging. In November 2024, Heliox signed a joint development agreement with VDL Bus for pantograph integration on next-generation electric coaches. These moves illustrate how product upgrades, regional deployments, certification milestones, and partnership structures are compounding into defensible competitive positions.
For customers and investors, the strategic question is not simply who leads today, but which capabilities will matter most in the next procurement cycle. The full report provides company-level analysis, including positioning narratives, product emphasis, deployment relevance, and the strategic implications of recent announcements. That level of detail is essential for benchmarking vendor options, anticipating partnership opportunities, and evaluating where the market is likely to reward differentiation.
Industry Dynamics Shaping the Next Cycle
Several structural forces are reshaping the operational environment for pantograph systems. On the supply side, raw material pricing continues to exert pressure on component economics. Copper prices for pantograph contact strips have risen sharply year over year amid supply constraints tied to mining disruptions, creating cost volatility that manufacturers and integrators must absorb or pass through. This dynamic is particularly relevant because contact-strip material quality affects conductivity, wear performance, and long-term maintenance requirements, making input-cost management a strategic concern rather than a simple procurement task.
Regulatory expectations are also becoming more explicit. In Europe, EU Regulation 2024/1680 mandates that pantograph systems used in e-bus charging comply with IP67 ingress protection and EN 50121-4 EMC standards. Such requirements elevate the importance of conformity testing, region-specific design adjustments, and documentation readiness. They also create a competitive advantage for suppliers with mature certification pathways and experienced integration teams.
Technology-driven performance gains are equally significant. Advances in carbon fiber reinforced polymers have reduced pantograph weight by roughly 25 percent compared with aluminum, enabling faster deployment speeds of up to 40 km/h. These changes influence vehicle packaging, cycle times, and operational flexibility, especially for high-frequency transit routes and opportunity charging scenarios where alignment precision and rapid engagement matter. Engineers and fleet planners are increasingly evaluating these improvements as part of the broader business case for pantograph-based electrification.
On the commercial implementation side, installation economics remain an important consideration. Average installation costs for pantograph infrastructure can be substantial in mature labor markets, where skilled labor rates and site preparation requirements drive project budgets higher. This reinforces the value of planning that accounts for total deployed cost rather than hardware price alone, particularly for operators expanding networks across multiple cities or jurisdictions.
Safety and scope limitations also define market boundaries. Pantographs for EVs are restricted to commercial vehicles over 3.5 tonnes, and passenger car use is prohibited under UN ECE R100 safety norms. This regulatory framing shapes the addressable market in practical terms, directing investment toward bus fleets, rail and tram systems, and light rail transit use cases rather than mass-market passenger car segments. Recognizing those boundaries early helps teams avoid misaligned roadmap assumptions and focus on the segments where pantograph value propositions are both viable and defensible.
Worldwide Pantographs for Electric Vehicles Market
Why the Full Report Is Essential for Execution
Aggregate figures and competitive narratives provide the starting point for strategy, but they do not replace the precision required for procurement planning, market entry decisions, or investor communication. The complete Worldwide Pantographs for Electric Vehicles Market study extends far beyond the summary view presented here. It delivers detailed segmentation insights, demand distribution patterns, application-level context, regional performance dynamics, and vendor-level intelligence that collectively enable organizations to translate market direction into operational plans.
For infrastructure developers, the report supports site-level economic modeling and technology selection. For component manufacturers and system integrators, it clarifies where product roadmaps should be concentrated and how certification and performance standards are influencing purchasing criteria. For fleet operators and transit authorities, it informs total-cost comparisons and deployment sequencing. For investors and strategy teams, it identifies where concentration, innovation, and regulatory alignment are likely to create durable advantages or expose vulnerability.
The strategic value of this analysis is that it bridges the gap between directional market growth and the granular decision-making that determines execution success. Organizations that rely only on top-line data risk underestimating segmentation opportunities, overstating addressable scope, or misjudging the speed at which compliance and cost pressures will reshape procurement behavior. The complete report is structured to mitigate those risks by providing the depth that planning teams require when they move from market awareness to action.
Conclusion: Positioning for the 2026–2032 Cycle
The worldwide pantographs for electric vehicles market is expanding along a clear growth path, but the most consequential strategic choices will be made in the details. Which product architectures align with high-power opportunity charging needs, how compliance requirements affect regional rollout speed, where material and installation costs reshape economics, and which competitors are strengthening moats through certification, partnerships, and deployment records all determine whether organizations capture value or merely follow the market.
This research is built to support those choices with analytical rigor and practical context. It translates historical performance and forecast direction into a framework for strategic planning across the 2026–2032 period, while leaving the most decision-critical segmentation and competitive intelligence to the full publication. For teams evaluating market entry, portfolio expansion, vendor selection, or long-term infrastructure investment, the complete report offers the level of depth required to move forward with confidence. To access the full market intelligence, detailed segmentation breakdowns, competitive profiles, and forward-looking deployment context, request the complete study and integrate its findings directly into your 2026 strategy process.
For detailed analysis of this topic, please visit the official page: Worldwide Pantographs for Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Compressed Breathing Air Testing Market to Hit $260.78 Million by 2032, 5.01% CAGR
By pmarketresearch, 2026-09-17
Strategic Imperative: Navigating the Global Compressed Breathing Air Testing Market in 2026
In an era where operational safety and regulatory compliance dictate the license to operate, the integrity of compressed breathing air has emerged as a critical frontier across multiple sectors. From firefighters relying on self-contained breathing apparatus during life-threatening emergencies to medical facilities safeguarding patient health through mandated gas purity, the demand for rigorous testing protocols is accelerating. As enterprises navigate a complex landscape of evolving standards and technological advancements, access to precise market intelligence is no longer a luxury but a strategic necessity. This article serves as an introduction to the comprehensive Worldwide Compressed Breathing Air Testing Market research report published by PW Consulting, designed to empower leadership teams with the foresight required for decisive action in 2026 and beyond.
Market Trajectory and Growth Foundations
Understanding the momentum of this industry requires a clear view of its historical performance and future trajectory. Our analysis tracks the market's evolution from 2020 through the forecast horizon extending to 2032. The data indicates a consistent expansion pattern, reflecting the heightened awareness of respiratory safety and the tightening of global compliance frameworks. In the base year of 2025, the market established a significant valuation, setting the stage for continued growth.
The forecast period from 2026 to 2032 suggests a robust path forward, driven by sustained investment in safety infrastructure and the adoption of advanced monitoring technologies. The compound annual growth rate observed during this interval underscores a healthy expansion trajectory that outpaces many traditional industrial maintenance sectors. For decision-makers, this growth signals more than just revenue potential; it represents a shifting priority landscape where air quality testing moves from a discretionary maintenance task to a core operational requirement. Companies that fail to align their service offerings or procurement strategies with this upward trend risk obsolescence in a market that is rapidly professionalizing.
The Landscape of Compliance and Safety Standards
The engine driving this market is not merely demand but regulation. The framework governing compressed breathing air is intricate, varying by application, geography, and specific operational hazards. In the United States, the Occupational Safety and Health Administration (OSHA) sets baseline requirements under standard 29 CFR 1910.134, mandating that atmosphere-supplying respirators utilize air meeting at minimum ANSI/CGA G-7.1-1989 Grade D specifications. These specifications cover critical parameters such as oxygen levels, carbon monoxide limits, and hydrocarbon thresholds.
However, compliance is often application-specific. The fire service sector operates under NFPA 1989, which imposes stricter limits on contaminants including carbon monoxide and dew point compared to general industrial standards. Similarly, across Europe, EN 12021 defines quality limits for contaminants in compressor and cylinder systems, ensuring a harmonized approach to safety within the continent. Recent updates to industry guidelines, such as those recommended by the British Compressed Air Society regarding purity classes, further illustrate the dynamic nature of these requirements. For organizations engaged in breathing air testing, maintaining agility in response to these regulatory shifts is paramount. Our report dissects these regulatory layers, providing a clear map of where compliance obligations intersect with market opportunities.
Technological Evolution and Service Models
The methodology of testing is undergoing a significant transformation. Historically, reliance on centralized laboratory analysis dominated the sector. While laboratory services remain a cornerstone of the market due to their precision and accreditation standards such as ISO 17025, the rise of portable testing kits and continuous monitoring systems is reshaping the competitive dynamics. Portable kits offer immediate field data, empowering end-users in diving, fire services, and manufacturing to conduct preliminary assessments or routine checks without waiting for off-site results.
Meanwhile, continuous monitoring systems represent the frontier of real-time safety assurance. Equipment manufacturers are increasingly integrating multi-gas monitoring capabilities directly into airline systems, offering instantaneous alerts on contaminants like carbon monoxide and water vapor. This shift aligns with the broader industrial trend toward Industry 4.0 and predictive maintenance. The market research delves into the adoption rates and strategic implications of these different testing methods, analyzing how the balance between outsourced laboratory services and on-premise monitoring solutions is evolving. For equipment manufacturers, this suggests new avenues for integrated service offerings, while for laboratory providers, it highlights the need for differentiation through speed, accreditation, and specialized support.
End-User Diversity and Sector-Specific Needs
The demand for compressed breathing air testing is not monolithic; it is fragmented across diverse end-user groups with distinct requirements. Fire and emergency services constitute a significant portion of the market, driven by the critical need for SCBA reliability and the adherence to NFPA 1989 standards. These departments require rigorous testing schedules and often integrate testing services directly with their compressor maintenance programs.
In the medical and healthcare sector, the focus shifts toward purity levels that ensure patient safety during respirator therapy or surgical procedures. Here, testing is often intertwined with broader facility compliance and quality assurance protocols. The diving and marine operations sector presents another unique challenge, requiring adherence to standards like CGA Grade E or PADI requirements, where gas purity is vital for diver safety underwater. Industrial safety and manufacturing also contribute substantially, utilizing breathing air for process applications and worker protection in hazardous environments. Each segment carries specific testing frequencies, contaminant limits, and accreditation preferences. Our analysis categorizes these segments to help stakeholders identify which verticals offer the most viable growth avenues for their specific capabilities.
Competitive Dynamics and Key Players
The competitive landscape of the compressed breathing air testing market is characterized by a mix of specialized accredited laboratories, equipment manufacturers, and hybrid service providers. Market concentration metrics indicate a competitive environment where no single entity dominates the entire value chain, allowing for niche specialization and regional strength. Several key companies define the current state of play.
In North America, TRI Air Testing stands out as an AIHA-accredited laboratory providing worldwide services for fire service, SCUBA, medical, and military applications. Their model emphasizes sampling kits and 24/7 technical support, catering to a broad range of compliance needs. Similarly, Trace Analytics (AirCheck Lab) has established a long-standing reputation since 1989, offering ISO 17025:2017 accredited analysis and proprietary AirCheck sampling kits compliant with major standards like NFPA 1989 and OSHA. Analytical Chemists Inc. further diversifies the laboratory landscape with patented processes for breathing air quality analysis across medical, pharmaceutical, and industrial sectors, often providing turnkey system certification.
Equipment manufacturers are also integral to the ecosystem. ENMET Corporation produces compressed airline monitors and filtration panels that meet OSHA 1910.134 requirements, facilitating real-time monitoring for supplied breathing air. In Europe, SUTO iTEC GmbH focuses on portable and stationary analyzers, such as the S605 Portable Breathing Air Quality Analyzer, designed for point-of-use monitoring at filling stations. Dräger contributes to this space with Aerotest systems capable of automatic analysis of multiple contaminants across a wide pressure range. AirChekLab Inc. serves the Canadian market with accreditation under CSA standards, while Breathing Air Systems integrates testing programs with BAUER compressor supply, serving thousands of fire departments.
Compressed Air Leak Detector Market
Recent Developments and Market Signals
Recent events highlight the vitality and responsiveness of this market. In mid-2025, SUTO iTEC GmbH released a new portable breathing air quality analyzer aimed at enhancing real-time data availability for filling stations, signaling continued innovation in portable monitoring hardware. Regulatory milestones also shape the landscape; for instance, NIOSH approval for new self-contained breathing apparatus models supports the compatibility and demand for associated compressed air system testing. Furthermore, industry bodies continue to refine purity guidelines. Updates suggesting specific air purity classes for manufacturing environments impact testing protocols indirectly by raising the bar for overall compressed air quality management.
For stakeholders, tracking these developments is essential. Product launches indicate where technology is heading, regulatory approvals validate new equipment ecosystems, and guideline updates preempt changes in testing requirements. Our report contextualizes these recent developments within the broader market strategy, helping readers anticipate how such events will alter competitive positioning and customer expectations over the forecast period.
Strategic Intelligence for 2026 Decision-Making
Why does this market research matter for your organization in 2026? Whether you are a laboratory seeking to expand your geographic footprint, an equipment manufacturer looking to bundle testing services, or a compliance officer evaluating vendor partnerships, the insights contained in this study are tailored to reduce uncertainty. The market is maturing, with increasing emphasis on accreditation, real-time data, and integrated compliance solutions.
By understanding the total addressable market size, the growth rates of key segments, and the strategic moves of competitors, you can allocate resources more effectively. The report provides a granular breakdown of regional dynamics without the opacity often found in aggregated industry reports. It details the specific revenue bases and growth velocities across North America, Europe, Asia Pacific, and other regions, allowing for targeted market entry or expansion strategies. It also disentangles the revenue contributions of laboratory services versus portable kits and continuous systems, enabling product managers to balance their portfolios according to where the growth money is flowing.
Furthermore, the analysis of end-user segments helps in tailoring marketing messages and service level agreements. A fire department's needs differ vastly from a pharmaceutical plant's, and a one-size-fits-all approach often fails in this specialized market. The included profiles of key companies offer benchmarks for operational scope, accreditation status, and service models, providing a reference point for competitive positioning.
Worldwide Compressed Breathing Air Testing Market
Conclusion: Taking the Next Step
The Worldwide Compressed Breathing Air Testing Market is at an inflection point where safety culture, regulatory stringency, and technological capability converge. The trajectory from 2020 through 2032 reflects a market that is expanding not just in volume but in sophistication. For businesses operating within or adjacent to this space, the margin for error is narrowing. Customers are increasingly informed, regulations are becoming more specific, and competitors are innovating rapidly.
This executive overview has highlighted the structural components of the market, the regulatory drivers, and the key players shaping the landscape. However, the full depth of strategic intelligence required to make high-stakes decisions lies within the complete report. To access the detailed segmentation data, precise regional revenue forecasts, comprehensive competitive profiles, and actionable recommendations, we invite you to explore the full study. Equip your strategy team with the detailed intelligence necessary to navigate the complexities of compressed breathing air testing and secure a competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Compressed Breathing Air Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Powder Transfer Pumps Market Hits $420M in 2025, Projects 5.5% CAGR to 2032
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Powder Transfer Pumps Market: A 2026 Outlook
The global landscape for material handling is undergoing a subtle but significant transformation. As industrial operations demand higher levels of safety, efficiency, and hygiene, the machinery responsible for moving dry bulk solids has moved from a background utility to a strategic asset. For decision-makers navigating the 2026 fiscal year, understanding the trajectory of the Powder Transfer Pumps Market is no longer optional; it is a critical component of operational planning and capital allocation.
PW Consulting has released a comprehensive market research study designed to decode these complexities. This article serves as an executive preview of the findings, outlining the macro-economic trajectory, the evolving competitive landscape, and the regulatory pressures shaping the industry. While we highlight the strategic contours here, the full report contains the granular data necessary for precise forecasting and vendor selection.
Market Trajectory and Financial Scope
The financial health of the powder transfer pump sector reflects broader industrial confidence. Our analysis covers a substantial historical window from 2020 through 2025, providing a robust baseline for future projections. The market has demonstrated resilience despite supply chain volatilities and shifting industrial outputs during this period. In 2020, the global revenue stood at approximately 345.21 Million USD. Following a period of fluctuation, the sector climbed to 420.0 Million USD by 2025.
Looking forward, the forecast period spanning 2026 to 2032 indicates sustained growth. The market is projected to reach 443.54 Million USD in 2026, accelerating towards a peak valuation of 610.97 Million USD by 2032. This expansion is driven by a Compound Annual Growth Rate (CAGR) of 5.5 percent. For CFOs and operations directors, this growth rate signals a stable investment environment, though one that requires careful attention to inflationary pressures and technological adoption curves.
It is important to note that these figures represent the aggregate global value. The distribution of this revenue across specific geographies and application verticals varies significantly based on local industrial maturity and regulatory enforcement. Our full report dissects these variations to help stakeholders identify high-opportunity zones without relying on generalized assumptions.
Segmentation Dynamics: Type and Application Nuances
Understanding where value is generated within the supply chain is vital for product development and sales strategies. The market is broadly categorized by pump technology and end-use industry. In terms of technology, pneumatic solutions currently dominate the revenue share, reflecting their widespread adoption in standard industrial environments. Electric variants and other specialized types constitute the remainder, often serving niche requirements where automation or specific power constraints are prioritized.
On the application side, the pharmaceutical industry remains a primary revenue driver. The stringent hygiene standards required in drug manufacturing align perfectly with the contained transfer capabilities of modern powder pumps. The food and beverage sector follows closely, driven by the need for contamination-free processing of ingredients. The chemical industry and mining sector also contribute substantial volume, though their requirements often lean towards durability and hazard compliance rather than sanitary design.
A key insight from our analysis is the shift towards portable and modular systems. Many powder pumps now serve as cost-effective, portable alternatives to complex pneumatic conveying systems or mechanical conveyors for dry powder transfer. This flexibility allows smaller facilities or temporary production lines to adopt high-quality transfer technology without massive infrastructure investment. However, the specific revenue contribution of each segment is detailed in the proprietary tables of the full study, as these figures are subject to rapid change based on regional economic conditions.
Regional Overview and Industrial Hubs
Geographically, the market is distributed across five major regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific represents a significant portion of the global volume, reflecting the concentration of manufacturing and pharmaceutical production in the region. North America and Europe maintain strong positions, largely fueled by stringent safety regulations and high replacement cycles for aging machinery.
Latin America and the Middle East and Africa represent emerging opportunities. While their current share is smaller compared to the established industrial hubs, growth rates in these areas are influenced by infrastructure development and foreign investment in chemical and processing facilities. For companies looking to expand their footprint, understanding the specific regulatory and logistical hurdles in these regions is essential. The complete report provides a detailed breakdown of market size by region, allowing strategists to prioritize market entry or expansion efforts effectively.
Competitive Landscape and Key Players
The market structure is moderately fragmented, with the top three companies holding a combined market share of 32.5 percent and the top five accounting for 41.8 percent. This concentration suggests that while large players dominate, there is ample room for specialized manufacturers to compete on technology, compliance, or regional service capabilities.
Several key companies define the current competitive arena. Tapflo, based in Sweden, offers compact powder diaphragm pumps such as the TXP series. These are designed for the economical transfer of industrial and sanitary process powders, including carbon black, resins, and food ingredients, with options for ATEX and FDA compliance. Similarly, Piab, also headquartered in Sweden, provides piFLOW vacuum conveyors tailored for hygienic, ATEX-compliant powder and bulk transfer in food, pharma, and industrial applications.
In the United States, Iwaki Air, located in Holliston, MA, provides AODD Portable Powder Pumps in aluminum or stainless steel. These are engineered for the safe, clean transfer of fine, dry, low bulk density powders. ARO, part of Ingersoll Rand, also operates out of the USA, offering powder transfer AODD pumps in the PP series ranging from 1 to 3 inches. These are positioned as a cost-effective alternative to complex systems for fast, clean bulk powder handling.
European engineering is further represented by De Dietrich Process Systems in France. They specialize in dense-phase Powder Pumps designed for contained, dust-free transfer in chemical and pharmaceutical industries, including mobile cart systems. In Asia, Yamada Corporation from Japan manufactures heavy-duty diaphragm Powder Pumps, specifically the BH series, which are built for fine-grained, low bulk density dry powders in dust-free operations. Ceracin, based in Vadodara, Gujarat, India, acts as a manufacturer and supplier focused on the effective transfer of powdered chemicals with high efficiency and portability.
Recent Developments and Innovation Trends
Innovation in this sector is currently driven by safety, flexibility, and containment. Recent activities among key players highlight this shift. In September 2025, De Dietrich Process Systems introduced flexible rental options for mobile Powder Pump carts. These units offer throughputs up to 3,250 lbs/hr, specifically targeting process trials and temporary use cases. This move indicates a market trend towards lowering the barrier to entry for advanced transfer technology.
Further emphasizing safety, Ovell Pump released details in January 2026 regarding their pneumatic powder diaphragm pumps. The promotion highlighted contained, spark-free transfer capabilities specifically designed for hazardous areas. This aligns with the growing demand for equipment that mitigates ignition risks in volatile environments. Additionally, in December 2025, Iwaki Air updated their information on AODD Powder Transfer Pumps, focusing on configurations in aluminum and stainless steel for fine, dry powders. These updates suggest a continued refinement of material choices to balance durability with product purity.
Regulatory Environment and Safety Dynamics
Compliance is no longer just a checkbox; it is a market driver. Many powder pumps currently comply with ATEX directives for explosion-proof operation in dust hazard zones and FDA standards for food and pharma applications. Manufacturers like Tapflo and ARO have integrated these standards deeply into their product documentation and design philosophies. As regulatory bodies tighten enforcement, non-compliant equipment faces increasing liability risks and market exclusion.
Furthermore, safety protocols are evolving. The OSHA Combustible Dust National Emphasis Program (NEP) continues to target industries such as food and chemicals for enhanced safety in powder handling operations. As of 2026, this ongoing initiative pressures facilities to audit their transfer equipment rigorously. Equipment that guarantees dust-free transfer and minimizes spark risks is becoming preferred procurement choices for EHS managers. The full market study includes a detailed regulatory impact analysis, quantifying how these directives influence purchasing cycles and equipment specifications across different sectors.
Strategic Value of the Full Report
While this overview provides the strategic framework, the complete PW Consulting report offers the tactical data required for execution. Decision-makers need more than top-line aggregates; they require segment-specific growth rates, detailed competitive profiling, and supply chain risk assessments. The full study allows stakeholders to:
- Validate investment decisions with precise historical and forecasted revenue data.
- Identify gaps in the current product offerings of key competitors like Tapflo, Piab, and ARO.
- Assess the impact of regulatory changes on operational costs and compliance timelines.
- Evaluate regional opportunities based on detailed market size splits rather than global averages.
The Powder Transfer Pumps Market is poised for steady expansion, but the winners in 2026 and beyond will be those who navigate the nuances of safety compliance, technological flexibility, and regional demand shifts. Accessing the full intelligence behind this preview is the next logical step for any organization serious about optimizing its material handling strategy.
Powder Transfer Pumps Market
Magnetic Pumps Market
For detailed analysis of this topic, please visit the official page: Powder Transfer Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polished Substrates Market to Reach $22.78B by 2032, 6.51% CAGR Post-$14.65B 2025
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Era of Advanced Electronics: Inside the Worldwide Polished Substrates Market 2026-2032
In the rapidly evolving landscape of global electronics, the polished substrates market stands as a foundational pillar supporting advancements in semiconductor manufacturing, optoelectronics, and power electronics. As we move into 2026, understanding the trajectory of this market is not merely an academic exercise but a critical component of strategic planning for industry stakeholders. PW Consulting is pleased to introduce our latest comprehensive study, the Worldwide Polished Substrates Market report, designed to equip decision-makers with the actionable intelligence needed to navigate the complexities of the coming years.
This report offers a granular analysis of the market landscape, synthesizing historical data from 2020 through the base year of 2025 with robust forecasts extending to 2032. The polished substrate sector, encompassing materials such as silicon, silicon carbide, gallium nitride, sapphire, and advanced glass ceramics, is experiencing a transformative period driven by the electrification of vehicles, the rollout of 5G infrastructure, and the relentless demand for high-performance computing. Our analysis provides a clear window into these dynamics, highlighting where value is being created and where competitive pressures are intensifying.
Market Trajectory and Growth Dynamics
The historical performance of the polished substrates market demonstrates a consistent upward trajectory, reflecting the broader health of the technology sectors that rely on these critical components. Between 2020 and 2025, the market expanded significantly, with revenues climbing from approximately 10.25 billion USD to an estimated 14.65 billion USD in the base year. This growth underscores the increasing reliance on high-quality polished surfaces for everything from consumer electronic displays to industrial sensors.
Looking forward, our forecasts indicate that this momentum will continue through the forecast period ending in 2032. The market is projected to grow at a compound annual growth rate of 6.51 percent, reaching a valuation that reflects the maturation of advanced material technologies and the expansion of capacity in key producing regions. This growth rate suggests a steady, sustainable expansion rather than a volatile spike, offering a stable environment for investment but also requiring precise timing for capacity planning. As we approach the end of the decade, the market size is expected to approach 22.78 billion USD, signaling a substantial increase in demand that will test supply chains and encourage further consolidation among key players.
For strategic planners, these macro-level figures provide a essential backdrop for budgeting and resource allocation. However, the true value of this study lies in the breakdown of these figures across different dimensions. We analyze how growth varies across material types, application sectors, and geographic regions, allowing clients to identify high-growth pockets within the broader aggregate. For instance, while traditional silicon substrates remain dominant, the surge in power electronics is reshaping the demand profile for compound semiconductors. Similarly, regional analysis reveals shifting centers of gravity as manufacturing capabilities diversify globally.
Segmentation Analysis: Materials, Applications, and Regions
A core strength of our research is the detailed segmentation that allows for targeted strategy formulation. The market is categorized by substrate type, application, and region, each offering distinct insights into supply and demand dynamics.
By Substrate Type
The market is heavily influenced by the performance characteristics required by end-users. Silicon substrates continue to hold a significant share of the market, driven by their established role in semiconductor fabrication. However, the narrative is shifting with the rise of wide-bandgap materials. Silicon Carbide (SiC) and Gallium Nitride (GaN) substrates are gaining traction due to their efficiency in high-power and high-frequency applications. Our report examines the cost structures and production scalability of these materials, noting industry trends such as the significant reduction in costs for SiC substrates over recent years, which is lowering barriers to adoption in automotive and energy sectors.
Additionally, specialty substrates like sapphire and advanced glass ceramics are critical for niche but high-value applications in optics, sensors, and harsh environments. We assess the technological advancements in polishing techniques that are enabling thinner, more precise substrates, such as ultra-thin sapphire formats, and how these innovations are opening new doors in consumer electronics and medical devices.
By Application
Demand is dispersed across a diverse range of applications, each with unique growth drivers. Consumer electronics remains a primary volume driver, leveraging polished substrates for displays and packaging. Meanwhile, the automotive and power electronics segment is undergoing a structural boom, fueled by the transition to electric vehicles and the need for robust power management systems. Telecommunications is another critical pillar, with the expansion of 5G networks and data center infrastructure sustaining demand for high-performance substrates.
Beyond these major sectors, industrial and medical applications are contributing steady growth, while aerospace and defense sectors rely on specialized substrates for reliable performance in extreme conditions. Our analysis maps the revenue contribution of each application area and projects how their relative importance will shift over the forecast period, helping clients align their product portfolios with the most promising end markets.
By Region
Geographically, the market exhibits clear patterns of regional specialization and growth. Asia Pacific continues to be a dominant force, reflecting the concentration of manufacturing and consumption in this area. North America and Europe maintain significant positions, often driven by high-value specialized applications and robust R&D ecosystems. Emerging regions, including Latin America and the Middle East and Africa, are developing their capabilities, contributing to a more globally distributed supply chain. Our report details the market size and growth potential for each region, providing context on local regulatory environments, trade dynamics, and investment flows that shape regional performance.
Competitive Landscape and Key Players
The polished substrates market is characterized by a mix of established multinational corporations and specialized manufacturers, with a notable degree of concentration among the top players. Our study provides a deep dive into the competitive positioning of key companies, analyzing their product portfolios, technological capabilities, and strategic moves.
Worldwide Polymer Substrates Market
Japanese manufacturers such as Ohara Corporation and Shin-Etsu Chemical are recognized for their expertise in high-quality glass and silicon substrates, respectively. Ohara's focus on double-side lapped and polished glass substrates for photomasks and optics highlights the precision required in advanced lithography and optical systems. Shin-Etsu Chemical, along with competitors like SUMCO Corporation and Siltronic AG from Germany, plays a pivotal role in the supply of high-purity silicon wafers, which form the backbone of the semiconductor industry. These players are continuously investing in capacity and process improvements to meet the demanding specifications of logic and memory chip manufacturers.
In the realm of compound and specialty substrates, companies like Rubicon Technology, Valley Design Corp., and Polishing Corporation of America are instrumental in advancing sapphire and ceramic substrate technologies. Rubicon Technology's focus on sapphire substrates for optoelectronics and LEDs, combined with Valley Design's capabilities in aluminum nitride and ultra-thin sapphire processing, illustrates the diversification of materials available for specialized applications. Similarly, CoorsTek Inc. and Kyocera Corporation contribute advanced ceramic solutions that are essential for high-performance electronics and semiconductor components.
Worldwide Polished Substrates Market
GlobalWafers Co., Ltd. from Taiwan and SK Siltron from South Korea are also key participants, offering a range of silicon and compound substrates that support the global semiconductor supply chain. The presence of major players like SCHOTT AG, which supplies innovative glass and glass-ceramic substrates for consumer electronics and telecommunications, further underscores the breadth of the competitive field. Edmund Optics rounds out the landscape by providing precision optics and photonics components, catering to the exacting needs of industrial and research applications.
The market concentration data indicates that a significant portion of revenue is captured by the top three and top five firms, suggesting that scale and technological leadership are critical advantages. Our report analyzes the strategic interactions among these players, including potential collaborations, supply agreements, and competitive pressures that could influence pricing and availability in the coming years.
Industry Dynamics and Emerging Trends
Beyond the static snapshot of market size and competition, our report delves into the dynamic forces that are reshaping the polished substrates industry. Cost reduction is a recurring theme, particularly in the SiC segment where scaled production and process efficiencies are driving down the cost of 6-inch substrates. Industry data suggests that costs have declined significantly between 2022 and 2025, with further reductions anticipated by 2028. This trend is vital for the adoption of wide-bandgap technologies in cost-sensitive applications such as electric vehicles and renewable energy systems.
Regulatory and geopolitical factors are also playing an increasingly prominent role. Semiconductor self-sufficiency initiatives, particularly in China, have spurred massive investments in domestic manufacturing capacity. Projections indicate that installed 6-inch SiC wafer capacity in China could surpass 600,000 wafers per month by 2027, a development that will have profound implications for global supply balances and competitive dynamics. Our analysis contextualizes these investments within the broader trend of supply chain diversification and the push for regional resilience.
Technological innovation continues to push the boundaries of what polished substrates can achieve. The availability of ultra-thin sapphire substrates with optical finishes, ranging from 25 to 200 microns in thickness, exemplifies the precision engineering that is enabling new form factors and functionalities in optics, sensors, and harsh environment applications. These advancements are not only expanding the application envelope but also raising the bar for quality and performance that suppliers must meet.
Strategic Value of the PW Consulting Report
The Worldwide Polished Substrates Market report is more than a collection of statistics; it is a strategic tool designed to inform decision-making at the highest levels of your organization. By integrating historical data, forward-looking forecasts, and deep qualitative analysis, the report provides a holistic view of the market that is essential for formulating robust strategies.
Whether you are evaluating market entry opportunities, assessing the competitive threat landscape, planning capacity investments, or seeking to optimize your supply chain, this study offers the insights you need. We highlight the segments and regions with the highest growth potential, identify the key success factors for market leaders, and flag the risks and disruptions that could impact your business.
In a market where precision, performance, and reliability are paramount, having access to accurate and timely intelligence is a competitive necessity. Our report equips you with the knowledge to anticipate changes, capitalize on emerging trends, and navigate the complexities of the global polished substrates market with confidence. We invite you to explore the full depth of our analysis and leverage these insights to drive your strategic agenda forward in the dynamic landscape of 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Polished Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com