

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polished Substrates Market to Reach $22.78B by 2032, 6.51% CAGR Post-$14.65B 2025

Strategic Intelligence for the Era of Advanced Electronics: Inside the Worldwide Polished Substrates Market 2026-2032
In the rapidly evolving landscape of global electronics, the polished substrates market stands as a foundational pillar supporting advancements in semiconductor manufacturing, optoelectronics, and power electronics. As we move into 2026, understanding the trajectory of this market is not merely an academic exercise but a critical component of strategic planning for industry stakeholders. PW Consulting is pleased to introduce our latest comprehensive study, the Worldwide Polished Substrates Market report, designed to equip decision-makers with the actionable intelligence needed to navigate the complexities of the coming years.
This report offers a granular analysis of the market landscape, synthesizing historical data from 2020 through the base year of 2025 with robust forecasts extending to 2032. The polished substrate sector, encompassing materials such as silicon, silicon carbide, gallium nitride, sapphire, and advanced glass ceramics, is experiencing a transformative period driven by the electrification of vehicles, the rollout of 5G infrastructure, and the relentless demand for high-performance computing. Our analysis provides a clear window into these dynamics, highlighting where value is being created and where competitive pressures are intensifying.
Market Trajectory and Growth Dynamics
The historical performance of the polished substrates market demonstrates a consistent upward trajectory, reflecting the broader health of the technology sectors that rely on these critical components. Between 2020 and 2025, the market expanded significantly, with revenues climbing from approximately 10.25 billion USD to an estimated 14.65 billion USD in the base year. This growth underscores the increasing reliance on high-quality polished surfaces for everything from consumer electronic displays to industrial sensors.
Looking forward, our forecasts indicate that this momentum will continue through the forecast period ending in 2032. The market is projected to grow at a compound annual growth rate of 6.51 percent, reaching a valuation that reflects the maturation of advanced material technologies and the expansion of capacity in key producing regions. This growth rate suggests a steady, sustainable expansion rather than a volatile spike, offering a stable environment for investment but also requiring precise timing for capacity planning. As we approach the end of the decade, the market size is expected to approach 22.78 billion USD, signaling a substantial increase in demand that will test supply chains and encourage further consolidation among key players.
For strategic planners, these macro-level figures provide a essential backdrop for budgeting and resource allocation. However, the true value of this study lies in the breakdown of these figures across different dimensions. We analyze how growth varies across material types, application sectors, and geographic regions, allowing clients to identify high-growth pockets within the broader aggregate. For instance, while traditional silicon substrates remain dominant, the surge in power electronics is reshaping the demand profile for compound semiconductors. Similarly, regional analysis reveals shifting centers of gravity as manufacturing capabilities diversify globally.
Segmentation Analysis: Materials, Applications, and Regions
A core strength of our research is the detailed segmentation that allows for targeted strategy formulation. The market is categorized by substrate type, application, and region, each offering distinct insights into supply and demand dynamics.
By Substrate Type
The market is heavily influenced by the performance characteristics required by end-users. Silicon substrates continue to hold a significant share of the market, driven by their established role in semiconductor fabrication. However, the narrative is shifting with the rise of wide-bandgap materials. Silicon Carbide (SiC) and Gallium Nitride (GaN) substrates are gaining traction due to their efficiency in high-power and high-frequency applications. Our report examines the cost structures and production scalability of these materials, noting industry trends such as the significant reduction in costs for SiC substrates over recent years, which is lowering barriers to adoption in automotive and energy sectors.
Additionally, specialty substrates like sapphire and advanced glass ceramics are critical for niche but high-value applications in optics, sensors, and harsh environments. We assess the technological advancements in polishing techniques that are enabling thinner, more precise substrates, such as ultra-thin sapphire formats, and how these innovations are opening new doors in consumer electronics and medical devices.
By Application
Demand is dispersed across a diverse range of applications, each with unique growth drivers. Consumer electronics remains a primary volume driver, leveraging polished substrates for displays and packaging. Meanwhile, the automotive and power electronics segment is undergoing a structural boom, fueled by the transition to electric vehicles and the need for robust power management systems. Telecommunications is another critical pillar, with the expansion of 5G networks and data center infrastructure sustaining demand for high-performance substrates.
Beyond these major sectors, industrial and medical applications are contributing steady growth, while aerospace and defense sectors rely on specialized substrates for reliable performance in extreme conditions. Our analysis maps the revenue contribution of each application area and projects how their relative importance will shift over the forecast period, helping clients align their product portfolios with the most promising end markets.
By Region
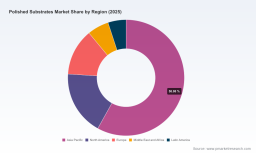
Geographically, the market exhibits clear patterns of regional specialization and growth. Asia Pacific continues to be a dominant force, reflecting the concentration of manufacturing and consumption in this area. North America and Europe maintain significant positions, often driven by high-value specialized applications and robust R&D ecosystems. Emerging regions, including Latin America and the Middle East and Africa, are developing their capabilities, contributing to a more globally distributed supply chain. Our report details the market size and growth potential for each region, providing context on local regulatory environments, trade dynamics, and investment flows that shape regional performance.
Competitive Landscape and Key Players
The polished substrates market is characterized by a mix of established multinational corporations and specialized manufacturers, with a notable degree of concentration among the top players. Our study provides a deep dive into the competitive positioning of key companies, analyzing their product portfolios, technological capabilities, and strategic moves.
Worldwide Polymer Substrates Market
Japanese manufacturers such as Ohara Corporation and Shin-Etsu Chemical are recognized for their expertise in high-quality glass and silicon substrates, respectively. Ohara's focus on double-side lapped and polished glass substrates for photomasks and optics highlights the precision required in advanced lithography and optical systems. Shin-Etsu Chemical, along with competitors like SUMCO Corporation and Siltronic AG from Germany, plays a pivotal role in the supply of high-purity silicon wafers, which form the backbone of the semiconductor industry. These players are continuously investing in capacity and process improvements to meet the demanding specifications of logic and memory chip manufacturers.
In the realm of compound and specialty substrates, companies like Rubicon Technology, Valley Design Corp., and Polishing Corporation of America are instrumental in advancing sapphire and ceramic substrate technologies. Rubicon Technology's focus on sapphire substrates for optoelectronics and LEDs, combined with Valley Design's capabilities in aluminum nitride and ultra-thin sapphire processing, illustrates the diversification of materials available for specialized applications. Similarly, CoorsTek Inc. and Kyocera Corporation contribute advanced ceramic solutions that are essential for high-performance electronics and semiconductor components.
Worldwide Polished Substrates Market
GlobalWafers Co., Ltd. from Taiwan and SK Siltron from South Korea are also key participants, offering a range of silicon and compound substrates that support the global semiconductor supply chain. The presence of major players like SCHOTT AG, which supplies innovative glass and glass-ceramic substrates for consumer electronics and telecommunications, further underscores the breadth of the competitive field. Edmund Optics rounds out the landscape by providing precision optics and photonics components, catering to the exacting needs of industrial and research applications.
The market concentration data indicates that a significant portion of revenue is captured by the top three and top five firms, suggesting that scale and technological leadership are critical advantages. Our report analyzes the strategic interactions among these players, including potential collaborations, supply agreements, and competitive pressures that could influence pricing and availability in the coming years.
Industry Dynamics and Emerging Trends
Beyond the static snapshot of market size and competition, our report delves into the dynamic forces that are reshaping the polished substrates industry. Cost reduction is a recurring theme, particularly in the SiC segment where scaled production and process efficiencies are driving down the cost of 6-inch substrates. Industry data suggests that costs have declined significantly between 2022 and 2025, with further reductions anticipated by 2028. This trend is vital for the adoption of wide-bandgap technologies in cost-sensitive applications such as electric vehicles and renewable energy systems.
Regulatory and geopolitical factors are also playing an increasingly prominent role. Semiconductor self-sufficiency initiatives, particularly in China, have spurred massive investments in domestic manufacturing capacity. Projections indicate that installed 6-inch SiC wafer capacity in China could surpass 600,000 wafers per month by 2027, a development that will have profound implications for global supply balances and competitive dynamics. Our analysis contextualizes these investments within the broader trend of supply chain diversification and the push for regional resilience.
Technological innovation continues to push the boundaries of what polished substrates can achieve. The availability of ultra-thin sapphire substrates with optical finishes, ranging from 25 to 200 microns in thickness, exemplifies the precision engineering that is enabling new form factors and functionalities in optics, sensors, and harsh environment applications. These advancements are not only expanding the application envelope but also raising the bar for quality and performance that suppliers must meet.
Strategic Value of the PW Consulting Report
The Worldwide Polished Substrates Market report is more than a collection of statistics; it is a strategic tool designed to inform decision-making at the highest levels of your organization. By integrating historical data, forward-looking forecasts, and deep qualitative analysis, the report provides a holistic view of the market that is essential for formulating robust strategies.
Whether you are evaluating market entry opportunities, assessing the competitive threat landscape, planning capacity investments, or seeking to optimize your supply chain, this study offers the insights you need. We highlight the segments and regions with the highest growth potential, identify the key success factors for market leaders, and flag the risks and disruptions that could impact your business.
In a market where precision, performance, and reliability are paramount, having access to accurate and timely intelligence is a competitive necessity. Our report equips you with the knowledge to anticipate changes, capitalize on emerging trends, and navigate the complexities of the global polished substrates market with confidence. We invite you to explore the full depth of our analysis and leverage these insights to drive your strategic agenda forward in the dynamic landscape of 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Polished Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com